Predicting Apple's Biggest Quarter Ever
by Horace Dediu
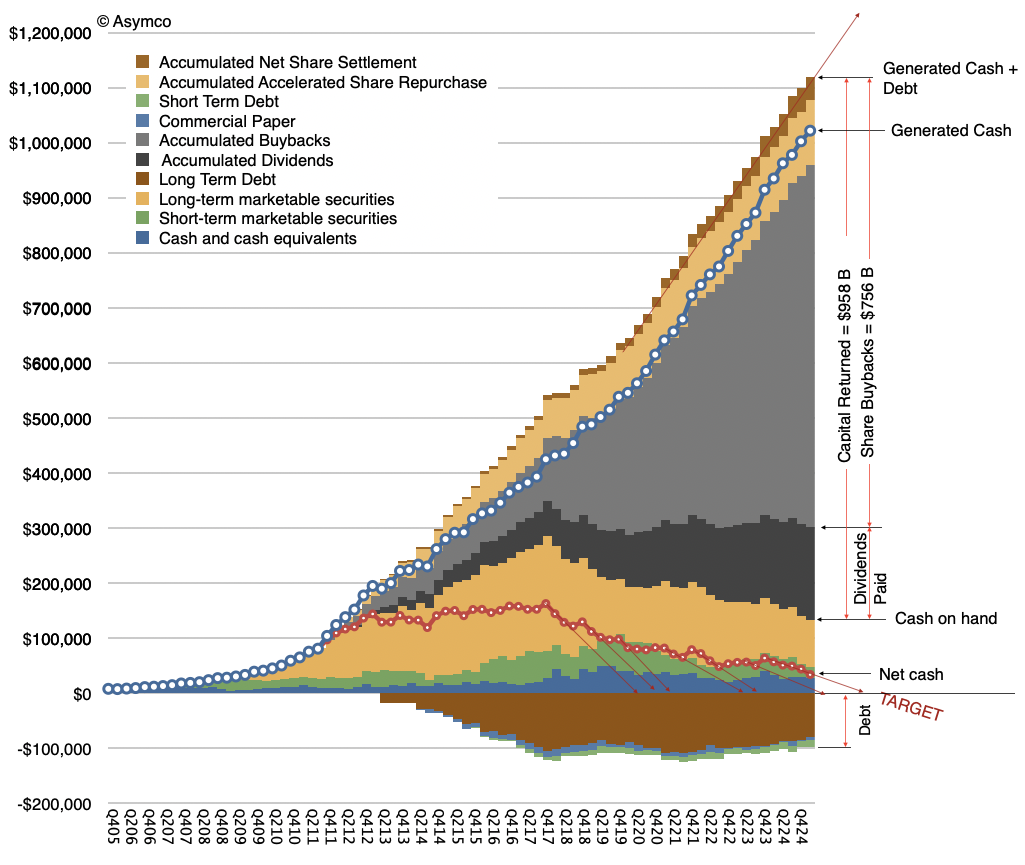
As we approach the earnings release for the first fiscal/fourth calendar quarter for Apple, it's time to look back three months at what the company delivered and guided in the previous quarter.
The summary for results for fourth (fiscal) quarter of FY2025:
- Revenue up 8% year-over-year, a new September quarter record.
- EPS was up 13% year-over-year.
- Product revenue was up 5% year-over-year driven by growth across iPhone and Mac.
- iPhone revenue was up 6% year-over-year, and set a September quarter record despite supply constraints faced on several iPhone 16 and iPhone 17 models.
The iPhone active installed base grew to a new all-time high and had a quarterly record for upgraders. Also, Apple reached a new all-time high for installed base of active devices.
- Mac revenue was up 13% year-over-year, driven by MacBook Air.
Apple grew in every geographic segment, with strong double-digit growth in emerging markets.
Mac installed base reached another all-time high, with nearly half of customers who purchased a Mac being new-to the product. - iPad was down 3% revenue and but over half of the customers who purchased iPad this quarter were new-to the product. iPad also had a September quarter record for upgraders.
- Wearables, Home & Accessories Revenue for the category was flat y/y.
Apple saw a September quarter record for upgraders to Apple Watch, and over half of Apple Watch buyers were new-to the product.Both the Apple Watch and AirPods installed bases reached new all-time highs. - Services again set a new all-time revenue record up 15% year-over-year.
Apple saw double-digit growth in both developed and emerging markets.
Apple saw a sequential acceleration across the majority of the categories and set new all-time records across Advertising, App Store, Cloud Services, Music, Payment Services, and Video. Apple saw a double digit growth in Apple Pay.
Guidance was provided as follows:
We expect iPhone revenue to grow double digits year-over-year, which would be our best iPhone quarter ever. On Mac, keep in mind, we expect to face a very difficult compare against the M4 MacBook Pro, Mac Mini and iMac launches in the year ago quarter. We expect Services revenue to grow at a year-over-year rate similar to what we reported in the fiscal year 2025.
We expect gross margin to be between 47% and 48%, which includes an estimated impact of $1.4 billion of tariff-related costs. And so for the December quarter, we expect operating expenses to be between $18.1 billion and $18.5 billion. We expect OI&E to be around $150 million, excluding any potential impact from the mark to market of minority investments and our tax rate to be around 17%.
Based on these forecasts my estimates for the top, bottom and middle lines are as follows:
- Revenues: $140 Billion (+12%)
- EPS: $2.70 (+12.5%)
- iPhone: $78.9 Billion (+12%)
- Mac: $9.4 Billion (+4%)
- iPad: $8.5 Billion (+5%)
- Wearables: $12.9 Billion (+10%)
- Services: $30 Billion (+14%)
If there is an error in the above I would guess it's in iPhone being too low and the iPad/Mac and Wearables being too high. Nevertheless, I think this will be Apple's biggest quarter ever with significant growth acceleration on the top and bottom lines. [Notable will also be a rapid acceleration in R&D spending (+25%) as suggested by guidance.]
As we head into this blockbuster quarter, Apple shares are trading at a P/E ratio of 32 to 33, a significant drop from above 35 during previous few quarters. During the last three months, the share price has declined about 15% as Mr. Market looked at the money mountain above and decided he wanted none of it.
Comments