Time to Buy, Time to Sell.
by Horace Dediu
One flipped to Buy, one flipped to Sell. By my count 28 say Buy and 20 say Hold or Sell.
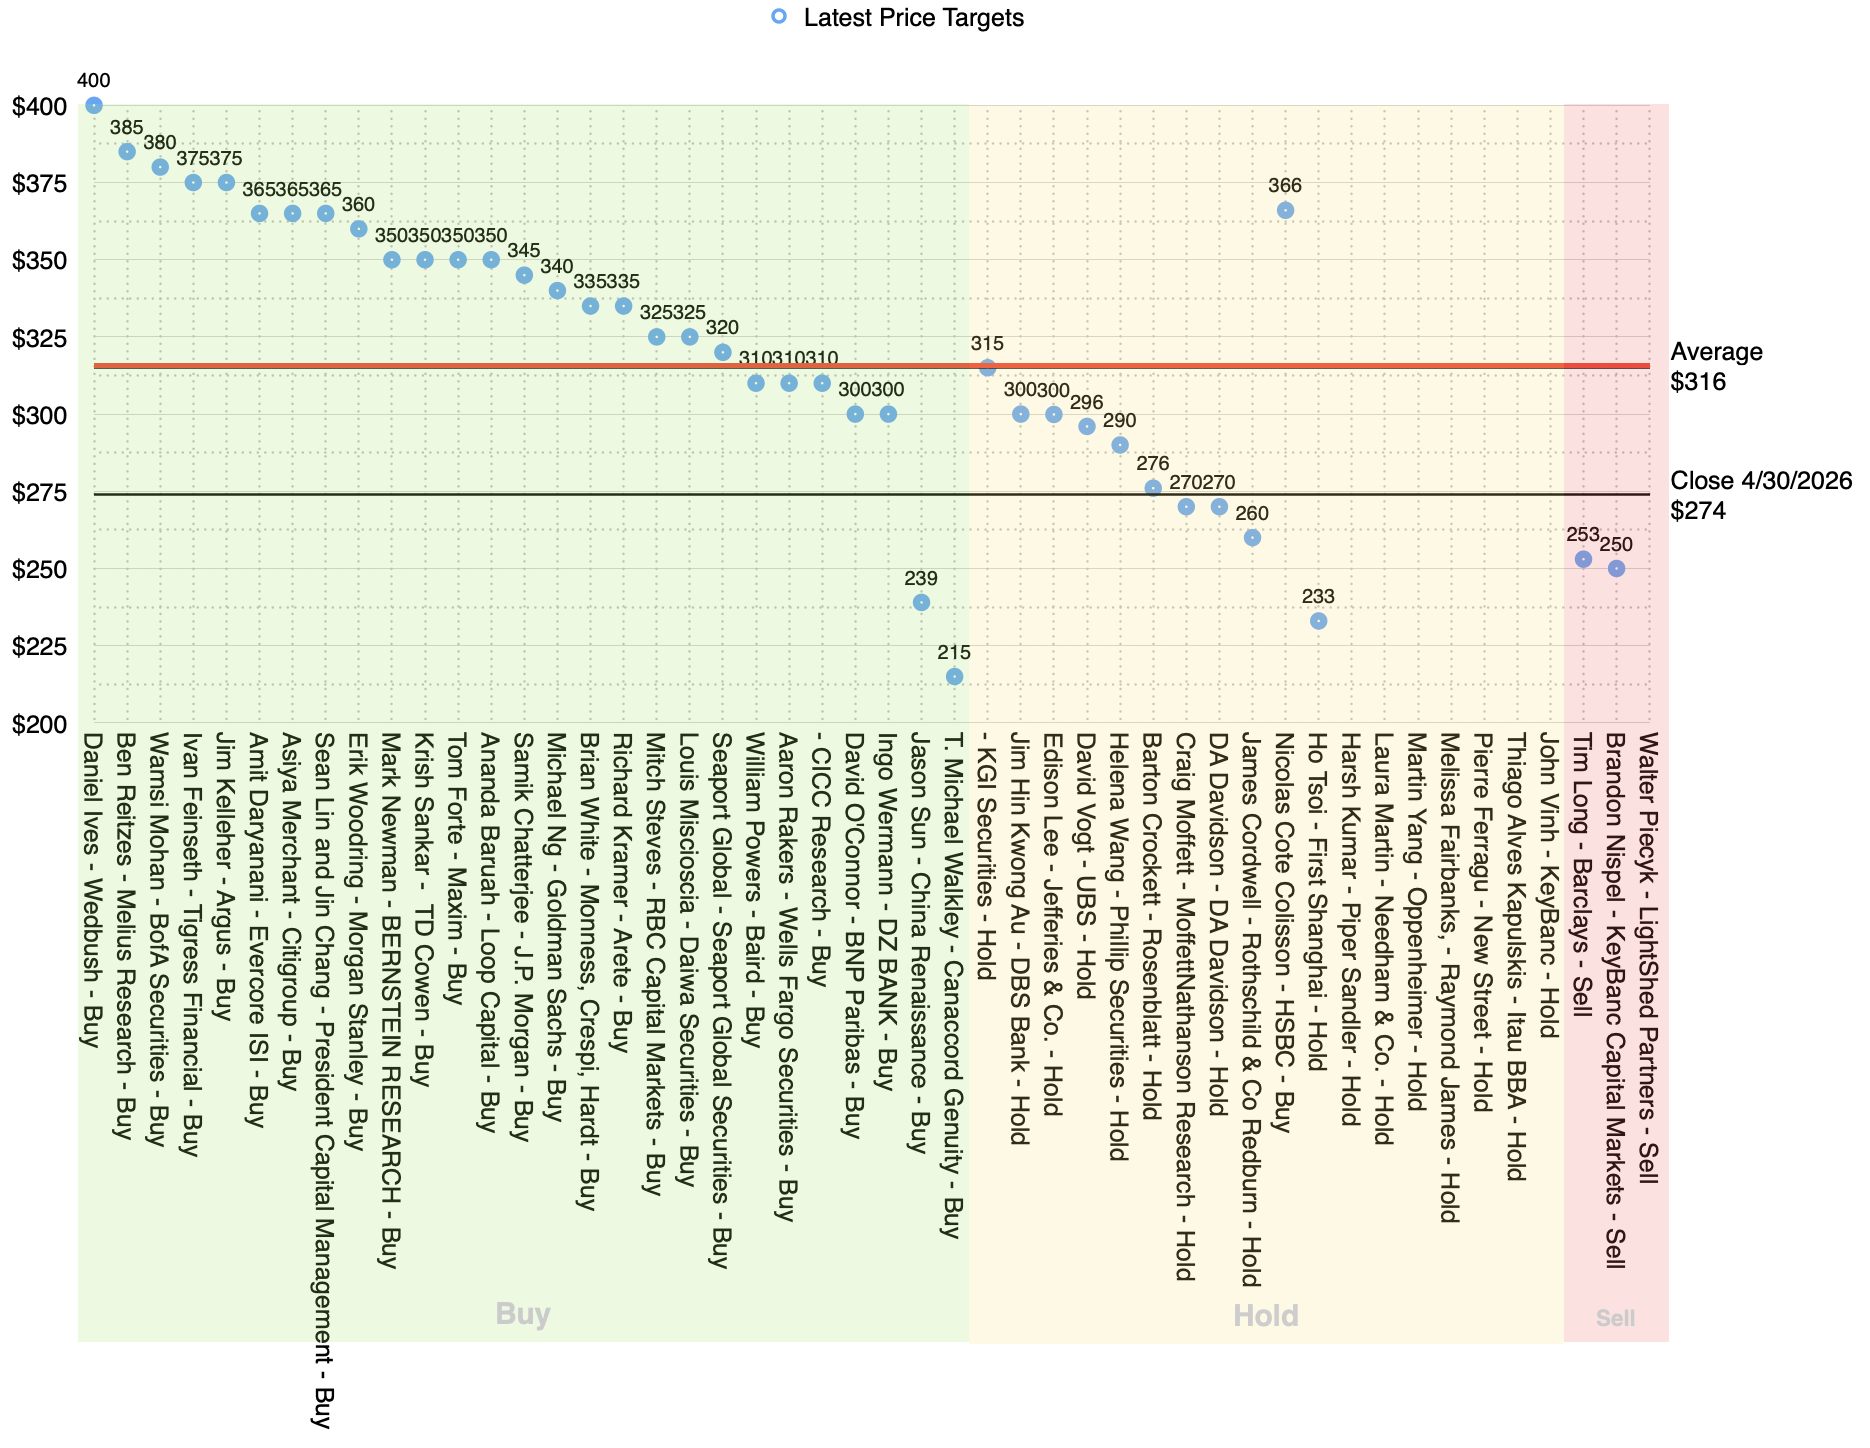
Apple stock inched lower in pre-market trading on Friday even after HSBC analyst Nicolas Cote Colisson upgraded the iPhone maker to Buy from Hold and raised its price target by about 41% to $366 from $260. The firm said Apple is nearing an “operational turning point,” helped by its AI plans and what it called “one of its most innovative product pipelines.”
Colisson said Apple is now better placed to benefit from AI than before. He believes the company can stay away from the “too high capex debate” while using its installed base of 2.5 billion devices to expand Apple Intelligence.
The analyst expects Apple’s revamped AI platform to play a key role. He said the new agentic Siri AI will add visual intelligence and richer interactions. It will also access information across apps to deliver better responses. According to HSBC, the AI upgrade comes at the right time as Apple prepares to launch new devices.
HSBC also highlighted Apple’s strong hardware roadmap. The analyst expects the iPhone 18 Pro and Pro Max later this year, followed by an iPhone Air, a book-style foldable iPhone, a 20th-anniversary iPhone, and smart glasses over the next two years. He believes these products, along with better AI features, could trigger a “strong renewal cycle” among iPhone users.
Reflecting this outlook, HSBC raised its 2027 and 2028 revenue forecasts by 7% to 9%. It also increased its 2027 iPhone sales forecast by 11% to 13% and lifted its 2027 EPS estimate by about 8%.
Source: TipRanks
NB: 41%! From $260 to $366 is quite a jump. Meanwhile, KeyBanc Capital Markets downgraded the iPhone maker to Underweight from Sector Weight…
… slapping a $250 price target on a stock that closed at $317.31 on Monday ($333 at time of writing).
KeyBanc sees iPhone revenue up 23.2% in FY26, ahead of consensus at 19.7%, but growth slowing sharply to 4.9% in FY27 versus Street at 8.3%.
As hardware unit growth cools, the firm also cuts back its Services view, modeling FY27 Services growth decelerating to 7% versus consensus near 12%.
With Apple trading at about 24.5x FY27 EV/EBITDA and roughly 35x forward earnings — more than two standard deviations above the S&P 500 and Nasdaq — KeyBanc argues the multiple no longer fits a maturing, slower‑growth hardware and services story.
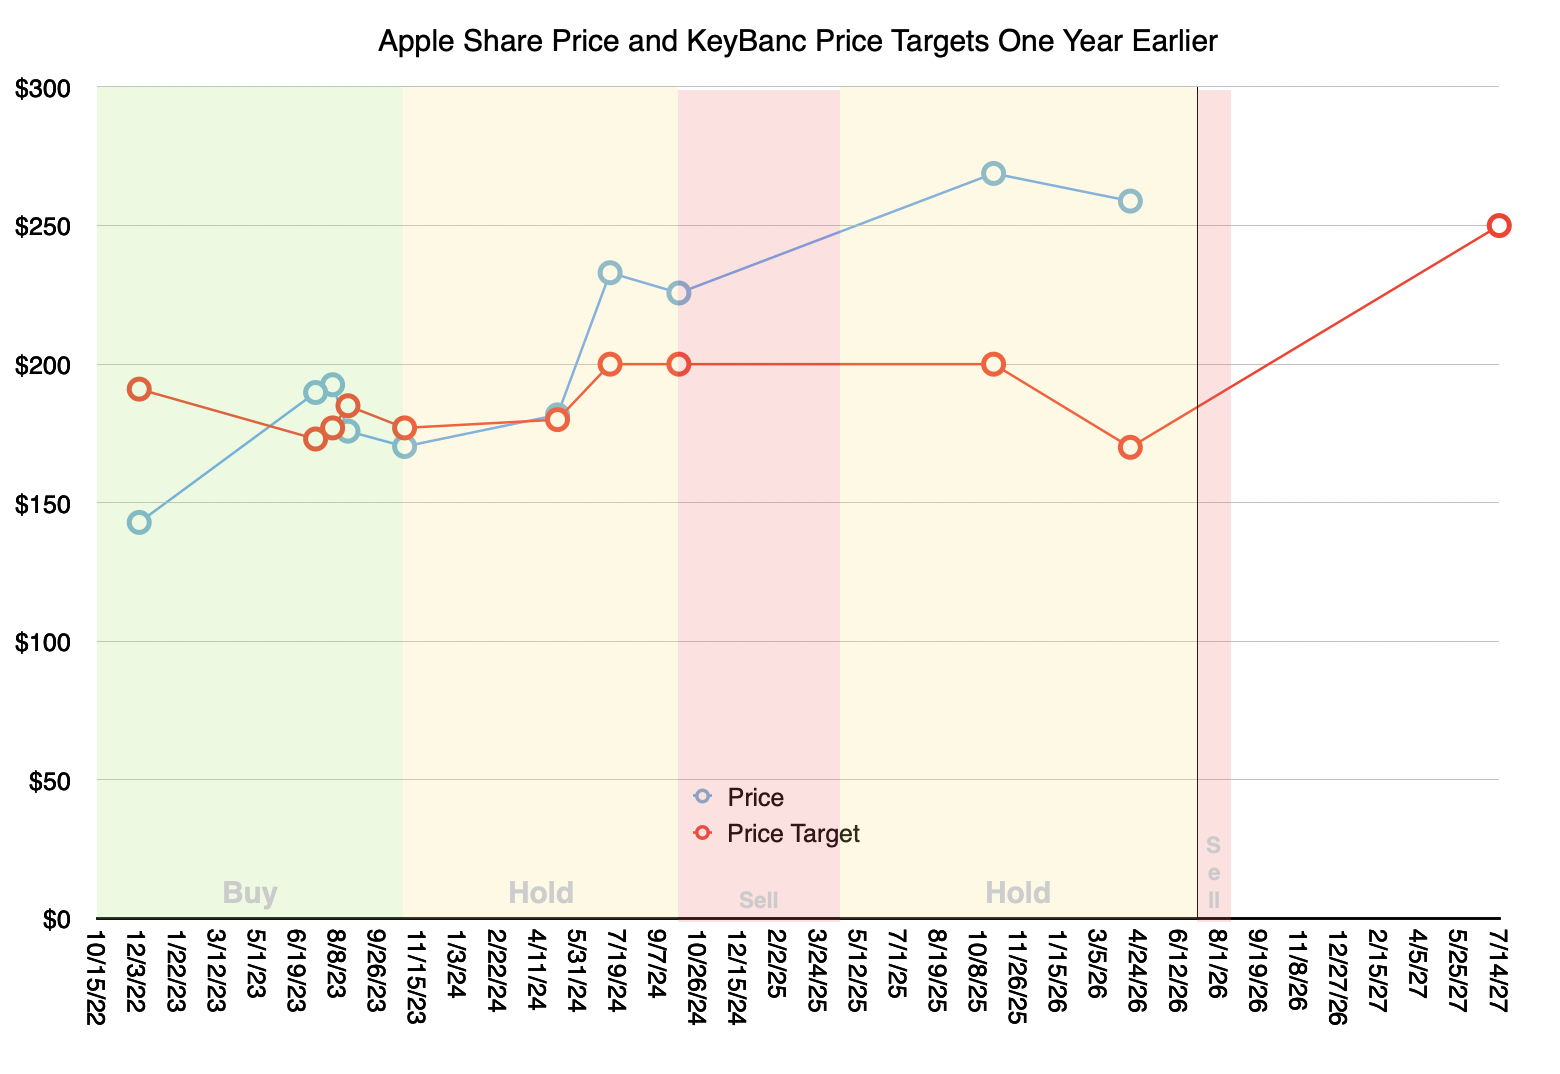
Here is Keybanc's performance on Apple targets. The red line shows the year-ago targets and the blue line shows the performance of the share price. Note that during the time when the rating was "Buy" the targets and results aligned very well, surprisingly so. As the rating switched to Hold and later to Sell, the targets diverged from results dramatically.
That happened already in 2024 and got worse since. The latest target set for $250 happened the day before the share price rallied and it now sits at $333. The implication is that shares will drop $83 or 25%.
Comments