Asymco

Asymmetric Intelligence

Research

  1. Other Products

    Research · 6 comments

    From the way Apple reports its revenues you might think that the company has several operating segments. There are the iPhone, the Mac, the iPad for which units and revenues are reported. Then there are Services and Other Products for which we have revenues only.

    Services is a collection of all non-hardware revenues and is (finally) being recognized as a non-trivial business. With reported revenues of $26.6 billion in the last twelve months, it's big enough to be a Fortune 100 company and set to double in four years. ((Although a non-zero business, the valuation of Services continues to confound observers who cannot separate it from the hardware businesses it attaches to--which themselves are considered near commodity value--thus paradoxically valuing the overlying asset of Services near or precisely at zero. Incidentally, Facebook is Fortune 98 at $27.3 billion and it is also one of the top 5 largest business by market capitalization.))

    That leaves "Other Products" which now becomes the revenue segment that is  "most likely to be ignored." This segment had revenues of only about $11.5 billion in the last 12 months which would place it at only a Fortune 245 ranking, equivalent to a Toys "R" Us or Biogen. How should we value Other Products?

    Other includes many hardware products including iPod, Apple TV, Beats, Apple Watch, AirPods and, soon, HomePod. Each is a significant product, with Watch probably the largest single contributor. But since we don't have specific unit numbers, we are left guessing at the contribution of each.

    The Watch itself has been a point of scrutiny as it could be initially teased out of the mix through an observation of the before-and-after launch vs. trend-line as shown below:
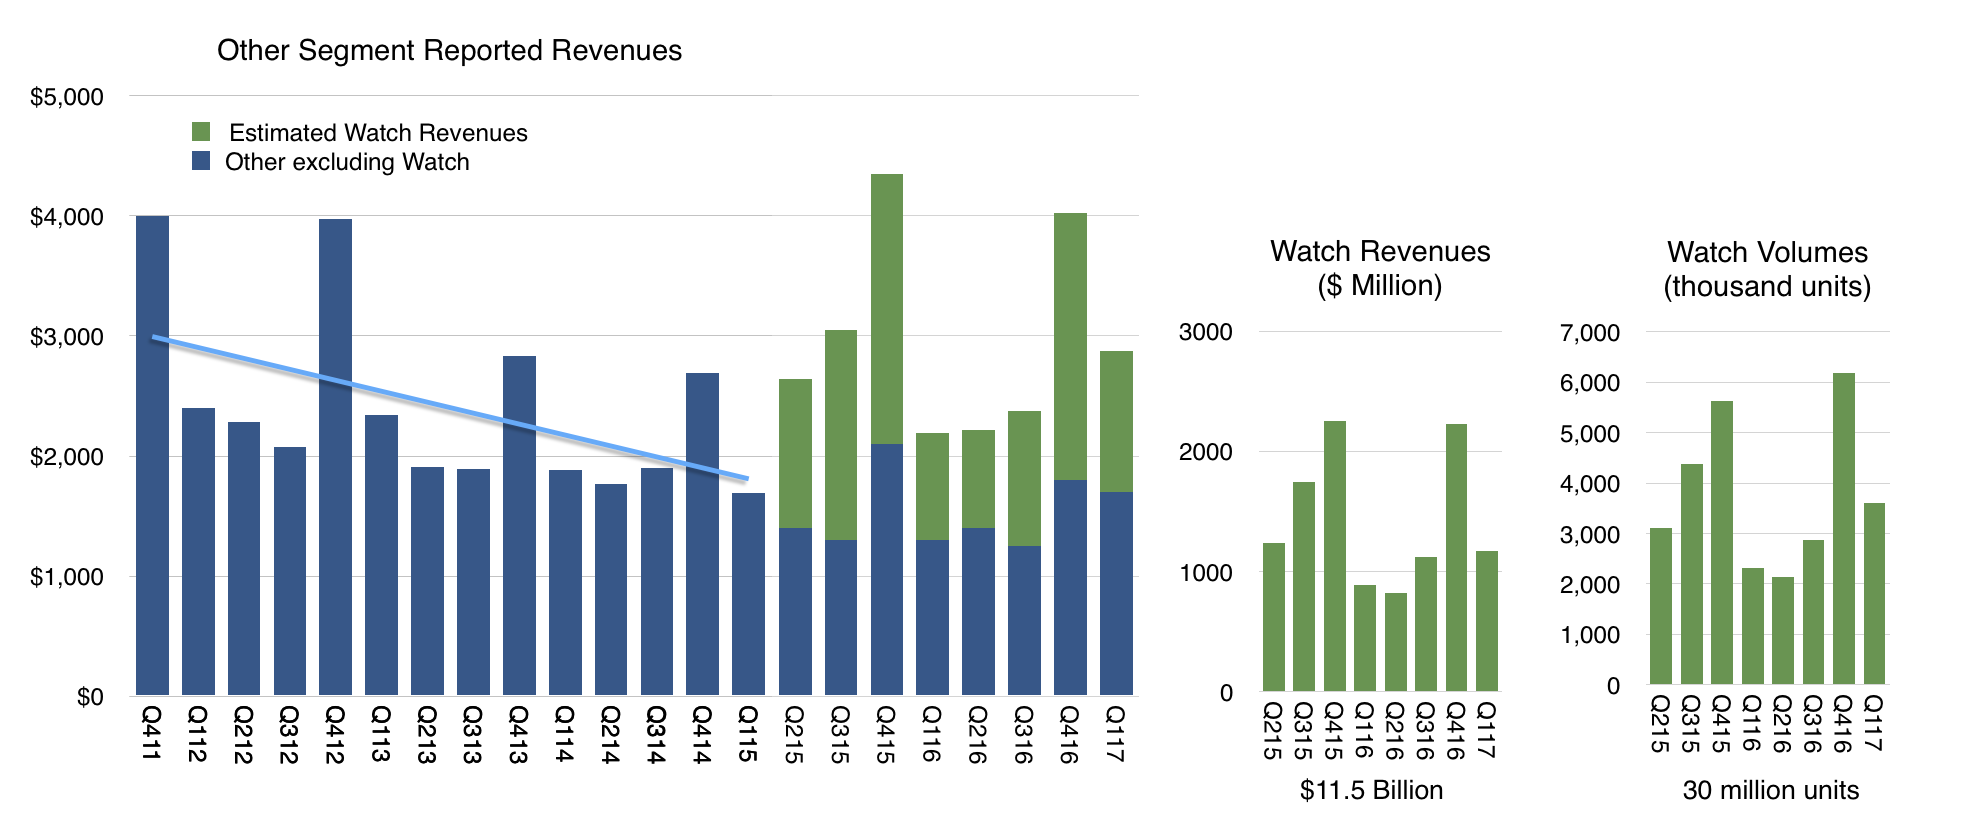
    This separation of Watch became harder to discern after the launch of AirPods. Though they are still very hard to obtain, they might be "moving the needle" by now with a contribution that would muddy the Other category further. Same with updated Beats headphones.

    This separation will be harder still with the launch of HomePod later this year. This product is priced at a point similar to the Watch and the quantities sold will be very hard to estimate without Apple's revealing of actuals.

    Fundamentally however, all the "Other products" will have a common relationship to the iOS and MacOS hardware: attachment to and integration with a "parent" platform. Apple TV might be stand-alone but I strongly doubt there are many sold into offices or households which don't have iOS usage.

    This means that "Other Products" are very similar to "Services" in that there is a dependency on a primary platform and, as it has been argued, they are therefore fragile. If the core platform declines then the Services and Other Products decline as well.

    Given this dependency it makes little sense to carve these categories out as separate businesses. They cannot stand alone. They are very much the "children" of the parent platforms.

    This is why it's assumed that Services, (a Fortune 100 company) and Other Products (a Fortune 250 company) can be discounted to zero. By focusing attention on the iPhone one can capture all the essential value of Apple. This is in contrast to the "sum-of-parts" valuation that could be applied to a set of independent business units in other companies.

    And yet I started this discussion with the point that you might be tempted to look at Apple on the basis of these reported revenue segments. The choice of what Apple reports is arbitrary. It could report no segment revenues at all and publish just one revenue number. This is roughly what Google Amazon and Facebook do. Or it could report segments in some other way. For instance, app store revenues and AirPods could be reported as part of "The iPhone Division". Or maybe it could bundle all iOS devices and services and accessories into another segment called "The iOS Group". Or it could create a "Devices group" and a "Personal Computing" group. Microsoft famously shuffles its revenues into creative segments based on various organizational structures or choice of what it wants to project as its focus.

    There is no limit to the ways Apple could slice revenues into segments. The reason Apple does it the way they do is mostly due to historical reasons. The company used to report the iPod separately as a segment but it no longer does. It also used to report Software separately, because, presumably,  it charged for it but now it no longer does. It also separated laptops or portables from desktops.

    The current reporting system is tempting us to draw certain "business unit" conclusions. These boundaries are illusions because Apple does not have business units. It has only one Profit and Loss statement (P/L) and is organized functionally. There is no "head of iPhone" or "head of Mac" responsible for each siloed revenue and cost structure. Instead, the entire business should be seen as a whole because it is managed as a whole.

    This is easily evident in how the products are designed and marketed and how they are engineered. The iPhone may spawn AirPods and AirPods may have no value outside the iPhone but the iPhone is valuable precisely because it has AirPods and Apps and Music and iCloud. And Apple TV, and HomePod and whatever comes next. The reason the iPhone can be sold at three times the price of competitor products is because of the Services and Other Products and iPad and Mac symbiosis. This integration drives the satisfaction, loyalty, price and brand value. There there are the Apple Stores and the launch events and the countless details that make up the ownership experience.

    The fact is that you can't slice and dice Apple.

    There is one Apple and it must be analyzed as a unitary entity. That analysis is therefore difficult. It is easy to pick up the numbers given and study them in isolation. The iPhone, the iPad, the Mac. We all do that.. However we miss a great deal in doing that.

    The lesson is that data we obtain leads us to see something but it also blinds us by taking attention away from what we cannot see. All data lies by omission. That which is left unmeasured may be where all the truth lies.
  2. Join the Micromobility Summit in Copenhagen September 6

    Research · 3 comments

    I'm Happy to announce that I'll be hosting the Micromobility Summit at Techfestival this year. Taking place on September 6 in Copenhagen, the one-day summit explores how new technologies affect society, cities and urbanization in the very near future.

    Join and contribute here: 

    About Techfestival:

    This September, Copenhagen will be home to 15,000+ people exploring a new, progressive agenda on technology. One week filled with 100+ conferences, summits, dinners, art installations and concerts, Techfestival’s goal is to break down today’s most complex questions into real talk and tangible experiences.f

  3. Defining the 21st Century

    Research · 50 comments

    The iPhone is the best selling product ever, making Apple perhaps the best business ever. Because of the iPhone, Apple has managed to survive to a relatively old age. Not only did it build a device base well over 1 billion it engendered loyalty and satisfaction described only by superlatives.

    To summarize I can offer two numbers:

    1,162,796,000 iPhones sold (to end of March 2017).

    $742,912,000,000 in revenues. $1 trillion will be reached in less than 18 months.

    But more important than any of these quantifiable measures of success are the unquantified accomplishments. These are the changes we note only when flipping an A/B switch on a decade. The changes ushered by the iPhone have been as momentous as those of the Ford Model T. Or those of electricity, telegraph, radio or TV.

    These are epoch-making technologies. They shape the fiber of society and the definition of quality of life. They obsolete entire economies and change the balance of political power. They shift the center of gravity of society.

    To glimpse the change you only need to observe how we shifted how we spend our time. The fact that 2 billion people are using Facebook every day. That the device is looked at for 2 hours a day. That it's unlocked 80 times a day. That it holds almost all our memories and our conversations and all our secrets. That it created new modes of communication and destroyed others, ancient and respected.

    That it substituted communications, entertainment, and interaction. That swiping became the most used human gesture. That we communicate with photos and not with words. That, like the voice call, transportation now comes to us rather than we to it. That it can answer to our voice. That we can never be lost again. That it makes us all publishers.

    That all this happened while the product itself was always perceived as fragile, vulnerable, copyable, doomed to early demise. That imitators outnumber it 10 to 1. That it somehow found ways to become better even though we exhaust what we can ask of it.

    For all these reasons I believe that future historians will point to the iPhone as the technological product that defined the 21st century. Much will follow from it and it may become something altogether different but it set humanity on a new course.

  4. App Story

    Research · 21 comments

    The App Store is almost 9 years old. In that time it has generated about $100 billion in revenues, of which about $70 billion has been passed on to developers and $30 billion was kept by Apple. It's very likely that running the App Store for 9 years did not cost $30 billion so, if it were an independent "business unit" it would probably have been and still be quite profitable.

    But Apple does not run "business units" with separate Profit and Loss statements. The App Store is a part of Services which is an amalgamation of non-hardware sources of revenues but that does not mean it's a business. The purpose of Services isn't to turn a profit or define its value through some metric of financial performance.

    The purpose of Services is to make the experience for the Apple user better. The combination of good experiences allows Apple to be perceived as a valuable brand and that allows it to obtain consistently above-average profitability through pricing power. I like to emphasize that the iPhone at over $600 in average price is more than twice the average price of all the other smartphones and captures over 90% of all available profits.

    This is something that remains after a decade and indeed the price is rising in the face of overall price erosion, all without a decrease in volumes. The sustainability of this exceptionalism is due to no one single thing. It's due to the persistence across all the things Apple does: product, stores, software and services and many other details too numerous to count.

    The result is a large and expanding base of satisfied customers and a large and expanding base of partners both in hardware and software and services. The WWDC event this year showed how the ecosystem of Apple is booming with over 3 million new developers and Keynote screenfuls of partnerships. All this makes for a complex picture but it's a real picture.

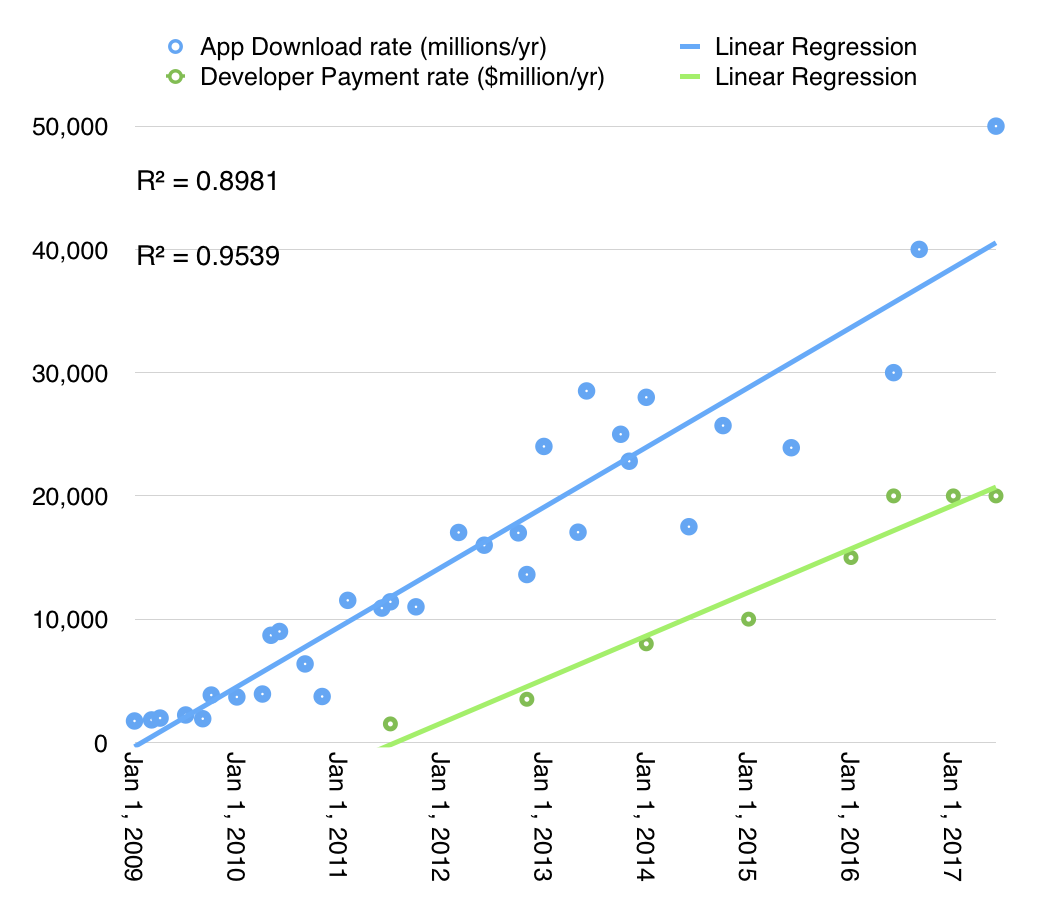
    The latest numbers on Services try to tell this story: 180 billion App downloads from 500 million App store weekly visitors. The download rate is accelerating as shown in the following graph:

    The revenue or payment rates can also be shown as accelerating though at a different rate. In both cases, the story of apps is not yet over, regardless of commentary to the contrary. Much of this growth comes from new markets like China and as India joins the iOS world, there is yet more opportunity emerging.

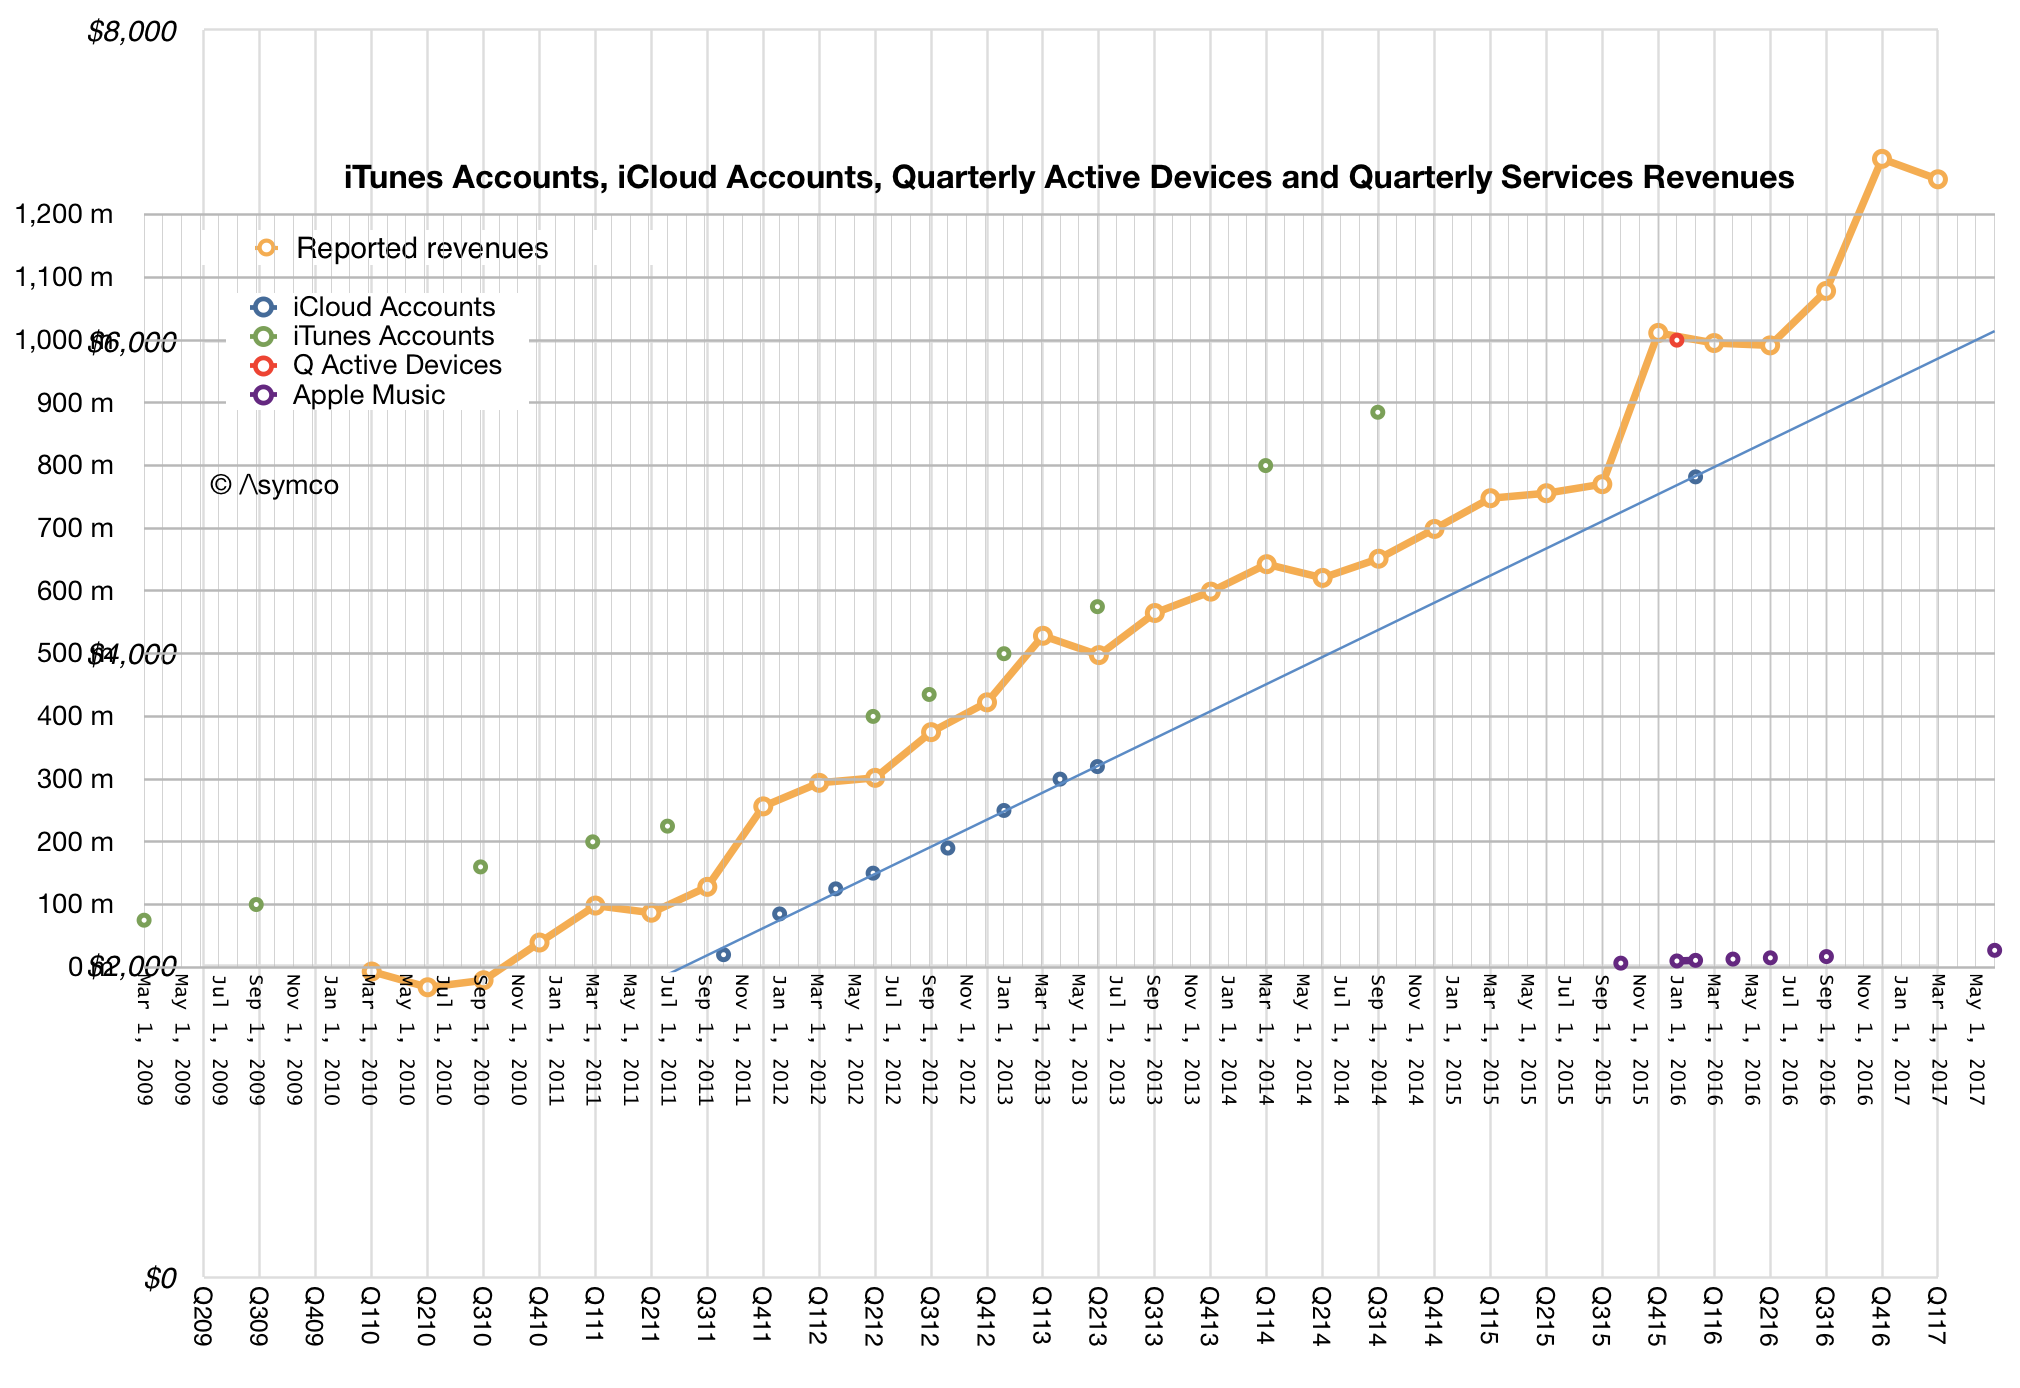
    This enables part of the story of Services which can be tracked with several other metrics: reported revenues, iCloud accounts, active devices, and iTunes accounts are highly correlated.

    The patterns after a decade are remarkably consistent. One would have thought that with mobile saturation in advanced markets, the content story would be told through horizontal lines. What we still see is the same slopes we've seen since the earliest days.

    But the biggest story at WWDC was the re-design of the App Store as a curated content market. The changes are profound: discovery, curation and the surfacing of content have been revamped. It's hard to predict the implications of this but one of the indications of direction was the separation of "Games" from "Apps". This is a jarring idea since if all Apps are content, what makes Games different from other Apps? Is this a genre elevated to a new medium?

    I can't yet get a sense of where this is heading, if anywhere, but the remarkable story of Apps is that it's still an ongoing story. We may be on chapter 2 and we can't predict how many chapters remain.

    Keep an eye on Apps and Services and developers. They are not lagging indicators of success for Apple. They are very much leading.

  5. Predictably Profitable, Unpredictably Valuable

    Research · 11 comments

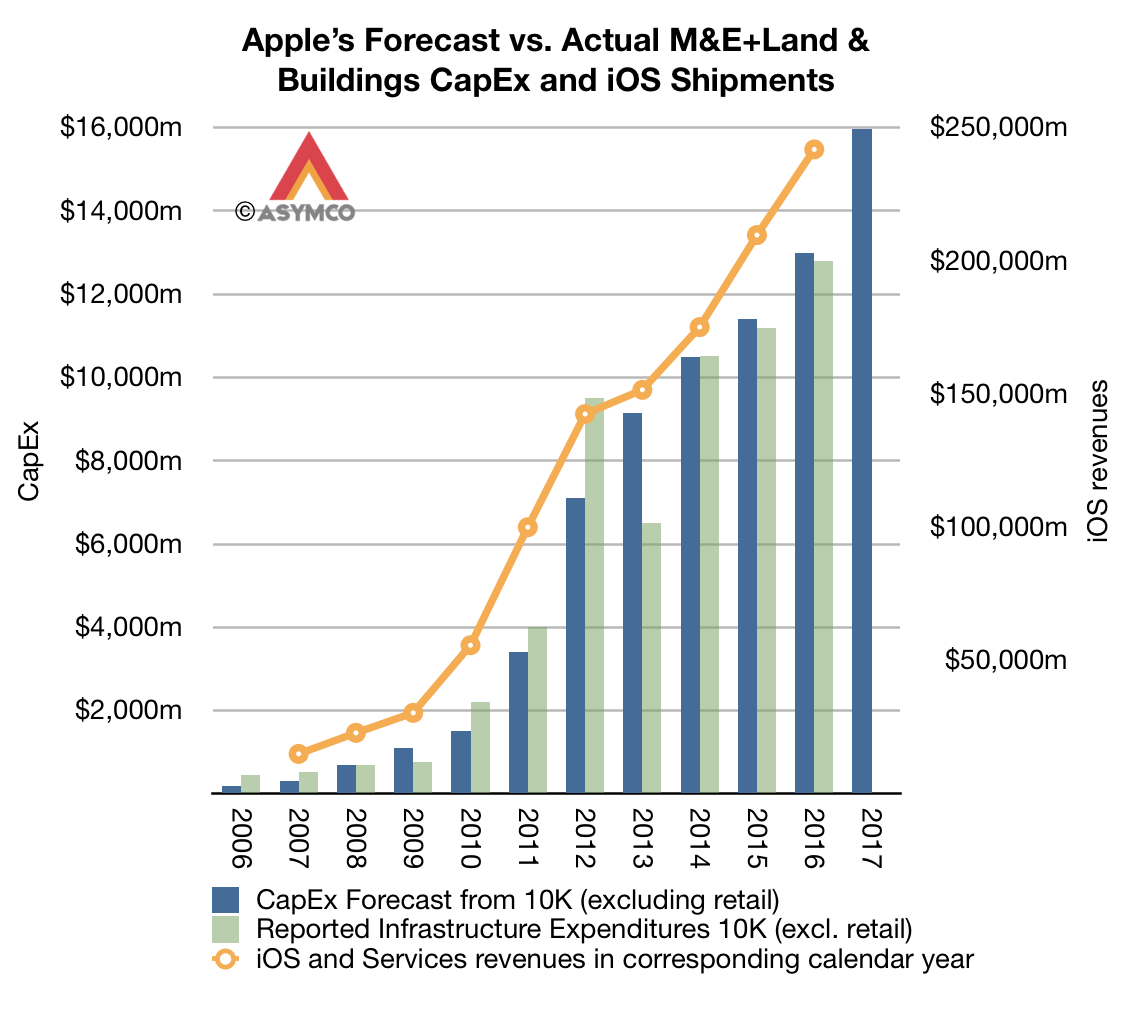
    Predicting Apple's yearly revenues has been fairly easy. The following graph shows the relationship between budgeted spending on Machinery, Equipment, Internal-use software, Land & Buildings and the shipment of iOS device revenues.

    The company conveniently publishes a full-year forecast of these expenditures every fiscal year so by October we know roughly how sales will be during the following year. This pattern has held for 10 years so there is little uncertainty about the 11th year of iOS devices.

    Although the two are not very tightly coupled, there is a causal link between them: spending on machinery and equipment for production leads to more production which leads to more sales (assuming prices are stable--which they are).

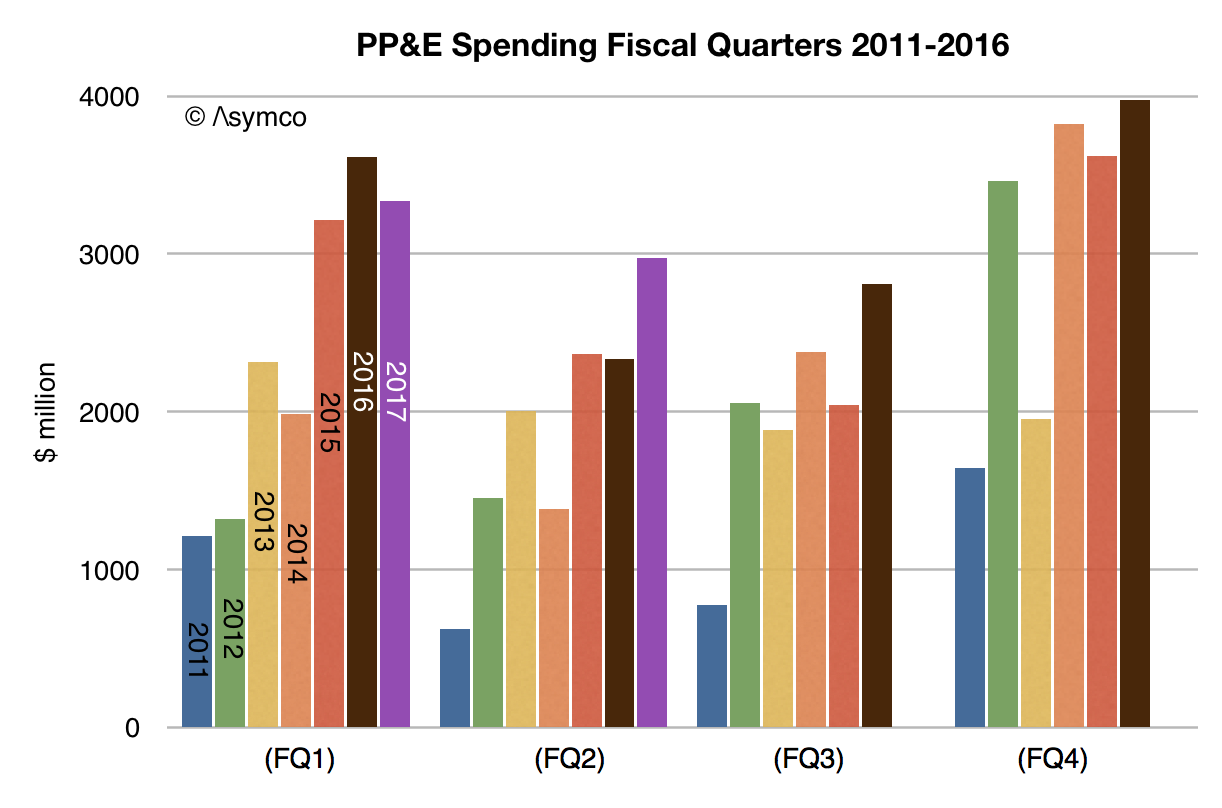
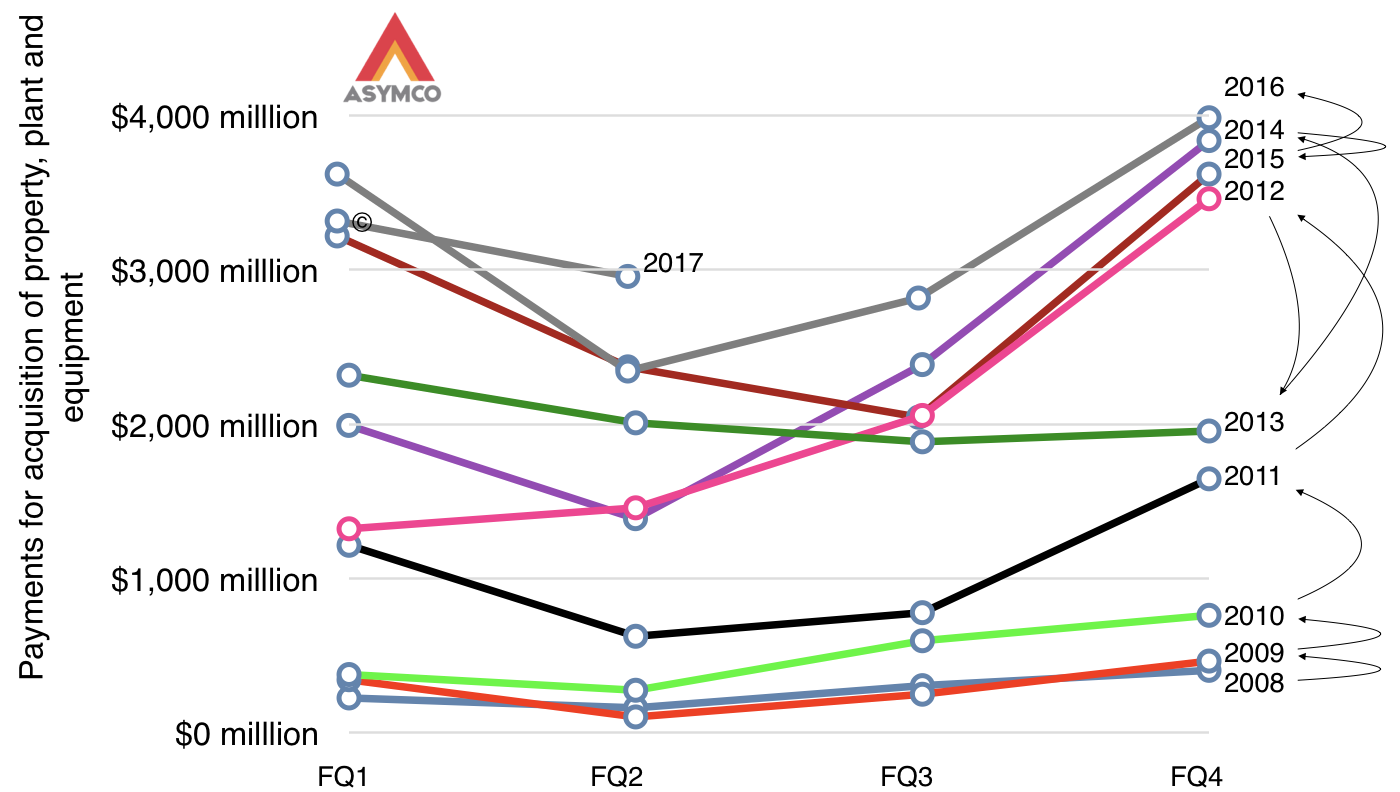
    We are, as of the time of writing, half-way through a fiscal year and the quarterly spending can be inspected for any surprises. None are evident as the second fiscal year (first calendar quarter of 2017) shows a new high in capital spending at nearly $3 billion, placing us on track for the surge into the production of the new iPhone (and iPads.)

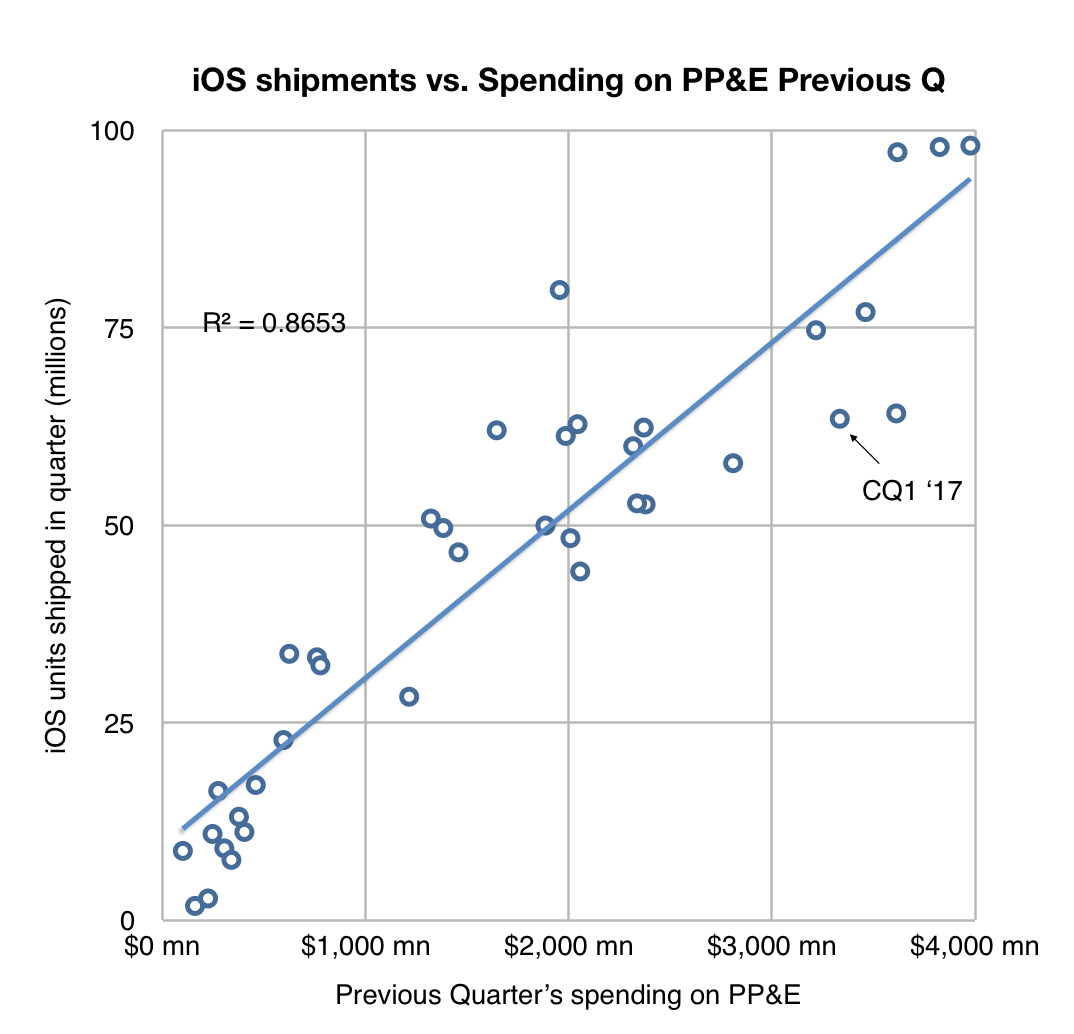
    The quarterly relationship between sales and spending is less precise as equipment buying is "front-loaded" into a production cycle but there is a strong correlation nonetheless.

    When looking through the data, quarter after quarter, year after year, there is a consistency and reliability to the spending/revenue relationship which implies, to me at least, a high degree of certainty.

    This predictability, however, has not detracted from the volatility in Apple's share price--an instrument designed to embody precisely this prediction.

    Apple's share price continues to see swings of more than 70% in any given 52 week period. In the latest 52 week period the shares traded between $89.47 and $154.88, a 73% swing.100% is not unheard of. Incidentally, S&P 500 volatility ranges around 45%. Apple is by far the largest company in the world and fairly old by large company standards. It should attract a certain premium of stability.

    And yet it doesn't. Skepticism around the company is continuously evident. It's in the headlines written every day which concoct convoluted reasons to doubt future performance. It's in the conversations I have with investors who question the tiniest of details in the design of a product (like headphone jack or home butto) in order to gauge their impact on the survival of the firm. It's in the continuous parade of "disruptive entrants" or "established giants" ready to knock the company off its perch by virtue of simply existing.

    Perhaps the panic it induces in investors with its reliable profits is Apple's most predictable attribute.

  6. Predicting The Second Quarter

    Research · 51 comments

    The last quarter of 2016 was Apple's biggest ever. $78.4 billion in revenues. 78.3 million iPhones. Both records. Earnings of $3.36 ((On shares priced at the time around $105 or 3.2% yield quarterly earnings)) and cash reached new highs. The growth was modest but Services is now not just the second largest revenue but also the fastest growing, on track to doubling in four years.

    The reason for this is the vastness of Apple's user base coupled with the loyalty the brand engenders. The company reached one billion active devices more than a year ago and is quite likely to have nearly a billion users. Not just any billion either--the best billion most probably.

    The realization that Apple benefits from extreme quantity and quality of customers has led some observers to defer the imminence of Apple's demise. Share prices have risen lately to new highs and the ratios between these prices and earnings have started to come closer to the average of other large companies.

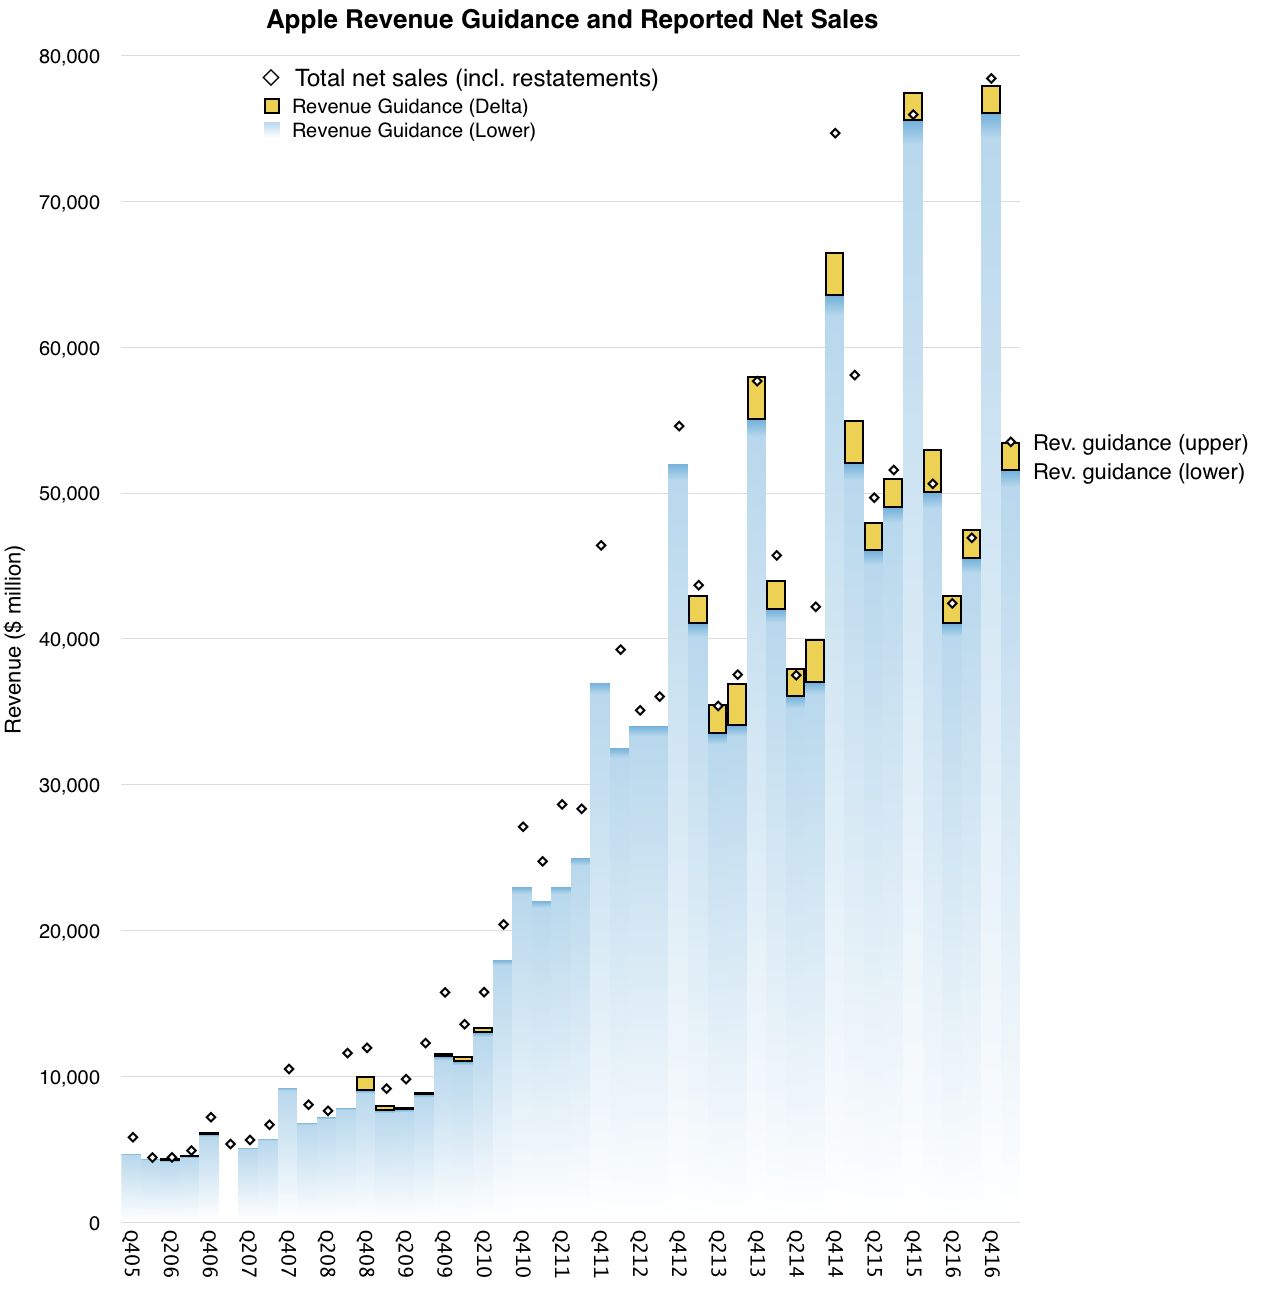
    But enough with the reductio ad absurdum. Let's look at the next quarter. The company has been very precise with its own offered predictions (guidance) so it's a simple task to make an accurate forecast. The history of guidance vs. outcomes for revenues is shown below:

    Placing the pipper on the upper edge of the guidance range was a safe targeting method for 11 of the last 17 quarters. We have never seen a drop below the bottom of the range but had a few overshoots, some huge. Doing this for the latest quarter and working backwards to the individual product contributions to revenue and using historical margin and cost patterns we can get the following core financial performance metrics:

    Fiscal Q2 2017:
    Rev ($B) 53.4
    EPS ($/share) 1.96
    iPhone (thousand units) 53100
    iPad (thousand units) 9900
    Mac (thousand units) 4100
    Watch (thousand units) 2300
    Services ($ million) 7129
    Other products ($ million) 2300
    Gross margin (%) 37.8

    I sent these estimates to Philip-Elmer DeWitt and I recommend looking at his survey of the other analyst estimates on his excellent Apple 3.0 blog.

    Overall, the quarter is shaping up to offer slight growth y/y and indicating a plateau formed after the surge from the iPhone 6 surge in '15. All eyes are on the "super cycle" for the next iPhone.

    The reason it's "super" is that the iPhone has a 2+ year cadence for form factor changes and the user base updates on a similar cycle. The demand is vast due to the user base and accumulated age of devices in use. Expectations are that supply will be offered to meet this demand.

    If history is a guide then the next iPhone will be the best iPhone ever.


  7. Contact Less

    Research · 21 comments

    In September 2016 Apple Pay came to support the world's largest public transit system. It happened through the integration with Japan's FeliCa and gave Apple Pay access to 160 million daily transactions.

    This, along with many other milestones don't get a lot of attention. Apple Pay is in what could be considered an attritional competition with non-consumption. There are no decisive battles won or lost, only the relentless pressure to make progress against a reluctance to change.

    Before I go on, I should make the attrition/decisive type of conflict clear. The terms come from military science. A war of attrition is one where two sides essentially grind against each other and the winner is the one which lasts longest. A decisive battle is one where a conflict is won through a single, acute encounter where, due to either demoralizing or circumstance reasons, one side gives up. It's the knock-out punch vs. the fight to exhaustion.

    When applying this dichotomy to competition, we need to be careful about who we define as competitors. Note that I said that Apple Pay is in a fight with non-consumption. It's tempting to say Apple Pay competes with some other payment system like Samsung Pay or Google Pay. But none of these alternatives are as powerful as the existing mix of contact payment systems: cash, credit card magnetic swiping and some other hybrid of codes and user experiences (especially online.)

    When seen this way the challenger must compete through persistence. It's impossible for Apple Pay to decisively defeat non-consumption in one battle. It takes literally millions of decisions for adoption: each consumer, each merchant, each bank, each point of sale. It's a relentless grind of pitching, selling, demonstrating and shaming into action.

    It's been three years of this type of competition and progress may seem hard to spot. That is because we don't see the big wins. We can only see small wins. The win in Japan, as significant as it might be (160 million daily transactions added to the addressable market) is still small compared to all transactions world-wide.

    Merchants tell Apple that 90% of contactless transactions in the US were Apple Pay. Apple sees continuous growth and cited 500% grown y/y in payments last quarter. The total amounts to hundreds of millions of transactions worth billions of dollars.

    Anecdotally, the points-of-sale supporting the system are growing. 76% of the top US merchants have agreed to deploy by end of this year. ((Note that that does not mean 76% of all points of sale will have it but rather the commitment at the top is there.))

    But the total market is probably measured in billions of transactions and trillions of dollars. There is a lot to go.

    On the bank side, the US wins came quickly and thoroughly. 3500 US banks support Apple Pay through their issued credit cards. Globally the figures are unstated with some countries absent completely and others engaging quickly. Australia lags while the UK is mostly on-board.

    The point of sale terminals are also largely not an obstacle with the current generations almost all being able to process contactless transactions. The amazing thing about this business is just how many sides there are to this market: merchants, users, Apple, banks, POS terminals, credit card companies, online payment systems, etc.

    To see progress at all is surprising. Changing payment systems is extremely complicated due to the breadth and depth of infrastructure. There are already 5 million contactless acceptors in the US. But there are many more points of sale ((How many exactly is actually hard to determine.)) There is a long tail distribution for these systems so saturation will take a very long time.

    Apple Pay is however only the first battle. Beside credit cards and cash, inside your wallet are more items that need to move into your devices: access cards, passports, driver's licenses, IDs.

    One unsung hero has been the device-based boarding pass. Security and gate agents don't touch your phone so when you are invited to place the phone on the scanner at security or boarding, there is a sense of tangible and visible progress.  It was a rare sight a few years ago but I see it more and more each day I fly. The paper-less boarding pass has crossed the chasm into mainstream. Cash, plastic cards and IDs will also be deprecated. All it takes is persistence and time.

    We all crave decisive battles and can't stay tuned for the attritional outcomes. Nonetheless that is how most conflicts end up. This is the sort of conflict where a superpower wins and an asymmetric challenger falters. It's resources and processes rather than enthusiasm that matter most.


  8. iPad Optics

    Research · 33 comments

    The iPad has an installed base of over 300 million. This is a far larger audience than that of the Mac (which has somewhere between 100 million and 150 million). And whereas the iPad acquired this audience in about 7 years, the Mac took 33 years.

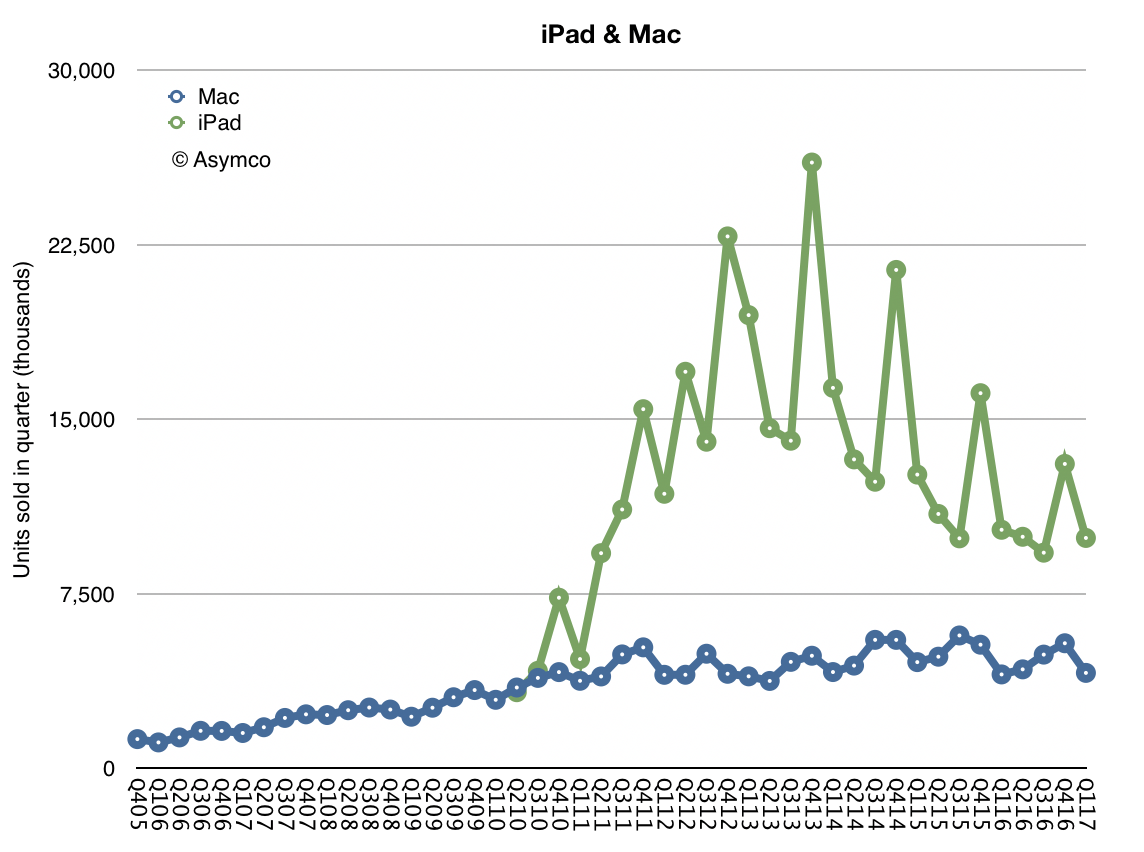
    Curiously however, it is the iPad that is seen as the more fragile product. The iPad is considered to be failing, with a presumption of an end of life in the near future. The evidence of this failure the year-on-year decline in units sold. This is illustrated by the following graph. 

    Screen Shot 2017-03-23 at 10.05.21 PM

    Note that the iPad decline is paired with a steady increase in the Mac. The iPad exhibits a four year decrease in overall volumes. This has, as they say, bad optics.

    But what is seen isn't all that might be,

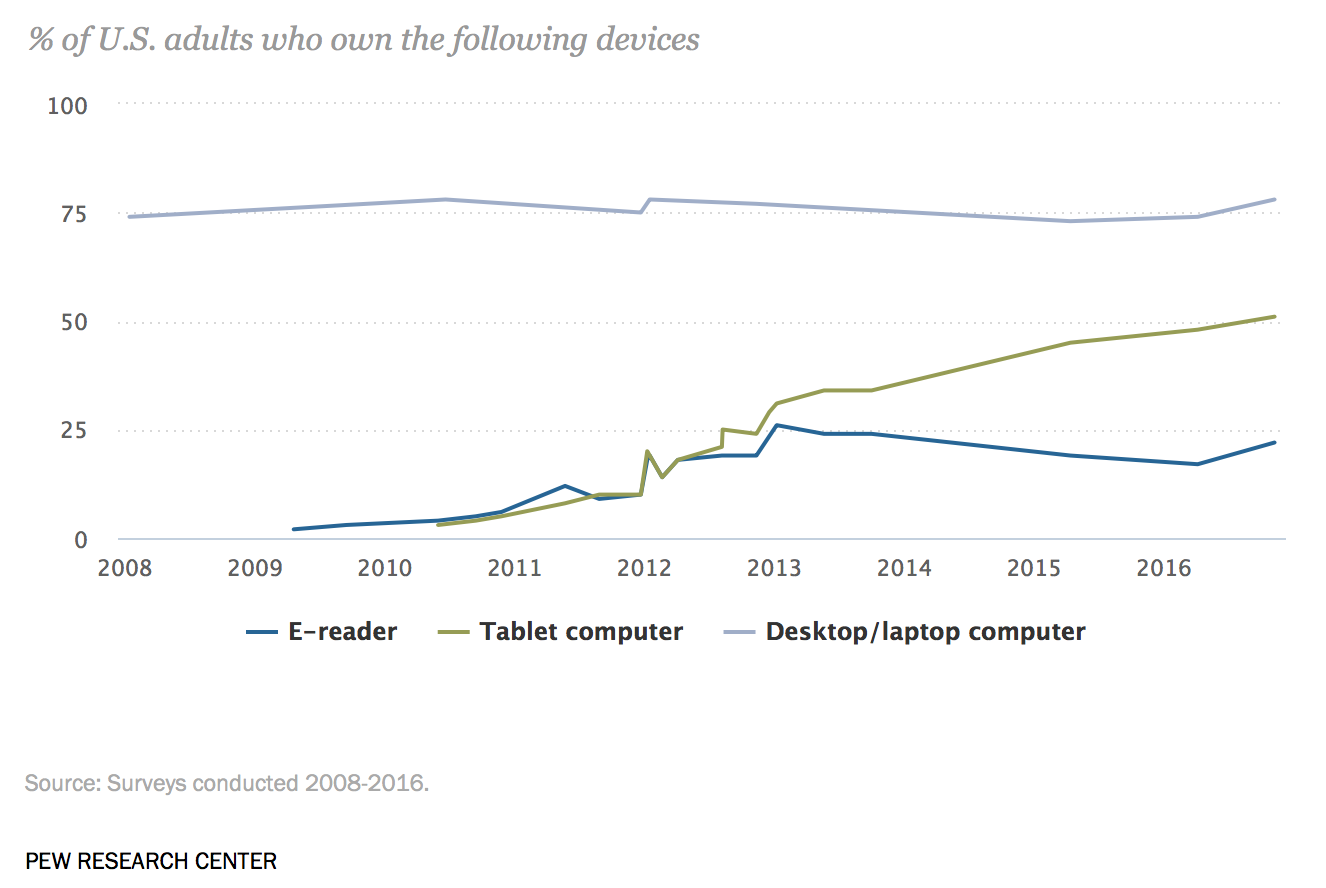
    If we look further we see that the iPad is still a much loved and much used product. Data from the Pew Internet Survey shows that tablet ownership among US adults increased from 45% in April 2015 to 48% in April 2016 and 51% in November 2016. The rise has been steady. Although this counts tablets, the iPad had 85% share of the U.S. market for tablets priced above $200 so it's a fair assumption that the iPad audience is growing. Similar data exists for the UK.

    Screen Shot 2017-03-23 at 10.11.50 PM

    In addition, user satisfaction with the product continues to be very high. Apple cited that in November, 451 Research measured a 94% consumer satisfaction rate for iPad Mini, a 97% rate for iPad Air, and 96% for iPad Pro. Finally, browsing, shopping and app usage data also show continuing high utilization for iPads.

    Furthermore, iPads are still growing in "non-consuming" markets. iPad posted double-digit growth in both Mainland China and India, it continues to attract a very high percentage of first-time tablet buyers.

    Finally, within corporate buyers there is a 96% satisfaction rate with 66% purchase intent. Apps and solutions are continually being developed for the platform.

    Taking into account that the iPad has a large, stable, engaged and loyal user base that continues to expand and find new uses the optically bad sales data needs an explanation. The simplest explanation is probably the best: iPads remain in use far longer than phones, and perhaps even longer than some computers.

    Anecdotally we can see evidence for this. Few iPads are replaced every two years the way phones are. They are not tied to service contracts or subsidized. They are also less likely to be damaged during usage as phones are dropped and banged-up. iPads are more stationary or carried in protected containers. Phones are in pockets, iPads are in bags.

    So iPads are longer-lived products and it's perfectly reasonable that people who have them keep using them and more people are joining them but slowly. Note also that the decline in sales seems to be flattening out and perhaps might show stabilization.

    Further countering of the iPad in decline idea is the continual improvement in the product. The latest is a refresh of the iPad with more battery life, a better screen and support for Pencil.

    Perhaps the iPad will not return to rapid growth, or perhaps it will. But the more likely possibility is that the iPad will level out maintaining steady levels and, perhaps, grow slightly. This flat rather than up/down trajectory is unusual in devices but it isn't when you look at the Mac. And isn't the goal of the iPad to become a computer?  If so then perhaps Mission Accomplished.


  9. Gravity

    Research · 39 comments

    Apple is doomed. So are you. As mortals we are used to the idea of death. We do not dwell on it even though it's inevitable. We do know that we'll die but what we don't know is when we'll die. That certainty/uncertainty makes us, more or less, do everything that we do. And so we carry on. But companies die too. And when they die is also a mystery but it's not at all clear that their inevitable demise determines what they do. If you think you're immortal you may live dangerously. Perhaps as a result they live shorter lives than we do.

    Life expectancy for humans has been rising but for companies it has been declining. Even more curiously, the richer you are the more likely you are to live longer but the wealthier a company, the more likely it is to keel over at any time. The longest lived small businesses live over 1000 years but the longest-lived large business is probably the East India Company that made it to the ripe age of 274. But that was before 1800.

    In the modern, industrial era there are very few corporations that survived over a century and the Fortune 500 shows a turnover in inhabitants that resembles that of a plague-infested medieval inner-city. In contrast to their conservative, geriatric organic owners, synthetic companies are more likely to behave like live-fast, die-young punk rockers.

    So it's no surprise that Apple, at age 40, is seen as being well past its sell-by date. And yet it seems to be saying, somewhat faintly, "I'm not dead yet". By generating more cash than can be comprehended by human observers and by controlling assets that are well beyond the means of many countries, they (it?) is confusing us with its persistence.

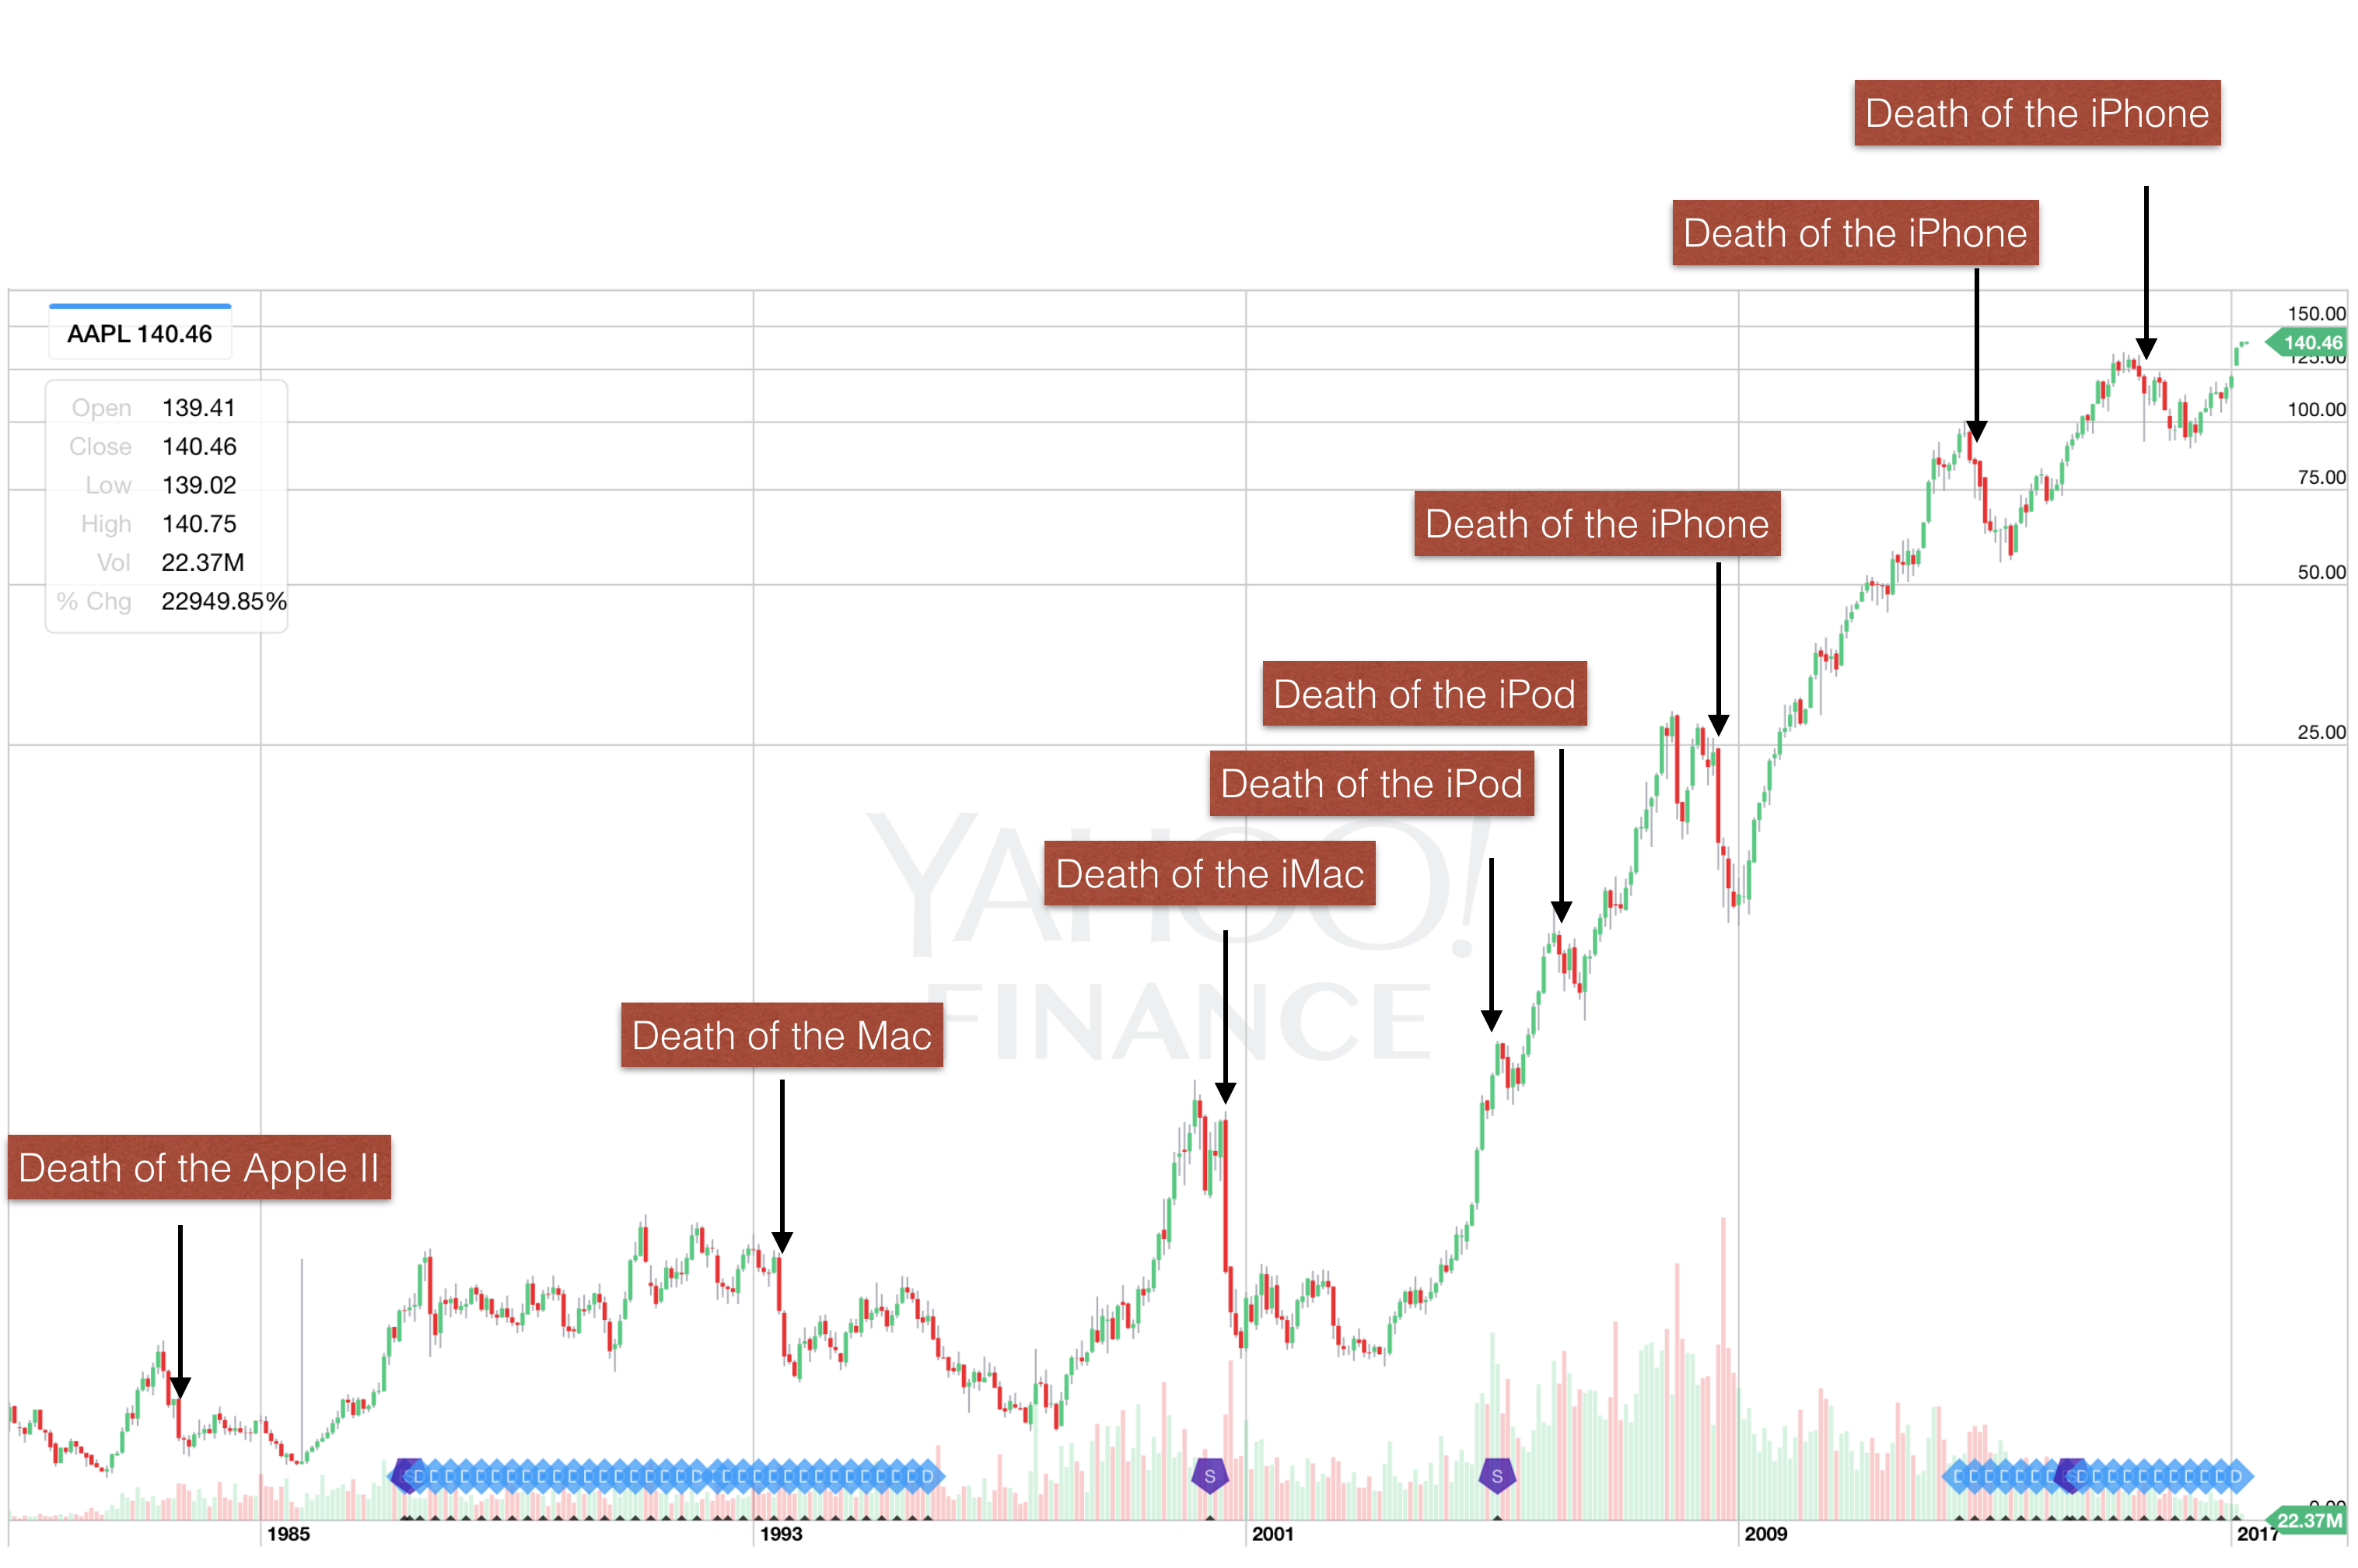
    The confusion is exhibited in the following graph which shows the crises in confidence by that wonderful reflector of human perception--the stock market. By voting millions of times a day, the market shows us with great precision the totality of human emotion with regard to an asset. That emotion turns rapidly negative on Apple with surprising frequency.

    Screen Shot 2017-03-16 at 2.32.03 PM

    There have been over 8 bouts of collapsing confidence (exhibited by 40% drops in value) for Apple's shares. Consider the latest where we've seen a 40% drop followed by 57% increase in share price over the last 12 months. 57% might not seem extraordinary for a small company but for the world's largest market capitalization with the corresponding colossus of cash that it straddles, the robustness of brand and the loyalty of customers, the mind boggles.

    The same thing happened in 2012 and 2008 and as far as I can tell the company has not changed one iota during that time. The same people, mostly, are in charge. With the same mission statement, and even the same product line. The resources, processes and priorities--the only determinants of the essential value of a firm--have not shifted.

    One could try to suggest that even if Apple is unchanged, the world around it has changed. But if anything the world has come to match Apple's own view: more mobile vs. fixed, more design vs. generic, more integrated experiences vs. more modular DIY.

    The ethos of Apple is rigid so why is perception about the company so fickle?

    If the graph above reflects perception about a constant entity then perhaps it charts how the world has changed rather than how Apple has. Perhaps perception revolves around a center of gravity far heavier and permanent. Perhaps the tug-of-war between fear and greed reflects more upon us that it does upon the object being observed.

  10. The First Trillion Dollars is Always the Hardest

    Research · 61 comments

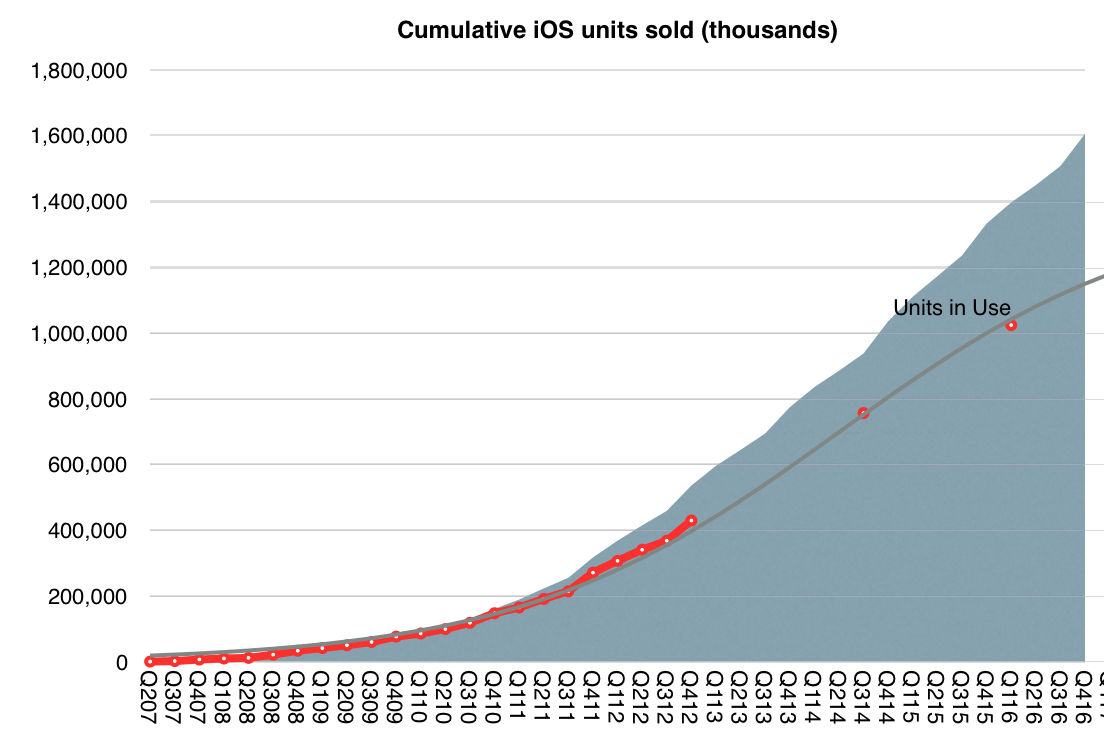
    In its first 10 years, the iPhone will have sold at least 1.2 billion units, ((Includes forecast for first six months of 2017)) making it the most successful product of all time. The iPhone also enabled the iOS empire which includes the iPod touch, the iPad, the Apple Watch and Apple TV whose combined total unit sales will reach 1.75 billion units over 10 years. This total is likely to top 2 billion units by the end of 2018.

    Screen Shot 2017-01-11 at 10.15.00 PM

    The revenues from iOS product sales will reach $980 billion by middle of this year. In addition to hardware Apple also books iOS services revenues (including content) which have totaled more than $100 billion to date.

    This means that iOS will have generated over $1 trillion in revenues for Apple sometime this year.

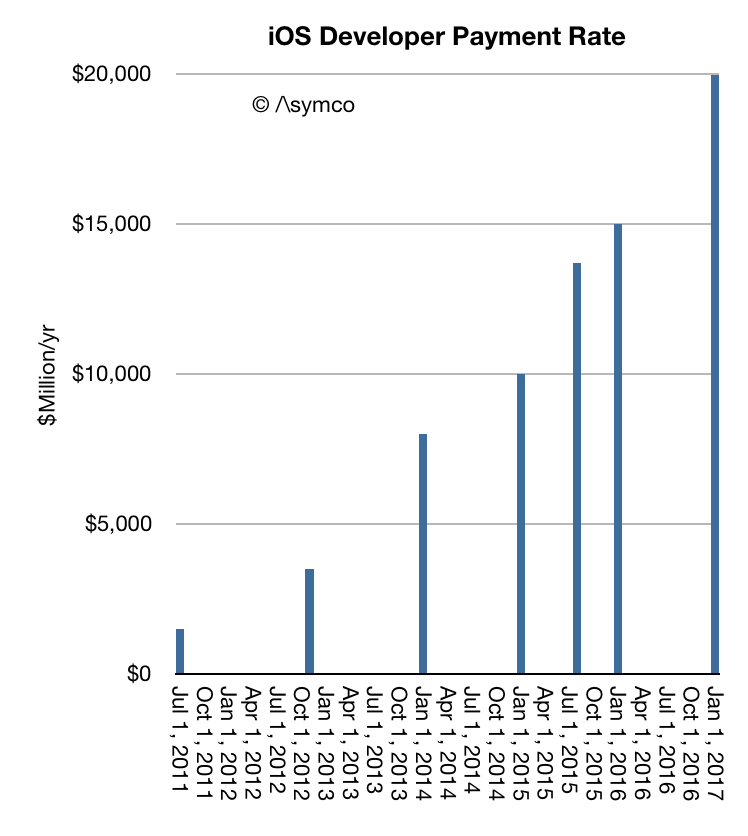
    In addition, developers building apps for iOS have been paid $60 billion. The rate of payments has now reached $20 billion/yr.

    screen-shot-2017-01-11-at-9-41-29-pm

    Not included in this payment total are "mobile-first" or "mobile mainly" businesses such as FaceBook, Twitter, Linkedin, Tencent, YouTube, Yahoo, NetEase, Pandora Radio, Google Search, Baidu, Google Maps, Gmail, Instagram, Amazon, eBay, JD.com, Alibaba, Priceline, Expedia, Salesforce and Other Enterprise Software, Ride Sharing Apps, AirBnB and many other services which monetize independently of the App Store.

    I estimate that the cumulative revenues enabled by iOS across these businesses have exceeded $500 billion, with a rate of revenue soon to reach $300 billion/yr.

    The revenue numbers can only hint at the change in behavior among users. An iPhone is unlocked 80 times a day. Assuming 600 million devices in use there are 48 billion sessions on iPhones every day. 17.5 trillion sessions every year. It is these instances of interaction and engagement which are desired by all businesses built on top of the ecosystem.

    These instances of engagement must be multiplied by the quality of the customers which Apple captures. iOS users spend more and are more loyal than those on alternative platform thus qualifying the platform as "premium" and thus adding to its value in the eyes of developers, content producers and service providers.

    As the install base of iOS increases and as users hire the devices to do more and spend more time with them the virtuous cycle of value creation will continue and accelerate.

    There is a temptation to think that such a business is fragile and will be disrupted. Challengers appear daily and the number of iPhone "killers" is not measurable. One can cite the billion users of Nokia phones which defected. One can cite the loyalty of BlackBerry users that evaporated. One can even cite the juggernaut of Windows and how it became impotent. One can cite the vast number of Android devices offered at low prices.

    But there are reasons to believe that the iOS empire is far stronger and resilient.

    Unlike Nokia's phones, Apple's product is an ecosystem with network effects and dependencies on software and services. It's also a monolithic product with a singular interface and form factor.

    Unlike BlackBerry, the iPhone does many jobs--too many to count. Indeed the iPhone evolves and changes its core value over time.

    Although different in many ways from Windows there are strong similarities in terms of loyalty and persistence of users. iOS even developed a dominant position in enterprises. Microsoft's attempt to become a hardware company is a testament to the confluence of the two business models.

    And whereas Android was originally seen as the "good enough" iPhone, potentially disrupting it, it turns out to be the ersatz iPhone. Chances are higher that users will switch from Android to iPhone and not the other way. Again, the reasons have more to do with the ecosystem and quality of users (which are hard to measure) than with the hardware (which is easy to measure.)

    As we look toward the second decade of the iPhone, the expectation isn't one of another "big bang" but a process of continuous improvement. The market is nearing saturation so the goals must be to capture more switchers from Android. Apple has achieved this with the Mac: survival, persistence and eventual redemption.

    More exciting is the apparent expansion of a network of ancillary "smart" accessories. The Apple Watch, the AirPods, Pencil and possible new wearables point toward a future where the iPhone is a hub to a mesh of personal devices. The seamless integration of such devices is what has always set Apple apart.


  11. The Genealogy of the MacBook Pro

    Research · 18 comments

    I was an early user of the first MacBook Air. When that product was launched I saw in it something different: a dedication to a new measure of performance: thinness and conformability. The key image used to launch the Air was the laptop sliding neatly into an inter-office envelope. The implication was that the laptop does not need to have its own special "laptop bag". It could fit into any bag. Users would be able to slip it into all manner of new contexts. It sought to compete with computing non-consumption.

    The Air was launched by Steve Jobs in 2008 and was almost universally panned. It was considered underpowered and the dedication to thinness was seen as irrelevant to what consumers wanted. The stock price fell.

    The product went on to become Apple's most popular laptop. It still is. It grew the base of Mac users to over 100 million today.

    For the same reason, I was an early adopter of the newest MacBook Retina. The even thinner new MacBook was spectacularly thin. It was smaller than an iPad. It had no ports except one USB-C and a headphone jack. It required dongles for physical connections. It had a new keyboard that barely registered movement and it had a new trackpad that did not move at all but played mind tricks to make you think it did.

    As I used it over the last year, I became used to it. It was not my only laptop. I had an older 15 inch Pro, but over time I came to use the MacBook Retina exclusively. I thought I could not do "real work" with it but I managed. I got used to the keyboard. I got used to the trackpad. I got used to the need for a dongle to connect a display. But these challenges were more than offset by delightful improvements. I was delighted by the small power brick and the ability to use any USB power to charge it. I was delighted at the all-day battery life which meant I would charge it the way I charged my Phone: at night.  I was delighted that I could use it in places where I could not use a laptop: on any airplane tray, stowing it in the seat back pocket. And I no longer cared what bag I had for my computer. It did not make me productive by completing tasks more quickly. It made me more productive by letting me be do things when and where I otherwise couldn't. I love my MacBook.

    Now Apple launched a new Pro Mac laptop.The new Pro laptop has the same (slightly improved) keyboard as my MacBook. It has the same (larger) trackpad as my MacBook. It has the same (but more of) USB-C port.  It has something new called a Touch Bar which puts function keys into a touch screen but mainly it feels like a grown-up version of my MacBook Retina. It's faster too.

    Overall, the new MacBook Pro feels to me like an evolution of the MacBook of 2015. I remember at the time thinking that this baby MacBook is probably the wave of the future: the new keyboard, new trackpad, new thinness, new USB-C, deprecation of other ports. These required enormous engineering efforts and it would be silly to leave them on only one model. In any case, from where I was standing all these were "better". Not along the previous definition of goodness but along a new definition: making the computer more conformable and easier to put into use in more places. The very ideas that drove the development of the Air of 2008. Indeed the very idea that drove the development of laptops since the 1990s.

    What's fascinating to me from a product management point of view is that the groundbreaking new features which re-define the product's direction are not designed to trickle-down from the top-of-the-line to the bottom, but rather that they trickle-up. The low-end product gets the updates first and the the Pro products adopt them later.

    And we can even trace this genealogy of features through to an even "lower-end" product: the iPhone. The iPhone "ethos" of usability and conformability has permeated through to the Macs, starting from the lowly and advancing to the top of the range. The question of where Apple's design direction comes from can be answered: the bottom.

    All this is consistent with a strategy of "low-end evolution". A way to defend the low-end rather than abandon it in pursuit of what the most demanding customers are asking for. Rather, Apple seeks to incubate a new performance measure. Re-defining goodness.

    So is this new MacBook Pro a worthy successor to the MacBook Retina? My attention is riveted by the Touch Bar. It seems a completely new way of interacting but requires discovery and practice. What Apple has to achieve is allow the product to work well without it but also to allow users to evolve their experience with it. Over time we got used to trackpads instead of mice (many resisted the change). We got used to a different, small travel keyboard. We got used to new ports (HDMI vs. VGA) and we got used to wireless everything (it may seem easier, but remember having to always enter credentials vs. plugging in a cable).

    The touch bar is a new UI metaphor. It will take time but it is looking at me right now, winking.