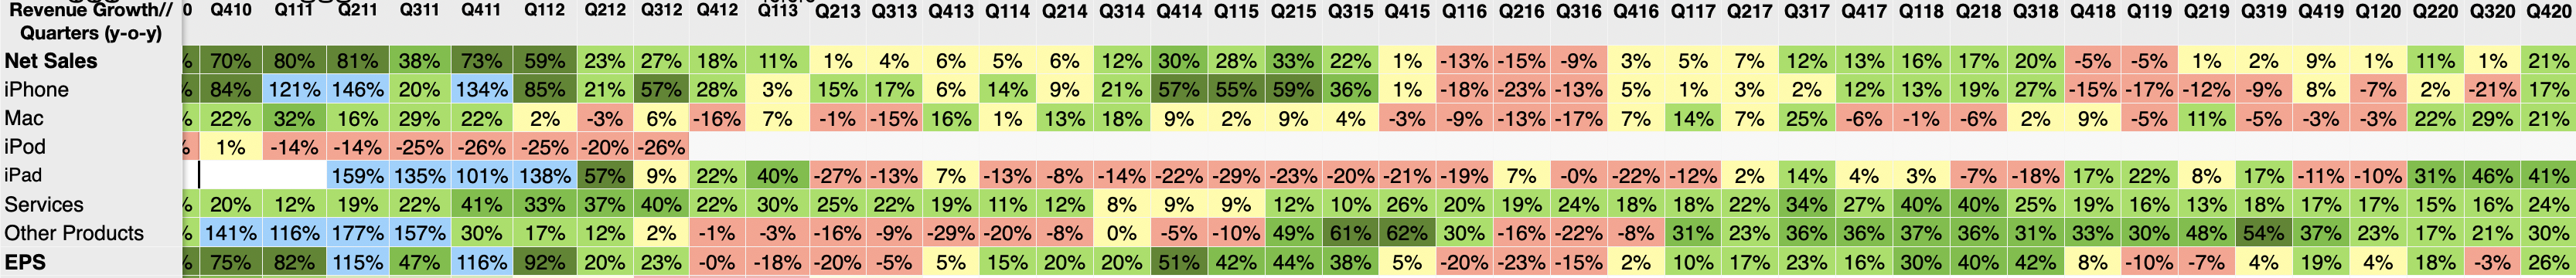
The last quarter of 2020 was a remarkable quarter for Apple. Every line in the income statement increased by double digits. Net sales up 21%, iPhone sales up 17%, Mac sales up 21%, iPad up 41%, Services up 24% and Earnings Per Share up 30%. This had not happened in over 10 years. The last time being the first quarter of 2010.
Take a look at the table below which color-codes each line based on the rate of growth. The darker the green the faster the growth (blue being above 100%).
A shockingly good performance is made all the more remarkable by its happening in a time of uncertainty. The company has refused (rightly) to issue guidance as long as a pandemic is raging world-wide. The disruptions in supply chains, demand and changes in behaviors due to new limitations on mobility and interactions between people are unprecedented and consequences are still to be estimated.
The growth surely, you say, is precisely because of this disruption. The "work and study from home" and lockdowns have forced people to buy more technology. Phones, Laptops, tablets are not just tools but lifelines for a society denied other forms of contact.
But this was not at all obvious at the beginning of the crisis. The months leading to pandemic caused the share prices of most equities to fall, and tech was not immune. Apple's shares fell in March 2020 to $57/share. I heard comments suggesting that Apple would collapse as a business with unemployment reaching 25% and nobody willing to pay for luxuries like iPhones.
The crisis has proven that technology is not a luxury but a necessity, and technology that works better is far more valuable than technology that works barely. Spending on better machines has increased.
Some of that is of course helped by stimulus programs but growth was not only in countries which gave out cash. The growth for Apple was in all regions of the world, breaking new records even in poorer countries.
Far more likely, the economic fuel for Apple's growth came from disposable income being unspent on other high-ticket items like dining, vacations and entertainment. Much cash sloshing around the economy surely ended up in an Apple cash register.
But this is all old news. The question into 2021 is what will this year look like. The first quarter already ended and the data is dribbling in: Apple has 1 billion customers, 88% of US teens have an iPhone, 70% have AirPods, China is growing at crazy rates, Foxconn reporting 40% growth, production of next generation iPhone chips starting early (May), etc.
There does not seem to be a let-up in growth, despite some component shortages postponing some non-iPhone product introductions. Apple's cautious comments 3 months ago are probably moot now.
We are providing some directional insights assuming that COVID-related impacts of our business do not worsen from our current assumptions for the quarter. For total company revenue, we believe growth will accelerate on a year-over-year basis and in aggregate, follow typical seasonality on a sequential basis.
At the product category level, keep in mind two items: First, during the March quarter last year, we saw elevated activity in our digital services as lockdowns occurred around the world, so our services business faces a tougher year-over-year comparison; second, we believe the year-over-year growth in the Wearables, Home and Accessories category will decelerate compared to Q1.
As you know, we were chasing demand on AirPods last year as we expanded channel inventory from Q1 to Q2. This year, we plan to decrease AirPods channel inventory as is typical after the holiday quarter. We expect gross margin to be similar to the December quarter.
We expect opex to be between $10.7 billion and $10.9 billion. We expect OI&E to be up around $50 million and our tax rate to be around 17%.
Luca Maestri
Given this, I am tentatively projecting top line growth of 15% (vs. 1% a year ago and 21% last quarter) and EPS growth of 11% (vs. 3.8% year ago and 25.6% last quarter.) A goldilocks quarter.
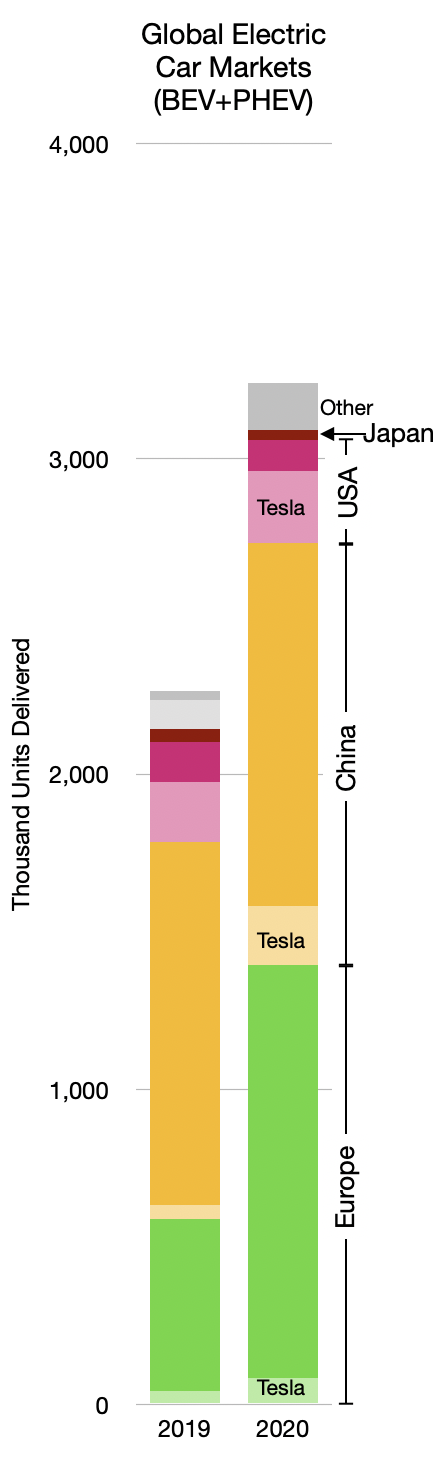
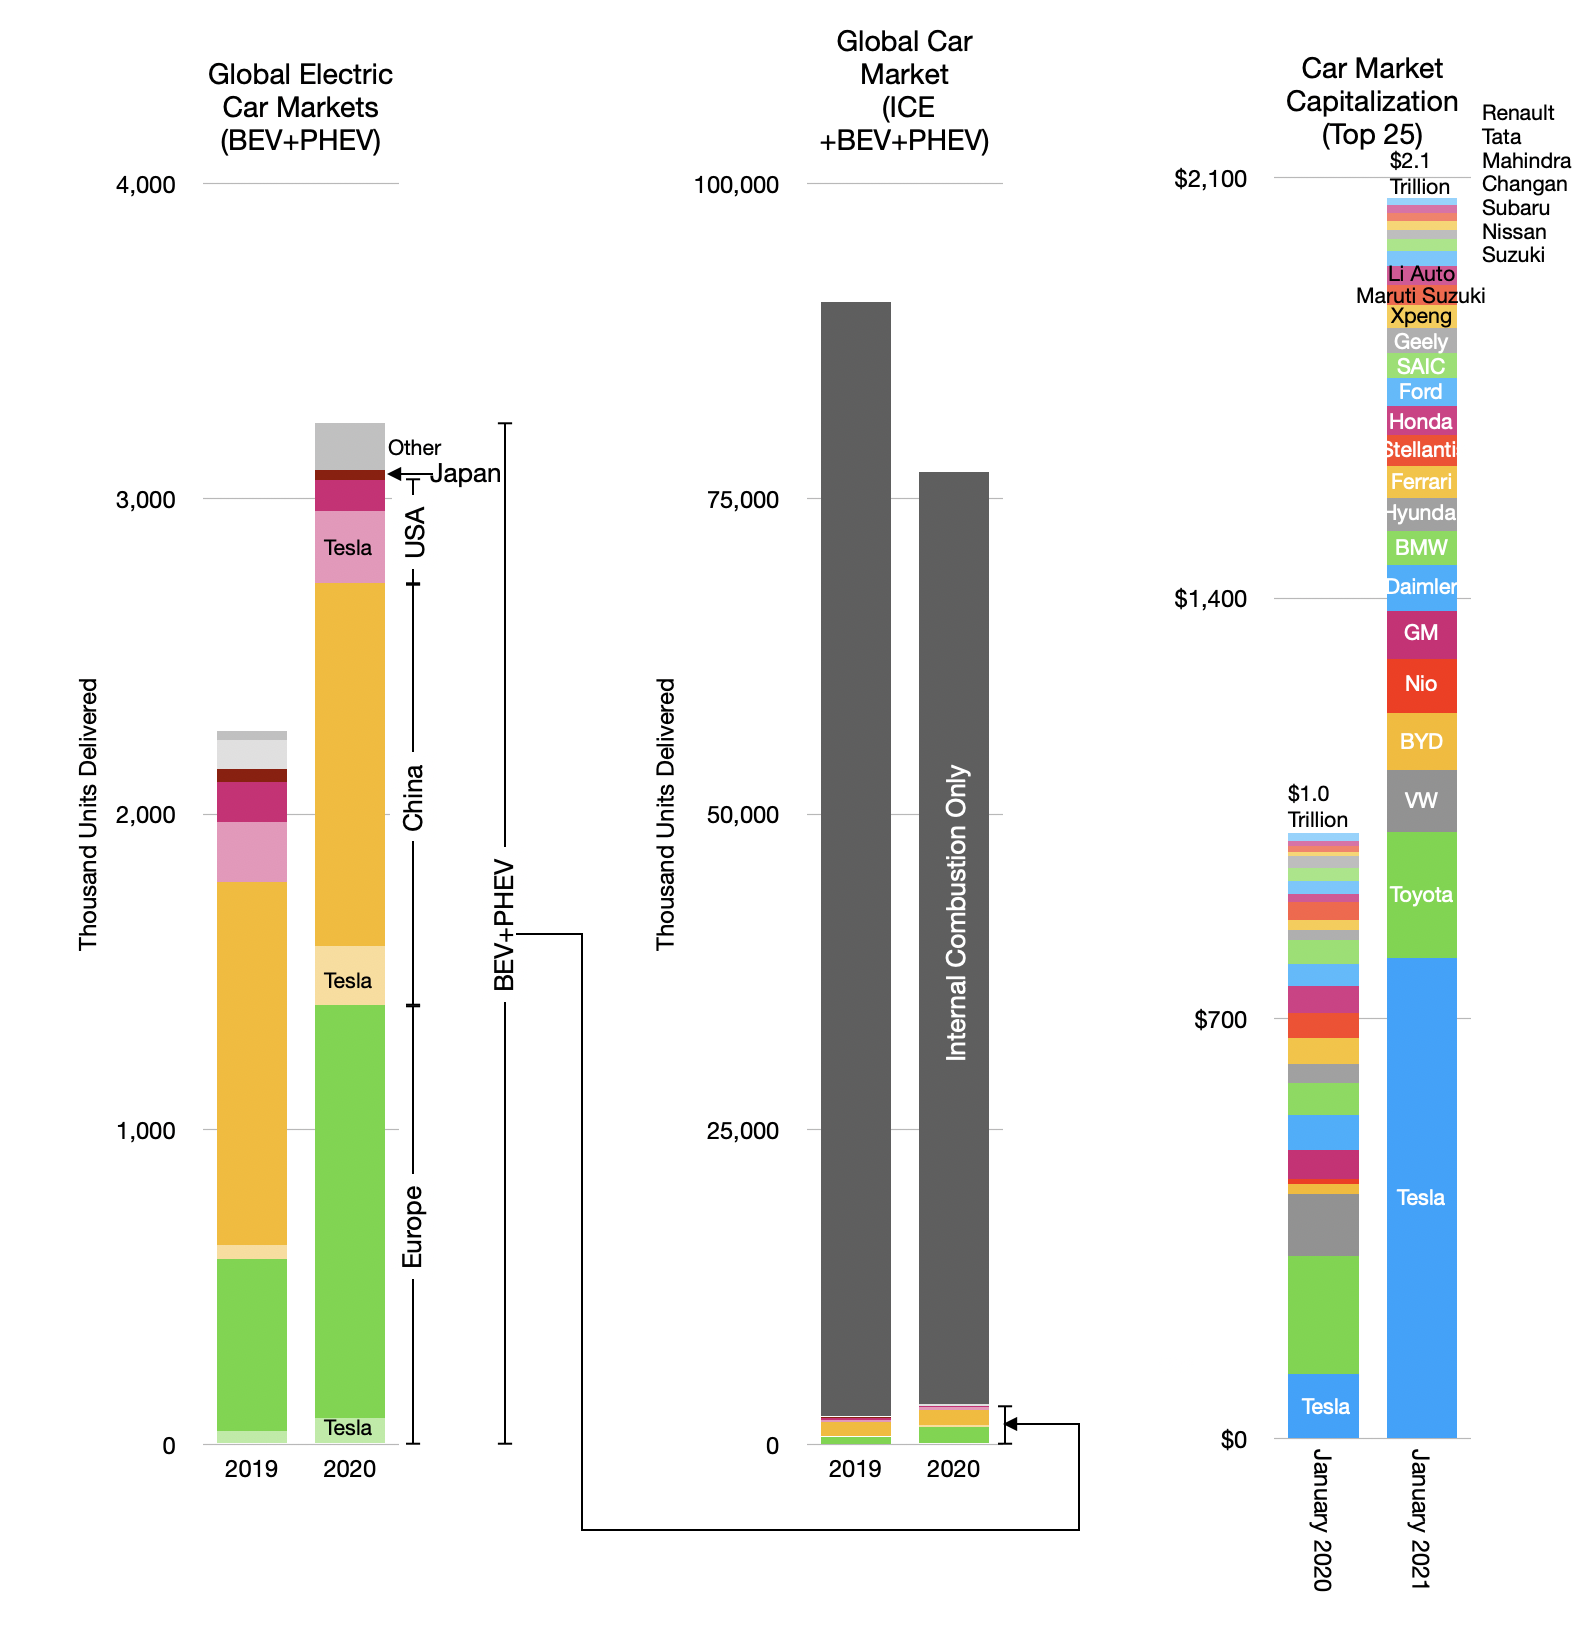
The EV car market is booming. The graph below shows the global market for plug-in electric cars (plug-in hybrid (PHEV) and battery (BEV)--BEV are about 70% of total). The data is split between 2019 and 2020 with further distinction between the main regions.
EV (PHEV+BEV) units sold 2019, 2020 by region.
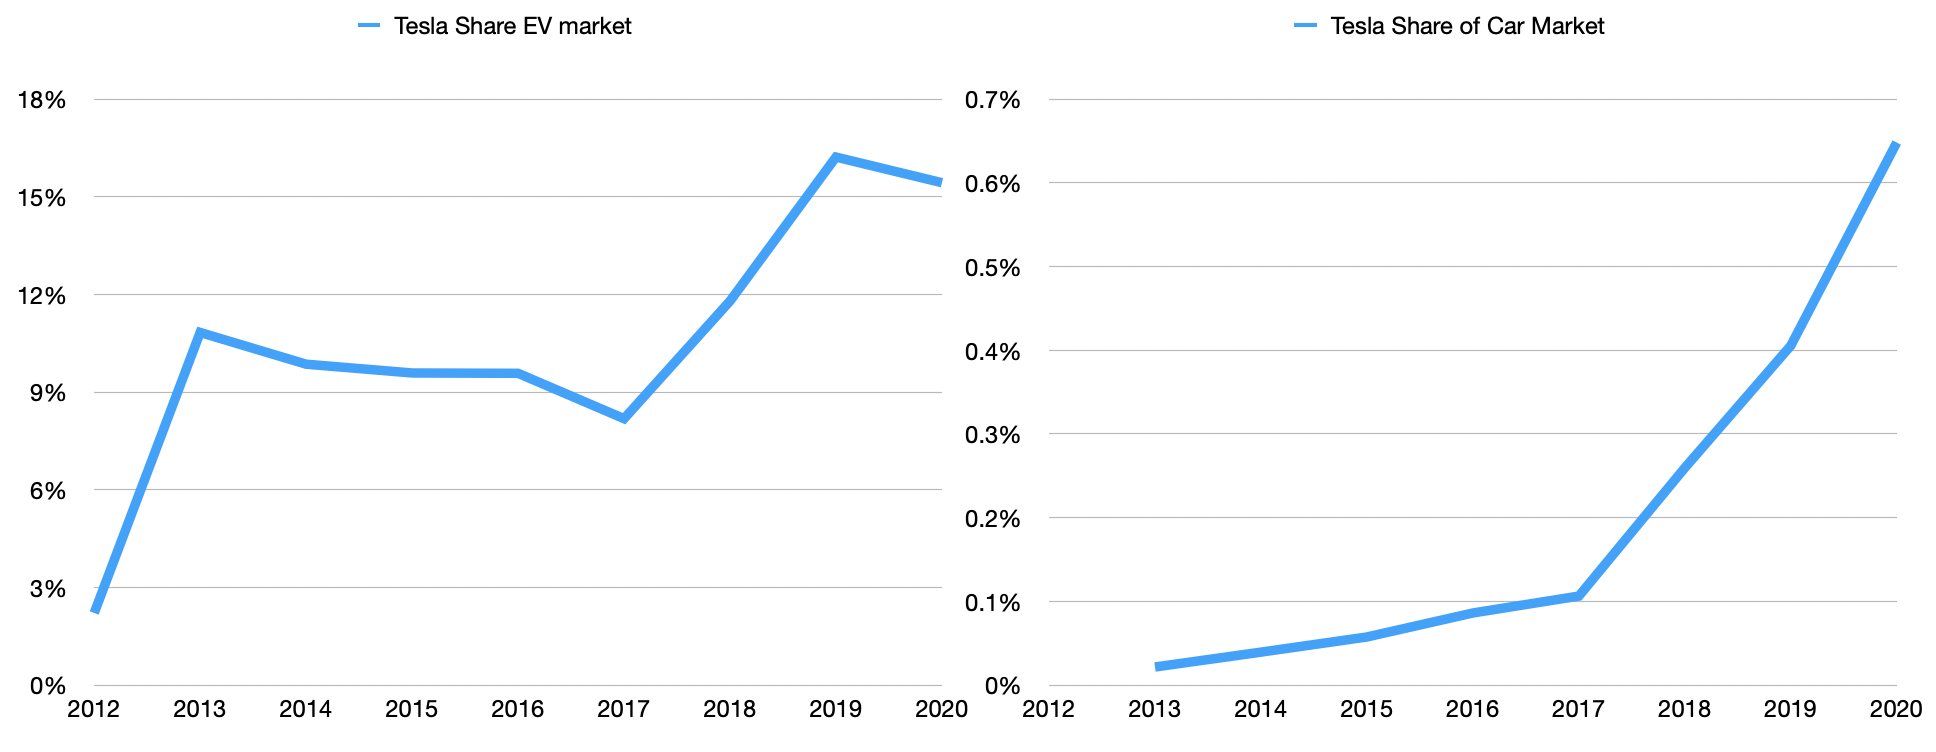
There is an additional detail in the delineation of Tesla's shipments into these regional markets. To that point Tesla's market share of all EV cars has remained roughly equal from 2019 to 2020.
Tesla share of EV car market and share of all cars.
The big story of 2020 was the growth of European EV shipments. Those who follow the market know that new EU penalties for CO2 emissions have come into effect, causing much of this increase. Indeed, previous surges in the US and China have also been driven by new incentives and/or disincentives.
As an aside, it should be noted the absence of Japan from this EV story. It's quite a shock, really. Japan is responsible for a large percent of all cars sold through its national heroes Toyota, Nissan, Honda, Mitsubishi (and Subaru, Suzuki, Mazda, Isuzu) and has been a driving force for innovation. The absence of a local market for EVs is a glaring indicator of lack of industrial policy. Unlike the US, Japan does not even have an oil industry, importing all its supply (while the US is a net exporter.) Yet the US produces and consumes far more EVs than Japan. This should give pause. One wonders what would happen if Japan followed Europe in providing incentives for EVs in the "JDM" market.
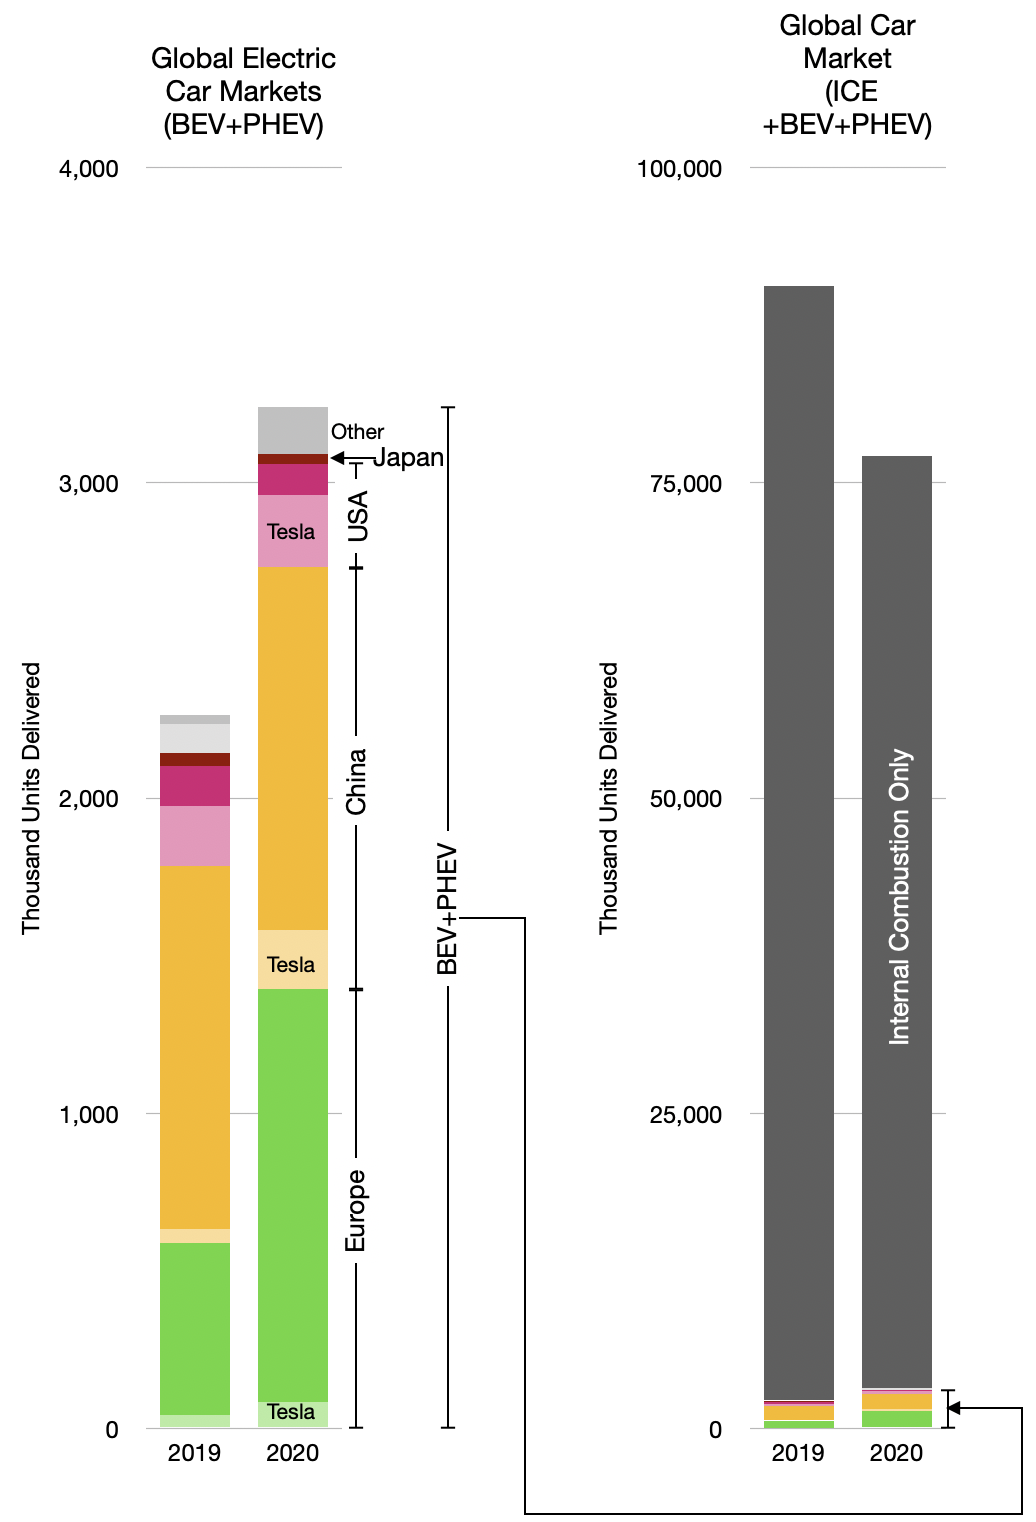
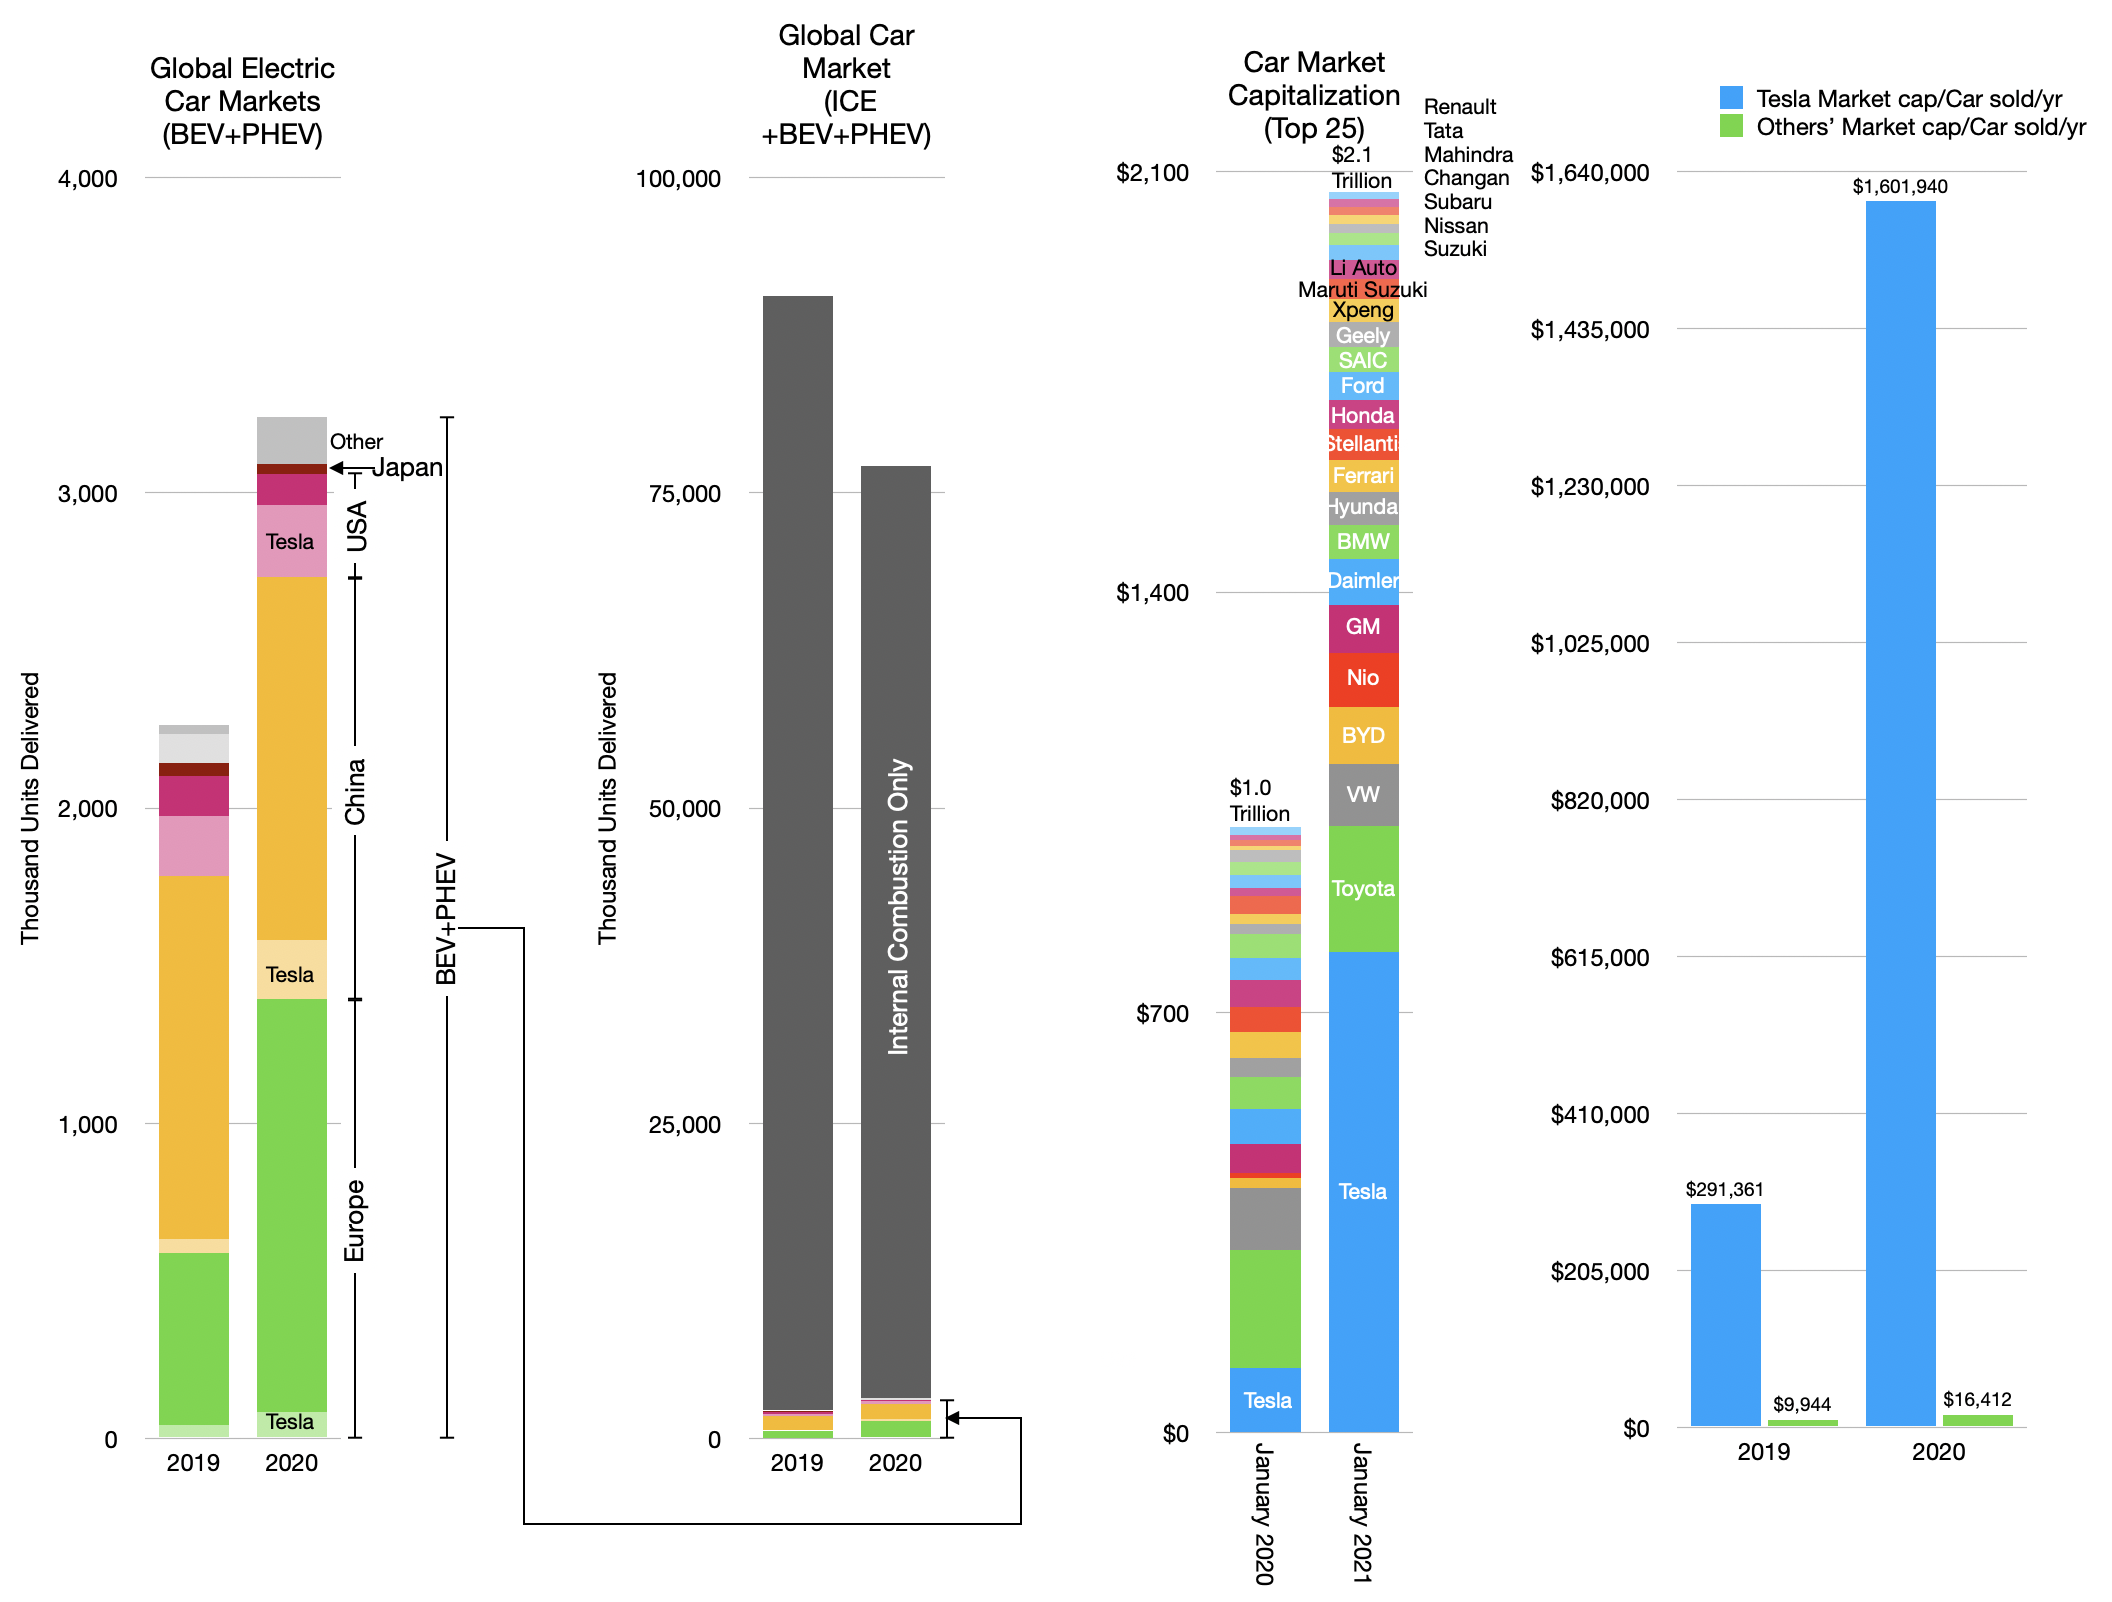
Japan and "Other" countries aside, there was growth. But much remains to be done. The overall industry is far larger, as shown in the following graph.
EV growth and global light vehicles 2019, 2020.
Nevertheless, optimism abounds. With an increase in market capitalization of about 648%, Tesla is now the most valuable automaker in the world.
Tesla, the champion EV maker has taken 17 years to reach 0.65% market share.
Market capitalization of the auto industry (top 25 firms) and the market size (in units delivered).
Actually, as the graph shows above, Tesla is now almost as valuable as the entire auto industry was a year earlier. But the rest of the industry did not collapse. The top 24 companies (i.e. apart from Tesla) increased their market capitalization from $901 billion to $1266 billion during 2020. That's a 40% increase during a year when sales fell by 15%. Quite an achievement.
Overall the market capitalization of the top 25 automakers more than doubled from $1.0 to $2.1 trillion. This begs many questions, mainly, how would such profits ever be generated.
To put a finer point on it, if we divide the market capitalization by units produced we get a figure of value that allows a historic perspective.
A measure of valuation by units of production.
Historically car companies were valued at $8,000/yr. 2019's value was about $10,000 which makes sense given some inflation. But the drop in volumes coupled to increase in valuation brought the ex-Tesla cap/unit to an eye-watering $16,400, a 64% increase in one year.
Tesla's valuation is on a different level. It went from $291,361 to over $1.6 million/car sold. Roughly this is 100x rest of industry.
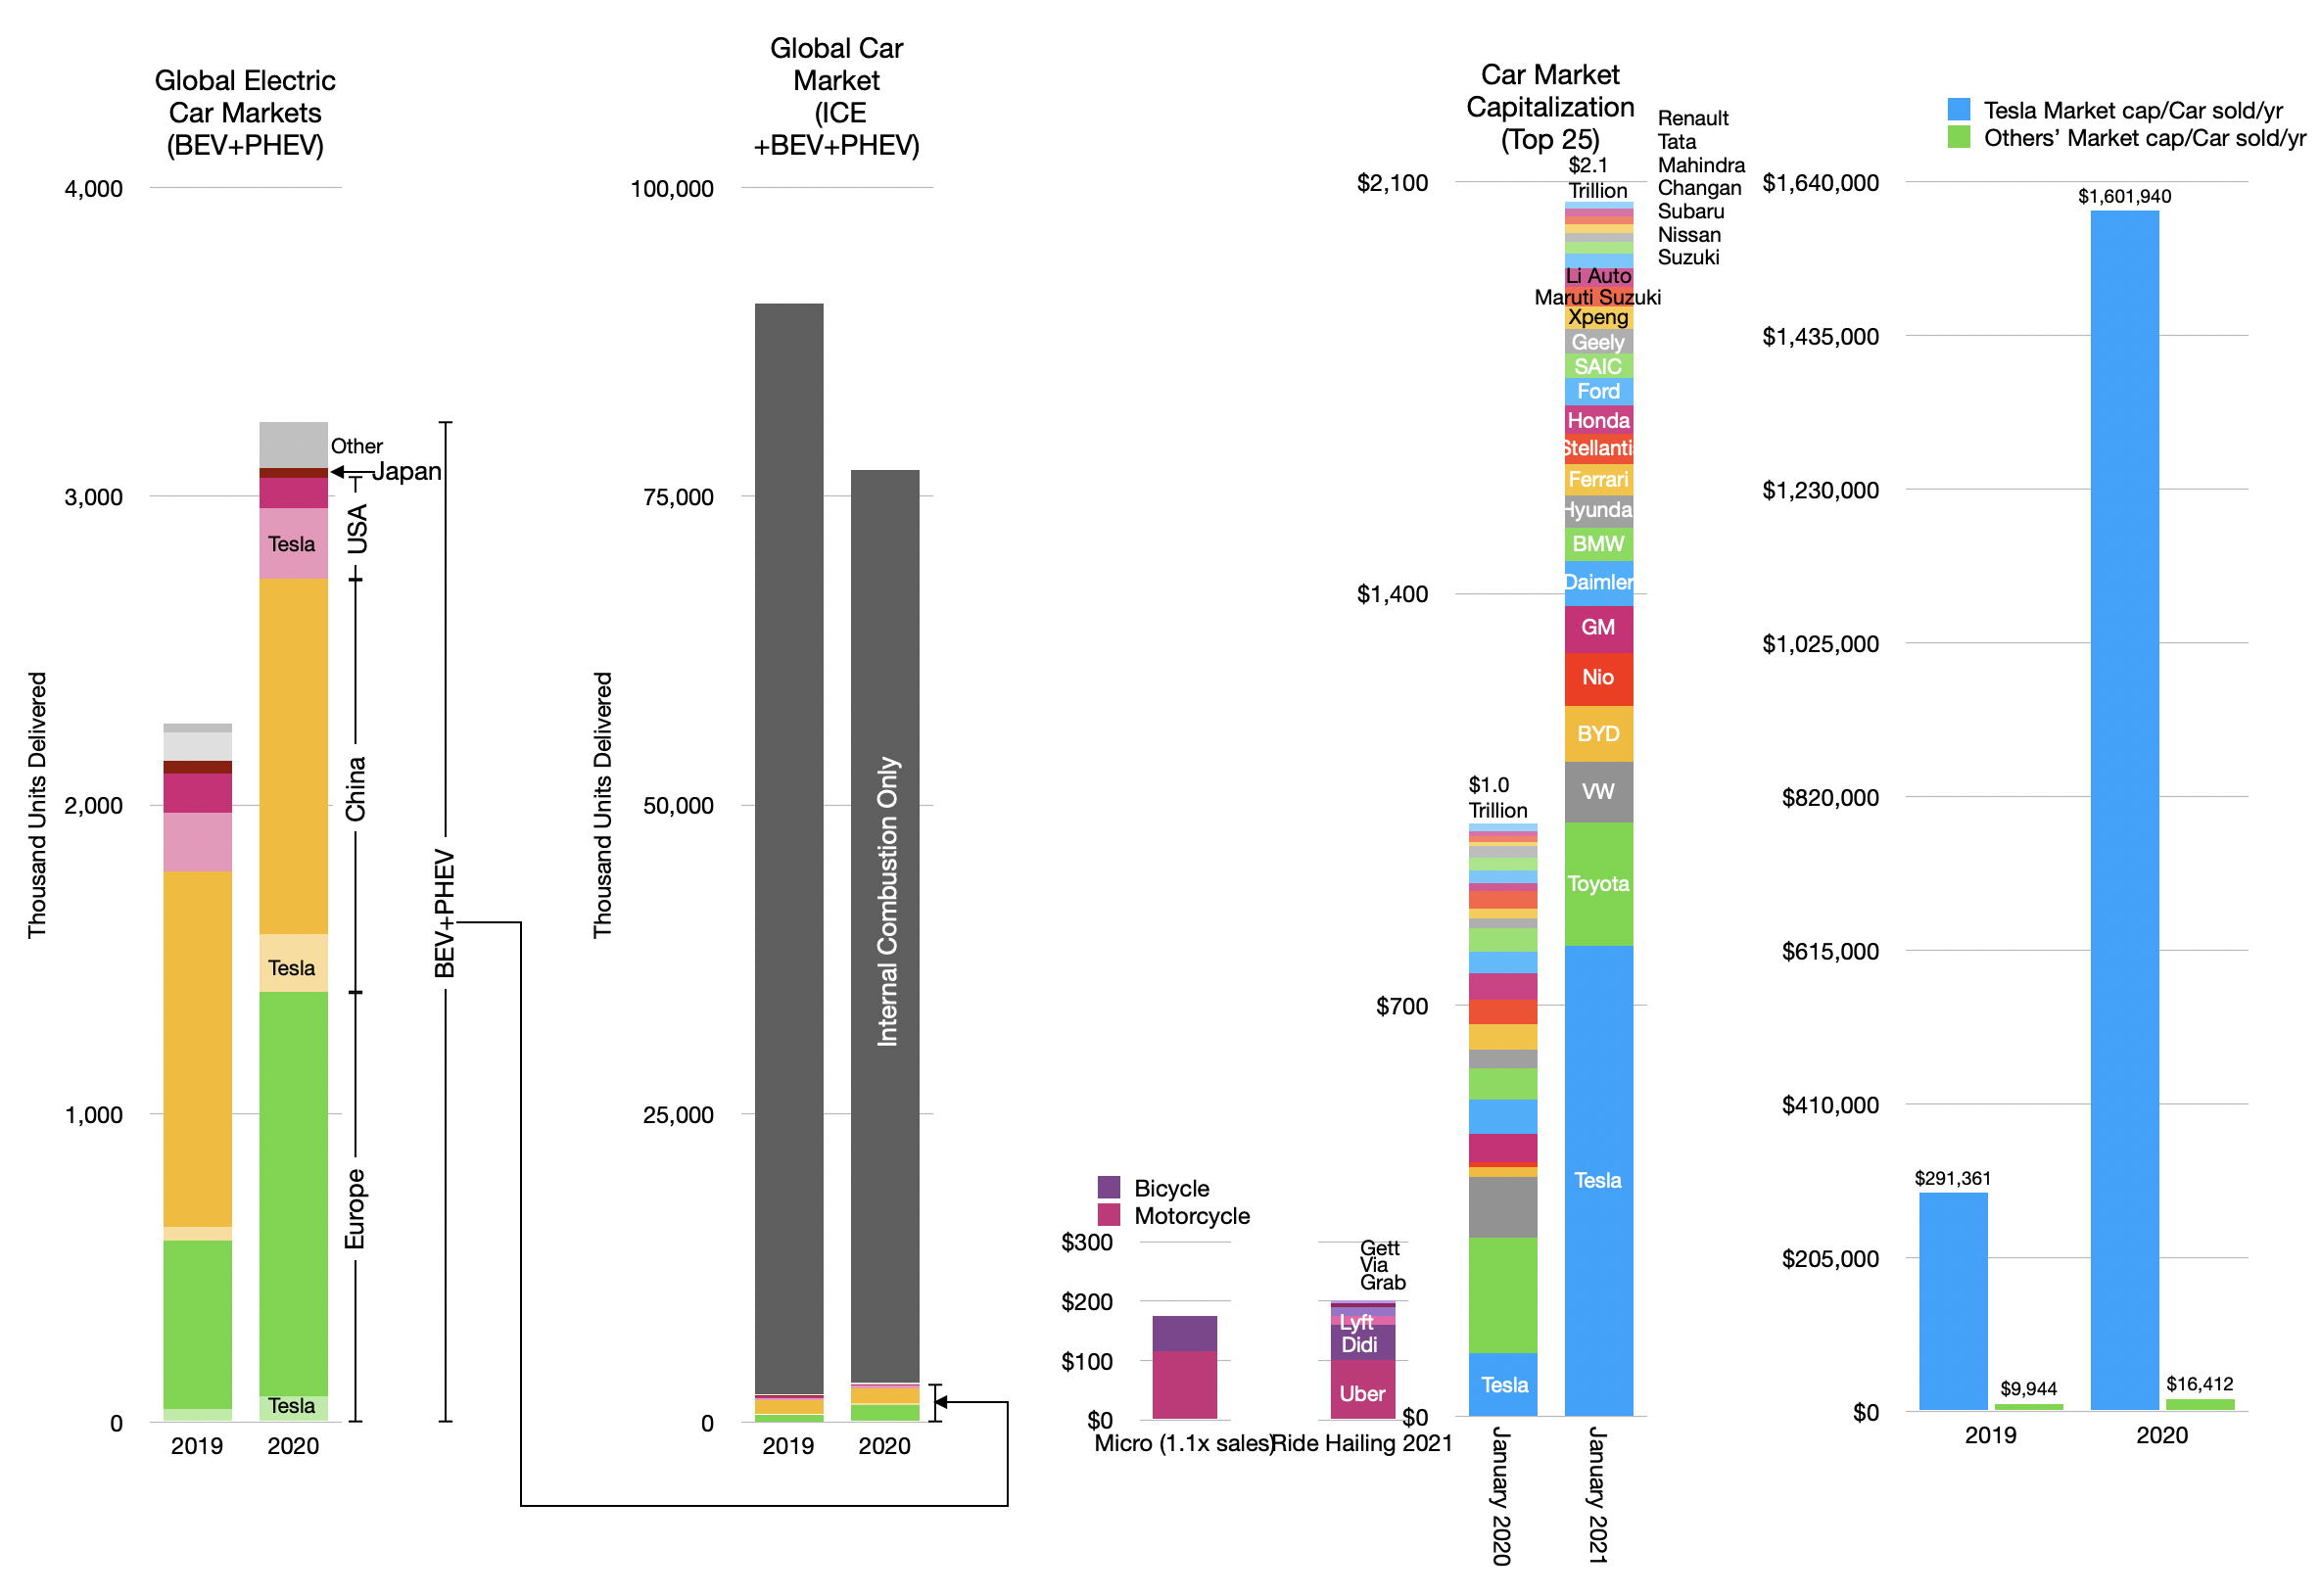
But if we continue to pull the thread there's yet another story to consider. The car industry (i.e. making and selling and servicing cars) is not the only way to deliver "miles" to citizens. There are multiple "modes" and services that deliver transportation.
There are also the ride hailing and micromobility which are positioned on different "jobs-to-be-done" than cars. The market capitalizations of ride hailing and micromobility are shown below
Adding the value of ride hailing and motorcycles and bicycles.
Note that micromobility is only measured by the value of motorcycles and bicycles whose markets are measurable and applying a 1.1 multiple to those sales yield a rough estimate of market cap.
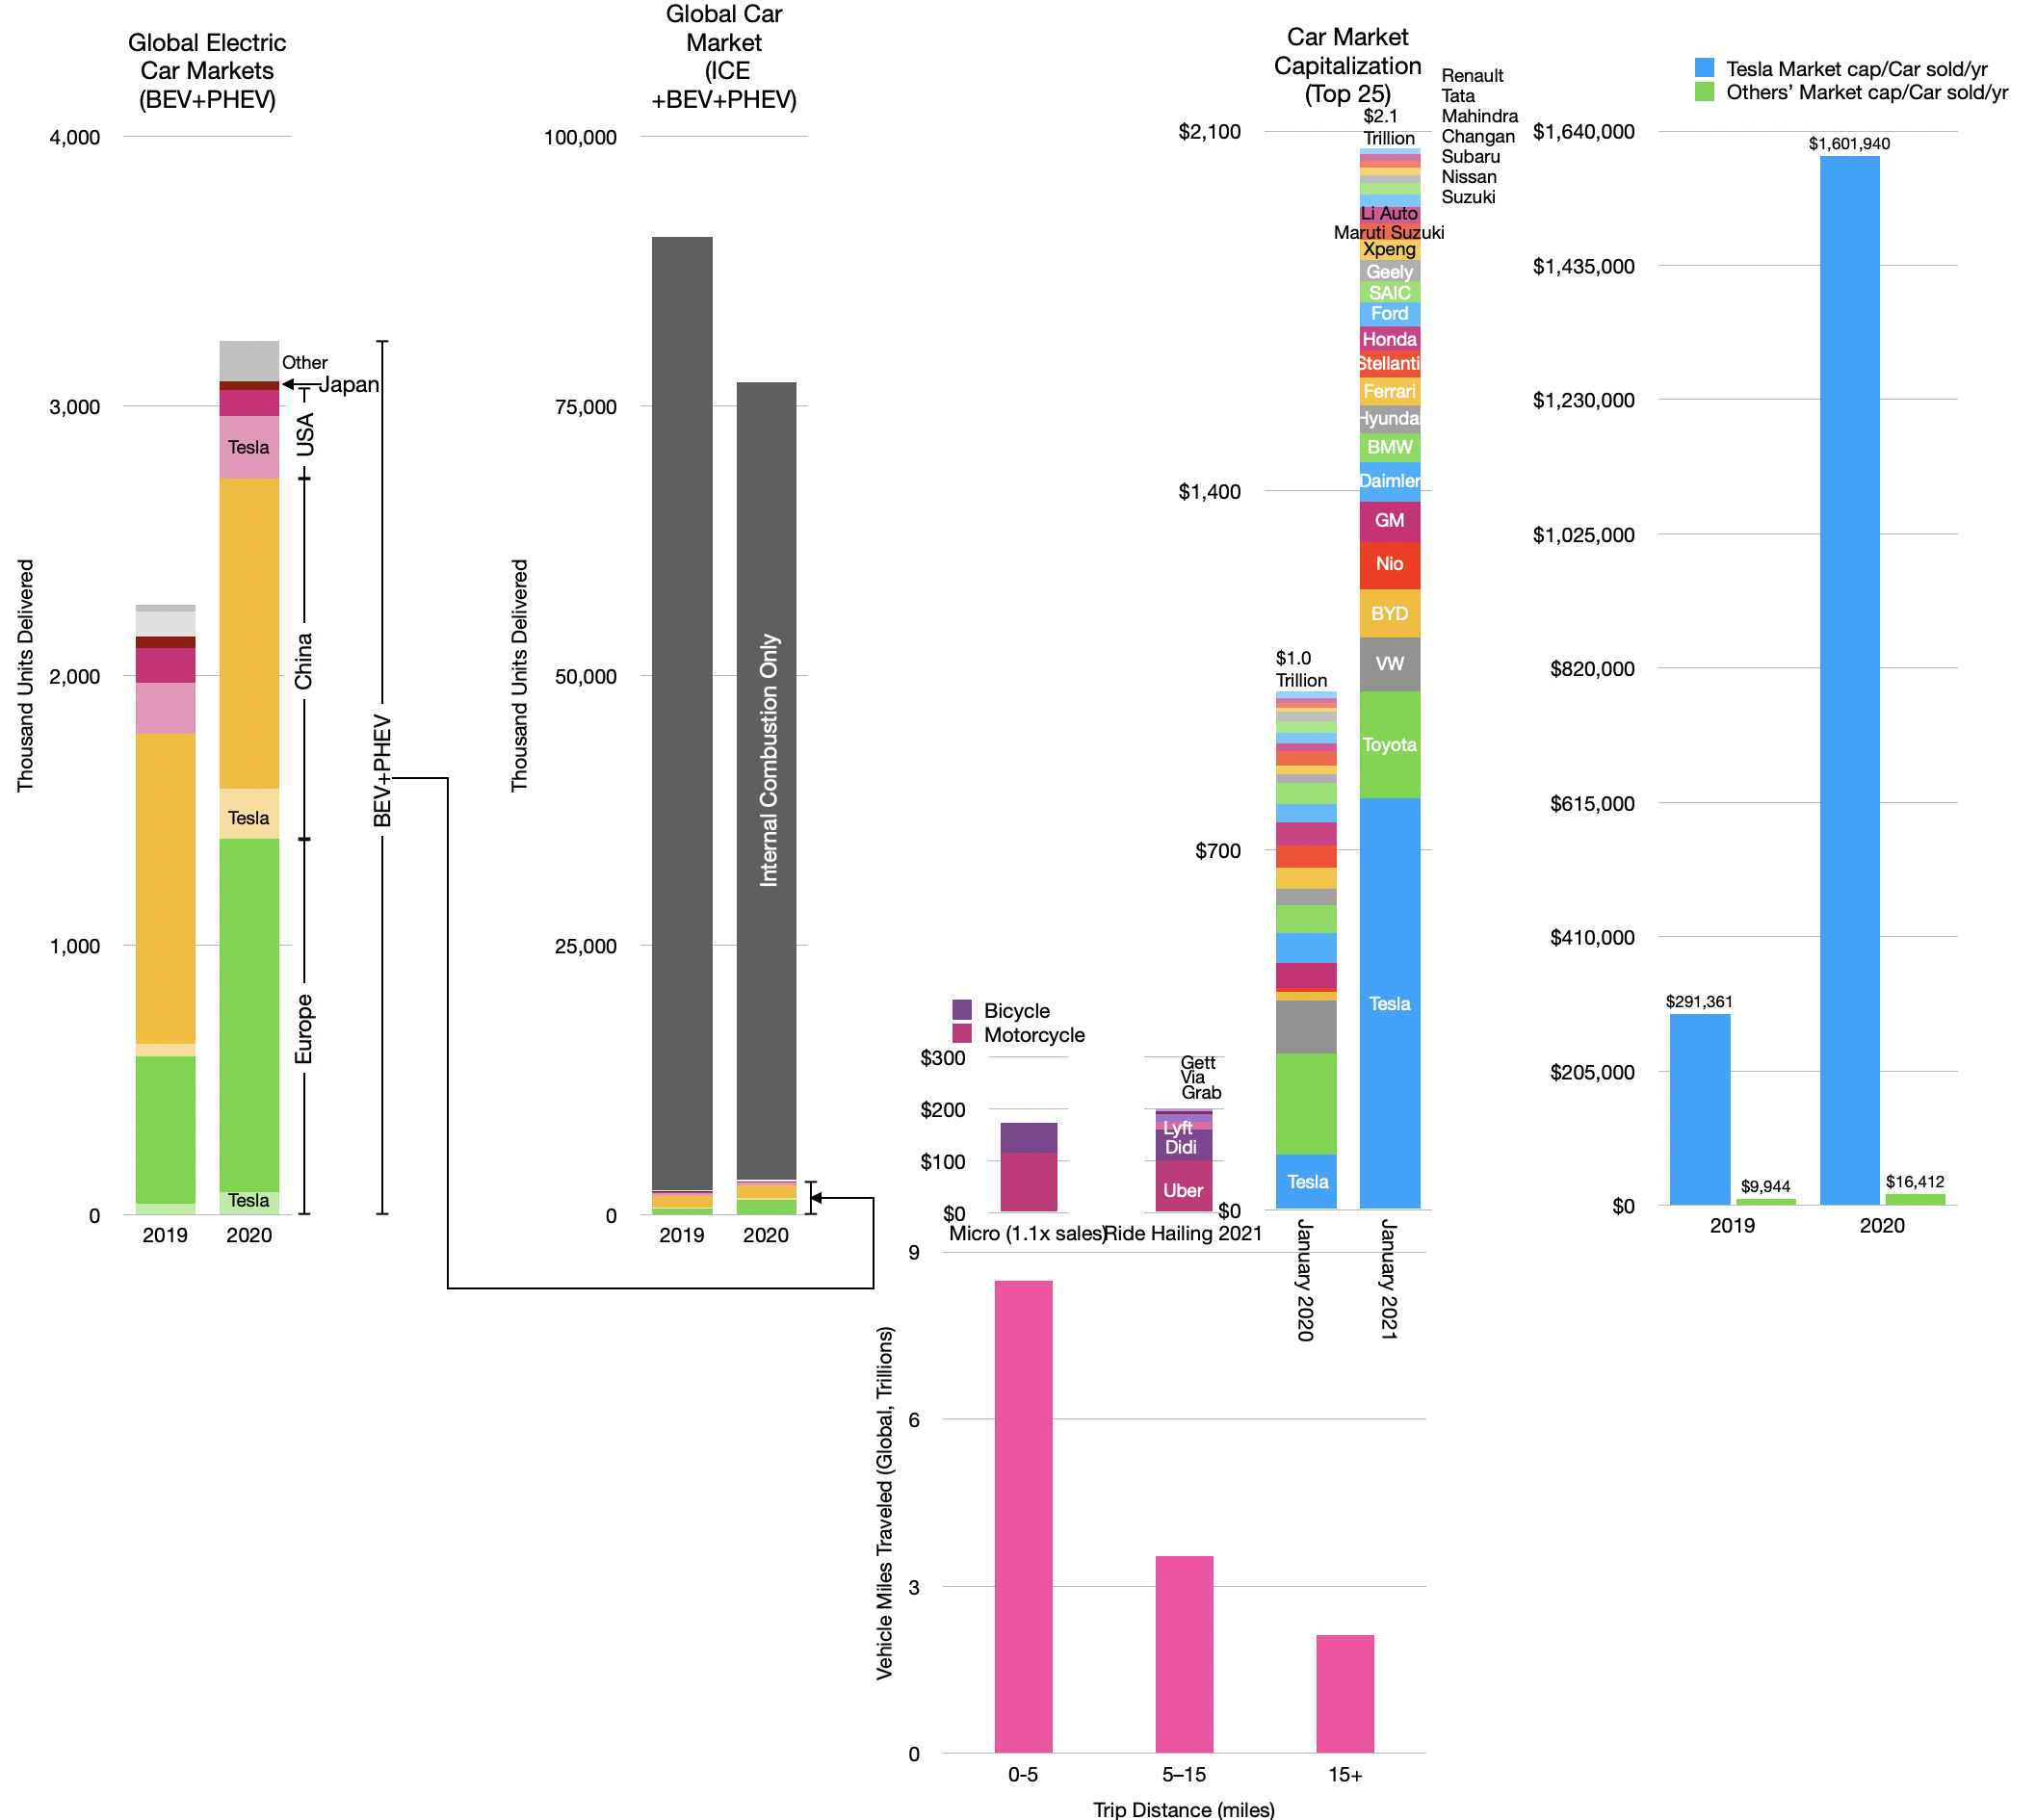
It's hard to get a measure on these jobs but I've taken to heart the idea that what you measure is most important in seeing what's next and have been dividing the "market for miles" into short, medium and long distance trips.
The "Car Bundle Paradox": The demand for travel vs. value of modes for travel by trip distances.
In the view above we get a sense of the scale of perceived value for businesses serving various trips. The inverted nature of valuation positioned on trips is, I believe, worthy of further analysis.
As the car today is a bundle, the design and engineering efforts are directed at serving the longest of long trips (with the largest payloads.) But the demand is for short trips.
If the car is to be unbundled (as the Personal Computer was into laptop, tablet, phone, wearables) then one can imagine that devices designed for short trips would accrue the value of those trips (and their popularity).
The absence of value in short trips is a paradox. Or perhaps it's just an opportunity.
IN a recent release, Apple reported that "more than 90% of stores in the US, 85% of stores in the UK, and 99% of stores in Australia accept Apple Pay." This is encouraging but a very small view for the global Apple Pay picture. How can we assess where Apple Pay is and how do we even measure success? My expectation six years ago was that Apple Pay would be a "$1 billion business" by 2020. Now that 2020 has ended, how was my six year prediction?
I always recommend counting customers rather than (or before) dollars so let's begin with that. According to one source Apple pay users worldwide reached 507 million by September 2020. This is about 50% of iPhone users and therefore a decent adoption rate (starting as it did six years ago.) The data shows a growth rate of about 66 million in 2020 but a deceleration from 150 million the previous year. This data is obtained through surveys as there is no reporting from any participants.
There is a smattering of other samples about transaction volumes, mostly behind pay walls, but the overall story of adoption is typical: an s-curve where we are either at the point of inflection or slightly after it. If we are half-way then perhaps saturation will occur in another six years.
More concerning is the distribution of these users. A lot of the data that is collected on mobile and online payments (and mobile wallets) is US only. Historically the US was a good place to measure technology adoption as the US was usually the leader. The automobile, PC and many other consumer technologies saw their market defined by the US.
But not so much anymore. The digital mobile phone broke the rule. Today mobile payments is breaking it again. Note that although the iPhone is over-represented in the US (as share of all phones) Apple Pay point-of-sale support is under-represented in the US.
According to one survey, in mid 2018, there were an estimated 38 million Apple Pay users within the United States, and 215 million outside (5.5 times more!) Outside the US mobile payments are nearly 100% accepted by default but in the US the support is patchy and characterized by active intervention to deny.
I've used Apple Pay everywhere in Europe without friction. From vending machines to highway tolls to drive-throughs, public transit and parking meters. I can recall one failure to do so in the last six months (a state-owned gas station).
The same cannot be said of the US. Where at WalMart and Home Depot there is the capability of support but an incomprehensible refusal to do so. One rumor about why Home Depot denies it is because they were hacked once and are paranoid about any technology. Walmart may be spiteful due to margin/cost, valuing a few basis points over customer satisfaction, convenience, hygiene and employee productivity. These holdouts are the laggards. Perhaps there is some pride in denying their customers a basic convenience but there certainly isn't profit in it.
It gets even weirder when it comes to banks. In the US almost all banks immediately supported Apple Pay as an extension of their bank cards. In Europe the banks became the holdouts, rolling out support slowly and perversely.
So when you consider the dependencies of Apple Pay:
Sufficient number of users with iPhones/Watches (check)
Support from Banks (great in US, spotty outside)
Willingness of retailers to accept (sluggish in US, perfect outside)
Availability of points-of-sale equipment (universal by now
It's an impressive achievement.
My expectation six years ago was that Apple Pay would be a "$1 billion business" by 2020. This was based on a take rate of 15 basis points ($15/$10,000 in transactional value). Juniper Research, which regularly examines payment transaction markets, now expects that Apple will see global Apple Pay transactions of $686 billion by 2024.
At that 15 basis point rate it amounts to $1.03 billion. Thus this particular research suggests that I was off by 4 years, making the $1 billion pay day a 10 year target rather than six.
But maybe that is no fault of Apple's. The transaction volume is also equivalent to 52% of the proximity mobile payment market. Half the addressable payment market is a pretty good market share for a company holding 25% of the smartphone user base.
As a rule, I don't like to make a forecast for Apple's performance during quarters where there is no guidance. There is a good reason why there is no guidance. The management does not feel confident that there is enough information to make a reasonable prediction. Keep in mind that the management has very detailed, very frequent updates on their business metrics.
Anyone who has run a business knows that signals of performance are abundant and one can only imagine how many signals arrive at Apple HQ from the 1.5 billion active devices, tens of thousands of points of sale, and a vast network of resellers. There are also billions of interactions in services. Then there are search queries, store visitor counts (online and physical), developer payments, app downloads, content downloads, subscriptions. All this information is collected and analyzed on (probably) a daily basis.
Also when guidance is given, it's usually a month into the next quarter. The company will have already seen about a third of the quarter already pass before they predict the next two thirds.
This last quarter in particular was even more difficult given the delays in launching the new iPhones and the dynamics related to the broader portfolio.
And yet, the company feels that they can issue some "insights on our expectations". Here is what was said about three months ago:
These directional comments assume that COVID-related impacts to our business in November and December are similar to what we've seen in October. […] [W]e expect iPhone revenue to grow during the December quarter despite shipping iPhone 12 and 12 Pro 4 weeks into the quarter and iPhone 12 mini and 12 Pro Max 7 weeks into the quarter.
We expect all other products in aggregate to grow double digits, and we also expect services to continue to grow double digits. For gross margin, we expect it to be similar to our most recent quarters despite the costs associated with the launch of several new products. For opex, we expect to be between $10.7 billion and $10.8 billion. We expect OI&E to be around $50 million and the tax rate to be around 16%.
Luca Maestri, Chief Financial Officer
So, given this information and some hints from IDC, Gartner and CIRP and China I'm willing to offer some estimates:
iPhone Revenue: $63.9 billion
Mac Revenue: $9.3 billion
iPad: $7.4 billion
Services: $15.1 billion
Wearables & Home: $12 billion
Net sales: $107.8 billion
Gross margin percent: 37.7%
EPS: $1.48 (Growth: 19%)
Of course, this is very speculative and I don't have a lot of confidence in it. If anything it may be on the high side.
I don't expect there to be guidance for the next quarter with a resumption of guidance only after the pandemic has largely subsided (probably Q3 of this year.)
App Store spending was $1.8 billion in the last week of 2020, up from $1.42 billion the previous year —an increase of 27% vs. an increase of 16% from the previous year.
On 1/1/2021 App Store spending reached $540 vs. $386 million for 1/1/2020. This was an increase of 40%. The previous year's increase was 20%.
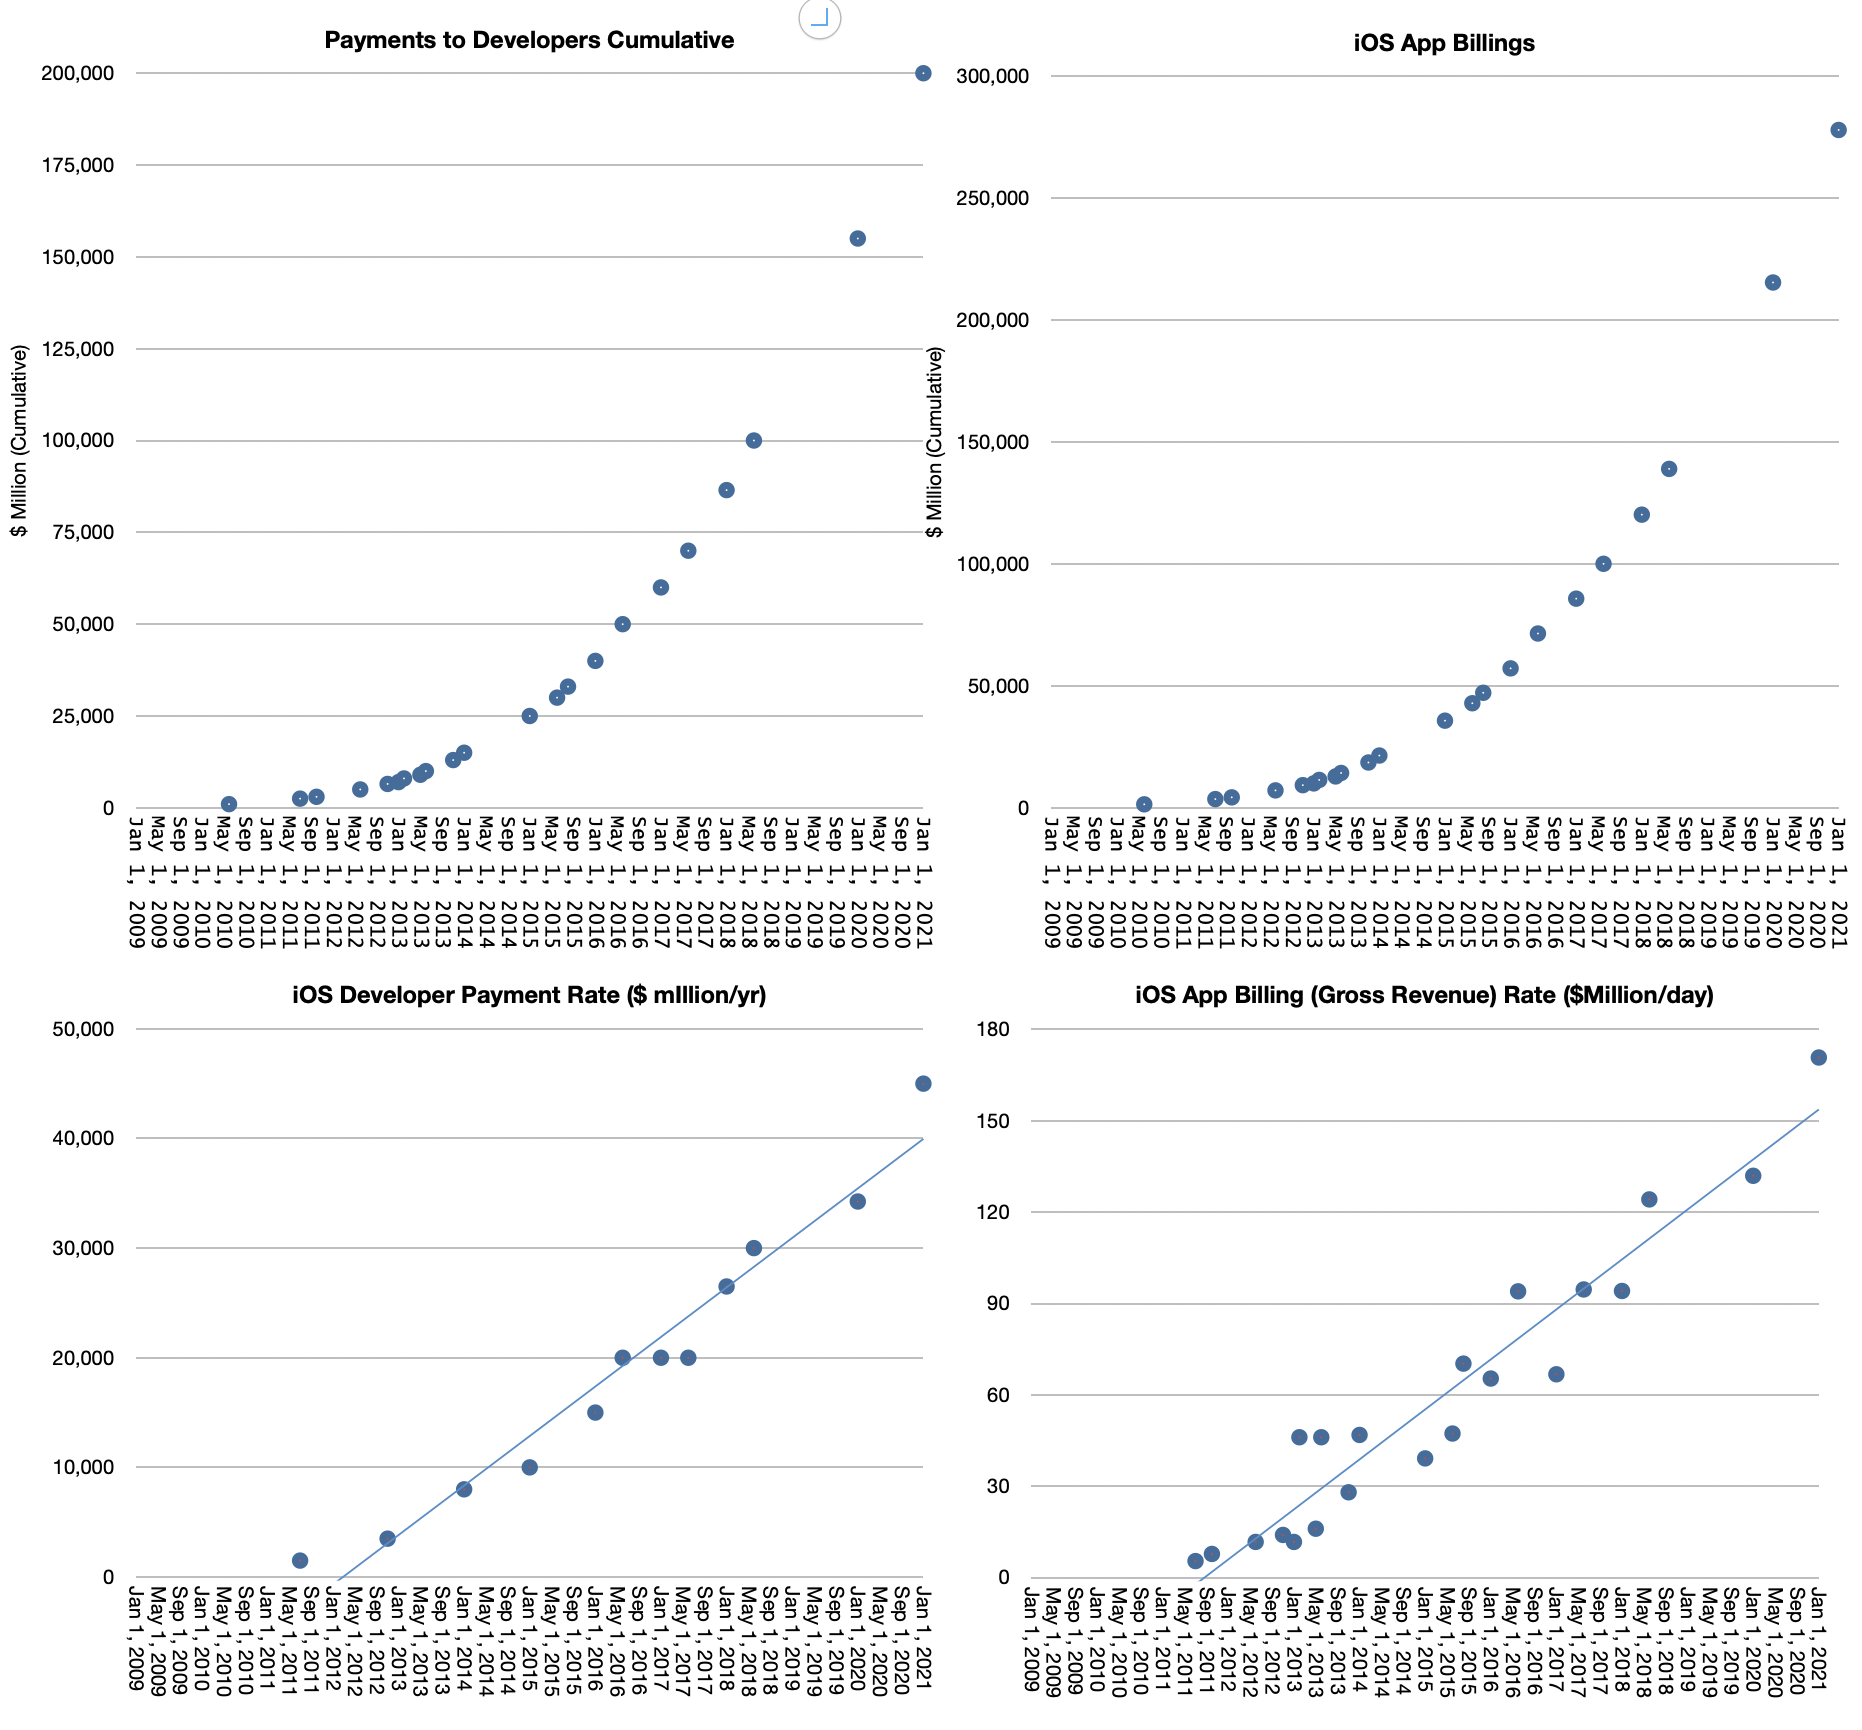
Developers selling through the App Store have now earned more than $200 billion since the App Store launched in 2008.
The previous year's figure was $155 billion, making the 2020 total $45 billion, a 30% increase from $34.5 billion average of the previous two years. Assuming a proportional increase, overall ecosystem transactions rose to $675 billion in 2020. This places Apple's valuation at a 3.2 multiple of its yearly ecosystem value and each customer is valued at approximately $1400.
The history of App Store revenue and the growth rates involved is shown below.
NB: A substantial amount of App Store revenue is derived through subscriptions which now total about 600 million.
A simple summary is that the App economy accelerated its growth in 2020. This implies an economic value reaching $1 trillion/yr. within two years. It would behoove the investor to evaluate the value of Apple as a multiple of its ecosystem as well as a multiple of its customer base.
As I have repeated over time, the strength and resilience of Apple is in its customer base. Strength in terms of willingness to spend for quality and value and resilience in terms of sustained satisfaction. As that base grows to well over 1 billion people and as this billion are exposed to an increasing spectrum of value options (products, services and ecosystem) the company becomes indispensable.
This is quite the opposite of the perceptions widely held even a few months ago.
In other news:
Apple added 52 new territories to Apple Music.
Apple TV is now available on over 1 billion screens in over 100 countries and regions, providing access to buy or rent over 100,000 new release and classic movies and TV shows
Apple Pay is accepted at more than 90% of stores in the US, 85% of stores in the UK, and 99% of stores in Australia
Apple Books now draws over 90 million monthly active users
Podcasts are now available in over 175 countries with programming in more than 100 languages
More than 85 percent of iCloud users are protected with two-factor authentication
The Apple product line-up for 2023 is almost completely decided. This is not conjecture but simply an observation of the lead times for developing the types of products that Apple offers. The integration of hardware, software and services, often cited as the key to Apple's sustainable competitive advantage, has a great cost: the time required to develop in an integrated fashion is far longer than the time required to develop in a modular fashion.
2.5 years is not a long time. The development process on truly new products could take 4 to 5 years. Apple Silicon, new Operating Systems and new services could all take longer than 2.5 years. The products we just saw launch this year were planned and engineered at least 2 years ago. The more integrated, the more time is needed. Wearables, AI/ML and process engineering are additional examples of long arcs of development needed to reach products.
This does not mean we can predict what these products will be. We don't have visibility to the process but Apple management does and they will make decisions now on adjacent dependencies in the business. For example, visible efforts in planning the use of cash, the carbon offsetting, capital expenditures and R&D are all synchronized to the roadmap and hints may be read into this data.
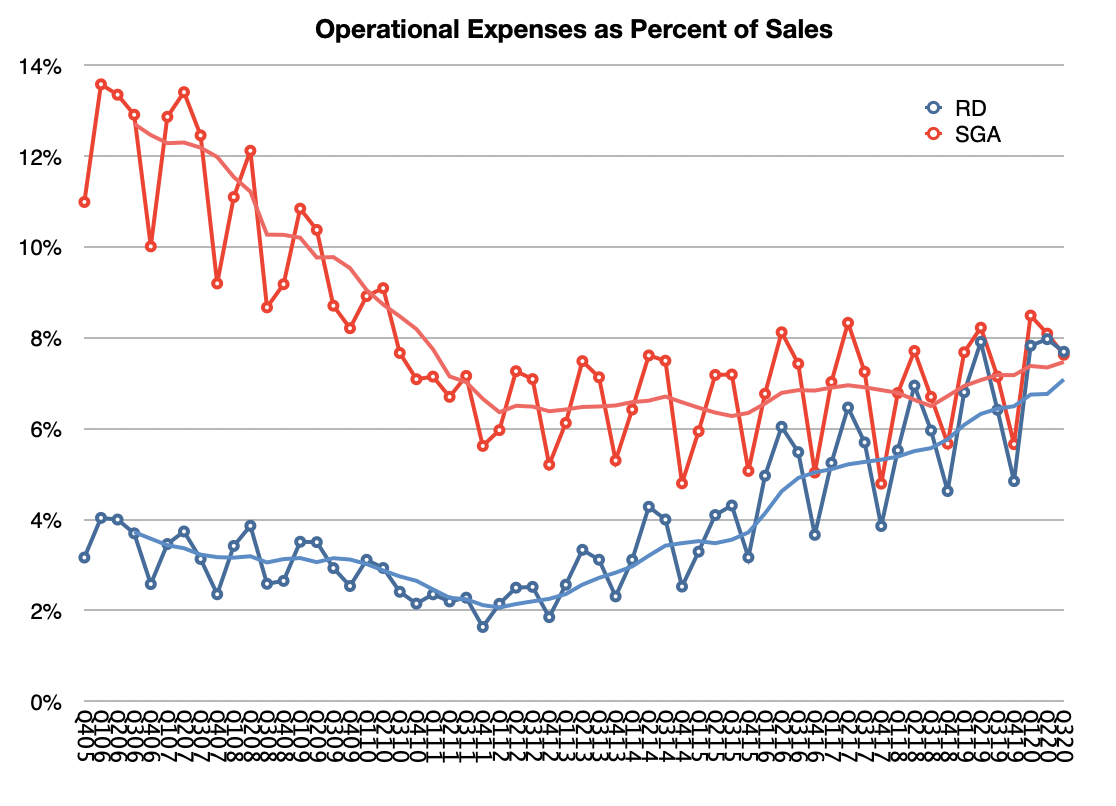
The biggest hints are the R&D spending and the company's capital return program. Combined they show a confidence in the roadmap that is hard to overestimate. First, R&D is reaching new highs of about 7% of sales (on a trailing 12 months' basis, see graph below). This is almost the same as the spending on SG&A which has declined as a percent of sales from above 12% pre-iPhone.
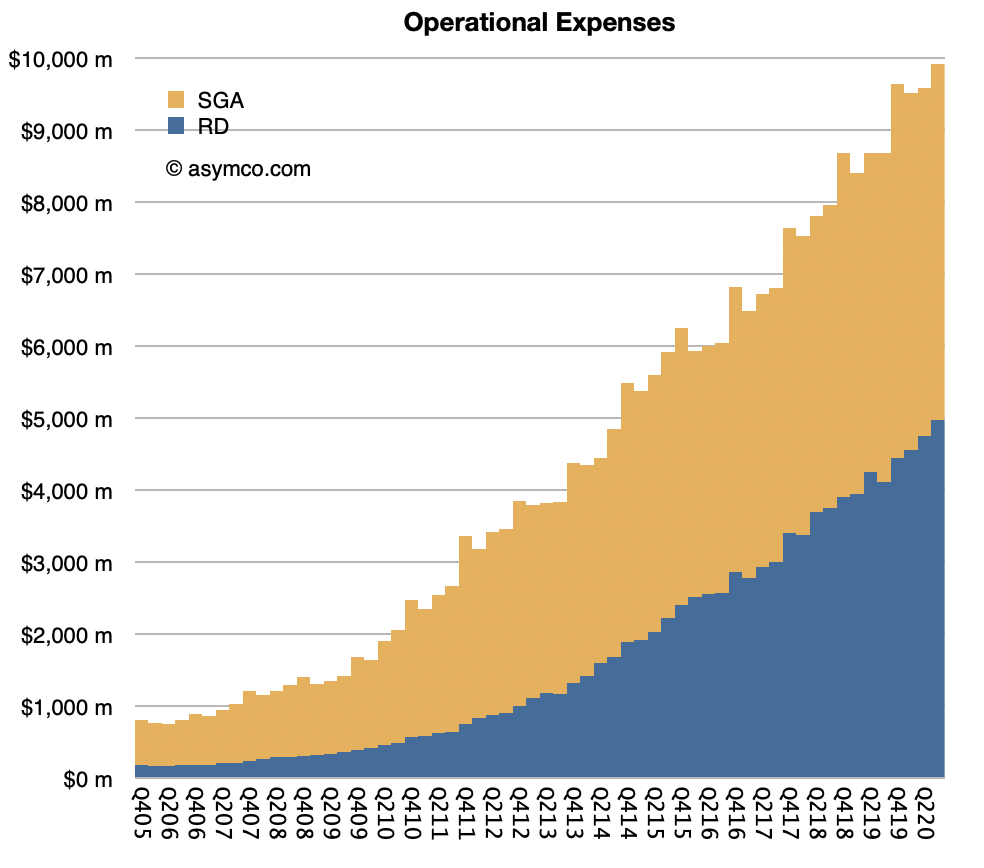
Of course sales have increased significantly over the time shown in the graph below and the absolute spending is shown the following graph. R&D spending is over $5 billion/quarter or about $20 billion/yr. Some of the results of this will be seen in 2023 or beyond.
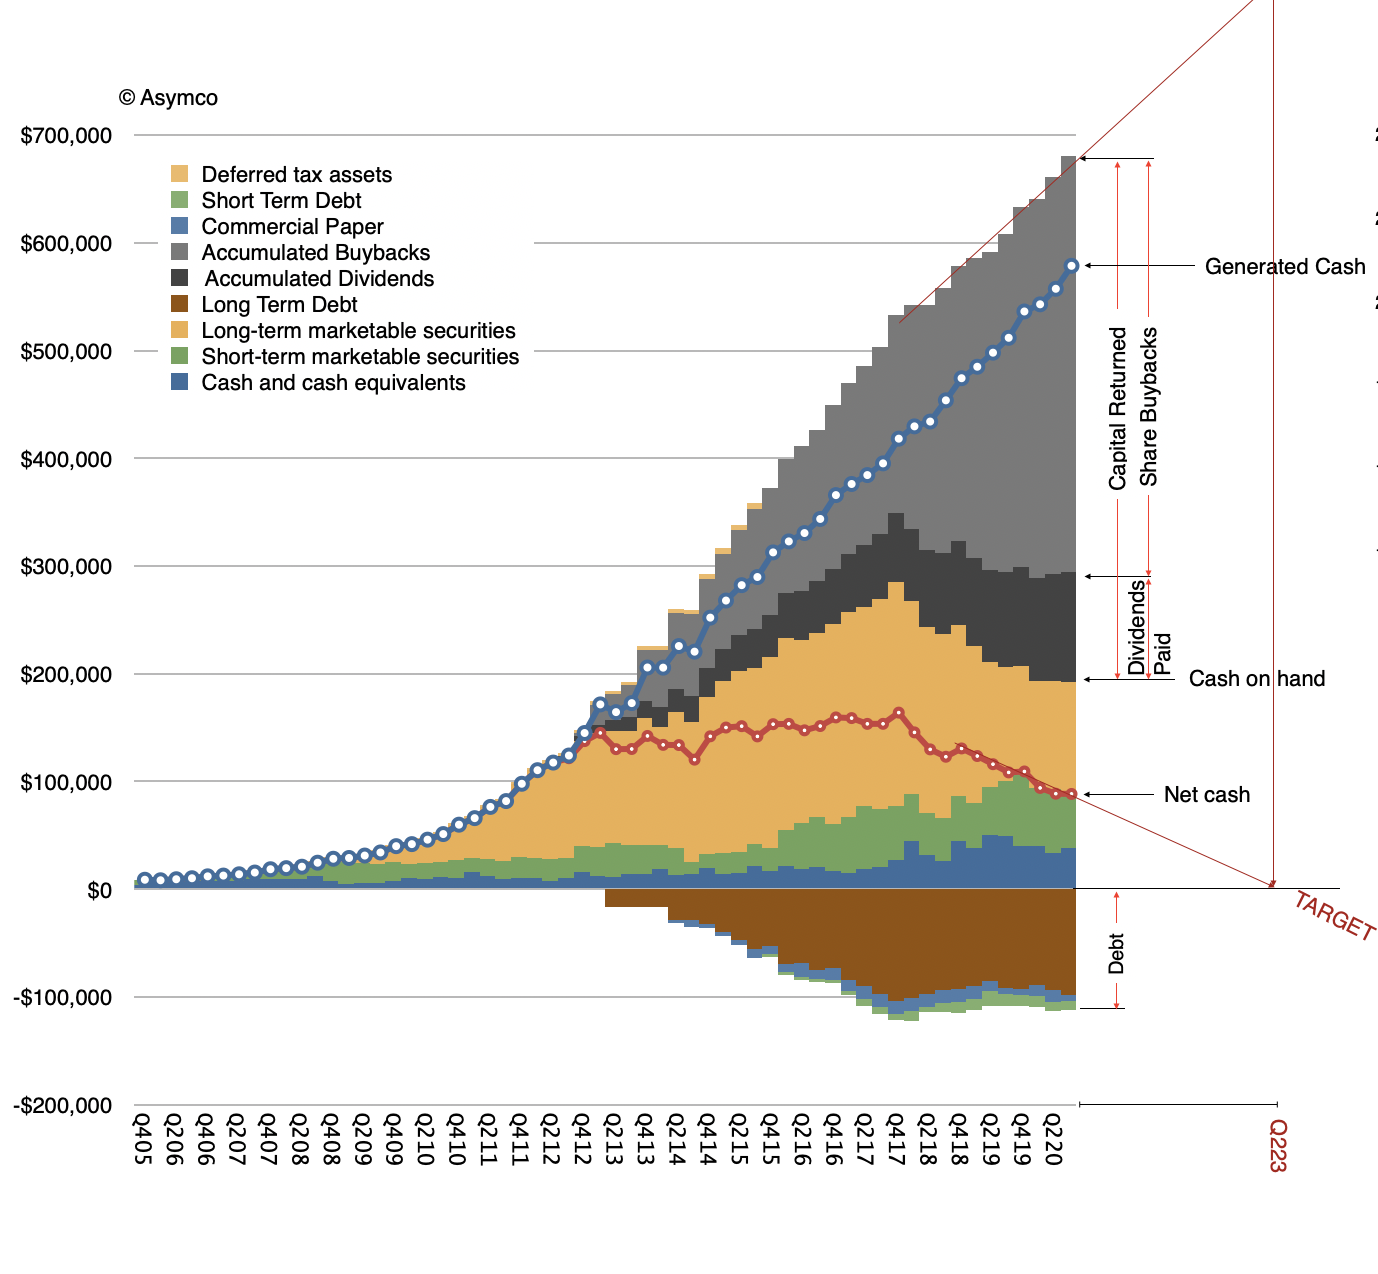
Next, capital returns. The company is returning almost all the cash it generates and is reducing its cash balance. It has returned about half a trillion dollars to date. Dividends paid has reached $100 billion and share buybacks about $400 billion. This is the largest capital return in US history.
The company has declared its intention to reduce net cash to zero. This means it will still have substantial cash due to loans in the form of bonds but no "excess" cash will be held by the company. This is in contrast to the strategy under Steve Jobs where he sought to keep as much cash on hand as possible due to the need to weather potential storms, Tim Cook's Apple is being very "casual" about cash.
Steve Jobs had his reasons for hoarding cash. The company had been through periods of existential crisis. The absence of cash jeopardized its independence and it was something he vowed never to happen again.
However if that strategy would be maintained to this day, as the graph shows, the company would have cash of nearly $700 billion today. It would make Apple the world's largest hedge fund, by far. Second only to a very few sovereign funds. Given a conservative cash preservation mandate it also means that that capital would largely go unrewarded because the return on it would have been minimal, negligible. Not to mention also the target it would paint on the company's balance sheet.
So given the trajectory in net cash being so consistent, it's probable that the goal of net zero will be reached mid 2023.
That leaves the question of what will happen at that time?
The answer is nothing. Nothing will happen. The capital return programs will probably be ended and additional cash generation will be paid as dividends going forward. That's it.
Rather than suggesting a change, the capital return program (and the R&D program) suggest a lack of change, consistency. The company management is anticipating a steady capital generation rate, a steady product roadmap (with predictable growth) and a steady customer base (with predictable loyalty).
This future for Apple in 2023 may seem boring. But that's exactly the plan. This is a plan that the company management has been making for a long time and has been executing for a long time. The plan is to be boring on the business side but exciting on the customer product side.
Consistency has been the characteristic trait of the Tim Cook era. It is a smoothing of seasonality with services. It is the clockwork delivery of product updates, regardless of macro and externalities. It is a growth in user base consistent for a decade.
It is perhaps because more people believe that consistency is the future that we have Apple's P/E ratio now in-line with its peers. Paradoxically, being boring is what makes Apple shares so exciting today.
The term Post-PC was first coined by MIT scientist David D. Clark in 1999 and was quickly adopted by both Microsoft's and Apple's former CEOs. Jobs popularized the term "post-PC" in 2007 (the launch of the first iPhone), and in 2011 when he launched iCloud, a service enabling Apple devices to synchronize data through cloud services, freeing them from dependency on a PC.
The Post-PC era was posited during the late 2000s and early 2010s presupposing a decline in the sales of personal computers (PCs) in favor of devices, phones, tablets, wearables, IoT, etc. These devices were mobile first (i.e. battery-first as opposed to plug-first), connected second and cloud-powered third. They were designed to run "apps" not "applications" and had new ecosystems with millions of developers selling through online-only stores, priced often as subscriptions rather than seat licenses.
In the last decade or so, the PC did endure an overall decline in sales while phones, tablets and wearables climbed to at least 10x volumes of the PC. But the last few months have shown a resurgence in PC sales. Certainly the necessity of working from home is the reason but will this last?
The fact is that the PC did not disappear. It certainly is still in use and there are buyers for it. There just isn't a lot of growth or energy. There hasn't been for a decade. The software and hardware efforts are uninspiring because the talent has moved elsewhere. The creativity, R&D budget have gone the same way.
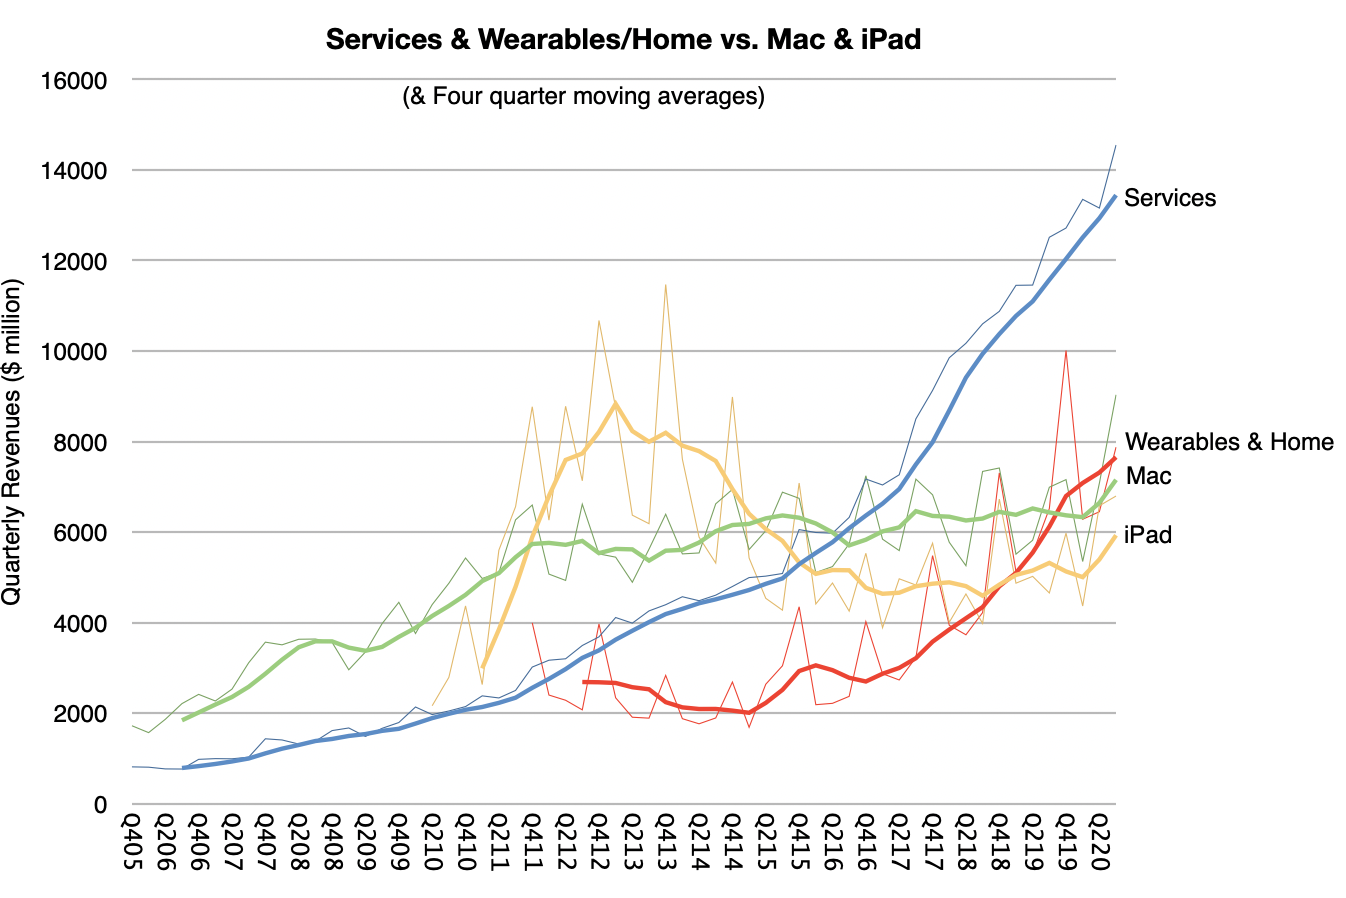
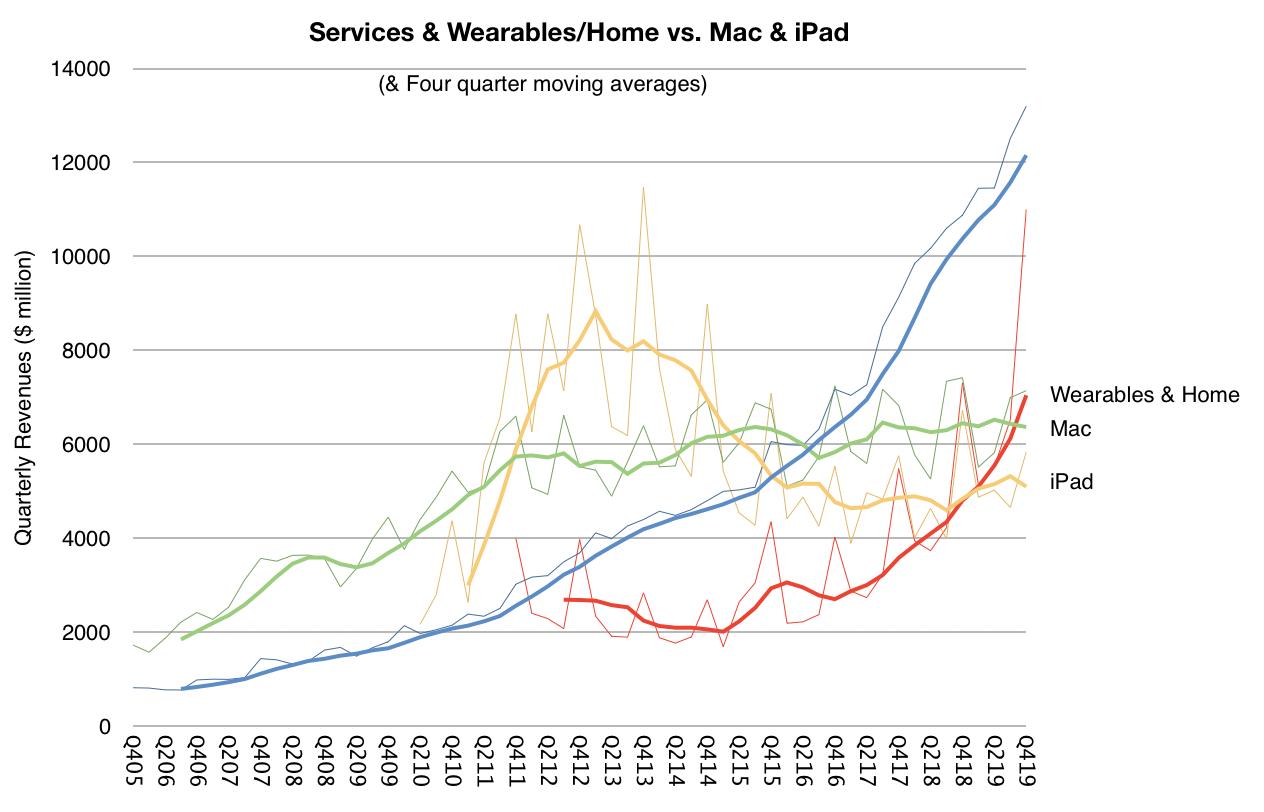
But what about the Mac? The Mac is the PC from the company that more or less defined the Post-PC era. Would it not be the first to be sacrificed for the new future? As it stands, as the graph below shows, the Mac today is double the business it was decade ago and although it has been overtaken by wearables, it has kept ahead (after a time) of the iPad.
As it turns out the Mac is doing just fine.
The trouble with PCs, including the Mac, is that they are stubborn in how they define themselves. Like the power user, they see performance along certain dimensions. They also don't see performance along new dimensions which devices offer with glee. For example connectivity to cellular networks (still missing in even the fanciest laptop but available on my watch.) Then there are the sensors which measure my heart rate, activity level, location, altitude, etc. Then there are cameras which on phones now boggle the mind. PC cameras are comical in comparison.
Then there is portability and usability without being plugged in.
Well, it was. With the M1, Apple has finally delivered the always-on feel of a tablet or phone and the more-than-one-day battery life. It also added a lot of neural engine horsepower and a lot of on-chip memory. Apple is delivering a system on a chip which makes the Mac more device-like in its integration. And sales are likely to rise, on the back of a great 2020 for the Mac. The form of the machine might even change with new designs being made possible by the lower heat profile and space savings.
And so I'm writing this post on a Mac. The graph you see above was created on the Mac. It's possible to do all this my iPad and even on my iPhone but it would be harder. But I'm also willing to bet you're reading this on a phone.
And that's the crux of it. The PC is still the machine of choice for authoring while the device is the machine of choice for consuming and consuming will always be more popular. What the iPad has done is taken a share of PC use and in my case I do use it for some tasks like email a lot more frequently. The theory would suggest that the iPad will continue its upward trajectory while the PC would abandon the low end.
This disruption has already happened but it hasn't been complete. The median performance band now belongs to devices but the professional will always ask for more of the performance which they see as productive while the consumer will always ask for more of the performance which they see as convenience. Here the market bifurcates.
What has been problematic with the smaller of the two markets has been the vicious cycle of lack of investment due to decreasing margins, commoditization and talent flight. What Apple is doing once again is ratcheting up the bar for the PC to make sure it's the top choice for creative professionals. And as long as they are productive, the consumers will keep them employed if not in riches.
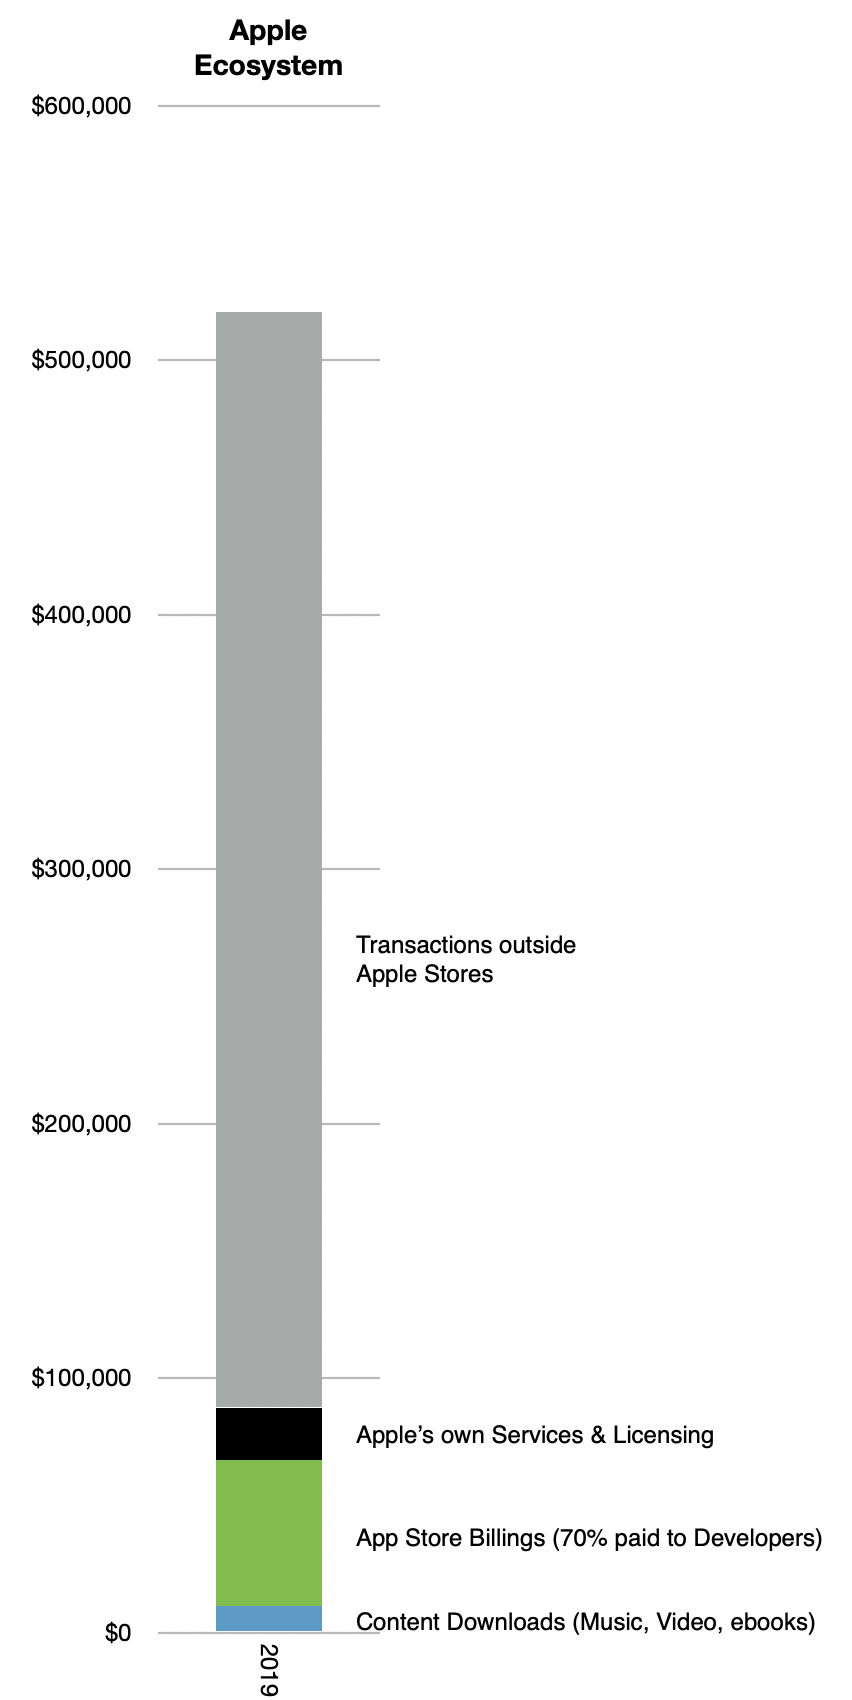
According to one estimate, in 2019 Apple's ecosystem was approximately $519 billion. This includes both transactions that Apple handles, such as paid apps, as well as purchases and other economic activity that happened through apps in which Apple is not involved in the transaction, such as Uber, Bird or Bond rides.
A fraction ($48 billion or 9.3%) of this total is reported as part of Apple's financial statements as "Services Revenues". The rest ($471 billion) is reported on other financial statements, typically businesses which use apps to book sales. These are app revenues are not even accounted as "Payments to Developers" as they are not paid directly to any developer.
The attention to Apple's terms and conditions with developers only apply to transactions in the area shown in green below. The grey area is all outside the App Stores and attracts no attention.
The attention paid to Apple's new services including the "+" brands of TV, News, Arcade, Music and now Fitness and the new bundling thereof refers to the area shown in black above.
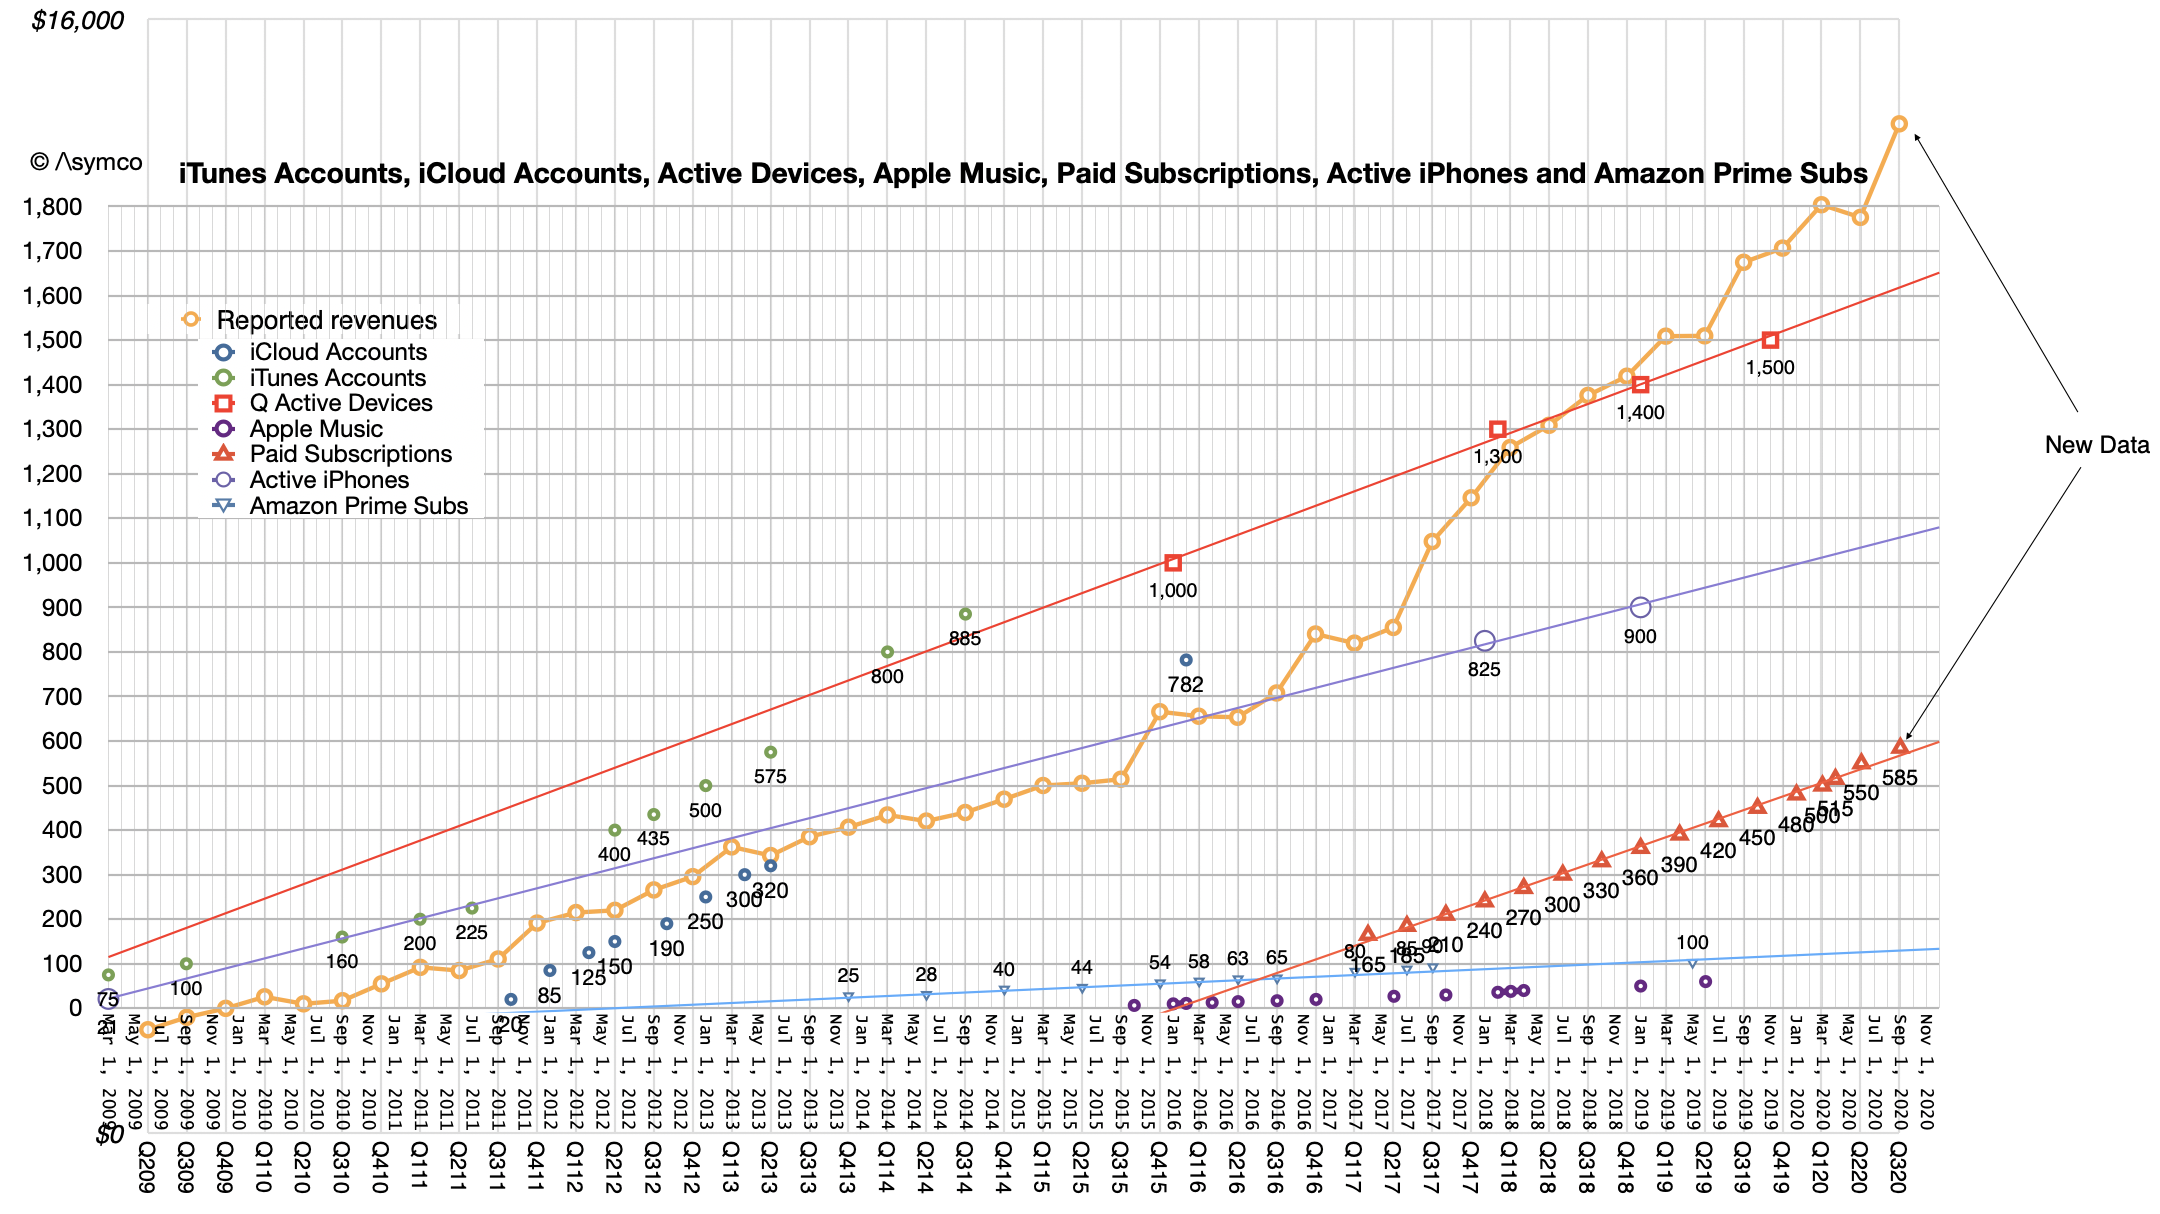
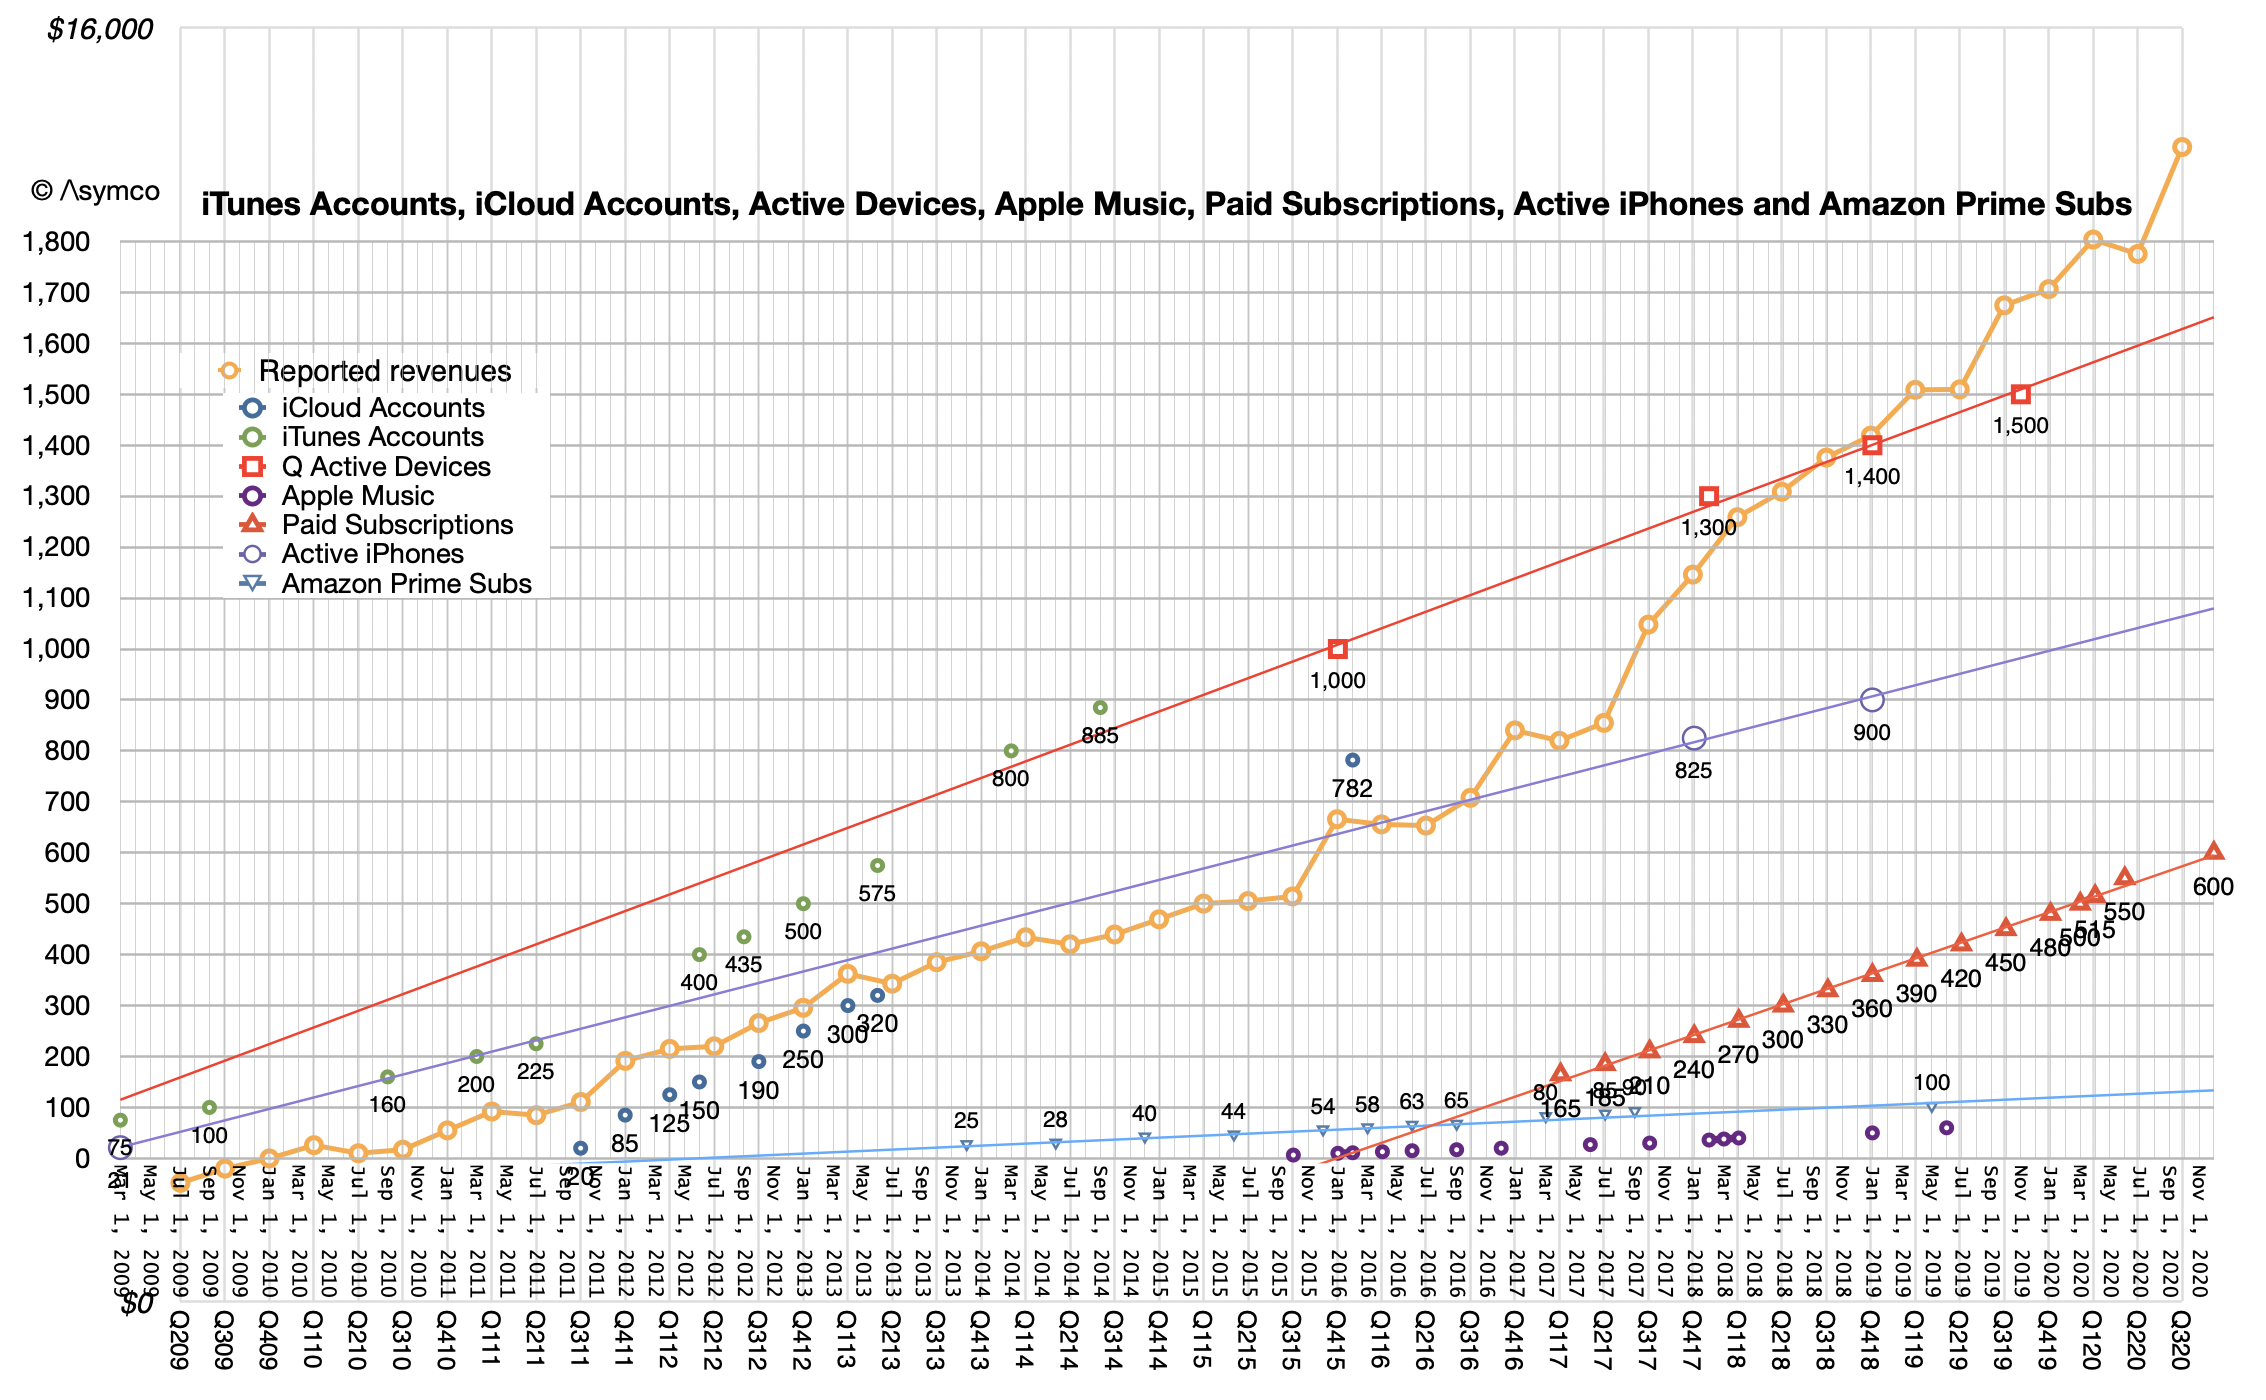
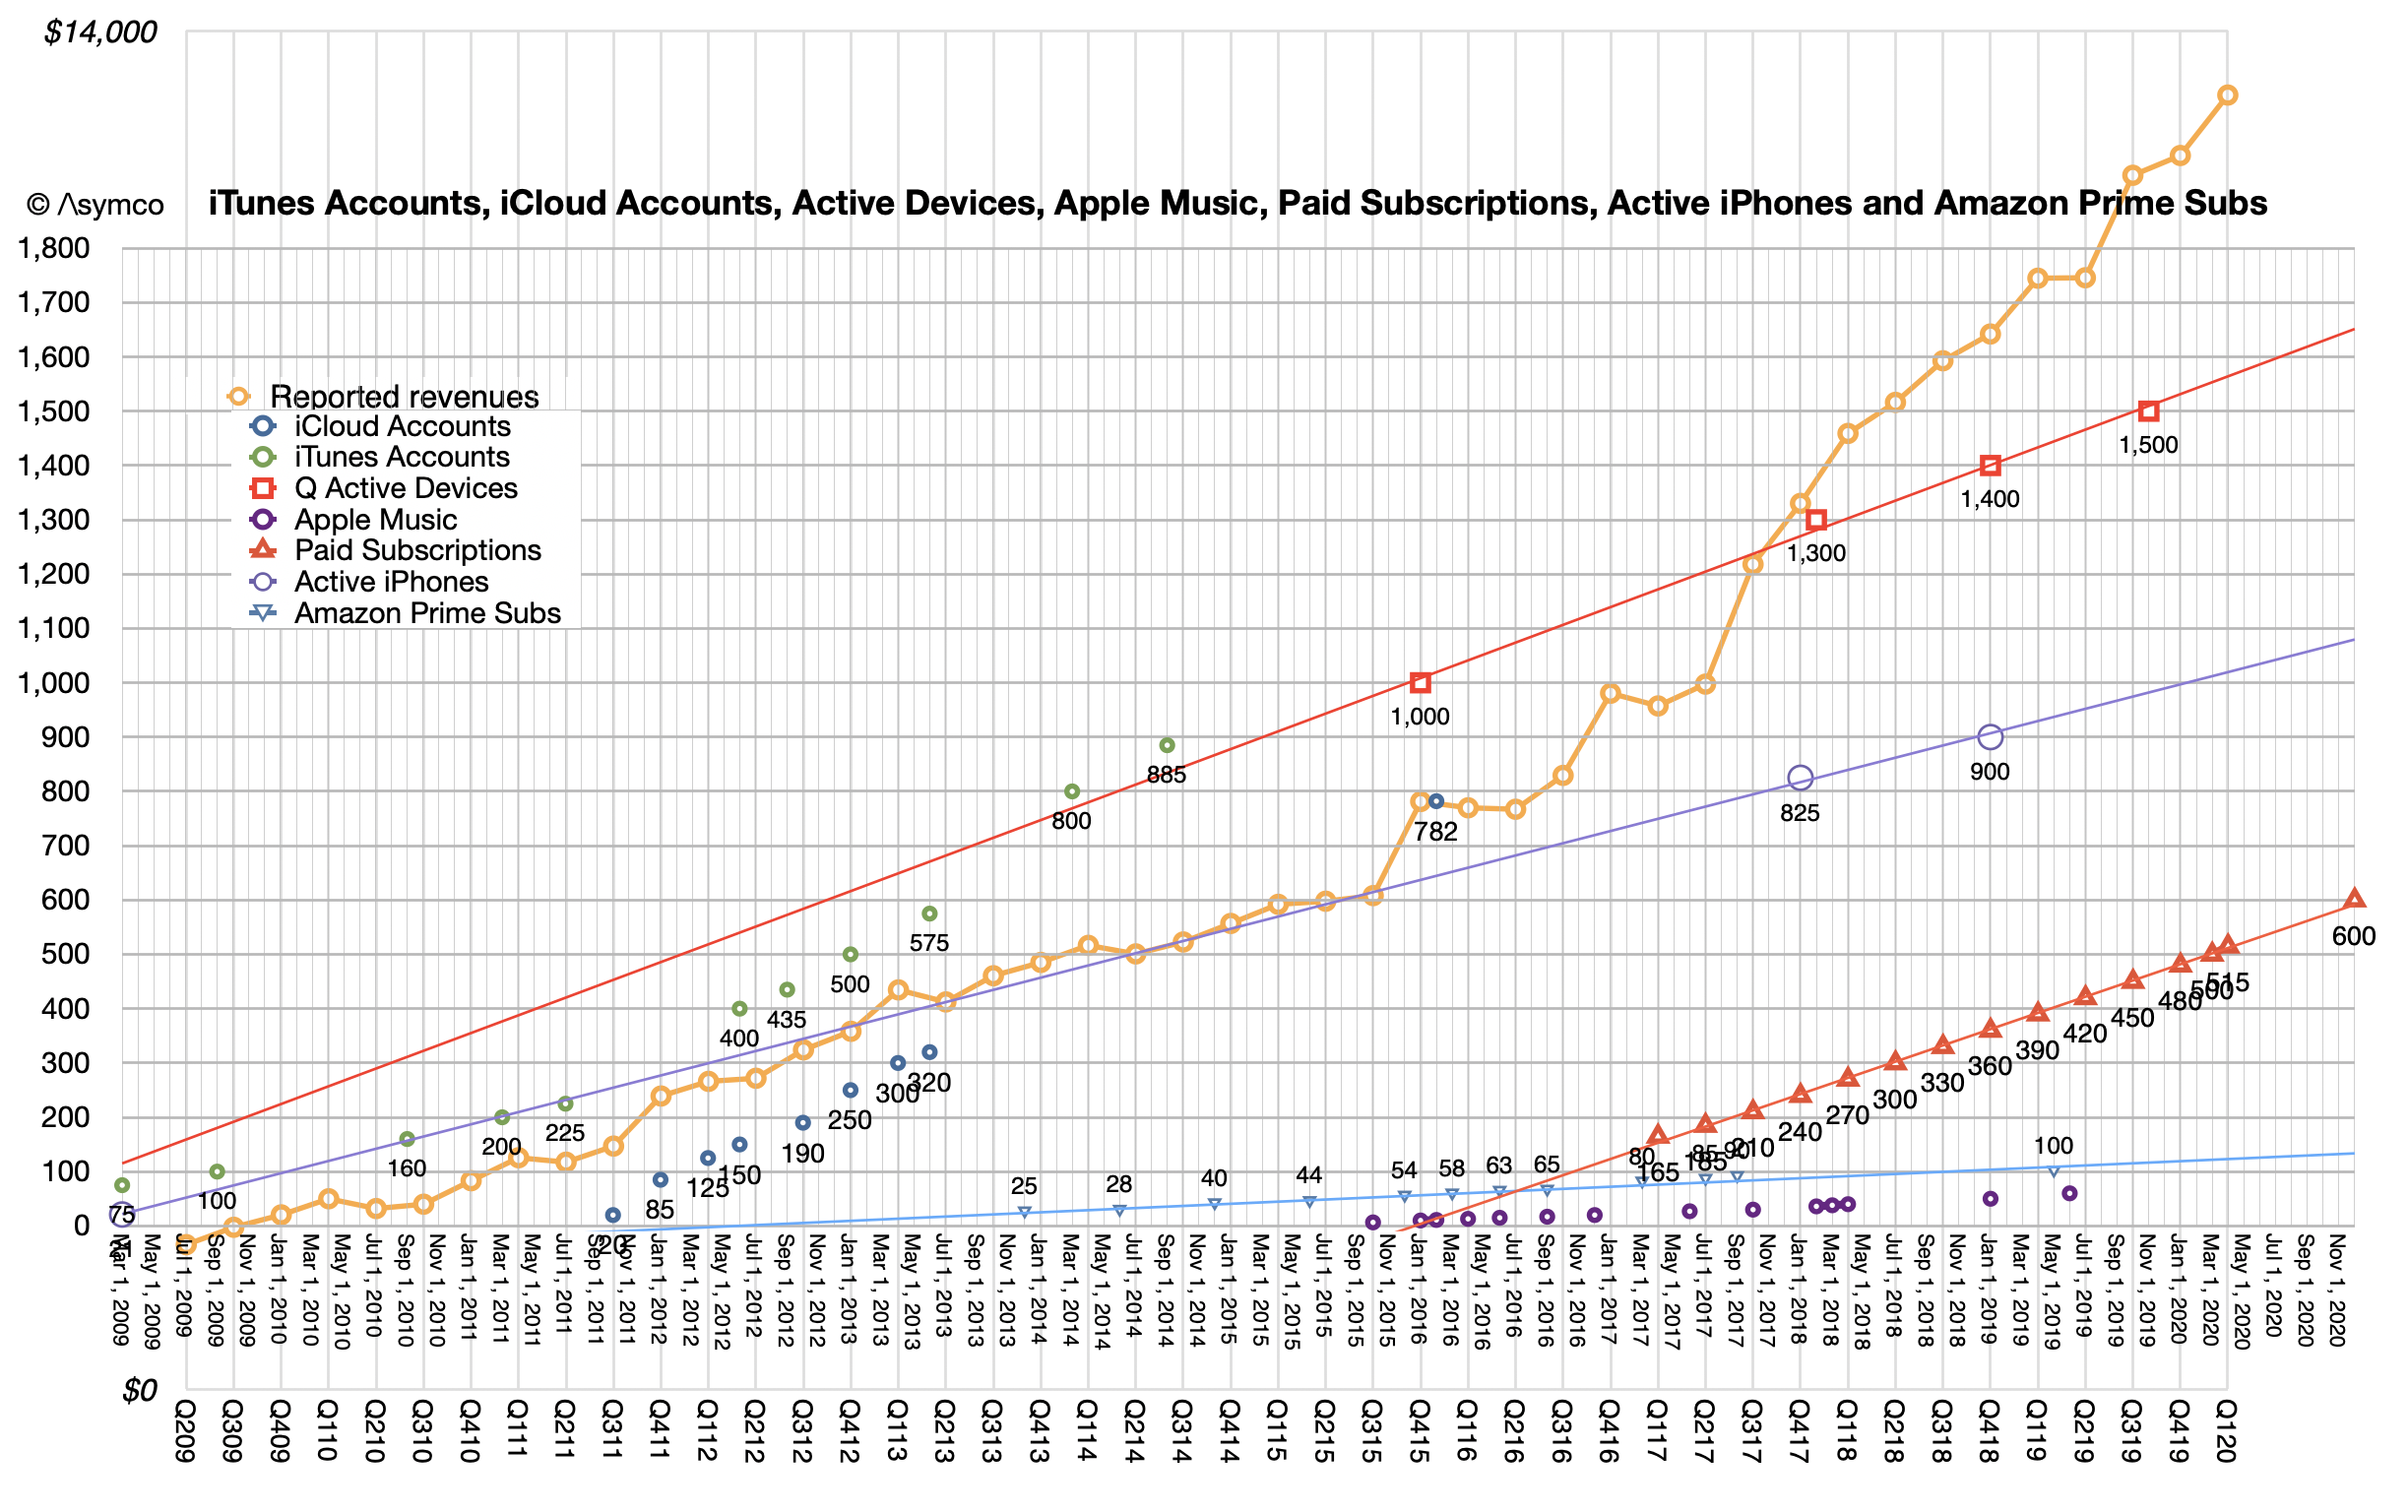
The Green and Black areas are also captured through subscriptions whose quantity is charted with triangles below. Note that the latest quarter saw an acceleration in the accumulation of subscriptions, putting the 600 million target set for end of this year closer than expected. Note also the change in slope of the yellow line as the triangles were added.
These two charts are an attempt to illustrate what is a huge set of activities. Apple's product lines may be something we can grasp in terms of objects for sale and price points, and feature sets, etc. But the Ecosystem that sits on top of these devices is not comprehensible.
There are literally millions of apps, services, and ways of delivering and capturing value. There are millions of people employed in what amounts to an economy bigger than the 25th largest in the world (Belgium (1)). It's half a trillion dollars of activity.
Given the growth of the underlying Services segment (~15%), it's probably going to double in 5 years to $1 trillion. Apple will certainly benefit as even if only 9% of that is booked as direct revenues, the rest will create resilience in the user base.
The power of an ecosystem isn't what Apple is able to skim from it but rather that millions of other people will want to encourage and preserve its existence as their livelihoods, hopes and aspirations will depend on it. This goes beyond loyalty of end users (which is extraordinary) as it's a loyalty of those who co-invest in it. All participants in an ecosystem become partners in its preservation.
Apple is not the only technological ecosystem out there, but I'm willing to bet that it's the most vibrant in terms of creative effort, economic value and growth.
This ecosystem is a thunderous declaration of value which is largely unheard by investors or analysts. While looking at the potential for growing the direct revenue with "+" Apple services, the indirect, qualitative added value of services which never hit Apple's income statement are ignored. Like the ignored value of a satisfied customer, how much is the value of an economic co-dependency?
Although it's inappropriate to compare a company's market capitalization (which is a measure of asset value) with GDP (which is a measure of economic activity) an "economy" like the value of all transactions in an ecosystem is comparable with GDP.
In March 2016 Ben Bajarin and I put on an event called SUBSCRIBE where we asked, among other things,
How will the online services business models evolve?
How will hardware affect software and services and vice versa?
How will users, usage, and capital connect?
Now is a good time to look back on that event.
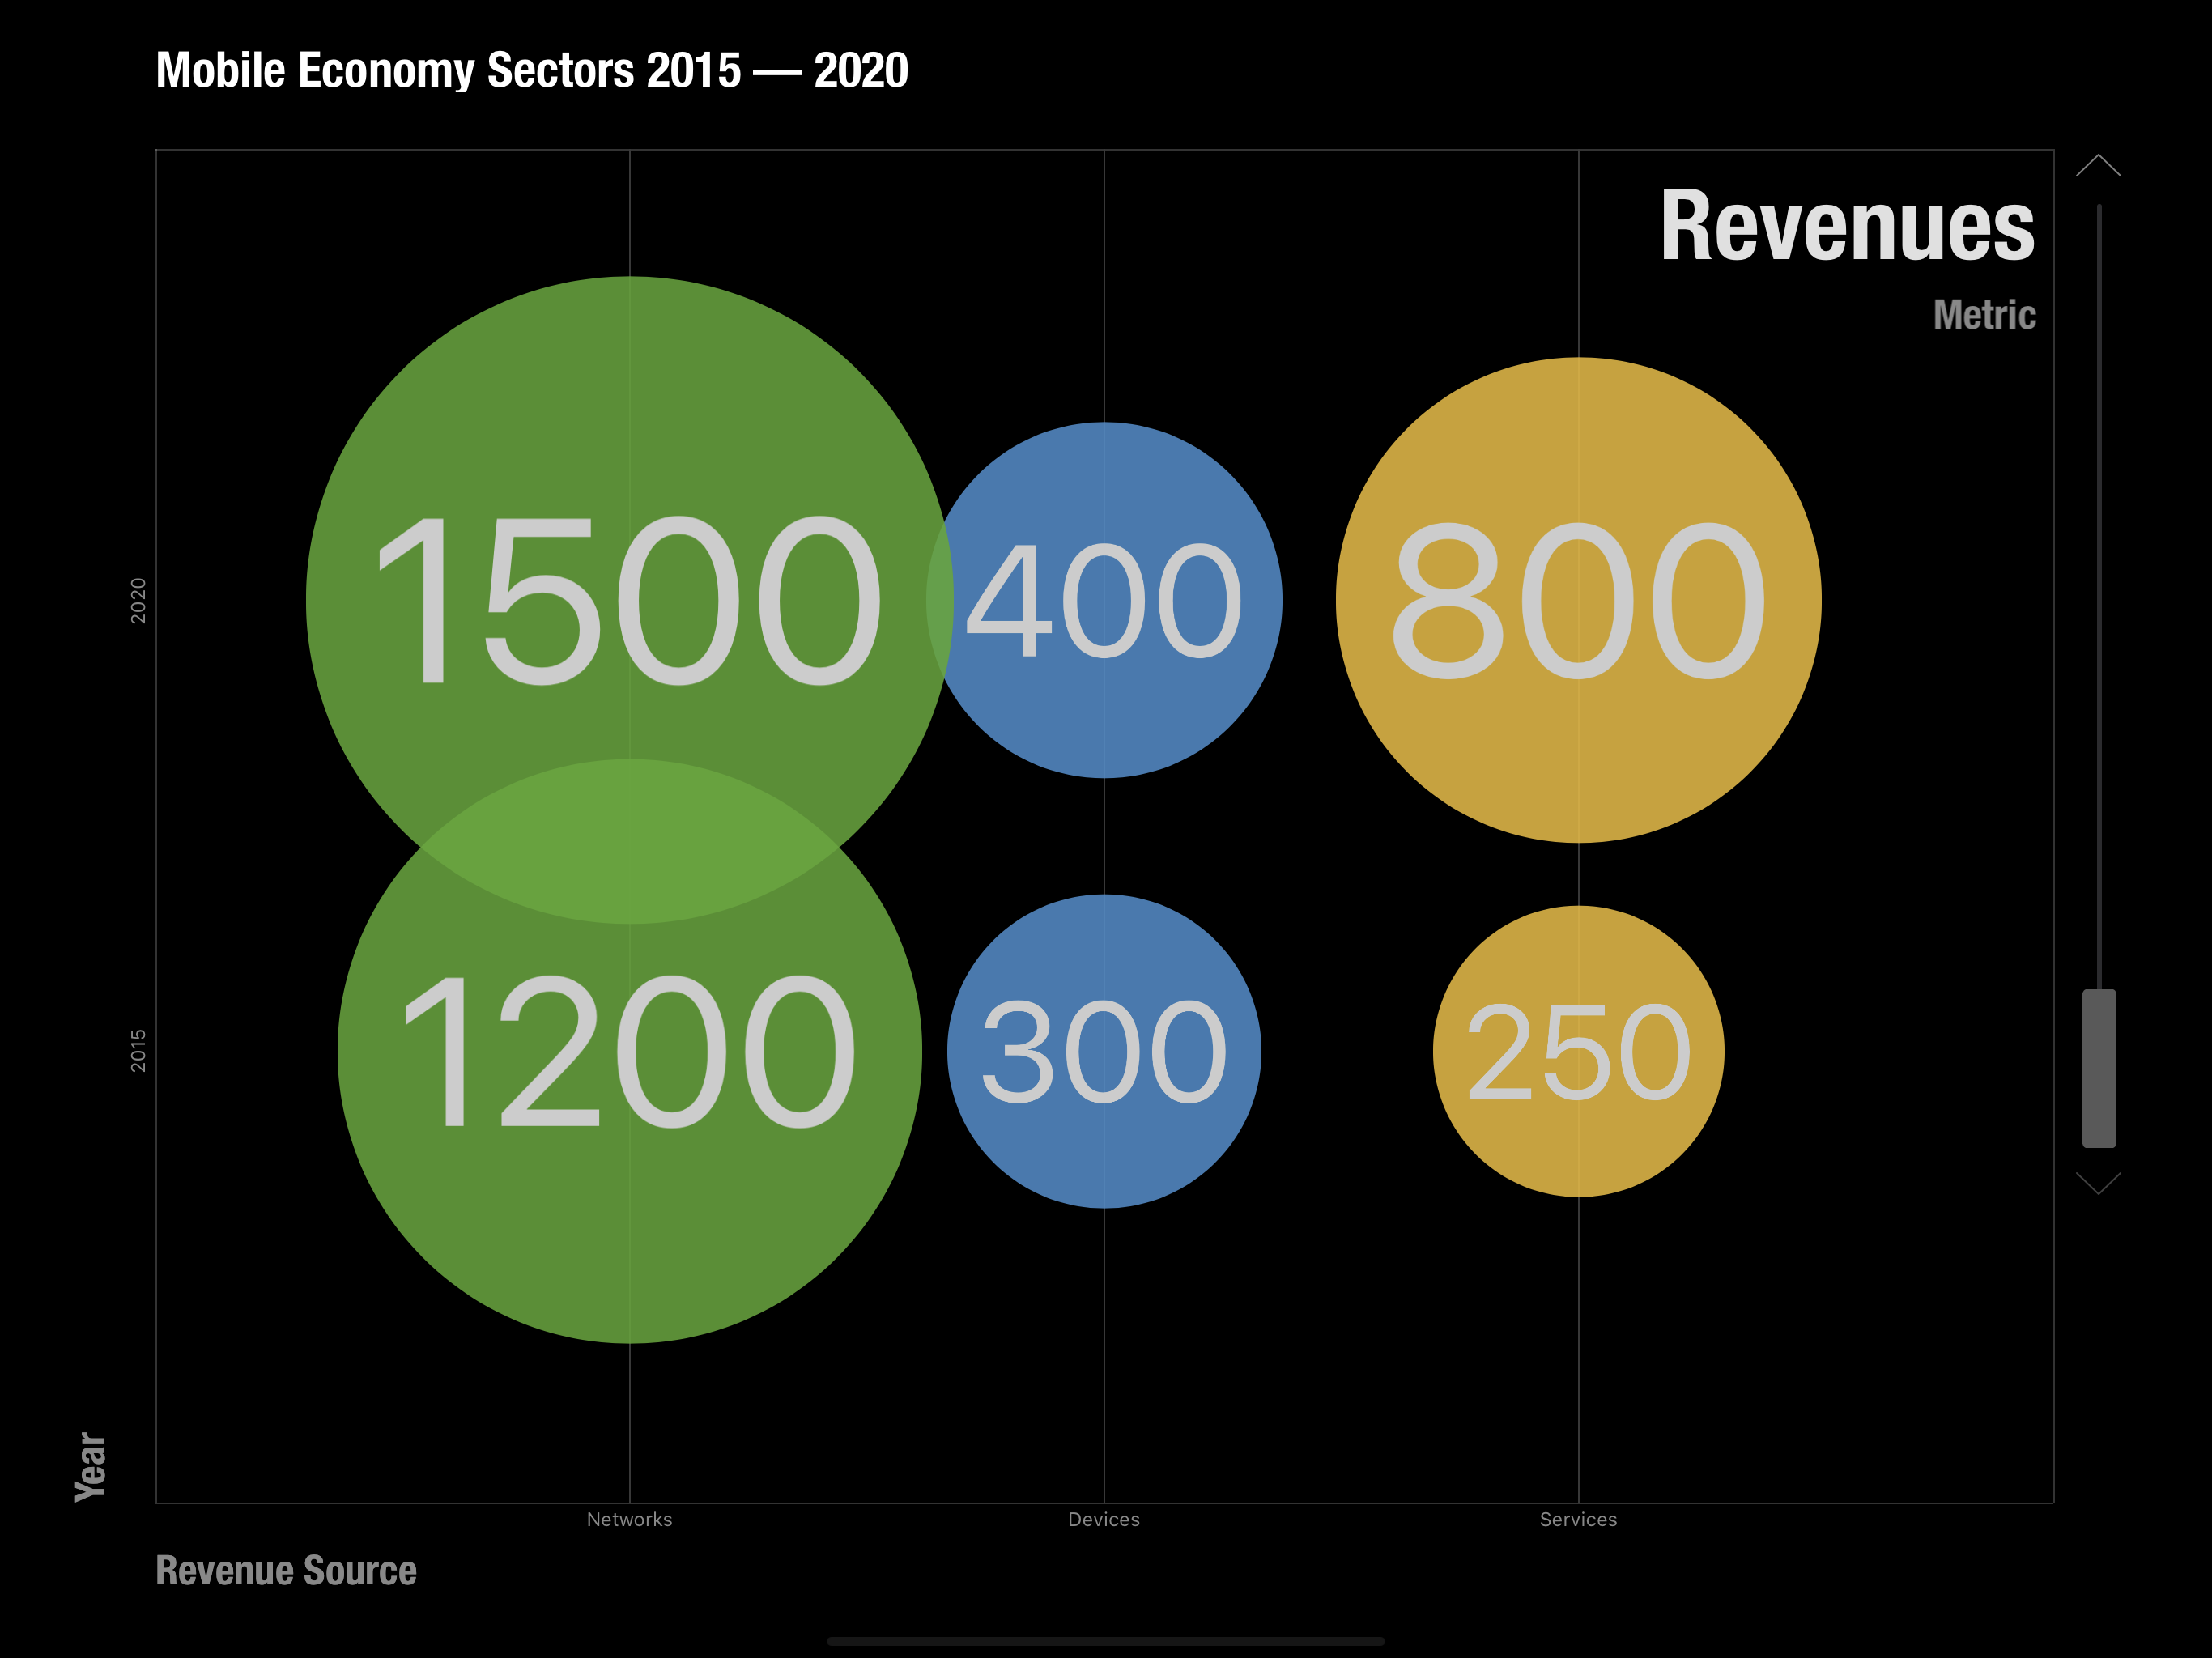
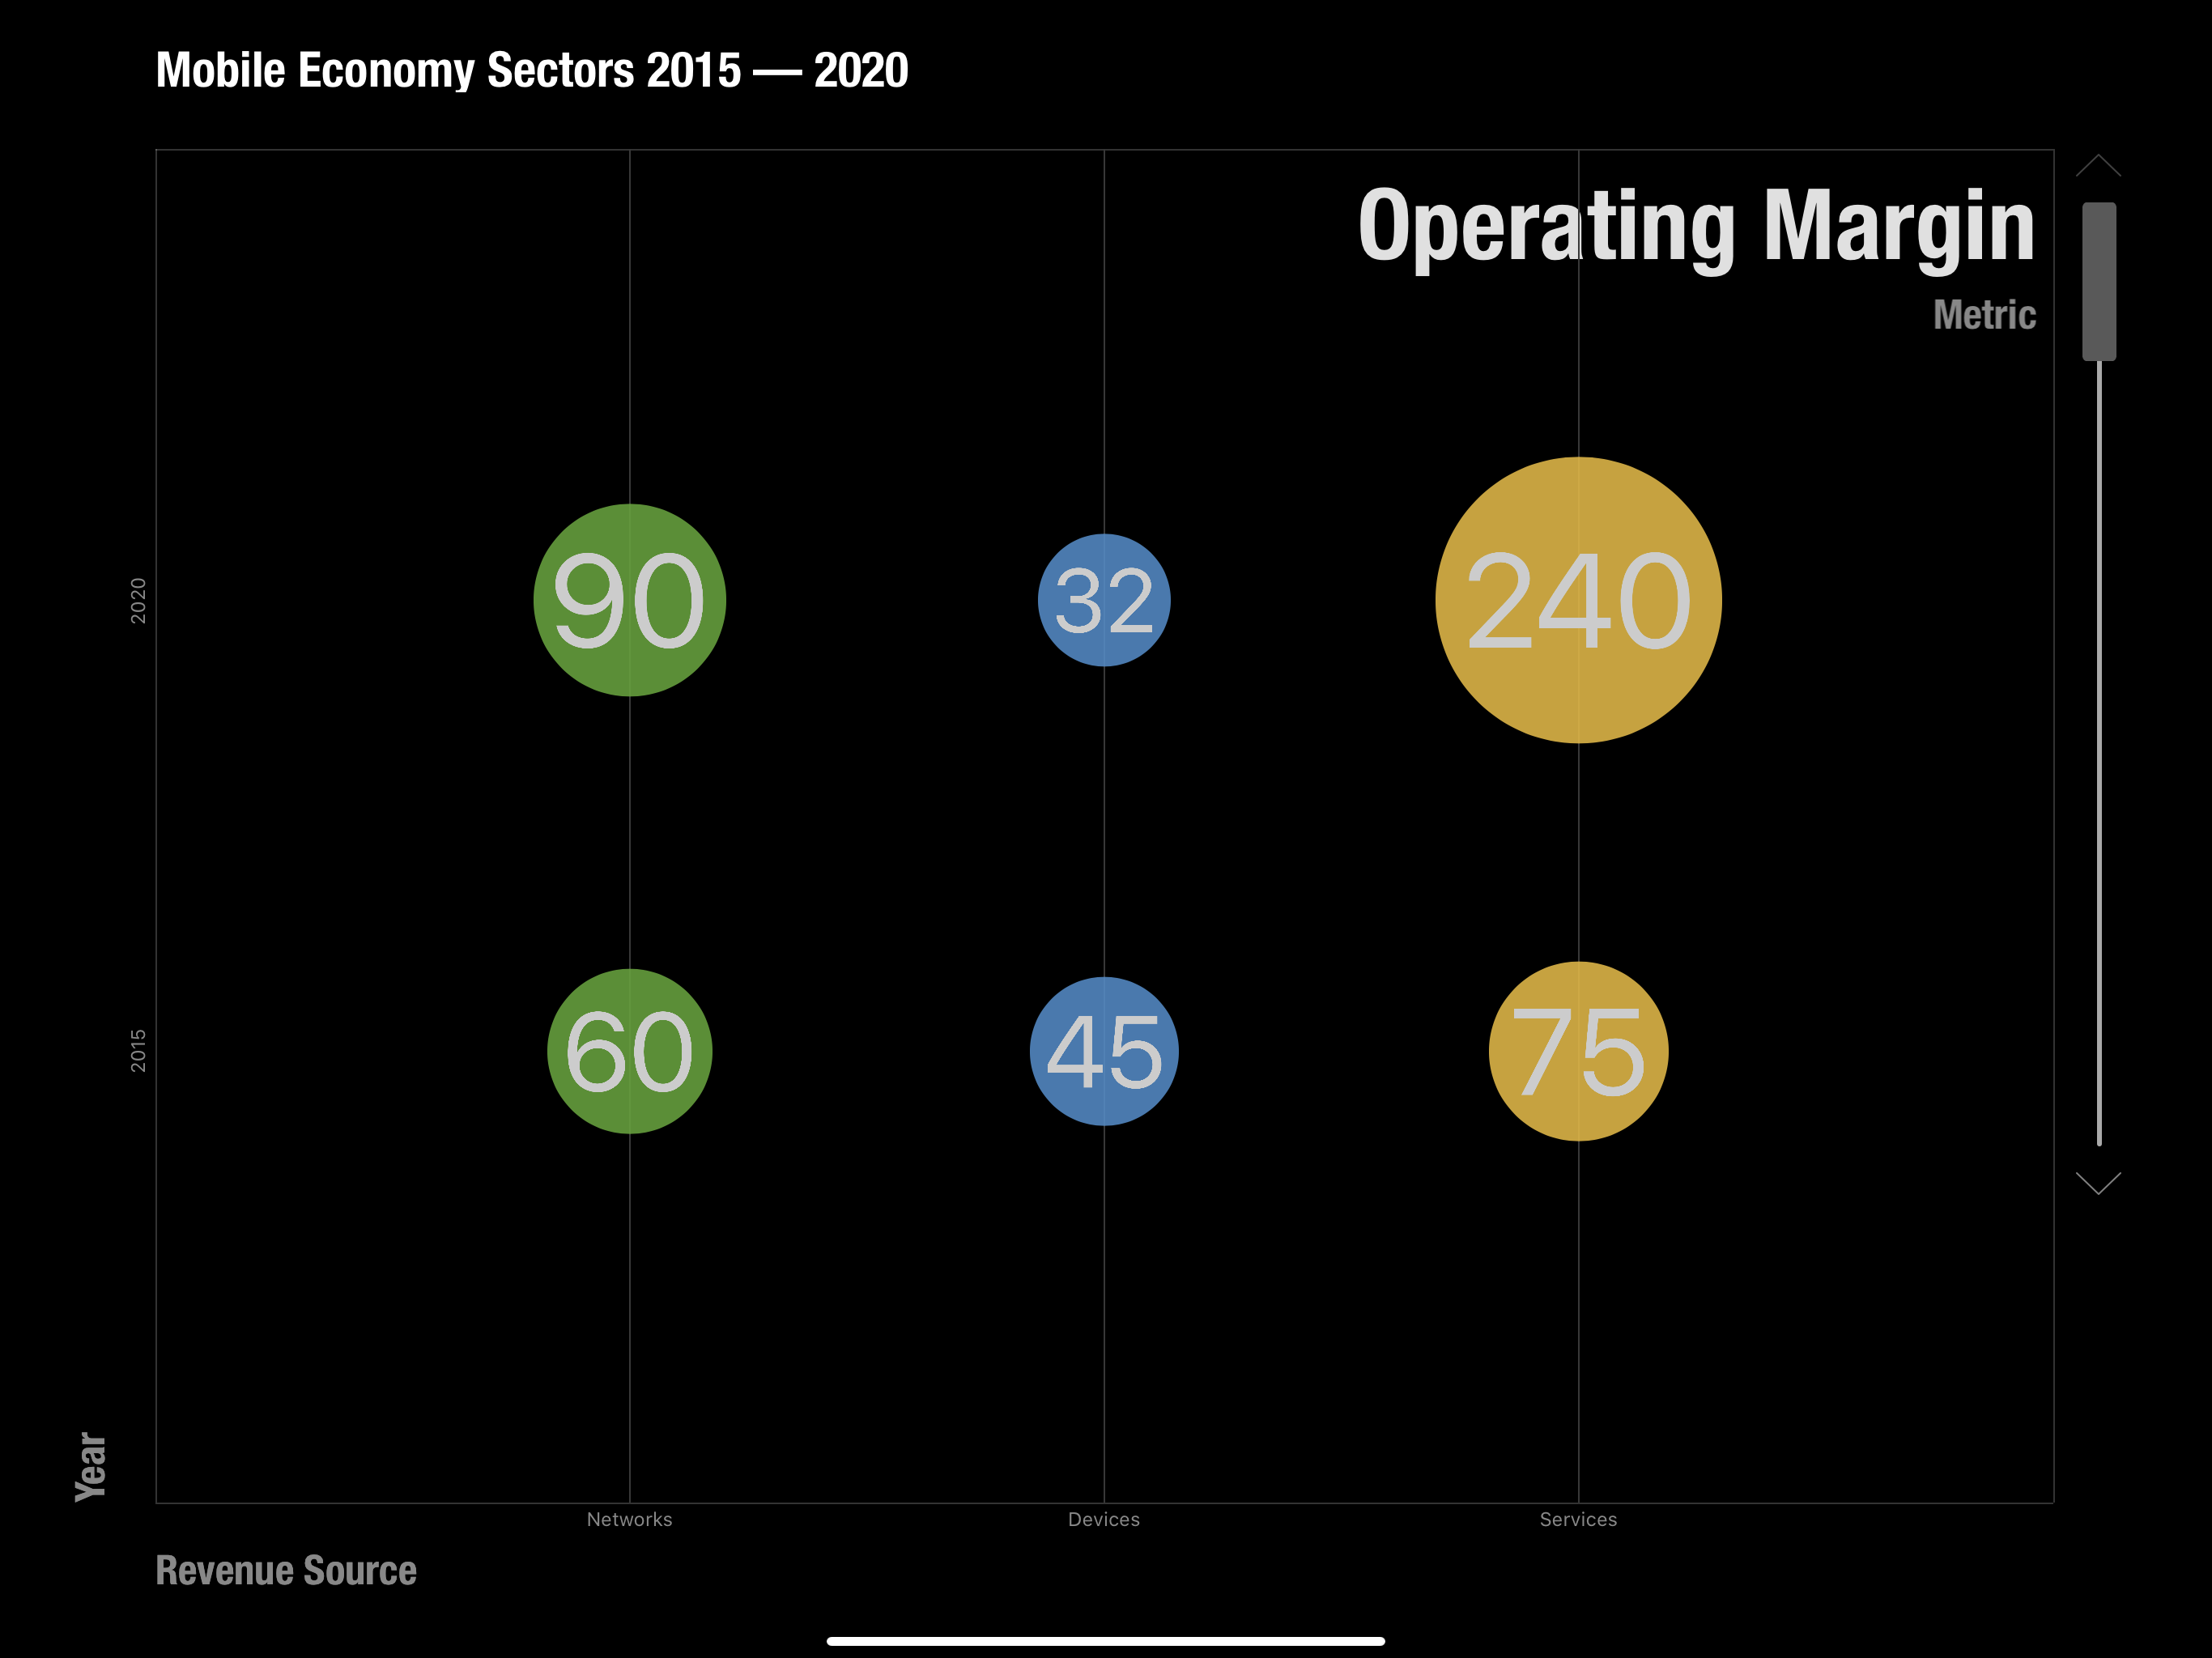
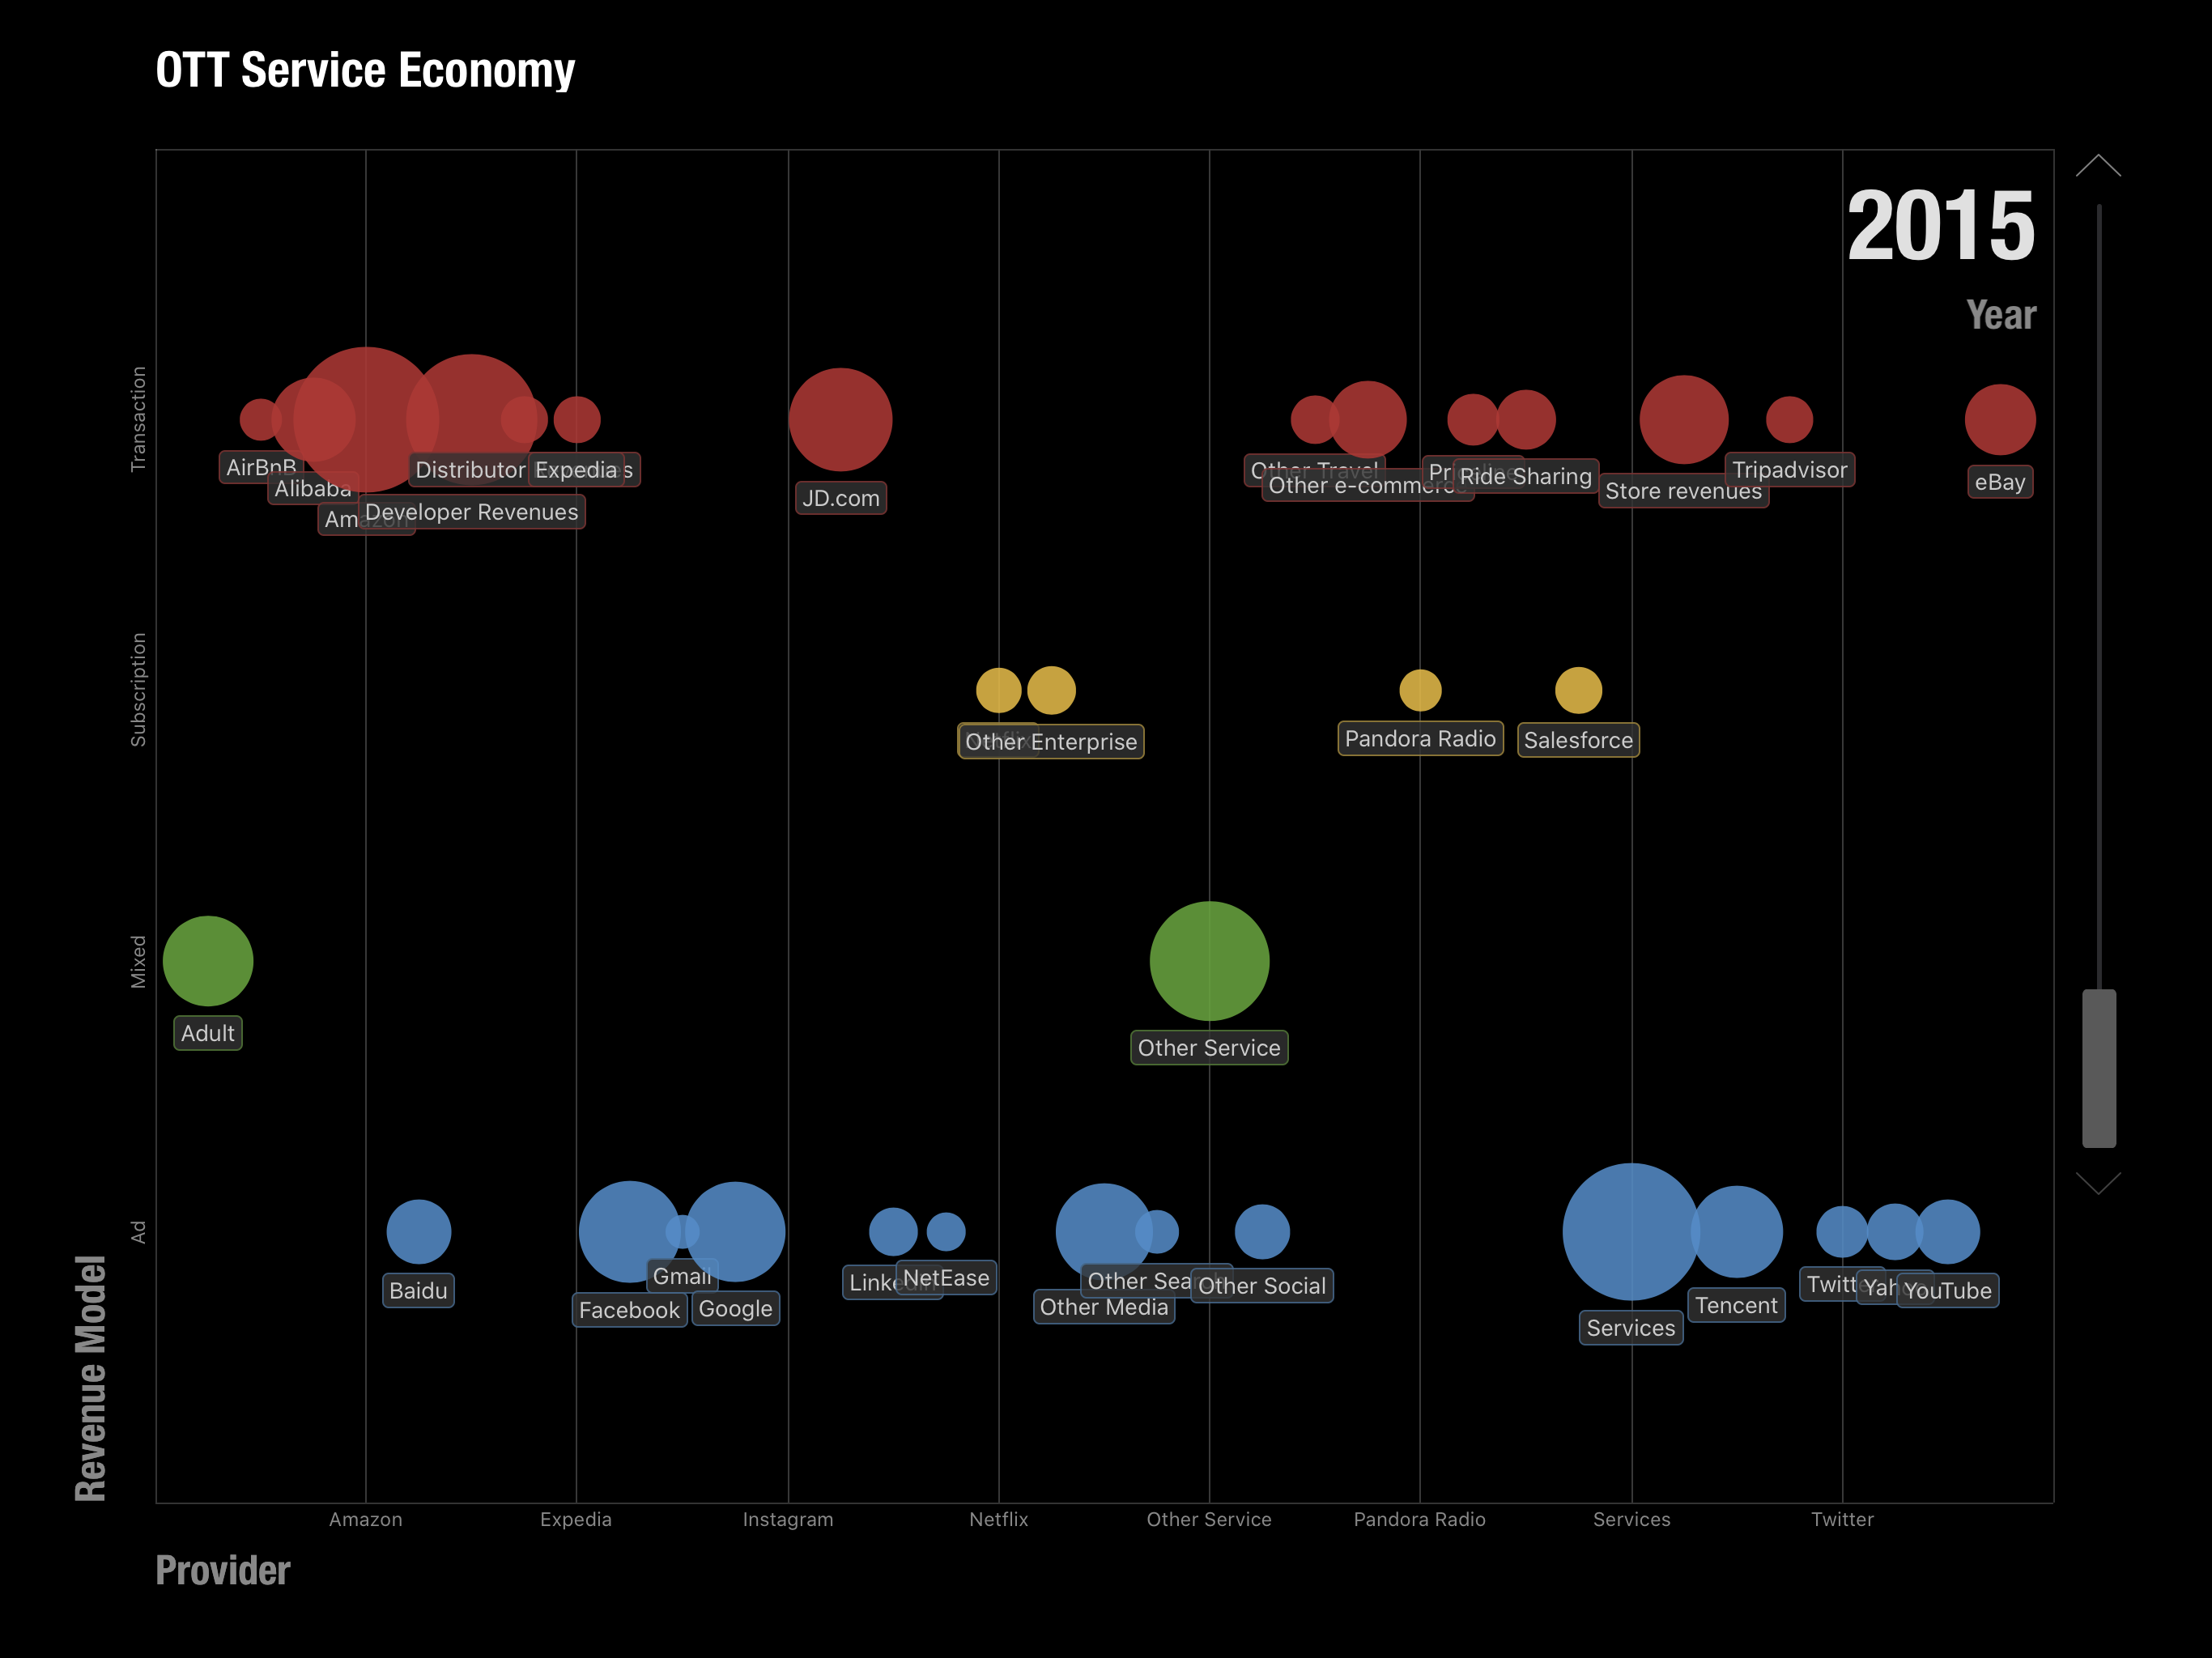
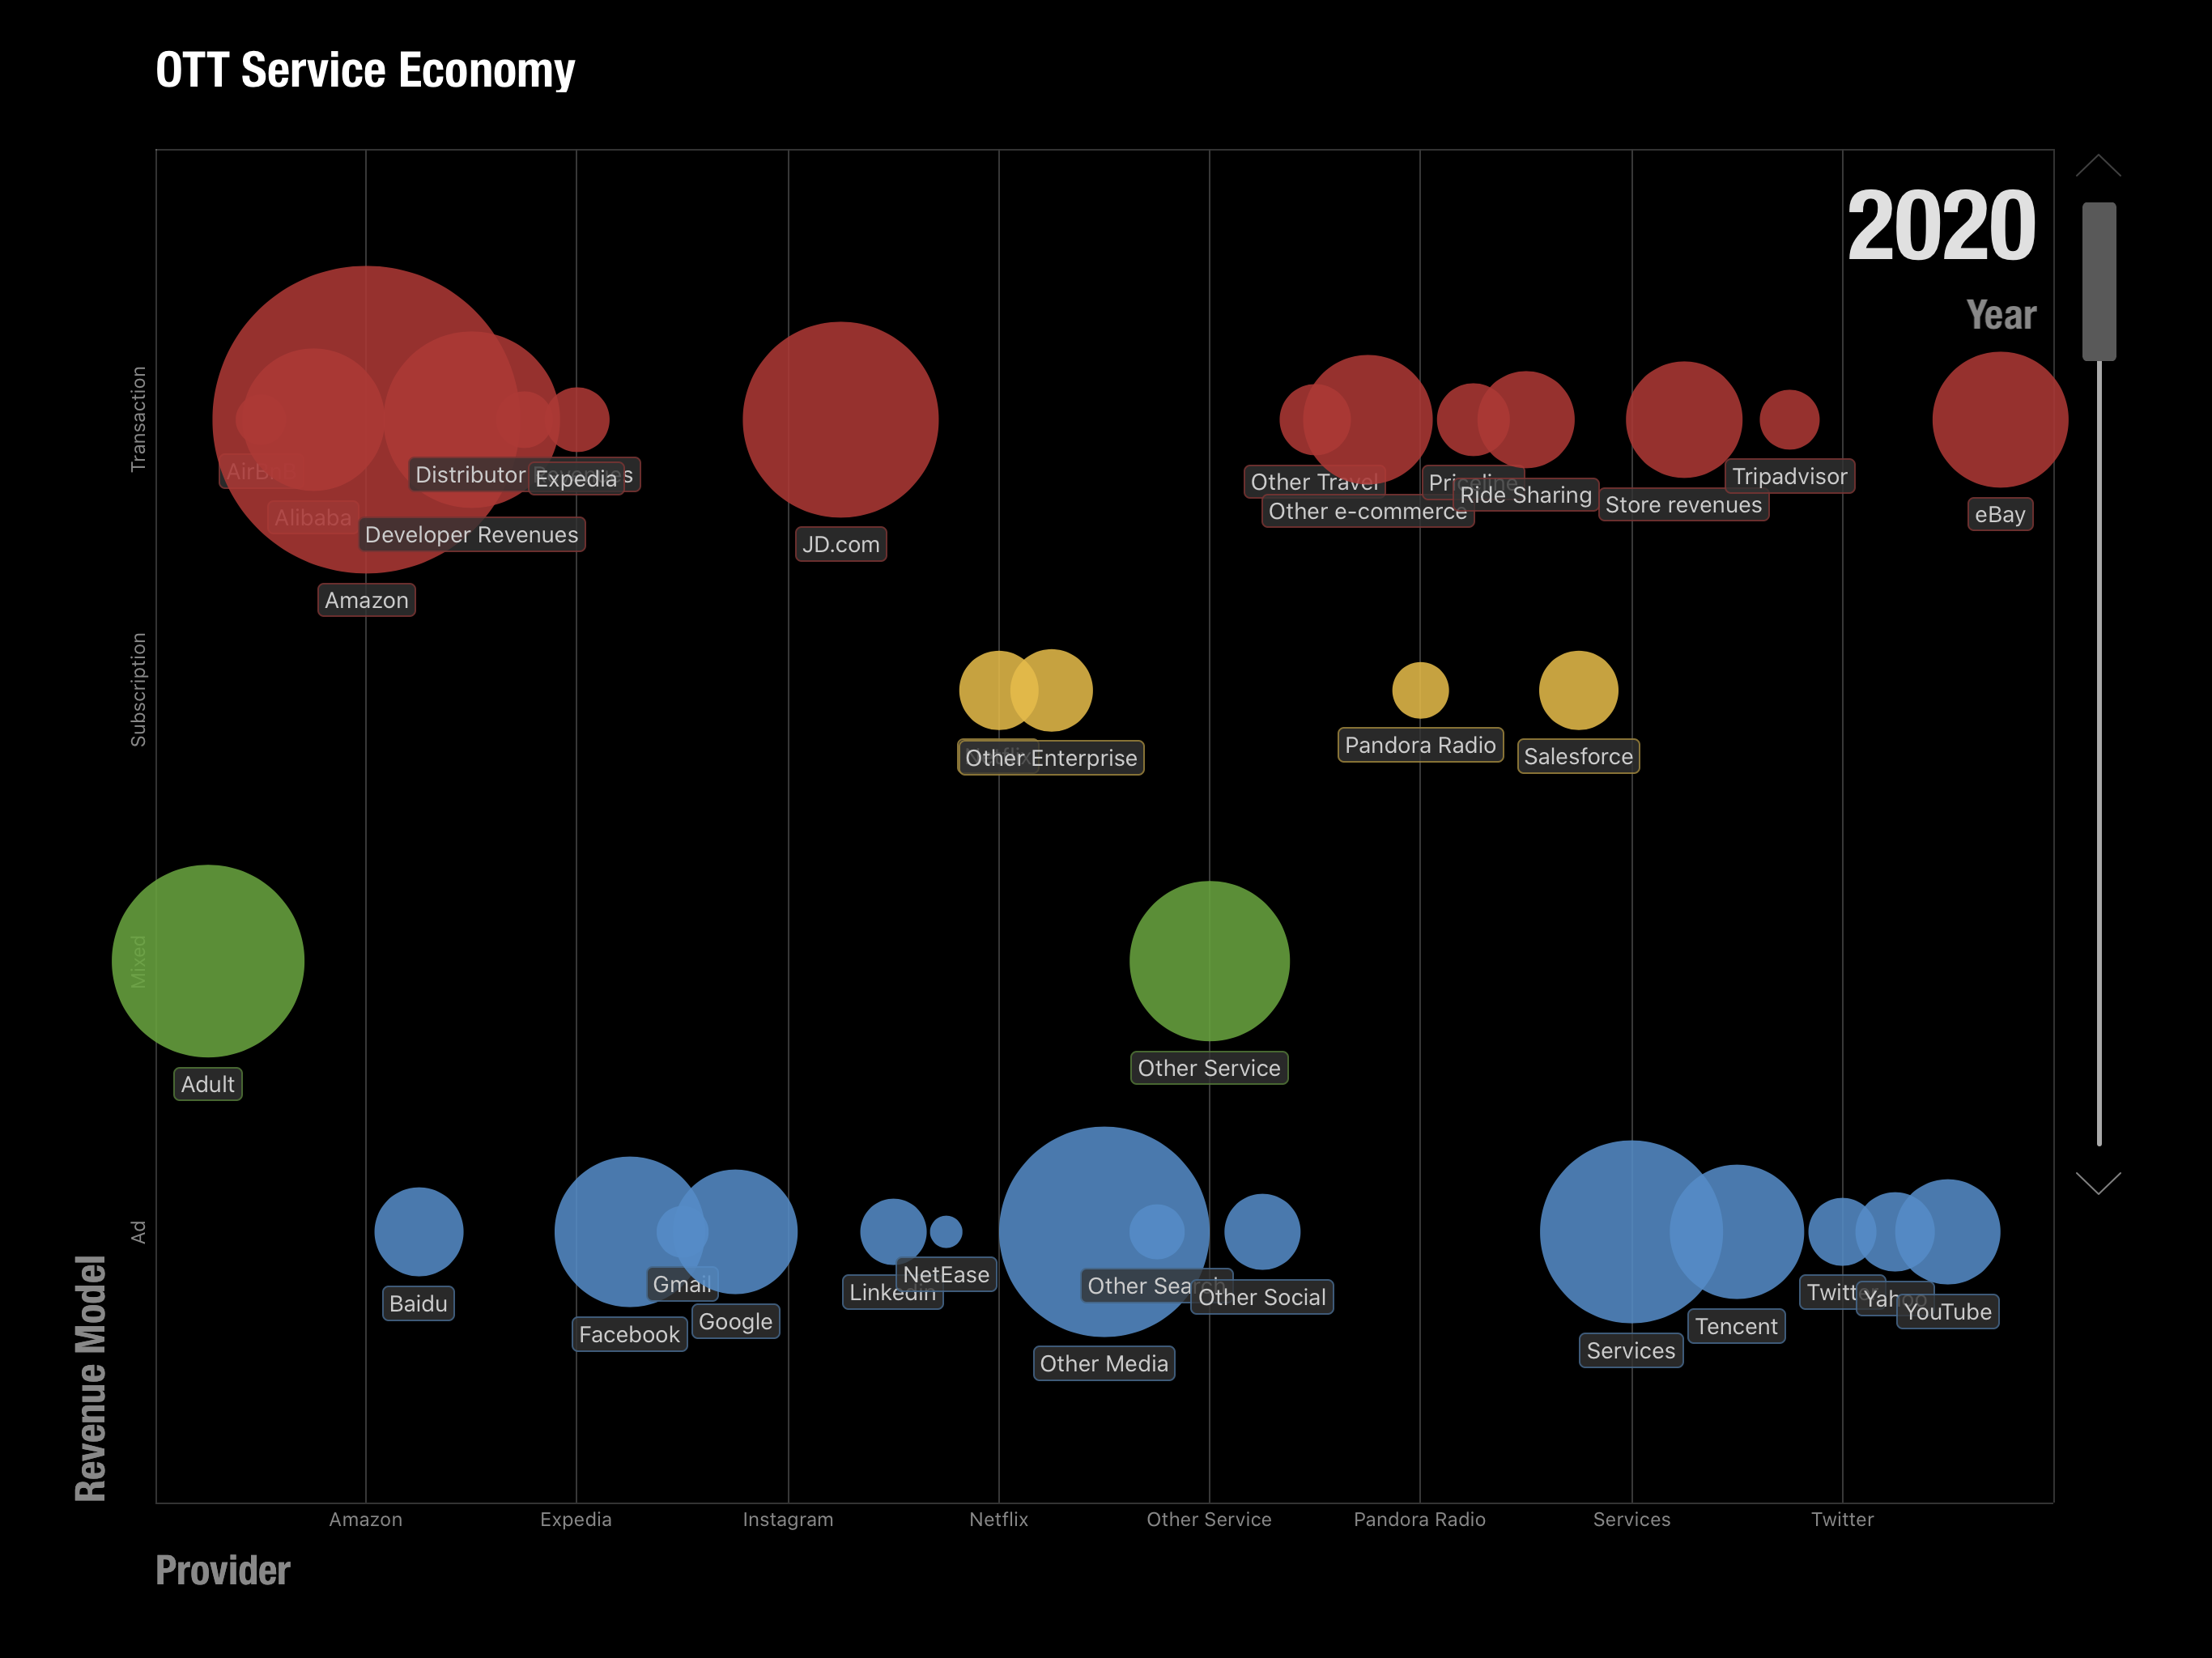
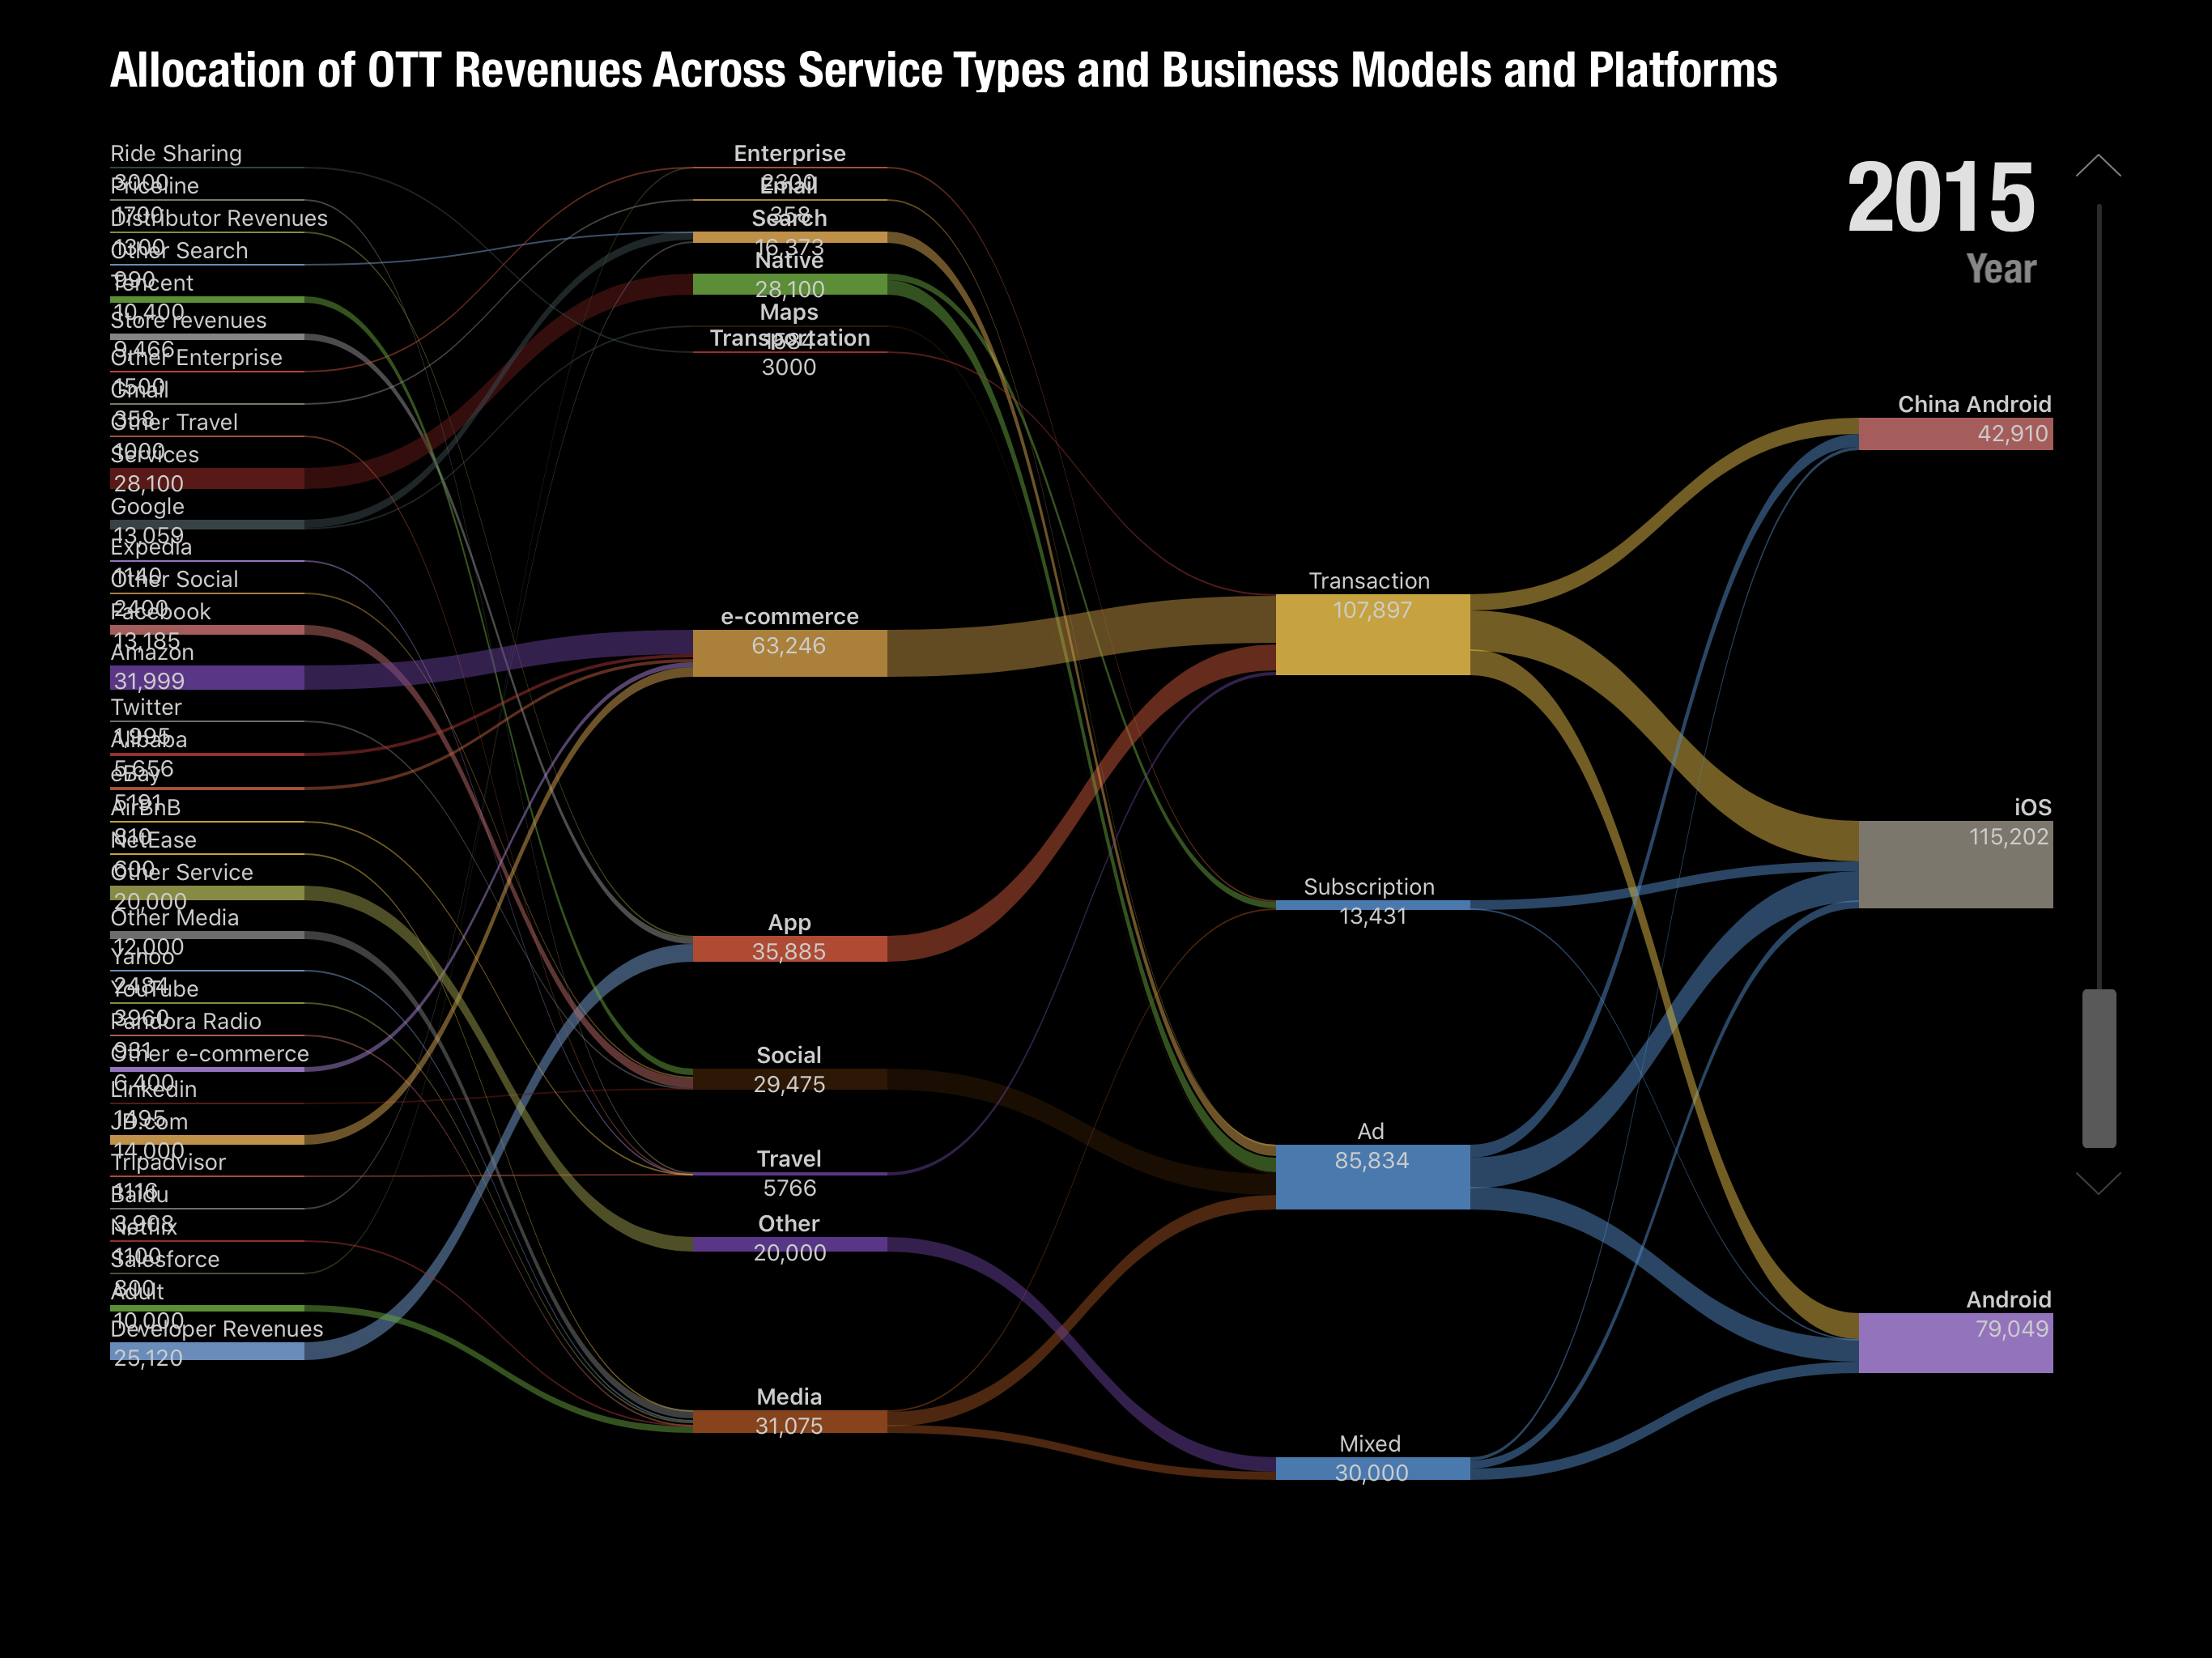
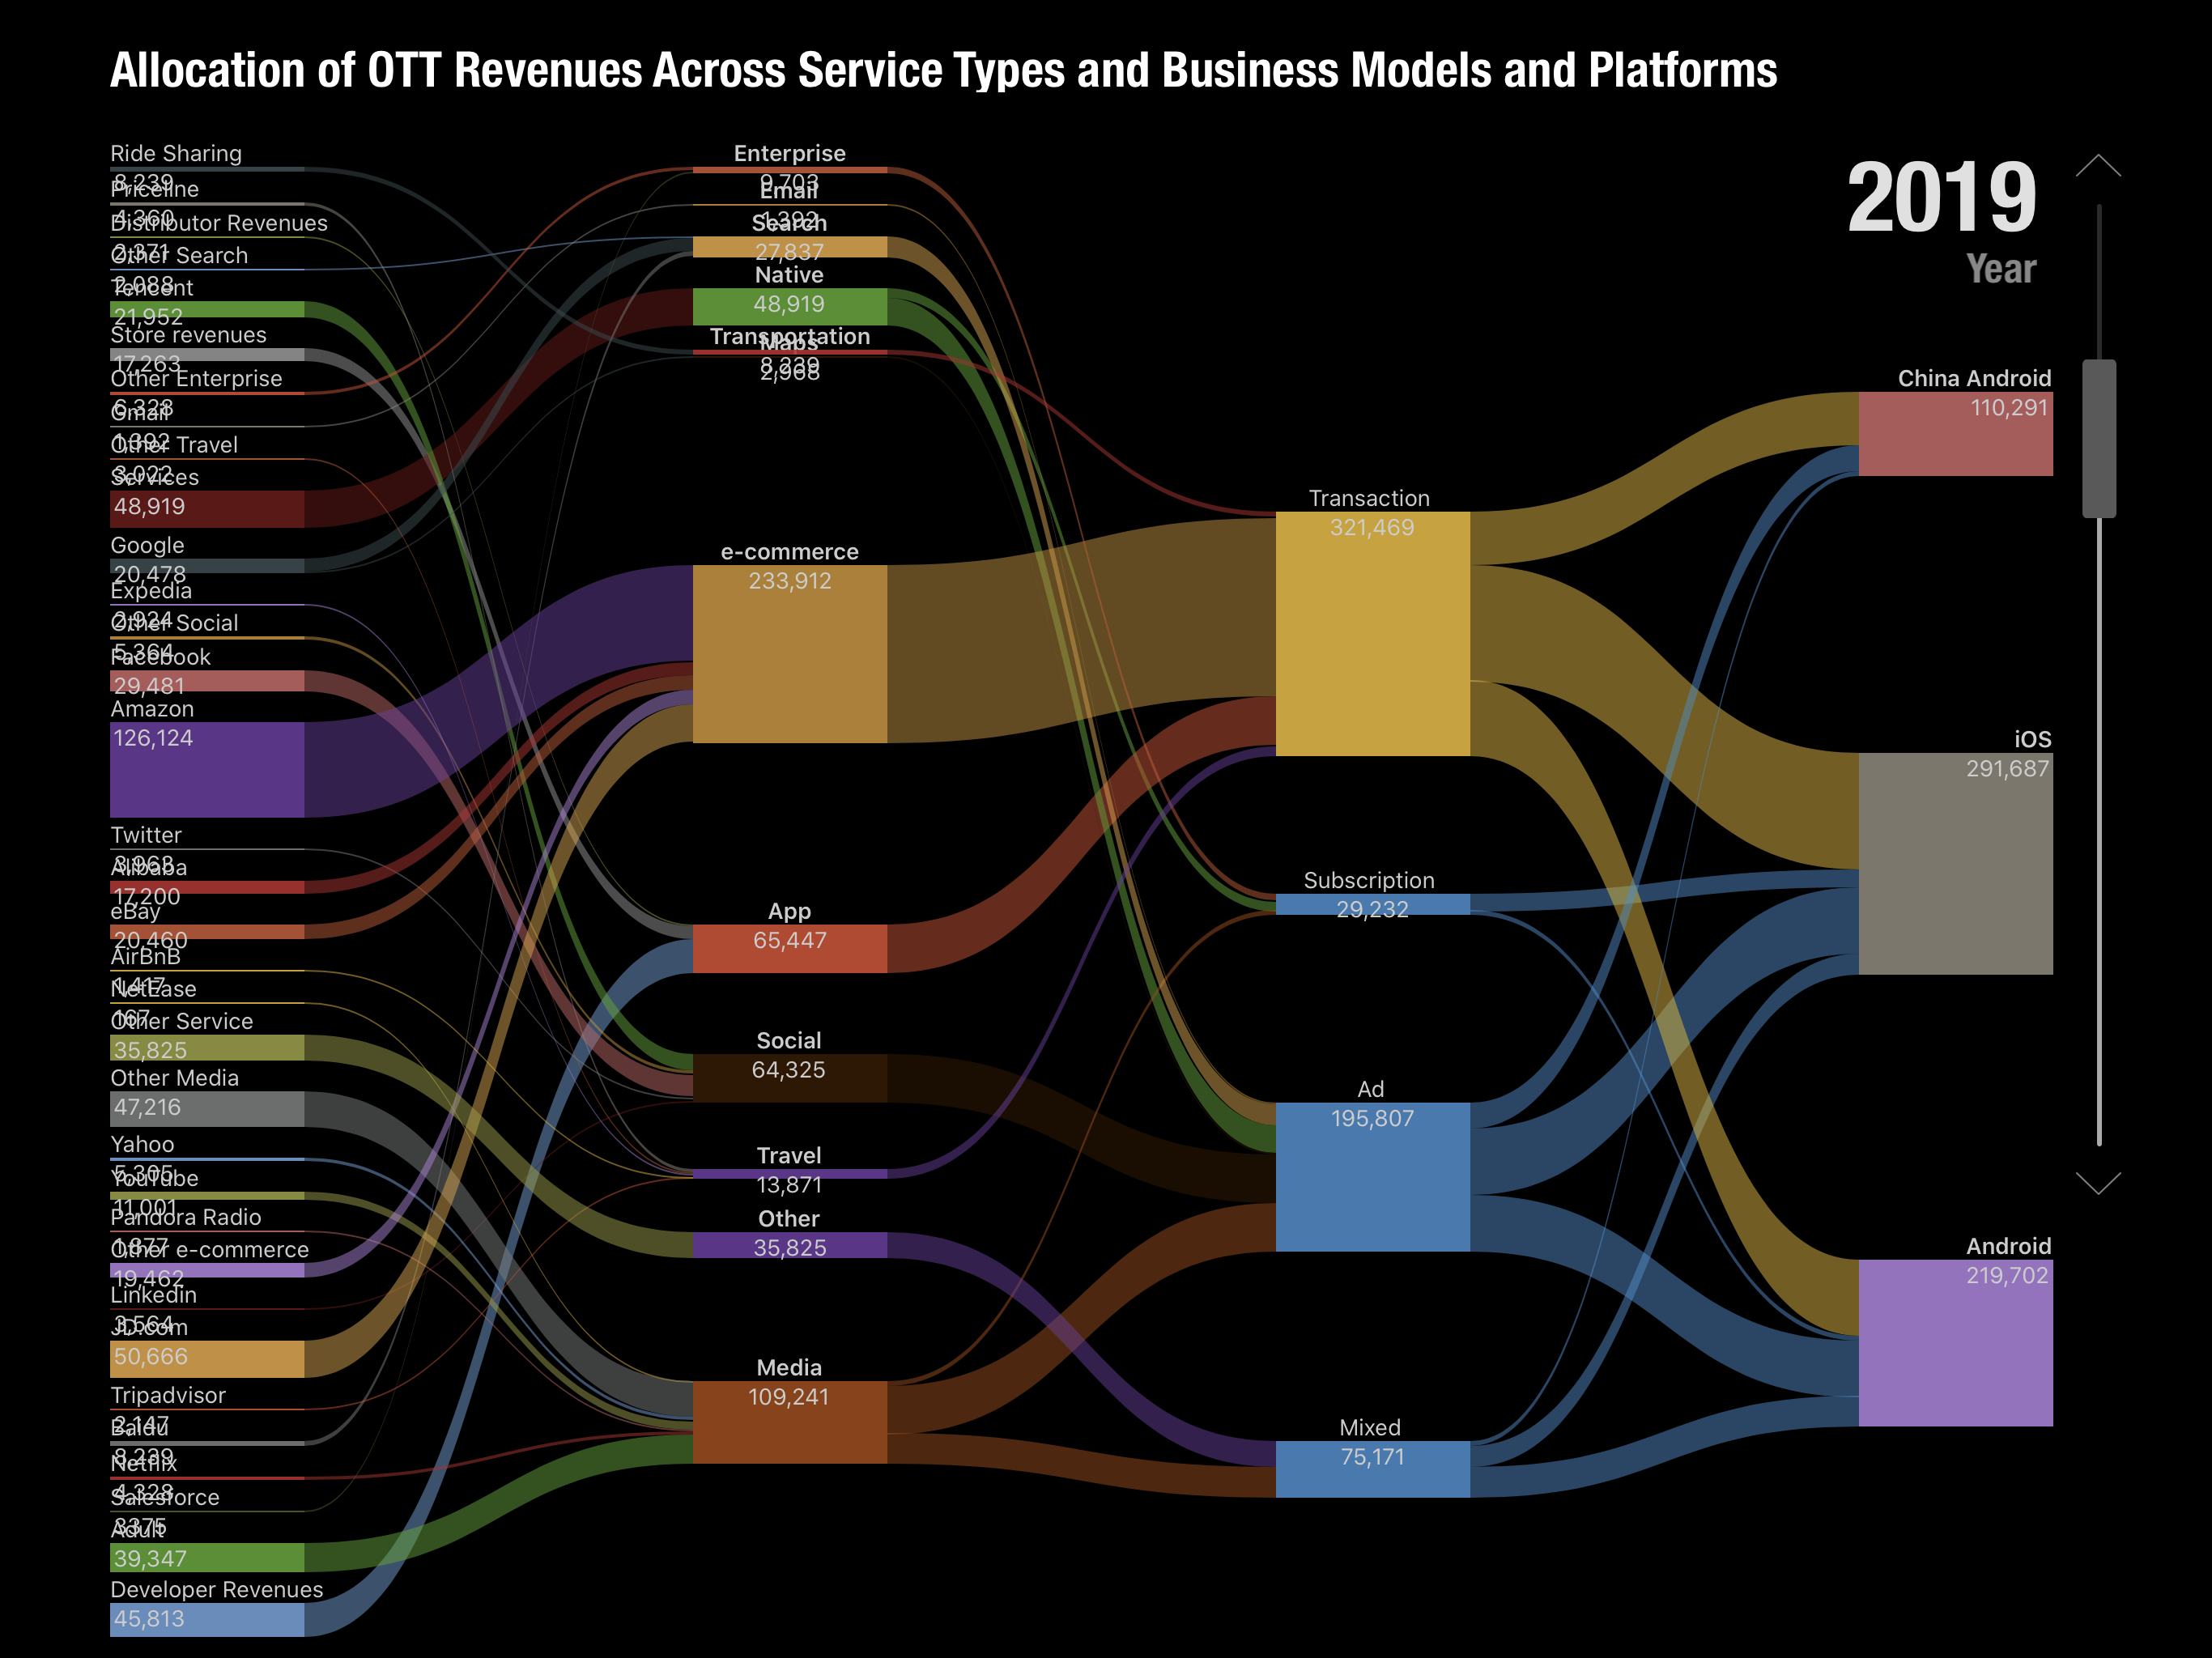
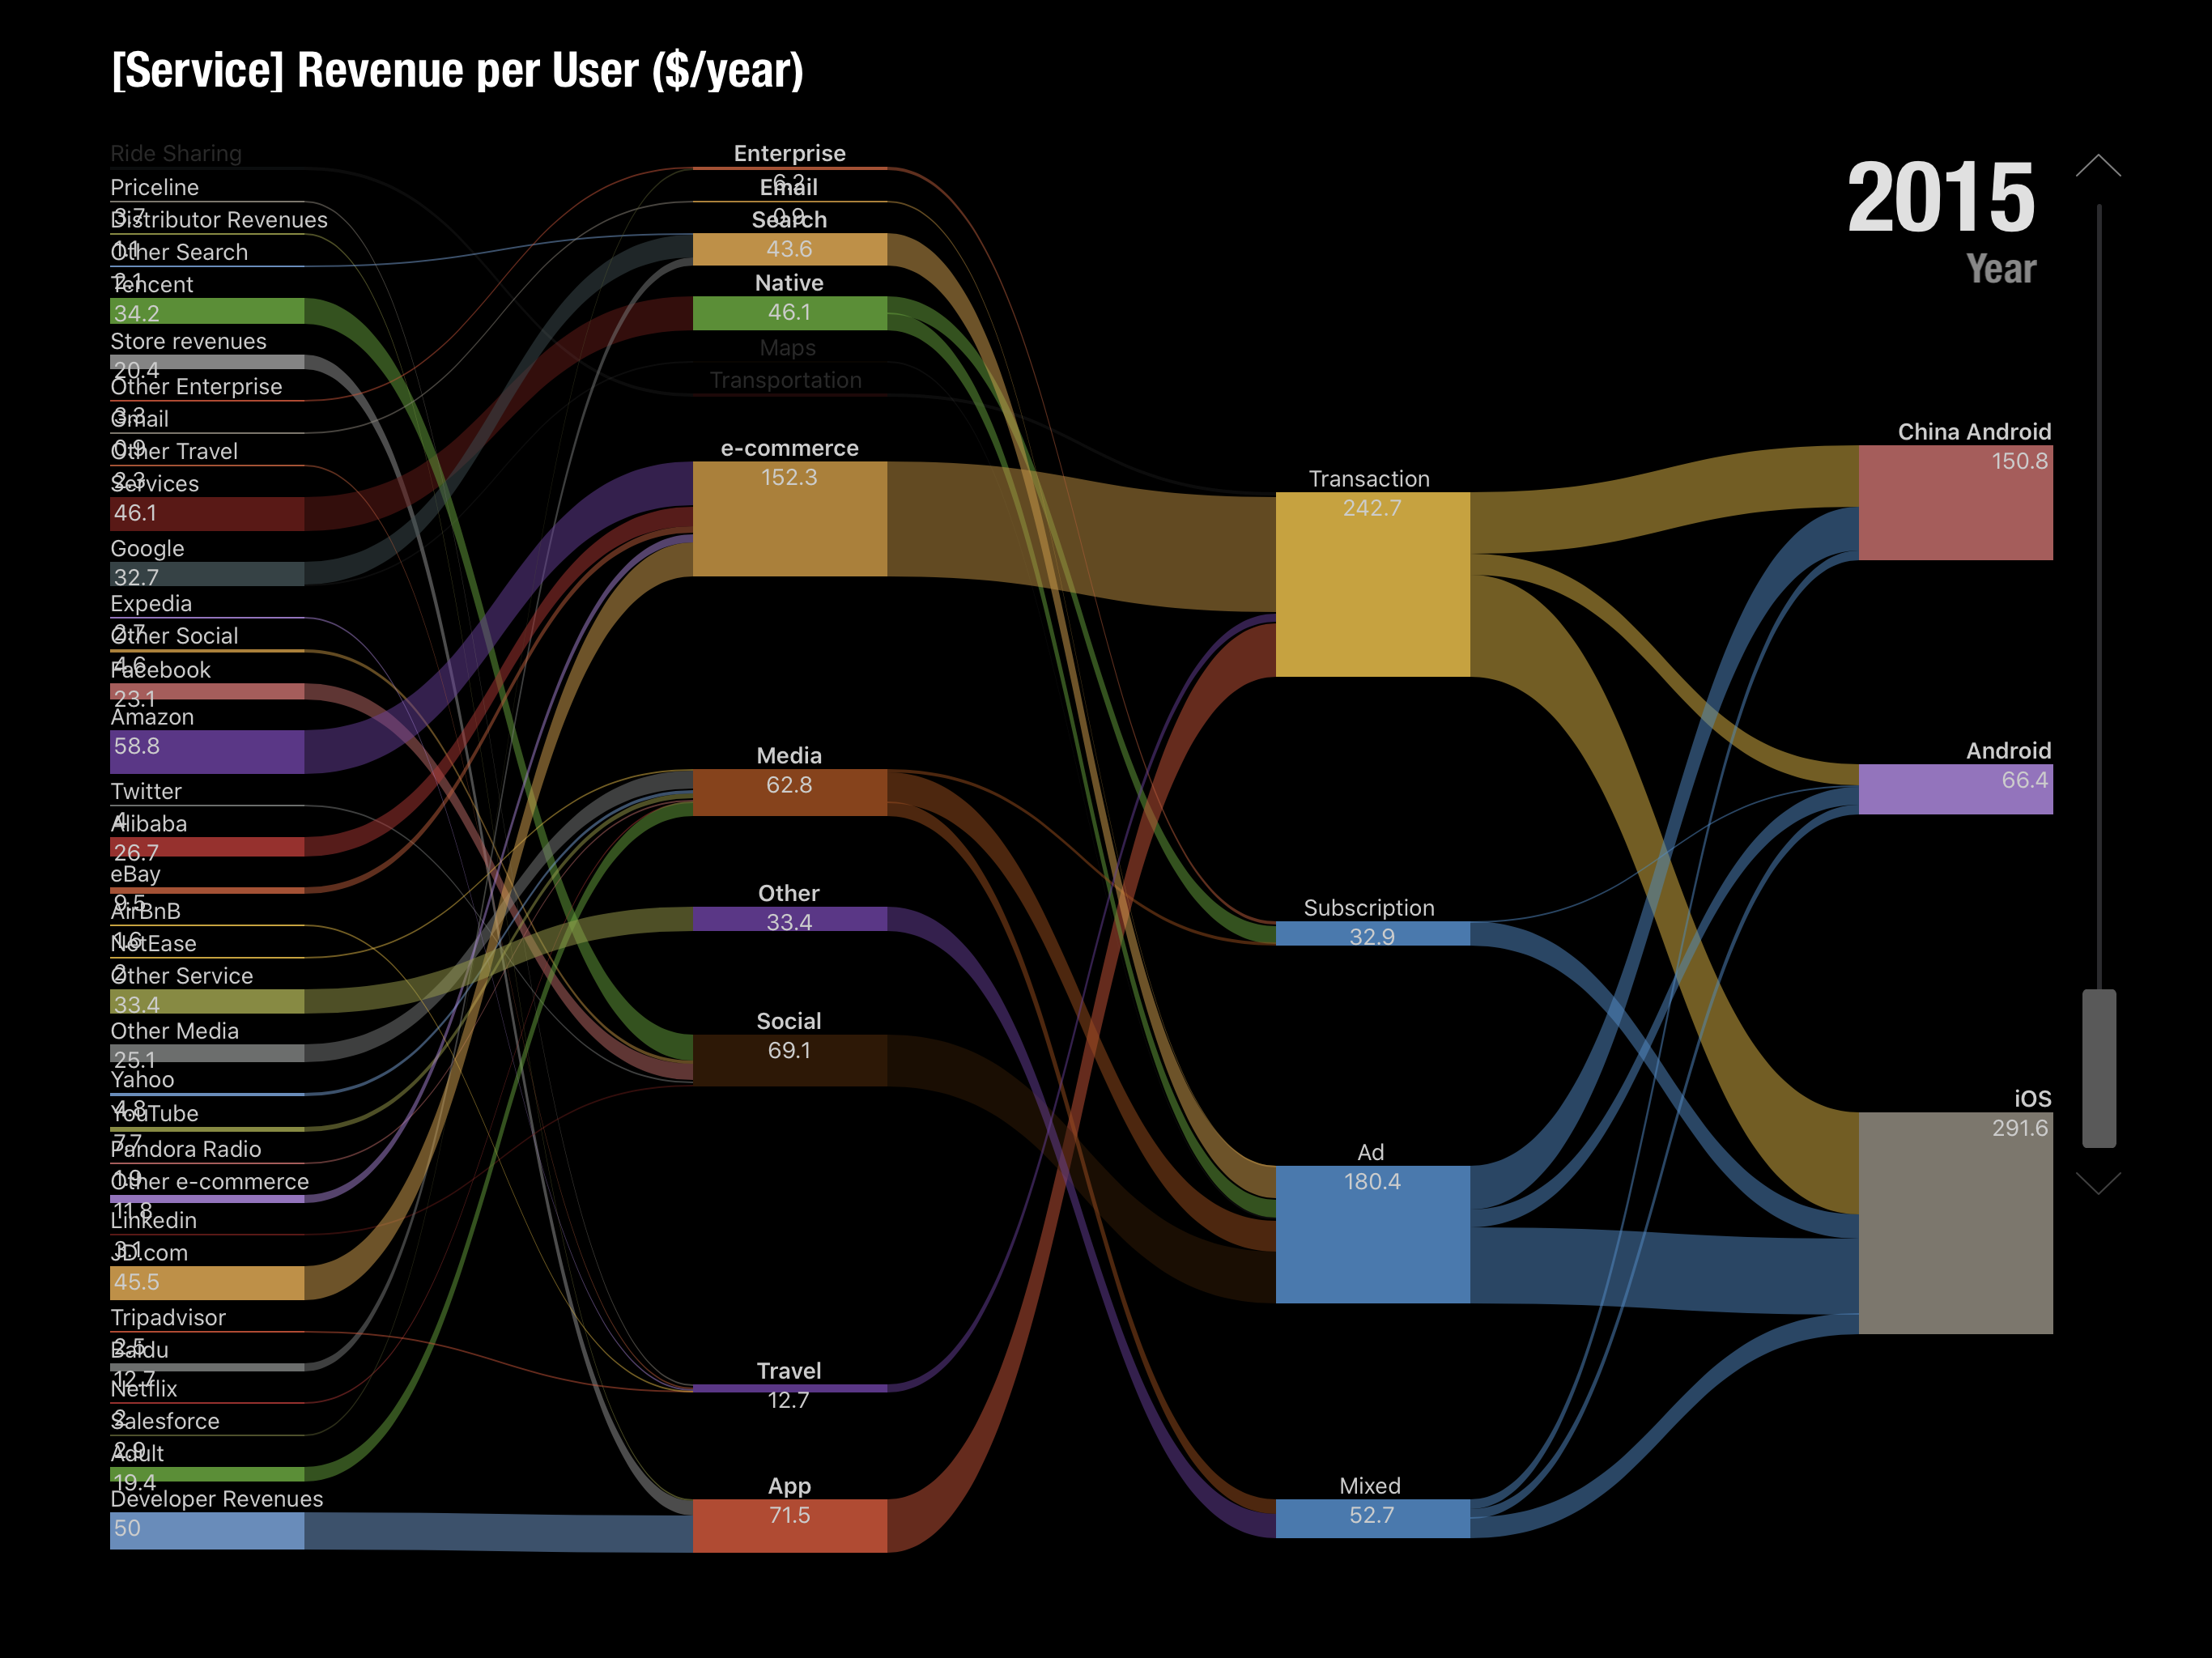
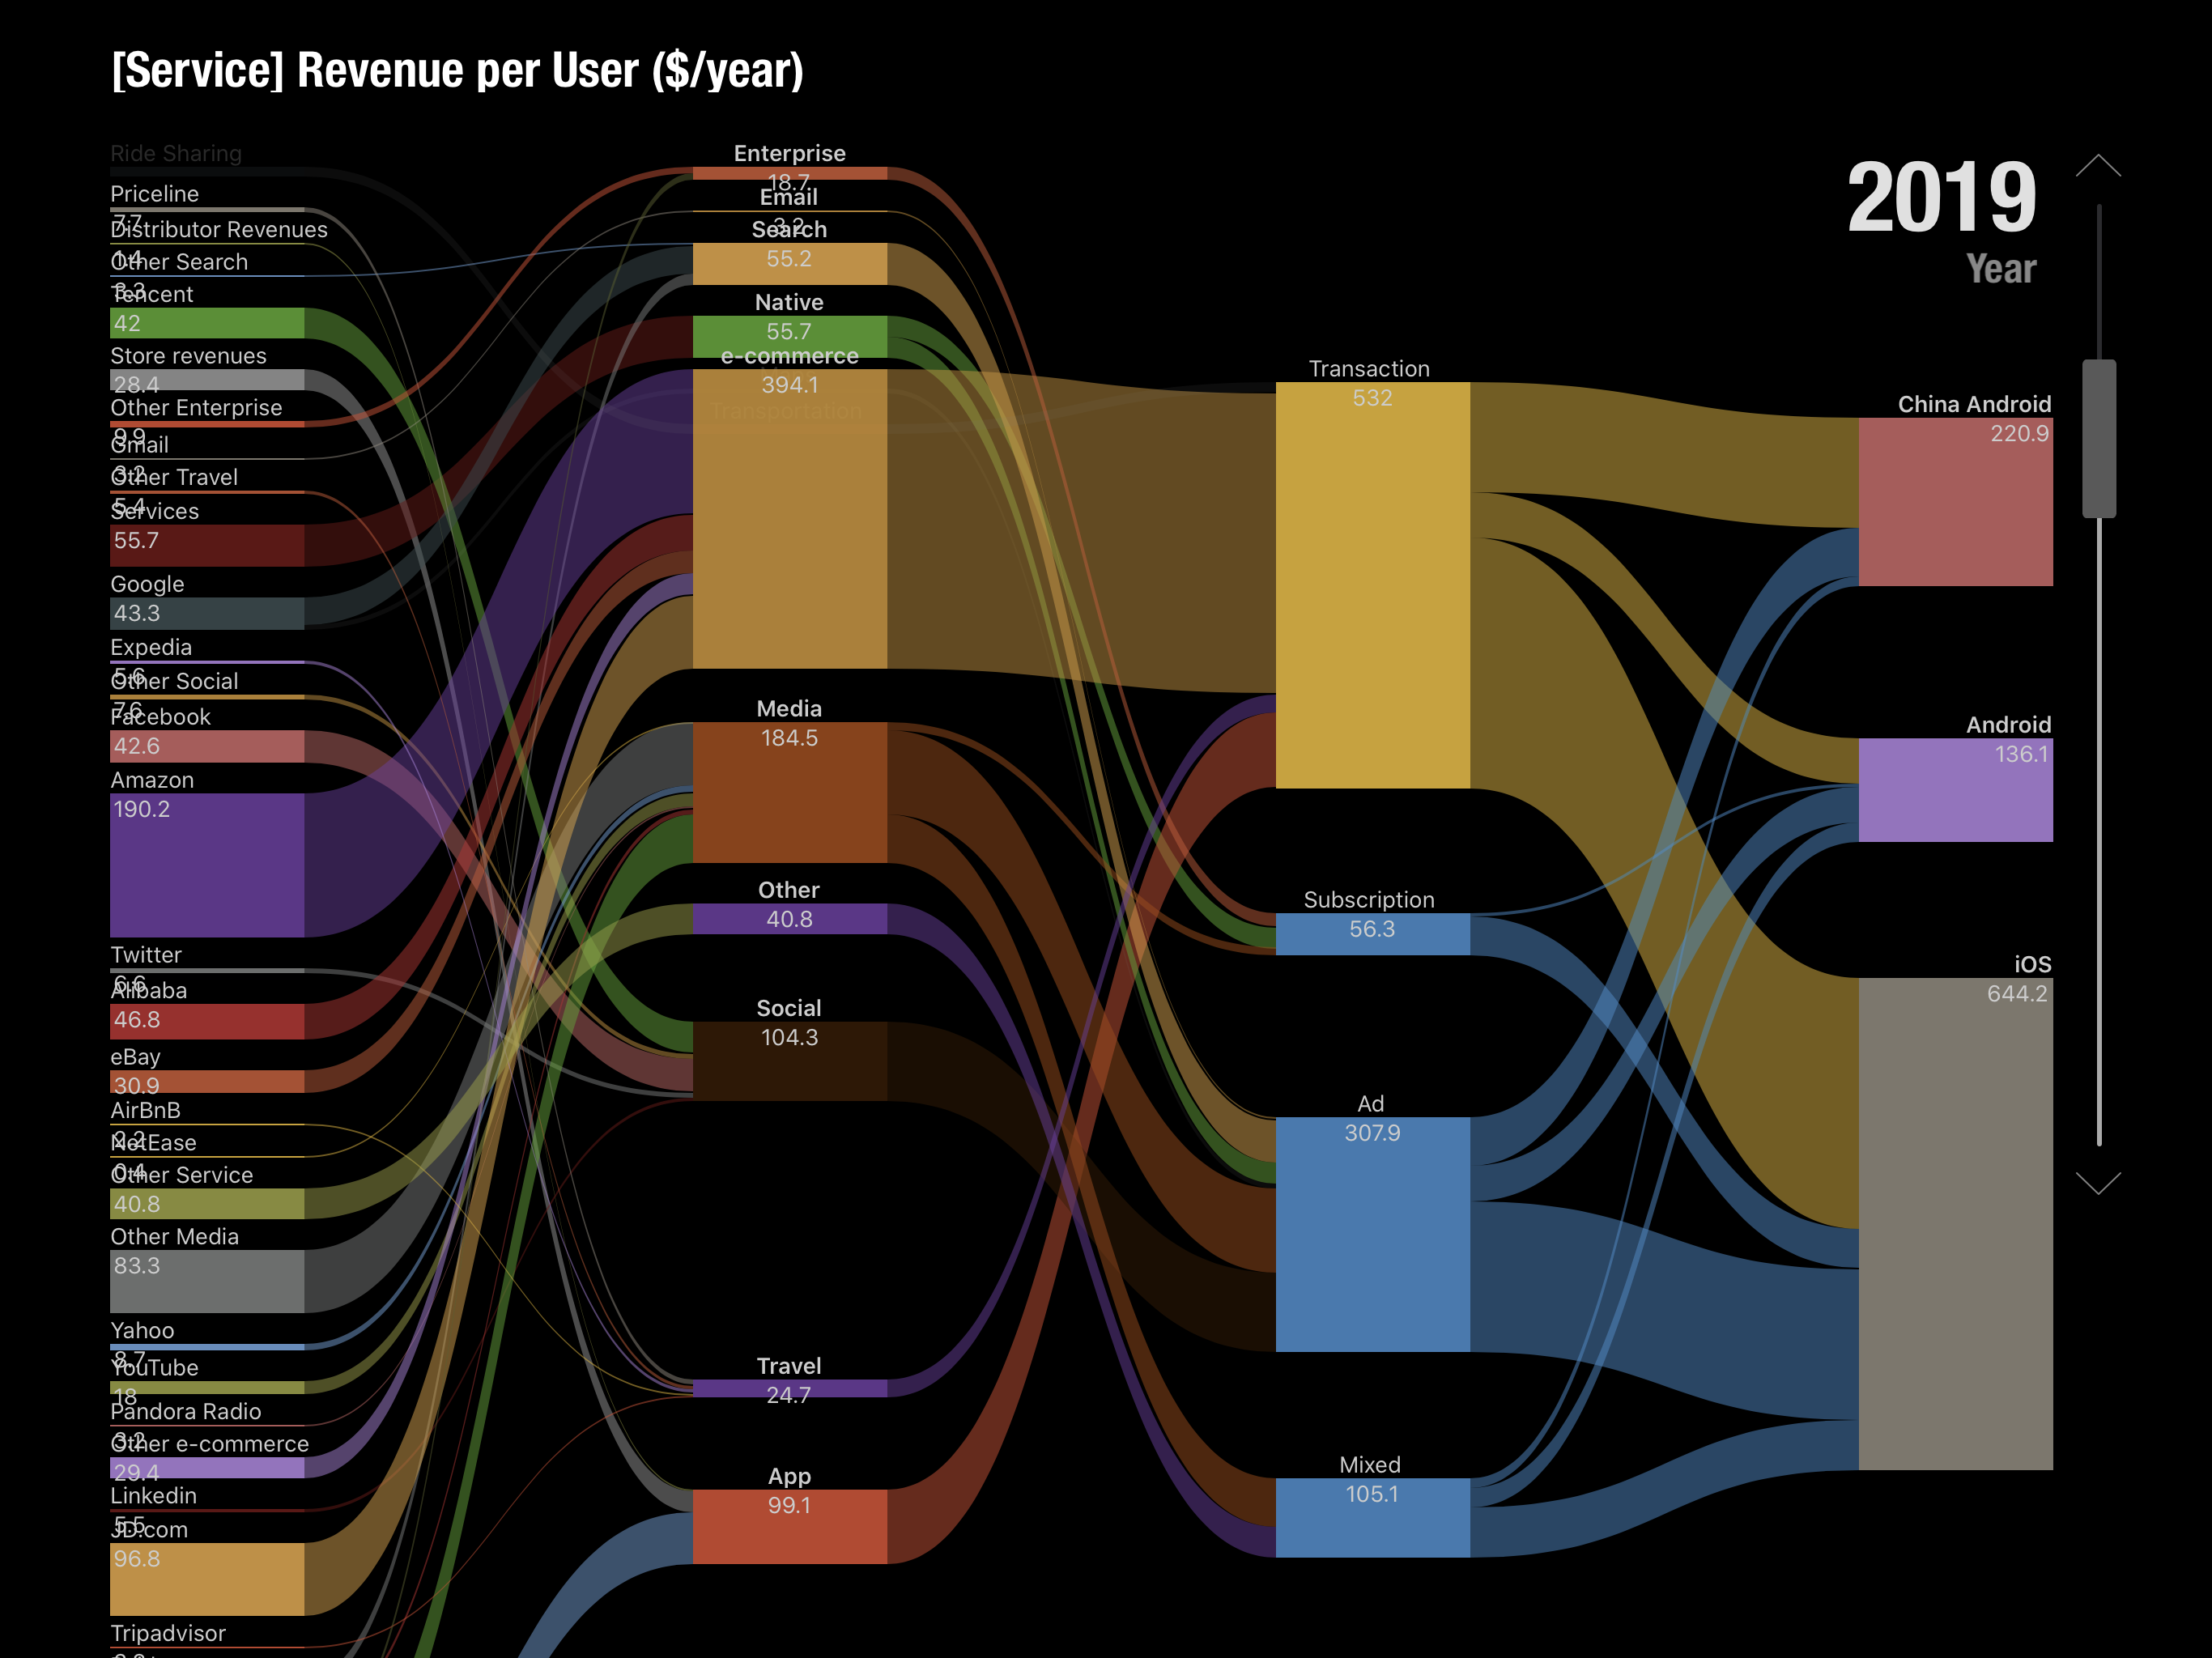
For the keynote I prepared a model which predicted the mobile ecosystems for iOS, Android and Chinese Android over the next 5 years (to 2020). The methodology involved taking a measurement of the revenues of the top internet service companies, building up the categories these companies occupied, estimating how much of those revenues are through mobile distribution and then splitting the result among the three platforms of iOS and the two Androids.
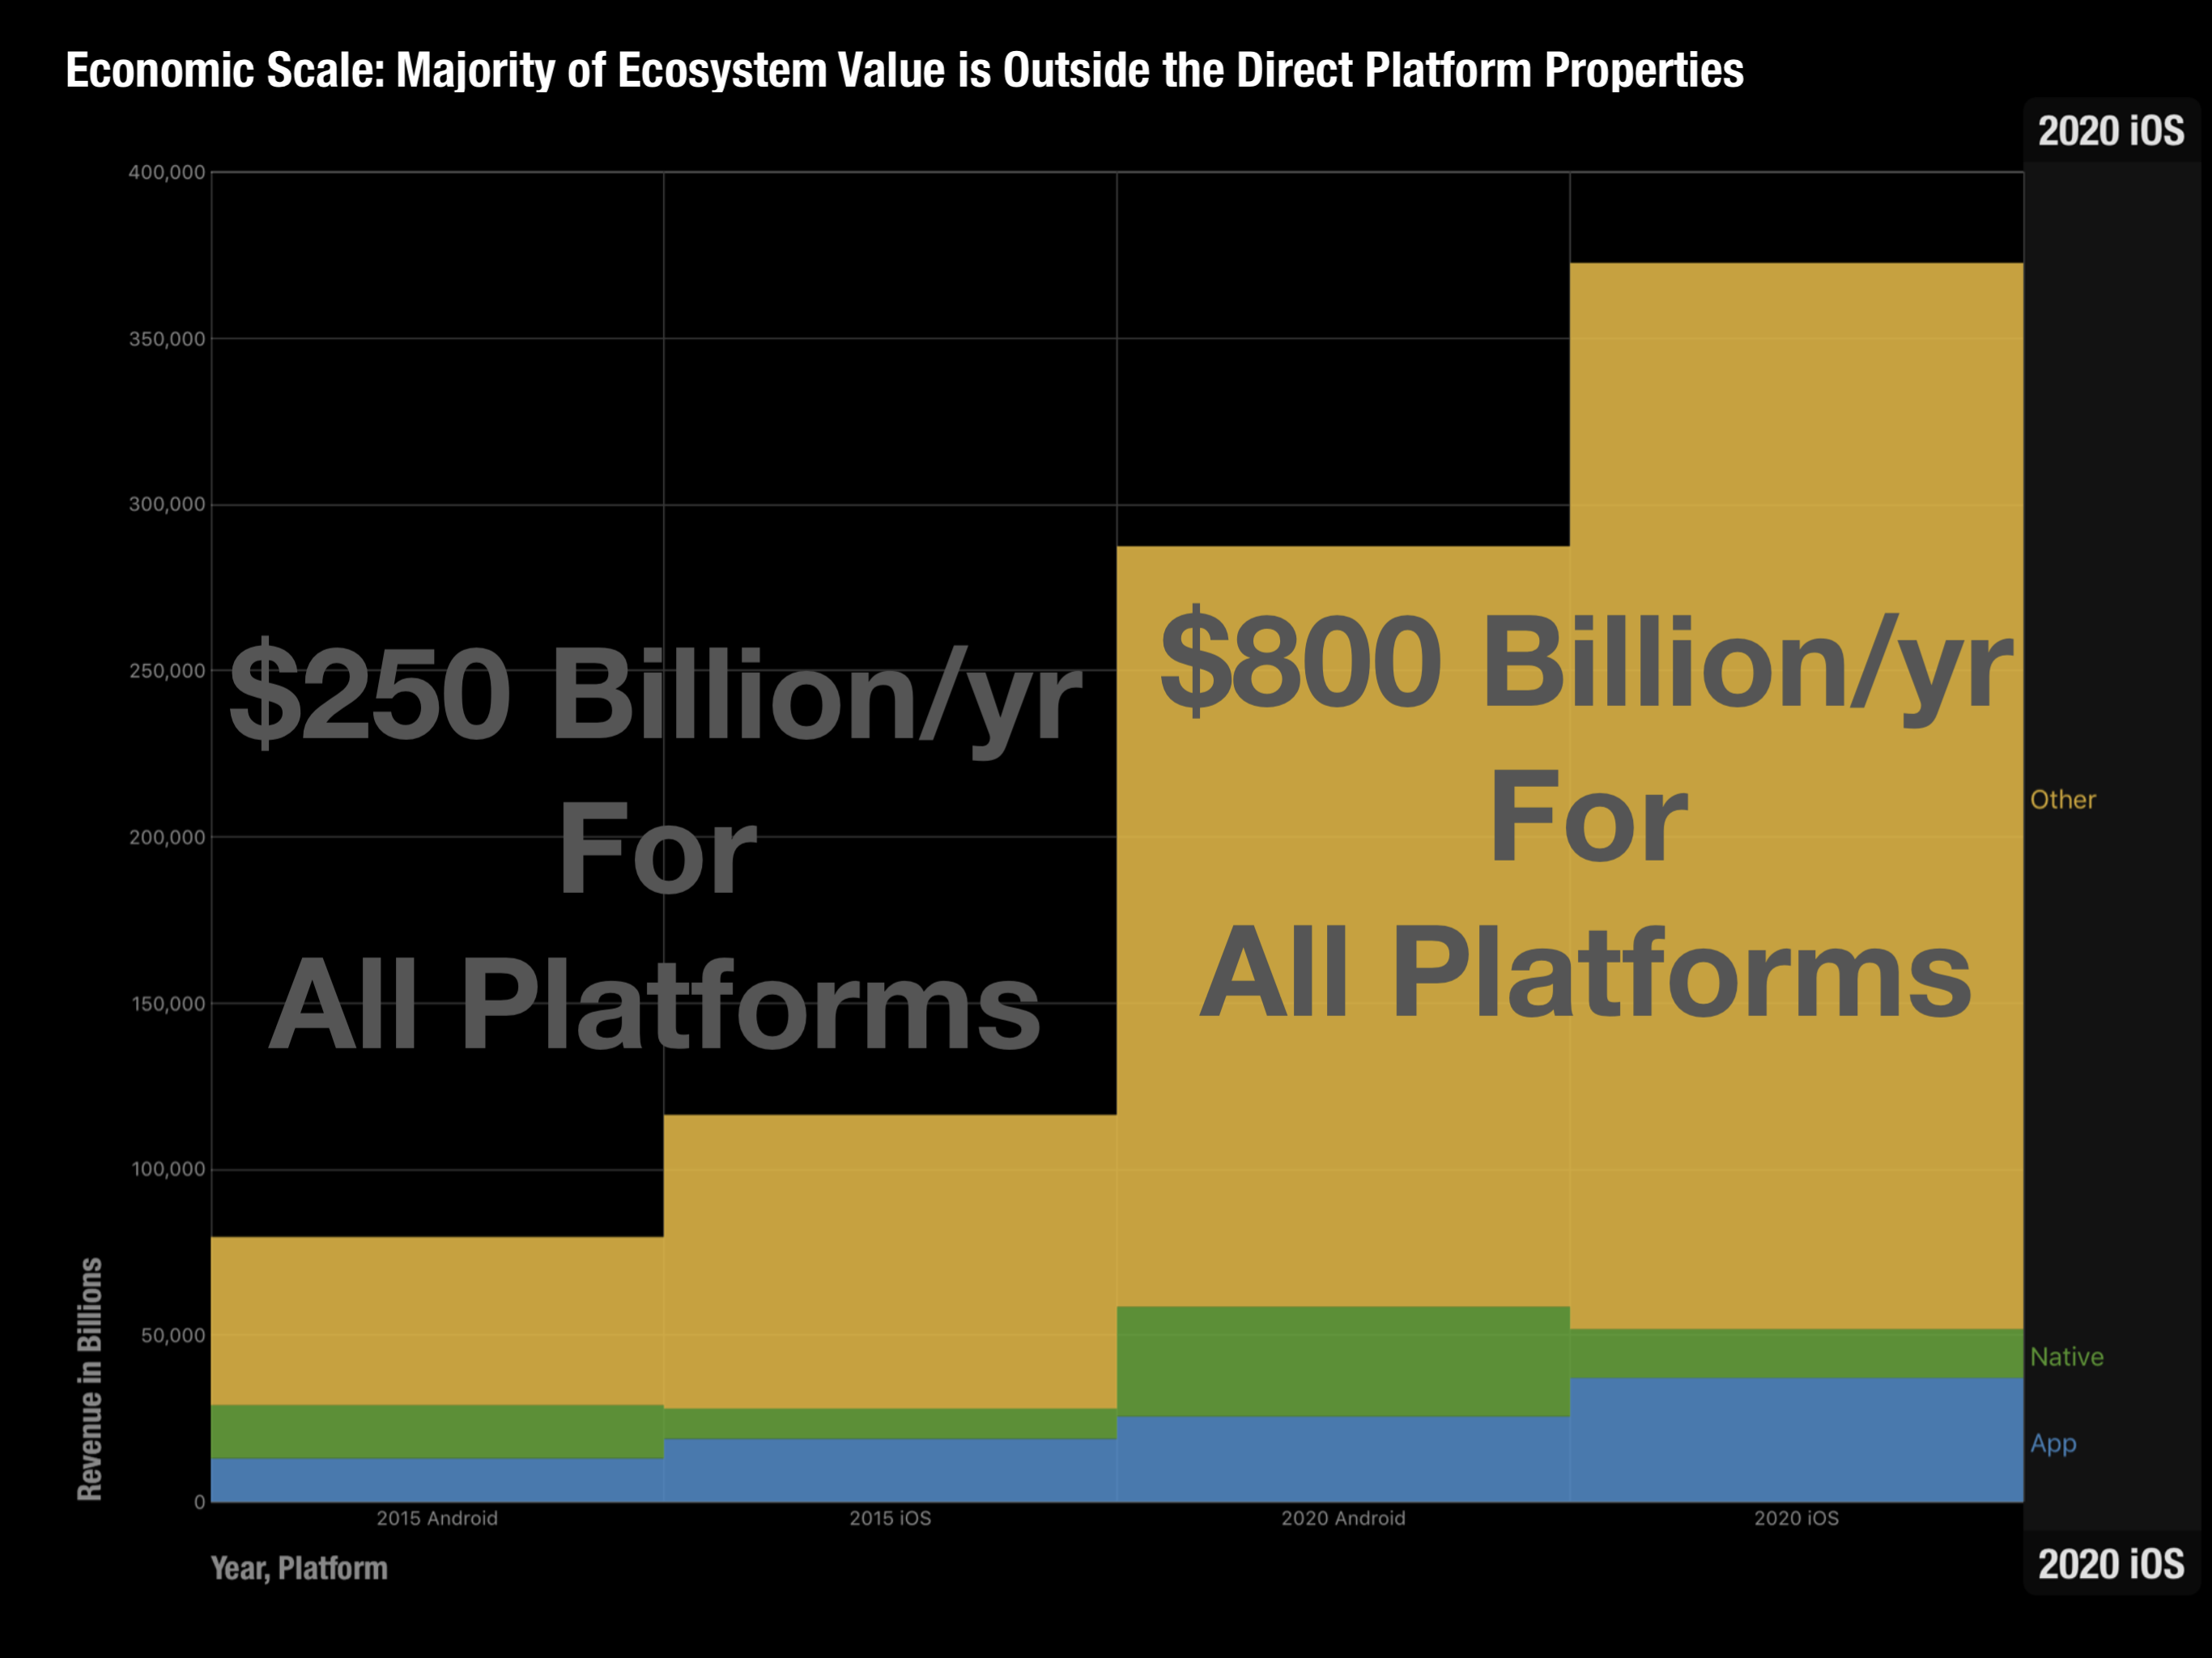
Adding to that the "native" app and content revenues for each platform would yield the Ecosystem total value. Applying a growth rate would offer some visibility into the future.
The following images are screen captures of the Perspective presentation.
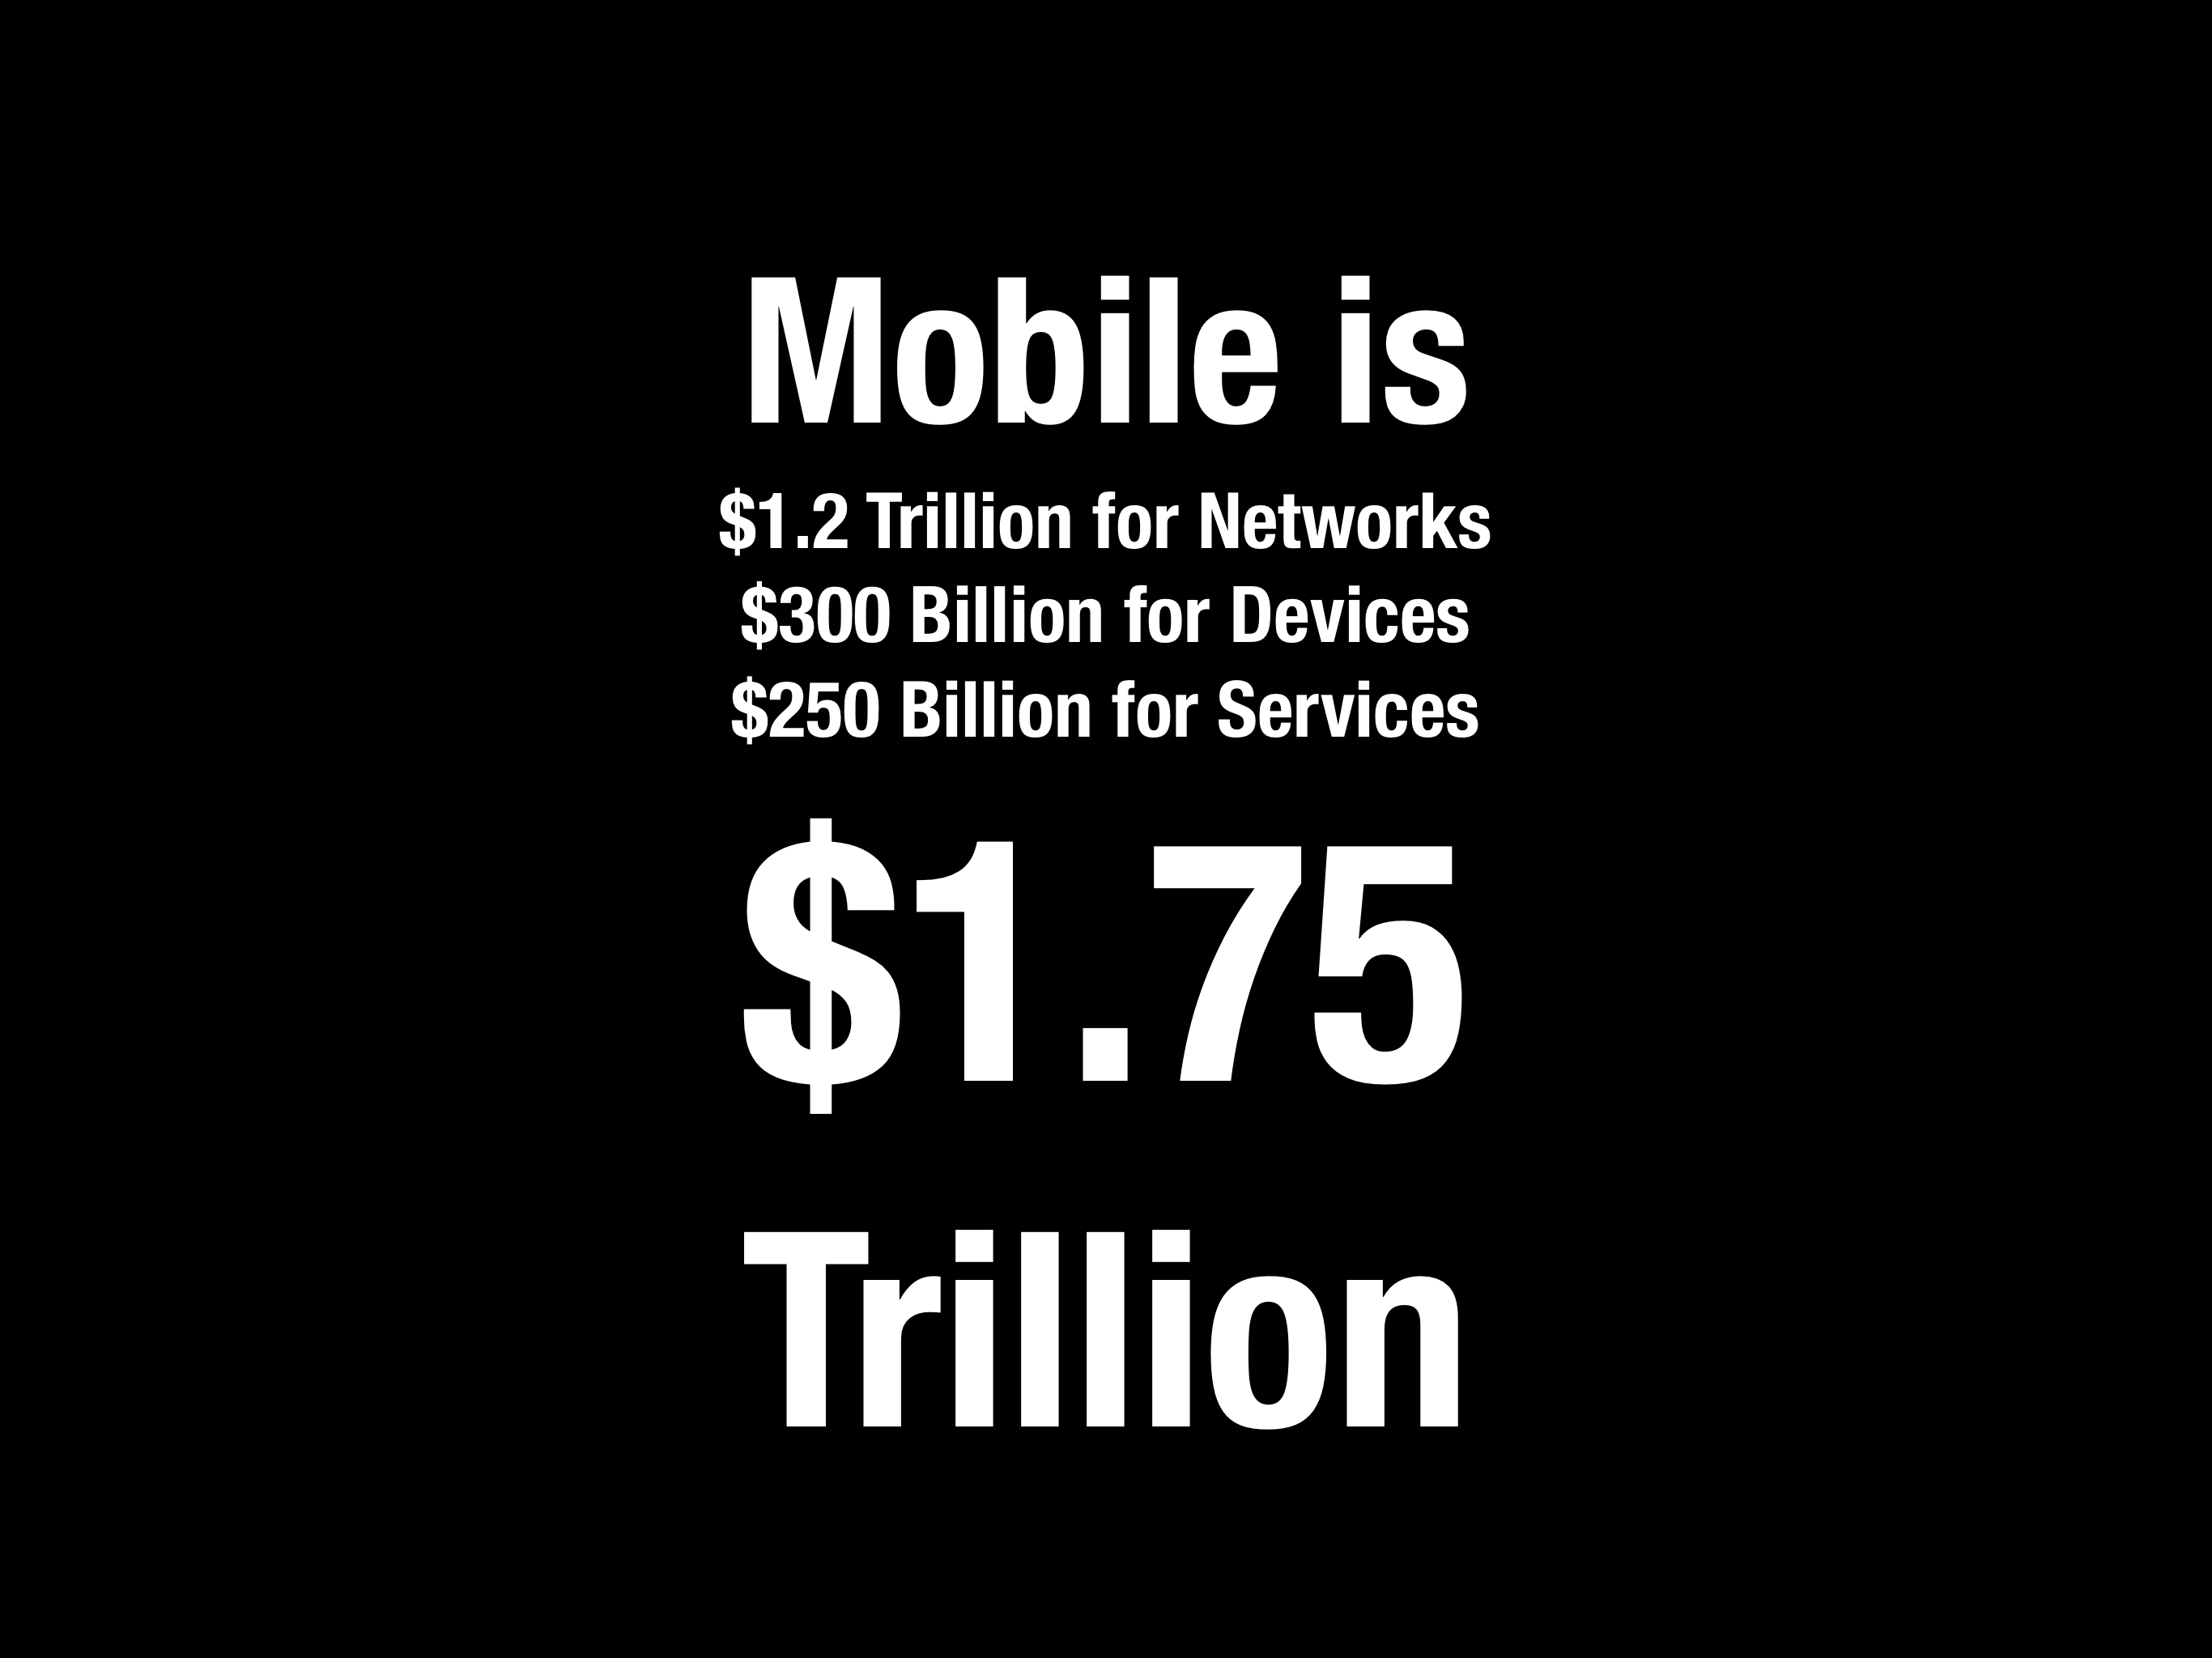
Revenues across Networks, Devices and Services 2015 to 2020 (estimated March 2016)Operating Income across Networks, Devices and Services 2015 to 2020 (estimated March 2016)Ecosystem composition (Third Party App, Native Apps, Other) 2015 to 2020, Android vs. iOS.Estimated mobile ecosystems total value by 2020 estimated in 2016.Over the top (OTT) service components by revenue model in 2015 estimated in 2016.Over the top (OTT) service components by revenue model in 2020 estimated in 2016.Allocation of OTT Revenues Across Service Types and Business Models and Platforms 2015 (estimated in 2016)Allocation of OTT Revenues Across Service Types and Business Models and Platforms 2019 (estimated in 2016)Composition of service revenues per user ($/year) for mobile platforms in 2015 (estimated in 2016)Composition of service revenues per user ($/year) for mobile platforms in 2020 (estimated in 2016)
Of course there are several potential errors in this methodology. The categories were not all inclusive. I used Social, Media, Search, Maps, email, Messaging, e-commerce, Travel, Enterprise, Storage, Transportation, Travel and Other as the top level categories. There are many products and services who would end up in Other. Moreover, these categories were anchored by the top companies in each category and the share of the top names was not always clear. Finally, the growth rates for these categories were based on historic trends which could change either way.
The online services ecosystem (all platforms) was thus estimated to be $450 billion in 2015, growing to $820 billion by 2019 and $914 billion by 2020.
The mobile split would vary by segment but would be roughly 75% by 2020 (25% would not be mobile). The final assumption was based on the split among the existing mobile platforms. I put a multiple of roughly 50% for iOS and 35% for Google Android and the rest for China Android.
Multiplying all these assumptions gave me a figure of $275 billion for the iOS portion of the global online services market in 2019. (Incidentally, Android was estimated at $207 billion and China Android $110 billion.) Note that this does not mean this was an expectation of Apple's revenues or that this was the opportunity of Apple obtaining any percentage of this revenue. It was simply the value of what would transact through iOS, a platform which would act as a commerce enabler. This was to be the size of the iOS "ecosystem" or co-dependency between Apple and the companies delivering through its platform.
Ecosystems are a powerful idea. As I recall, this term applied to mobile was coined by a Palm executive in the late 1990s when he referred to the value of all the apps built for the Palm Pilot. The biological term refers to the system of multiple species living in close proximity. It implies an equilibrium as each species benefits from the others and the environment. There might be predators and prey but biodiversity is the successful construct.
The idea of an ecosystem for a platform was also the core strength of Microsoft's Windows which created the network effects around it and it has been the goal of every platform since. The nature of computing and networking implies that these systems grow faster and are more resilient than the more traditional value networks of other businesses or industries.
Now this ecosystem was something we wished to highlight in 2016 as a core strength for Apple. It was not considered as such at the time and I thought putting a figure of $275 billion in 4 years' time was a way to highlight the potential. Time since has proven us right.
This week Apple highlighted the result of another research team who attempted to measure the iOS ecosystem. Their conclusion was that billings and sales facilitated by the Apple App Store Ecosystem in 2019 was $519 billion. More than twice the amount I had so optimistically forecast four years earlier.
The authors also emphasize that this is a conservative estimate and should serve as a baseline.
I feel partly vindicated about that figure as my attempt at a figure was intended to highlight the scope of the ecosystem and it is better to have underestimated it than overestimated it. The authors' methodology was also similar in being bottom-up summation of components by categories of services but the information available today is enhanced by the new data Apple made available on subs and Services revenues and install base.
Note that in the graph below the salient data points of subscribers (red triangles) had not begun until 2017 causing the acceleration in Services revenue (yellow line). Note also the additional square points representing install base.
This figure of more than half a trillion dollars of value transacted through iOS should give some pause. It it a very powerful figure that can be combined with the other data from Apple:
More than 1.5 billion active devices
More than 1 billion iPhone users
More than 500 million paid subscriptions
More than $1/day iPhone hardware revenues for Apple
The half-trillion per year on services implies between $335 and $520 in spending per user (likely closer to $500) per year. This would be in addition to the approximately $365/yr in hardware spending per user (which Apple books as hardware revenue). In the case of the iPhone there is yet more: the cellular network service which may average $350 per year.
To simplify, the "average Apple user" spends $1/day for each device, $1/day for the network and $1.4/day on items bought through the device. Adding a margin of error, that's between $3.4 and $4 per day each user spends. Oh, and there are about a billion such users.
The total spending enabled by iOS thus is close to $1.4 trillion/yr.
That's a significant amount. It's bigger than many industries. There are only about 12 countries with higher GDP (Spain is about the same.)
How does Apple benefit from this?
Apple captures 30% of billings through its App Store. My estimate for these billings were $67.9 billion in 2019 which means App Store billings were 13% of the 2019 ecosystem. Apple's 30% cut of Billings amounts to 3.8% for the whole ecosystem. It's hardly an oppressive number.
If Apple only captures 3.8% what use is this to Apple?
The last decade has seen Apple emerge as the world's largest company in terms of market capitalization, and not doing so with a wild multiple of revenue or earnings, quite the opposite. It did this by creating the world's greatest customer base. Not in absolute scale. Android and Facebook have larger customer bases with multiple billions of users.
No, Apple's one billion users are simply the best billion users. They are the most likely to stick with Apple and they are the most likely to buy more from Apple and—this is crucial—they are the most likely to buy everything else. Those other companies whose sales come from Apple customers have been taking note. They know that Apple customers are desirable customers and choose to target Apple customers, as much as they can. Associating your company with Apple makes a lot of economic sense.
I will admit however that my argument that Apple created a customer base is contrived. The fact is that Apple creates productsand services and those products are the root of its power to attract the right customers. By choosing to create the best products it coincidentally chooses to create the best customers. The power flows from product not from pricing or positioning. This is a lesson lost for many.
Developers and regulators might feel Apple's massive power is perhaps too much. In the last decade, the narration around Apple has shifted from Apple being perpetually "doomed" to it being too dominant. Although I'm sure there are some who will try to conflate the two declaring that dominance will inevitably result in doom, most critics of Apple went from laughing (at it) to crying (about its practices).
The argument that Apple should change its practices developed to price as it does, distribute as it does or design as it does because it was too successful or is "unfair" is getting the causality wrong. Dominance won't be altered by a few points of percentage change (on a tiny fraction of ecosystem transactions). Fairness won't be altered when there are thousands of business models and many remain to be invented. Case in point is pornography which is not permitted on the App Store but which exists in abundance thorough other access methods.
The argument is that Apple should be more generous. That it should decrease the "cut" it takes for distribution. Or that it should not enforce revenue split for the customers it exposes to others.
But this is problematic on many levels. The playing field for all developers needs to be level. The customer must be respected and access to that customer should be constrained or certainly metered. Abuses must be policed and that requires leverage.
These practices are inter-dependent and the effect multiplicative, not additive. Apple has a monopoly on iOS and on MacOS and WatchOS and iPadOS. It does this to control the experience, security and safety of the user. It's that control which created the customer in the first place. It should naturally control access to its hard-earned customers.
It does not monetize the distribution of content or apps unless the developer/creator directly charges for the product or service. Distribution is not cost free and to offer it for free is a subsidy which would create additional market and innovation disincentives. The loyalty of Apple users is evidenced by the 600 million paid subscriptions (end of year estimate) that are booked through the App Store. Developers benefit directly as a result.
One could argue that the abundance of services which don't distribute through the App Store is evidence that the system works as intended. Apple's App store front is its property and it reflects its core values.
Being on the shelf in the App Store means you operate on the terms of the shelf owner. If the rules are not agreeable then the half trillion dollars of ecosystem activity is testament to the availability of alternatives.
At time of writing (December 12, 2019) AirPods Pro delivery wait time is over 4 weeks. It's been like this since they shipped. I tried stores in several countries and although units can make an appearance on a shelf, they sell out immediately.
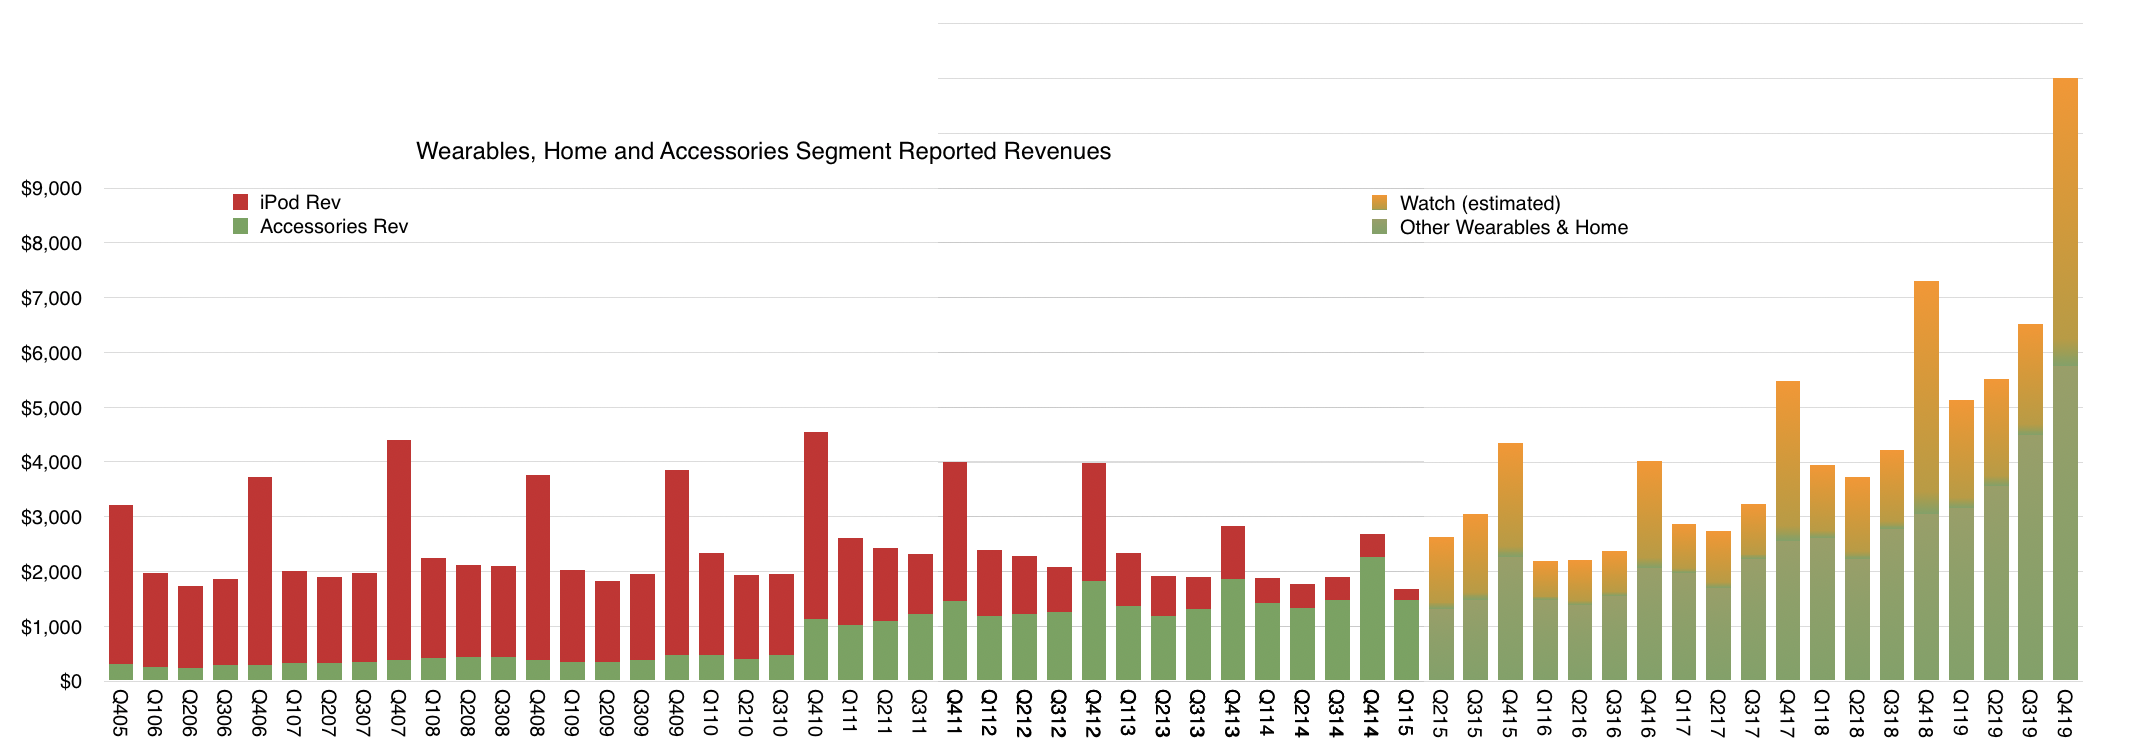
AirPods are part of the "Wearables & Home" category for Apple which used to be called Other Products and include also the Watch, iPod, Apple TV, Beats and HomePod (among other items.) iPod revenues were broken out as recently as 2015 but as the graph below shows, there have been no specifics on any product in "Wearables & Home" since then.
Wearables, Home and Accessories in a historic perspective with the iPod.
It therefore falls upon us to estimate how much of the entire category is any one product. It's been very difficult as the only clues lie in growth rates, sometimes cited for the Apple Watch and sometimes for "Wearables" alone. As far as I can tell from the available clues, the split is roughly as shown between the Orange and Green areas. Orange reflects estimate for Watch and Green everything else.
This analysis helped me conclude the Apple Watch overtook the historic "peak iPod" which occurred in the fourth quarter of 2007 at $4 billion. My Watch revenue estimate was $4.2 billion in the fourth quarter of 2018. This conclusion was confirmed by statements from the Company.
The problem lately has been that AirPods have become huge unto themselves. There is literally no information about AirPods sales as a product category. The only option is to guess Watch and subtract it from Wearables and then guess again the portion of "non-Watch Wearables & Home" that is AirPods.
Looking forward to the next quarter, I am expecting a 51% increase y/y for Wearables and 24% growth in Watch. This results in a Watch revenues about $5.2 billion and non-Watch $5.7 billion. Now if we assume $1.7 billion for non-Watch-non-AirPods (i.e. Apple TV, HomePod, Beats, iPod, other) then this quarter AirPods will have overtaken peak iPod.
Remember that iPod was the phenomenon which reset all expectations for Apple. It caused Apple to cease calling itself Apple Computer. It (at least psychologically) laid the foundation for iPhone and everything else that followed. In 2005 and through 2007 Apple was "the iPod company". I remember people working in a large search engine company calling Apple "that media company" as a result of over-intellectualizing iTunes.
(One more footnote on the AirPods Pro is that at $250 a pair and $300 for Apple Watch, throwing in a case puts these attached accessories for an iPhone at roughly the same average selling price for the iPhone of a few years ago.)
For the AirPods to overtake the iPod highlights just what a phenomenal category Wearables has become. In combination with Home and other accessories the category is going to decidedly overtake the Mac, having already passed the iPad.
And so it goes, something dismissed as inconsequential–"does not move the needle"–ends up becoming a massive force of change. The iPod was that, the original Apple II, the Mac and yes, also the iPhone. It's the asymmetry of humility that this happens over and over again.
To hear more about the profundities of AirPods Pro tune in to the next Critical Path podcast.
During 2016 Apple services revenues were $25.6 billion. In January 2017, just after the end of that year, Tim Cook said "We feel great about this momentum, and our goal is to double the size of the services business in the next four years".
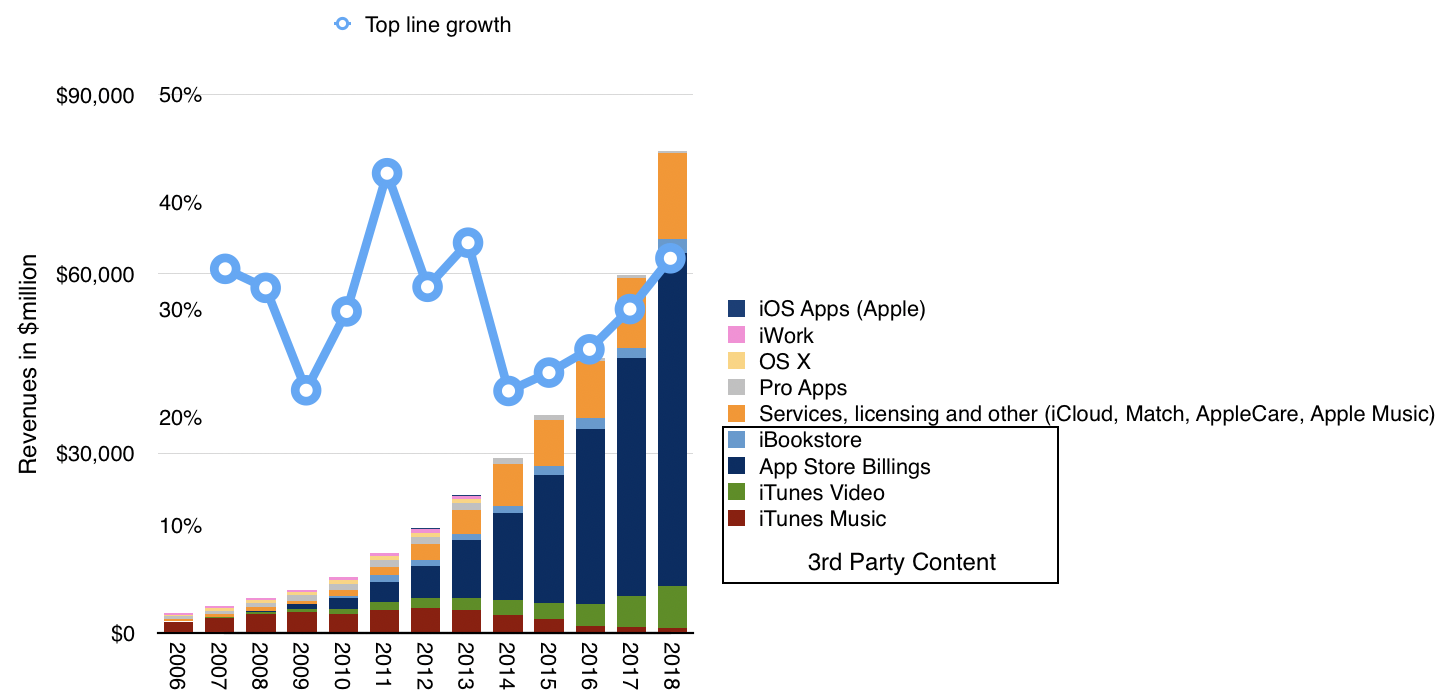
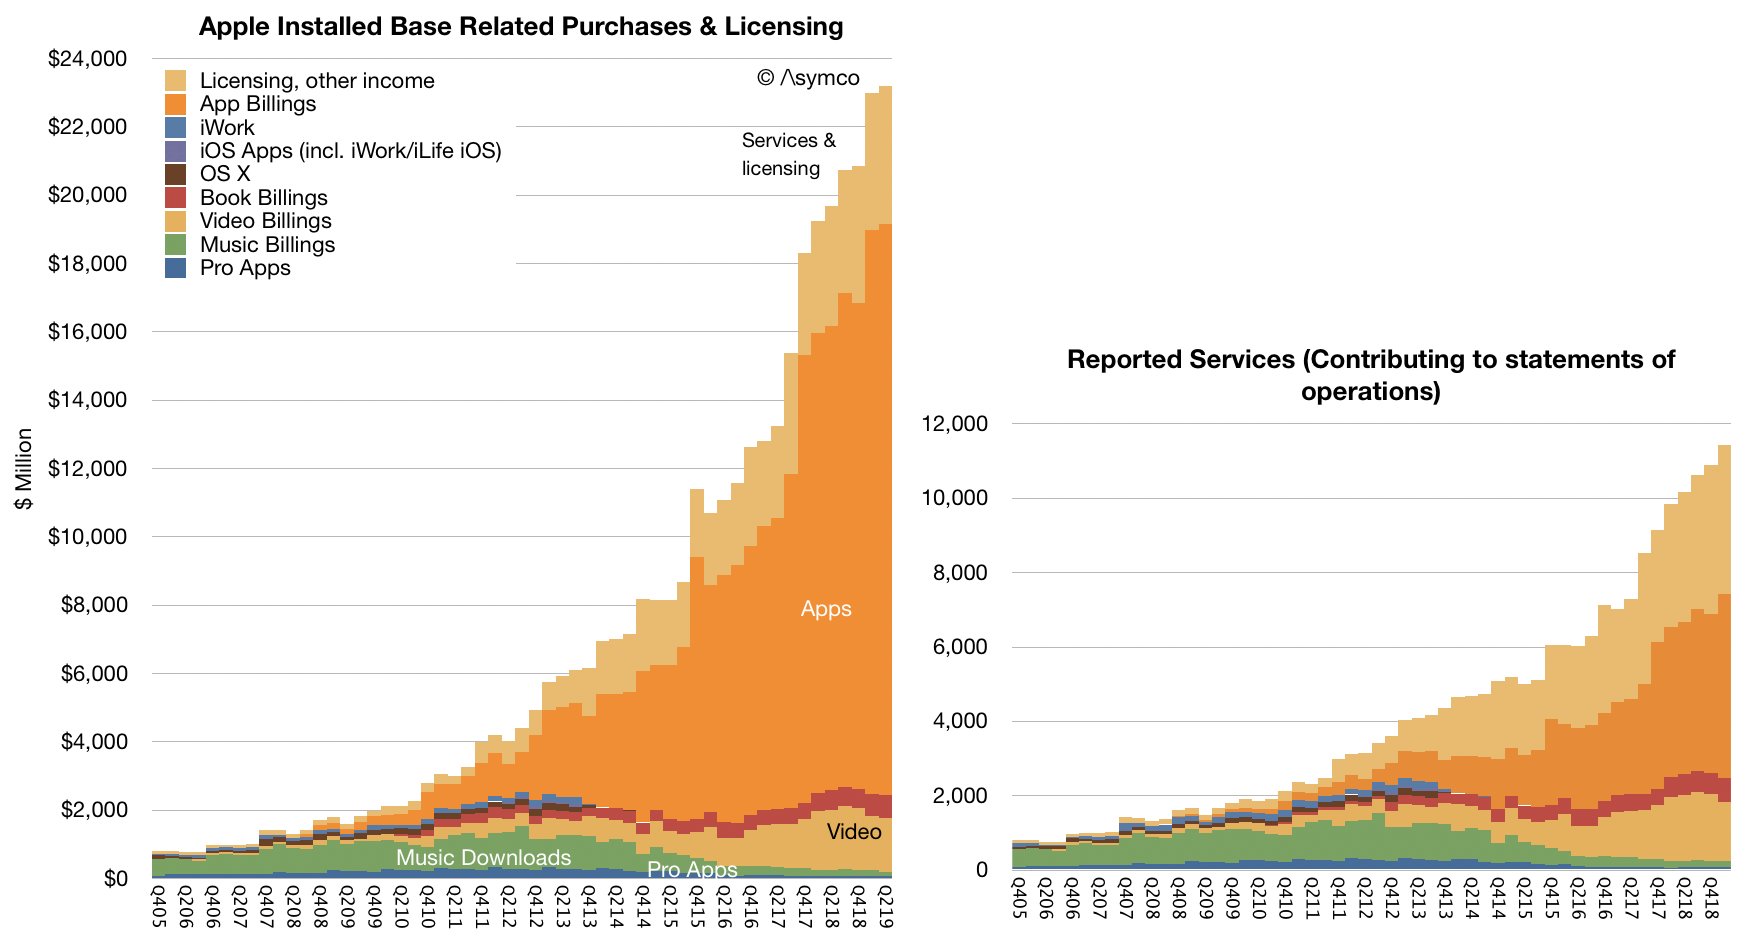
If Apple were to hit that target, during calendar year 2020, Apple's services revenues should exceed $50 billion. In 2017 they were $32 billion, in 2018 they were 41.5 billion and so far this year they are 23 billion. If, as has been the case during 2017 and 2018 (see graphs below,) Apple were to maintain 30% growth in Services during the rest of this year they will have revenues of $51 billion in 2019; reaching the doubling tarted a year sooner than predicted.
Apple will have doubled Services in 3 years to a level equivalent to a Fortune 63 company (right behind Goldman Sachs).
Keep in mind that the reported revenues are not billings or what consumers actually spend. That figure is at a run rate of over $71 billion. You can see the difference between billings and reported revenues in the graphs above.
So what made this possible and what is the source of growth in the future?
As my estimates above show, the growth came from apps and licensing and other revenues. Apps include many third-party subscriptions and licensing includes Google TAC and other income includes Apple's own subscription services and a few additional items like Apple Pay, AppleCare and iCloud.
What Apple is launching this year will boost this even further with TV+, Card, Arcade and News+. These are a new set of specific services that, apart from Card, will require subscriptions and will deliver Apple-specific content. Unlike previous Music and TV offerings, what Apple has embarked on is a high degree of involvement in the content creation process. These will be Apple TV shows, Apple video games and Apple-directed News feeds.
This is quite the watershed moment. Apple, a company dedicated to providing tools to content makers and content consumers, choosing to be involved in the lottery-like game of choosing and backing winners in creative works.
Can a company with good taste about devices and software successfully extend that capability to content? That seems to be the question many are asking: How good is Apple at creating hits? The process of hit creation is difficult but it's not completely random. There are many individuals who have skills or taste. And Apple's approach seems to be to hire people with such skills. These "executives" then proceed to attach people with great track records in hits and who may have the star power to attract audiences. It's not a matter of complete guesswork. It's actually the approach most "streamers" have: They hire studio executives, attach talent to projects and spread bets.
This is why there has been a rush by streamers to secure programs and A-listers. There might be a variety of subscriptions users are likely to pay for but there is a fixed number of bankable names in the business.
But let's pause here to think more deeply about what is happening. Without much notice, we are seeing a content world where distributors are locking up talent and creating a studio model where production, talent and distribution and display are under one roof. This is exactly where the movie industry was in the so-called golden age of Hollywood. The era of the studio system. An era that ended with divorcement—the complete separation of exhibition interests from producer-distributor operations or the forced divestiture of theaters by production/distribution.
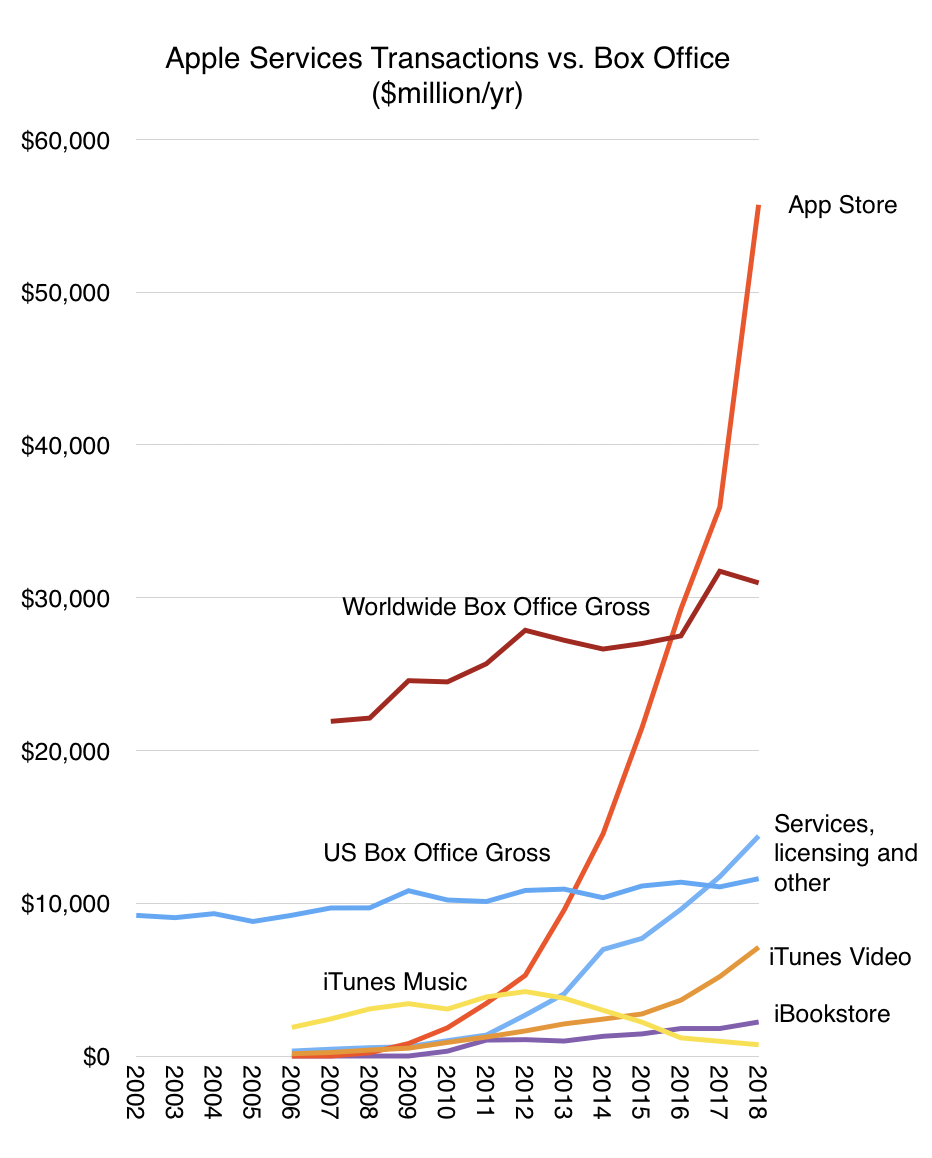
Another observation to be made is that the bundling and binding of content into specific distributors creates a walled garden effect. This extends beyond video content to games (a larger business than film, at least at the box office, see below) and to apps. Arcade games are Apple-exclusive. Many apps which depend on Watch, AR and other unique technologies become exclusive, and of course unique titles.
As far as consumers are concerned this might be just fine. There are very implicit lock-in effects of ecosystems, from UX muscle memory, switching costs for data, network effects from friends/family/co-workers in the same system. The extension of this to cultural content, news curation, music curation and privacy curation could be the comfortable default for many.
In this world-view the proposition Apple offers is very attractive. Look at the preference vacationers have toward packaged experiences. Look at the popularity of cruises. Look at the way features are packaged in cars. Look at meal delivery and the packaging of ingredients into something you can cook at home. Look at fitness and the packaging of instruction with the exercise venue. The examples are plentiful.
A garden is lovely after all. The walls are there to keep danger and chaos away as much as to keep you in it. The constraints simplify as much as they restrict. Though it may be contrary to some modular and interoperable utopias which paralyze with choice, we might well be experiencing a triumph of the walled garden.