As we move ahead into the September quarter, I'd like to review our outlook, which includes the types of forward-looking information that Saori referred to at the beginning of the call. We expect our September quarter year-over-year revenue performance to be similar to the June quarter, assuming that the macroeconomic outlook doesn't worsen from what we are projecting today for the current quarter. Foreign exchange will continue to be a headwind, and we expect a negative year-over-year revenue impact of over 2 percentage points.
We expect iPhone and Services year-over-year performance to accelerate from the June quarter. Also, we expect the revenue for both Mac and iPad to decline by double digits year-over-year due to difficult compares, particularly on the Mac. For both products, we experienced supply disruptions from factory shutdowns in the June quarter a year ago and were able to fulfill significant pent-up demand in the year ago September quarter.
We expect gross margin to be between 44% and 45%. We expect OpEx to be between $13.5 billion and $13.7 billion. We expect OI&E to be around negative $250 million, excluding any potential impact from the mark-to-market of minority investments, and our tax rate to be around 16%.
Luca Maestri, CFO Apple Inc., Aug. 03, 2023
In August Apple reported Net sales growth of -1% and EPS growth of 5.4%. My expectation is a 1% sales growth with EPS growth of 11.4%. This might be slightly optimistic but it's based on the following assumptions:
iPhone unit growth of -1.4% (y/y) but revenue growth of 2% (as per guidance, up from -2% previous quarter's growth).
Mac unit and revenue growth of -12% (this might be optimistic, low confidence)
iPad unit growth of -2% but revenue growth of -12%.
Services revenue growth of 12% (acceleration from 8% q/q)
Wearables 2% revenue growth (consistent q/q, down from 10% y/y)
I estimate the gross margin to remain at 44.5%, open to be $13.5 billion (low-end of guidance), OI&E at -$250 million (per guidance) and tax rate at 16%.
The number of shares I estimated at 15.666 billion (down 109 million, below 126 million average drop for last 8 quarters.)
To summarize, for the fiscal fourth quarter 2023:
Total revenue: $91.1 billion
EPS: $1.43
Revenue by segment:
iPhone: $43.5 billion
iPad: $6.2 billion
Mac: $10.0 billion
Services: $21.5 billion
Wearables/Home/Accessories: $9.8 billion
Gross margin on total revenue: 44.5%
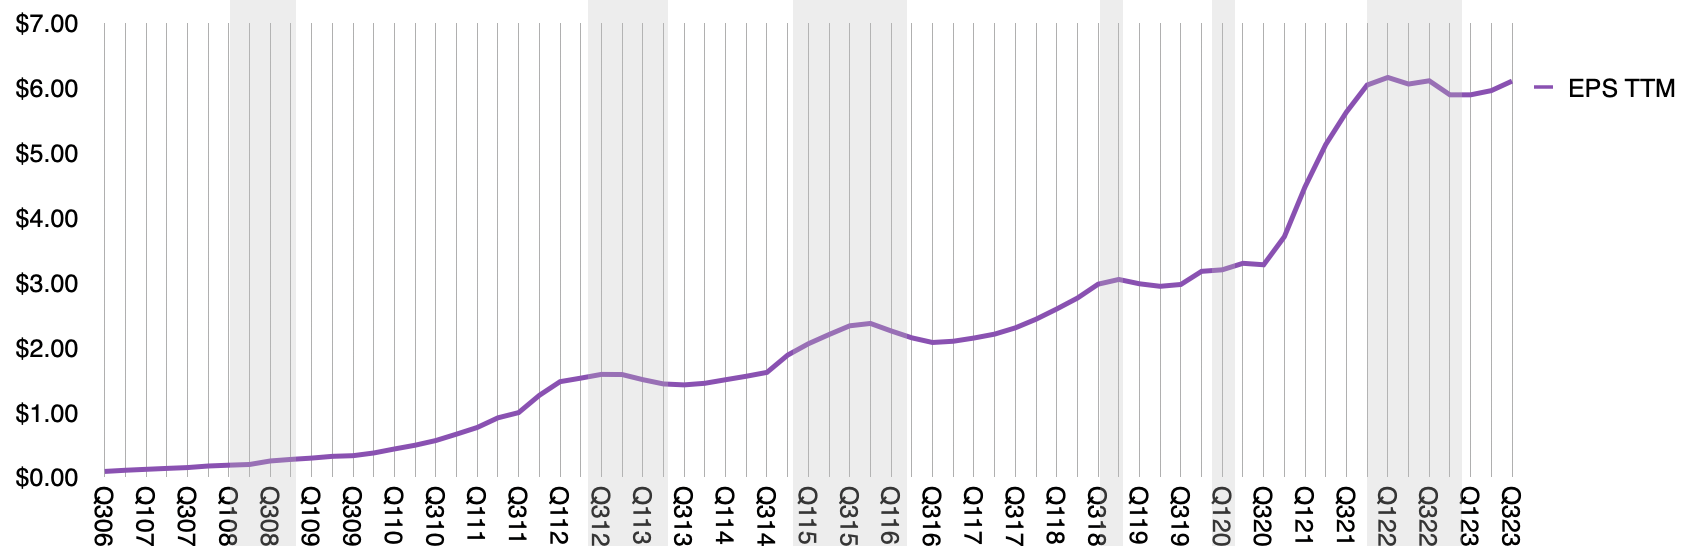
As can be seen in the following graph, my expectation is that the company will return to a pre-Covid growth trajectory (on a TTM EPS basis) after a transient surge and recovery due to the phenomenon of work-from-home and reduced travel. The uncertainty related to Covid is subsiding but macro and geopolitical uncertainties remain and the company continues to provide limited guidance.
The term Post-PC was first coined by MIT scientist David D. Clark in 1999 and was quickly adopted by both Microsoft's and Apple's former CEOs. Jobs popularized the term "post-PC" in 2007 (the launch of the first iPhone), and in 2011 when he launched iCloud, a service enabling Apple devices to synchronize data through cloud services, freeing them from dependency on a PC.
The Post-PC era was posited during the late 2000s and early 2010s presupposing a decline in the sales of personal computers (PCs) in favor of devices, phones, tablets, wearables, IoT, etc. These devices were mobile first (i.e. battery-first as opposed to plug-first), connected second and cloud-powered third. They were designed to run "apps" not "applications" and had new ecosystems with millions of developers selling through online-only stores, priced often as subscriptions rather than seat licenses.
In the last decade or so, the PC did endure an overall decline in sales while phones, tablets and wearables climbed to at least 10x volumes of the PC. But the last few months have shown a resurgence in PC sales. Certainly the necessity of working from home is the reason but will this last?
The fact is that the PC did not disappear. It certainly is still in use and there are buyers for it. There just isn't a lot of growth or energy. There hasn't been for a decade. The software and hardware efforts are uninspiring because the talent has moved elsewhere. The creativity, R&D budget have gone the same way.
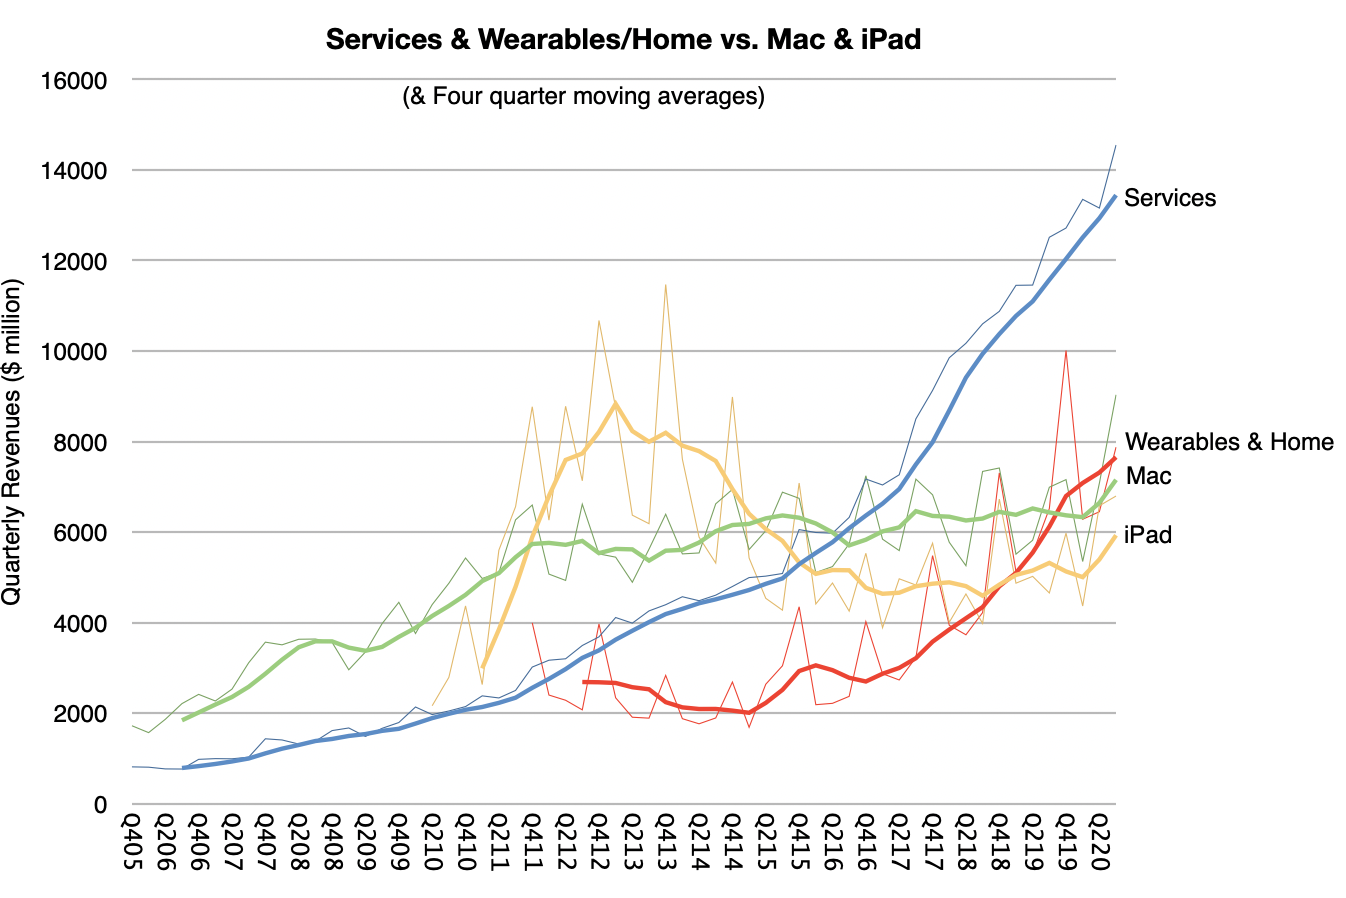
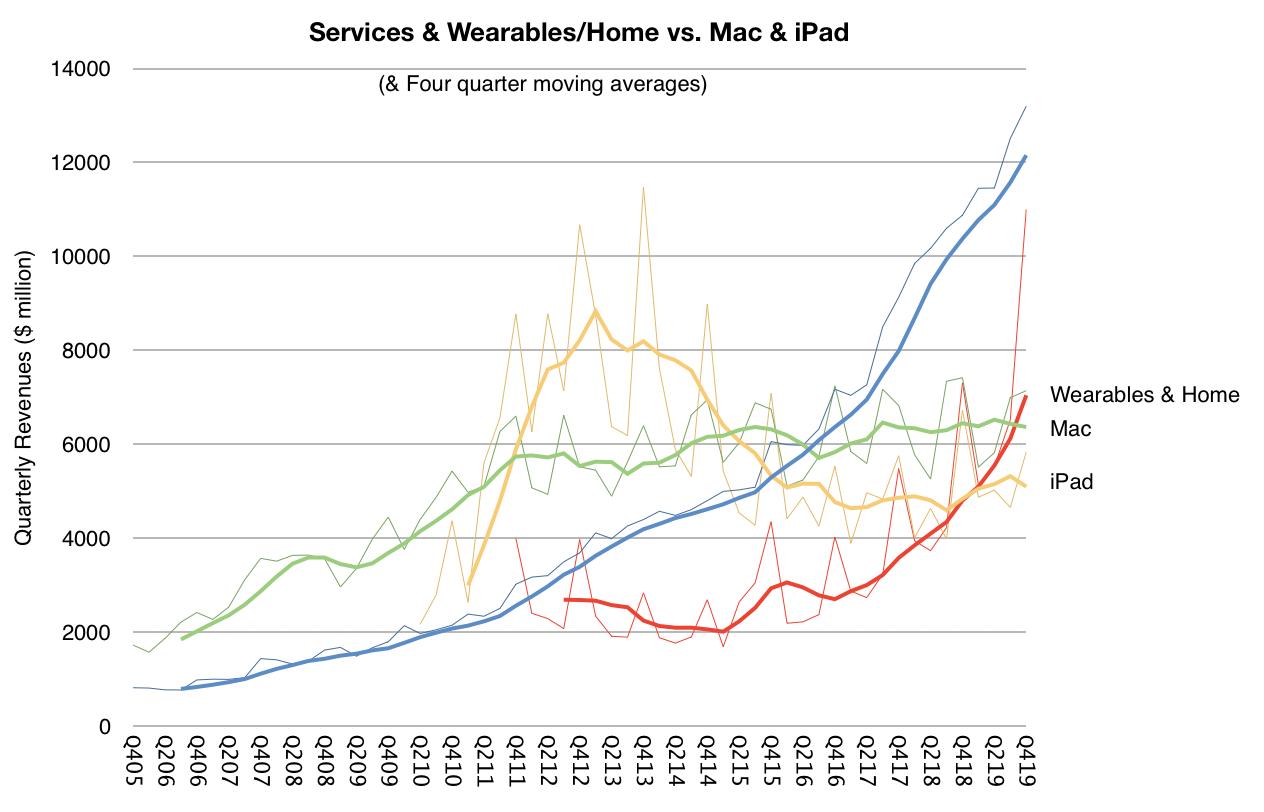
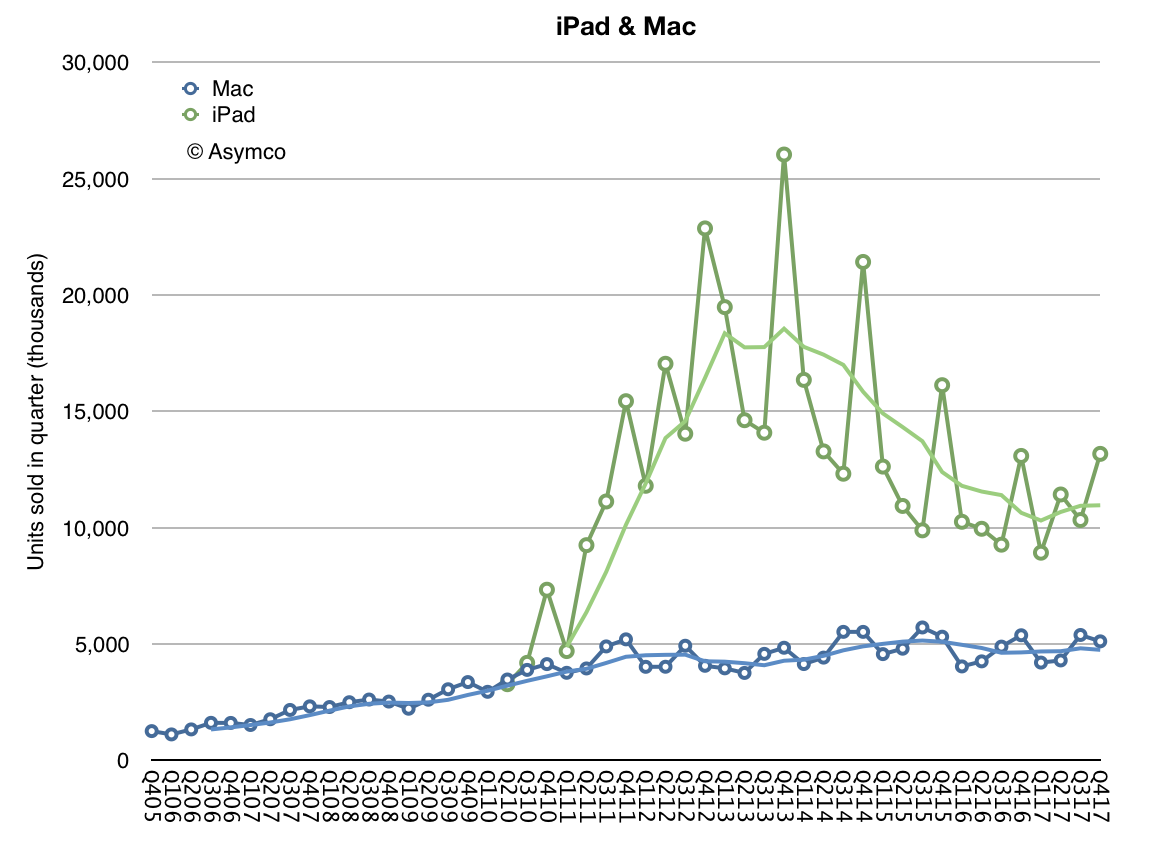
But what about the Mac? The Mac is the PC from the company that more or less defined the Post-PC era. Would it not be the first to be sacrificed for the new future? As it stands, as the graph below shows, the Mac today is double the business it was decade ago and although it has been overtaken by wearables, it has kept ahead (after a time) of the iPad.
As it turns out the Mac is doing just fine.
The trouble with PCs, including the Mac, is that they are stubborn in how they define themselves. Like the power user, they see performance along certain dimensions. They also don't see performance along new dimensions which devices offer with glee. For example connectivity to cellular networks (still missing in even the fanciest laptop but available on my watch.) Then there are the sensors which measure my heart rate, activity level, location, altitude, etc. Then there are cameras which on phones now boggle the mind. PC cameras are comical in comparison.
Then there is portability and usability without being plugged in.
Well, it was. With the M1, Apple has finally delivered the always-on feel of a tablet or phone and the more-than-one-day battery life. It also added a lot of neural engine horsepower and a lot of on-chip memory. Apple is delivering a system on a chip which makes the Mac more device-like in its integration. And sales are likely to rise, on the back of a great 2020 for the Mac. The form of the machine might even change with new designs being made possible by the lower heat profile and space savings.
And so I'm writing this post on a Mac. The graph you see above was created on the Mac. It's possible to do all this my iPad and even on my iPhone but it would be harder. But I'm also willing to bet you're reading this on a phone.
And that's the crux of it. The PC is still the machine of choice for authoring while the device is the machine of choice for consuming and consuming will always be more popular. What the iPad has done is taken a share of PC use and in my case I do use it for some tasks like email a lot more frequently. The theory would suggest that the iPad will continue its upward trajectory while the PC would abandon the low end.
This disruption has already happened but it hasn't been complete. The median performance band now belongs to devices but the professional will always ask for more of the performance which they see as productive while the consumer will always ask for more of the performance which they see as convenience. Here the market bifurcates.
What has been problematic with the smaller of the two markets has been the vicious cycle of lack of investment due to decreasing margins, commoditization and talent flight. What Apple is doing once again is ratcheting up the bar for the PC to make sure it's the top choice for creative professionals. And as long as they are productive, the consumers will keep them employed if not in riches.
At time of writing (December 12, 2019) AirPods Pro delivery wait time is over 4 weeks. It's been like this since they shipped. I tried stores in several countries and although units can make an appearance on a shelf, they sell out immediately.
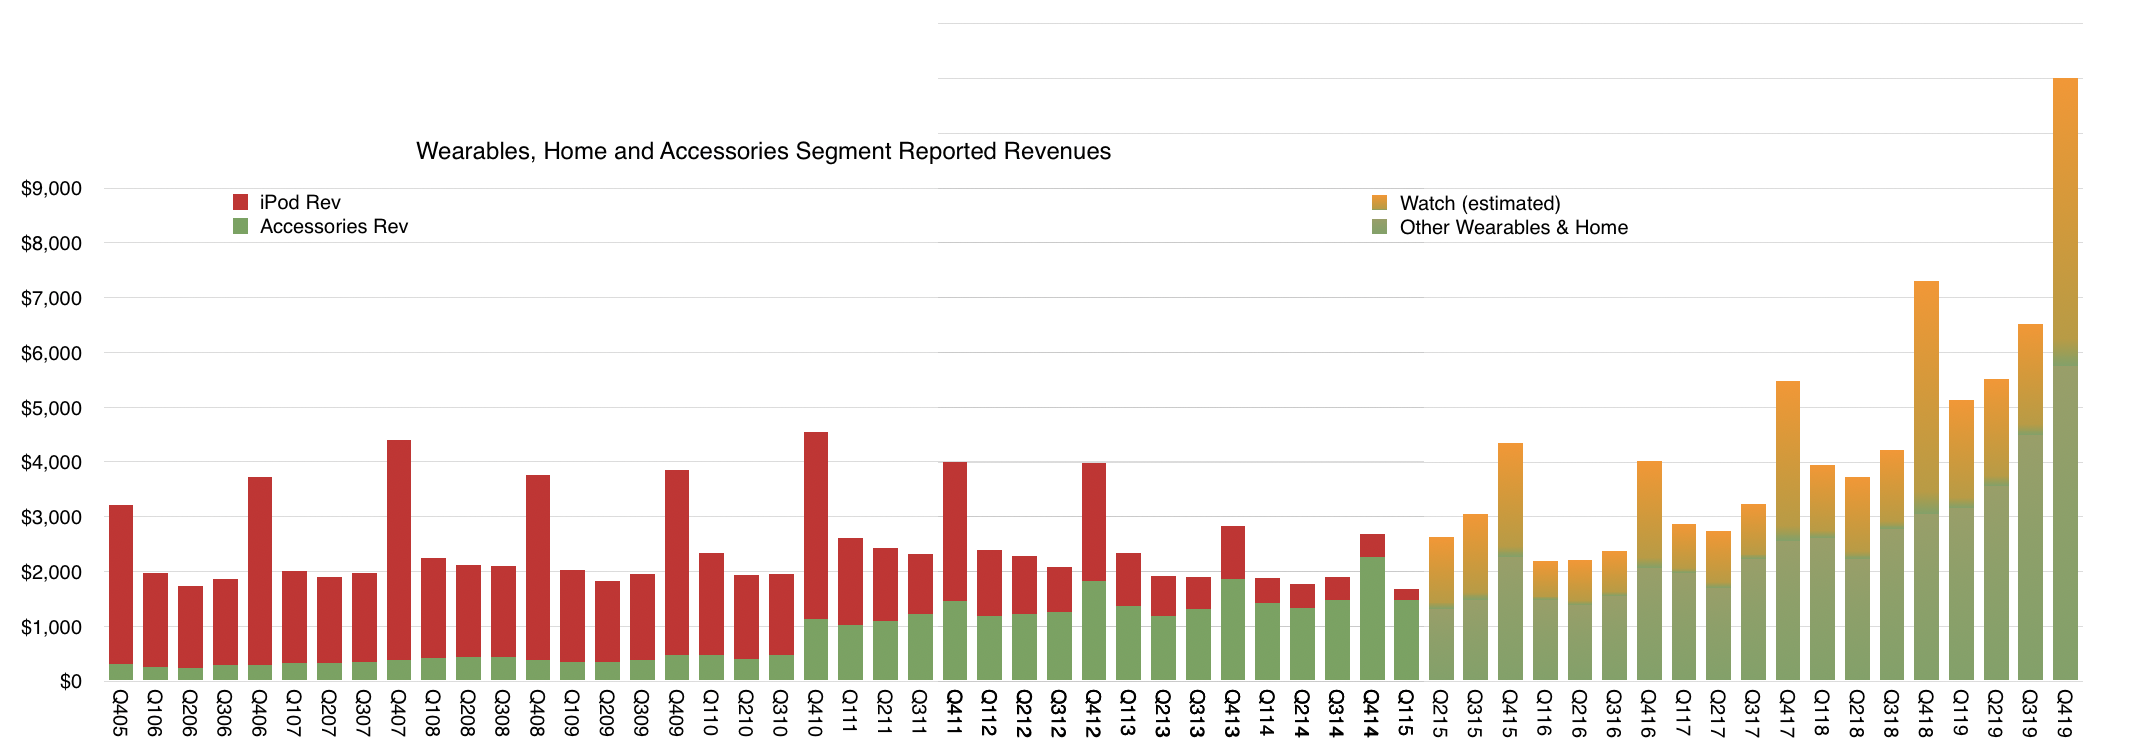
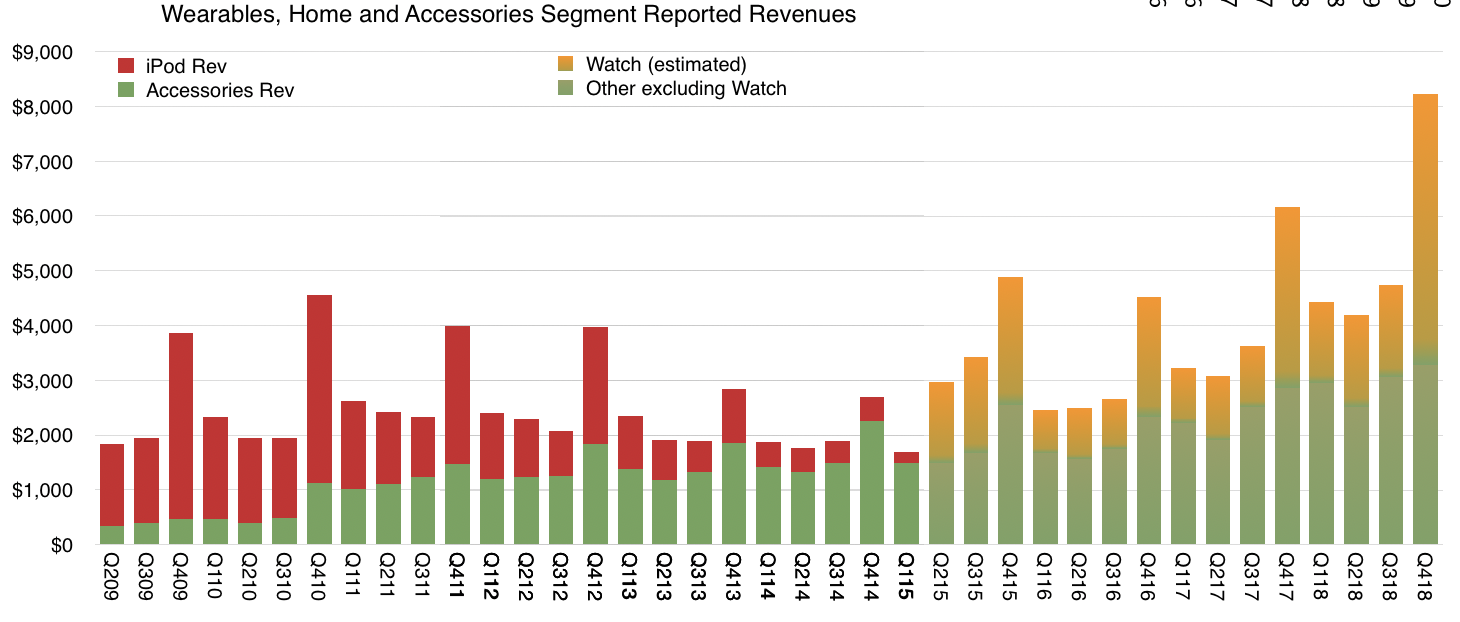
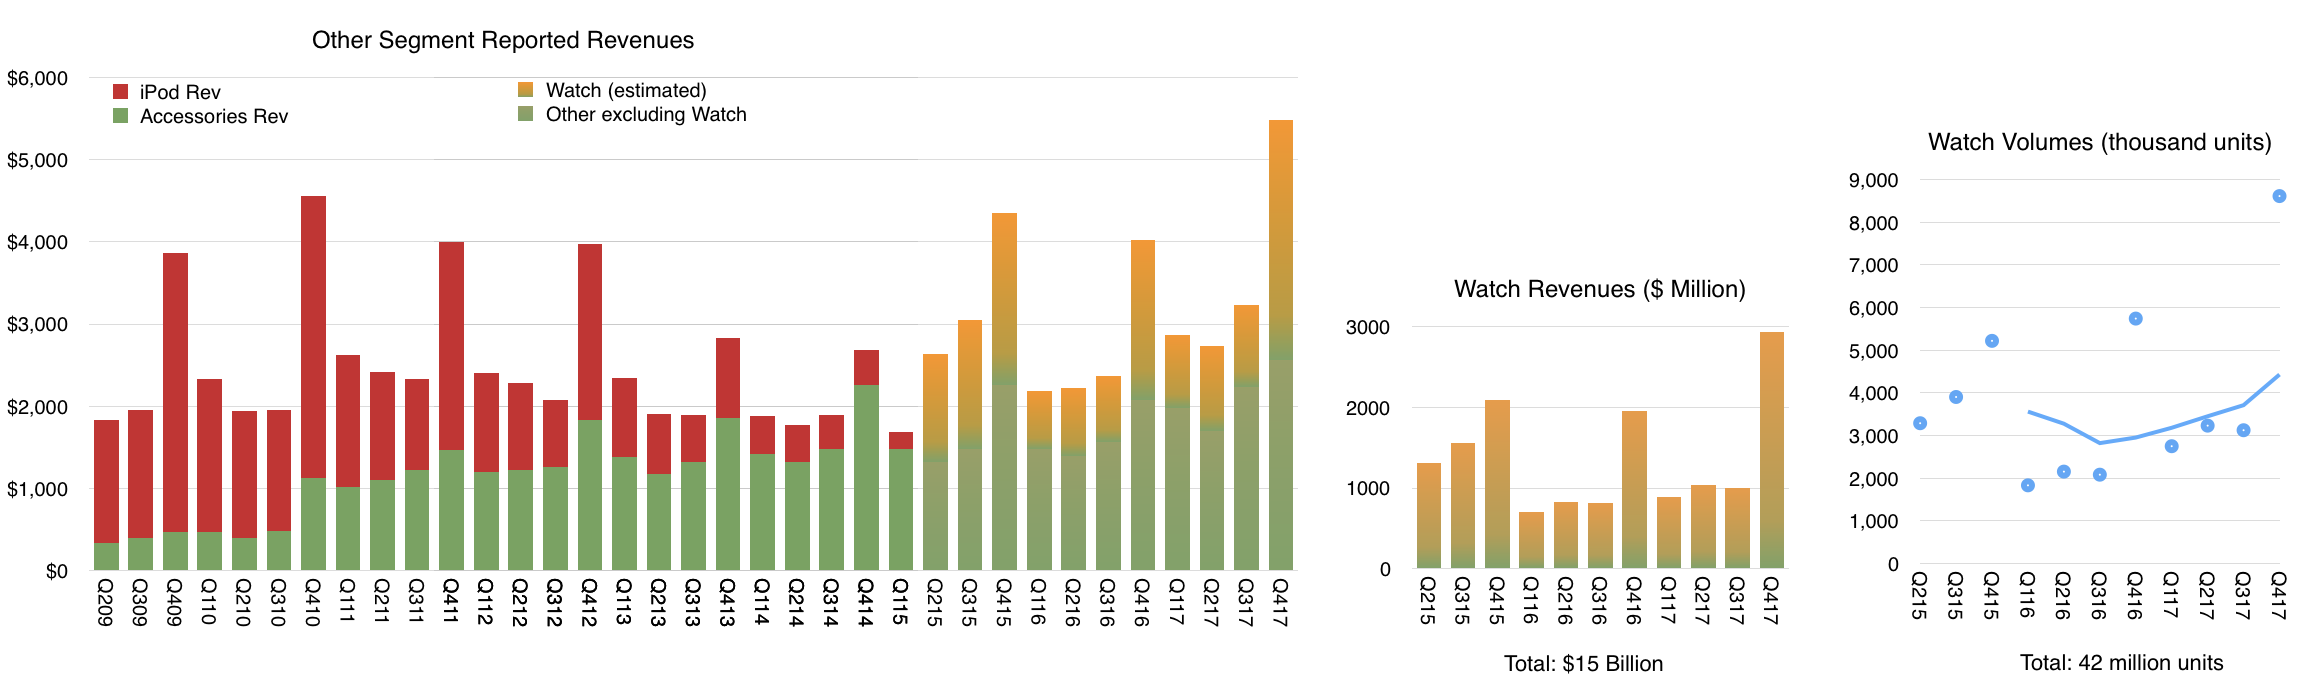
AirPods are part of the "Wearables & Home" category for Apple which used to be called Other Products and include also the Watch, iPod, Apple TV, Beats and HomePod (among other items.) iPod revenues were broken out as recently as 2015 but as the graph below shows, there have been no specifics on any product in "Wearables & Home" since then.
Wearables, Home and Accessories in a historic perspective with the iPod.
It therefore falls upon us to estimate how much of the entire category is any one product. It's been very difficult as the only clues lie in growth rates, sometimes cited for the Apple Watch and sometimes for "Wearables" alone. As far as I can tell from the available clues, the split is roughly as shown between the Orange and Green areas. Orange reflects estimate for Watch and Green everything else.
This analysis helped me conclude the Apple Watch overtook the historic "peak iPod" which occurred in the fourth quarter of 2007 at $4 billion. My Watch revenue estimate was $4.2 billion in the fourth quarter of 2018. This conclusion was confirmed by statements from the Company.
The problem lately has been that AirPods have become huge unto themselves. There is literally no information about AirPods sales as a product category. The only option is to guess Watch and subtract it from Wearables and then guess again the portion of "non-Watch Wearables & Home" that is AirPods.
Looking forward to the next quarter, I am expecting a 51% increase y/y for Wearables and 24% growth in Watch. This results in a Watch revenues about $5.2 billion and non-Watch $5.7 billion. Now if we assume $1.7 billion for non-Watch-non-AirPods (i.e. Apple TV, HomePod, Beats, iPod, other) then this quarter AirPods will have overtaken peak iPod.
Remember that iPod was the phenomenon which reset all expectations for Apple. It caused Apple to cease calling itself Apple Computer. It (at least psychologically) laid the foundation for iPhone and everything else that followed. In 2005 and through 2007 Apple was "the iPod company". I remember people working in a large search engine company calling Apple "that media company" as a result of over-intellectualizing iTunes.
(One more footnote on the AirPods Pro is that at $250 a pair and $300 for Apple Watch, throwing in a case puts these attached accessories for an iPhone at roughly the same average selling price for the iPhone of a few years ago.)
For the AirPods to overtake the iPod highlights just what a phenomenal category Wearables has become. In combination with Home and other accessories the category is going to decidedly overtake the Mac, having already passed the iPad.
And so it goes, something dismissed as inconsequential–"does not move the needle"–ends up becoming a massive force of change. The iPod was that, the original Apple II, the Mac and yes, also the iPhone. It's the asymmetry of humility that this happens over and over again.
To hear more about the profundities of AirPods Pro tune in to the next Critical Path podcast.
The Apple Watch is now bigger than the iPod ever was. As the most popular watch of all time, it's clear that the watch is a new market success story. However it isn't a cultural success. It has the ability to signal its presence and to give the wearer a degree of individuality through material and band choice but it is too discreet. It conforms to norms of watch wearing and it is too easy to miss under a sleeve or in a pocket.
Not so for AirPods. These things look extremely different. Always white, always in view, pointed and sharp. You can't miss someone wearing AirPods. They practically scream their presence.
For this reason wearers, whether they want to or not, advertise the product loudly. Initially, when new, they looked strange, even goofy. But the product's value to the wearer overcame any embarrassment and for those courageous enough to wear them, they became a point of pride. As all things distinctive enough, the distinction rubs on the user and that distinction begets new users and new distinction, and so on. So now we have a bona fide cultural phenomenon.
I have both my son and parents angling to get these things. I have not seen this universal appeal recently, even for the watch. You have to explain the watch. The AirPods explain themselves. The only thing which AirPods do remind me of is the original iPod. The iPod-and-white-earbuds had a similar signal/function ratio. Looks distinctive, works well, nails the job to be done and is self-describing. The "iconification" of white was the phenomenon of its decade.
One wonders how much of this behavior is by design or, more precisely, engineered by designers. Did Jony Ive's team plan on users "flexing" with their AirPods? Did they make them distinctive on purpose with the stalks pointing down vs,, for example, wrapping around the back of the ear for a more discreet look? Was it just good luck and the form followed function? It's hard to imagine that taste could be engineered but here we are.
Whether planned or not, the newest AirPods offer a functional upgrade with no visual upgrade. This is noteworthy because whatever they got right with the original design they decided not to mess with it. You can't tell if someone is wearing the newest AirPods or the originals.
As far as the added functionality it is typical Apple: faster connections due to a new chip, longer talk time, longer listen time, voice-activated Siri and wireless charging. Broadly speaking they are just better in ways that need to better and not better in ways they are good enough.
The product is part of the "wearables" category at Apple which includes watch and is growing almost 50%/yr. and not from a small base either. The following graph show the history of the segment since 2009 (before the iPod peaked).
As can be seen, Wearables and Home segment grew out of the iPod segment, through "Other" products and is now almost double what the iPod used to be alone.
It should be noted that the AirPods can be paired directly with the Apple Watch and used independent from the iPhone. If not from this point alone, culturally the iconic white AirPods and jewel-like Apple Watch embody the spirit of the iPod.
We want things to get better. The desire of improvement and an increase in performance is seemingly innate. The old adage goes that using the word "new" is the most effective way to increase sales. "New & Improved" if you want to be redundant.
For many in technology, New & Improved means faster with more of every measurable parameter. More memory, more pixels, more storage, more bandwidth, more resolution. In devices, the tendency has been to communicate "new & improved" through an increase in screen size. We are subject to this to such an extent that phones are becoming unusable with one hand, stretching screens to the edge of the device and then wrapping those screens around the edges and then even folding the screens so that we have to unfold or unroll to use the product. Maybe an origami phone is in the works.
But there is a parallel movement where "New & Improved" means smaller. This is the trend to miniaturization. Smaller is better because it's more portable, more conformable. Things sold by the ounce are better than things sold by the pound. The best computer, the best anything, is the one you have with you and having it with you is more likely if you can take it with you. So that which you can take with you is the best. QED.
Apple has had a great history of miniaturization. The original Macintosh was tiny compared with personal computers of its day. It had a handle so you could take it with you. Apple pioneered laptops with breakthroughs in utility and form which made them truly portable. The iMac followed with a degree of integration and portability which made it iconic. Of course the iPod and iPhone were marvels when they first appeared.
Over the years these products expanded into ranges with "good, better, best" type segmentation. The bigger being the best in performance and the smaller typically being the most convenient. However it seemed that the positioning was toward "bigger is better" for a lot of these products. The iPhones Plus, the iPads Pro, etc. As even the largest were getting thinner, the "mini" versions appeared to be neglected. You could get "good enough" portability from the larger products so why bother with the minis.
It came to a head when the iPhone SE was discontinued last fall. Its demise felt like the end of an era. I always considered the SE as the "Steve Edition". It was the last design Steve Jobs was involved in and it pained me to see it go. With it seemed to go the positioning around "mini".
But also last fall we saw a re-boot of another almost-forgotten mini: the Mac mini. For me the Mac mini was quintessentially Jobsian. I remember that he loved tiny products. His launch of the iPod nano was spectacular; reaching into his jeans' watch pocket to pull it out on stage. Holding the Mac mini up as if a tiny tray. Even the iPod shuffle was a quirky and lovable idea ((probably the first Apple wearable as you could actually pin it to your clothes)). And let's not forget the Mac Cube which made the iMac look huge.
When the Mac mini was released last fall in Brooklyn with a huge spec bump and a thunderous reveal I thought something was up. When the MacBook Air was also out at the same event I felt that the company was signaling something. Perhaps a re-dedication to the low end.
Also in parallel there is the wearables product line. The AirPods and the Apple Watch are jewelry. The essential qualities of products you wear are that they be small and beautiful. The smaller the better. Above all, both the Watch and AirPods are marvels of miniaturization. They pack so much in so little volume and that volume is shaped in such an aesthetically elegant way that they become daily essentials. I use my Apple wearables more than any other Apple product. Watch glances and time with AirPods exceeds the iPhone unlocks and iPhone use time. The fact that we don't even realize that the smallest Apple products are also the ones we use most is a testament to their conformability to us.
So the Mac mini that is suddenly the Mac Maxi in performance, the MacBook which is an extraordinarily small laptop, the wearables success, all pointed in a direction that the iPhone did not: that "mini" was back.
And now we see the iPad mini being re-launched with a huge spec bump. We should take the hint. The iPad mini is just charming. I have been trying it out for a few days and it has worked its way into my routine. I have an iPad Pro that I use on a desk to design presentations (and to deliver them). I use it with a keyboard for dealing with email on my lap or on a plane and take it instead of a laptop when going to meetings.
But the iPad mini worked its way to my nightstand. It the one I reach for when on a couch. It is like an iPhone but when you're at home it's better than the iPhone because you can linger on that new true tone screen. It works well one handed. It now has Pencil support so it can be used for sketching and doodling.
I am an analyst not a product reviewer but I sense how it fills a gap between iPhones and larger devices--in a home setting. Of course it can be used in an office. It is much easer to take with you if you carry a laptop in a bag.
Fundamentally explaining mini is pointless. mini is something that is felt more than it is perceived. You can see the attraction of a tiny product only when you come face-to-face with it. In a picture it's hard to get it--there is no frame of reference. What draws me to a MacBook or to a mini or a Watch is when it's touched and held and carried or worn. The experience of the product is not how it works but how it works with you. You have to be part of it. It's not asking "Does it look good?". It's asking "Does it look good on me?" mini means more personal.
That is the nature of mini and that is why I love the new minis: the iPad mini, the Mac mini, the MacBook (mini) and that is what I dare to hope that there is an iPhone mini coming.
The following is a transcript of the comments from Tim Cook (CEO) and Luca Maestri (CFO) at Apple's Q1 2018 Earnings Conference Call February 1, 2018. I color coded my interpretation of the comments into four categories:
Grey: Background and promotional commentary
Red: Strategy and signals of what management considers important and may include data beyond the regularly reported numbers.
Green: Financial data
Black: Commentary.
Blue: My commentary, in brackets.
For a quick read of Apple's strategy, read the Red text. These comments are not repeated in financial reports. Highly recommended.
For a quick read of Apple's financial performance, read the green text (which are replicated in financial reports). Read this if you don't want to wade through the financial reports.
For marketing or product material, read the grey text.This is sometimes unique but also repeats product launch information.
---- Tim Cook: Thanks, Nancy and thanks everyone on the call, and welcome to everyone today. Before we dive into the quarter, I'd like to take a moment to talk about a significant milestone we recently crossed.
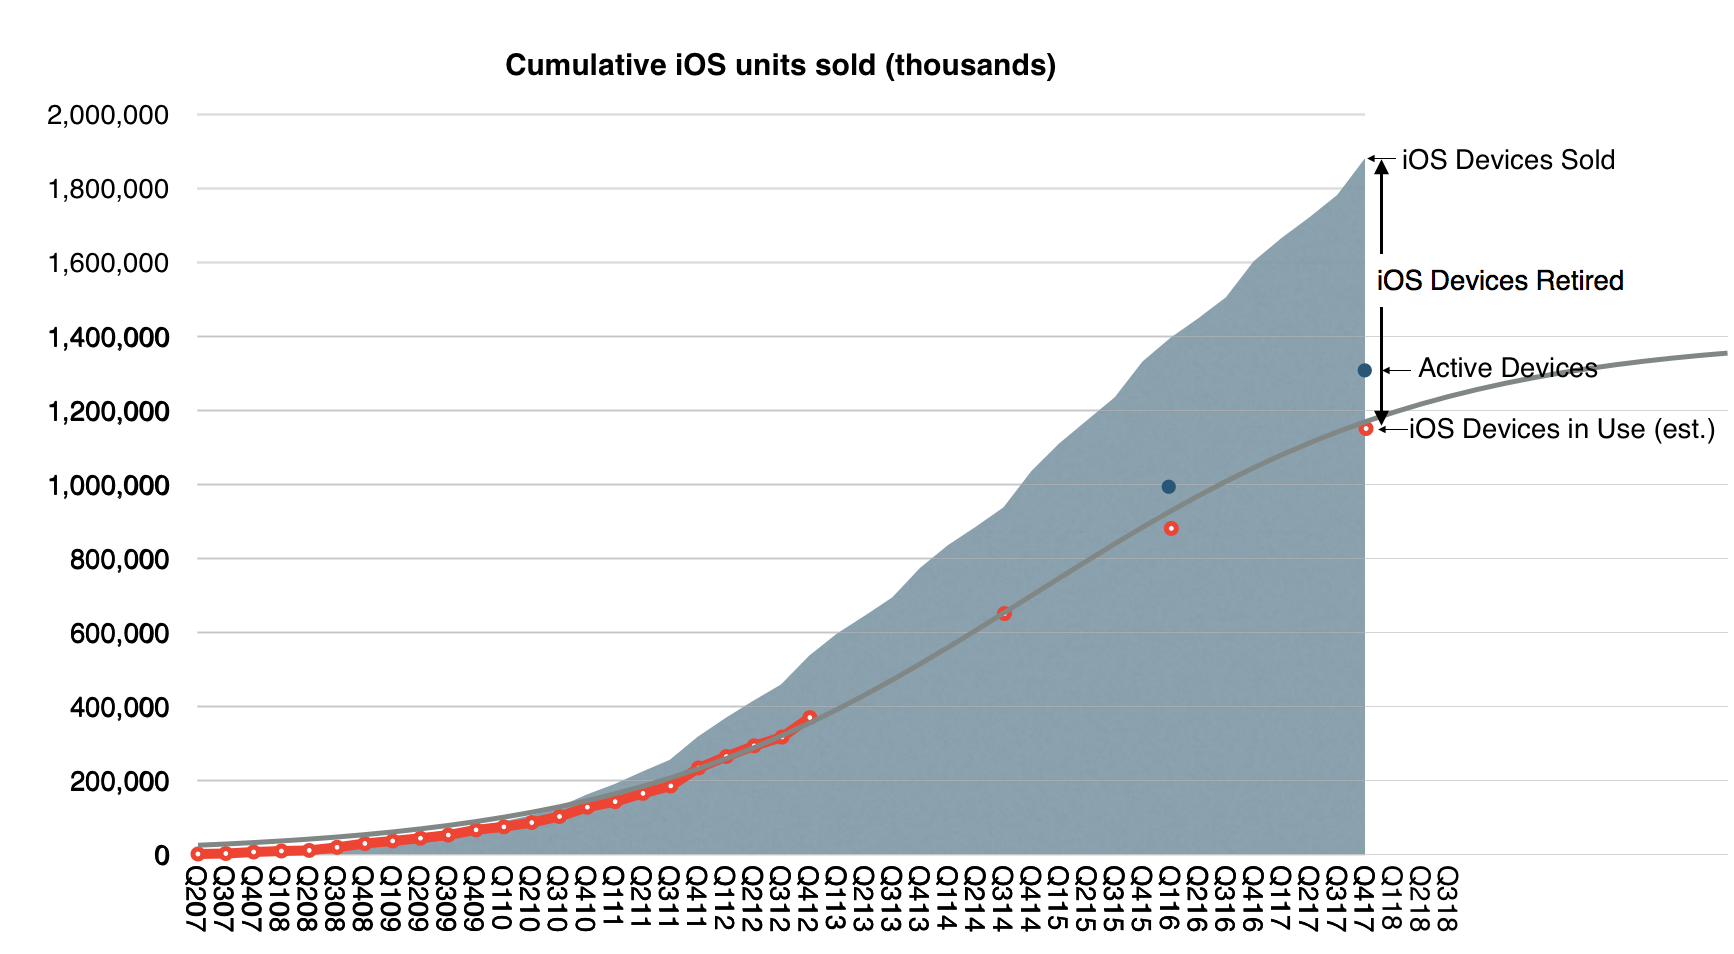
Apple's active installed base reached 1.3 billion devices in January and is at an all-time high for all of our major products. 1.3 billion devices represents an astonishing 30% growth in just two years. It speaks to the strength and reliability of our products and our ecosystem, as well as the loyalty, satisfaction and engagement of our customers. It's also fueling tremendous growth in our services business, which I’ll talk about a little later in the call. [This is probably Apple's most important number. For at least the next 20 years this is the key performance metric and it can be used to derive company's valuation. A summary of the history of active devices vs. units sold is shown in the graph below:]
Turning to the December quarter. We're thrilled to report Apple's biggest quarter ever, which set new all-time records in both revenue and earnings. We generated revenue of $88.3 billion, which is above the high-end of our guidance range, and it is up almost $10 billion or 13% over the previous all-time record we set a year ago.
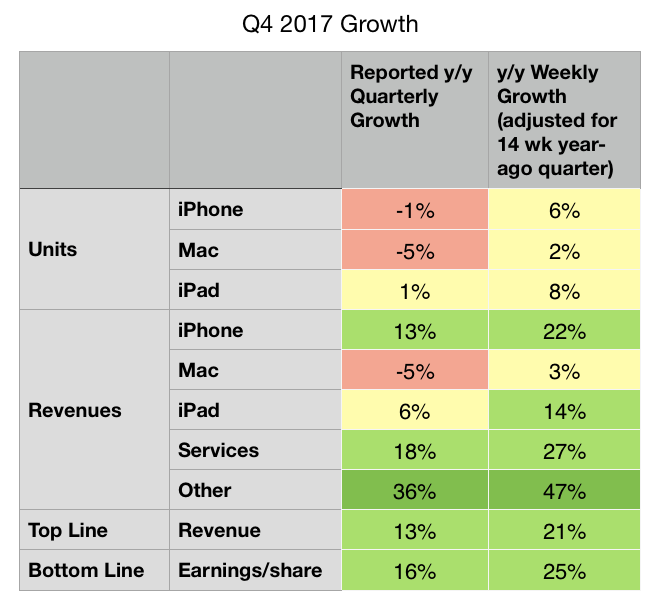
It's also our fifth consecutive quarter of accelerating revenue growth with double digit growth in each of our geographic segments around the world. What makes us even more remarkable is that the quarter we're reporting today was 13-weeks long, while the year ago quarter was 14-weeks. When we look at the average revenue per week in the December quarter this year compared to last year, our growth was a stunning 21%. [The 13-week vs. 14-week year-on-year comparison is repeated several times. The summary differences are shown in the table below:]
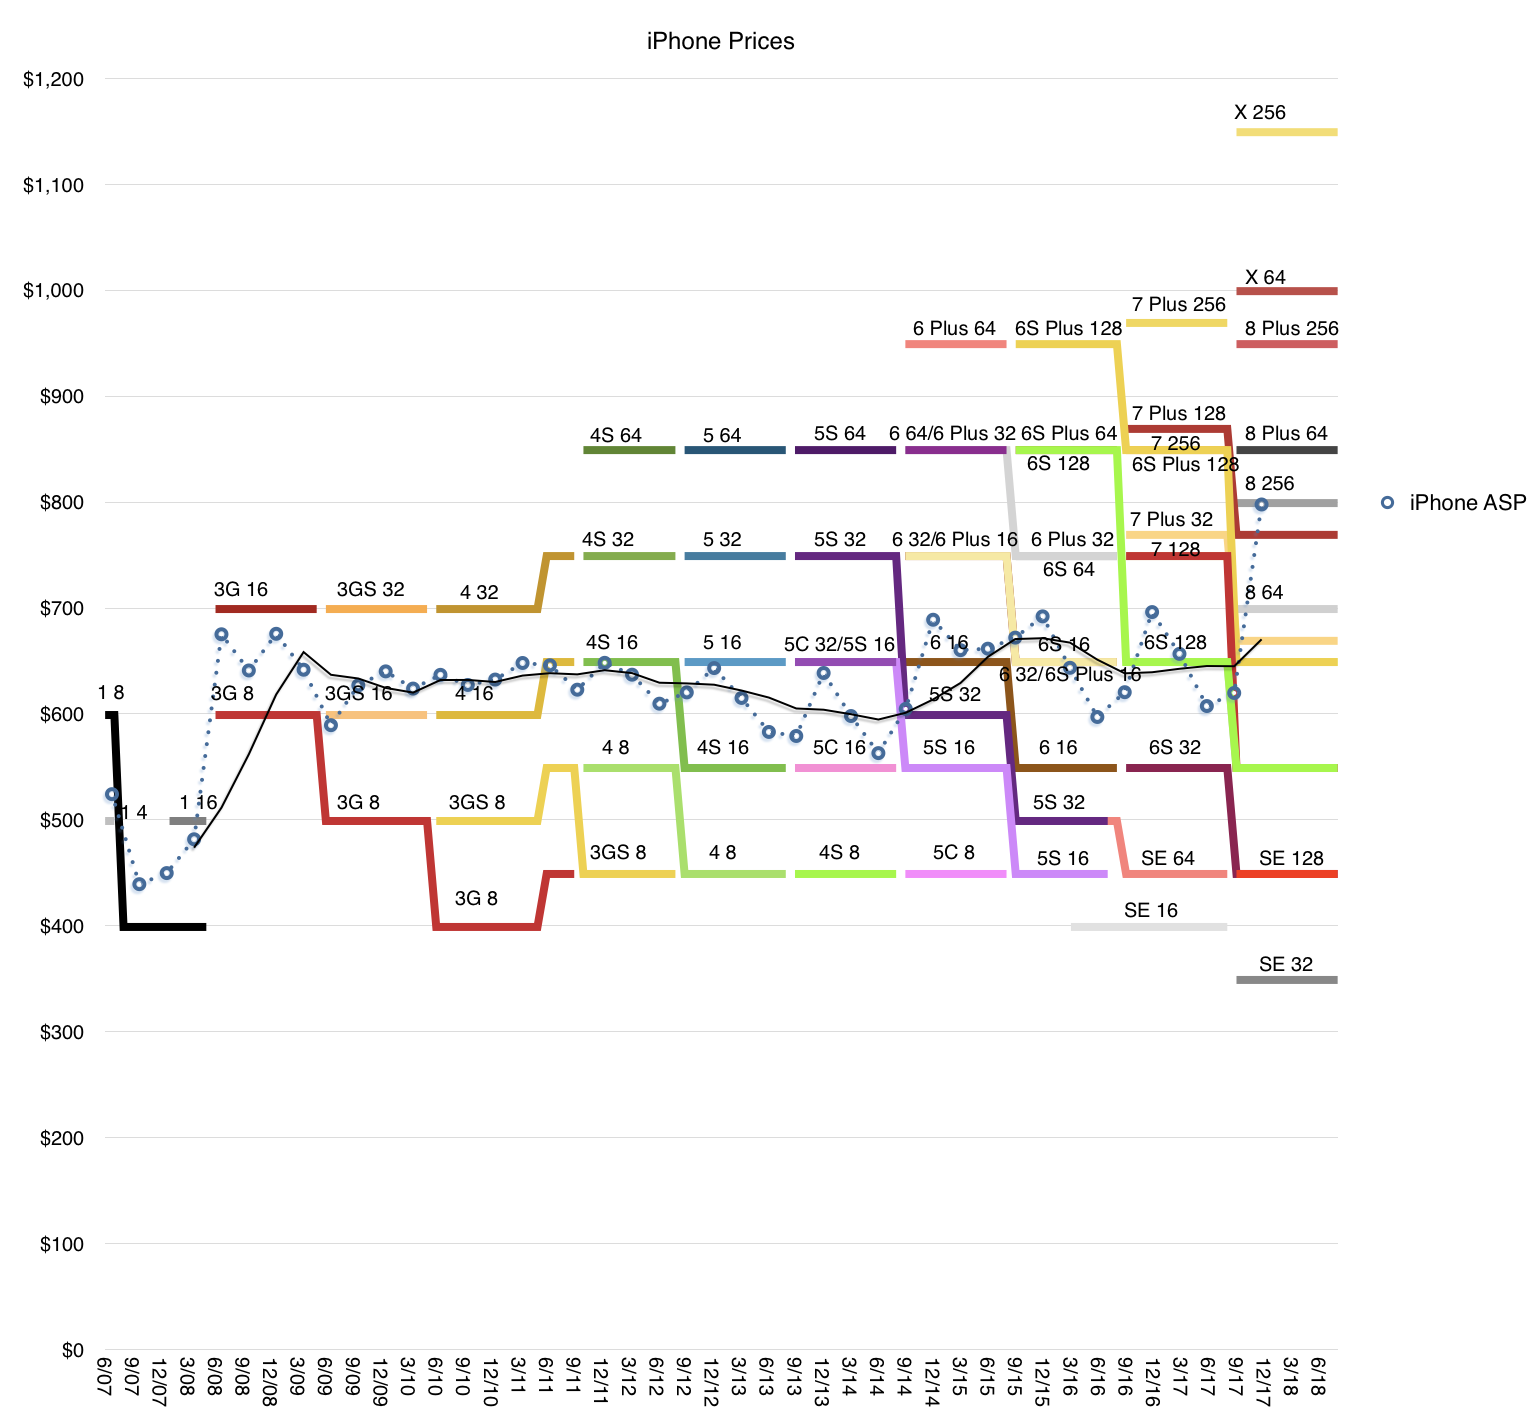
Our growth was broad-based and a key driver was iPhone, which generated its highest revenue ever. iPhone X was the best-selling smartphone in the world in the December quarter according to Canalys, and it has been our top selling phone every week since it launched. iPhone 8 and iPhone 8 Plus rounded out the top three iPhones in the quarter. In fact, revenue for our newly launched iPhones was the highest of any lineup in our history, driving total Apple revenue above our guidance range. [The iPhone X is a huge hit. It drove the average selling price $100 higher y/y. This is not only unprecedented for Apple but for the entire Industry. The average smartphone sells for less than $300 while iPhones sold for $800. The gap is widening. The following graph shows the product mix and the average resulting price.]
I want to take a moment to recognize the tremendous amount of work that went into creating iPhone 10. Our teams carried out an extremely complex launch from both an engineering and operations perspective, executing an outstanding product ramp that required years of research and development; one that introduced innovative features like an edge-to-edge Super Retina Display and the TrueDepth Camera, which enables face ID. Our customers love these new features and the new gestures like simply swiping up from the bottom, which make using iPhone even more intuitive and enjoyable.
Our team has put the technology of tomorrow in our customers’ hands today, set a standard for the next decade of smartphones and we are very proud of their achievements.
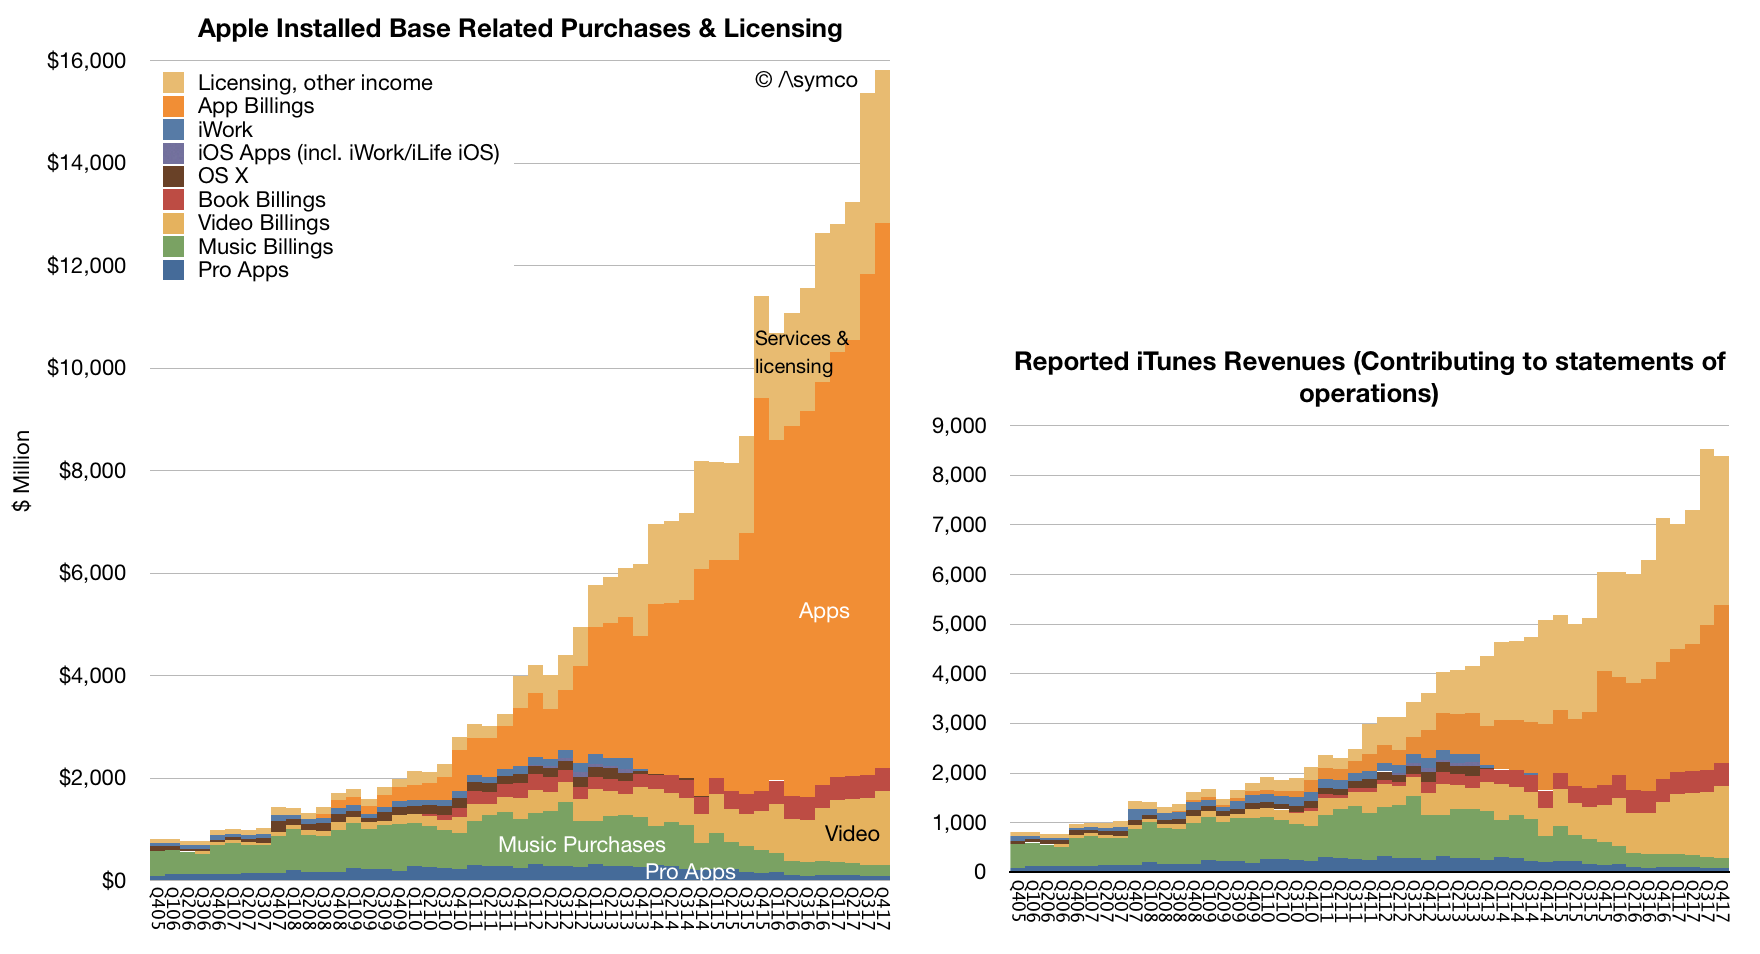
It was another very strong quarter for services with revenue of $8.5 billion, up 18% over last year, and we’re on pace to achieve our goal of doubling our 2016 services revenue by 2020. The number of paid subscriptions across our services offerings passed 240 million by the end of the December quarter, that’s an increase of 30 million in the last 90 days alone, which is the largest quarterly growth ever. [Services has been growing relentlessly for over a decade. This steadiness of growth makes is a juggernaut. Apple is increasingly speaking about subscriptions as the key metric and 240 million is reaching record territory. The rise of Services is shown below (both revenues and consumer spending.)]
We had an all-time record quarter for the App Store with our best holiday season ever. We’re seeing great excitement around augmented reality with customers now enjoying over 2,000 ARKit enabled app, spanning every category in the App Store. In December, when Pokémon GO released its new augmented reality features built with ARKit, it jumped the top of the App Store charts. Last week, on a stop in Toronto, I met developers who are hard at work on creative applications using ARKit from art appreciation to ecommerce, and I was very impressed with what I saw.
Just for months after ARKit launched to the public, we’ve already released ARKit 1.5 in beta to developers around the world, and the response has been tremendous. Augmented reality is going to revolutionize many of the experiences we have with mobile devices. And with ARKit, we’re giving developers the most advanced tools on the market to create apps for the most advanced operating system running on the most advanced hardware. This is something only Apple can do.
In addition to the App Store, several other services had their biggest quarter ever, including Apple Music, iCloud and Apple Pay, all of which saw growth in both active users and revenue.
Apple Pay has reached an important milestone in the U.S. As a result of 50% year-over-year growth in merchant adoption, it’s now accepted at more than half of all American retail locations, which includes more than two-thirds of the country’s top 100 retailers. Now available in 20 markets, global Apple Pay purchase volume more than tripled year-over-year and we’re delighted to be expanding to Brazil in the coming months. [There are no absolute data points on Apple Pay but we do have some scattered growth data. The US data is cited here but in my experience it's more popular in select countries like UK where users are using it habitually]
Today, you can use Apple Pay to take the subway in Guangzhou, China, see a concert at London’s Wembley Stadium or buy a souvenir in Yosemite National Park. In the U.S., we launched Apple Pay Cash in December, and it’s off to a terrific start. Millions of people are already using it to send and receive money with friends and family quickly, easily and securely; to split a bill, pay someone back, or send last minute gift right from the messages app.
It was our best quarter ever for the Apple Watch with over 50% growth in revenue and units for the fourth quarter in a row and strong double-digit growth in every geographic segment. Sales of Apple Watch Series 3 models were also more than twice the volume of Series 2 a year ago. Apple Watch is the most popular, smart watch in the world and gained market share during the quarter based on the latest estimates from IDC. [Apple Watch is growing consistently. The following graph shows my estimates of volume (total 42 million to date) and revenues (total $15 billion) based on all available data and commentary from management.]
It was the third consecutive quarter of growth for iPad revenue, thanks to the strength of both iPad and iPad Pro. Based on the latest data from IDC, we gained share in nearly every market we track with strong outperformance in emerging markets.
Worldwide, almost half of our iPad sales were the first-time tablet buyers are those switching to Apple, and that’s true in some of our most developed markets, including Japan and France. In China, new and switching users made up over 70% of all iPad sales.
For Mac, we launched the all new, iMac Pro in mid-December. It’s an entirely new product line designed for our Pro users who love the all-in-one design of iMac and require workstation class performance. It's the fastest, most powerful Mac ever, delivering incredible computational power, for simulation and real time 3D rendering, immersive VR and complex photography audio and video projects. Worldwide, 60% of our Mac sales were the first time buyers and switchers and in China, that number was almost 90%.
We're looking forward to getting HomePod in customers’ hands beginning next week. HomePod is an innovative wireless speaker, which delivers stunning audio quality wherever its placed in the home, thanks to the advanced Apple engineered hardware and software.
Together with Apple Music, HomePod gives you instant access to one of the world's largest music catalogs. And with the intelligence of Siri, it’s a powerful assistant you control through natural voice interaction. We're very happy with the initial response from reviewers who've experienced HomePod ahead of its launch, and we think our customers are going to love this new product.
We believe one of the key issues of the 21st century is education. And because of that, we've strengthened our commitment and investment into initiatives like everyone can code. To find the innovators of the future, we need to nurture the students of today. Our App Development with Swift curriculum, which is available free on iBooks, has been downloaded more than 1.2 million times worldwide with almost half of those coming from here in the United States. It’s also being taught in dozens of community colleges across the country, putting practical skills in the hands of today’s jobs seekers.
I was in London two weeks ago as we announced that the program was expanding to more than 70 colleges and universities in Europe. Millions of students around the world will have the opportunity to add Swift to their coding vocabulary and gain skills that are essential for today’s economy.
This is an exciting time at Apple and with the best lineup of products and services we've ever had and a set of initiatives that show how business can be a force for good in the world. We could not be more excited about our future.
Now, for more details on the December quarter results, I'd like to turn over the call to Luca.
Luca Maestri: Thank you, Tim. Good afternoon, everyone. Our business and financial performance in the December quarter were exceptional, as we set new all-time records for revenue, operating income, net income and earnings per share.
Starting with revenue, we’re reporting an all-time record, $88.3 billion, up nearly $10 billion or 13% over the prior record set last year. It is our fifth consecutive quarter of accelerating revenue growth. As you know, the December quarter a year ago spanned 14-weeks compared to 13-weeks this year, which is important to consider as we have set the underlying performance of our business this year. When we look at average revenue per week, our growth rate was even higher at 21% with growth across all product categories for the third consecutive quarter.
Our results were terrific all around the world with double digit revenue growth in all our geographic segments, an all-time quarterly record in the vast majority of markets we track, including the U.S., Western Europe, Japan, Canada, Australia and Korea, as well as Mainland China, Latin America, The Middle East, Central and Eastern Europe, and India.
In Greater China, we were very happy to generate double digit revenue growth for the second quarter in a row and in emerging markets outside of Greater China, we saw 25% year-over-year growth.
Gross margin was 38.4% at the high end of our guidance range. Operating margin was 29.8% of revenue. Our net income was $20.1 billion an all-time record, and up $2.2 billion over the last year. Diluted earnings per share were $3.89 also an all-time record and cash flow from operations was very strong at $28.3 billion.
During the quarter, we sold 77.3 million iPhones, the highest number ever for a 13-week quarter. Average weekly iPhone sales were up 6% compared to December quarter last year with growth in every region of the world despite the staggered launch of iPhone 10. We established all-time iPhone revenue record in nearly every market we track with double-digit growth in all of our geographic segments. iPhone ASP increased to $796 from $695 a year ago, driven primarily by the launch of iPhone 10 and the success of iPhone 8 and 8 Plus.
We exited the December quarter towards the lower end of our target range of five to seven weeks of iPhone channel inventory with less than 1 million more iPhones in the channel compared to the December quarter a year ago, in line with our growth in average weekly unit sales. Customer interest and satisfaction with iPhone are very, very strong for both consumers and business users.
The latest data from 451 Research indicates U.S. customer satisfaction ratings of 96% or higher across iPhone models. In fact, combining iPhone 8, iPhone 8 Plus and iPhone 10, consumers reported an amazing 99% satisfaction rating. And among business customers planning to purchase smartphones in the next quarter, 77% planned to purchase iPhone. Our customers are also incredibly loyal with Kantar's latest U.S. research, reflecting a 96% iPhone loyalty rate, the highest ever measured. [Customer satisfaction is the second most important figure after active user base. Combining these two figures yields the recurring revenue value of the company. Remember what Deming said: the most important measurements for a company's value are the multipliers of a satisfied customer and a dissatisfied customer--these numbers never appear on any financial report but they are applied to all the numbers on every report].
Turning to services. We had a terrific quarter with revenue of $8.5 billion, up 18% year-over-year and up 27% in terms of average revenue per week; that is an acceleration to the 24% services growth run rate that we experienced in the September quarter.
The App Store set a new all-time revenue record. The Store’s all-new design is off to a fantastic start with quarterly store visitors, transacting accounts and paying accounts, reaching new all-time highs. During the week beginning December 24th, a record number of customers made purchases or downloaded Apps from the App Store, spending over $890 million in that seven-day period, followed by $300 million in purchases on New Year’s day alone.
And according to App Annie’s latest report, the App Store continues to be the preferred destination for customer purchases by a very wide margin, generating nearly twice the revenue of Google Play. Across all our services offerings, paid subscriptions reached $240 million with growth of 58% over last year and they were a major contributor to the overall strong growth in services revenue. [Apple has half the user base of Google Android. This is based on Google's May 2017 report of 2 billion active devices vs. the 1.3 billion that we just got from Apple. And yet these users collectively spend twice as much on apps. This ratio of "half the users, twice the spending" has been cropping up in individual developer anecdotes and can also be seen in other metrics of engagement and consumption. This should not be surprising as it conforms to the Pareto distribution of economic value.]
As Tim mentioned, it was our best quarter ever for Apple Watch. And when we add to this us from Beats and AirPods, our total revenue from wearables was up almost 70% year-over-year. In fact, wearables were the second largest contributor to revenue growth after iPhone, which is impressive for a business that started only three years ago. In total, our other products category set a new all-time record with quarterly revenue exceeding $5 billion for the first time. [Wearables now includes more than watches but watches are likely still the dominant product.]
Next, I’d like to talk about the Mac. We sold 5.1 million Macs during the December quarter, which translates to a 2% year-over-year increase in average sales per week. Mac performance was particularly strong in emerging markets with unit sales up 13% year-over-year and with all-time records in Latin America, in India, Turkey and Central and Eastern Europe. On a worldwide basis, the active install base of Macs was up double-digits year-over-year to a new record.
It was also another growth quarter for iPad. We sold 13.2 million units with average iPad sales per week up 8% over last year’s December quarter. iPad sales grew strong double-digits in many emerging markets, including Latin America, the Middle East, Central and Eastern Europe and India, as well as developed markets, including Japan, Australia and Korea. The active install base of iPad has grown every quarter since its launch in 2010, and it reached a new all-time high in December, thanks to extremely high customer loyalty and large numbers of first-time iPad users. [iPad is clearly recovering from a long decline. ASPs are rising as it's being positioned as a PC alternative. Its low end functions are being absorbed by large screen iPhones.]
NPD indicates that iPad had 46% share of the U.S. tablet market in the December quarter, up from 36% share a year ago. And the most recent surveys from 451 Research found that among customers planning to purchase tablets within 90 days, 72% of consumers and 68% of business users planned to purchase iPads. Customer satisfaction is also very high with businesses reporting a 99% satisfaction rating for iPad.
We are seeing great traction in enterprise as businesses across industries and around the world standardize on iOS. For example, Intesa Sanpaolo, one of Europe’s leading banks, has chosen iOS as the mobile standard for its entire 70,000 employee base in Italy; choosing iOS for its security, user interface, accessibility and reliability, Intesa Sanpaolo will deploy native apps to improve employee productivity in customer support, human resources, and marketing across the company.
And LensCrafters, one of the largest optical retail brands in North America, will be using over 7,000 iPad Pros to enable digital eye exams and digital optical measurements in a personalized and interactive experience. We’re also rolling out a new initiative, called Apple AtWork to help businesses implement employee choice programs more easily and offer Apple products company-wide.
Resources from both Apple and our channel partners will enable enterprise IT and procurement teams to buy or lease Apple products more efficiently, streamline the setup of iPhone, iPad, and Mac, and deliver a seamless onboarding experience for employees. We launched the program with CDW in the U.S. last week, and we would be expanding to more channels and regions later this year.
The December quarter was extremely busy for our retail and online stores, which welcomed 538 million visitors. Traffic was particularly strong during the four-weeks following the launch of iPhone 10, up 46% over last year. And across the quarter, our stores conducted over 200,000 today at Apple sessions, covering topics including photography, music, gaming, and app development, and art and design. Just last weekend, we opened our first store in Seoul, Korea and we’re looking forward to opening our first store in Austria in a few weeks. These newest openings will mark the expansion of our retail store presence to 21 countries.
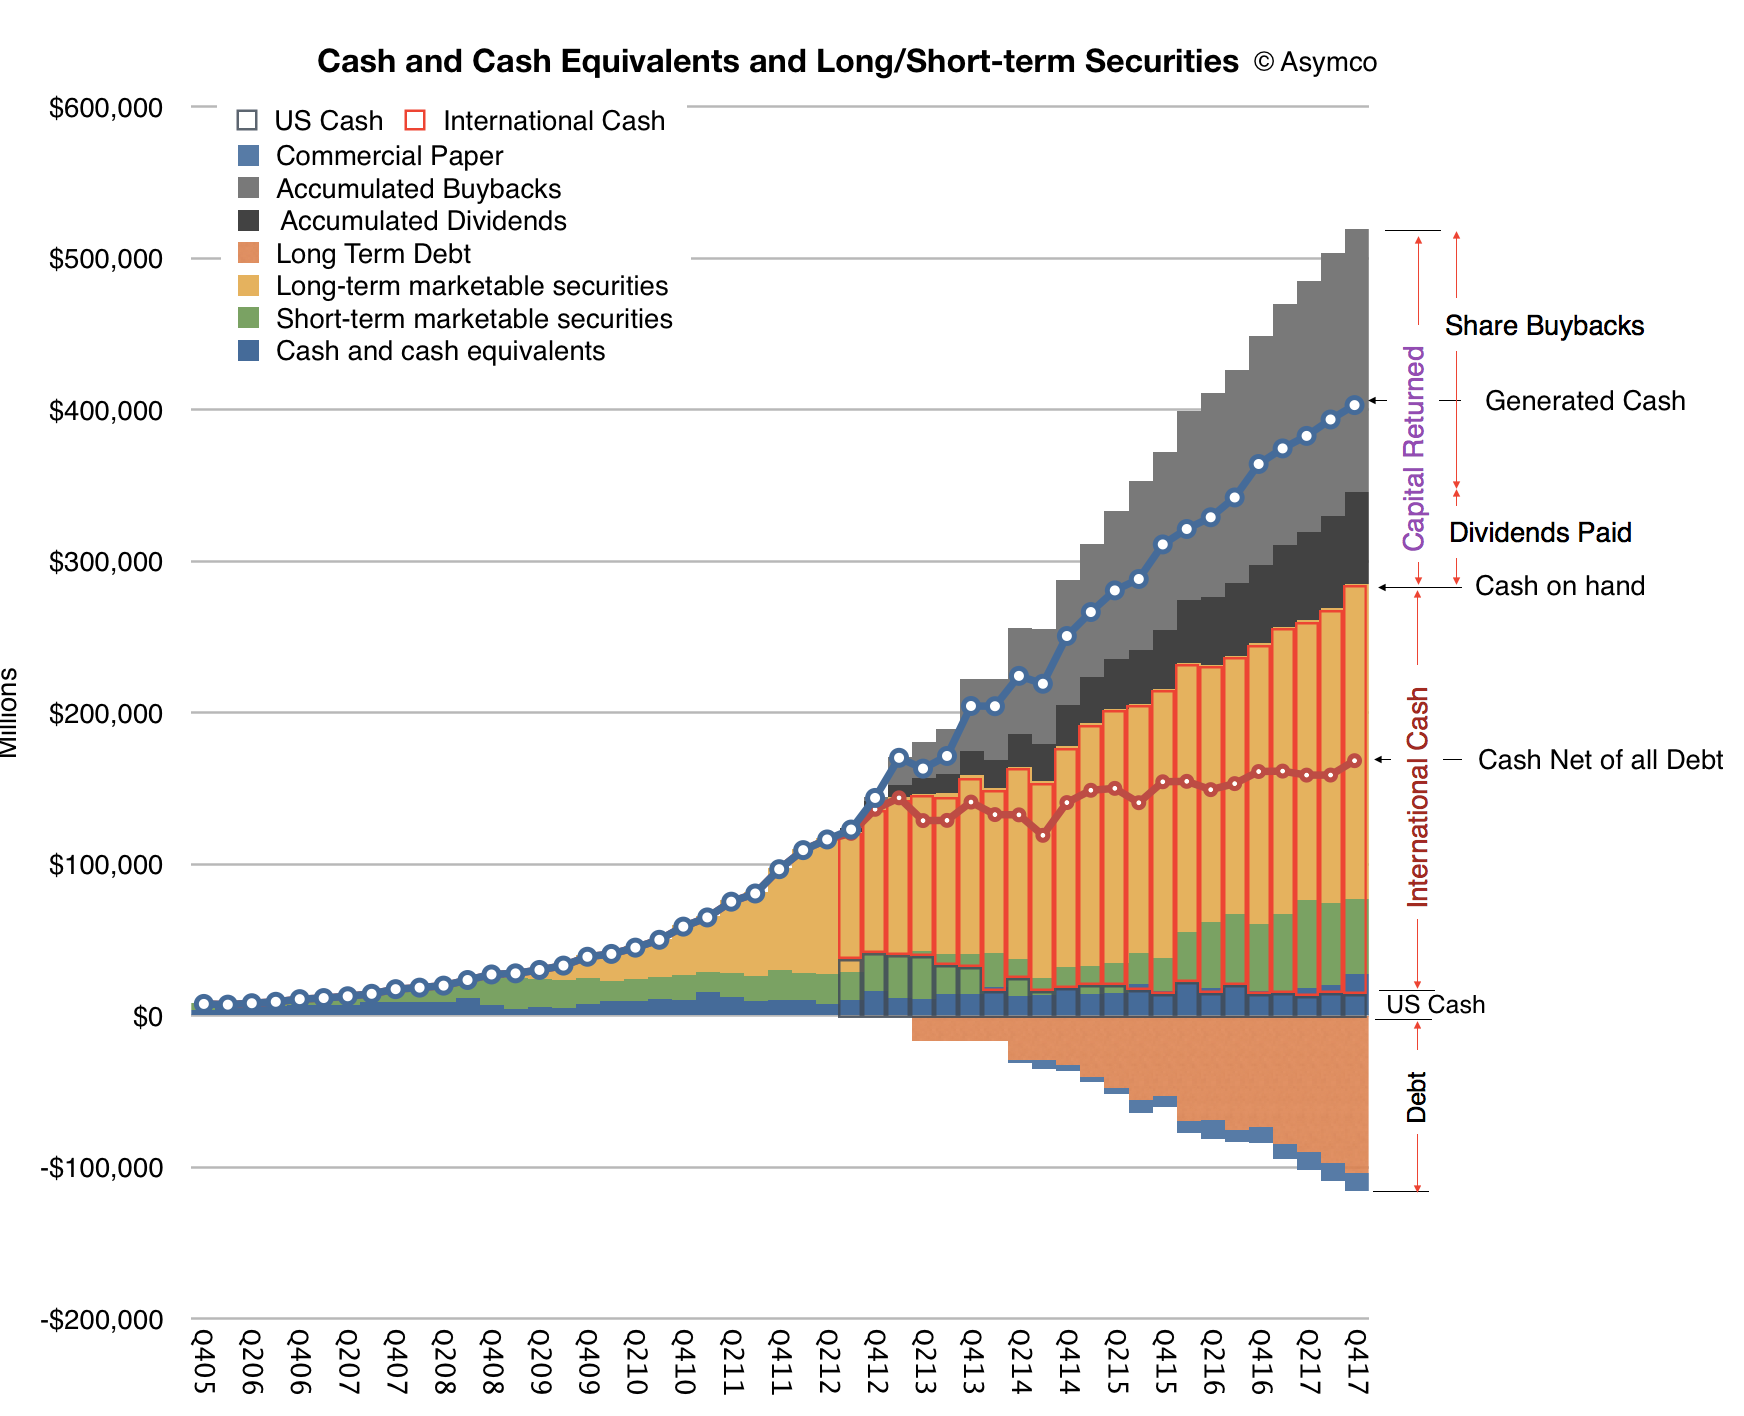
Let me now turn to our cash position. We ended the quarter with $285.1 billion in cash plus marketable securities, a sequential increase of $16.2 billion. $269 billion of this cash, or 94% of the total, was outside the United States. We issued $7 billion in debt during the quarter, bringing us to $110 billion in term-debt and $12 billion in commercial paper outstanding, for a total net cash position of $163 billion at the end of the quarter. We also returned $14.5 billion to investors during the quarter. We paid $3.3 billion in dividends and equivalents, and spent $5.1 billion on repurchases of 30.2 million Apple shares through open market transactions.
We launched a new $5 billion ASR program, resulting in initial delivery and retirement of 23.6 million shares and we retired 3.8 million shares upon the completion of our 12th ASR during the quarter. We’ve now completed over $248 billion of our $300 billion capital return program, including $176 billion in share repurchases against our announced $210 billion buyback program with $34 billion remaining under our current authorization. [An updated look at Apple's cash is shown below]
Turning to taxes. Due to the recently enacted legislation in the U.S., we estimate making a corporate income tax payment of approximately $38 billion to the U.S. government on our cumulative past foreign earnings. This amount is very similar to what we had been accruing on those earnings in our financial results through fiscal year 2017, including the $38 billion payment. We will have paid over $110 billion of corporate income tax on our total domestic and foreign earnings during the last 10 years for a cash tax rate of about 26%. [Apple has paid more tax than any company in history, and is about the make the largest single payment to the US Treasury.]
Our tax rate of 25.8% for the December quarter was close to our guidance of 25.5% as the lower U.S. statutory rate from the new legislation was effective offset by the remeasurement of deferred tax balances.
As we move ahead into the March quarter, I'd like to review our outlook, which includes the types of forward looking information that Nancy referred to at the beginning of the call; we expect revenue to be between $60 billion and $62 billion; we expect gross margin to be between 38% and 38.5%; we expect OpEx to be between $7.6 billion and $7.7 billion; we expect OI&E to be about $300 million; and we expect the tax rate to be about 15%.
Tax reform will allow us to pursue a more optimal capital structure for our company. Our current net cash position is $163 billion. And given the increased financial and operational flexibility from the access to our foreign cash, we are targeting to become approximately net cash neutral overtime. We will provide an update to our specific capital allocation plans when we report results for our second fiscal quarter, consistent with the timing of updates that we have provided in the past.
Finally, today our Board of Directors has declared a cash dividend of $0.63 per share of common stock, payable on February 15, 2018, to shareholders of record as of February 12, 2018.
I recently tweeted that any discussion related to wearable technology needs to begin with a description of the job it would be hired to do. Without a reason for building a product, you are building it simply because you can.
The reason a product deserves to exist is that it can do a job that needs doing and that few, if any others can also do it. This happens when the job is unstated and difficult to perceive. Put another way, the difficulty behind jobs-to-be-done based design is that jobs are never plainly evident. In contradiction to invention, where the problem being solved must be as clearly stated as its solution, value-creating innovation meets new and unarticulated needs. Even when created, the value is more subtly perceived, often only after prolonged use.
Which brings me to the M7. Apple chose to highlight a component (curious in itself) which it bills as a "motion coprocessor". It claims to be measuring motion data via accelerometer, compass and gyroscope and processing the information in some way. By bundling the sensors and their management into one integrated chip battery consumption is reduced and these motion monitoring functions are performed more efficiently.
But what for? The examples given during the presentation for an iPhone with M7 don't add up to a lot of benefit. An iPhone could be used as a fitness companion but it would not a very good one. Compared with, for example, a Nike FuelBand, an iPhone could not track your activity well. It's often not moving, sitting on a desk or in a purse or pocket while you are doing exercise. It's too big to take into a basketball game. It can't "observe" your activity because it's not worn during many activities and if it is worn it is in a position which does not inform much about what you're doing. Phones are too big to be used as physical activity monitors.
Hence the question of what is the M7's job to be done. As part of an iPhone, it does not seem to have one. Saving a bit of battery life is not a job, and certainly not one that needs to have billing in a media special event. The answer must be that the M7 was developed for some other, as yet unstated reason.
When the A series chips were created Apple leveraged the in-house design and cost reduction to make a wide range of products with more than 700 million examples built. Designing a chip needs a broad application domain.
Perhaps this is why Apple chose to describe the iPhone 5s as "forward-thinking". The M7 and the Touch ID are like research projects whose actual value will be realized at some future time, in probably different contexts. The M series of chips may become Apple's "low end" microprocessor as the A series climbs the trajectory into core computing tasks (read: phone, tablets, TV, laptops).
M might be the chip for the wearable segment, woven into a whole new fabric of uses and jobs to be done.