AI as Infrastructure
by Horace Dediu
Build it and they will come?
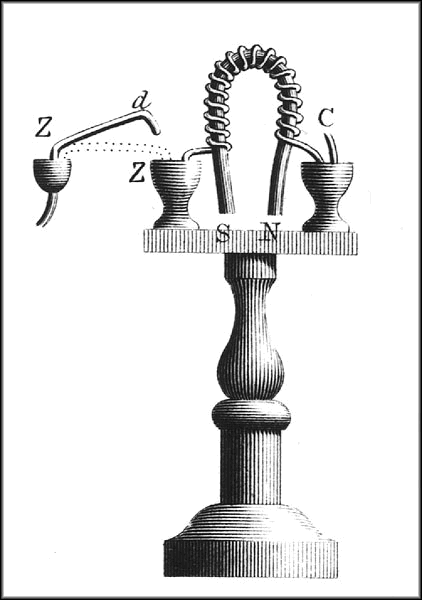
ON September 3, 1821, 37 years after James Watt invented the concept of horsepower and started charging £5/horsepower/year for the use of his steam engine, the first demonstration of the production of a mechanical force by the interaction of an electric current and a magnetic field was given by Michael Faraday in the basement of the Royal Institution in London.
1820 is, in many chronicles1, noted as beginning of the industrial revolution. It marked the end of 50 years of war2, whose conclusion unleashed pent-up demand. That demand was served by relatively free trade, guaranteed by British naval power, coupled with property rights and financial instruments which allowed inventions of the previous century to finally be harnessed for commercial gain. The steam engine is the canonical invention of the era and its implementation as a source of power for factories, shipping, rail and machinery is legend.
Not usually noted as coincidental to this period is the electric motor. Yet not long after Faraday's 1821 demonstration in London, the first DC electric motor capable of turning machinery was invented by William Sturgeon. In 1832 he built on Faraday's electromagnet by incorporating a commutator which oscillated the direction of current to ensure continuous rotation.
However, for 30 years after its invention, no practical uses could be found for the electric motor. It wasn't because there was no demand. The steam engine was in use and, as Watt's £5/horsepower/year business model demonstrated, very lucratively so. The electric motor was not in use because there was no electricity distribution system. There were no power plants, there was no grid. The motor could not stand alone.
In contrast, the equivalent distribution system for steam was the coal industry. Coal as fuel pre-existed the steam engine. Used not just for heating, it was the fuel of foundries that made iron and other metals. More energy dense than wood, coal had been mined for thousands of years. From mining concessions to barges for transport on newly dug canals to bunkering for storage, sourcing coal was a well-developed, stable and profitable industry.
Finding coal to power a steam engine in the 19th century was not a problem. Finding electricity to power your electric motor was. You could not store it, you could not ship it, you could not meter or price it. It required a completely new value network and infrastructure.
For this reason, even though the electric motor was available through most of the 19th century, the period was still known as the age of steam. The electric grid—an infrastructure—was only possible by the late 1800s as generators, capacitors and AC power were perfected. It wasn't until the early 20th century that the age of electric power began.
This illustrates perhaps better than any other example that the device precedes the infrastructure. That is, that the instrument of utility precedes the network that enables it. the boat precedes the port, the locomotive precedes the railroad, the automobile precedes the motorway, the telegraph precedes the telegraph network, the radio precedes the radio network, the phone precedes the phone network, the cell phone precedes the wireless network and the smartphone precedes the social media. The device induces the supply of its own power.
The implications are profound. It puts to the test the idea that we need to build infrastructures before we know how they will be used. The inventors of electric motors or lights relied on batteries. Investors had to imagine a grid to power more than one. The inventors of the radio had to demonstrate a single transmitter/receiver pair. Investors had to imagine broadcasting. The inventors of the car had to find fuel in pharmacies. Investors had to imagine a gas station. Steve Jobs demonstrated the iPhone without an App store. Investors had to imagine a Services business.
As AI has emerged as a technology, we are in a strange position where the interface, born as a chatbot, suggested an infrastructure that is massive in scale. The magic sauce of GenAI isn't so much the algorithm, which is quite a simple idea. It's the scale of the data and computation that permits the illusion of intelligence.
In developing the commercial idea, investors are imagining the device while investing in the infrastructure. In other words, the investors are poised to put trillions of dollars to work on what amounts to "the grid" without knowing exactly what the motor will be.
The cash flows associated with infrastructures are very different from those of devices. Devices are iterated rapidly and evolve to changing tastes and discoveries of behavior. Infrastructures are built once, maintained and perhaps re-built but only after decades. Therefore financing for infrastructures is more likely through bonds (debt) rather than shares (equity). Returns are also much more subdued as the risk for infrastructures is lower. Regulation and relations with labor are also dramatically different.
Moreover, few businesses implement both the device and the infrastructure. Indeed, the capital structures, financing, longevity and valuations of the two types of businesses are dramatically different. In cases where they are merged, regulators typically intervene to separate them.
Watching from afar, it would seem that if AI is indeed infrastructure then it will not provide a brilliant business model. Like all network business models, you either iterate constantly at great expense to deliver the next generation or you harvest the built environment to pay back the investment, hoping that a parallel network does not steal users. But the cruelty of the model is that if you have a monopoly of any kind, your margins are beaten to zero by regulation and cost of parasitic maintenance.3
We can see this with all current "grids". From electric to hydrocarbon distribution, to communications and even food distribution. The struggles to avoid commoditization, corruption and corrosion of trust and a lack of innovation are endemic.
The device however, is another story.
- I recommend "The Birth of Plenty: How the Prosperity of the Modern World Was Created" by William J. Bernstein. Bernstein argues that in order to prosper, a country must possess four main attributes: property rights, the scientific rationalism, capital markets and an effective means of transportation and communications.
- Reverse chronology: French Revolution, 1803-1815, (including the War of 1812 in US & Canada), which followed a decade of the French Revolution 1789-1799 which followed the American Revolution 1765-1783. This global war, involving most world powers, lasted 50 years.
- In a research note published April 7, Goldman Sachs strategists led by Chief Global Equity Strategist Peter Oppenheimer acknowledged the historical basis for those concerns. "The history of technology breakthroughs, from the steam engine to railways, PCs and the internet, is littered with examples of new technologies that attracted large sums of capital to build out underlying infrastructure which have led, ultimately, to low returns," he said. "The gains are then enjoyed by other companies, many of which piggyback off the original investment," he added.
4 comments
deemery ·
I happen to know a bit about 19th century US railroads. For the most part, the large systems were built up by purchasing/leasing/merging with lots of smaller railroads. The rail system was badly overbuilt by the 1880s. There were a few exceptions. The Transcontinental Railroad was built by 2 companies (who met not quite half-way...) And throughout the 19th century, railroad stocks were subject to massive manipulation, contributing to several financial panics. (See "The Scarlet Woman of Wall St" for a good discussion of one of those panics.) By the end of the 19th century, there were a few major railroad projects, particularly in the Pacific Northwest, that required lots of capital investment. The large railroads were able to manipulate rates, particularly when a community was served by only 1 railroad. And it was rate manipulation and rate rebates that allowed John Rockefeller to build up his oil monopoly. I think several other industrial monopolies were also enabled by similar mechanisms. This led to railroad regulation and 'trust busting' particularly by Teddy Roosevelt. But even after regulation, railroads made money up until the 1960s, when trucks started being the primary shipping carrier, and cars replaced trains for passenger traffic.
So I'm not quite sure how well railroad infrastructure tracks with the current path of AI infrastructure. But the one conclusion I do take: If AI infrastructure becomes dominant and exhibits monopoly behavior (particularly with private deals, and the Google-Apple deal does look like Rockefeller/Pennsylvania RR :-) ), there will be substantial regulation in response.
(I use the dividends from my AAPL stock to fund my model railroad, set in the 1890s.)
Horace Dediu ·
Thanks. Nice to hear details such as these. I have read a bit about the US and also about the UK canal investments and later communications networks globally. The overall theme I came away with is that some get wealthy but there is a gold rush mentality and many lose money chasing infrastructure as a get-rich-quick scheme. So many aspects of the business are not visible to the early visionaries and usually all the profit is carved up by unexpected expenses or regulation. I'm questioning whether this is always the case given the static nature of the business model. (As an aside: In most of the world, railroads either started out or became state owned primarily because they were both too important and too dependent of public assets. Same with post, telephone and telegraph networks and even radio and television.)
(Have you been to Hamburg and the Miniatur Wunderland? I've been there three times. https://www.miniatur-wunderland.de)
deemery ·
I've seen video of Miniatur Wonderland, and heard from others it's a great visit.
What's not clear to me, because I don't have the knowledge of other 19th century infrastructure, or of other 19th century monopolies outside of railroad and oil, is how clearly defined the pattern is. It's my sense that canals didn't provide the same physical ability to consolidate and integrate individual canals into larger scale infrastructure corporations (based mostly on US canals, I know very little about UK canals.)
It was the ability of smaller/localized groups of investors to create railroads that could be swallowed up into larger integrated systems (particularly after the adoption of the national Standard Gauge) that strikes me as different from at least LLM AI infrastructure. But once there were the large regional railroad near-monopolies, they were instrumental in facilitating other trusts/monopolies.
deemery ·
The other thing from 19th century railroading that might be relevant was the growth of car billing systems across the railroad industry. In the beginning, moving from one railroad to the other, you'd have to unload from the first railroad's cars (wagons, if you prefer) into the other railroad's cars. Eventually the industry worked out standardized billing, including tracking repair expenses, handling of empty cars, etc, so a car could move from one railroad to another to get to its destination. That kept A Lot of people employed by the railroad industry to maintain those records. An innovation along the way were 'fast freight lines' (FFL) where a group of railroads would provide expedited handling for specially marked FFL cars. FFLs were regional consortiums handling freight for shippers served by the consortium railroads. This was in addition to the express services (American Express, Adams Express) that handled small packages/ less-than-carload shipments. Together these made it feasible for small businesses and individuals to ship boxes of stuff to the next town all the way to across the country.
Could the idea of 'AI tokens' as a currency resemble these kinds of cross-railroad agreements?