Asymco Bulletin 010 - Apr 26, 2026
by Horace Dediu
Asymco Bulletin is a digest of all the work we have published for the week ending Apr 26, 2026.
Office Hours
Office Hours Live Q&A with Horace Dediu: Friday May 1, 2026 → Join Asymco One for an exclusive Office Hours Live Q&A to delve into Apple's landmark quarter and ask your questions—register now and bring a guest!
Listen to: Apple Earnings Call →
Thu, April 30, 2026 5PM ET / 2 PM PT
Join our Live Discussion →
Fri, May 1, 2026, 12PM ET / 09AM PT
Research
Succession, study of the firm vs. study of the person
A part of Horace's interview with Asahi Shimbun on the 50th Anniversary of Apple's founding. The portion here discusses management succession and occurred on April 1. Apple announced the succession of Tim Cook as CEO to John Ternus last week. This analysis of Apple leadership decisions focuses on culture and attributes of the firm rather than attributes of the persons leading it. It may prove a more reliable predictor in future leadership changes.
…, the speculation is John Ternus is the next in line. I think that's a very plausible hypothesis. And one reason, by the way, is I always maintain if you study the company from a cultural point of view, you'll realize that there are people who cannot be CEO. You may not know who it's going to be, but I can tell you who won't be. Many people over the years suggested candidates, and I would say no, never. And here are examples. Johnny Ive would never be CEO. An external hire would never be CEO. Even a head of marketing would never be CEO. Many people think that Apple is a brilliant marketing company. No, it's an engineering company. It's a huge secret out there. →
John Ternus has left big shoes to fill
Writing the story of John Ternus' tenure as Apple CEO from April 21, 2040. What changed and what didn't.
It’s been 15 years but John Ternus has finally stepped down as Apple CEO. Analysts described the transition as expected rather than disruptive, noting that investors had long anticipated Ternus’ eventual departure. Nevertheless, he leaves with many questions still unanswered about Apple’s long term strategy. Apple incoming CEO faces a defining challenge: Fixing the company’s Services dependence. It’s been a tumultuous tenure for Ternus but he is leaving with significant accomplishments: John grew Apple devices to 4.5 billion from 2.5 billion when he took over in 2026. Many have pointed out that he has been building on… →
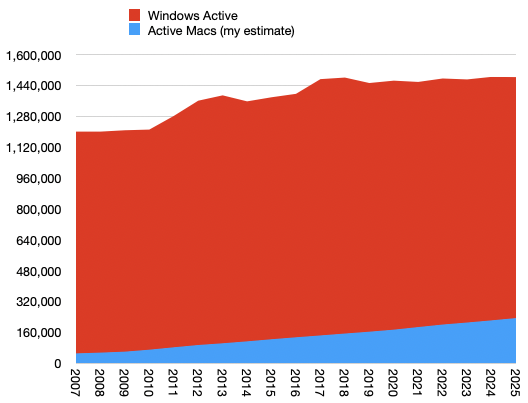
The Composition of Active Devices
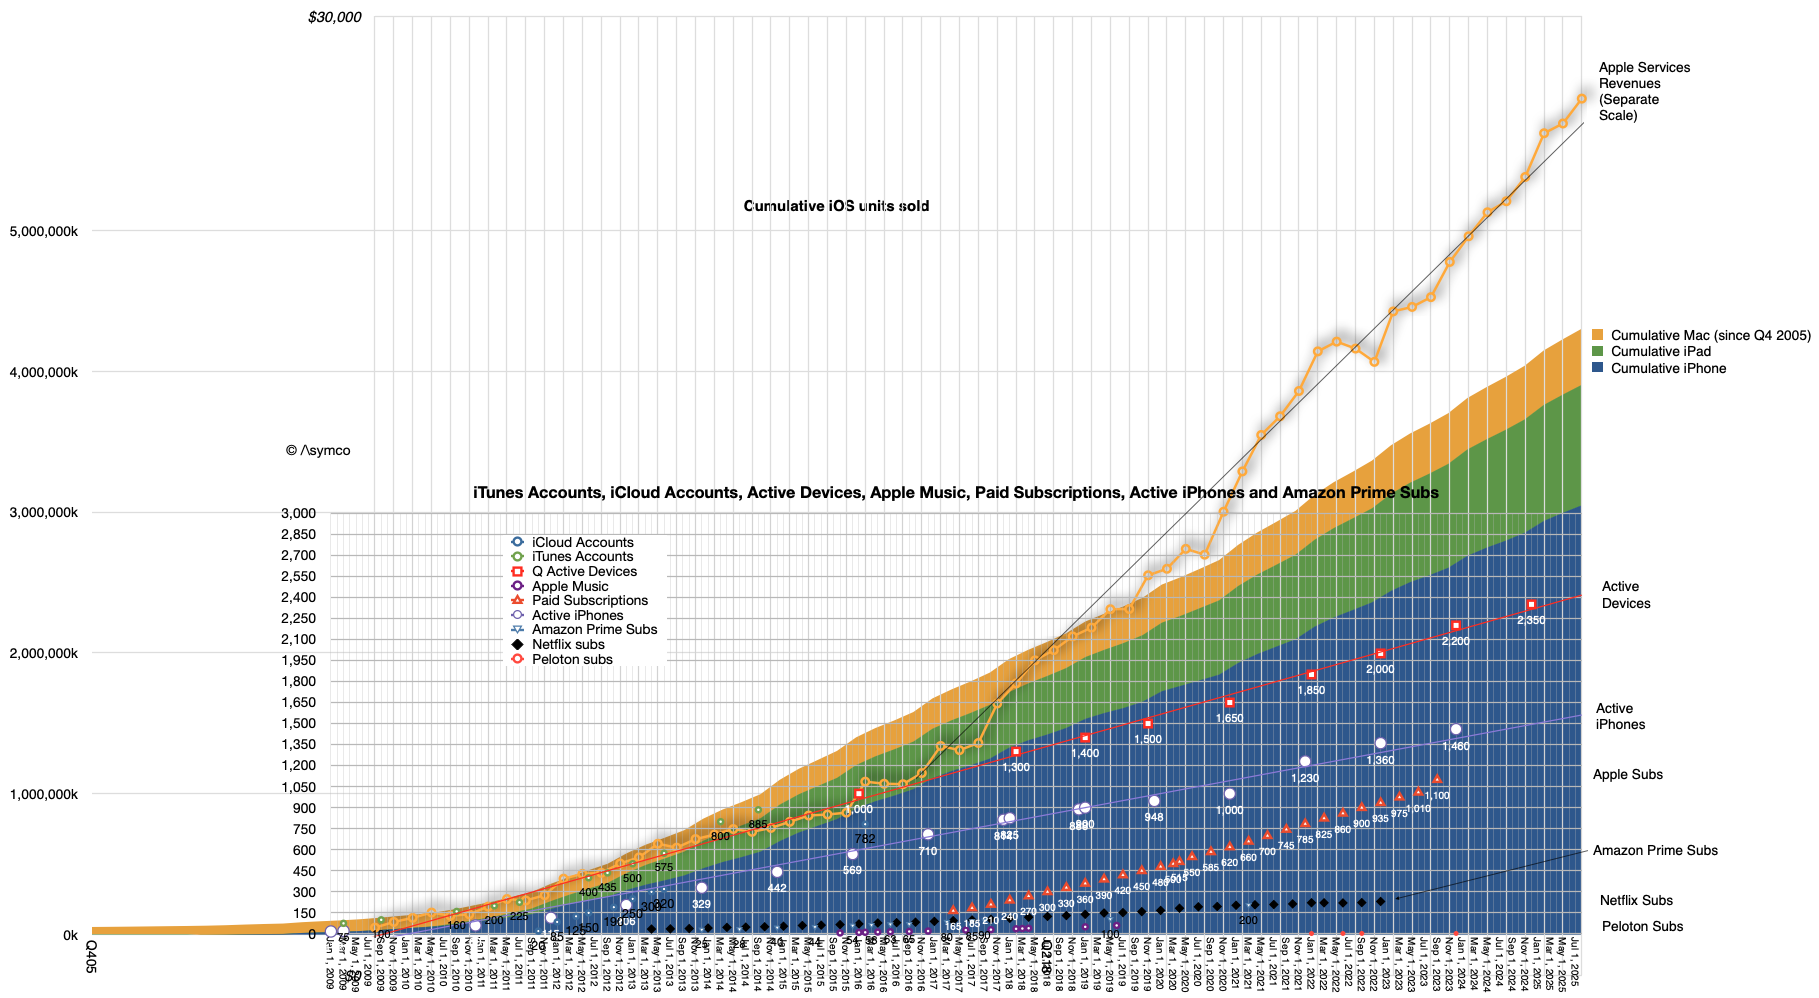
In January this year Apple reported that there were 2.5 billion active Apple devices in use. This figure has been getting updated for years and I’ve been reporting its trajectory and other measures that are correlated to it. For instance the number of Apple subscriptions, Apple Services revenues and other historical indicators such as iCloud accounts and Apple Music.
Simplifying, I published the “ACTIVE” model which makes some basic projections of this total device count and it’s shown below” One element of the analysis that has eluded me was the more precise composition of this total “devices”. →
Nota Bene
IDC: Apple Grows 33.3% in China as Market Declines 3.3% in Q1 2026
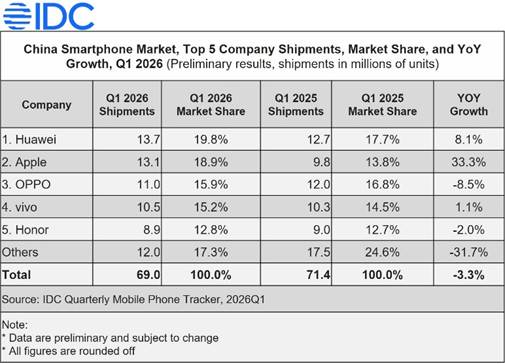
IDC: Apple Grows 33.3% in China as Market Declines 3.3% in Q1 2026 → CounterPoint reports a 4% YoY decline in China's Q1 2026 smartphone shipments, with Huawei and Apple holding nearly equal shares around 20% each, as memory shortages impact the market.
Both researchers say Apple share in China is about 19%, nearly tied with Huawei at 20%…
Some analysts are increasing their targets finally realizing that the memory supply crisis might be beneficial to Apple. This should have been noted already three months ago when Apple provided extraordinary guidance for the March quarter. →
MacBook Neo Sold Out Through April
MacBook Neo Sold Out Through April → Despite high demand and stockouts, Apple's strong brand and competitive pricing could turn challenges into opportunities for market expansion.
Microsoft’s cheapest laptop is three times more ex…
As I will argue in a further post perhaps this is one of those pivotal moments. →
Goldman forecasts fiscal second-quarter EPS of $2.00
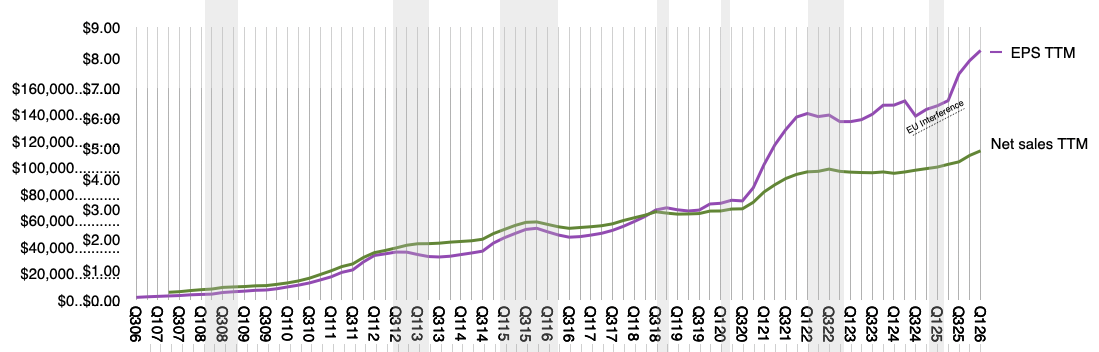
Goldman forecasts fiscal second-quarter EPS of $2.00 → Goldman Sachs remains bullish on Apple, forecasting $2.00 EPS driven by strong iPhone and Services growth, dismissing overly pessimistic sentiment as the company consistently gains 100 million new customers annually.
My target of $1.98 seems amiss.…
What is always happening, the reaction that is always ongoing, is the creation of 100 million new customers every year. Accelerating this process is not a matter of just new products or change in sentiment with AI. Much of this rate is due to overall global economic and demographic change. →
What’s the consensus on $AAPL?
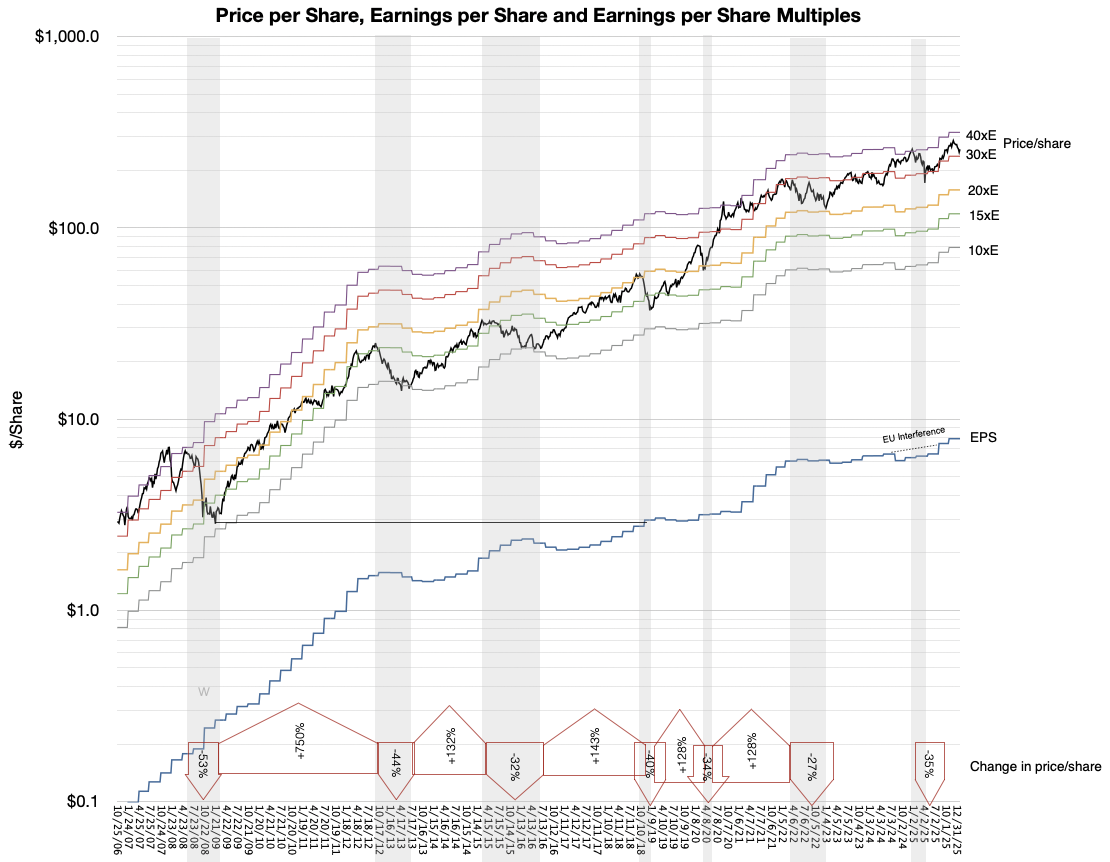
What’s the consensus on $AAPL? → Apple's strong analyst backing with a 15:1 Buy:Sell ratio and $315 target contrasts its 39% year-to-date rise, overlooking potential future growth.
The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027.
NB: The consensus is positive though share price target does not consider significant share gains and service growth acceleration into 2027. →
Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week
Apple 3.0: JP Morgan expects that Apple will beat its own guidance next week → Analyst Samik Chatterjee projects Apple's EPS to rise to $2.05 from $1.96, driven by strong iPhone and Mac demand, with a revenue boost to $112.7 billion, while I estimate a slightly lower 20.2% EPS growth, anticipating guidance will be met.
Read the original for a more detailed commentary from Chatterjee. He implies Apple will grow EPS 24%…
…My own estimate is about 20.2%. I look forward to a lively quarterly update. The primary source of growth must be the iPhone and I have that growing at 19% revenue growth. Last quarter the growth was 23%. Perhaps Chatterjee is assuming a similar growth rate into March quarter. That is not impossible but I am assuming guidance will be met rather than exceeded. →
Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.
Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We’d love to hear from you.
Comments