UBS Raises Price Target from $280 to $287 but Maintains Neutral Rating
by Horace Dediu
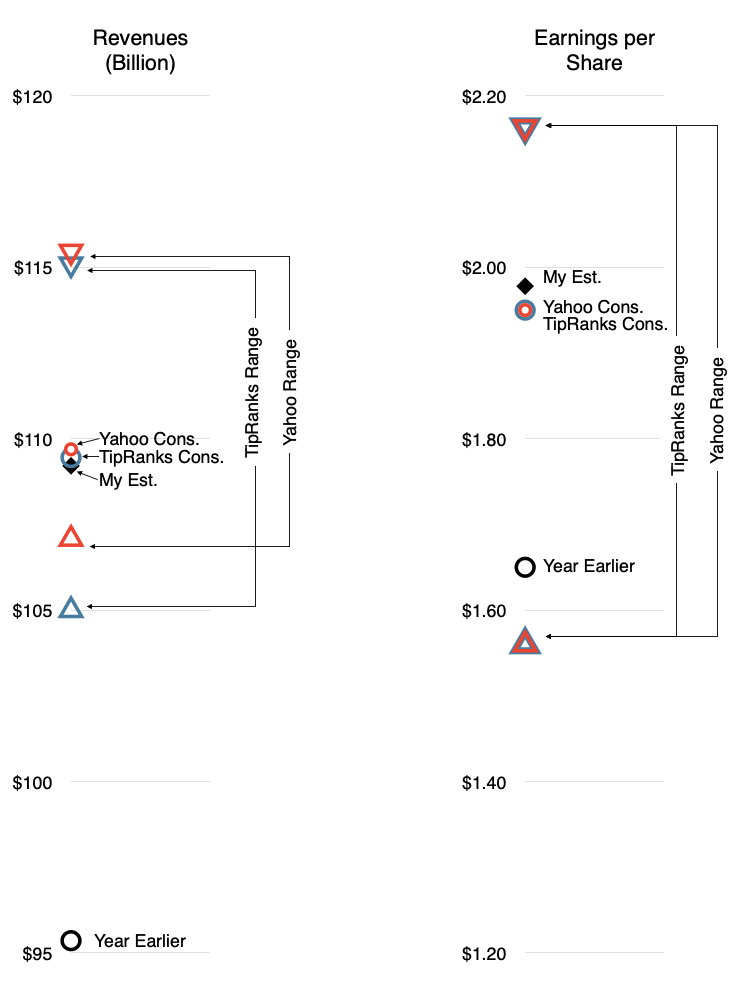
Neo and Claw incrementals
Apple is set to report fiscal second-quarter results on April 30, and investment firm UBS is expecting a “slight” upside to the consensus, based on Mac and iPhone-related strength.
“Supply chain checks and analysis of sell-through data suggest modest upside to our iPhone estimates while demand for the Neo and Mac mini suggests demand at least in-line with our Mac rev forecast,” UBS analyst David Vogt wrote in a note to clients. Vogt reiterated his Neutral rating on Apple but raised his price target to $287 from $280.
Turning to guidance, Vogt said he is expecting a “solid” offering for the June quarter and upped his earnings estimates as a result.
“Rising memory prices and Apple's ability to secure adequate supply is driving smartphone share gains for the iPhone product line at the expense of the broader Android ecosystem in our view,” Vogt explained. “In addition, solid demand for the Mac portfolio in part driven by initial success of the lower priced 'Neo' as well as demand for the 'mini' increasingly used to run AI agents like OpenClaw should drive incremental upside relative to our expectations.”
A consensus of analysts expects Apple to earn $1.94 per share on $109.73B in revenue for the fiscal second quarter.
Source: Seeking Alpha
NB: Missing the forest for the trees. Tune in to the post earnings discussion on Office Hours.
"At least in-line" is as weak as one can be in enthusiasm. “Supply chain strength and sustained demand/share gains for the iPhone 17 series should lift iPhone rev up ~20% YoY,” is more robust.
The neutral rating suggests that he does not see any strategic leverage gain as weak phone hands are shaken out.
1 comment
FredHS ·
It's funny really. David says literally; "AI agents like OpenClaw should drive incremental upside relative to our expectations."
So why not raise your expectations? Yes it is risky; The upside is unproven.
The upside for AI software, especially agentic Apps, may drive sales of Macs at all price and power levels. (In my non-professional opinion.)