Morgan Stanley forecasts fiscal second-quarter EPS of $1.74
by Horace Dediu
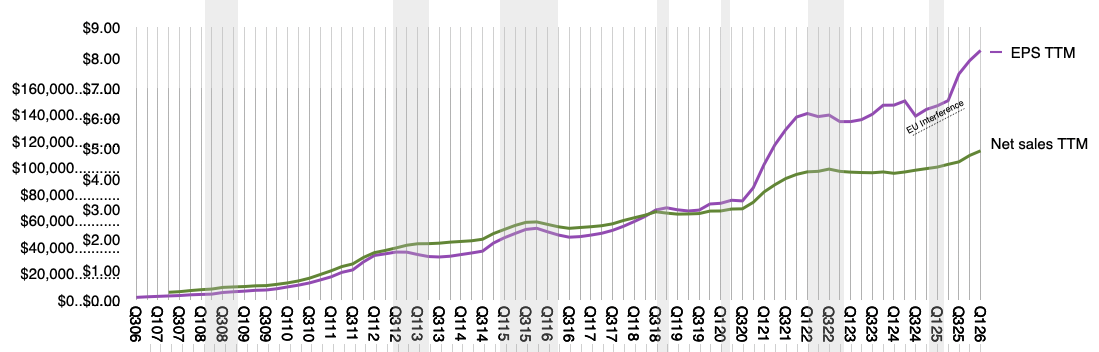
Expectations are low due to memory pricing, apparently.
Apple has multiple catalysts for strong revenue growth, so investors shouldn’t be spooked by any margin pressure from rising memory…
“Memory inflation will pressure margins, but this is well-known, and iPhone revenue upside sets up for a better than feared June quarter guide,” Woodring wrote.
He added that any announcements regarding an AI powered Siri at the company’s Worldwide Developers Conference in June, and the expected release of a foldable iPhone, would be positive tailwinds that can help push the stock higher after earnings.
Woodring, who rates the stock as Overweight with a $315 price target, also thinks Apple stands out against large tech peers as the company continues to report strong free cash flow while competitors continue to spend massive amounts of capex on building out AI infrastructure.
We expect gross margin downside to be more than offset by revenue upside in the June quarter guide, making for a better than feared earnings and a clearing event into WWDC this June, and the iPhone launch in September.While our gross margin forecast remains below Consensus given rising memory cost pressure, continued strength in iPhone, Mac, and Services revenue should more than offset this pressure and result in a June quarter implied EPS guide in-line with Street estimates (~$1.74) – a better-than-feared outcome against relatively low expectations.
At 28x next year GAAP EPS – roughly the midpoint of Apple's historical 24-34x valuation range – valuation is neither cheap nor taxing, but with our ~$10 of FY27 EPS 5% above Consensus, we see a path to $300 for Apple shares by this September, driven by modest multiple expansion and more robust positive EPS revisions.
Source: MacDailyNews
NB: Multiple catalysts, revenue upside, positive tailwinds, sentiment tailwind, favorable seasonal window, modest multiple expansion, thematically favorable backdrop, robust positive EPS revisions.
1 comment
Sacto Joe ·
Revisiting after earnings report.
So MS was way, way off, and they're one of the most Apple positive analysts. It's like they were throwing darts from a pitcher's plate....