Asymco Bulletin 011 - May 3, 2026
by Horace Dediu
Asymco Bulletin is a digest of all the work we have published for the week ending May 3, 2026.
Editor's Note: Starting next week, we will be sending Asymco Bulletin to Asymco One subscribers only. You will still receive Updates when new posts are published per your notification settings.
Office Hours
Asymco Office Hours — Apple Fiscal Second Quarter 2026 Review: The Presentation
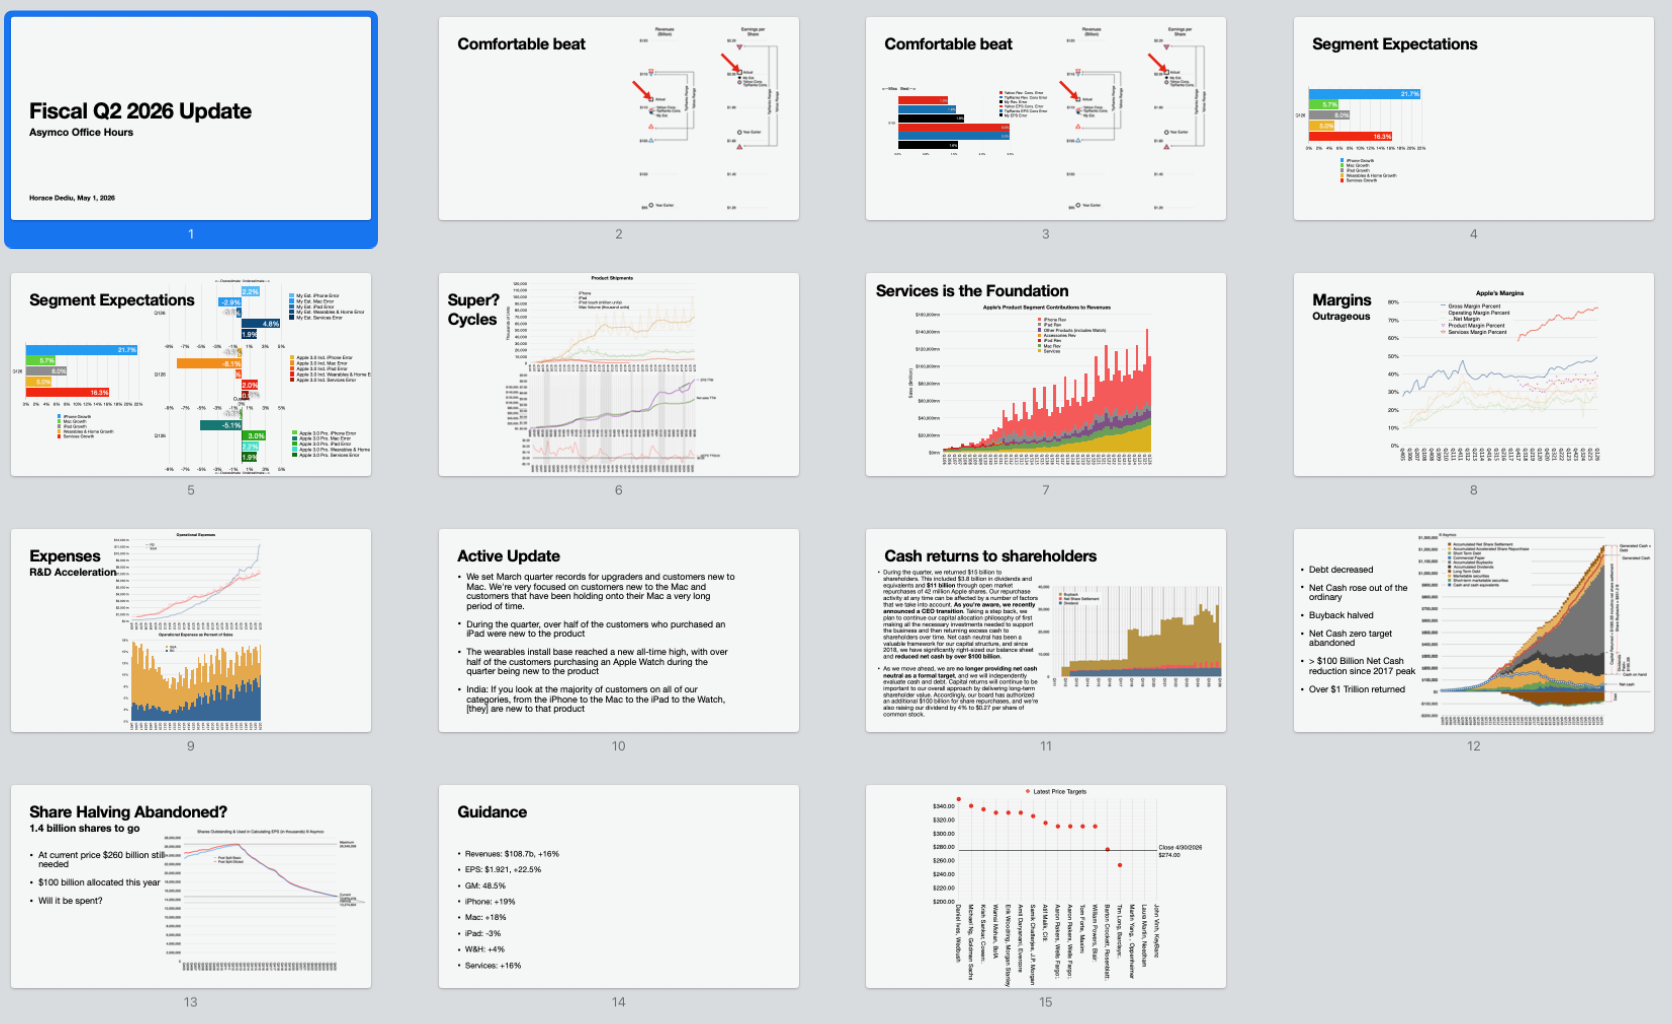
In Asymco One's May 1, 2026 Office Hours session, review of Apple's Q2 2026 earnings, segment growth: iPhone at 22%, Services at 16%, iPad at 8%, Mac at 5.7%, and wearables at 5%. Steady, foundational growth of Services, Gross margins reached nearly 50%, R&D spending surged, a shift in Apple's capital return strategy showing perhaps the hand of John Ternus. Guidance suggests 16% revenue growth, 22% EPS growth. Analyst sentiment turned positive post-earnings, with most price targets rising above $310. Apple's evolving identity as an engineering-centric company was the focus of many questions. →
Research
Expectations for the Quarter
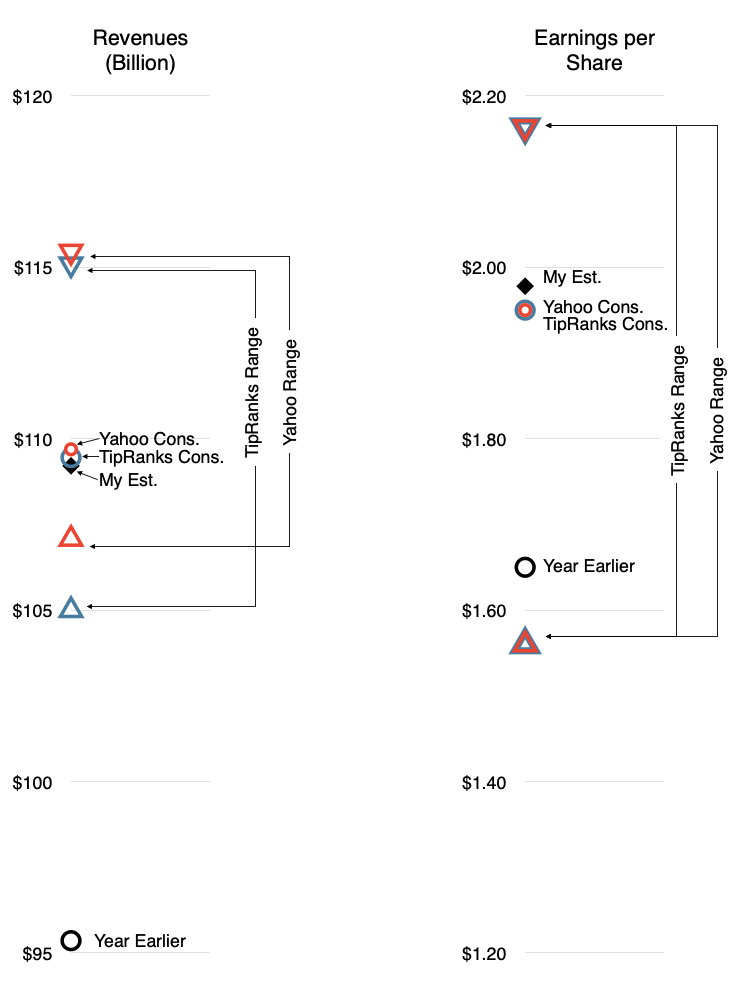
Revenue and EPS consensus, year-ago results and my expectations Yahoo Finance Yahoo Finance’s revenue estimate for Apple in Q2 stems from 31 analysts. As of April 25, the average estimate is $109.69 billion, with a low of $107.08 billion and a high of $115.37 billion. For the earnings per share estimate, 32 analysts put it at an average of $1.95. The low is $1.56 and the high is $2.16. TipRanks TipRanks also does its own analyst polling on Apple’s quarter. In its forecast as of April 19, its consensus is for a revenue of $109.45 billion, with a high of →
Nota Bene
The Economist Interview: Hints at the future direction of the company → As is often the case, a 45 minute discussion turns into two sentences. The article sadly does not provide hints at the future direction of the company. But we can…
TD Cowen: 15% revenue growth, 10% growth guidance → Apple is projected to gain market share in both smartphones and PCs, driven by strong iPhone 17 demand and the new MacBook Neo, with anticipated revenue growth of over 15% in Q3 and positive sentiment ahead of earnings.
UBS Raises Price Target from $280 to $287 but Maintains Neutral Rating → Apple's fiscal Q2 shows promise with iPhone strength and solid Mac demand, especially for the budget-friendly Neo and AI-capable Mac mini, potentially boosting earnings beyond expectations.
Morgan Stanley forecasts fiscal second-quarter EPS of $1.74 → Despite memory pricing pressures, Apple's strong iPhone sales, potential AI and foldable iPhone announcements, solid free cash flow, and favorable market conditions position it for better-than-expected earnings and a possible stock rise to $300 by September.
Is Apple borrowing Samsung’s Market Expansion Strategy? → Bernstein SocGen maintains optimism on Apple's strategic pricing and ecosystem strength, forecasting EPS growth and potential market share gains, while Samsung faces smartphone profit challenges but thrives in memory.
Separately, it’s been reported that Samsung might see its first operation loss from its phone division, resulting in Apple capturing 100% (or more) of global smartphone profits. Simultaneously, Samsung is seeing huge profit gains from memory, even overtaking Nvidia’s profitability. This is remarkable…
Apple share of the smartphone SoC market grew from 15% to 19% in Q1 → In Q1 2026, global smartphone SoC shipments fell 8%, but Apple thrived in the premium market by leveraging its efficient supply chain and passing costs to consumers, boosting its market share from 15% to 19%.
Google to sell TPU chips as Gemini shows returns → Why pour cash into Nvidia when you can craft your own cutting-edge chips like Google, and then turn that innovation into a lucrative side hustle by selling them to tech giants like Meta and Anthropic?
The Vision Products Group Expanding → Gurman's 2025 dissolution claim clashes with 2026's active Vision Products Group hiring spree. The Vision Products Group posted 14 new senior roles last week.
Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.
Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We’d love to hear from you.
Comments