Asymco Bulletin 016 - June 7, 2026
by Horace Dediu
Asymco Bulletin is a digest of all the work we have published for the week ending June 7, 2026.
Coming Up: Post-WWDC Office Hours
Office Hours Live Q&A, Tuesday June 9, 2026
Day after Apple WWDC'26 Keynote
Join us for our June 2026 Office Hours the day after WWDC'26 for a look into Apple's announcements, implications, and insights, and our live Q&A.
To sign up, and for the latest live event information, visit: asymco.com/live. →
Research
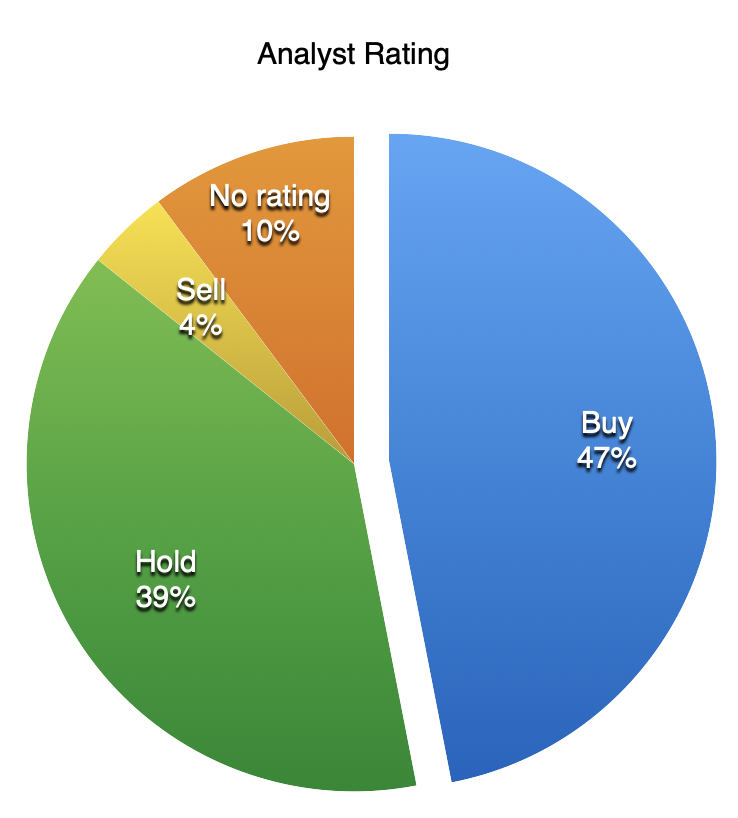
42% of Apple Analysts rate it a Hold or Sell
Apple has compounded net income at 26.6%, revenue at 21.5%, and share price at 27.7% for two decades, thus doubling every three years. Yet despite this, 21 of 49 analysts rate it Hold or Sell, with another 5 having no opinion. Extraordinary claims require extraordinary evidence yet assuming the Apple flywheel is about to grind to a halt is still a majority opinion. →
The Apple Ecosystem Approaches $2 Trillion
The App Store ecosystem facilitated $1.4 trillion in 2025. Add Apple's direct sales and the Apple Ecosystem comes to $1.8 trillion; add browsing, social, and messaging activity and the Apple Economy reaches roughly $3 trillion. Seen another way, at a $4.57 trillion market cap, Apple is valued at only 2.5 times its ecosystem and 1.5 times its economic footprint. These third-party dependencies are a measure of platform resilience and a carefully worded caution to regulators about the downside of interfering with it. →
How not to over serve; The machinery of vanity
Part 4 of the Asahi Shimbun interview turns to the spec trap. Apple maintains improvement but is selective: it ignores refresh rates beyond what the eye can see, and invests instead in features nobody asked for, like Face ID and AirPods. The phone became a machinery of vanity because the supply of cameras created demand for image editing, not the other way around. Christensen thought Apple would be disrupted by the low end. The honest answer for why it isn't is: culture, held together by extreme diligence. →
Nota Bene
Morgan Stanley reiterates $330 price target with bull-case $440 → Morgan Stanley reiterated $330 with a $440 bull case if WWDC unlocks an AI re-rating. Apple does not respond to market fads, and a multiple above 40 is almost never experienced. Disappointment after WWDC is nearly guaranteed because it has always been a software and tools show. →
Citi reiterated a Buy rating and a $315 price target → Citi reiterated its Buy and $315 target ahead of WWDC, expecting a revamped Siri to make Apple an edge AI winner. Edge AI is inevitable, but it was also inevitable two years ago. The target is already priced in, making the AI story a non-starter. →
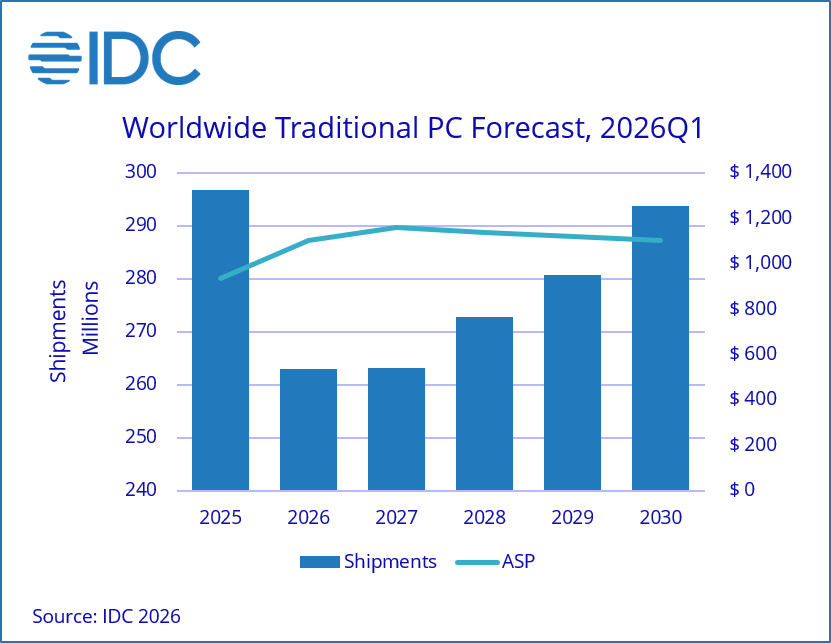
Q4 PC shipments are expected to fall 20% year-over-year, 11.3% for the full year → IDC now sees PC shipments falling 11.3% for 2026 and 20% in Q4, with no recovery in volumes until after 2030. The MacBook Neo is the only thing keeping the broader notebook forecast from being worse. This is a multi-year opportunity for Apple that may reset PC market share dynamics permanently. →
Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.
Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We'd love to hear from you.
Comments