Rothschild & Co. Redburn upgrades Apple to ‘Buy’ from ‘Neutral’
by Horace Dediu
Raised the price target to $400 from $260
Schulze-Melander expects Apple to launch the iPhone Ultra in September, giving it a new product category to tap while potentially lifting the average selling price of its broader iPhone lineup.
The analyst estimates the device could cost $2,199, or about an 83% premium to the iPhone 17 Pro Max, meaning even relatively modest volumes could have a meaningful impact on Apple's revenue mix.
The firm expects the foldable iPhone to increase Apple's average selling price for the iPhone lineup by 11% by June 2027.
Apple could [also] have [a] revamped artificial intelligence strategy.
Source: Stocktwits
NB: This upgrade was from $260 to $400 which seems significant. This might be because the last target that I could find was in September 2025, so almost a year ago. Not sure if anything of note occurred since. But this is not the only change in analyst targets. There have been 8 other changes in ratings and targets in the two weeks since earnings. Four price target cuts, four downgrades, four price target raises and one upgrade…
- Aug. 11 Loop Capital Cuts Target to $340 From $350, Keeps Buy Rating
- Aug. 11 Daiwa Securities Raises Price Target to $335 From $325, Keeps Outperform
- Aug. 10 Jefferies Downgrades to Underperform From Hold, Cuts PT to $263.66 From $285.56
- Aug. 6 Citic Securities Raises Raises PT to $349 From $300, Keeps Add Rating
- Aug. 4 China Renaissance Downgrades Apple to Hold From Buy, Cuts Price Target to $280 From $329
- Aug. 4 CICC Raises Price Target on Apple to $340 From $310, Keeps Outperform Rating
- Aug. 3 DZ Bank Downgrades From a Buy to Neutral rating
- Aug. 3 Phillip Securities Downgrades Apple to Reduce From Neutral, Cuts PT to $290
The average price target is $329. There are 28 Buy, 13 Hold and 5 Sell ratings. 15 Analysts have not updated ratings in over a year.
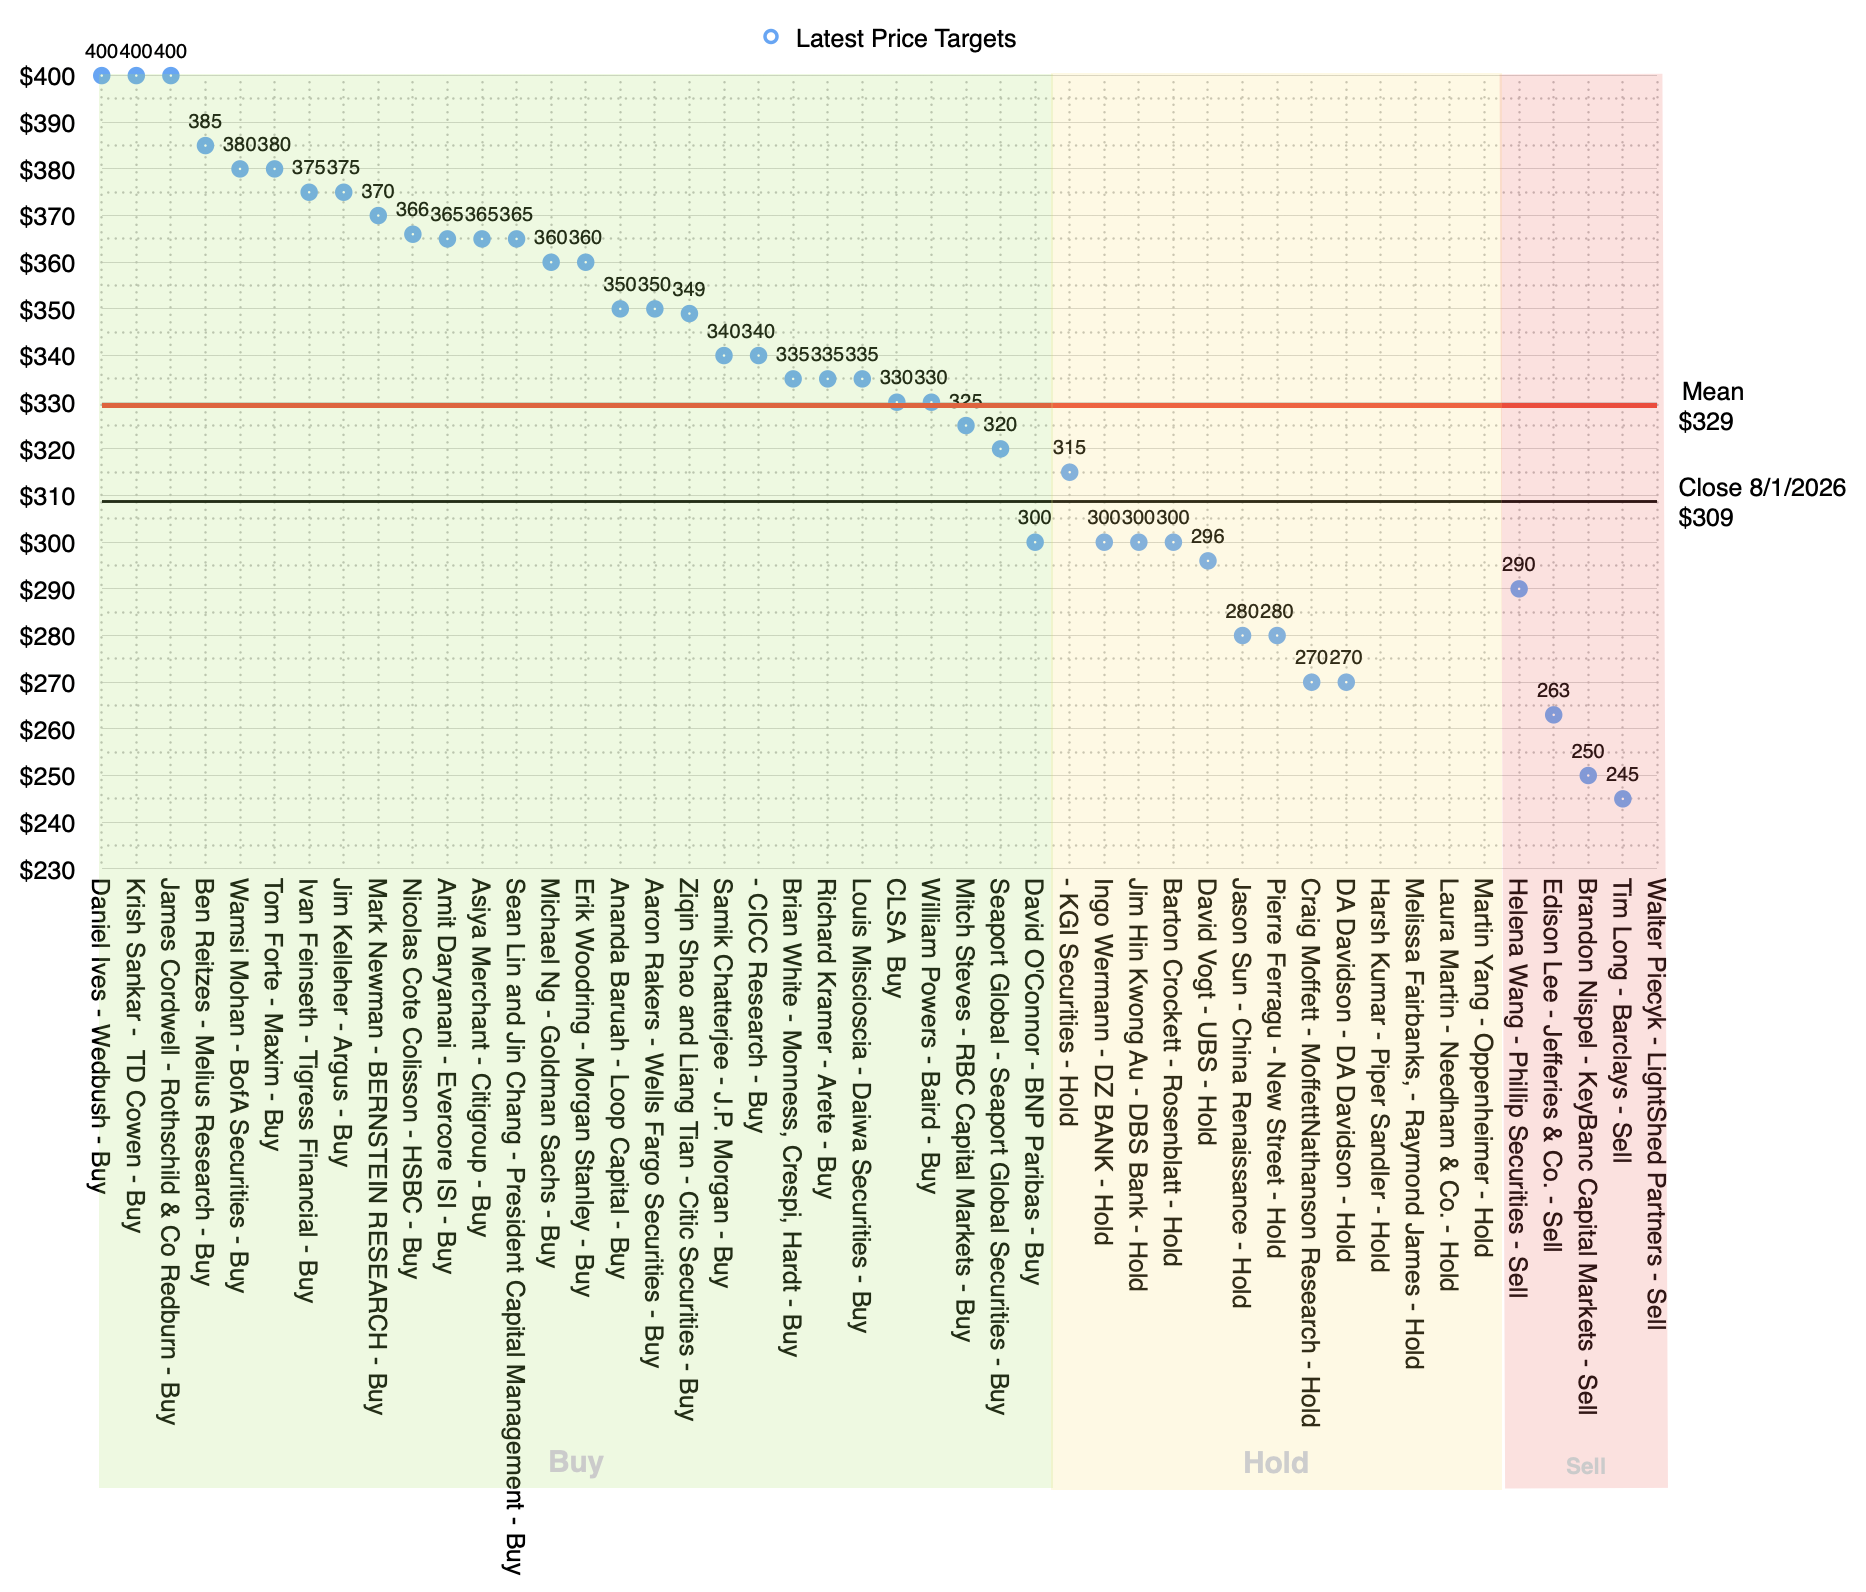
Much was made of the Jefferies downgrade which seems to have hinged on a rumor of the cancellation of the iPhone 20(!) The rumor was debunked by three sources within hours but it did not deter coverage of the downgrade and its reason for days after.
The trend apparent is that analysts who previously insisted on counting iPhones have turned to predicting iPhone pricing, thus swinging between "too high" or "too low" reasons for Apple's imminent market failure.
The AI (win/fail, take your pick) drumbeat still attracts attention but overall it seems less loud.
1 comment
Sacto Joe ·
Honestly, AAPL was effectively sandbagged during post-pre-trading the night of the earnings report. A tiny number of shares traded creates enormous leverage in that market, and that lever was definitely pulled! Everything else since has been a pissing contest between those who want to own the stock and those who want to keep it depressed for the short term.
Bottom line: It's ALL about the short term "traders" versus the long term "investors".
But for this long term investor, I'm fine with the "volatility", even if it is manipulated by FUDD stories and aided and abetted by the options market. Why? Because (1) we only sell these days, both being octogenarians, and we can time our sales by having a large enough cushion of cash, built up over the years since we first bought AAPL; and (2) because these are opportunities for Apple to buy back AAPL, which is essentially Apple investing in itself on our behalf so we can just relax on the Good Ship Apple and enjoy the cruise.
BTW. Apple 3.0 has a surprising number of folks just like us.... Ask PED about the "survey" he did a year or so ago....
Sacto Joe