Asymco

Asymmetric Intelligence

Horace Dediu

  1. iPhone only Smartphone to Grow in China this January

    Nota Bene

    Market that was down 23% overall

    Every major Chinese mobile maker, from Huawei Technologies to Xiaomi, saw major declines in a market that was down 23% overall, largely due to reduced subsidies and a shift in the timing of the Lunar New Year, Bloomberg News reported, citing Counterpoint researchers.

    The iPhone 17 lineup, however, helped Apple to 8% growth, raising its share of the market to roughly a fifth, sharing the lead with Huawei. Cupertino, California-based Apple has seen its flagship product stage a major comeback since the September introduction of new models.

    “Apple stood out as the only major brand to achieve year-on-year growth, and its market share reached the highest January level in the past five years,” according to the researchers. “The iPhone 17 base version now qualifies for government subsidies, boosting its value-for-money appeal and driving a 9% month-on-month sales increase.” 

    Source: Seeking Alpha via Apple News

    NB: Still wondering if it's the new orange color that's the reason for the iPhone's success in China?

  2. BofA Analysis Suggests Low Impact on Apple of Higher Component Prices

    Nota Bene

    Apple is best placed to withstand memory inflation

    Analyst Wamsi Mohan told clients in a note that the bank applied its existing elasticity framework to assess how Apple, Dell and HP can offset sharply higher component prices expected in 2026.

    Mohan wrote that NAND prices are projected to rise “+140% in C26 and DRAM +14% in C26,” forcing PC OEMs to rely on a mix of “price increases, reconfigurations, and pressure on supply chain to offset headwinds.”

    BofA divided each OEM’s units into demand-elasticity cohorts and found that Apple is best placed to withstand memory inflation because its “units skew the least elastic with ~85% in the Inelastic cohort.”

    Based on BofA’s modelling, Apple faces a potential earnings impact of just $0.12, compared with $3.77 for Dell and $1.55 for HPQ.

    Mohan said the bank does not expect the full theoretical impact to materialize because memory pricing in long-term contracts is likely to be lower than current projections.

    “The implied downside to EPS is modest for AAPL,” he wrote, adding that BofA maintains its Buy rating on optionality from new products, new markets and “eventual success with AI at the edge.”

    BofA believes Apple’s operating margins could still see over 600bps of year-over-year deleverage, though they remain positive due to the company’s stronger profitability. Dell and HP would need to cut operating expenses by 5–20% and reduce specifications to remain profitable.

    The bank now expects 2026 PC units to fall 8% year over year, compared with a prior view of flat growth..

    Source: Investing.com

    NB: "I've seen gluts not followed by shortages, but I've never seen a shortage not followed by a glut." Nassim Taleb.

  3. Does Apple's AI Opportunity Outweigh Component Cost Inflation?

    Nota Bene

    Apple's cost pressures are real, but the growth story is bigger

    Apple’s latest Wall Street price targets

    Wedbush:$350 (outperform).
    Goldman Sachs:$330 (buy).
    JPMorgan:$325 (overweight).
    BofA Securities:$325 (buy).
    Morgan Stanley:$315 (overweight).
    Sources: Yahoo Finance, Investing.com

    Despite memory cost inflation being a big deal, it still doesn't fundamentally impact Apple’s tremendous earnings power, Bernstein’s Mark Newman shared in a CNBC interview.

    That’s not to say he doesn’t expect iPhone production costs to rise, though.

    Heightened component costs could push iPhone prices up by as much as 15%, Newman added, while bumping the overall average selling price by nearly 12% as some customers trade down to cheaper models.

    That increase is substantial, and it comes down to a staggering 237% surge in mobile DRAM contract prices since Q2 2025, along with a 70% jump in NAND.

    Despite the pressures, Newman feels that Apple separates itself from the pack through its superb execution.

    He says Apple is “managing better than competition,” led by unmatched scale advantages, supplier leverage, product mix, and durable pricing power.

    To his point, Apple has evolved into a powerful platform company with a walled-garden ecosystem that locks users in.

    That matters a ton when costs spike.

    That’s why even with the memory pressures in play, Bernstein’s modeling points to iPhone gross margins dropping by nearly 1.5 percentage points by Q4 2027.

    Though that’s meaningful, Newman believes the EPS impact will be substantially offset by higher-margin services revenue, mix shift, and aggressive cost management.

    Apple’s AI ambitions outweigh rising costs

    Newman’s bullish take on Apple centers around AI.

    Instead of AI technology showing up just as a chatbot, Newman says Apple is deploying it as a system-level layer, making its ecosystem stickier.

    What makes this possible is a hybrid design that handles as many requests on the device and reroutes the heavier ones (advanced reasoning) through Private Cloud Compute using Google’s Gemini.

    That robust setup ensures Apple’s privacy positioning remains firmly intact, while delivering cutting-edge responses and features.

    Unlike many of its peers, Apple isn’t in the race to win AI benchmarks or translate those gains into tangible financial gains. It just needs those features to change behavior and pave the way for healthier services revenue.

    In fact, some of the earlier modeling supports that logic.

    Morgan Stanley’s April 2025 survey, as reported by Investing.com, was an early “tell” that Apple’s AI pitch would likely move the needle.

    At the time, 51% of iPhone owners said they were “extremely likely” to upgrade in the next 12 months. More importantly, those respondents, compared with those in the previous fall, showed a 12% higher willingness to pay $9.11 per month for Apple Intelligence.

    For perspective, the significant Siri 2.0 (the next phase of Apple Intelligence) is reportedly set to launch in spring 2026, according to Mac Rumors.

    Ironically, Apple stock was initially blasted for lagging in the AI realm. However, as we’ve gotten deeper into the cycle, Newman argues that investors have actually felt a lot “more comfortable” amid the AI wars.
    Source: TheStreet

    NB: A 237% surge in mobile DRAM contract prices since Q2 2025 is spot pricing. Apple does not buy on the current market but what is effectively on a futures market. It would behoove the reader to calculate the quantity of orders for e.g. SoC and Memory Apple places vs. hyperscalers. If "51% of iPhone owners said they were “extremely likely” to upgrade in the next 12 months" that's 850 million people worldwide.

  4. The Apple Car lives through the Ferrari Luce (It most certainly does not)

    Nota Bene

    Macworld If you’ve ever wondered what could’ve been with the Apple Car, you’ll now be able to satisfy your curiosity a bit. Ferrari on Monday announced the Luce, the company’s first electric vehicle. And the main designer behind the car’s cabin and controls is LoveFrom, the company headed by A...

    Read the original article →

    NB: This is outrageously wrong. The Luce is a driver's car. The Apple car was always designed not to be driven and the reason it was not launched is because a self-driving car is still a fantasy. The Luce interface is extremely engaging rather than disengaging. The Apple car interface was to be your iPhone.

  5. It’s over. The iPad won

    Nota Bene

    In 2010, one firm said the iPad “failed to convince buyers” after its unveiling because the number of people who said they were uninterested in the iPad nearly doubled. Small footnote to that survey that somehow didn’t make the headline: the number of people who said they _would_ like to buy an iPad tripled.

    The Macalope’s favorite pundit gag of 2011 was lauding the Motorola Xoom because it had 4G connectivity and the iPad 2 did not. Case closed! Advantage: Xoom! Oh, well, except, ha-ha, small note, just a tiny thing, really: the Xoom didn’t actually have it, either. It was simply promised that, at some point in the future, you’d be able to mail your Xoom in to add 4G to it.

    Read the original article →

    NB: Good times. The Macalope is on form. Remarkable how little humor there is in the tech press. Decades go by and nobody else thinks of it.

  6. How Many Songs Does Apple Music Have?

    Nota Bene

    The current Apple Music catalog features over 100 million songs as of late 2025. This massive library places it at the very top of the streaming industry, tied with other major giants like Spotify and Amazon Music. Since its launch in 2015, Apple Music has aggressively expanded its library, growi...

    Read the original article →

    NB: A useful categorization of the catalog with some insight into positioning relative to alternatives.

  7. What is Apple's Investment Narrative?

    Nota Bene

    Some say it's "Cosmic Orange".

    To own Apple today, you need to believe its ecosystem can keep deepening even as growth expectations are already high and the stock trades on a premium multiple. The latest quarter’s US$143.76 billion in revenue and US$42.10 billion in net income, powered by iPhone 17 demand and a rebound in China, reinforce that story, while expanding AI features and services aim to make each device more valuable over time. The upcoming low cost MacBook fits neatly into this, extending macOS and Apple Intelligence to more price sensitive users without changing the core near term catalysts, which still sit around iPhone 17 uptake, AI rollouts and services momentum. Key risks feel more about execution and sentiment: memory cost pressures, high expectations baked into the price and any cooling of AI enthusiasm..

    Source: Simply Wall St. via Finance.yahoo.

    NB: Another money quote: "An interesting angle is how design-led appeal in China, such as the viral “Cosmic Orange” iPhone 17, combined with new AI features across devices is reinforcing Apple’s ecosystem pull for both consumers and developers."

    I tried but failed to connect how Cosmic orange is reinforcing Apple's ecosystem pull for consumers and especially developers.

  8. Jony Ive Advises Ferrari on the Luce

    Nota Bene

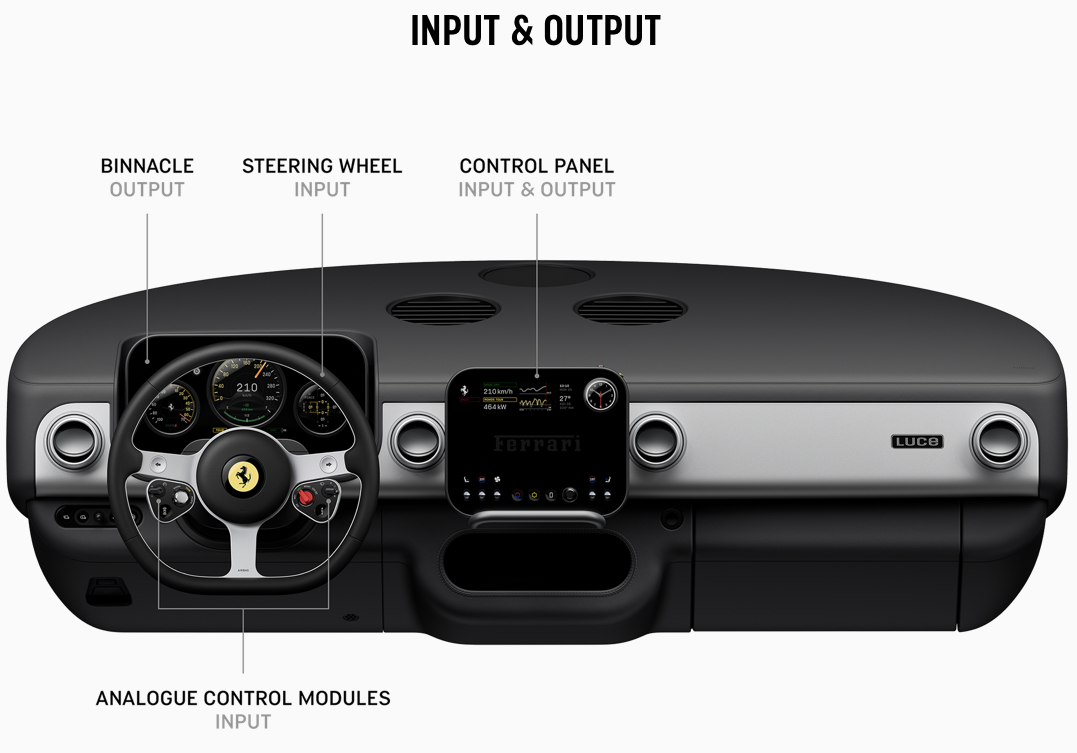
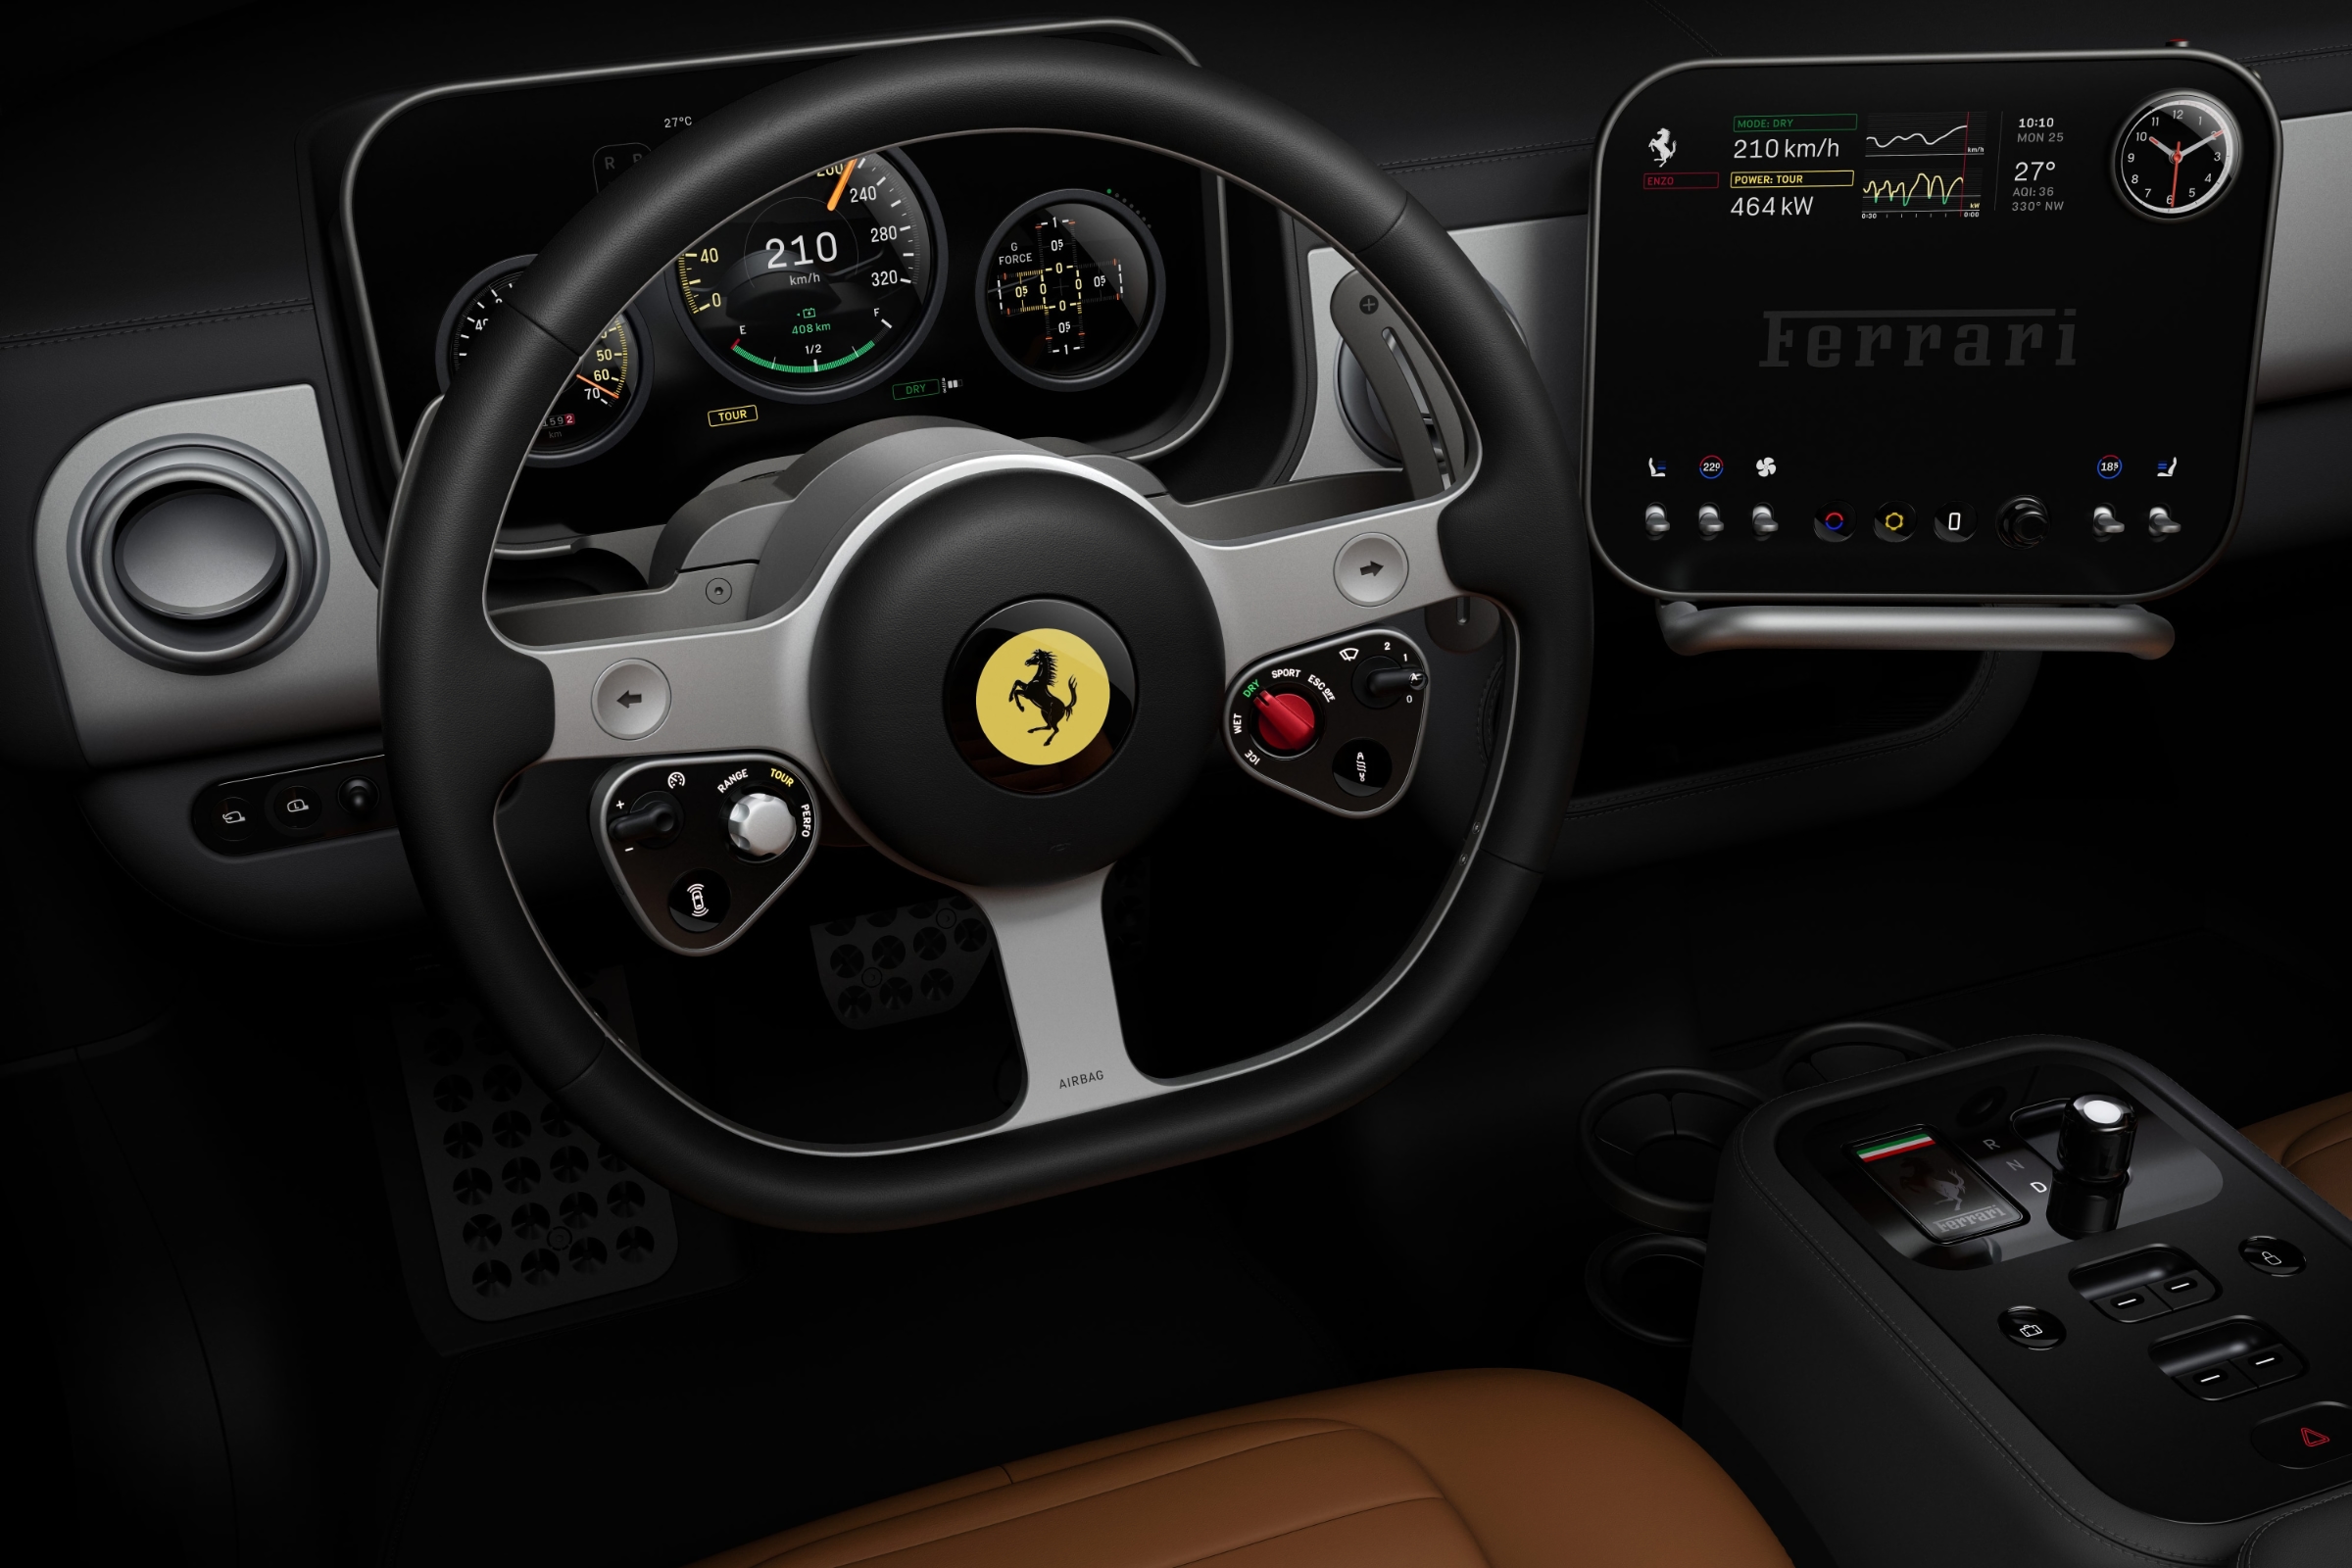
    The design language suggests a computing interface.

    The Ferrari Luce's interface is designed with clear organisational principles. Controls and displays are grouped functionally, with the most essential commands and feedback directly in front of the driver.

    Source: Ferrari. A rather content-free video shows Sir Jony.

    Update: More details here: Top Gear

    NB: Unlike most consultants, Jony seems to have had some influence. It's also refreshing that a car is now being designed with a minimum of touchscreens. My 1983 Saab 99 starts to look good.

  9. Goldman Reiterates Buy and Bernstein Reiterates Outperform

    Nota Bene

    $330 and $325 Price targets, respectively.

    Investment bank Goldman Sachs discussed Apple Inc. in January. It reiterated a Buy rating and a $330 share price target on the firm. The bank discussed the firm’s App Store performance in its coverage. It outlined that the App Store spending trends were improving as spending grew by 7% in January to accelerate by one percentage point over December’s 6% growth. Goldman added that the App Store growth should contribute meaningfully to Apple Inc. Services business.

    Along with Goldman Sachs, Bernstein also praised the firm. It reiterated an Outperform rating and a $325 share price target. Bernstein cited Apple Inc.’s record iPhone revenue and optimistic growth guidance to point out that the firm was correctly navigating the turmoil in the memory industry.

    Source: Insider Monkey.

    NB: I remember when both of these banks had negative ratings on Apple.