Apple is doomed. So are you. As mortals we are used to the idea of death. We do not dwell on it even though it's inevitable. We do know that we'll die but what we don't know is when we'll die. That certainty/uncertainty makes us, more or less, do everything that we do. And so we carry on. But companies die too. And when they die is also a mystery but it's not at all clear that their inevitable demise determines what they do. If you think you're immortal you may live dangerously. Perhaps as a result they live shorter lives than we do.
Life expectancy for humans has been rising but for companies it has been declining. Even more curiously, the richer you are the more likely you are to live longer but the wealthier a company, the more likely it is to keel over at any time. The longest lived small businesses live over 1000 years but the longest-lived large business is probably the East India Company that made it to the ripe age of 274. But that was before 1800.
In the modern, industrial era there are very few corporations that survived over a century and the Fortune 500 shows a turnover in inhabitants that resembles that of a plague-infested medieval inner-city. In contrast to their conservative, geriatric organic owners, synthetic companies are more likely to behave like live-fast, die-young punk rockers.
So it's no surprise that Apple, at age 40, is seen as being well past its sell-by date. And yet it seems to be saying, somewhat faintly, "I'm not dead yet". By generating more cash than can be comprehended by human observers and by controlling assets that are well beyond the means of many countries, they (it?) is confusing us with its persistence.
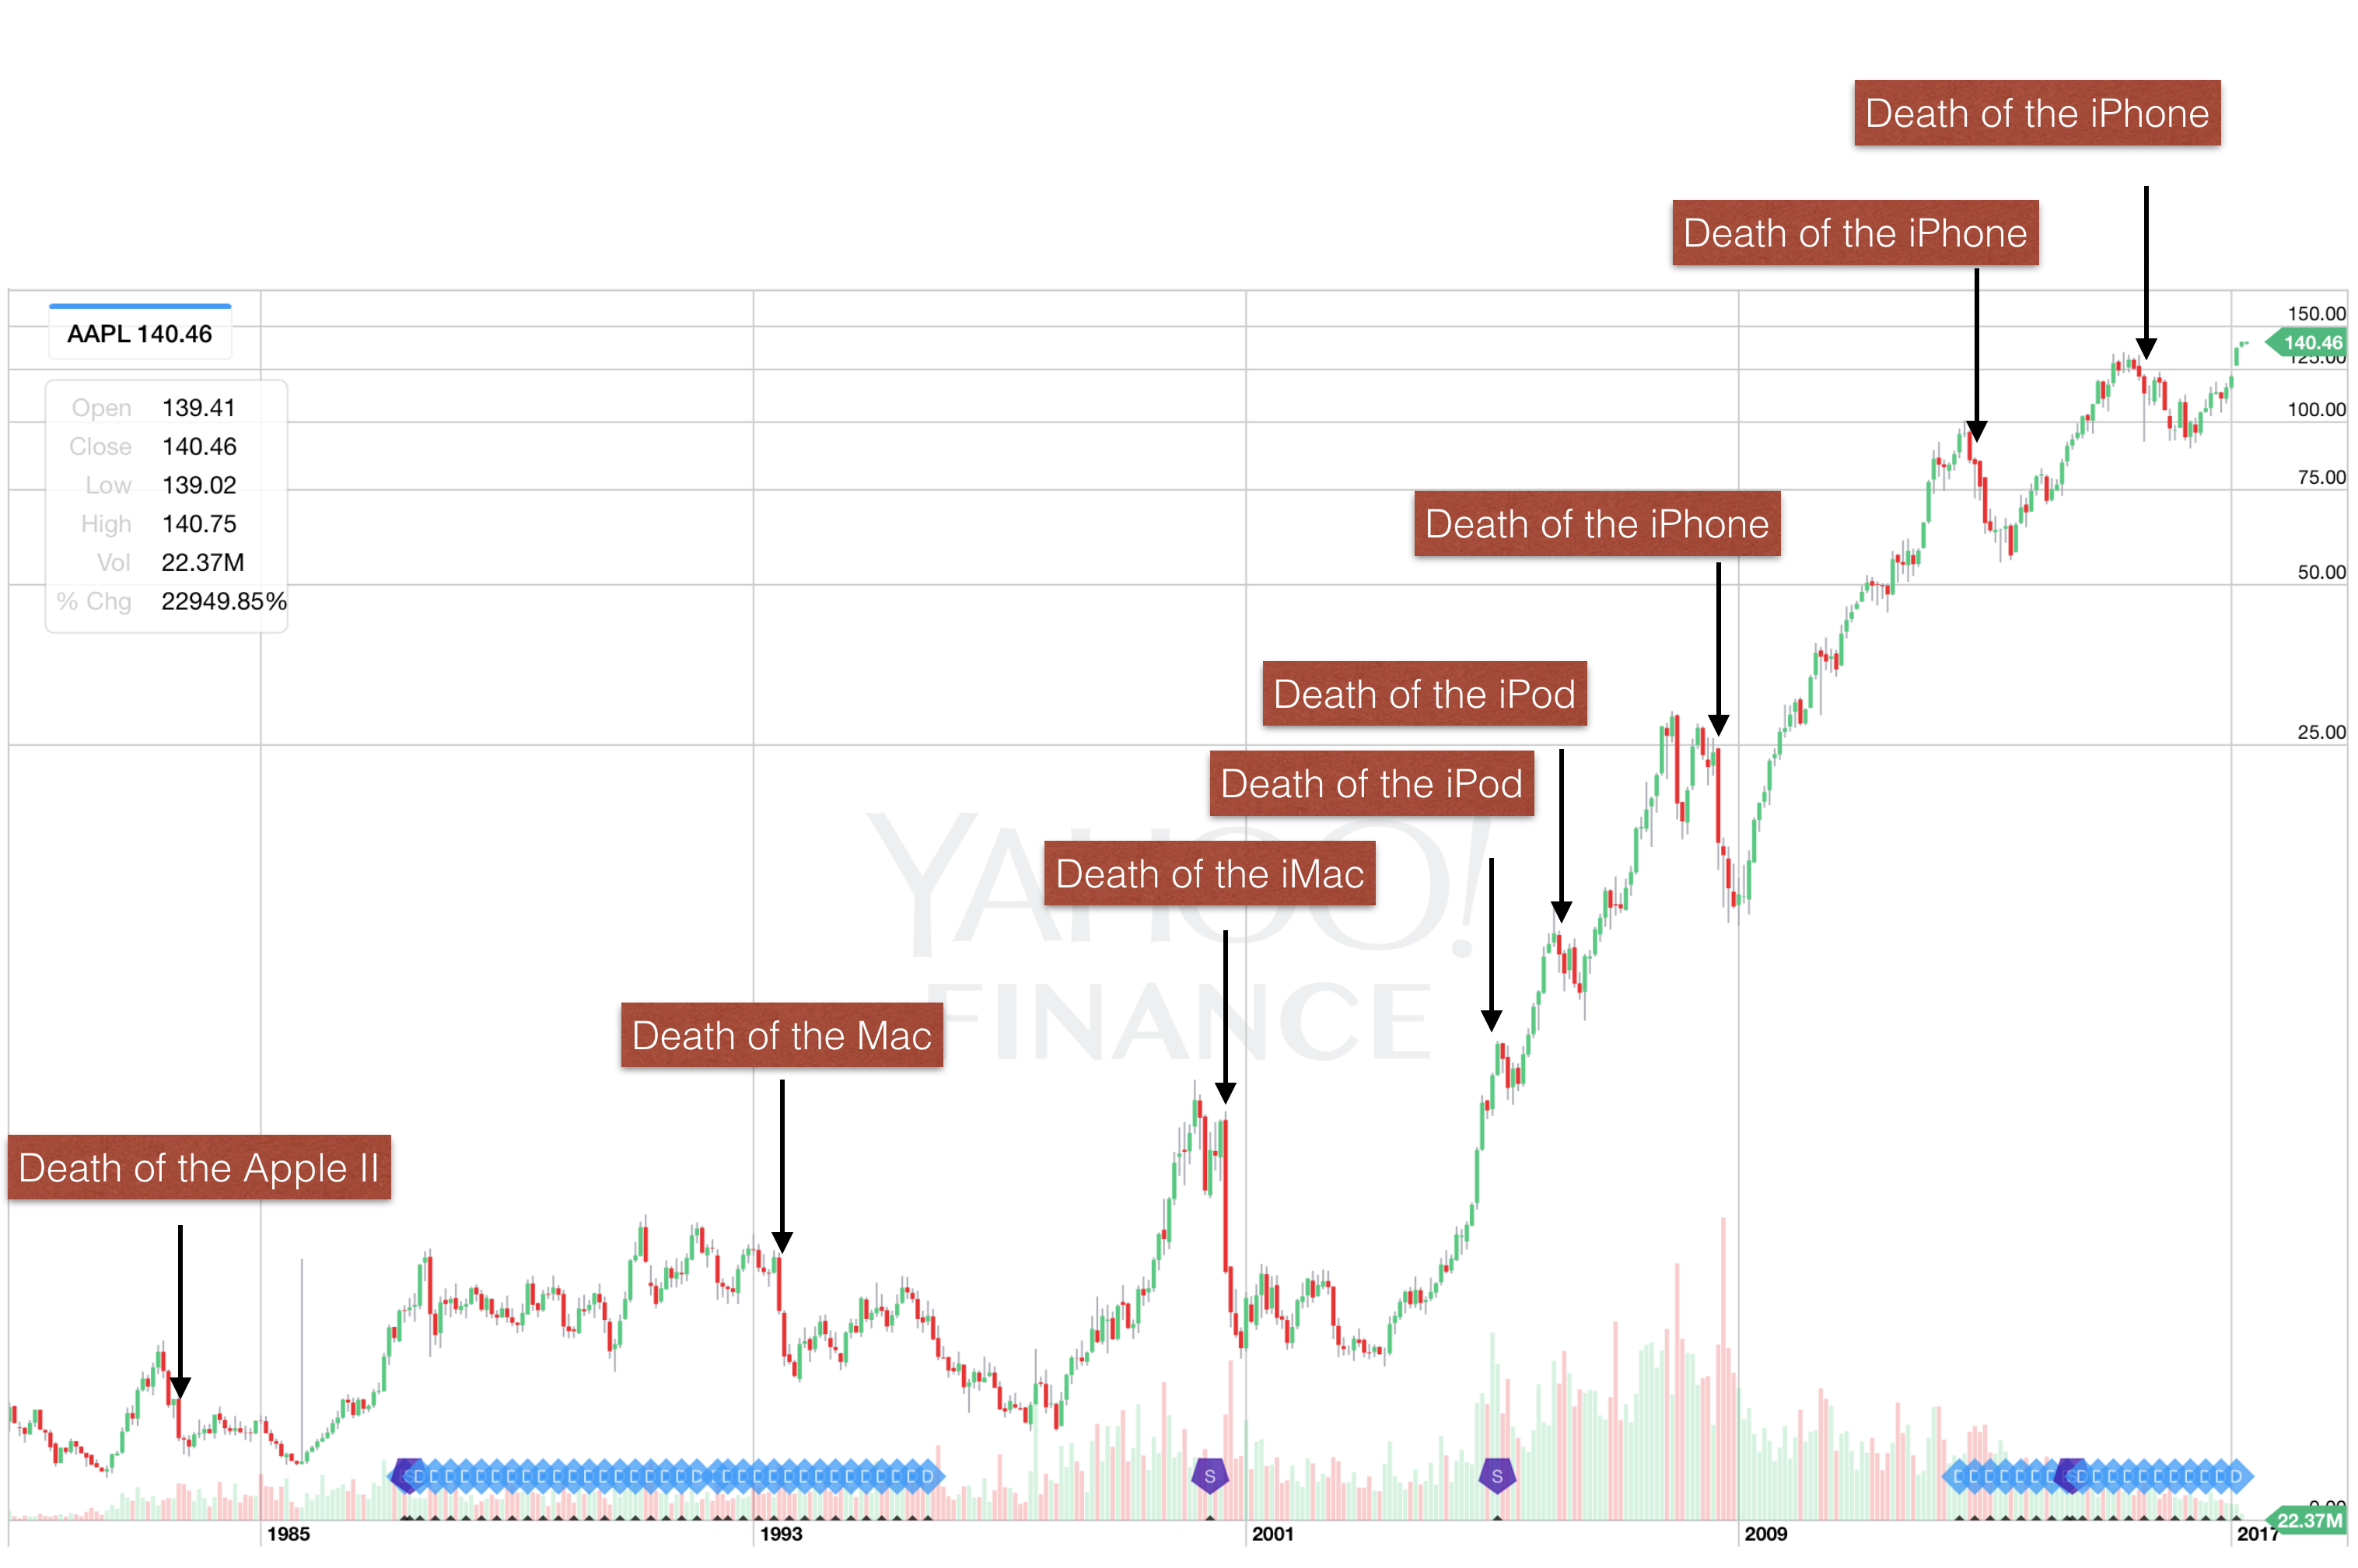
The confusion is exhibited in the following graph which shows the crises in confidence by that wonderful reflector of human perception--the stock market. By voting millions of times a day, the market shows us with great precision the totality of human emotion with regard to an asset. That emotion turns rapidly negative on Apple with surprising frequency.
There have been over 8 bouts of collapsing confidence (exhibited by 40% drops in value) for Apple's shares. Consider the latest where we've seen a 40% drop followed by 57% increase in share price over the last 12 months. 57% might not seem extraordinary for a small company but for the world's largest market capitalization with the corresponding colossus of cash that it straddles, the robustness of brand and the loyalty of customers, the mind boggles.
The same thing happened in 2012 and 2008 and as far as I can tell the company has not changed one iota during that time. The same people, mostly, are in charge. With the same mission statement, and even the same product line. The resources, processes and priorities--the only determinants of the essential value of a firm--have not shifted.
One could try to suggest that even if Apple is unchanged, the world around it has changed. But if anything the world has come to match Apple's own view: more mobile vs. fixed, more design vs. generic, more integrated experiences vs. more modular DIY.
The ethos of Apple is rigid so why is perception about the company so fickle?
If the graph above reflects perception about a constant entity then perhaps it charts how the world has changed rather than how Apple has. Perhaps perception revolves around a center of gravity far heavier and permanent. Perhaps the tug-of-war between fear and greed reflects more upon us that it does upon the object being observed.
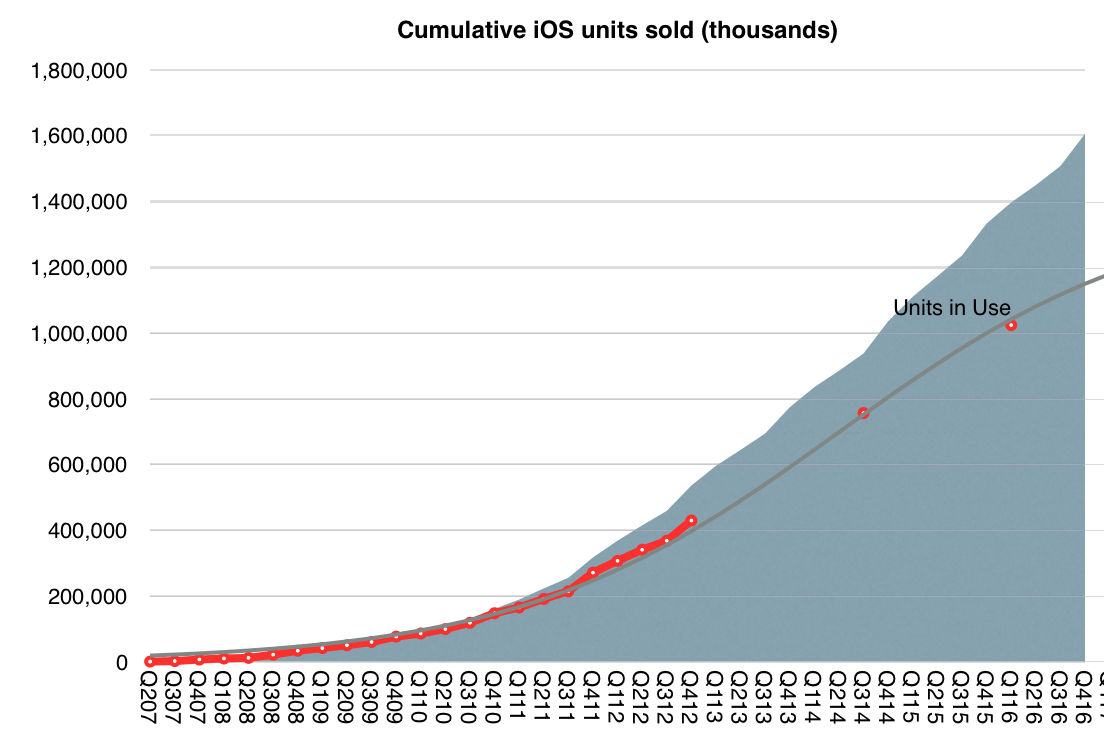
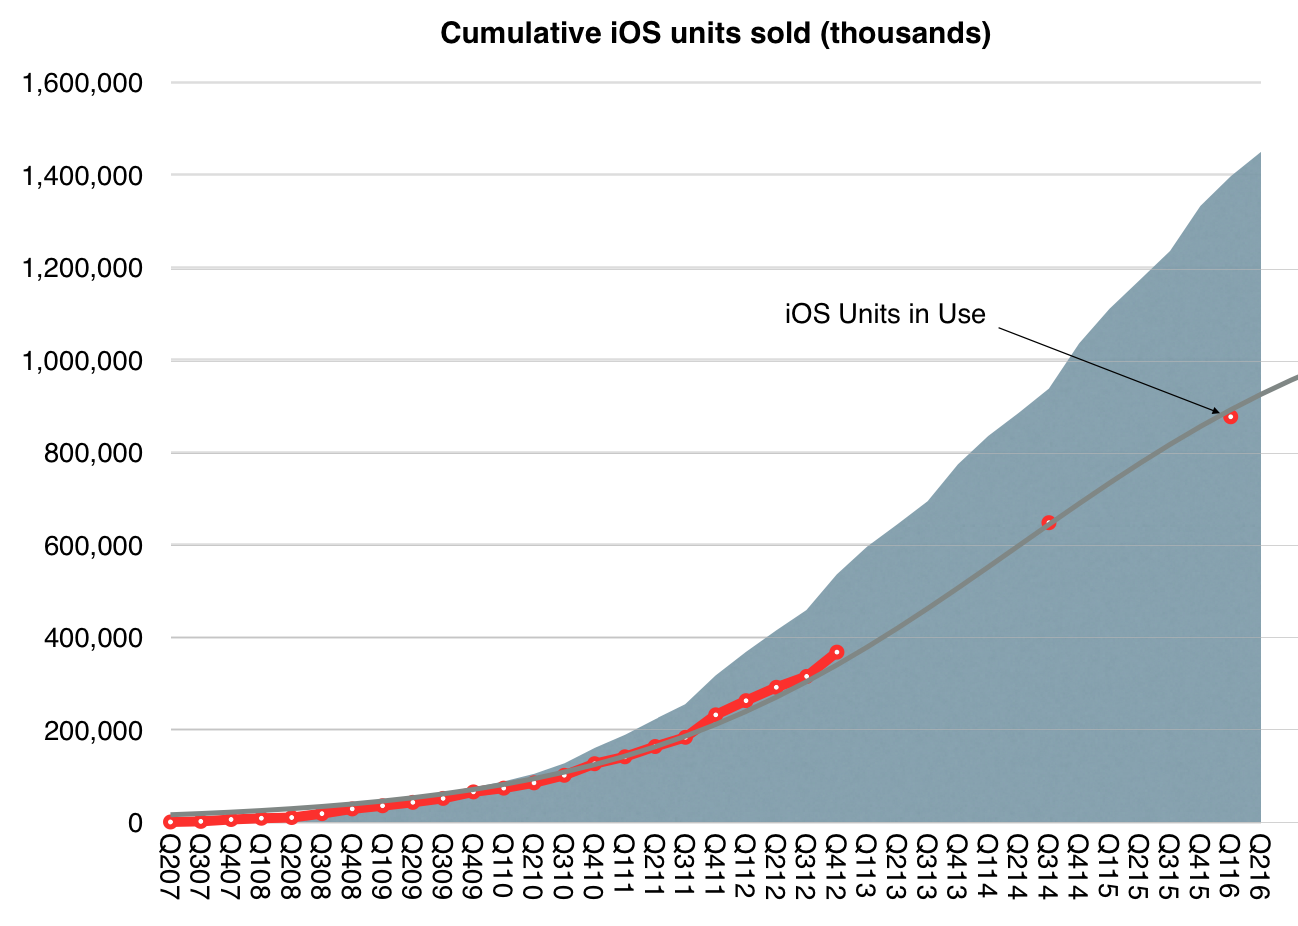
In its first 10 years, the iPhone will have sold at least 1.2 billion units, ((Includes forecast for first six months of 2017)) making it the most successful product of all time. The iPhone also enabled the iOS empire which includes the iPod touch, the iPad, the Apple Watch and Apple TV whose combined total unit sales will reach 1.75 billion units over 10 years. This total is likely to top 2 billion units by the end of 2018.
The revenues from iOS product sales will reach $980 billion by middle of this year. In addition to hardware Apple also books iOS services revenues (including content) which have totaled more than $100 billion to date.
This means that iOS will have generated over $1 trillion in revenues for Apple sometime this year.
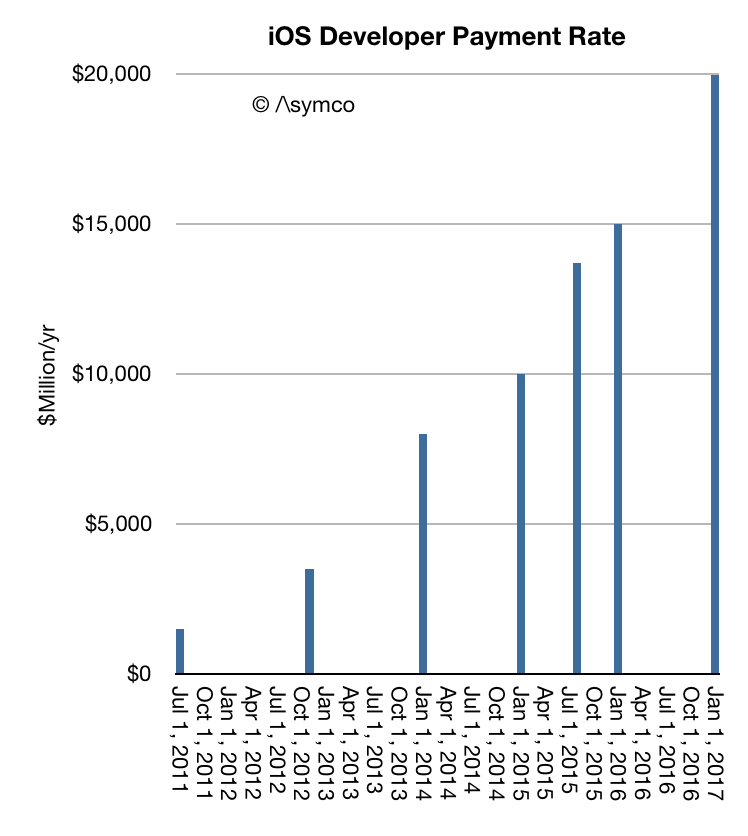
In addition, developers building apps for iOS have been paid $60 billion. The rate of payments has now reached $20 billion/yr.
Not included in this payment total are "mobile-first" or "mobile mainly" businesses such as FaceBook, Twitter, Linkedin, Tencent, YouTube, Yahoo, NetEase, Pandora Radio, Google Search, Baidu, Google Maps, Gmail, Instagram, Amazon, eBay, JD.com, Alibaba, Priceline, Expedia, Salesforce and Other Enterprise Software, Ride Sharing Apps, AirBnB and many other services which monetize independently of the App Store.
I estimate that the cumulative revenues enabled by iOS across these businesses have exceeded $500 billion, with a rate of revenue soon to reach $300 billion/yr.
The revenue numbers can only hint at the change in behavior among users. An iPhone is unlocked 80 times a day. Assuming 600 million devices in use there are 48 billion sessions on iPhones every day. 17.5 trillion sessions every year. It is these instances of interaction and engagement which are desired by all businesses built on top of the ecosystem.
These instances of engagement must be multiplied by the quality of the customers which Apple captures. iOS users spend more and are more loyal than those on alternative platform thus qualifying the platform as "premium" and thus adding to its value in the eyes of developers, content producers and service providers.
As the install base of iOS increases and as users hire the devices to do more and spend more time with them the virtuous cycle of value creation will continue and accelerate.
There is a temptation to think that such a business is fragile and will be disrupted. Challengers appear daily and the number of iPhone "killers" is not measurable. One can cite the billion users of Nokia phones which defected. One can cite the loyalty of BlackBerry users that evaporated. One can even cite the juggernaut of Windows and how it became impotent. One can cite the vast number of Android devices offered at low prices.
But there are reasons to believe that the iOS empire is far stronger and resilient.
Unlike Nokia's phones, Apple's product is an ecosystem with network effects and dependencies on software and services. It's also a monolithic product with a singular interface and form factor.
Unlike BlackBerry, the iPhone does many jobs--too many to count. Indeed the iPhone evolves and changes its core value over time.
Although different in many ways from Windows there are strong similarities in terms of loyalty and persistence of users. iOS even developed a dominant position in enterprises. Microsoft's attempt to become a hardware company is a testament to the confluence of the two business models.
And whereas Android was originally seen as the "good enough" iPhone, potentially disrupting it, it turns out to be the ersatz iPhone. Chances are higher that users will switch from Android to iPhone and not the other way. Again, the reasons have more to do with the ecosystem and quality of users (which are hard to measure) than with the hardware (which is easy to measure.)
As we look toward the second decade of the iPhone, the expectation isn't one of another "big bang" but a process of continuous improvement. The market is nearing saturation so the goals must be to capture more switchers from Android. Apple has achieved this with the Mac: survival, persistence and eventual redemption.
More exciting is the apparent expansion of a network of ancillary "smart" accessories. The Apple Watch, the AirPods, Pencil and possible new wearables point toward a future where the iPhone is a hub to a mesh of personal devices. The seamless integration of such devices is what has always set Apple apart.
Managing the Mac product line must be one of the most challenging problems at Apple. That may not be obvious given the product's success. Consider what it has achieved:
The product is in its 32nd year of market presence. A longevity that in unmatched by any other PC maker.
Apple reached a top five position in the ranking of PC vendors. This was achieved for the first time only this year, far along in the evolution of the market.
With about $23 billion in revenues per year, Apple places among the top four PC vendors in terms of revenue.
With an estimated $5.5 billion in operating margin Apple is the most profitable PC vendor, capturing over 60% of the available PC hardware profits.
The product has retained an average selling price of over $1200 for at least a decade. At the same time the average pricing of Personal Computers has more than halved.
Although volumes have fallen for three quarters, the product grew volumes and sales for 22 out of 29 quarters. As a result, volumes almost doubled in eight years. ((The unit volumes in third quarter 2008 were 2.6 million. Eight years later they are 4.9 million and could easily be over 5 million in the holiday quarter.))
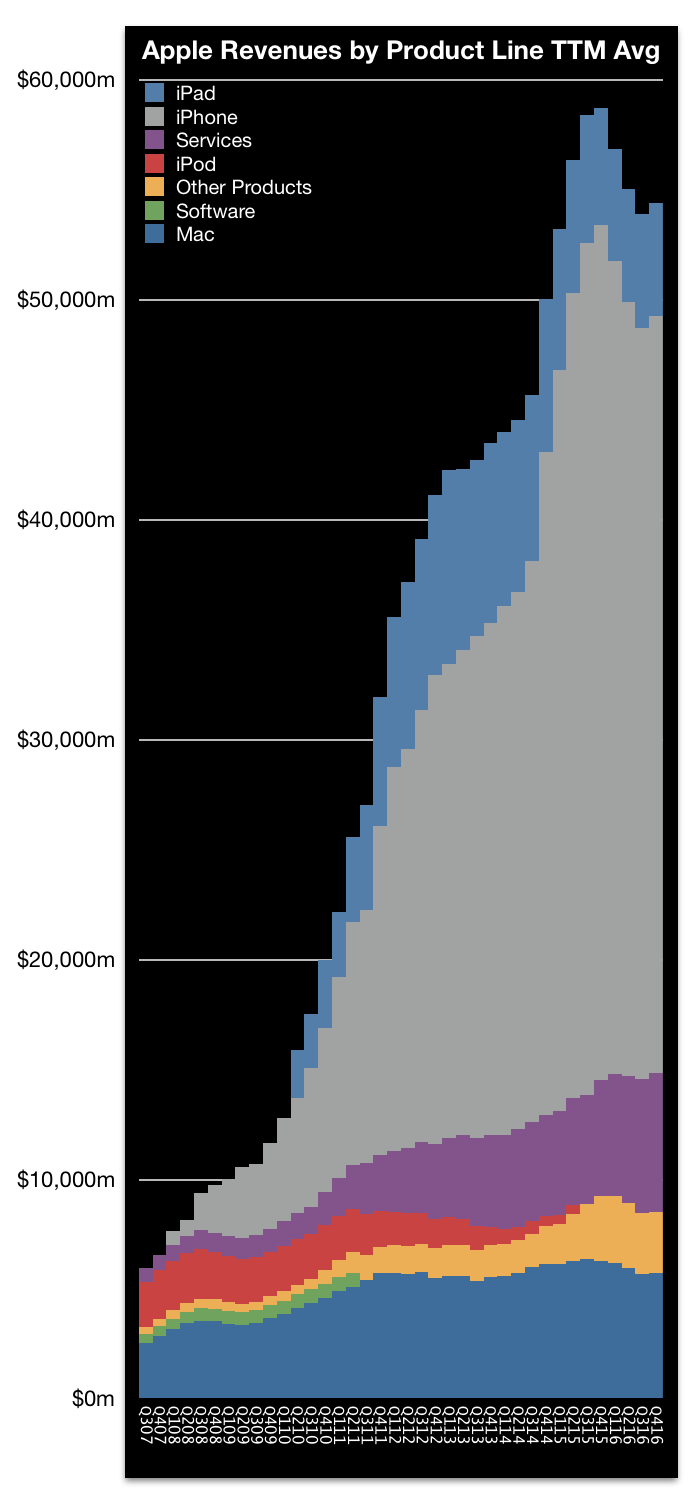
The contribution of the Mac to Apple's revenues is shown in the following graph.
It's attractive and convenient to contrast the Mac with the rest of the PC industry. A David vs. Goliath tale of redemption. The classic comeback story. But the split between the two old rivals (Windows/MacOS) focuses the mind into a limited view of the computing market. The big change in computing has not been a growing Mac vs. declining PC. It has been a huge surge in mobile device use vs. a decline in PC use overall.
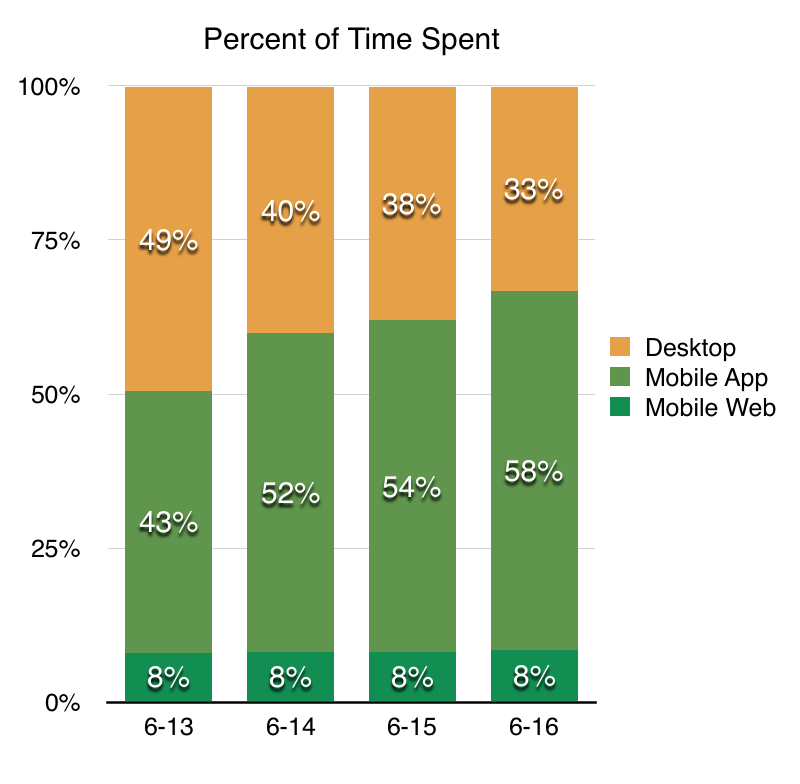
This data is visible in many ways. Browsing data shows mobile overtook PC use this year. Shopping data around Black Friday points in the same direction. Data on user interaction captured by comScore is shown below ((Although US only, the global picture is likely to be even more skewed toward mobile as PC didn't saturated global markets before the smartphone swept to power.))
PC use went from half to a third of time while mobile went the other way: from a third to half of time within only four years. All the data is consistent: mobile use has swept PC use aside.
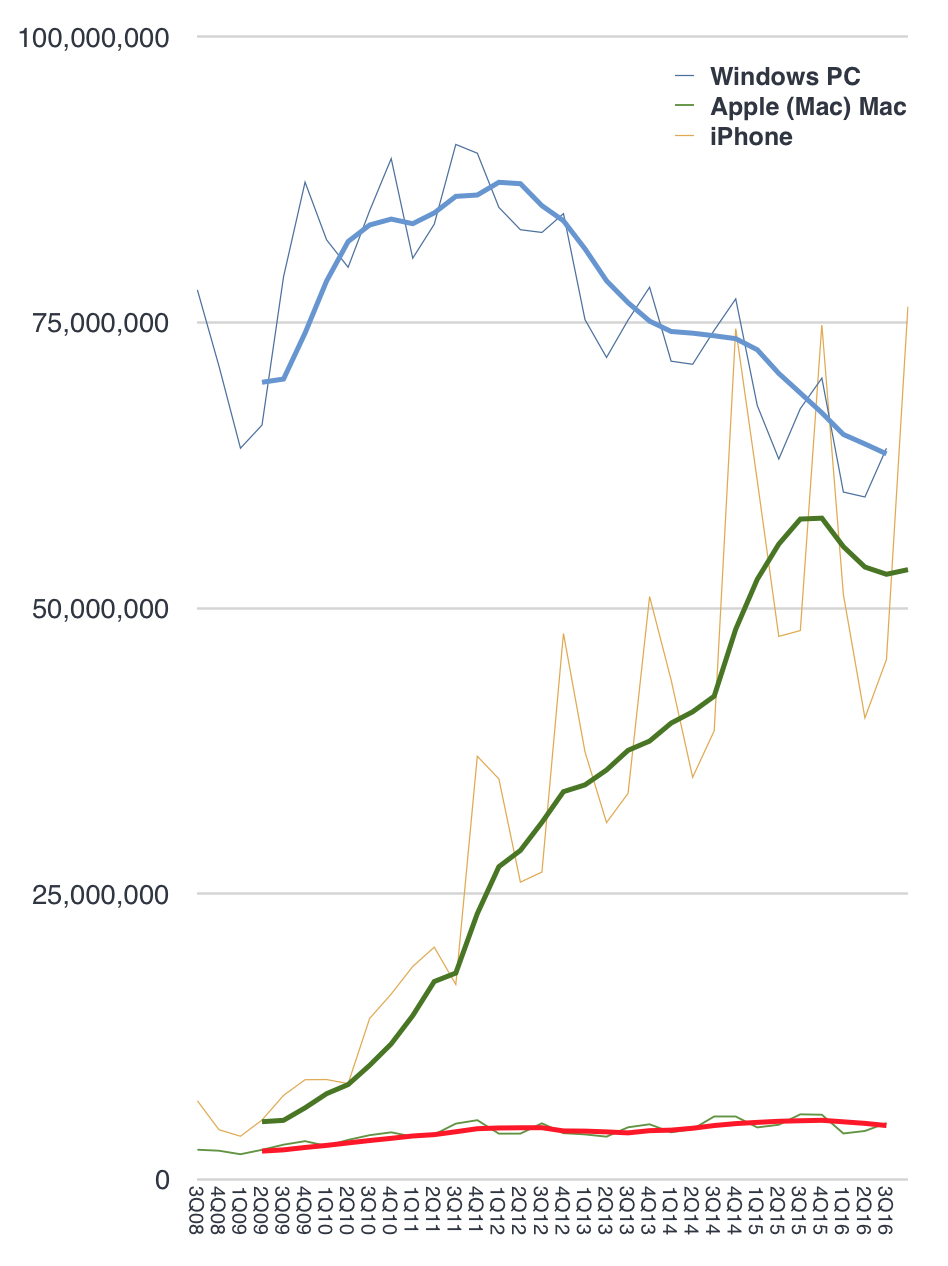
We can see the contrast simply by placing iPhone, Mac and all Windows PC on the same shipment graph.
This contrast is spectacular.
I bring this contrast up because I believe it is what focuses the minds at Apple. For them it's pretty clear where the puck is going. And not just now. Mobile has been foreseeable as a disruption to computing a decade ago–at least to some of us.
And so what do you with the Mac?
To answer this we have to ask what exactly is the purpose of the Mac in the age of the Mobile device?
Note that this is not the same as asking what is the PC in this world. The PC is not having to share a resource pool with an iPad/iPhone. It does not have to answer for its existence to a phone. PC makers and Microsoft are not fighting with an usurper in their midst. They may see the outsider challenger but it's not an inside challenger. This makes all the difference.
Indeed, because no usurper was allowed to emerge, PC/Windows never moved to a mobile evolution of computing. Microsoft's platform future was lost because the antibodies which eat disruptions were left unchecked.
But Apple's immune system was suppressed. It allowed a disruptor to emerge from within. Apple gave birth to its future by suppressing the reaction to that new seemingly parasitic organism. It took an immense willpower to allow this to happen.
But it takes us back to the question of what to do with the incumbent, the donor of DNA and resources. The parent that sacrificed for the child.
The Mac is thus not treated disparagingly. It deserves and gets respect. It is preserved but with limited responsibilities.
Which brings me to the question of what it is allowed to be and hence what it is. It cannot take on the role of being the future. That belongs to the touch screen devices. It will not morph into a touch device any more than a teen's parent will become cool by putting on skinny jeans. What it will do is become better at what it is hired to do.
The key to the Mac therefore becomes that which the iPad/iPhone isn't: an indirect input device. The keyboard and mouse/trackpad are what define the Mac. The operating system, the apps, the UX, are all oriented around the indirect input method. The iPhone's capacitive touch brought about the direct input method, a third pivot in input methods (first was mouse, second trackpad/scroll wheel). Each pivot launched a new set of platforms and the Mac is the legacy of the second.
It's not obsolete but it is a decreasing share of engagement. Alternate ways of doing the jobs it does well with direct input are emerging on the third pivot but they are not yet good enough. The children are still adolescent and making lots of stupid mistakes. There's still life in the parents.
The management thus has to focus on how to make the keyboard/trackpad interface better while still saying and believing that the future is touch.
In this context the newest MacBooks Pro are a logical extension of the second wave of computing while avoiding cramming them into the third wave. They are defined by their constraints. Seen thusly, the move from keyboard/trackpad to keyboard/touchbar/trackpad is pure genius.
The touchbar coupled to the other two inputs is a totally new way to interact with computing products. It's not an "easy" interface as it's not direct manipulation. It remains indirect, a defining characteristic of the second wave. Indirect inputs are powerful and lend themselves to muscle memory with practice. This is the way professional users become productive. The same way keyboard shortcuts are hard to learn but pay off with productivity, touchbar interactions are fiddly but will pay off with a two-handed interaction model. They are not something you "get" right away. They require practice and persistence for a delayed payoff. But, again, that effort is what professionals are accustomed to investing.
This is a leap forward and a big deal. For 32 years the UX model of the Mac has been two-handed typing with one handed gesturing. Now we have the option of two-handed indirect manipulation: one hand on the touchbar and one hand on the touchpad ((the iPad pro already encourages two handed direct manipulation)). Imagine you've been playing guitar with one hand for years and then someone lets you use your left hand. Holy cow.
Even so, it may seem that Apple is pulling punches. The product could have evolved into the full-touch, dual screens, pen input, hybrid model of Windows. But that only makes sense if you don't have a mobile product that is promising the same and tearing up the world at the same time.
You've unleashed a disruptive force and now you're supposed to retrofit the incumbent with the tools to compete. Why not just let the disruptor grow up unhindered.
The Mac is what it is because it's not alone. It's part of a family. It is a parent. It strives to be better but will not take the future from its child.
The Critical Path is sponsored by Wealthfront, the automated investment service that makes it easy to invest your money the right way. Get your first $15,000 managed for free when you visit Wealthfront.com/5by5.
Support also comes from Braintree, code for easy online payments. If you’re building a mobile app and searching for a simple payments solution, check out BraintreePayments.com/criticalpath.
Horace gives an update on his EVW electric car project, listener-contributed battery technology information and listener questions in this extended episode.
Berkshire Hathaway, led by Warren Buffett, now owns about $1.4 billion of Apple. Occasionally we hear about various "celebrity investors" taking positions in the company or exiting those positions. The last one I remember was Carl Icahn. He seems to have exited Apple before Berkshire entered. There are some who will act because of these decisions. You should not be one of them.
Nor should the management of the firm act in response to investor decisions or concerns. Management is specifically distinct from ownership in the corporate construct precisely in order to bring professionalism to the role. The manager must set priorities as they see fit, irrespective of what the transient owner might prioritize. The separation of ownership and management is one of the greatest innovations in commerce.
There are many opinions on what priorities should be. Delivering a specific financial ratio, achieving a certain market position, changing the world for the better. These have all been cited as top priorities. I happen to believe that what matters most is the creation and preservation of customers. That is because I see customer creation as causal to the other desirable outcomes and it is therefore the more important priority.
And this is why, whenever possible, I try to deduce how well a company is performing on this metric. The greatest companies (by market capitalization) today are certainly examples of achievement in customer creation. Facebook, Microsoft and Google are members of the "billion user club" or companies that crossed a billion active users.
But do they really have a billion customers? Microsoft has over 1.2 billion users but many (most?) of those users are using computers that their employers provide on which Microsoft software was installed. They may not have made the choice to purchase the tools they are using. Microsoft certainly has millions of customers in the form of "accounts" purchasing its products and services, but It's not likely that there are a billion people who have directly chosen to buy a Microsoft product.
Facebook has over a billion daily users. Facebook users are certainly using the service of their own accord but they are not paying for the service. Quite the contrary, the actual customers of Facebook are companies buying an advertising service offered in the form of exposure to those billion users. The Facebook users are the product being sold, not the buyers. Thus Facebook's total number of paying customers is probably only in the tens or hundreds of thousands. ((Orr Sella @orrsella pointed out that Facebook has stated that they have 3 million businesses actively advertising on their networks.))
Same with Google. We don't know how many accounts Google send invoices to but the number is very likely not even in the 100 million range. Its billions of users are beneficiaries of services but they are not paying Google/Alphabet.
Amazon has many millions of customers, if not billions. Prime membership is above 50 million but not above 100 million. Amazon may some day have a billion customers but there are limits to how quickly that can happen. The growth potential is governed by logistics and that's as much an issue with atoms as it is with electrons.
Which brings us to Apple. Apple does not offer a figure on its specific user count, but we have some viable proxies:
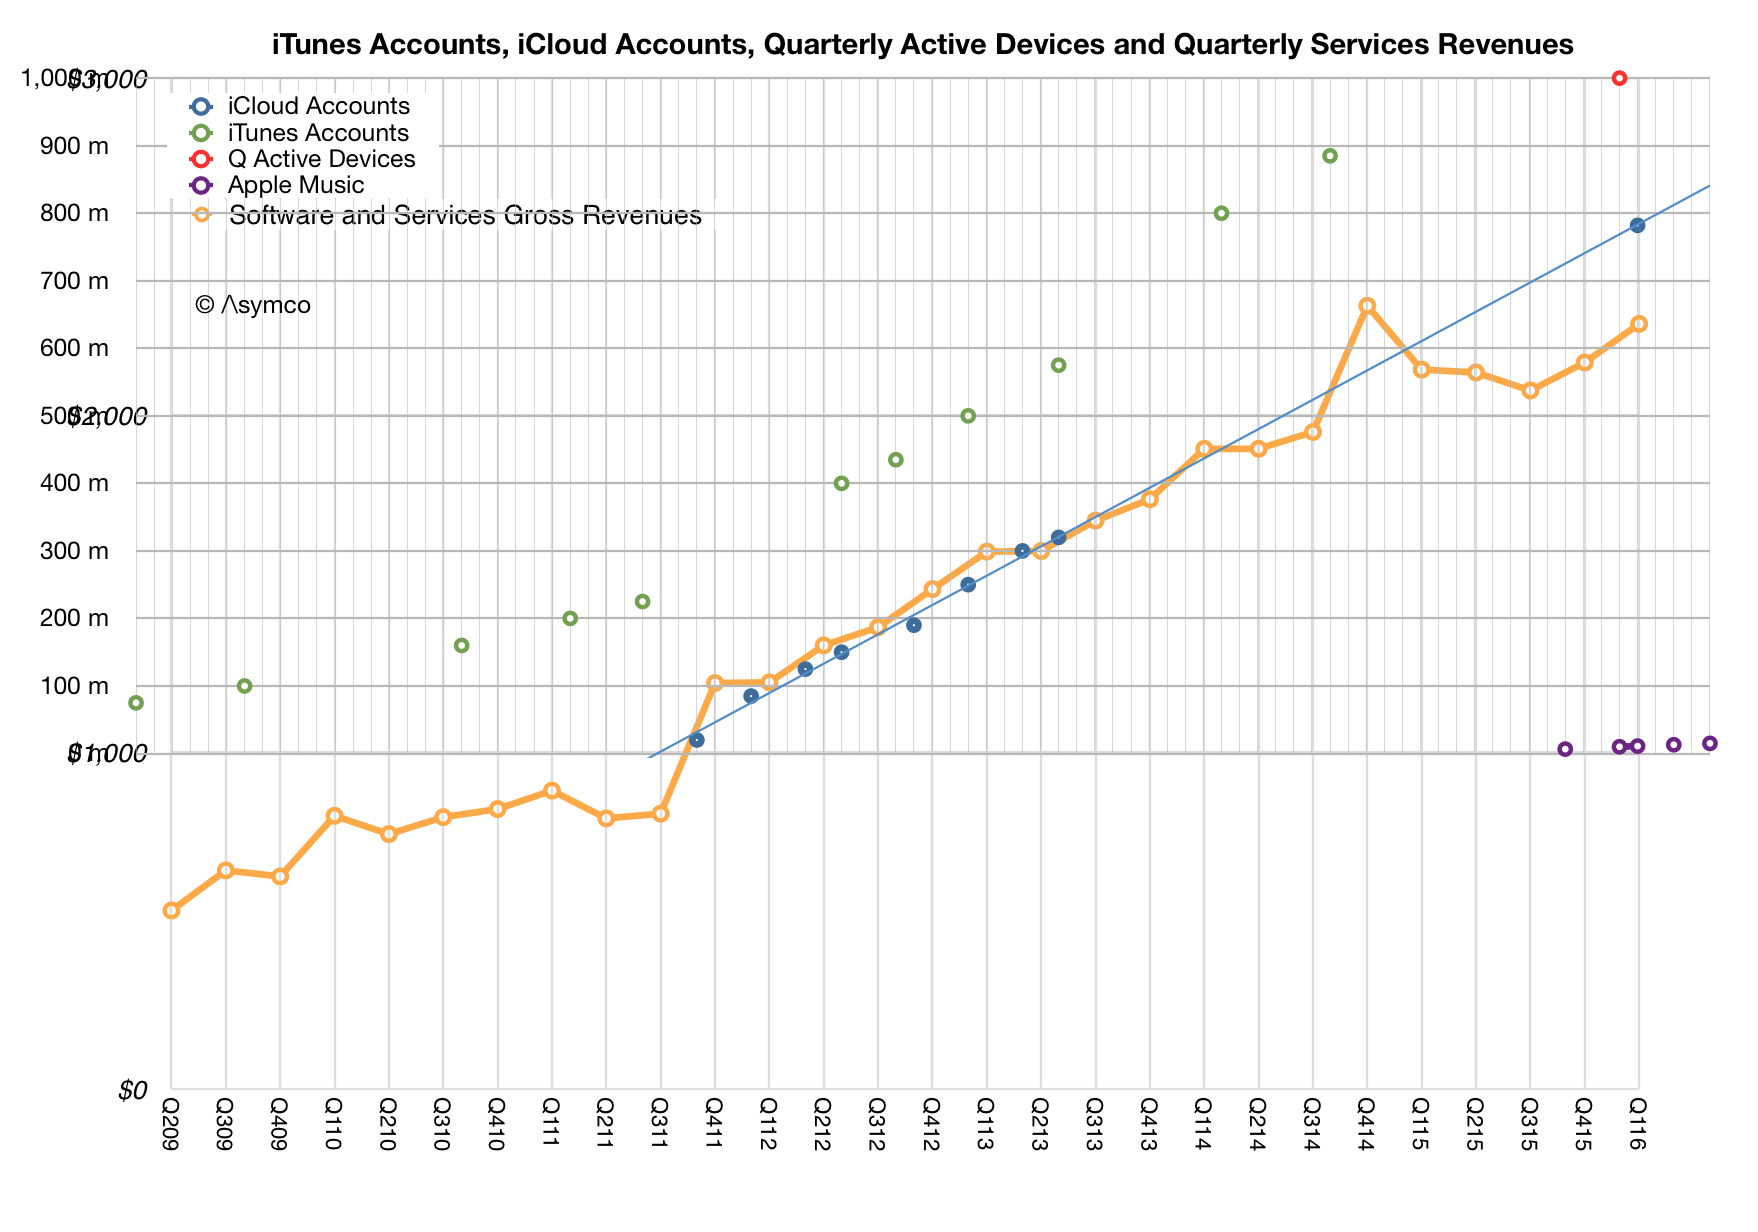
iCloud accounts reached 782 million in February 2016.
iTunes accounts reached 885 million in September 2014
Active devices reached one billion in January 2016. That number is likely above 1.1 billion now. (Includes all devices, hence Macs and Apple TVs).
These figures are also parts of patterns (shown below) which offer an indication of predictable growth.
In addition to the absolute figures and their growth there is also the question of loyalty (frequently cited by the company), switching from other platforms (also frequently cited) and revenues. The company publishes specific figures on service revenues for consumer attached devices showing a run rate of $41 billion/yr in services for their device base.
In combination, a picture emerges which shows that Apple has nearly a billion customers. I can't say how many with any precision but it's certainly above 500 million (on the basis of iCloud and iTunes accounts). It's below one billion because some users have more than one device.
Even though it has not happened yet, the trend is pretty clear. Apple will at some point in time have a billion paying customers.
What is more significant than the specific count is that these customers mostly chose to be customers individually. Some may have been given the products as gifts, but the vast majority bought the items for themselves. Apple benefitted from hundreds of million of individual purchase decisions.
Furthermore, having made the decision to purchase, chances are that they will do so again. Apple customers are a recurring revenue stream. In fact, it's fairly easy to calculate that being an Apple customer is equivalent to spending about $1/day on its products and services, indefinitely.
Apple is not there yet, but a billion dollars a day from a billion customers is not inconceivable. That would be quite an achievement.
The following is a list of the best-selling products across several categories:
Car model: VW Beetle 21.5 million Car brand: Toyota Corolla 43 million Music Album: Thriller 70 million Vehicle: Honda Super Cub 87 million Book Title: Lord of the Rings 150 million Toy: Rubik’s Cube 350 million Game console: Playstation 382 million Book series: Harry Potter Series 450 million Mobile Phone: iPhone 1 billion
The iPhone is not only the best selling mobile phone but also the best selling music player, the best selling camera, the best selling video screen and the best selling computer of all time.
It is, quite simply, the best selling product of all time.
It is that because it is so much more than a product. It is an enabler for change. It unleashed forces which we are barely able to perceive, let alone control. It changed the world because it changed us.
And it did all that in less than nine years. One has to wonder what it will enable in the next nine.
What is an innovation? What is the difference between ideas, inventions, novelties, discoveries and creations?
What is a disruption, formally-speaking? Also, what is it informally speaking? Why the distinction?
What is Performance (or P-space)? How does Performance relate to utility, quantity, price and other microeconomic concepts?
What is a new market? How do we distinguish a new industry from a new market.
Do firms matter? Are firms causal to economic growth?
What is the role of technology in innovation? Can we innovate without technology? Can we fail to innovate with technology?
Do firms have life in the biological sense? If not how do we measure their existence?
What are entrepreneurs? What do they do that’s different than what managers or business leaders do?
How do you navigate P-space? How do you think about your business and economy in performance terms.
What is a diffusion? Is adoption a good measure of technological progress? What is the connection between diffusions and disruptions?
How does Capital map to P-space?
How can we maximize economic growth? Is there a growth algorithm? What is the role of government policy in growth? What about the role of the creation of customers?
What is the difference between consumption and non-consumption? What is non-production?
What are the known forms of disruption? Can there be forms we don’t yet know about?
Why do customers buy solutions? Understanding the causes of purchase decisions.
Are profit motives necessary for growth? What motivates individuals, if not profit?