Asymco

Asymmetric Intelligence

Latest from Asymco

  1. Warner Music waits for Godot

    Research · 19 comments

    You really can’t stress this point enough: We’re a decade past Napster, but the music industry still runs on CD sales. In Warner’s case, digital now accounts for 25 percent of overall revenue.

    via Warner Music Renews Spotify's European Deal, Waits for Google | Peter Kafka | MediaMemo | AllThingsD.

    What's even more amazing is that after ten years not a single industry participant has found a new job for which its product can be hired by consumers.

    The music companies wait for Apple, Google, Spotify to  "invent" some new consumption model from which they can extract a rent.

  2. Subscribe to Asymco One for full access to our research.

  3. Subscribe to Asymco One for full access to our research.

  4. Operators' last stand: payment platforms.

    Research · 13 comments

    Operators “had high hopes until 2007 or 2008,” said Patrik Karrberg, a researcher in the London School of Economics’ Department of Management. The hopes dimmed after the emergence of iPhones and improved data speeds that made the Internet directly accessible on handsets.

    “They gave up the idea of controlling the entry point,” Karrberg said. “That was the death of the portal.”

    via Vodafone, France Telecom Push to Regain App Edge From Apple - Bloomberg.

    It looks like a payment platform may be one of only a few opportunities remaining.

  5. Subscribe to Asymco One for full access to our research.

  6. HP/Palm's Rubinstein believes in integration

    Research · 34 comments

    In other words, to differentiate and succeed in the mobile device space, you need to own a veritically integrated stack strategy — software, hardware and services — like the one Palm is now building out with the help of HP’s not inconsiderable resources

    via Palm Chief: By Birthright, Palm Should Have Owned the Smartphone Market | John Paczkowski | Digital Daily | AllThingsD.

    I would not write Palm/HP off in this market.

  7. Subscribe to Asymco One for full access to our research.

  8. Is the smartphone a commodity?

    Research · 42 comments

    People throw around the idea of things being or becoming "commodities" but there is little clarity about what "commodity" status implies.

    If you look up the word, it has nothing to do with technology or innovation. In economics, a commodity is something that is substitutable (fungible) and roughly equal to competing versions of the same thing. A mineral good (oil) or agricultural product (pork bellies) is roughly of equal value regardless of where it comes from or who produces it. Commodities also have very liquid markets and are therefore easily priced according to demand.

    Commodities have a "fixed" quality which cannot be and most likely never was improved. It's a product that is essentially frozen in terms of innovation.

    But in technology and especially in terms of complex, rapidly improving and evolving products with uneven distribution a commodity is not easy to identify and there can be a lot of arguing about what is and isn't.

    So here is another way to define it:

    In terms of innovation, a product can be defined as a commodity if it reaches a point where improvements do not create additional value. As the product gets better, it reaches a point where customers can no longer absorb the improvements and therefore they become unwilling to pay for them. Thus the price of the product cannot be increased or maintained in the face of competition.

    In other words, you can't get a premium price for a better product.

    If you can't improve the product, one consequence is that you can no longer differentiate it. Becoming commoditized is a natural result of the improvement of a product beyond the customer's ability to utilize that progress.

    So we're back to the debate about whether a product is good enough. You can argue that commodity status is that point where it over-shoots the market. Before that point is reached the product can obtain a price premium for technology innovation. After that point, the product becomes a "commodity".

    How does this relate to the mobile market today? Again, it's important to ask what is the basis of competition. Is hardware not good enough? Is software? Or is the whole widget?

    For those who say that smartphones are commodities, they have to also account for the inevitable consequence: that improvements will not be valued and hence will not be implemented. It also means that profits will evaporate from the current incumbents to new models of profit capture.

    This is the essential argument for Android. But I'm still struggling with what the argument implies. That the product as it exists today is all that will ever exist.

  9. Subscribe to Asymco One for full access to our research.

  10. Updated theme

    Research · 7 comments

    I updated to Basic Maths theme v. 1.1. I am trying a new, "native" theme iPhone users. Please let me know if there are problems with it in the comments below.

  11. Subscribe to Asymco One for full access to our research.

  12. Law of conservation of modularity

    Research · 32 comments

    When I applied the modularity dichotomy to smartphone operating system there were several implications that came to light. One was the question of whether the market has reached the point where products were "good enough" and the speed of innovation became less important than price. Another was: will integrated vendors be able to hold on to a healthy share of growth against non-consumption?

    Now I bring up another implication of modularity: the concept of "law of conservation of modularity".

    Clayton Christensen illustrated this as follows[1]:

    If you are writing a software application to run on top of a platform, are you permitted to modify the platform to make your application run better?

    If the platform is interdependent, changing it could cause unintended side-effects and you will not be allowed to make them. If the platform is modular, changes are possible and you will have access to the code.

    The reason is not not political. It's that in the case of interdependence, the application has to be suboptimized and conform itself to the platform so that the platform could remain optimized (to its goals). The platform needs to remain optimized is because it needs to keep improving (since it's not good enough).

    In the case of modularity, the application can be optimized and the platform can conform itself to the application because the application needs to keep improving while the platform is good enough and does not.

    Conformability is what constrains up-market progress.

    This also holds in hardware architecture. This was plainly evident in the WinTel era. During that time the microprocessor and the operating systems had a proprietary and interdependent architecture even while Dell’s product has a modular architecture.

    So the microprocessor wasn’t good enough. That meant that the desktop computer had to have a modular architecture to conform itself in order to allow this to be optimized because the line widths on the circuit were not good enough.

    This is what is meant by conservation of modularity: one side or the other of an value chain boundary needs to be modular and conformable to allow what’s not good enough to be optimized. The key question is what's not good enough: the device or the platform (the whole or part?)

    How does this apply today in the post-PC era?

    If you think about it in a hardware context, because historically the microprocessor had not been good enough, then its architecture inside was proprietary and optimized and that meant that the computer's architecture had to be modular and conformable to allow the microprocessor to be optimized. But in a little mobile computer like the smartphone, it’s the device itself that’s not good enough, and you therefore cannot have a one-size-fits-all Intel processor inside of a BlackBerry or iPhone, but instead, the processor itself has to be modular and conformable so that it has on it only the functionality that the BlackBerry needs and none of the functionality that it doesn't need (hence the ARM modular architecture is dominant). So again, one side or the other needs to be modular and conformable to optimize what’s not good enough.

    Now today (and, I believe for some time to come) in smartphones, or in any situation where logic gets embedded in a system it’s the device itself that is not yet good enough and, therefore, you cannot back off the frontier of what’s technologically possible. It has to be optimized with a proprietary interdependent architecture. That means that the processor and the operating system inside of a Smartphone has to be modular and conformable to allow that to be optimized.

    In order for you to believe otherwise you have to convince yourself that smartphones, as a system, have reached the limit of what is technologically possible.

    [1] The source is a presentation by Clayton Christensen at  Open Source Business Conference in 2004

  13. Subscribe to Asymco One for full access to our research.

  14. Is Android fragmented by design?

    Research · 99 comments

    When I wrote about the absence of copyright enforcement on the Android marketplace, I was trying to point out that Google did not have the interests of copyright owners at heart. This attitutde is also apparent in many ways from the absence of desktop sync for Android (and hence the absence of discovery or acquisition of commercial media) to the absence of protection for the app developer.

    Moreover, recently Google TV was blocked from all major US TV content and Google faced litigation from copyright holders in print publications and before that for YouTube infringements and before that from newspaper publishers for Google News' unlicensed reuse of their content.

    Therefore it should not come as a surprise the following revelation that Android lacks any common DRM framework.

    The hurdle has been the lack of a generic and complete platform security and content protection mechanism available for Android. The same security issues that have led to piracy concerns on the Android platform have made it difficult for us to secure a common Digital Rights Management (DRM) system on these devices.

    Setting aside the debate around the value of content protection and DRM, they are requirements we must fulfill in order to obtain content from major studios for our subscribers to enjoy. Although we don’t have a common platform security mechanism and DRM, we are able to work with individual handset manufacturers to add content protection to their devices.

    Unfortunately, this is a much slower approach and leads to a fragmented experience on Android, in which some handsets will have access to Netflix and others won’t.

    via Netflix blog.

    But the absence is not just oversight. DRM is, by its nature, proprietary and, by necessity, "closed". DRM ultimately includes "secrets" which would always be revealed in open source. If Android is to be open source, then it cannot include a DRM framework.

    This leaves the problem of content protection up to the device vendors who must license schemes from various third parties.

    The upshot is more fragmentation.

    As John Gruber points out,

    More and more, I’m convinced that Android isn’t a single platform. It’s a meta-platform upon which handset makers build their own platforms.

    In other words, Android fragmentation seems to be not only impossible to rein in, but it may actually be by design. Google is doing nothing to stop the centrifugal force that is building up in its ecosystem. They have neither the means nor the incentives to control the spiraling.

  15. Subscribe to Asymco One for full access to our research.

  16. What job is a Blackberry hired to do?

    Research · 15 comments

    When mobile platforms are discussed, the conversation frequently turns to market share battles between Android and iOS. I've pointed out before that the problem with this reasoning is that market share in a market that's growing at 90% is a false measure of performance.

    The more important measure is how much of the non-smartphone market is being taken by smartphones and how fast the whole phone market is growing. Competition with non-consumption is very different from platform warfare.

    But even when discussing the rivalry between current platforms, the Blackberry and Symbian are often overlooked as contenders. Windows Phone and iOS come in and out of discussion only on the basis of press releases. The truth is however that Symbian, Windows, Blackberry are not going to disappear anytime soon.  Why is that?

    The reason is that when you stop framing the market as rivalry between platforms, you see that many buying decisions are driven by specific device value propositions or jobs that the products are hired to do. For many years smartphones were purchased because they had the best cameras or the best keyboards and users never downloaded any apps or even used data plans.

    Later, smartphones were purchased because they allowed for browsing and gameplay. Very rarely did buyers opt for "iOS" or "Symbian". Most buyers don't even know what these words mean. Phones are rarely advertised according to their platforms. (As an aside, the mention of Windows in a PC ad is made possible by Microsoft funding, the same as "Intel Inside." So for platform recognition, someone needs to fund the promotion and that implies some revenue to justify it.)

    To illustrate, consider the Blackberry: A product that continues to grow despite a completely different basis of competition from the large screen touch competitors. It comes down to being good at some very specific jobs. RIM continues to grow in certain markets like Latin America and the Middle East on the basis of BBM (RIM’s sales outside the U.S. climbed 94 percent last quarter from a year earlier.)

    “A 15-year-old boy who likes a 15-year-old girl, sends her a BBM and he’s able to measure how important he is to her based on the speed of response after the letter turns to an R,” meaning it’s been read, he says. “No one else runs an end-to- end service plan like we do. That’s killer and is why it’s almost a social phenomenon.”

    or

    BBM is also popular in socially conservative Saudi Arabia where its speed -- messages are typically sent in less than two seconds, according to Morgan Keegan -- has made it a way for teenagers to communicate in a country where religious police bar unmarried couples from meeting in public.

    You could argue that the other platforms also allow for free messaging (through free texting apps) but the combination of a low cost device, a data plan and attention to detail (like Message Read notification) gives the Blackberry an edge.

    The general purpose smartphone that Google and Microsoft and Apple promote is still not the prevailing view of mobile usage for most buyers. One could also argue that many if not most Nokia smartphones are still being "hired" to do feature phone jobs.

    The fact that all these devices are classified as smart and therefore competing misses the point that they are hired for different things.

  17. Subscribe to Asymco One for full access to our research.

  18. Google Nexus S

    Research · 52 comments

    Google Nexus S is real, gets leaked by Best Buy [U] | Electronista.

    Can you imagine Microsoft launching a Microsoft branded phone to compete with its Windows Phone licensees? When Microsoft launched the Zune, their licensing model (PlaysForSure) was quietly folded up.

    A Google phone makes little sense, but then again Google does not seem to care much about its ecosystem or relationships with Android device vendors. They even claim that they have no idea how many phones are being built using Android and, except for activations, have no way of measuring the number sold.

    From their point of view, if Motorola feels it's unfair to have to compete with a Google branded Samsung (or HTC) designed phone then too bad. There's lots of white label vendors lined up to make these with or without anyone's blessing.

    In fact, the biggest opportunity for Android growth seems to be the large unlicensed (and illegal) grey market which seems to be rapidly expanding.

  19. Subscribe to Asymco One for full access to our research.

  20. 20% vs 33% for "Others": Why are Gartner and IDC so far apart on mobile phone market estimates

    Research · 39 comments

    The latest mobile phone estimates from Gartner made a startling claim that "Others" vendors increased share from 16% a year ago to 33%. Doubling share in a year is possible if you're at 1% share but to double from a base of 16% is sounding improbable. They allege that the "Others" now sell more phones than Nokia. And Others don't even include ZTE and Huawei, the prototypical low end challengers.

    They emphasize this point in their discussion and state that the incumbent vendors are being pressured by these low end entrants. They go on to explain that the same set of vendors will probably use Android to enter the smartphone space.

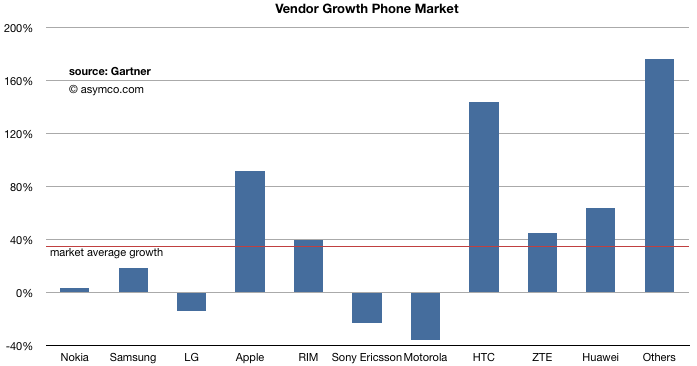
    To illustrate, the growth of individual companies is shown here (all phones).

    Also puzzling is that ZTE and Huawei did not share in this boom. They barely beat market growth and were growing at half of "Others". Until recently ZTE and Huawei were themselves Others, so the new vendors are truly unbranded "white box" vendors.

    To put it in perspective, their year-on-year growth is astronomical: 176%, selling 87 million more phones this third quarter than last year's. This is equivalent to saying that a new company was born in the last year and has already become the second largest in the world. The growth in volumes is higher than the total units Samsung sold!

    Mind the gap

    Extraordinary claims require extraordinary evidence. Can we check what other analysts estimated and do some form of validation of the claims?

    Yes we can.

    IDC reports the same data and they only reported 340.5 million phones sold (vs. Gartner's 417 million). Excluding ZTE and Huawei the total share for "Others" in IDC would be about 20%.

    20% share vs. 33% share is a big gap.

    IDC and Gartner both agree on smartphones, so the difference is even more glaring when you consider the "non-smart" comparisons:

    Non-smart phones:

    Total Market: millions of units sold____3Q2009______3Q2010
    Gartner268337
    IDC244260

    For added emphasis, I added a comparison of last year's quarter. Last year the Gartner total estimate was about 10% higher than IDC. This year they are 30% higher.

    How could the difference in the total phones sold be so big: 77 million phones?

    If Gartner is right, how could IDC miss 77 million phones. If IDC is right how did Gartner conjure up 77 million phones in one quarter? That number is nearly as big as all the smartphones sold (81 million). This is not within any margin of error for whatever sampling method they use.

    Perhaps they need to clarify this because until they do, neither is credible.

    --

    Note: My own models are built from individual company public reports. The only data I depend on from IDC and/or Gartner is this total market size which allows me to back out what the "Others" are doing. If the total market estimates disagree so much, I'll be forced to throw out the "Others" all together.