Asymco

Asymmetric Intelligence

Latest from Asymco

  1. How many iPhone ``5''s will be sold?

    Research · 77 comments

    Phil Schiller stated (under oath) that when assessing sales for a new model of the iPhone, Apple used an easy shorthand:

    Each new generation sold approximately equal to all previous generations combined.

    That's a helpful gauge. Did it hold and will it continue to hold?

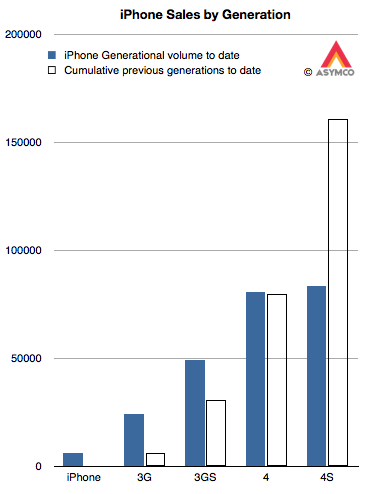
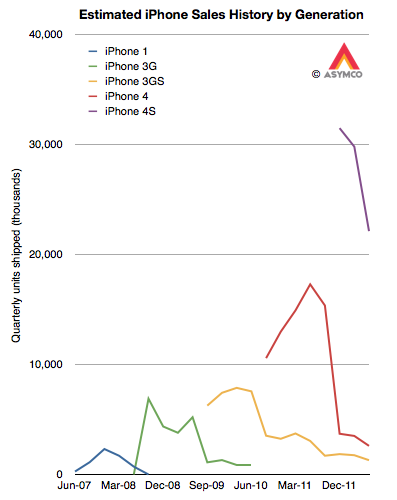
    In order to test this rule of thumb we need to know generational sales. Although we know overall unit sales for a given quarter, since Apple has been selling several versions simultaneously, we need to make some guesses about the ratio of generations in the mix. My guess is about 10% for 3G vs. 90% 3GS and 5% 3GS vs. 10% 4 vs. 85% 4S. That results in the following pattern:

    The cumulative totals for these generations can then be generated and they appear as follows:

    The solid bars are the shipments for each generation (to date) and the outlined bars are the cumulative shipments of all prior generations. The assumptions show that:

    • The 3G easily outsold the original iPhone. In fact, it sold nearly four times as many.
    • The 3GS also handily beat the 3G+original total by a factor of 1.6
    • The 4 also beat the 3GS+3G+original. As the 4 may continue to sell into the future, the beat will only grow larger.
    • The 4S is only half way through beating  the 4+3GS+3G+original. Assuming the current quarter's sales roughly equal the last quarter's, the total for 4S will reach two thirds of the sum of the previous generations (i.e. 100 million) by the end of September. Bearing in mind that the 4S is likely to remain in production at least one more year means it has a potential to come close to the target of 162 million.

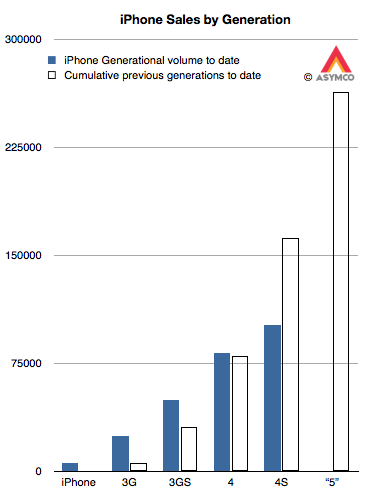
    This leaves us with the question of how many iPhone "5"s will sell. As it stands today, the cumulative total would have to be greater than 263 million units (including assumptions for the current quarter.) That target is shown below:

    Is that a reasonable target?

    Unfortunately, this is a moving target. As the 4S (and maybe 4) remain in production, the target continues to increase with time. However, we can still take a stab at this.

    Recall the analysis of production based on budgeted CapEx spending. It resulted in a best guess of about 165 million iOS units sold in the following two quarters. I further forecast iPhones in isolation to be about 102 million over the same period. Taking that forecast forward and assuming a 60% growth rate,  I currently have about 200 million iPhones over the next twelve months. If 85% of those are the next generation, that yields about 170 million iPhone "5"s through mid 2013.

    This is well short of a target of 265 million. But that's only over the next four quarters. If the iPhone "5" remains in production for at least as long as the 3GS then it might cross 200 million. There is also the question of whether the "mix" will begin to favor the older generations more. If that's the case, we might see version "5" meet its target.

    Underlying all this is the question of a change in strategy toward more penetration (vs. current skimming.)  That might allow for sustaining the 100% historic growth rate. If so then Apple will easily sell 250 million iPhone "5"s.

  2. The biggest loser

    Research · 36 comments

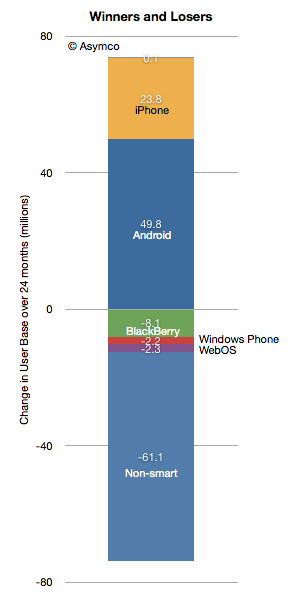
    According to data from comScore, in the past 24 months 50 million Americans became Android phone users. In the same time frame Apple added 24 million iPhone users. As I mentioned in my Asymmetric Competition post, it would be unwise to consider this data in isolation. Consider the following graph showing the net change in users in the US.

    Android and iPhone grew mostly at the expense of non-smart users. The BlackBerry lost 8.1 million users and all the others only lost about 4.5 million.

    With penetration at 50% it's still impressive that there is so little "churn" between platforms. In fact, measuring churn as the net platform user loss as a percent of all smartphone users, we get something less than 1% per month.

    The smartphone competition is still primarily with non-consumption.

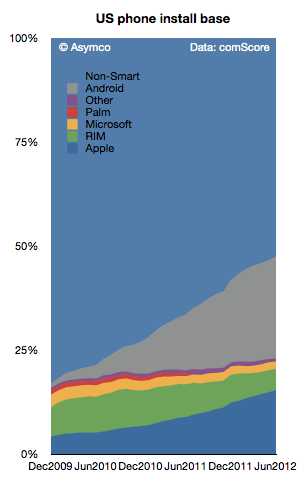
    That will change at some point when smartphone penetration (shown below) will begin to saturate. The basis of competition will have to shift from converting non-smart users to converting users of other platforms while maintaining one's own user base.

    The market has not experienced this sort of rivalry on a wide scale. The defections of BlackBerry and Symbian users are relatively rare events.

  3. Perspective and Context in Personal Computing

    Research · 49 comments

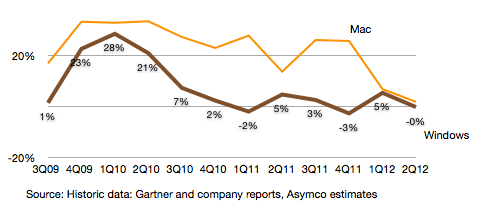
    The Mac grew at the extremely low rate of 1.8% over last year's second quarter. Although it grew faster than the Windows PC market, the gap has narrowed quite a bit. The following graph shows the growth of the two members of the computing Ancien Régime.

    We have to wait a few more quarters before we can decide whether the Mac will enter a new phase of diminished expectations. Although it's not immune from the impact of the iPad, the effect can take a long time to be evident and in either case, growth can come from conversion of Windows users which vastly outnumber loyal Mac users who might upgrade.

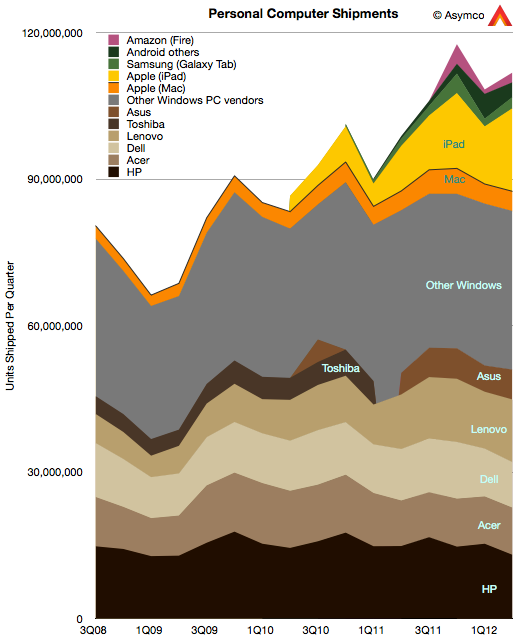
    If we see the computing market as the superset of keyboard+mouse input and touch-based input then new computing consumption becomes easier to spot:

    Seen this way, rather than there being a crisis in personal computing, we have a renaissance. And as in the actual Renaissance, it's a volatile and unsettling period.

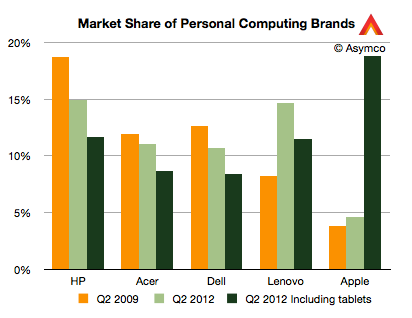
    Nowhere more so than in the changing of bases of power. Consider the following data:

    A change in perspective leads one to conclude that Apple is the new leader in selling personal computers. Maybe this charting is putting too fine a point on it, but the data is beginning to make evident that which has been perceived subjectively by only a few.

  4. Asymmetric Competition

    Research · 55 comments

    Thanks to Angel Lamuno for sending me to a dry and boring lecture by Dr. Israel Kirzner from Feburary 1988. It got me thinking again about competition and how confusing it can be.

    The lecture was in part about how the word "competition" is used by economists with directly opposing meaning from that of the layman and how that leads to confusion about the role of free markets.

    I won't dwell on that, but instead I want to explain how this word can also be contradictory in meaning when applied in everyday usage in business analysis. Nowhere is this more evident than when we argue whether Apple competes with X or Y or Z.

    Does Apple compete with Android or Google or Samsung? How could Apple compete with Google and yet cause it to be the default search engine in Safari thus enriching their competitors? How could Apple compete with Samsung and yet select their semiconductors for the heart of its most important and profitable product? And how could the people across the table from Apple agree to terms on these deals while being sued by them?

    Some have tried to characterize this situation as "coopetition" or the co-habitation of conflicting strategies for a balanced optimum. I find this characterization uncomfortable and unsatisfying. The balance sought will be very fragile and change daily and no optimization is practically possible. It seems contrived.

    Rather, I think about these situations as examples of asymmetric competition. This is competition where companies are rivals but they have different definitions of the basis of competition. In a way, they are like gladiators who have weapons which cannot be brought to bear or wielded effectively to counter the opponent's.

    Consider the following question: does the iPhone compete with the Galaxy SIII? Well, obviously it does. The products have similar attributes. If we define competition as rivalry in a market for similar products then, by default, they compete.

    But what about non-consumption? What if there aren't enough of either product to go around and people cannot actually face a purchase decision where both products are in front of them at the same time, under identical terms and conditions, waiting for a purchase to be made.

    It gets worse. What if there are network effects related to each product such as brand loyalty, platform switching costs, media and data tied to either one that make them impossible to switch? What if advertising spending is skewing the buyer's knowledge of competing products?

    If a product is unavailable, invisible or requires burdensome switching, does it really compete? When these exceptions are raised, you'll hear people say that Apple (or Samsung) don't compete with X or Y. They compete with themselves or with products outside the category. There may be many ways of rationalizing that  what appear to be similar products don't compete because of "differentiation" or "positioning".

    In fact, jobs-to-be-done theory suggests that the only successful competition is against non-consumption, especially if you're an entrant. Non-consumption is easy to beat (because the alternative is no solution to the job) while an entrenched incumbent is very difficult to beat, and it's often inefficient to even try even if you have the resources. This is what I describe in talks as the "David vs. Goliath" approach vis-à-vis the "Charge of the Light Brigade" approach.

    So the theory that competition exists on the de-facto basis of a similar feature set fails a whole series of tests in the real world. Consumers decide based on complex criteria and businesses actually conspire to make the choices as complex as possible reducing the decision to a single option.

    But I want to step back and think about the situation from the competitors' point of view. In other words, how should management think about competition? Is it possible to develop a competitive strategy or should one even bother with competitive response?

    Let's take a basic question: Does Apple think of Samsung as a competitor? When did it begin to think about it as such? What can it do to win?

    Let me answer this by asking another hypothetical question. Assume it's 2008 and Apple is in the process of planning its product roadmap. Whom would they decide to count as competitors? Android devices have not yet shipped and the gorilla in the space is the BlackBerry with Symbian still overhanging the market with a huge volume lead. Should they then build products to compete with RIM and Nokia?

    Assume further that their decision will define how developers will build apps and content makers will target your product. They have to account for the time scales that developers think about and they have to match hardware innovation to the rate of OS innovation and API innovation and toolchain innovation, etc.

    So did Apple consider Samsung a competitor in 2008? A time when Samsung did not actually make smartphones? It seems hard to believe they did. Now you may answer that things have changed since 2008 and they have. But the decisions made in 2008 regarding the platform remain in place today.

    Furthermore if you happen to look at the dozens of hardware designs that are making the rounds today (as evidence for a trial with Samsung) you'll see familiar designs first penned in 2004 or 2006. You quickly realize that the product design process is lengthy and largely isolated from the froth of main street (or mall) sales fistfights.

    Few people appreciate the disconnect between the design process and competition. This because few people have spent time in an organization building mass market consumer phones. The time scales are staggering. If your product is a platform product you make decisions six years in advance. If you are a "fast follower" you can make decisions six months in advance. This is maddening, asymmetric competition.

    One competitor sees one basis of competition and another sees it completely differently or sees a completely different basis. They are competing with each other but more as a guerrilla fighter competes with a nuclear missile.

    Which brings me to another discipline. In military circles asymmetry has been noted as a valid form of warfare for some time. At least since 1975. It was in use long before it was recognized or studied, (e.g. in the American Revolution.) But the situation now exists where it's taken for granted that modern conflicts are almost always asymmetric. Drones vs. insurgents and citizens vs. armor and, the most sinister of all, unarmed-but-tightly-integrated-through-communication protest against established regimes. The impact of this realization is affecting governments around the world.

    So it's time to elevate our thinking about business competition along the same lines. Yes, Apple competes with Samsung but it does so asymmetrically (as it does against Google and dozens of others). It's a multi-dimensional rivalry and one which requires a different form of analysis. It is something which I do instinctively but it's not something that is easily explained. Disruption theory helps. It turns out that asymmetric competition is the only form of competition that matters in a rapidly disrupting industry.

    It is also why this site is called Asymco.
  5. Estimating third and fourth quarter iOS shipments

    Research · 42 comments

    In the 2011 Annual Report(10K) published October 26th Apple states:

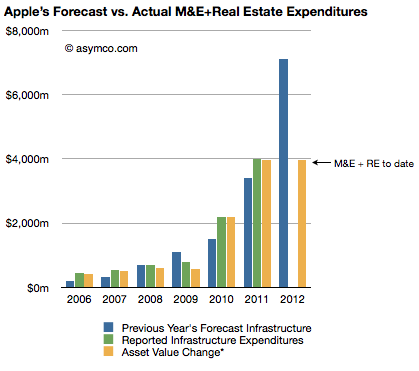
    The Company anticipates utilizing approximately $8.0 billion for capital expenditures during 2012, including approximately $900 million for retail store facilities and approximately $7.1 billion for product tooling and manufacturing process equipment, and corporate facilities and infrastructure, including information systems hardware, software and enhancements.

    The history of these expenditures is shown below (the blue bars are statements from 10K reports including the one above shown as the right-most bar):

    Three 10Q reports so far this fiscal year have given us updates on asset values and the change in these values are shown as the right-most yellow bar. The asset value change suggests $3.9 billion has been spent so far of the $7.1 billion budgeted. Thus we can estimate that about $3.2 billion remains to be spent in the fourth fiscal quarter (thus bringing the yellow bar to parity with the blue bar in the chart above--a parity that was achieved or exceeded for five out of the last six years).

    Assuming $200 million of the fourth fiscal quarter budget will be for land and buildings[1] results in an estimated $3 billion remaining for product tooling and manufacturing process equipment and data centers.

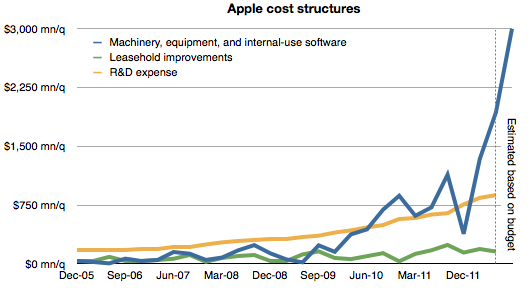
    The history of spending for various cost centers is shown below.[2]

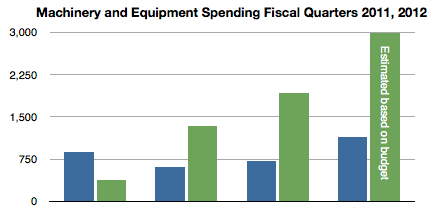
    Note again the forecast for the fourth quarter based on budget given last October. Also shown below is the spending on machinery and equipment by quarter for the fiscal years 2011 and 2012 including the estimate for FQ4 2012. (Blue bars represent 2011 quarters and green represent 2012.)

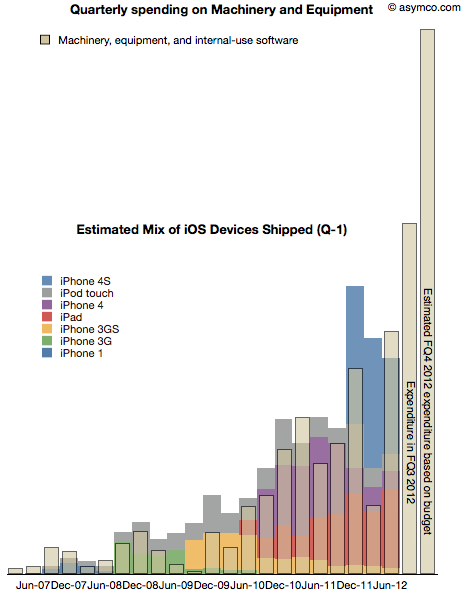
    As discussed previously, spending on machinery and equipment has shown a strong correlation with the output of iOS devices in the following quarters. The following chart shows the superposition of M&E spending in a given quarter and iOS output in the following quarter.

    Note that due to the time-shifting the Expenditure for FQ3 does not have a corresponding output--expected in FQ4--and that FQ4 expenditure is estimated based on budget.

    With this data in place, we can now begin to answer the question of what are the total iOS device shipments expected in the current (ending September)  and the following (ending December) quarters.

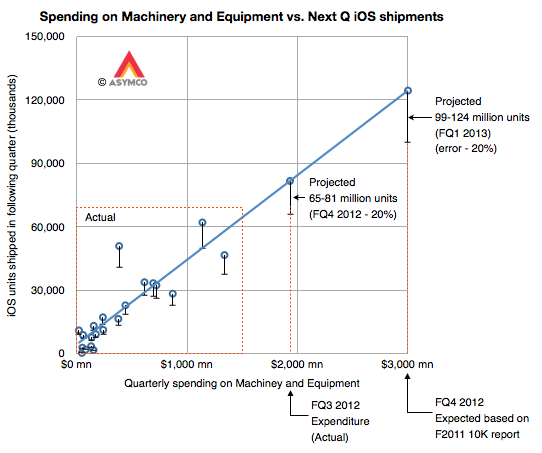
    Our eyes are pretty good at seeing patterns in data so perhaps it would suffice to know the scale to the graph above and thus fill in the colored output bars to match the spending. But to make it a bit more precise, I drew the following chart:

    It shows the same data but as an X-Y scatter plot where the X axis is quarterly spending and the Y axis is iOS unit shipments. Note that the actual data points are in the lower left area delineated with a dashed red rectangle.

    I drew the blue line corresponding to an assumed linear relationship between the two variables to project the iOS output based on additional expenditures for FQ3 and FQ4.

    I used error bars of -20% to show a possible conservative range.[3]

    This yields an iOS output of approximately between 65 and 80 million units in the current quarter and 100 to 125 million in the fourth calendar quarter. The sum of the low ends of this estimate is 165 million units.

    My current forecast is  53 million units in CQ3 and 110 million units in CQ4 which, together, add up 163 million. Close enough.

    Stay tuned for a padcast report with more details on this approach.

    ---

    Notes:

    1. The company spent $31 million, $66 million and $159 million for the first three quarters on Land and buildings. $200 million in the fourth quarter seems reasonable unless there is a pending large land deal closing in the next two months.
    2. I added leasehold improvements as a proxy for store openings and R&D expense as a proxy for overall product development. These are in contrast to expenditures for product production and support which are represented by Machinery and Capital Equipment.
    3. Note the other data points' error bars
  6. Apple's growth scorecard for the third fiscal quarter 2012

    Research · 23 comments

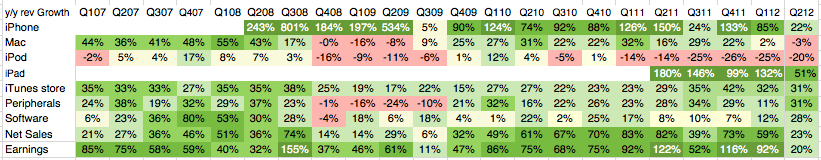
    As the following revenue growth table shows, the second calendar quarter of 2012 was not like the recent past.

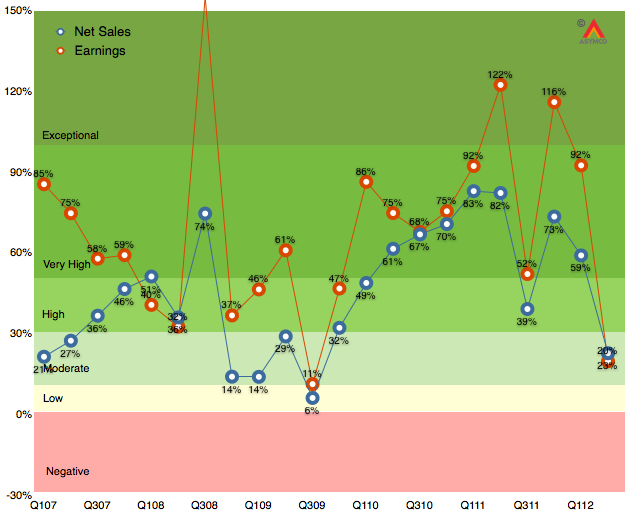
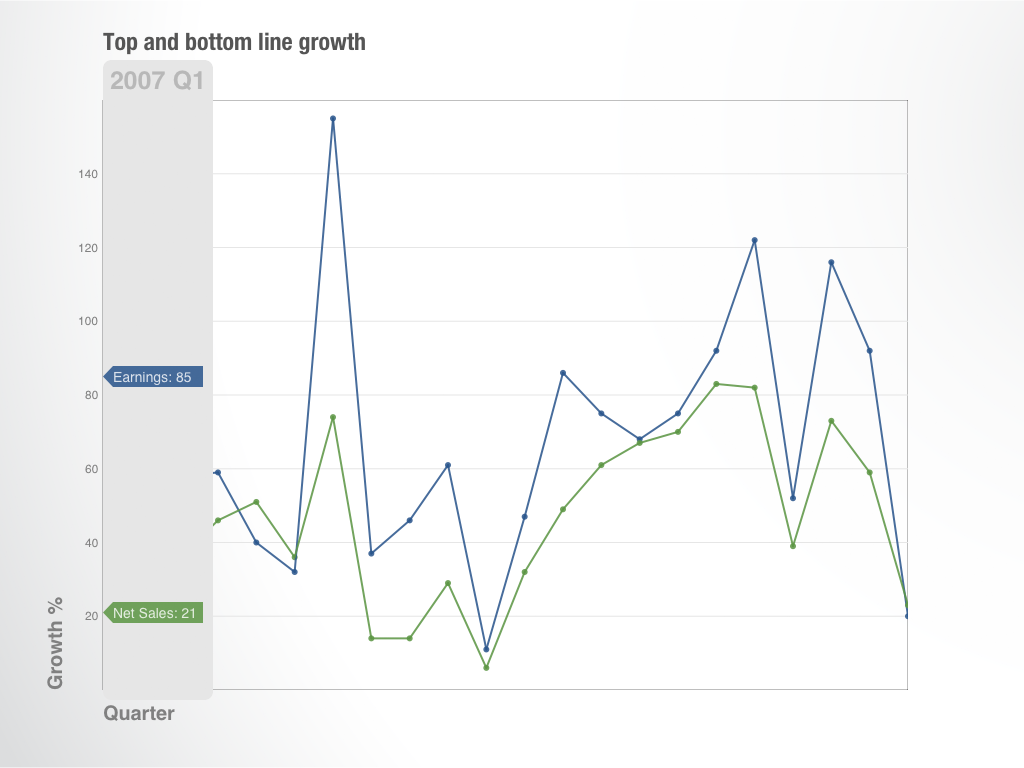
    The bottom line growth (earnings) is the slowest since Q309 which had a difficult comparison with Q308 when the iPhone 3G launched and saw 800% iPhone growth. This past quarter also had a difficult comparison with 150% iPhone growth a year earlier and 122% earnings growth.

    This is shown in a different way in the following graph:

    Growth is sometimes victim to difficult comparisons and sometimes the launch of products comes late or early in a particular cycle. This quarter was a mix of multiple factors that went the wrong way:

    1. iPhone did not get expanded distribution and was stale late in its cycle. Emerging market traction outside of China still elusive.
    2. iPad is not getting volume purchasing from institutions and spring is not an ideal launch quarter for consumers
    3. Mac portables missed a few weeks of sales due to lack of Intel components
    4. Some signs of macroeconomic slowing especially in Europe and countries dependent on commodities exports.

    The silver lining is the return of higher growth to iTunes store and peripherals. These are "hobbies" for Apple but they might form a foundation for significant new opportunities in the years to come.

  7. Scoring my performance on the third fiscal quarter forecast

    Research · 16 comments

    Did I get anything right in last forecast?

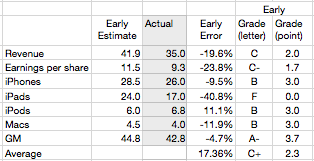
    The table below shows the scores for my various estimates[1]

    Last quarter I managed a B+ overall but this quarter was a C+. The iPad estimate was a complete failure mitigated slightly by a, directionally at least, correct call on the iPhone. The failure on iPad dragged down revenue and EPS while the accuracy on iPhone improved the gross margin. iPod and Mac estimates were consistent with recent performance.

    The error on iPad is a harsh lesson which shows how the category is still unpredictable. With only four quarters where we could measure y/y growth, and with those quarters showing 183%, 166%, 111% and 151% growth, I assumed that the 150% growth was sustainable.

    That turned out not to be the case. The iPad slowed to 84% unit growth and 51% revenue growth. It's perhaps unrealistic to expect 150% growth for more than one year. This is the main learning for the quarter and I will adjust my expectations accordingly. Overall, the product has sold 84 million units since launching in early 2010. I now expect it will sell approximately 80 million this year and 150 million units in 2013.

    ---

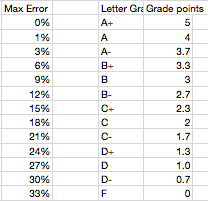
    Note: Grading algorithm is based on this table:

  8. Padcast: Reviewing Apple's Third Fiscal Quarter 2012

    Research · 56 comments

    Here is the second Perspective "padcast" where I discuss:

    1. Top and bottom line growth
    2. iPhone, iPad, iPod and Mac revenue growth
    3. iPad vs. Mac
    4. iOS product mix
    5. Other product line growth
    6. Gross Margins by product
    7. Pricing and revenue per unit by product
    8. Cash and cash growth
    9. Guidance and whether results were a surprise to management

    The discussion is an audio presentation with animated, interactive motion charts which can be manipulated by the user.

    It's available as an in-app purchase for $0.99 on the iTunes app store via the Perspective iPad app.

  9. Cracking the India Code

    Podcast · 67 comments

    In my last podcast (Impatient for Growth) I mentioned my frustration at Apple's slow entry into emerging markets outside of China. I cited Tim Cook's comments that he did not see an opportunity there in the short term. He mentioned the multi-level distribution challenge which I took to mean the difficulty in setting up Apple stores (in itself due to restrictions on foreign owned retail chains) and the absence of device/service bundling.

    This requires more analysis and the best place to start is to look at the data available.

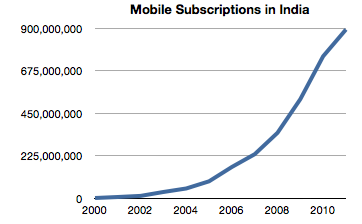
    The market potential is enormous. Globally, there are 6 billion mobile cellular subscriptions (end of 2011, ITU) and 86% penetration, but only 1 billion have mobile broadband subscriptions (which make ownership of a smartphone worthwhile).  In India there are 893 million subs (vs 986 million in China).

    In 2011 142 million mobile cellular subscriptions were added in India, more than in the Arab States, CIS and Europe put together.

    So the potential and growth are spectacular. But that is just 2G. Mobile broadband (i.e. 3G) is rare. Globally, developing countries have only 8% mobile broadband penetration vs. 51% in the developed world. Mobile broadband is a proxy for mass adoption of the iPhone (though perhaps not for Android inasmuch as it's employed as a feature phone).

    The situation for 3G in India is even worse than the overall developing world. 3G licenses were only first awarded at the end of 2010 and the process was fraught with allegations of corruption. In the year and a half since, there came to be an estimated 10 million HSPA connections in the country.

    The potential therefore is huge but the timing is difficult. Analysts are projecting 100 million mobile broadband connections by 2014 and over 350 million by 2016. Apple can affect this rate of growth as it's not only enabled by the network roll-out but can affect the take-up rate by consumers.

    It's a chicken-and-egg problem. No network means no devices but no devices may mean the network cannot be paid for. In the initial phases, the economics of mobile broadband are still dominated by the incentives for operators to pay for the infrastructure rather than for consumers to pay for the service. The iPhone will have a role to play and the question is whether 2014 or 2016 are the dates when Apple will be able to claim that they've cracked the India code.

  10. 5by5 | The Critical Path #47: Impatient for Growth

    Podcast · 40 comments

    This episode is recorded on the day after Apple's second quarter earnings release. We go through all the income statement updates and discuss what went wrong (almost everything) and what went right (precious little). We use statements by management about India to answer the question of where the emerging market potential is for iPhone. Putting aside some of the missed opportunities or bad timings, the quarter is reviewed as less than the stellar performance we've become accustomed to but not bad all things considered.

    via 5by5 | The Critical Path #47: Impatient for Growth.