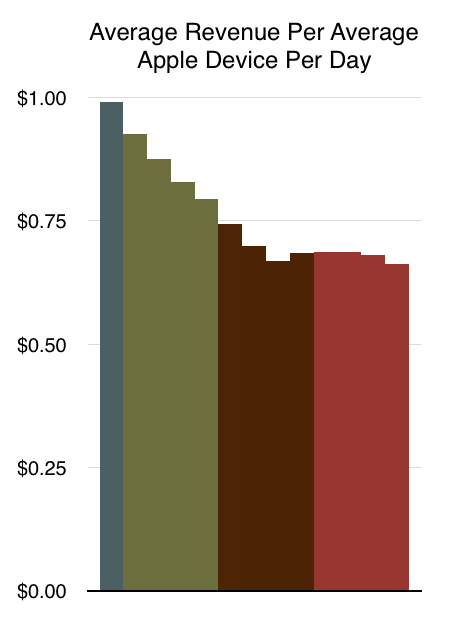Asymco

Asymmetric Intelligence

PC

  1. Wherefore art thou Macintosh?

    Research · 151 comments

    Managing the Mac product line must be one of the most challenging problems at Apple. That may not be obvious given the product's success. Consider what it has achieved:

    • The product is in its 32nd year of market presence. A longevity that in unmatched by any other PC maker.
    • Apple reached a top five position in the ranking of PC vendors. This was achieved for the first time only this year, far along in the evolution of the market.
    • With about $23 billion in revenues per year, Apple places among the top four PC vendors in terms of revenue.
    • With an estimated $5.5 billion in operating margin Apple is the most profitable PC vendor, capturing over 60% of the available PC hardware profits.
    • The product has retained an average selling price of over $1200 for at least a decade. At the same time the average pricing of Personal Computers has more than halved.
    • Although volumes have fallen for three quarters, the product grew volumes and sales for 22 out of 29 quarters. As a result, volumes almost doubled in eight years. ((The unit volumes in third quarter 2008 were 2.6 million. Eight years later they are 4.9 million and could easily be over 5 million in the holiday quarter.))

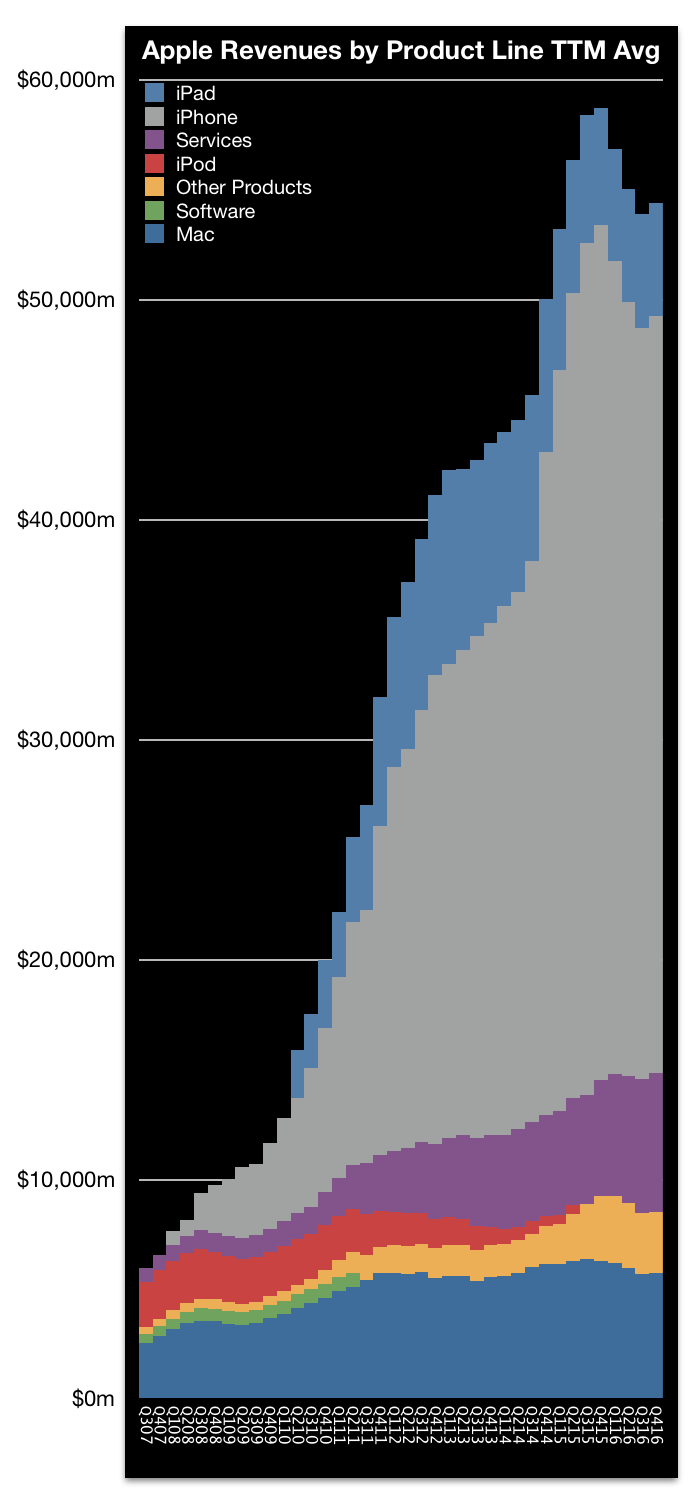
    The contribution of the Mac to Apple's revenues is shown in the following graph.
    screen-shot-2016-11-02-at-2-22-23-pm

    It's attractive and convenient to contrast the Mac with the rest of the PC industry. A David vs. Goliath tale of redemption. The classic comeback story. But the split between the two old rivals (Windows/MacOS) focuses the mind into a limited view of the computing market. The big change in computing has not been a growing Mac vs. declining PC. It has been a huge surge in mobile device use vs. a decline in PC use overall.

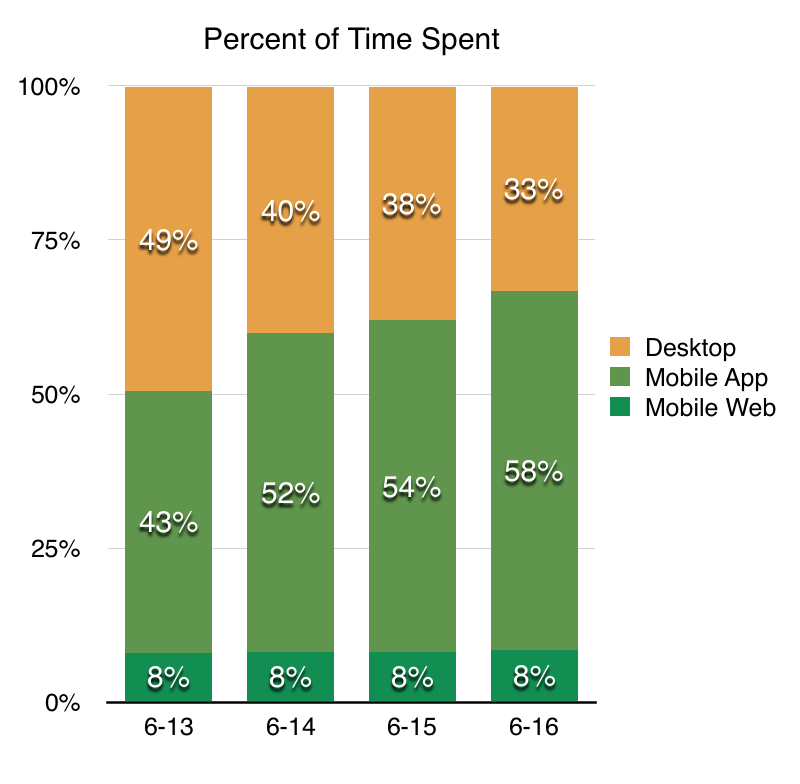
    This data is visible in many ways. Browsing data shows mobile overtook PC use this year. Shopping data around Black Friday points in the same direction. Data on user interaction captured by comScore is shown below ((Although US only, the global picture is likely to be even more skewed toward mobile as PC didn't saturated global markets before the smartphone swept to power.))
    screen-shot-2016-11-02-at-3-45-49-pm

    PC use went from half to a third of time while mobile went the other way: from a third to half of time within only four years. All the data is consistent: mobile use has swept PC use aside.

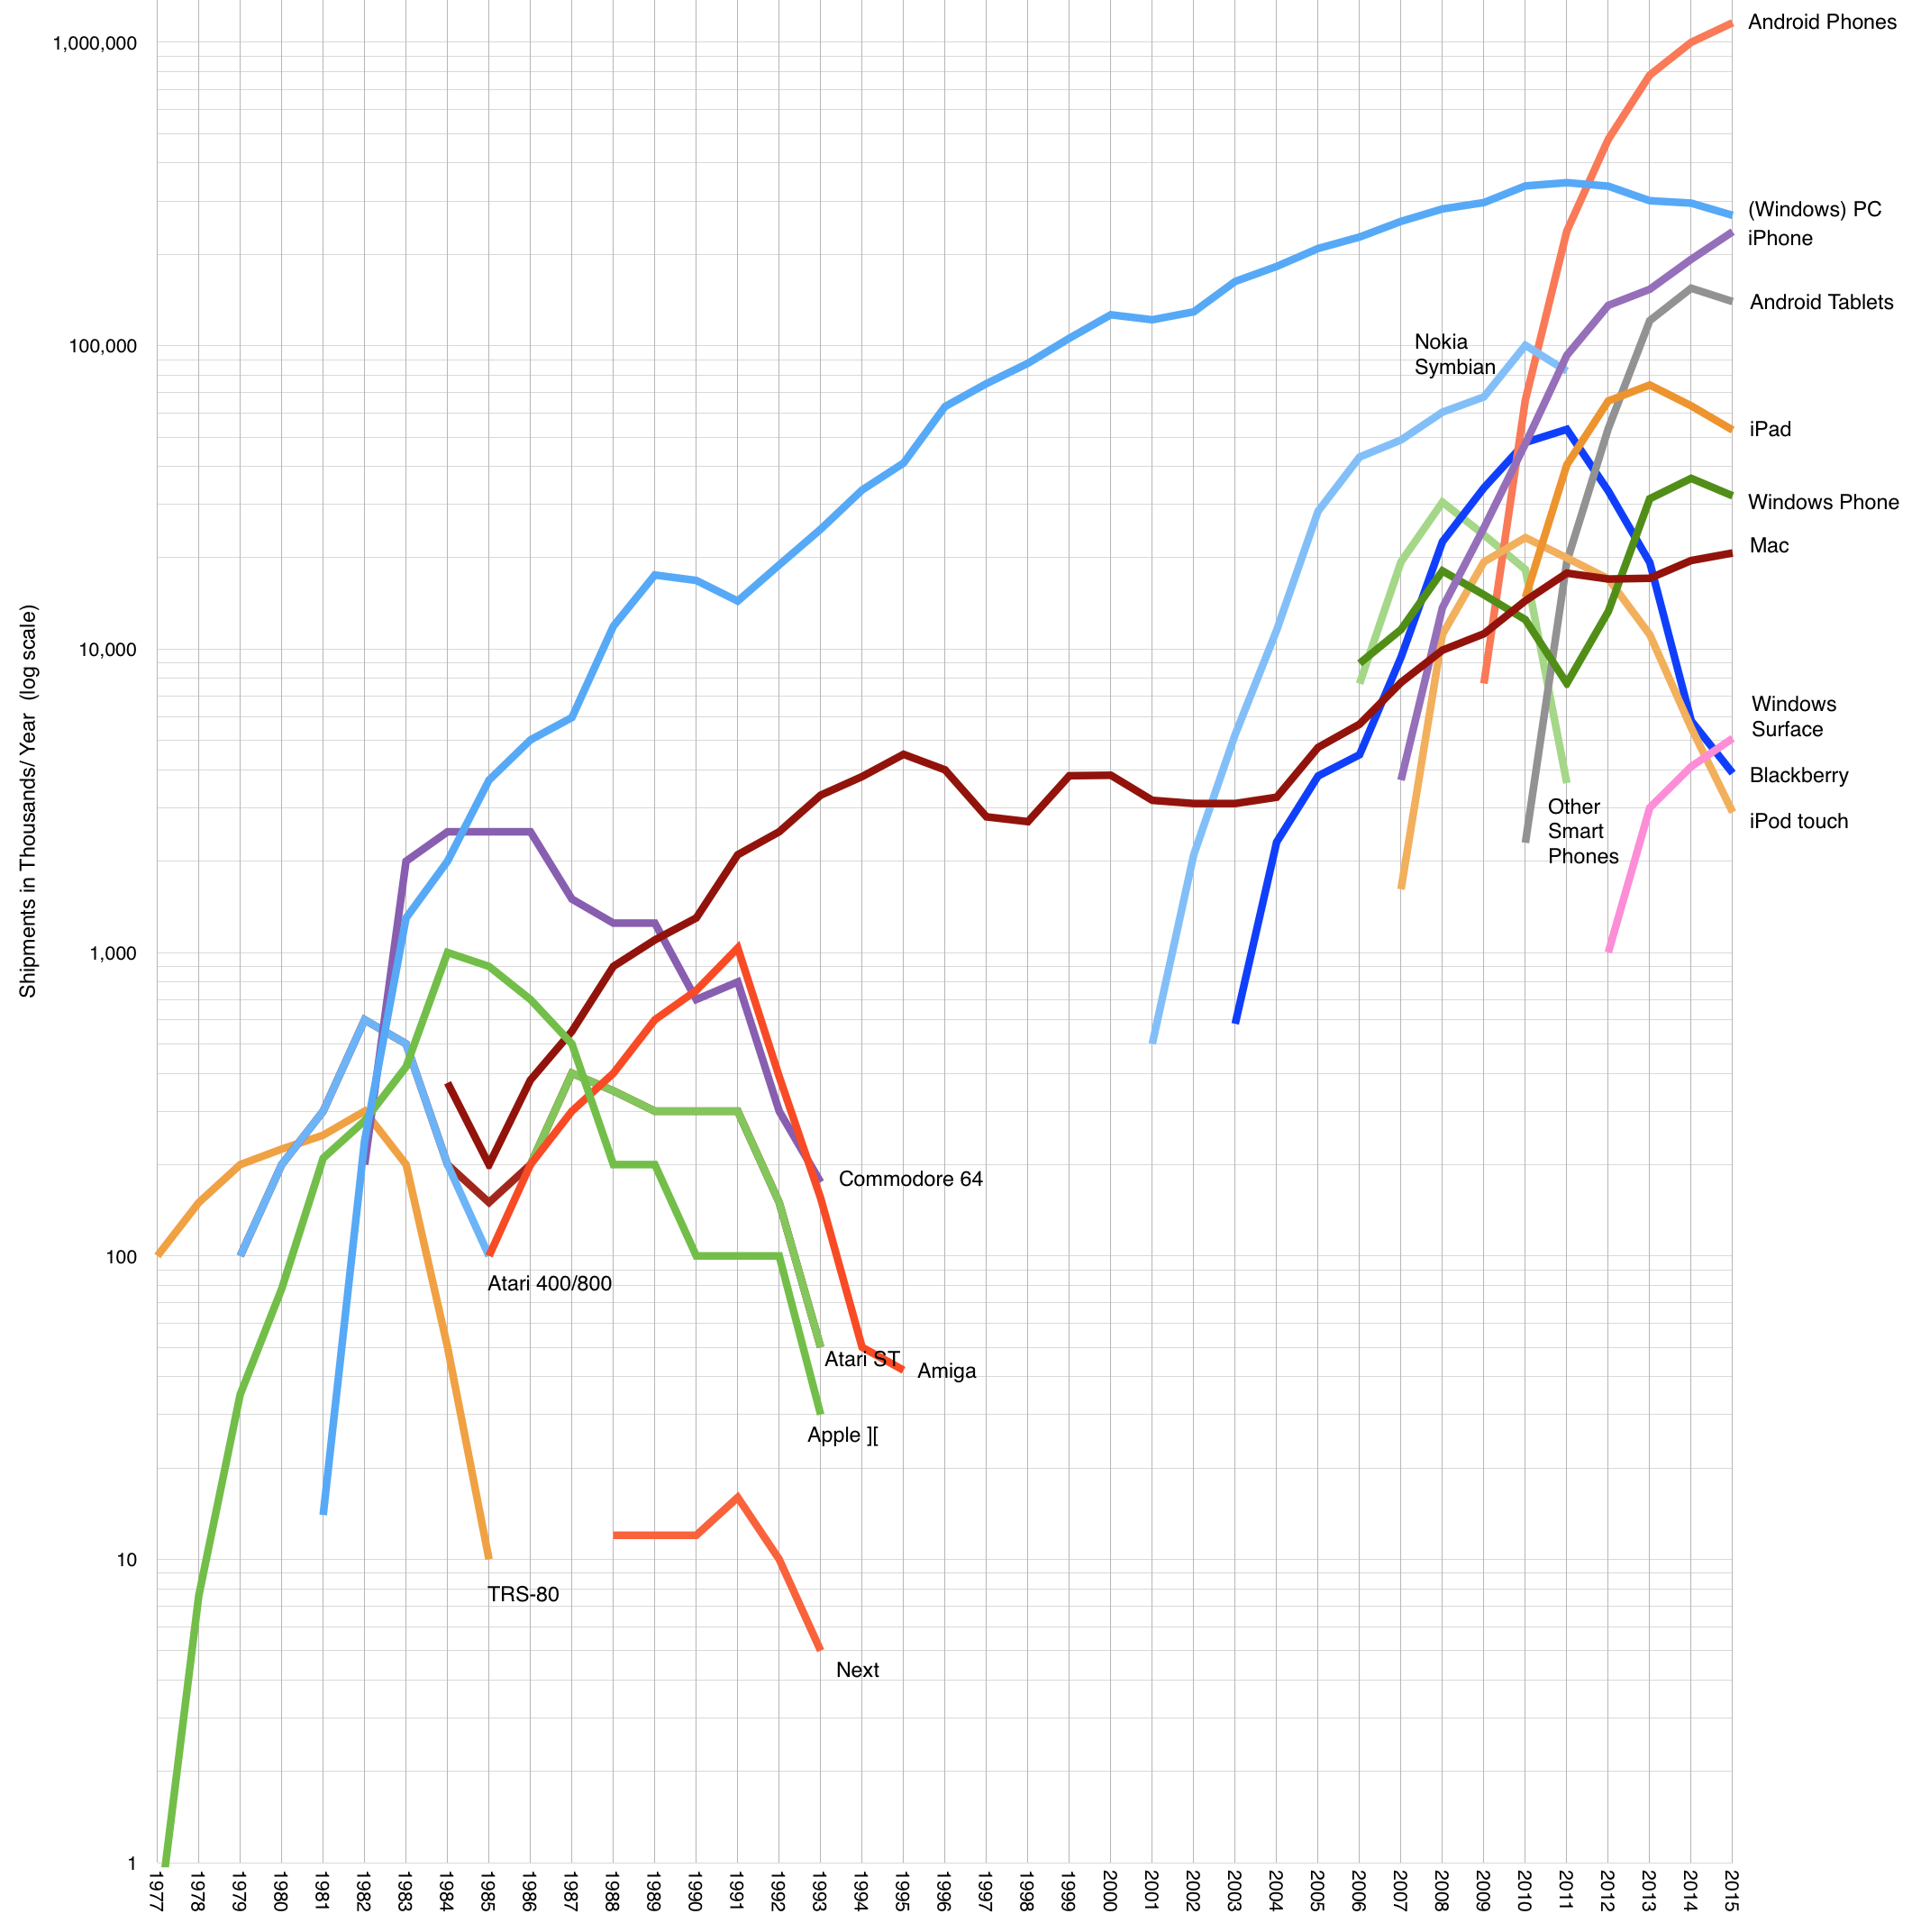
    We can see the contrast simply by placing iPhone, Mac and all Windows PC on the same shipment graph.
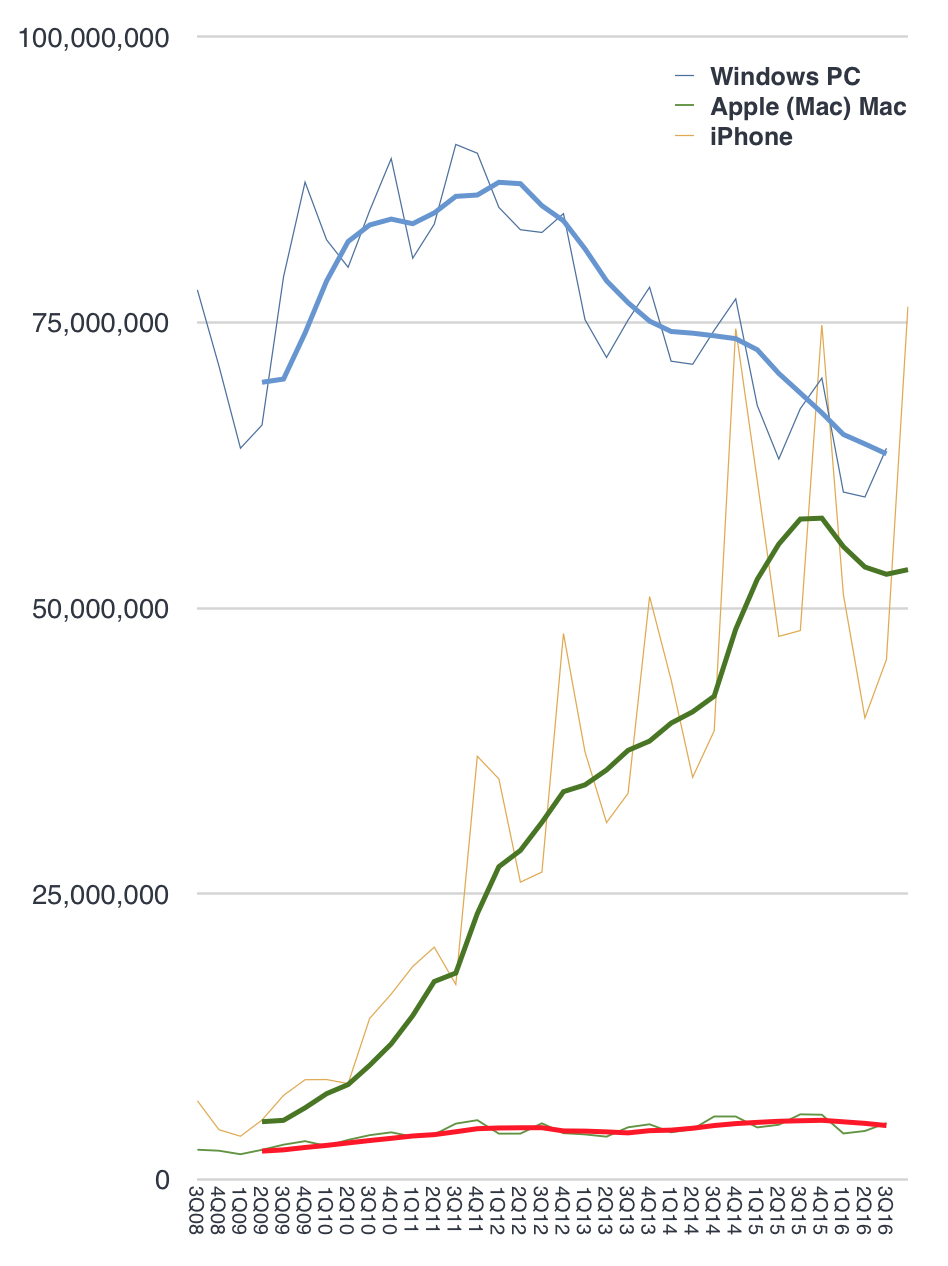
    screen-shot-2016-11-02-at-3-47-05-pm

    This contrast is spectacular.

    I bring this contrast up because I believe it is what focuses the minds at Apple. For them it's pretty clear where the puck is going. And not just now. Mobile has been foreseeable as a disruption to computing a decade ago–at least to some of us.

    And so what do you with the Mac?

    To answer this we have to ask what exactly is the purpose of the Mac in the age of the Mobile device?

    Note that this is not the same as asking what is the PC in this world. The PC is not having to share a resource pool with an iPad/iPhone. It does not have to answer for its existence to a phone. PC makers and Microsoft are not fighting with an usurper in their midst. They may see the outsider challenger but it's not an inside challenger. This makes all the difference.

    Indeed, because no usurper was allowed to emerge, PC/Windows never moved to a mobile evolution of computing. Microsoft's platform future was lost because the antibodies which eat disruptions were left unchecked.

    But Apple's immune system was suppressed. It allowed a disruptor to emerge from within. Apple gave birth to its future by suppressing the reaction to that new seemingly parasitic organism. It took an immense willpower to allow this to happen.

    But it takes us back to the question of what to do with the incumbent, the donor of DNA and resources. The parent that sacrificed for the child.

    The Mac is thus not treated disparagingly. It deserves and gets respect. It is preserved but with limited responsibilities.

    Which brings me to the question of what it is allowed to be and hence what it is. It cannot take on the role of being the future. That belongs to the touch screen devices. It will not morph into a touch device any more than a teen's parent will become cool by putting on skinny jeans. What it will do is become better at what it is hired to do.

    The key to the Mac therefore becomes that which the iPad/iPhone isn't: an indirect input device. The keyboard and mouse/trackpad are what define the Mac. The operating system, the apps, the UX, are all oriented around the indirect input method. The iPhone's capacitive touch brought about the direct input method, a third pivot in input methods (first was mouse, second trackpad/scroll wheel). Each pivot launched a new set of platforms and the Mac is the legacy of the second.

    It's not obsolete but it is a decreasing share of engagement. Alternate ways of doing the jobs it does well with direct input are emerging on the third pivot but they are not yet good enough. The children are still adolescent and making lots of stupid mistakes. There's still life in the parents.

    The management thus has to focus on how to make the keyboard/trackpad interface better while still saying and believing that the future is touch.

    In this context the newest MacBooks Pro are a logical extension of the second wave of computing while avoiding cramming them into the third wave. They are defined by their constraints. Seen thusly, the move from keyboard/trackpad to keyboard/touchbar/trackpad is pure genius.

    The touchbar coupled to the other two inputs is a totally new way to interact with computing products. It's not an "easy" interface as it's not direct manipulation. It remains indirect, a defining characteristic of the second wave. Indirect inputs are powerful and lend themselves to muscle memory with practice. This is the way professional users become productive. The same way keyboard shortcuts are hard to learn but pay off with productivity, touchbar interactions are fiddly but will pay off with a two-handed interaction model. They are not something you "get" right away. They require practice and persistence for a delayed payoff. But, again, that effort is what professionals are accustomed to investing.

    This is a leap forward and a big deal. For 32 years the UX model of the Mac has been two-handed typing with one handed gesturing. Now we have the option of two-handed indirect manipulation: one hand on the touchbar and one hand on the touchpad ((the iPad pro already encourages two handed direct manipulation)). Imagine you've been playing guitar with one hand for years and then someone lets you use your left hand. Holy cow.

    Even so, it may seem that Apple is pulling punches. The product could have evolved into the full-touch, dual screens, pen input, hybrid model of Windows. But that only makes sense if you don't have a mobile product that is promising the same and tearing up the world at the same time.

    You've unleashed a disruptive force and now you're supposed to retrofit the incumbent with the tools to compete. Why not just let the disruptor grow up unhindered.

    The Mac is what it is because it's not alone. It's part of a family. It is a parent. It strives to be better but will not take the future from its child.
  2. The Next 40

    Research · 28 comments

    In Apple's first 40 years it shipped 1,591,092,250 computers ((including Apple II, Mac, iPhone, iPad and iPod touch; excluding Apple Watch, Apple TV and other iPods. Includes Q1 shipments estimated at 63,597,000 Macs, iPhones and iPads)).

    This shipment total is higher than any other computer company in its first 40 years. Actually there are no other PC makers that are 40 years old. One computer maker (IBM) is older but they only sold PCs for 24 years and what they still sell they don't sell in high numbers.

    That does not make it the top seller in a given year. Looking at only the Mac, Apple's traditional form factor personal computer, Apple has only returned to the top 5 last year. Only if including the iPad it was the top computer vendor in 2011 and including iPhone, it was first in 2009.

    Screen Shot 2016-03-28 at 11.36.56 AM

    After having a 40 year run and after selling more computers than all American and Japanese computer companies put together, how should we think about the next 40 years?

    First, clearly Apple shifted from being a "computer company". It has already changed its name to exclude the word "Computer" but that has been interpreted as saying that it sells devices (which happen to also be computers.) The word "computer" is already archaic. We stopped using computers to compute in the 40s. We used them to make decisions, keep track of things, speed things up and then to communicate and then to entertain.

    Devices, it seems, are what customers mainly use to do, well, everything. Computing has grown to encompass most activities we engage in. So is Apple then a device maker?

    More broadly, irrespective of the name, is Apple at 40 still defined as a hardware company? Certainly Wall Street ((i.e. average people)) still think so. The conversations one hears clearly consider Apple's future to be tied to the sales volume of specific products. At one time it may have been the Mac, another, the iPod and now the iPhone. This thinking is again a legacy of where the company was but mainly it's a reflection of how revenues are reported.

    We see a line item in the income statement that says "iPhone" and it has a big number next to it so we, of course, fixate on that big shiny number. But if we were to unpack that number and see why it's so big we would discover that buyers are buying something other than what financial statements report.

    Buyers are buying experiences, I hear you say. Yes, but more than that. Much more. They are buying safety, comfort, convenience, simplicity, productivity. They are buying modules to combine with other modules that help to do something. Something better. They are buying hope, satisfaction, escape or vanity. In other words they don't know what they want but know when they have it. They trust products unseen which have a reputation of delivering that which they think they might like, without knowing what that is. By employing the product, and a whole lot more—effort, time, mental energy and repetitive actions—they learn to exploit a product to achieve satisfaction.

    Screen Shot 2016-03-28 at 4.59.14 PM

    Products are enablers, as are experiences and software and ecosystems and services. They are modules used in a melee of activity to make the user feel they are making progress. And if that module is better than no module then it will command a price and if it's better than another module or modules then it will command a premium. And if most people agree then it will be popular with many. And only if all these are true will it create a big number on a report.

    And so we must search for other names to call a company that delivers an enabler that may lead to progress. Crude categorization like the reporting of finances leads to self-deception and a loss of opportunity to understand. Firms are often victims of this self-deception because they start believing that customers buy the things they sell. They start to believe that what is on their financial reports is a reflection of the value they create. It's a simple mistake to make, but a mistake which leads to catastrophe. If its data is mis-categorized, by chasing numbers the company runs away from opportunity, leaving it to competitors otherwise unencumbered with knowledge of numbers.

    Assuming Apple avoids mis-categorizing what it does, will it be a "solutions" or "services" or "brand" company? Is it, as I used to say, a "blockbuster manufacturing line"?

    Yes, and still that's not all it could be. Nor is it enough to understand what will come.

    My simple proposal is to think of Apple (and actually any company) as a customer creator. It creates and maintains customers. The more it creates, the more it prospers. The more customers it preserves the more it's likely to persevere. This measure of performance for a company is not easy to obtain. It's not a line item in any financial report.

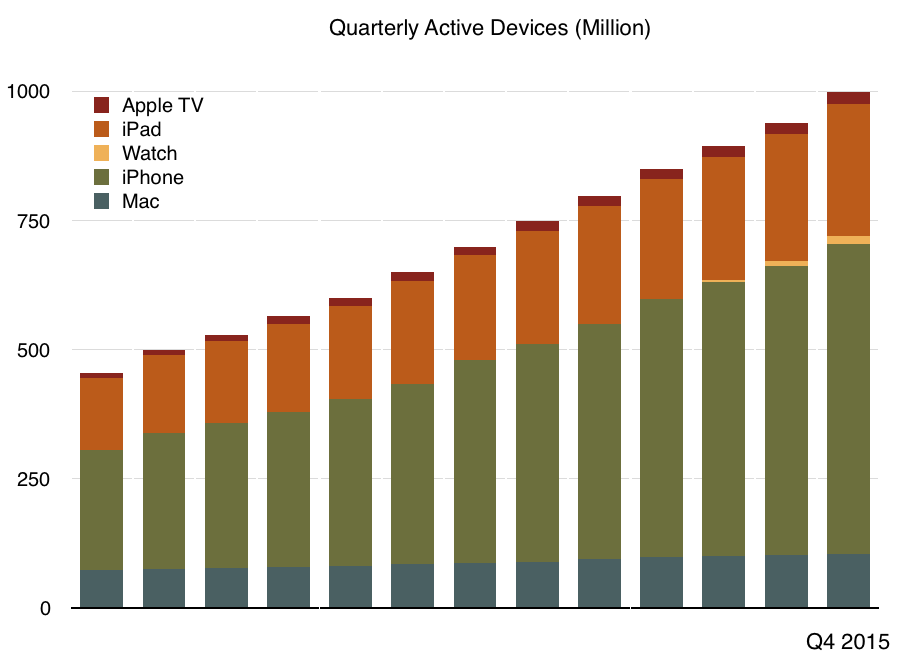
    The closest figure we have is that today Apple has one billion active devices in use. We're not told of the total users or total customers because Apple cannot count people or wallets as accurately as it can count active devices. But as imperfect as it is, this number gives us a way to get close to counting customers.

    So we know that at least Apple has created a large number of customers. Knowing total devices sold and number in use means that we can be sure that 63% of all the computers Apple sold are still in use. This means that most customers are recent customers. That is not necessarily good news. New customers are not well understood. We don't know how these new customers might behave in the future.

    Screen Shot 2016-03-28 at 12.28.22 PM

    Will they come back for more of whatever Apple makes? If we look at the history of competitors or technology products in general, chances are they won't. The industries Apple has been a part of are filled with one hit wonders. Companies which had parabolic trajectories and built no loyalties. Statistically speaking, success in Apple's markets is always followed by failure.

    But what if we did not seek correlation but looked for causation? What if we ignore statistics about companies other than Apple and focus on statistics about Apple's actual customers? Rather than assume all companies are the same, what if we assume that some can be exceptional?  What if we we look for the anomalies, not the clusters?

    We might want to ask about the causes of success or failure for a single company. We might want to sample its specific customers.  We might want to observe how Apple's own customers behaved in the past.  We might want to use theories of brand value or theories of network effects or theories of software ecosystems.

    These measures, rather than those of "comparable companies" might lead to different conclusions: That customers are loyal, that they will value the brand and that they are invested in a network. In other words, that they will buy from Apple again.

    If we then factor in the size and persistence of Apple's audience (customer base) we might conclude that there are factors which will allow it to grow rather than shrink. My analysis based on public data shows that the customer base has been increasing steadily.

    Screen Shot 2016-03-28 at 4.17.19 PM

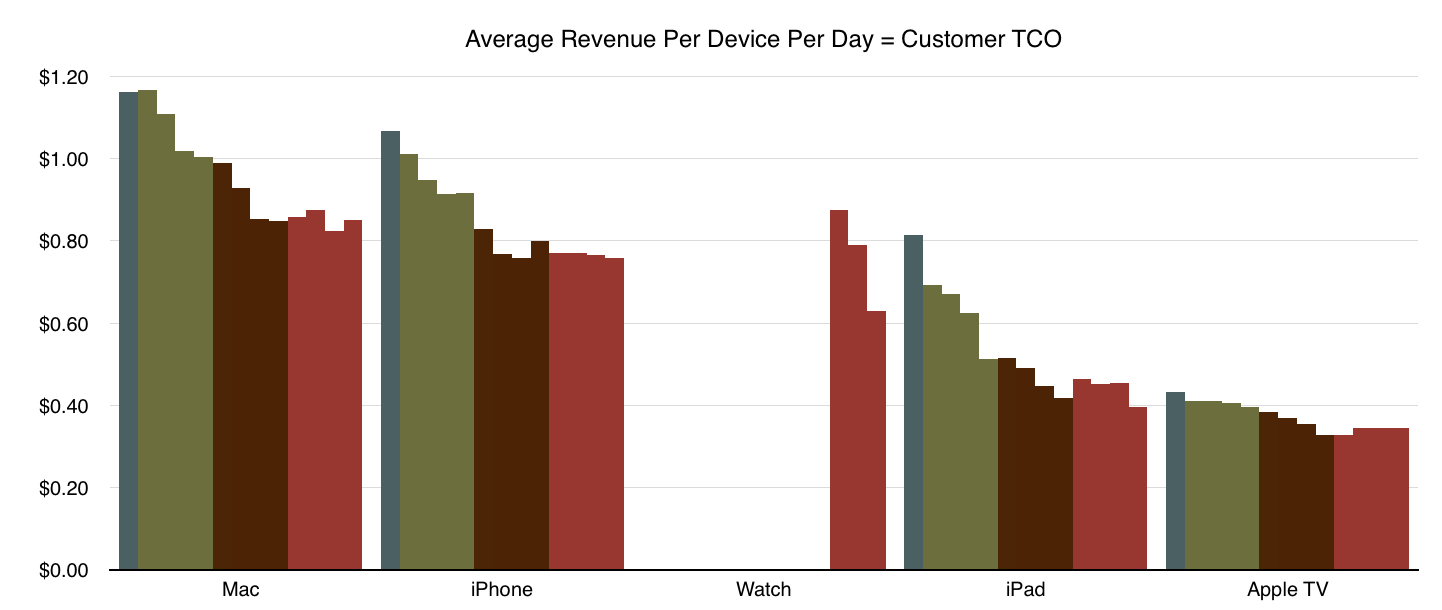
    Considering this audience and the revenues generated, we can categorize the revenue by active device as follows.

    Screen Shot 2016-03-28 at 4.15.51 PM

    Each bar represents that product's revenue per day in a given quarter (from Q4 2012 to Q4 2015). Each year is therefore represented by a different color. Dark green for 2012, light green for 2013, burgundy red for 2014 and dark red for 2015. For example, each iPhone in use was generating exactly $1/day in revenues (including services and accessories) during the first quarter 2013.

    This allocates all of Apple's revenues to these products and by proxy to customers.

    In summary, the "average revenue per Apple device per day" is currently $0.68. If we assume one unique user per device then Apple collects 68 cents from each customer each day. ((In reality the figure may be closer to $1, as there are likely to be more 1.2 to 1.5 devices per person.))

    Screen Shot 2016-03-28 at 4.19.39 PM

    Combining the history of customer creation and customer preservation with the value obtained from each customer implies that the next 40 years will be about creating another large tranche of customers whose willingness to spend on whatever Apple creates will be relatively unchanged.

    We don't know the limit. One billion was hard to imagine even one year ago. We might see two billion devices in short order. Perhaps not. Perhaps as we have a multitude of devices about us all day the number will become less meaningful. But if the number of middle class customers grows and as Apple keeps its products within their reach, there is no reason to think that there will be a reversal of the last 40 years in terms of customer acquisition.

    This analysis contradicts the current perception of the company as reflected by its stock price. That price assumes the audience will wither ((With a P/E ratio of 11, without a change in revenue per user, the only justification would be the audience shrinking by more than 90% over the next 20 years.)) That is not insanity. It is what we could expect if Apple were unexceptional.

    We could surrender to correlation and ignore causation but statistics show that such an approach rarely works.

    -------

    Incidentally, this and a lot more will be discussed at the next Subscribe conference.

  3. How iPad Educates

    Research · 20 comments

    The fact that the iPhone is contributing over 90% of the operating profits in mobile phone sales has penetrated even as far as the Wall Street Journal. However, it's not yet commonly known that the Mac captures a majority of personal computer operating profits, at least when considering the sale of hardware.

    My calculations suggest at least 60% of operating margin in personal computing hardware is captured by Apple. This is mainly due to the fact that the average Mac sells for more than $1200 while the average PC sells for less than $450.That is equivalent to $1.5 billion per quarter for Apple vs. $930 million for all the other PC makers combined.

    Screen Shot 2015-07-17 at 12.16.27 PM

    If we are to consider the iPad as a "PC equivalent" computer ((for a substantial minority of tasks)) then another $billion/quarter is contributed to the profit pool. It increases Apple's share of profits to 73%. As a result, Apple absolutely dominates computing profits.

    But, as we know, computing, even on handheld devices, is enabled by a multitude of business models. Selling hardware is one thing, but Microsoft showed that one could sweep up profits in the industry by selling enabling software. It's much harder to assign a share of profits if we try to consider all the business models associated with computing and all the form factors that computing has taken shape in.

    The problem can be acutely observed with the iPad alone. It's sold with a decent margin ((my estimate is a gross margin of around 27%)), though not one which approaches that of the iPhone ((my estimate of the iPhone gross margin is near to 48%)). It also enables an ecosystem with thousands of collaborating firms and users.

    Consider the uses of the iPad in education. 15 million iPads were sold to educational institutions. An unknown number of millions have been hired for education uses by end-users or teachers. The result is over 100,000 education apps are available in the App Store.

    The education sector's "jobs-to-be-done" has led to the product being associated with entire new processes for education. Education is not a product but a process and therefore any technologies must be hired as part of the process. In the App Store you can see the “Apps in the Classroom” guides along with impressively powerful apps being used in education. These are educator-created guides designed for other educators.

    There is no way to measure the "profit" in this endeavor.

    Nor is there a way to capture the "profit" in people engaging in exercise because they wear an Apple Watch.

    Nor is there a way to track the operating profit of HealthKit which has enabled 1000 apps to help people manage their health.

    These education and health efforts are not designed to be profitable. And yet Apple is very profitable. That is because creating valuable things generally leads to value being accrued by their creator. How that happens is not very important. Indeed, focusing of the how is actually often self-defeating. What matters is the why and the what is done.

    Understanding this leads us to understand the foundation of any great organization, not just Apple.


  4. iOS v. Windows and Immunity to Disruption

    Research · 30 comments

    The pattern of Mac growth exceeding Windows PC growth (and overall PC growth which includes the Mac) is old news. It has been observed for at least 40 of the last 42 quarters.

    Screen Shot 2015-07-10 at 12.47.04 PM

    It's a historically interesting contest, but the story of computing has moved on.  Starting with building computing, via floor computing, office computing and then to desktop computing and portable computing we are now in the era of mobile computing. ((And as sure as the sun will rise tomorrow we will move beyond mobile computing)). The problem with observing mobility in general is that there are too many mobile computing options. Phones have a wide range of capabilities, tablets and various other form factors are positioned on differing jobs-to-be-done. Platforms and services are also scattered around jobs which have been carved from fixed computing or have been established with no fixed precedent.

    So can we pinpoint with any accuracy the moment when the tipping point has been reached? We could point to all mobile phone shipments, or even the vaguely-defined smartphone shipments compared to all PC shipments. We could look at tablets alone. If we could get accurate measurements.

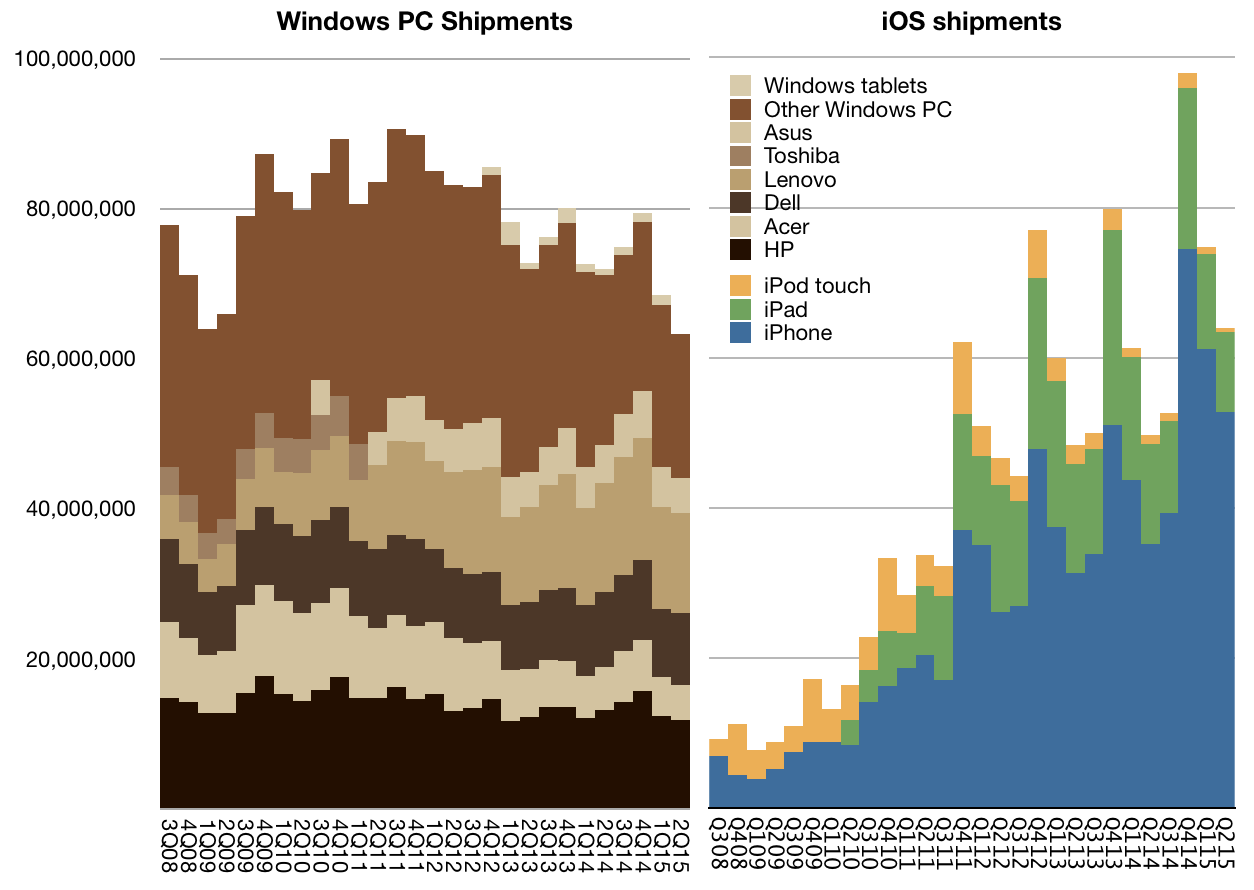
    One measurement could be to look at operating systems alone. When comparing iOS shipments (iPhone, iPad and iPod touch) to Windows we can see that combined iOS shipments exceed all Windows PC shipments for all three previous quarters.

    Screen Shot 2015-07-10 at 12.54.25 PM


    Which reminds me. This week Microsoft wrote off the acquisition of Nokia's mobile phone business. The growth of mobile as an alternative to desktop/laptop computing was foreseen by Microsoft a decade before the the data in the graphs above. It began in 1994 with Windows CE development, proceeded with a PDA operating system by 1998 and the Pocket PC brand in 2001 and Windows Mobile in 2004 and Windows Phone in 2009.

    After anticipating, predicting and dedicating decades of work why didn't Microsoft  participate in its own vision?

    The curious thing about disruption is that predictability does not result in immunity. If the new trajectory threatens the current profit formula, the trajectory is not joined with enthusiasm. There is an uncanny unwillingness to self-disrupt.

    The exceptions to this rule are so rare that they are seen as magical, enabled only by accident or catastrophe.

  5. What next for iPad?

    Research · 81 comments

    ComScore suggests that there are 100 million tablet owners in the US. On a per capita basis that implies penetration of about 30%. As a percent of mobile phone subscribers (above age of 13) that implies 40%. As a percent of smartphone users that implies 43%. As a percent of iPhone users that represents 47%. As a percent of households assuming one device per household that implies 85% penetration. By another measure (Pew) household penetration is around 50%.

    Regardless of the difficulty in defining what is the correct "addressable market", the more important question is whether tablets will be an ubiquitous object. Perhaps what we are seeing in the US is something similar to the MP3 player market or video game console markets where penetration saturated at around 50%. Perhaps tablets will reach PC levels which are closer to 80% of population or perhaps they will reach phone levels which are above 90%. The reason we can't answer the question of ubiquity easily is because competing solutions can carve the usage out of a category "disrupting" it with alternatives.

    The idea that jobs are the segments into which products fit and not demographics or product attributes is key to understanding this migration. The reason phones have subsumed more jobs onto themselves is because they have a rapid rate of evolution and because they have larger scale of economy and because they are conformable to our life spaces. As phones get better they take on more jobs and some of those jobs are those of tablets. The MP3 did not become ubiquitous because the phone took its job. Same for the video game and same perhaps for the PC and tablet.

    But tablets are also getting better. At WWDC we saw how the iPad got a lot better for in terms of multi-tasking, data entry and edits. With the addition of more screen space it will get better still. The improvements will mean that it will possibly be hired for jobs that PCs are still uniquely good at.

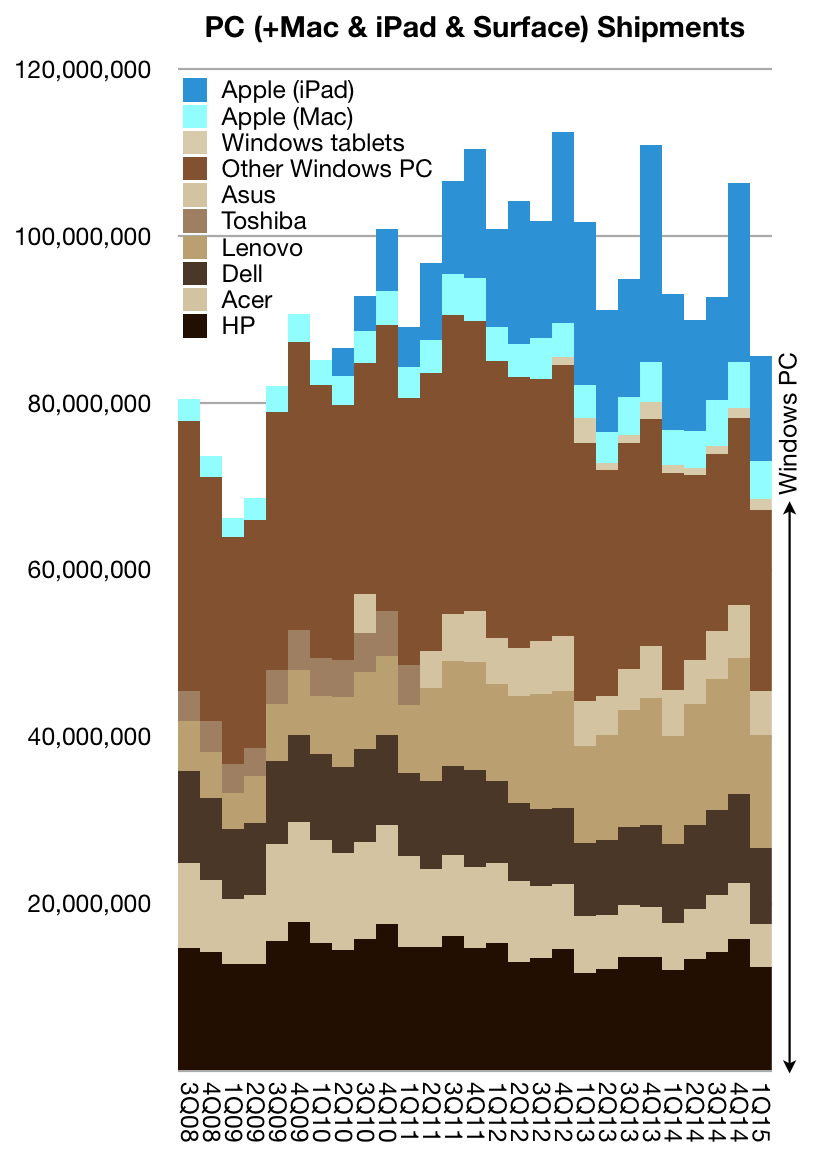
    If so then the tablets can continue disrupting PCs from below. As the graph below shows, iPads have captured a great deal of the growth of the overall "computing" market as defined by the PC.

    Screen Shot 2015-06-16 at 2.41.00 PM

    However even that growth has stalled. The combined PC+Mac+iPad market is declining suggesting that "computing" is inexorably being absorbed by the mobile phone.

    Apple management remains bullish on the future of the iPad as a PC disruption. That is certainly possible to continue, especially as PC usage in enterprises needs to migrate in order to take advantage of mobile productivity. But before we see progress we need to see the iPad get better in meaningful ways.

    The dimension of input and interaction seems to be about to get an upgrade. This is just what the product needs.

  6. The Battle for The Wrist

    Research · 41 comments

    The Apple Watch offers a hierarchy of surfaces onto which software can compete for attention:

    1. The Complication Layer
    2. The Notification Layer
    3. The Glances Layer
    4. The App Screen

    These surfaces are arranged in a hierarchy where the highest is the most accessible and the lowest is the least accessible. In a similar fashion we can consider the hierarchy of screens a person could reasonably be considered to be exposed to:

    1. The Watch
    2. The Phone
    3. The Tablet
    4. The TV
    5. The Personal Computer
    6. The Public/Work Computer

    Note that this hierarchy is correlated to the size and hence the portability and persistence of proximity to the user. Each of the screens has its own "surfaces" which expose software to the user with various degrees of ease. For instance the iPhone has Notifications, Control Center, Home Screen, etc. The OS X personal computer has the Desktop, Notifications, the Dashboard, the Browser etc.

    It follows then that software which is located at the top of each hierarchy on each device will have the greatest exposure to user interaction and that the device which has the nearest proximity to the user will provide the greatest value to software developers.

    This implies further that the most valuable "real estate" for software will be the Complication layer on the Watch.

    The software which receives either default placement there or which convinces the highest number of users to opt for placement there will have the greatest potential value. As suggested in my post on how the Watch will be valued, how software will be valued will be by the probability of its Settings being enabled for display on the Watch and its presence within Glances.

    The jostling for position within the constrained real estate on the wrist will be analogous to the competition for positioning on the phone. You'll note that the winners on the phone were different than the winners on the PC. My bet is that the winners on the Watch will be different than the winners on the Phone.

    And that's not a bad thing.

  7. Personal Computer

    Research · 34 comments

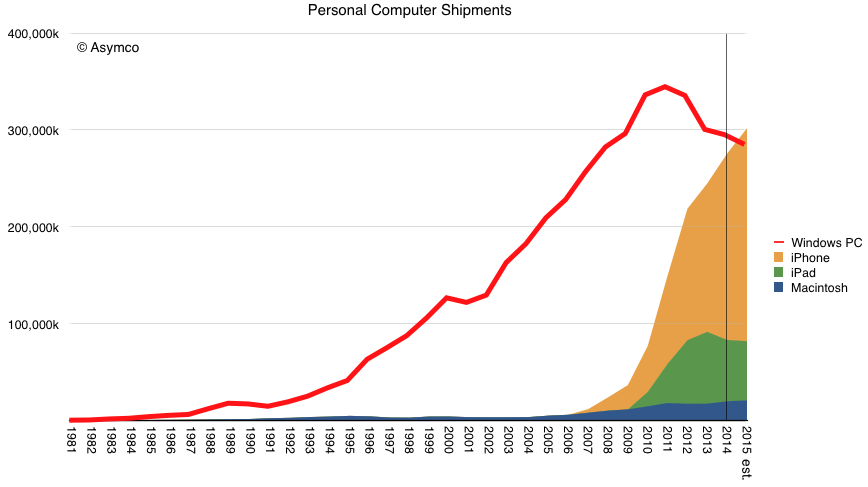
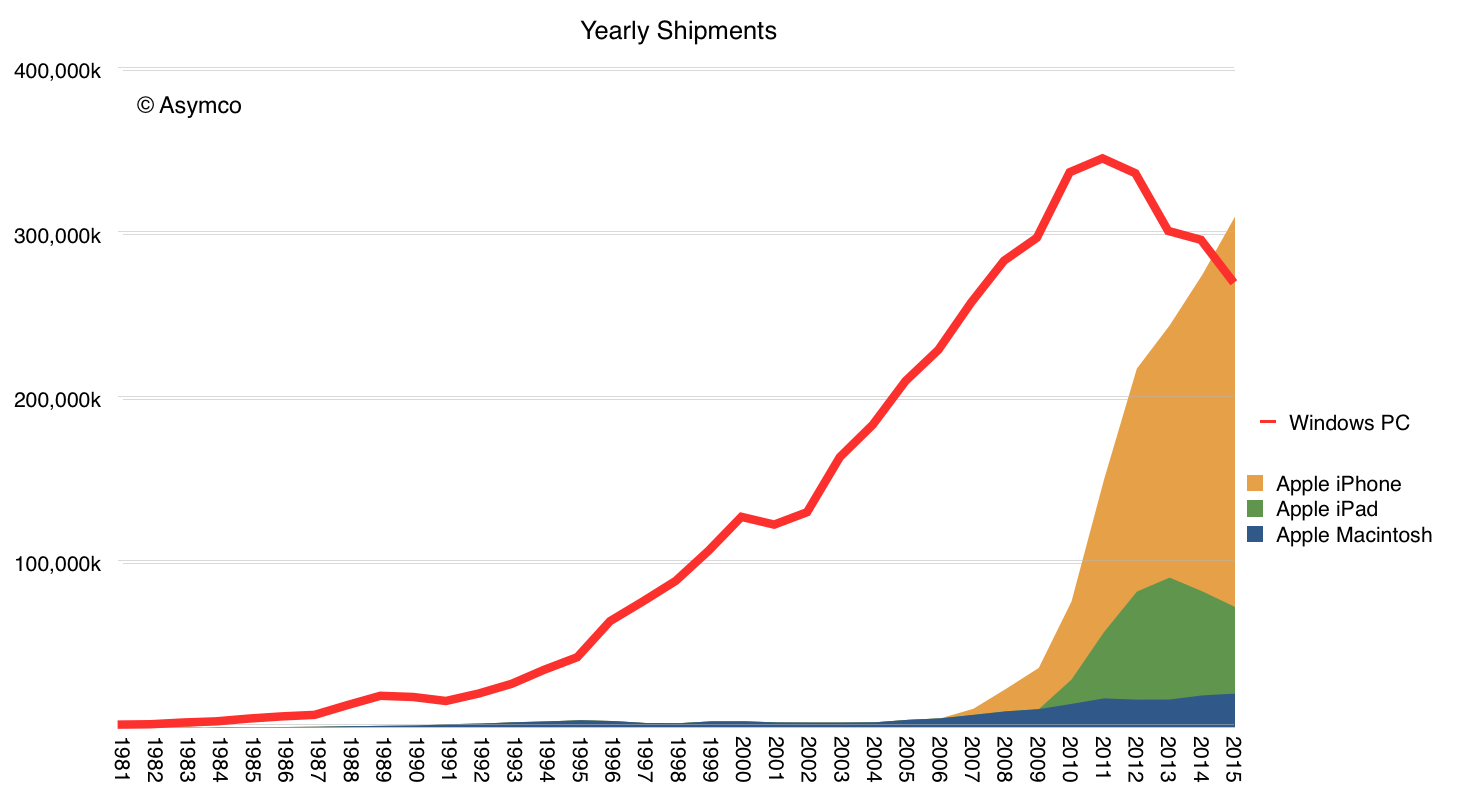
    The history of the Personal Computer market (since 1981) is shown below:

    Screen Shot 2015-04-14 at 4-14-10.55.36 AM

    Note that I added a forecast for 2015.  Data from Gartner shows Windows PCs declining at a 6% rate in Q1 with a full-year forecast of -2.4% (including OS X). Assuming 20.7 million Macs, the Windows PC market will decline to 285.6 million units (from 295 million in 2014). My estimate is that iOS and OS X combined shipments will total about 302 million.

    If this rather conservative forecast is correct then in 2015 Apple will ship more iOS and OS X computers than all Windows PCs combined ((This excludes iPod touch, Apple TV and Apple Watch. PC data is from public Gartner press releases.)) .


  8. The Monopolist

    Research · 36 comments

    When the Apple Watch will begin sales, there will have been dozens of "smart watches" released. At CES this week at least 56 "wearables" were on display. One could be forgiven for thinking that Apple's Watch will compete with at least that many alternatives. Those alternatives don't even include the entire existing mechanical and electronic watch market, which, surely, is also filled with competitors.

    When analyzing competition, it's easy to get caught up in one-on-one competitive comparisons, each posited as a decisive life-or-death battle. Consider the list of competitors that Apple has been declared as being in a death-match with:

    • Real Networks. Yes, there was a time when Apple's survival depended on success vs. alternative media encoding technologies.
    • Adobe. Remember Flash? No Flash support meant that Apple's fledgling phone would fail.
    • "The Music Industry". Unhappy partners could surely shut down the iTunes music store, and their insistence on DRM would surely cripple the experience.
    • IBM. In nearly every aspect, their business/strategy/inclination and glimmer of intent was an existential threat the Apple.
    • Microsoft. In nearly every aspect, their business/strategy/inclination and glimmer of intent was an existential threat the Apple.
    • Google. In nearly every aspect, their business/strategy/inclination and glimmer of intent is an existential threat the Apple.
    • Samsung. Obviously. But not just phones or tablets. They have control over key components that Apple used in many of its products, before the iPhone even.
    • Palm/BlackBerry/Nokia/HTC/Huawei/Xiaomi et.al. Every phone maker (and every phone) was/is an existential threat to Apple.
    • Dell/HP/Asus/Lenovo et. al. Every PC maker was a threat to Apple. Some of them made MP3 players. Some of them make tablets.
    • Amazon. Obviously. Not only as an iTunes killer but as a device disruptor. They are working on drones, after all.
    • Sony. Remember them? No longer a PC maker but they moved in many circles Apple moved in. While we're at it, add all the consumer electronics companies in Japan.
    • Dropbox. "If Apple can't do iCloud right, they're doomed".

    This is a very short list (feel free to suggest more) and it becomes clear that the total count of competitors that Apple has to counter "or else" seems to number in the thousands. Practically every hardware, software and service company is positioned as an "Apple Killer". in fact, the more interesting question might be which companies are not competing with Apple.

    Another interesting question relates to why there is no transitive property of competition. I.e. if company A competes with Apple and Apple competes with company B then it does not follow that company A competes with company B.

    To wit, whereas HTC competes with Apple and so does Dropbox, it does not follow that HTC competes with Dropbox. So it's entirely possible that it's axiomatic that

    "Most companies compete with Apple but few of them compete with each other".

    Recognizing a pattern, one could build a model of the technology world where Apple is the focus of all competitive efforts. But this starts to sound absurd.

    Indeed, the flaw in the logic is that these competitive pairings are based on the overlap of features of products/services being offered. The features become the attributes of a product which supposedly defines their competitive power. But this is false for the same reason that the attributes of a buyer do not determine their buying behavior. Buyer attributes ((E.g. demographic, sociographic))  are easy to measure and they may correlate to purchasing behavior but they don't cause it.

    Similarly, product or company attributes are easy to measure and they may correlate to competitive behavior but they don't cause the substitution of a purchase.

    Therefore, appealing to Apple to change its strategy, operations or even its core beliefs in response to a competitor's behavior is deeply misguided. The cause of success and failure in the marketplace is based on being hired by the customer to get a job done. Once hired, the chances are that the trust is secured and the relationship continues even if alternatives are available. There is comfort in the knowledge of whom you're working with.

    This aspect of trusted relationship between the buyer and the product and the interweaving of 'brand' (aka intentions) of the hired is the root of loyalty. Of course, loyalties can be betrayed and trust can be lost. But that implies that the primary responsibility of the manager is the creation and preservation of trust. When seen in this light, an alternative axiom becomes clear:

    "Great companies don't have any competition."

    Great companies are "monopolists of customer trust" and are unaffected by alternatives. They are positioned on and nailing the job their products and services are hired for. The alternatives must not only duplicate the exact job (which they almost never do), but they must also overcome the switching costs.

    Remember this when analyzing the impact of yet another competitor and considering the "Apple must fix/do X or else" assertions.


  9. Is the PC back?

    Research · 119 comments

    Gartner's own press release has an interesting spin:

    "After Two Years of Decline, Worldwide PC Shipments Experienced Flat Growth in Second Quarter of 2014, According to Gartner"

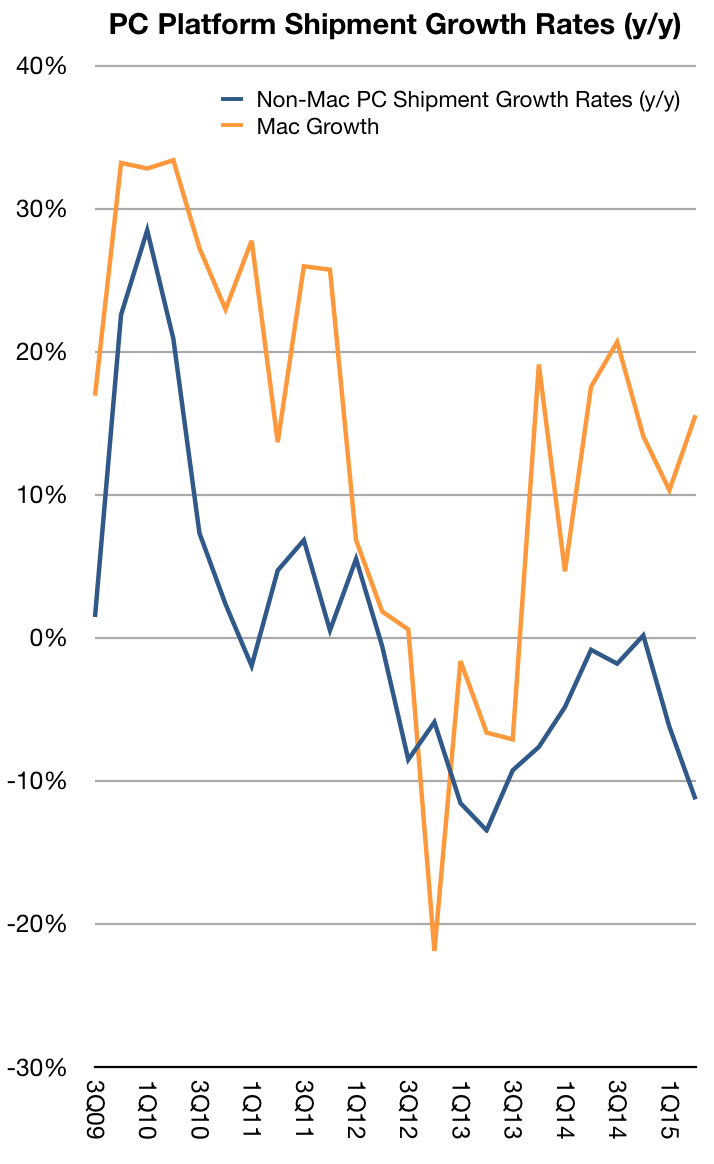
    Gartner's actual figure is 0.1% growth. Gartner and IDC measure slightly different quantities as "PC" but they don't disagree much. IDC still shows declining PC sales at about -1.7%. However both also include the Mac in their accounting of PC. If we were to remove the Mac and measure "Windows PC" ((In quotes because this total includes Linux and Chromebook)) Gartner's figures would show -0.8% drop in PC ex-Mac shipments.

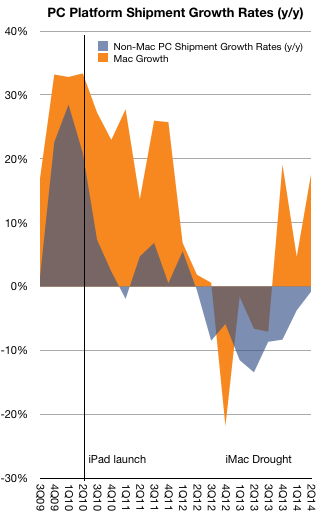
    The difference in growth between the Mac and non-Mac PCs is shown in the following graph.

    Screen Shot 2014-07-23 at 7-23-5.23.08 PM

    As Apple puts it, the Mac grew faster (and hence gained share) for 31 out of the last 32 quarters.  It missed on this perfect record during the fourth quarter of 2012 when the then fresh new iMac was impossible to buy due to production issues.

    So as far as the Mac is concerned the slowing of the decline in PC unit shipments isn't at its expense. What has been discussed as a cause for the moderation of market contraction is the expiration of Windows XP support. Certainly that seems plausible and is supported anecdotally. If it's true then the PC respite may be transient.

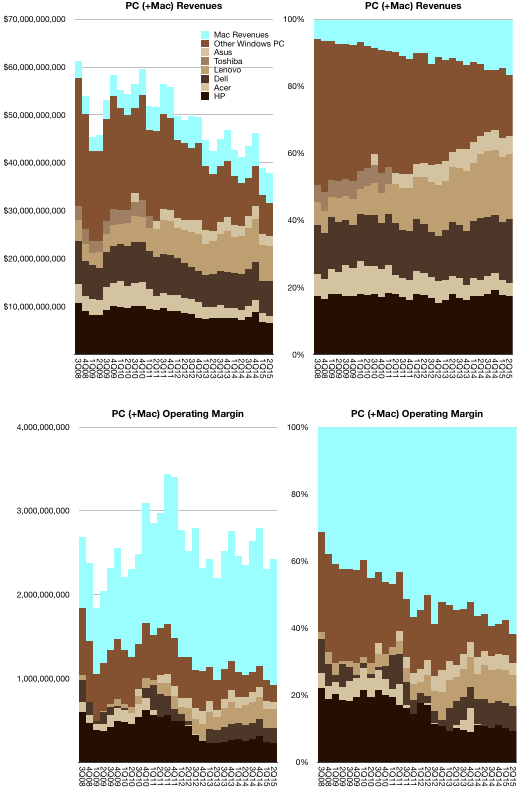
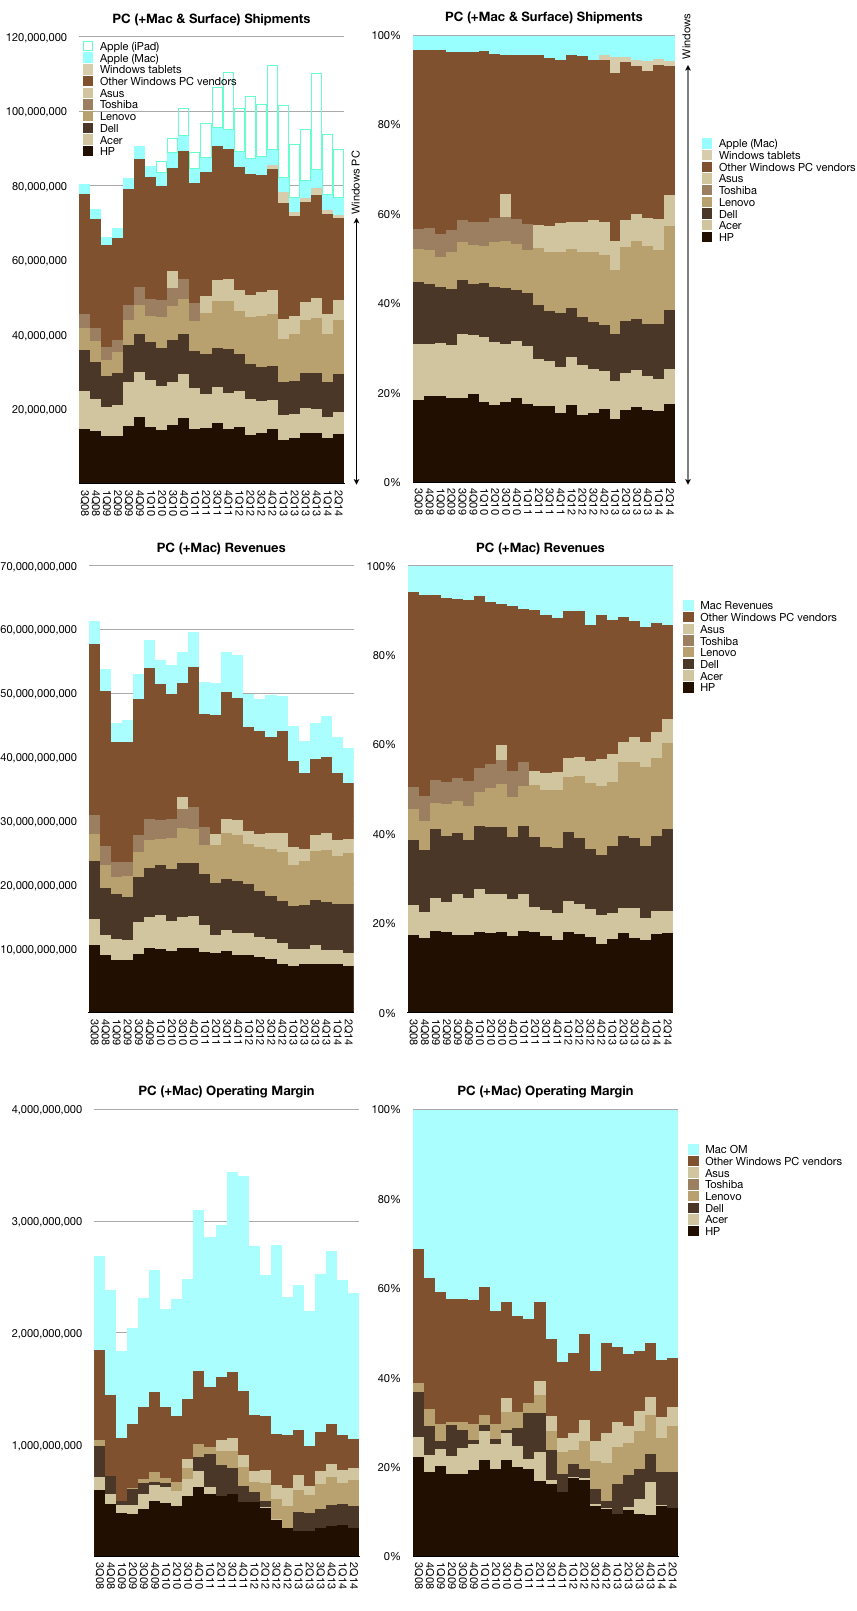
    To put a finer point on it, it would be useful to know  revenues and profits  in addition to volumes. Thanks to Charles Arthur for providing most of the data that allows this picture to be drawn:

    The revenue pictures shows that (non-Mac) PCs have been declining for almost four years and into the present quarter and operating margin ("profit") has shrunk to nearly $1 billion (while being generous with "other" PC vendors).

    Incidentally, the Mac is nearly the highest revenue PC brand and by far the most profitable. Indeed, it's more profitable than all the other vendors put together.

    If one includes the Mac, the PC industry may be limping along, but if we were to exclude it then this post conforms to Betteridge's law of headlines.

  10. IBM and Apple: Catharsis

    Research · 62 comments

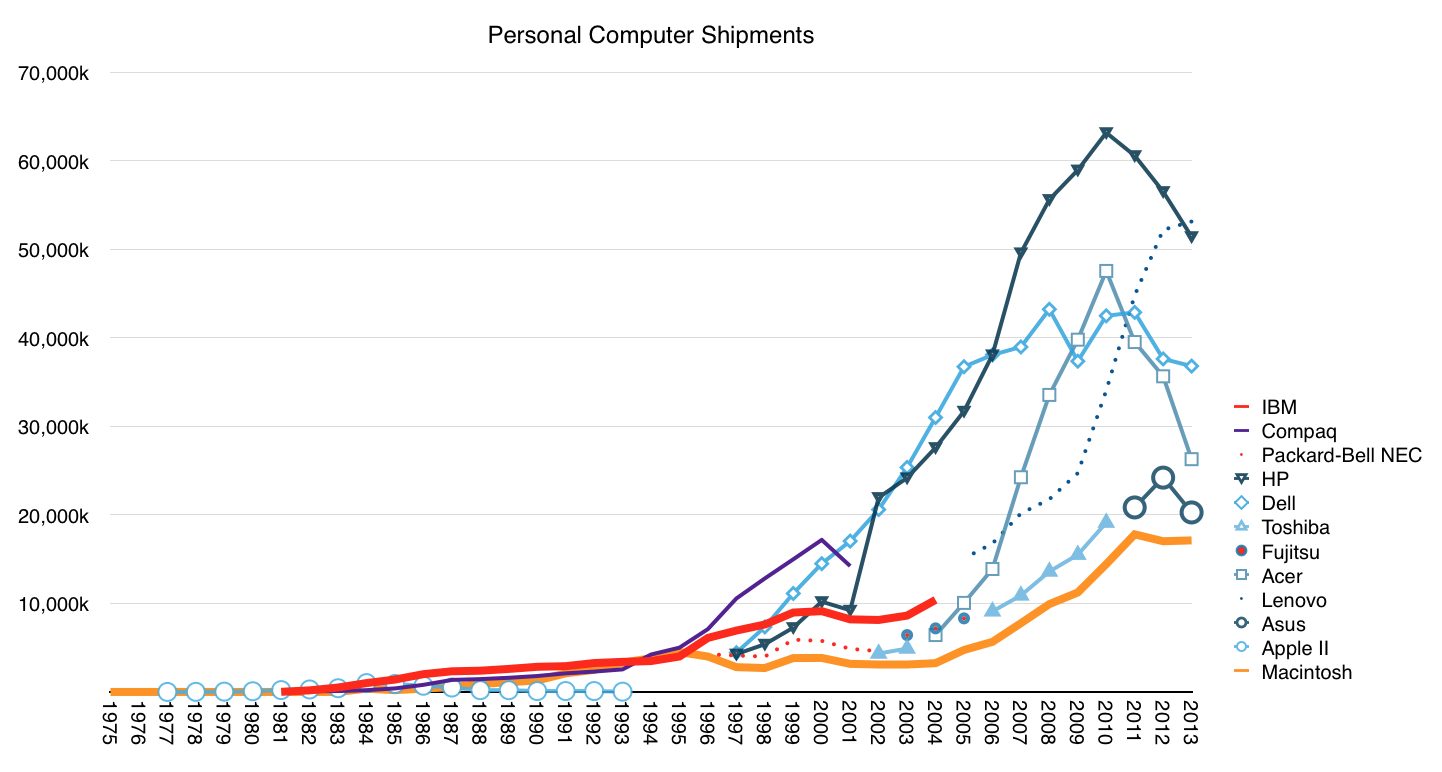
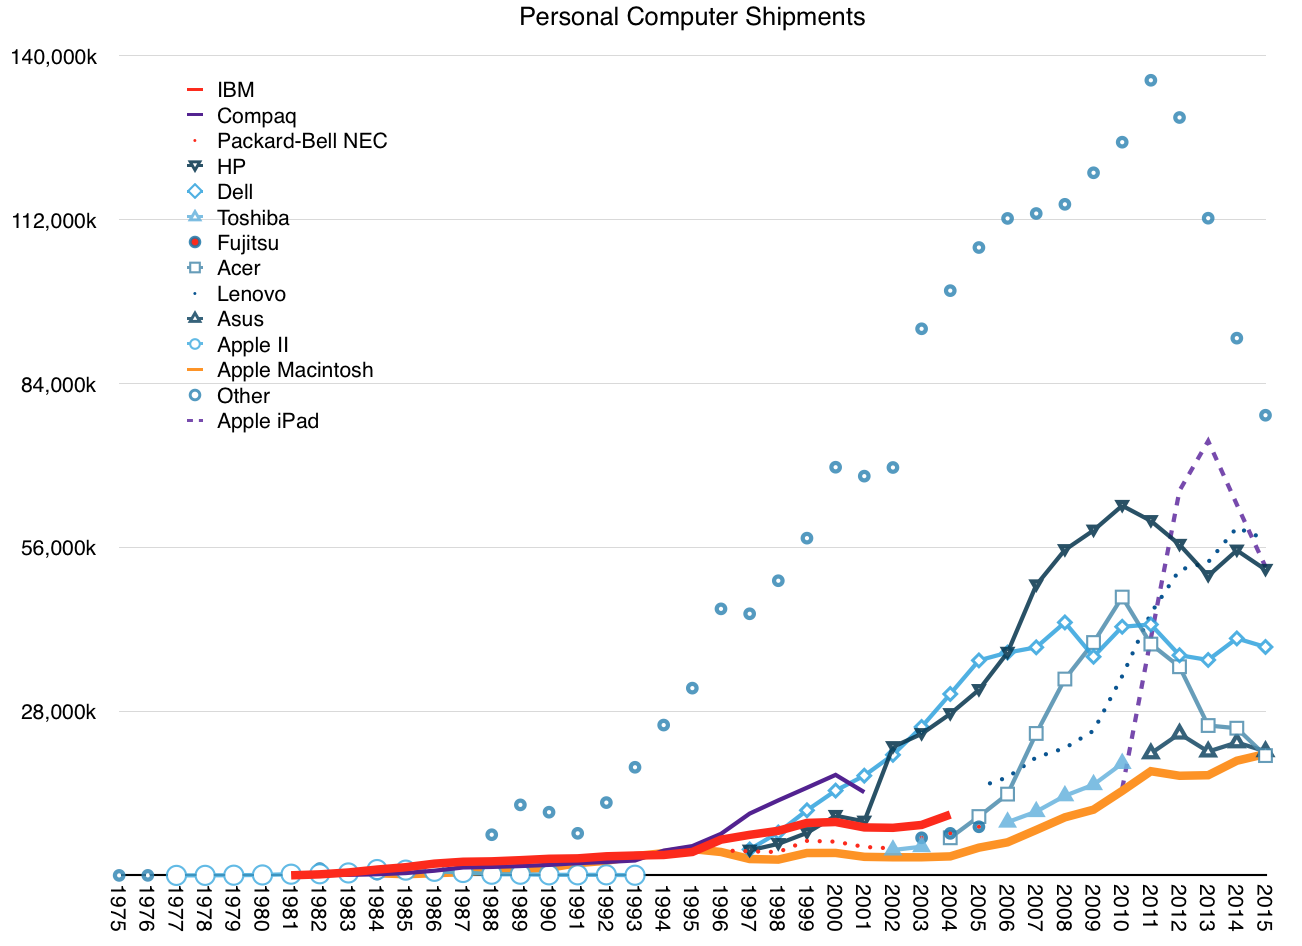
    IBM did not invent personal computing but their "PC" became synonymous with the category. Having entered the market in 1981, the IBM PC quickly became the top selling brand. From 1984 to 1993 IBM sold more PCs than any other vendor, conceding the spot to Compaq which remained on top only until 2000. No PC vendor remained at the top of the sales leagues longer than IBM. HP had the second longest run but that run was broken last year as Lenovo (who acquired IBM's PC business) surged.

    Screen Shot 2014-07-16 at 4.19.11 AM

    As the graph above shows, the period of time when IBM was dominant was characterized by far lower volumes. In 2004, the year IBM exited, they sold about 10 million units. ((as the graph shows, if we consider Lenovo as taking over from there, they did a very good job extending the legacy.)) It was a decent performance but one that did not keep up with the Dell and HP/Compaq race to the bottom in pricing and subsequent rise in volumes.

    However, throughout its position of strength, IBM was a reluctant PC maker. IBM never controlled the PC platform the way they had controlled their mainframe and mini-computer businesses. Their falling out with Microsoft over OS/2 and their attempts at differentiating with the PS/2 architecture show how uncomfortable the situation was. Their exit in 2004 must have come as a relief and, in retrospect, they should be congratulated for having exited the market well before it began deteriorating. First came pricing and margin collapse and later total volumes began to decline. Most of the remaining vendors are today in various states of distress. Lenovo is growing but incumbents like Dell, HP and entrants have come and gone (Fujitsu, Sony, NEC, Toshiba). Potential disruptors  like Asus and Acer have found no long-term success with PCs.

    This is because without control over the platform, PC hardware is nothing more than a commodity, with negligible margins, intense competition and an inability to control one's destiny.

    One company making computers did manage to control its destiny. By continuous refinement, the Macintosh survived and even thrived as the market pivoted toward mobility (and hence requiring integration that values design).  Indeed, Apple now ships over 17 million Macs a year. More than either IBM or Compaq did at their peaks. It's not in the top five globally but has a very profitable niche. ((It's very likely that it captures more operating profit than the top five vendors combined.))

    As a matter of fact, through 2013 Apple shipped a total of 156.5 million Macs,  50% more than all IBM PCs ever shipped. Apple also shipped more than twice as many iPads and five times more iPhones. And it's not just popular with consumers. With iOS Apple manages to reach 98% of Fortune 500 companies and 92% of Global 500.

    At the same time, even though IBM exited the hardware business, it remained a powerful force in computing. IBM pivoted to primarily being a service company with a vast client base and increasing global reach. It essentially moved up the value chain to become an integrated services provider to business customers. IBM's reach in breadth and depth of services is extraordinary.

    This dramatic turnaround–Apple moving to a device leadership position and IBM moving to a service leadership position–created the conditions for today's announcement of a strategic partnership--an event which is astounding to those who witnessed the 1980s and 1990s. Were it not for the tenacious independence of Apple and the business model agility of IBM, neither company would be around today to leverage one another.

    There is drama in this industry and this latest chapter has a plot twist which any poet would envy.

  11. Competing effectively against your most potent competitor

    Research · 55 comments

    New market disruptions take root in non-consuming contexts. For instance, mobile phone photography began not because early phone cameras were good. They weren't good at all but good enough when a camera was not within reach. The quality was poor but the photo taken would not have otherwise been taken, making a lousy photo better than no photo.

    The result is that the total number of photos taken this year will be ten times higher than the total number of photos taken before the advent of mobile phone cameras. ((The total number of photos taken in 2014 is likely to be around 880 billion. Prior to 2000 the total number of photos ever taken is estimated at 85 billion.))

    This rush to use the phone as a camera has meant that phone makers are keen to improve their product (so as to compete effectively with it against each other) and as a consequence they overtake the incumbent camera makers in quality as well as quantity.

    The same phenomenon was experienced by fixed component "Hi-Fi" audio products. The quality of mobile music was poor but it was convenient and convenience translated into consumption and consumption translated into quality improvement and eventually the evaporation of usage of the traditional category.

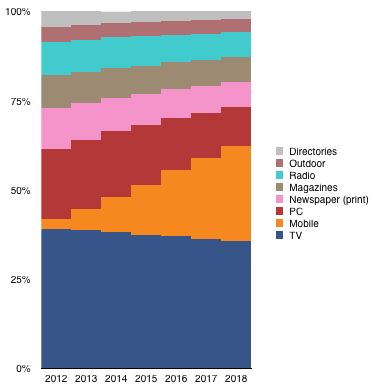
    Now consider how ad dollars are getting spent. The following chart shows the eMarketer forecast for ad spending mix across different media in the US.

    Screen Shot 2014-07-02 at 7-2-8.12.01 PM

    It would appear that the "Mobile" media is competing effectively against the other media types, especially the non-Mobile digital (i.e. PC-based experiences).

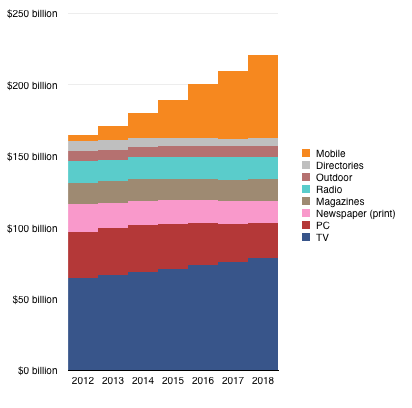
    However, if we look at the absolute spending forecast the picture shows that Mobile is responsible for most of the growth in the overall spending.

    Screen Shot 2014-07-02 at 7-2-8.13.10 PM

    In other words, Mobile is creating new consumption of ad spending. If the forecast is correct, it suggests that if Mobile was not an option, ad spending would probably remain flat.

    Mobile is capturing all the growth but it's also the creator of this growth. The reason for this is that people are consuming mobile (i.e. looking at their device screens) more without necessarily looking at other media much less. Mobile is effectively creating consumption and therefore competing effectively against non-consumption.

    Nielsen data backs this up by also citing that user "app time" on devices increased from 18 hours and 18 minutes per month in late 2011 to 30 hours and 15 minutes in late 2013.

    That's a lot of screen time which results in a lot more "inventory" of valuable ad space becoming available. Of course the ad buyers will buy the inventory. The value it provides is clear and they will increase their budgets to accommodate it. ((Note that the PC does suffer a decline in ad spending but it's not nearly as much ($8.5 billion drop) as Mobile's gain ($54 billion gain) ))

    Note that mobile phone makers did not set out to punish newsprint manufacturers. They did not set out to cause suffering for Canon or Nikon. They did not build devices to crush JVC and Pioneer or the myriad of music, photo, and print industry participants. They just wanted to make better phones.

    Because they focused on a job to be done that was not done well by alternative products they created consumption. They then used that additional consumption to expand into obvious adjacent use cases. The result was disruptive.

    There was no escape for the incumbents. The approach of making a camera into a phone would be doomed as would making an amplifier into an iPod. The outside entrant approach was the only way to "pivot" if such a pivot was even thought desirable.

    This is why non-consumption is such a difficult competitor to those in the business of serving consumers and a pushover for those in the business of doing something else altogether.