Asymco

Asymmetric Intelligence

revenue

  1. How many iPhone ``5''s will be sold?

    Research · 78 comments

    Phil Schiller stated (under oath) that when assessing sales for a new model of the iPhone, Apple used an easy shorthand:

    Each new generation sold approximately equal to all previous generations combined.

    That's a helpful gauge. Did it hold and will it continue to hold?

    In order to test this rule of thumb we need to know generational sales. Although we know overall unit sales for a given quarter, since Apple has been selling several versions simultaneously, we need to make some guesses about the ratio of generations in the mix. My guess is about 10% for 3G vs. 90% 3GS and 5% 3GS vs. 10% 4 vs. 85% 4S. That results in the following pattern:
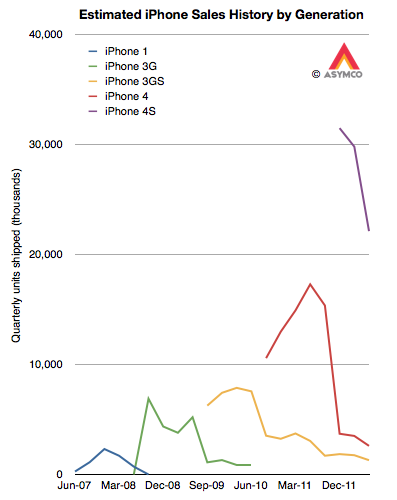
    The cumulative totals for these generations can then be generated and they appear as follows:
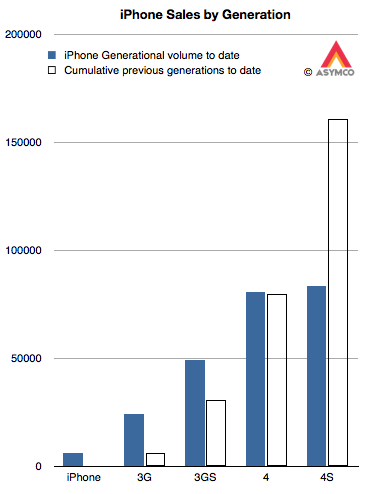
    The solid bars are the shipments for each generation (to date) and the outlined bars are the cumulative shipments of all prior generations. The assumptions show that:

    • The 3G easily outsold the original iPhone. In fact, it sold nearly four times as many.
    • The 3GS also handily beat the 3G+original total by a factor of 1.6
    • The 4 also beat the 3GS+3G+original. As the 4 may continue to sell into the future, the beat will only grow larger.
    • The 4S is only half way through beating  the 4+3GS+3G+original. Assuming the current quarter's sales roughly equal the last quarter's, the total for 4S will reach two thirds of the sum of the previous generations (i.e. 100 million) by the end of September. Bearing in mind that the 4S is likely to remain in production at least one more year means it has a potential to come close to the target of 162 million.

    This leaves us with the question of how many iPhone "5"s will sell. As it stands today, the cumulative total would have to be greater than 263 million units (including assumptions for the current quarter.) That target is shown below:
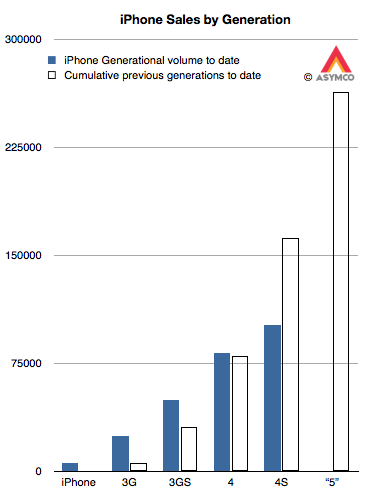
    Is that a reasonable target?

    Unfortunately, this is a moving target. As the 4S (and maybe 4) remain in production, the target continues to increase with time. However, we can still take a stab at this.

    Recall the analysis of production based on budgeted CapEx spending. It resulted in a best guess of about 165 million iOS units sold in the following two quarters. I further forecast iPhones in isolation to be about 102 million over the same period. Taking that forecast forward and assuming a 60% growth rate,  I currently have about 200 million iPhones over the next twelve months. If 85% of those are the next generation, that yields about 170 million iPhone "5"s through mid 2013.

    This is well short of a target of 265 million. But that's only over the next four quarters. If the iPhone "5" remains in production for at least as long as the 3GS then it might cross 200 million. There is also the question of whether the "mix" will begin to favor the older generations more. If that's the case, we might see version "5" meet its target.

    Underlying all this is the question of a change in strategy toward more penetration (vs. current skimming.)  That might allow for sustaining the 100% historic growth rate. If so then Apple will easily sell 250 million iPhone "5"s.
  2. Apple's growth scorecard for the third fiscal quarter 2012

    Research · 90 comments

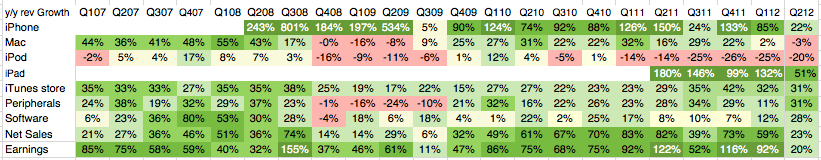
    As the following revenue growth table shows, the second calendar quarter of 2012 was not like the recent past.

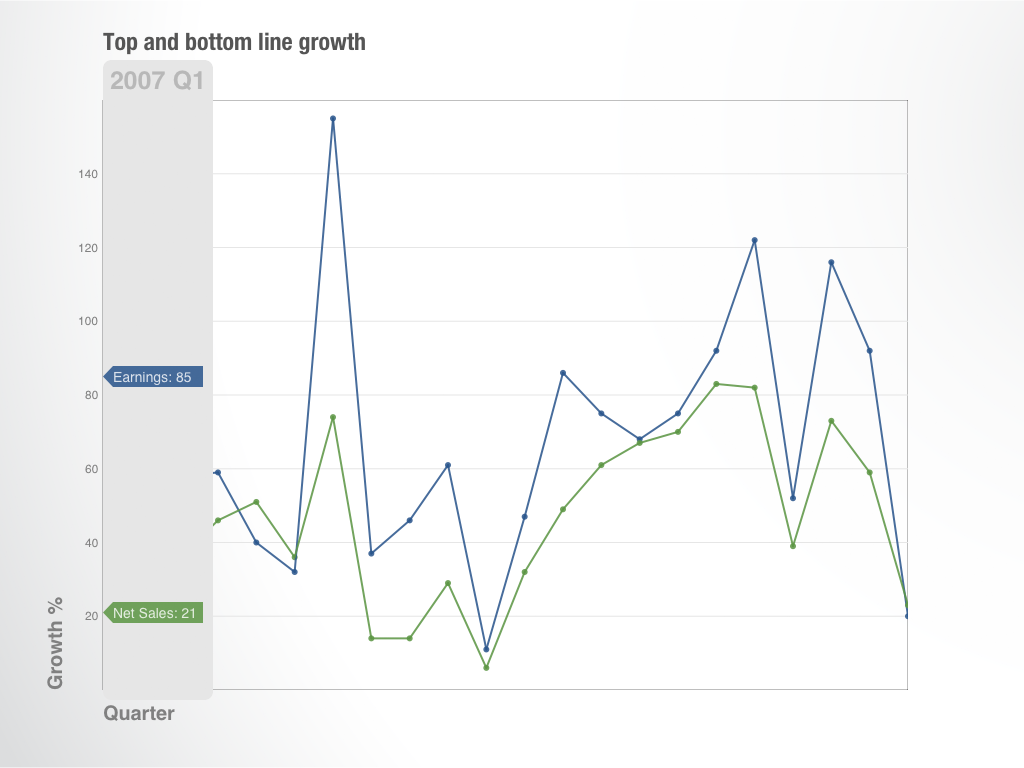
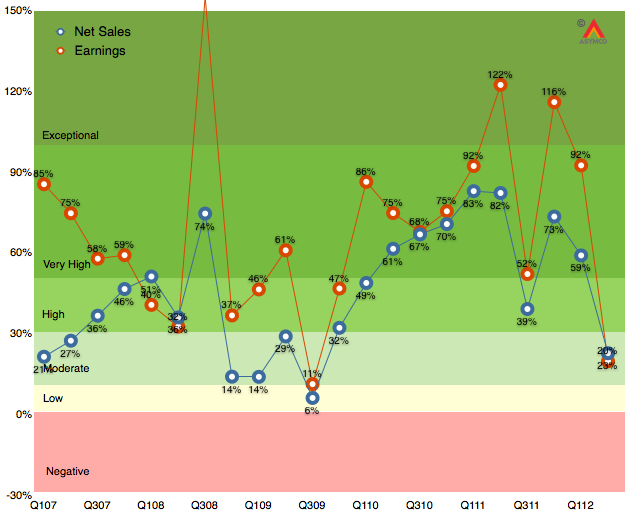
    The bottom line growth (earnings) is the slowest since Q309 which had a difficult comparison with Q308 when the iPhone 3G launched and saw 800% iPhone growth. This past quarter also had a difficult comparison with 150% iPhone growth a year earlier and 122% earnings growth.

    This is shown in a different way in the following graph:

    Growth is sometimes victim to difficult comparisons and sometimes the launch of products comes late or early in a particular cycle. This quarter was a mix of multiple factors that went the wrong way:

    1. iPhone did not get expanded distribution and was stale late in its cycle. Emerging market traction outside of China still elusive.
    2. iPad is not getting volume purchasing from institutions and spring is not an ideal launch quarter for consumers
    3. Mac portables missed a few weeks of sales due to lack of Intel components
    4. Some signs of macroeconomic slowing especially in Europe and countries dependent on commodities exports.

    The silver lining is the return of higher growth to iTunes store and peripherals. These are "hobbies" for Apple but they might form a foundation for significant new opportunities in the years to come.

  3. Scoring my performance on the third fiscal quarter forecast

    Research · 21 comments

    Did I get anything right in last forecast?

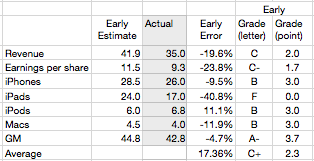
    The table below shows the scores for my various estimates[1]

    Last quarter I managed a B+ overall but this quarter was a C+. The iPad estimate was a complete failure mitigated slightly by a, directionally at least, correct call on the iPhone. The failure on iPad dragged down revenue and EPS while the accuracy on iPhone improved the gross margin. iPod and Mac estimates were consistent with recent performance.

    The error on iPad is a harsh lesson which shows how the category is still unpredictable. With only four quarters where we could measure y/y growth, and with those quarters showing 183%, 166%, 111% and 151% growth, I assumed that the 150% growth was sustainable.

    That turned out not to be the case. The iPad slowed to 84% unit growth and 51% revenue growth. It's perhaps unrealistic to expect 150% growth for more than one year. This is the main learning for the quarter and I will adjust my expectations accordingly. Overall, the product has sold 84 million units since launching in early 2010. I now expect it will sell approximately 80 million this year and 150 million units in 2013.

    ---

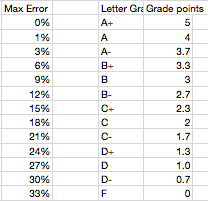
    Note: Grading algorithm is based on this table:

  4. Padcast: Reviewing Apple's Third Fiscal Quarter 2012

    Research · 59 comments

    Here is the second Perspective "padcast" where I discuss:

    1. Top and bottom line growth
    2. iPhone, iPad, iPod and Mac revenue growth
    3. iPad vs. Mac
    4. iOS product mix
    5. Other product line growth
    6. Gross Margins by product
    7. Pricing and revenue per unit by product
    8. Cash and cash growth
    9. Guidance and whether results were a surprise to management

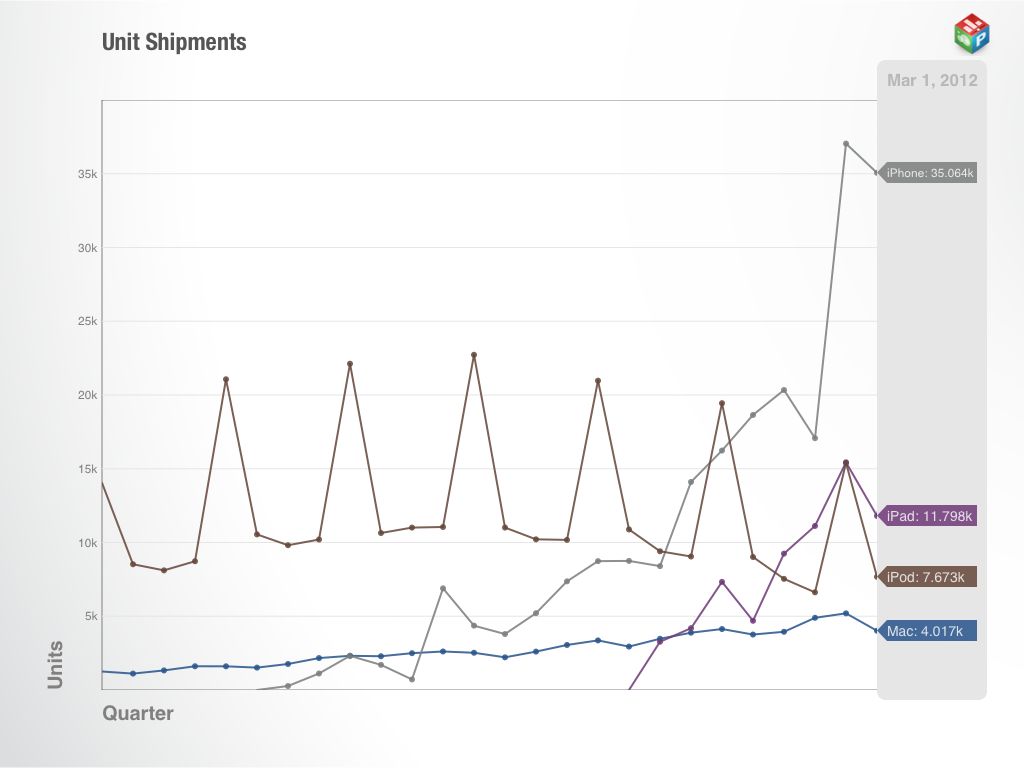
    The discussion is an audio presentation with animated, interactive motion charts which can be manipulated by the user.

    It's available as an in-app purchase for $0.99 on the iTunes app store via the Perspective iPad app.

  5. A preview of Apple's performance in Q2

    Research · 60 comments

    In anticipation of the earnings release tomorrow, I prepared a iPad-enabled audio-visual chart-based discussion of my expectation for product-level performance.

    I discuss six topics in a historic context and the reasoning behind my expectations for the just-ended June quarter:

    1. Units by product line
    2. Unit growth
    3. Gross Margin percent (profitability) by product
    4. Pricing power in terms of revenue per unit sold
    5. Contribution to revenues for each product
    6. Contribution to margin for each product (i.e. profitability)

    The discussion is packaged as a "padcast" which means you need to have an iPad and the Perspective App available on the iTunes App store in order to view the content.

    It's available for $0.99 here.


  6. How many Lumia phones were shipped in the US?

    Research · 41 comments

    The US is a crucial market for both Nokia and Microsoft's strategies. This importance was highlighted during the launch at CES in January when not one but three CEOs (Microsoft's Steve Ballmer, Nokia's  Stephen Elop, and AT&T's Ralph de la Vega) were on stage to launch the Lumia. Knowing how well this strategy is working would be very useful to understanding how this market behaves.

    My first take on this was when I asked the question How many Lumia phones were sold in the US? The answer suggested through the combination of survey data from Nielsen and comScore[1] was 330,000. The figure is quite small compared to expectations. As it's so extraordinary, it should be supported by good evidence. Unfortunately the methodology used is weak. The figure itself is probably close to the margin of error of such sampling techniques. It would be nice to have another way to calculate this.

    Today Nokia offered another set of data which might help determine how many Lumia phones were shipped in the US. (Note the shipped versus sold distinction. Companies report shipments while surveys nominally measure consumption or usage.)

    Unfortunately, Nokia did not offer specific data on US shipments. What they did offer was:

    • Global Lumia shipments were 4 million in the last quarter
    • Global average selling price was €186 for a Lumia phone
    • North American[2] phone shipments were 600k. This includes all phone types and all operating systems.
    • North American sales were €128 million.

    That's all we have. So how can this help with the question of US shipments?

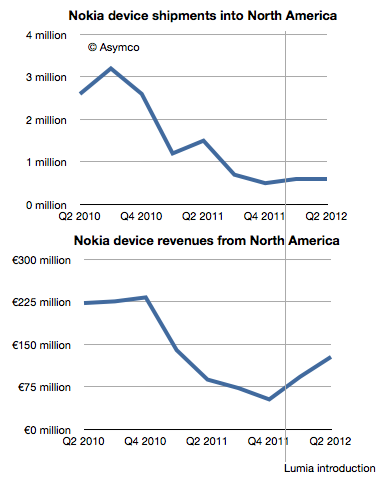
    As often happens, it helps to look at the data historically. The following charts show North American shipments and sales with the Lumia launch date highlighted.

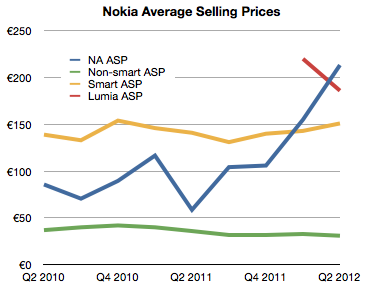
    While unit shipments were flat, revenues increased significantly. This suggests that we could plot the average selling price of phones in North America (NA) specifically. I did that in the following chart:

    Here the effect of Lumia is clear. The average revenue per phone in the US (blue line) jumped dramatically after the launch. So much so that it actually overtook the average global ASP for Lumia.

    What we need therefore is a way to estimate the "mix" or percent of smart and non-smart phones sold into North America and derive perhaps the US portion of that and then finally try to separate the Lumia from all the smart volumes.

    To help, I plotted the historic ASP for Smart and non-Smart devices as provided by the company.

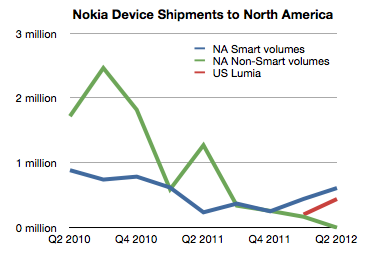
    Using a simple formula[3] it's possible to derive the mix which is shown as Green and Blue lines in the following chart.

    Getting estimates for smartphone shipments (blue line) is pretty close to Lumia shipments, but we still have to correct for US/Canada split (estimated at 90:10) and Symbian/WP split among smartphones (estimated 50:50 in Q1 and 20:80 in Q2).

    The result is the red line showing US Lumia shipments. The sum of the two quarters then comes to 630k.

    This is nearly twice the estimate from consumer survey data however I would not draw too many conclusions from this. Mainly because there are many assumptions place in both estimates, but also because there is the distinction between shipments and usage.

    However, it might be safe to say that US install base is somewhere between 400k and 1 million users. Is this good or bad?

    It's good because it's progress and there is some growth. It's bad because it's frightfully small relative to the competition. Nokia itself acknowledges the challenge and states that "We believe the Windows Phone 8 launch will be an important catalyst for Lumia."

    It seems that what Nokia needs most today is time. That is a very expensive asset. Perhaps infinitely so.

    ---

    Notes:

    1. A practice neither company would condone, principally because they are competitors, but also because they use different sampling methods.
    2. North America I take to mean US and Canada. Although geographically, Mexico is part of North America it's usually grouped as part of Latin America as a category. I'd like to get this confirmed.
    3. There are a few implicit and explicit assumptions: (a) Global ASPs are roughly comparable with NA ASPs but (b) smartphone ASPs are higher in NA by about 30%
  7. Waiting for Godot

    Research · 46 comments

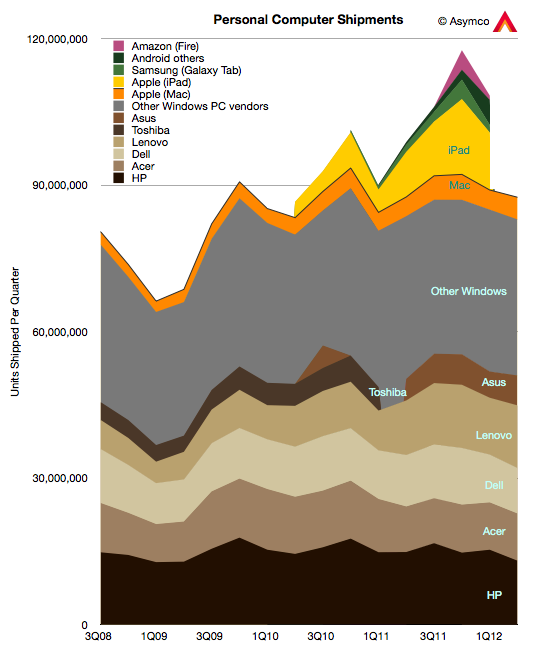
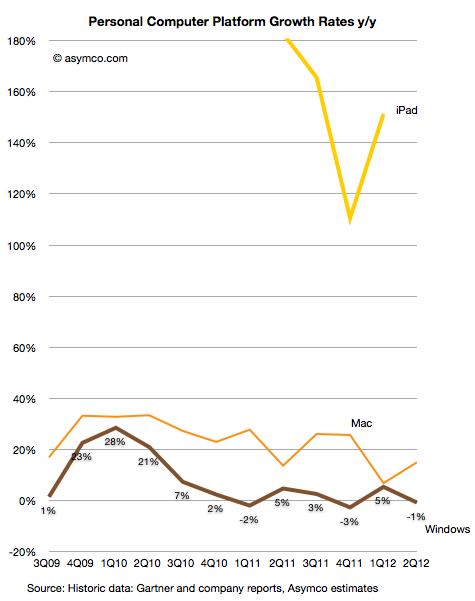
    Gartner has published preliminary PC unit sales for Q2. The data from Apple's Mac sales has not been published yet but based on some estimates, we can draw a partial picture of the personal computer market.


    My estimate is that the Windows PC market fell by 1% while the Mac market grew by 15%. Gartner reports an overall flat market. I'll leave out the iPad for the time being, and show the growth of the Mac vs. Windows:


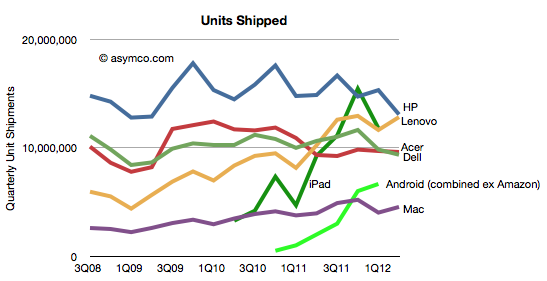
    In terms of individual vendors vs. each other, the patterns are as follows:

    It's perhaps a bit early to tell, but if the Windows PC market continues to slow or contract, it may be possible that HP and Dell will cede their market share leadership positions to Lenovo and Acer. Already "Others" account for as many units as HP and Dell put together.

    If we are to believe the analyst community reflects consensus, the industry, in the aggregate, continues to treat the potential for disruption from devices as unlikely. There always seems to be a wrinkle, a quirk, or an exceptional circumstance that is to blame. I won't get into all the excuses given by analysts for the slowing of PC sales but will point out that there's been a series of initiatives put forward by the industry to act as "catalysts" for growth. So far they have not worked. The current expectation is that Windows 8 will reverse this trend.

    Perhaps. But perhaps the relief, if it comes at all, will be temporary.

    [UPDATE: Due to a data error, the drop in Windows was overstated in the initial version of this post as 10%. It's been corrected to a drop of 1%]

  8. RIM's tailspin

    Research · 63 comments

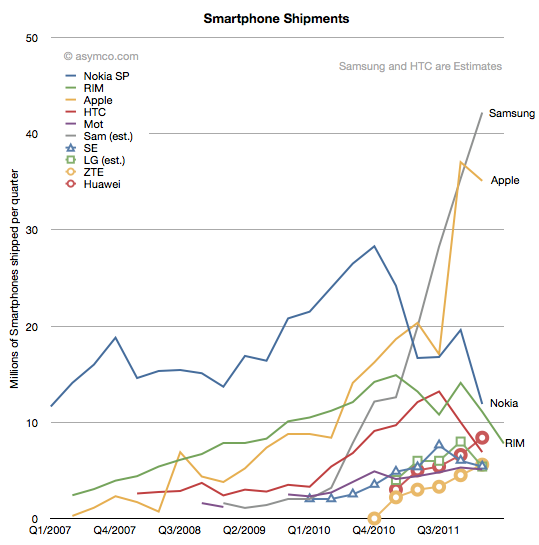
    The number of BlackBerry phones sold fell 41% year-on-year in the last RIM fiscal quarter. Sequentially the fall was 30%. Though surprisingly poor, I note that Nokia's smartphone business fell even more dramatically last quarter (down 50% y/y and 39% sequentially). LG also saw a 44% decline in unit shipments in Q1.

    The history of smartphone shipments for the largest vendors is shown in the following chart:

    From forecasts made by Huawei it's probable that they overtook RIM in the last quarter, dropping RIM to 5th or 6th ranked vendor in smartphone units.

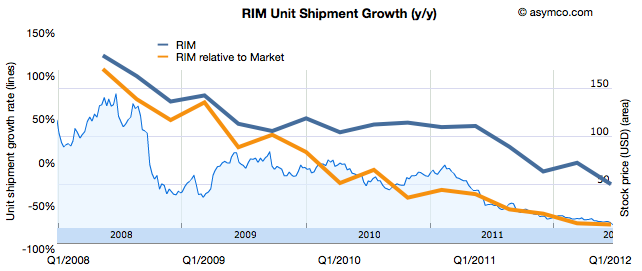
    RIM's 7.8 million units is the same level of sales as it had in early 2009. The total market was only about 250 million units per quarter then. It's around 400 million today. A quick calculation shows that RIM's smartphone market share has fallen from a peak of 22% to about 6%.

    RIM's stock performance reflects this performance relative to the market.

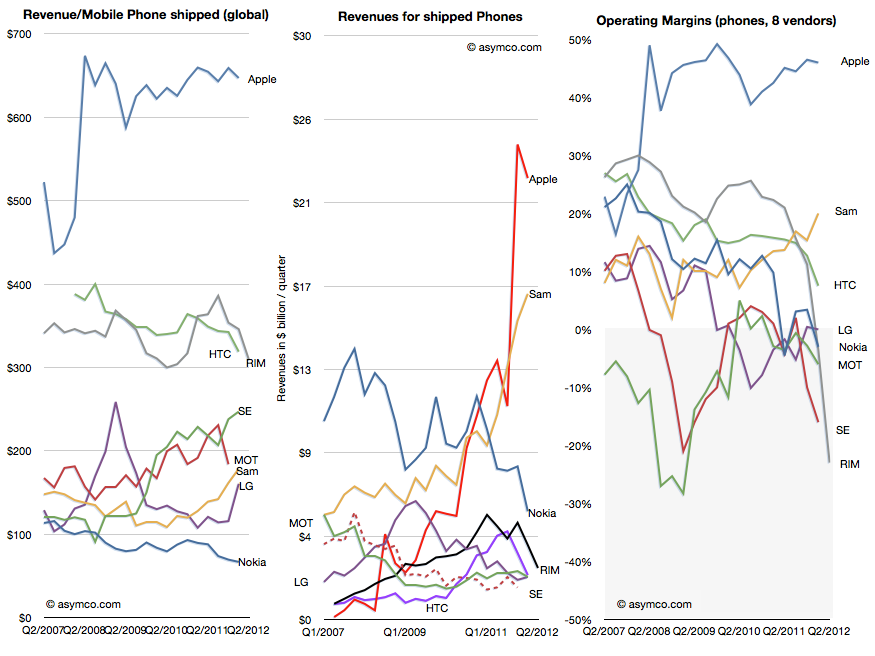
    Hardware revenues were $1.652 billion. Matt Richman calculates the average hardware revenues for the BlackBerry of $203. I include service revenues in my ASP calculations (for Nokia and Apple these are also significant values) yielding $309 per BlackBerry. The history of total revenues, revenues per phone and operating margins are shown below relative to competitors.

    Operating margin tells the most sobering story. As I've often repeated, historically no company has survived dipping into the grey zone.

    To reiterate, the logic of irrevocability in this industry is as follows:

    Success depends on three conditions being met by the vendor's products:

    • consumers trust the platform's promise
    • operator see the product as creating value to their core business
    • developers offer investment to innovate on top of the platform

    If all these factors are present, the vendor enjoys a virtuous cycle of growth. If any of these is lost, the others are also likely to be lost as well creating a vicious cycle of decline.

    Loss of operating margin is an early indicator that at least one condition is not met. Usually, a failure of consumer trust leads to a drop in purchases which leads operators and distributors and retailers to flee and then developers defect.

    It's been impossible to recover from this tailspin so far. There is a procedure which works in theory: accelerate downward by investing in a new platform. The move is counter-intuitive but essential in re-building trust, quality and relationships.

    However, the reason it does not work in practice is that this struggle is not with gravity alone. While spinning downward, the company is also subject to competitive attack. Competitors fill the void and take customers into locked-in ecosystems. There is neither the time nor the ability to defend.

    Cash runs out and customers are divided up between the survivors. Nokia and RIM face this scenario today.

  9. Activating 5.6 million units per day

    Research · 22 comments

    Google reported a new activation rate milestone: 1 million/day.

    The rate of activations has been increasing steadily which leads to a question: how high can it go?

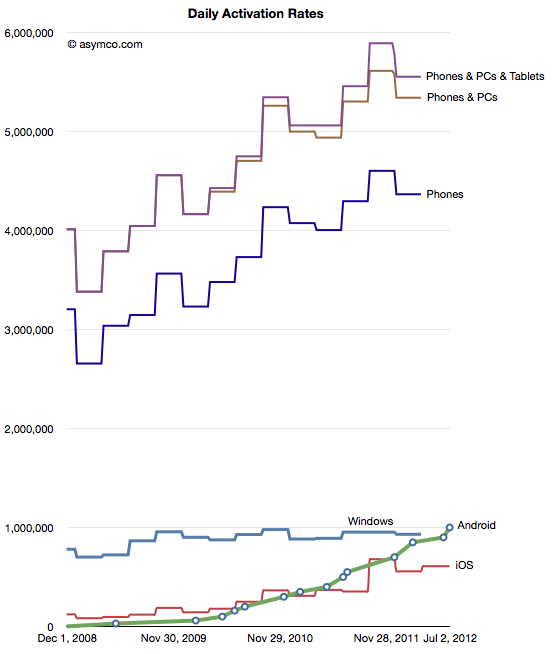
    The answer is easy to determine. It can go no higher than the sales rate of phones and tablets and PCs. So what's that sales rate? The answer is to take sales (shipments actually) per category and cast the data as "activations".

    The result is shown in the chart below:

    Defined as "activations" device and computers are being adopted at the rate of about 5.6 million units per day.

    As a percent of total activations, Android is running at about 15% and iOS is at 10%. Android has already overtaken Windows activations and with the new iPhone, it's likely iOS will do as well this year.

    In terms of available headroom this means that iOS and Android are running at a combined share of 25% of available activations.  They both should consider that three quarters of the opportunity is left to go.

    Will iOS and Android reach a duopoly in terms of activations, topping 5 million per day? Probably not, at least not without some fragmentation or platform diversification (to put it nicely). Nevertheless, 3 to 4 million per day seems an easy target to set.

  10. What will happen to Nokia?

    Research · 42 comments

    There is no shortage of information about what happens to companies in distress. The cause of distress varies widely and is often not well understood but the actions and symptoms of distress are very consistent. We can look at examples in each industry, even in each product category for a rich set of distressed company data.

    For over a year I've been chronicling the decline of incumbents in the mobile phone industry. However, decline cannot continue indefinitely. At some point a company "exits" the industry. Either through a sale or divestiture or, rarely bankruptcy. The list of exits is already long. The length and the correlation between exit and the lack of recovery implies that Nokia will also exit.

    But how, exactly?

    Will Nokia be acquired? If so, then by whom? What other options exist? How can we analyze this?

    The easiest way to guess is to look at what happened to other companies in similar circumstances. The clearest and easiest comparison to apply is Motorola. Motorola was at one time the largest phone vendor and it went through a violent decline. Like Nokia, it was diversified into networks and a few other businesses. Unlike Motorola it's not an American company. This matters because American companies are more comfortable targets for corporate raiders. The legal and boardroom mechanics are not "better" or "easier" in the US than in Europe but they are more familiar to those who might engage in it.

    So one avenue that Motorola traveled on was the intervention of activist investors who forced management change, affected strategy and pushed some tactical initiatives. This external pressure was successful in the case of Motorola. The company was split up, it was re-purposed and re-focused and, with a bit of good luck, was acquired.

    The process however still took two years. In that time the company languished but stayed alive. Its headcount was reduced by nearly two thirds. It was in a precarious situation throughout. Its story is not over but ownership did change hands and those who took a risk with it while in distress managed to get a reward.

    This example (and Sony's acquisition of Sony Ericsson and HP's acquisition of Palm) cannot apply to Nokia.  An activist investor is unlikely and the company has not yet made itself attractive to a buyer. So what would Nokia need to do to  be acquired?

    The first step toward an acquisition will be divestiture of its Nokia Siemens venture. The second will be a spinoff or sale of its non-smart phone division. The third might be the allocation of its IP across these separate entities or in a separate holding.

    As the company is broken up, value can be released. Investors will be able to value it better and make appropriate assessments of risk. Only at this point would an acquirer perhaps buy the "rump" Nokia smartphones group.

    However, even this scenario is not without huge risks. By the time the split is completed, the operating companies could have deteriorated to such a degree that they are no longer viable. Timing is critical.

    So if the smartphone group is isolated and made available, who could buy it? Microsoft is always cited as the primary buyer. I've been skeptical of this as Microsoft has found it difficult to make hardware work. It acquired Danger leading to Kin which failed. It has struggled with Xbox for a decade and has yet to recover all its costs for the effort. It has failed embarassingly with Zune. It also has shown no particular success with its original Surface table computer.

    But management has re-committed itself to a new hardware effort with the new Surface. This renewed potential opens up the possibility of entering into the integration of a phone again into their business, and Nokia would be remarkably well positioned to help.

    At this time, the possibility still seems remote. The company has dismissed speculation of building phones again and again. Unlike PCs, the phone platform is not yet mature and volumes and distribution are very different.

    However, there is one other option.

    Microsoft has historically "rescued" technology companies in distress with cash infusions for minority equity stakes. It injected some cash into Apple, Barnes & Noble and even Facebook. It did so not because they wanted to own these companies but because they wanted them to survive or thrive. The move acts as a signal to the industry, partners and developers. So what I see more likely than an acquisition is Microsoft capitalizing a spun-off Nokia Smartphones company in exchange for a small equity stake.

    The valuation of this stake will be huge as I expect billions of dollars for single digit share ownership. However, Microsoft would not be doing it to get a return from those shares. It would probably later sell them at a loss. But it would be buying a strategic option whose value may be far greater.

  11. The face and the brand

    Research · 72 comments

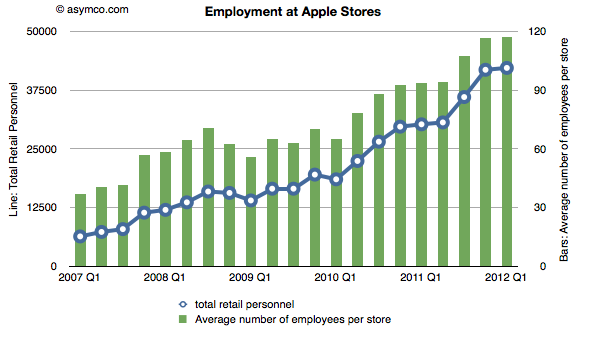
    In the five years since the iPhone launched, Apple created a total of 35,852 retail jobs.

    Some of those jobs came from new store openings. The total store count went from 172 to 361, more than doubling. But the growth in employment was faster: from about 6400 to 42,200, more than quintupling. This is reflected in the total number of employees per store which increased from 37 in Q1 2007 to 117 in Q1 2012.

    Which brings up an obvious question:  Why did Apple triple employment at each store? One could answer that many of the newer stores are bigger, so-called flagship stores. But the vast majority of stores are in mall locations which are of limited size. Flagship stores alone cannot account for the increase. One could also suggest that perhaps the stores are open longer and there is a need for more shifts. Again, the vast majority of stores are constrained by the opening hours of malls which, as far as I know, have been steady. Anecdotally, it's also evident that there are more employees in a store at a given time. There are many more of those colored T-shirts at first glance.

    One hint is in the design changes in the stores. Apple has removed shelving, registers and almost all non-Apple merchandise. It has replaced the visible stock with tables on which rest products that can be used. If there weren't any people in the store, the store would look almost completely empty, just an open space.

    But that's the whole point. The stores are designed to be filled with people. The stores have an open layout because it allows more people to be inside the store at the same time. And the more people the more employees.

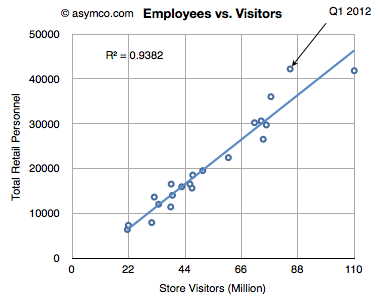
    We have the data to prove this: The visitors per store per quarter increased from 125k in Q1 2007 to 235.5k last quarter. Nearly double the number of visitors in five years. It's this increased traffic that is closest tied to the increase in employment. This is illustrated by the following chart:

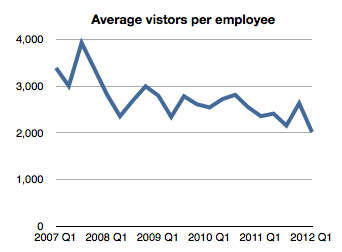
    Employment is very closely correlated with total visitors. In fact, employment has risen faster even than visitors. By dividing the number of visitors by the number of employees we see how the number has declined.

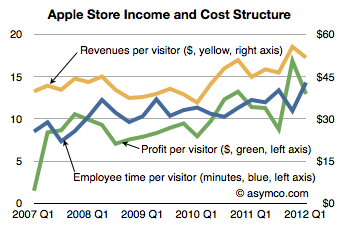
    [If we consider the time an employee spends working we can even guess that the average visit was served by about 14 minutes of employee interaction--this is up from 9 minutes five years ago.]

    If we assume this relationship as causal, then it might be that the stores are "tuned" to ensure a reasonable if not pleasurable experience for the visitor. In other words, the proxy for a "quality" experience is the assistance of an Apple retail employee.

    Taking this a step further, we can perhaps hypothesize that Apple is treating its retail stores as hired to provide a human touch to its products--not just as a service but as a way to listen and help in the most basic way. Steve Jobs once said that Apple no longer had to be present at trade shows because they have millions of conversations with their customers every day through their stores. These conversations happen with the retail staff.

    Through their Apple retail staff, Apple might even be said to be putting a face on their brand. You can see it in the advertising.

    The corollary to this would be that the job of the store is not primarily to sell things. This is confirmed by the fact that store employees are not on commission and there is no sales pressure on visitors. Indeed, the sheer number of employees in a store of modest size (117 employees on an average of about 8k sq. ft.) implies a brazen disregard for the economic orthodoxy of retail efficiency and incentives to sell.

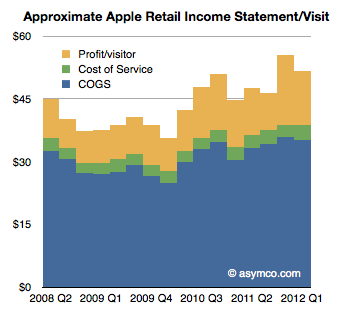
    And yet the stores are astonishingly efficient at selling things. The statistics are off the charts in terms of sales per square foot and overall profitability. Even though this employee time has a cost, revenues and profits have all risen in unison.[1]

    Of course, the products have a lot to do with this performance. Apple stores sell desirable, popular products which are premium priced. But taking these desired products and coupling them with a "human touch" job to be done strengthens the brand as well as expands its volume of sales. It may be that Apple's retail approach could not work with a brand that was less desired. I.e. regardless of a large head count, a Sony store may not see the return on retail investment that Apple gets. Conversely, by not putting a face on Apple's brand the products may not sell quite as briskly. Ron Johnson said on the launch of the iPad that the stores were almost designed for it. Discovery and hands-on time create demand.

    It's as if Apple retail has an inter-dependence with Apple, the brand. One cannot live without the other.

    This is, as far as I know, a unique relationship for a technology company. If anything, most technology companies have sought the exact opposite: to put others' faces in front of customers--to break the messy process of sales and support down into pieces to be outsourced to "value adding" resellers.

    A pity then that this humanizing touch takes such a long time to build.

    ---

    Note:

    1. If we take a visitor-centric point of view, the analysis of the retail business simplifies considerably.  We can even derive an "income statement per visitor". Revenues are measured per visitor (currently about $52/visit). Costs are measured in terms of employee time. A $15/hr average wage and 15 min interaction time per visit puts the service cost at $3.75/visit. Profit per visit is also measurable and it's currently at $13/visit. Therefore the employee "FaceTime" costs 7% of sales, while other costs, including the cost of goods sold, add up to 66% of sales.