As you know, as we crossed into 2001, the great crash occurred.
Ben Thompson • 25:05 Yep. And suddenly a job offer from a big phone company sounds pretty great.
Horace Dediu • 25:09 Yeah, but the crash occurred and it impacted my startup because I couldn't raise money anymore. And that's why I'm throwing in the towel. I'll take this idea to Nokia and build it inside of this company. So for the first year, I worked out of the U.S. and then they invited me to come to Finland. And I fell in love with it, not to mention finding someone to fall in love with. Yeah, I'm still here.
So we created an internal venture called media distribution. And it struggled for a couple of years. We partnered with a publishing company here in Finland that is the biggest newspaper and magazine company. And we worked with them. 9-11 happened. We worked with them throughout that period to test this idea of distributing content on phones. That's how I met my wife. She was working for the publishing firm. Remember when Apple News launched? I forget how many years ago it was already. It was five, six years ago. [My wife] texted me during the keynote. She goes, "you realize that's what we were working on together in 2001?"
It was called Project Melissa. Project Melissa was this idea of Apple News today. And that was [our project] 20 years earlier. That just goes to show you the story of my life. I was doing search 10 years before Google existed. I was doing e-books 10 years before Amazon launched the Kindle. I was doing smartphones and media distribution on smartphones 20 years before Apple showed how it's done.
So my problem has been that I see things happening or see where things are going, but way too early. And that's why one of the theses I have over time is the idea that the difference between a futurist and a billionaire is knowing when one thing happens. So it's not about knowing what's going to happen. A lot of people are very good at that.
Ben Thompson • 27:31 Including Nokia, to your point.
Horace Dediu • 27:33 Nokia, science fiction writers, Elon Musk, a lot of people predict this. But getting the timing right is where the money is made. And so that was one of those lessons I learned.
Ben Thompson • 27:45 Well, when you talk about the publishing and Nokia and the reading and all those sorts of things, what it makes me think of is when the iPhone comes along in 2007, And I'm very curious to get your perspective on what that was like inside Nokia when the iPhone launches.
Horace Dediu • 27:59 I'll tell you exactly.
Ben Thompson • 28:00 But before I get there, but to this publishing point specifically, the key bit was the Internet was permissionless in terms of producing content. Like, it's great that you met your wife, but the fact that you needed to be in a situation where you could meet your wife was actually the reason why it wasn't going to happen. Because if you have to make a deal to do everything, it's just never going to get there. Whereas if you can just surf the Internet, the real Internet, and no one needs to do anything to adapt to it, suddenly you get it all for free. And then you get the virtual cycle going where they're making stuff for you. And that was sort of the, that's the timing bit is like the, the external structure around what you're doing.
Horace Dediu • 28:41 Yeah, it's, it's, it's complex and it's multi-causal and you're right. It's multiple, the reasons why things happen the way they are. And it's just not foreseeable. The internet was, and by the way, the thing that really caused the project to fail and be abandoned--this media distribution side note-- it was the fixation on DRM.
DRM actually killed a lot of great businesses with content ideas back in the day, whether it was music or video or textual. It was people just obsessed about protecting it before they obsessed about distributing it and making it great. And this is why when iTunes came along, even though there were some circumstances there with being on a Mac and not on the PC, that the publishers finally said, why don't we go ahead with this?
So long story there. But as far as what Nokia was doing, after four years of doing this startup inside of Nokia that did not work out, I got into the job of strategy analysis and competitive analysis. So they asked me to do Microsoft.
Microsoft was the biggest worry for everyone because they had intentions of being in the phone business. They made no secret about it. They had prototypes. They were working with competitors to Nokia. [Intending to] give them the operating system so that [for instance] Samsung running Microsoft [Mobile]. That was the effort.
They were pushing on all fronts. Nokia was holding out and saying "we've got our own operating system" and so on. So they gave me this job because every other competitor was hardware. All the analysts were covering hardware. I was the only guy who was covering a software company.
And in doing that, I was also sort of nibbling at Apple a little bit because the iPod had come out. The iPod was doing amazing, but it wasn't a phone product. And I was kind of looking at it a little bit.
Now Christensen comes back in the picture, because his book had taken off. He had already written the second book, which is The Innovator Solution. And I was like, hang on a second, a lot of stuff that I read in the book, and I remember back from my days at school, applies to Apple here because they're doing a lot of interesting things with being disruptive as the case may be.
Nokia itself had been disruptive in its early years. But I'm focused on Microsoft. And my point was that we can fight this battle and win, but we got to be very careful. And there's a lot of twists and turns there, but I took it upon myself also to understand what's going to happen with this media product from Apple.
And then I began to write a few internal notes because nobody was covering Apple. This is interesting and important. Imagine you have a team of a dozen analysts, you could put them on multiple jobs, assign people to multiple problems. No one thought that Apple was a problem to be looked at, even part time. No, there was nothing interesting about it.
And part of that had to do with the fact that [Nokia perceived that Apple had been] one foot in the grave already in the 90s. And now they were this little toy media company. They didn't really have scale. Phones were on the orders of billions of users already. And this iPod was in the tens of millions, maybe a hundred million. So it was orders of magnitude. There was no real worry there.
But I was really annoyed at this thing. And I started building a model. I remember distinctly opening a spreadsheet, looking at research reports and thinking to myself, let's look at the history of the iPod, how it's growing. And I started to match that to the Razr, which was the most viral product at the time, the Motorola Razr.
Even Nokia was jealous about this thing. At that time, [Motorola] had cumulative sales of 50 million, which was considered way too scary. (And BlackBerry was another one, by the way.) So I'm doing this and I'm like, hang on a second, what if they do a phone and it's a combination of the Razr and the iPod, could that resonate? And I just put it out there. I said, it's possible. And there was a rumor of the iPhone coming out.
Ben Thompson • 33:31 So Apple did do a Motorola Razr with iTunes functionality. Did that actually end up, because that was a flop. And did that actually make people not as like more relaxed?
Horace Dediu • 33:46 Because we knew that it didn't run an operating system. It didn't have a developer API, there was nothing, no hooks in it. It was just an appliance. And as such, it was like a feature phone. And that was not interesting. We had been talking and pounding the table on smartphones already since 2001. Remember, when I joined, we had a communicator. We had Symbian, Series 60. We had the interfaces. We had all picture phones, music, etc.
Ben Thompson • 34:20 I was a user as well.
Horace Dediu • 34:22 And I had done the numbers, and by 2005, people were burned out on smartphones. Because the projection was like this, but it was more like this. It wasn't growing as much as you thought it would. And so a lot of people said, especially the top management was like, "you guys are very enthusiastic about the software stuff, but it's just not working out. We're going to double down on hardware."
So there was a lot of burnout. So, but I kept looking at the phone at Apple and I suggested, hey, what if this thing scaled anyway? Like I said "what if they could sell as many as 50 million?" That was my provocation. And people were like, dude... I was essentially taken aside and told, tone it down. First of all, you're not doing yourself any favors by being so provocative. You're just going to lose credibility. My boss, who's a great guy he just took me aside and said, just don't do that. You know, it's bad for you.
Ben Thompson • 35:22 And this is like 2005, 2006, around then?
Horace Dediu • 35:25 Well, already 2006, because the iPhone was rumored. It wasn't out, but it was like, if you're going to have iPod success and you're going to do this crap phone with Motorola, you're probably thinking, maybe they're going to do something interesting beyond that, because we knew they could, in theory, do something.
We didn't see the touch interface, but we saw maybe like a scroll wheel or something. You know, Tony Fadell was running the thing. So, bottom line is, when it finally came out, it was January 2007. It came out and was not for sale, but it was on stage. And I was so excited. And I said, this is unbelievable.
I remember running into the office the next day. Usually you socialize at lunch hour, sitting in the cafeteria, talking to your friends and asking them what do they think about this? And most people just said, oh, it doesn't look that interesting. aspects of it were copied. There were copies from here and there. There are other people that do touch. You know, a stylus has been around for a long time with BlackBerry also doing amazing things with keyboard and so on and so on.
So there was a lot of cynicism and sort of not really interesting. I said, man, it's running OS X, it was running a full operating system. And I said, this is going to get developers working on it. But again, the other thing, the other head fake from Apple was that Steve Jobs said they're not going to put any apps on this thing unless Apple write them. I was anticipating far more than even was being talked about. And for that reason, it was just super frustrating. Anyway, I left in 2009. But by then, Nokia were still not following Apple.
Ben Thompson • 37:13 How is that possible? Like even two years on, this device is out there.
Horace Dediu • 37:19 Because it still didn't have distribution. And this is the thing that consumed everyone following the iPhone in the beginning. It's like they had one launch partner. It was initially Cingular, became AT&T. Don't forget that the old AT&T had nothing to do with this AT&T. It was just a rebrand of Cingular, which was a crappy, small, not very small, it was maybe second tier [operator.]
Ben Thompson • 37:47 Verizon didn't want to do it. Apple did this again and again. Verizon was number one.
Horace Dediu • 37:50 Verizon was number one. Absolutely. But Verizon was in CDMA. But the thing is that it was a crappy network and they didn't have a lot of points to sale. They didn't have distribution. and everybody said this, you need 500 network operators to saturate the global market, right?
And how fast are you going to be able to obtain distribution was the question. And so they're so cantankerous. You know, Apple is known as being "my way or the highway."
Verizon said no for years. Nokia was like, this is not going to fly. These guys are, if anything, they're naive. Don't forget, by the way, there's a separate story on how BlackBerry dealt with the iPhone. There's a movie about it, by the way. Everybody should watch it. But basically, everyone had the similar responses: that this is not kosher.
This is not the way things are done in this business. It's all about relationships with operators. It's about getting shelf space. It's about getting salesmen in the store who are bribed effectively with a commission to tell you what to buy, effectively yank the phone out of your hands and give you another one. So this was a very dirty business at the street level.
Ben Thompson • 39:19 So do you know what was the first what was the first article of mine that I think you ever linked to? It was about precisely. No, no, you don't need to know. I know because it was very formative to me. That's what I'm going to tell you. It was basically about talking about this was how distribution worked.
And what Apple changed about the whole thing was that customers actually switched networks for the iPhone. And it was doing just sort of a traditional sort of business school analysis of and pointing out the power shifted to instead of distribution to the buyers. Basically, what I ended up writing about for 13 years now is demand mattering more than sort of the supply bit. But it was the exact same thing. That's why you linked to it. You are you are already on board with it.
Horace Dediu • 40:04 But it was also the thing that resonated for me personally. Not that I knew something about the phone. Mostly I knew how big it could get. I knew that there were billions of people, many more billions than used PCs, which was by far the most dominant influence in technology.
Most people oriented themselves, like even Gruber and others who were Mac first and then all these accessories. But I knew the phone would be a couple of zeros more. That was number one.
Number two, there was this problem of the incumbency, which were all the phone makers, who were so far from understanding what the software dynamics of platforms were. By the way, platform theory was developed by Microsoft. They pretty much invented the whole idea.
Ben Thompson of the Stratechery interviews Horace on the Stratechery Plus Podcast to discuss Horace's journey to become an influential tech analyst: early career in research, business school under Clayton Christensen, and his time at Nokia during the rise of the iPhone.
The conversation further explores Disruption Theory in the context of both smartphones and AI, why Christensen misjudged Apple, and whether AI could challenge today’s tech giants. It also marks the launch of Dediu’s new paid service Asymco One and reflects his continued conviction in Apple Inc. at its 50-year milestone.
This is a transcript of an Asymetric podcast. It was lightly edited for legibility.
Judd Rubin: Three continents, one conversation, this is Asymetric. We are very excited to have Balaji Srinivasan with us today. Balaji, you're a busy man, Horace you're on the run as usual, so why don't we dive right in. Thanks for joining us today.
Balaji Srinivasan: Good to be here. Good to see you, Horace.
Horace Dediu: Likewise.
Balaji: I know you from online, from Twitter, or at least, I know of your work. It’s always interesting for people to understand how they're maybe thought of by folks who are maybe a little bit on the periphery. And I, we've, always thought of you as the most quantitative Apple analyst, I guess you and [John] Gruber would be the two people who, if you're in the Apple ecosystem, might be the most perceptive commentators outside of Apple itself.
Horace: And John's a qualitative guy, right, so that makes sense.
Balaji: Yeah, exactly. And I'm not like a huge, I mean, it's funny, certainly I have a lot of Apple equipment, but I wouldn't consider myself an Apple fanboy, per se. I converted to Apple when they supported BSD in OSX, because it was a better compute experience.
And, for the last, almost 20 years, the typical developer/engineer/founder, whatever, set up has been a Mac laptop locally, and then all your compute is on AWS or a Linux box or something in the cloud.
Horace: Yeah, me too, actually, because when I started my university work, it was all on Unix, and this was in the days of VAX computers, Digital Equipment, and I just loved that interface at the time of DOS. This felt like, you know, ages ahead. And then I moved from a console to a workstation, which would have been a large screen using the X windowing system and that was my career for five years.
I wasn't even on a PC anymore, I wasn’t using a Mac, but in 2000 when they switched, roughly around that time they switched to being, like you said, BSD. And I was like, okay, Mac is the way to go. Anyway, we don't want to talk about necessarily Apple, tell us what you're working on these days.
Balaji: Sure. I've actually got the crypto plan for world domination that I thought I might discuss with you. Which is essentially how if you're a crypto maximalist, so to speak, how I think crypto is the most important threat to the Big Five.
And essentially the plan for the next decade for how crypto goes after, not just FinTech, but Messaging, Log-in, Social, Search; Crypto Phone, Crypto OS, compilers, databases, advertising, actually reinventing CPA (cost per action), hosting, data centers, creator monetization, and then, on the back end, equity, compensation, privacy, and then most importantly: values.
I actually think that people are underestimating the scope of how big of a deal crypto is and that the Big Five don't really get it. The Big Five, meaning, Google, Apple, Facebook, Amazon, Microsoft.
And there's pieces of their empires that I haven't yet figured out how crypto might disrupt. Amazon's physical logistics, for example, but there's much more of it that is crypto vulnerable than I think people think. And your audience might be interested in this. Some of this is new, even, for maybe my audience.
So we could go area by area. And push back.
Horace: Yeah, the one thing I would caution on, is this usage of the word disruption, because I'm also a student of Clay Christensen. To what extent what I challenge you to answer is, to what extent might these Big Five find [crypto], possibly sustaining?
So if they would say, ‘Oh, well, thank you very much. We'll take it from here.’ So, I agree that there's an opportunity here to disrupt, but many times people just assume change is always disruptive, but change can be sustaining as well. So, please tell us.
Balaji: So, actually, on that point, there's a colloquial usage of disrupt, which just means a change. And then there's the more technical, the Clayton Christensen version, which is, it starts out as sort of an inferior product in some ways, but it's 10x on one axis, it's sort of underestimated. And then it takes the bottom end of the market, and then zooms up to the top in such a way that the incumbent finds it difficult to adopt it because it attacks their margins and so on.
Right? That's assuming the kind of, more technical --
Horace: That's what I mean, yes. That's low end disruption. There's also new markets where it basically carves out for itself a new niche and it does things that nobody's asked it to do. Or markets that are non-consuming, like, you know, emerging markets or something like that, and grows from that base as opposed to low end.
But, yes, generally speaking, that it comes in and is not good enough initially.
Balaji: Yeah, so I think that this fits, as I'll go through each of these examples, I think each of these fit both the sort of colloquial usage, as well as the more technical usage. But let me go one by one and just talk through these points.
So first, at a high level, I'm actually pretty confident that, with the exception actually of Facebook and Twitter, I think crypto is kryptonite to large companies because they don't understand it. And in particular, they're sort of frozen by antitrust and they can't take on more regulatory risk, even if they had the personalities internally to do so. I actually give a lot of credit, even if I think Libra was misguided in some respects, in terms of implementation, I give a lot of credit to [Mark Zuckerberg] for trying to get into crypto relatively early and putting out a project. Even if, in many respects, I think the parameters were flipped, as I can get into, to simply push through that relatively early, starting in 2018, when the other companies didn't get there is because he has a founder's mentality still.
And I think Twitter is actually the dark horse here where it's the furthest ahead on Bitcoin, specifically, as opposed to crypto more generally, that's an internal distinction in the community that I can talk about. But I don't think that Google, Apple, Microsoft, Amazon actually get it because they're not founder led.
And also because they're under this regulatory microscope.
Horace: By the way, just a funny story. So I'm here in Germany because I'm at an event for e-bikes called Eurobike, or just bikes in general. So I'm a fan of Micromobility, I've been talking about it for a couple of years now. I get the same impression. I've spoken to people at those companies that they're not seeing it, they’re not feeling it. Their entire mobility focus is still automotive. It's not that there's a cognitive problem. They understand the idea, but they can't actually implement it, it's this innovator's dilemma thing.
Balaji: Yeah. I mean, it gets to the fundamental thing, right? Which is that a founder is able to say, ‘Hey, we were doing X for such a long time and X got us to where we are, but now we're doing, not X. We’re doing the opposite of that.’
And they have the credibility to turn the entire organization, in particular, to impose short-term costs for long-term benefit to cannibalize or disrupt, in the colloquial sense, an existing product for a new one.
You know, Satya [Nadella, Microsoft CEO] is actually the exception. I would put him, if I rank order the existing companies by their crypto friendliness…
What's interesting is it's the $100 billion and $10 billion and $1 billon companies that are much more crypto friendly than the trillion-dollar companies.
So Shopify, for example, gets it, right? Coinbase. Stripe, I think, is coming around. So the ones that are sort of like the sophomores or the juniors, as opposed to the seniors, are going to, I think, use this to slip stream. And I think this is a disruption again, you know, I know you're from the Christensen club, so I may use that colloquially, so poke at it.
I think this is a change or an alteration or a forcing function, whatever you want to call it. That is actually on par with the desktop to internet transition. That you can think of this as, just like you went from on disk to online, the transition from online to on chain involves a similar number of cultural and technical changes that render the current generation, basically like the Borlands and DEC Alphas and so on of the previous generation.
Horace: So tell us how do you think that… You gave a lot of examples, of things going on chain --
Balaji: Yeah, so let's go to specifics. Let's start with the obvious, which is FinTech. One of my colleagues, friends, Chris Dixon runs the crypto fund at a16z. He observed a while ago that many Unix command lines became apps.
For example, GIT became GitHub. That's an obvious one, but had these command line chat apps that effectively became Facebook and IRC and Slack and so on and so forth, right? Command line apps turned into full-blown UXs. Crypto is actually the reverse in some ways where every FinTech app can be turned into a crypto command line. For example, Affirm or PayPal or Funbox, or, many of these things that essentially are doing cashflow transformations of some kind can be written as a few lines of code in Solidity. Which is Ethereum's programming language. And that alone is actually kind of a big deal where you can write that down and then just start piping arbitrary amounts of money through it, between countries, where it really is the internet of money. Any user can route money to any other user, if both users have a crypto address, if they have a Bitcoin address or an Ethereum address for the purpose of smart contracts.
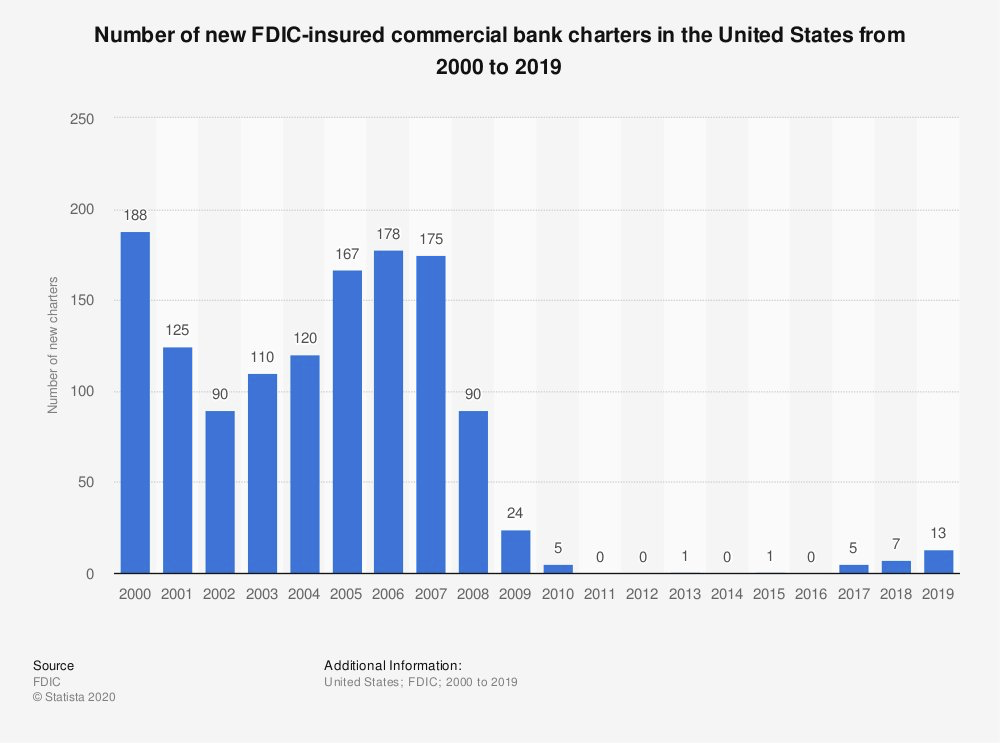
And so that's just a fundamental backend change. And one way of thinking about it is over the last 10 years, since the financial crisis, Dodd-Frank basically stopped the issuance of new banking charters. Were you familiar with that? Did you ever see the graph of that?
Horace: No. No, tell us.
Balaji: So, you're a graph guy - I've got a chart on this somewhere on Twitter, but basically the way that they dealt with the banks' failure during the financial crisis is to effectively reward them by eliminating their competition entirely by refusing to issue new bank charters for almost a decade. And, here's the graph over here.
The state's solution to the financial crisis was to stop issuing commercial bank charters for almost a decade and to reward failure by regulating away competition via Dodd-Frank.
The network solution was FinTech and now DeFi.
The reason I bring this up is FinTech is a front end, Blockchain is a backend. Over the last 10 years... You're probably familiar, at least to some extent, with the FinTech side of things. Imagine if, when I sent you a message via Gmail, that behind the scenes, Google printed out the email, put it on a Pony Express, took it to you cross continent, scanned that and put that into your inbox.
And it looked like it was digital, but it actually had this antiquated pre-internet backend of a two or three-day delay in there, but the company did the best it could to obscure that. You know, all of those hacky steps in between, yeah? That's a good analogy for what FinTech is, where it's this shiny web-like front end, but on the back end, you're dealing with pre-internet mechanisms for settlement where it's often FTP or flat files or some horrible Cobol-era file format. It just wasn't set up for the workloads that we have when you actually press on that. Right? Once you set it up and you give people the expectations of being as performant as a Facebook or a Twitter or a Gmail, and you start putting huge workloads through - that the financial system doesn't anticipate, you get things like the Robin Hood issue of earlier this year.
Horace: Yep.
Balaji: Right? You make people think that it can handle internet-like workloads. But it can't, it just kind of simulated that. Taking that Gmail analogy a little bit further, with Gmail, every email that I send you is basically non-fungible. In the sense that each one is just a different set of characters. But if it was fungible, if it was money where every dollar is the same as every other dollar, Google could… when I hit a button to send you a hundred bucks, Google could just extend you effectively a hundred bucks on credit where it's assuming I'm good for the hundred bucks. Right?
And that is essentially the mechanism by which a lot of FinTech companies operate where they're like a central buffer that makes users think that this stuff is instant and fast, but it's actually not on the backend. Okay, so FinTech is a front end. Blockchain's a backend, where it's a genuine innovation.
So it's almost like this flanking thing where bank charters were cut off. FinTech built all of these fancy front ends on top of banks by doing deals with banks, by now, more recently starting to get licenses in Utah and places like that. And then blockchain, the crypto space, built a completely different set of rails where they essentially, over 10 years, got people to accept these things as money-like.
And now they're coming together where, with Robin Hood, with Square, most FinTech companies are aware that crypto is a big deal. It's not going away. And the reason many of them have a hard time getting their head around it is that it flips basic assumptions.
What Satoshi did with Bitcoin is he flipped absolutely basic assumptions. Where the concept of Bitcoin starts with the idea that deflation is actually good if it's coming from productivity. The typical macroeconomist would say hyperinflation is bad, but deflation is also bad. A little bit of mild inflation is good. This is what you'll read in every Econ 101 textbook.
Horace: Yep, that's true.
Balaji: And so Satoshi said, actually, no, that's not the case.
You want to have users be able to hold their own funds and you want to have a fixed monetary policy that gives certainty for investing in the future. That can't be monkeyed around with, by the Fed open markets committee, to bail out banks and stop transactions and so on. That meant so many flips of fundamental premises.
Number one, digital gold being good rather than bad. Number two, that users should be able to custody their own money rather than having it at banks and they should be able to take that risk. Number three, that transactions by default should all be able to go through. So it's like a default approved as opposed to a default sanctioned and so on and so forth. They basically just flipped fundamental premises.
And when you flip fundamental premises, you can often get to just a completely different environment, completely different worldview, completely different set of solutions. I mean, it's like land animals versus sea animals or like Google's culture versus Apple's culture, right?
I mean, now they've become more similar but Apple for a long time, it used to be very private internally and Google was very public internally. Both of them worked on their own terms, but were just fundamentally different in terms of their premises and axioms.
Horace: Let me get back to this example you gave us, of online as a way to do fundamental transactions. Now, one of the things that, and this seems very much, like you said, behind the scenes, because from the front end the consumer is given an illusion of technical competence. But in the backend, it's actually still jury rigged.
Now, the thing that I would ask is what does that mean and how does it feel different for the consumer? Because if you fix the backend, then yes, it's much more robust and clean and probably safer. But I think that the way it affects behavior is not so much that people feel different about that interface, but rather that they will do more of it.
In other words, that, like you said, it was about volumes that caused the cracks to appear in Robin Hood. So to me, the question, the reason, let's say I'm not skeptical, but I'm slightly reluctant to dive headfirst in on crypto is that I'm asking all the time is: How does it feel different for the end user?
And the end user would have to have some sort of emotional response to this change and say, ‘Wow, this is really amazing! Now it's much better.’ Or, ‘Now I can do things that I couldn't do before.’ So what I would posit is that the change you speak of would allow the users to suddenly say, ‘You know, I may do a wire to pay for a very large sum, but now I would do it a hundred times a day. Or I would do it to pay my friend, or I would do something financially that I never did before.'
And I, by the way, I feel this pain a lot because I live in two countries and you probably do as well, and you have to always transfer money and it's an absolute nightmare. And it's almost confiscatory in the way they steal money on the way, to try to transfer funds internationally.
So do you see this driving new user behavior or is it simply that you fixed something that was broken?
Balaji: Absolutely, excellent question. Let me give a few points on that. An interesting thing Evan Williams once said, in a sort of counter-intuitive way, was that the way to get people to adopt an app is to not do something totally different, but to take something they're already doing and just cut out steps. Make it just faster, simpler, etc.
You know, people were blogging and then they did Twitter. People were blogging and then they did Medium and made it simpler, with front end editing. And that's one view, that technology is incremental. But the other view is it's transformative. Wait a second - our lives are so different than the past.
And here's how I reconcile those, then let me get to specifics. If you go from physical mail to email, just sending point to point email, to a group email with reply all. To a group email with reply all where you add attachments of images to a Facebook thread, to then real-time chat in something like Slack or Discord where you're attaching images.
Each one is an incremental step over the previous one. But if you were to think about how expensive it would be to do a Facebook thread by physical mail. You'd have, I don’t know, a thousand friends and you'd be printing out the thread each time and sending postcards to each of them, with someone saying LOL…
If you would just diagram that out and see how many packets were moving back and forth between those thousand participants of which maybe 95, 99% of them are, actually, not even participating. So therefore they wouldn't even go and send in their postcards. And you'd say how much of a cost that would be on the legacy postal system?
At a certain point, when it's a million postcards to be one simple Facebook thread that we take for granted that has some images and a reply and maybe a link or something like that. Well, then the quantitative difference makes a qualitative difference.
Horace: Absolutely. Yup.
Balaji: Right? And in the same way, that's basically what's happening with crypto. And one way of thinking about it is - and this is now changing, but in the first 10 years, what crypto was best for and by the way, within crypto the term ‘crypto’ is an overarching thing that encompasses... There's just different people who have a beef with the term. One group, are those people for whom, you know, crypto used to mean cryptography, right?
And the second are those folks who think of Bitcoin as its own area, as distinct from crypto in general. I think crypto is the right term for the space as a whole. I think, in particular, cryptocurrency and blockchain is to cryptography roughly as the internet is to software. Software is not synonymous with the internet. Computer science is not synonymous with the internet, but it’s certainly the most frequent deployment and monetization point for it. And, in the same way, I think many cryptographic concepts will be deployed and monetize within the blockchain and cryptocurrency space.
On the second thing, just to finish this little tangent for a second, Bitcoin people think of Bitcoin as the only real cryptocurrency and everything else is a scam and a fraud and blah, blah, blah.
Which I don't believe. And I don't think Satoshi Nakamoto believed that, but this is something you'll probably hear more and more of.
But just in terms of that term, ‘crypto’ is basically thinking of the space as a financial and technological and efficiency related movement. There’s also a very strong overlap, which I'll get to on the ethical aspects and how it's actually a pro-freedom movement. And those overlap. And a Bitcoin maximalist would be like purely on the pro-freedom side, or in their mental model of it.
Okay. Just coming back up the stack. So, end-user benefit basically in the first 10 years, crypto benefited what I'd call the power users and the marginalized. The people who are at both ends of the spectrum. It's the exact opposite of the bell curve.
It's not the person in the middle. It's a person at the extremes. And so that's why I like the example of, ‘Hey, I'm buying coffee at Starbucks. You know, this crypto thing doesn't seem like too much of a benefit.’ It's actually a good point. And the reason is crypto is good for transactions that are very large, very small, very fast, very international, very automated and/or very transparent.
So those six things: large, small, fast, automated, international, transparent.
Your Starbucks [order], maybe it's 10 bucks or 15 bucks, whatever, for coffee and bagels or something like that. You know, big city prices nowadays. That's not a very large nor very small transaction. It's not millions of dollars. It's not a cent. It doesn't need to be very fast because to clear it, settlement can happen over a day or something like that. It doesn't need to be ridiculously fast. It doesn't need to be very automated because with both you and the clerk, there are humans monitoring the transaction on both ends.
It's not very international. You're both literally in the same coffee shop and doesn't need to be very transparent. There's no reason for either of you to have that receipt on chain. So everybody thinks about coffee payments because that's maybe the most frequent thing that people actually buy on a daily basis.
There are not too many other things. People used to buy a newspaper on daily basis, but they don't really do that anymore. They may have a subscription, but they don't consciously buy it. So relatively a few other things you buy on a daily basis. You don't buy a chair on a daily basis. You don't buy a computer on a daily basis.
So they think about their coffee purchase, but that's actually sort of the opposite. So where crypto is actually really good - let's start at the power users first. The power users can be split into two overlapping groups, which are engineers and investors. Both of them are trying to do things like, for example, move a million dollars across the world to Japan in a day to do something, right?
The engineer might be doing that because they're moving money around on the back end of Airbnb or Uber or PayPal or something like that. They're pooling capital from lots of users and trying to do something with it. Take the profits from one area and move it to another. Accept all of these wire transfers in different currencies and convert them into USD within Airbnb's main account, something like that.
Brian Armstrong, founder of Coinbase, saw what a big deal this was as an Airbnb payments engineer. He realized it was not a solved problem. That's actually how he got into Bitcoin originally. So as an engineer, you understand it from that perspective. An investor understands it from a similar perspective where you want to do an international wire and, you know what? It's actually still a pain to do that.
Wires get lost. There's [the matter of] correspondent banks. It's a huge pain to do a wire trace or something. But you know what's really simple? If both sides use USDC, which is the stable coin I helped launch, but it's the number two stable coin in the world. Maybe the number one, if you think of it, as in terms of legal stable coins, you can go to a website, stablecoinstats.com.
Right now, it's $26 billion outstanding in USDC and over the last 24 hours, it was $694 million in volume. Okay. That's quite a lot of wire.
Horace: Impressive. Yeah. That’s striking.
Balaji: That's striking. The whole space is bigger than people get from the outside.
A good metaphor is crypto is a country. It's a fractal country of a hundred million people, which is bigger than most people realize. Cambridge had a study on this last year. It's probably bigger than that now, but it's a hundred million people who hold some crypto, according to the surveys, spread across countries.
And the key is you have to have that sort of value flip right in your head to think of it as money. It's basically like, do you think of the yen as money or not? Do you think of the ruble as money? And if you do, then you can participate in the Japanese or the Russian ecosystem. And if you do not, then you do not.
But crypto is like a country that is exponentially expanding. And there's a million people at the core and then 10 million people around that and a hundred million and it'll keep growing. And then once you’re part of this economic environment, all these other people accept cryptocurrency as money, all of these things become possible.
And once the other person, on their side, accepts USDC as a dollar equivalent, well, I can hit enter. And just like how sometimes you'll send somebody a file and you'll talk to them on the phone for a minute or 30 seconds, and they'll be like, ‘Oh, okay. I got the file in my inbox, done.’
You can now do that with an international wire transfer with USDC. You can hit enter, and they will see it on chain in a few seconds. Now, at first, all that's doing is it's similar to the transition from mail to email, where you go from a two to three day delay to seconds. But then over time that increases the metabolism of business.
For example, I sold a company, Earn.com, to Coinbase several years ago.
One of the things we did there was kind of a V1 of this where we would accept Bitcoin from somebody in Greece or Japan, let's say $10,000 worth. And then we were able to issue a thousand $10 amounts of Bitcoin to a thousand individual people in different places for microtasks.
And the thing is that, because I could get that $10,000 wire or wire equivalent from them same day, you didn't have to know whether they were good for the money.
Horace: I think it's unbelievable. But let me bring you back to the Big Five and the questions [from earlier in the discussion]. We just did FinTech, I think convincingly, the next question is how does this, which yes, it will increase metabolism, but how –
Balaji: How does it disrupt the Big Five?
Horace: Yeah. In particular, those examples you gave: messaging and platforms and coding and all these other things.
Balaji: Let me just tie up one last point on the previous thing, if you don't mind. I mentioned [crypto] is good for the power user and the marginalized.
So the power user - the dev or the investor wants to move millions of dollars around the world with the keystroke. The marginalized, that's somebody who just wants to hold on to a bank account equivalent. That's somebody in a Venezuela or a place where the currency is being inflated. Or Nigeria, where people are being pushed out by the police.
But it's also anybody who's de-platformed or canceled or ostracized, or basically locked out of the financial system for whatever reason. Like the OnlyFans.com thing recently, [which is an] obvious example of something where… That's what cryptocurrency sells, where the banking system can't just lock you out.
And what's interesting is sometimes these are the same entity at the same time. Something like binance.com, for example, is both a power user of crypto but it's also marginalized where it's sort of on the margins of the legal systems in the world.
A couple of other quick points on this before I move on.
One thing people often talk about is, ‘Where are all the use cases for crypto?’ Well, now there are many of them are out there. You know, I've actually got a post on this: And What Has Blockchain Ever Done For Us?Crypto has transformed crowdfunding, it's transformed international wire transfers, it's transformed gold.
Just those three applications are worth trillions of dollars, but there's way more. If you go to defipulse.com, it's transformed loans, it's transformed derivatives. Many of these applications are actually out there and already at substantial scale.
But a very important point is speculation was installation. Without people speculating that this thing could be big, it wouldn't have had a price. Without it having a price you couldn’t treat it as money. Without it being treated as money, you couldn't build all of these apps. The loans wouldn't work because it'd be just sending zero for zero.
The thing about crypto, in particular, is it has the opposite emergence mode from social networks. You know, we've now been tuned to such an extent to DAUs (daily average users) and MAUs (monthly average users) and whatnot, that we sort of forget in the 2000s, that those were metrics that people scoffed at and poo-pooed because social networks were piling up all the users, but where the money, you know?
Even as late as 2012 or 2013, there was an article, something like why Facebook will never make a significant profit. And just a few years later, [people were saying] ‘Oh my God, they're so evil, They're dominating the world.’
And you've seen all these kinds of things. With Facebook in particular, it piled up users. It made money, actually, pretty early on, but Twitter, Pinterest, Snapchat, this entire model of piling up users before making money was, and is, a common one. Now people understand it so much that they think that's the default emergence mode of new technology,
But crypto flips that. Where it piled up the money before it had the users. Making money, almost in the literal sense, before the users came. So it flipped it around. And so instead the question people were asking is, ‘Oh, where's the utility?'
Now it's actually coming.
But I wanted to point that out. It's the opposite of the social network model, MAUs and DAUs, there’s a totally new set of metrics you need for crypto, which are not daily active users, but daily inactive holders - that is people who are holding for the long-term and are committed to it.
So that's macro, let's go to specifics. So I mentioned FinTech. Pretty much every FinTech app is going to get backend blockchain-ified. Unless there is some prohibition within the country on that. And if that is the case, it'll probably get out-competed internationally, even if it has a captive market at home.
And the reason for that is, if you think about an email address, it is something which is uniform across geographies. I don't need to look up the postal code of this, or the zip code of that. With an email list, you don't need to know whether somebody is in Nigeria or Switzerland or India. Just hit enter and you send it. That uniformity alone is something that blockchain addresses give you. It’s way easier to do a cross-border deal with somebody in Japan and Brazil or Nigeria with the smart contract than it ever was before.
In fact, one might even argue international business didn't even really exist before smart contracts and cryptocurrency. And the reason I say that is if a Brazilian company wants to acquire something in Bangladesh - -
Judd: You need locals.
Balaji: Yeah. You know, what you might do is say, all right, there's not too much law on the Brazil - Bangladesh interface, but there'd be U.S. - Brazil and U.S. - Bangladesh. So let’s set up an intermediate there and work through the precedents on both sides and get A plus B and B plus C.
The other country you might use for this is China, but if we actually go down to brass tacks and think about what the obligations are for each side and how the legal systems interact, you sort of need that centralized intermediate, the U.S. and China are the only two countries that do so much business worldwide.
There's probably a Chinese enterprise in Bangladesh, probably a Chinese one in Brazil, and so you could make the things add up and the laws add up and the property rights add up. But that's something that only works at scale. For large companies doing those kinds of transactions, you can make it work and you'd probably set up a U.S. or Chinese intermediary to help make it work. To lubricate it.
But if you wanted to do it direct - how do you do direct? These people don't speak each other's language? They certainly don't know or trust each other's legal system. So all kinds of weird peccadilloes. But on chain, everybody can read the same code. So, essentially, the pooling of money, the friction of diligence, the consistency and uniformity of naming, all of those things are 10x improvements just from a developer-investor standpoint, the power user standpoint with FinTech.
So all FinTech gets disrupted by blockchain. That's very clear to me, it's already happening in some ways, but that's very obvious. All right, let me pause there and get your thoughts, feedback, and then I’ll move on to the next one.
Horace: Yeah, exactly. I love the way you framed it in those six categories of applicability.
Most people don't experience small transactions or international or transparency's not a concern of theirs. But that allows me to classify this as the type of disruption where it would allow things to happen which normally wouldn't happen. It would allow, like you said, inter[national] deals to happen in ways that no one would even think of doing today.
And as a result, it's sort of a new market disruption. It would unify people who are now divided by country boundaries. It would unify them in, as you said, this new country, this country of coin, [of] which they would be all effectively citizens that would somehow communicate and understand each other so much better, because they are not divided by these artificial boundaries. And I think that would, if you said the exponential growth is current[ly happening], then it would encompass a substantial part of the globe. And that in itself is so powerful that we can't even fathom the consequences of. But it's effectively, in the FinTech world, I think what you're saying, and I'm sort of reading ahead of it here, so what you're saying is that once that platform or that foundation is laid, you can imagine a lot of new things emerging and that will build new empires. Is that where you getting at?
Balaji: Yes. I actually think crypto is to America as America was to Europe. Like you can, and let me explain what I mean by that. It's actually-
Horace: No, I get it, yeah.
Balaji: And just like you had, so why is that actually a good analogy and not just simply verbiage? If you know different kinds of distance metrics, the most obvious distance metric is the great circle distance on the surface of the earth between two people.
That's just the distance as the Crow flies. You know, on the surface of globe. There's another distance metric, which is the geodesic distance between two people in a social network. You could have, for example, you and I right now are closer geodesically than we are geographically. And then there's people outside who are closer geographically than geodesically. People I don't know, or haven't spoken to, but they’re within a mile of me or, or within a mile of you.
And so those metrics, they actually have typologies associated with them. Just like you can have a cartography of continents, you can have a cloud cartography of who is close to who in the social network. In many ways, you're probably closer to people in Cupertino and New York and various financial capitals around the world than you are to people who are a mile away physically.
And that is something, when you start visualizing what that cloud continent looks like, with all the nodes colored by what coins they hold, you know, a big orange for Bitcoin and blueish for Ethereum and so on and so forth. You start getting a visual that looks a lot like the European incursion into the New World.
Without, of course, any Native Americans or anything like that, it's sort of the pure expansion of different demographics into this new region where people are spending more and more of their time. And VR will make this more than a metaphor. It'll actually be like physical space.
Now the one thing I would edit on your point is that when I said crypto's a country and you said without internal boundaries, there actually is a lot of crypto tribalism. So it's actually an interesting thing where just like there was the New World and the Old World, there's a crypto world and the fiat world, and there are conflicts within the crypto world and there are alliances with folks in the fiat world.
So it's actually an interesting analogy to the age where the French and the English and the Spanish and so on all slugged it out for the Americas. Again, without the native population there, it's sort of the pure version of that. So with that as an analogy, it's something where you can build things from scratch. All these ideas that were infeasible in the Old World, like democracy or so many innovations that the U.S. had in terms of governance and —
Horace: The federation, the transportation networks, the frontier, the way the U.S. was constructed, mostly accidentally, allowed it to become a superpower.
And I think the continental scale of it, which again was accidental by acquisition of territories peacefully and not peacefully, but generally Europe was stuck in a centuries old grid of monarchies, feudalism and all the other baggage they had carried. It just wasn't able to have a frontier mentality. I sometimes think that that conquest of land, that the open horizons is reflected in the dynamism and the ability to invent that followed.
Balaji: Yes. This is Frederick Jackson's Turner's frontier thesis, and one can argue whether these changes were all good or all bad. I think there were some both good and bad innovations that came back from the New World to the Old. For example, The French Revolution, they were in part inspired by The American Revolution, but had a much worse result.
Communism actually, there were a fair number of Americans that were involved in it. There's a book by Kenneth Ackerman, for example, Trotsky in New York, where he raised money in New York. Also Lenin was basically released by the German government. Even the New York Times had something of this, like Lenin was a German agent.
So some of that stuff that came back to Europe from the Americas, that’s not that well-known, but it's also not that obscure. You can Google around and find it. Some of that stuff that came back from the Americas was not good, but some of it was. The modern railroads and the history of how many technical innovations came back from the U.S. to everywhere else. From mass production to, I mean, in some ways bad, but the atomic bomb, nuclear power, all of these things that you would not have had without that fresh new, clean slate to build things and have influence back [the Old World].
And I think that's very similar to what we're seeing in crypto, where in many ways it's already changing the financial system. The most obvious is every government in the world, every bank, knows what CBDCs (Central Bank Digital Currencies) are, at least in concept. And China is shipping a digital Yuan. Which means that a post on a message board by a pseudonymous guy 10 years ago has shook the entire world, and is already a topic for not just discussion, but active execution by the governments of a billion people.
And that's, that’s-
Horace: Just while we're on this cultural aspect, what is your opinion on who Satoshi is? I'm curious as you seem to know —
Judd: Are you Satoshi?
Balaji:. No, I'm not Satoshi. I wouldn't tell you if I was Satoshi, but I'm not Satoshi.
Judd: What if we asked twice?
Balaji:. What's that? What if you asked twice? Ha ha. No, I mean, Satoshi Nakamoto had a very important combination of skills.
First, he was a world-class programmer. The thing about something like Bitcoin is computer security. The late Dan Kaminsky, who was a friend of mine and absolutely a genius in computer security had an article in 2013 where he said, I tried to hack Bitcoin and I failed. And this was very exciting.
The point that he made was that, in most applications, security can rightfully be a little bit of an afterthought. That’s to say that in the early years of the web, maybe not so much today in 2021, but in the early years of the web, you just needed to stand up a site and get users. And you could sort of assume that there wasn't that much to be hacked and people didn't care that much. And so people would optimize for growth over security, because if you have growth and no security, then you can hire engineers and add the security later. But if you have security and no growth, you have no money, and it doesn't matter. Nobody cares if it's secure.
And the thing that's different about cryptocurrency is that security is a fundamental characteristic. If it's hacked, even once, if you can duplicate coins, inflate coins, and that's a persistent issue and an unfixable issue, then the value goes away.
So security wasn't an afterthought. Satoshi built the code like you'd build the code for a space shuttle. Where it was just a different mentality from the very start. And so, first of all, he’s a genius programmer. But, second, he clearly had a deep humanities background to build something — I mean, with many kinds of inventions, there's Newton and there's Leibniz. You know, there’s an idea in the air and there's simultaneous invention of some kind.
But Bitcoin wasn't like that. It really was something where one person's genius shaped the world and it took a while for people to catch up. And it wasn't like there were a lot of contemporaneous Bitcoins with similar ideas. It was something where it was kind of out there and it took a while for people to get it. And even still today, people don't get it because it flips premises.
And unless you're actually reasoning from first principles… people will quote Econ 101 as if it's like some kind of inoculation against this thing that’s at a trillion dollars [in market value]. It's similar in my view, by the way, the American, just to digress on this for a second, the American school and maybe the international school of macroeconomics, I think is similar to like Soviet economics where the Soviet Union had all of these prizes that were given out for Marxist economics. But it didn't amount to a hill of beans because their premises were actually wrong. Some of it was good. Like, I think Kantorovich did linear programming. Some of the math was useful, but it was something where the premises were wrong. And one of the reasons for that is that with macroeconomics, you can't actually run experiments very easily. Because the maximum that we know in macro is something like communism doesn't work. In the sense if you compare a North Korea versus South Korea or China before Deng Xiaoping to Hong Kong and Taiwan and Singapore, or East Germany versus West Germany. You take ethnically similar populations, you partition them, run the experiment for 40 years, communism impoverishes one side of the country versus the other. We've now seen that multiple times. So that's the extent to which you can see that within macroeconomics and so in that sense you've got controlled experiments, but that's not actually the fundamental principle of macroeconomics.
It's something more like John Lanchester wrote this in London Review of Books, you know, almost a decade ago. And Tyler Cowen wrote about it. The fundamental principle of macroeconomics is governments aren't households. Meaning governments can print money, meaning governments can seize things at gunpoint, and so on and so forth.
And this type of stuff, this kind of discussion goes to philosophical roots. It goes to economics. It goes to history. It goes to policy. It's inseparable.
Horace: But just to build on that, the way I would say it, governments typically have a monopoly on violence. What it boils down to is that they can do these things, which are not allowed by households, is because they have armies.
Balaji: Yes.
Horace: They have police forces that effectively are armed. Citizens may or may not be armed, but generally never could match the firepower of the state. So this is — the monopoly on power is monopoly on violence, at this moment.
Balaji: That's right. And the thing about that is that the modern school of macroeconomics is backed not by mathematics, but by guns. Actually, Paul Krugman, in an interview with Joe Weisenthal said, fiat currency, if you like, is backed by men with guns. It's like Mao’s thing, “power comes from the barrel of a gun.” Whereas, and so once we're honest about that, we're like, oh, it's not Econ 101, it's AR-15. Right? And so once you realize, okay, that's actually the backing. These fancy formulas, it's just like the Soviet Union, the Marxist stuff was backed by AK-47. Right?
So once you realize that, okay, well, I'll give you another one, which is Bitcoin is backed by SHA256. So Bitcoin is actually backed by cryptography and mathematics versus violence. And that's just a fundamentally different set of premises. So the reason this is inescapable to talk about is that you can use JavaScript without really knowing much about history. But to understand the problem that Bitcoin solves, you really do need to understand history and philosophy. And that's why Satoshi was-
Horace: Yeah, exactly. I was going to bring you back to Satoshi. So he's a humanist and he's also a programmer par excellence. But you also speak of him in the past tense. Why do you do that? Is he not still with us? And what’s happened, what will happen with his share of Bitcoin?
Balaji: Well, nobody knows. It's something, which is interesting, where it shows that with good enough OPSEC, to my knowledge, nobody's actually, de-anonymized him.
A lot of people suspect that Satoshi was close to Hal Finney, who was an early extropian and programmer, but nobody knows for sure. Some people think it's Nick Szabo. I don't think it's Nick because Nick has never published code to my knowledge. So I don't think he could have done it himself, but Nick has published ideas that are clearly influential on Bitcoin. But the reason we speak of it in the past tense is for him to authenticate a message he'd have to do so from the private keys that are associated with early Bitcoin addresses that we know belong to him that only he would hold.
He could trivially do that. And he has not done that in last seven years. And Hal Finney actually died of Lou Gehrig's disease, I believe, around that same time. So it sort of connects that Hal Finney might be Satoshi, but it's not known. And nobody really wants to poke into it because in many ways what Satoshi did, it’s amazing that it was a human being who did it, like a single human being. And I think it really was a single human being because something like that is just sort of hard to do as a team. Satoshi… the fact that he has disappeared means that Bitcoin is “decentralized,” or rather it is one of the forces that makes Bitcoin feel decentralized.
It is something where there's no identifiable leader, yet it has massive global adoption. Now, you can argue, well, the core developers and the miners and the reference client, and so on, are points of centralization. Each of these are tested over time. I think mining centralization just got tested. People had made the point, oh, China could take over mining, but China just cracked down on mining.
It was a huge drop. If you looked at the Bitcoin mining charts, the hash rate dropped from, I think, around 180 exahashes to like 80 exahashes. That's a huge drop. The biggest drop I think ever in Bitcoin history. And all that happened was what you'd sort of predict by looking at it. Transactions slowed down for a little while, and now it's back up to 140 exahashes.
So China, which is probably the largest and most organized and ruthless and technologically competent state, all the things combined, took a hard swing at Bitcoin mining, actually pushed it out of the country. Bitcoin kept ticking. So Satoshi's absence has helped decentralize it because everybody can imprint their own thing on it.
In this sense, Bitcoin is like Linux where ferocious competitors like Google and Facebook still collaborate on Linux. And the reason is Linux is a demilitarized zone where one party's contributions cannot be deleted or removed by the other parties. It is a true commons where you can give, but not really take back.
And that's what Bitcoin is like: a truly decentralized technology where every user is a root user. Nobody else can de-platform you, nobody else can take away your funds. It is something where you have parties that can be highly dis-aligned, but aligned on BTC. Very, very powerful thing.
And a big part of that comes from Satoshi’s absence and disappearance.
Horace: Okay. Take us home then, back to the Big Five. How do we think about all this building up to something much more visible.
Balaji: All right, so the first 10 years, we can very much compare the current era to the year 2000 for the internet where you had infrastructure, you had Yahoo, you had AOL and you had the early broadband connections.
You have the first billionaires, you had everybody knowing what the internet was, but a lot of the applications of daily use didn’t yet materialize. And there were a lot of people who’d use the internet to check news or send email, but you could basically get away with a completely offline life, even in the year 2000. By the year 2010, that was not true.
And by the year 2020, it's flipped the other way around. Now you need a phone in many places in Asia to get in with your vaccine passport and so on and so forth. And so I think that's similar to where crypto is today. Where the infrastructure is being built out. We have the exchanges, we have the mining, we have the coin developers.
We have the first billionaires. We have widespread awareness of it. But yet today, you can still live a completely crypto free life. I do not believe that will be true by 2030. And I believe it will be totally flippened by 2040, where it'll be crypto first for the entire financial system. But let me go to specifics, okay?
So we talked about FinTech. Every loan, every mortgage, it'll start with all the digital stuff first because that’s which is easiest. The stuff that has an offline correlate to it, like mortgages, will be harder because you have to have so-called crypto oracles recording the transfer of things offline. But all the FinTech stuff, that's kind of obvious.
Okay, then messaging. The big thing about crypto is it allows for provably, encrypted end-to-end encrypted messaging. See when, nothing against WhatsApp, but it just tells you that it's end-to-end encrypted. They could have a bug in the implementation. It's not easy for the user to verify that. You know, it feels the same as Facebook Messenger.
It's trusted [as] end-to-end encryption, but then you can get backdoors and stuff put in. Whereas with crypto messaging… You know, it's funny, when you say cryptocurrency is taking two concepts that seem to be totally distinct like encryption and money, they have, of course, come together since the advent of HTPS and credit card payments on the internet twenty-five years ago.
But crypto has put them directly together in a very powerful way. In the 1990s and the 2000s people talked about this thing, they still talk about it, called the public key infrastructure problem, which is if you could assume that everybody had public and private key pairs, you could imagine this magical world where all of these privacy preserving things were possible.
Now many of your [listeners] may not know what public and private key pairs are. Roughly speaking, a public key is like a sealed envelope that you can give out and people can then put a message in there and seal it up and send it. And only you with your private key can actually see what's inside that envelope.
They can send you messages that only you can decode. There's many other uses for them, but that's one way of explaining them. The thing about it is, when you talk about everybody having a private key and public keys that are out there, well, you could do secure messaging.
For example, if your public key is out there next to your Twitter account, I could just take that public key. I could gin up a message. I could post that to you publicly, but only you would be able to decrypt it. The reason public key, private key, the whole public key infrastructure problem has been hard to solve is you need people to keep their private key available and secure at all times. So if you want to keep it available, you can just put a post-it note on your desktop computer, but it wouldn't be secure. If you want to keep it secure, you could go and put it in a lockbox somewhere, but it wouldn't be available. You’d forget where it was.
To have something be secure and available at all times is actually very expensive. It's like your wallet, it’s like your cell phone. It's something which, you've got eyes on it at all times. And that's something which basically has to be on your person and you need a strong incentive for doing it.
And so the big thing that crypto has done is it's made that incentive literal. It's money. If you lose your private keys, you lose money. And so because of that, everybody, millions of people, hundreds of millions, billions of people will have private keys that they can encrypt messages with. And so that will unlock end-to-end encrypted messaging in a provable way where you don't have to trust WhatsApp, or what have you.
And that's going to become more and more important as you're seeing, for example, Apple ran all these billboards on privacy and, I’m not sure what your stance is on that, but the CSAM thing, if you saw that, recently was basically cracked. Where people were able to put fake caches on people's devices to make it seem as if they had CSAM on there, but they didn't.
And I think you're going to see more and more of this, where there's a lot of advertising based assertions of privacy that are then eroded by some action and people will not want to take the Big Five’s word on trust. They already don't. And they're going to want provable end-to-end encrypted messaging.
We already saw this earlier this year, where there was an exodus in part from WhatsApp to Signal over some rumors that’s WhatsApp’s new terms of service were making it more feasible to eavesdrop on you. And I'm not sure how true that was or not, but you're actually starting to see consumer demand for privacy, which people didn't think existed.
Let me pause there. That's messaging, let's talk about that.
Horace: I think therefore the, let's say, the disruptive technology, as opposed to business model, is trusted encryption. And I think that what you're saying, effectively, is that the incumbents are going to struggle to implement. That's why I'm struggling. I'm thinking of it as a competitive question.
But if the struggle seems to be what you're suggesting, this is asymmetric or contrary to the way they would implement this new demand for privacy.
Balaji: Yeah, here’s the thing. A lot of people tried to separate blockchain and cryptocurrency.
They were like, ‘Oh, this blockchain thing is a great database, but this crypto thing it's weird and unregulated and volatile and it's bad. And so let's do it without that.’ And they tried to do enterprise blockchain where eight banks would get together and have some shared database. And that actually was the worst of both worlds solution where it had all the complexity of enterprise and all of the technical complexity of blockchains.
And the thing is that every application of blockchains will involve a crypto component. So the reason that big companies will find it hard to adopt this is… Why do people have these public and private key pairs? Because they have cryptocurrency, probably because they have an Ethereum or a Bitcoin address or a wallet locally on their computer. That is the prerequisite.
That installation is like having a web browser locally on your computer. And from that you can access internet. If you have a crypto wallet on your computer, you can access the financial internet. And if you do not, you cannot. And so these big companies, because they haven't yet grasped the nettle of how important it is to have Bitcoin and Ethereum integration in their messaging and payment apps, will not get that until too late.
They'll try their own in-house solution because they understand open source, but they don't understand open state. You know, they understand open source in the form of GitHub and open source code and whatnot. But open state is yet another level where it's not just a source code that’s public, it's a database that’s public. The Bitcoin blockchain is public. The Ethereum blockchain is public. Every user is a root user. It's shared state. It's the next step after open-source. They just don't get that culturally. And by the way, I wouldn't call it trusted end-to-end encryption. I'd actually call it something slightly different, which is verifiable end-to-end encryption.
It's end-user verifiable. So that's the big difference. Trust only if you can verify.
Horace: So that gets us to messaging. Potentially you get a situation where unless they buy the whole concept, as you said, the implementation has to be coin plus blockchain. So it's not just blockchain. It has to have this, sort of, pain.
Well, I call it pain because it's like you suffer if you lose, you know, it's verifiable
Balaji: Yes. That's right.
Horace: And, so I think what you're getting at culturally in terms of what's asymmetric about this technology is that it's not just utility, it's utility plus consequence. And that consequence or consequential nature, I think, is what is difficult to absorb for, not just the Big Five, but almost any larger platform company or technology as we know it.
We get into a state of triggered, let's say, consequences, which are negative. And people are just squeamish about it. And I think that you can't be a manager in these companies and say, ‘Man, the consequences of this, I mean, we could get sued, you know?’
Balaji: Exactly.
Horace: Am I getting close?
Balaji: Absolutely. Because, you know, what’s more scarce than financial budget? Risk budget.
Horace: Yes.
Balaji: Yeah. These giant companies have cash cows and are under regulatory scrutiny. So they don't have the risk budget.
They don't have the appetite for risk. And it's actually true that their risk is greater than that of a small company on doing this because they're under the microscope more. That doesn't mean it's impossible. [Jack] Dorsey has managed it with Twitter, but that may be because he's just under the level of scrutiny, where the Big Five are under that maximum scrutiny.
But even Facebook has actually said, ‘You know what, we're going to take the hit on this.’ I give them props for trying in the space. Simply as a founder, it's actually a non-trivial thing to do, but it is one of these things where the short-term incentives are so strong to not take a risk. And you really need CEO buy-in to do it.
I mean, as I said, Satya did a decent job on this, where Microsoft was relatively early on Ethereum support on Azure, and so on. And there's some of that. There’s some of the public cloud stuff they're doing, like the safe things. But putting it into Google Pay or Apple Pay or things like that, or buying it at the corporate level, these guys are all going to be late adopters on that because the risk budget isn't there. You need consensus within the company. And the thing about a crypto company is everybody is hired from the crypto country. Everybody's hired and they already have that consensus.
It's similar to the 1990s and early 2000s, and people thought open source was communism. Ballmer said something like that. If you remember that in the year 2000-ish. And this is hard to remember right now, but if you remember in the early 2000s, there was a cultural and ethical movement around tech, related to open source that was pro-Linux, anti-Microsoft, anti-corporate in some ways and so on. And that actually gave a lot of the early energy for people in technology thinking of themselves as the good guys.
And then over time the good guys became the big guys. And now they are sort of in play at safe corporate mode with lots of MBAs and spreadsheets and chiseling of customers and all the stuff that is hard to escape when you've got millions or billions of users and all this regulatory pressure. But it just changes your culture.
Then on top of that, they've got all of these political disputes internally at the company and leaks and all of this stuff. And so now crypto is like the next version of that, where it is not simply a technology, it has an ethical component to it. It has that philosophy, that community aspect, where it is returning power to the user, it is pro-privacy. It is decentralization as opposed to these centralized tech companies. That by the way, as a user —
Horace: I would even take it a step further. It has an ethical component, which may be a bit squishy, but I'd say it has even a political component. And I think by political here, I mean it's divisive in some ways. And you have to accept the premise that as a participant, you have essentially a partisan point of view.
And that itself is a giant leap because I think the neutrality of, the implicit neutrality, of a company’s governance is like, ‘You know, we play both sides of the aisle where we're going to be.’ And I don't mean this in the sort of left-right sense. But this is a new dimension.
Balaji: Absolutely.
Horace: And if you want to participate, you have to be willing to put yourself in that state. I sensed this myself because I find myself being drawn into this world. And that's been uncomfortable for me because I do not wish to be partisan. I do not wish to be political.
I do not wish to make a statement with my support for a currency or whatnot. But this discomfort also attracts me in the sense that, intellectually I'd say, ‘Well, that's interesting.’ We call the show Asymetric - as an asymmetry, it's fascinating, right? That you have to be in that dimension now. And that's what I think fundamentally would be the root of the disruption. In the true sense.
Balaji: That's right. I think I was able to articulate this in a recent post. That's the difference between Web 1, Web 2 and Web 3.
So Web 1, roughly, was about technology risk. Can we even build it? Can we make packet switched networks? Can we make web browsers, all of that stuff? Can we make operating systems? Okay. Web 2, it wasn't that tech risk went away completely, but much more of it shifted to market risk. Now that you had open source databases and you had all of this open source tooling, a lot of it was, ‘Hey, we know we can build it.We can snap together this web app or later this mobile app, but will people buy it?’
Will this consumer behavior be adopted? Will they use, you know, Snapchat versus FrontBack? If you remember FrontBack, there were a lot of these fruit fly type experiments with consumer internet, in particular, where the risk was not so much, ‘Will the app work?’ It is, ‘Will people actually buy it, will they use it?'
And now we're in the third stage, which is Web 3. With crypto [related] things, we know we can build it. The tooling has now become mature enough that it's not, again, there is still technical risk, but you can launch a token or a coin and we know people will buy it.
It's actually kind of interesting that there's almost always going to be some demand for the thing, at least, you know you can get it off the ground. But the question is now will people ban it? So in other words, Web 1 was about tech risk. Web 2 was about market risk, but Web 3 is about regulatory risk.
Horace: Yeah, that’s what I mean by political. I think I've used this word in maybe my own way because regulatory ultimately gets into the question of politics and that isn't, again, the classical left-right divide, but more like, ‘What is your philosophy? What do you believe in?’ What matters is your point of view and, and that you're forcing people to have that.
That's the thing here. I think it's forcing people and you cannot separate them any more, saying, ‘I'm neutral. I just believe in tech.’ It's forcing you to make a stand and that’s a very uncomfortable position for any corporate entity. It forces them to become partisan, in a way, on this dimension.
And that is what they will resist. I'm sort of taking your point here. And I'm trying to, myself, think of how this becomes disruptive
Balaji: You’re right. You’re right. When you're serving a billion people, they have an Innovator's Dilemma-like thing. The problem for them is that this is a, whether you want to call it political belief or partisan belief, or what have you, ethical belief, in decentralization, which is growing exponentially.
If you think about the number of crypto adopters as just one metric, it's like a hundred million today. And it was certainly not that in 2010. Sub 1,000,000, probably, sub10,000, probably sub 1,000, even in 2010. So that's massive, massive growth, but it's growth that they feel that, probably correctly, that it would be challenging for them to tap into without taking a significant messaging and risk budget hit.
Now, again, can they do it? I mean, as I said, Dorsey has managed it. I think Facebook could have, rather than doing Libra or Diem, they could have just built Bitcoin and Ethereum into their Messenger app and started with that. And that would have been smart. And they could still do that in VR, potentially. They're at least further ahead.
They've actually taken some of the hits internally on getting there. They've got some engineers, but the biggest companies that want to be all things to all people and do inoffensive things… You know, the thing which people tell startups, they tell them focus, focus, focus, focus, focus.
You almost can't focus too much on some micro demographic. You win there and then you level up, and you win there and you level up again. And the big company is not going to be able to focus because they're all things to all people. And that's now something which is no longer simply a market thing, but it's also a political / ethical thing, where you have to essentially bet on decentralization.
Horace: I'm starting to get it. Do you want to get into some of the others - we've done messaging, do you want to get into some of the others?
Balaji: So we talked about FinTech. We talked about messaging and, by the way, messaging is not simply, just like you go from email to group mail to Facebook threads.
Messaging starts with one-to-one messages, but every single messaging app will be rebuilt with verifiable end-to-end encryption, where you'll use your, probably your Ethereum name, but you could do one to one messages. You could do one to N, you could do N to N. You could do blogs, you could do blogs behind encryption walls.
You can do Slacks. All of these things are being built around so-called DAOs (Decentralized Autonomous Organizations) today, which combined sort of messaging plus corporate governance plus communities. So, relate to that login.
So right now, a huge moat for these big tech companies is log-in. With Apple login, with Facebook login, with Google login, with Twitter, where they've got hundreds of millions of users and you can use their APIs and implement logging onto your site, but you're also subject to them.
They can cut you off. That's no longer the case with something like ENS (Ethereal Name Service), where you can log in as Horace.eth. Just your local private keys are determined, not a password that can be reset, not account that you can be deplatformed from. That is a fundamental change where the solution to that equation, the private key, is held locally on your computer and that's the sufficient and necessary condition to log in.
If you have that you can log in. And if not, you can’t. So that completely changes login where it means that for example, you can't be deplatformed from social networks. It means you can authenticate also without people necessarily knowing who you are besides the fact that you have that key.
It's a structural shift in how you actually even log into systems and it's sort of like phone numbers or emails. Where, if I have a collection of your phone numbers or your emails, like on a sub stack, or in a set of numbers that have opted into text messaging, I can contact you. But even better than that, because nobody can even intermediate with the phone number the telcos could in theory, stop you. But with this kind of messaging login combination, they can't really stop me from messaging somebody on ENS.
So that disrupts Facebook login, Twitter login, Google login, LinkedIn login, all those - and it’s already happening with applications like Uniswap, for example, you could log in with ENS.
Number four: Social. So when you've talked about messaging and login, you get to social and social is basically just sending lots of different kinds of messages back and forth to each other.
Decentralized social networks are now actually out there and early and working. Just technologically - Mirror, Bitclout, Capsule Social, many others. A lot of the DAO chat-style networks are out there. I've invested in a bunch of these. I'm going to invest in more, no particular endorsement of any one of them, but decentralized social networks are now actually out there where every like and post equivalent is actually on chain versus simply in a centralized database. And the way of thinking about what a big deal that is is you do not have root access to Twitter's database or Facebook's database. But with a decentralized social network, a developer can hit enter and print out every tweet equivalent from the beginning. They can print out the social graph, they can index a social graph and they can search the social graph.
So there's applications, so-called block explorers. This gets us from Social into Search. One thing that is not very much thought about, because this battle happened almost 10 years ago, is how Google strive mightily try to buy Facebook. They were really annoyed at the emergence of Facebook and LinkedIn and Twitter because they were dark to them.
These are graphs that they couldn't search and they knew how big it was going to be. And they were like, ‘Oh, we're only gonna be able to index the open web, this is closed.’ The only thing that really came out of open social was the open graph standard. But they weren't able to get these social networks to open up their databases because, of course, they could make more money with them closed than open because if the database were open and anybody could read and write to them, well, they would not be any more the monopoly provider of advertising on their platform.
That's why Twitter shut down Tweetdeck and deplatformed all these companies that were initially building on its open protocol, it made more money with advertising vs having an open protocol. The critical thing that decentralized social networks have solved is the alignment of interests between the developers and the users and the platform creators where everybody just benefits from the token’s appreciation. And now you can build on this decentralized social network in a way that you could not do so on Twitter, because they'll deplatform you. You can't build on Facebook's API, they’ll deplatform you if you get successful enough.
So decentralized social networks, don't just enable decentralized social they also enable decentralized search because an underappreciated aspect of Google… First, a lot more searches are done on Twitter these days than people realize. I think it's, it's crept up quite a lot relative to Google. I'm not sure if you have this behavior, are there days where you search on Twitter more than on Google?
Horace: Not more, but there are days. And when I do, it's frustrating because I don't find searching on Twitter easy.
Balaji: It's not that easy, but —
Horace: But I sense what you're saying. Also with the Facebook problem that the shift to social from web was, I think Google dropped the ball there. I think that's one of the greatest failures that they didn't manage to transition to social in any way.
Balaji: Yeah, they got YouTube. That’s their big one that they did get.
Horace: YouTube was, yeah, it's the best thing they've done actually since search.
Balaji: So alright, so extending this point, a very important technical point where you’re thinking about search is [that] closed social network databases are harder to index in the open web, but blockchains are easier to index in the open web. And, this actually is something which most people don't realize, blockchains, until really the last year or so, were for the most part used to contain financial data.
And so block explorers like Blockchain.com or btc.com, that are indexes of the Bitcoin blockchain, or Etherscan.io [which] indexes the Ethereum blockchain. Those don't look like search engines to people, really, because the data structures they were indexing were things that weren't really things you thought of as being on Google.
You're looking for Bitcoin addresses and transactions and later on smart contracts and tokens, but these are very high volume search engines. And to show how behind the eight ball Google is, Google hasn't built a block explorer for Bitcoin, even. Or any of the major crypto chains. Forget even Ethereum, they haven't done Bitcoin. And that’s so within their core competency, it has zero regulatory risk, but just shows how behind they are, that they haven't done that in 2021. The reason that's important is what we've just proven over the last year, which is a huge milestone, is something like Bitclout or Mirror shows that you can host social networking data on a blockchain. There are others like Hive and Steam that have also shown this. And once it's all on chain, it becomes so much easier to index for the purposes of search.
People for example, stood up a thing, cloutavista.com to index Bitclout. This is a demo, I'm not saying any particular decentralized social network will win, but in 10 days they were able to stand up the search engine.
How long would it take you to stand up a search engine for Twitter? It would take basically forever because you need access to their API. They're not going to give you access to the API. And if they do, it's going to be very throttled and very expensive, and you'll have to raise venture just to pay for that. They can cut you off or change it at a moment's notice. They don't care about your business. And even if you give them a hundred percent of the company, they might not care.
Search will be transformed by block explorers. There's so many different ways from a technology standpoint that blockchains are easier to index.
Just one example, there are entire PhD dissertations that are written on freshness indexing. You've got a million websites, you've got a limited crawl budget. You can't crawl all of them every second. It'll make the servers mad, but it'll also use up your own bandwidth. And they don't update every second.
So how do you actually crawl them? Well, you have to have some statistical model of when they're likely to get updated and you have to go back to the website when it's predicted to have been updated and you have to have some provision for them going from one update a week to one update a day when you see a lot more changes than they used to have, and you're updating your parameters… It's this huge mathematically complicated thing.
And that's just one aspect of search indexing. And all that goes away with blockchains because you just subscribe and you get a block every 10 minutes or one minute, and it's got all the changes there. So, just the architecture obviates that entire —
Horace: It’s self indexing.
Balaji: It’s self indexing. You get a change set. You know, this is also related to the broader move towards, log structured databases and so forth, which, if you've got listeners who know about what's been happening in data science, that's been a big deal. But it all kind of comes together where you have Kafka and so on.
These change sets that are coming in, you can just subscribe to them as opposed to having to go out and get them. You don’t have to crawl. So that simplifies fundamentally - that alone makes search easier.
Okay. Going a little bit further. The Crypto Phone, you know what's happened recently with Apple and the CSAM thing?
The reason that it's bad for Apple to be searching your phone like that is today they're searching for photos with incredible possible levels of false positives, because people can put these adversarial machine learning images on somebody's phone and frame them for a very serious crime.
Tomorrow, though, they can use the same technology to scan for cryptowallets on phones. And it may be ordered to do so by governments. So that alone is going to mean, and there's already pushes for a crypto phone out there. Foundation Devices, for example, there are people who are building it. But a crypto phone is also important because of other things like payments. You have all this pressure on Google and Apple for payments.
The fact that you've got login, payments and identity, getting decentralized and app developers making more money and users having their funds secure. These are the kinds of pressures that could actually lead to a new mobile operating system. And actually that gets to the next point, which is Crypto OSes.
So that's actually where, unbeknownst to most people, the operating system innovation today is happening in crypto. The reason is, a blockchain like Ethereum has a compiler and a database and a built-in programming language, and is as complicated as a web browser in many ways. Because you can write programs on it.
You don’t just write programs on it. You write programs that interface with other programs on it. Ethereum is a programming environment where one Solidity program can call another. That's what it means to be composable. You know, you can take a loan and you can pipe it into a Dex (decentralized exchange), and you can pipe that into interest, and so on and so forth.
So the innovation in operating systems is happening in crypto where the operating system and the payment system and the login, and then eventually the social network, they're all just kind of baked into one thing that's happening in plain sight. But that's actually what comes after Android and iOS and Windows and so on. It's in plain sight and it's an operating system that also has the community, the fan boys, which are critical for it, because they're all the token holders.
Horace: I’m already extrapolating what you're saying. So my concern now is this, what you're saying is effectively, then… Let me put it to you from an investor's point of view and say, okay, I got you. It sounds like the value of Apple, Google and others will probably start to evaporate.
Balaji: Well, I wouldn't say… it's gonna take like 10 or 20 years. These are huge incumbents —
Horace: Like I said, I’m just extrapolating. I ask you this then, okay, what would you do instead? Who would take their place? And the answer, if I may, it sounds like there is no way to concentrate profit anymore in an operating system. Because, by nature, this isn't going to be replaced by another Apple or another Google.
Those business models will simply not longer be viable. You're going to have to find ways of creating value elsewhere. Because what you're saying, effectively, is search is not value accruing. Platforms that are effectively communication platforms are no longer accruing. And so that includes Facebook and messaging. And even the phone itself. So then, what would be the new empires if there were new empires to be built?
Balaji: The coins.
Horace: The coins themselves?
Balaji: Yes. Because basically, if you think about the whole fiduciary duty model of a corporation and people have pushed back on that, they said, ‘Oh, you know, a corporation has duties to the community, not just to its shareholders’ and so on.
Crypto answers that by making the community the shareholders.
Horace: So would you recommend any coin in particular or is, are they all pretty good?
Balaji: Well, they’re definitely not all pretty good. I would say if you're just starting out, buy Bitcoin. That’s just where to start.
I think Ethereum is also, obviously, at very large scale, and those are like the number one and two. Once you are familiar with… If you can only do one thing, buy Bitcoin. If you're a little more adventurous, buy 50/50 Bitcoin and Ethereum. Beyond that, I could go on for hours and hours about different kinds of coins and what they do.
But what I will say is if you think about what happened with the internet, it took all these different forms of media, like radio and television and newspapers, and it turned them all into packets. And what crypto is doing is it's turning every single existing financial instrument into on chain debits and credits.
Because ultimately what is a loan? It's debits and credits somewhere. What is a mortgage, what is a derivative? What is equity? What is a cap table? And the fundamental mechanism of value creation… what’s the most important data structure in Silicon Valley? You can argue it was the cap table. You know, the capitalization table determines who holds what equity. And that little Excel data structure, with a thousand odd rows is what led a thousand odd people to build Google in 2004 and align all these people from around the world to build this amazing thing. Even more than their billion row data sets.
That cap table is now on chain. If you go to something like the Brave Basic Attention Token, or any of these other tokens, and you look on Etherscan, you go from a thousand people to 50,000 or 100,000 or even 1,000,000 people that hold a given token.
So you've scaled up the basic aligning function of Silicon Valley, the equity shares for shareholders, into something that is not equity, but it's like Equity 3.0 or the sequel to equity. The problem with this, of course, is the reason crypto is not equity is it's API keys. It's something which you can use to interface with an app.
It is your encrypted messaging system. It is your login. It's all these things that a share doesn't do. And so fitting it into older classifications, like the SEC and others want to do is just sort of like trying to treat every packet that's being sent to your house as physical mail and requiring you to get a stamp for it and saying, 'Oh my God, I can't believe how bad you are. You're not in compliance. You don't have a stamp.’
It's this old way of looking at things that I don't think is going to survive long-term. I think we're in the middle of, you know how there's a Reformation and then the Counter-Reformation you're familiar with that. Right?
Horace: Yeah, sure.
Balaji: We're in the middle of what I would call the Decentralization and the Counter Decentralization in both the U.S. and China. They're pushing back on decentralization. Pretty hard in China and fairly hard in the U.S. And I think it's going to increase.
But I think the rest of the world also has a say. And I think what's really under-appreciated is, and this is kind of related to this also, you know, that Google, Apple, Microsoft, Amazon, Facebook have to deal with; the rest of the world no longer wants to have American tech companies be able to deplatform their political leaders in these countries. Or unbank them. And they don't want the Chinese companies to do so either because the new boss would be same as the old boss. So I wrote a series of articles on this, where what I think happens is that the new non-aligned movement is the aligned movement, the decentralized movement. Where just like many of these countries have actually said, ‘Hey, you know, for military or government purposes, we should look at open source software first versus proprietary software.’
They're going to, over time, shift to using Bitcoin and Ethereum and other decentralized cryptocurrencies for different purposes. Because they are a transaction and soon communications networks that cannot be shut down by American or Chinese companies. And that's another thing which a Google or Apple or Facebook can't really compete with because the whole point is it's not them. Unless they manage to launch a fully open source project.
You know, React is something Facebook launched that is a genuinely open source project that people can use. Because even if Facebook cuts them off, you can go and modify it. Unless they actually launch a chain and take the whole hit of doing that, they won't have the trust. Because people don't want them to have server side control.
So going a little bit further, advertising and e-commerce. So, the engine of Facebook and Google is CPM and CPC ads. Costs per impression. And then per click. Every thousand impressions, every click, you pay them. They don't usually do full CPA advertising where you only pay them when something is sold.
If [you’re] Casper mattresses, though, what you'd want to do is you say, ‘Hey, I'm selling a mattress for X dollars. I only want to pay Google when I've got a conversion that came through Google.’ The issue with this is Casper as an incentive to understate the number of conversions and Google has an incentive to overstate it.
You would need an incorruptible neutral third-party ledger of all transactions in order to actually do full CPA advertising. And guess what? That's what the blockchain is.
So CPA advertising is going to be an area where I think that's going to start really hitting the Big Five in an area where they don't expect it because the people within the crypto community, on both the e-commerce and the consumer side, the merchants and the consumers are at sufficient scale where if a pure CPA thing was introduced, it would just be better.
It would be something where you might offer discounts to people because of it. It gives you better analytics. And then what this also does by the way, is it's better for merchants because it means automated accounting. All the stuff that you're currently paying PwC or all these guys to do, can be turned into a shell script if all your stuff is on chain. Which is a huge thing, because it also automates diligence and then automates M & A, you can start actually stacking things. Once you, I mean, we're talking five or 10 years out, but once you start going from, okay, all transactions are on chain, then all financial statements are on chain, then actually M & A can be put on chain because these higher order abstractions can be built on it.
And this is sort of like saying in 1990, well, once you've got emails, you'll have blogs and social networks. We're looking far out, but that's what happens once you start having more stuff on chain, it becomes more programmable. Okay, so CPA advertising: there’s e-commerce, there’s accounting, a few more pieces.
[Let’s talk about] hosting. AWS. So, centralized hosting is going to be tricky to fight head on for awhile because you know, the scale, the capacity of blockchains isn’t there yet. But it's improving dramatically. And if you look at Filecoin and Chia, and of course, Bitcoin itself, Ethereum… one of the most remarkable things is a moat that I thought 10 years ago would be very difficult to disrupt, which is just the sheer scale of Facebook and Google's data centers, right?
That's something that seemed like only a huge centralized company could do. We have now proven that if the protocol is fixed, people will do massive multi-billion dollar international data center build outs, not just for Bitcoin mining, but for Chia and Filecoin and many other lesser well-known coins.
If the protocol can make money, people will buy the hardware and they will rack and stack it. And that means that many things that we think of as companies will be turned into monetizeable protocols and decentralized in this way. So the hosting, the data centers will get there.
Creator monetization. This is another attack where, you know, Facebook and Twitter are now trying to do these newsletters and so on. But for 10 years, 15 years, they really didn't give creators a cut. And with crypto, creators, don't just things like NFTs, they don't just make money from art, they can make money from equity-like appreciation. People can buy into their coin to go and attend their events, or you could log into a Substack equivalent by just holding enough of the coin.
So this combines like the earlier things I was saying about login. So the crypto, the encryption, the payments are kind of the same thing. It also kind of attacks the Big Five and other tech companies on the backend. It's like holding a coin is in many ways better than equity compensation. It's liquid, it's marked to market. If it's legal in a country, you would just do that.
Some countries are just going to be smart and they're going to stop with all this stupid stuff from the 1930s and orange groves… just using 100 year old regulations to harass founders today. You have to deal with it because that's what the environment is.
And you can, I think, make a very strong argument that crypto is not the same as equity because you can use it for API keys, you can use it for other things. But eventually there'll be countries, and actually, even in the U.S., Wyoming has passed DAO laws.
There are states within the U.S., both subnational and international regulators that are enlightened and are going to say, absolutely, we want the entire stock market on chain. We want the stock chain. We want the transparency, we want the throughput, we don't want to have the Robin Hood situation where we're still dealing with DTCC (Depository Trust and Clearing Corporation) and these antiquated ways of recording stock transfers with paper certificates. We want modernity, we don't want to talk about orange groves and try to fit a square peg into a round hole.
So I think equity compensation, the backend, that gets transferred to coins. And these companies that are used to outbidding are not going to be able to do so, because if you actually look at the growth of Bitcoin and Ethereum and other coins over the 2010s, as remarkable as the growth in the Big Five tech companies are, those coins make them look like slow growth companies.
The story of the 2010s, in retrospect, with zero offense to Uber or Airbnb or Stripe, it was Bitcoin. That was the biggest hit of the 2010s. It was bigger than all the other startups combined, because it wasn't a startup. It was a coin.
I mentioned FinTech, messaging, login, social, search, crypto phone and crypto OS, advertising, hosting, data centers, creator monetization, equity compensation.
There's also values. You know, this is very important, actually. It almost goes unsaid, but it shouldn’t. The initial values that tech stood for back in 2012, or thereabouts, Twitter called itself ‘the free speech wing of the free speech party.’ And there was a huge emphasis on this during the Arab Spring. And of course with open source. And that strain still exists. The current non-free and focused, very state aligned thing where you're censoring people, for contesting, what the WHO is saying, where the WHO changes what it said last week is, is basically the Western equivalent of the Chinese censoring Li Wenliang for getting the message out.
And I certainly don't agree with everything that is said on social networks, but I do agree that the centralized authority is not always right. And to simply treat that as truth and censor people who are saying something contrary to that means it's not a free society anymore.
So the values aspect, anybody who cares about those values, and those are some of the most ideologically motivated and committed engineers, those folks are going to crypto. Then there’s, obviously on the privacy end, you only get verifiability if you've got the private keys locally.
So you put all that together and that's actually a recipe for attacking enormous swaths of the whole thing.
There's one other aspect I'll add there, which is when the back ends become open, this actually disrupts APIs in a very fundamental way. Because right now, yes, you have APIs, but they're pretty siloed. You'd use a bunch of APIs in your app, but to make Stripe talk to Shopify, to this or that, maybe you'd use Zapier or maybe you'd write your own customer integration. It's not that easy to work with because you don't have root on those databases.
With crypto backends you do have root, you have total root access. Every user can look at every single row of the, it's not exactly a row, but every entry in a blockchain. Any user who owns coins can write and any user with sufficient compute can write blocks. And so, because of that, anything that's like the next Google Docs or the next messaging app that's built on a blockchain has much better interop[erability] between chains because it transforms what an API is.
API access, your API key, is holding the coin. And you can do anything you want so long as you hold enough coin, within compliance of the protocol. So what I just outlined, that’s essentially a recipe for 10 years of disruption.
Horace: Absolutely. But let me say this - I think it's not just disruptions of the Big Five as you put it, or maybe Big 100. A lot of possible asymmetries here. But my concern or, rather, optimism even, is that this is about institutions more, even, than private equities. It's institutions that have been built throughout the Industrial Revolution. And you talked about putting equities on, the very idea of holding paper to represent something else. The very idea of institutions, which are there to ensure transactions and trusts.
Those, again, I'm sort of parroting the ethos of coin, but you've effectively shown the roadmap as how it happens in the ways that are very tangible. My point is this - because when I wanted to have the show with you was to ask a sort of a profound question.
Is someone living in a 21st century, as my son was born in 2005, will they see as much change throughout their life as someone born in 1900? Or even someone born in 1800 living through the 19th century.
So if I asked this question of myself, because it's not so much about me but the next generation. And I struggled with this question because I felt like the first 20 years of this century, haven't been all that exciting in the same way that the first 20 of the last century or even the one before it. If you think about the 18th Century, sorry, 19th Century- early 1800s were very volatile. There were the Napoleonic wars. And then we ended up with the Industrial Revolution taking off. Steam engines, railroads. It was a crazy century. And then you get to the 20th and you've got World War I already would have passed [by now]. We would have had the invention of the airplane, the mass production of automobiles.
We were heading into the Roaring 20s by now, and the 21st Century looks pretty lame so far. And I thought to myself, you know, all of these changes… I am a technologist. So I think of all the changes that we saw in the previous centuries, it was due to technological innovation, due to inventions.
And the formation of the Industrial Revolution was fueled by capitalism. That's what we call it, capitalism. But I ask myself, and I’ll put the question to you, is: Do you think someone born in 2000 and then living 100 years, which is not improbable, would they experience this century in as much of a sense of wonder and change and drama that the 20th Century, now, of course, there's a lot of negative things have happened. But, fundamentally, someone born in 1900 dying in the 1990s would have seen a completely different world.
And that's exciting. That's very exciting to think that you're part of this dramatic, poetic change. And good and bad, but generally progress. And I would say I'm excited now from what I heard, that possibly the 21st Century will be even more exciting because it certainly would undo a lot of things, if what you say is true, but also might create new things we cannot imagine.
Certainly, 1900 Man would not have imagined life in the 1990s, no way. And I don't know if we can, and we should be humble about what will be created from this creative destruction that has to happen. But do you believe, as I do that, should we be optimistic that something will emerge, that will be even more exciting than than the last century?
Balaji: Yes, though, let me get my take on that, I actually did a whole interview - it’s funny because we think about some of the similar things, but I did a whole interview with Sotonye, which you might find interesting on this topic of 1800s, 1900s, 2000s, actually, in its own way.
My thesis is 1950 was sort of peak centralization. And in many ways, if you go forward and backward in time, we're getting more decentralized from then. So 1950, you had one telephone company and two super powers and three television [networks]. You had AT&T you had the U.S. and U.S.S.R., and you had ABC, CBS, NBC.
If you go forward in time, 1991, the internet frontier opens, NSF (National Science Foundation) repeals its acceptable use policy and allows commerce on the internet. Backward in time, 1890, the frontier closes, the western frontier. Frederick Jackson Turner, his [essay], the frontier thesis, where he talks about how actually it was the frontier that made America, more than even democracy or capitalism.
It was exit, it was immigration, it was the free soil. And the fact that people could just start a new community or a new business, or go out west and, and make their name on nothing that gave America its character. Now, of course, there's the Native Americans and so on, which obviously complicates that story.
With the internet you have a frontier that did not have that issue. And if you go backwards and forwards, there's lots of parallels where as the centralized state in the west, its grip loosens. We see the Coronavirus and the Spanish Flu. We see left and right fighting in the streets. And we saw that in the 1920s and 1930s.
We see the tech billionaires, and we have the Robber Barons of the past. We see the private banking era of the past, and we have the cryptocurrencies of the present. We see the same, well, not the same but similar, arguments in William Jennings Bryan’s Cross of Gold speech on monetary policy was a huge thing in the late 1800s in the U.S. and digital gold is an issue again.
We see fundamental arguments over the role of the state and all this stuff with sanctuary cities, and gun laws being different at local level from the federal level and states pushing against the federal government as similar to some of the tectonic plate movements in the 1930s with the federal government versus the states. And then also even the mid 1800s.
And what I think happens is all of those things get resolved in the opposite direction this time. Where if you ramp up from, arguably, the 1700s, you might track it all the way back to 1492, or something like that. But at least from the 1700s to 1947, technology's favored centralization.
You've had railroads, telegraph, radio, television, movies, mass media and mass production, where a few people could control a lot. And then you go to de-centralization with the transistor, the personal computer internet, remote work, smartphones and now cryptocurrency where you're decentralizing power away from the Maos and the Stalins and the Pol Pots. And even the FDRs. The people who run these gigantic countries, where who's the number two after them? All of this power is concentrated in a few people.
Now we're actually decentralizing it out. And, in many ways, people talk about inequality rising, but actually in many ways, equality is rising and that's actually what people have a problem with.
And what I mean by that is A) global income equality is converging because China, India, other countries have been rising, relatively, they were very poor 40 years ago. But it's not just them. It's also chunks of South America and Southeast Asia and Eastern Europe and Russia, and so on.
B) consumption inequality is plummeting because a kid in Nigeria or India or Brazil has basically the same Google experience as Larry Page because it costs just fractions of a cent. And then C) and this is to my point, power inequality is decreasing because some kid in India or Nigeria is not going to grow up to be the president of the U.S. but they can become the founder and CEO of their own tech company. Or their own crypto protocol. And so they can rise in a different way, which doesn't include migrating to the U.S. and doing that whole 20th Century rigmarole.
So I do think it's an exciting century in many ways. I actually think the 20th Century was a much worse century than the 19th Century, because the 20th Century was two world wars and communism and socialism for much of the planet.
It was okay in the U.S. and Western Europe. But [for] much of the planet, it really sucked. And now it actually might flip where the U.S. and Western Europe, the U.S. more so even, that feels like it's kind of… Maybe not all of the U.S. I'm actually bullish on individual states like Wyoming and Colorado and cities like Miami and so on. They've gotten behind crypto. And the reason I just keep saying, ‘crypto crypto,’ is because, as we just went through, the sheer scope of applications is difficult to realize until you've gone through it. It's really a big deal. It's a civilizational technology. It's not simply like a toaster oven or something.
So those states have gotten behind crypto. I think there's pieces of the West that are going to be good, there’s pieces that aren’t. And it's almost like a flip of the 20th Century where it's the East that is more capitalist, that's India in particular, but it’s also east Asia, it is probably Eastern Europe that is maybe more capitalist than the U.S., much of the U.S., and much of Western Europe.
So, that's my broad scope of history.
Horace: Yeah, I wouldn't be as… my judgmental question on better or worse was not really that most people would be better off or [had] suffered more, but more in this poetic sense. We feel like we've made progress
Balaji: Acceleration, yes. Yes.
Horace: And the 20th Century… I don't think that you can argue that the technologies that emerged, that someone born in that century would have witnessed —
Balaji: Yes, they go from out houses to flush toilets, and so on.
Horace: Yeah, exactly. Not distributed very well, but the thing about the 21st is I cannot imagine how it's going to go. But to me, I sense that we will [eventually] feel like we're making progress. And I think we'll feel, because the first 20 years, it hasn't felt like that. I mean, we've certainly had a lot of… the joke goes, you know, we didn't get flying cars, but we got 132 characters.
So there's going to be much more coming. And I think there's a sense of wonder in the sense of opportunity, a sense of optimism in the sense of the decentralization. But also, like I said, that optimism around the small states. I live in Finland now, but my point is -
Balaji: Yes. Small states, yes.
Horace: I said this once, the 20th Century was the century of the large state. The superpower was every everyone's idea of success. But now, I think it's going to be much more the small states that are going to be the 21st Century giants, if you will.
And so that's my point. I agree that it might be a very different feel from an individual point of view, but I think, as a civilization, we're probably going to look back, or historians will look back on 21st and say, what was the defining thing?
Like, I think of the 19th Century, sort of as the steam century. And I think of the 20th as the chemical engineering [century]. You know, at the end of the day, it was the fact that we built everything on top of energy that was suddenly released, right?
Balaji: Well, it's interesting, because I'd say the 20th century had a lot of stuff.
You can argue this, but going up to the moon landing. Then after 1969, outside of digital technology, things really slowed down. It's hard to think of some, I mean there's a microwave oven and stuff like that. This is the point Thiel has made, people have made this with the website, WTFhappenedin1971.com.
I think partially it is the gold standard, but partially it is, essentially, the sort of risk aversion that arose after that point in time. When nuclear power plants were made very difficult to build and regulations were enforced in such a way that it was just difficult to take risks, voluntary risks.
Balaji: It's by J. Storrs Hall. It's self published. It has a really bad looking cover, but it's really good. It's something where you learn something from every few pages. Highly recommended —
Horace: I did my own conference once on the subject of what happened to modernism.
The idea of utopia, it being foreseen in the 1950s based on technological progress, which, I put it to you this way. So if you were born in 1900, by 1950, you were middle-aged. But you would have seen all of this progress. And if you were, technologically sort of extrapolating it you'd say, well, that's where you get the flying cars by the 1990s.
So you see the ad copy, the way advertisers were, and the usual visuals from the 1950s of flying, or progress in agriculture, in transportation, progress in, not so much computation, but the extrapolation of the first half of the 20th Century.
And I pointed out that the last place where such optimism existed was in the tech sector because the rest of the country, the rest of the world, felt like it was in stagnation. And, again, we can quibble on this or discuss this on another episode. But I think we're in agreement that possibly this is the key.
If someone were to look back on the 20th and then say, okay, maybe it was internal combustion. But someone looking back on the 21st would say it's Bitcoin.
Balaji: Yes.
Horace: It’s crypto. That's the biggest thing that happened in this century.
Balaji: It is. I actually do think Bitcoin, the impact of it is at least on par with the steam engine. Maybe more like the Reformation or even the Bible, in terms of where it's going to be long-term. It is just such a fundamental, it's a social technology, because it just changes the relationship of people to each other and decentralizes power in this very, very, very fundamental way. And I don't think people get that.
Horace: I think that's a great thesis. That's what I wanted to do in this show is to sort of zoom out as much as possible. But you took us zoomed in to explain that these are the building blocks. And it's hard for people to, you need —
Balaji: Yes, crypto is too zoomed out in some ways, right?
Horace: Yeah, but you need the mind that can grasp this, can go both ways. And that that's very hard, flexible plastic minds. I've spoken to people in the community who are very nuts and bolts. And then there are some who are very idealistic and some very ideological. And most people, when they look at this and say, ‘My God, it’s filled with nerds and it's filled with ideologues. They're a bunch of maniacs.’ So it's important to bridge those two somehow. So thanks for all that.
Balaji: Hopefully this was good. We talked about applications and of relevance to your audience. Happy to do it again. This was great.
Last year's Micromobility Summit was a great success. We had a great turnout and the presenters and audience met to discuss the future of this new modal shift that seemed so imminent.
Perhaps partly because of our meeting, the shift has since accelerated. The amount of capital allocated, firms participating and usage have all exploded. In one year micromobility went from a curious hobby to the biggest startup story in the world now attracting mainstream attention.
Bird, Lime, Skip have pioneered scooter sharing. Smide in Switzerland is offering e-bike sharing and Uber, Lyft and Didi made acquisitions. More OEMs and Tier 1 suppliers are betting on this sector and we have hundreds of new e-bike models entering the European market and literally billions of vehicle miles traveled using micromobility. 400 million users are registered in China alone with 70 million daily active.
Micromobility Summit 2017 was the catalyst of several startups that operate in the space today. It was great opportunity for like-minded entrepreneurs to discuss this market.
It's time then to follow-up with the second Micromobility Summit. Coming almost exactly a year after the first, we will conduct a similar approach: speakers and panels covering the following topics:
Micromobility definition and categorization
Micromobility competitiveness relative to incumbents
Micromobility business models and asymmetry to macromobility
Regulation and evolution of normative behaviors
I will present research currently under peer review on the competitiveness of new modalities relative to existing and their conversion potential. Titled “When Micromobility Attacks”, it's an adaptation of a paper just submitted to a peer-reviewed journal (written with ETH Zurich)
If you would be interested in attending or speaking let me know through the sign-up sheet at the event web page.
Jim Zellmer: I thought we'd start by describing your education from the beginning, Horace.
Horace Dediu: OK, that's good, yeah. I like to say I'm the product of the public school systems. I went to public schools in three different countries, and probably maybe a dozen different schools altogether because we moved a lot, moved over 30 times.
My family emigrated, and we were what you might call political refugees for a while. We were stateless. We didn't have passports. We were officially not citizens of any country. So, for a period of about four or five years, that was the case. I started having regular schooling in Romania, and then moved to Italy and was enrolled in a school, actually, in the city of Verona, which is where "Romeo and Juliet" was originally set.
I was saying...my background. I spent a year in school in Italy, and I went to school in the north of Italy, in Torino. The thing was that I didn't know Italian, so I actually had to learn. But that's a lot easier for children. I was about nine, I think. And so, I learned Italian, was able to have a good school year. But then we moved.
In the summer, we moved again, and we emigrated to the United States. It took about a year to get the paperwork for that--because that was our ultimate goal was to be in the US. I was enrolled in the public schools. First, in Cleveland, where we found someone to help us. I actually went to, I guess, elementary school in the city of Cleveland, where we lived.
And then, later on, for middle school... What happened in Cleveland around that time was that busing started, desegregation. It would have meant, for me, more than one-hour journey across the whole city, from the west end to the east end of Cleveland, and my parents would have none of that. So, we moved to a suburb, immediately adjacent, which is called Lakewood. I went to middle school and high school in Lakewood, Ohio, for three years in high school.
And then, we actually moved yet again, to Boston. My father got a job in the booming tech sector at the time, which was in the early '80s. I ended up in a suburb of Boston called Medford. We didn't know much. Again, we were flying pretty blind here. We weren't familiar with neighborhoods or what were good schools or anything like that--"good schools." Mostly it was a question of, "Can we find affordable housing?"
Medford turned out to be a pretty lucky choice. In one hand, at the time, it was a blue-collar town. It was one of the near suburbs. So the closer to the city, it tends to be the older the immigrant generations are. It was settled mostly by Italian Americans. And so, a lot of the children I met in school were of some ethnic background.
Again, in the Midwest, that was a bit more rare. So East Coast, for me, was a little bit more vibrant in the sense that there were more interesting ethnic backgrounds and people from different histories and so on.
I enjoyed it, but I only had one year at Medford High School. It was actually more enjoyable, that year, I would say, than my years in Ohio. I have friends that I retained from that one year, and I don't have friends I stay in touch with from Ohio.
But it has changed. The city since has become much more, I would say, a lot of those families moved yet again, probably to a further suburb, and has changed character. I think it's more Hispanic now, the city overall. Nothing wrong with that, it just probably would feel different to anyone there now.
I was, again, in Medford. My choice, my next question, was where to go to college. I had been doing OK in school. And that was an interesting puzzle to solve as a kid, because you don't quite know how to fit in, the usual problems. Fortunately, having moved around so much, I had a pretty thick skin, and having had an accent or a strange background just made you a little bit tougher. And so, I was pretty immune to some of the high-school politics.
I focused on studies, and my parents are both educators. My father has a PhD in mathematics, and my mother had a Master's in mathematics and she taught. Actually, her job was as a teacher. They both got certified as teachers in the United States. My father had taught, also, university in Romania, but he ended up teaching high school and other two-year colleges in the US. It's very hard to go into academia from another country.
In any case, the fact that I had such devoted, academically inclined parents helped in focusing me on academics. That also, I think, was my nature. As far as college, my concern, we always had financial concerns, right?
Jim Zellmer: Right.
Horace: So, for me, I wasn't interested in the social aspect of college. For us, really, the decision was, "Can we keep expenses down?" I was accepted at Tufts University and also at Brandeis, which were local. That was important to me, that it would be near to my home and I could actually commute to these places.
Tufts was slightly better. It was a little bit closer. It was actually in Medford. So, I almost went to the college that was nearest to me. It had a very good program, also, in both engineering and computer science.
The odd thing is now, in college for me, was that - it's almost accidental - but, they had an option for you to take two degrees. The dual degree program was meant for people to study liberal arts and engineering. The idea would be you'd be a well-rounded individual.
The weird thing is that when I went there, which is 1985 to 1989, the School of Liberal Arts included the mathematics department and included the computer science department, which is a spinoff of the math department. So, computer science was a Liberal Arts degree; whereas, engineering was like electrical, mechanical, and so on, the traditional subjects.
I enrolled in the dual degree program with the intention of obtaining a computer science degree from the Liberal Arts School and a computer engineering degree from the School of Engineering. That meant that I would essentially take about 30 percent more courses. I think it was 50 credits versus the standard 30, or so. So, I was going for incrementally more material, but I would end up with two bachelor's degrees.
That's what I did. I actually also did it in an accelerated fashion. I ended up doing that in three and a half years, rather than what they expected it to take, five years.
Jim Zellmer: Wow.
Horace: That involved a lot of summer school. I was actually going through taking some of the requirement courses in the summer. So, I was basically a student 365 days a year and I managed to get the two degrees.
In the third year, there was one of these internship opportunities for research in a lab, GTE Laboratories.
Jim Zellmer: I'm sure.
Horace: GTE Labs was, again, local, which was important to me. They actually put us up in the dorms. So, the only time I spent living in a dorm was during the summer of my internship because it was paid for by the employer.
That was a great time. I loved it. I absolutely adored it. Those years right at... In my third year, which actually was my, I guess, my second year as I was a junior a bit early, I was going through this internship and I was studying, I was going working in the research lab. Then I ended up doing my senior year, my last year, I kept going back there. Somehow they kept me around as a part time employee because the project I had been on turned out to be useful.
It was in the library. I was actually working on indexing, which turned into search, which turned into Google later on, but we didn't know what it was then. We called it information retrieval. The algorithms, so we now do search intuitively when it actually became a commercial product, but it was something we did as research back then.
It was great because I was getting the experience I wanted desperately, loved it, and then I was still in school and I managed to get my degree. I was even earning money while I was doing this. It worked out very well, but it was a very tough period.
I graduated with not the highest scores, but I think I was magna cum laude, or something like that, which is not summa cum laude, but it's pretty good. It's like 3.8 GPA, or something like that. That's it. I don't know if that's what you wanted to hear. Then, of course, I did grad school.
Two years, while I was still employed. I took a full time job at the labs, then essentially I did two years. In '92, I got my Master's in computer engineering. Then I spent about a year or two figuring out what to do next. I went to New York to have a bit of experience. Oh yeah, I remember. I applied to Harvard because I wanted to go to business school. The reason I wanted to go to business school was I didn't understand business.
Jim Zellmer: [laughs] How did that play out? MBA's are often criticized.
Horace: Yeah, I'll tell you how it played out. Well, first thing is this. I'm sitting with my friends. We're all engineers, hackers, if you will. We're like, "We don't understand. We don't understand how we get funded."
Here we are sitting in these nice offices, but how does this company, who's basically a boring utility, how are they going to fund us to do cool stuff? We just compared notes and nobody knew. I realized none of us knew how business worked.
I said, "Well, I better learn about this." To me, I had been so focused in engineering that all this business stuff, the only thing I knew was because I would read the "Wall Street Journal." I didn't have either friends, acquaintances, families. All my friends were nerds. All my family were educators. I knew nobody, literally not one person, who could tell me how the stock market worked.
I would pick up the Wall Street Journal, read it cover to cover, and I wouldn't understand what the heck they were talking about. It sounded very abstract to me. It sounded like I need to learn something that there was something missing in my education.
I felt that the only way to get that training was to go to business school. And so, I applied. I was rejected, and the assumption was, in my mind, that I was too technical, too focused in a very, very narrow niche. Back then, there were headhunters that were trying to headhunt people. So, one headhunter got a hold of me and they said they had an opportunity in New York. I said, "Oh, New York. I know they do business in New York. So I better learn more from going to New York."
And so, I took a job with Chase Manhattan, at the time. It's called something else now, but it was Chase Manhattan. The job was also in IT, but at least it was IT, more pragmatic--corporate technology they call it. But I was there trying to understand more about business. I would still read the "Wall Street Journal" every day, still wouldn't understand it.
I reapplied to business school. I told them what I did. I said, "Look, I took this job because I wanted to learn business." I think I somehow convinced them the second time because I was so mad to do these things.
Jim Zellmer: Persistent.
Horace: Persistent. Somehow, I got accepted. I'll never know how they made that mistake.
Jim Zellmer: [laughs] Yes, of course.
Horace: But, anyway, once I went there, I was like, "OK, teach me." Now, the problem was that you start to learn with the case method, and you realize pretty quickly that there is no real curriculum. This is actually a lot of examples you're being given. It's not even empirical. It's like, "Let's throw a lot of examples and see if something makes sense in a pattern somewhere."
Jim Zellmer: This was Harvard?
Horace: Yeah. So, Harvard Business School. It was the only school I applied to, because I felt I didn't know how to qualify quality in terms of business. It was just a brand name. If you know nothing about phones, you just buy the iPhone because you know it's the best, right? So that was me, very naive. And throughout the school, it wasn't as rigorous.
In many ways, it was easy, because in engineering, engineering is very hard. You have to take test and you have to get answers right. And then in business school, it seemed like you just had to talk and you had to be articulate and you had to somehow be sufficiently smart-sounding to succeed.
Jim Zellmer: The theater, aesthetics.
Horace: Yeah. They drilled that into you. They said, "This is what we're teaching you is how to basically be a leader," and that leadership meant being proactive, not being passive. It meant getting in, if you will, on the discussion. I got that. I got it. It made sense to me because, yeah, in the meeting, if you sit there and say nothing, probably no one pays attention to you. You won't go anywhere in life.
So that was one of lessons. The other ones were about vocabulary. What we're not learning here, however, is that there's axioms. There's no specific rules of business. In fact, if you were to put rules down, there'd be many which would contradict each other. One of the classics is that money now is better than money later. But you need spend money now in order to have money later.
Jim Zellmer: [laughs]
Horace: So these two things are contradictory. There were no rules in business that made any sense as if you were proving a theorem or something like that. I decided all right, let's just go with the flow. I met nice people. I learned more from a lot of people.
The best thing that happened to me is that I had Clay Christensen as a professor. He was the nicest guy. The way he taught, it just resonated with me. He hadn't yet published "The Innovator's Dilemma." He was only teaching us operations, which is a first year course.
It's the only technical course in the sense that you do some process diagrams and you do some analysis. Finance is another analytical course, but the math is pretty straightforward. It's not very conceptual, in a way. Accounting is not either. It's interpretation.
But the professor, Christensen, he had a way of speaking to me that made sense as an engineer. It wasn't just me, there were a lot of people in the class who just felt that this guy was getting to the heart of a lot of the questions that we had. I took him as much as I could. I also had the option to take him in the second year. But, unfortunately, there was change in the dean and I think he had to change courses that he was teaching in the second year.
In any case, we had a good two years there. My question was, what do I do after I graduate? This was 1996. The Internet, at the time, was just emerging. Netscape existed as of 1994 or 1995. There were no Internet business models per se. Certainly, there was a technology industry. But it was pretty much boring and either IBM or commodity PCs and you had a bunch of software companies like Microsoft and Adobe.
It was already getting a little bit tired as an industry. As an MBA, it wasn't really that exciting. Everybody was doing either consulting or investment banking. Those were the typical ways of getting out of school. I had, of course, done something different. I did a startup. And nobody...
In fact when I told people I wanted to do a startup everybody said "You came to the wrong school. No one goes to Harvard to learn how to do a startup. There are specific schools that train you for entrepreneurship." Like for example, Simmons or something. I forgot the names now. Maybe that's a women's college. I don't remember the names.
But the point is guys were saying "No, when you come out of here, you are either going to become a CEO of a Fortune 500 company or you're going to be a consultant for life or you're going to be in finance, managing other people's money or in private equity." I was like "Oh man. All right, well, whatever."
Jim Zellmer: [laughs]
Horace: I went and did this startup. I did a startup with no VC money. It was done with a partner in California who had raised money from the government using SBIR grants.
We're talking the Department of Defense, and we were doing algorithms research. I went back to my university and recruited an engineer who I worked with in a basement office right off of Massachusetts Avenue. That was in '96. We built a system. We ended up licensing it to Adobe. It was a plugin to Acrobat. We didn't benefit much from it financially. Other people made a lot of money but not us.
But we did learn a lot. So I'm thinking: In business school, I didn't really learn how business works, but I have this degree which gives me credibility. Now, I'm going to do my own business...
Jim Zellmer: It's a ticket horse, yes.
Horace: Yeah, but I did my own business. I threw away the ticket. It didn't help me at all. What I was realizing, for example ... I didn't know how to do sales. I thought when you're doing your own business, you actually need to know how to do sales, and they don't teach you that at business school. I actually went and took a sales course, like they do in a daylong seminar.
I'm saying there are so many pieces that are missing. I didn't know how VCs, how to handle VCs and how to do pitches and do all these things. And none of that was taught, so I thought, OK, what I'm going to do? I'm going to do on-the-job training. I'm going to figure this out. And [learn from] networking with people in technology.
Eventually, I decided from the learning we had in the first startup to do another one, to do e-books! That was 1999. I'm trying to do an e-book startup in 1999. [So] I get on a standards body. I'm doing something with folks and I'm actually in a standards group that includes people from Microsoft, from Adobe, from a bunch of other startups, and from Nokia.
Actually that's where I met someone from Nokia, who...
At the time--it was 1999--I realized at that moment, with or without Nokia, I said, all computers are going to be handheld devices. This is so obvious. I can't express how obvious it is. I was interested, because Nokia had pretty much at the time the best mobile devices.
Jim Zellmer: Yeah, they were the player, no doubt.
Horace: I was asking myself, look, everybody in the U.S. doesn't get mobile. It's obvious that either it's Japan or Europe. And so, the question in my mind was, do I stay with the technology industry and try to figure out how this mobile computing will play out, or do I go to somebody who really knows mobile and expect that they will actually figure out how to become a computing company?
I chose the latter, partly because they also offered me a job and the dot-com bubble burst, and I wasn't ever going to get funding for my e-book business, which was called Handheld Media by the way. It was a great idea, great business idea, that we would actually help publishers convert books. Because at the time, the publishing workflow didn't include exporting tools. You either went to print or PDF, and we had this tool that would reformat a PDF book into a publishable format, like what e-pub is now.
Jim Zellmer: E-pub, right.
Horace: At the time, it was called OEBF, Open E-Book Format. It was using HTML, a variant. I actually had a workflow I could execute on my own and I could basically produce e-books. I did a couple of dozen, mostly as trials. I remember them even now, actually going through and manually extracting hundreds of pages, fairly quickly though.
But, anyway, that all came crashing down because although e-books were still interesting, there was no more funding in the docket. I had the opportunity to work with Nokia because they were actually very interested in launching something, not necessarily in e-books, but in media distribution. They wanted to sell music. They wanted to sell video. They wanted all those things in 2000. I came to them. Now, I'm playing my ticket, my bus ticket.
[The job] was something about how to do business strategy. They hired me. I had this technical background as well. One year I spent based in Boston. But then I was fairly quickly moved to Finland because that's really where you need to be to have any career opportunities. I was young. I was not married. Finland has its charms.
[I met] another American ex-pat who had moved there before I did and he extolled its virtues. I was pretty sold on that. Even though you pay more taxes, you get less wages, everything I did was economically the wrong thing to do.
Jim Zellmer: [laughs] That's a learning, though, too. You've learned a lot. Looking back on all that, Horace, what might have been better or more effective? When you think about your kids today...?
Horace: I don't know. I'm probably having too long of a chat on this, I mean fooling around this. But yeah, I'm very conscious of education, as I said. I realized pretty much after a year after leaving ... When I started Asymco, it's very weird. Again, you never know when you start down a journey where you're going to end up.
It was purely going to be app development because apps were just starting out. Apps were really almost invisible or there was no development going on in Europe. So my idea was why don't I bring iPhone apps into the land of Nokia, because here it's a green field site.
Jim Zellmer: Yes.
Horace: But it was a tough sell. I got one customer, but it was very, very tough. I wanted to bring apps to small and medium companies. I was going to essentially do apps as marketing material, like apps that are essentially a branding thing.
I was naïve also about the Finnish business culture because I think Finnish businesses are extremely conservative and that wasn't playing out. But the fortunate thing was that I began to blog because I had blogged while I was inside Nokia. I told that story about how I started doing it because I realized I wanted a bigger audience.
Then when I left, people kept saying "Why don't you do that while you're on the outside, just for fun?" I took that year to figure things out. I went back to writing my blog. Then, literally, everything was happening in 20 minutes. It was like a fire hose. I had to learn everything. I kept asking: OK, how do I do this?
So, I am learning every single thing, because I had done it inside Nokia where it was movable type. It was a completely different system. I didn't have to set up anything. It was very simple. It was done for me.
But on the outside, I am having to do it all myself. I started using actually iWeb, which at that time had a blogging tool. So, I opened an account on MobileMe. I was just putting everything through the desktop tools. They were right under my nose. Then I realized the limitations of that, and I moved to the next thing. I was like, "Oh! Seems like WordPress is something people use. Let's go to that." So, I went to WordPress.
Then I realized, "Oh! Hang on! If they are hosting me, they are going to put ads in my stuff, and I don't know what they put there. So, I better host myself...how do you do that? " I need to find a hosting provider. How do you do that?"
So, every technology, every bit of knowledge I had to have, I obtained strictly on my own. I say that every single character written in Asymco and every single mouse click that made it possible was performed by me.
I had no technical support at all. It helps maybe to have a computer science background, but years had passed. So, I was able to... Here the key to the whole thing is that, every step, I am learning, and it keeps me motivated. I am like, "Oh! I understand how this works."
I had some friends, who were more technical, and I would ask them, and they would say, "Oh! You are wasting your time. You can't get any traffic. This won't work." I would ask: "Tell me about Twitter", and they would say, "Oh! You're better off on Facebook." I was like, "Oh! Man!" Every single thing that I was given as advice turned out to be...
Jim Zellmer: Wrong?
Horace: Yes, doing the opposite would actually be the right thing. And so, I started learn about stats, the numbers game of blogging. So, how does that work? What does it mean to have good traffic?
I didn't expect to get advertising revenue, but I was thinking: what does it mean to be successful? So, I would go to John Gruber's site. John puts up his own rates, and I am like, "Oh wow! Look at the numbers." He actually tells you how much he charges per week, and then he says he is fully booked. So, you know what his income is. And so, from that, I was like wow! That's my goal I said to myself.
If I can get the traffic that Gruber gets, then I can charge these rates. I was trying to figure out how much traffic he was getting. He was getting like four million page views a month. I said, "I don't know if that's a lot or not." It certainly is a lot to get money, but you know, how do I get from zero to four million? So, what happened is that also when I was starting out, I reached out to John by email, directly by email.
Some time before I mailed him and said, "I used to work at Nokia and there's a couple of things you're writing about that I wanted to amplify or I wanted to give you some background." He has great stuff, and he actually used my material in one or two blog posts. I wasn't blogging at that moment.
But once I started blogging I mentioned to him, I said "Remember me? I sent you that info, and now I have my own blog." He didn't say anything. But then I wrote, I think the first piece that I wrote that was provocative. It was why someone at Microsoft had been fired or something like that. He linked to me. Then I saw. Then my eyes were open, because then my traffic... from zero to 12,000 a day.
Jim Zellmer: Yeah.
Horace: 12,000 views, for me, was like infinity. My server crashed and all that. I went back [to him] and I said "Thanks for the traffic. Now what do I do because I need money to be able to get this traffic managed." He said "No, you don't need money." You need to turn on caching." I was like "Oh."
Jim Zellmer: [laughs]
Horace: That solved the problem. But then I was asking him "So where do I go from here? Should I think about putting ads on my site? Is that the right thing," because I was so naïve. And he said "No, no, no."
He gave me one piece of advice. This is the only piece of advice I ever got from and from anybody that was useful. He said "Don't put ads. Just do what you do. Your value is in the future. Just keep doing what you're doing." That's all he said, one line.
I said "OK. If he says that, I believe it. That makes sense. Let's do it." I kept getting better at what I was doing, basically writing as well as I could, getting the feedback from comments and learning every step of the way.
This is still going on. One year on, I learned what Twitter really meant. I didn't know Twitter. The first thing I learned at Asymconf was what a hash tag is good for. [I mean] I knew what they were. But I did not use them. I never used a hash tag before Asymconf because I don't use Twitter that way. I don't use it to look up stuff. I mostly use it as a way to get my word out and get feedback, just like a mini micro blog.
But then I didn't understand the potential of a hash tag. It dawned on me when people were writing about Asymco and using a hash tag and if I searched on that I could find out everything that everybody said about it, a great idea.
But that I learned again just a few days ago. So many things I learned, thousands and thousands of details. So many things that the tables are now turned. Now people expect me to teach them about blogging.
Jim Zellmer: Yeah. [laughs]
Horace: For example, how to get traffic. A lot of people are sending me emails with paragraphs and paragraphs of effusive, "Oh you are so great. Thank you so much. Can you help me with this?" I'm like "Well, you don't need to say any of those thank you things, just tell me what you need."
A 15 year old sent me a request for an online interview. He made it easy. Five questions. So sure, I'll answer five questions. I treat everybody equally. Whether it's the Wall Street Journal or a 15 year old. I give them equal attention. I learn as much from both. The kids will teach you more, actually.
Jim Zellmer: Given all of that, if you were entering college today, what would you study?
Horace: I would still study engineering, absolutely. I am at heart an engineer. My son, I hope he does the same things I do. When I was a kid I loved building things.
I loved building Lego, although I didn't have money for a lot of them. I loved building model kits, the little plastic model kits, planes, and so on. That's not fashionable anymore, and mostly, it's old men who do it nowadays.
Jim Zellmer: [laughs]
Horace: [But] I'm trying to teach my kid. I actually bought a whole bunch of kits and began to model again so he could see me do it so he would get a passion for it.
I think building things with your hands, learning how things work, being passionate about numbers and about technology and things that are tangible is the only way to really create if your mind works that way. I'm not saying it's for everyone. To me, that's the heart and soul of progress.
By the way, I didn't mention this, but my parents also infused in me a love for the arts, and not "modern music". Being Romanians and of a certain age, they weren't ever part of the Rock and Roll, if you will, generation, although they knew of the Beatles.
So, they listened to classical music. Throughout my life I was exposed. I was taken to the theatre, opera, ballet. I used to sit in these performances since I was five years old. I maybe didn't get it. I wasn't talented. I tried to play the violin. I wasn't good at it, but I understood, after repetition, I understood the value of that.
When I went to that liberal arts college and got my degree, even though it was in computer science, I had a lot of requirements. I had to take English poetry. I had to take Japanese art. I had to take a lot of courses that were basic requirements. At the time, they were a burden, but in retrospect, they actually taught me a great deal. I'm very proud of having that background.
I'm not saying to not have an arts education, but absolutely, if you have the skills and can execute or can perform as an engineering student, do that and do the other things. Do the other things which develop the other half of your brain.
Jim Zellmer: Where did you learn to write, Horace? You write very well. Especially given that English is not your first language, you're able to be succinct and you have a wide ranging command of the language. So, where did you learn that?
Horace: Reading, partly. OK, so I have to give a lot of credit, and I did once on Twitter, give a credit to my English high school teacher. I said if you like the writing I have on Asymco, you should thank her.
Actually I wrote to her. She had seen my work in "The Boston Globe." It had been syndicated from that or something.
Jim Zellmer: [laughs] Wow.
Horace: She wrote me an email saying me an email saying, "I'm so proud to see your work and I sent it to your calculus teacher, as well."
They were both retired. The calculus teacher had seen my work in the financial section, actually. He sent her a note saying, "Check out the. . ." They read the paper. These are from that generation, right?
Jim Zellmer: Yes.
Horace: I've never seen my work in print. I've seen it online, but there it was. I thanked her. What I said is this: What she taught me was to write plainly and write clearly. This was Medford High School, a working class neighborhood, nothing special about it.
The teachers I had in English in Ohio didn't instill in me the same passion. The same books were read. Right? The same classics.
Jim Zellmer: Classics, yeah.
Horace: Twain and Conrad and all those classics, but the teacher in Medford, when I would write an essay, and also, I think, there was positive feedback because I was perhaps a little bit better than average in her class. Better than I was in Ohio. There I was about average, maybe.
I had good grades, but I didn't feel like I was great at it. I was nervous because a lot of the tests were vocabulary, or a lot of the tests were not essays.
This teacher instilled in me the passion for writing good essays. She kept telling me how great my essays were. I was writing somehow, and I loved reading the books. That's the other thing, the other kids would cheat. They would read the Cliff Notes.
Jim Zellmer: Yes.
Horace: They would copy from each other or do all these things. I was like, "No, no. I want to go home and I really want to read this book. These are really nice books." So, a lot of reading, a lot of passion for reading and I think practicing with essays. Practicing, also, in the writing of work online.
Now, again, when I look back at my early stuff, I cringe. It took me a while to find my voice. I didn't know what a voice was. I figured that out quickly. Then I had this challenge of working in the rigor of data. I realized the way to make my stuff stand out is to avoid opinion, to avoid hyperbole, to avoid all these things which bloggers seem to do.
So, anyway, it took some time. I think there's both a lot of ability, like, Einstein said, "It's 20 percent ability, 80 percent perseverance or perspiration." It's just practice. The other thing is it's like an athlete, right? An athlete gets good because they practice every day.
When I set out I said, "This is so much fun. I want to keep to it. I want to write a story every day. I want to write a blog post every day. I pretty much stuck to that. I was even writing on weekends, but I stopped because time, family. But, I write every day. I think of it as mental athleticism. You've got to go running every day if you want to be an athlete. You've got to write every day if you want to be a writer.
I heard, later on, that Jerry Seinfeld said he wrote every day. That was his key to success. He always tried to write jokes every day. That, to me, is what I learned. You bite your tongue sometimes, you learn how to deal with comments. Through comments, you see exactly how people make mistakes. They make mistakes by getting ahead of their thoughts, or they are too impulsive.
You get this great sense of what makes it good and I thought myself being able to write things. I write email in a good way, crisp in the email. You get a sense for it. For example, if somebody sends me ad copy, like a sponsor, and they send me a copy, I sometimes cringe when I look at it.
Jim Zellmer: I noticed that!
Horace: I can't help myself, I edit their copy, and even though they probably don't want me to, there is no time to go back and do feedback. But it's something you learn as a skill.
Some other people have asked me, "How can I teach my son to write well?" To me, it's not about being able to do more, it's actually being able to cut stuff out, and just go straight to thought. Maybe it takes practice.
Jim Zellmer: Now that you are a parent in Finland, your children are in Finland, so what choices do you have for your kids'?
Horace: We are very conscious of that. So, I like [Finland]. Well, I came for one reason, because, it was a wonderful place to play. But I stayed because it's a wonderful place for families.
What Finland's known for, among other things, is that it has the best scoring students on tests ...So, their educational system is considered absolutely in the top, literally top of the world.
There's a lot of mystery about why that is, and you can't really put your finger on it. A lot of educators from Finland have been on world tours trying to explain what they do, and everybody comes away scratching their heads.
I think this actually goes back to Christiansen theory, because when you study it people want to see a formula or an algorithm, but in fact, what is happening is, is something about whether the system is integrated or modular.
Whether the system is centralized or decentralized. So, it's not a question of process. It's like when he approaches health care, he comes at it from these two different angles. He says, "It's not about being public or private. It's being modular or integrated."
The assumption in other countries is always that everything is modular, and it cannot be anything else. So, in a sense, you need to question down at the deeper roots of causality.
So, my son, just to give you some perspective. He is now in pre-school.
He is six now or he is in grade zero, as they call it here, and he is going to a French school, meaning that they speak French in class.
Jim Zellmer: An immersion school. Yes.
Horace: There are several language schools like this. We're going to the French one partly because his mother went to a French school, his uncle went to a French school and they have loyalty to it, but also because I'd personally like for him to learn a romance language because I knew one. I still know Romanian. I had learned Italian, and I took French in school myself.
The thing is that it doesn't cost any more to go to that school than any other school. All education is free. Not everybody can get into any school, but it isn't about money. The other thing is that it's a small nation.
There's only about five million people, so all the decision-making can be centralized. There is no local school boards. There's no organization down to the smaller units that you might imagine. It's very simple and it's top down.
If you were to try to do a top down approach for a country as big as the United States it wouldn't work. You can't really transplant this system. People are very wary of centralization and control and the decision-making at the top that is incompetent. I completely understand that.
However, this being a small nation, it works and it's central. There's a question of optimum size. I mean, in some sense five million might be the right, maybe 8, even 10 million maybe works. I don't know beyond that.
There's also the question of how different the people are in terms of homogeneity. Although Finns are fairly homogeneous, there are minority groups as well and there's been plenty of immigrants. I'm not an expert on any of this, but I'm just pointing out some minor details.
I really like the school system. We actually had a parent teacher meeting this morning. They're very relaxed. Children seem to be much more relaxed. This is one thing that came across from the educators meeting and discussing around the world.
There's no pressure. Even though they're performing exceptionally well, there doesn't seem to be that pressure on testing, on measurement, on all these things that supposedly correlate with performance. In many ways, it's asymmetric, or doesn't make sense to people who are steeped in education theory.
I don't know if that's advisable, though. The problem, again, is that it may only work in this context. It may only work in the Nordic country, but we're very happy with the way it works. It's the same thing, by the way, with healthcare. Healthcare here is also centralized. It is a public resource.
Jim Zellmer: Yeah. What's your sense of the teachers you've encountered? One of the things "The Economist" reported a couple years ago was that Finland requires master's degrees from teachers. Contrasting that with what you experienced in America and Verona and Romania, do you have a sense of differences in the teacher capabilities, or no?
Horace: Because here mostly all degrees are considered Master's, it's essentially, I think, five years of school, of education. There's so many differences I can't even begin.
My wife, for example, she has a master's degree. A bachelor's degree would be more equivalent to like a two year college in perception.
Jim Zellmer: OK.
Horace: So, if you have a technical degree...a lot of people drop out. They get out because it is somewhat long and tedious and it is also not conducted in the American's style of valuing... It's so hard to explain. I actually would like him to go to university in the U.S., but I'd like him to go to every other school in Europe, or in Finland, more specifically.
I think the U.S. higher education system is better. It's better because it actually doesn't teach you according to a cookbook. It's actually much more open. In a way, that's the opposite in the lower grades.
Jim Zellmer: Yes.
Horace: The lower grades are open and the students are given a lot more freedom, and the teachers are given a lot more freedom. So, it's the opposite.
You'll see this, also, in Japan. Japan's educational system is a bit of a joke because they drill so hard in order to get good scores and get into a good university, but once they get into the university, they do nothing.
The entry is your ticket. After that there's hardly any effort. I've heard from others that the way university programs here are, many students will stay in for 6, even 10 years. It takes a long time because they'll drop in and out. They'll take a couple of courses. They'll do something else.
It isn't rigorous in the sense of, "Hey, the clock is running. This burns a lot of money. You've got to get a job to pay off loans." Because you've got that pressure on you in American universities, I think people actually are faster. It's more efficient. It tends to also draw more talent into it. The professors are more ambitious.
So, there's something I like about the U.S. higher education system, although if you listen to Clay, he'll say that it's also being disrupted, and he's probably right, especially the bigger names are going to be pressured from online education.
Jim Zellmer: Given your steep experience in technology and engineering, what is the role or is there a role for technology in education? Certainly in America and other countries we have all these people who say "Gee, our kids don't have iPads, they're just falling behind," among other things. So what is your perspective on that, Horace?
Horace: Well, technology is useless without the software. Hardware is useless without software. Computers are useless without a job to be done.
Jim Zellmer: Yes.
Horace: I believe technology will help, but we have to make sure that we solve the job problem with technology, rather than saying that technology itself is this answer. I think the iPad has potential because it enables the content to come through again. What you might learn by using it is focused on the content itself.
In other words, a computer was always hard to use. Most of the time you spent using it was actually learning how to use it. So you have to fight through it to get to the actual content and material was supposed to teach you something. Even the way that it used to be, that there was a computer room or a computer lab and you would go and sit in front of these computers and there were all these things considered.
In other words, it got in the way. I think that what the content needs to do is be more pervasive. You need to give the platform to someone who can build something on top of it, someone who can actually create new content, new material, new ways of teaching.
The real innovations that I've seen have been the Khan Academy or even Ted Talks or something along the lines of video content that is packaged in small pieces that people can take and learn at the rate that they're comfortable with. That makes a lot of sense to me. I don't know how that can be worked to the K-12 system because that is so regimented. But I think kids having iPads seems to be potentially a breakthrough opportunity there for how to really teach.
It's all going to come down to the materials. Is this a platform that teachers can build stuff on? The only thing I have to criticize the system for is that it's still not possible for laymen to create material for it. We need more and better tools that sit on top of the tools we have. So abstract from the hardware so you can create great e-books, you can create... experiments and so on.
Jim Zellmer: Right. Well, that's great. I appreciate your time today, Horace. Perhaps we can continue this again one day on education, which certainly continues to change. Again, good luck with the French school, with your son.
Last year we began offering revenue and operating income comparisons between Apple and Microsoft. It was becoming evident that the iOS franchise was beginning to overtake both in revenue and profitability the Windows franchise. To offer more dimensions of comparison this time I am adding Google's top and bottom lines for comparison (click image for detail):
Note that the graphs have the same scales when read horizontally. I've broken out the sub-divisions of revenues as the companies report them. Here are some observations:
The time spanned is 4.5 years (September 2007 to December 2011)
If we compare the fourth quarter 2007 to fourth quarter 2011 the ratio of Google : Microsoft : Apple went from 1: 3.39:2:16 to 1:1.97: 4.38. In other words, Microsoft was 3.4 times bigger than Google but today it's only about twice. Apple was twice and is now about 4.4 times bigger.
In terms of operating income (i.e. before R&D, SG&A and OI&E) the ratios were 1:4.48:1.53 and are now 1:2.28:4.82. Microsoft's income gap to Google halved while Apple's more than tripled.
Google and Microsoft have grown but not by adding new sources of revenue. Apple grew its base but, more importantly, added new businesses for spectacularly more growth.
Compared to Microsoft and Apple, Google's revenue is distinctly single-source: advertising. Though divided between own sites and those of affiliates, advertising is today 96.1% of revenue and was 98.6% four years earlier.
If we compare the individual product/business operating incomes individually we see some interesting patterns:
Google's advertising profits have overtaken Windows as has the iPhone and the iPad may do so quite soon.
Microsoft's Business (Office) and Server businesses are growing more quickly than Windows
The hardware oriented Apple' operating margin is now 37% and exceeds Google's 33% while being nearly equal to Microsoft's 38% (see chart below)
I presented a subset of this material January 30th at a TechMeetups event titled "Apple - world's biggest startup." A presentation by Adam Lashinsky focused on the cultural and procedural aspects which highlight Apple's "startup" nature. My presentation showed, using these graphs, Apple's growth characterizes it as a "startup". The growth did not come from a broadening of its core products markets. It came from the creation of new product categories. Google, a much younger company does not exhibit this non-secular growth any more than Microsoft which is about as old as Apple is.
The lesson is perhaps that rapid growth is not the right of small companies alone. Apple has used disruptive innovation to transform itself and offers a stunning contrast to two other companies which are also seen as innovative leaders.
It's perhaps fitting that an industry that produces illusions is in itself an illusion. The absence of public scrutiny of its finances and business model leads to a lot of myths or misconceptions. Some of these are discussed anecdotally in books and other works[1], but the absence of data makes the anecdotal evidence unsatisfying to an analyst.
What if we could find patterns in data about the industry to confirm or deny these oral histories? Fortunately some data actually exists. There are collections of data about movies released and some of the attributes of these releases such as box office receipts, theaters opening, budgets (sparsely), and distributors. This data is typically used for marketing purposes to celebrate the "hits" and thus entice more people to see the movies.
However, other information can also be obtained through analysis of the data. In fact, a rather compelling story can be told. That's the purpose of this post. Our story will be expanded over time but this first draft should be enough to allow a discussion to begin. The story is built in four sub-stories:
Drama / Comedy vs. Adventure / Fantasy: Why the Ancient Greeks had it all wrong.
The magic of summertime: Market access and school schedules
The perpetual incumbency: What happens to Hollywood startups
The Popcorn economy: The peculiar power of theaters in an age of television
These stories were the result of observations in data alone. We have no first-hand knowledge of the industry and have only used basic software tools to seek out patterns in public data[1].
The data set includes approximately 12,000 titles released between 1975 and present with various degree of completeness. Some of these years are not completely populated and some data is undoubtedly in error. However the large sample should offer enough substance for patterns to emerge in spite of this.
Drama / Comedy vs. Adventure / Fantasy: Why the Ancient Greeks had it all wrong
Storytelling has not changed throughout history. The same types of stories affect audiences the same way since stories were first told. The earliest known "genres" were tragedy and comedy and they are still seen as the bedrock of theater today. The same is true for movies. The following bar chart shows the distribution of genres as cited by movies over our data set.
Drama and comedy are about 50% of all movies made. If we add romance they are 60% of cited genres. This is understandable given the history of theater. However the profitability (or revenue potential) of those genres is not as strong as Action, Adventure and Fantasy. The following chart shows the same count of genre citation but only for movies grossing over $200 million (which we chose to call "blockbusters").
Action, adventure and fantasy handily beat Comedy and even SciFi beats drama. Romance, musicals and and mystery genres typically associated with female audiences are very rarely successful as blockbusters. The overall data is shown in the following table. The rows represent gross revenues and the columns genres cited ranked in order of frequency. One can easily observe the density of low earning drama and comedy (grey colored) vs. the more lucrative instances of fantasy and adventure. These male-dominated genres have consistent success into middle, high and very high revenue tiers.
The reason for this blockbuster attention to action and adventure is probably the prevailing theater-going audience demographic: adolescent males. The industry still produces the classic genres but less profitably than what the current targeted markets.
Indeed, these genres were very uncommon in eras predating the late 1970s. More "adult-oriented" movies like romance (Gone with the Wind), musicals (The Sound of Music) and epic movies (Ben Hur, The Ten Comandments) were common in the "golden age" of Hollywood. As we'll see in the next section, the age of the audience is a now driving more than just genre selection.
The magic of summertime: Market access and school schedules
Using the word "Summer" before "Blockbuster" has become almost redundant. What is less understood is that watching movies in the summer is rather a new idea. It started effectively with Jaws in 1975 and ever since major film studios have planned their annual marketing around a summer schedule. There is clear evidence for this in the data. Here is a table showing the blockbuster release months since 1975. (The number of titles grossing over $200 million and the months in which they were released).
The same pattern repeats for the next tier of highly successful movies--those grossing between $100 and $200 million.
But what about the less successful movies? Those earning less than $50 million actually show a counter-success pattern.
To contrast this further, here is a stacked bar chart comparison between frequency of release by month for the most successful tier vs. the least successful tier (colors represent years with oldest at the bottom).
It would seem that summer and success are in a causal relationship. There is a clear pattern with the only non-summer months having blockbuster releases being November and December.
But there is more to this pattern.
The blockbuster schedule happens to coincide with the school holiday schedule in the US. This again points to the "profitable" audience being school-age children, and mostly male.
The perpetual incumbency: Where are the Hollywood startups?
The third observation has to do with the major film studios. We took the box office revenues and allocated them to the studios over time. The following chart shows the share of those revenues for the top 30 studios.
The top five were earning 64% of revenues in 1975 and the top five were earning 60% in 2011. One of the top five from 1975 is no longer in the running this year (MGM) and one new major was added (Buena Vista, owned by Disney).
There has been one other notable change: Columbia was acquired by Sony but stayed out of the top 5. Beside Disney there is one new significant entrant in Dreamworks gaining share in the last decade.
But the prevailing impression from the data is that the incumbents remained as such during the last four decades. There are many small studios but they have not "disrupted" the market by shifting significant revenues out of the hands of the majors. Indeed the typical strategy seems to be to start a studio with the hope of it being acquired by a major.
Even the entrants are industry insiders: Disney and Dreamworks are not asymmetric in their business models in any way. In fact, when viewing the data by blockbuster creation, the majors feature prominently. There are only a handful of blockbusters from the smaller companies.
When looking at overall production rates, again the majors (and their subsidiaries) dominate. Here are the top 75 distributors of movies showing nearly 9000 movies (click image for full-size):
The conclusion from this data might be that Hollywood does not change all that much in terms of who makes the money. But that itself is a symptom of a deeper reality: that there is little that changes at all.
We can even perhaps hypothesize that there is no business model innovation taking place. Any such innovation is usually manifested in a reversal of fortunes for incumbents.
But technological change is happening. The following section describes how this appears in the data.
The Popcorn economy: The peculiar power of theaters in an age of television
The data we are sampling (box office gross revenues) is actually a small and shrinking subset of what movies generate. In addition, there are international revenues, media sales (DVD, video tape), TV rights, and merchandise to name a few. But theaters are still an important part of the picture.
Although they make up less than 20% of gross, their importance is disproportionate due to the signal they send other markets about the popularity of a movie. In other words, a movie must first be proven in a US theater before its value is priced by the other channels.
However, this essential theatrical release has changed in one fundamental way. Releases are now geared for larger initial scopes with shorter runs and less dependency on "word of mouth" to increase sales.
Consider the following view of release breadth (how many theaters are in an opening) by openings over time. The columns represent the number of theaters used in the opening of a movie in increments of 100. The rows are years. The cells contain the number of movies opening with that size footprint.
The pattern shows the number of theaters used in openings increasing steadily. the mean number of releases is shifting to the right. Part of the reason is that theaters shrank in size over time, but there is also the factor of needing to create a large audience at the outset of a release. The increase in "footprint" at launch (a factor of 10) is in excess of the slicing of theater sizes (a factor of two)
This broadening of launch is coincident with a decrease in viewers. As a result the notion of how movies are marketed has changed. The idea that a movie could start small and gain a following gradually through word of mouth is obsolete. That low cost approach to marketing (called "earned media exposure" in marketing) is unreliable and completely discounted.
Instead, studios manufacture an audience through paid advertising and promotion. This initial burst of viewers is essential not just for generating revenues. It's essential to driving long-term revenues.
The reason is that technology now allows the movie to be "monetized" through multiple channels. Recorded media, broadcast rights and even in-flight entertainment are all there to milk a franchise. But there is a need to get that initial vote of confidence from one crucial audience. That happens to come only from theatrical release.
So with the scheduling pressures, the narrow window of purchased release buzz, the onus is on a broad release as quickly as possible. This holds especially true if we filter out only the blockbusters. Note how the release has increased steadily as well and that since 2000 all blockbusters released to over 3000 theaters. Compare that to Star Wars in 1977 releasing to only 30 theaters.
Data sources: Coolector, Imdb, BoxOfficeMojo, The-numbers.com
Many thanks to David McCandless and the Information is Beautiful folks (http://www.informationisbeautiful.net) for setting up the Hollywood Budgets Award that provided us with much motivation for researching this topic.