Apple FQ2 2026 Earnings Call: Live Commentary by Horace Dediu
by asymco-admin
Below are Horace's live commentary during the release of Apple FQ2 2026 Earnings, lightly edited. For an in-depth look, and a discussion of what turned out to be a record-breaking quarter, join uss at Asymco Office Hours: Apple Live Q&A.
Transcript: Friday 30 April 2026, 4:30pm-6pm EST | asymco@mastodon
Apple will release earnings at 4:30PM ET and conference call begins half hour later and lasts for one hour. I will try to make some comments as I process the news. This might be the 75th Apple conference call I listen to.
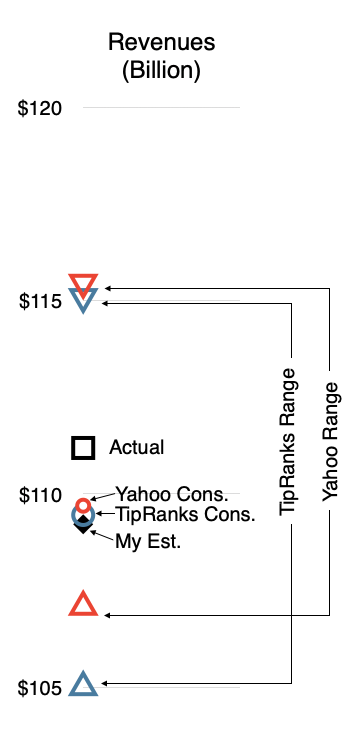
My estimates: EPS $1.98 Rev. $109.2b iPhone Rev 55.716684 Mac Rev 8.640 iPad Rev 6.9552 Wearables & Home Rev 7.522 Services Rev 30.3753
iPhone revenue came in at $56.99 billion. My estimate was $55.71b.
Here is a graph of the expectations vs. actual Revenue results.
iPhone revenues grew 22%. Extraordinary. The growth barely slowed from 23% the previous quarter.
Mac revenue growth was 6%. Slightly less than I expected.
Revenues were up 17%, earnings per share were up 22%.
Best March quarter ever.
The board of directors has declared a cash dividend of $0.27 per share of the, an increase of 4 percent. Repurchase program authorized for up to $100 billion for the next 12 months. No surprises here.
Greater China growth was 28%.
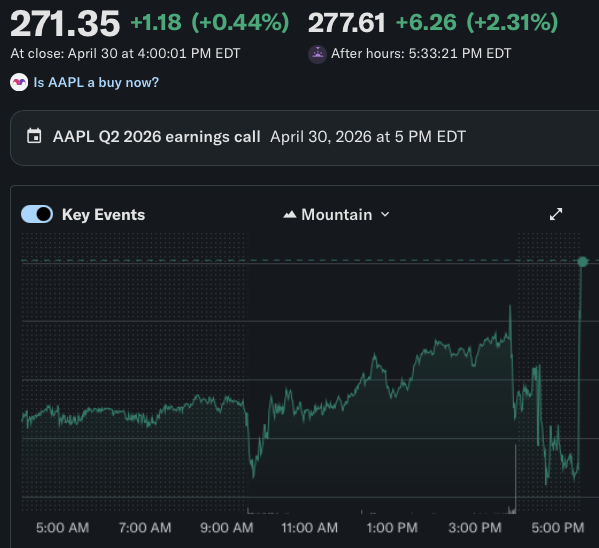
Apple shares are down 0.6% after-hours. Normal drop when company beats on the top and bottom. The big drop comes when the CFO talks guidance.
John Ternus will join the call for a few remarks.
Gross margin came in at a record high of 49.3%. This is three months after the great memory panic of 2026 was declared.
Shares fall 0.81% after John Ternus remarks.
Apple reports double digit growth in every emerging market.
Mention of Mac Neo leads to more drops in the share price as the pain of share growth sinks in. Now down 1% after hours.
iPhones went to the moon, stock not mooning.
“Our strong business performance during the March quarter generated over $28 billion in operating cash flow and drove new March quarter records for both operating cash flow and EPS,” The fact that Apple did not turn over this cash flow t...
5% in Wearables and Home. Modest growth is shameful growth. Compounding shompounding.
Apple has 6 stores in India. So much more to do there.
Supply constraints mean that the growth could have been higher —CFO.
Active iPhone install base grew to all-time high. (No surprise). Customer satisfaction was 99% for iPhone 17 in the US.
Customer satisfaction for Mac was 97%.
Half of customers buying an iPad are new to the product. Most of these new customers are in emerging markets.
Customer sat for iPad at 98%.
Tap to pay (Apple Pay) now in 50 markets.
Net cash was $62 billion. No longer placing net cash neutral as a target!!!! OMG OMG.
June Q guidance: 14% to 17% growth. Shares recovered to +1.35%.
Margin guidance: 47.5% to 48.5%. Despite the great memory panic of 2026 being in full effect.
Shocked, shocked, shocked that CFO remarks did not crash the stock.
Several months to reach Mac supply demand balance. Neo and Studio constrained.
Net cash neutrality question and comments. Returned over $1 trillion so far. Another $100b allocated so they are still committed to that.
Shares now +4% in AH but not at record high.
Margins synopsis.
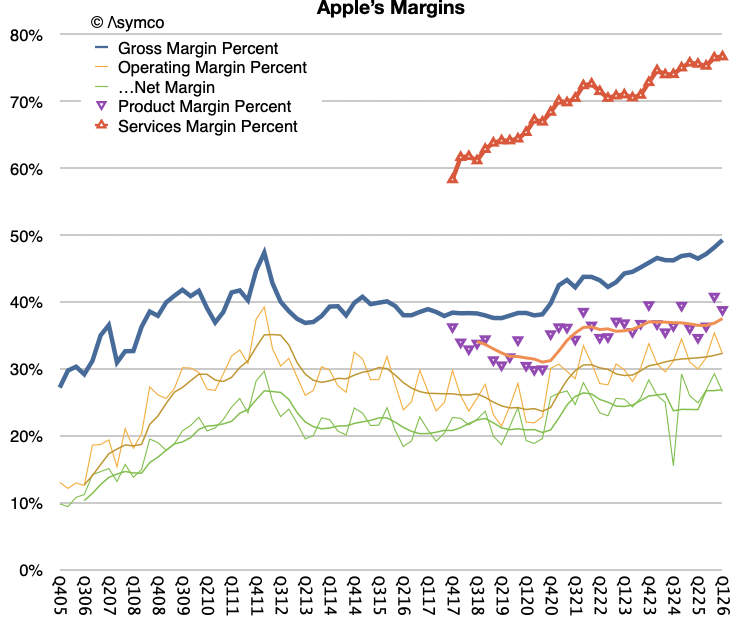
Tim says they did see higher memory costs. For the June quarter they expect significant higher memory costs and more beyond that. Still, margins are brilliant.
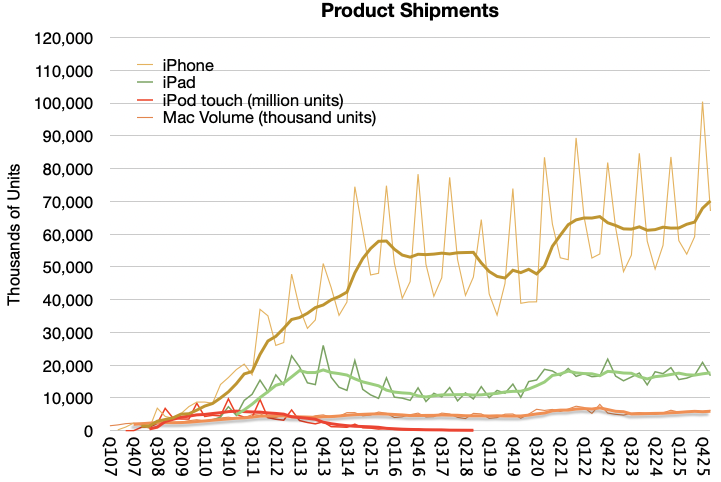
My estimates for unit shipments for Products.
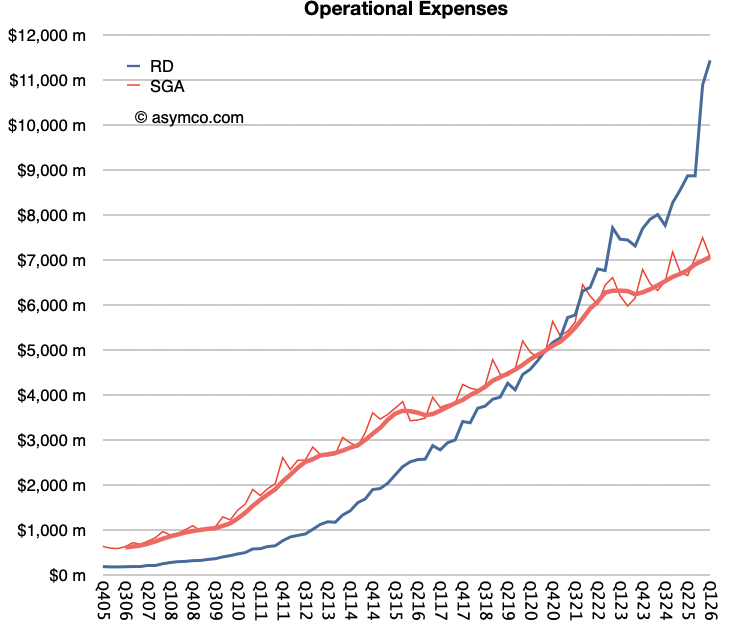
Look at that R&D.
Any tariff refunds will be re-invested in US production or operations (beyond existing commitments.) —Tim the Enchanter.
India: low share is an opportunity; large middle class growing. I see no reason why it's not an equal opportunity to that of China.
That' a wrap. See you during the Office Hours tomorrow.
1 comment
Sacto Joe ·
I'm surprised nobody commented here, and I'm late commenting (4/3). But it was a shocking and positive earnings call, which you'd never know from the Thursday and Friday closes. Yes, up over $280/share, but that's actually underwhelming, considering the shock value.
However, there's a pattern that suggests large scale "traders" (as opposed to long term investors) had a hand. Max Pain was down at $267.50, and on Thursday's last 10 minutes, the stock dropped like a rock, hitting about $265 at one point before settling at about $271. Then on Friday, after the shock, after hitting about $285, the stock was driven down to close at $280.14, for a moderate 3.24% gain over Thursday's close - which was dunked handily on Thursday.
To me, this is a bald-faced stock manipulation by very deep pocketed short term traders who essentially "engineered" a way to avoid getting completely screwed on Friday.
Fortunately, Apple is still buying back its own undervalued stock. However, part of the bombshell was last quarter's buyback, which was significantly less than what would normally be expected for the first quarter, when they had access to a ton of new cash flow. But that has been, of course, masterfully unpacked by Horace in his later deep analysis, and I'll talk more about that issue on that thread.