Preview of Apple's June Quarter
by asymco-admin
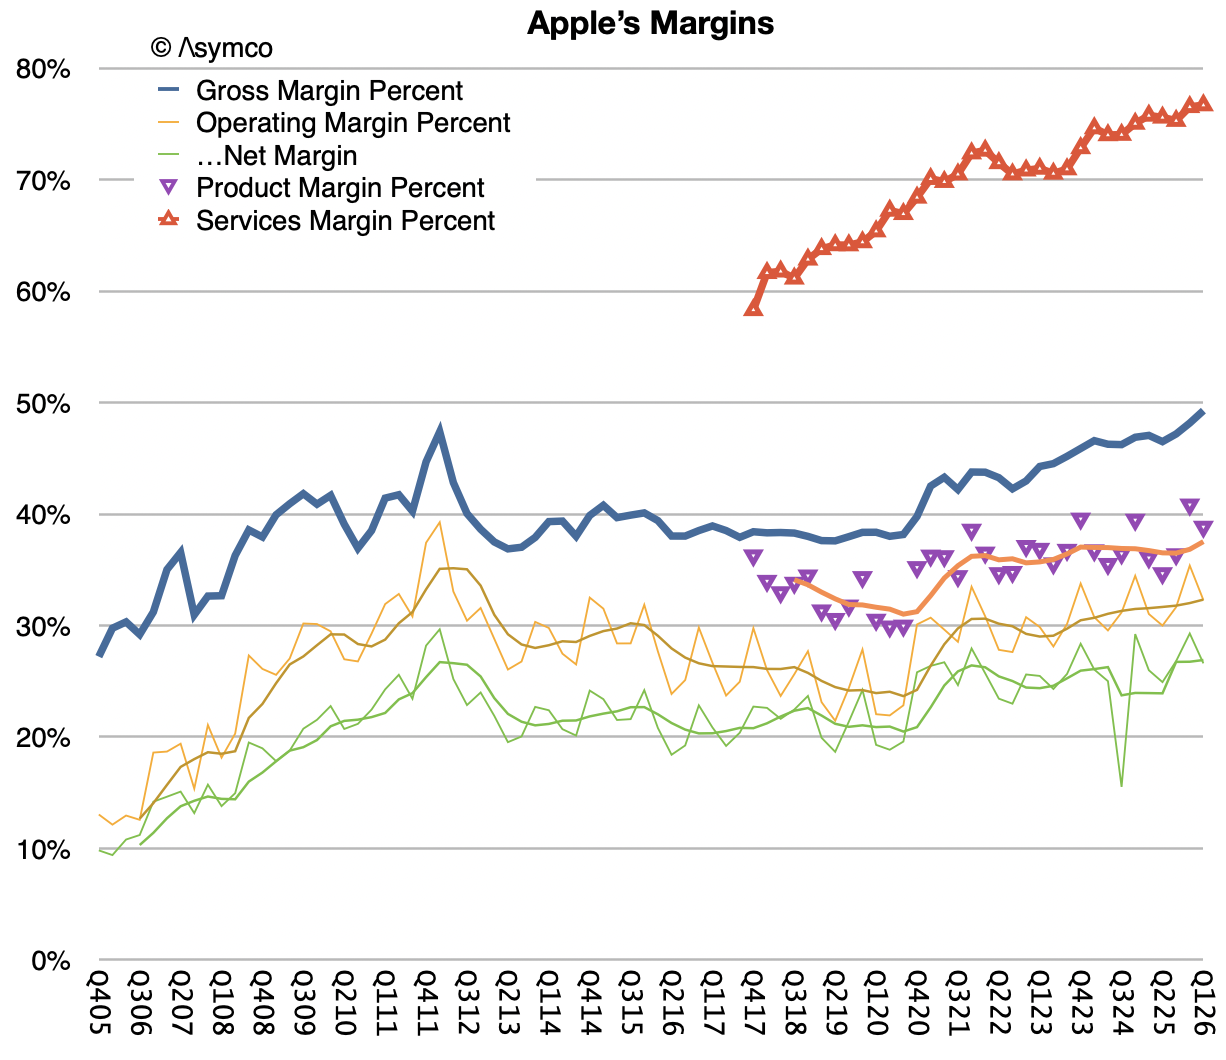
Memory prices won't have had a big impact
As we move ahead into the June quarter, I'd like to review our outlook, […]. Importantly, the color we're providing assumes that global tariff rates, policies, and their application remain in effect as of this call [and that] the global macroeconomic outlook does not worsen from today.
We expect our June quarter total company revenue to grow by 14%-17% year-over-year, which comprehends our best view of constrained supply. On iPad, keep in mind, we face a difficult compare driven by the launch of the A16-powered iPad in the prior year.
We expect services revenue to grow at a year-over-year rate similar to what we reported in the March quarter after removing the favorable year-over-year impact from foreign exchange tailwinds. Keep in mind, during the March quarter, FX was a 2.5 percentage point tailwind to the total company growth rate, and for services, that impact was slightly more favorable.
We expect gross margin to be between 47.5% and 48.5%. We expect operating expenses to be between $18.8 billion and $19.1 billion. We expect OI&E to be around $250 million, excluding any potential impact from the mark-to-market of minority investments, and our tax rate to be around 17%. - Kevan Parekh, CFO
Apple will report results on July 30th. We will conduct Office Hours to discuss them the next day. In anticipation, here are my estimates:
The revenue guidance of 14% to 17% follows a 16.6% increase in the previous quarter. My estimate is growth of 15.9% consisting of the following segments:
- iPhone +21%
- Mac +15%
- iPad -3%
- Services +16%
- Wearables +4%
My gross margin estimate is 48.5% based on the following segments:
- iPhone 38.2%
- Mac 31%
- iPad 26%
- Services 77%
- Wearables 41.8%
My estimate for operating expenses is the maximum of the range ($19.1 billion.) OI&E is set at the same level as guidance ($250 million) and the tax rate also set at the estimated 17%.
I expect the number of outstanding shares to decrease by 74 million to 14.625 billion. This is a reduction in the rate of re-purchase from the previous quarter's 80 million and the average over the previous 4 quarters of 83 million. This is due to higher share pricing.
As a result of these estimates, the fully diluted Earnings Per Share should be $1.93, a 23% increase from the prior year. Trailing 12 months' EPS would thus be $8.63, with a corresponding trailing P/E of 38.6 at the closing price last Friday.
My estimates were made soon after the May conference call quoted above.
Has something happened since to change these estimates?
The biggest concern is the increase in memory pricing which would have a direct impact on margins. Especially on Mac, iPad and Wearables. Less so on the iPhone as that supply is provisioned and priced well in advance.
I suspect that management factored in all the data known one month into the second quarter and that any changes in memory pricing that forced a price increase to be announced in July would not have affected June and July Mac and iPad inventory. For this reason I'm still comfortable with what the company guided for the June quarter. There might even have been some pull-forward of demand across all hardware lines as the channel began anticipating a price increase. Anecdotally, we saw Amazon and other big retailers running summer sales even after the price increases were announced. This implies channel inventory was quite high heading into July.
To summarize, I'm not worried that there will be a margin miss this quarter but there might be a significant reduction in margin into the next quarter's guidance. Margins are currently at record levels (48%!).
A reduction to 45% into the next quarter would not be surprising.
The September quarter will be minimally affected by the new iPhone relative to the December quarter but it might signal how iPhone margins will change.
Low 40% range will be a possibility into CQ4 though that depends on what iPhone pricing changes we will see. I still expect approximately a $100 increase across the board on iPhone. $200 is where the worry lies.
2 comments
AAPL ·
Why do you think share buyback will be so high? Weren't buybacks actually zero in March after dropping slightly in Jan + Feb and messaging on the call was net cash zero wasn't a priority anymore. I took that as buybacks were being throttled back and building up cash. Or do you think cash will have grown enough for whatever they see needing it for 'soon'?
AAPL ·
Your info for number of shares repurchased for last quarter is off…see page 24 of 10-q. With Feb near zero and March at zero, I’m not sure they’ve opened the spigot in this next quarter.