Asymco Bulletin 023 - July 26, 2026
by asymco-admin
Asymco Bulletin is a digest of all the work we have published for the week ending Jul 26, 2026.
Office Hours
Asymco Office Hours Live Q&A — Friday, July 31 → The next Asymco Office Hours Live Q&A will be on Friday, July 31st at 12pm ET / 9am PT, the day after Apple’s fiscal Q3 2026 earnings call on Thursday. Horace will review the results and their implications, and we will take Q&A from our live audience.
Asymco One subscribers are guaranteed seats, can bring a guest, and will have access to the live recording.
Sign up and latest updates at asymco.com/live. →
Research
How to maintain a Sell rating on Apple
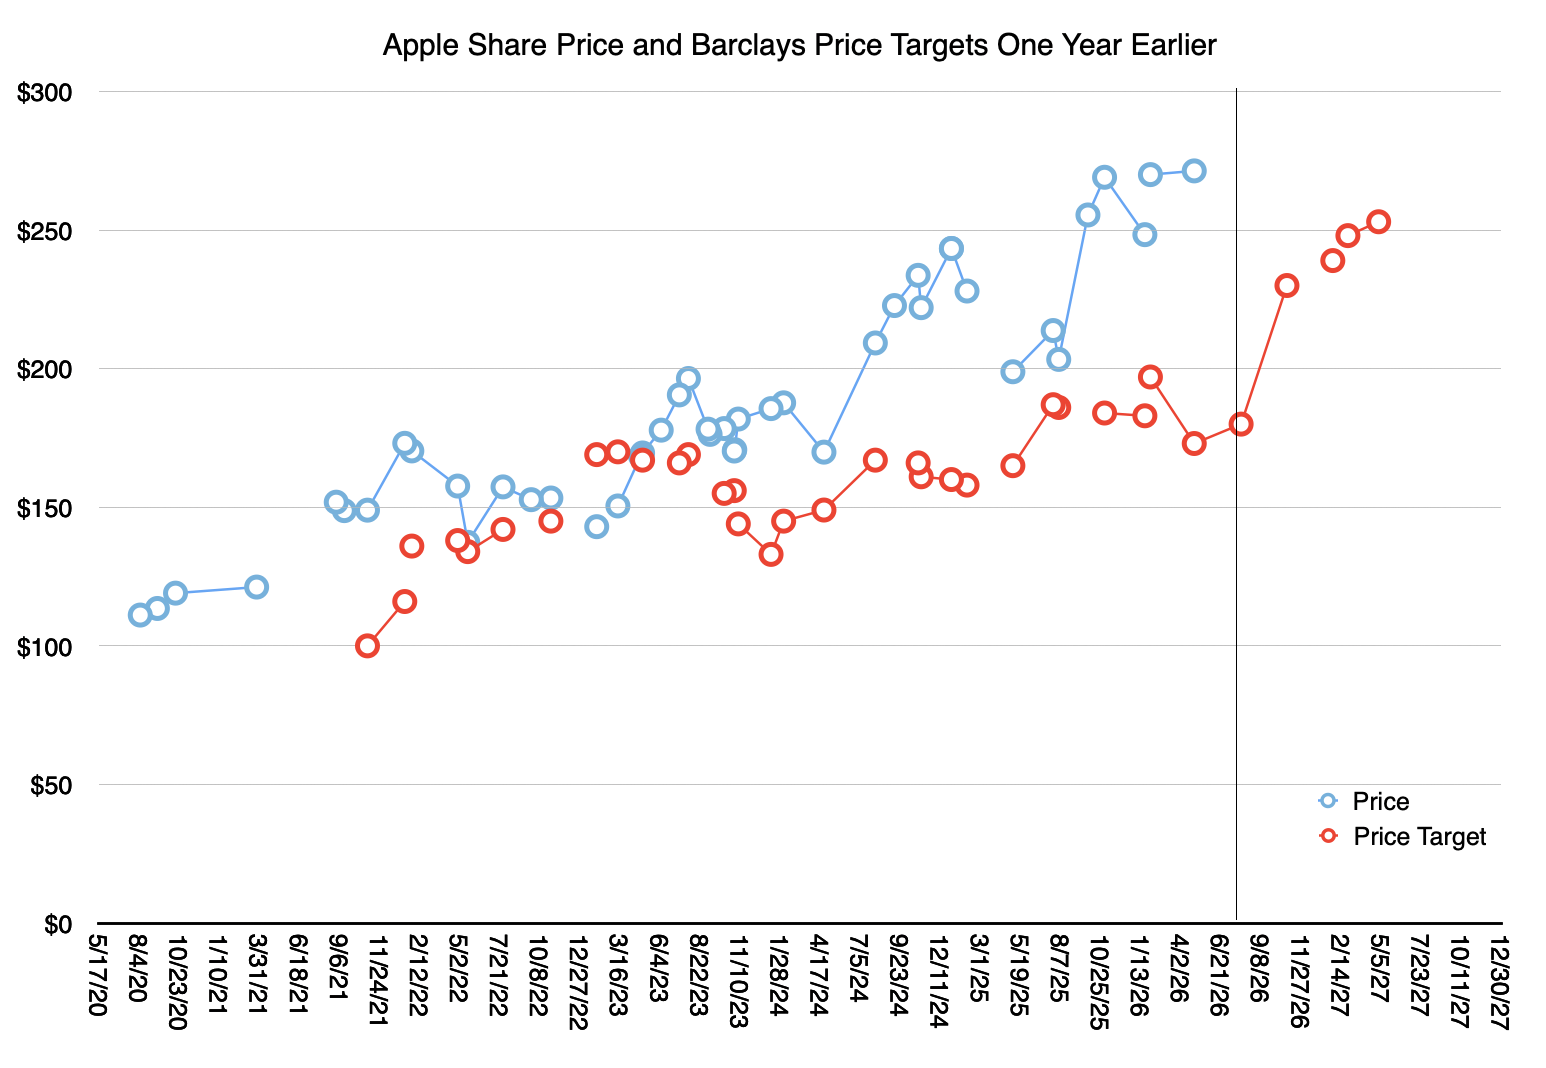
Tim Long of Barclays has a Sell rating on Apple while the shares sit at an all-time high. Barclays has been at hold or sell since 2014, when the split-adjusted price target was $20. Since then the targets have risen 1,165% while the rating has fallen, with a 30% average error on one-year targets. The only way to square rising targets with a falling rating is to argue that all your previous ratings should be ignored. How long does an analyst insist on being ignored? →
Preview of Apple’s June Quarter
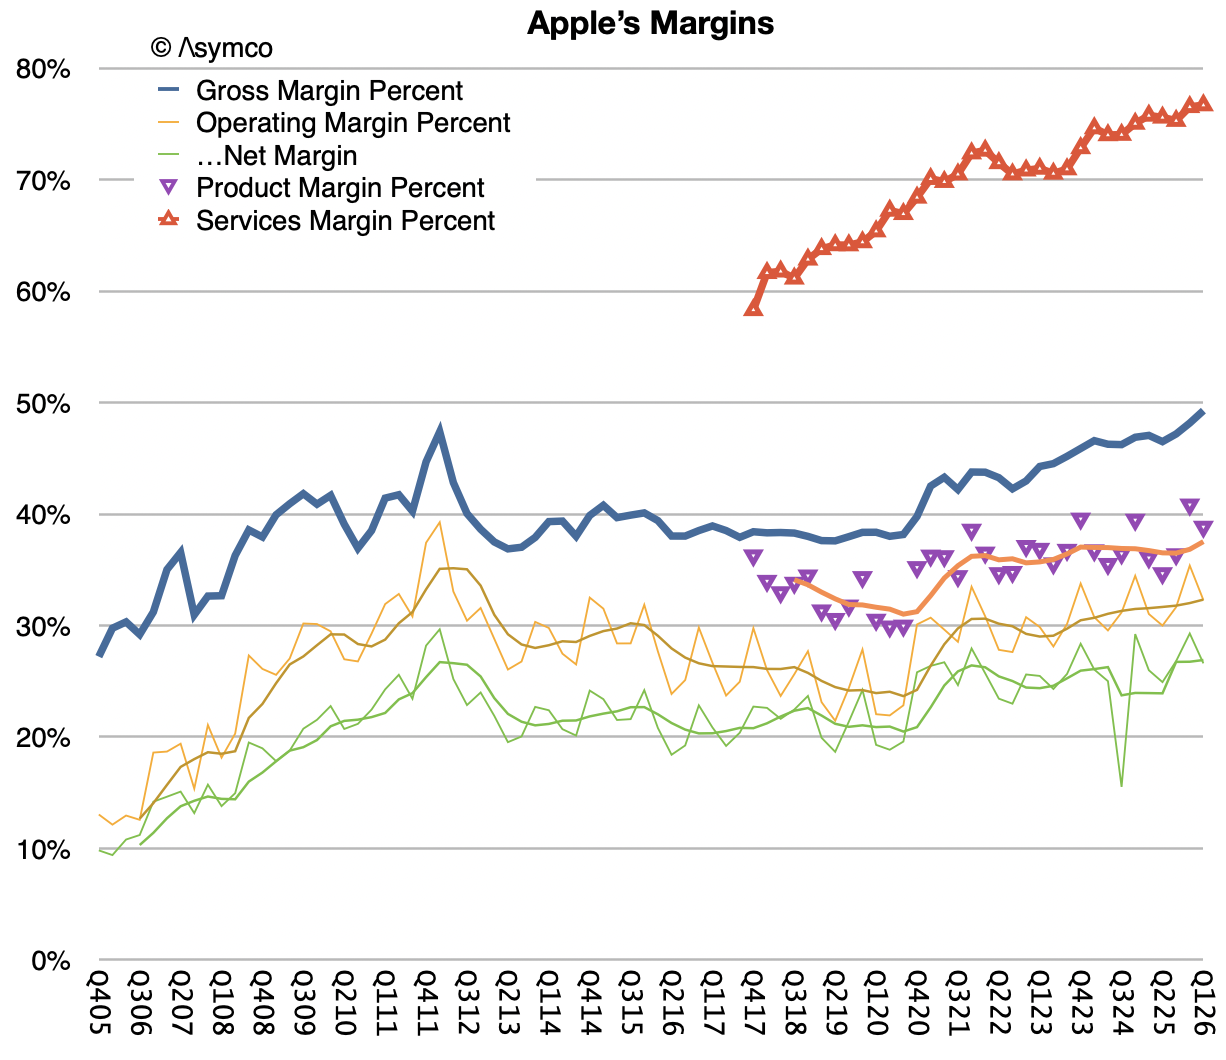
Apple reports on July 30th and we will hold Office Hours the next day. My estimate is 15.9% revenue growth with iPhone up 21%, gross margin at 48.5% and EPS of $1.93, up 23%. Memory pricing is the big worry, but June and July inventory was provisioned before the increases, so I am not worried about a margin miss this quarter. The squeeze arrives in next quarter’s guidance, where 45% would not surprise. →
Beware December Quarter Guidance
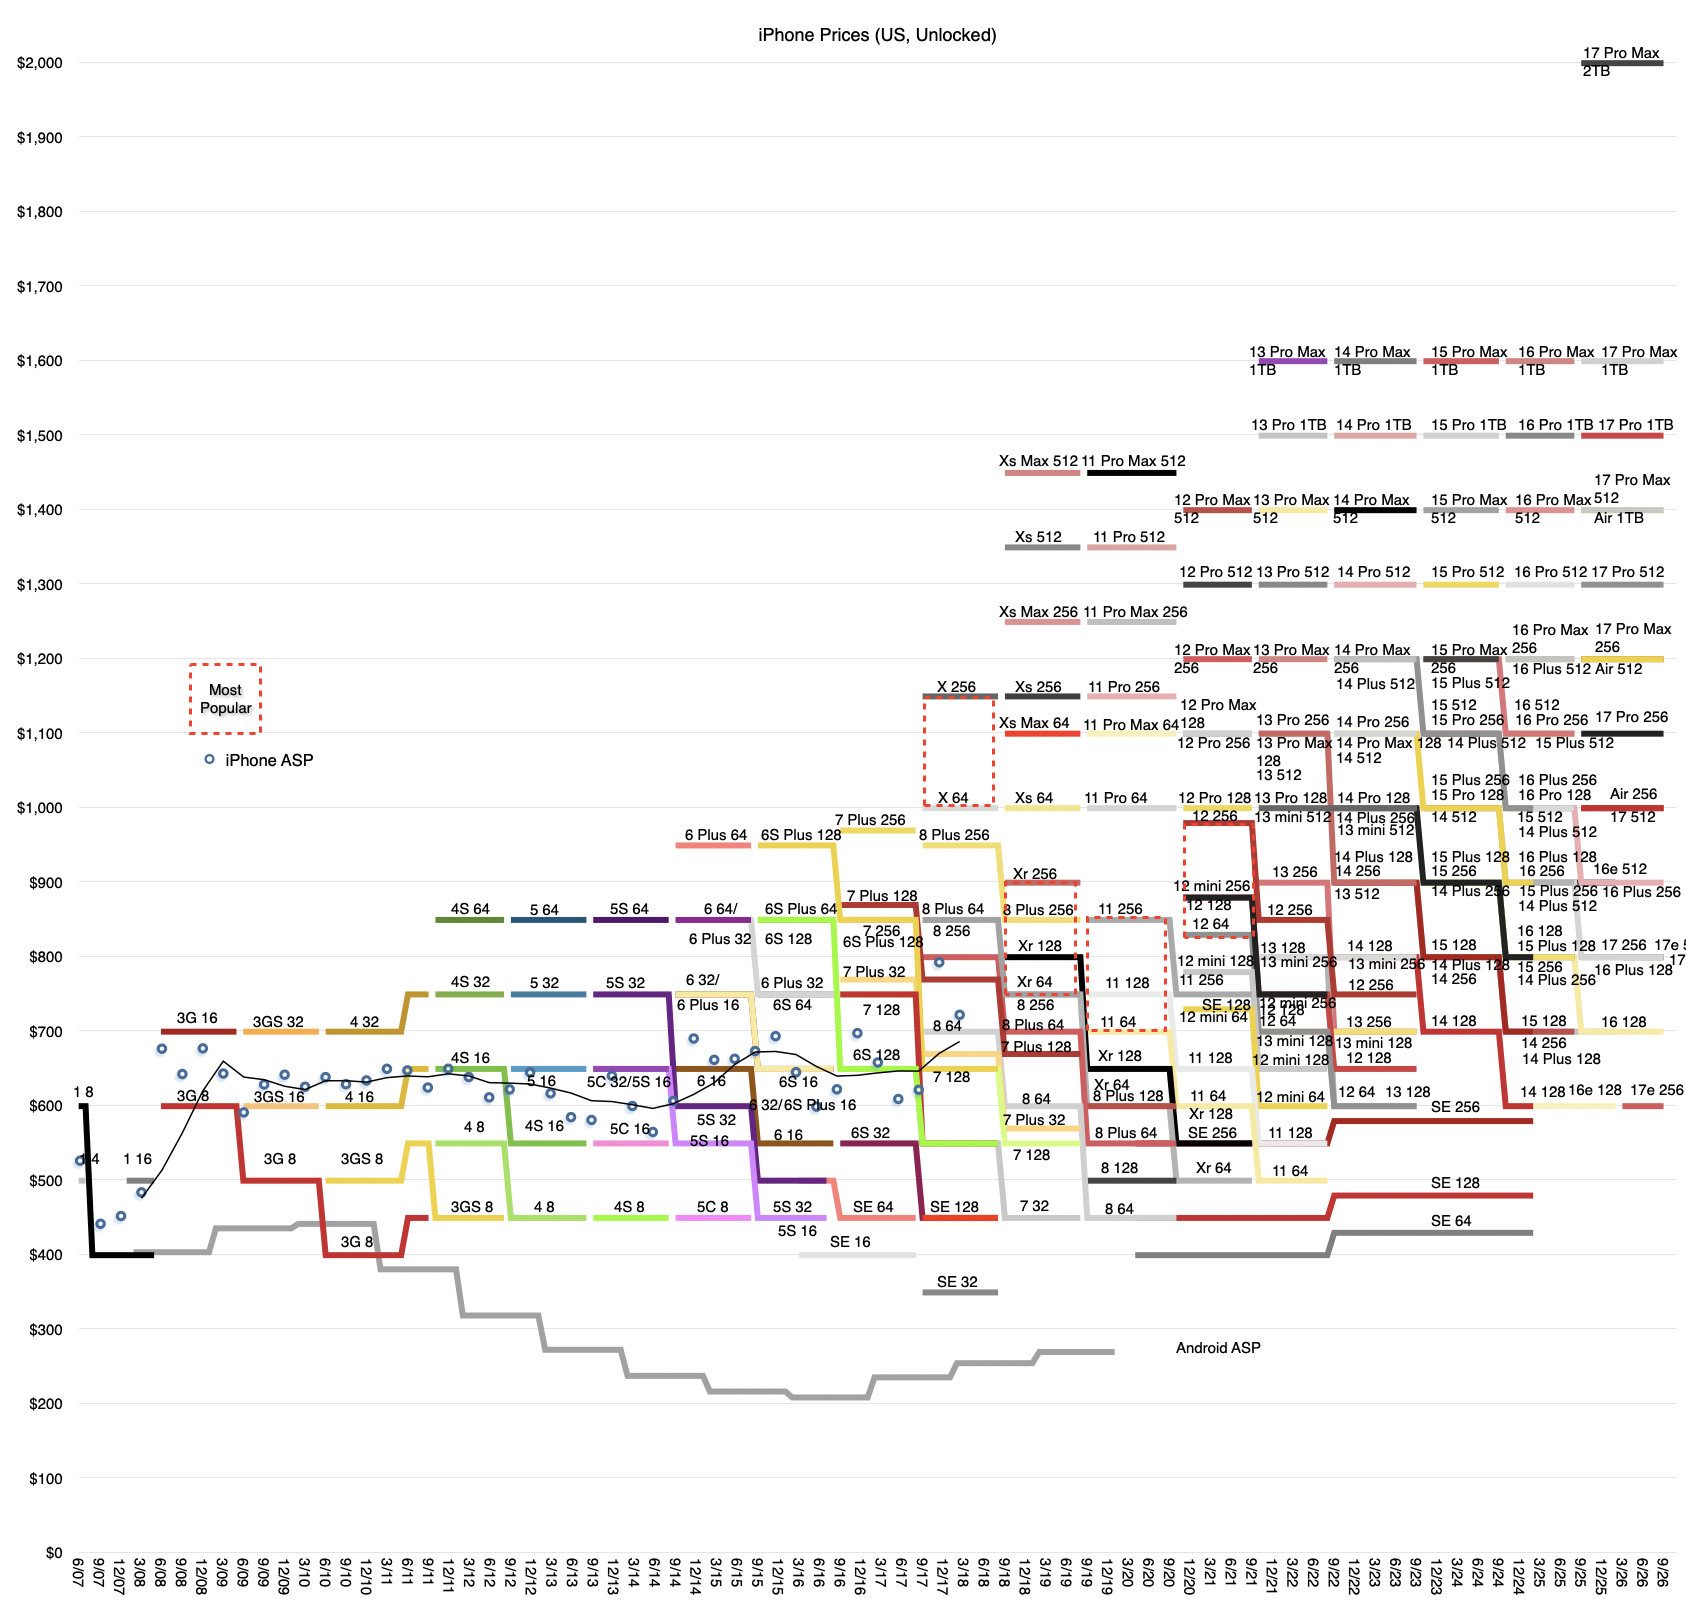
Rumors point to a split iPhone launch across two quarters, a folding model priced above the Pro Max, and the first break in the pricing cadence charted in the stairway to heaven. Any of these leaves management a dilemma: accurate guidance tips their hand, withheld guidance signals a miss. The next few quarters will be different and transitory while the fundamentals get stronger. The reporting will be all over the place and the negatives will overwhelm reason. Don’t be fooled. →
Nota Bene
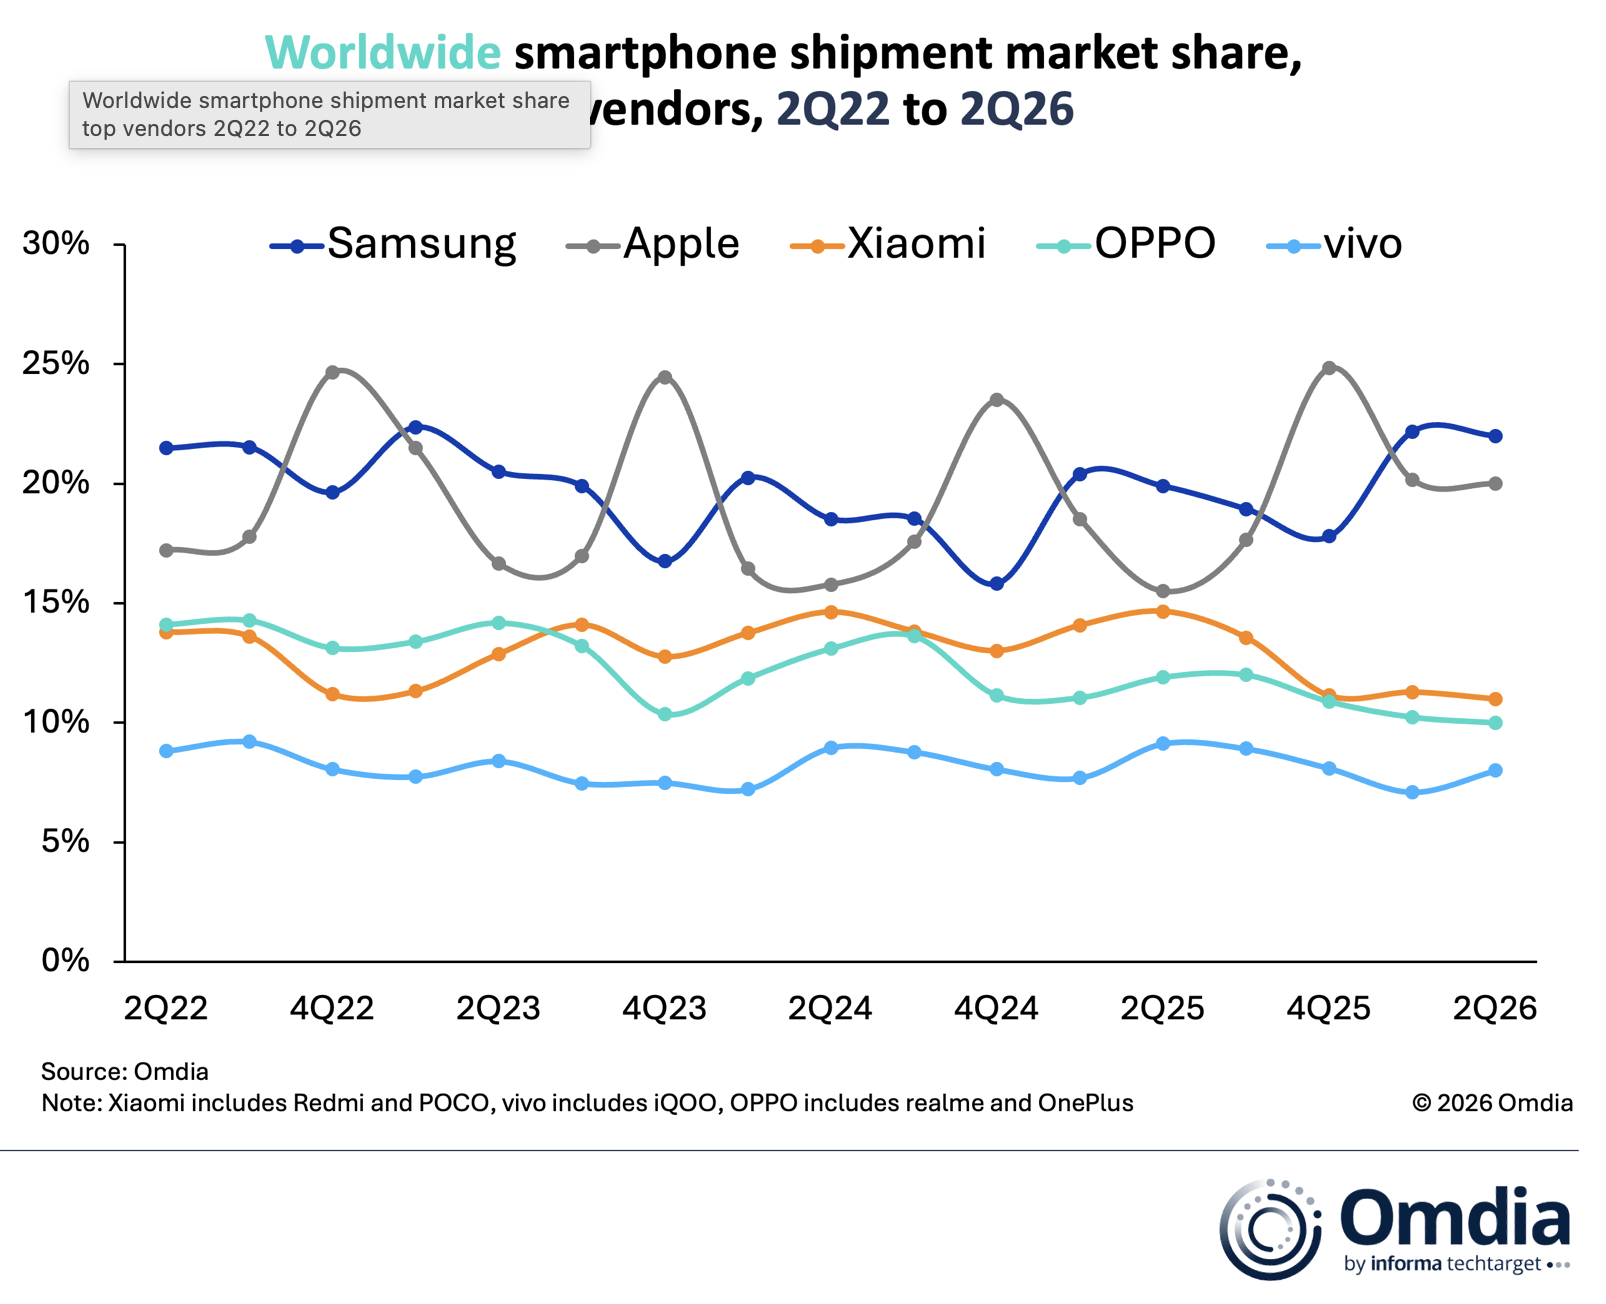
Omdia: Global smartphone market down 4% in 2Q26 while Apple and Samsung soared → Omdia has the market down 4% in the second quarter while Counterpoint has sales down 11%, and either way Apple hit a record 20% share in its slowest quarter. The steepest drops are in the sub-$400 segment, where memory is now over 60% of the bill of materials. Xiaomi, OPPO and vivo all fell steeply on rising memory prices. In a contracting market with contracting margins, Apple is moving in the opposite direction, and every crisis of the last six years ended with the business emerging stronger. →
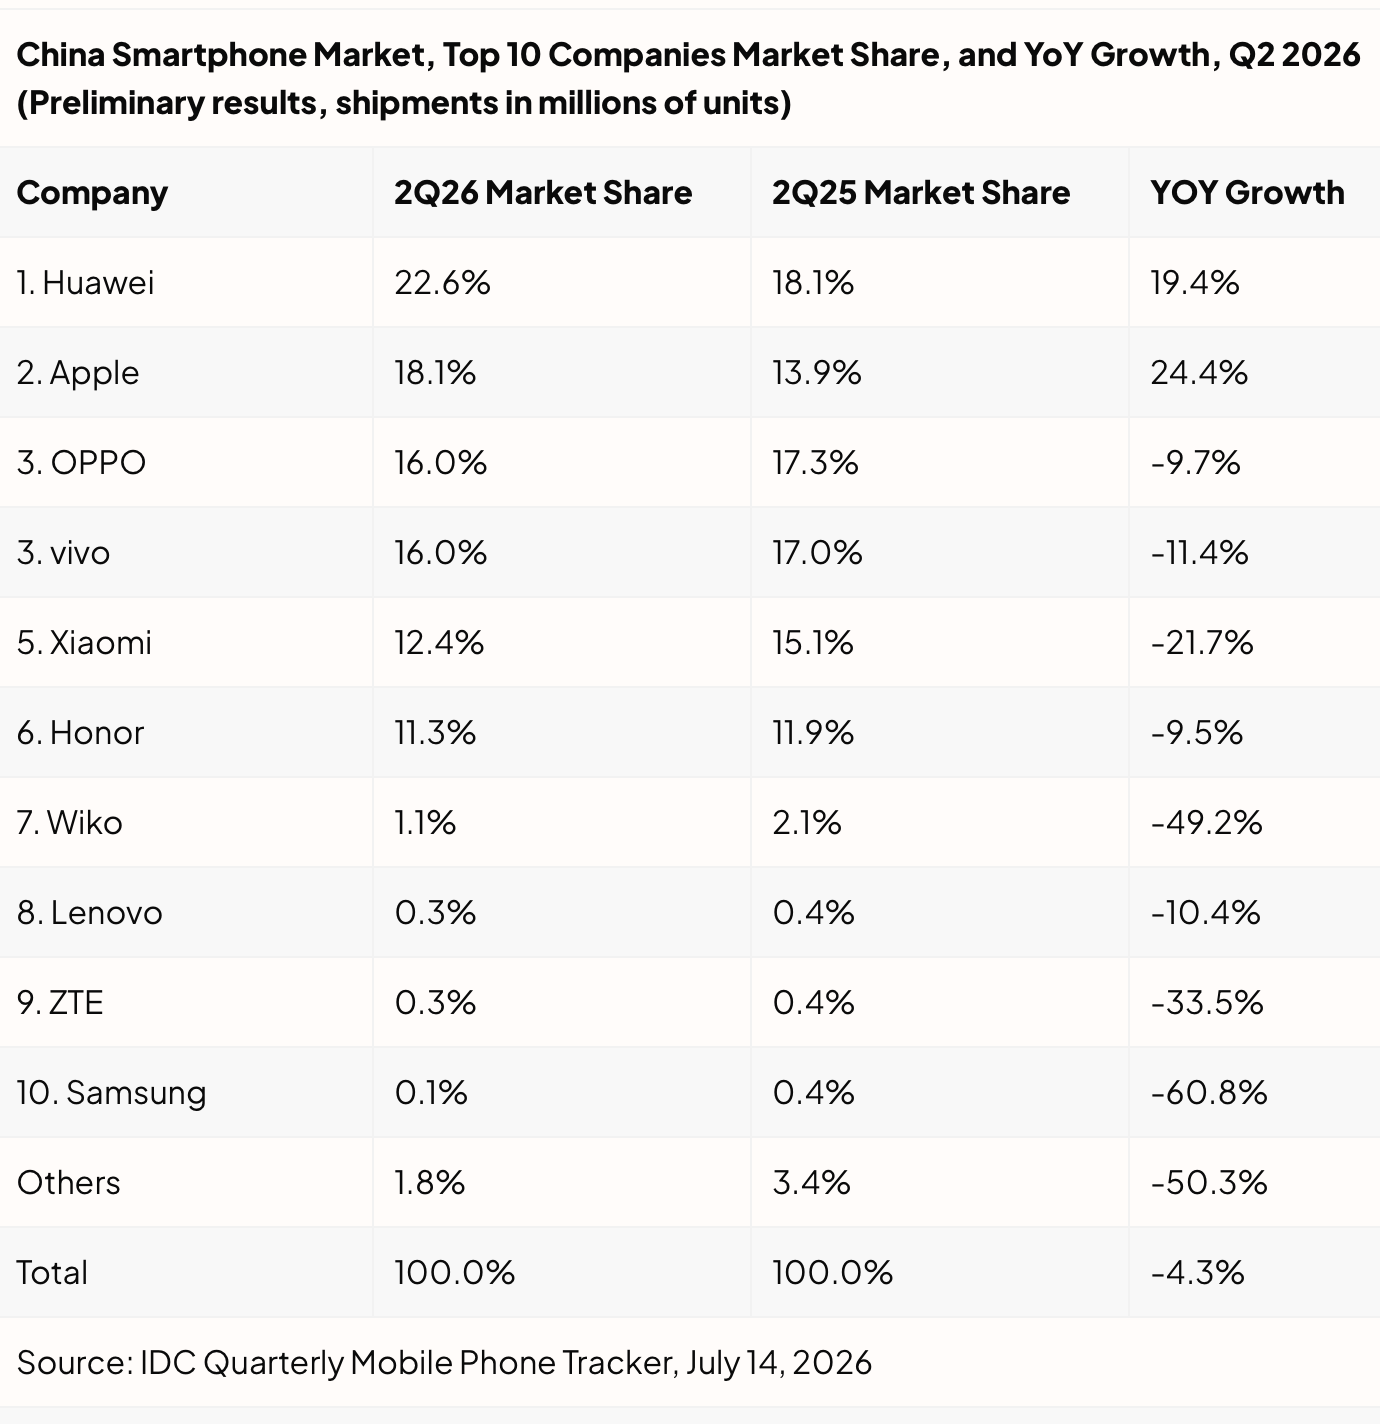
Why Huawei and Apple Grew While China’s Smartphone Market Fell Again in Q2 2026 → China shipments fell 4.3%, the fifth straight quarterly decline, while Huawei and Apple each grew about 20%. Both held prices steady as the Android field raised them, and Apple’s early signaling of second-half increases pulled buyers forward into the iPhone 17. The repetition matters less than the discontinuity: pull-forward demand and iPhone price increases collide in the holiday quarter, with the line-up probably split across two launch quarters and China likely targeted with the later one. →
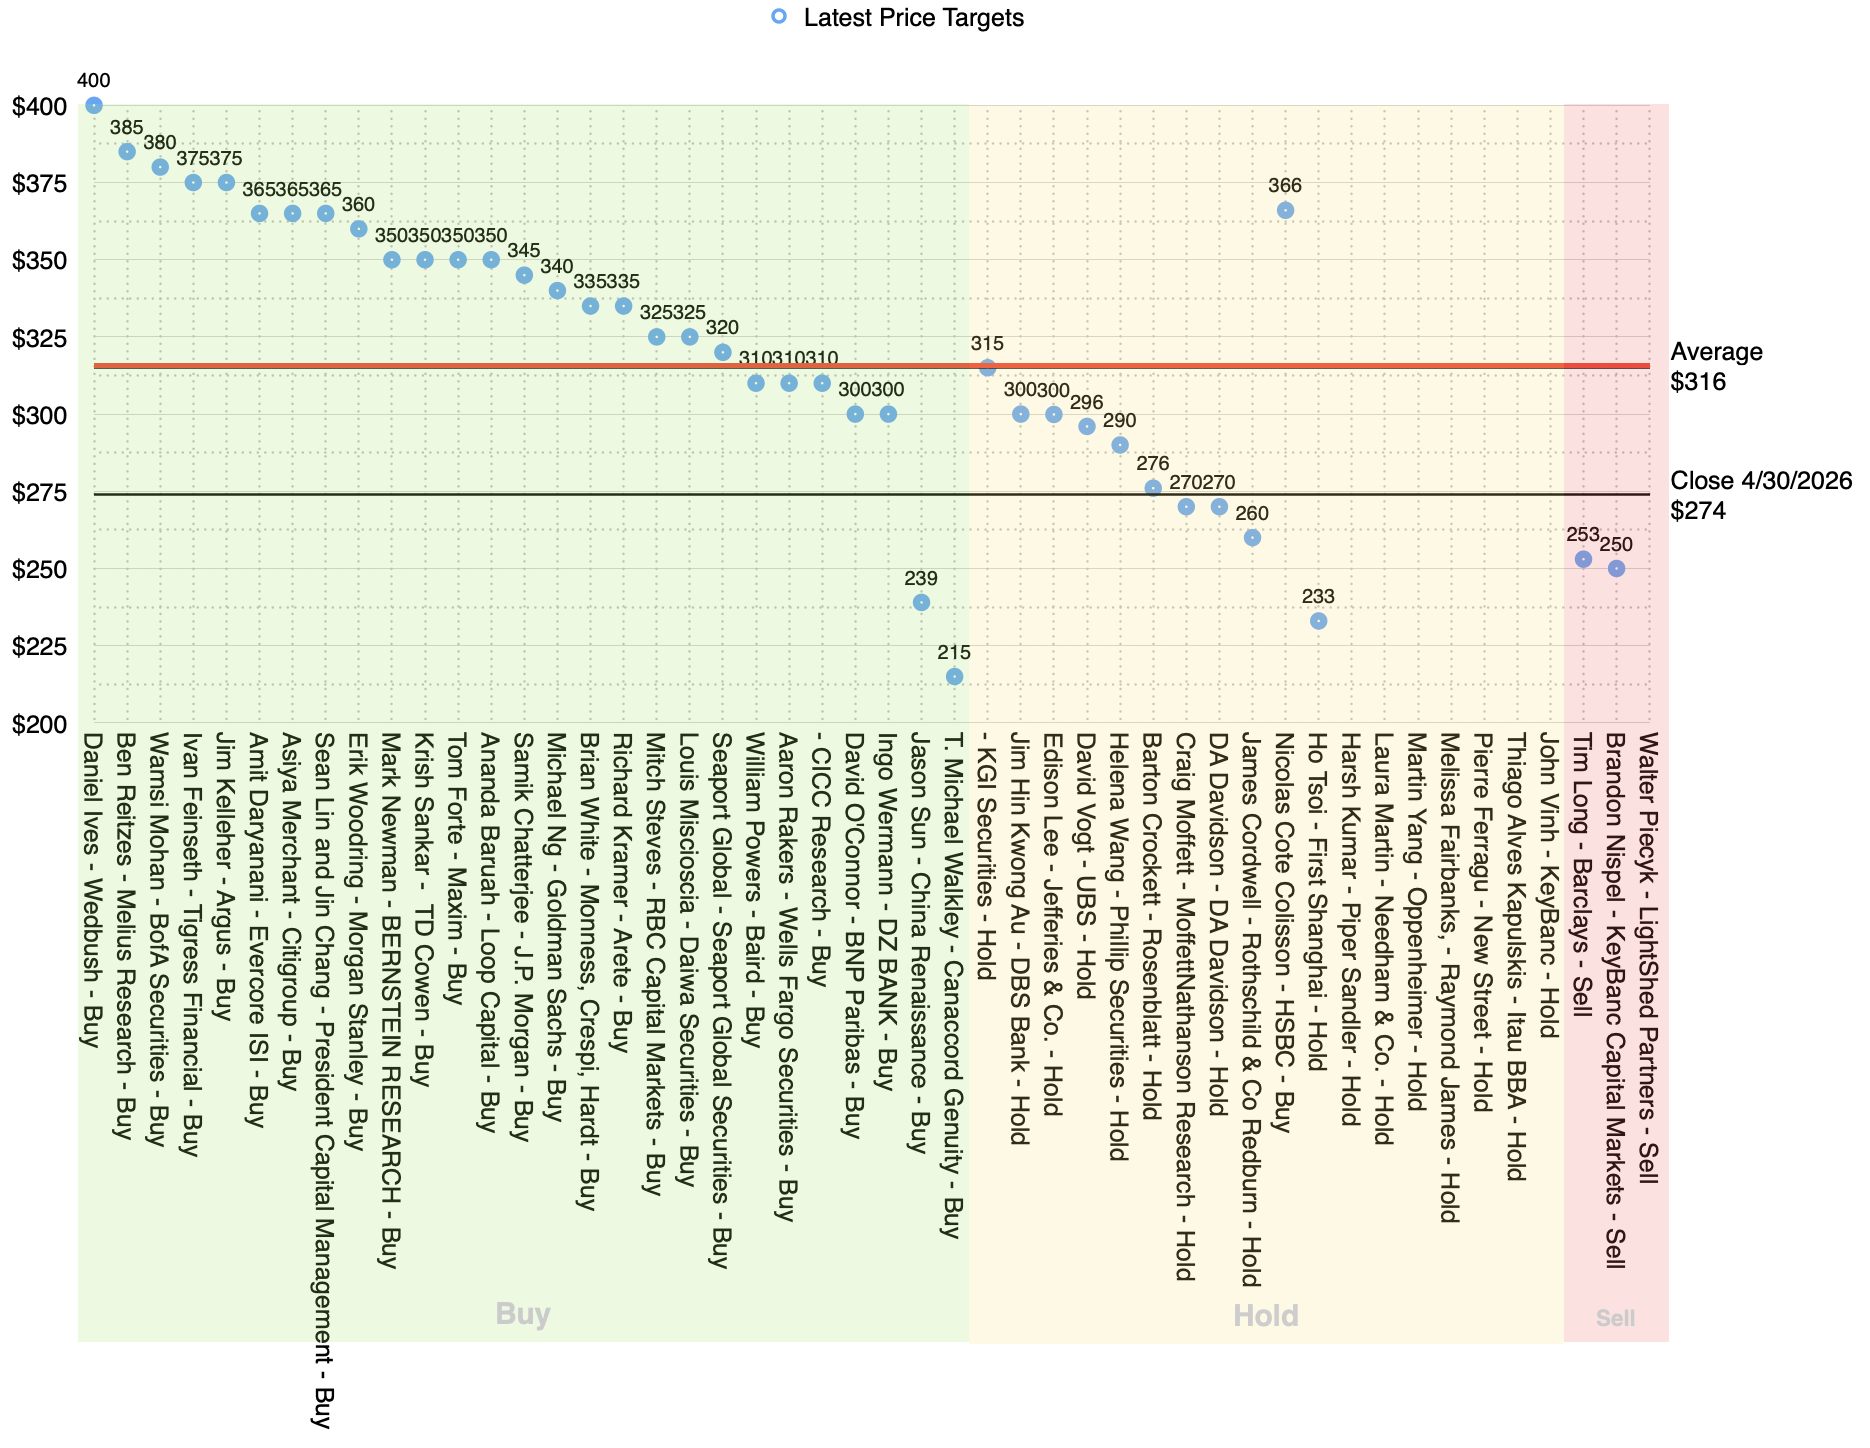
Time to Buy, Time to Sell. → HSBC flipped to Buy with a 41% target hike to $366 while KeyBanc flipped to Underweight with a $250 target on a stock at $333. By my count 28 say Buy and 20 say Hold or Sell. KeyBanc’s own record shows targets tracking results closely while rated Buy, then diverging dramatically once the rating fell. Its latest target implies a 25% drop, set the day before the shares rallied. →
Asymco One gives you full access to our research, analysis, and commentary. Subscribe with code BULLETIN for a discount.
Feedback: Have questions or comments? Reach out to us at contact@asymco.com. We'd love to hear from you.
Comments