Asymco

Asymmetric Intelligence

Horace Dediu

  1. M is for Mystery

    Research · 87 comments

    I recently tweeted that any discussion related to wearable technology needs to begin with a description of the job it would be hired to do. Without a reason for building a product, you are building it simply because you can.

    The reason a product deserves to exist is that it can do a job that needs doing and that few, if any others can also do it. This happens when the job is unstated and difficult to perceive. Put another way, the difficulty behind jobs-to-be-done based design is that jobs are never plainly evident. In contradiction to invention, where the problem being solved must be as clearly stated as its solution, value-creating innovation meets new and unarticulated needs. Even when created, the value is more subtly perceived, often only after prolonged use.

    Which brings me to the M7. Apple chose to highlight a component (curious in itself) which it bills as a "motion coprocessor". It claims to be measuring motion data via accelerometer, compass and gyroscope and processing the information in some way. By bundling the sensors and their management into one integrated chip battery consumption is reduced and these motion monitoring functions are performed more efficiently.

    But what for? The examples given during the presentation for an iPhone with M7 don't add up to a lot of benefit. An iPhone could be used as a fitness companion but it would not a very good one. Compared with, for example, a Nike FuelBand, an iPhone could not track your activity well. It's often not moving, sitting on a desk or in a purse or pocket while you are doing exercise. It's too big to take into a basketball game. It can't "observe" your activity because it's not worn during many activities and if it is worn it is in a position which does not inform much about what you're doing. Phones are too big to be used as physical activity monitors.

    Hence the question of what is the M7's job to be done. As part of an iPhone, it does not seem to have one. Saving a bit of battery life is not a job, and certainly not one that needs to have billing in a media special event. The answer must be that the M7 was developed for some other, as yet unstated reason.

    When the A series chips were created Apple leveraged the in-house design and cost reduction to make a wide range of products with more than 700 million examples built. Designing a chip needs a broad application domain.

    Perhaps this is why Apple chose to describe the iPhone 5s as "forward-thinking". The M7 and the Touch ID are like research projects whose actual value will be realized at some future time, in probably different contexts. The M series of chips may become Apple's "low end" microprocessor as the A series climbs the trajectory into core computing tasks (read: phone, tablets, TV, laptops).

    M might be the chip for the wearable segment, woven into a whole new fabric of uses and jobs to be done.
  2. A new platform classification

    Research · 35 comments

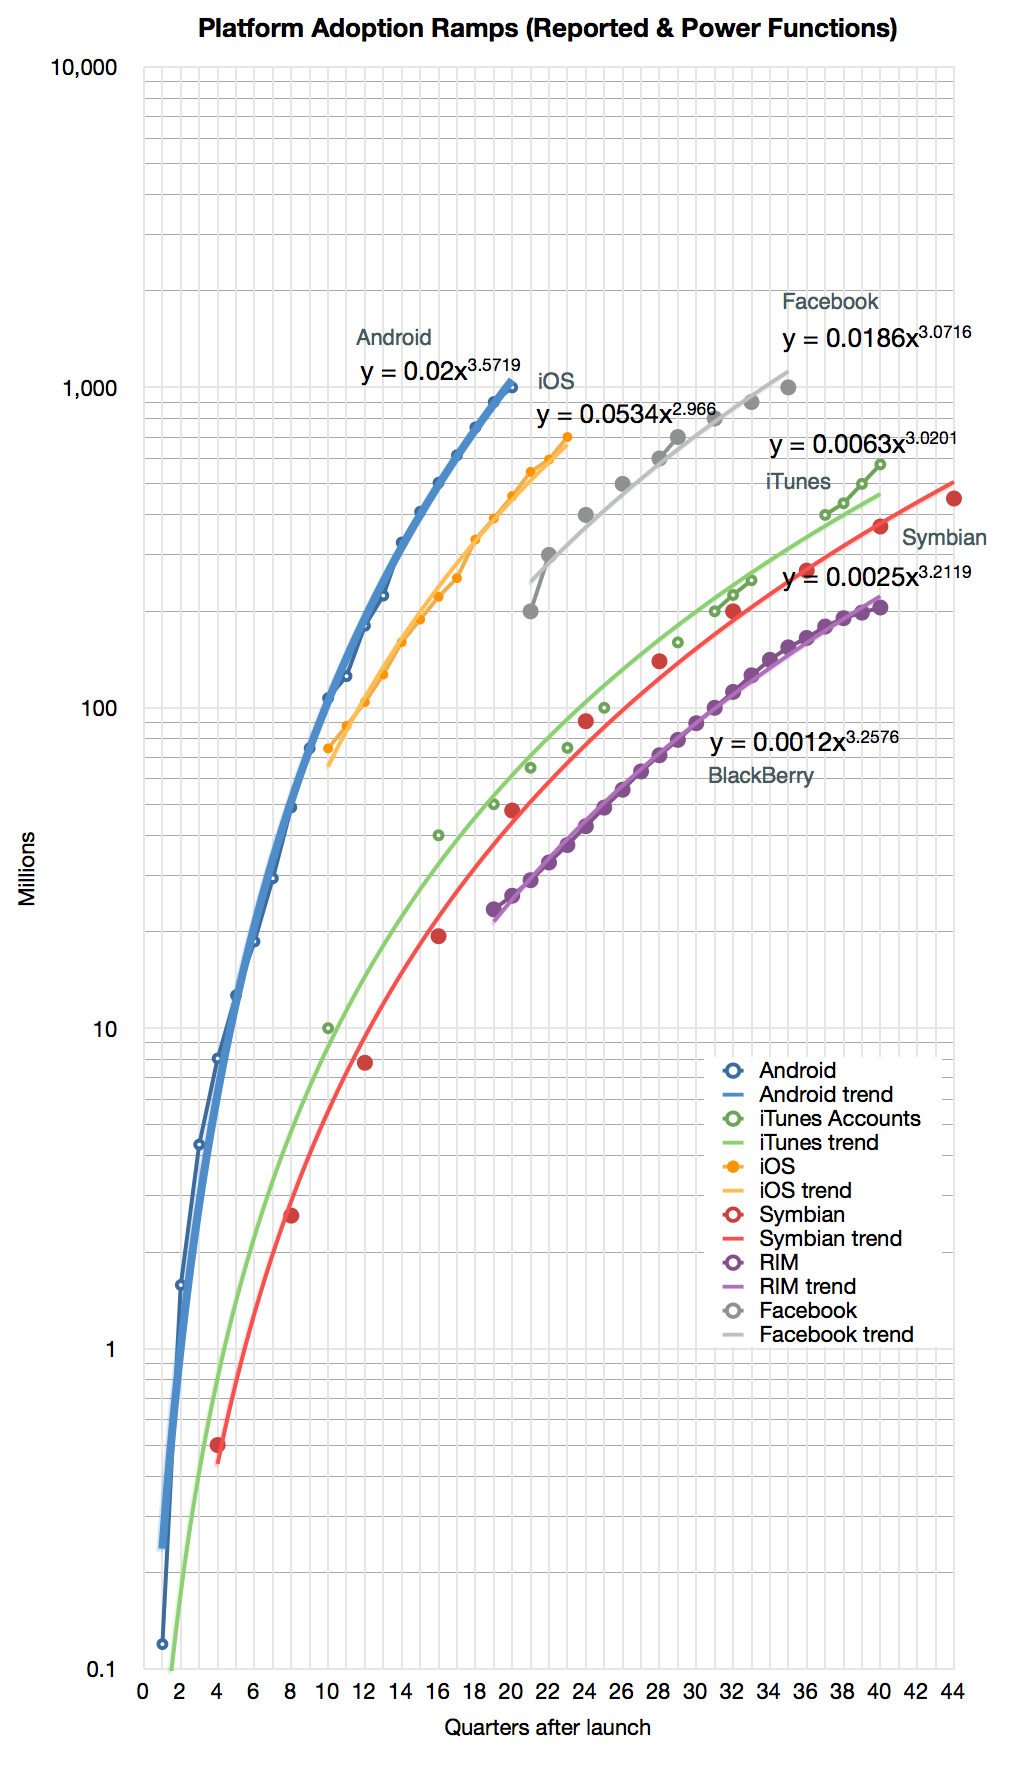
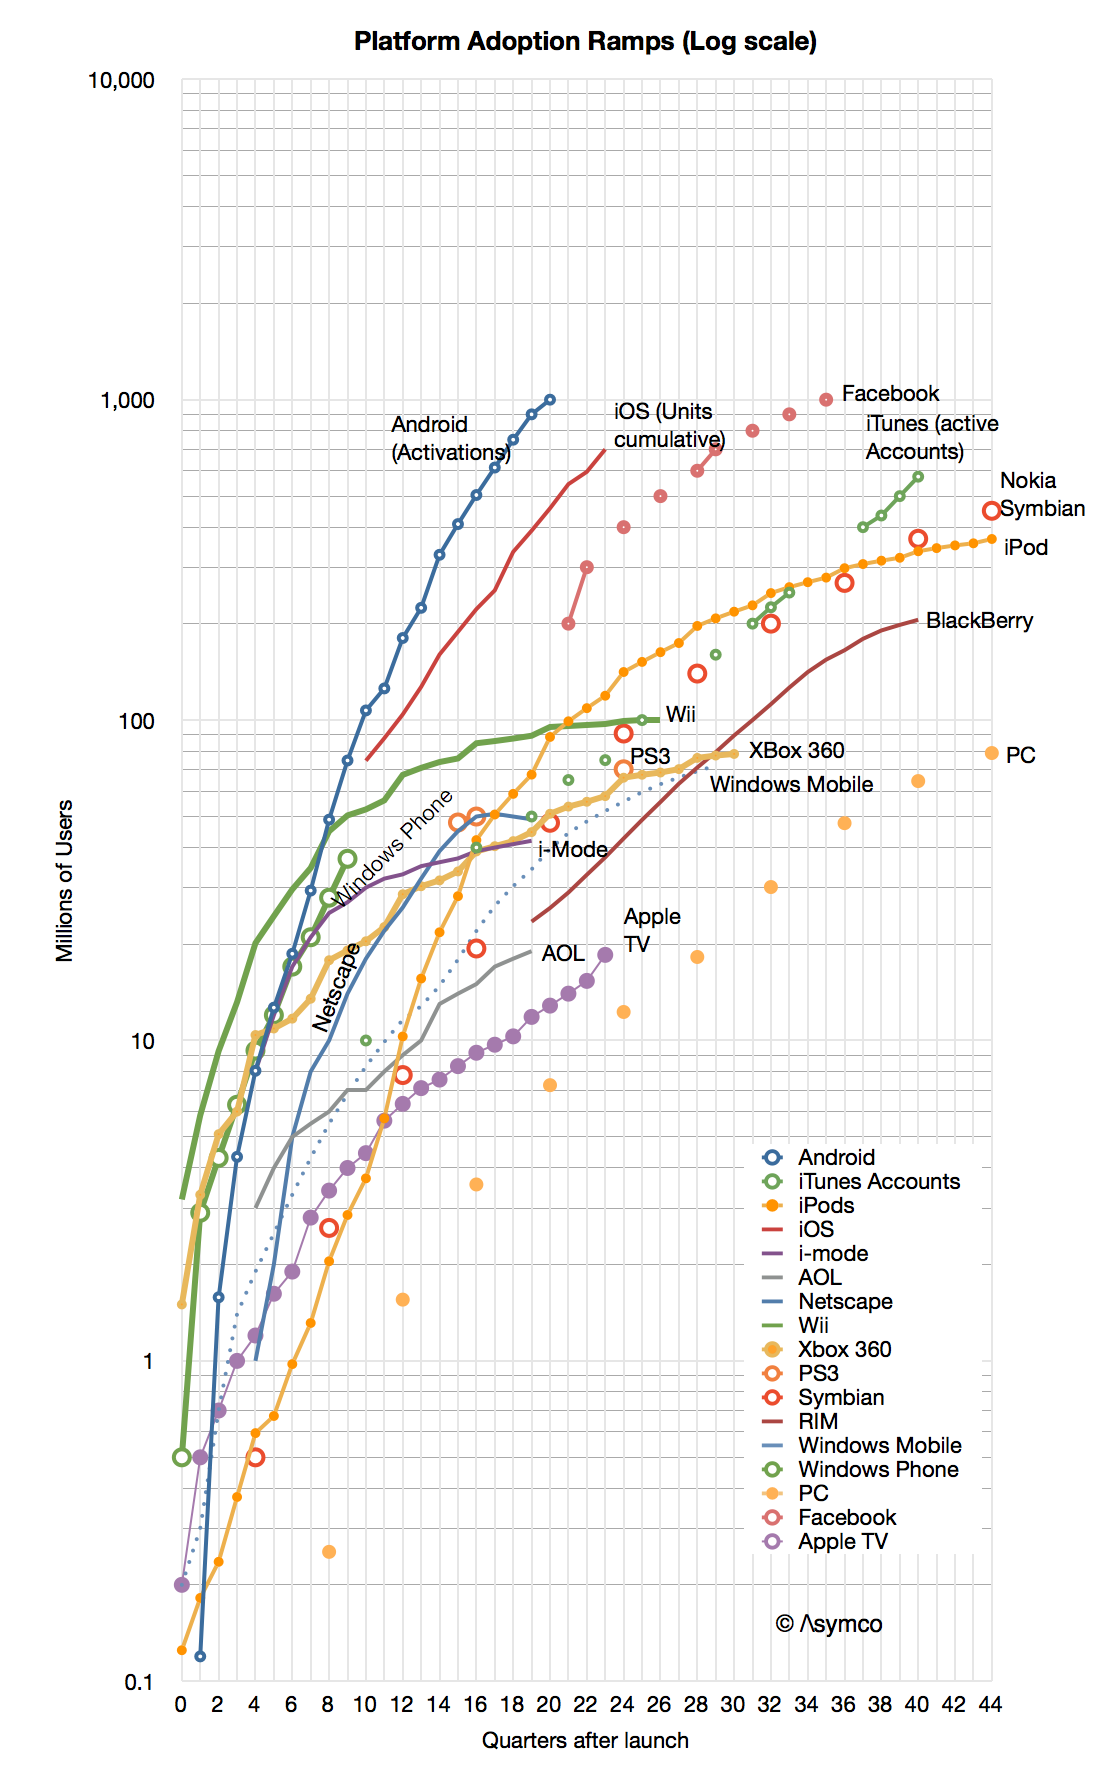
    When looking at the Race to a Billion data I noticed that some platform adoption ramps look quite different from others. It's not just a matter of "slope" or rate of growth but a distinctly different shape.

    If you look at the graph below you might see the difference yourself.

    Screen Shot 2013-09-12 at 9-12-4.41.13 PM

    First, note that the graph is logarithmic. A straight line on a log chart implies exponential growth (the y values are a constant to the power of the x value). However, none of the graphs show straight lines. None of the platforms follow exponential growth ((Except perhaps in the very early periods)).

    Second, we can eliminate linear or logarithmic functions. They simply do not fit.

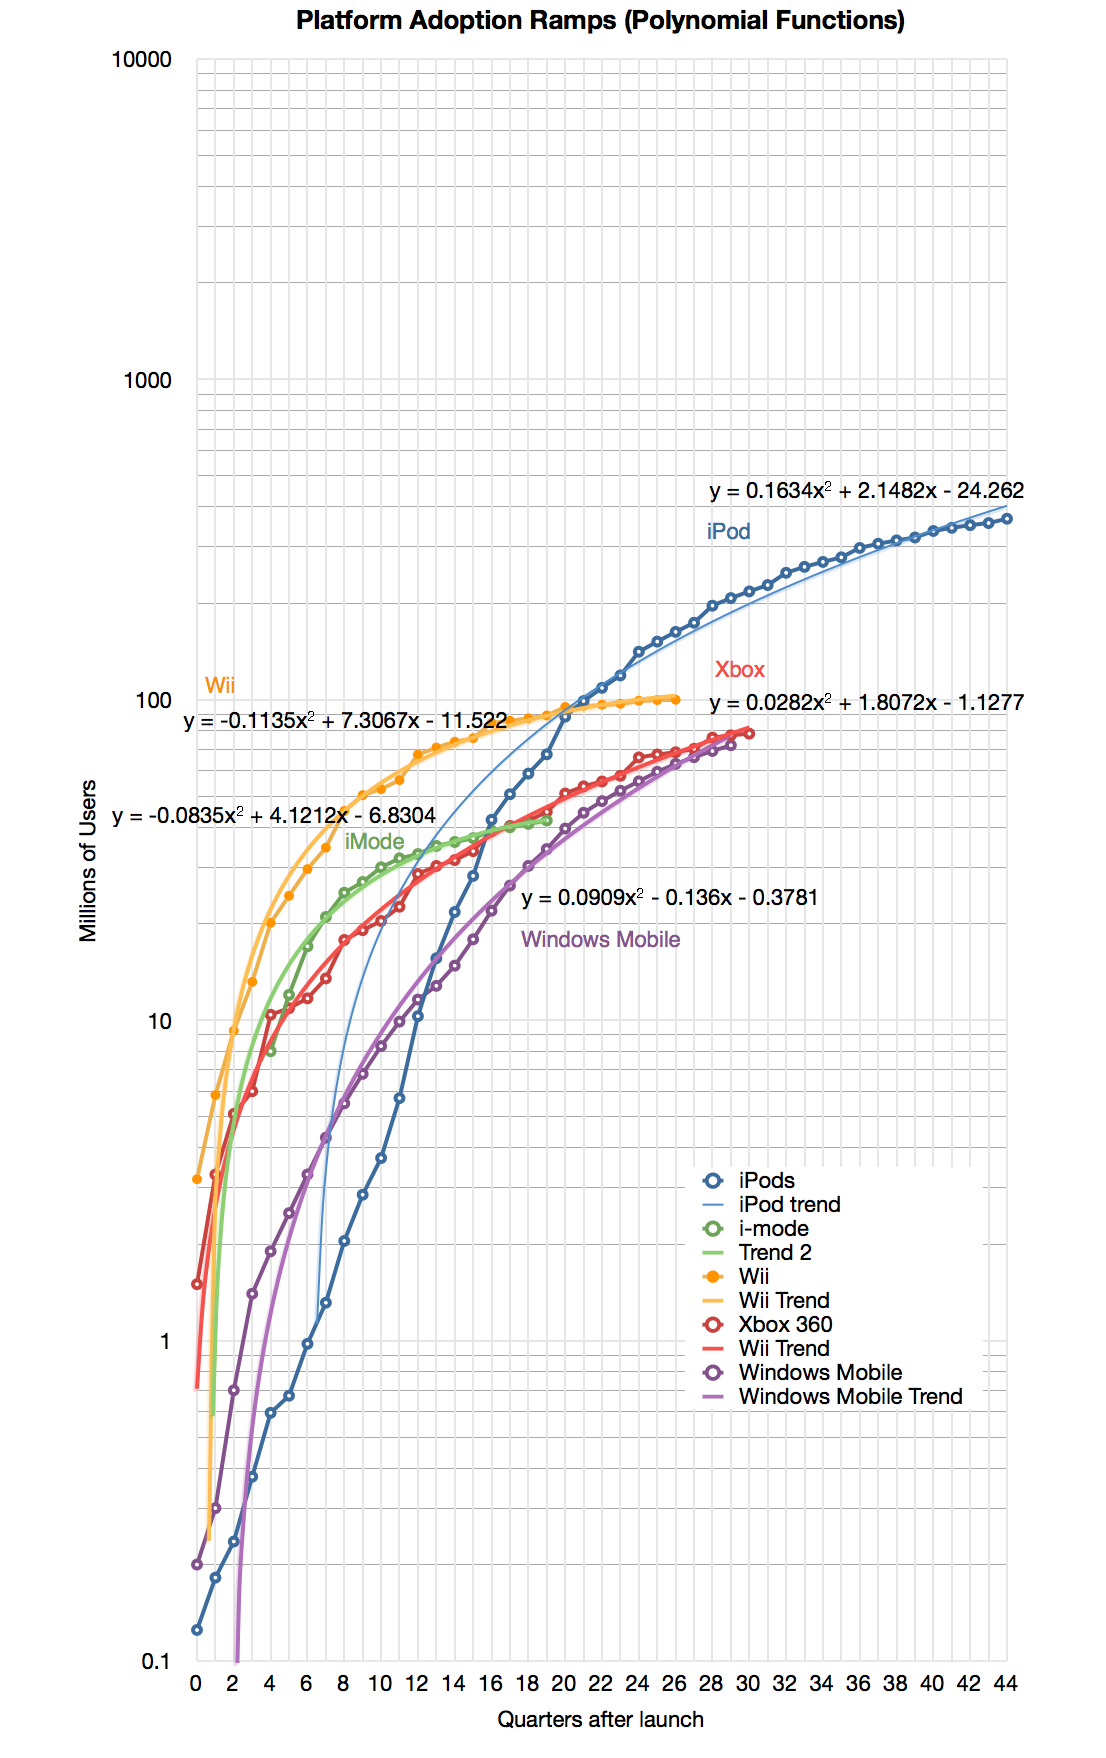
    That leaves: polynomial or power. It's easy to test these alternatives for all the functions and it becomes clear that most of the platforms split into one of these two classes.

    Here are the classes ((Some of the platforms had to be dropped because there was no easy fit. My observation is that some of these platforms went through some crisis or change in strategy during their history which caused the pattern of growth to change)):

    Screen Shot 2013-09-12 at 9-12-4.43.43 PM
    Screen Shot 2013-09-12 at 9-12-4.44.58 PM

    Note that I added the formulas for the selected platforms.

    I named these classes after their function types: "Power platforms" or "Second Order platforms" ((Note that all Polynomial functions found above are second order)).

    This classification has two benefits:

    1. It allows a clearer distinction in scope. Both may exhibit signs of network effects, but Power platforms seem to exhibit "global" or unlimited reach while Second Order platforms may have a strong upper bound on reach.
    2. It allows more reliable forecasting. If a platform classifies as Power, the forecast could be created with fewer data points.
    3. It allows us to guess at the causes of entry into each class for any potential platform challenger.

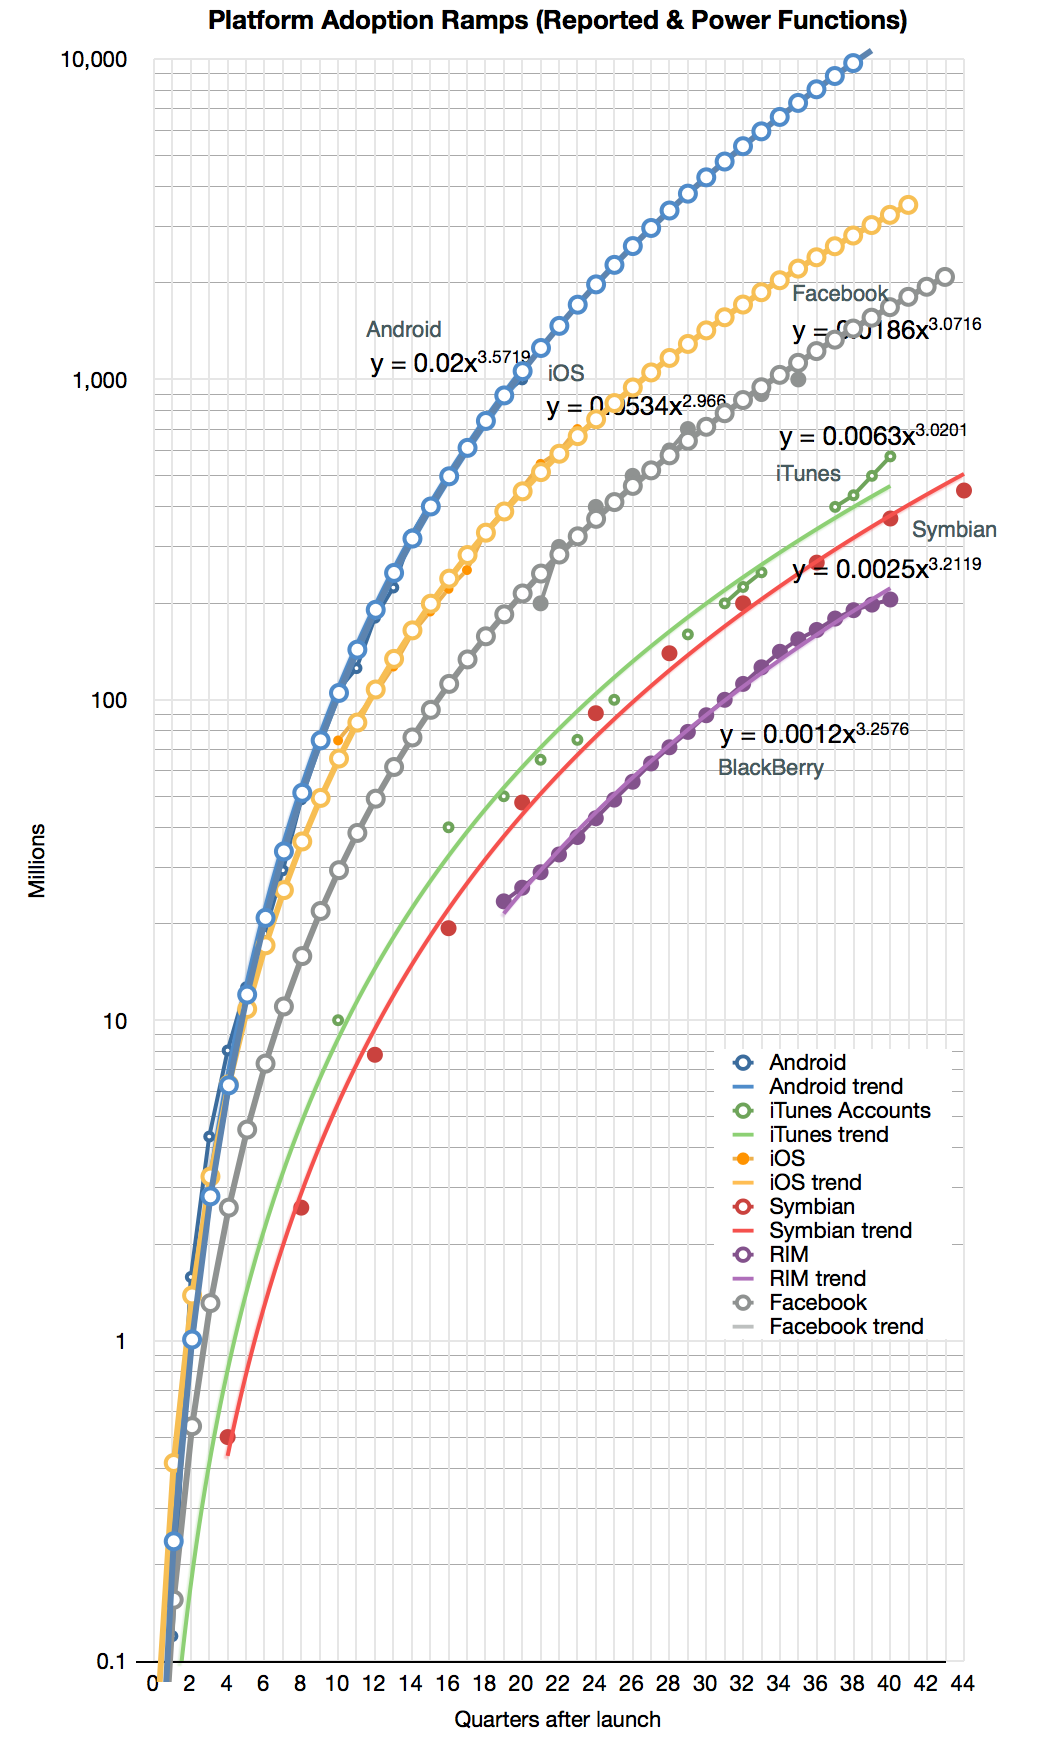
    To illustrate the second benefit, I took the Android, iOS and Facebook power functions and modeled (i.e. extrapolated) them for a few quarters into the future. The result is shown below:

    Screen Shot 2013-09-12 at 9-12-4.46.01 PM

    The forecast shows the following:

    • Android will reach 10 billion activations 10 years after its release (mid 2018)
    • iOS will reach 1 billion units sold by end of next year and 3 billion units by its 10th anniversary in 2017.
    • Facebook will reach 2 billion users by 2015 after the end of its 10th year.
  3. S is for Service

    Research · 96 comments

    One of the enduring mysteries of the iPhone has been its lack of a portfolio. After six years it seems that Apple has finally acquiesced that there should be one, albeit currently limited to two items. The second enigma is related to the price, namely why does Apple ask so much for its phones? At an average sales price of $600 it's a shocking premium to the average phone, and with a six year run, a shocking resistance to the corrosive effects of competition.

    The obvious answer to why Apple asks so much is because it can. Anybody would if they could. That's a poor question. So the right question should be: why does anybody pay this much? One could answer that few do and it's not a mystery that some feel better paying more simply because they can. But those who pay Apple's prices are, mainly, not consumers. They are operators. Exactly 270 of them.

    So then let's re-ask the question: Why do so many operators pay so much for Apple's phones? We can't answer that with the psychological slurs usually directed at the brand. Surely Operators aren't competing in beauty contests or need to soothe their collective egos. The decisions operators make on whether to range a phone are driven by hard economic realities: ARPU, churn, network costs, depreciation, ROI, etc. Some clearly can't make the iPhone fit their economic models and indeed about two thirds of them don't. But the most prominent ((Arguably the most important)) do. DoCoMo, the largest in Japan just did after holding out for five years. Verizon held out for years, as did T-Mobile. China Mobile's acceptance also seems imminent.

    But that still leaves the question of why are those operators who do carry the iPhone willing to pay so much for it? I only assume that their decision process is likely to be rational. Mainly because we have a large enough sample but also because there is a lot of money at stake requiring quite a bit of internal consensus and vetting before committment. We have to conclude that operators place the orders because they obtain value from the iPhone even when it's priced at a premium to the average alternative.

    The question which follows then is how do they obtain value? I've argued that this follow-the-money process leads one to conclude that the iPhone helps in moving users to higher revenue data services. These are more profitable services for operators and the subsidy model creates more loyalty and thus reduces churn and creates a stable cash flow which can then be leveraged through debt to upgrade networks and attract yet more loyal iPhone users.

    Therefore the iPhone is "a data service salesperson" receiving a large commission (in the form of a price- and hence margin premium) for doing what few others can do. In that sense the iPhone is hired by the operator to do a unique and valuable job and is paid well for doing it.

    This answers the question of why Apple can get away with charging so much for its phone: because operators love it. The entire product depends on a reward system and for years we've heard fears that it's going to end. But it hasn't. Operators love subsidies and they've been honing them for long before the iPhone showed up. ((Recall that the first iPhone was sold without subsidy and with a separate, secret revenue sharing plan. It did not last because it was cumbersome and because operators convinced Steve Jobs that their way was better.))

    But this is not the end of the money trail. The premium is initially paid by the operator but they tend to get most of that payment back from the consumer. In other words the subsidy that inflates the iPhone price is at least partly if not mostly paid by the consumer in the form of a higher phone bill.

    You won't see it itemized on your bill, but it's likely that $10 to $15/month from a subsidized phone service plan goes toward paying for your phone.

    So in a way, Apple has managed to place itself on many people's monthly phone bills. It's a nice place to be. It's nice for the same reasons operators like post-paid customers: predictability. It's also nice because recurring services are a better business model than products; they have higher levels of loyalty and are more "sticky".

    But this placement is not transparent. It smacks of misdirection. The link is not made in the mind of the consumer that they are paying for a phone through their service plan and many see it as a thinly veiled con. The value of the iPhone to the user may be evident through its use but the payment for that value is not.

    But in many ways this is similar to how many services are valued: through bundling. We pay for the value of a great retail experience through a higher price on items purchased. But we still associate that price with the good sold not with the place where it was bought. We get great value from Google's services but don't know how to quantify the cost of their peering into our minds. In fact the whole Internet and all business plans that are built on it depend on a subtle "something for nothing" type of misdirection. The Internet runs on the arbitrage between a consumer service market where everybody consumes but nobody pays and a separate data market where nobody consumes and everybody pays.

    The iPhone could thus be finally understood as a complex service business. It captures value through the phone bill but delivers value through a screen. A misdirection magic trick which many have tried to pull off. It's essentially tapping into the $1.3 trillion communications market, skimming profits by delivering the "content" which lights up the wires.

    It's great except it does not work everywhere. Not yet at least. The complexity of services means that they are usually found in more advanced so-called service economies and rare in less developed so-called goods economies.

    Economists have observed this process and even have a name for it: servitization: The process whereby almost all sufficiently advanced products are indistinguishable from services.

    As a service, the iPhone's strengths are easier to understand. Its weaknesses as well. Services simply don't work in economies which don't have robust institutions of credit, capital intensive infrastructure and distribution networks.

    It's also the reason why Apple is so slow to penetrate all markets. It's not in the business of selling phones. It's in the business of enabling and creating services.

  4. C is for Cognitive Illusion

    Research · 192 comments

    My assumption going into this, sixth iteration, of the iPhone was that we would see the expansion of the iPhone into two distinctly positioned products: a low-end C and a high-end S. The assumption was based on what what we saw with the iPad: the regular iPad and the mini iPad.

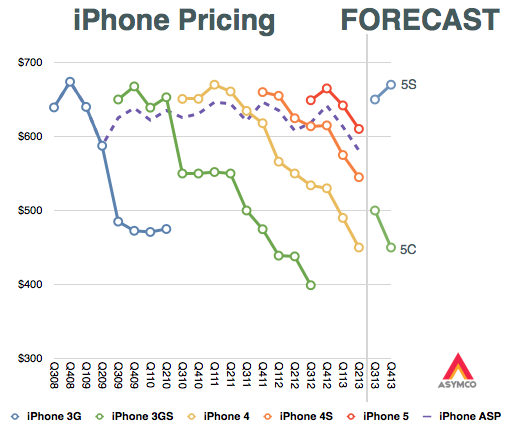
    By using the iPad as a template, my exercise in August was to forecast what the pricing ((Revenue/unit to be more precise)) might turn out to be for such a split-personality product.

    I expected the 5C would replace the "low end" n-2 variant ((Older by two generations as the iPad mini replaced the iPad 3)) and the 5S would continue as the core product. This is reflected in the original graph as devised in mid-August:

    Screen Shot 2013-08-12 at 8-12-11.44.05 AM

    The surprise was that the 5C was not "low end" in any way other than having a plastic case. It has a minor spec increase over the 5 but is otherwise a 5 feature set in a plastic skin. It also is priced as if it was the continuation of the 5, with a modest reduction in ASP.

    In addition, the continuation of the 4S and 4 (in China at least) means that the old strategy continues more-or-less unchanged.

    Knowing the line-up and pricing all that remains to understand is the positioning, or how the products are defined relative to each other.

    This is where there might be a shift happening. Under the old model the n-1 variant was meant to be a modest volume contributor to the portfolio, being essentially a cognitive illusion which encouraged buyers to stick with iPhone n at the expense of competitors. However, the new n-1 product (the 5C) has a distinct positioning that makes it seem fresh and not a lesser, stale version of the flagship. It is designed to appeal as a legitimate upgrade for iPhone 4/4S users.  It is, in other words, not meant as an illusion, and not focusing attention on the flagship ((It might still be an illusion for many but I'm suggesting that it won't be for most.)). Rather, it is meant to be a genuine, core product.

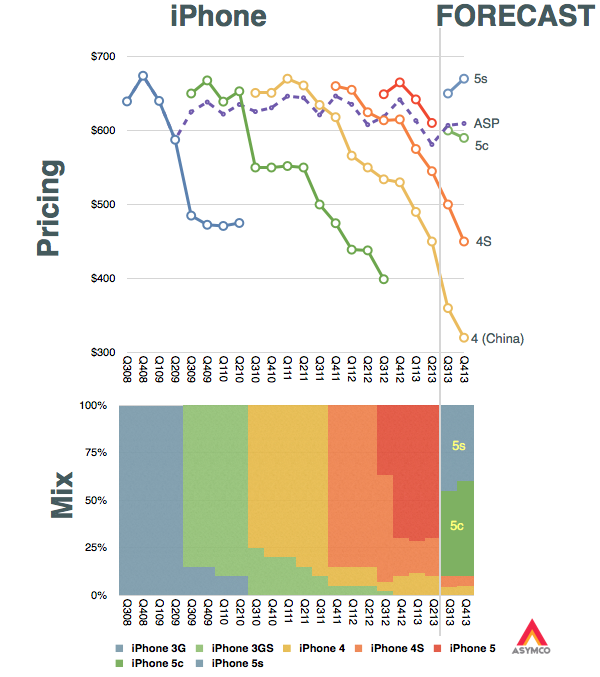
    As a result, I expect the mix of iPhones to be more evenly split between the C and S variants. I expect the C to even become the most popular version in the mid-term. My expectations are shown in the following graphs.

    Screen Shot 2013-09-11 at 9-11-11.57.11 AM

    There are several implications for this shift in positioning:

    1. Apple is recognizing that the market is actually "segmentable". This is the notion that one size does not fit all--a radical idea for the brand. Its mechanism to address it is a "good+better" portfolio. Note that this is not at all like the iPad where the Mini is actually suited to different tasks. The iPad can be thought of as a "small+big" portfolio. The iPhone shows a clear delineation within the same product.
    2. It is signaling that the premium may be more than what the mainstream needs. This is a corollary to the segmentation implication above but stands on its own because it also implies that the iPhone C is "good enough" and the S is more than good enough (or, to spin it another way, it is for "more demanding" customers.) It also implies that the premium "S" version will be a lower volume contributor.
    3. The third implication is that the basis of competition is shifting. ((It has always been expected to shift, but the timing is where all the value is captured)) The shift is toward competing for late adopters in advanced markets and with early adopters in trailing markets. The new C model is still not suitable for trailing markets as it still over-serves and is over-priced ((This post deals with the iPhone portfolio structure or the placement of iPhone models relative to one another. It does not deal with a separate question of why the overall pricing is so high. That question needs to be dealt with as a discussion about the jobs iPhone is hired to do and by whom. I'll re-visit this job-based segmentation of the market in a future post.)), but it is at least signaling the "end of the beginning" phase in the smartphone market.

    In summary I'd say that the C signals the beginning of the "good enough" phase which was also evidenced by the increasing mix of the older models during the last year. Financially it shows up as lower ASP, which, as the graph above implies, I expect to drop to $600 and lower during the next year.  Margins may not be affected much as the C is still very highly priced relative to its cost of production.

    Finally, if the good enough alternative is being "pinned" by Apple as the mid-range it also begs the question of why there isn't a specific "low end" version. It took six years for Apple to fork the product into two variants. Maybe it will take another year for it to stretch to a third. ((For more on the subject see S is for Service.))


  5. My interview with Chloe Cho on CNBC Asia's Cash Flow show

    Research · 3 comments

    My thanks to Kirk Burgess for providing this transcript:

    Horace Dediu interview on CNBC Asia Cash Flow show - 10th September 2013

    Chloe Cho (CNBC): Take us through what Apple is exactly trying to do?

    Horace Dediu: Well, this is the first time in the six years of this competition in the smartphone market that Apple has broadened its portfolio. We have seen only a single product launch every year--this is very unorthodox in the industry. Normally each competitor [ranges] dozens of devices. Apple's entry has been asymmetric from the start, and now in its sixth year we are expecting to see, finally, a broadening perhaps into two separate products. The question will be whether [there will be] a significantly lower price point for the so-called 5C and whether that will change the average selling price overall for the portfolio. The average selling price has been remarkably steady, and remarkably high, typically around $600 for the duration of this products life. Something, again, unprecedented. My expectation is the new price point will be quite a bit lower than $600, starting with about $450, it might drop a bit further, [which] would cause the overall price range to come down as we have seen with the iPad; [where we] also had a price erosion happen as the smaller version came out.

    Q: Horace, do you think they have got the timing right? Should they have done this a little bit earlier when the market wasn't so saturated and filled with cutthroat competition?

    A: Indeed, I think. As I said, as a product with six years in the market it's a bit late; I expected this to happen last year. I think a lot of the momentum that has been lost in the past year in terms of sales growth has been because of the lack of low end. To note also will be whether they indeed expand their carrier footprint. We are expecting something new in Japan and possibly China Mobile. There is a second announcement happening with a few hours delay in China. This is again the first time that has ever happened.

    Q: Horace, do you think they didn’t move down the value chain fast enough largely because they didn’t have a deal with China Mobile?

    A: Well that's always a good question whether they are driven more by carrier channels or are they driven more by consumer market expectations. I think it's a bit of both. We do have this hybrid approach where they continue selling this older product for one or two years after the new product is launched--so the 4 and 4S are still available while the 5 is being ranged. This strategy is hybrid I say because this isn't truly a low end product, it is a stale product that is being put out there. This [strategy] may be driven more by consumer demand, not so much what operators are asking for. With the 5C we might be looking at a solution for operators in particular.

    Q: Horace, how much do some these incumbents like Apple and Samsung need to be worried about Microsoft approaching their space?

    A: I believe Microsoft will not be competitive in the near term. I don't think [during] the next year we are going to see a very impactful entry from Microsoft. What Microsoft is likely do is lower prices significantly on Nokia's portfolio and their pipeline as it is. That might cause more pressure on the pricing, but the problem has been that consumers have not really been taking up the Windows Phone platform very aggressively. It has been somewhat successful in Europe but not taking off elsewhere. I think Microsoft will be in an integration mode with the Nokia assets into 2014, but I would expect in a year from now we might see some new entry product that would be exciting. I think 2-3 years down the road we might see something from Microsoft that would excite consumers as well.

    Q: There has been a lot of focus on which companies have a more integrated house, Apple or Samsung. In light of the fact that they are having to move into lower price points, in your view which is doing the better Job, Apple or Samsung?

    A: Well Samsung is a great industrial enterprise and they are doing very well by broadening as much as possible their portfolio, even before the smartphone race started for them, which was in 2010, they were known for being one of the most prolific product creators out there. They actually had over 100 different mobile phones, not smartphones, just regular mobile phones that they would range, and Nokia were extremely concerned by this pressure they were getting from Samsung.

    What they have seen since 2010 is the same thing, except with smartphones, and so they’ve been really prolific and covering the spectrum of price and screen and every other possible variant that could be made. I think however that Samsung hasn’t got a software platform under its belt. They could become a software player by taking over some of the control of Android as we have seen Amazon do, and thus really establish themselves as a platform player. They are doing so to some degree with the "Gear" product, and they might be doing something like this by launching their development conference this year.

    But they aren't yet a platform player whereas Apple is, but then again we just don’t know what the politics of Android are with respect to forking it by an OEM as large as Samsung.

  6. Third to a billion

    Research · 166 comments

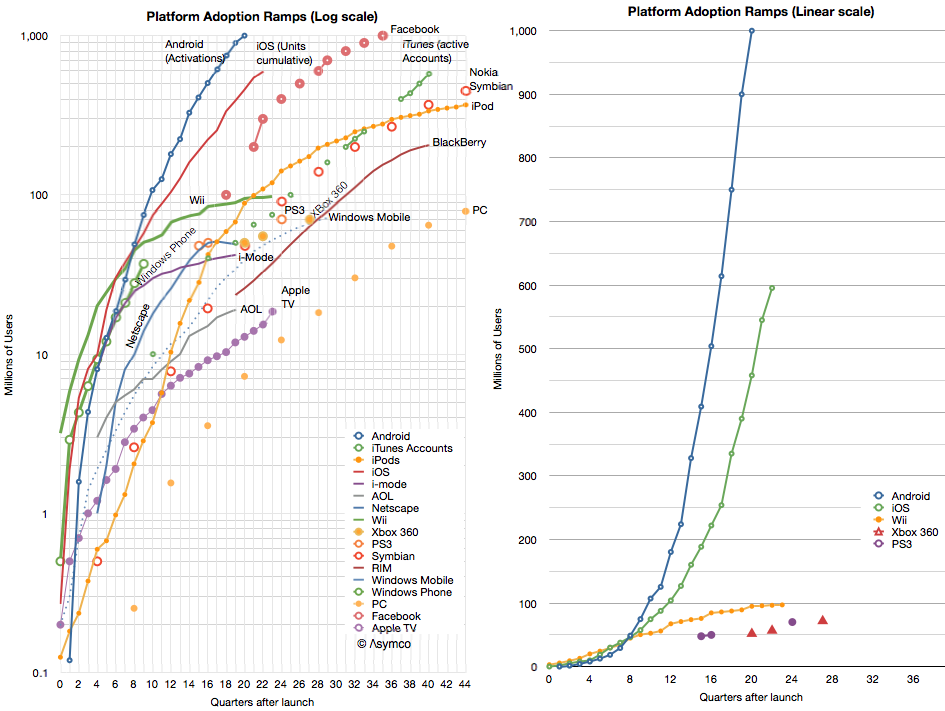
    Android is the third platform to reach a billion users ((Although activations are not users, I'm assuming that usage is not far behind and the cumulative sales figures I gather are roughly comparable.)) .  The first was Windows and the second was Facebook. Apple sold around 650 to 700 million iOS and is expected to be the fourth to a billion sometime next year. ((Separately, iTunes reports 575 million account holders.))

    If we define the Race To a Billion to be bounded by a time limit of 10 years, then Windows does not qualify and Android is actually second. The race is shown in the following graphs (the one on the left is logarithmic scaled, the one to the right includes only a few contenders for illustrative reasons).

    Screen Shot 2013-09-06 at 9-6-4.06.29 PM

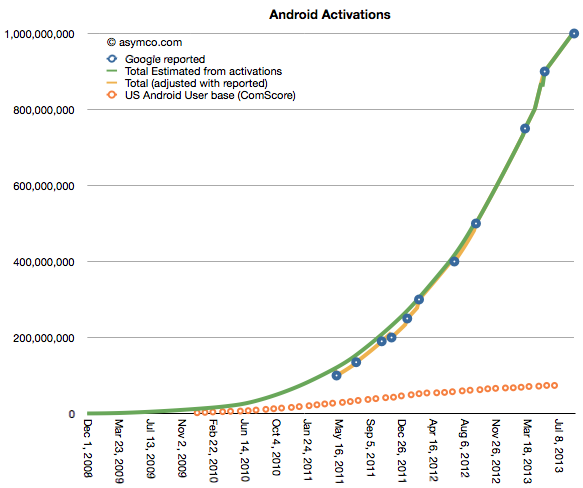
    Android's activations as reported are shown in the following graph:

    Screen Shot 2013-09-04 at 9-4-1.15.38 PM

    Without qualification, Android has been a viral success story. It reached one billion activations in about five years, almost half the time it took FaceBook and far faster than Windows.

    However, Android growth can be qualified. I added another set of data which is the number of US Android phone users as deduced from measurements by ComScore. ((ComScore surveys users on their primary phone. Survey includes only those aged over 13 years and excludes phones issued by businesses.))

    One way to read the two graphs is: Between March and August, of the 250 million Android devices activated, 4 million were to new Android consumers in the US. In other words, In the last six months, 1.6% of Android activations went toward new usage in the US. The equivalent figure for iOS is about 6%. Note that these are new users, not included are upgrades. It's likely that more of the US buying goes toward upgrades because iOS has been in use longer.

    So whereas Android is growing very rapidly, there is a question of reliability of that audience. Engagement is one thing, but in the market which shows highest penetration (and deepest distribution of an alternative) Android is peaking.


  7. Who's next?

    Research · 166 comments

    In February I asked Why doesn't anybody copy Apple?

    Put another way: Why is it that everyone wants to copy Apple’s products but nobody wants to copy being Apple?

    Being Apple means, at least:

    • Insourcing all aspects of operations which affect the customer experience. Increasingly that has meant insourcing everything, a toxic idea to every MBA-trained professional since forever.
    • Organizing functionally and having no product level P/L responsibility. That also means removing almost all incentives for employees to climb ladders and thus prove their worth.
    • Developing products using integrated "heroic" efforts which shun  every best (or even adequate) process for product development.

    I asked somewhat rhetorically because it's an open question. Apple's operating model and devotion to integration have been asymmetric to technology dogma for decades. To the casual (read: naïve) observer, pursuing the Apple way seemed also to be tied to one individual. You could not "be Apple" unless you were also Steve Jobs and there was only one of him.

    But it seems I did not give enough credit to other observers.

    According to Microsoft, they began negotiating the buying of Nokia assets in earnest (coincidentally) in February. It has, also since February, been planning a massive re-organization along functional lines. Thus, by owning significant hardware operations and organizing functionally, Microsoft might go about two thirds toward "being Apple-like". The development process is the final hurdle and it may be a bridge too far, but my thesis that nobody wants to copy Apple is now in tatters.

    And it gets worse. We can see a similar, though far weaker, example in Google's approach to integration. Their purchase of Motorola did not result in an integrated business, with Motorola being kept at arm's length and allowed to wither on the vine. Crucially, while Google bought Motorola's IP, Microsoft only licensed Nokia's. Microsoft clearly valued Nokia for something different than  what Google valued Motorola for.

    Nevertheless there is a semblance of similarity. We can generalize enough and say that Apple (iOS), Google (Android/Chrome) and Microsoft (Windows (Phone)) are all becoming near facsimiles of each other. They are all producers of Software, Services and Hardware. Each came from a different basis but expanded into areas which were missing.

    • Google started with a service, expanded into systems software and bought into hardware.
    • Apple started with hardware running its own software, expanded into application software and is developing services.
    • Microsoft started with software, expanded organically into services and bought into hardware.

    All three major platform companies are now racing to offer that which completes them as an integrated producer and eliminates the dependencies on others as a modular producer.

    This is re-integration of the computing industry--a reversal of the dis-integration brought about by the personal computer. Mobility, it turns out, was as important to the evolution of the computing value chain as microprocessors were to the previous era. It just had the opposite effect.

    I should point out that Apple was more lucky than enlightened through this sea change. Having always been integrated, Apple was out of favor during one period of the computing epoch, but, simply by surviving, its model came back into favor in the next. I don't think anybody there foresaw just how dramatic the shift would be and how important their structure was to being successful.

    But there is one company which seems left out of this discussion. Samsung is absorbing a large part of the available profits in computing today and it's not an integrated hardware/software/services player. Does this mean that there is room to be a module in an interdependent world?

    I argue that no, there isn't. Samsung must either stretch into becoming one of the ecosystem contenders or be relegated to a commodity hardware company--a path clearly visible when looking at Chinese entrants. Samsung itself benefited from disrupting from below and should be aware of the threat it faces as it races up-market. More importantly though there is the ability of creating new markets altogether. This new market creation and rapid iteration due to integration is what the Google/Microsoft/Apple trio are seeking.

    Without the components of software (ecosystems included[1]) and services, Samsung will depend on the good graces of suppliers. They may not be as keen to share when profits accrue to the whole rather than the part.


    ---

    Note:

    [1] e.g. BlackBerry

  8. Who's buying whom?

    Research · 115 comments

    When a prosperous company buys a struggling company you have to wonder what they're really buying.

    Here's how to think about it. A company is defined as the sum of three values: resources, processes and priorities (RPP). Everything of value can be classified into these three categories.

    When one company buys another it's the equivalent of one set of RPPs trying to engulf or swallow another set of RPPs. The simplest (naïve) interpretation is that an acquisition is the purchase of Resources in terms of customers, sales, profits, etc. It might be of assets like employees, intellectual properties, brand etc. I say this is naïve because Resources are the easiest to value because they can be measured and valuing only what can be measured while ignoring what can't be measured is deeply mis-pricing.

    So most people look for the "R" value or the value of Resources in an acquisition. It's may be naïve but it is what markets typically value because it's what they can price. But what happens when the "R" is flimsy or fleeting?

    The answer has to be that it's  the processes or even priorities which are valued by the acquirer.

    These are difficult to value which, as I've argued in The Innovator's Curse, is why they are not reflected in a share's price. When there is a price paid for these fuzzy assets, they are often interpreted as a "premium" to the market price. But that may not be the way a buyer sees it.

    When buying a set of Processes, a buyer may see a bargain because their costs for building a similar process could be enormous, even infinite. In the case of Nokia, the process of building hardware may be infinitely valuable to Microsoft as they have had dreadful luck doing it themselves. But they're seen as value free to the market because it seems that there are many others who are building hardware.

    The trickiest thing to perceive though is the value of a set of Priorities. Priorities are the answers to the "Why" question as much as Resources are the answers to the "What" and processes are to the "How." If you were to think in terms of software engineering Priorities are the "Specifications" where the Resources are the data and Processes are the algorithms. They determine the direction and reasoning of why a company even exists. If you have bad specs, it never matters whether the algorithm is efficient and you have all the data: you are building the wrong thing.

    Acquiring Priorities is also fundamental in that they are usually exclusive. A company typically only has room for one set. If there are conflicting priorities, they need to be sorted out else the company can end up in a state of internal conflict and dysfunction. So if you're acquiring a set of Priorities, it's likely that you'll have to discard your own. It makes most sense when a company which might otherwise be prosperous needs to change direction.

    So, in a way, an acquisition of Priorities is almost a reverse acquisition. The acquired is actually "buying" the acquirer. The acquired company's Priorities (and hence Processes and Resources) become the guiding principles in the acquirer. It's what happened when Apple bought NeXT and may have happened when Disney bought Pixar.

    Some companies are "Resource-heavy", some are "Process-heavy" and some are "Priority-heavy". Great companies tend to have great sense of priority. They may also have greatness in the other asset classes but it's rare to find a great company without a great sense of purpose.

    So the question for the Microsoft Nokia deal is what is Microsoft buying?

    Resources? Sure, there is IP and a team. But the chances are that not all the team members will be kept on. See what happened to Motorola after it was acquired by Google.

    Processes? Absolutely. Microsoft needs device development processes desperately.  They may seem a commodity but it turns out that running great hardware businesses is hard, very hard.

    Priorities? Here we have to pause. To acquire Nokia's priorities means acquiring its business model; its belief system. Perhaps they will be discarded and they're not valued. Perhaps, as is often the case, the acquirer becomes allergic to the new priorities.

    But Microsoft has made it clear that they are now a "Devices and Services" company. As much as Apple changed its name to exclude "Computer," Microsoft is almost changing its name to exclude "software". It will still make software, to be sure, but for it to get paid it needs to integrate that software into hardware and services.

    My first thought on this is that Nokia's priorities are not sufficient for the company that Microsoft wants and needs to become, but there are some priorities which are necessary and which it values.

    It may be too much to say that with respect to Priorities, Nokia acquired Microsoft, but insofar as Microsoft is having to transform its business model, what Nokia devices brings is an integral component of the new.


  9. Unforgiven, Continued

    Research · 5 comments

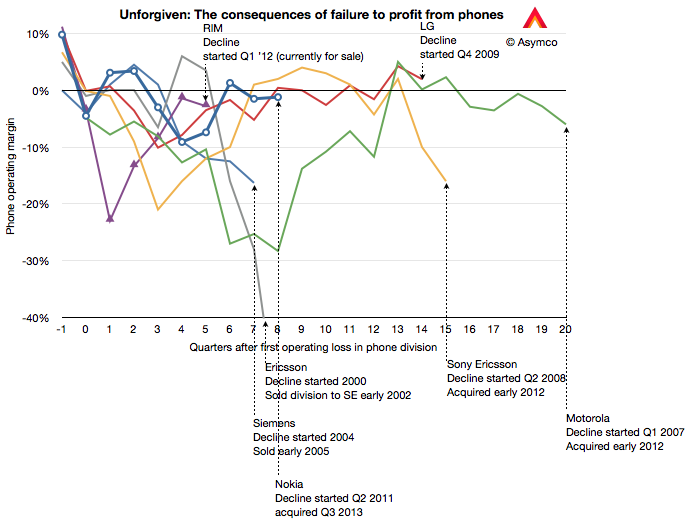
    In June of 2011 I asked "Does the phone market forgive failure?" Not much time has passed since but the answer still seems to be no. The trigger I was using for this point of no return when the vendor began making losses.

    The list at the time consisted of 13 phone vendors who either merged, were liquidated or acquired after this trigger point was reached. There were no examples of vendors who recovered. Since then two more vendors reached the threshold (Nokia and RIM) and a third will do so this quarter (HTC). One vendor (LG) may be recovering but Nokia has just been acquired and RIM has put itself up for sale. Some Japanese vendors like Panasonic have also called it quits since then. So the score so far is about 18 triggers, 15 exits and three pending.

    Some of this data is summarized in the following graph:

    Screen Shot 2013-09-03 at 9-3-9.19.51 AM

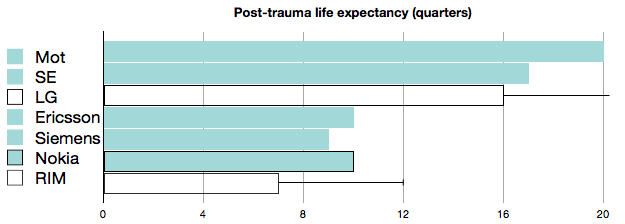
    It shows that post-trauma life expectancy is now running at about 2.5 years. As RIM is only in its second year, one could perhaps expect another 6 to 9 months of independence. HTC could go on until 2015 but the smaller the company, the more vulnerable, so HTC's exit time should be shorter.

    Screen Shot 2013-09-03 at 9-3-9.20.57 AM

    The exception might be LG which seems to be recovering. As a conglomerate, LG is much less vulnerable and might have the resources internally to sustain the phone business indefinitely.