Asymco

Asymmetric Intelligence

Horace Dediu

  1. Airshow coming to New York

    Conference · 2 comments

    I'm delighted to once again have the sponsorship of IBM for the presentation of Airshow. This time it's in New York City on Wednesday, 25 September at the IBM Building, 590 Madison Ave. My thanks again to Paul Brody for being so gracious and earnest in his support.

    Seating is limited but there are still 25 20 3 available.

    This will be the third Airshow, having started in June in San Francisco and rolling into Chicago in July. The event keeps getting better with a plan to introduce a hands-on module allowing participants to build cinematic data-driven presentation during the afternoon.

    Airshow is intended as both an exhibition of technique and as an explication of   the methods for creating persuasive presentation enabled by new technologies.

    Without revealing too much, the gist of the theory espoused is that presentations can benefit from:

    • The use of directly manipulated visuals
    • Cinematic effects honed by cinematographers over a century
    • Aristotelian presentation principles

    Together, these techniques solve the "job to be done" of persuasion—a job universally in demand but deeply underserved by current tools and techniques.

    The participant should come away from the event with the ability to:

    • Use the iPad as their primary presentation tool, with or without a projector to large and small audiences
    • Use a cinematic technique of presentation where a layer of implicit yet easily sensed meaning is overlaid upon the words spoken and images viewed
    • Appeal with empathy, logic and credibility to all audiences.

    You can register for Airshow New York here.

    See also: The end of the projector.


  2. It's a wonder

    Research · 3 comments

    My responses to questions from Juliette Garside of The Guardian newspaper:

    Q: Will noise from Icahn distract the Cook from focussing on product?

    A: Investors may think that they can influence management but they do so only when companies are in distress. It’s only then that shareholders can affect some change with their votes as they have a common purpose. The voice of investors carries little weight or distraction when a company is successful. At first glance it seems that Icahn thinks he can unlock value in Apple by getting management to accelerate share buybacks. That’s a modest goal and not one which needs to distract managers.

    Q: What will do most for the share price – a buyback or a blockbuster new device?

    A: Neither. What will do most for the share price is a change in the perception that Apple is not going to survive as a going concern. At this point of time, as at all other points of time in the past, no activity by Apple has been seen as sufficient for its survival. Apple has always been priced as a company that is in a perpetual state of free-fall. It’s a consequence of being dependent on breakthrough products for its survival. No matter how many breakthroughs it makes, the assumption is (and has always been) that there will never be another. When Apple was the Apple II company, its end was imminent because the Apple II had an easily foreseen demise. When Apple was a Mac company its end was imminent because the Mac was predictably going to decline. Repeat for iPod, iPhone and iPad. It’s a wonder that the company is worth anything at all.

  3. How will iPhones 5S and 5C be priced?

    Research · 175 comments

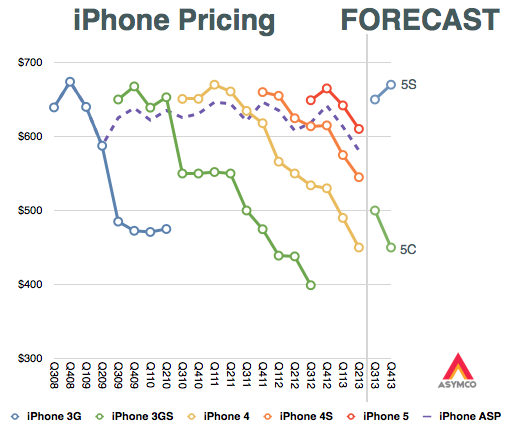
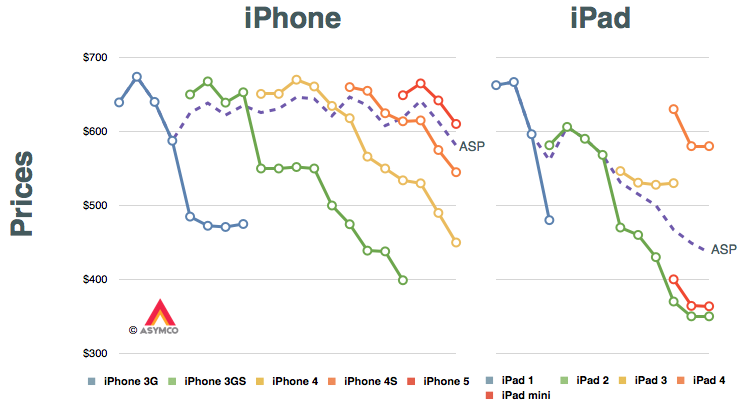
    The answer may lie in the way the iPad mini has been marketed. The pattern for iPhone pricing is pretty regular but that for the iPad shows a marked difference. The reason is, of course, that the iPad has already gone through a portfolio broadening. The following graphs tell the story.

    Screen Shot 2013-08-12 at 8-12-11.30.09 AM
    Screen Shot 2013-08-12 at 8-12-11.49.19 AM

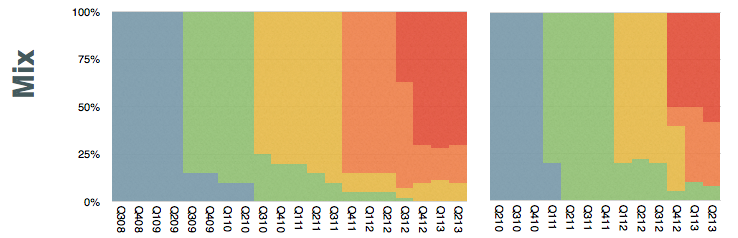
    The only data in these graphs that is provided by Apple are the dashed purple lines. They represent the average selling prices (ASP[*]) for the two product lines. I added assumptions about product mix (shown in the lower set of graphs) and thus generated prices for each product variant at a given point in time shown as  line graphs.

    If you look at the iPad, ignoring the legacy iPad 2 (which I presume sells mostly to educational institutions) the replacement of the iPad 3 was with a "bracketed" portfolio of the higher-priced iPad 4 and the lower-priced iPad mini. Note also that the mini reflects similar pricing to the legacy iPad 2.

    My second assumption is therefore that the 5S and 5C will form a similar bracket as the new iPads did. I also assume that the iPhones 4 and 4S will be retired. This means that the 5C will take up the trajectory of the 4S while the 5S will take up the upper bracket around $650.

    Screen Shot 2013-08-12 at 8-12-11.44.05 AM

    The average pricing for the entire portfolio will depend on the mix. This is still highly speculative since we can't predict how the end-user (operator) pricing will be set for the 5C. Aggressive promotion and new market growth might skew the 5C considerably. On the other hand, upgrade promotions might move the 5S in existing markets.

    ---

    Notes:

    • These prices reflect blended average prices of all SKUs to the channel and do not necessarily reflect prices offered to end-users.
  4. Signs of US Android net user decline

    Research · 255 comments

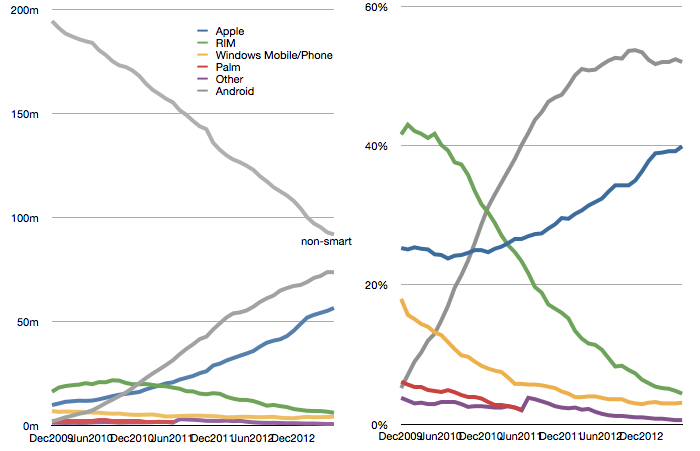
    ComScore's latest survey  for US smartphone users showed that Android had 52% share of about 142 million users. That amounts to 73.84 million Android devices in use.

    ComScore's previous such survey showed that Android had 52.4% of about 141 million users. This amounts to 73.88 million Android devices in use. It also means that Android usage in the US went down for the first time.

    Screen Shot 2013-08-08 at 8-8-10.10.39 AM

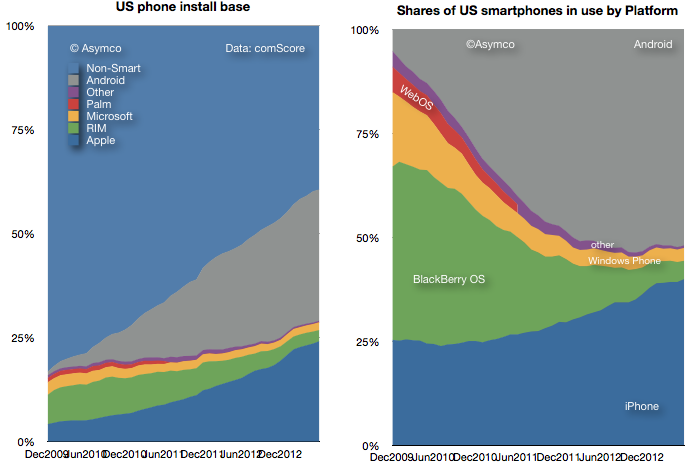
    The difference is surely within a margin of error so it's not something to declare definitively, but the pattern of Android "peaking" has been evident for some time.

    Screen Shot 2013-08-08 at 8-8-10.11.44 AM

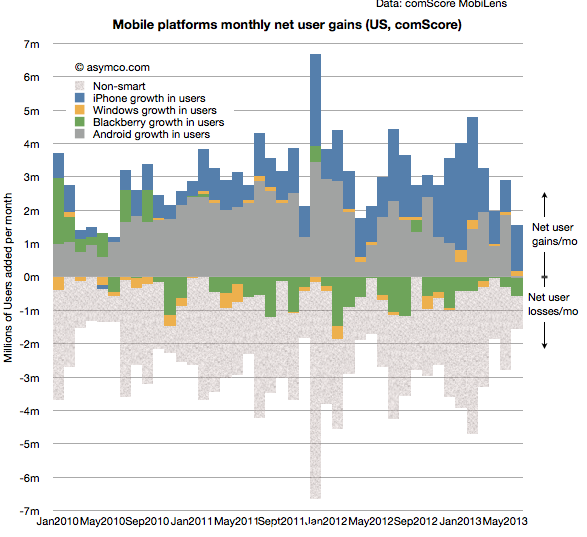
    Even though share stopped growing about a year ago, Android continued to gain users as overall smartphone consumption increased. The last few months however have shown a slowing of new smartphone users and therefore we have this first instance of Android appearing to lose usage.

    Screen Shot 2013-08-08 at 8-8-10.12.35 AM

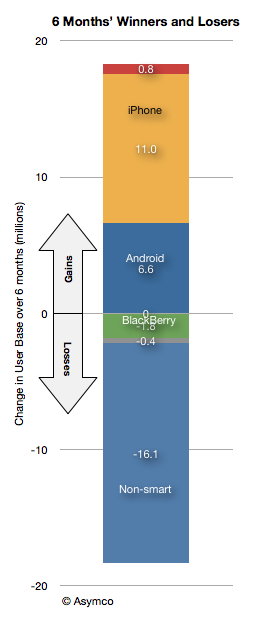
    Note that this has not been the case for iPhone as usage over the last six months is up by 11 million users vs. 6.6 million for Android.

    Screen Shot 2013-08-08 at 8-8-10.13.07 AM

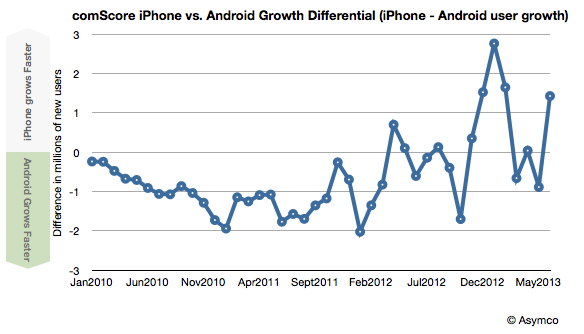
    Indeed, iPhone gained more users than Android for the last 6 out of 8 months.

    Screen Shot 2013-08-08 at 8-8-10.16.36 AM
  5. The Anti-Apple

    Research · 268 comments

    Building a successful business is hard. Many try, few succeed and those that do tend not to thrive for long. So success in business it should be respected. Especially in highly competitive industries like technology. The fragility of success however should also give one pause to think about how delicate a business model is.

    The presumption that companies can shift business models at will is usually false. Businesses are balanced on a knife's edge of dependency on multiple variables. Almost all resources are expended on preserving this balance.

    This being my observation, I take issue with assumptions that large companies can "pivot" on a dime or that they can change their business models "when conditions are right". Consider Microsoft's dilemma. They have all the resources in the world and yet they could not pivot to take advantage of a change so mundane as a low power microprocessor (which enabled a mobile computer and hence a new ecosystem and profit model for software.)

    Or consider the dilemma of Apple which after building a successful computer business which included system software, could not pivot to license that system software so others could build computers with it.

    Or consider the dilemma of Nokia which had an early and large leadership in smartphones including having its own OS and platform and large volumes and users bases. It could not pivot to allow into an ecosystem and had all its advantages disappear.

    Each company thought they could manage change but none of them actually did.

    It's with this thinking about inertial navigation that came to consider the idea that Amazon has a flexible business model which, though unprofitable today, will be profitable some day.

    The premise that Amazon can, on a whim, change its business model from selling other people's products at a razor thin margin while investing in capital-intensive distribution to selling other people's products at a large margin while not investing in capital-intesive distribution is not credible.

    I would argue that Amazon's existing business model is a direct consequence of the market it's in: that it could not be anything else given the circumstances it finds itself in. Enlightenment may be an illusion.[*]

    That's not to say that there is no wisdom in the management of Amazon. Quite the contrary; recall the respect that's called for in creating a great business. Managing the business to this point was a work of decades of vision and creativity.

    What I take issue with is the premise that Amazon is the "anti-Apple" in its hunger for growth and patience for profits. Apple has its own "Amazon-like-business": iTunes has been growing at a steady 25% or more and it also has its ancillary zero-profit hardware analogue to the Kindle called Apple TV.  iTunes is a great business in the Amazon vein, harvesting hundreds of millions of users (and their credit cards.) Presumably iTunes could also some day "flip the switch" and become profitable, but something magical needs to happen. Something like becoming a payments processor or retailer of other things. Analyst beware however. There might be conditions that make such switch flipping extremely difficult.

    At an even deeper level, Apple and Amazon are much more alike than they are different. They are both hired for similar jobs (convenience, ease of use and a controlled, predictable environment for average users interacting with technology). They both focus on delighting customers and controlling all the variables which come into contact with that delight. They both have long-term views and are driven by vision rather than competition.

    Where they differ is in others' perception of sustainability. Whereas Apple is perpetually given an expected lifespan of less than a decade, Amazon is expected to have an indefinite lifespan. This is because Amazon is seen as having no competition and Apple is seen as having infinite competition. In other words, Amazon is perceived as a monopoly and Apple is perceived as the  innovator that is in a permanent state of being disrupted by the low end.

    I disagree with both assumptions. I've always thought Apple fragile but dedicated to moving into new markets as older markets are disrupted. It's a tough strategy and one which (literally) nobody believes possible. But I've also thought Amazon's monopoly status fragile. This too is not a popular idea but the company depends on many variables.

    Retail is hard and it is being disrupted by technology wielded well by Amazon. But it's also subject to further disruption. Amazon's job to be done can be done by alternatives. Buyers are typically hiring Amazon for convenience, not just price and ease of use is where the value is. But again, new information technology which makes shopping, discovery and delivery of products directly from the vendor, bypassing the aggregator (i.e. retailer) could shift value along the value chain yet again.

    By the time Amazon reaches some point of monopoly in distribution it could be too late to make the switch to profit generation.

    I don't want to suggest that failure is inevitable, but I want to point out that success is not certain by any means. Disruption happens.

    --

    * It's possible that Enlightenment is also an illusion at Apple. Even if they once had it, there are forces which act on companies that make them lose their wisdom.
  6. iTunes Update

    Research · 29 comments

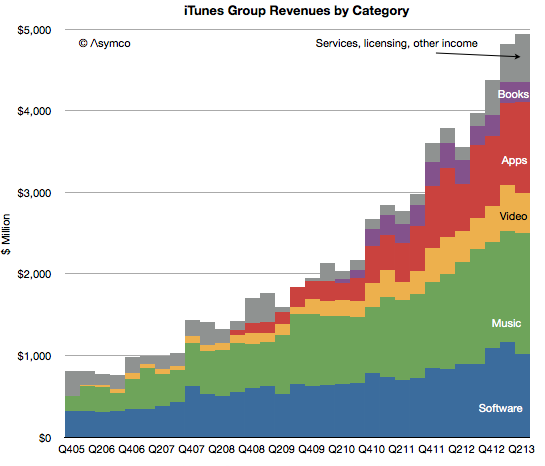
    In the latest quarter the iTunes group top line grew by 25%.

    Additional newly reported items:

    • Quarterly revenues dipped slightly to $4 billion (second highest after $4.1 billion last quarter).
    • iTunes Stores billings (i.e. gross content revenues) were $4.3 billion
    • Reached the best month and best week ever for App Store billings at the end of the quarter.
    • iTunes billings translated to quarterly revenue of $2.4 billion, up 29% from the year ago but flat q/q. Company reports “strong growth in revenue in both content and apps.”
    • New content added includes HBO GO and WatchESPN available on Apple TV. Apple TV catalog now includes over 60,000 movies and over 230,000 TV episodes.
    • Users have downloaded more than 1 billion TV episodes and 390 million movies from iTunes to-date. They are purchasing over 800,000 TV episodes and over 350,000 movies per day.
    • iOS developers have now created more than 900,000 iOS apps including 375,000 apps made for iPad. Apps created grew by 50,000 overall and 25,000 iPad apps.
    • Cumulative app downloads have surpassed 50 billion.
    • App developers are being paid at the rate of $1 billion per quarter.
    • App developers have been paid over $11 billion for their sales through the App Store (half of which was earned in the last four quarters.)
    • There are now over 320 million iCloud accounts
    • There are 240 million Game Center accounts
    • Almost 900 billion iMessages have been sent
    • Over a 125 billion photos have been uploaded and over 8 trillion notifications were sent.

    Some observations and estimates:

    • Music revenue growth remains at around 15% while video revenue growth remains around 25%
    • Apps continue to accelerate with a near doubling of revenues
    • Book revenues are contracting as pricing pressure is being felt
    • The software group grew moderately at 15% as Apple’s apps are reaching saturation within the iOS user base and as Mac sales stagnate.

    As a reminder, you can order the iTunes Business Review from the Asymco Store.


    Screen Shot 2013-08-05 at 8-5-4.21.54 PM
  7. Asymcar 2: Is Tesla Disruptive? Also Segway, Multiair, Winglet, Organ Donors & Regulation

    Podcast · 5 comments

    Podcast 2: Is Tesla Disruptive? Also Segway, Multiair, Winglet, Organ Donors & Regulation Über Alles | Asymcar.

    Horace Dediu and Jim Zellmer discuss the odds of disrupting the present automotive club via Tesla. We further dive into the regulatory and cultural environment that sustains the current players, while reflecting a bit on Segway, Toyota’s Winglet, organ donors and the Fiat “multiair” engine. Finally, we preview a larger discussion on apps in and around the car. [24MB 57 minute mp3]


  8. That Competition Thing

    Research · 62 comments

    Bill, I think the smartphone market has always been competitive. [Only] the names have been changed.

    Tim Cook responding to Bill Shope's question on the competitive landscape, April, 2013.

    Indeed, over the years, the companies considered Apple's primary competitor have been many.

    In years gone by in the phone market there were RIM and Nokia and Palm and HTC. In the iPod era there was Creative and Sony and innumerable others long forgotten (not to mention the tyranny of DRM).

    Even today we struggle to decide whether Apple competes with Google first or Samsung. Or perhaps with the iPad it's with Amazon or  Microsoft. Or maybe iTunes is threatened by Netflix or Spotify. The Mac surely competes with HP and Dell and Toshiba. What about iCloud? Clearly it's Dropbox or Google Drive. iWork? Both Office and Google Docs.

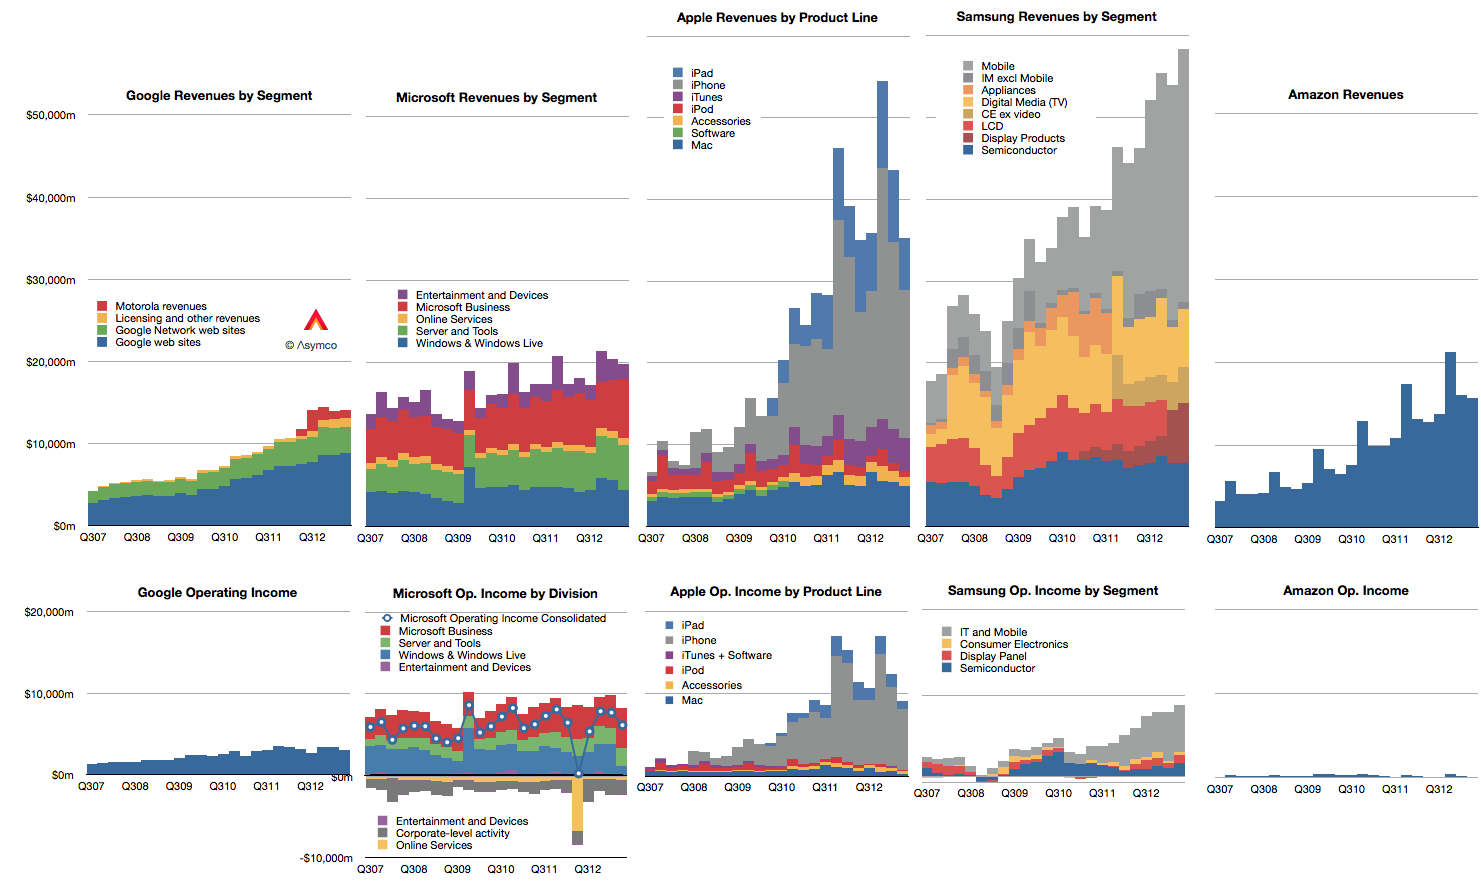
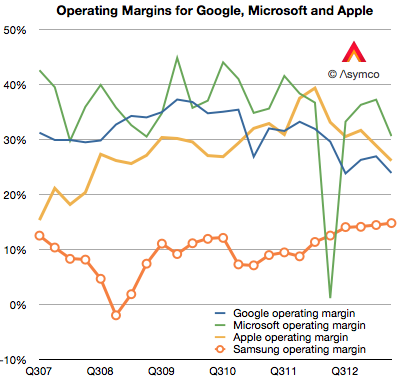
    Doing a competitive analysis for Apple is then mostly a struggle of whom to compare it to. So forgive me that I only track the few challengers shown below.

    Screen Shot 2013-08-13 at 8-13-2.14.59 PM

    Note also that these companies all may compete with Apple to some degree but they may not compete with each other. Competition, it seems, is not transitive.

    There isn't much that I can observe in the data that hasn't already been observed. Google shows steady but not spectacular growth in revenues with decreasing margins. Microsoft shows even more modest growth in revenues with flat earnings. Apple growth is moderating from near vertical while earnings pause. Samsung has great growth but there is a similar set of doubts about its sustainability and finally, Amazon continues to grow the top line by 20% and  has nothing to show for it.

    Operating margins have mostly fallen with the exception of Samsung whose increasing reliance on smartphones has led to a modest increase, though not nearly to the level of the others. (Amazon, lacking in profits, cannot be compared.)

    Screen Shot 2013-07-30 at 7-30-10.54.44 PM


    In summary there is little change to report.

    Except that it's been reported that in the last quarter Samsung managed to "dethrone" Apple from the phone operating profit crown. This is a matter of estimates and for that we need to understand clearly the assumptions.

    I estimate that this is not the case. That indeed Apple remains most profitable phone maker by a wide margin.

    To estimate operating margins you need to estimate gross margin and the allocation of operating expenses (SG&A and R&D) to a particular "division" or product line. The problem is that Apple does not operate as a divisional organization so its marketing and R&D budgets (i.e. people) are not assigned permanently. You have to move them around based on whatever is being worked on at any given time.

    What's more, we need to account for the huge SG&A costs associated with iTunes and Retail. They both consume vast resources which cannot be allocated directly to any product. There are 41,000 people working in retail.  Also, some of the expenses for iTunes are overhead and cannot be considered cost of sales. That's also SG&A. Then there's corp research and design (Mansfield and Ive), which are not allocated to any particular product. When you slice out these costs, there is very little to apply to iPhone, etc.

    So if (and it's a big, sanctimonious if) you want to cast iPhone out as a separate business unit, it would be wildly profitable. There is a huge gross margin of 46% (this assumes a cost per unit of $316) and only another 5% of sales spent on engineering and marketing leaves a 41% operating margin or $7.4 billion. (Why only 5%? Because there's only 10.8% to allocate and after taking out iTunes, Retail you're really only left with 4.49% for SG&A and 3.3% for R&D or 7.79% so 5% is about two thirds of the operating budget).

    If you take all of Samsung's IM division which is PCs, Tablets and phones their operating profit was only $5.6 billion.

    You can see the difference in the grey areas of operating profit in the first graph above.

    Bear in mind that this is still an artificial comparison. The split of profit between product groups is not only an estimate by the analyst, it would be an estimate for Apple itself since it has only one P/L.

  9. The iPhone Stores

    Research · 29 comments

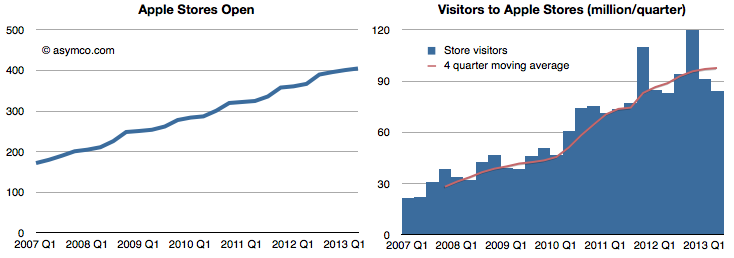
    Here are the latest performance figures for the Apple stores:

    Stores Open and Visitors

    Screen Shot 2013-07-30 at 7-30-2.17.25 PM

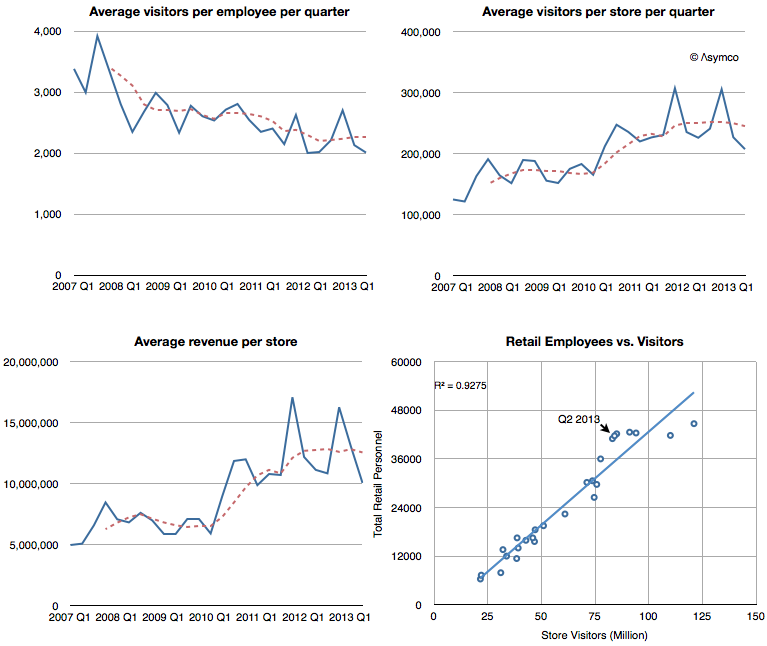
    Visitors per employee,Visitors per store, Revenues per store and Employees correlated with Visitors.

    Screen Shot 2013-07-30 at 7-30-2.15.23 PM

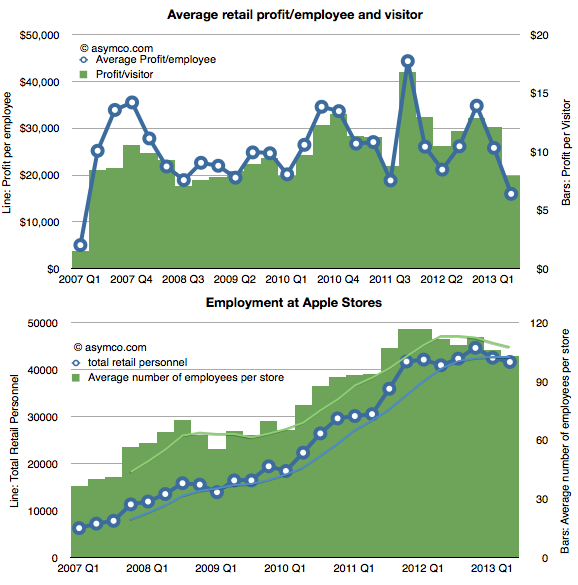
    Employment and Profitability (per Employee and per Visitor)

    Screen Shot 2013-07-30 at 7-30-2.17.48 PM

    The pattern that seems to appear is one of a plateau or peaking of sales, especially when values are seen on a per-store basis. Revenues, employment and visitors per store are all flat or slightly down when seen on a seasonally adjusted basis (trailing four period average).

    Profitability has been more steady over a long period, though more volatile in a short-term window.

    Seen in isolation, Apple Stores would appear to be coming to a point of quiescence.  But they should not be seen in isolation. Apple Stores mainly sell Apple products, so if Apple products slow then retail sales should also slow.

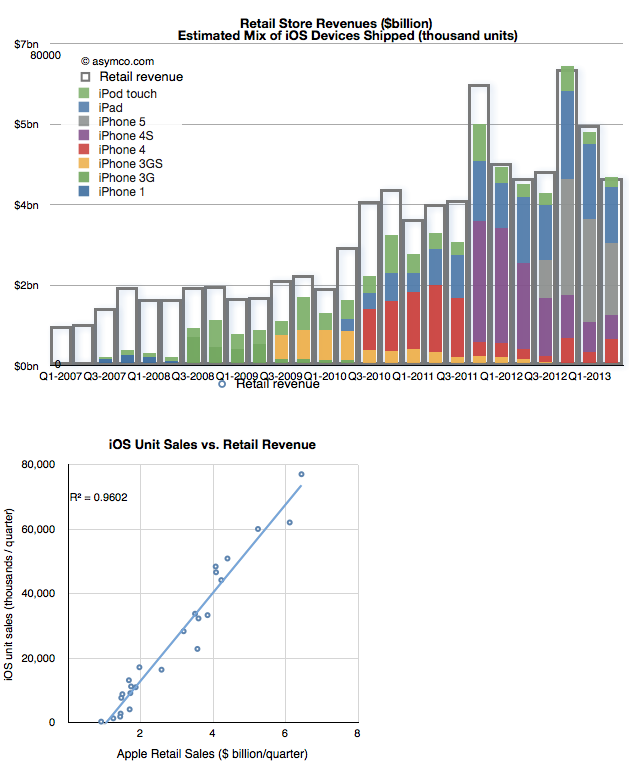
    Indeed, in 2007 Steve Jobs told Fortune that the Apple stores had been built to sell the iPhone and in 2010 Ron Johnson said the Apple stores had been built to sell the iPad. These statements were meant metaphorically but they are literally true when looking at what is actually sold. The following graph shows the relationship between iOS device sales and Retail revenues.

    Screen Shot 2013-07-30 at 7-30-2.17.56 PM

    The first chart shows the relationship plainly enough and the r-squared coefficient of 0.96 puts a finer point on it.

    So at the end of the day, the performance of the Apple stores depends on the performance of Apple's portfolio of products. It stands to reason that as iOS units slow, Apple stores should as well.

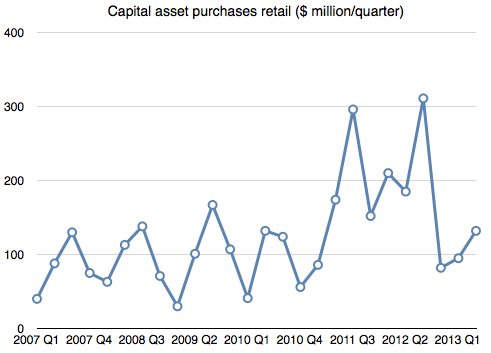
    This is something Apple management should be well aware of. Therefore, if Apple were confident in the future of iOS it would be investing in retail (as it would in other capital projects like manufacturing.)

    And that answer would be here:

    Screen Shot 2013-07-30 at 7-30-2.47.21 PM
  10. Apple's biggest acquisition

    Research · 76 comments

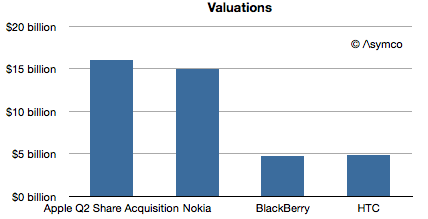
    At the end of the first quarter 2013 there were 946,035,000 fully diluted shares of Apple stock outstanding. At the end of the second quarter there were 924,265,000. The 21,770,000 shares that disappeared were purchased by Apple and retired. Apple shares traded between $390 and $463 during the quarter so it's hard to know exactly how much Apple paid for them, but at an average of $426.5 per share Apple would have spent $9.3 billion

    Management explains:

    In late April we executed a very successful debt offering issuing 17 billion of debt across 3, 5, 10 and 30 year maturities. We paid $2.8 billion in dividends in the quarter and we also utilized a total of $16 billion in cash on share repurchase activity through a combination of a new accelerated share repurchase program and open market purchases. $12 billion of the $16 billion was utilized under a new ASR program initiated with two financial institutions in April.

    An initial delivery of 23.5 million shares was made under this program with the final number of shares delivered in average price per share to be determined at the conclusion of the program, based on the volume weighted average purchase price of Apple’s stock over the program period, which will conclude in fiscal ‘14. In addition to the new ASR, we executed $4 billion of open market share repurchases, resulting in the retirement of 9 million additional shares.

    Later, during Q&A:

    Tavis McCourt - Raymond James: Thanks for taking my question. Peter, first a clarification on the share buyback and can you tell us what the ending basic share count was in the third quarter?

    Peter Oppenheimer: All of that is on the income statement, so you got the ending basic and diluted, but let me give you a couple of points that I think could be helpful for you. During the June quarter, we concluded the first $2 billion ASR program that we started in December and then so we got the final shares in on those, and we did our second ASR program of $12 billion, that started at the end of April and we received 23.5 million shares initially on that. And I went through in my prepared remarks, at some point during fiscal ‘14 that program will close and we will get the final number of shares. We also bought back $4 billion of stock in the open market during the June quarter and received about 9 million shares. So, the impact of those in the June quarter lowered our diluted share count in the quarter by about 22.9 million shares. And as you look forward into the September quarter before any further buybacks or any issuance to employees we would expect to see an additional approximate 11 million share benefit from the things that occurred during the June quarter.

    This is a bit convoluted, but it seems that Apple has committed to buy $16 billion worth of its shares but has not completed the retirements. They see an additional 11 million shares being retired from activities conducted in the June quarter. (Nota bene: when calculating future EPS, take these shares out of consideration.)

    If we add the 11 million yet-to-be-retired to the 21.7 million already retired and assume $16 billion was paid for them then the average price paid was $488.25.

    Not a bad price. Share re-purchases are valuable only if the price paid is low (a determination that is usually beyond the scope of management to make.)

    But what is even more interesting is that if we consider the $16 billion expenditure as an acquisition, then Apple has made what amounts to its biggest. It's more than some familiar companies are worth:

    Screen Shot 2013-07-25 at 7-25-11.38.09 AM
  11. Apple’s 3Q FY13 Review (Padcast)

    Research · 16 comments

    Preview 3Q-13 screenshot

    Using interactive graphics and narration, this latest Apple Earnings Review discusses Apple's performance in relation of its historic performance as well as to expectations (published in the Preview) on the following topics:

    1. Guidance vs Actual performance: Now that Apple changed the way it provides guidance, are we seeing a new degree of precision in their signaling. We look at the history of earnings guidance and how effective (or not) the current method is in helping predict performance.
    2. Gross and Operating Margins analysis: What is the pattern of margins and how important are margins to the perception of competitiveness?
    3. Margins by product. How are margins allocated by product?
    4. Average selling prices for each product. Any surprises in Pricing? What was the magnitude, cause and significance of iPhone ASP drop.
    5. iOS product shipments. Comparison with expectations, trends and explanations. Overall iOS growth story.
    6. Cash balance and the effect on cash of share re-purchase.
    7. Sales growth and Earnings growth, a long term retrospective.

    Duration is about 1hr.

    As a reminder, the Padcast can be reviewed interactively users can access to the underlying data.

    It's available for download on the iPad for $19.99. Those who already bought the Preview will be receiving an updated version soon that includes the Review at no extra charge.