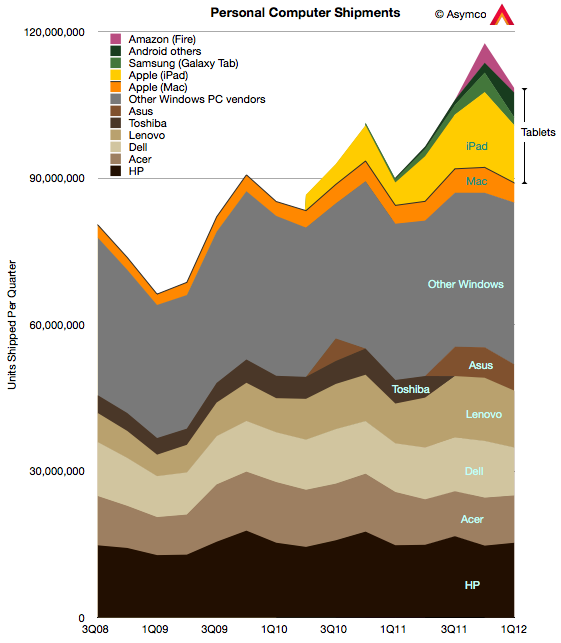
In terms of units Windows-based computers made up 78% of all PCs sold in Q1. That was an increase from the 74% in the previous quarter but a decline from 90% a year ago. OS X based computers were about 3.7%, a decline in share both q/q and y/y, something the company attributed to a transition quarter.
The following chart shows the composition of vendor volumes with tablet and traditional form factor computers included:
iOS computers (i.e iPad) were 11% of the market, declining from 13% last quarter but increasing from Q1 '11's 4.2% share. Apple reported that the iPad was not at supply/demand balance and thus could have sold more units.
Amazon's shipments went down significantly though sell-through was perhaps twice sell-in due to inventory build-up during the previous quarter. Overall, about 5 million Amazon Fire tablets were sold since the product's launch.
The third significant tablet vendor was Samsung, which sold about 1.6 million tablets, down sequentially but up y/y. Other Android tablets may have shipped another 5 million units.
Overall, Apple remained the top vendor with 14.6% share, followed by HP with 14.1% and Lenovo in third at 10.7%. Dell just barely managed to beat Acer with 9% vs. 8.9%.
The impact of the tablet (aka iPad) market is being described in the response to a significant earnings miss by Dell:
Sterne Agee, which admits it probably shouldn't have upgraded DELL from underperform last week, says it's notable that the PC maker acknowledged competition from Apple and Google for the first time as part of Tuesday's dour F1Q report and forecast. Meanwhile, Mizuho calls DELL a "show-me-story for now" in cutting it to neutral and cutting its price target 25% to $15. And ISI snarks "everything is bigger in Texas--including the misses." It adds while the company "is making the right business-model changes...results will remain 'chained' for years (not quarters) to commodity desktops/notebooks, which comprise over half of sales."
- Dow Jones Newswires (Kevin Kingsbury)
And so, two years later, the impact of the iPad is becoming abundantly clear, even to the incumbents. The resistance and denial was profound. Even on this blog, the agitation and anxiety when the subject of the iPad as disruptor came up was palpable.
Perhaps that is the greatest testament to the disruptive potential of a product.
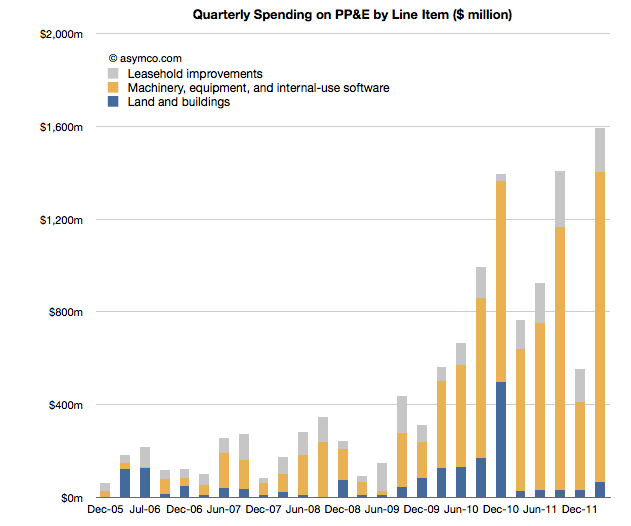
During my talk at the first Apple Investor Conference in January I said that I would pay very close attention to the Machinery, equipment and internal use software line item from its PP&E during the next quarterly report (it appears on Page 13 in the latest report).
The reason I consider this important is because capital spending has provided reliable foreshadowing of iOS device production. This is itself because Apple invests in the equipment used in the manufacturing processes for its devices. The more spending on equipment, the more production capacity is brought to bear and the more units are produced. Since iOS devices tend to be supply constrained, the more units are produced then the more are sold.
The first quarter of the fiscal year saw a very small increase in CapEx which caused me to "backload" spending later in the year. By watching this spending, we can assess approximately when and for which products is investment allocated. If the spending happens early then we can anticipate an early update to the iPhone. If it happens late then we can anticipate a late release. So has the ramp-up begun as of the second quarter (first calendar quarter)?
The following chart begins to give us the answer. It tells the story of spending by tracking the change in asset values:
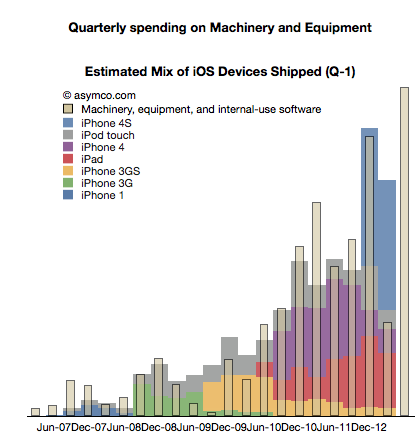
Stripping out the Machinery and Equipment portion (in yellow above) and overlaying the following quarter's iOS shipments yield the following composite graph:
It would appear that there is significant acceleration into the second quarter. Is it something significant?
The increase in M&E is the highest for any quarter to date. Some of that is undoubtedly in service of the new iPad but some must also be the initial ramp-up for the new iPhone.
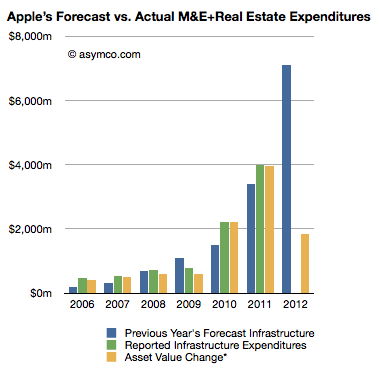
To gauge it further however, we need to look at overall expectations. The company also signals future production plans though its yearly report. As I concluded from October's 10K, fiscal 2012 production should double from the year before (as it did from the year before that and the year before that, etc.)
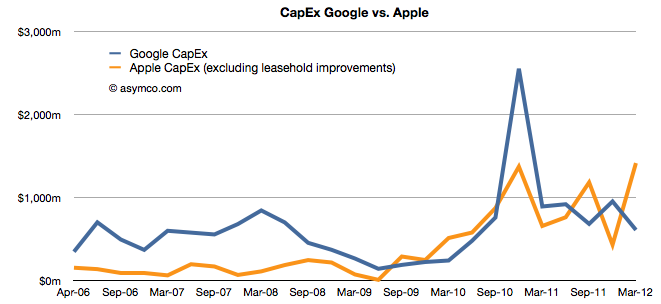
At $1.3 billion, the spending is substantial and a new record, but it does not make a big dent in the overall budget for the fiscal year. Half-way through the year, the total spending on M&E and Real Estate is still only 26% of the budgeted $7.1 billion. You can see the gap in the following chart. The yellow line needs to match or exceed the blue line after the next two quarters.
In order to reach its own expectations, the spending therefore needs to double from the current rate to at least $2.5 billion/quarter over the next two quarters.
Such numbers are hard to grasp. They are unprecedented not only for Apple but for almost any comparable company. Just as a reference point, they will have to exceed the historic average CapEx rate for Google by more than 100%.
Regular readers will note that there is nothing new in this analysis. This is only an update in a continuing story. The pieces are in place for continuing the existing rate of growth.
My thanks to Bruno Ferrari of Exame magazine Brazil for asking the following questions. My answers were written two weeks ago on April 2nd.
Based on financial data of the first fiscal quarter, it is possible to confirm that 2012 will be the best year in Apple's history?
Actually, it's possible to confirm without looking at first quarter data. Every business line Apple has except the iPod is growing and is likely to keep growing during this year. That means that sales will increase over 2011, which was Apple's biggest year. You can see historic sales growth data here:
What are your predictions for the second fiscal quarter?
The iPhone number seems to be higher than consensus. It's aggressive but I'm basing my opinion on the launch of the iPhone 4S in China and the Chinese New Year and new carrier agreement there. Also the iPad will do quite well.
Do you think Apple will hold the iPhone 5 launch to September in order to open 2013 with an extraordinary result?
The next iPhone will launch between June and September. It might be earlier due to the 4S being the "wide end of the egg". Think of the iPhone as an egg rolling down the hill. There is a sharp end and a wide end and the speed of rolling depends on which end is down.
Besides the iPhone 5, which products that Apple could announce in 2012 you think may help them to maintain this extraordinary growth?
I think the iPhone is becoming more predictable. What I'm more curious about is what they will do with the iPod. Apple takes its brands seriously. I am watching the iMac, MacBook and iPod for clues of a re-fresh or replacement as they have aged.
Do you think we will see the “iTv”? Do you think it could be “the next iPad” of technology market?
Apple TV is in waiting mode. It's like an airplane circling, waiting to land. Something will happen but not sure when. Fundamentally, the opportunities are still there but the entertainment industry is very complex. The more complicated it is the more necessary for an entrant is to create a parallel version of it. That takes time.
The building blocks are all there however. See additional thoughts here.
If we analyze the growth of Apple in recent years, it is supported by the launch of new products, especially the iPhone and the iPad. Do you think Apple can lower your rate of growth in coming years since we don’t see in its roadmap new innovative products like a new smartphone or a new iPad?
New products created new growth but iterations of those products also created and will continue to create growth. Of all of Apple's products only one product is not growing today, the iPod. And that is after 10 years in the market and with a "dominant" market share. In addition, Apple has a lot of room to expand internationally and into enterprise and professional sectors.
I do agree that 100% growth is hard to maintain without new products. I believe there might be a few products still waiting for launch. TV is one area (along with game-based entertainment). New user interfaces might be enabling new categories of products. Intelligent assistance and companionship are open problems that software can solve but which have not been productized.
When do you think we’ll stop to see Job’s legacy in Apple new products. And what then?
Jobs' legacy is not in specific products but in how products are built. He also taught the importance of putting products first and markets second (this is, at its base, an artistic principle, not a commercial one). I think that legacy can last forever, if managed properly.
How do you analyze the dividends pay and the buyback made this month?
I wrote some thoughts about it here. I believe the impact will be mostly psychological for investors.
And finally, I was reading at Asymco some analysis of Apple’s share price. Do you think $600 is enough? Do you think in a 1 trillion dollars company in 2014 as some analysts are saying?
The share price depends on the psychology of people. I like to say that Apple is the same exact company today as the one that was priced at $78/share three years ago. When I look out the window of my office I see the same view year-to-year. When I look on my computer screen at Apple's financials I also see the same view year-to-year. I don't know how people can see Apple differently one year to the next. To me it's like looking out the window and seeing mountains instead of the sea.
But this is how markets behave. I can't say what the price will be. It may be $1000 or it may be zero. But the company will not change in either case. It won't change because it does not need to change.
Chris Brennan asked a few important questions regarding potential saturation of the iPhone market.
Is the iPhone anywhere near saturation? Can Apple continue to shift iPhones in ever increasing numbers or is a sales plateau realistically on the horizon?
The market for mobile phones is approximately 5.5 billion connections, perhaps 5 billion users. The iPhone has approximately 300 million installed base. I consider a base of 1 billion users to be a minimum for continuing participation in this market long term. Licensed platforms will reach this in no more than two years. I don't know what Apple's ambitions are but if they don't triple their base I don't see a strong future for the company in mobile phones. In order to triple the base the company will need to sell substantially more than an additional 700 million iPhones. The retirement rate can be as high as 50% of installed base. Apple will need to sell at least 1 billion iPhones in the next few years. Seen another way, Apple has a market share of about 9% on a quarterly basis. This needs a lot of improvement. Chinese vendors are not standing still.
Can the Mac also continue to outperform the rest of the PC market for long?
The PC market is in decline. It will continue to decline as its disruption continues. The PC market will still exist 10 years from now but, similar to the mainframe market, it will be hard to notice. Apple is doing a fine job carving out a large portion of that market for itself but overall it's an increasing portion of a decreasing pie. It would be better to track the share of profits captured or even share of value rather than units. The reason units were important 20 years ago was because platform dynamics determined whether a marginal platform could survive. Would a 5% share be enough to attract developers? That is no longer an interesting discussion. Applications for PCs are not an area of investment for any significant pool of capital. Development has moved almost entirely into mobile or web. Therefore, as the PC is now a commodity product, the best performers are those who can capture a larger margin. Those margins should be subsequently be invested in new platforms. PC vendors who neither capture margin, nor invest in new platforms are strategically insolvent.
Finally, this exponential growth of Apple products has to end some time soon doesn't it? How many high-income buyers for expensive products can there be left for Apple to target?
Trying to calculate the limits to growth is futile. There are limits but they are not calculable and inaccurate estimates don't offer any useful information.
In 1939 a total of 921 military aircraft were built in the United States. Five years later, in 1944, annual production was 96,318. A question could have been asked by an aviation analyst in 1939 about whether the American aircraft industry could grow. Aircraft, especially multi-engined ones used by the military were _extremely_ expensive. The reason an industry grew exponentially making extraordinarily expensive products was not because of organic demand but because the primary buyers engaged in a cataclysmic global war. In other words, there was a will to buy and hence there came a way to build. Therefore the answer to the question of sustainable growth comes not from an analysis of demand but from an analysis of the consequences of not growing. Not growing would have meant the end of many nation states.
Your question was framed by an implied market categorization: that buyers are either high-income or, presumably, low-income. This is a false dichotomy. Buyers are either needful of a job to be done or not. If the job is important enough, money will be found to hire a product. Sellers of products will also find ways to meet the demand through lower prices and increased capacity. Every product Apple makes used to be out of the reach of all consumers. Whether computers (portable or not), music players and professional grade software, voice recognizing personal assistant cellular phones and tablets are all luxuries or necessities is only a question of timing.
Kenney Ho, a staff reporter from Korean newspaper The Chosunilbo (The Chosun Daily) sent me a set of delightful questions.
According to Kenney, The Chosunilbo "has a history of 90 years, has been the most dominant, and influential paper of all time in Korea. It is the No.1 newspaper company in Korea with more than 1.8 million circulation, firmly holding the largest market possession. The paper is recognized Asianwide, where there are many readers in Japan and China."
-You said "All mobile device vendors experiencing losses are not likely to really recover". Even though, it wouldn't mean that the employees, executives of Nokia has completely nothing in hands for recovery. If you are the CEO of Nokia right now, What are your steps to make Nokia recover its deficits?
My statement was based on the historic data which shows that 14 phone vendors have either exited the business or lost their independence during the last decade. No vendor that has reached a period of prolonged loss making has recovered. These are just observations and it's possible that Nokia may be the first to recover. However, going by the patterns of the past, it would be very unlikely. When I thought about the reasons why companies have not been able to recover I came to the second observation about the way phones are sold. Once a brand reaches a point where it's considered "risky" for distributors and operators to range they tend to defer purchases which leads to a spiral of continuing losses and more damage to the brand. The market amplifies "distress" and recovery becomes impossible.
If I were the CEO of Nokia I would set course for turning the company into a new business. I would approach the market asymmetrically and not try to compete directly with the other vendors. I would look toward services, platforms and software solutions and de-emphasize hardware.
-Many experts say that because Nokia dominated phone making industry in the 2000s, they maintained a corporate culture of complacency, which led them to decline. Do you agree with this? If you agree, Can you point out the examples of Nokia's complacency?
Complacency would mean that Nokia would not invest or try new things. This is not quite right. The company invested in software, services and platforms. It tried many new things and had a large R&D budget. It was the leader in mobile software for many years. There was, however, a culture of arrogance about their position. This meant that they did not think the basis of competition would change. They thought they were too big to fail. They did not challenge the core business model of hardware-first and try to find an internal disruptive business.
-Experts note that Nokia should have reacted directly to Apple's iPhone appearance at 2007. What should have Nokia have done at that time?
The iPhone showed that software and experiences matter more than operator relationships. Nokia did a lot of research on user experiences and software but when the decision came to implement the ideas, the constraints of hardware and logistics and operator preferences took precedence and the software was compromised. What Nokia needed to do is build product around software not software around the hardware and the market.
-Since Apple's iPhone appeared in 2007, Samsung took a Fast-follower tactics which made them successful, which Nokia could not. Do you think Fast-follower have advantage over first-mover?
I don't consider first-mover or fast-follower to be accurate descriptions of strategy. Success follows from innovation and only from innovation. There are various forms of innovation: there is new market creation, new business models, low cost or distribution innovation. Nokia tended to create low cost innovations which opened new, low-end markets. Apple created a new market for browser-based devices and for app-based experiences. These were enabled by an ecosystem that benefited from integration.
Samsung implemented a portfolio strategy with a large number of devices and price points which allowed them to find market niches that could be exploited. This was a distribution innovation. Each strategy has advantages and disadvantages and each strategy is usually linked to company core priorities and processes. There are times during a technology cycle when one strategy is better and another is worse. This is why companies find themselves successful and then fail. Their processes don't match the technology adoption cycle.
For example, in the PC market there is little potential for new experiences tied to an integrated device (except for tablets) and hence there is little growth opportunity for an Apple-like approach. The innovation that matters in the PC market is mostly cost reduction. Nokia was doing cost reduction at a time when voice products were commoditizing. Cost reduction does not work when the basis of competition is new experiences and new business models. As smartphone hardware commoditizes, it's unlikely that Samsung will have an advantage unless is goes to a low-cost approach and enters into direct competition with low-end devices.
-Can you predict the 'Big 5' in handset industry 10years from now? Many people think the list will include Apple, Samsung. Who else might be on the lists?
There is no guarantee that Apple or Samsung will be the top vendors 10 years from now. I expect Chinese brands to become dominant in market volumes. I expect online service companies like Amazon, Baidu, Facebook to create new platforms which and have their own devices, perhaps in large volumes. I expect new input methods (like voice) to create new opportunities and perhaps new platforms and ecosystems. I expect Google may make a lot of money. One thing is for sure, being a hardware-oriented company without software and services and platforms and ecosystems is a sure path to becoming disrupted.
-Nokia was the leading company in Finland. What are the reactions of Finland towards Nokia's downfall?
People tend to blame each other for failures and this is the main discussion topic in Finland: who's to blame. The failure of a company is rooted in complex decision processes which usually take years to run their course. It's quite futile to lay blame on persons, especially since the same persons were celebrated for their wisdom at another point of time. At the same time as Nokia is failing however, another Finnish startup is celebrated world-wide and about to go public: Rovio, the maker of Angry Birds. It will be bigger than Nokia. Finland should make sure there are more Rovios to come.
In the iPhone cost structure analysis I showed how revenues and costs for iPhone are probably allocated. The revenue per iPhone was shown to include $29 for revenue items "above" the price of the phone to the channel. This total includes Apple's own iPhone accessory sales plus revenue from licensing the "Made for iPhone" trademark to third party accessory makers. Apple also receives some revenues from cloud services. But, pertinent to our recent discussions on the Android business model, Apple also receives revenues from Google.
Wouldn't it be nice to know how much? Here's a way we can estimate it.
I've read an estimate that 50% to 60% of ad revenues from Google search initiated via iOS are paid to Apple. This is believable because the TAC for Google overall is about 40% and Apple probably drove a hard bargain to get a premium for its, presumably, premium traffic.
So if we knew the revenue run rate for Android search on a per device basis we could perhaps guess how much of each phone's revenue comes from Google. What we've heard last year in Congressional testimony is that two thirds of its mobile revenues come from iOS devices. This would imply that the run rate for iOS would be 2x the run rate for Android.
Having a model of Android revenues helps at this point. Assuming Google obtains $4.4 from Android (excluding AdMob and App sales) and assuming negligible other mobile revenues from other platforms gives a possible Google revenue per iOS device per year of nearly $9.
Taking the lower bound of the revenue share estimate above means that half of Google's revenue goes to Apple or $4.4/iOS device/year or $9 over the two year life of the device.
That would put revenue from Google at about 1.4% of iPhone revenues (see average revenue per iPhone here). And that revenue comes without any costs and so flows straight to the bottom line. That, in turn, would imply that 3% of Apple's operating margin is provided by Google. Not a bad deal considering that some phone vendors can't get that for their entire product line.
The interesting factors at work here are that this contribution by Google to Apple is higher than the contribution by Android to Google. In yesterday's post, I calculated that in 2011 Android contributed about $590 million to Google's operating margin (5% of total).
If we consider that Google pays Apple $9[1] for every iOS device and since Apple sold 156 million iOS devices in 2011 then Apple received $1.4 billion from Google, all of which went to the bottom line.
$1.4 billion from Google to Apple vs. $600 million from Android to Google. Three percent contribution of Google to iPhone profits vs. 5% contribution of Android to Google's profits.
This sets up all kinds of game theorizing which will undoubtedly entertain and enrich us all.
---
Notes:
Perhaps this $9 value is not valid for all devices. Perhaps iPod touch does not get a lot of traffic and is less valuable. Perhaps iPads get more traffic and are worth more. On average, this may be plausible.
Horace and Dan wade into Android Economics expanding on the series of posts on Asymco. We also give an update on The Critical Path Kickstarter project.
Yesterday I presented the estimated Android income statement vis-à-vis Apple's income statement. In this post I'll compare Android as a part of Google's overall business.
Recall that Google has already been compared in terms of overall revenue, growth and profitability to Apple and Microsoft here. The argument can be made that mobility has not yet had a measurable impact on Google (certainly not noteworthy enough to be reported by management).
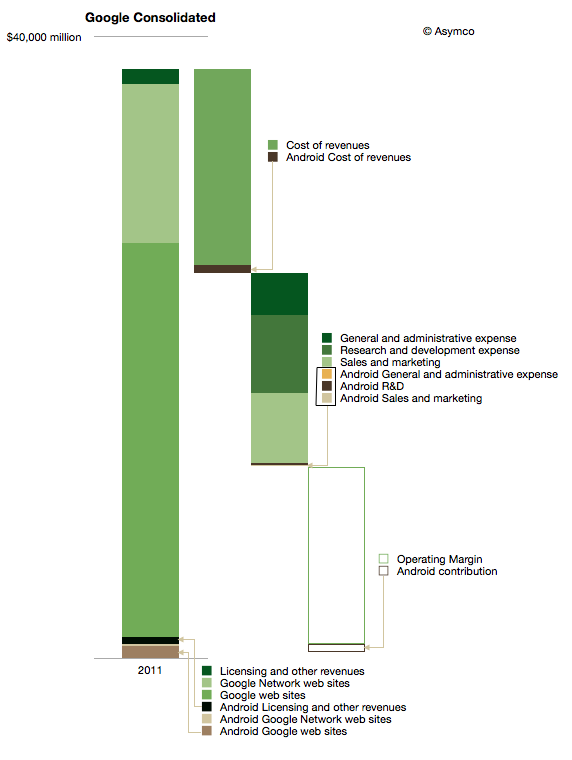
The impact on Google of Android can be shown in the following diagram:
I used color coding to identify non-Android (Green) and Android (Brown) segments of the business. Overall, Android could amount to about 3.5% of total Google revenues and about 5% of operating earnings.
It's important to note that this is not all the revenue that Google obtains from mobility. This diagram represents Android only and there are revenues also coming from alternative platforms and operator deals.
iOS contributes between 3 and 5 times more ad revenue to Google than Android.[1] The contribution to earnings is even more difficult to assess. We don't know the terms between Google and Apple for search revenue sharing and placement. One analyst suggests that the cost of sales (TAC) for mobile Safari search could be as high as 60%, far above what Android traffic costs.
The other observation is that Android cost structure is quite small (see third bar from the left above.) My estimate is that Android R&D is only about 3% of total Google R&D. I'm projecting $200 million for 2012. That implies between 700 and 900 headcount. It's interesting to compare that total to the 20,000 or more that came with the Motorola acquisition.
Having these estimates allows one to calculate many ratios and potential valuations. I'll refrain from putting a value on Android using multiples or sales or earnings, but would come out well below what was paid for Motorola's $12.5 billion.
Which again compels one to ask what is the strategy at work here.
---
Notes:
There are various reports of the ratio including congressional testimony and reports to courts. BlackBerry, Docomo and KDDI were listed as significant other sources of ad revenue by Google in 2010.
One week into this project and the response has been phenomenal. We are at nearly 500% funded. There are 414 backers so far and the average pledge is nearly $34. This means that the vast majority of people (328 so far) opted for the $35 pledge. Many pledged even more than $35.
Perhaps it's only symbolic but the interest in the hard copy version was something I did not expect. It's gratifying that people would prefer to have a physical representation of the work. It also means that I have to think carefully about the production of a good quality paper book.
The abundance of support allows me to invest in design, editing and perhaps illustration as well as the text. I will also have to do a lot of signing.
Thanks again to all who have contributed. I'm completely humbled by the level of support and can only promise to keep doing that which has been so resolutely defended by you all.
Data is useful only when put in perspective. Yesterday's post on the Android Income Statement showed how sales and revenues are captured and how costs are paid for that revenue. The data was shown for the entire calendar year 2011 and the maximum value in the vertical axis was $1.5 billion.
Google has also reported that their revenue "run rate" is now in excess of $2.5 billion so there is significant growth, as would be expected from an exponentially increasing user base.
However, it's important to place this growth in perspective, both in absolute and in relative terms.
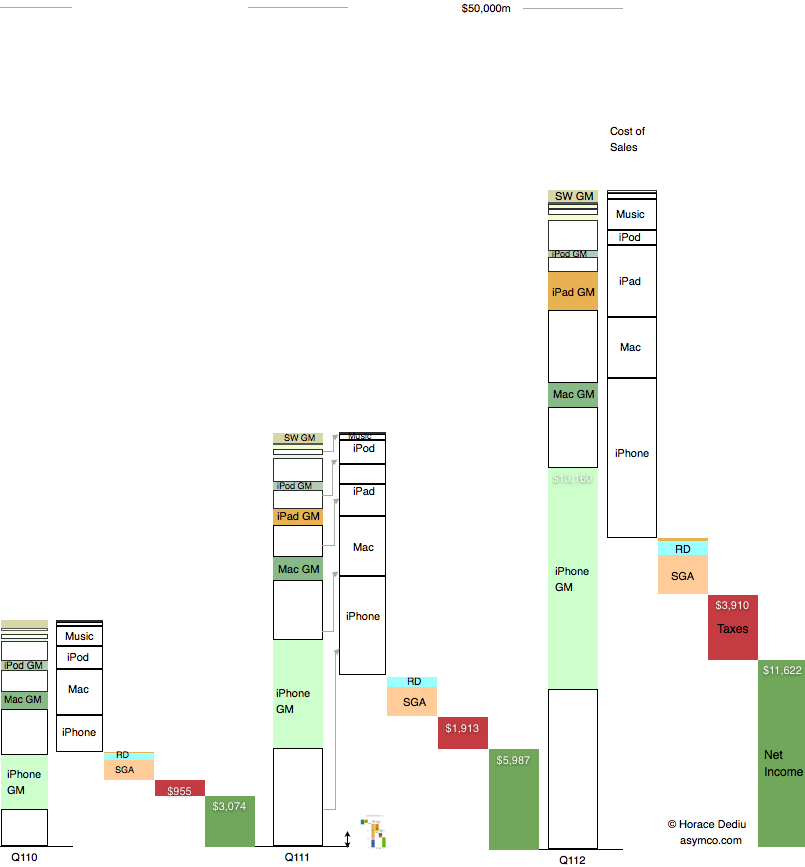
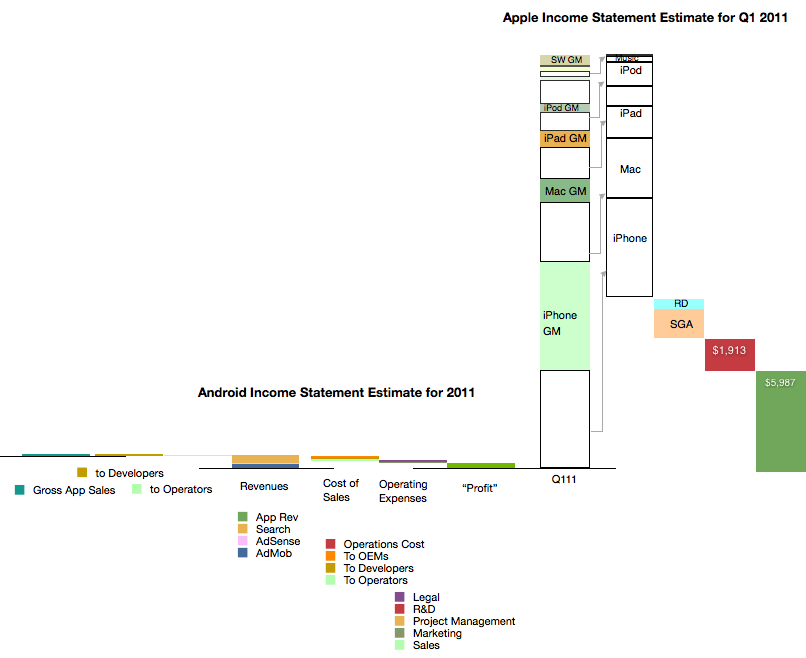
Below is a diagram showing Apple's revenues for the first calendar quarters of 2010, 2011 and 2012. Each product group (iPhone, Mac, iPad and iPod) is shown separately with estimated gross margins (GM). Operational costs, taxes and net income are also shown.
Consistent with previous versions of this data are the color schemes where white areas represent costs of goods sold.
I also placed a scaled version of the Android Income statement next to the first quarter 2011 revenue bar for Apple. The scale is maintained where $1 billion is represented by the double-ended arrow line.[1]
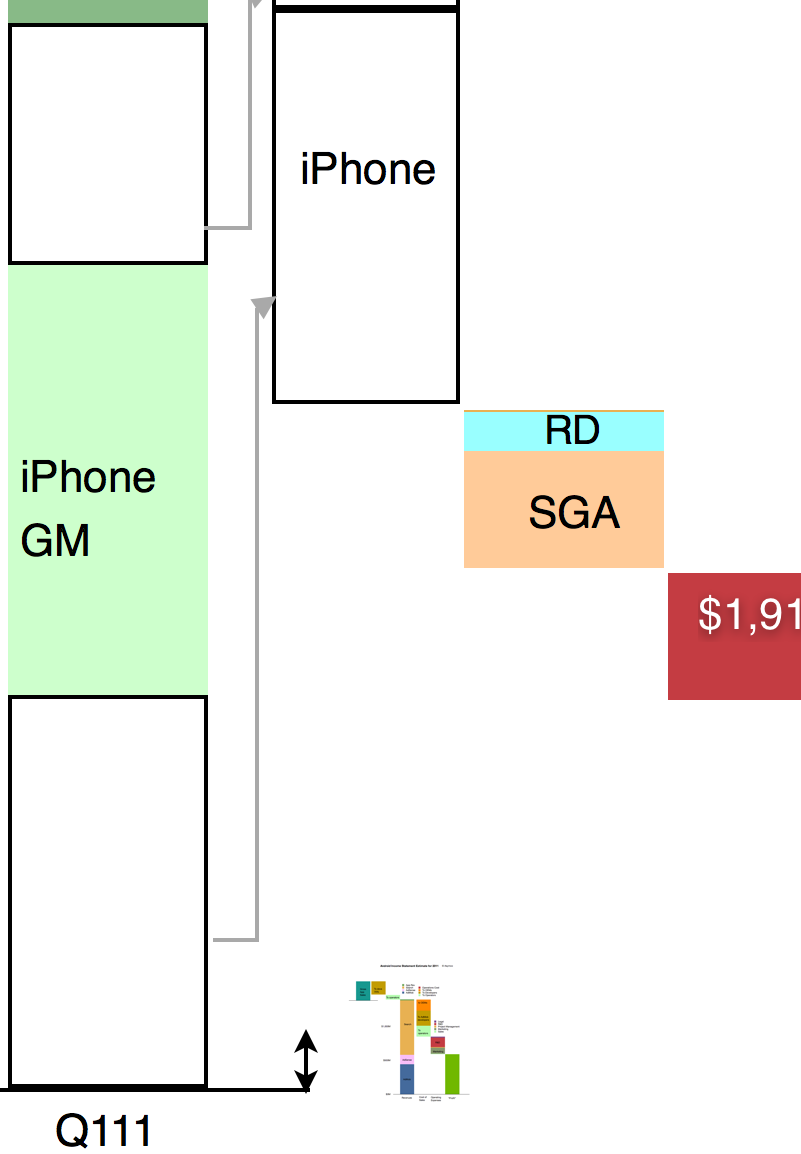
It might be hard to see the Android section of the chart so I expanded it below at 400% the original:
It is still difficult to resolve the data at this resolution but the picture should become clear nevertheless. Keep in mind that the iPhone data is for one quarter while the Android data is for one year. Comparing revenue "run rates", on a yearly basis Android is 2.5% of iPhone or 1.6% of iOS.
As various members of the Android ecosystem are rewarded from the 40% revenue share of Android, it would be important to consider the scales involved in these illustrations when considering the influence Google exerts. It could be argued that Google's spreading of wealth from search creates strong incentives for participation in its ecosystem.
However, there is little wealth created. 40% of a little is a lot less.
---
Note:
The scaling of the image in both X and Y dimensions can be deceptive. I provide the following view where only the vertical dimension (value) is reduced for Android
This is a continuation of the "Android Economics" series of posts. It deals with how revenues and costs are categorized for Android.
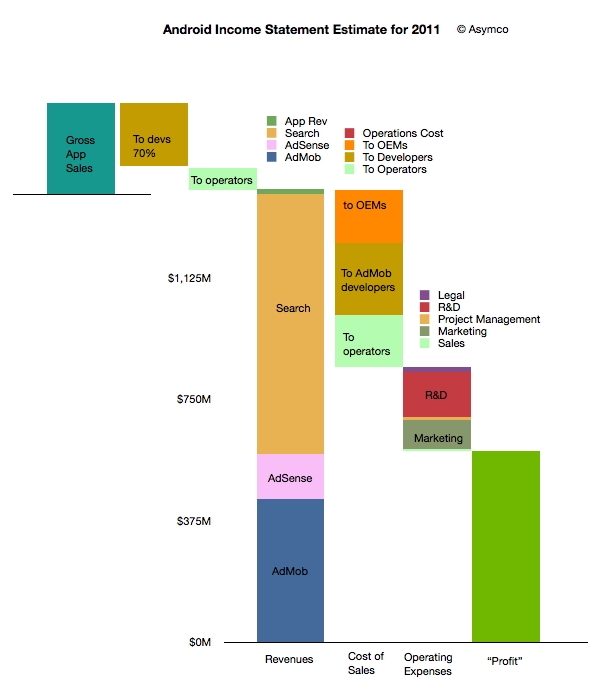
The following diagram shows an approximate representation of what Android's "Income Statement"[1] would look like.
I'll discuss the assumptions that are built into the model as I go along. I'll begin at the upper left and move toward the lower right in the discussion.
The first thing to note is that sales from Google's (formerly known as Android Marketplace) Play are not registered as revenues. This is because Google, like Apple, treats itself as an agent. Agency means that the revenues don't "belong" to the agent but get passed on through to the primary beneficiaries. In the case of Play, Google passes 70% to developers (or content owners) and then distributes on average 25% to network operators (or carriers).
I emphasize on average because there are many cases where Play transactions are not handled by or don't pass through operator billing systems. In those cases where operators are involved, it's possible that they capture more than 25%. It's not uncommon for operator billing to capture 45% of a transaction's value. The reason for this is that there is significant collection risk on billing--far more risk than on credit cards. It would also imply that on some transactions Google may be paying out more than it receives.
This means that on average about 5% of Play content sales to be booked as revenues for Android.
This 5% ends up a quite a small amount if overall app sales are small. We don't know the exact amount but anecdotal evidence from developers seems to indicate that they receive far more revenues from ad sales than from direct app income. Hence the size of the Android app sales is overall, modest. My estimate is that in 2011 there were about $330 million in gross app sales through the Android market. (Google estimated its sales to be 76 million for 2010 half way through that year.)
The bulk of revenues are therefore from other sources: Search, AdSense and AdMob. I'm modeling that overall revenues are based on a "revenue per device in use" multiplied by the number of devices in use. Google has publicly stated that they are targeting $10/device/yr. in revenues. This is probably ambitious as the amount was nearly that much in early 2010 but the number of devices bought by emerging market consumers exploded. As they are not actively targeted by Google's primary customers (especially in China), the average revenue per phone is likely to be much lower. I estimated $6.5 on average for 2011.
However, even if we use $6.5 per phone per year, the total revenues are quite strong since there were likely more than 215 million users at year end[2]. That results in a total revenue base of $1.4 billion for 2011. Removing the app revenues results in about $1.38 billion from Search and AdSense and AdMob.
How to allocate revenues to these three businesses is mostly guesswork. I used a split of about one third to AdMob, 10% to AdSense and the rest to Search. If we assume this split then the next step is to consider how to allocate costs to these sources of revenue.
As discussed in the introduction to this series, the primary costs of sales for Search and AdSense are network operators and OEMs or phone vendors. They are the primary "channel" which ensure the flow of search terms to Google. As Google also explains, the channel receives revenue share--so-called traffic acquisition costs (TAC).
I used an overall allocation of 39% for TAC. Crucially, this includes the payments to developers for AdMob traffic. The rule of thumb I used was:
Network operators get 20% of Search
Developers get 50% of AdMob
OEMs get the rest (of the TAC)
The resulting split is shown in the column above with the "Cost of Sales" at the bottom. There are also additional operations costs which are negligible.
After this 39% TAC (revenue sharing), Google needs to pay its operating expenses. This includes R&D, Marketing, Sales and Legal costs for the Android division (including AdMob). You can see the approximate values in the column labeled "Operating Expenses". This operating cost amounts to about 27% of sales, with R&D at 14% and Marketing at 9%. These rather high fixed costs make sense as there is a significant development work underway for Android.
Finally, after these costs are allocated, the remainder is the contribution of the division. This comes to about 34% of revenues which is called the operating margin. Google has to attach depreciation from data centers and other costs as well as taxes before placing this into earnings.
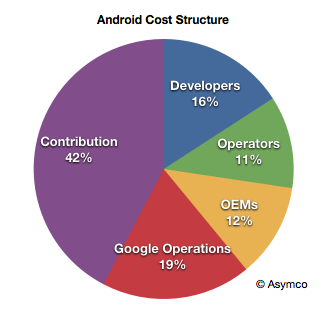
Considering the agency structure, the overall cost structure of Android looks like this:
When playing with the assumptions, it becomes clear that the model is most sensitive to the revenue per device and total devices in use. The profitability is entirely dependent on those figures as variable costs are a percent of sales and fixed costs are limited by talent constraints.
For example, if revenues per device drop to $4.5/yr then the operating margin drops to 38%.
Now we can calculate some of the more interesting figures. For example:
Android OEMs receive $0.76 on average per device per year
Android Operators receive $1.07 on average per device per year (including Play)
Android Developers, as a group, receive $1.94 per device per year (including Play and AdMob)
Google receives a contribution of $2.75 per device per year from Android
Again, these figures are very sensitive to the revenue per device (currently assumed to be $6.5).
Because of the number of devices involved, these cash flows are an important part of the value network of mobile computing. The next step will be to assess how they affect the incentives, alignments and competitive stance of various platforms vying for a seat at the table of the future of information.
--
Notes:
An income statement shows the sources of revenues and the costs associated with those revenues. It also shows the fixed costs (or costs which are independent of revenues so they don't go up or down if revenues change). Finally it shows the operating income which is called contribution if it's a division within a company. This contribution is still subject to taxes and depreciation before it's recorded as earnings.
I'm using Android installed base estimated based on daily activation rates as published by Google. I've discussed these estimates here. I'm using year-end estimates but subtracting retirements based on a two year device life.