I extend a heartfelt thank you to all 831 backers of my first Kickstarter financed book project. Thanks to you not only will there be a way to refer to and cite the podcasts but, since the project reached 980% of its target, the project allows me to explore new means of publishing and content production.
Clay Christensen said that a disruptor should be patient for growth but hungry for profit. The Asymco experiment is continuing and is staying true to this principle.
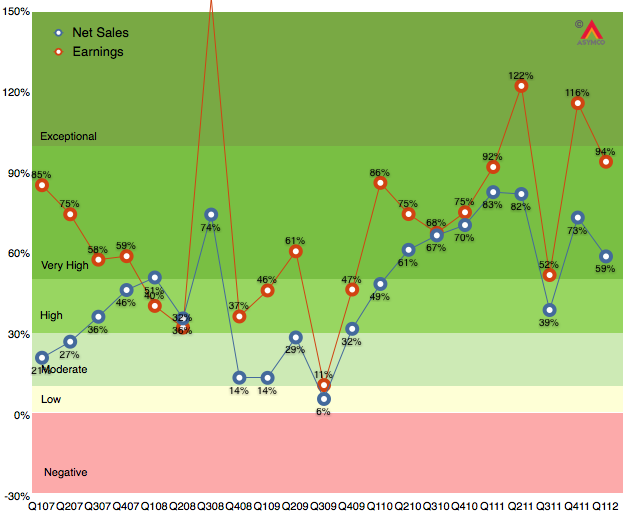
As the chart below shows, the last quarter (first calendar 2012, second fiscal 2012) was robust with 94% earnings growth and 59% net sales growth. Subject to the usual superlatives, the performance was, again, unexpected by many.
Much of that surprise was due to the underestimation of iPhone sales in China during what is a holiday quarter in that nation. Growth this quarter will be more difficult to estimate. The iPhone is still the most important component but the iPad is becoming increasingly decisive in overall performance. In fact, I'm projecting that the iPad will have the equivalent of 73% of the iPhone revenues this quarter.
In this quarter the iPhone is reaching a late stage in its launch cycle but it continues to reach more points of purchase through distribution agreements and it also has a "portfolio" in terms of multiple price points and models available.
The iPad was supply constrained last quarter and may be in balance this quarter. Management has very clearly and repeatedly signaled that the iPad will have a very strong quarter.
So with these clues, here are my estimates for the quarter (with y/y growth in parentheses):
iPhone units: 28.5 million (40%)
Macs: 4.5 million (15%)
iPads: 24 million (160%)
iPods: 6 million (-20%)
Music (incl. app) rev. growth: 35%
Peripherals rev. growth: 20%
Software rev. growth: 15%
Total revenues: $41.9 billion (46%)
GM: 44.8%
EPS: $11.54 (48%)
This earnings value would imply a trailing twelve months’ EPS of about $44.8. At the current price of $571/share the P/E would be 12.7[1]. Cash and equivalents will probably increase to $118 billion.
---
Apple's P/E also dropped to 12.7 around Christmas 2008. I did a search for some headlines to recall that time and came across one that seems appropriate: "Unrest Caused By Bad Economy May Require [domestic] Military Action, Says US Report".
Dan and Horace talk about the distinction between what Facebook is and what its value is perceived to be. We touch on both the opportunities and the challenges for social media and how these are reflected in the IPO. We note how and why Facebook integration in iOS might happen. Horace has a few words about China, WWDC, and the future of apps on TVs. It's all about context.
Here is a video of my presentation at Mobilism 2012 on the story of mobile phone disruption. Thanks to Peter-Paul Koch (aka PPK) for organizing a great event and allowing me to present to such a smart and knowledgeable audience.
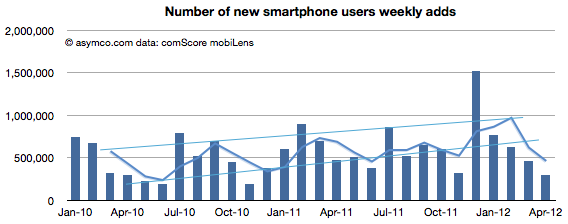
The latest data from comScore showed a few surprises:
New smartphone users dropped to a very low level, below the trend line.
Slightly less than 300k new smartphone users abandoned their feature phones every week during the month. Compared with the 1.5 million per week in November, it's quite a slowdown.
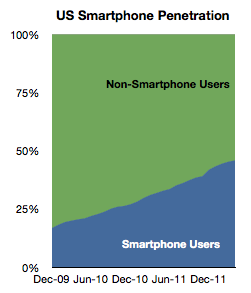
Penetration growth slowed as a result as well. Only 1.3 points of share were gained by smartphones.
It's still likely that the penetration will reach 50% by the end of summer this year (as was predicted in 2010).
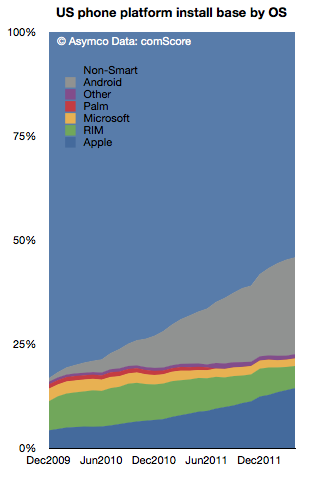
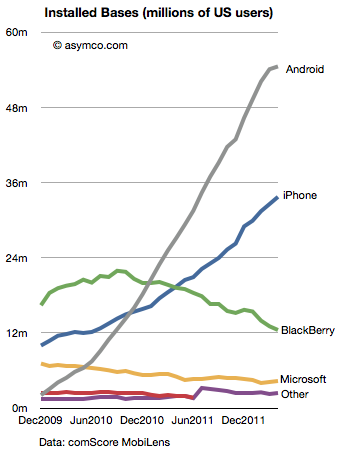
When looking at the picture above broken out by platforms, we see signs that the slowing in smartphone growth seems to be attributable to a slowing in Android adoption:
Here are the installed bases in users over time of the different platforms:
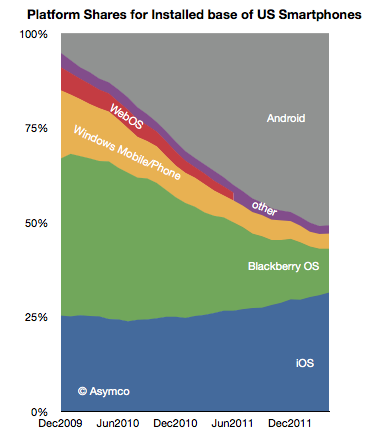
The share of users of the platforms is shown below, first as a stacked area:
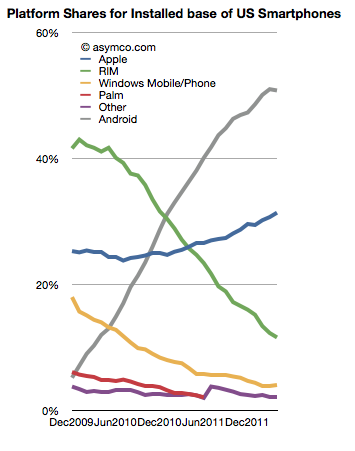
And also as a line chart:
This last chart shows the first time when Android share dipped sequentially. It should be watched closely as an indicator of a change in market dynamics. As we reach saturation, the basis of competition will change.
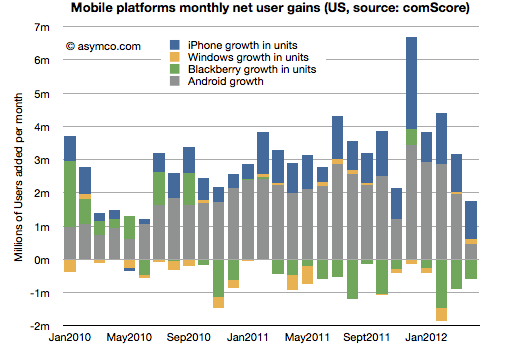
Finally, the last chart shows net user gains for the platforms.
Here again we see the lowest user growth for Android since 2009 (and hence since it reached mainstream distribution.)
It's perhaps too early to suggest that we're seeing a slowdown in the US for Android. Perhaps there will be a return to growth in the fall. The concern has to be that rather than seeing the net adds growing--as they have for two years with only two contiguous months of decline--Android net adds have been falling for four months.
A glance at Nokia and RIM's market values today shows that they are both valued below book. With respect to RIM,
The company's share price has collapsed in the past year, and it is now only valued at about $5.4 billion, down from $84 billion at its peak in 2008. Excluding its cash and the estimated value of its patents, RIM's device business and its 78 million subscribers around the world are in aggregate worth less than $1 billion to investors.
MKM: We are downgrading Nokia to Sell from Neutral following our U.S. retail Lumia model checks. We assume no value for the handset business and no value for the roughly four billion euros [about $5 billion] in net cash.
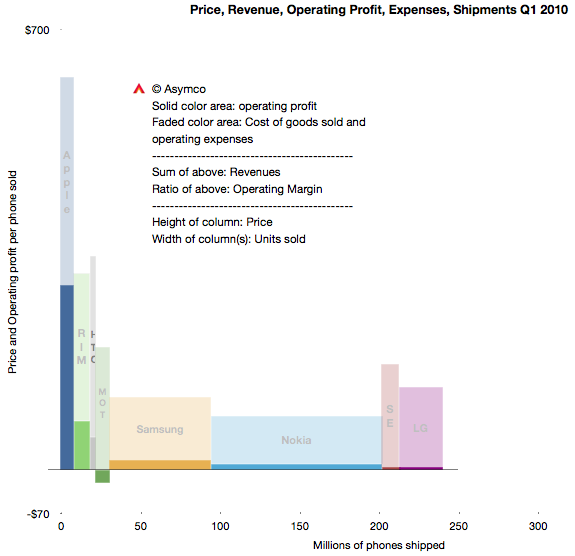
Three years ago the situation was dramatically different. RIM's share price was six times higher and Nokia's about four times higher. Here's what the market looked like in Q1 2010:
This summary view shows individual competitors in the phone market as well as their combined total volumes. The profitability/volumes/pricing can be visualized as well as margins and revenues.
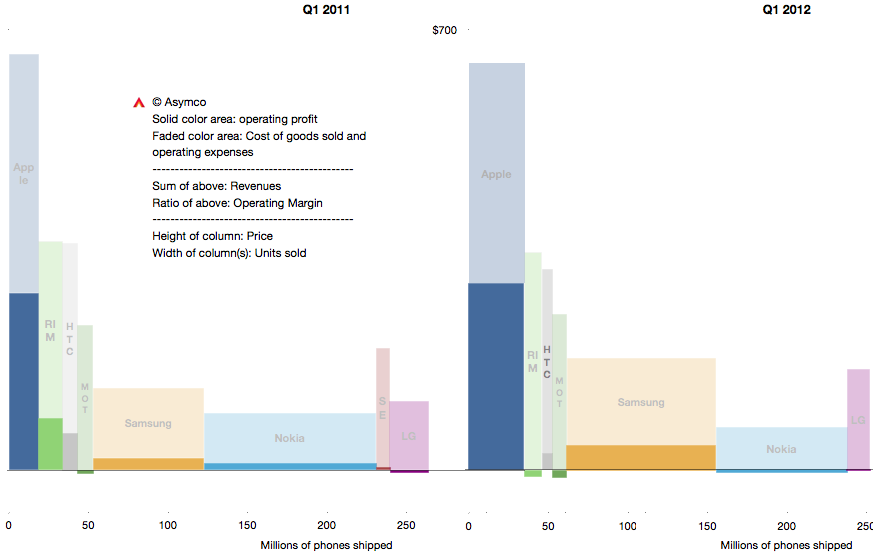
The same visual summary is presented for the first quarters of 2011 and 2012 below:
The change may be subtle to the untrained eye, but it can be summarized as contraction for most vendors and expansion for Apple and Samsung. RIM and Nokia not only contracted in terms of revenues and volumes but also, crucially, lose money.
I've written about this before (many times.) But it's important to repeat again that this is a very short time span. Only three years separate the top chart from the bottom right. The "shape" of the market participants has not changed much but a tipping point has been crossed. This is the point where some participants are disrupted enough that they cannot recover.
Did it happen in 2010, 2011 or 2012? We're only looking at data which results from hundreds of decisions and thousands of actions. It's improbable that there was a single moment when the shift occurred or a single decision that caused it. But it's equally improbable that the disrupted could have countered any of the actions that got them to this point.
The cause (and remedy) for disruption is never found in a single act. It's a process and a way of operating and thinking. Is management to blame? That's always the answer. But how did management go from being smart to foolish so quickly and why did all managers in a firm, even an industry, conspire to become foolish at the same time?
If you study the decisions on a day-to-day basis, management consistently applies all the lessons they learned that led to success in the past. But these lessons lead to decisions that end up with exactly the worst result possible.
The crux of this dilemma is that doing the "right thing" leads to the wrong result. In a comment I questioned the possibility of management in a public company solving the dilemma.
Some have argued that public companies with professional managers entrusted with fiduciary responsibility are inherently incapable of solving the innovator's dilemma and are thus doomed to be disrupted. I'm starting to believe the argument. Whenever you as a manager try to work out the solution to the dilemma, you encounter a value destroying obstacle that cannot be surmounted while maintaining your position in the company. [As you attempt to solve it, you lose your position] Your successor won't make the same mistake and [thus] the whole enterprise collapses.
There are counter-examples however. The reason Apple should be studied is that it gives hope that they have cracked this problem.
This week, Horace follows up on his discussion of automobiles and road infrastructure by talking about how road networks were rebuilt in European countries to accommodate cycling. That leads to hints about the challenge of re-building energy infrastructure to support new power train technologies. We talk about RIM's post-trauma life expectancy. Finally He and Dan also analyze comments made by Tim Cook at the recent D10 conference about Apple TV and disruption of the entertainment industry.
I note the "our" in "our year". This implies fiscal year (that and the fact that he spoke in the past tense before six months had passed in the calendar year.)
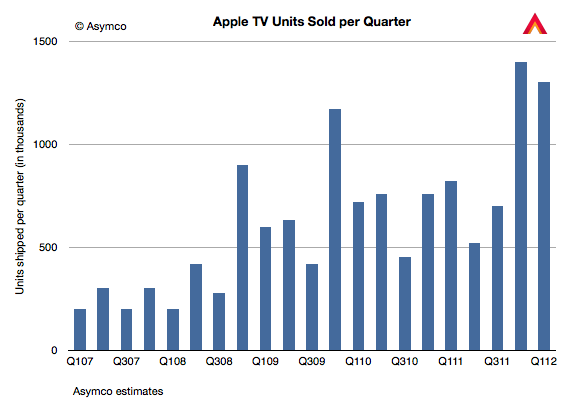
Given the public information we have so far, it's now possible to estimate with some confidence the sales history of Apple TV. The following chart is my estimate. It includes all the known data so far with some interpolations to fill in the gaps.
Assuming average revenues per device of $100, we can get an estimate of about $344 million in Apple TV hardware revenues for calendar 2011. This is not a large amount relative to Apple's other lines of business. It is, for example, only 14% of the overall Peripherals revenues and only 5% of the iPod.
However hardware revenues are not the whole story. The business model for the device is in many ways the polar opposite of the business model of the iPhone. Whereas the iPhone employs "break-even" iTunes App Store (and the Music and Video and Book stores) in order to sustain its high hardware margins, the Apple TV business has low hardware margins that sustain content.
The complete picture therefore has to include an assessment of the content attach rates and the agency fees that Apple gets for that content.
Let's assume that each Apple TV is used to generate $10/month in content sales. This is not a lot. It's equivalent to 5 TV shows or one movie purchased or two movie rentals per month. The model I have shows that the installed base of Apple TVs was about 10 million by the end of 2011. That means that the run rate is $1.2 billion in content sales for the Apple TVs in use.
Now Apple does not book all that. They book only about 30% as revenues as their agency fee. That means that Apple TV could be generating revenues at a run rate of $360 million (to Apple.)
If we add that to the $344 million in hardware revenues we get about $704 million for 2011. This is still not a huge business. It is about equal to the revenue from iPad Smart Covers[1]
Looking forward, if Apple TV units sell at double the rate of last year and we increase the footprint accordingly, we could see a revenue rate of $1.2 billion for 2012.
Now this is not a high margin business. The margin on the content may be less than 50%--depending on transaction costs and hosting/traffic fees. The margin on the hardware is also likely to be below 40%. So the business is not wildly profitable. But it probably is profitable. Which means it makes sense to keep it running while waiting for other pieces to fall into place.
As Tim Cook repeated, they are very interested in this space. However, any discussion of the future must include an analysis of the business model and the sustainability in terms of profit that keeps long term development focused on getting the product to be good enough for the right jobs to be done.
What we should think about however is this "polar opposite" business model. Apple is running this as a "hobby" or as an internal experiment. Sales are (relatively) tiny but it generates some profit. Volumes are small but they are growing. It's taking a heck of a long time. It's asymmetric to the prevailing model the company relies upon. It's beneath contempt from all observers. Sounds familiar?
---
Notes:
In 2011 there were about 40.5 million iPads sold. If we assume half of those purchases also resulted in a Smart Cover purchase and if the average revenue per Smart Cover was $35 then total Smart Cover revenues were $709 million.
“Clearly this stuff isn’t selling,” said Monga [an analyst at Veritas Investments Research in Toronto.]...
RIM took a $485 million pretax charge to write down the value of its PlayBook inventory in December, after shipping just 150,000 of the tablet computers in the quarter. Then in March, the company recorded a $267 million expense for BlackBerry inventory. RIM said at the time that it would stop giving sales and profit guidance because of “ongoing weakness” in the U.S.
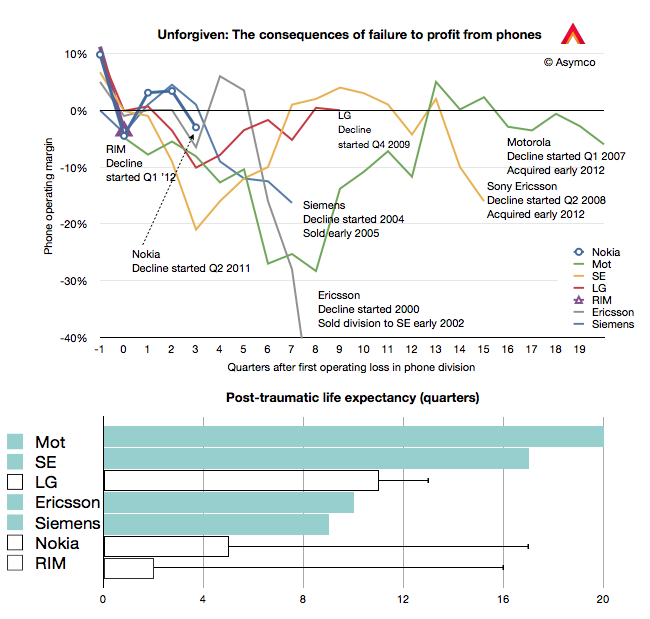
RIM has just entered what I call the Post-traumatic period of a phone maker's life. This period is defined as beginning with a loss-making quarter and ending with the company's exit from the business. These post-traumatic periods were visualized first here and the pattern was first discussed about a year ago here.
I've updated the chart with the current data and added the bar chart below to illustrated the "post-traumatic life expectancy" for the companies shown. Companies still operating are shown with bars without color while companies that have exited are shown with solid color bars.
The pattern may be that companies either have short post-trauma lives of about two to three years or relatively long post-trauma lives lasting 4 to 5 years. What determines this life expectancy and how long do RIM, Nokia and LG have?
There is precious little data, but perhaps one hypothesis I could offer could be that the bigger the commitment to the industry (in terms of having no fall-back options) the longer the post-traumatic period lasts. In other words, as there is no easy way out, the fight lasts longer.
This can also be interpreted using Porter's "barriers to exit" force analysis where companies which can liquidate a division see it as a low cost of exit whereas companies that need to restructure (usually more than once) and then seek either a buyout or rescue may interpret exit as a very costly endeavor.
Long exits compile larger costs of distress and can cause more pain for stakeholders, especially if the end is inevitable.
Given this hypothesis, as both Nokia and RIM depend largely on mobile phone sales, it's likely that they will not exit quickly. (Ironically perhaps, LG has a better shot at a quick exit given its diversified conglomerate status.) It might imply that there are at least two more years before Nokia and RIM call it quits.
Markets are difficult to measure. Mainly because the information is not easy to obtain and that which is obtained is not made public. Collecting, analyzing and filling in the gaps is big business with many firms involved in selling it.
However, with all the analysts and companies selling and promoting their "numbers" it's important to understand the difference between the methods used. There are for instance at least the following measurements:
Units sold to end users. For example NPD or GfK data of retail transactions. Also Gartner's estimates for phone units sold.
Units sold to the channel. For example units recognized on income statements usually reported by companies. Also IDC's estimates for phone units sold.
Units in use. For example comScore and Nielsen survey data.
Units "activated". The measurement Google uses to describe Android performance.
Intent to buy. For example ChangeWave surveys of early adopters.
Utilization rate. For example browser statistics.
Each measurement tells a different story about the market but the best story is told when all data is analyzed in a combined integrated market review.
Before diving into that it's important to understand the difference between the first and second measurements or the difference between shipped and sold.
What does "Sold" mean?
Let’s say that you sell a phone to another party. What constitutes a sale? The sales agreement? That you shipped it? That he wanted it? That you were paid for it?
What if he changes his mind and returns it? Is it still a sale? What if a manager's bonus depends on these sales? What if the company’s share price depends on these sales? Is there a way to rig the accounting?
As it turns out, yes there are; many ways. Unethical and fraudulent practices happen surprisingly often. A classic instance would be: A customer is shipped ten phones, though he only wants one, and he gets paid to ship the other nine back, after the close of the year.
The sales manager records ten times the sales he actually made, making ten times the commission and the company’s stock price rises. To compound the offense, the manager could also tip his friends to short the stock at the end of the year, leaving investors “holding the bag” when the inevitable correction follows.
There have been so many cases of this kind of accounting fraud that the FASB (GAAP), SEC, and IFRS have placed a very stringent definition on “revenue recognition”. This means that although you can sell all you want, the company can only recognize the proceeds and profit in the financial statements according to strict rules.
In the case of hardware (Sales of Goods), the customer must receive it (“delivery has occurred”), and like it enough to not return it (“amount to be refunded”), and be able to pay for it (“collection is probable”). If some are projected to be returned or unpaid, that percent is subtracted from total revenue. In the case of software (Sales of Services), it is generally accounted for over a time period. And because it is customary to send the customer upgrades, the revenue must be spread out over the time the service is provided. (“upgrade rights … 24 to 48 months.”)
It gets complicated when a piece of hardware has upgradeable software. The rules used to stipulate that the hardware, in its entirety, must be accounted for as a service and have subscription accounting. This is how Apple had to report sales during the first few years of the iPhone. It still defers some revenues for its hardware, mainly on account of iCloud, but the vast bulk of hardware revenue (96%) is now accounted upfront, recognized upon the product's acceptance by customers. 4% is for software upgrades and is accounted for over a specific lifetime of the product (24 months in the case of the iPhone).
What does "Shipped" mean?
The discussion so far implies that if a product that is accounted for as "Sold" on an income statement does not mean that it's in the hands of an end user. These "revenue recognized" products are sold to a distributor, typically for a phone that's an operator.
These sales satisfy the requirements for financial reporting as revenues booked. But they are not in the hands of users. Nor are they "activated" and they don't generate page views that are measured by web analytics companies. Most analysts and companies now use the phrase "Shipped" to describe these revenue-recognized units though it's also common to hear "sold".
When a product sells to end users it's sometimes called "sell-through". It's counterpart is "sell-in" which is sales to the channel distributors.
A big gap between sell-in and sell-through might imply large amounts of in-channel inventory. This is product that is sitting either in stores or in warehouses or on trucks in transit. If sales are steady, the inventory is measured in time as in "weeks of inventory". This means that the excess is expected to be sold within a fixed time frame if shipments were to end. The smaller this amount, the better or "tighter" the operations are. Inventory, as Tim Cooks says, is fundamentally evil. It eats capital and erodes profitability.
Sometimes miscalculation of sell-through could result in vast amounts of inventory that has to be returned by distributors. That inventory is either written off or sold at fire sale prices resulting in a "write-down". This happened recently with both the HP TouchPad and with the RIM PlayBook. This special charge against income is a one-time (usually) incident but it can also affect a firm's reputation with channel partners for a long time. This type of failure is very costly.
Therefore what matters most is to keep the difference between Sell-in and Sell-through as small as possible. However, it can't be too small. Sometimes if Sell-through is too fast, you get stock-outs which means that there is more demand than supply and sales opportunities are missed. This has happened many times with iPhones and iPads. This is also an unwanted situation (unless there was too much inventory in the channel during the previous period and thus it was being drained in the current period.)
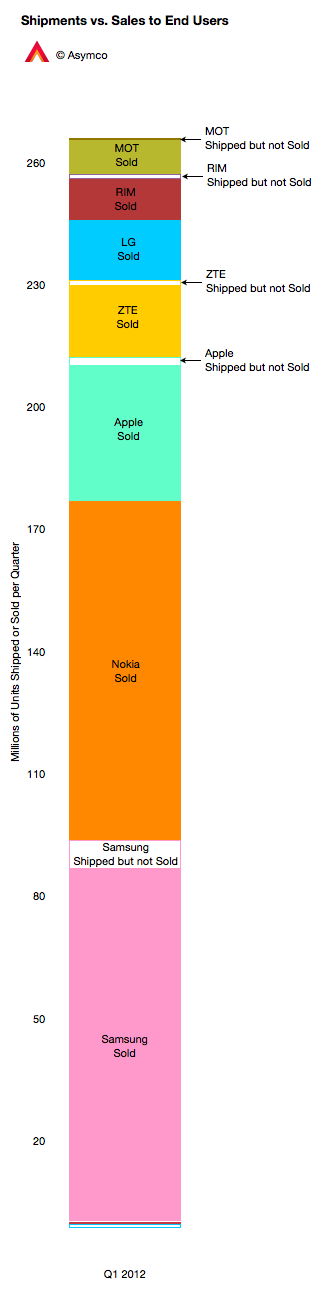
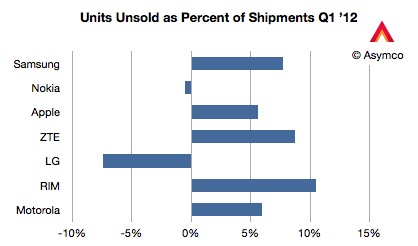
The chart to the left shows how the phone market looked for various vendors last quarter. I compiled the data based on Gartner's "sales to end users" and IDC's "shipments" data. Two vendors had higher sell-through than sell-in (Nokia and LG) probably because they were draining excess inventory. The others had channel inventory of between 5% and 10% of units shipped.
This ratio is shown below in a chart comparing the largest phone vendors.
Management is often rated for performance on this metric, as they should be, since it's a measure of operational skill. However, there are many factors that affect overall performance.
New product launches, windows of opportunity related to seasonal buying patterns, anticipating macroeconomic slowdowns, even natural disasters and legal challenges can affect this metric.
Understanding the overall market requires an appreciation of this distinction but also an understanding of all the other metrics listed above and what stories they tell.
---
Notes: My thanks to Michael Dediu for input on this discussion.
Dan and Horace take a nostalgic trip through the automotive industry. Horace asks why should a 20 year old car (which he happens to own) be replaced? Why are cars built to be disposed of and why aren't they meaningfully improved based on new jobs to be done? In this episode we look at the auto industry as a proxy for other "network-based" industries which reach plateaus of innovation and can go no further. Plus, Horace challenges readers to guess what car he drives.