Asymco

Asymmetric Intelligence

Horace Dediu

  1. Why was Wall Street surprised by Apple's performance?

    Research · 76 comments

    The Earth's axis is tilted relative to the orbital plane it follows around the Sun. The angle is about 23.44 degrees. Because of this axial tilt, the intensity of sunlight incident on the northern and southern hemispheres varies alternatively throughout the orbit, which, by its duration, is called a "year". This change in sunlight intensity causes weather changes. Colder when there is less light, warmer when there is more light. Life on Earth became used to this cycle and humans came to call these changes in weather "seasons".

    The warm seasons became the easier seasons for people, especially when agriculture was introduced, since that was when food grew.  Because of the geography of landmasses on Earth, humans became more concentrated in the northern hemisphere. As the northern hemisphere turned away from the Sun darkness and cold returned every year. When that darkness was at its worst people decided it was time to celebrate the return of warmth and sunshine, and thus plentiful food.

    So it became very common in northern lands to celebrate the winter solstice or the darkest and coldest time of the year. The amazing thing was that all peoples did this regardless of culture or geographic location. In fact, it became common to mark the end of year at around the same time as the solstice. A new year was said to begin when the Sun began to move higher in the sky every day. The Europeans celebrated the solstice with a festival which eventually came to be called Christmas and the Chinese celebrated it as a Winter Festival which came to be called Chinese New Year.

    As part of these celebrations, gift giving also became the default practice. And so, around what came to be called "December" and "January" most of the people in the Northern Hemisphere gave gifts to each other. Interestingly, as people migrated to the southern hemisphere they kept the same festival schedule so that gifting was done in what was the height of summer!

    What Wall Street seems to have missed is that the gifting season is a global event spanning into January. In other words, buyers of iPhones aren't concentrated in one part of the planet and they don't all celebrate one single gifting festival.

    The reason lies in the way the Earth is tilted and the way the continents are arranged upon it. So perhaps a better understanding of astronomy and geography would have helped investors make decisions during the past few weeks. I suggest remedial lessons for those who missed this.
  2. 5by5 | The Critical Path #35: Joys and Sorrows

    Podcast · 9 comments

    A review of Apple's performance in the first calendar quarter. Covering the iPhone's predictability, greater China and international opportunity swamping the US opportunity, the iPad surprise and what mobile means to Apple. Dan and Horace ponder what it means for the largest company in the world to also be the fastest growing company in the world. We discuss whether there is a mobile bubble and, as a bonus, Horace predicts the launch timing of the next iPhone.

    via 5by5 | The Critical Path #35: Joys and Sorrows.

    Covered a lot of ground. Be sure to rate the show on iTunes.

  3. Apple's Growth Scorecard for the first quarter of 2012

    Research · 117 comments

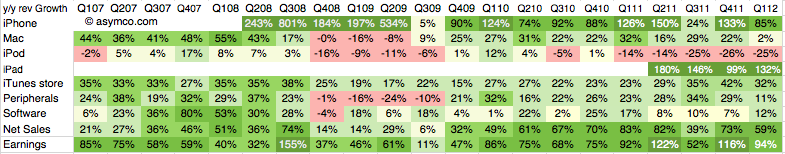
    For Apple 2012 started with almost the same growth as 2011 started. Q1 2011 saw earnings growth of 92% and Q1 2012 saw growth of 94%. As the following revenue growth table shows, the pattern for the last twelve months has been very consistent:

    Here are some notes:

    • The iPad is growing at a faster rate than the iPhone and has achieved in two years what the iPhone took four.
    • The iPhone grew units at nearly 90% and revenues at 85%. This is slightly below the quarterly average over the last two years of 99%
    • The Mac showed significant weakness though the previous year's Q1 had exceptionally high growth of 32%. The Mac still grew faster than the market and therefore gained share
    • The iPod is declining consistently. Units showed a lesser decline than revenues as the average price dropped from $164 to $157.
    • The iTunes store continues to grow very rapidly, reaching a new record level above $2.1 billion revenues
    • Peripherals were weak with 11% growth but that may have something to do with lowered Mac sales
    • Software had good quarter though not exceptional
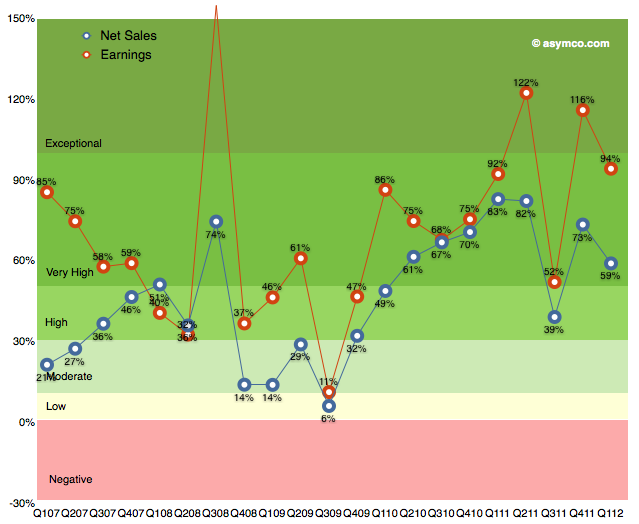
    • The top line grew at nearly 60% which is not exceptional but the bottom line grew at 94% which is above average

    Overall, the company had a very good quarter and showed consistency, which, incidentally, implies predictability. The following graph shows the top and bottom lines in historical context with color coding matching the table above.


  4. Unforgiven: The consequences of profit failure in mobile phones

    Research · 34 comments

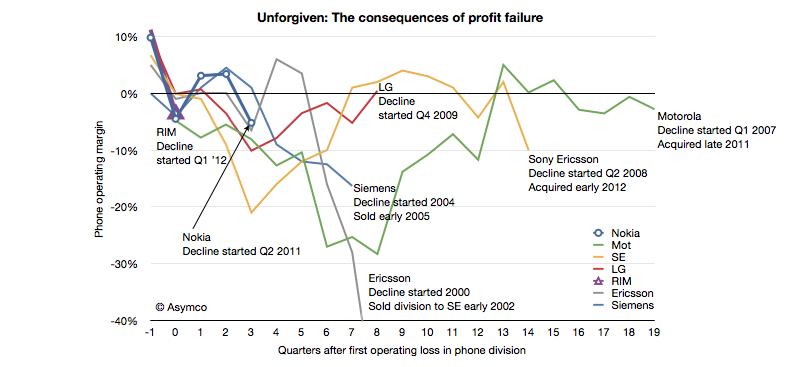
    In June of last year I wrote a post titled "Does the phone market forgive failure?" It was written on the eve of Nokia's Q2 2011 report highlighting the historic consequences of a dip into negative operating margins for a phone vendor.

    I listed 13 phone vendors who were either merged, liquidated or acquired. There are no examples of vendors who recovered from a position of loss making.

    I was prompted to follow-up by a note Charter Equity Research analyst Edward Snyder wrote illustrating the effect of negative operating margins on phone vendors. I took his illustration and expanded it with additional data.

    Since my post in June last year Sony Ericsson and Motorola were acquired making the victims list total 14 companies, with Nokia, LG and RIM having joined the "endangered species list". If the pattern repeats, then RIM and Nokia are in early phases of what promises to be an extended period of pain followed by an exit.

    What the analysis does not answer is when a vendor loses its independence after beginning loss making. Motorola took 20 quarters; Sony Ericsson 14, Ericsson 8 and Siemens only 7. We cannot tell if or when LG, which is still operating after 8 and Nokia, which is now in its fourth and RIM, now in its second quarter post-loss, will lose independence.

    The rumors swirling around RIM and LG are centered around exits and some suggest Nokia will follow. Many also argue that these companies will recover. The conditions they each face are different in details but broadly they are the same. Earlier last decade the exits were prompted by loss of brand value and subsequent loss of distribution. This decade disruption brought upon by mobile computing brings with it new business models centered on ecosystems and value captured through software and services.

    Until and unless these endangered companies solve the dilemma of having the wrong business model at the wrong time, the chances are that they will not be forgiven for market failure.

  5. Google and Microsoft speak volumes with silence

    Research · 23 comments

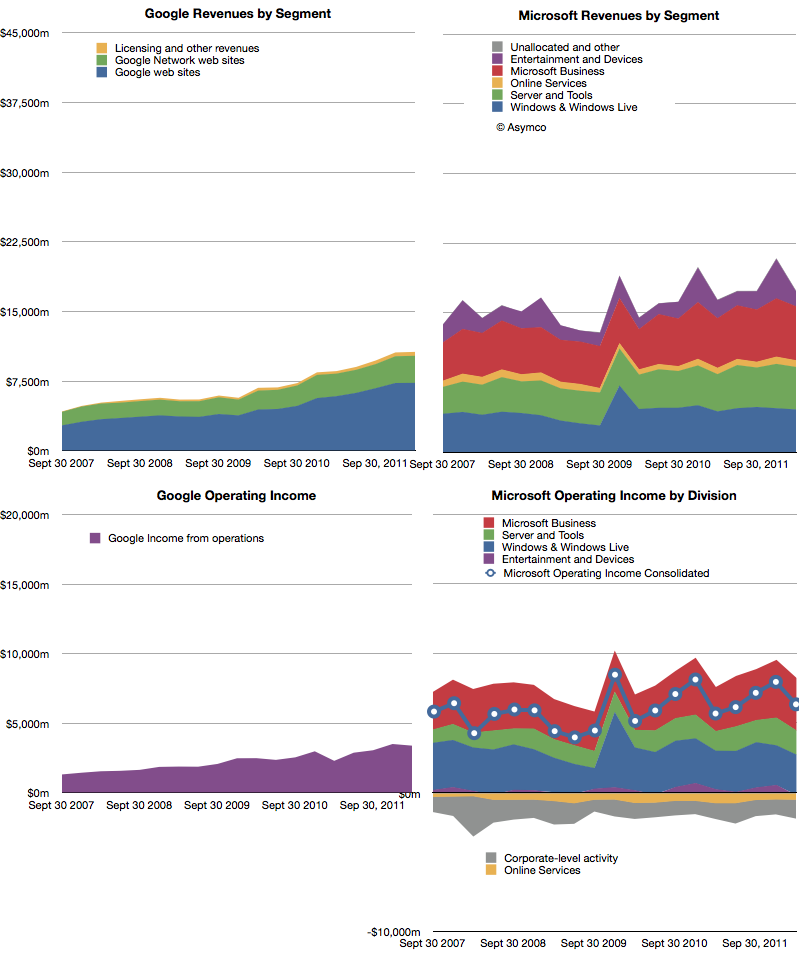
    The following charts show Google and Microsoft revenues and operating income:

    Both companies showed healthy growth. Revenues: Microsoft 6%, Google 24%. Operating Income: Microsoft 12%, Google 48%. Google had a particularly weak margin Q1 2011 so its income growth appears very strong.

    The surprise in Microsoft's performance was the 4.8% increase in Windows revenue at a time when PC sales were expected to be declining or flat. Final PC numbers are not yet out so we'll have to check back on this figure to see whether Microsoft has been able to get higher pricing for Windows or whether the market did expand. (Average revenues per PC sold have been quite steady for years). Overall, Microsoft's business shows consistency. Of course, that should not be cause for comfort. Nokia had remarkable consistency until it jumped from a burning platform and RIM grew more rapidly until its platform imploded.

    As Google still obtains 96% of its income from advertising, it's quite remarkable that it is now at 61% of Microsoft's revenues. Google is also growing more rapidly than Microsoft so the possibility exists that the top ad service will overtake the top software company in revenue, establishing a new benchmark for how software can be monetized.

    The curious thing about both of these companies' financial performance is that mobility does not appear to have had any impact on either top or bottom lines[1].  There is no business division or income statement line that can be attached to mobile revenues. Microsoft placed Windows Phone under Entertainment and Devices but that division is dominated by Xbox and accessories. Google bundles everything under Advertising and has never broken out mobile, much less Android-derived income.

    The surge in valuation for mobile-focused startups seems to leave investors in both these companies unaffected. The damnation for both companies lies in mobility being non-core businesses whose strategies center on reaction and defense.

    ---

    Notes:

    1. Google does not answer specific questions about the impact of mobile on their business but they do acknowledge that there are traffic acquisition costs (TAC) associated with OEMs and Carriers who deploy Android. This means that there are costs of mobile sales (i.e. Search) but not to any measure of specific value.
  6. Forecasting Nokia's Windows Phone sales and Microsoft's mobile customer acquisition cost

    Research · 56 comments

    Our agreement with Microsoft includes platform support payments from Microsoft to us as well as software royalty payments from us to Microsoft. In the first quarter 2012, we received a quarterly platform support payment of USD 250 million (approximately EUR 189 million). We have a competitive software royalty structure, which includes minimum software royalty commitments. Over the life of the agreement, both the platform support payments and the minimum software royalty commitments are expected to measure in the billions of US Dollars. The total amount of the platform support payments is expected to slightly exceed the total amount of the minimum software royalty commitments.

    From Nokia's Q1 2012 financial interim report

    The figure of $250 million for Q1 is the same as the amount Nokia received for "platform support" in Q4 2011. This means Microsoft has paid $500 million over two quarters. During the same time frame Nokia shipped approximately three million Windows Phone devices. The average cost to Microsoft to acquire a Nokia Windows Phone user is therefore $167 per user. This is down from $250/user in the last quarter.[1]

    If the royalty is equivalent to a license fee then the more interesting question is how and when will the royalty payments nearly match the platform support payments as expected. This might give us an estimate of what both parties are expecting from the relationship.

    If the payment schedule of $250 million per quarter is maintained through 2014, Microsoft will have paid $3.25 billion to Nokia. This is well within the "billions of US dollars" range that is cited above. (The minimum would be $2 billion which would mean payments through the end of 2013).

    We also need to estimate the royalty payment structure. One figure that has been circulating for a long time is that Microsoft prices Windows Phone (and its antecedent Windows Mobile) at $15/unit. It's an aggressive price point for a mobile software license and should be subject to volume discounts but let's assume it's correct. If it is correct then the only remaining question is how quickly will Windows Phone units grow at Nokia?

    One way to begin is to calibrate WP growth to iPhone growth. For the first two quarters iPhone and Lumia have sold at rough parity.[2] iPhone sold 1.4 million in its first quarter (including opening weekend sales of 270k in previous quarter) while Nokia sold "approximately" one million Lumias in its first quarter[3]. In the second quarter Nokia cited 2 million Lumia units and Apple had 2.3 million iPhone sold in Q4 07. So far Lumia is slightly under the iPhone ramp, but let's give it the benefit of doubt.

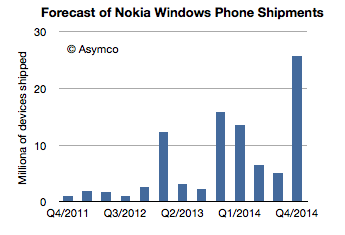
    If we  apply iPhone growth rates to Lumia then we have the following sales forecast for Nokia's Windows Phones:

    This looks like healthy growth, as was the iPhone's. However, this "iPhone growth" pattern only results in about $1.4 billion in payments in exchange for $3.25 billion from Microsoft, leaving a deficit of $1.9 billion in the "platform support" balance.

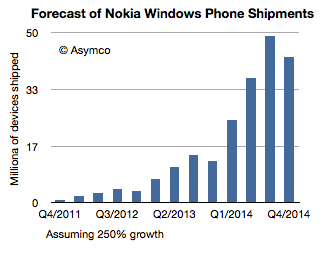
    To erase the deficit, I tried an approach where I assigned 3 million and 4 million for Q2 and Q3 shipments respectively then applied a constant (y/y) growth rate thereafter. Solving for a figure of growth which results rough parity with platform support payments gives us about 250% growth. The resulting sales profile looks like this:

    This ramp would result in 210 million Windows Phones shipped over about three years. It would also generate nearly $3.2 billion in "royalties" for Microsoft offsetting $3.25 billion in "platform support" payments by Microsoft to Nokia.

    There are many assumptions in this, royalty rate and length of contract chief among them, but the key question should be a sanity check: is this a feasible product ramp. It's certainly far faster growth than Apple has been able to achieve. On average Apple obtained about 160% quarterly y/y growth. It also exceeds the growth rate that Samsung has been able to achieve (165 to 170 million smartphones shipped from a standing start three years ago). It implies 150 million units shipping in the third year of sales and nearly 50 million in a peak quarter. It assumes perhaps as much as 20% market share in smartphones in 2014. It's certainly ambitious.

    But even if it's achieved, it's only a break-even point for Microsoft's relationship with Nokia. It would imply that payments to and payments from Nokia would be in balance. The road to (dare one say it?) profitability for Microsoft in mobile would just begin to be visible at that point.

    ---

    Notes:

    1. What the quote above also reveals is that Nokia is also expecting to pay back some of these "support payments" in the form of "royalty payments" for the software. That's an interesting word choice as usually an OEM would pay a license rather than a royalty for software. I'm not sure if this implies anything but it may.
    2. See also Charles Arthur's analysis of comparable growth ramps for mobile phone platforms here.
    3. This figure was cited "to date" in a March statement so actual calendar Q1 may have been less, perhaps 650k.


  7. Nokia's evaporating brand value

    Research · 65 comments

    Nokia reported Q1 results following very closely the warning issued last week.

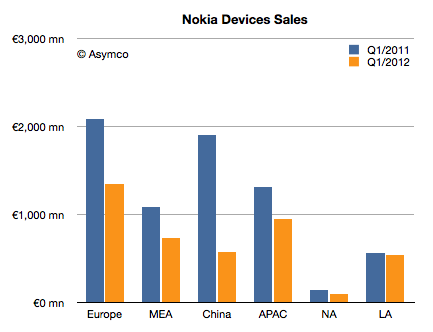
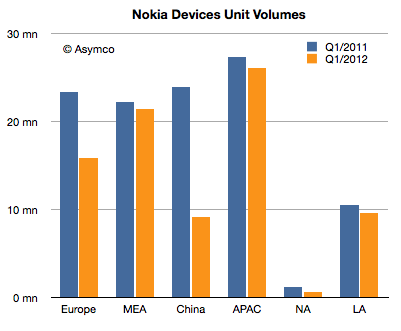
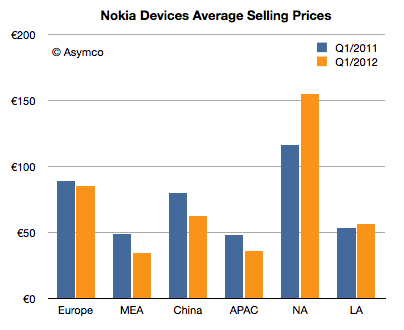
    There were few surprises. There is much more detail in terms of regional performance which might be a better indicator of how the smartphone strategy is playing out. I plotted the data in three charts.

    Regional Sales Value

    A year ago Europe and China were nearly equally valuable as regions to Nokia (€2.1 billion and €1.9 billion, respectively). Even though sales fell across all regions, China fell so much that it has become the fourth in value and nearly the same value as Latin America (€577 million for China vs. €542 million for Latin America). This is a significant reversal for a very important market. The drop in value is a staggering 70%. Is there some clue as to what caused this?

    Regional Unit Volumes

    The data on volumes shows that Europe's drop is consistent (35% drop in value coupled with 32% drop in units). This implies an erosion in pricing but not a very large drop. However, in China the volumes fell less rapidly than sales (70% drop in value and 62% drop in volume). The pricing story was significantly worse. This story repeats in Middle East, Africa and Asia Pacific where volumes held but value dropped. This implies significant change in pricing in those regions. That's borne out by the chart below:

    Regional Selling Prices

    Prices in Europe dropped by about 4% but in China they dropped by 21% (from €80 to €63). In APAC the drop in price was 25% and in Middle East and Africa it was 30%. In the Americas prices increased with North America up by one third and Latin America by about 6%.

    This uplift in NA is primarily due to the Lumia launch as channel was being filled. However, note that North American volumes were extremely small: only 600,000 units sold (inclusive all models).

    As the Lumia line was not available in many markets, and as only 2 million were sold, it's hard to see its impact. The only clear effect was on North America prices and that overall smart devices ASP held the line (down only 2% y/y and up 2% sequentially). The €220 average price for Lumia was well above the €143 for all smart devices sold. Nevertheless, smart device volumes were down 50% to about 12 million units--nearly the same as RIM's pitiful results.

    What these data points add up to is that Nokia cut pricing aggressively while losing volumes. The price cuts were "forced" by conditions and probably were designed to slow the drop in demand. Emerging markets, once Nokia's core growth area, showed dramatic value contraction due to price pressure. Nokia's brand value, which normally allows for price premiums regardless of functional value, is clearly evaporating in its last bastions.

  8. 5by5 | The Critical Path #34: Climax and Anti-climax

    Podcast · 6 comments

    Horace and Dan talk about Asymconf 1.0 focusing on the risks taken and rewards obtained. We cover the concept, technical implementation, dynamics and where the show will go from here. Horace describes the fascinating "lost tapes" of Steve Jobs and Nokia's latest anticlimactic results.

    via 5by5 | The Critical Path #34: Climax and Anti-climax.

    Show notes:

  9. Apple Stores have seventeen times better performance than the average retailer

    Research · 50 comments

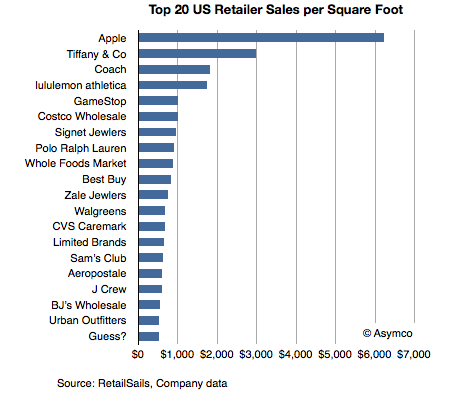
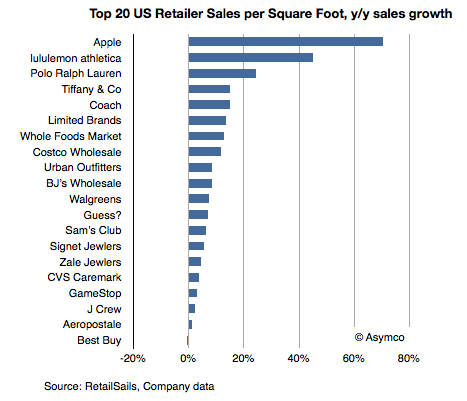
    Thanks to RetailSails we have some data on retailers in the US which can be used to calibrate the performance of Apple retail. RetailSails compiled a table of the top 20 chains by sales per square foot (annual basis). The total sample was 160 American retailers (excluding restaurants) that publicly report results.

    Sales per unit area is a standard and usually the primary measurement of store success. Here are some benchmark figures:

    • Annual store sales in the range of $300 per square foot is considered respectable in the US.
    • The US national average for regional malls is $341.
    • The average for specialty apparel retailers is $400 per square foot.
    • The average for jewelers is in the range of $600 per square foot.
    • The median for the best 20 US retailers is $787/sq. ft.

    The data for the top 20 is shown in the following chart:

    The data shows Apple leading by a significant margin. It's more than twice as efficient as the second place Tiffany and Co. It's also more than seven times the median of the top 20 and seventeen times better than the average mall retail space.

    Note also that this data includes only physical retail and excludes e-commerce, catalog or services revenues. It should only be used to compare physical retail performance.


    The achievement is also remarkable when measuring growth in overall sales.

    Apple leads in absolute performance but also in growth.

    Note also the performance of electronics retailers that might be comparable to Apple. Only Best Buy and GameStop are on the list, but their growth is among the poorest, with Best Buy going in the wrong direction (data was current as of August 2011).

    We'll be getting an update on Apple retail at the next earnings call in a few days. To read more about Apple retail see:

    Apple retail growth data | asymco

    The growth surprise in Apple retail | asymco

  10. Asymconf 1.0

    Research · 32 comments

    The first Asymconf was conducted on Friday, April 13th, 2012 in Amsterdam. Here are some statistics from the show:

    1. 155 registered participants and over 1000 participation hours
    2. Over 500 tweets generated during the day (#asymconf)
    3. Eight hours of conference executed on schedule
    4. Three iPads used to facilitate: one as a whiteboard, one as a slide presenter and one as an interactive motion chart.
    5. Seven video cameras used to capture over 1 terabyte of video data.
    6. Four cases conducted with majority of time spent on audience participation

    Overall, feedback has been very positive. We will now edit the video to make it available for download. We will also analyze all aspects of the event to understand how it can be improved and post our findings.

    We plan to hold Asymconf 2.0 in approximately six months somewhere on the West Coast of the US. We are already scouting for locations.

    If you have photos or additional comments regarding the event that you'd like to share, please post them below.

    My thanks to those who made Asymconf possible:


  11. How Samsung beat Nokia

    Research · 154 comments

    Nokia currently estimates that Devices & Services net sales in the first quarter 2012 were EUR 4.2 billion, comprised of Mobile Phones net sales of EUR 2.3 billion (71 million units), Smart Devices net sales of EUR 1.7 billion (12 million units),

    via Nokia lowers Devices & Services first quarter 2012 outlook and provides second quarter 2012 outlook » Nokia – Press.

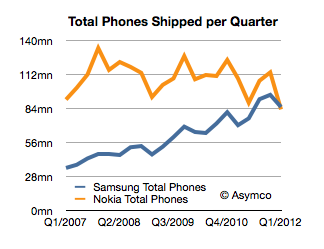
    We don't have the total number of Samsung shipments, however estimates exist. They range between 41 and 44 million smartphones and 44 and 47 million feature phones. The low end of that range would imply Samsung shipped 85 million phones.

    Nokia's press release indicates that it shipped 83 million.

    This would be the first quarter that Samsung beat Nokia in total phone shipments. It had already overtaken Nokia in sales volume and profitability last year but this is the most cited metric of market performance: being the biggest in volume. Here is the tale of the shipments:

    How did this happen?

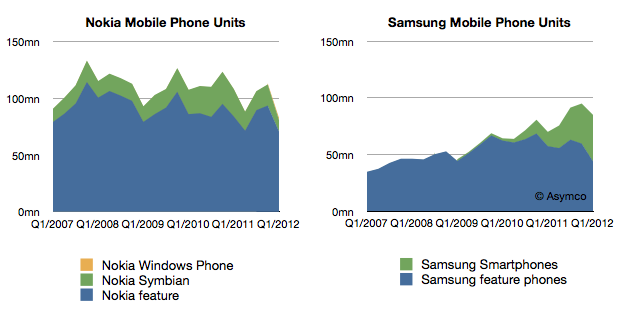
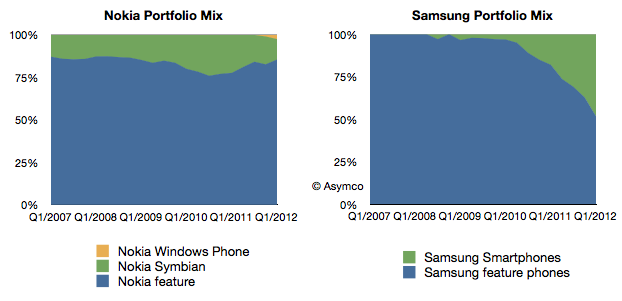
    The answer should become visible when we look at at another set of data. If we split the smartphones from feature phones the charts look like this:

    Looking at product mix, Samsung growth is shown to be almost entirely due to smartphones while Nokia's stagnant growth seems to be a failure to have any smartphone traction.

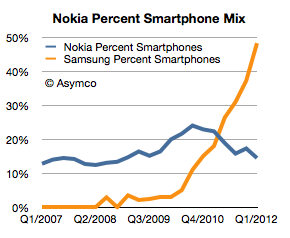
    It's even more clear when showing the above mixes of devices as percents of total.

    As a percent of total, Nokia has shrunk its smartphone business from a peak of 24% in Q3 2010 to 14% last quarter. In the same time frame Samsung's smartphone share of portfolio has exploded from 10% to nearly 50%.

    Note that both companies have seen non-smart device volumes contracting. Samsung's level is approximately the same as it had in late 2007 and Nokia's is lower than at any point in the last six years (perhaps longer).

    So the answer to the question of how Samsung beat Nokia is told in the following chart:

    Samsung was able to convert its portfolio to smartphones while Nokia failed to do so. This is the sort of transition that can only come about from an explicit strategic intention on the part of management. Market demand can steer you in any number of directions, but a vision of a future should provide the compass for making the big bets.

    The bet Nokia made many years ago was that there would be a continuing, substantial business in the "low end". And low end meant feature phones. This strategy was still in evidence last year under the moniker "the next billion" users. The decisions were not driven by whether the products would be hired for different jobs, but that they would hit different price points. In other words, segmentation of customers by their ability to pay for devices rather than categorization of the jobs they hired mobile devices to do.

    Perhaps Samsung was no wiser, but they were more pragmatic. Being non-dogmatic meant being flexible. They ran with off-the-shelf technologies and managed a transition to smart devices faster than anyone expected. It may not be a perfect strategy but it beat a bad strategy.