Asymco

Asymmetric Intelligence

Research

  1. It’s costly and has unpredictable consequences

    Research · 25 comments

    ``It’s costly and has unpredictable consequences. That makes it a very bad business model. I suppose both companies have agendas that are not visible in court and perhaps Apple is signaling to other parties, and perhaps Samsung is using it to raise its profile. It still seems that unintended consequences may arise and the result could be very bad for everybody,’’ said Horace Dediu, founder of equity-research firm Asymco, in an e-mail interview with The Korea Times.

    The above was a quote from the article  Samsung can’t afford to lose Apple fight by Yoo-chul Kim from The Korea Times. Yoo-chul contacted me via email with a series of questions. I want to share all his questions and my answers as well:

    Samsung wides market gap with Apple, according to research firms. You think the gap will further be widen and please tell me why

    As Samsung converts its phone portfolio to be all smartphones, it is very likely to reach much higher smartphone volumes. One year ago Samsung sold about 56 million feature phones. Last quarter it sold about 43 million. The smartphone portion increased from 20 million to 50 million. At the same time, Apple has maintained a growth in its smartphone business of about 100% on a yearly basis. I expect that to continue into 2013 as well. Therefore it's possible that Samsung could sell 290 million smartphones in the next 12 months and Apple could sell about 200 million in the same time frame.

    However, it's important to understand that the companies compete on different bases. What I mean is that what generates a profit (i.e. payment by the consumer above what a product costs) is different for each company. Apple is a platform company that sells access to the iOS ecosystem across many other device types. Samsung sells consumer electronics with limited "network effects" but desirable features. In this view, the gap in device sales is "asymmetric" and not reflective of the actual competition which is between Google's Android and Apple's iOS as forms of access.

    Samsung's rapid rises mainly due to the company's heady dependence
    on Google Android. If Google applies better software for Motorola,
    then you think Samsung will face difficulties?

    Think of Google as a supplier to Samsung. No manufacturer wants to have a situation where they are dependent on only one supplier, especially when there are huge substitution costs for another supplier. And even more especially if that supplier owns one of your competitors. However, it's unlikely that Motorola will become a strong competitor to Samsung. I also don't expect Google will damage their OEM "customers" by favoring Motorola. Motorola can't become big enough quickly enough to be a threat to Samsung. What is more likely to be a problem for Samsung is ZTE and Huawei. They are on the same trajectory that Samsung was on 10 years ago. For Samsung to beat them in the future it will need to develop products that nobody can copy.

    How about software? Samsung is good to roll out price competitive
    models, however, software is always problem. Any advice for this
    issue?

    Software is hard and expertise can't be quickly acquired. It takes time. Only advice [I have] is that efforts must be patient and there need to be many experiments like Bada and Tizen. Google started with Android in 2005 and Apple started with iOS in 2003 or 2004.

    How about the patent dispute with Apple and Samsung. The patent war
    is helping Samsung see a rise in its brand awareness and that also
    worked for Samsung to grab more shares in smartphones?

    It's very difficult to measure the impact of litigation, both in the positive and negative. It's costly and has unpredictable consequences. That makes it a very bad "business model". I suppose both companies have agendas that are not visible in court and, perhaps, Apple is signaling to other parties and perhaps Samsung is using it to raise its profile. It still seems that unintended consequences may arise and the result could be very bad for everybody.

    Samsung wants to become a market creator not just a fast follower.
    For me, it's quite negative for Samsung to create a wholly-new
    eco-systems because Samsung's edges are coming from manufacturing, not creative thinking. What do you think? If Samsung wants to be a
    creator, what conditions should Samsung need and what things should
    the company do?

    Unfortunately, manufacturing excellence is not enough to remain successful long term. US companies were successful, then the Japanese, Taiwanese, Hong Kong, and now Chinese. Companies either adapt or become irrelevant. Building ecosystems is the new basis of competition but it's not the only option. Unfortunately we don't know what will be necessary to build the next basis. What matters is experimentation and the building of new businesses. I can't offer specific recommendations as there is no recipe book for how to create new markets.

    For your views, who is much better so far since the trial has begun
    in the US. Samsung or Apple?

    I cannot comment on this. Performance in court can only be judged by those present and I'm sure everybody present disagrees.

    You think Apple is enjoying its so-called a homeground advantage
    for the trial and is there any possibility that the issue to go for
    the highest court in the US. My Samsung contacts say that's the
    possibility, though.

    Again, I don't have an opinion on legal matters. Broadly speaking, IP litigation is similar to playing the lottery.

    Need your perspectives about Google's support for Samsung. Google
    confirms its supports for Samsung for an united front against Apple
    because the fight between Samsung and Apple is a kind of version that
    represents Google and Apple fight.
    Any comments about that?

    I believe Google does support Samsung. I question however how this relationship will develop over time. I attached below commentary from a researcher at Deutsche Bank on Android in China. I think it has some clues about how Google treats its partners.

    What are pre-conditions before Samsung making an action to sign a
    peace treaty with Apple?

    It depends on the motives behind Apple's actions. I think they want to see a "no copying" rule. They don't mind competition and Android could be a help in the long run by moving users from feature phones to basic smartphones which could later be upgraded to Apple phones. But what I think they want is to signal to others that direct copying is unacceptable. Essentially, the work of their designers is very important to them and copying destroys [the designers'] incentives to do breakthrough products.

    ---

    See also: Who Cares If Samsung Copied Apple? by James Allworth - Harvard Business Review
  2. International Tablet of Mystery

    Research · 31 comments

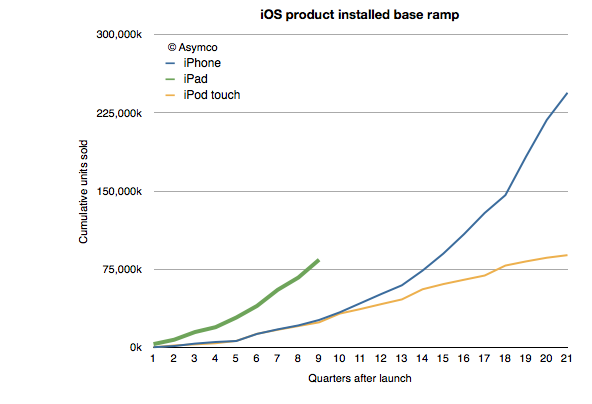
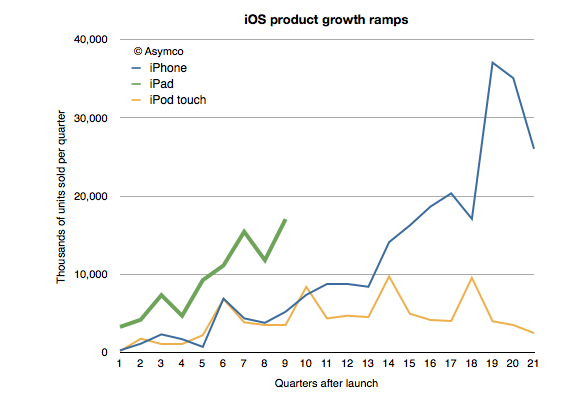
    One of the remarkable patterns associated with the iPad has been its growth rate. Looking at the ramp of the product relative to the iPhone and iPod touch reflects this sense of raised expectations:


    At the same point in time, and adjusting for seasonality the iPad is outselling the iPhone by a factor of 3 and the iPod touch by a factor of about 5. This is also reflected in the installed base of devices, where the 84 million iPads sold through its first nine quarters is more than three times the iPhone base at a similar point in time.

    Of course, the world of 2012 is different than the one from 2009 when 25 million iPhone sold. iPhones are available in far more points of sale and to many more buyers world-wide. But the interesting contrast is between the iPad and the iPod touch.

    I've always maintained that the dynamic difference between the iPad and the iPhone is that it's unrestrained (and unsupported) by the operator channel and all that it implies. The iPad is a pure computing product whose means of communication is unregulated. That means transparency in pricing and transparency in distribution.

    But so is the iPod touch.

    The iPod touch is a "nano iPad" (or as detractors put it, the converse of that.) So shouldn't the iPod touch behave as the iPad?

    We don't know exactly how the iPod touch behaves. We don't have specific figures on its sales. What you see in the charts above are my estimates for the iPod touch based on company statements that "about/above 50%" of iPods are touch versions. That and the cumulative sales totals that are occasionally reported.

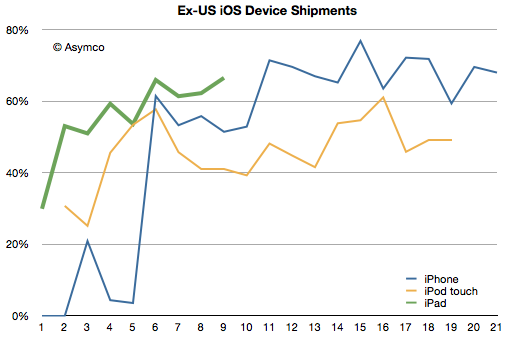
    However, we have received an unexpected morsel of data from the Samsung v. Apple trial that may help characterize the two products: US sales data. Having the US data and knowing/estimating the global data gives us an estimate of the international (ex-US) sales for all three products.

    I indexed the three products to measuring quarters since launch. The pattern here is that the iPad diverges from the iPod touch in its international appeal. Since the iPad expanded internationally even faster than the iPhone, the issue is not only one of rapidity in appeal but also a qualitative difference.  The iPod touch seems to have stabilized at 50% non-US sales while the iPhone is between 60% and 80% outside the US.

    The iPad reached 60% non-US sales in its first year. Its last quarter was 70% outside the US.

    So what's going on?

    The characteristic value of the iPad is in its appeal to "computing non-consumers". Computing has come to mean media consumption, education, communication and entertainment. These jobs to be done are casually done with much more ease on an iPad. The iPod touch can do these jobs as well, but not as comfortably. The iPod touch is "absorbable" by younger consumers and typically they have their hiring done by their parents. Those parents are less likely to indulge where incomes are lower.

    But the universal appeal of the iPad is evident in its global visibility. Like the tasks it performs, the iPad itself is becoming less of a mystery.

  3. Are Apple stores overstaffed?

    Research · 45 comments

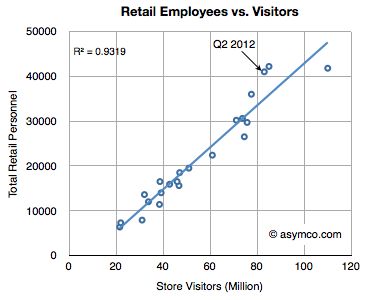
    ifoAppleStore's Gary Allen alleges that John Browett, head of Apple Retail, felt the stores were "too bloated". He cites "numerous tipsters" that Browett ordered a reduction in the number of employees. As the information on employees and visitors is public, we can quickly test the assumption.

    The following graph shows the relationship between Retail employees and Visitors on a global basis.

    The total figure for the last quarter was 41,000 employees for 83 million visitors. This is above the expected ratio as shown by the line shown in the graph. Reversion to that line would imply that about 35,000 employees should have sufficed during that quarter.

    However, Apple's business is cyclical and employment is not--or at least not on the same frequency of cycle.

    During a slow, transition quarter, there will be over-employment and during a rush holiday period there would be under-employment. Consider the right-most point in the chart. It represents Q4 2011 when there were 110 million visitors and only 800 more personnel than during the last quarter.

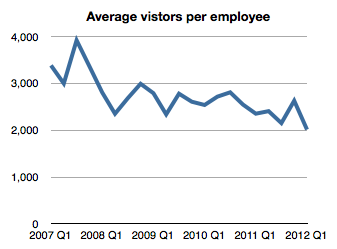
    Overall, this ratio of visitors per employee has been relatively steady, though declining.

    Perhaps the company should check this decline. Perhaps the company has not been able to match demand with supply as well during the last six months. Perhaps they are overstaffed. However, I doubt that there has been a decision to reduce the overall level of service offered. Or that service is not paramount.

    The accusation that employment is being sacrificed for the sake of profits seems disingenuous. The stores were never designed as a profit center. They have to be profitable in the sense that they have to justify themselves. But we need to recognize that they rely on a brand and product mix that is unique to that store. In return, they are designed to sustain that brand and offer a service rather than merely a sales channel.

    For the head of the division to misidentify this fundamental purpose for the operation would be catastrophic and I would expect a lot more evidence to support such an extraordinary claim.

  4. American exceptionalism

    Research · 45 comments

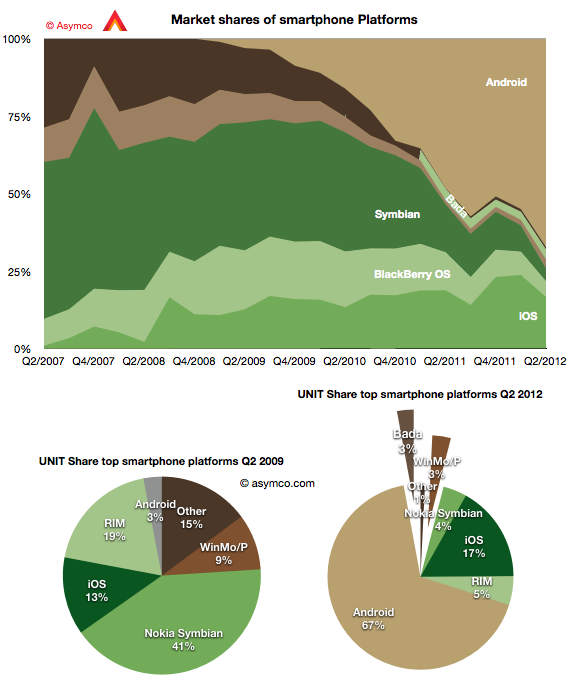
    The second quarter showed continuing growth for Android with 19 points of share growth from a year ago. Only Windows Phone showed a gain y/y in share up 1.6 points to about 3%. In the same time, Bada lost half a point, iOS lost 2.1 points, RIM lost 7.2, Symbian 11.4.

    The result is shown in the graph below:

    I also show a "before-and-after" pair of pie charts which show the difference in smartphone platform market share from the same quarter three years ago. Android went from 3% share to 67% while Symbian went from 41% to 4% and RIM went from 19% to 5%. iOS increased its share from 13% to 17%.

    If this trend continues Android could reach 50% of all phones sold in a few years. That's a run rate of 200 million per quarter. And it's likely that 100 million of those will be shipped by Chinese vendors.

    However, looking at the global picture can also miss some important trends in local markets. Had one looked at the global smartphone business in 2005, the conclusion would have been that Symbian would be the dominant platform in perpetuity.

    What affected the global market was a change in the US: the launch of iOS and thereafter of Android. The US, a smartphone backwater until then, became the most vibrant market and today it's the most penetrated and has the highest ratio of smart to non-smart of any of the major regions.

    The curious thing about this vast market is that it's still not truly open. There are technology and political reasons why some platforms are permitted to sell in one region or not. The iPhone is not available on either the largest Chinese operator or on the largest Japanese one. It's largely absent from India because of distribution (i.e. subsidy) and much of South America. Even in the US, the iPhone is still, after five years, not available on one of the top four operators and has only reached another less than a year ago.

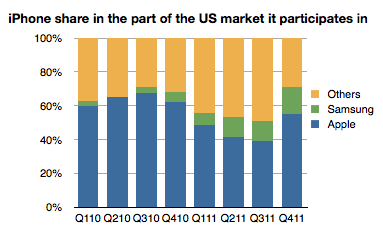
    What intrigues me is what would the market look like if distribution were not an issue. What if there was equal choice to all buyers. We can't test this question directly but we can ask. But there is some pattern we can look at in the US data. Thanks to recent revelations at the Samsung vs. Apple trial we can see the effect of increasing distribution in the US.

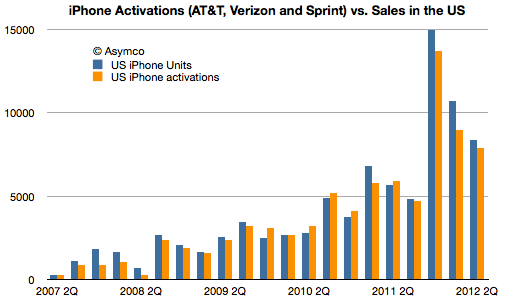
    The data on smartphone market share by carrier can be blended with data from carriers about iPhone activations (which are a proxy for sales, see note below) to give a more precise figure of market share in markets where iPhone participates.

    For example, when the iPhone was only available on AT&T, one could measure iPhone market share vs. the global smartphone market, or the US smartphone market or within AT&T alone. Some assumed that the AT&T share would be reduced once the product would become available on Verizon or other US carriers. However there was no appreciable drop. Share in Q4 2010 was 63% at AT&T and it was 63% a year later after the iPhone was available for four quarters at Verizon.

    So the share of iPhone within those operators which carry it tells a story independent of distribution.

    The following graph shows the share of the iPhone vs. Samsung in the market defined by its availability. (I.e. the volumes of smartphones sold by AT&T throughout the time period, Verizon Q1 2011 to end and Sprint in Q4 '11).

    The share of iPhone thus defined shows a slight decline but it's an overall number that is remarkably resilient as distribution increases and is remarkably high overall. Note that globally, the iPhone gets only about 17% share of smartphones--a value that has not varied greatly since mid 2009.

    So at least in the US, on carriers where it's available, the iPhone is holding on to a significant share. In a global market it's expanding distribution but not yet covering the world. As a consequence it's keeping up with overall market growth and staying between 17% and 20% share.

    The big question is what will happen if and when its availability matches that of Android in terms of points of sale. Or even that of BlackBerry or Symbian. Is America a different market from the rest of the world? It was different in being isolated while Symbian roamed globally. It was different in being a launch platform for BlackBerry and then iOS and then Android. But now that iPhone is beginning to be widely available there, will it be exceptional in how it rewards Apple?

    ---

    Note:

    1. Activations data can be seen next to Apple's testimony of US sales in the following graph. Note that more phones were sold by Apple than were activated in total of the life of the product. 86 million sold and 80 million activated. This implies that an analysis based on activations undercounts the iPhone. 
  5. How many smartphones did Samsung ship in Q2?

    Research · 62 comments

    50.2 million.

    That's the estimate from IDC. So why bother asking?

    Because that is an estimate. Of the 104 million Android phones shipped in the quarter (itself an estimate from another, possibly different methodology), I could only account for 7 million actually reported. That figure comes from a close reading of an investor presentation from Sony. HTC does not report their shipment numbers. It stopped some time late last year. Neither does Motorola now that it's a part of Google. Huawei is silent except for setting targets and ZTE published a press release citing IDC's estimate of its own shipments.

    But most glaring of all is the absence of any mention by Samsung of its performance. The company stopped reporting any data on either overall phone shipments or of smartphones within that total since Q3 2011. We may have been able to estimate Samsung if we had more competitor actuals, allowing us to back into a figure. But we don't.[1]

    Which leaves us with IDC's estimate[2]. But the problem is that since the industry is growing so quickly it is very sensitive to assumptions. Consider how difficult it is for consensus estimates for Apple's iPhone shipments to come near the actuals--and that's for one quarter, and knowing all the previous quarters with precision. The absence of visibility into the assumptions made by market analysts (or their methods) should lower confidence in the results.

    Consider that IDC specifies 50.2 million Samsung smartphones, implying an accuracy down to 100,000 units. Is this accuracy believable?

    There is reason for doubt.

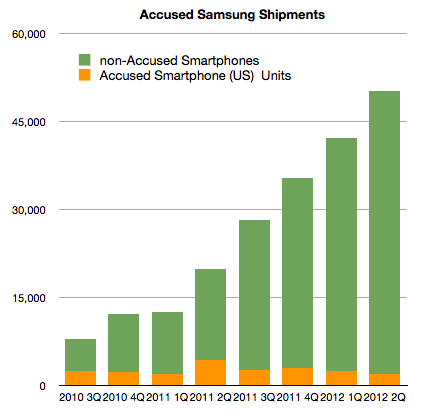
    I start with the following graph:

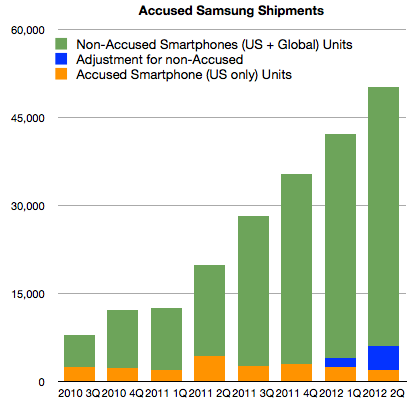
    It shows the estimates for Samsung global shipments (latter four quarters are estimates without the benefit of company reports.) I separated the component of shipments that Samsung reported as part of its submission to the Samsung v. Apple trial in California. Note that this (orange) segment consists of most US smartphone shipments. It's not all US Samsung shipments. It notably excludes the Note, the latest Nexus and the Galaxy SIII.

    Without these "non-accused" phones, it would appear that Samsung's US volumes dropped to 4% of global totals from a 10% average[3]. In order to return to 10%, the US totals would need to be adjusted as shown below:


    I added 1.5 million units in Q1 and 4 million units in Q2 (to account for Galaxy SIII).

    So far this seems consistent with the total estimated global shipments of 50.2 million from IDC. US units would result in 12% of global shipments.

    However, there is more data we can test against. First, we are also given pricing for the US phone portfolio, or at least we have revenue per unit sold. This allows us to get an idea of what revenues can be obtained for the smartphones in the US, and possibly world-wide[4]. Knowing prices for smartphones and knowing global sales (which Samsung reports) and finally knowing global total phone shipments allows us to price the average non-smart phone.

    Excluding the non-accused smartphones, the average revenue per smartphone in the US for Samsung in Q2 was $339. Adding in the estimated Galaxy SIII (4 million) at an average price of $470 gives a new "ASP" of $413.

    This is where the analysis goes off the rails.

    If we assume the global ASP is equal to the US ASP and knowing everything else about the mix of smartphones (54% of total) and revenues (as reported) yields a negative ASP for feature phones. Assuming the revenue figure is correct, either the number of smartphones is wrong (50.2 million) or the global ASP ($413) is wrong. The total phone number is also an analyst estimate which can be called into question.

    There are many assumptions being multiplied here so I have very low confidence in the result, but we should ask "what do you need to believe" in order for the 50.2 million figure to be real. The following scenario for example has to be true:

    1. Global Samsung phone shipments total 93 million units (which means 42.8 million feature phones sold as well as the 50.2 million smartphones).
    2. 6 million smartphones shipped into the US, equivalent to about 50% increase y/y, roughly in-line with market growth
    3. 4 million Galaxy SIII shipped (but not necessarily sold through) at an ASP of $450. This results in a US total smartphone ASP of $413
    4. The global smartphone ASP is significantly lower (at 80% of the US or $330)
    5. Global revenues of $18.14 billion is essentially all from phones
    6. Global feature phones will have an average price of $36

    If these conditions are met then it's possible that 50.2 million Samsung smartphones did ship.

    The figure for feature phone ASP is difficult to accept as it would be lower than Nokia's. Also, the low global smartphone ASP is also difficult to accept but it might be possible to find a scenario with the above variables which makes the 50.2 million figure believable.

    Unfortunately this is an unsatisfying analysis. I could propose another figure to answer the question in the title, based perhaps on more "believable" assumptions. But I have no means to defend my assumptions. The only option I have remaining is to caution that the total smartphones shipment estimate for Samsung remains precarious. The new evidence from the US trial places more doubt on it but it is not enough to disqualify it entirely.

    ---

    Notes:

    1. This cone of silence over 93% of the most popular mobile platform is somewhat puzzling in contrast to the perfect information we are used to having about iOS, BlackBerry and even Symbian. It seems that the more open a platform, the less is revealed about its market performance. This extends to the licensed Windows Phone whose shipments are only revealed through Nokia's reporting of Lumia shipments.
    2. In the PC market, vendors also selectively publish their units. The norm is, however, not to. As a result IDC et. al. are the only sources for global market data. However, the PC market can be sampled more easily than the phone market. PC retail measurement methods are more reliable compared with all the points of sale for phones.
    3. Note that Apple sells about 30% of iPhones in the US.
    4. Apple's pricing world-wide is very consistent with pricing in the US which makes sense from a channel management point of view. One would not want to create incentives for cross-border arbitrage of phones.
  6. Samsung's basis of competition

    Research · 69 comments

    Samsung has been selling smartphones for a relatively short time. Although the company sold Windows Mobile, Linux and PalmOS during the last decade, it did not gain significant volumes until it began selling Android phones in 2010 with strong operator support.

    That support was substantial in the US. The company crashed the Android party in mid 2010 with its Galaxy brand. Trial evidence reveals that the sales level for Galaxy S1 series phones burst out of the gate taking Samsung from 90k units to 2.5 million units in one quarter.

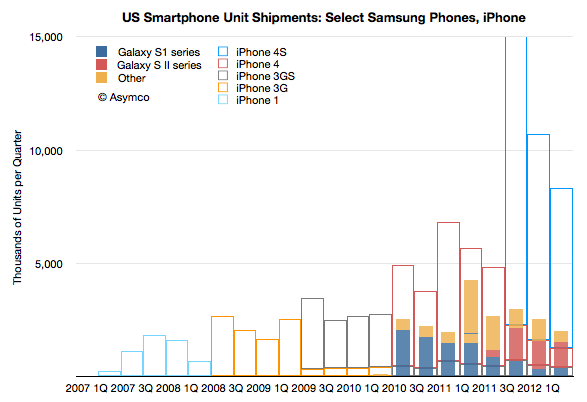
    The following graph shows the unit shipments recorded by Samsung for a set of US smartphones.

    Note that the profile of sales volume shows a cyclicality with respect to product launches. Each new generation overlaps with previous generations and "fills in" while the older generation product tails off in sales. This is standard portfolio strategy. It also shows the cycle time of launches is approximately four quarters. As the S1 was four quarters old, the SII launched and the SIII follows after four quarters of SII.

    What is surprising is that the overall sales volume is not growing. At least for the products catalogued (which exclude the Note) growth for the last four quarters has been: 5%, 34%, 31%, -53%. These are in stark contrast to the iPhone pattern shown in the outline bars behind Samsung's.

    The iPhone ramped slowly in 2007 and 2008 and has been showing remarkable generational growth.

    Perhaps it's still early and Samsung SIII product will ramp up as the contemporary iPhones do, but if it doesn't we have entertain the possibility that the iPhone does not compete along the same basis.

    What does it mean to compete on a different basis?

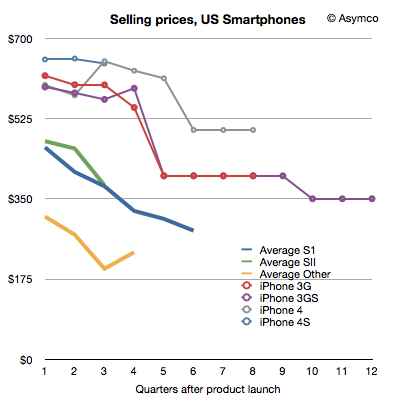
    The basis of competition is the aspect of an offering for which a customer is willing to pay a premium price. It's hard to know (or to put your finger on) what the basis actually is, but we can test whether it's the same by measuring whether two products capture prices the same way. If one product that seems to resemble another can obtain price advantage consistently, then perhaps it's being bought for a different reason.

    To test this, I produced the following chart showing the prices that Samsung's phones have been able to capture through their lifetimes; and the same for the iPhone.


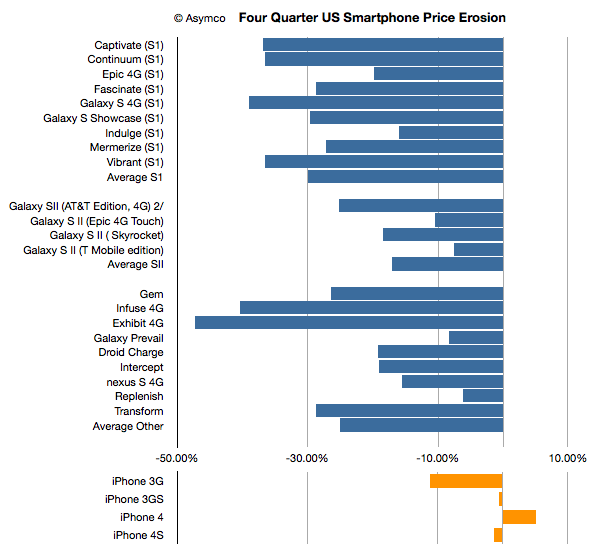
    I've narrowed the analysis to the first four quarters and summarized the price erosion across all the products as well:


    [Note: iPhone 4S, Skyrocket, T-Mobile Galaxy SII showing only three quarters]

    As mentioned, it's still early perhaps, but the pattern for the iPhone has been different.

    Samsung's pattern is not unusual. I've seen similar pattern for almost all Nokia products. Prices drop. It's a standard industry phenomenon.

    Therefore the question is not perhaps what is Samsung's basis of competition: it's the same as the overall phone industry. The question is what is the basis of competition for the iPhone.

  7. Apple Store Operational Economics

    Research · 18 comments

    In a footnote to my last post on Apple Retail (The face and the brand) I used data on operating performance from Apple and an assumption about employee salaries (which turned out to be low) to estimate that about 7% of Apple store sales are spent on "cost of service" or the operational expenses, which consist of mostly employee salaries.

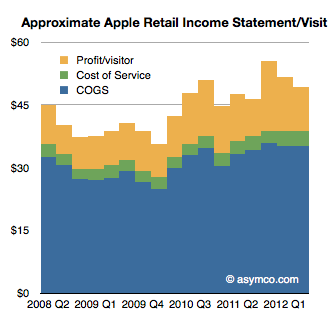
    An updated view of this store income statement (on a per-visitor basis) is shown below:

    To summarize the logic, during the last quarter Apple received $49.2 in store revenues per visitor. Knowing the retail profit ($10.46/visitor) and knowing the time spent per visitor (14 minutes, itself derived from the number of full time equivalent employees--41,000 or 112 per store) and assuming the cost of that time in employee salaries ($15/hr including benefits), gives us an estimate of the service cost ($3.55/visitor) and therefore the cost of goods sold ($35.2/visitor).

    Now I want to focus on this ratio of service cost/sales which turns out to be about 7%[1] and ask whether this is significant or revealing.

    In order to do this we have to understand that most stores, especially electronic goods retailers, don't spend this much on salaries. They do spend quite a bit on commissions however. From a post on the subject, I gathered the following commission rates for various retailers:

    • Phone stores: $25 for activations, 10% of accessory sales
    • Beauty/handbags at department store counters: 3% to 5%
    • Shoes, appliances, electronics: 8 to 10%
    • Furniture: 2% to 6% (low rate includes salary)
    • Real estate: 2.5% to 3% (no salary)
    • Car salesmen: 30% after dealer costs

    Now 7% to 10% that Apple spends on salaries starts to make some sense, economically. It's roughly equivalent to what another retailer might spend out of their sales on the help.

    The difference is that Apple does not pay commissions and that cost is spread over a far larger headcount of staff. Roughly speaking it implies that Apple hires five times as many employees (consider how many people you might see in an Apple store where the average is 112 and in a similarly sized Polo Ralph Lauren outlet) as would be needed to "just sell stuff."

    The trade-off seems to be that Apple will pay a modest wage to a hundred employees rather than a commission to a handful. The trade-off is pretty even since the profits would be the same.

    But they wouldn't be.

    The difference is that what the customer buys is different. Or, put another way, a store bursting with staff is hired by the customer to do a different job than a store filled with a handful of "salesmen".

    Even though the economic ratios are similar, the result is that visitors at an Apple store are made to feel they're getting a service rather than being sold a product.

    And that's the key to there being very many visitors. And, incidentally, they happen to buy more things. And also incidentally they come to value the brand more.

    It also leads to a virtuous cycle. More visitors means more visibility for the store and that leads to more visitors still, and that leads to more employees.

    So a simple decision to hire in proportion of a level of service rather than a level of sales leads to completely different bottom line results.

    That's not to say that this model is transplantable. The entire system depends on having the right goods to sell and the right brand image. But if Apple had all those things and imposed a commission structure in its stores, one can be fairly certain that sales would not be as spectacular and growth itself would suffer.

    ---

    Note:

    1. Again, this is probably quite an under-estimate and the actual cost of service might range up to 10%.
  8. Exclusive interview with Asymco's Horace Dediu | The Tech Block

    Research · 18 comments

    Horace, you spent nearly a decade at Nokia, where you worked as a business development manager and industry analyst. Did you foresee their current, increasingly dire situation?

    I did not see an explicit downfall. I anticipated difficult times ahead and a deep crisis. My view of what would happen was published as my first Asymco post.

    What led you to start Asymco?

    I started a consulting company which I hoped would generate leads through a blog. The blog became far more exciting than consulting and it became my primary focus after about one year. I had no ambition to write for a living or to be a “blogger”. I did not anticipate there would be any interest on the topic I wrote [about] beyond a handful of people. In that regard, things played out as they do at most start-ups: what you end up doing is not anywhere near the target you aimed at.

    Apple’s clearly one of your favorite topics. What about the company appeals to you?

    Business education is predicated on storytelling, also known as the case method. Business management is not a discipline that has “axioms” defining basic truths, or if it does, they change frequently. Therefore business education (i.e. the MBA) is the equivalent of people teaching each other by telling stories around a campfire. The best stories get repeated more often and are better ‘teaching tools’. So it is with Apple. It’s a great medium for story telling because people can see the stories unfolding in real time or at least within their lifetimes. They are not about a distant past or an abstract industry. There is also a lot of passion around the brand, both positive and negative and so it leads to more attention.

    Read more here: Exclusive interview with Asymco's Horace Dediu | The Tech Block.

  9. Measuring iOS as a gaming platform

    Research · 35 comments

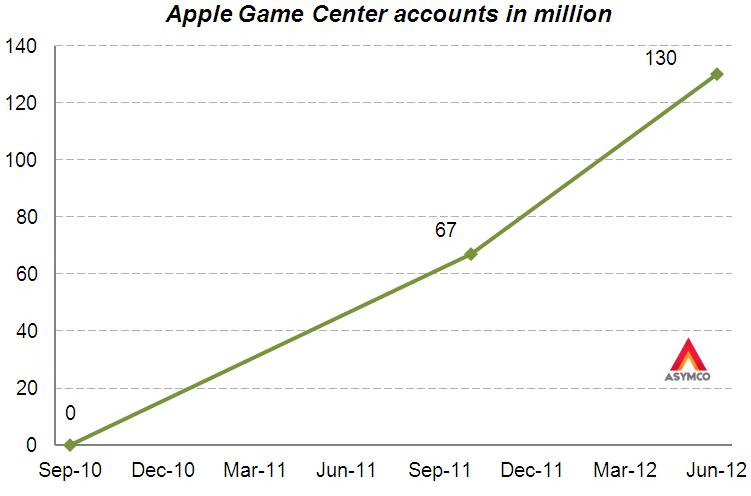
    At this year's WWDC Apple offered an update on Game Center accounts. The data we have so far is shown in the following graph.

    Before being acquired, another network, OpenFeint, announced 180 million iOS accounts in October 2011. Another figure to consider is the 40 million subscribers to Xbox Live (out of 66 million Xbox users). This subscriber base is paying for a service (about $1 billion per year) so it's not the same as the free Game Center model.

    Rather than being a revenue source, Game Center is designed to engage users and to capture usage information. It also lets us gauge gaming "consumption" on iOS devices. That itself allows us to contemplate it as a gaming platform vis-à-vis alternate platforms.

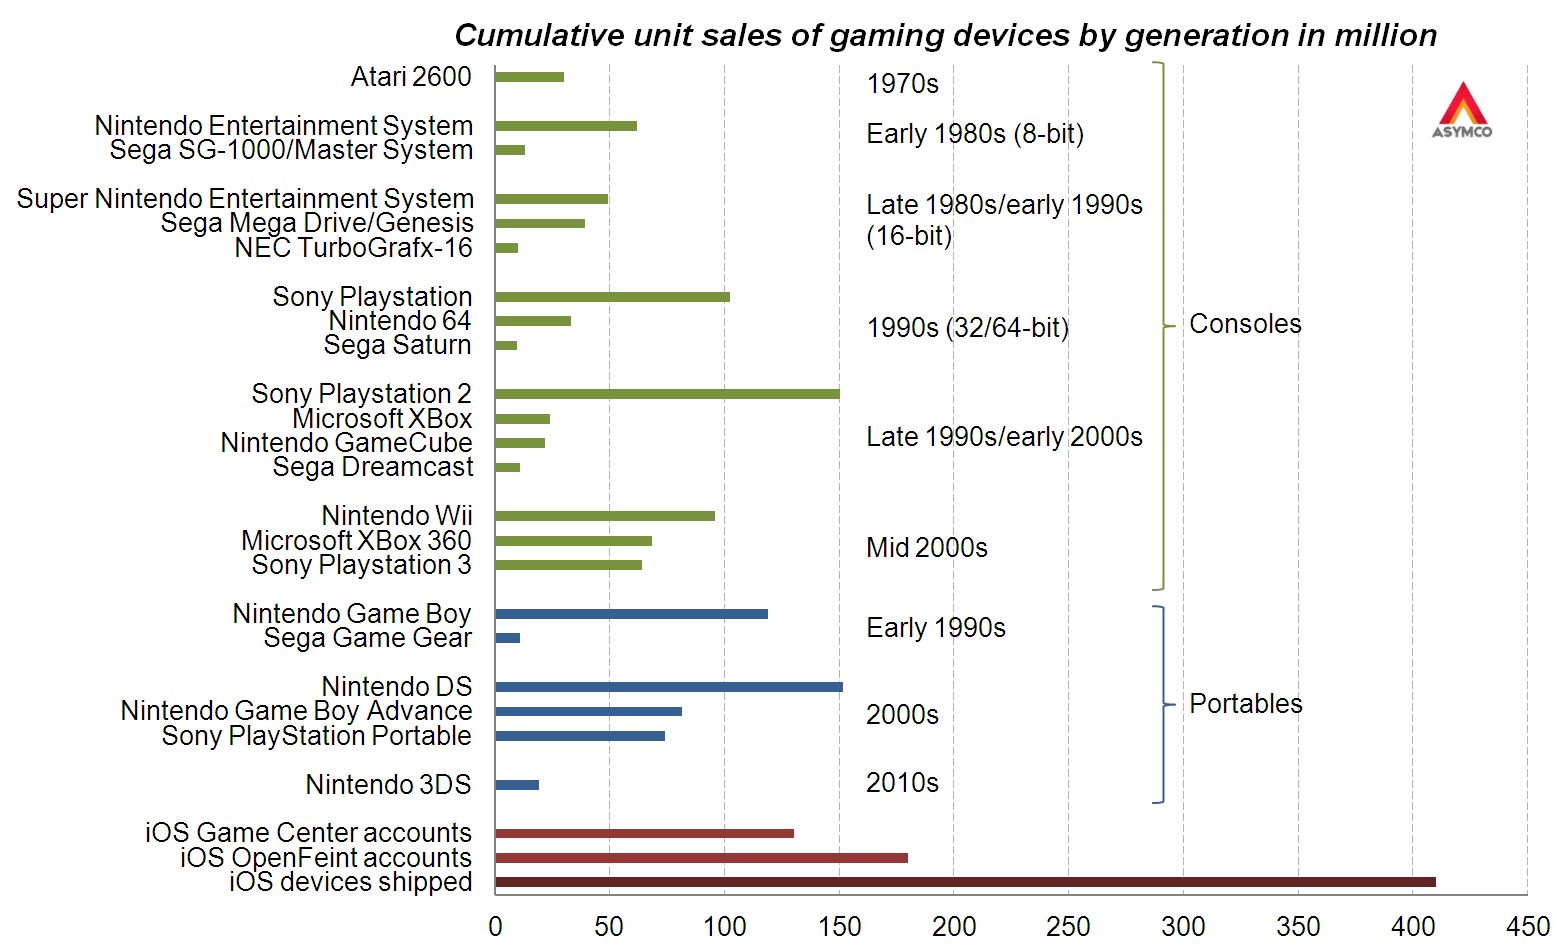
    To consider the figure as a proxy of penetration and engagement, the graphic below shows cumulative sales of gaming devices.[1]

    Here are some observations:

    • There is a pattern of turnover of market participants
    • Each console "generation" had a clear market leader
    • The best-selling gaming device was the Nintendo DS closely followed by the PlayStation 2 [2]
    • Considering the 130 million Game Center accounts, iOS is already the third largest gaming platform
    • Furthermore, considering the OpenFeint iOS figure of 180 million accounts announced in 2011, iOS has already surpassed the cumulative sales figures for the Nintendo DS
    • No gaming device has ever reached the 200 million mark
    • At the current growth rate the number of Game Center accounts will surpass 200 million before the year end

    Apple cites the number of games, downloads and payments to developers as evidence of ecosystem health and growth. The figure of Game Center accounts is yet another indicator. It shows growth in and of itself, but it also has the side effect of offering comparative measurement of performance. That measurement compares favorably with other game platforms.

    The economics are different but they always are when a disruption takes root.

    ---

    Notes:

    1. Based on reported cumulative sales (Wikipedia), excluding gaming devices with less than 10 million cumulative sales (excludes for example PlayStation Vita), excludes also “home computers” due to missing reported figures
    2. This Wikipedia article contradicts the previous.
  10. How many iPhone ``5''s will be sold?

    Research · 77 comments

    Phil Schiller stated (under oath) that when assessing sales for a new model of the iPhone, Apple used an easy shorthand:

    Each new generation sold approximately equal to all previous generations combined.

    That's a helpful gauge. Did it hold and will it continue to hold?

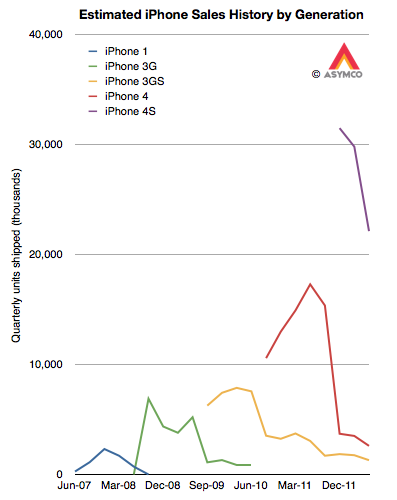
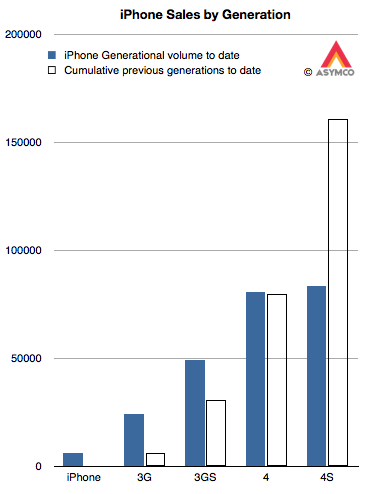
    In order to test this rule of thumb we need to know generational sales. Although we know overall unit sales for a given quarter, since Apple has been selling several versions simultaneously, we need to make some guesses about the ratio of generations in the mix. My guess is about 10% for 3G vs. 90% 3GS and 5% 3GS vs. 10% 4 vs. 85% 4S. That results in the following pattern:

    The cumulative totals for these generations can then be generated and they appear as follows:

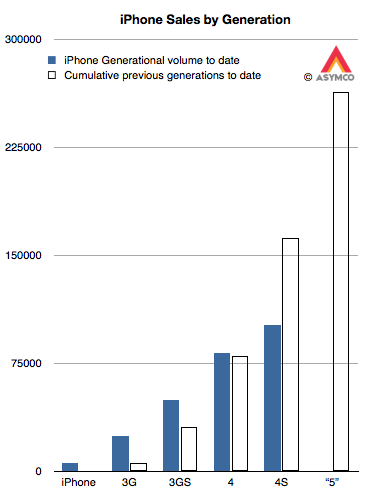
    The solid bars are the shipments for each generation (to date) and the outlined bars are the cumulative shipments of all prior generations. The assumptions show that:

    • The 3G easily outsold the original iPhone. In fact, it sold nearly four times as many.
    • The 3GS also handily beat the 3G+original total by a factor of 1.6
    • The 4 also beat the 3GS+3G+original. As the 4 may continue to sell into the future, the beat will only grow larger.
    • The 4S is only half way through beating  the 4+3GS+3G+original. Assuming the current quarter's sales roughly equal the last quarter's, the total for 4S will reach two thirds of the sum of the previous generations (i.e. 100 million) by the end of September. Bearing in mind that the 4S is likely to remain in production at least one more year means it has a potential to come close to the target of 162 million.

    This leaves us with the question of how many iPhone "5"s will sell. As it stands today, the cumulative total would have to be greater than 263 million units (including assumptions for the current quarter.) That target is shown below:

    Is that a reasonable target?

    Unfortunately, this is a moving target. As the 4S (and maybe 4) remain in production, the target continues to increase with time. However, we can still take a stab at this.

    Recall the analysis of production based on budgeted CapEx spending. It resulted in a best guess of about 165 million iOS units sold in the following two quarters. I further forecast iPhones in isolation to be about 102 million over the same period. Taking that forecast forward and assuming a 60% growth rate,  I currently have about 200 million iPhones over the next twelve months. If 85% of those are the next generation, that yields about 170 million iPhone "5"s through mid 2013.

    This is well short of a target of 265 million. But that's only over the next four quarters. If the iPhone "5" remains in production for at least as long as the 3GS then it might cross 200 million. There is also the question of whether the "mix" will begin to favor the older generations more. If that's the case, we might see version "5" meet its target.

    Underlying all this is the question of a change in strategy toward more penetration (vs. current skimming.)  That might allow for sustaining the 100% historic growth rate. If so then Apple will easily sell 250 million iPhone "5"s.

  11. The biggest loser

    Research · 36 comments

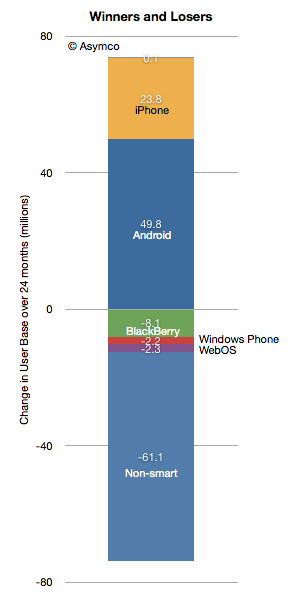
    According to data from comScore, in the past 24 months 50 million Americans became Android phone users. In the same time frame Apple added 24 million iPhone users. As I mentioned in my Asymmetric Competition post, it would be unwise to consider this data in isolation. Consider the following graph showing the net change in users in the US.

    Android and iPhone grew mostly at the expense of non-smart users. The BlackBerry lost 8.1 million users and all the others only lost about 4.5 million.

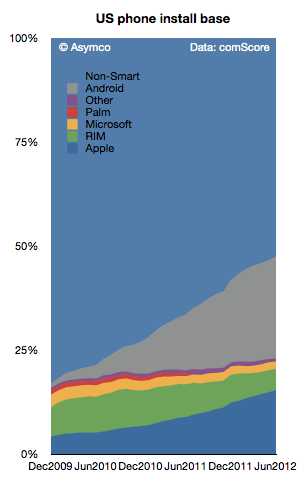
    With penetration at 50% it's still impressive that there is so little "churn" between platforms. In fact, measuring churn as the net platform user loss as a percent of all smartphone users, we get something less than 1% per month.

    The smartphone competition is still primarily with non-consumption.

    That will change at some point when smartphone penetration (shown below) will begin to saturate. The basis of competition will have to shift from converting non-smart users to converting users of other platforms while maintaining one's own user base.

    The market has not experienced this sort of rivalry on a wide scale. The defections of BlackBerry and Symbian users are relatively rare events.