Asymco

Asymmetric Intelligence

Latest from Asymco

  1. The parable of Nintendo

    Research · 100 comments

    With the launch of the Wii console, Nintendo averted disaster. When the Wii launched in late 2006 Nintendo had been facing the simultaneous attack from the "seventh generation" Xbox 360 which launched a year earlier as well as the PlayStation 3, both of which set as their bases of competition 3D graphics at HD resolutions. Many wrote off the company and called the console market a two horse race.

    Then, in what seemed a desperate downward leap, the Wii was launched into a different trajectory. It addressed non-consumers with a new, more intuitive controller and standard resolution rather than competing for hardcore gamers with more power and richer graphics.

    Because the Wii was asymmetric and addressed non-consumption rather than trying to be a "better" console in what was becoming a horsepower race, Nintendo expanded the console market. Its innovation was interesting enough that many hard core gamers used the console in addition to a PS3 or Xbox and many non-gamers bought it as their first console.

    The result is that 95 million Wii's have been sold vs. 66 million Xbox 360's and 62 million PS3's.

    The effect of the Wii introduction on Nintendo's console unit sales is shown below (pink line).
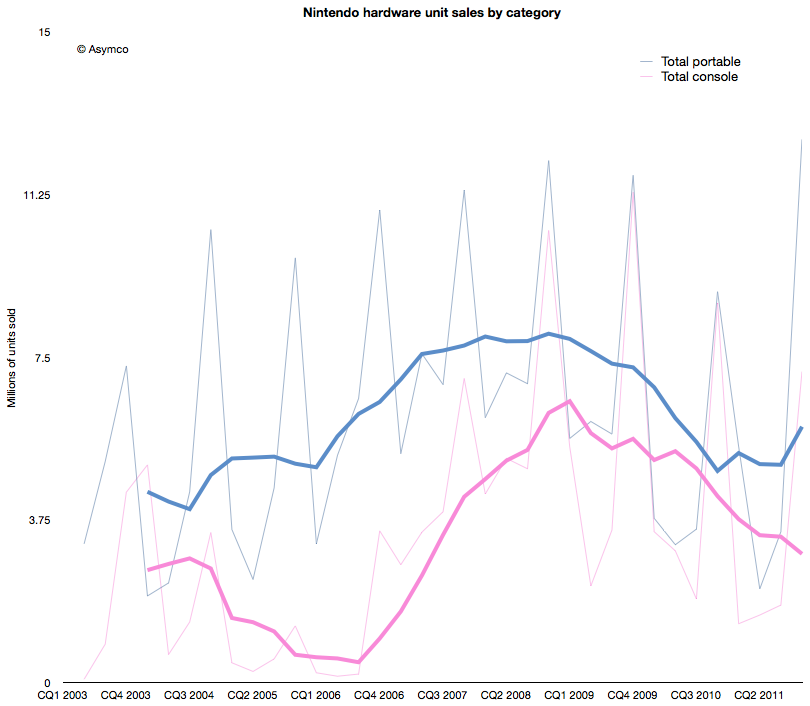
    The graph above shows that the growth from Wii has stopped. In fact, the console has been in decline since early 2009. Fortunately for Nintendo, the company also developed a mobile strategy. Learning from its Game Boy device, its DS series of portable game consoles allowed the company to diversify its portfolio. The graph also shows the total portable units sold in blue.

    However, this strategy has not been enough to protect the company from the disruptive effect of mobile computing. As the following chart shows, each new generation of portable from Nintendo has failed to break out of a general pattern of overall decline.
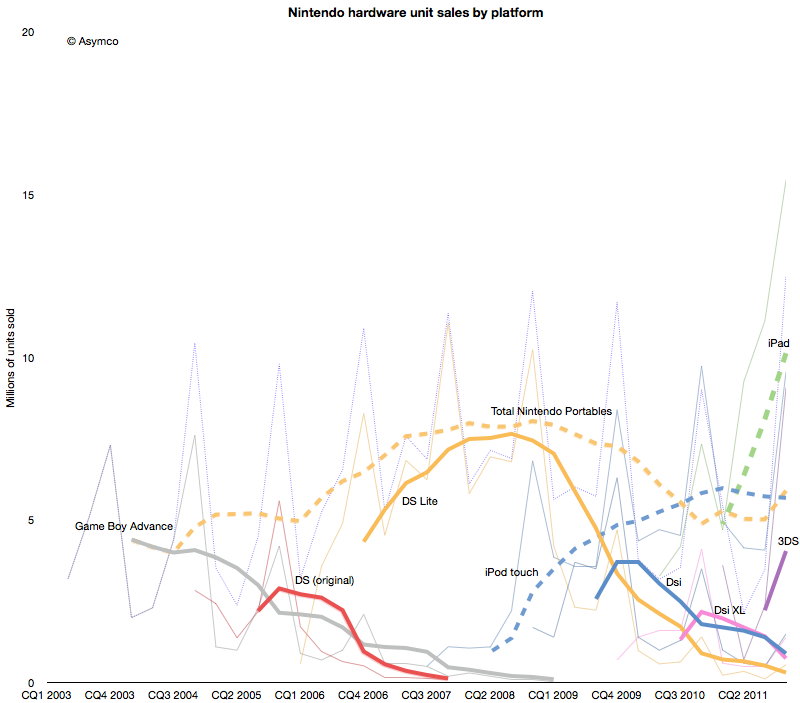
     

    Contrast the DS product patterns with the iPod touch and iPad--multi-purpose products whose game functionality is "good enough" but whose communications and general-purpose app catalogs are re-defining the basis of competition yet again.

    Nintendo bet on the 3DS to reboot the franchise. The 3DS product does show the characteristic initial spike in adoption but the level it launched at is far lower  than the level of the iPad. Nintendo has a big hill to climb to even recover the volumes it held in 2009. In contrast, the usurper Apple's volumes are doubling each year.

    When products are compared as "ramps" in terms of growth post-launch the story becomes even clearer.
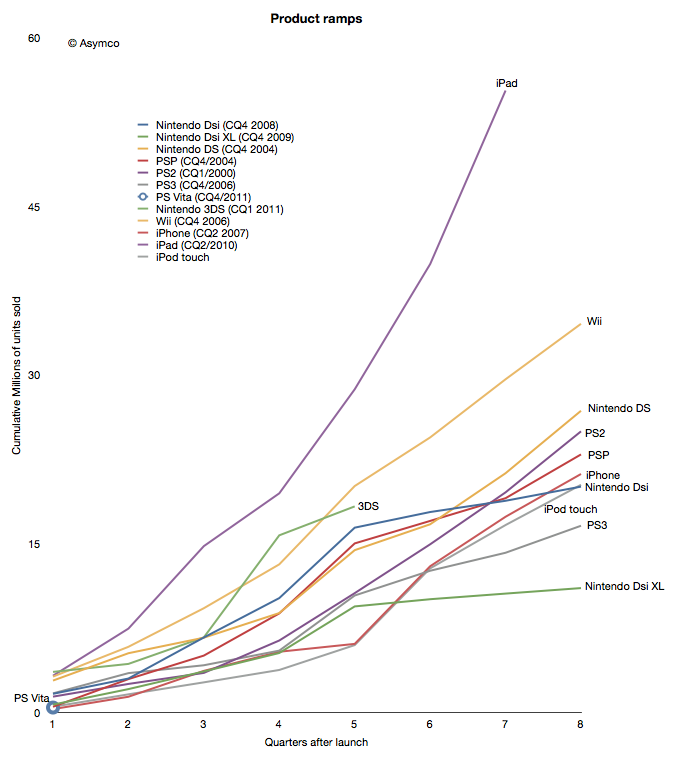
    Although the iPhone and iPod touch ramped in similar ways[1] to the gaming platforms, iPad took an entirely different path. The 3DS benefited temporarily from a price cut but it seems to be returning to a well-worn trajectory.

    The data points a bleak picture for Nintendo. The Wii was a success due to its competitiveness vs. non-consumption of gaming. But another low end disruption took hold in 2007. Good enough games on phones and mobile computers are taking consumption away from dedicated consoles, both fixed and mobile.

    In addition, the rate at which game experiences are improving on iOS imply that they will overtake the "quality" of consoles in the not too distant future. Differences in distribution models also guarantee lower pricing for software for end users and enabling a far larger catalog of titles.[2]

    This may sound like another story of fortune gained and fortune lost. The inevitable "what goes up must come down" aphorism. We become used to this pattern and assume it to be axiomatic. But there are causes for each success and causes for each failure.

    The lesson here is that a company that disrupts does not necessarily survive. Long term survival depends on the ability for serial disruption. Serial disruption is an uncomfortable state for an organization to exist in. As the story above shows, disruptions are usually enabled by "desperate" necessity. Desperation is not something management is trained to aspire for.

    What management strives for is steady state satisfaction and predictability from intelligent planning.

    ---

    Notes:

    1. Though the iPhone ramp matched the consoles, the growth for the iPhone is persisting at 100% y/y five years into the product. This means it is outstripping all console installed bases by at least a factor of 2.
    2. The catalog is not only broad but deep in the sense that there are many new game concepts and experiments being tried. The app store is a vast testbed for game and entertainment ideas.
  2. Estimates for Apple's second fiscal 2012 quarter

    Research · 74 comments

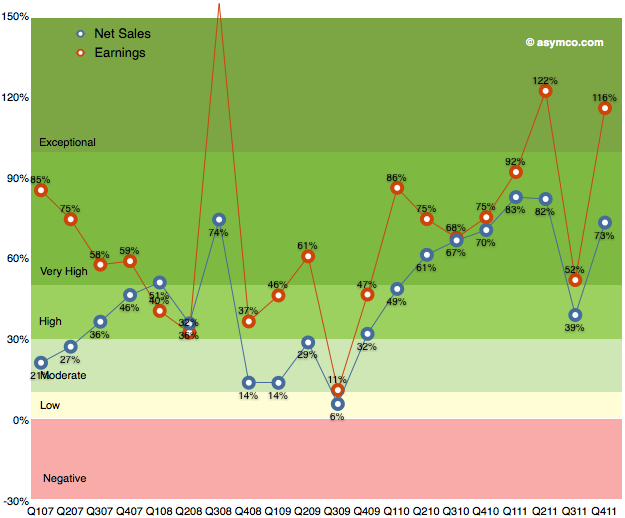
    As the chart below shows, the last quarter (fourth calendar 2011, first fiscal 2012) was robust with 116% earnings growth and 73% net sales growth. I've heard many superlatives used to describe it. It is certainly exceptional but it was not as good as the second calendar quarter of 2011.

    Sales grew faster both in CQ1 and CQ2 of 2011 and earnings grew faster in CQ2. It was in many ways a return to normality due to the iPhone returning to 133% revenue growth after the lull of the transitional third quarter.

    Now it's time to consider the current quarter. It's already quite late in the quarter to make predictions, but I waited to hear some data about the iPad. The iPad remains a difficult product to forecast. Mainly because it is a new category and the pattern of growth takes a long time to establish. We've only had three quarters where y/y growth could be measured. Sales growth has been 180%, 146% and 99%. Unit growth has been 183%, 166% and 110%.

    These rates have been higher than the average iPhone growth rates (average of which was 100% in units and 108% in revenues over the calendar 2011). Indeed, the average iPad growth rate so far seems to be 150%.

    Is it sustainable?

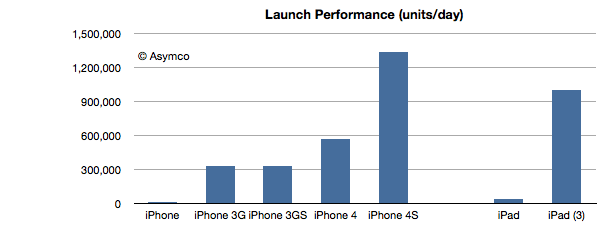
    The answer from this latest launch seems to be yes. The following chart shows the launch performance of the various iOS devices whose launch performance has been announced.

    The growth in launch performance between iPad 1 and iPad 3 is a factor of 28. iPad third generation had broader distribution but the volume boost from first generation is enormous. This implies a vastly improved production ramp. As the product remains supply constrained, the most important indicator of performance is production throughput.

    So given this data on the iPad and the ongoing broadening of the iPhone distribution network, here are my first quarter estimates (with y/y growth in parentheses):

    • iPhone units: 37.3 million (100%)
    • Macs: 4.7 million (25%)
    • iPads: 12.2 million (160%)
    • iPods: 7 million (-22%)
    • Music (incl. app) rev. growth: 40%
    • Peripherals rev. growth: 25%
    • Software rev. growth: 10%
    • Total revenues: $42.7 billion (growth: 73%)
    • GM: 44.7%
    • EPS: $12.0 (88%)

    This earnings value would imply a trailing twelve months’ EPS of about $40.7. At $600/share the P/E would be 14.7. Cash and equivalents will probably increase to $108 billion.


  3. Tim Cook's latest promise to Apple's employees

    Research · 45 comments

    In the recent event discussing Apple's cash plans, Tim Cook stated that the primary objective of the stock repurchase program is to reduce dilution from the ongoing distribution of shares to Apple's employees and executives as part of their future compensation.

    The amount allocated to this is $10 billion over a three year period.

    This sets up an interesting analysis. The company is saying that they will continue to pay employees with newly issued shares (in addition to wages) but that a portion of those shares will be purchased back from the market to reduce dilution.

    To understand the impact, it would make sense to look back and observe how many shares were issued in this way historically and consider how much $10 billion buys.

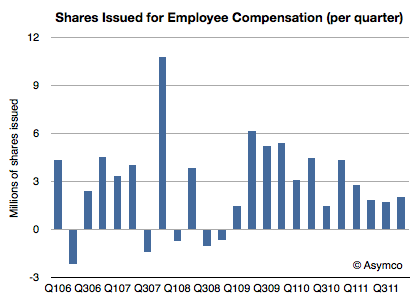
    The following chart shows the quarterly change in shares outstanding.

    The absolute number of shares outstanding grew from 874.2 million in Q4 2005 to 941.6 million last quarter. That's a net increase of 67 million shares over a six year period. The rate of growth has been accelerating. Over the last three years  40 million shares were issued.

    These issuances have an effect for shareholders. They "dilute" the total shares outstanding and thus spread the earnings more thinly. You can get an instant feel for this as the EPS figure must be re-computed each quarter with a different denominator. This is a real cost.

    Here is how to compute it. Last quarter there were two million shares issued at a "cost" of about $400/share. That means that shareholders lost the equivalent of $800 million (2 million x $400/share average price in Q4) of value.

    Now what Apple has just promised is that they would buy back the equivalent of $833 million per quarter ($10 billion/(3 years x 4 quarters/yr)) for the next three years. Note how close this figure is to the one calculated above.

    What we can also obtain is a ratio between stock-based compensation and wage-based compensation. Since we can estimate the total Apple employee wages at $3.2 billion per quarter (average R&D and SG&A over the last year), the stock compensation of $800 million amounts to a 25% bonus.

    In other words, on average an employee is likely to get compensation of $X in wages and 0.25X in stock grants.

    Therefore Apple's $10 billion dollar pledge is not only a commitment to shareholders that the dilution will be eliminated. It's also a signal to employees: for at least three years, Apple will continue to offer shares as compensation and will do so in a ratio of 1:4 of wages.

    This seems like a good use of cash.

  4. Apple's dividend and share re-purchase plan: the impact on cash growth

    Research · 132 comments

    Today Apple announced both a dividend and a share re-purchase plan which, when combined, will consume 45% of Apple's current US cash reserves.

    The dividend will be $2.65/share/quarter and the buyback will cost $10 billion over three years. The dividend will therefore cost about $2.5 billion per quarter (starting next quarter) and the re-purchase will cost about $833 million per quarter (starting next fiscal year).

    However, note that Apple's cash has been growing far more quickly. It increased by $16 billion last quarter or $37 billion over the last year. This rate of increase is itself increasing.

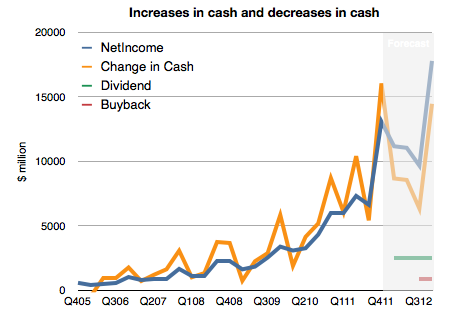
    To illustrate, I prepared the following chart. It shows historic net income, change in cash and a forecast of the costs of the new uses of cash and future net income (based on my estimates).

    I made an assumption that future cash growth will equal net earnings minus costs for the new dividend and share re-purchase. What we should see is that the previously tight coupling between increase in cash and earnings will remain but that there will be a negative offset by $3.333 billion each quarter. In other words, cash will increase but at a slower rate.

    This means Apple's total cash should still grow by more than $35 billion this year.

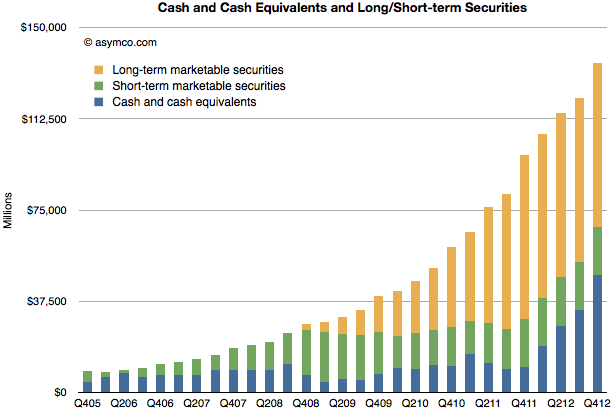
    That would result in the following, more subdued, total cash trajectory (for simplicity, I assumed all added cash would be in cash and cash equivalent accounts)

  5. [Asymconf] What are the jobs that the entertainment industry is hired to do?

    Research · 18 comments

    @mastermmik: love how @asymco thinks of everything and everyone as being "hired" to do something. lol

    via Twitter.

    Hiring products to do jobs for us is not a difficult cognitive leap to make. But can we extend the metaphor to "everything and everyone?" Aren't there parts of the human experience that are outside the realm of the implied trade that hiring suggests?

    Of course there are.

    There is an implied rationality to the practice of hiring. Commerce itself is implicitly, at least partially if not totally, rational. Buying and selling depends on a mix of instinct and calculation. And yet much of what drives human activity is not motivated through the calculus of rational thought. It could even be argued that, as we are all gifted with emotions, instinct and passion, we are anything but rational beings.

    The epitome of the triumph of the emotional over the rational is the practice of making art. Art is created to stimulate or cause appreciation. The appreciation is the reward. There is no calculation.

    However, during the last century the arts have become industrialized. That is to say that works of art are produced for profit on a grand scale. The technologies of communication and media have meant that the appreciation of art has turned into the entertainment of the masses. And since these creations are made for commercial gain then it is not only fair but fitting that entertainment should be analyzed as product.

    The industry resists analysis not just because it's difficult to define the product but because it's difficult to define why it's consumed. The 'job-to-be-done" framework that leads to insight about which products to build and how to design them seems to fail when we look at a product that seems to exist only to be appreciated.

    To suggest that appreciation can be categorized sounds presumptuous. Human perception is infinitely nuanced and every person can perceive differently from another.

    And yet, for resources to be allocated (aka. financing) or for development decisions (production) or promotion (marketing) a theory has to exist about who buys and why they do it.

    The theory that seems to be in common use in the industry is that a few experts have the knack for knowing how to allocate the resources for what is created. These persons are entrusted with an increasingly large influence. There are only a few major studios for deciding what most of the world consumes in the form of either visual (cinematic) or audio (music) productions. The concentration of power is a result of the distribution model of physical media or broadcast networks. These are artifacts of a technological infrastructure that was built in the last century. An infrastructure whose replacement is unavoidable.

    Its replacement will enable creation and distribuion of art to be democratized[1].

    It's important to understand the jobs entertainment is hired to do. Not because the creative process can be synthesized. It's important because those creators need to learn how to allocate their own resources. A framework is needed to help dis-intermediate the resources allocators--the central planners, if you will.

    In other words, learning how to create commercially valuable appreciable products should be a skill all creative people possess.

    These are not complicated ideas. They don't require powers of deduction beyond the reach of the average person. What they require is perspective.

    The dialogue on this topic will begin in Amsterdam on April 13th 2012, at Asymconf. I look forward to seeing you there.

    —

    Notes:

    1. The proof of this is left to the reader.
    2. This is the material accompanying the first case discussion at Asymconf. Participants are encouraged to read it before the show.
  6. What is disruption and how can it be harnessed?[1]

    Research · 49 comments

    The phenomenon we call business disruption could benefit from a different name. Although it signifies a disturbance or an interruption in an industry, it's much more than that.

    The nominal definition I work with is that disruption is the "transfer of wealth in an industry from dominant incumbents to disadvantaged entrants." It's a convenient definition because it's brief, it puts the emphasis on economic value and because it alludes to a reversal of fortune and the implied extraordinariness.

    However, there are several nuances lost and contradictions ignored in this definition. I want to enumerate them here and now:

    1. Although in a disruption there is a transfer of wealth, that wealth is not necessarily conserved. An industry that undergoes a disruption often emerges larger, more productive or more influential. Disruption typically creates net growth.
    2. Although extraordinary and spectacular it is also very commonplace. Disruption is not rare. In fact, it rarely fails to happen. One could even say that if it does fail to happen, it's a symptom of an industry in crisis.
    3. Being so common, it can be seen as a regular occurrence. But if the regularity of disruption can be considered to have a clock cycle, its frequency is increasing.
    4. Disruption in the literal sense implies discomfort, displacement and even destruction. But it's necessary to the health of any economy. The analogy to biology is that death is the most important thing in life.
    5. Although only recently characterized and studied in cases set in the past century, the pattern is evident throughout history.

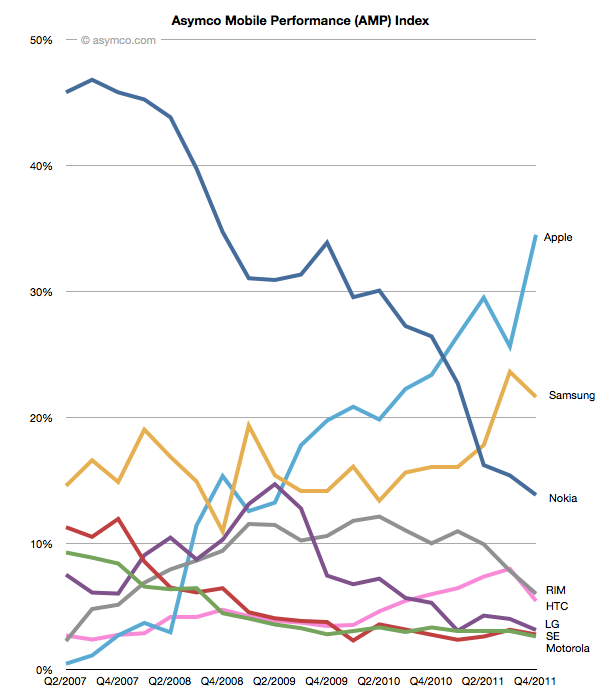
    I've offered examples of these consequences or side-effects of disruption but I'll emphasize once more the example I'm most familiar with. To illustrate the primary definition, the AMP index is a measure of the success of one company relative to a set of peers in the mobile phone industry. It's the average of four market shares: mobile phone units, smartphone units, revenues and operating profits.

    This chart shows the shift in AMP index values for the competitors whose data is public and which make up the vast majority of units sold:

    The reversal of fortunes, though not complete, is clearly evident. Motorola and Sony-Ericsson, two of the brands that were a significant part of the mobile phone landscape for more than a decade, have ceased to exist as independent companies. A third, LG, is likely to follow. Nokia, the most successful phone vendor for the decade of the 2000's is in severe distress at this time, valued barely above book. RIM, a pioneer, is priced below book value and HTC, another pioneer is also looking for a way to remain relevant.

    But we have to appreciate that as these valuations evaporated, the market grew both in value and in volume. The overall spending on phones has never been higher. The total profits captured is also growing. By any standard, smartphones are a booming business. Queues form for the latest versions, there are supply constraints and media coverage is almost universal.

    We also have to appreciate that the Nokia that is faltering today was itself disruptive when it gained its prominence. In the 1990s the mobile phone market was dominated by Motorola, then by Ericsson. Nokia was a relative latecomer and succeeded by being better in some regards (e.g. the ease of use of text messaging on its phones) but also by being asymmetric. Using logistics and a portfolio approach to the market allowed it to build scale while maintaining margins. Process innovation led to component shortages for competitors and allowed Nokia to build massive distribution. It also allowed it to invest in software which gave it a unique selling point for several years.

    Looking into the even more distant past, the mobile phone market has seen several waves of disruption. Going from analog to digital was such a turnover. The companies which were successful with analog (mainly Motorola which supplied not just handsets but infrastructure) were sidelined when global digital standards took root. Integrated European vendors dominated a period when 2G GSM was becoming predominant. Isolated pockets of integrated innovation like iMode in Japan also had mini-booms but were swamped by standardization and the Galapagos syndrome.

    And let's not forget that mobile itself has been disruptive to fixed line telephony. Looking at all telecom, the transitions from fixed to mobile, analog to digital and most recently feature-based to computing-based platforms have all been disruptive, bringing a new set of companies to lead while incumbents fretted.

    It should also be noted that these changes are happening more rapidly. The chart above has a five year period. The change from analog to digital took longer. Over 10 years since its inception analog was still dominant. If we look how long it took for mobile to take consumption away from fixed, that process is still ongoing, several decades later. The speed is so slow that some countries have skipped over fixed networks altogether.

    With software-defined devices and cloud-based distributed computing the changes will become even more rapid. Even though the user base is expanding to cover nearly the entire global population, the replacement rate of devices means that change in the tools and services people use are limited by supply rather than demand. Supply-based innovation or "the new manufacturing" will probably be the dominance-defining asymmetry of the next decade.

    The disruption of mobile phones that Apple has foisted on the world through iOS has caused it to reach a point where it dwarves the values of other companies, not just in the sectors it competes, but in all sectors. Some suggest that Apple is an anomaly and does not reflect the economy. To truly understand the state of the economy, they say, means to subtract Apple from it. But I feel this is exactly wrong. Apple is, through the iPhone and iOS ecosystems, defining this era. Just like Microsoft defined an era of increased productivity through the creation of the "knowledge worker", or like GM re-defined transportation and the notion of the brand in the 50's, or like IBM re-defined business process efficiency with automation in the 60's and 70's, these companies were not anomalies of their era. They were the eras. They were the locomotives of growth that taught other companies how to operate and the contemporary managers how to manage.

    Companies that study Apple today will benefit by understanding how it re-wrote the rules. The anomaly is the norm. The exception is the rule. The times they are indeed a-changin'.

    Finally, to put disruption in a historical perspective. I wrote a retrospective on the history of the telegraph as a parable of how disruption could be interpreted to have happened even a century ago. What I hope to do now is to show how, given this set of spectacles, we can see how the fate of nations was determined, in part at least, by the ability of leadership to accommodate disruption.

    The case of growth or limits to that growth, the question of integration vs. modularity and the evolution of value chains all have application for regulators, policy makers and political leaders.

    The dialogue on this topic will begin in Amsterdam on April 13th 2012, at Asymconf. I look forward to seeing you there.

    ---

    Notes:

    1. This is the material accompanying the first case discussion at Asymconf. Participants are encouraged to read it before the show.
  7. The new feeds and speeds: iPad vs. MacBook Air and iMac

    Research · 81 comments

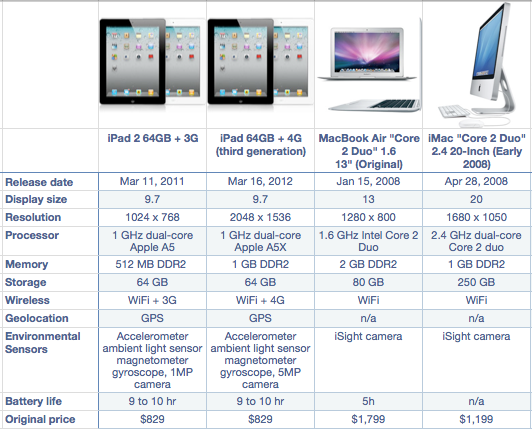
    At last year's iPad 2 launch, I compared the specs of the newly announced iPad with those of a laptop and desktop from five years earlier. This year I am comparing the new iPad with Apple's computers from four years earlier:

    The new iPad now exceeds the total display resolution, has similar speed and storage capacity while having twice the battery life of the thinnest laptop of four years ago. It also has very high quality cameras and GPS and cellular network connectivity which have yet to appear on mainstream PCs. It's still a lot smaller and half the price and has a larger selection of available software titles at prices a fraction of its elder cousin.

    The only value that a desktop of 2008 has over a new iPad is the size of the screen and a larger hard drive.

    The point is not so much that the usurper is a "better" computer but that it has come from non-existence to being a contender in two years. It is also narrowing the gap to its comparable ancestors by one year, every year. Arguably that gap now stands at four years.