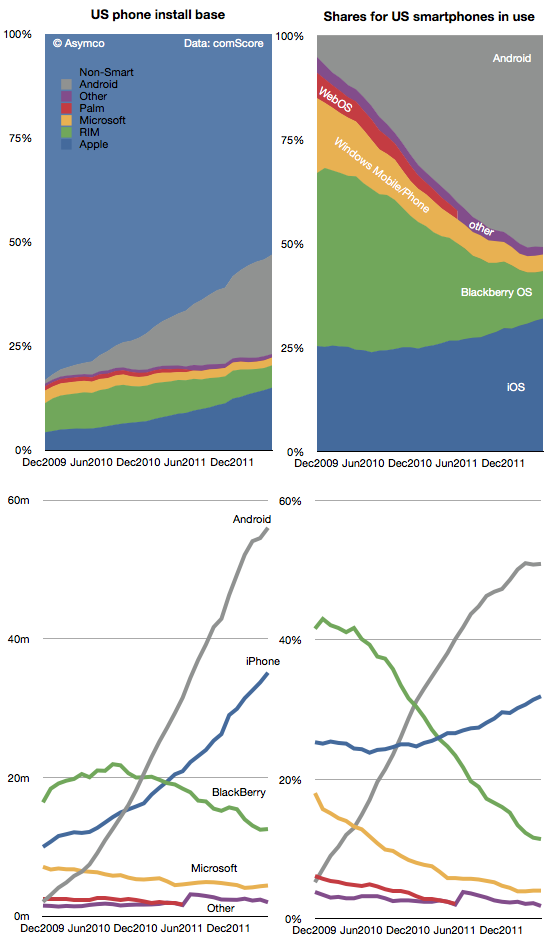
According to comScore, as of end of May, the ratio of consumer phone users in the US (aged more than 13) who use smartphones as their primary phone has reached 47%.
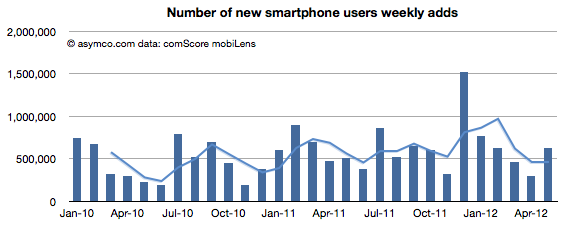
The question is whether this is reaching saturation. My guess has been that saturation will be at levels well above 80%. The data shows that during May the rate of smartphone adoption (first time users) was 630k/week. This number is a good recovery to above the historic mean indicative that saturation is not yet in effect.
50% penetration will happen this summer. A year ago the predicted "tipping point" date was also the same: August 2012.
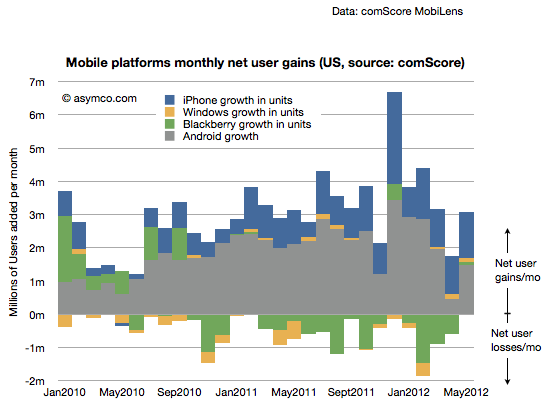
The platform shares data is also returning to a historic consistency. A month ago I asked if there was "trouble with the robot" because Android net adds dropped to a level unseen for two years and the decline in net adds had been going on for four months.
This last report shows a recovery in Android net adds to about 1.5 million new users.
[Note here too that there is no sign of saturation: The net user gains are far above net user losses. Even BlackBerry showed a gain. In a market where there is saturation, net gains and losses among platforms would balance each other out.]
In terms of share, Android shows two months of no growth. The following charts show the history of platforms in terms of share and actual units in area and line charts.
I'd say the jury is still out on whether Android has "peaked" in the US. Globally, the rate of additions seems to still be increasing but in the US we might be seeing the effect of upgrades as many first time Android buyers are reaching the end of their contracts. iPhone and Android "purchase rates" are already at parity but the install base might take some time to converge.
With half the population still not using smartphones, there is still headroom for the platforms, but the inter-platform dynamics are becoming very interesting.
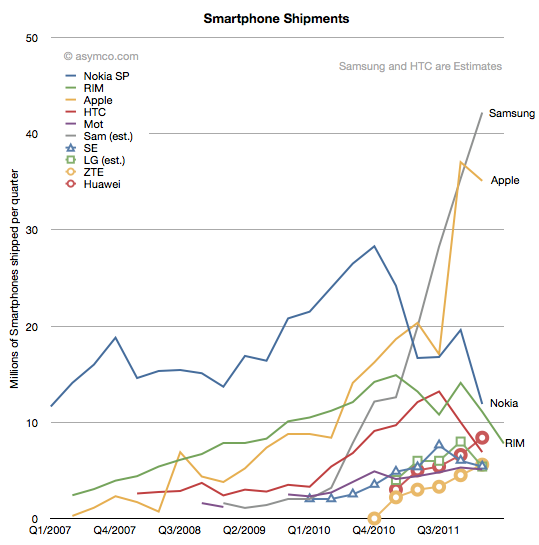
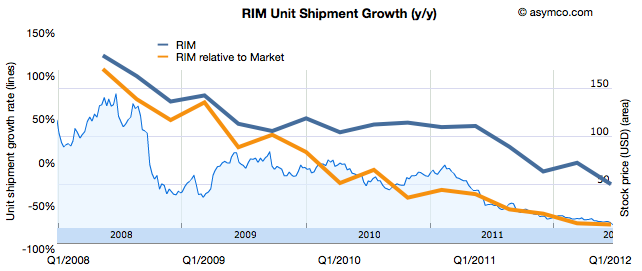
The number of BlackBerry phones sold fell 41% year-on-year in the last RIM fiscal quarter. Sequentially the fall was 30%. Though surprisingly poor, I note that Nokia's smartphone business fell even more dramatically last quarter (down 50% y/y and 39% sequentially). LG also saw a 44% decline in unit shipments in Q1.
The history of smartphone shipments for the largest vendors is shown in the following chart:
From forecasts made by Huawei it's probable that they overtook RIM in the last quarter, dropping RIM to 5th or 6th ranked vendor in smartphone units.
RIM's 7.8 million units is the same level of sales as it had in early 2009. The total market was only about 250 million units per quarter then. It's around 400 million today. A quick calculation shows that RIM's smartphone market share has fallen from a peak of 22% to about 6%.
RIM's stock performance reflects this performance relative to the market.
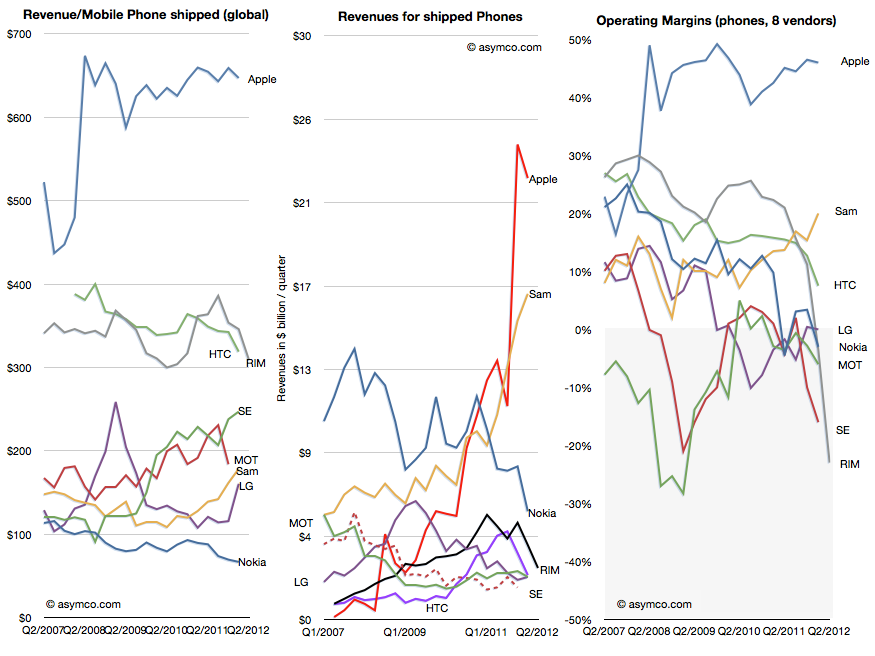
Hardware revenues were $1.652 billion. Matt Richman calculates the average hardware revenues for the BlackBerry of $203. I include service revenues in my ASP calculations (for Nokia and Apple these are also significant values) yielding $309 per BlackBerry. The history of total revenues, revenues per phone and operating margins are shown below relative to competitors.
Operating margin tells the most sobering story. As I've often repeated, historically no company has survived dipping into the grey zone.
To reiterate, the logic of irrevocability in this industry is as follows:
Success depends on three conditions being met by the vendor's products:
consumers trust the platform's promise
operator see the product as creating value to their core business
developers offer investment to innovate on top of the platform
If all these factors are present, the vendor enjoys a virtuous cycle of growth. If any of these is lost, the others are also likely to be lost as well creating a vicious cycle of decline.
Loss of operating margin is an early indicator that at least one condition is not met. Usually, a failure of consumer trust leads to a drop in purchases which leads operators and distributors and retailers to flee and then developers defect.
It's been impossible to recover from this tailspin so far. There is a procedure which works in theory: accelerate downward by investing in a new platform. The move is counter-intuitive but essential in re-building trust, quality and relationships.
However, the reason it does not work in practice is that this struggle is not with gravity alone. While spinning downward, the company is also subject to competitive attack. Competitors fill the void and take customers into locked-in ecosystems. There is neither the time nor the ability to defend.
Cash runs out and customers are divided up between the survivors. Nokia and RIM face this scenario today.
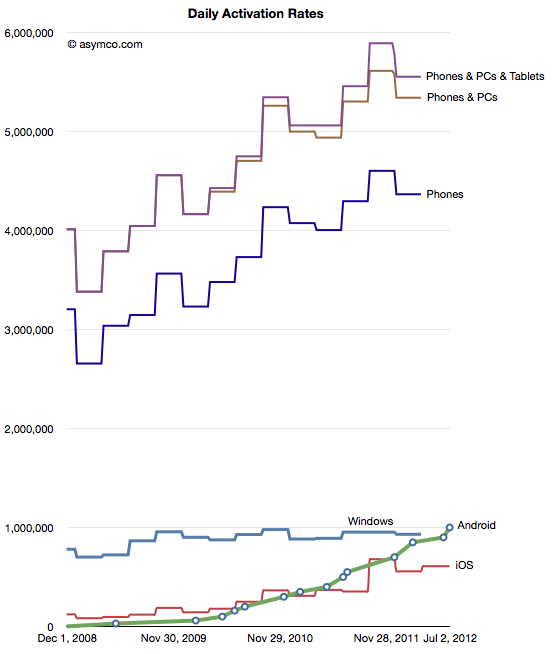
Google reported a new activation rate milestone: 1 million/day.
The rate of activations has been increasing steadily which leads to a question: how high can it go?
The answer is easy to determine. It can go no higher than the sales rate of phones and tablets and PCs. So what's that sales rate? The answer is to take sales (shipments actually) per category and cast the data as "activations".
The result is shown in the chart below:
Defined as "activations" device and computers are being adopted at the rate of about 5.6 million units per day.
As a percent of total activations, Android is running at about 15% and iOS is at 10%. Android has already overtaken Windows activations and with the new iPhone, it's likely iOS will do as well this year.
In terms of available headroom this means that iOS and Android are running at a combined share of 25% of available activations. They both should consider that three quarters of the opportunity is left to go.
Will iOS and Android reach a duopoly in terms of activations, topping 5 million per day? Probably not, at least not without some fragmentation or platform diversification (to put it nicely). Nevertheless, 3 to 4 million per day seems an easy target to set.
Dan and Horace reflect on the Osbourne effect of Windows Phone 8 on Nokia and how to value a company in distress. In particular, we talk about the potential of a Microsoft acquisition and the conditions needed to make it happen. Horace takes two reader questions: How did Samsung succeed while other vendors failed with Android and what are the pitfalls that could cause Apple to stumble.
This week Mr. Dediu was a guest on The Web Ahead (another 5by5 show hosted by Jen Simmons) where he discussed how the forces of disruption apply to the web. It was an interesting discussion as usual, but if you’re pressed for time you should turn your attention to the bit after the sixty-five minute mark, when Horace volunteers some of his thoughts on the web vs. native application platforms.
Today I was a guest on Jen Simmons' The Web Ahead. It was a chance to discuss some of the big questions facing the Web in general especially vis-à-vis apps and mobile in general.
How can we understand the business of the web? Horace Dediu joins Jen to talk about the web through the lens of disruption theory, discussing innovation and jobs to be done. Along the way we get into advertisement on the web, and the old website vs native app debate.
There is no shortage of information about what happens to companies in distress. The cause of distress varies widely and is often not well understood but the actions and symptoms of distress are very consistent. We can look at examples in each industry, even in each product category for a rich set of distressed company data.
For over a year I've been chronicling the decline of incumbents in the mobile phone industry. However, decline cannot continue indefinitely. At some point a company "exits" the industry. Either through a sale or divestiture or, rarely bankruptcy. The list of exits is already long. The length and the correlation between exit and the lack of recovery implies that Nokia will also exit.
But how, exactly?
Will Nokia be acquired? If so, then by whom? What other options exist? How can we analyze this?
The easiest way to guess is to look at what happened to other companies in similar circumstances. The clearest and easiest comparison to apply is Motorola. Motorola was at one time the largest phone vendor and it went through a violent decline. Like Nokia, it was diversified into networks and a few other businesses. Unlike Motorola it's not an American company. This matters because American companies are more comfortable targets for corporate raiders. The legal and boardroom mechanics are not "better" or "easier" in the US than in Europe but they are more familiar to those who might engage in it.
So one avenue that Motorola traveled on was the intervention of activist investors who forced management change, affected strategy and pushed some tactical initiatives. This external pressure was successful in the case of Motorola. The company was split up, it was re-purposed and re-focused and, with a bit of good luck, was acquired.
The process however still took two years. In that time the company languished but stayed alive. Its headcount was reduced by nearly two thirds. It was in a precarious situation throughout. Its story is not over but ownership did change hands and those who took a risk with it while in distress managed to get a reward.
This example (and Sony's acquisition of Sony Ericsson and HP's acquisition of Palm) cannot apply to Nokia. An activist investor is unlikely and the company has not yet made itself attractive to a buyer. So what would Nokia need to do to be acquired?
The first step toward an acquisition will be divestiture of its Nokia Siemens venture. The second will be a spinoff or sale of its non-smart phone division. The third might be the allocation of its IP across these separate entities or in a separate holding.
As the company is broken up, value can be released. Investors will be able to value it better and make appropriate assessments of risk. Only at this point would an acquirer perhaps buy the "rump" Nokia smartphones group.
However, even this scenario is not without huge risks. By the time the split is completed, the operating companies could have deteriorated to such a degree that they are no longer viable. Timing is critical.
So if the smartphone group is isolated and made available, who could buy it? Microsoft is always cited as the primary buyer. I've been skeptical of this as Microsoft has found it difficult to make hardware work. It acquired Danger leading to Kin which failed. It has struggled with Xbox for a decade and has yet to recover all its costs for the effort. It has failed embarassingly with Zune. It also has shown no particular success with its original Surface table computer.
But management has re-committed itself to a new hardware effort with the new Surface. This renewed potential opens up the possibility of entering into the integration of a phone again into their business, and Nokia would be remarkably well positioned to help.
At this time, the possibility still seems remote. The company has dismissed speculation of building phones again and again. Unlike PCs, the phone platform is not yet mature and volumes and distribution are very different.
However, there is one other option.
Microsoft has historically "rescued" technology companies in distress with cash infusions for minority equity stakes. It injected some cash into Apple, Barnes & Noble and even Facebook. It did so not because they wanted to own these companies but because they wanted them to survive or thrive. The move acts as a signal to the industry, partners and developers. So what I see more likely than an acquisition is Microsoft capitalizing a spun-off Nokia Smartphones company in exchange for a small equity stake.
The valuation of this stake will be huge as I expect billions of dollars for single digit share ownership. However, Microsoft would not be doing it to get a return from those shares. It would probably later sell them at a loss. But it would be buying a strategic option whose value may be far greater.
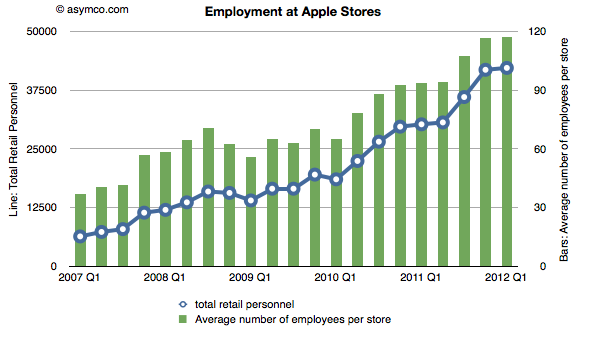
In the five years since the iPhone launched, Apple created a total of 35,852 retail jobs.
Some of those jobs came from new store openings. The total store count went from 172 to 361, more than doubling. But the growth in employment was faster: from about 6400 to 42,200, more than quintupling. This is reflected in the total number of employees per store which increased from 37 in Q1 2007 to 117 in Q1 2012.
Which brings up an obvious question: Why did Apple triple employment at each store? One could answer that many of the newer stores are bigger, so-called flagship stores. But the vast majority of stores are in mall locations which are of limited size. Flagship stores alone cannot account for the increase. One could also suggest that perhaps the stores are open longer and there is a need for more shifts. Again, the vast majority of stores are constrained by the opening hours of malls which, as far as I know, have been steady. Anecdotally, it's also evident that there are more employees in a store at a given time. There are many more of those colored T-shirts at first glance.
One hint is in the design changes in the stores. Apple has removed shelving, registers and almost all non-Apple merchandise. It has replaced the visible stock with tables on which rest products that can be used. If there weren't any people in the store, the store would look almost completely empty, just an open space.
But that's the whole point. The stores are designed to be filled with people. The stores have an open layout because it allows more people to be inside the store at the same time. And the more people the more employees.
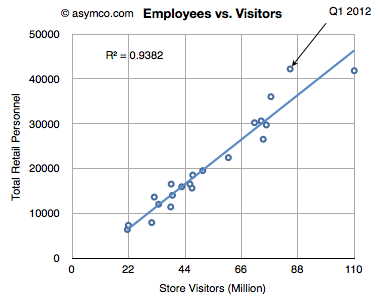
We have the data to prove this: The visitors per store per quarter increased from 125k in Q1 2007 to 235.5k last quarter. Nearly double the number of visitors in five years. It's this increased traffic that is closest tied to the increase in employment. This is illustrated by the following chart:
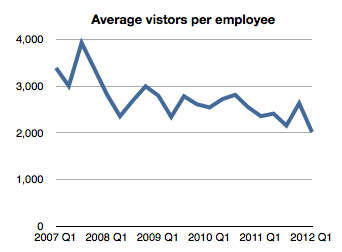
Employment is very closely correlated with total visitors. In fact, employment has risen faster even than visitors. By dividing the number of visitors by the number of employees we see how the number has declined.
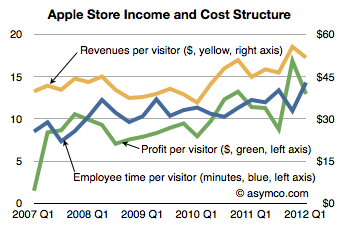
[If we consider the time an employee spends working we can even guess that the average visit was served by about 14 minutes of employee interaction--this is up from 9 minutes five years ago.]
If we assume this relationship as causal, then it might be that the stores are "tuned" to ensure a reasonable if not pleasurable experience for the visitor. In other words, the proxy for a "quality" experience is the assistance of an Apple retail employee.
Taking this a step further, we can perhaps hypothesize that Apple is treating its retail stores as hired to provide a human touch to its products--not just as a service but as a way to listen and help in the most basic way. Steve Jobs once said that Apple no longer had to be present at trade shows because they have millions of conversations with their customers every day through their stores. These conversations happen with the retail staff.
Through their Apple retail staff, Apple might even be said to be putting a face on their brand. You can see it in the advertising.
The corollary to this would be that the job of the store is not primarily to sell things. This is confirmed by the fact that store employees are not on commission and there is no sales pressure on visitors. Indeed, the sheer number of employees in a store of modest size (117 employees on an average of about 8k sq. ft.) implies a brazen disregard for the economic orthodoxy of retail efficiency and incentives to sell.
And yet the stores are astonishingly efficient at selling things. The statistics are off the charts in terms of sales per square foot and overall profitability. Even though this employee time has a cost, revenues and profits have all risen in unison.[1]
Of course, the products have a lot to do with this performance. Apple stores sell desirable, popular products which are premium priced. But taking these desired products and coupling them with a "human touch" job to be done strengthens the brand as well as expands its volume of sales. It may be that Apple's retail approach could not work with a brand that was less desired. I.e. regardless of a large head count, a Sony store may not see the return on retail investment that Apple gets. Conversely, by not putting a face on Apple's brand the products may not sell quite as briskly. Ron Johnson said on the launch of the iPad that the stores were almost designed for it. Discovery and hands-on time create demand.
It's as if Apple retail has an inter-dependence with Apple, the brand. One cannot live without the other.
This is, as far as I know, a unique relationship for a technology company. If anything, most technology companies have sought the exact opposite: to put others' faces in front of customers--to break the messy process of sales and support down into pieces to be outsourced to "value adding" resellers.
A pity then that this humanizing touch takes such a long time to build.
---
Note:
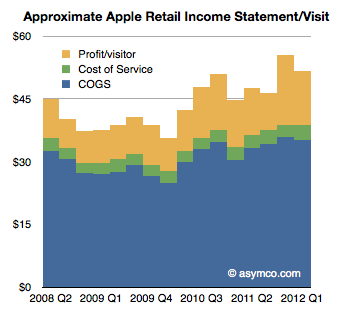
If we take a visitor-centric point of view, the analysis of the retail business simplifies considerably. We can even derive an "income statement per visitor". Revenues are measured per visitor (currently about $52/visit). Costs are measured in terms of employee time. A $15/hr average wage and 15 min interaction time per visit puts the service cost at $3.75/visit. Profit per visit is also measurable and it's currently at $13/visit. Therefore the employee "FaceTime" costs 7% of sales, while other costs, including the cost of goods sold, add up to 66% of sales.
HD: Apps are like the sauce in a dish. They add flavor and distinguish the dish. Increasingly they also offer nourishment. Some would argue that we can live with plain cooking but spices drove people to do incredible things like risking life to discover new continents. Being the world's best source for spices means the most innovative and brilliant minds will be attracted to innovate on top of Apple's platforms.
Horace and Dan look at Microsoft's Surface through disruption colored lenses. First, the ongoing evolution of the computing value chain and how it foretold us of Surface. Second, how the economics of Microsoft's businesses makes Surface compelling. We also begin a new segment tentatively called "Reader Questions". This time it's education: is it disruptable? If so how can we tell and where will it lead us?
As previously noted, Apple has overtaken Microsoft (and Google) in operating margin percentage. This is an astonishing statistic as Apple is still largely perceived to be a "hardware company" while Microsoft is a "software company" and Google is a "services company."
To suggest that "hardware" could be more operationally profitable than either software or services is akin to heresy in technology analysis. This reversal is newsworthy indeed. However, even the most casual observer would note that Apple does not derive its market power from hardware alone. It is, in fact, an integrated hardware, software and services company (with a few more roles besides.)
So the emergent successful business architecture in this technologically transitional period is of integration and completeness of solutions.
This shift explains at least at a conceptual level Microsoft's tectonic Surface shift.
But what about another point of view? What does integration mean for Microsoft's income, cost and profit structure? Is integration self-disruptive to Microsoft?
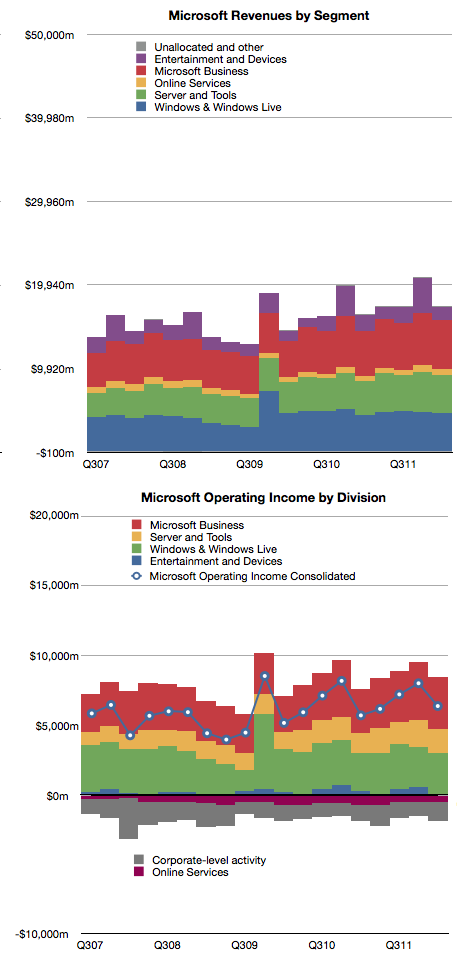
Here's a reminder of Microsoft's revenues and operating income by division:
The challenge of devices for Microsoft is that the licensing of software for devices is very difficult to sell.
In 2011 Microsoft received about $18.7 billion in Windows revenues and $23 billion in Office revenues. The chart shows that this is a fairly steady growth business. According to Gartner, in 2011 there were about 336 million Windows PCs sold and that this too is a fairly stable and mature business.
If we simply divide revenues by PCs sold we get about $55 Windows revenues per PC and $68 of Office revenues per PC sold [1]. The total income for Microsoft per PC sold is therefore about $123. If we divide operating income by PCs as well we get $35 per Windows license and $43 per Office license. That's a total of $78 of operating profit per PC.
Now let's think about a post-PC future exemplified by the iPad. Apple sells the iPad with a nearly 33% margin but at a higher average price than Microsoft's software bundle. Apple gives away the software (and apps are very cheap) but it still gains $195 in operating profit per iPad sold.
Fine, you say, but Microsoft make up for it in volume. Well, that's a problem. The tablet volumes are expanding very quickly and are on track to overtake traditional PCs while traditional PCs are likely to be disrupted and decline.
So Microsoft faces a dilemma. Their business model of expensive software on cheap hardware is not sustainable. The future is nearly free software integrated into moderately priced hardware.
For Microsoft to maintain their profitability, they have to find a way of obtaining $80 of profit per device. Under the current structure, device makers will not pay $55 per Windows license per device and users will not spend $68 per Office bundle per tablet. Price competition with Android tablets which have no software licensing costs and with iPad which has very cheap software means that a $300 tablet with a $68 software bill will not be competitive or profitable.
However, if Microsoft can sell a $400 (on average) device bundled with its software, and is able to get 20% margins then Microsoft is back to its $80 profit per device sold. This, I believe, is a large part of the practical motivation behind the Surface product.
The challenge for Microsoft therefore becomes to build hundreds of millions of these devices. Every year. Sounds like they need a Tim Cook to run it.
---
Notes:
Microsoft accounts for revenues using deferrals due to Software Assurance pre-payment models for many corporate customers so this figure is not a precise value for each license sold.