Asymco

Asymmetric Intelligence

Latest from Asymco

  1. The evolution of the computing value chain

    Research · 34 comments

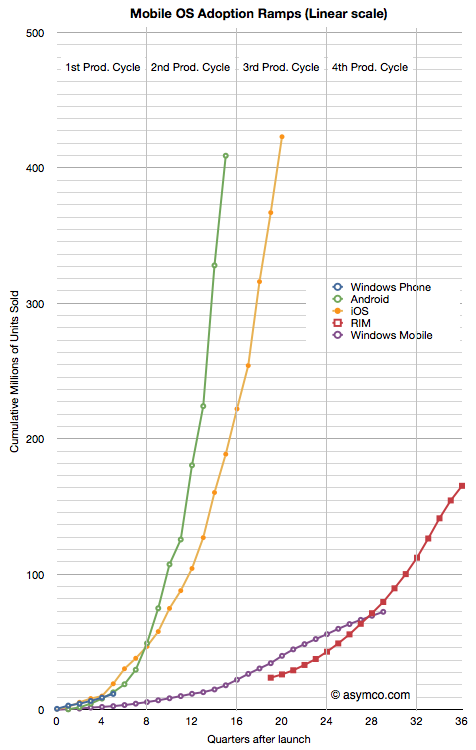
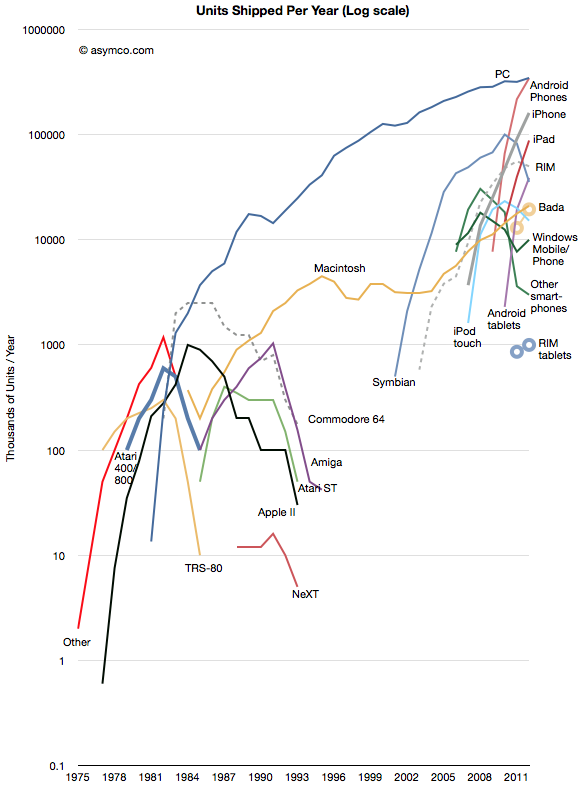
    The history of personal computing has come to be defined as the history of Microsoft. At least since 1981 Microsoft's operating systems have been the consistent market share leaders, and by a very large margin. That is about to change. This year Android will be on more devices sold than Windows. iOS is also set to also overtake Windows next year. The following chart illustrates the wave of mobile platforms that has emerged, and in spite of some notable failures, is overtaking traditional computing.
    Of course we should remember that PC themselves overtook entrenched predecessors like minicomputers and mainframes which themselves overtook business computing systems based on adding machines, typewriters and slide rules. This is the cycle of disruption and there is nothing new about it.

    However, it always seems to take people by surprise. This is because it happens in unforeseen ways and at unpredictable rates. And so it is that we are surprised by Microsoft's seeming abandonment of a business model that has sustained it for three decades.

    Yesterday's reveal of Surface, Microsoft's first personal computer, was a watershed event in the evolution of value chains around computing. In a famous slide Clay Christensen illustrated (in 2004) the value chain evolution in computing from the 1960s to 2000.
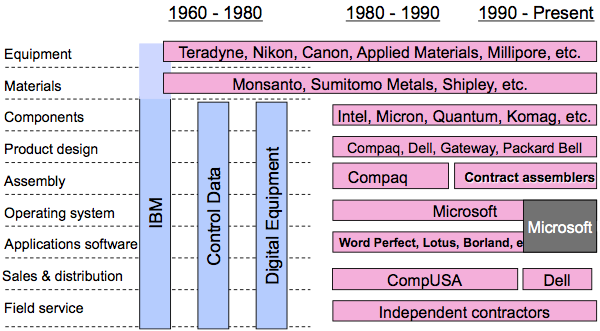
    As computing moved from the desktop to the pocket the industry re-integrated. First, Apple moved from Product Design into Sales & Distribution with its stores. Then it moved into service with Genius bar. Then it moved into component design with the A series chips and unique batteries. Then it moved into materials with exclusive licensing of LiquidMetal. It also began to own the equipment used in its manufacturing. This in addition owning the operating system.

    Now we see Microsoft following in the same footsteps. First applications came early then stores, then service, and now product design. Google is also tracking closely behind as well with its acquisition of Motorola, the results of which have yet to be revealed.

    And so we can see value chains evolving in real time before our very eyes. They have always evolved but in technology industries they evolve far more rapidly and will continue to accelerate.

    Whether Microsoft or Google will be successful in their integration efforts remains to be seen. The challenges are immense as the value of the existing chains are enormous and the bonds that tie the company to them very strong. Breaking these ties will seem like value destruction and corporate antibodies will be set loose to kill the transitions. HP, RIM, Nokia and Dell are vivid examples of what happens when the response mechanisms have their way.
  2. A more precise measure of Apple's device installed base (and device longevity)

    Research · 42 comments

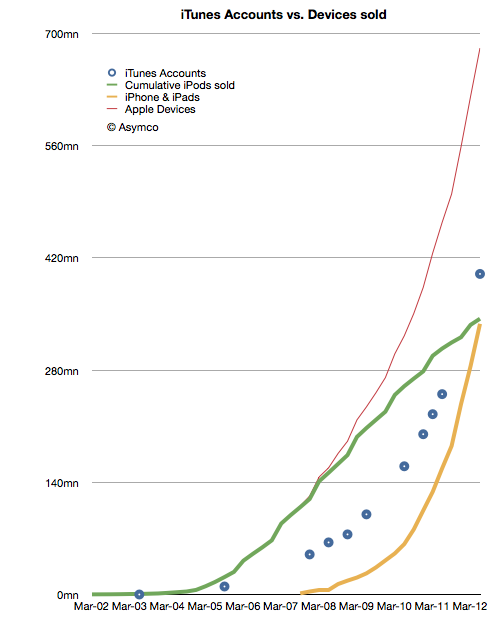
    Apple announced that the total number of iTunes account (with credit cards attached) has reached 400 million. This was touted as being the largest collection of credit card accounts for any retailer and I have no reason to doubt it. However, looking beyond the bragging rights, there are more interesting patterns to observe about this asset.

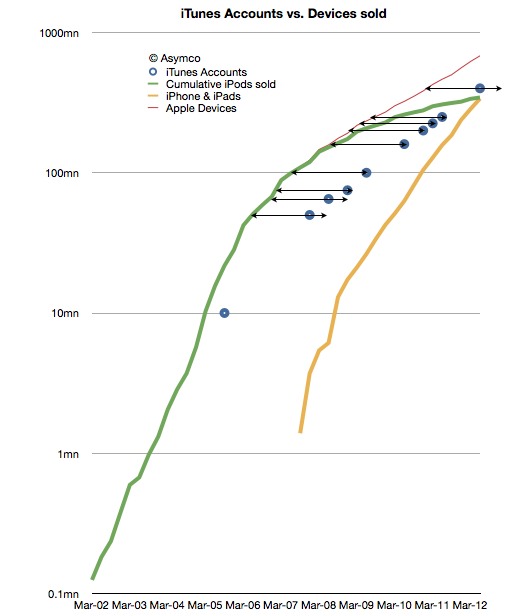
    What I plotted was the cumulative number of iPods sold (green), the cumulative number of iPhones and iPads (yellow), the combined devices total (red) and the reported number of iTunes accounts (blue).

    The first observation is that the combined total iPhones + iPads have overtaken cumulative total iPods. The iPhone started in Mid '07, more than five years after the first iPod shipped. The acceleration in that product line is still evident while the iPod decelerates gracefully.

    The second observation is that the total device count has reached 680 million in the last decade. It's a big number but it is still a number that is dwarfed by the overall device market. Apple is still around 10% of the devices market today. It should give an idea of how many devices could still be sold in the next decade.

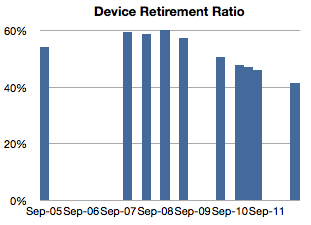
    The third observation is the ratio between the iTunes accounts and the total devices sold. Since iPods, iPhone and iPads have been dependent on iTunes, the number of iTunes accounts gives a rough indication of active users. Combining active users with total devices sold should give a rough estimate of the number of retired devices. In other words, if we assume that account holders typically use one device then by taking the difference between devices sold to date and accounts at that point in time we should know how many devices have been retired.

    Dividing that number of retired devices by devices in use should give us the retirement rate and that is shown in the following chart:

    Note that as the iPod was slowing and the iPhone was still a small part of the total, the retirement ratio was increasing. As the iPhone accelerated, the ratio began decreasing and is still decreasing.

    Projecting the retirement rate should give us a way of more precisely estimating  the addressable market for developers, accessories makers, and other ecosystem participants.  Currently that means that about 60% of all Apple's devices sold are still in use. We can tune that figure upward in the next few quarters and make better estimates as Apple releases their shipment data.

    The iTunes account data is not just a way to calibrate addressable markets but also a valuable method for measuring device longevity. The distance between the red line and the blue happens to be nearly a constant 8 quarters as shown in the following chart (note change to log scale for the vertical axis).

  3. Update on Android growth

    Research · 24 comments

    In February of this year MediaTek introduced an ARM chipset for Android smartphones targeting $160 end user pricing. I've heard estimates that this chipset will sell in the "hundreds of millions".

    The question is: are these units going to be "activated" as per Google's definition of Android?

    Historically, MediaTek's chips have been used in "grey market" devices. These are typically copies of branded phones and are sometimes shipped without IMEI numbers and hence not even sanctioned by regulatory authorities. If hundreds of million of such Android devices are sold in the next few years then tracking Android will become even more difficult.

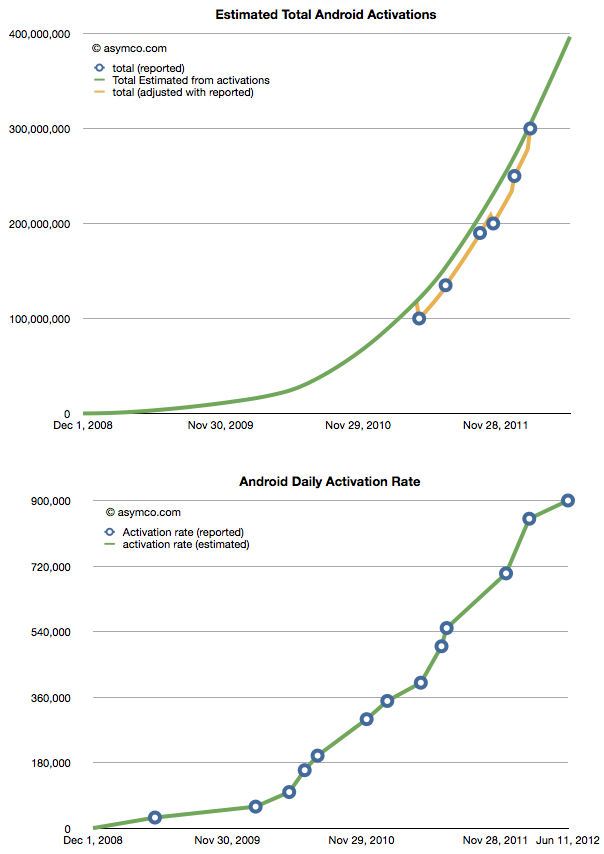
    The current total is difficult enough. We just received an update on the activation rate (900,000 per day) and that allows us to create a picture of total cumulative activations.

    We still don't know the retirement rate so these are not devices in use, however most of these devices have been sold in the last two years implying they are (nominally) still functional. The following chart shows the ramp overlaid with an estimated 24 month product life cycle.

    The one million per day Android activation rate has probably already been crossed with all the unsanctioned versions of Android available today. What will be the rate once the MediaTek chipsets are in wide distribution?

  4. Are revenues per app decreasing?

    Research · 22 comments

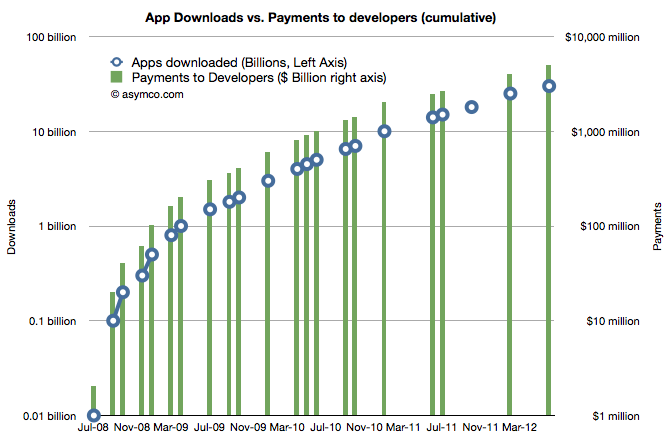
    Apple has been releasing data about payments to developers with increasing frequency. Last week's $5 billion announcement was the fifth such update and came after about one quarter since the last.

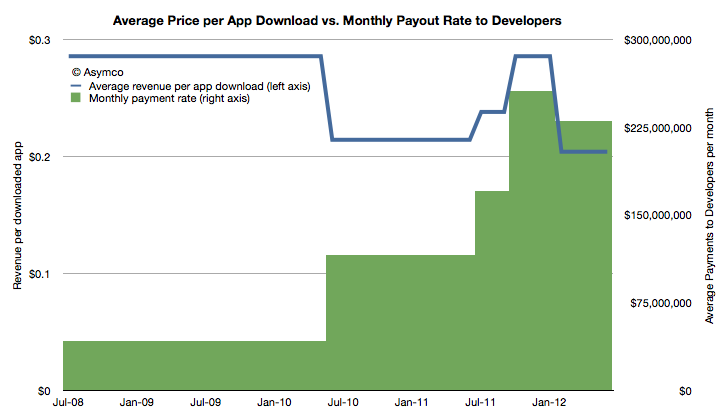
    Knowing the payments to developers and the cumulative download count allows us to get a very accurate revenue point for each download. As the frequency increases we can observe growth and seasonality patterns.

    The following chart shows how average revenue per app download and the average payment rate to developers has changed since the iTunes app store opened and given the data points available:

    The green area in the chart should add up to $5 billion. The average revenue for all downloads is 24c. 

    Although there has been a drop in the revenue and payout rate in the last six months, the cause may be due to seasonal effects. We have not been able to see data that might show seasonality in prior years so we can't be sure it exists. However, it makes sense to me that new buyers are likely to engage in a burst of app buying and there are more iPhone purchases in the second half of the year than in the first.

    In any case, the current "run rate" of payments to developers is about $7.5 million per day or $230 million per month. Both are up from last year.

    Whether revenues are decreasing or not will require some more data. The last period's 20c is not far below the app store lifetime pricing of 24c.


  5. 5by5 | The Critical Path #42: Full Circle

    Podcast · 12 comments

    Having just returned from China, Horace gives his impressions which leads to a discussion about industrialization and innovation and how countries "mature" and what is Apple doing in China and the new relationship between Apple and strategic partnerships and the new stats from WWDC 2012 about developer revenues and how that differs from Android and the 400 million Android devices activated vs. 400 million iOS devices built, in China.

    via 5by5 | The Critical Path #42: Full Circle.

  6. The iOS App market sales run rate is $4 billion per year

    Research · 53 comments

    At the 2012 WWDC, Apple released new data concerning its App ecosystem. Namely:

    1. 30 billion apps downloaded to date (excluding updates)
    2. $5 billion paid to app developers
    3. 400 million iTunes accounts

    These three data points allow us to update our picture of the app economy. First, the app download rate.

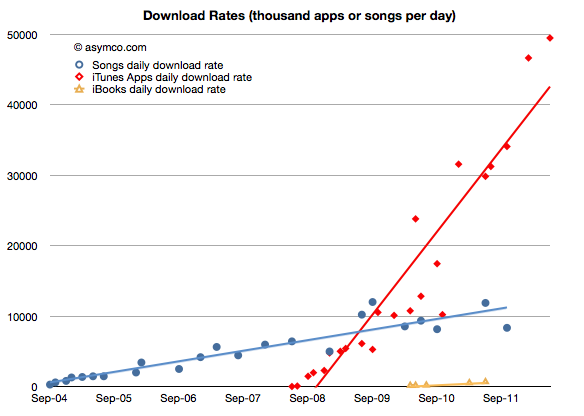
    As would be expected from an expanding user base, the app download rate has been increasing. It is now at about 49.5 million apps downloaded every day. The history of this rate is shown in the chart below:

    I added the same data for iTunes songs and book downloads for comparison. Note that although music and books are available to the same user base (actually higher due to Macs and iPods which do not run apps,) apps are being downloaded at a far faster rate--at least four times faster.

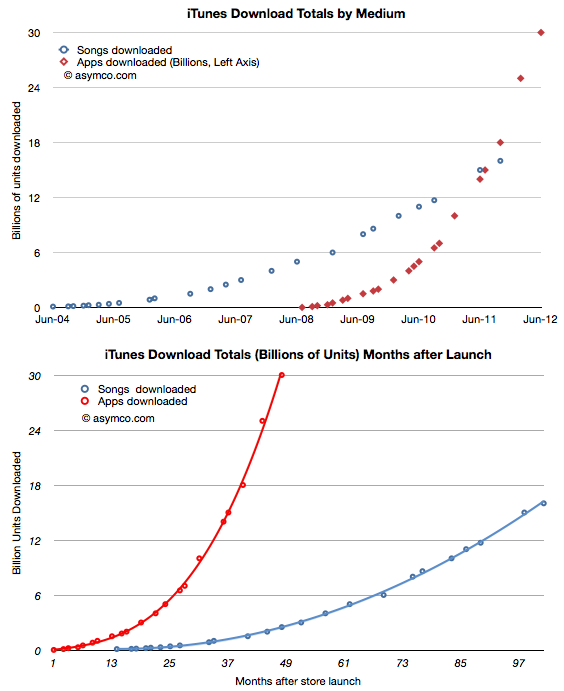
    In terms of total, cumulative downloads, the comparison is even more stark:

    It won't be long before total app downloads will be double total song downloads. Put another way, in the time it took the App store to reach 30 billion, the song store sold only 3 billion.

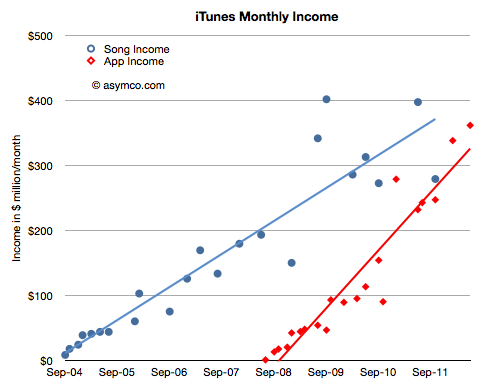
    On average, songs are more expensive than apps ($1.29 vs. $0.24). What is the difference in value, not just units?

    The data shows that apps have very likely overtaken songs as "gross" income. Apple does not book all app income, only the 30% share they keep, but in terms of transaction value, clearly apps are now a bigger business.

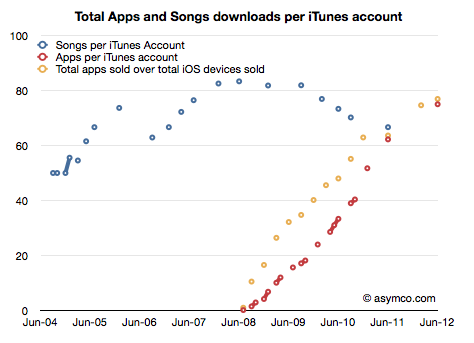
    What about consumption? Are individual iTunes account holders buying a constant or variable number of songs or apps?

    Here again apps show a distinctive pattern of out-performing songs. As far as digital media is concerned, apps are taking the download business by storm.

    What about pricing? Is the expansion of the user base into the hundreds of millions leading to a collapse in app pricing?

    No. You can see the price as the ratio between the downloads and the revenue to developers. If downloads scale more rapidly than payments then pricing is decreasing. As it turns out the average price of an app has held steady since approximately 1 billion downloads were recorded. That price is now about 24 cents per app (including free).

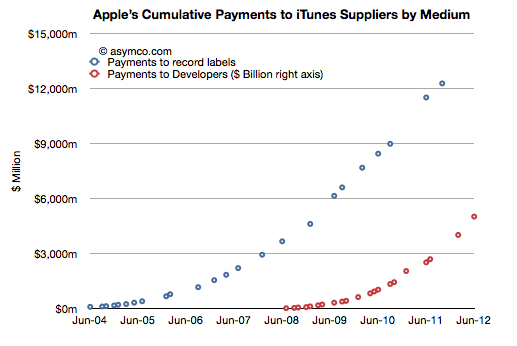
    Finally, how about the content owners? Are payments to the owners of the media beginning to favor developers over music publishers/promoters?

    Developers still have a long way to go. We can't be sure about how revenues are shared with music labels, but it's probable that they are still receiving bigger checks than developers. However, under some scenarios this will change quite soon.

    The bigger story here is that the iOS app economy has reached a run rate of $4.3 billion per year from a standing start four years ago.

    How big will the TV app economy be four years from the launch of an Apple smart TV?

  7. The Critical Path: The First Year by Horace Dediu — Kickstarter Funding Successful

    Podcast · 7 comments

    I extend a heartfelt thank you to all 831 backers of my first Kickstarter financed book project. Thanks to you not only will there be a way to refer to and cite the podcasts but, since the project reached 980% of its target, the project allows me to explore new means of publishing and content production.

    Clay Christensen said that a disruptor should be patient for growth but hungry for profit. The Asymco experiment is continuing and is staying true to this principle.

    The Critical Path: The First Year by Horace Dediu — Kickstarter.


  8. Estimates for Apple's third fiscal 2012 quarter

    Research · 62 comments

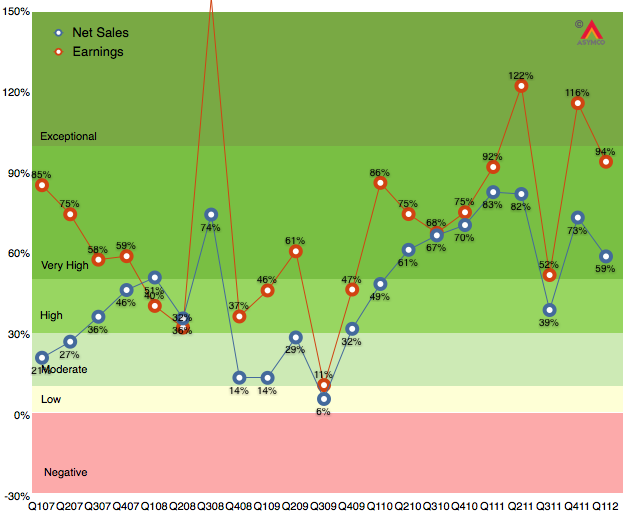
    As the chart below shows, the last quarter (first calendar 2012, second fiscal 2012) was robust with 94% earnings growth and 59% net sales growth. Subject to the usual superlatives, the performance was, again, unexpected by many.

    Much of that surprise was due to the underestimation of iPhone sales in China during what is a holiday quarter in that nation. Growth this quarter will be more difficult to estimate. The iPhone is still the most important component but the iPad is becoming increasingly decisive in overall performance. In fact, I'm projecting that the iPad will have the equivalent of 73% of the iPhone revenues this quarter.

    In this quarter the iPhone is reaching a late stage in its launch cycle but it continues to reach more points of purchase through distribution agreements and it also has a "portfolio" in terms of multiple price points and models available.

    The iPad was supply constrained last quarter and may be in balance this quarter. Management has very clearly and repeatedly signaled that the iPad will have a very strong quarter.

    So with these clues, here are my estimates for the quarter (with y/y growth in parentheses):

    • iPhone units: 28.5 million (40%)
    • Macs: 4.5 million (15%)
    • iPads: 24 million (160%)
    • iPods: 6 million (-20%)
    • Music (incl. app) rev. growth: 35%
    • Peripherals rev. growth: 20%
    • Software rev. growth: 15%
    • Total revenues: $41.9 billion (46%)
    • GM: 44.8%
    • EPS: $11.54 (48%)

    This earnings value would imply a trailing twelve months’ EPS of about $44.8. At the current price of $571/share the P/E would be 12.7[1]. Cash and equivalents will probably increase to $118 billion.

    ---

    1. Apple's P/E also dropped to 12.7 around Christmas 2008. I did a search for some headlines to recall that time and came across one that seems appropriate: "Unrest Caused By Bad Economy May Require [domestic] Military Action, Says US Report".
  9. 5by5 | The Critical Path #41: Contextual Inquiry

    Podcast · 2 comments

    Dan and Horace talk about the distinction between what Facebook is and what its value is perceived to be. We touch on both the opportunities and the challenges for social media and how these are reflected in the IPO. We note how and why Facebook integration in iOS might happen. Horace has a few words about China, WWDC, and the future of apps on TVs. It's all about context.

    5by5 | The Critical Path #41: Contextual Inquiry.


  10. Asymmetric competition | Horace Dediu | Mobilism 2012 on Vimeo

    Research · 12 comments

    Here is a video of my presentation at Mobilism 2012 on the story of mobile phone disruption. Thanks to Peter-Paul Koch (aka PPK) for organizing a great event and allowing me to present to such a smart and knowledgeable audience.

    Asymmetric competition | Horace Dediu | Mobilism 2012 on Vimeo

    Nearly one third of the time is spent in Q&A, which, even if I do say so myself, is the best part.

    Also note the exclusive use of a custom iPad app for wireless presentation (pre-release version of the Perspective App.)