Asymco

Asymmetric Intelligence

RIMM

  1. [Updated] RIM's sales down 15% in the US, up 112% outside the US

    Research · 41 comments

    First, a round-up of the quarter's numbers:

    • 14.2 million devices shipped, sell-through: 12.3 million
    • expect to ship 14.5 to 15 million units in the next quarter
    • ASP of approximately $315
    • US, UK and Canada are 56% of sales
    • US represented 34% of the total revenue
    • Last year US represented 57% of revenue
    • BlackBerry Torch launched in over 75 new markets, Torch launched with the $99 pricing from AT&T
    • BlackBerry Curve 3G launched with 118 carriers in 48 countries
    • China Mobile introduced BIS for small-to-medium sized businesses. The service starts at $14 per month
    • App World applications grew 60%
    • More than 16,000 applications available
    • 2 million downloads daily
    • 1,000 vendors registered for PlayBook apps
    • Revenue: $5.5 billion
    • Net subscriber additions: 5.1 million
    • Top three customers: 12%, 9%, and 9% of revenue
    • The same quarter a year ago: 25%, 13% and 10% of revenue
    • Service revenue in Q3: $835 million
    • Software revenue: $78 million
    • Gross margin in the quarter was 43.6%
    • Cash: $2.5 billion

    For comparison, here are a select few vendors' smartphone reported shipments. RIM is the first to report and we'll be hearing the the rest by the end of January.
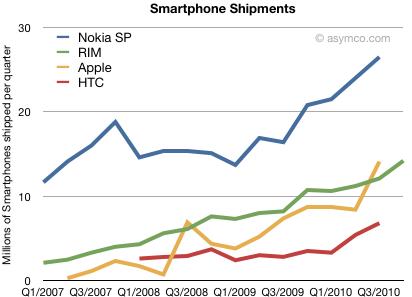
    The number most RIM "bears" focus on is the new subscriber additions. At 5.1 million out of 14.2 million units sold implying that the new subscribers added per unit sold is 0.34, a new low.

    The bulls will argue that the gross margin is healthy and slightly higher than anticipated.

    My observation is that the company is finding growth outside its traditional markets. Given the figures above, the US went from $1.65b in revenue to $1.87b; a mere 13% growth while the company experienced 89% overall growth in revenues.

    The following chart illustrates the situation:
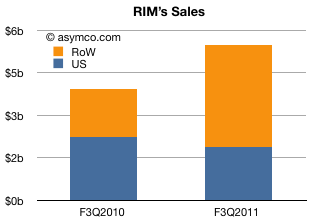
    Of the total increase in sales ($1.6 billion), the US contributed -15% while the rest of the world accounted for 112%.

    This can be seen as positive news since RIM has been weak internationally for many years and they really need to penetrate world markets. However, a -15% growth in the US is implies significant share loss in a rapidly growing and traditional stronghold.
  2. Android is a BlackBerry killer

    Research · 2 comments

    Much has been made of the potential for Android to reduce the growth of iPhone. The iPhone seems to be doing very well and continuing to be supply rather than demand constrained.

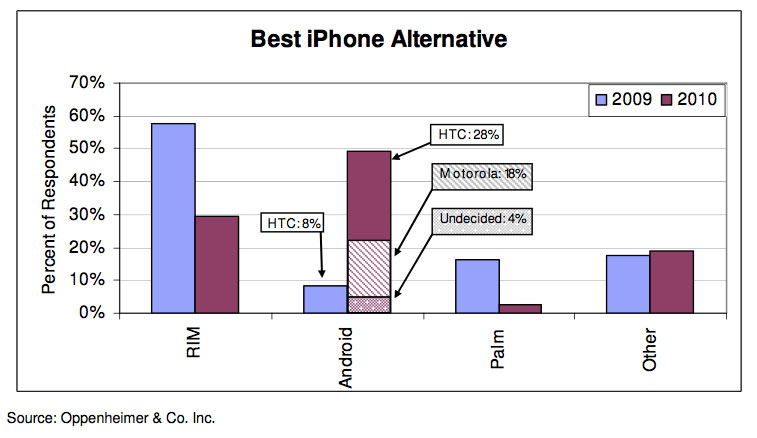
    RIM however seems to be under significant pressure.  A Goldman Sachs analyst first pointed this out in her last report and placed a "Sell" on RIMM.  The fact is that most of RIM's sales are in the US on the carriers other than AT&T.  In those very same carriers, Android is being pushed hard as a customer retention strategy, so iPhone is pressuring RIM only indirectly through Android.

    The evidence is also in survey data.  In the graph below, we see how iPhone buyers are considering Android as the most credible alternative to the iPhone whereas they considered BlackBerry the best alternative a year ago.  In terms of vendors, what RIM lost HTC gained.

    One can only wonder what will happen when the iPhone enters unrestricted distribution in the US.  The results in other markets speak for themselves.

    AppleInsider | Apple's recurring revenue stream: 77% of iPhone 4 sales were upgrades.

  3. RIMM near 52 week low

    Research · 1 comment

    RIMM shares dropped more than 5% after hours after company reported "light" units and a 20% rise in profit with a 24% rise in revenue.

    RIMM sold 11.2 million units (of which 4.9 million were new subscribers and the rest replacement units--a deterioration in replacement rate). This represents 43% growth. The unit growth is nearly double the revenue rise implying a lower ASP ($300--half the iPhone) and margin (45.4%).

    RIM passed another milestone: 100 millionth BlackBerry was sold during the quarter. We've noted before that Apple will also pass its 100 millionth iOS device this month. RIM sold 20 million units as of October 2007, right on the heels of the iPhone launch. That means that iOS grew 100 million to BlackBerry OS growing 80 million in the same time frame.

    So why are shares at a P/E of 13? 20% EPS growth would be respectable numbers, but the smartphone market is growing faster than that. The implication is that RIMM is losing share and everyone is expecting that loss to accelerate.

    Simona Jankowski from Goldman Sachs repeats her Sell rating. “RIM has now missed top-line expectations for three of the last four quarters, in our view demonstrating the building competitive pressures on its business from the iPhone and more recently from Android,” she writes. “We estimate that net subscriber additions in North America declined on a sequential basis, which we attribute primarily to the success of Android-based phones, such as the Motorola Droid and the HTC Incredible at Verizon.”

    Research In Motion Limited (USA): NASDAQ:RIMM quotes & news - Google Finance.

  4. iPhone OS download rate 10X Blackberry

    Research

    Today, Research in Motion co-CEO Jim Balsillie said his BlackBerry App World has 20 million registered users and nearly 1 million daily app downloads.

    via Apple Doing 10-20X As Many App Downloads A Day As BlackBerry.

    As previously stated, The App download rate increased to a record 10,753,000 per day during the last 90 days.  That makes the download rate for the iPhone platform 10x that of the Blackberry Platform.  The iPhone platform is nearing 100 million installed base.  Blackberry is citing 20 million registered users.  I think everyone is pretty clear on where this is going.