Asymco

Asymmetric Intelligence

Theory

  1. HP's decade-long departure

    Research · 221 comments

    HP's sudden departure from a business model that has sustained the company since inception is symptomatic of the passing of an era. Yesterday HP announced that it would exit the PC and tablet computer business, focusing on higher-margin "strategic priorities of cloud, solutions and software with an emphasis on enterprise, commercial and government markets." In other words, HP is fleeing upmarket, away from a core that it will abandon to device makers.

    HP management conceded that the disruptive impact of the iPad forced their hand but that hand was already quite weak from a decade of over-serving the market. The last decade offered plenty of opportunities for incumbent PC companies to adjust to the realities of mobility. However only one computer maker made the transition.

    Why is that?

    Consider how HP and Apple faced the changes in the PC market almost exactly a decade ago.

    • On September 3, 2001, HP announced that they would acquire Compaq.
    • On October 23, 2001, Apple announced the iPod.

    The rest, as they say, is history.

    But what would any reasonable person have done? The PC industry was no longer young but still thriving, why not consolidate? Consolidation is a natural and well-reasoned practice for maturing industries. You get rid of over-capacity, you consolidate overhead, "leverage synergies" and boost margins.

    And it's not like they were ignoring innovation. Compaq had a growing line of PDAs, so there were plenty of diversification opportunities. Microsoft was offering Pocket PC and the Phone edition was on the roadmap. HP was clearly watching mobility carefully.

    Contrast that with Apple's predicament. Which aspiring manager would want to deal with the disaster that was Apple at the time? Apple was struggling with a declining Mac business and had just re-booted it with OS X but it seemed a quixotic effort. Moving to music players seemed desperate (and late). Margins were low, commodity vendors were lining up, record labels offered resistance, they did not have any IP or any DRM and nothing but Mac users as target audience.

    As it turns out, the path of sustaining and the path of disruption diverged that moment in time a decade ago. Companies like HTC, Apple and RIM were embryonic in their device businesses vs. Goliaths like Microsoft, HP and Dell. But they grew, at first slowly, but at all times profitably.

    By the time their success was worth noticing, in 2004, HP and Dell decided to dabble in devices. But all their efforts were half-hearted. They did not crave profits but growth and share. HP's PDAs and phones never received management attention. How do I know? Because they relied on off-the-shelf components for everything including software. It indicated that the value to be offered was in "leveraging" (there's that word again) their brand and distribution. The value of HP was not to build something great--something that required blood, sweat and tears.

    The result was a set of mediocre experiences while the (now incumbent) Apple was iterating rapidly into new directions. By the time the future was self-evident, it was too late to build foundations. HP did the right thing to acquire Palm, but they did it far too late. In 2010 the game was over.

    How cruel.

    But that's the nature of unforeseeable growth: you cannot foresee what will happen and plans never work out. Data and planning don't help. The lesson is that you need to plan for that which cannot be planned. When you are at your peak you must assume failure is imminent and when you are at the trough you must assume success is inevitable.

    All failures of strategy are rooted in the assumption that outcomes are predictable.

    This is why I expect Apple is now working on shaping the post-iPhone world.

    --

    Update: This article has also been published in the Harvard Business Review blog: HP's Decade-Long Departure - Horace Dediu - Harvard Business Review

  2. The fate of mobile phone brands

    Research · 97 comments

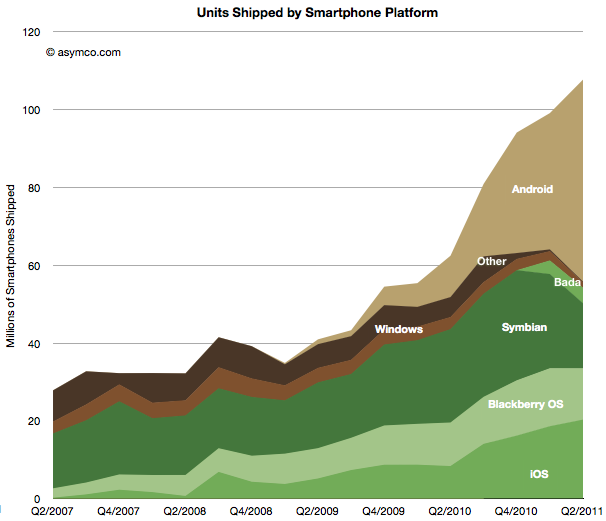
    The violence with which new platforms have displaced incumbent mobile vendor fortunes continues to surprise.

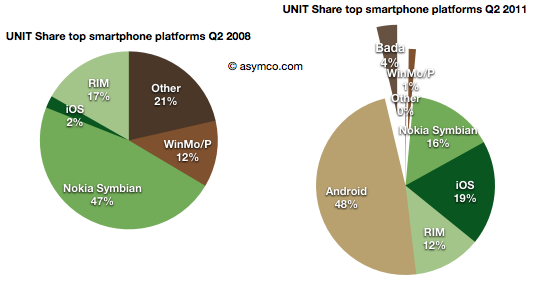
    • Nokia's Symbian platform has gone from 47% share to 16% in three years
    • Microsoft's phone platforms have gone from 12% to 1%
    • Other platforms have gone from 21% to zero
    • Although far less dramatic, RIM's decline from 17% to 12%  is causing acute pain and anxiety

    This while entrants have grown share in spectacular fashion:

    • Android from zero to 48% (A two year period)
    • iOS from 2% to 19%
    • Bada from zero to 4% (two quarters only)


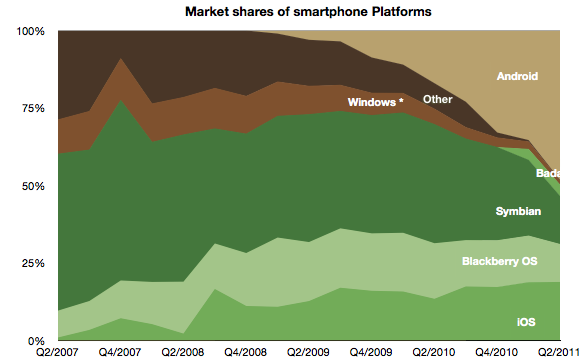
    The picture of platform share over time looks like this:


    The platform volume growth is shown in the following graph:

    Shocking

    Or is it?

    The surprising thing is that it should not be surprising. When the iPhone re-defined the basis of competition (at the beginning of the time frame of these charts) it unleashed forces which are still spinning the industry into a new configuration.

    In that context, Android is a natural consequence. As iPhone created a threat, the response from all other vendors (other than Nokia and RIM) was to seek something that would sustain their business. Android was salvation.

    It enabled the pursuit of better margins and hence better returns. So much so that Android offers the escape up-market they have always sought. It enables vendors to abandon the profit-free feature phones to low-end entrants like ZTE and Huawei.

    LG, Samsung, Motorola and Sony Ericsson all took the bait. They are racing as quickly as possible to turn their feature phone portfolios into Android portfolios. This is certainly something that Google also wants to see happen and has been planning all along.

    However one of the consequences of the modular (aka "open") approach is that the low end disruptors gobbling up low-end share are also motivated to move into the Android business as soon as it comes within reach.  The only reliably predictable consequence of Android will be the postponement of displacement of the existing brands by the low-end entrants.

    Is this fate unavoidable for all brands?

    Clearly some vendors see the trap. For all its apparent failings, Nokia saw this outcome and chose to attempt a "Hail Mary Pass" with Microsoft. The strategic point being that because they no longer had faith in their ability to execute on an independent platform, they would pick a platform that gave them at least some control or leverage. There are serious risks and problems with this approach--something which has been covered here already--but the bet being made is a clear rejection of the slippery Android slope.

    RIM is trying to resist with QNX which is a similar approach but timing may also be the undoing of this strategy. HP's approach with WebOS and Samsung's Bada are also hedges to avoid this fate.

    And what about Apple?

    Apple is always skating in a different direction. iOS needs to be seen as not so much a phone platform but a computing platform. Given what we know, iOS was always conceived as the future of computing. Voice, after all, is just an app on iOS. So my expectation is that Apple's iOS will continue its attack on the mobile computing market, skimming (or carving as the case may be) profits from the phone business to sustain its ultimate target of reclaiming the computing universe.

    By this thinking iOS lives only by improving more rapidly than anything else in dimensions that redefine the basis of performance. In other words, doing more of what the iPhone did in the first place to set off this disruption.

  3. A new way to value Apple

    Research · 38 comments

    Almost all valuation models for Apple assume it's a hardware company. The modeling algorithm for hardware is simple:

    • For each year in near future
    • For each product line
    • Compute contribution
    • Determine company value by summing contributions and multiplying by a P/E ratio

    The major difficulty is in predicting the growth of each product line. This is difficult because buyers can be fickle. Companies employs all sorts of tools in order to secure repeat customers but if switching costs are low, the company can crash in value. For this reason, analysts pick various ways to predict device  sales. Some choose to index each product on production (channel checks), demand (customer surveys,)  or even on a top-down share of total (market research on growth of whole market and assumptions of share).

    Although simple and convenient, this model does not probably match the way Apple is managed. The company does not build hardware products to sell and forget. It builds platforms which are best seen as sources of recurring revenues. Users are incentivized to continue buying devices. iCloud, iTunes and other Apple properties are expressly designed to that goal--and they are not cheap to run. So, the company must see the world through a different set of lenses than the default model shown above.

    To think about the business like they do, we need to put the data through a similar set of lenses. I began with a modest proposal last month to value each user as a source of recurring revenue. Now it's time to expand on this method.

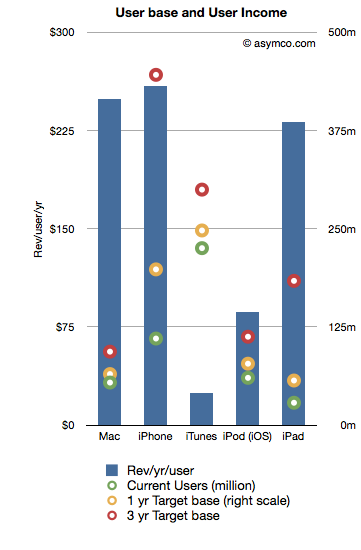
    The following chart shows the recurring revenues per user by product and the current and possible future size of user bases.[2]

    Revenues/yr/user are bars with the left axis and the User bases are various colored circles indexed with the right axis.

    The assumptions that went into the data are as follows:

    1. Device life span is as per previous article linked above
    2. User base growth for 1 year is: Mac 20%, iPhone 80%, iTunes 10%, iPod 30%, iPad 100%
    3. User base growth for 2nd and 3rd years (recurring): Mac 20%, iPhone 50%, iTunes 10%, iPod 20%, iPad 80%.
    4. The Revenue per user is assumed constant

    Note that the user base growth figures are lower than the product growth levels seen historically. Obviously, the model is highly sensitive to these growth assumptions so they need to be scrutinized and tested rigorously.

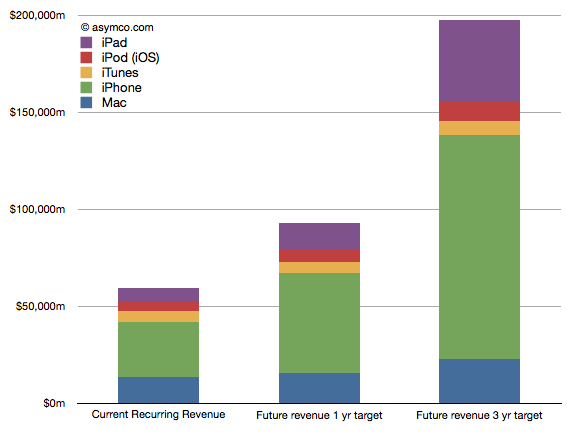
    Nevertheless, as a straw-man proposal,  the recurring revenues for all these products[1] is shown in the following chart:

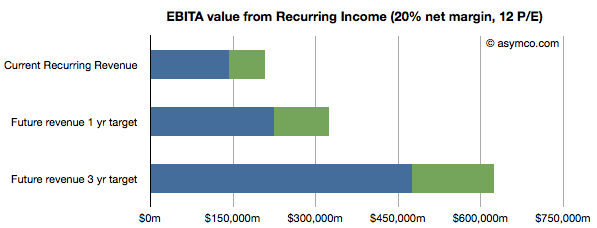
    Once the income is estimated, we can take that value and assume a profit margin (net) and then multiply the earnings by a multiple. Using a 20% net margin and 12x P/E yields the following chart.

    (I added an assumed level of cash in green.)

    This model would imply that the company today could be valued at $208 billion on the basis of its installed base alone. That value would be about $323 billion in one year and $620 billion in three years. Dividing by the number of shares outstanding (935m this year increasing at 2% a year) yields a share price of $222, $339 and $629 by mid 2014.

    These values can be considered "lower bounds" on valuation since they assume income from previously secured customers. The speculative part of investment would be based on what the future bases will look like (so, for example, if one believes these assumptions, the $629 figure could be considered a target to be discounted to today).

    ---

    Notes:

    1. Excludes Software, Peripherals, non-iOS devices, and any other service revenue.
    2. Compare this char to social media companies (MIT Technology Review)
  4. The Frontiers of Platform Adoption

    Research · 46 comments

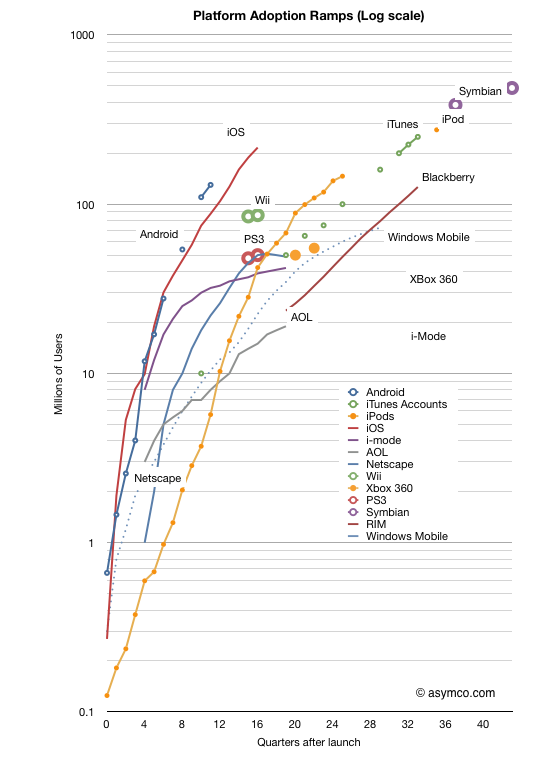
    In the last two weeks we received two more data points which allow an update to the "race to a billion" platform growth trajectories. Android reached 130 million active users and iOS reached 200 million.

    The updated picture looks like this:

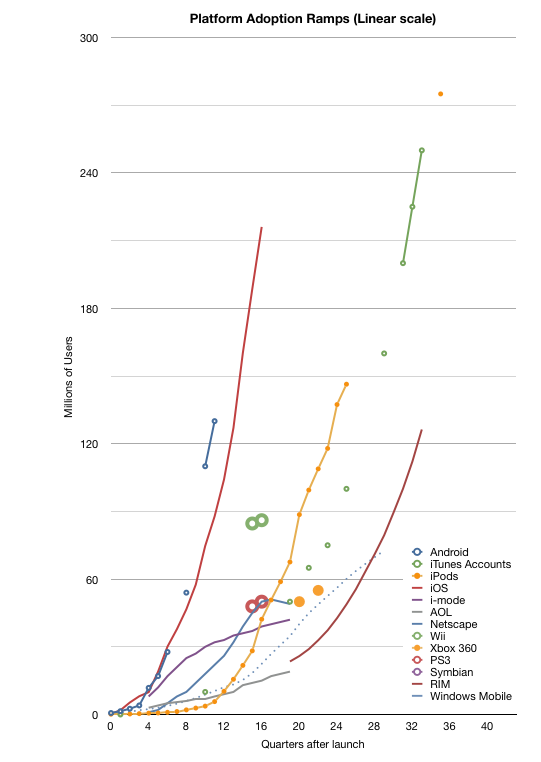
    Note again that this is a log scale graph. Every major horizontal gridline is an order of magnitude (10x) larger than the one below. It's a busy graph. The linear version follows:

    For the detail-minded, it makes for some interesting comparisons, but I want to create a more compelling visualization. One where each platform can be judged for potential and impact at a glance.

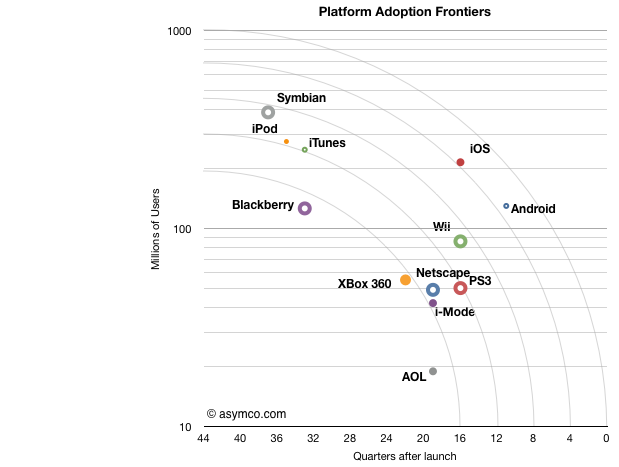
    To that end I came up with something I call the platform "adoption frontier" view. Based loosely on the Pareto efficiency concept the chart is reduced to show the latest known figure of (users,time) and overlay concentric arcs centered on 10 million/10 years and radii of unit years (x-axis).

    Note that the time axis is reversed from the chart above. This was to allow the best performers to be shown at the upper-right of the chart.

    The way to read this is as follows:

    • Each platform is represented by a point which shows its currently known peak in users and time to reach that number of users.[1]
    • The arcs (frontiers) represent possible performance classes.
    • The lowest frontier spans "four years to reach 10 million" to "10 years to reach 200 million". The highest frontier spans "<1 year to reach 10 million users" to "10 years to reach 1 billion users". Each frontier can be read in a similar way.
    • The main assumption is that a platform can reach more users but it takes time. Better performance is when a platform moves toward a frontier further from the origin.[2]
    • I chose the limits of the chart specifically: 10 years is roughly the limit of most platforms[3] in the current cycle time of technology disruption; One billion users is an upper bound set by Windows.

    One thing you can read from the chart is to say that "from a growth point of view, Blackberry is weaker than any of the other platforms." Sitting below the lowest frontier with fewer users than Android which has been in the market for less than a third of the time it seems to be less impressive. It is, however, in a similar band of growth as Xbox 360, which, by some measures, is a success story. So the performance standard is relative.

    One can also see the rough equivalence in growth between iPod and Symbian, both having crossed the second frontier. But iOS and Android are in a different league. They sit alone beyond the fourth frontier. The fifth frontier is the "billion user in a decade" potential and it seems within reach for both.

    What this view also offers is an answer to the question of competitiveness. Although platforms can co-exist and don't necessarily overlap, the question of becoming overwhelmed with "good enough" by widespread low end alternatives looms for the specialized platforms. For example, game consoles look very vulnerable because they simply do not have the potential to cross high frontiers and orders of magnitude of casual gamers (with potential TV connected devices) might orphan the consoles.

    I've also included some platforms that have peaked and faded (AOL and i-Mode and Netscape) as a warning. The frontiers illustrate of how hard it is to reach the upper limits of growth. Each level is exponentially more difficult than the last and achieving it with paying customers is a remarkable story of value creation.

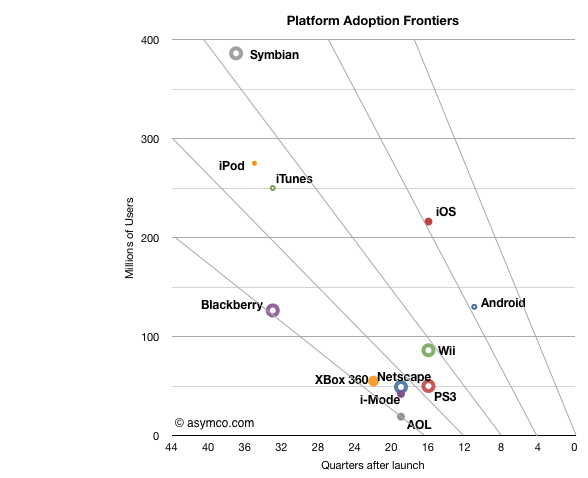
    [UPDATE]

    I add below the frontier chart with a linear vertical axis. Note that the frontier lines are not equivalent to the frontier arcs in terms of coverage.

    ---

    Note:

    1. The data I have is for platforms where users have to pay something to participate. I exclude platforms where users are the only merchandise being sold (i.e. social networks or email provision).
    2. I only include the initial ramps not upgrades. Windows is anomalous because it is so old. During its first decade (1985 to 1995) it reached over 17 million users but placing it on this chart does not do it justice given the growth occurred in its second decade.
    3. See Symbian and Windows Mobile. However again, Windows which is nearly 30 years old, is an exception.


  5. The Android (in)adequacy: How to tell if a platform is good enough

    Research · 97 comments

    About 10 years ago I met an advertising executive in New York who explained the difficulty of advertising a new brand of deodorant to consumers. “Most people never change their deodorant,” I remember him saying. “They pick one brand when they are young, and stick with it for a long, long time. If it works, why switch?”

    The same theory can be applied to customers who are making the switch to smartphones today. Once they have picked a type of phone, whether it’s Apple iOS, Google Android or something else, it’s difficult, and often expensive, to switch. Consumers become comfortable with the interface and design of the phone and the apps they have purchased on that platform. If it works, why switch?

    Many Smartphone Customers Are Still Up for Grabs - NYTimes.com

    This quote says a lot. The notion that customers remain captive to a platform is well understood. After all, it seems impossible to get people to switch out of Windows (or Mac or iPod). Platform vendors are aware of this as the land grab for users seems to be running at full pitch.

    However, there is a critical condition described in the quote above: "If it works, why switch?"  The condition which keeps users loyal is that the product they chose is good enough--i.e. "it works." That's a symptom of over-service and commoditization. If a product, like deodorant, is good enough you won't be tempted to move to another brand even if it's marginally better since the new brand has switching costs in the form of uncertainties ("Will it be as good? What if I don't like the smell? etc.) People are inherently conservative and you can't compete with comfort and familiarity by launching a marginally better product.

    So with that in mind, why is it that millions are switching mobile platforms?In this blog I've cataloged the massive shifts occurring away from mobile platforms that have been around for years with deeply entrenched user bases. Microsoft's Windows Mobile, Nokia's Symbian, Palm's PalmOS and RIM's Blackberry have collectively lost tens of millions of users. A net of half a million Blackberries are being abandoned in the US every month.

    So we would need to say that the condition of "it works" or being good enough was not met with those platforms. The attraction of something better is clearly greater than the switching cost.

    So this highlights a good test for how to tell if smartphones are good enough: If users are fiercely loyal with a given platform then it's probably good enough but if they are willing to switch (i.e. disloyal) then it's probably not good enough. It seems like a trivial observation but it's a very important clue to the bigger question of whether we can "call the end" of the market. Just like it would have been premature to call the end in 2006 when Symbian and RIM seemed unbeatable, it will seem premature to call the end now in the event that a significant innovation is yet to appear.

    The correct calling of the end has profound investment implications. Do you (like Microsoft) invest billions in a new platform if you know that there is no more room for entrants? Should Samsung bother with Bada or HP with WebOS if the game is already over? Even more, should Apple even bother to improve iOS if they have no shot at switching a billion likely Android adopters. Why not just nurture the current installed base and work on building walls and moats around them?

    So with this hypothesis in mind, it makes sense to analyze whether Android or iOS, the current presumed champions, are "good enough" on the basis of how often users switch out of them. My bet is that neither is good enough and that there will be increasing churn between platforms. I imagine that Android is less sticky (and hence less than good enough) based on app consumption but there is little evidence of churn because most phones in use have been bought less than one device generation ago. More importantly, there have been few opportunities yet for switching as many Android buyers don't even have the choice of other platforms either due to where they live or how much income they have available.

    To really tell where we stand, we would need to collect stats on switchers to know just how satisfactory the platforms may be. Remember that a choice of a new deodorant on the same shelf at nearly the same price is the test for loyalty. For an adequacy test we need to see better distribution and more choices for consumers. It's still very early even in the US for any conclusions to be drawn about the adequacy of Android.

  6. Is Nokia worth less than Skype?

    Research · 57 comments

    Yesterday Nokia warned that its guidance for the quarter and the year were "no longer valid." The surprise to me is that management was surprised. In February I warned that even if Nokia could fool consumers into buying products whose platform was publicly executed, distributors and operators would not likely go along with the deception. Pricing collapse is the proof of a channel breakdown.

    That seemed predictable. What I struggled with was how Nokia itself could present such an optimistic forecast. Absent any explanation, Nokia's forecast of robust sales for Symbian products into the near future belies a failure of understanding of the dynamics of platforms and especially the impact of destruction of trust and brand value that commenced in February. Distress is a slippery slope and it does not model well in a spreadsheet. It takes a leap of non-linear faith to predict the piling-on effect on the up- and the down-side.

    Faith in the company's guidance meant that the market reacted to the bad news by discounting Nokia down to a market cap of $26.7 billion. One analyst even cut his target price down to $4/share, 57% of yesterday's close. How can this fair? What is Nokia's phone business worth?

    Here's a quick sum-of-the-parts analysis. After yesterday's hair cut Nokia's overall enterprise value is about $20 billion. The Navteq part of the business (purchased for $8.1 billion in 2008) could get a value of $3 billion (based on about 3x sales) and the value of Nokia Siemens networks could be at $6b (less than 0.5x sales). That makes Nokia's phone business worth about $11 billion.

    An alternative view based on "the Motorola case study" $4 target price would imply an overall enterprise value of $11 billion. This either makes Navteq and NSN worthless and Phones worth $11 or it makes the phone business worth a lot less than $10 billion. Perhaps less than $8.5 billion which is what Microsoft paid for Skype. Should we be shocked? Nobody would argue that Nokia is worth more than Facebook so who's to say that Skype or Twitter aren't more valuable than a device company in crisis?

    I don't try to predict the market's behavior, nevertheless, the markets are now very skeptical that there is much in Nokia to salvage. It's perhaps unfair and illogical but this is the end game of disruption. It ends much more suddenly than it begins. It's the consequence of nobody noticing the beginning that makes the end so shocking.

  7. Is RIM's management the cause of its failure?

    Research · 61 comments

    "Jim and Mike brought the company to where it is ... which is part of the biggest problem they're facing," said Charter Equity analyst Ed Snyder, who has covered RIM since its public listing in 1997, two years before the BlackBerry was launched.

    "They're stuck in the past. They know what worked and keep playing that card and it's not working any more, and they don't seem to have any ideas," he said.

    via BAY STREET-As RIM struggles, talk of a change at top surfaces | Reuters.

    In the case of Apple, the departure of the founder is considered a grave threat to the continuing success of the company.

    In the case of RIM and Microsoft, the continued tenure of the founders is considered a grave threat to the success of the company.

    Clearly, the theory that founders of successful companies can assure continuing success is flawed. Coupled to that implied causality is that departure of founders is always a problem.

    Both are reflections of the idea that companies are predominantly successful (or fail) because of the skill (or incompetence) of a small group of individuals.

    What the idea fails to explain is why companies fail (or succeed) as a cohort. RIM's troubles are similar to Microsoft and to Nokia's. Did they conspire or collude to fail simultaneously? Historically, incumbents fail simultaneously, regardless of who's in charge.

    And what about the problem that a company goes from success to failure (and vice-versa) while the same management is in charge. The "smart manager" theory of company success is as pervasive as the "stupid manager" theory of company failure. The perplexing thing is that while both of these theories are applied within the lifetime of a company, the management does not change.

  8. Did Microsoft pay for the wrong Skype?

    Research · 51 comments

    When a company is acquired, the price paid is usually higher than what the company is worth. This is because there is a "control premium" that needs to be paid so that the acquiring company can control the destiny of the acquired company (while the seller loses that right). So the question has to be what does the premium (or excess cost) buy? What is the value of that control? What will be the new destiny? Whose destiny is changed?

    Clayton Christensen succinctly defined the value in any company as the sum of three constituent parts: resources, processes and business models. Market value can be nothing more and nothing less than these three things.

    An acquisition has to be positioned on one of these targets just like a product is positioned on a specific market. The problem with being deliberate about where the value lies is that once positioned a certain way, the integration team will begin to execute on that plan. This means that the thing you decided was worth most (e.g. resources) gets all the attention and the other potential sources of value (processes or profit models) are discarded.

    This argument reduces to there being three separate companies being available. The buyer pays for all but gets to keep only one.

    When you look at it this way you realize that the reason most acquisitions fail is that the buyer throws away most of the real value in the company.

    For example, when looking at Skype through Microsoft's eyes, they could be valuing it for its resources (employees, management team, customers, or intellectual property.) Or they could be valuing its processes (how it makes software and how it recruits customers) or it could be its business model (viral distribution, very low prices with wide distribution, plan to disrupt telecommunications). Each of these is a separate, mutually exclusive deal with separate integration plan and separate strategic justification. Each is targeting a separate Skype.

    If Microsoft were to pay a premium for Skype's resources then they will probably not make use of the processes or business models. There is some value in this Skype. Microsoft could use the customer base to sustain their existing businesses and to up-sell services.

    But what if the real value is not in resources but in the business model? A model which would allow for Microsoft to disrupt its core business. Perhaps Microsoft could use the Skype approach to creating new customers, eliminating its partner network and expensive direct sales force. This would be a different Skype. It would have the potential to transform Microsoft. Microsoft could become what Skype is now: a communications network or carrier that disrupts the way people use network operators.

    This type of value exists in Skype but its asymmetry with Microsoft's core would make it a very tough sell internally. A recent article pointed out that when Skype was up for sale last time, Google's acquisition was sabotaged internally by people who realized that peer-to-peer would be "incompatible" with the centralized architecture of Google's services. If not for the effort of certain individuals, Google might have ended up with Skype and destroyed it with internal antibodies.

    Chances are that Microsoft paid for Skype's customers and engineers but will not apply the innovations of viral peer-to-peer distribution or disruptive voice pricing. If that happens then perhaps Microsoft will pay $8.5 billion for the wrong Skype and telecom disruption will find another home.

    Notes:

    Adapted from an answer published in Capital.bg. My thanks to Adrian Georgiev for asking the right questions.

  9. A new era is only a new state of mind

    Research · 51 comments

    The following interview was conducted by Bruno Ferrari a writer about technology for EPOCA, the weekly magazine of Organizações GLOBO, the largest Brazilian media company on March 30 2011. The article (published in Portuguese here) is an edited subset of the following exchange.

    Q: In your analyses, you mention tablets as part of a new era, the “Post PC era”. Why do you think the PCs will be replaced by tablets?

    This is not quite correct. Post PC does not mean the end of the microcomputer. The way to think about it is this: The stone age did not end because we stopped using stones. Same with the iron age and the industrial era. The era of jet travel did not end automobile or even ship travel (though that changed to recreation rather than transportation for passengers.) Each phase of technology does not fully replace its predecessor. It offers a new set of solutions and perhaps a slightly different way of solving old problems. We'll still have PCs but we will use a new type of computer, an even more personal computer. The world still uses the microcomputer's technological ancestors.

    In terms of what new jobs will we hire the tablets to solve, they will vary greatly from what we used PCs for. Just like we used microcomputers for different things than we used time-shared minicomputers and mainframe computers. I expect social interaction, media consumption and entertainment will move from a PC to a tablet. New uses will emerge from the vast experiment that is the app phenomenon.

    Q: What are the new ways to interact with machines? With gestures? How will this change the market?

    Each major disruption of computing came from a new generation of input and/or output methods. Terminals (vs. punch cards) enabled minicomputers. The GUI enabled the rise of the microcomputer and touch is enabling the rise of the tablet. Perhaps this era will last decades perhaps only years, but there will be new input and output methods available. The world's research laboratories are filled with ideas from projection screens (from high brightness LEDs) to motion sensing (as implemented partly by Kinect) and even novel voice control methods. I believe that each major innovation will create a new wave of growth and, if coupled with a new business model, a new set of companies and platforms.

    Q: What are the main differences between PC and Post PC era?

    The main difference will be in the context in which the product will be used. Tablets and smartphones allow "computing" to be done in previously non-consuming contexts: while standing, while in the active company of others, while commuting or while lying back and relaxing. It will also allow more individual use. Like the transistor radio allowed teenagers to listen to rock-and-roll out of hearing range of their parents who had control over the family stereo, a truly personal computer will allow people to "escape" into a world of more intimate consumption and communication.

    Q: Do you think physical keyboards and mouse will be extinct?

    Even physical keyboards have been evolving dramatically. If you look back to the earliest IBM PC keyboards, they were mechanically complex and had a rich feel. Modern laptop keyboards are flimsy things with barely any feedback. Early PC keyboards were patterned after the needs of professional typists (aka secretaries). Current keyboards are designed around space constraints. Same with mice. They went from two to three to one to no buttons. With laptops we ended up with track balls,  little knobs in the middle of the keyboard or with trackpads. Users adjusted over time.

    What changed with tablets is the removal of an on-screen pointer. The pointer was there because the mouse/touchpad was one layer of abstraction for controlling what was on screen. Without a pointer you have direct manipulation. I'm sure many people who never used a mouse would find the direct method more intuitive and in a generation people will wonder how we put up with mice. Conversely, those who are used to a mouse will find it uncomfortable at first. Remember that in the 80s many keyboard experts found mice something that slowed them down.

    So I believe that people will adjust to a world without mouse pointers. I suspect children born today will grow up without ever using a mouse (or a phone with a wire permanently attached to the bottom).

    Q:  Apple has more than 90% of tablet market worldwide. Do you think Apple will be the leader of technology market in the next few years?

    The challenge for Apple is that they cannot serve the whole world. They can only grow so fast. On one hand we have their inability to meet demand and on the other we have alternative products which can. Market leadership may not be sustainable just because the market is so big and no single company can supply it. I do believe that Apple is not sitting on its hands however. Their culture promotes pushing forward.

    Q: At smartphone market, do you believe on a risk of a new duopoly, Apple-Google? Some analysis says that they’ll control the channel sales of software, content and hardware. The conclusion is companies like RIM, Nokia and HP (Palm) will not be able to keep up.

    Analysts differ in their opinions. IDC just released a forecast that shows Microsoft growing beyond iOS in four years. I don't try to make this type of prediction. At least not to a high degree of precision. I do believe that there will be more than two platforms. This is because the market is so large and so diverse and there are so many ways to reach customers (through operators, through retail stores, through online).

    Q: Can we compare the beginning of the tablets with PCs? Apple developed the interface and made ​​the first computers nice and easy to use. But Windows has allowed hardware manufacturers to invade the market, popularizing it. This will be repeated with Android? Or with other systems?

    Innovations are always copied. Even when protected by all sorts of laws or patents. What makes a company successful with innovation long term is to always keep innovating. Often coming up with the next big thing means damaging the old thing. That's hard to do for many companies so they don't do it and somebody else does. This is why great companies end up as formerly-great companies. As I pointed out above in the discussion about input methods, innovations are always bubbling up. As long as Apple takes these ideas and polishes them and brings them to market, they'll do all right.

    Q; How about Microsoft? Do you think the company will lose the podium in Post PC era?

    Microsoft already has lost its position as leader in personal technology. The end actually came in about 2000. Once Windows became "good enough" and did not crash so much, they have had a hard time finding something to improve. If you go back and watch every CES keynote that Microsoft presented since then it's been a litany of dead end ideas.

    Every major innovation since 2000 has been in consumer technology and that's never been an attractive business for Microsoft (with the exception of XBox which was really aimed at Sony and Nintendo without the intention of creating a new market.) Microsoft struggles not because they lack talent (engineering or management) but rather because their business model is relatively rigid. They make money through software licensing. You can see how that's a hard thing to sell to consumers ("I'm buying what?") Consumers tend to pay Microsoft through the purchase of another product. If the market demands hardware/software integration (like in a phone or tablet) or making money by giving software away (like Google), they struggle. This business model rigidity is present in almost all companies, so Microsoft is not uniquely troubled.

    Q: Most of the tablets will use mobile networks to connect to the internet. Do you think the world is ready with an infrastructure that supports this growth in access via mobile networks?

    This is a good question because the growth of mobile broadband is a major enabler (or constraint) on growth. Fortunately, the roll-out of mobile broadband is fairly predictable and it looks good. There are some challenges for operators long term in paying for the infrastructure, but they don't lack for financing today and the business case for more infrastructure seems to be very attractive. It will take time and it won't be even globally, but the incentives are clearly there. A lot of value is being created with mobile computing and much of that value will end up paying for the bandwidth.

    Q: How about the App Market. You posted recently a chart showing how fast developers are buying thickets for both Google and Apple developer events. You said that it is one signal of the Post PC Era. What will be the importance of apps on the next years. Do you think Apps market will be more important than hardware, content and OS market?

    Developers are one more sign that something big is happening. It's not the only sign and may not be the cause of the change, but it's yet another signal. But apps are a phenomenon that will result in something bigger than we can imagine. The way to think about apps is as a new medium, similar to the emergence of radio, television, cinema and even books. The app is a new art form as well as something that provides functional value. We don't know whether the app phenomenon will be tied to one platform or will evolve to something like HTML5, a common standard. But the value of having an app for everything is plainly evident. The economics, creative energy and dynamism of apps cannot be overestimated. I will write more about this subject as I think it's one of the most important consequences of the post-PC era.

    Q: What’s the destiny of the PC? Are they on their last years?

    Again, it's not so much that PCs will disappear any more than mainframes or servers have disappeared. What is more likely is that they will be used for isolated, focused jobs. The "end of an era" is the end of growth, not the end of existence. The PC has arguably reached end of growth in most developed markets. There is still strong growth in emerging economies but even there, much of that growth will probably be replaced with smart devices growth.

    Q: We had the Mainframe Era, the Terminal Era, the MiniPC Era, The PC Era and now we starting the PostPC Era. Do you imagine what Era we'll se after the tablets? When do you think is it going to happen?

    I don't try to be a futurist who can see with clarity technological change. I try to see the patterns of markets through the motivation of companies. With that in mind, my answer will be that large companies will acquire promising new technologies from start-up companies and implement products with global distribution. To see the future you therefore need to look at what small companies are doing today. I note that there is a lot of innovation in new communication methods (social media) and new input methods around gestures and display technology. I am skeptical about the power of voice controls.

    I'm most confident that there will be a re-definition of television, a "socialization" of almost all media. So I'll abstain from answering directly what happens after the Tablet Era. Perhaps something more personal and more of a companion than a tool.
  10. Mobile device OS upgrades: How hard can it be?

    Research · 45 comments

    Until the iPhone's arrival in 2007, upgrading the software on a mobile phone was a rare experience for users. So rare that effectively it was not done. Few people were bothered though since they did not see the product they used as a software product.

    This was even true for Windows Mobile and Symbian which were licensed platforms. Microsoft tried several times to offer upgrade paths, but more often than not the device vendors did not push out updates or the process required to perform an upgrade made it the reserve of either those who were paid to do it or those who enjoyed the challenge.

    In the era of the modern smartphone, upgrades are more common. Certainly with the iPhone the process is easy enough that opting out of an upgrade is more challenging than opting in. But it's still not as common with other platforms. Even with all the resources and experience behind them, Microsoft is still stumbling with Windows Phone upgrading.

    UPDATE 1-Microsoft explains phone software update delay | Reuters

    But is it really a matter of blundering or is there evidence of nominal partners working at cross-purposes?

    Upgrading a mobile device is technically challenging. There are many things that can go wrong. Integration helps, but it is also possible for a modular solution to be implemented. There are harder things to coordinate.

    However, things go wrong and as the linked article above shows, fingers get pointed. Device vendors who have no stake in a platform can easily interpretan upgraded OS as one fewer hardware upgrade. Platform vendor's lament that device guys want to proliferate unique versions and act with passive aggression. Device vendors see the software upgrade cycle as increased support and engineering costs with no upside. Consumers don't know whom to blame and often turn to the operators since that's who they pay every month.

    The problem of upgrade failure is a symptom of a deeper dysfunction inherent in immature modular business architectures. It's not just that the brightest at Microsoft or Nokia or Google can't make an upgrade stick. It's that the upgrade is not universally beneficial to the value chain. To remedy this, licensors have to resort to contractual obligations to ensure upgrades, but enforcement is non-trivial and can lead to aggravated relationships.

    Unless all licensees of a platform find compelling value in shouldering the burden of upgrades, they will continue to be really hard. This leads to increasing fragmentation and a corrosion of platform value for licensed platforms vis-à-vis their integrated alternatives.

  11. Pattern recognition for smartphone investors

    Research · 42 comments

    I spent the last few days in Hong Kong at a conference discussing the smartphone industry. The participants were mainly investors or investment managers. One of the most frequently asked questions was how to spot investable trends in this notoriously unpredictable sector.

    The data I presented did not offer much of an answer. If anything, it showed just how much the industry has changed and how unlikely it is to remain a facsimile of what it is today.

    But theory allows us to still make some bold claims. Grounding your investment thesis in pattern recognition rather than extrapolation should be the better strategy. So here are the telltale signs I recommend watching for investable ideas.

    1. In hardware look for what's not good enough. The smartphone is great. But it's not good enough for many jobs that we can recognize with little effort. For example, smart devices never seem to have enough battery life. Storage, screen quality and speed are pretty good, but battery life is worse than what voice phones offered years ago. Companies dedicated to improving battery technology or charging technology should be worthy of a bet. Breakthroughs in power saving will be much more valuable than breakthroughs in storage or processing speed or screens.
    2. Pricing needs innovation. Phone pricing is opaque, user unfriendly and often leaves buyers confused and angry. I use the word innovation instead of reduction because it's not about making prices necessarily lower, but removing complexity and defining value clearly through price. The challenge is not just for devices but for service providers as well. Companies innovating by abstracting pricing complexity will do very well. Interestingly, pricing innovation is not as easily copied as it may seem. It is often coupled with business model innovation and cost restructuring.
    3. Applications currently conform to platform needs but there will come a time when platforms will need to conform to application needs. By applications I mean not just apps but the app/service bundle that will drive consumer purchasing behavior. If we consider social media, entertainment and shopping as applications, it will make sense for those applications to eventually take some control or equity in the platforms. Android is the first sign of this: search and services associated with search and advertising sought control over platforms. Perhaps Facebook, Amazon and Baidu will feel a similar need.
    4. As a new medium, apps will eventually be more valuable than the tools used to render them. The global app brands are probably not yet born, but some day they will be as important as Disney, News Corp and Universal Pictures in their heyday. The App Store is the incubator for these embryonic megabrands.

    I realize that these are not specific enough investable ideas but casting your eye on patterns should yield better returns than selecting winners from a set of "current players".  After all the great returns from smartphones to date have come from bets on entrants (HTC, Apple, RIM) and not from incumbents (Nokia, Microsoft or Motorola).