I went to the link below to look at some of the apps. I clicked Top Free tab and scanned through the featured apps. As Google puts it: "This is a showcase for some of the featured and top ranked applications and games available on Android Market".
LG has reportedly told Korean sources that “it expects WP7 to outperform the two rival smartphone operating systems” – one of these platforms is definitely Android (I’m not sure about the other platform LG is referring to; Symbian? iOS? BlackBerry?).
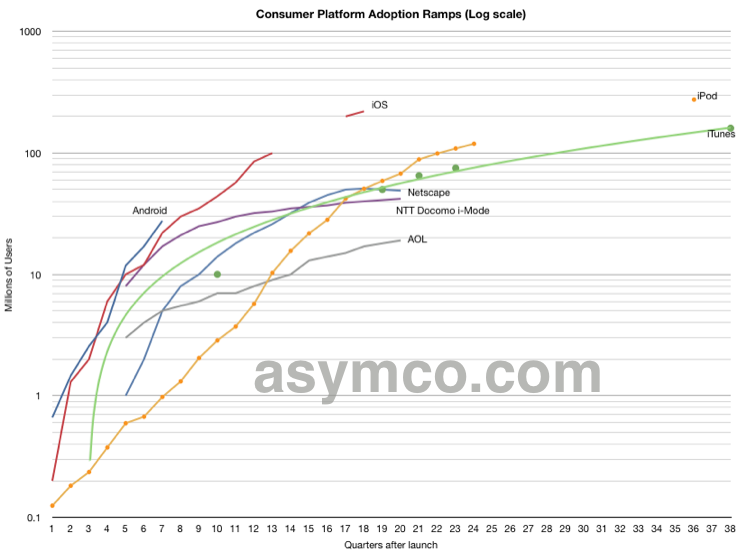
To make it more readable (but conceptually more complicated) I put the data on a log chart.
Discussion
The time span covered is nine and a half years. The top of the graph marks the one billion threshold. Reaching one billion in less than 10 years is an interesting challenge for any platform and, at first glance, it seems that both iOS and Android have a shot at it. This does not seem likely for any of the other platforms.
The challenge is that as penetration grows, it's natural for the slope for the lines to become shallower. Some platforms are simply not able to address one billion users:
i-Mode, AOL and other technologies with localized value networks are clearly limited to populations in their home countries.
iTunes is limited by the use of a PC, which has a small footprint in under-developed countries (dependency by iOS on iTunes should throw up a red flag here).
The iPod was embraced and extended by more ubiquitous mobile phones.
In contrast, mobile phones in general and smartphone platforms in particular have potential to reach a billion users (per platform.)
To wit, note that iOS and Android have similar curves to date and are both likely to overtake iPod and any other contender.
So for the obligatory theological question: Will Android follow the curve of iOS or will it diverge and continue on a steeper trajectory? Does it matter?
A few years ago I read a book called "Breaking Windows" which was the story of the DOJ investigation into Microsoft's abuse of monopoly. The book was written by a journalist who tried to summarize some of the findings from the published internal emails.
One of the takeaways was the logic of Microsoft's entry into the Office market. The main internal justification was not that it would be a hugely lucrative new business, but that it was a necessity to the maintenance of the Windows business.
The story was that Lotus, having a huge installed base, could (and did) arbitrarily refuse to upgrade their software to the latest Windows version and in so doing, could kill the franchise. Lotus owned the "killer app" and could hold Windows hostage. Users would rather keep their applications than upgrade a largely invisible OS.
Another way to read this was that Microsoft needed to "vertically integrate" Windows so that it encompassed not only the OS but also the key applications that ran on the platform. A purely horizontal OS platform was obviously not viable as a business even back in the early 90s.
What reminded me of this story was the news that Dell is launching a new smartphone in the US. Called Aero, it will run Android 1.5, an ancient version released in April of 2009, 18 months ago.
Now think about the idea of Adobe coming to market next week with a new version of Photoshop that ran only on Windows XP. Or even more poignantly, if Office were not part of Microsoft, seeing a *new* version of Word that only worked with Vista.
Through an aggressive acquisition plan twenty years ago, Microsoft avoided this scenario. Google today is faced with the prospect that not only the devices (which sit on its OS) but also services and apps on top would choose to remain on old versions of Android. There is nothing to stop them from doing just that. Unlike Microsoft, Google does not enforce licensing terms for Android. It is at the mercy of the value chain.
Couldn't Google crack down and deprecate Cupcake? It's not as easy as that. Not only do they not have license terms that permit that but in the phone business, development lead times are so long and global distribution can be so elastic that a low volume vendor like Dell has no choice but to sell multiple OS versions of their own products. Microsoft has almost the same problem with Windows Mobile, with a variety of given-up-for-dead Windows Mobile 6.5 powered devices still in the pipeline while Windows Phone 7 is imminent.
Microsoft executives told Goldberg during a recent visit to company headquarters that the company, carriers, and manufacturing partners, would spend "billions" of dollars in the first year on marketing and development of Windows Phone 7. Another source estimated a $1 billion price tag for the launch, with half of it going to marketing.
Note the scale of spending here. The number quoted is twice Apple's yearly ad budget, for all its products.
$500 million is roughly the equivalent of Apple's entire advertising budget for its 2009 fiscal year. In its 2009 Form 10-K filing to the SEC, the Cupertino, Calif., company listed $501 million in advertising expenses. Microsoft's fiscal 2009 advertising budget was $1.4 billion.
But beside the unrepentant destruction of Microsoft's shareholder wealth, one other thing jumps out at me: why are the operators and vendors going along with this?
Fragmentation increases the cost of development, marketing, operations and hinders the creation of cohesive ecosystems.
Most companies are very aggressive in consolidating around internal platforms and standards. Supporting R&D teams and marketing teams around each platform is costly and dilutive to one's brand.
With hundreds of Android devices and RIM and Apple increasing distribution, why would operators be willing to spend hundreds on a venture to promote a new platform? This decision is even more puzzling when realizing that the vendor of the new platform left nothing but business model carcasses behind the last time they got involved in the industry.
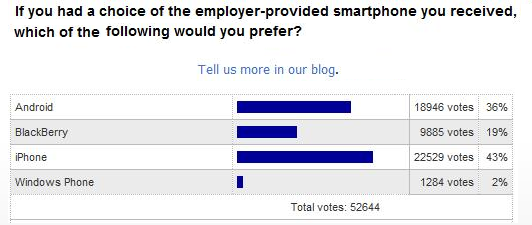
In addition the positioning of this product is suspiciously awkward. One could argue that as a vendor or operator, having an unaddressed or underserved market (say, business users) might mean this platform could expand the distribution of your product or service. But Windows Phone is being positioned as a consumer brand and that's a crowded space where every other platform is also targeted. See the survey data below (unconfirmed source: US Army)
So again, why would operators and licensees spend hundreds of millions to introduce yet another platform in the market?
Much of what is published here relies on data, lots of data. It's important that data be published along with conclusions, but data in spreadsheets is often difficult to read. Spreadsheets are not "productized" so they are hard to explain and therefore impossible to share.
However, I am considering sharing the data I have in a format that is easier to read than a spreadsheet but richer than a screen shot of a chart.
To that end I've begun experimenting with a solution based on a service called Roambi. Interested readers can download Asymco authored "roambi" files which I call ADDs (Asymco Data Downloads) will display rich data sets on iOS devices. These representations are interactive and easy on the eyes.
Rather than bore with details, the following images should be sufficiently descriptive.
A: Hopefully you won't need help, but there is help in the app and at Roambi's site.
Q: Will ADDs work with Android?
A: No.
Q: Will ADDs work with <insert non-iOS device here>?
A: No.
Q: Can I see ADDs on a Windows PC or with a Mac?
A: No.
Q: Can I download the actual spreadsheets?
A: No.
Q: How much does it cost?
A: ADDs are free.
Q: What if I see an error?
A: Send me a message.
Q: Will you publish more of this data, like the Apple financials?
A: Yes. I hope to publish all my data. Stay tuned.
Q: I don't have time to read your blog every day, can I just get the data?
A: I'm considering ways of creating a "premium" service. If you are interested send me a message that you would like to receive email-based links. Send request to: horace.dediu -at- asymco.com.
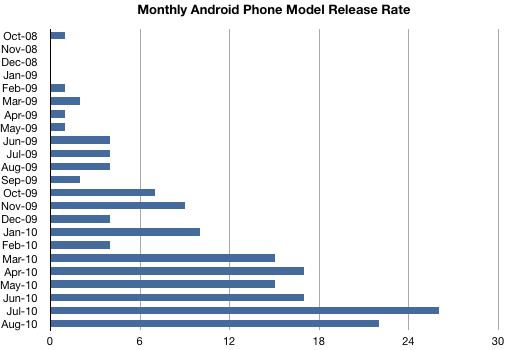
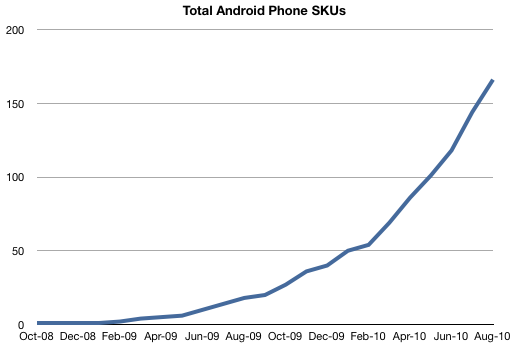
Next month will be the 24th since the first Android device launched in October 2008. The G1 was followed by another HTC device in February of 2010 and a few others in the spring. The summer of '09 showed a steady release of up to four new phones every month. Since then the number of Android phone stock keeping units (SKUs, uniquely identifiable stockable products) increased dramatically, with the release rate increasing to 26 per month during July of this year (source: pdadb.net).
Altogether, there are have been 166 Android phone SKUs in the market with another probable 25 or so ready to launch in the next few months.
Now this may seem like a large number of different phone models in a short time, and it is, but Windows Mobile was even more proliferated as a licensed OS. At its peak over 50 new devices were released every month. The total now is over 1700 and it's still growing.
The 183 known Android devices are distributed among 10 principal vendors with another 18 minor vendors. The 18 "other" vendors (see footnote 1) have either one or two devices in the market.
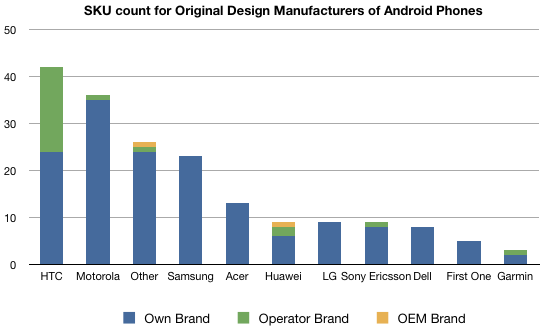
The vendors or original design manufacturers list ranked by most devices follows:
I broke out the devices also by the number of operator branded devices designed by the same manufacturer (green) and any devices designed and built by one vendor but sold under a different vendor's brand (orange). It shows how, excluding "other", HTC is the most prolific Android builder (and seller) but also how it still depends a lot on Operator branding.
The proliferation of Android devices is indeed striking, but as I've pointed out before, the licensing model for Android is symmetric with that for Windows Mobile with the exception that Android is both open source and cost-free to license. This should make it highly disruptive to the paid-license model that Microsoft worked so hard to implement. It should be no surprise then that the adoption dynamics for the platform are very similar, with the same licensees that took Windows Mobile a few years ago embracing Android today.
The proliferation still has a while to go. There is production capacity for over 2000 SKUs among all the vendors in the market (especially the "other" category) and it's only been two years since a stable version of the OS has been available. So it would not be surprising if the total number of licensed Android products will overtake the 1700 or so Windows Mobile SKUs.
So what's the paradox?
The question that should jump out from this data is what's the value to the participants in this, or any mobile OS licensing model? When I analyzed the Windows Mobile field in 2007 or so, it was pretty evident that very few vendors other than HTC shipped enough volumes to make a product profitable. In fact, I coined the phrase Pocket PC Paradox to describe the situation where hundreds of vendors would line up to make undifferentiated products competing for a shrinking pie. This went on first with Pocket PC PDAs, then repeated with Windows Mobile and is now repeating with Android. Nobody ever made money except for HTC, not even Microsoft.
It's still a mystery to me why any manager would decide to make the (n+1)th Android/WinMo phone. It must be difficult to make market projections that justify the cost of developing and marketing this new product.
But here's some help: The total number of Android phones sold through the end of last quarter was about 23 million units. The total number of SKUs launched to date then was about 118. That means that the average Android phone SKU sold 200k units (2).
Now this may seem comically low, but I will again bring up history and point out that while the WinMo bubble was in its zenith, the average Windows Mobile SKU had 50k units sold. With the SKU count increasing more rapidly than the sales rate (40% more SKUs since June) it's very likely that the average units per SKU is dropping. So by my reckoning there's plenty more in the Android bubble to go.
-----
(1) The "other" category includes the following vendors:
Lenovo
Gigabyte
Highscreen
Notion Ink
WayteQ
Forsa Posh
Inventec
Kyocera
Pantech
TechFaith
Saygus
Sharp
Ziss
Alcatel
General Mobile
(2) I'm fully aware that the distribution of sales over the products is not even and very likely exponential, but there is no way to predict whether a given new product will be a "hero" or DOA. The dream for every manager must be that his product will be a star, but the odds get worse and worse over time and the average units sold has to be considered as including these odds.
I installed HTC's leaked version of 2.2 on my incredible last month. It has been noticeably faster, has better battery life, and the extra features are nice. As expected, Verizon put a lock down on the wifi tethering feature, and if I want to use it I have to pay an ADDITIONAL $25/month, which is completely ridiculous. Luckily, my phone has been rooted (it was the only way to get froyo on there) and I can use a number of FREE wifi tethering applications that don't cost anything extra per month either.
It's pretty sad that the only way to enjoy an android phone is to hack the crap out of it, and doing so requires relative technical expertise.
Reminds me of Windows Mobile in another way: the only real fans were those who could play with cooked ROMs. Conversely, imagine if the only iPhone fans were those who jailbroke/unlocked iPhones.
The OS market in the mobile space is dominated by other players. Is that a cause of worry?
I think it’s a temporary issue. I don’t put a lot of face and snapshot and time into what is going on. On a global basis, I see what is growing and what is shrinking. Text messaging is the fastest-growing on simple phones part of the mobile market. That’s where growth is. The smart phone part of the market, or the premium market, is in the downward part of the market. It will not be there for a long time in the future.
People want something that’s simple. The design goal for the Windows Phone 7 is that with rich experience you get simple stuff easily. Great keyboard or touch or both – so you can have that. It is too early to talk about dominating, but I’m excited about it. Android coming into the market says there is room for more innovation and we see ourselves playing a role in that space. People talked about the iPhone and thought that was the end of the world for OS. Windows Phone 7 will prove there is more room for innovation.
In other words, Android's entry in the market and remarkable growth, there is room for Windows Phone. And because Windows Phone is easy to use and has a keyboard and touch it will have a chance at dominating.
Microsoft's enthusiasm for yet another mobile platform joining the fray (along with iOS, Android, RIM, Symbian, Windows Mobile, Meego, various sundry Linux and Bada) is not just delusion. I'm sure that they gathered positive feedback from operators. By this time next year there will be dozens of Windows Phone devices on the market. After all, Windows Mobile attracted 1700 licenses.
When I wrote about Android's pursuit of the biggest losers, I made the explicit claim, backed by data, that Android was most attractive to device vendors who were in financial distress. Android is a lifeline to sustain failing business models. But underlying that claim was the more sinister implication that Android is sustaining to the incumbent operator business models. That means that Android is subject to operator manipulation and its market access as well as those of competing platforms will be throttled to maintain control.
The article below makes an even stronger case.
As a result, we now have a situation where the U.S. telecoms are reconsolidating their power and putting customers at a disadvantage. And, their empowering factor is Android. The carriers and handset makers can do anything they want with it. Unfortunately, that now includes loading lots of their own crapware onto these Android devices, using marketing schemes that confuse buyers (see the Samsung Galaxy S), and nickle-and-diming customers with added fees to run certain apps such as tethering, GPS navigation, and mobile video.
I would not say that Android is enabling the consolidation of operator power. I would say that operator power never wavered.
The article concludes:
Despite the ugly truth that Android is enabling the U.S. wireless carriers to exert too much control over the devices and keep the U.S. mobile market in a balkanized state of affairs, Android remains the antithesis of the closed Apple ecosystem that drives the iPhone and so it’s still very attractive to a lot of technologists and business professionals.
But, the consequence of not putting any walls around your product is that both the good guys and the bad guys can do anything they want with it. And for Android, that means that it’s being manipulated, modified, and maimed by companies that care more about preserving their old business models than empowering people with the next great wave of computing devices.