
Asymco

Asymmetric Intelligence

cash

  1. Apple’s Enterprise Value Peaked in 2007
    Research

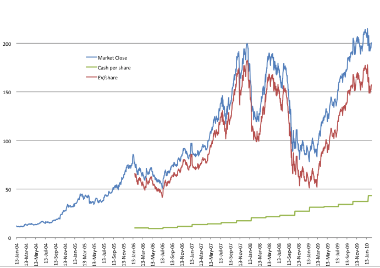
    On Christmas Eve 2007 to be precise. That’s when the Enterprise Value/share was $181.5. These days it’s around $150. The Enterprise Value (EV) measures the value of future cash flows excluding current assets and is a better indicator of the potential of a company than its current overall value.

    As you can see in the graph above, the cash per share (in green) has grown to $43 while back in late 2007 it was less than half that. As a result, although the market value for Apple peaked at $215 on 19th January this year (the blue line), the EV/share was only about $178 (the red line), below the all-time-high in 2007.

    As Apple’s cash continues to grow, the gap between EV and MV will also grow. If the MV remains low (as the P/E is indicating) then the Enterprise Value, i.e. the net present value value of future cash flows, drops.

    Did Apple’s prospects peak in 2007--six months after the iPhone was first launched--or is the current valuation still a function of sentiment of the overall economy, independent of the company’s fundamentals?
  2. Apple's Valuation Dredging Bottom

    Research

    The fact that AAPL is less valuable -- in terms of the P/E ratio -- than the average S&P 500 company continues to baffle me.

    Apple's P/E is a bit misleading because of the price "P" a large part is cash which should not be considered "at-risk" capital.

    The logic of a P/E ratio is to measure how many years it might take to recover one's investment. The cash on the balance sheet is not at risk for this calculation. Therefore the Enterprise Value /Free Cash Flow is a more accurate measure of company value creation. Until the recent re-statement the FCF and Earnings were divergent. They have since become equivalent.

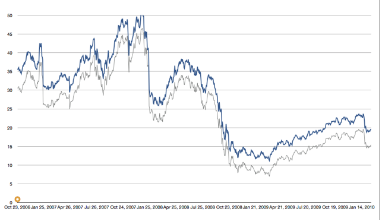
    Therefore, if you take cash out, (currently $43/share) the Enterprise Value / Free Cash Flow for Apple is about 15. It had bottomed at 7 (now that we have restated data we can go back and re-calculate this).

    The graph above shows the traditional P/E in blue and the EV/FCF in grey (using restated financials).

    On a forward basis the EV/FCF is probably around 12 to 13.

    Also of note is that Apple's EV/FCF is lower than the S&P 500 (at 23.52 at the end of Q4 2009.)

    If we continue to use the S&P as a comparable, I looked up the estimates for quarter-end P/E for the S&P 500:

    12/31/2011 17.15

    09/30/2011 18.35

    06/30/2011 19.97

    03/30/2011 21.61

    12/31/2010 23.00

    09/30/2010 24.43

    06/30/2010 22.57

    03/30/2010 21.54

    12/31/2009 23.52

    Apple EV/FCF (and also traditional P/E) are lower than S&P on current and forward bases.

    How do we read this? Is the market considering that Apple's prospects are less than the average large company? This does not quite make sense to me. What other theory could be at work to explain this valuation?

    S&P estimates are sourced from:http://www2.standardandpoors.com/spf/xls/index/SP500EPSEST.XLS