Asymco

Asymmetric Intelligence

Goldman Sachs

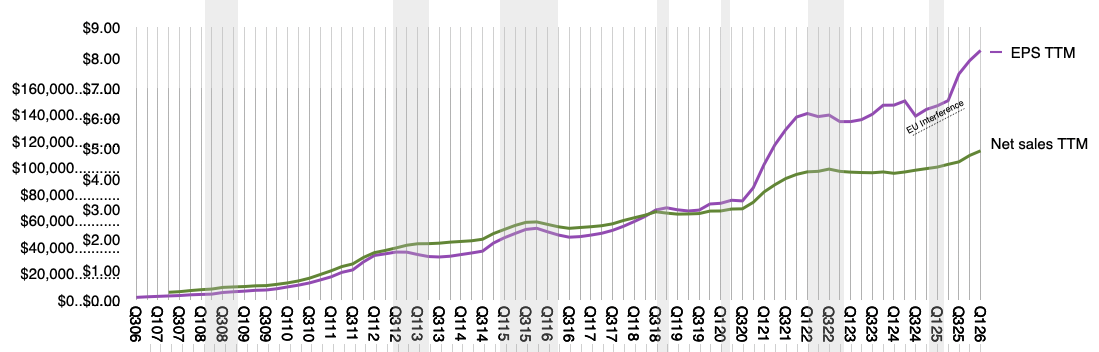
  1. Goldman forecasts fiscal second-quarter EPS of $2.00
    Nota Bene · 2 comments

    Second call for EPS $2.00

    Goldman Sachs is pushing back on negative sentiment surrounding Apple ahead of its second-quarter earnings, arguing that the stock's recent underperformance reflects fears that do not match the company's underlying position.

    But analyst Michael Ng said, "concerns for Apple are overly pessimistic given its much stronger relative position."

    Goldman Sachs forecasts fiscal second-quarter EPS of $2.00, above the Street consensus of $1.93, with outperformance expected across iPhone revenue, Mac revenue and gross margins.

    Favorable foreign exchange and strong Services revenue growth are also expected to flatter results.

    On Services, Goldman Sachs projects 14% year-on-year growth despite another slow App Store quarter, with iCloud+, AppleCare+, prior price increases on Apple TV+ and solid advertising performance cited as supporting drivers.

    Looking ahead, the bank sees advertising inventory expansion in the App Store and Maps as further tailwinds.

    Recent data points cited by Goldman Sachs include high-end smartphone outperformance flagged by TSMC on its latest earnings call, iPhone share gains in China, and reports that Apple is actively securing mobile DRAM supply while keeping pricing competitive.

    The bank sees further catalysts ahead, including WWDC, where new AI Siri features are expected, and the fall iPhone lineup, which Goldman Sachs described as likely "the most innovative ever with the introduction of the iPhone Fold."

    Source: Yahoo Finance

    NB: My target of $1.98 seems amiss.…

  2. Goldman Sachs: App Store spending accelerates 7% YoY in January 2026

    Nota Bene

    The good news keeps rolling in.

    Previously, on February 3, Goldman Sachs maintained its Buy rating and $330 price target on Apple Inc., highlighting favorable App Store spending trends. The firm noted the company’s App Store spending acceleration of approximately 7% YoY in January 2026, relative to the 6% growth in December last year. While Entertainment grew 7% (from 3% to 10%), the Games division declined 3% YoY.

    Goldman Sachs believes that App Store spending will continue to be a meaningful growth catalyst for the company’s Services revenue in the future

    Source: Insider Monkey

  3. Goldman Reiterates Buy and Bernstein Reiterates Outperform

    Nota Bene

    $330 and $325 Price targets, respectively.

    Investment bank Goldman Sachs discussed Apple Inc. in January. It reiterated a Buy rating and a $330 share price target on the firm. The bank discussed the firm’s App Store performance in its coverage. It outlined that the App Store spending trends were improving as spending grew by 7% in January to accelerate by one percentage point over December’s 6% growth. Goldman added that the App Store growth should contribute meaningfully to Apple Inc. Services business.

    Along with Goldman Sachs, Bernstein also praised the firm. It reiterated an Outperform rating and a $325 share price target. Bernstein cited Apple Inc.’s record iPhone revenue and optimistic growth guidance to point out that the firm was correctly navigating the turmoil in the memory industry.

    Source: Insider Monkey.

    NB: I remember when both of these banks had negative ratings on Apple.