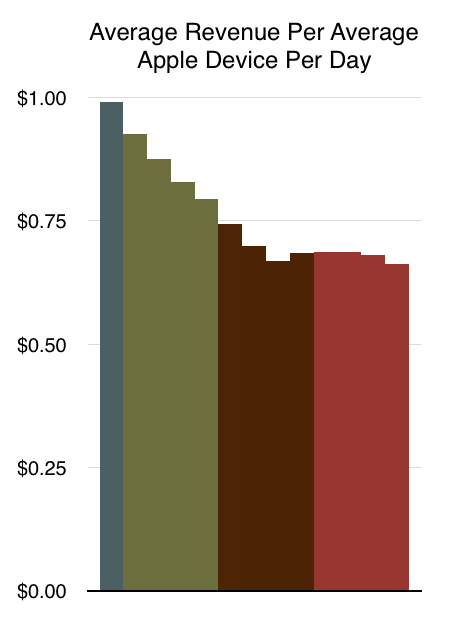Asymco

Asymmetric Intelligence

Mac

  1. Other Products

    Research · 6 comments

    From the way Apple reports its revenues you might think that the company has several operating segments. There are the iPhone, the Mac, the iPad for which units and revenues are reported. Then there are Services and Other Products for which we have revenues only.

    Services is a collection of all non-hardware revenues and is (finally) being recognized as a non-trivial business. With reported revenues of $26.6 billion in the last twelve months, it's big enough to be a Fortune 100 company and set to double in four years. ((Although a non-zero business, the valuation of Services continues to confound observers who cannot separate it from the hardware businesses it attaches to--which themselves are considered near commodity value--thus paradoxically valuing the overlying asset of Services near or precisely at zero. Incidentally, Facebook is Fortune 98 at $27.3 billion and it is also one of the top 5 largest business by market capitalization.))

    That leaves "Other Products" which now becomes the revenue segment that is  "most likely to be ignored." This segment had revenues of only about $11.5 billion in the last 12 months which would place it at only a Fortune 245 ranking, equivalent to a Toys "R" Us or Biogen. How should we value Other Products?

    Other includes many hardware products including iPod, Apple TV, Beats, Apple Watch, AirPods and, soon, HomePod. Each is a significant product, with Watch probably the largest single contributor. But since we don't have specific unit numbers, we are left guessing at the contribution of each.

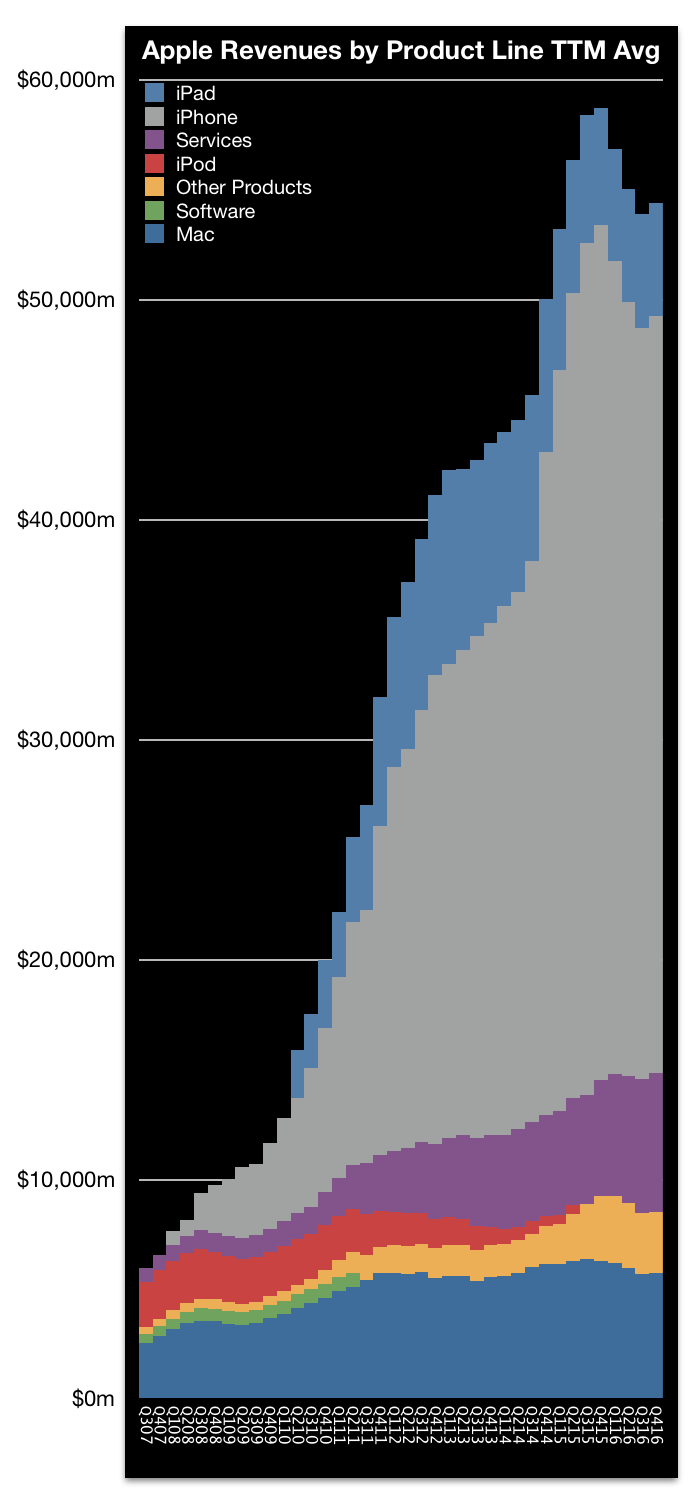
    The Watch itself has been a point of scrutiny as it could be initially teased out of the mix through an observation of the before-and-after launch vs. trend-line as shown below:
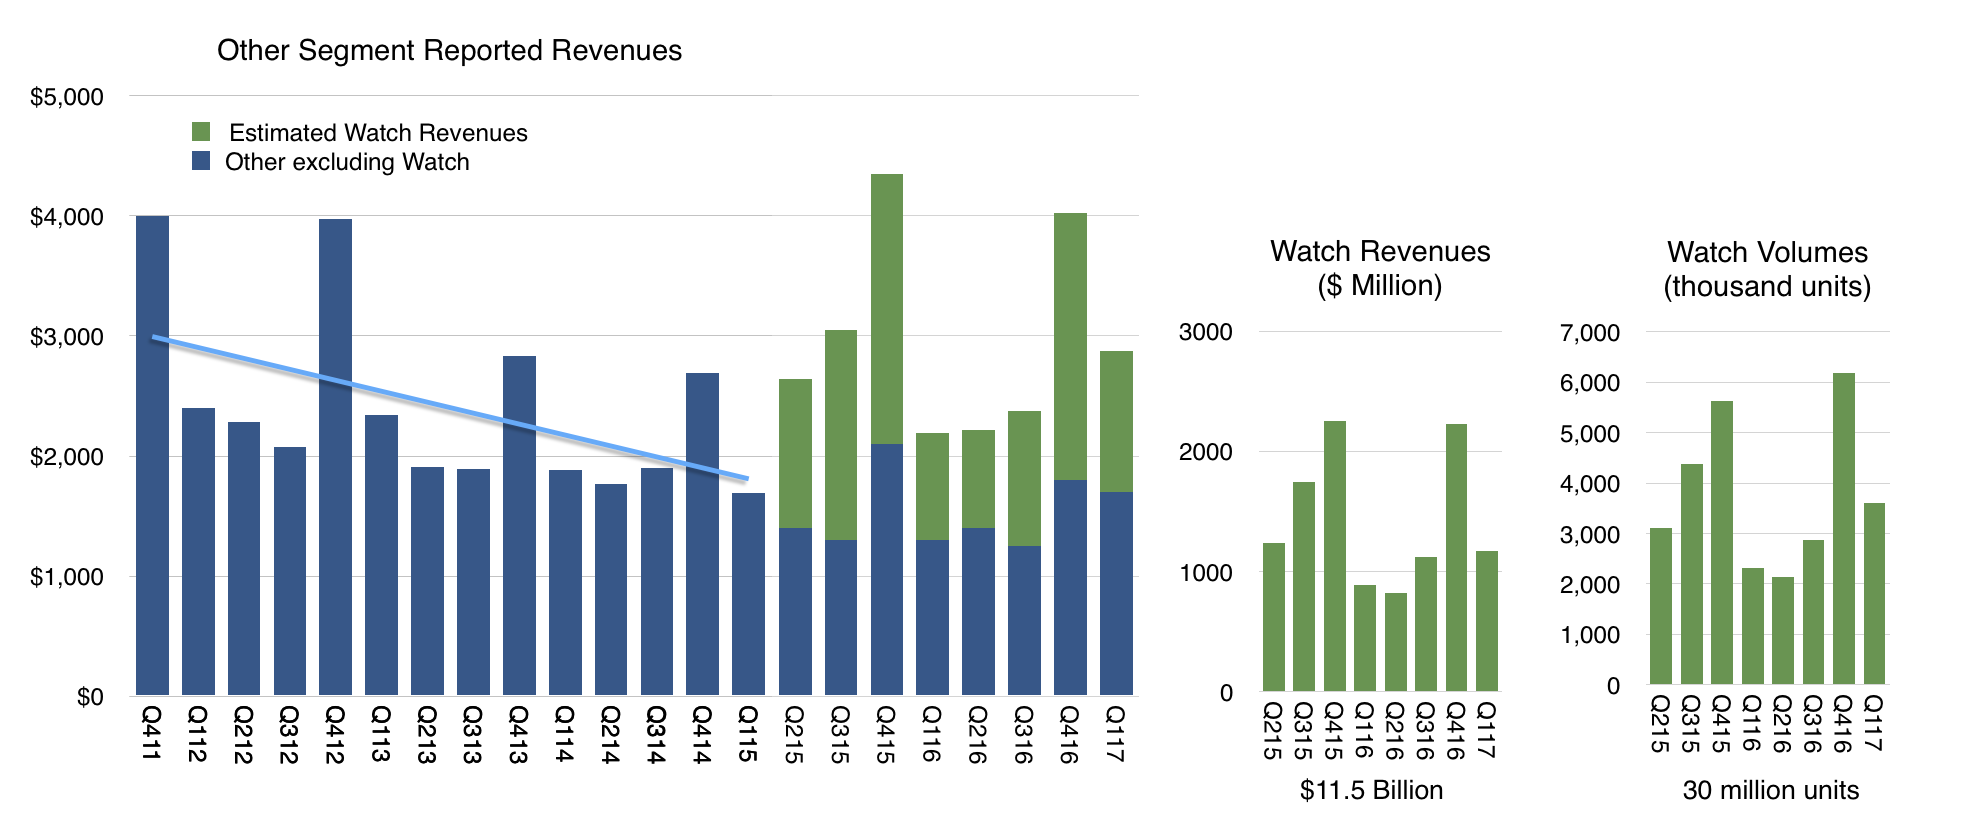
    This separation of Watch became harder to discern after the launch of AirPods. Though they are still very hard to obtain, they might be "moving the needle" by now with a contribution that would muddy the Other category further. Same with updated Beats headphones.

    This separation will be harder still with the launch of HomePod later this year. This product is priced at a point similar to the Watch and the quantities sold will be very hard to estimate without Apple's revealing of actuals.

    Fundamentally however, all the "Other products" will have a common relationship to the iOS and MacOS hardware: attachment to and integration with a "parent" platform. Apple TV might be stand-alone but I strongly doubt there are many sold into offices or households which don't have iOS usage.

    This means that "Other Products" are very similar to "Services" in that there is a dependency on a primary platform and, as it has been argued, they are therefore fragile. If the core platform declines then the Services and Other Products decline as well.

    Given this dependency it makes little sense to carve these categories out as separate businesses. They cannot stand alone. They are very much the "children" of the parent platforms.

    This is why it's assumed that Services, (a Fortune 100 company) and Other Products (a Fortune 250 company) can be discounted to zero. By focusing attention on the iPhone one can capture all the essential value of Apple. This is in contrast to the "sum-of-parts" valuation that could be applied to a set of independent business units in other companies.

    And yet I started this discussion with the point that you might be tempted to look at Apple on the basis of these reported revenue segments. The choice of what Apple reports is arbitrary. It could report no segment revenues at all and publish just one revenue number. This is roughly what Google Amazon and Facebook do. Or it could report segments in some other way. For instance, app store revenues and AirPods could be reported as part of "The iPhone Division". Or maybe it could bundle all iOS devices and services and accessories into another segment called "The iOS Group". Or it could create a "Devices group" and a "Personal Computing" group. Microsoft famously shuffles its revenues into creative segments based on various organizational structures or choice of what it wants to project as its focus.

    There is no limit to the ways Apple could slice revenues into segments. The reason Apple does it the way they do is mostly due to historical reasons. The company used to report the iPod separately as a segment but it no longer does. It also used to report Software separately, because, presumably,  it charged for it but now it no longer does. It also separated laptops or portables from desktops.

    The current reporting system is tempting us to draw certain "business unit" conclusions. These boundaries are illusions because Apple does not have business units. It has only one Profit and Loss statement (P/L) and is organized functionally. There is no "head of iPhone" or "head of Mac" responsible for each siloed revenue and cost structure. Instead, the entire business should be seen as a whole because it is managed as a whole.

    This is easily evident in how the products are designed and marketed and how they are engineered. The iPhone may spawn AirPods and AirPods may have no value outside the iPhone but the iPhone is valuable precisely because it has AirPods and Apps and Music and iCloud. And Apple TV, and HomePod and whatever comes next. The reason the iPhone can be sold at three times the price of competitor products is because of the Services and Other Products and iPad and Mac symbiosis. This integration drives the satisfaction, loyalty, price and brand value. There there are the Apple Stores and the launch events and the countless details that make up the ownership experience.

    The fact is that you can't slice and dice Apple.

    There is one Apple and it must be analyzed as a unitary entity. That analysis is therefore difficult. It is easy to pick up the numbers given and study them in isolation. The iPhone, the iPad, the Mac. We all do that.. However we miss a great deal in doing that.

    The lesson is that data we obtain leads us to see something but it also blinds us by taking attention away from what we cannot see. All data lies by omission. That which is left unmeasured may be where all the truth lies.
  2. iPad Optics

    Research · 33 comments

    The iPad has an installed base of over 300 million. This is a far larger audience than that of the Mac (which has somewhere between 100 million and 150 million). And whereas the iPad acquired this audience in about 7 years, the Mac took 33 years.

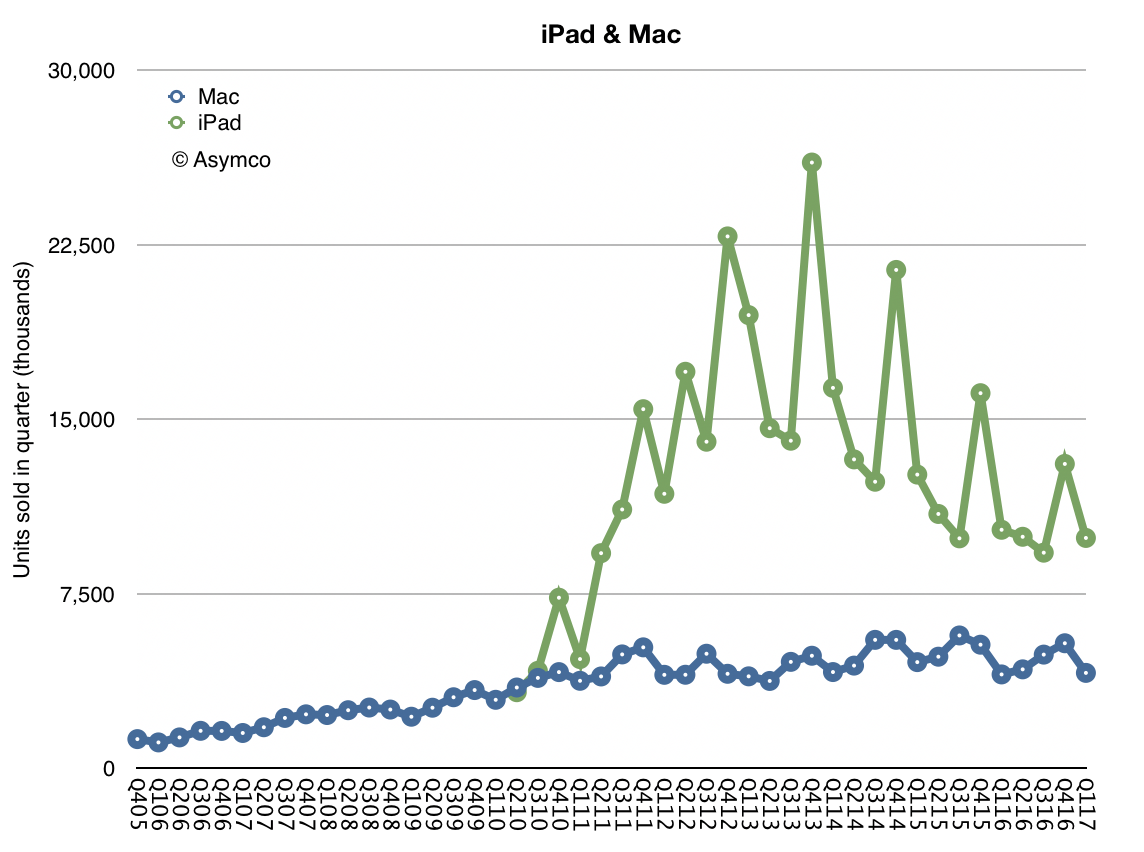
    Curiously however, it is the iPad that is seen as the more fragile product. The iPad is considered to be failing, with a presumption of an end of life in the near future. The evidence of this failure the year-on-year decline in units sold. This is illustrated by the following graph. 

    Screen Shot 2017-03-23 at 10.05.21 PM

    Note that the iPad decline is paired with a steady increase in the Mac. The iPad exhibits a four year decrease in overall volumes. This has, as they say, bad optics.

    But what is seen isn't all that might be,

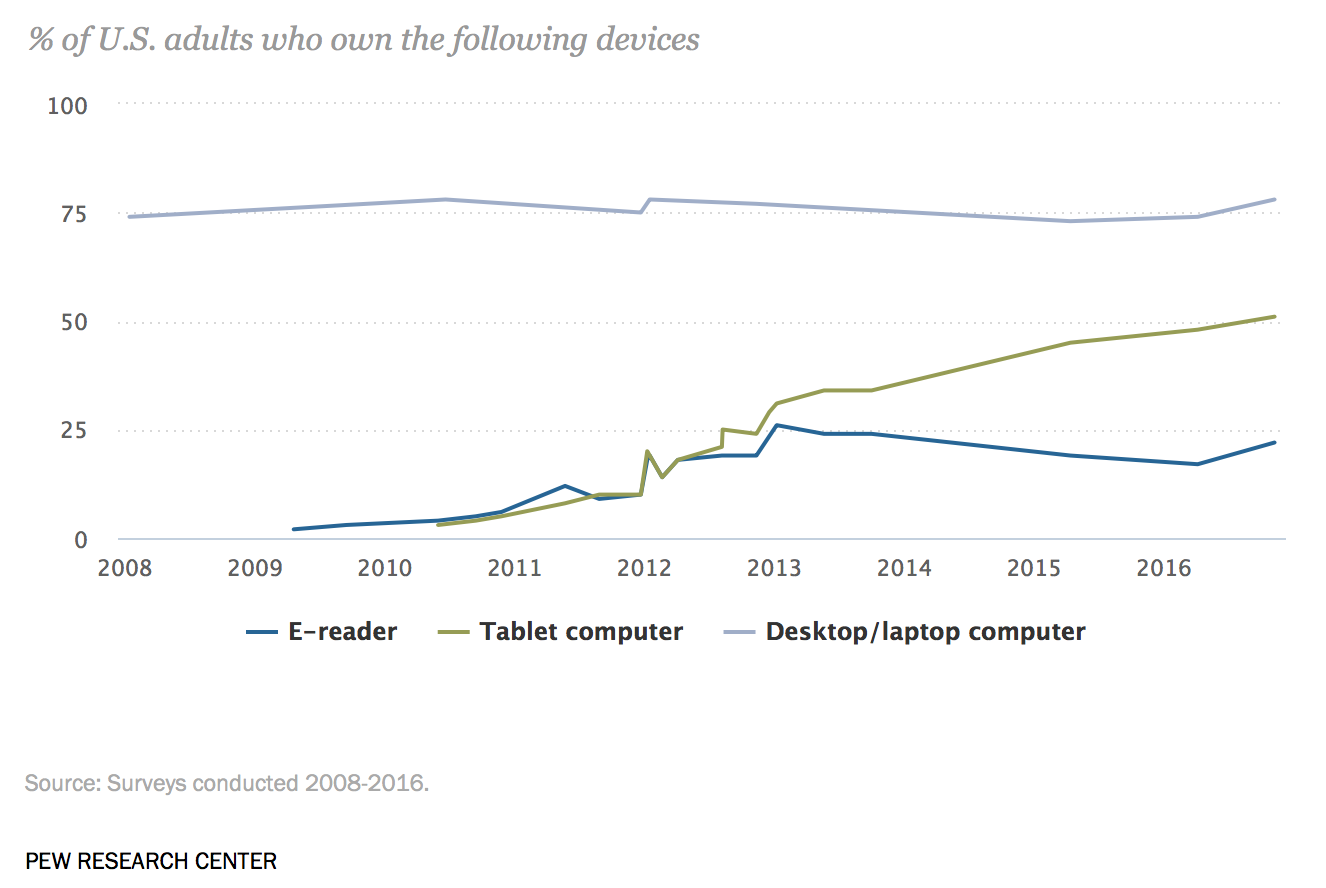
    If we look further we see that the iPad is still a much loved and much used product. Data from the Pew Internet Survey shows that tablet ownership among US adults increased from 45% in April 2015 to 48% in April 2016 and 51% in November 2016. The rise has been steady. Although this counts tablets, the iPad had 85% share of the U.S. market for tablets priced above $200 so it's a fair assumption that the iPad audience is growing. Similar data exists for the UK.

    Screen Shot 2017-03-23 at 10.11.50 PM

    In addition, user satisfaction with the product continues to be very high. Apple cited that in November, 451 Research measured a 94% consumer satisfaction rate for iPad Mini, a 97% rate for iPad Air, and 96% for iPad Pro. Finally, browsing, shopping and app usage data also show continuing high utilization for iPads.

    Furthermore, iPads are still growing in "non-consuming" markets. iPad posted double-digit growth in both Mainland China and India, it continues to attract a very high percentage of first-time tablet buyers.

    Finally, within corporate buyers there is a 96% satisfaction rate with 66% purchase intent. Apps and solutions are continually being developed for the platform.

    Taking into account that the iPad has a large, stable, engaged and loyal user base that continues to expand and find new uses the optically bad sales data needs an explanation. The simplest explanation is probably the best: iPads remain in use far longer than phones, and perhaps even longer than some computers.

    Anecdotally we can see evidence for this. Few iPads are replaced every two years the way phones are. They are not tied to service contracts or subsidized. They are also less likely to be damaged during usage as phones are dropped and banged-up. iPads are more stationary or carried in protected containers. Phones are in pockets, iPads are in bags.

    So iPads are longer-lived products and it's perfectly reasonable that people who have them keep using them and more people are joining them but slowly. Note also that the decline in sales seems to be flattening out and perhaps might show stabilization.

    Further countering of the iPad in decline idea is the continual improvement in the product. The latest is a refresh of the iPad with more battery life, a better screen and support for Pencil.

    Perhaps the iPad will not return to rapid growth, or perhaps it will. But the more likely possibility is that the iPad will level out maintaining steady levels and, perhaps, grow slightly. This flat rather than up/down trajectory is unusual in devices but it isn't when you look at the Mac. And isn't the goal of the iPad to become a computer?  If so then perhaps Mission Accomplished.


  3. The Genealogy of the MacBook Pro

    Research · 18 comments

    I was an early user of the first MacBook Air. When that product was launched I saw in it something different: a dedication to a new measure of performance: thinness and conformability. The key image used to launch the Air was the laptop sliding neatly into an inter-office envelope. The implication was that the laptop does not need to have its own special "laptop bag". It could fit into any bag. Users would be able to slip it into all manner of new contexts. It sought to compete with computing non-consumption.

    The Air was launched by Steve Jobs in 2008 and was almost universally panned. It was considered underpowered and the dedication to thinness was seen as irrelevant to what consumers wanted. The stock price fell.

    The product went on to become Apple's most popular laptop. It still is. It grew the base of Mac users to over 100 million today.

    For the same reason, I was an early adopter of the newest MacBook Retina. The even thinner new MacBook was spectacularly thin. It was smaller than an iPad. It had no ports except one USB-C and a headphone jack. It required dongles for physical connections. It had a new keyboard that barely registered movement and it had a new trackpad that did not move at all but played mind tricks to make you think it did.

    As I used it over the last year, I became used to it. It was not my only laptop. I had an older 15 inch Pro, but over time I came to use the MacBook Retina exclusively. I thought I could not do "real work" with it but I managed. I got used to the keyboard. I got used to the trackpad. I got used to the need for a dongle to connect a display. But these challenges were more than offset by delightful improvements. I was delighted by the small power brick and the ability to use any USB power to charge it. I was delighted at the all-day battery life which meant I would charge it the way I charged my Phone: at night.  I was delighted that I could use it in places where I could not use a laptop: on any airplane tray, stowing it in the seat back pocket. And I no longer cared what bag I had for my computer. It did not make me productive by completing tasks more quickly. It made me more productive by letting me be do things when and where I otherwise couldn't. I love my MacBook.

    Now Apple launched a new Pro Mac laptop.The new Pro laptop has the same (slightly improved) keyboard as my MacBook. It has the same (larger) trackpad as my MacBook. It has the same (but more of) USB-C port.  It has something new called a Touch Bar which puts function keys into a touch screen but mainly it feels like a grown-up version of my MacBook Retina. It's faster too.

    Overall, the new MacBook Pro feels to me like an evolution of the MacBook of 2015. I remember at the time thinking that this baby MacBook is probably the wave of the future: the new keyboard, new trackpad, new thinness, new USB-C, deprecation of other ports. These required enormous engineering efforts and it would be silly to leave them on only one model. In any case, from where I was standing all these were "better". Not along the previous definition of goodness but along a new definition: making the computer more conformable and easier to put into use in more places. The very ideas that drove the development of the Air of 2008. Indeed the very idea that drove the development of laptops since the 1990s.

    What's fascinating to me from a product management point of view is that the groundbreaking new features which re-define the product's direction are not designed to trickle-down from the top-of-the-line to the bottom, but rather that they trickle-up. The low-end product gets the updates first and the the Pro products adopt them later.

    And we can even trace this genealogy of features through to an even "lower-end" product: the iPhone. The iPhone "ethos" of usability and conformability has permeated through to the Macs, starting from the lowly and advancing to the top of the range. The question of where Apple's design direction comes from can be answered: the bottom.

    All this is consistent with a strategy of "low-end evolution". A way to defend the low-end rather than abandon it in pursuit of what the most demanding customers are asking for. Rather, Apple seeks to incubate a new performance measure. Re-defining goodness.

    So is this new MacBook Pro a worthy successor to the MacBook Retina? My attention is riveted by the Touch Bar. It seems a completely new way of interacting but requires discovery and practice. What Apple has to achieve is allow the product to work well without it but also to allow users to evolve their experience with it. Over time we got used to trackpads instead of mice (many resisted the change). We got used to a different, small travel keyboard. We got used to new ports (HDMI vs. VGA) and we got used to wireless everything (it may seem easier, but remember having to always enter credentials vs. plugging in a cable).

    The touch bar is a new UI metaphor. It will take time but it is looking at me right now, winking.

  4. Wherefore art thou Macintosh?

    Research · 151 comments

    Managing the Mac product line must be one of the most challenging problems at Apple. That may not be obvious given the product's success. Consider what it has achieved:

    • The product is in its 32nd year of market presence. A longevity that in unmatched by any other PC maker.
    • Apple reached a top five position in the ranking of PC vendors. This was achieved for the first time only this year, far along in the evolution of the market.
    • With about $23 billion in revenues per year, Apple places among the top four PC vendors in terms of revenue.
    • With an estimated $5.5 billion in operating margin Apple is the most profitable PC vendor, capturing over 60% of the available PC hardware profits.
    • The product has retained an average selling price of over $1200 for at least a decade. At the same time the average pricing of Personal Computers has more than halved.
    • Although volumes have fallen for three quarters, the product grew volumes and sales for 22 out of 29 quarters. As a result, volumes almost doubled in eight years. ((The unit volumes in third quarter 2008 were 2.6 million. Eight years later they are 4.9 million and could easily be over 5 million in the holiday quarter.))

    The contribution of the Mac to Apple's revenues is shown in the following graph.

    screen-shot-2016-11-02-at-2-22-23-pm

    It's attractive and convenient to contrast the Mac with the rest of the PC industry. A David vs. Goliath tale of redemption. The classic comeback story. But the split between the two old rivals (Windows/MacOS) focuses the mind into a limited view of the computing market. The big change in computing has not been a growing Mac vs. declining PC. It has been a huge surge in mobile device use vs. a decline in PC use overall.

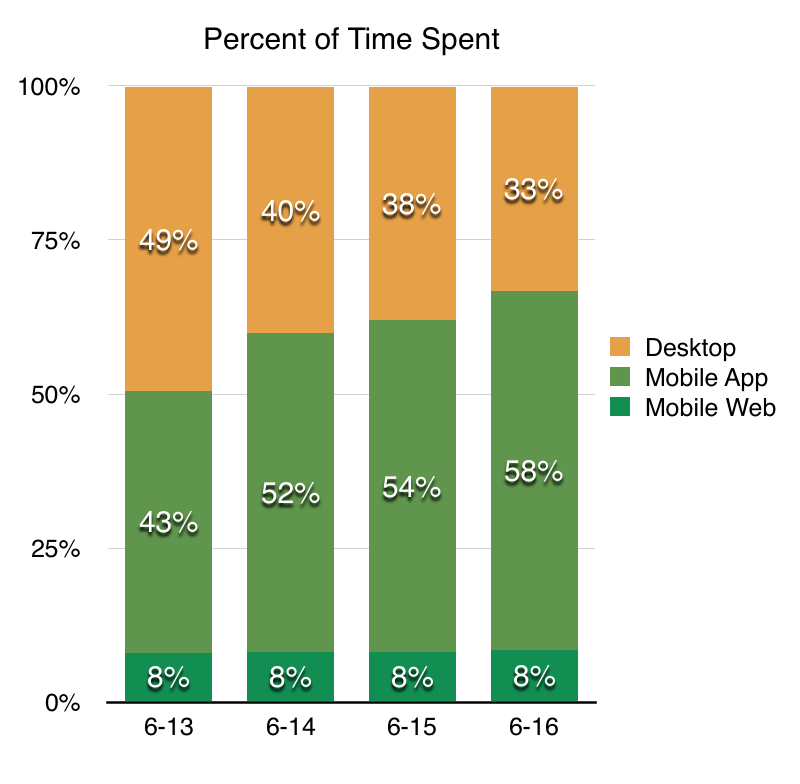
    This data is visible in many ways. Browsing data shows mobile overtook PC use this year. Shopping data around Black Friday points in the same direction. Data on user interaction captured by comScore is shown below ((Although US only, the global picture is likely to be even more skewed toward mobile as PC didn't saturated global markets before the smartphone swept to power.))

    screen-shot-2016-11-02-at-3-45-49-pm

    PC use went from half to a third of time while mobile went the other way: from a third to half of time within only four years. All the data is consistent: mobile use has swept PC use aside.

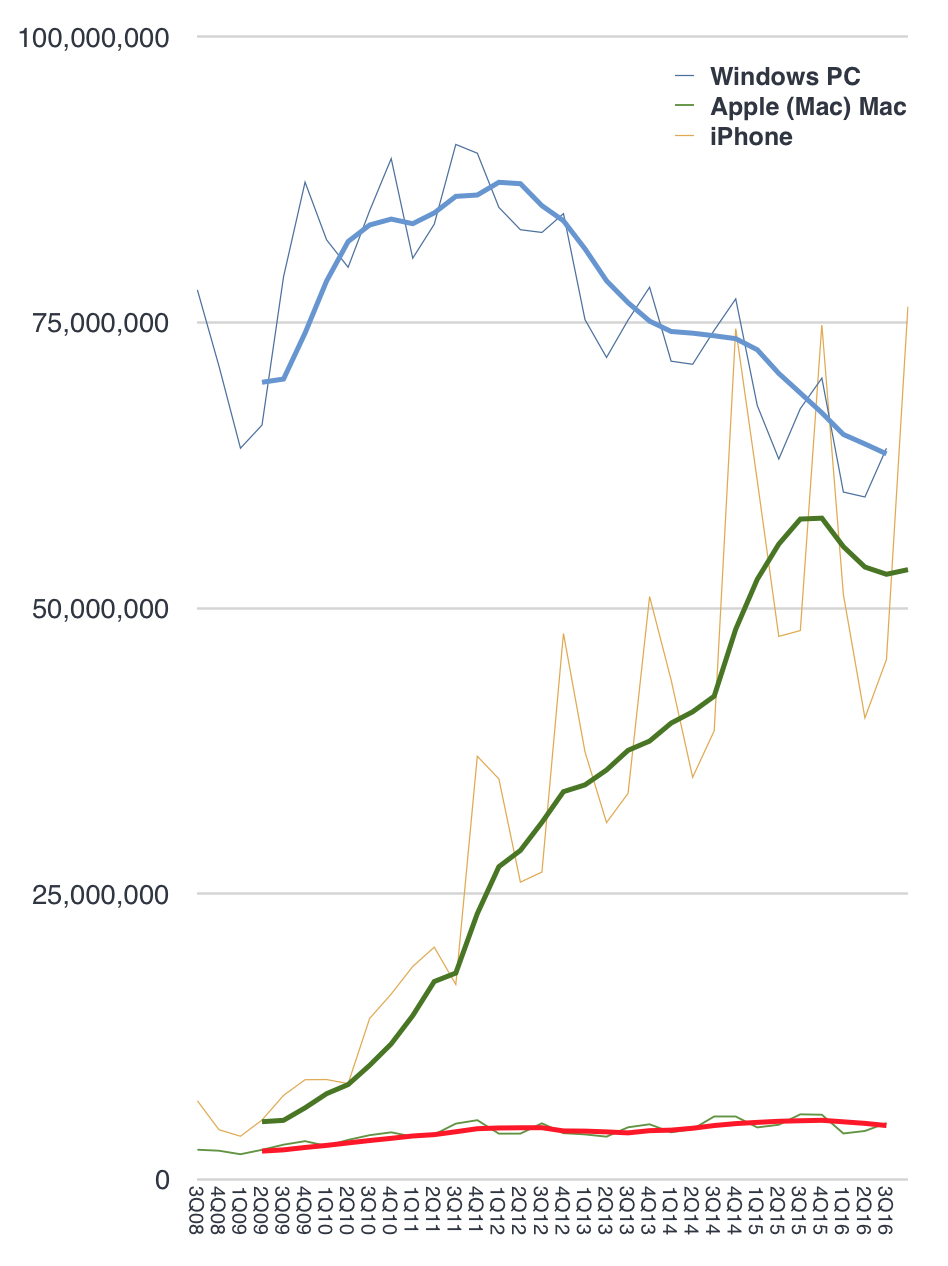
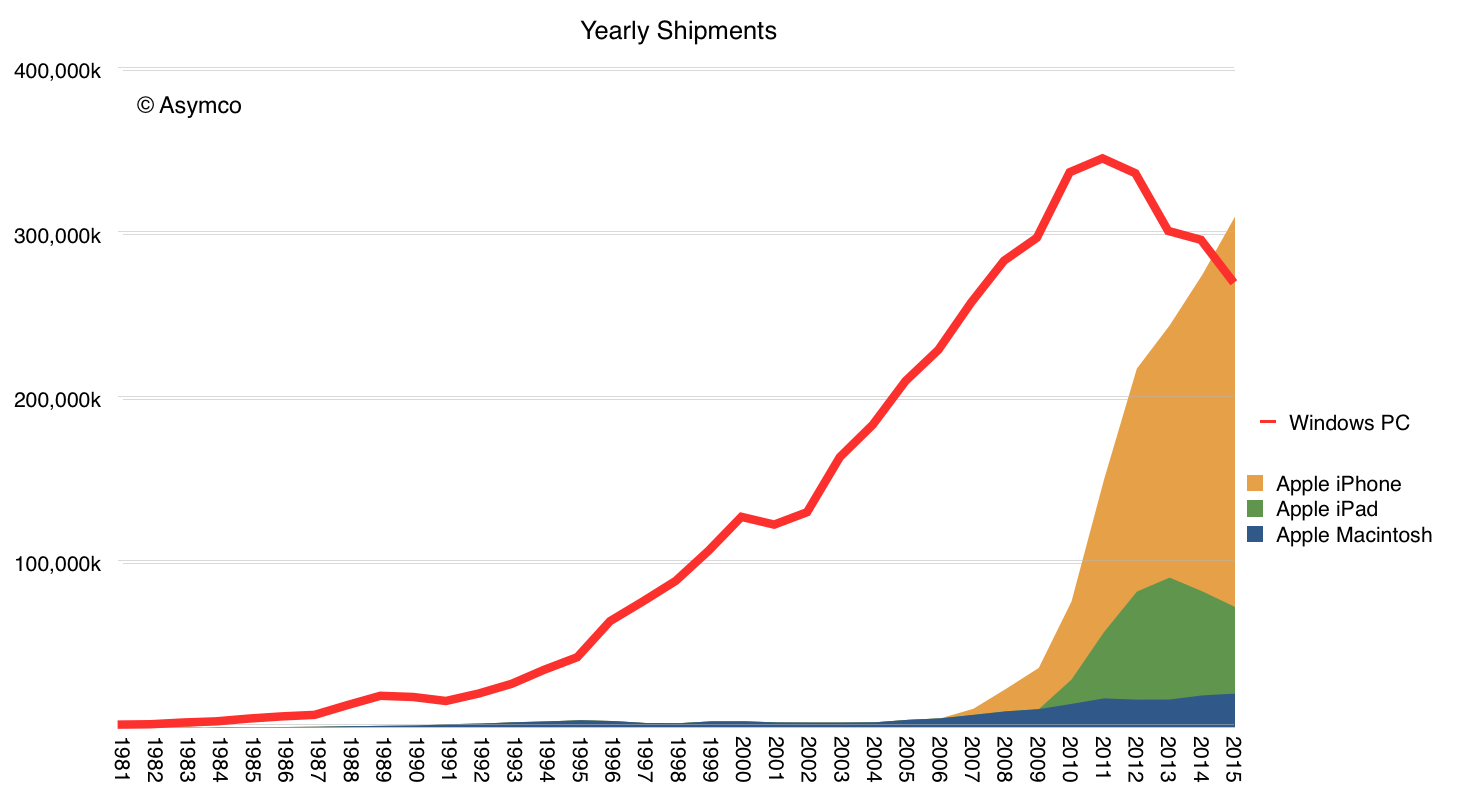
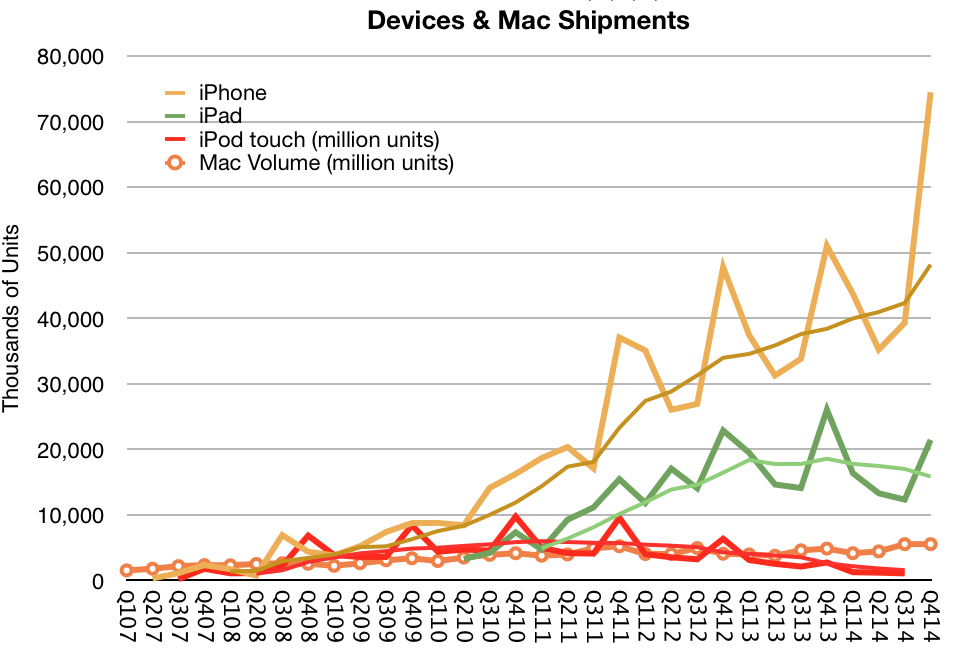
    We can see the contrast simply by placing iPhone, Mac and all Windows PC on the same shipment graph.

    screen-shot-2016-11-02-at-3-47-05-pm

    This contrast is spectacular.

    I bring this contrast up because I believe it is what focuses the minds at Apple. For them it's pretty clear where the puck is going. And not just now. Mobile has been foreseeable as a disruption to computing a decade ago–at least to some of us.

    And so what do you with the Mac?

    To answer this we have to ask what exactly is the purpose of the Mac in the age of the Mobile device?

    Note that this is not the same as asking what is the PC in this world. The PC is not having to share a resource pool with an iPad/iPhone. It does not have to answer for its existence to a phone. PC makers and Microsoft are not fighting with an usurper in their midst. They may see the outsider challenger but it's not an inside challenger. This makes all the difference.

    Indeed, because no usurper was allowed to emerge, PC/Windows never moved to a mobile evolution of computing. Microsoft's platform future was lost because the antibodies which eat disruptions were left unchecked.

    But Apple's immune system was suppressed. It allowed a disruptor to emerge from within. Apple gave birth to its future by suppressing the reaction to that new seemingly parasitic organism. It took an immense willpower to allow this to happen.

    But it takes us back to the question of what to do with the incumbent, the donor of DNA and resources. The parent that sacrificed for the child.

    The Mac is thus not treated disparagingly. It deserves and gets respect. It is preserved but with limited responsibilities.

    Which brings me to the question of what it is allowed to be and hence what it is. It cannot take on the role of being the future. That belongs to the touch screen devices. It will not morph into a touch device any more than a teen's parent will become cool by putting on skinny jeans. What it will do is become better at what it is hired to do.

    The key to the Mac therefore becomes that which the iPad/iPhone isn't: an indirect input device. The keyboard and mouse/trackpad are what define the Mac. The operating system, the apps, the UX, are all oriented around the indirect input method. The iPhone's capacitive touch brought about the direct input method, a third pivot in input methods (first was mouse, second trackpad/scroll wheel). Each pivot launched a new set of platforms and the Mac is the legacy of the second.

    It's not obsolete but it is a decreasing share of engagement. Alternate ways of doing the jobs it does well with direct input are emerging on the third pivot but they are not yet good enough. The children are still adolescent and making lots of stupid mistakes. There's still life in the parents.

    The management thus has to focus on how to make the keyboard/trackpad interface better while still saying and believing that the future is touch.

    In this context the newest MacBooks Pro are a logical extension of the second wave of computing while avoiding cramming them into the third wave. They are defined by their constraints. Seen thusly, the move from keyboard/trackpad to keyboard/touchbar/trackpad is pure genius.

    The touchbar coupled to the other two inputs is a totally new way to interact with computing products. It's not an "easy" interface as it's not direct manipulation. It remains indirect, a defining characteristic of the second wave. Indirect inputs are powerful and lend themselves to muscle memory with practice. This is the way professional users become productive. The same way keyboard shortcuts are hard to learn but pay off with productivity, touchbar interactions are fiddly but will pay off with a two-handed interaction model. They are not something you "get" right away. They require practice and persistence for a delayed payoff. But, again, that effort is what professionals are accustomed to investing.

    This is a leap forward and a big deal. For 32 years the UX model of the Mac has been two-handed typing with one handed gesturing. Now we have the option of two-handed indirect manipulation: one hand on the touchbar and one hand on the touchpad ((the iPad pro already encourages two handed direct manipulation)). Imagine you've been playing guitar with one hand for years and then someone lets you use your left hand. Holy cow.

    Even so, it may seem that Apple is pulling punches. The product could have evolved into the full-touch, dual screens, pen input, hybrid model of Windows. But that only makes sense if you don't have a mobile product that is promising the same and tearing up the world at the same time.

    You've unleashed a disruptive force and now you're supposed to retrofit the incumbent with the tools to compete. Why not just let the disruptor grow up unhindered.

    The Mac is what it is because it's not alone. It's part of a family. It is a parent. It strives to be better but will not take the future from its child.

  5. The Next 40

    Research · 28 comments

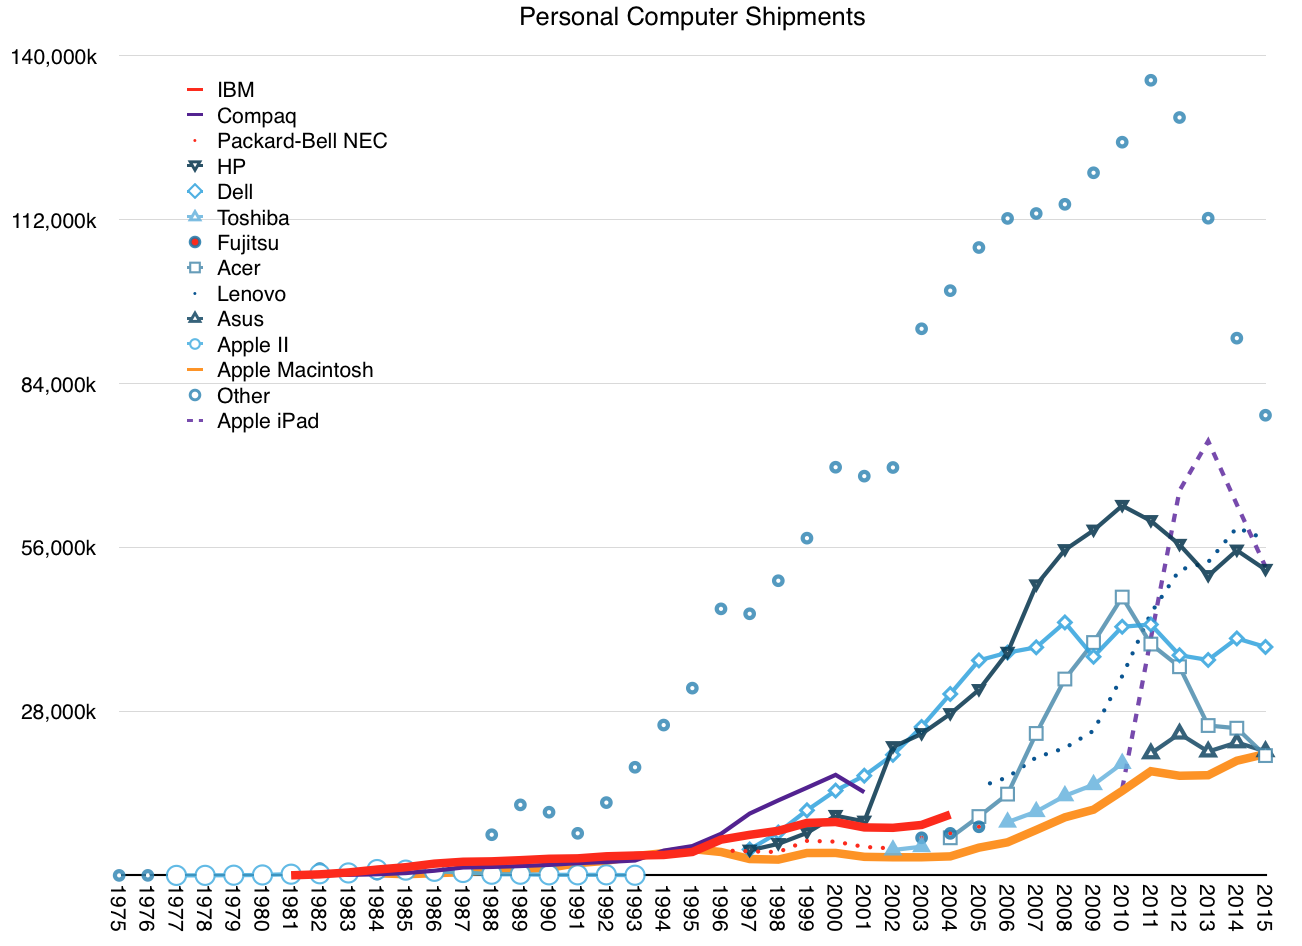
    In Apple's first 40 years it shipped 1,591,092,250 computers ((including Apple II, Mac, iPhone, iPad and iPod touch; excluding Apple Watch, Apple TV and other iPods. Includes Q1 shipments estimated at 63,597,000 Macs, iPhones and iPads)).

    This shipment total is higher than any other computer company in its first 40 years. Actually there are no other PC makers that are 40 years old. One computer maker (IBM) is older but they only sold PCs for 24 years and what they still sell they don't sell in high numbers.

    That does not make it the top seller in a given year. Looking at only the Mac, Apple's traditional form factor personal computer, Apple has only returned to the top 5 last year. Only if including the iPad it was the top computer vendor in 2011 and including iPhone, it was first in 2009.

    Screen Shot 2016-03-28 at 11.36.56 AM

    After having a 40 year run and after selling more computers than all American and Japanese computer companies put together, how should we think about the next 40 years?

    First, clearly Apple shifted from being a "computer company". It has already changed its name to exclude the word "Computer" but that has been interpreted as saying that it sells devices (which happen to also be computers.) The word "computer" is already archaic. We stopped using computers to compute in the 40s. We used them to make decisions, keep track of things, speed things up and then to communicate and then to entertain.

    Devices, it seems, are what customers mainly use to do, well, everything. Computing has grown to encompass most activities we engage in. So is Apple then a device maker?

    More broadly, irrespective of the name, is Apple at 40 still defined as a hardware company? Certainly Wall Street ((i.e. average people)) still think so. The conversations one hears clearly consider Apple's future to be tied to the sales volume of specific products. At one time it may have been the Mac, another, the iPod and now the iPhone. This thinking is again a legacy of where the company was but mainly it's a reflection of how revenues are reported.

    We see a line item in the income statement that says "iPhone" and it has a big number next to it so we, of course, fixate on that big shiny number. But if we were to unpack that number and see why it's so big we would discover that buyers are buying something other than what financial statements report.

    Buyers are buying experiences, I hear you say. Yes, but more than that. Much more. They are buying safety, comfort, convenience, simplicity, productivity. They are buying modules to combine with other modules that help to do something. Something better. They are buying hope, satisfaction, escape or vanity. In other words they don't know what they want but know when they have it. They trust products unseen which have a reputation of delivering that which they think they might like, without knowing what that is. By employing the product, and a whole lot more—effort, time, mental energy and repetitive actions—they learn to exploit a product to achieve satisfaction.

    Screen Shot 2016-03-28 at 4.59.14 PM

    Products are enablers, as are experiences and software and ecosystems and services. They are modules used in a melee of activity to make the user feel they are making progress. And if that module is better than no module then it will command a price and if it's better than another module or modules then it will command a premium. And if most people agree then it will be popular with many. And only if all these are true will it create a big number on a report.

    And so we must search for other names to call a company that delivers an enabler that may lead to progress. Crude categorization like the reporting of finances leads to self-deception and a loss of opportunity to understand. Firms are often victims of this self-deception because they start believing that customers buy the things they sell. They start to believe that what is on their financial reports is a reflection of the value they create. It's a simple mistake to make, but a mistake which leads to catastrophe. If its data is mis-categorized, by chasing numbers the company runs away from opportunity, leaving it to competitors otherwise unencumbered with knowledge of numbers.

    Assuming Apple avoids mis-categorizing what it does, will it be a "solutions" or "services" or "brand" company? Is it, as I used to say, a "blockbuster manufacturing line"?

    Yes, and still that's not all it could be. Nor is it enough to understand what will come.

    My simple proposal is to think of Apple (and actually any company) as a customer creator. It creates and maintains customers. The more it creates, the more it prospers. The more customers it preserves the more it's likely to persevere. This measure of performance for a company is not easy to obtain. It's not a line item in any financial report.

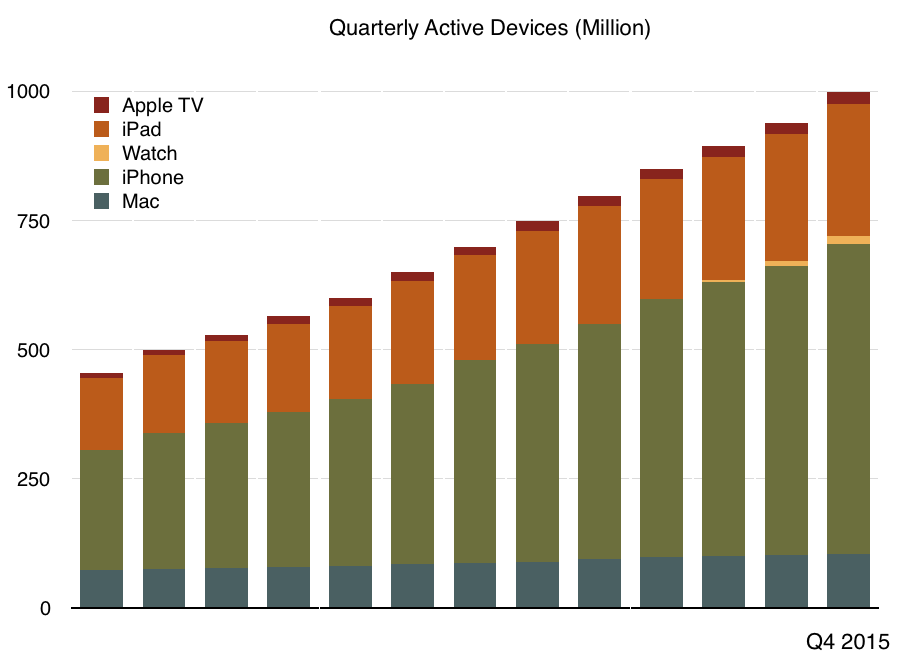
    The closest figure we have is that today Apple has one billion active devices in use. We're not told of the total users or total customers because Apple cannot count people or wallets as accurately as it can count active devices. But as imperfect as it is, this number gives us a way to get close to counting customers.

    So we know that at least Apple has created a large number of customers. Knowing total devices sold and number in use means that we can be sure that 63% of all the computers Apple sold are still in use. This means that most customers are recent customers. That is not necessarily good news. New customers are not well understood. We don't know how these new customers might behave in the future.

    Screen Shot 2016-03-28 at 12.28.22 PM

    Will they come back for more of whatever Apple makes? If we look at the history of competitors or technology products in general, chances are they won't. The industries Apple has been a part of are filled with one hit wonders. Companies which had parabolic trajectories and built no loyalties. Statistically speaking, success in Apple's markets is always followed by failure.

    But what if we did not seek correlation but looked for causation? What if we ignore statistics about companies other than Apple and focus on statistics about Apple's actual customers? Rather than assume all companies are the same, what if we assume that some can be exceptional?  What if we we look for the anomalies, not the clusters?

    We might want to ask about the causes of success or failure for a single company. We might want to sample its specific customers.  We might want to observe how Apple's own customers behaved in the past.  We might want to use theories of brand value or theories of network effects or theories of software ecosystems.

    These measures, rather than those of "comparable companies" might lead to different conclusions: That customers are loyal, that they will value the brand and that they are invested in a network. In other words, that they will buy from Apple again.

    If we then factor in the size and persistence of Apple's audience (customer base) we might conclude that there are factors which will allow it to grow rather than shrink. My analysis based on public data shows that the customer base has been increasing steadily.

    Screen Shot 2016-03-28 at 4.17.19 PM

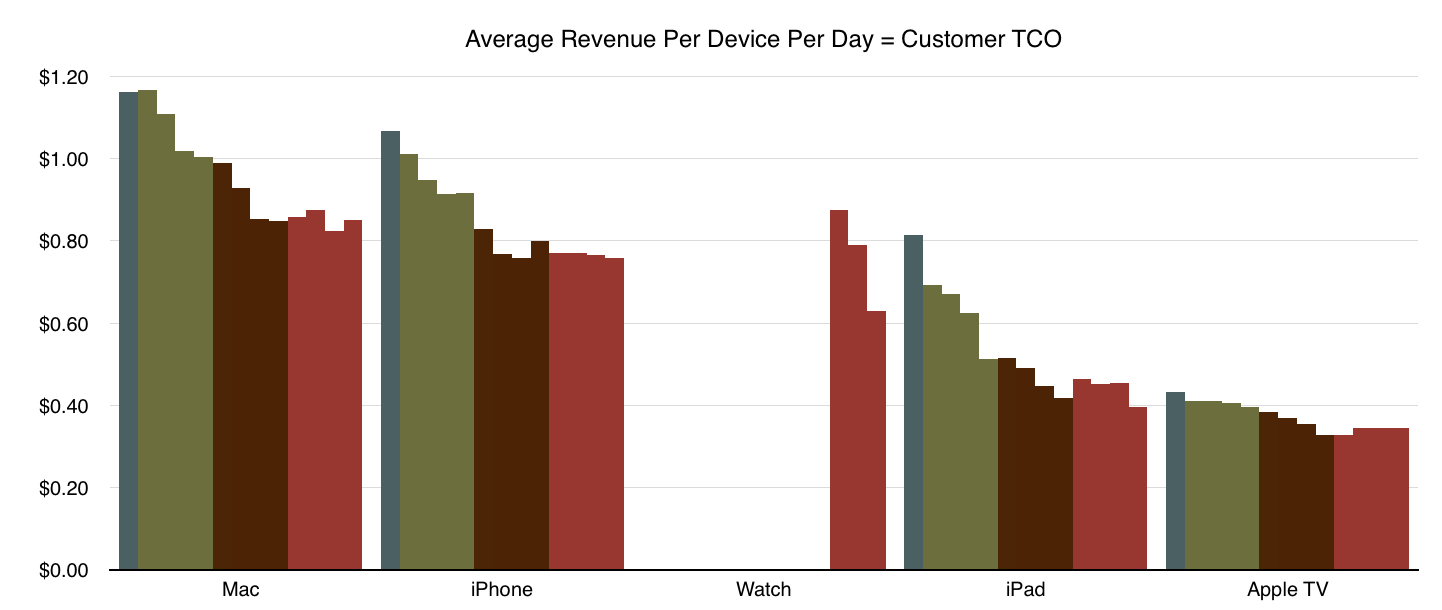
    Considering this audience and the revenues generated, we can categorize the revenue by active device as follows.

    Screen Shot 2016-03-28 at 4.15.51 PM

    Each bar represents that product's revenue per day in a given quarter (from Q4 2012 to Q4 2015). Each year is therefore represented by a different color. Dark green for 2012, light green for 2013, burgundy red for 2014 and dark red for 2015. For example, each iPhone in use was generating exactly $1/day in revenues (including services and accessories) during the first quarter 2013.

    This allocates all of Apple's revenues to these products and by proxy to customers.

    In summary, the "average revenue per Apple device per day" is currently $0.68. If we assume one unique user per device then Apple collects 68 cents from each customer each day. ((In reality the figure may be closer to $1, as there are likely to be more 1.2 to 1.5 devices per person.))

    Screen Shot 2016-03-28 at 4.19.39 PM

    Combining the history of customer creation and customer preservation with the value obtained from each customer implies that the next 40 years will be about creating another large tranche of customers whose willingness to spend on whatever Apple creates will be relatively unchanged.

    We don't know the limit. One billion was hard to imagine even one year ago. We might see two billion devices in short order. Perhaps not. Perhaps as we have a multitude of devices about us all day the number will become less meaningful. But if the number of middle class customers grows and as Apple keeps its products within their reach, there is no reason to think that there will be a reversal of the last 40 years in terms of customer acquisition.

    This analysis contradicts the current perception of the company as reflected by its stock price. That price assumes the audience will wither ((With a P/E ratio of 11, without a change in revenue per user, the only justification would be the audience shrinking by more than 90% over the next 20 years.)) That is not insanity. It is what we could expect if Apple were unexceptional.

    We could surrender to correlation and ignore causation but statistics show that such an approach rarely works.

    -------

    Incidentally, this and a lot more will be discussed at the next Subscribe conference.

  6. How iPad Educates

    Research · 20 comments

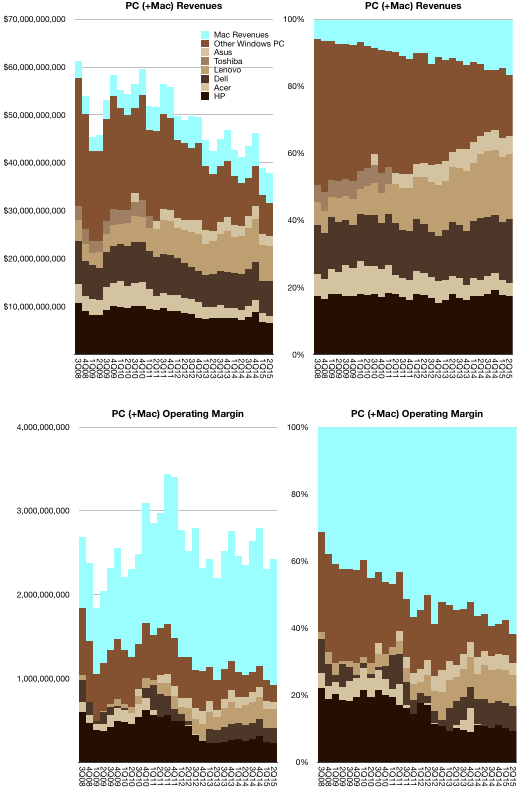
    The fact that the iPhone is contributing over 90% of the operating profits in mobile phone sales has penetrated even as far as the Wall Street Journal. However, it's not yet commonly known that the Mac captures a majority of personal computer operating profits, at least when considering the sale of hardware.

    My calculations suggest at least 60% of operating margin in personal computing hardware is captured by Apple. This is mainly due to the fact that the average Mac sells for more than $1200 while the average PC sells for less than $450.That is equivalent to $1.5 billion per quarter for Apple vs. $930 million for all the other PC makers combined.

    Screen Shot 2015-07-17 at 12.16.27 PM

    If we are to consider the iPad as a "PC equivalent" computer ((for a substantial minority of tasks)) then another $billion/quarter is contributed to the profit pool. It increases Apple's share of profits to 73%. As a result, Apple absolutely dominates computing profits.

    But, as we know, computing, even on handheld devices, is enabled by a multitude of business models. Selling hardware is one thing, but Microsoft showed that one could sweep up profits in the industry by selling enabling software. It's much harder to assign a share of profits if we try to consider all the business models associated with computing and all the form factors that computing has taken shape in.

    The problem can be acutely observed with the iPad alone. It's sold with a decent margin ((my estimate is a gross margin of around 27%)), though not one which approaches that of the iPhone ((my estimate of the iPhone gross margin is near to 48%)). It also enables an ecosystem with thousands of collaborating firms and users.

    Consider the uses of the iPad in education. 15 million iPads were sold to educational institutions. An unknown number of millions have been hired for education uses by end-users or teachers. The result is over 100,000 education apps are available in the App Store.

    The education sector's "jobs-to-be-done" has led to the product being associated with entire new processes for education. Education is not a product but a process and therefore any technologies must be hired as part of the process. In the App Store you can see the “Apps in the Classroom” guides along with impressively powerful apps being used in education. These are educator-created guides designed for other educators.

    There is no way to measure the "profit" in this endeavor.

    Nor is there a way to capture the "profit" in people engaging in exercise because they wear an Apple Watch.

    Nor is there a way to track the operating profit of HealthKit which has enabled 1000 apps to help people manage their health.

    These education and health efforts are not designed to be profitable. And yet Apple is very profitable. That is because creating valuable things generally leads to value being accrued by their creator. How that happens is not very important. Indeed, focusing of the how is actually often self-defeating. What matters is the why and the what is done.

    Understanding this leads us to understand the foundation of any great organization, not just Apple.


  7. Breaking the Law

    Research · 22 comments

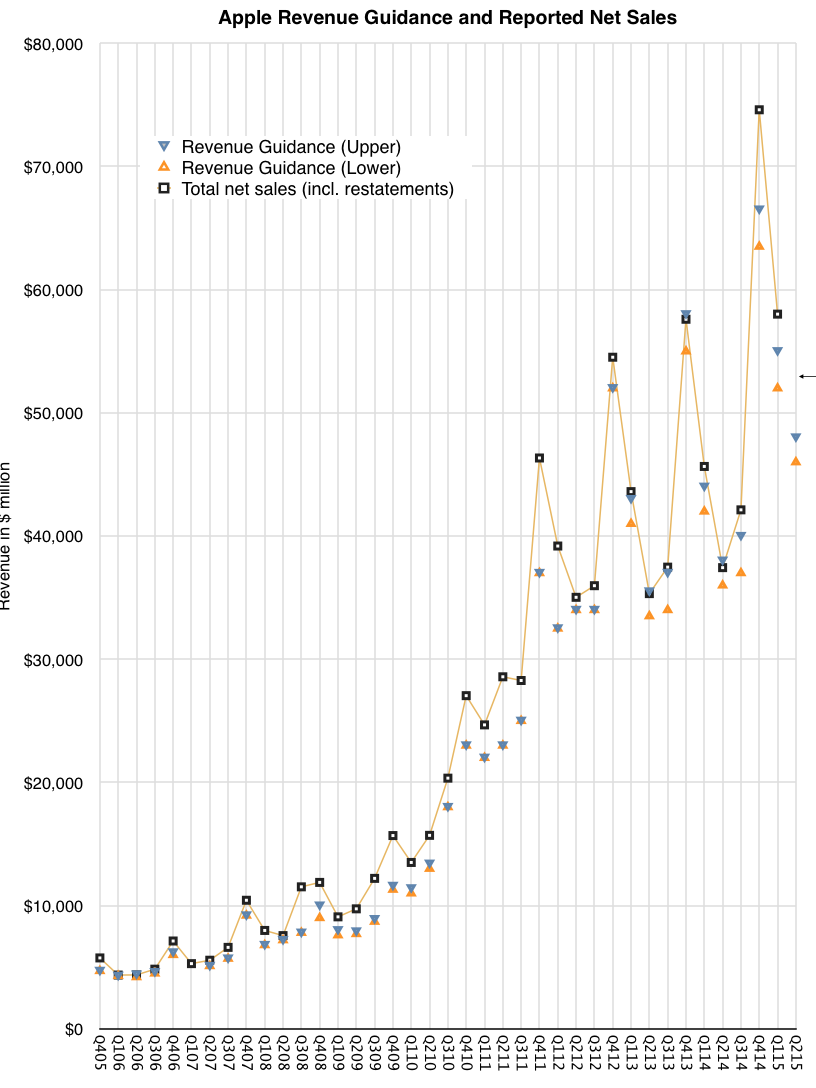
    For the first time in many years I feel that there is some potential uncertainty in the results Apple will announce. After a period of excellent accuracy (shown in graph below), the company's guidance has begun to diverge dramatically from reality and the trend might continue this quarter. The cause might be unanticipated demand for the iPhone 6/6 Plus. The growth rate for the product was 46% in Q4 and 40% in Q1. This is unanticipated because growth rates have been below 20% for five quarters and below 50% for eight.

    Screen Shot 2015-07-13 at 12.21.00 PM

    This slowing of growth was explainable given the rate of diffusion of smartphones in the global population. Within the US and some other early adopting economies the market is reaching late stages where most people have switched to smartphones. Globally we are at a more modest 30% or so but in many of the late adopting economies Apple does not have wide distribution.

    Of course this thesis is thinly supported. There are many reasons to think that late adopters would still start with iPhone and that earlier adopters of Android would upgrade to iPhone after a few purchase cycles. Thus, the iPhone could prosper in later-adoption or even in post-saturation states of the market.

    Indeed, in the post-saturation PC market, Apple is doing very well with the Mac and in the late to post-saturation MP3 player market the iPod did extremely well. This suggests that when it comes to value capture brand, experience and satisfaction trump function, price and share considerations in almost all consumer markets ((Enabled by design for jobs to be done. See non-technology markets for abundant evidence of this. ))

    With so many assumptions put asunder the iPhone business suddenly looks downright lively. I adjusted my own growth assumptions and the resulting figures are shown below.


    F3Q15Daniel TelloHorace Dediu
    iPhoneUnits51.052.8
    Price626645
    Revenues3192534059
    iPadUnits10.010.6
    Price428430
    Revenues42804567
    MacUnits4.954.94
    Price12401240
    Revenues61366129
    ServicesRevenues50065196
    OtherRevenues39023092
    TotalRevenues5124953043
    COGS3057731766
    GM40.3%40.1%
    OpEx57335789
    OpInc1493915488
    OI&E357350
    Pre-tax1529615838
    Tax40234165
    NetInc1127311673
    Shares57795780
    EPS1.952.02


    I include for comparison Daniel Tello's forecast as his work carries quite a bit of thoughtful analysis.

    The upshot of this is that the company is poised to grow earnings per share at a rate of at least 50%!

    That growth rate is astronomical, especially for what is already, by far, the world's biggest company by market capitalization.

    This was not supposed to happen because of a so-called "law of large numbers." The "law" is actually a probability theorem which states that the average of experimental results should be close to the expected value given sufficiently large number of experiments. The way it's applied in market analysis (I assume) is that "no company can perform above market average performance for a sufficiently long time".

    It implies that there can be no outliers and that all companies "revert to the mean because ..."

    Actually, I don't have any idea why they might. The premise that all companies are the same must play into this but companies can only be alike if they have the same processes, priorities and resources. As long as I've been able to observe and as much as I've ever read on the subject I have never encountered any two which had anything in common.

    And so the law of large numbers, as applied to market performance is a myth. It is easily disproved with a simple deconstruction into the causes of firm performance, but the empirical data from Apple alone shows how foolish it is to believe it.

  8. iOS v. Windows and Immunity to Disruption

    Research · 30 comments

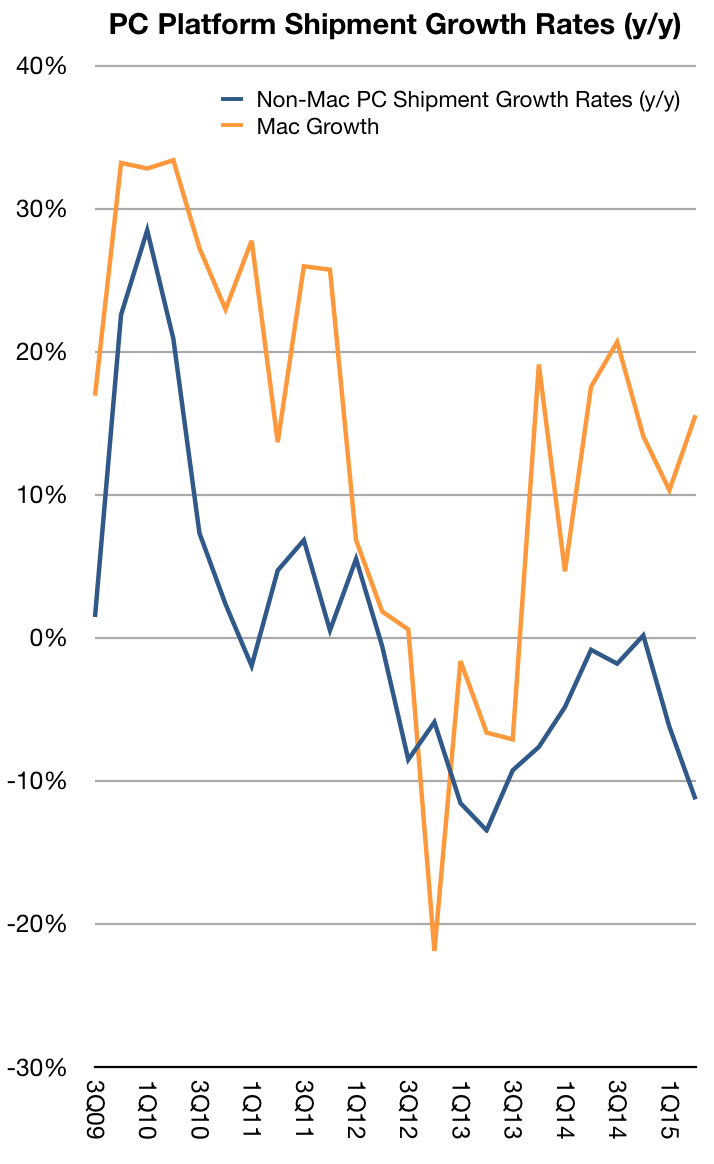
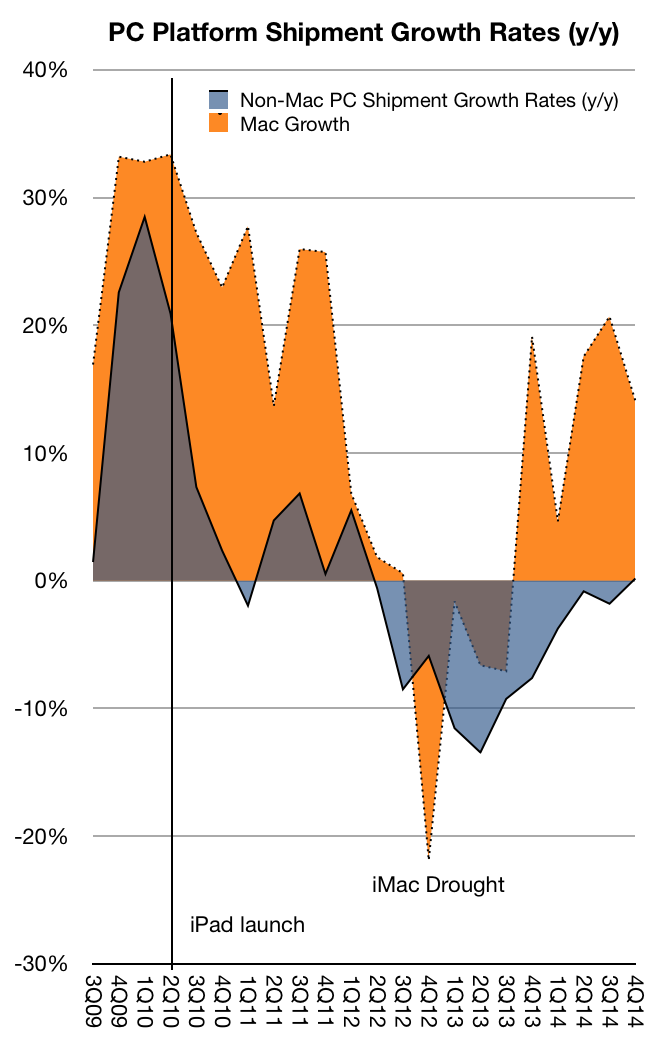
    The pattern of Mac growth exceeding Windows PC growth (and overall PC growth which includes the Mac) is old news. It has been observed for at least 40 of the last 42 quarters.

    Screen Shot 2015-07-10 at 12.47.04 PM

    It's a historically interesting contest, but the story of computing has moved on.  Starting with building computing, via floor computing, office computing and then to desktop computing and portable computing we are now in the era of mobile computing. ((And as sure as the sun will rise tomorrow we will move beyond mobile computing)). The problem with observing mobility in general is that there are too many mobile computing options. Phones have a wide range of capabilities, tablets and various other form factors are positioned on differing jobs-to-be-done. Platforms and services are also scattered around jobs which have been carved from fixed computing or have been established with no fixed precedent.

    So can we pinpoint with any accuracy the moment when the tipping point has been reached? We could point to all mobile phone shipments, or even the vaguely-defined smartphone shipments compared to all PC shipments. We could look at tablets alone. If we could get accurate measurements.

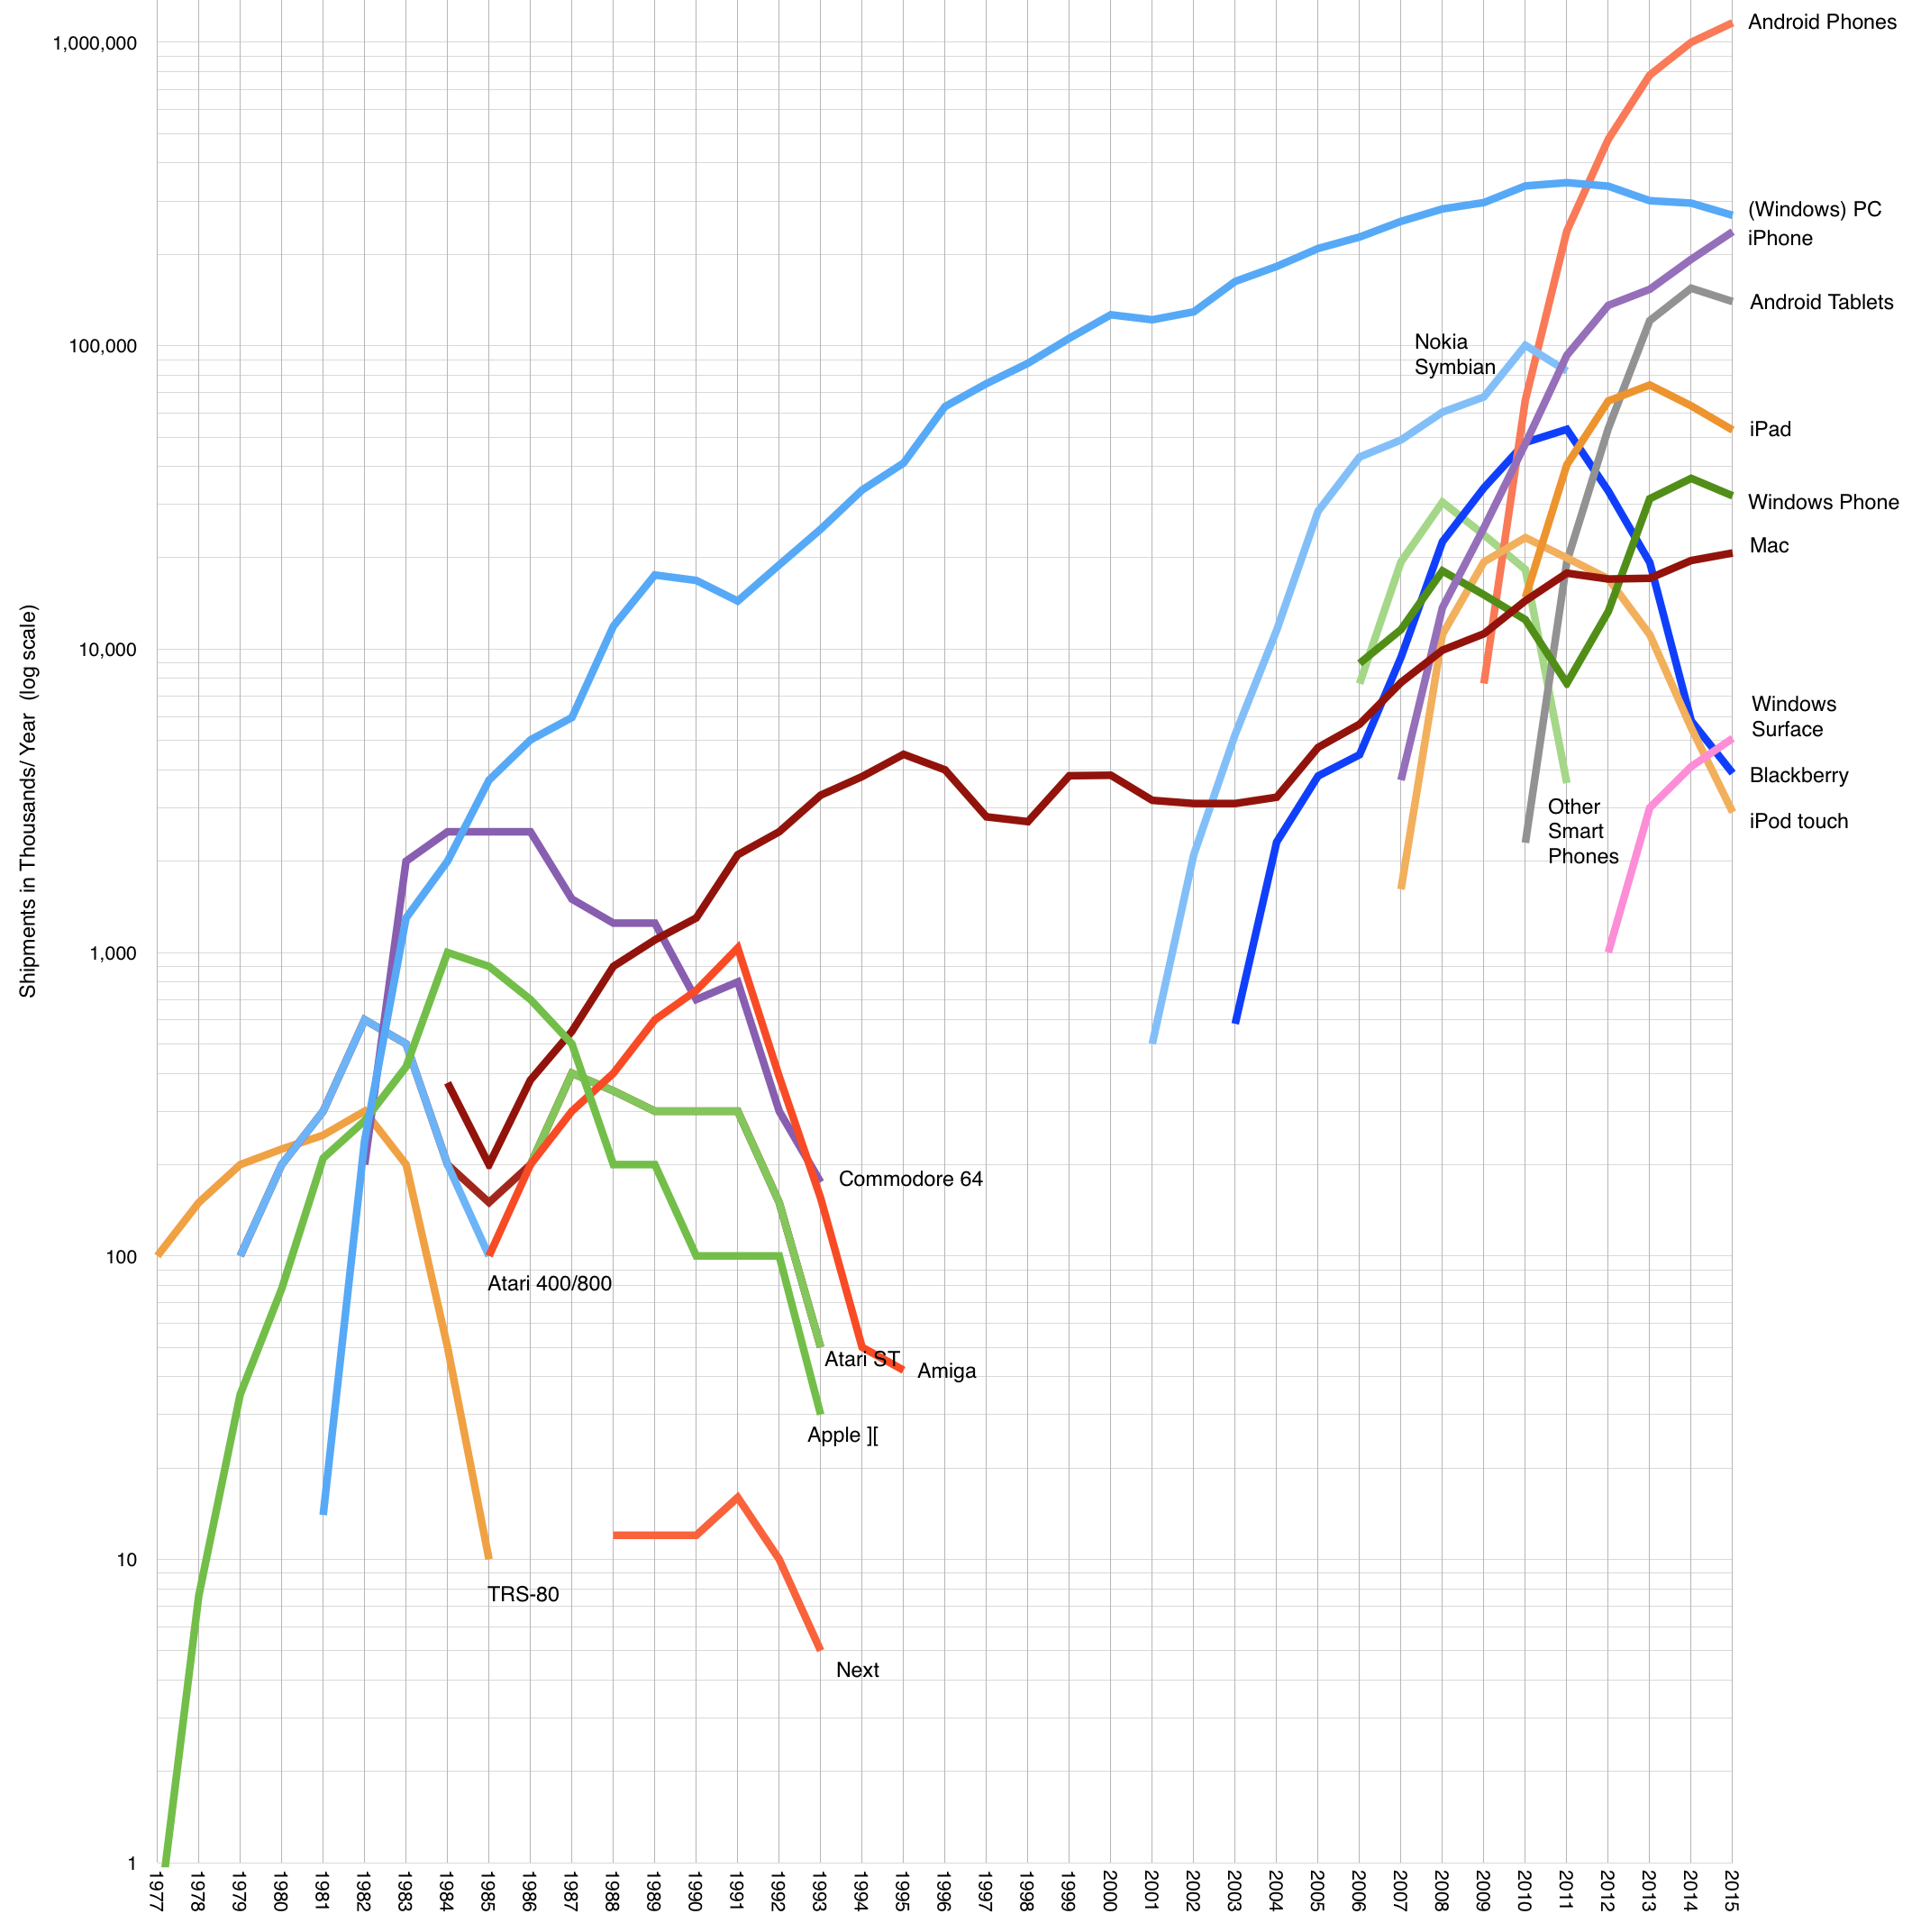
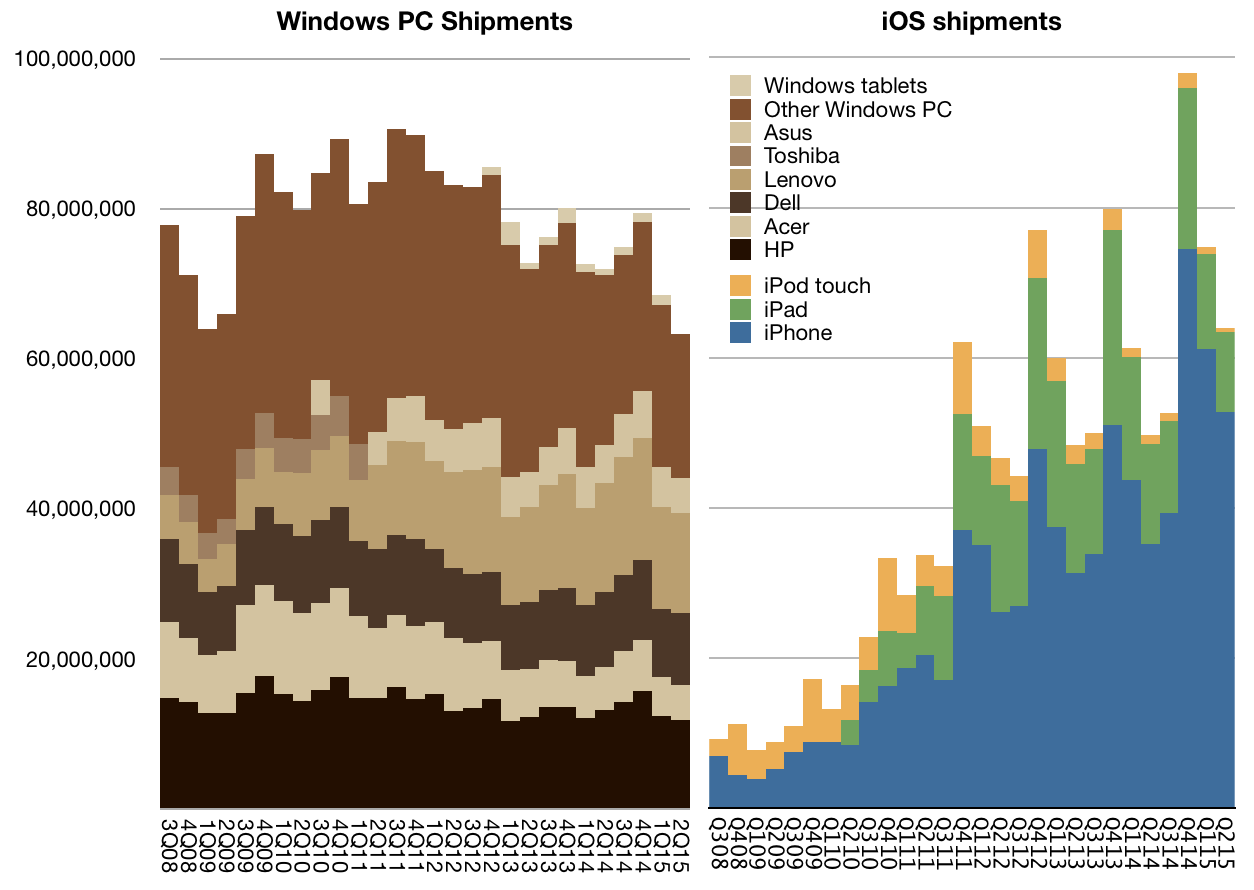
    One measurement could be to look at operating systems alone. When comparing iOS shipments (iPhone, iPad and iPod touch) to Windows we can see that combined iOS shipments exceed all Windows PC shipments for all three previous quarters.

    Screen Shot 2015-07-10 at 12.54.25 PM


    Which reminds me. This week Microsoft wrote off the acquisition of Nokia's mobile phone business. The growth of mobile as an alternative to desktop/laptop computing was foreseen by Microsoft a decade before the the data in the graphs above. It began in 1994 with Windows CE development, proceeded with a PDA operating system by 1998 and the Pocket PC brand in 2001 and Windows Mobile in 2004 and Windows Phone in 2009.

    After anticipating, predicting and dedicating decades of work why didn't Microsoft  participate in its own vision?

    The curious thing about disruption is that predictability does not result in immunity. If the new trajectory threatens the current profit formula, the trajectory is not joined with enthusiasm. There is an uncanny unwillingness to self-disrupt.

    The exceptions to this rule are so rare that they are seen as magical, enabled only by accident or catastrophe.

  9. Luxurious

    Research · 102 comments

    Apple's new watches are priced in a pattern unlike any of the previous pricing models for Apple products.

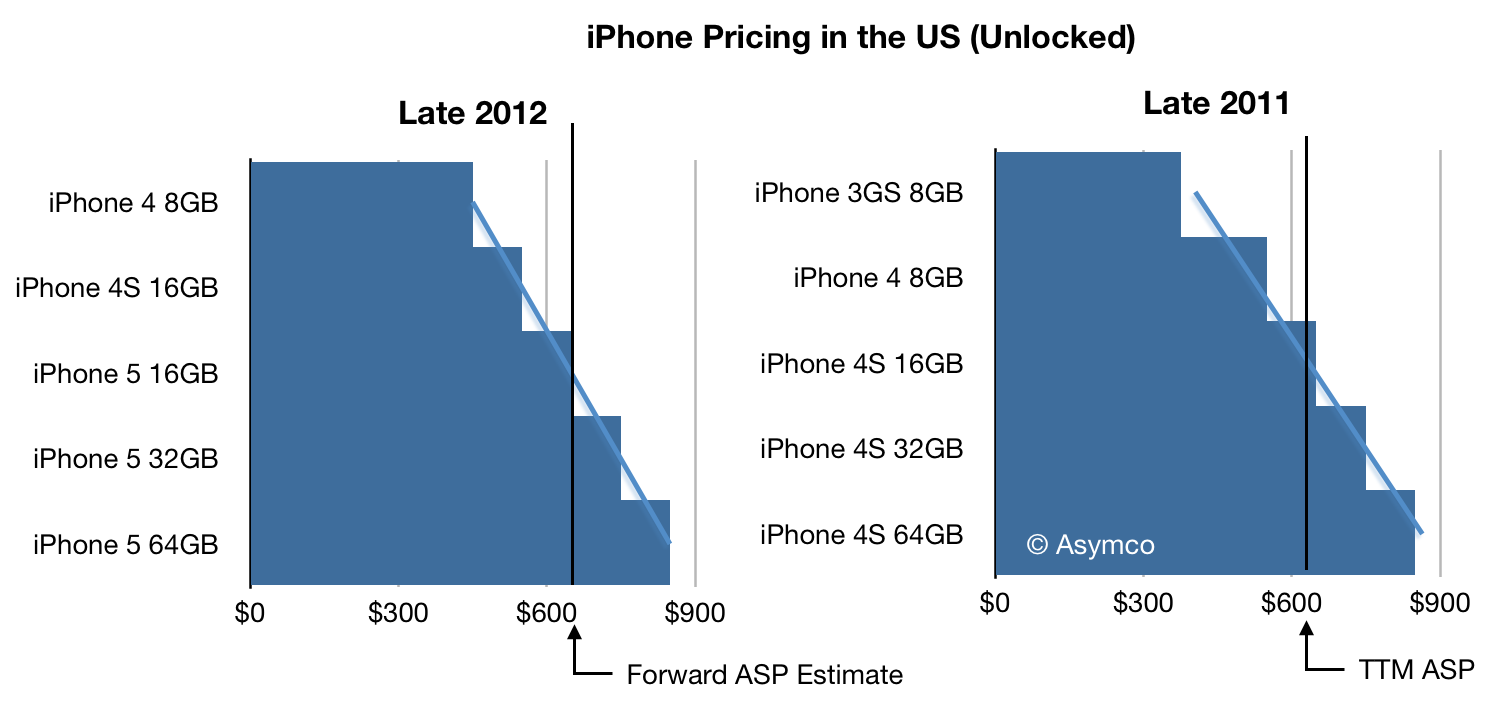
    Previous pricing models for iPhone, iPad, Mac and iPod were typically structured around storage differences. The higher the storage, the higher the price. The Mac had a slight variation where processor and graphics offered some additional configuration options. To illustrate, the graph below shows typical price bands for the iPhone (2011 and 2012)

    Screen Shot 2015-03-30 at 11.51.16 AM

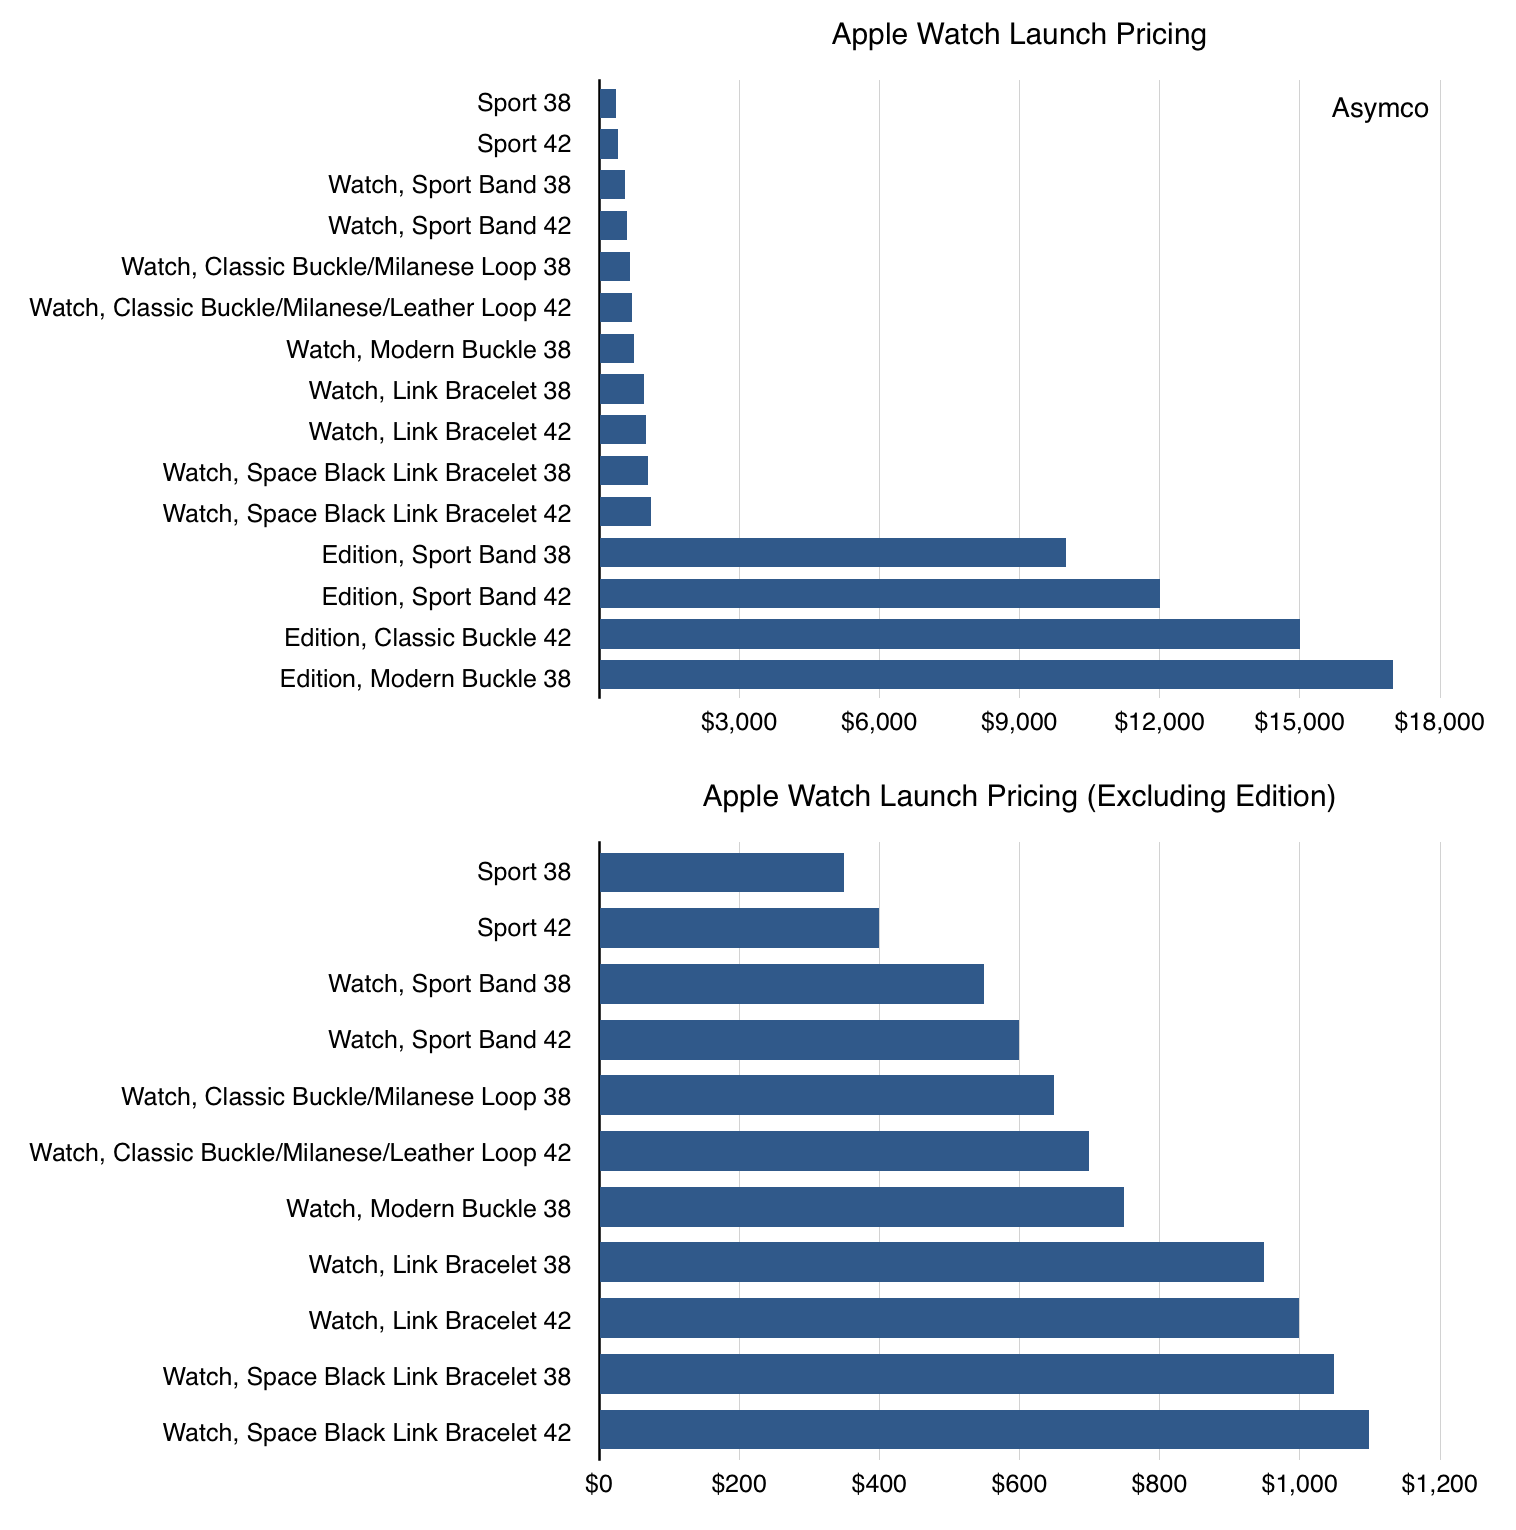
    In contrast, the watches are differentiated by size, materials and bands. There are also a total of 38 watch configurations available at launch (SKUs) and another 38 bands that can be purchased separately.

    The bands come in four price points and the watches in 15. Of these 15 watch prices, four are dramatically different. The pricing of the watches is shown in the two graphs below (with and without the Edition).

    Screen Shot 2015-03-30 at 12.03.19 PM

    This mix of product makes average pricing estimation more challenging, but the more pertinent question is what does this new pricing model signify? Is it something that Apple can "pull off"? Can Apple actually price not on functionality (or options thereon) but on materials?

    It used to be said that Apple's profit engine was fueled by the ability to price memory at a significant mark-up on its cost. The iPod earned the vast bulk of music player profits by offering additional memory increments at significant price increments. Even today, a 64GB iPod Touch is priced $100 higher than a 16GB version. Sounds reasonable, but a quick check shows that 64GB of Flash memory probably costs about $5. This exploitation of pricing/cost differences at the margin allows for great profitability and is rooted in the ways the buyers contemplate value.

    Therefore the difference between memory-based pricing and materials-based pricing is only in the choice of how to attach value in the mind of the buyer. In one case it's having the option on storage, in the other it's having the option, perhaps, of more durability, quality or glamour.

    The tricky part is understanding just how much the market will bear. What is the right differential for pricing of steel vs. aluminum? Or what makes gold worth so much more?

    The cost of these materials (and the processes needed to manufacture them) is not very important. As with memories, the differences are not that significant. It could even be that the Aluminum process is more expensive than the steel process--it depends also on volume.

    What matters most is how to gauge the perception of value.

    This is where one can take cues from the existing market. Gold is costlier than steel but the pricing difference is greater still. Multiplying $1000 (cost) by 10 (to get a price) yields far more profit than multiplying $1 by 20. This perception of gold as being worth it is far beyond its utility--a perception which has taken centuries to build. What Apple is doing with Watch pricing is simply leveraging existing perceptions of value for materials and using them to capture profits for an otherwise purely functional product.

    But that process of using perception to gain pricing advantage for function is how Prestige branding has always worked. The notion that materials, craftsmanship and attention to detail can be priced at huge multiples of cost is possible only with the right brand. That brand, itself built over decades, even generations, gives assurance of quality, perhaps exclusivity and comforts the purchaser in the moment of decision. It also provides assurance after the purchase and preserves the feeling of value well into the future. So-called Luxury brands are those which can impart these qualities on their products and extract the pricing advantage.

    Sounds great, so why doesn't everybody do it? The answer is that it takes time and perseverance, with typically low volumes. This is not something technology brands have been able to do. Mainly because the products are perishable but also because they have not been around for long. With technology, the value is high at purchase on a functional basis but diminishes rapidly afterwards. It's as if, in order to preserve notional brand value, a product needs to be a functional commodity, undifferentiated on what it does but differentiated on the way it does it.

    This is the unique value of Apple's brand: among technological brands it can stretch to cover the perception of value for design, materials, craftsmanship and prestige. At the same time it offers new experiences and introduces new products for new jobs to be done.

  10. Apple's Growth Scorecard

    Research · 26 comments

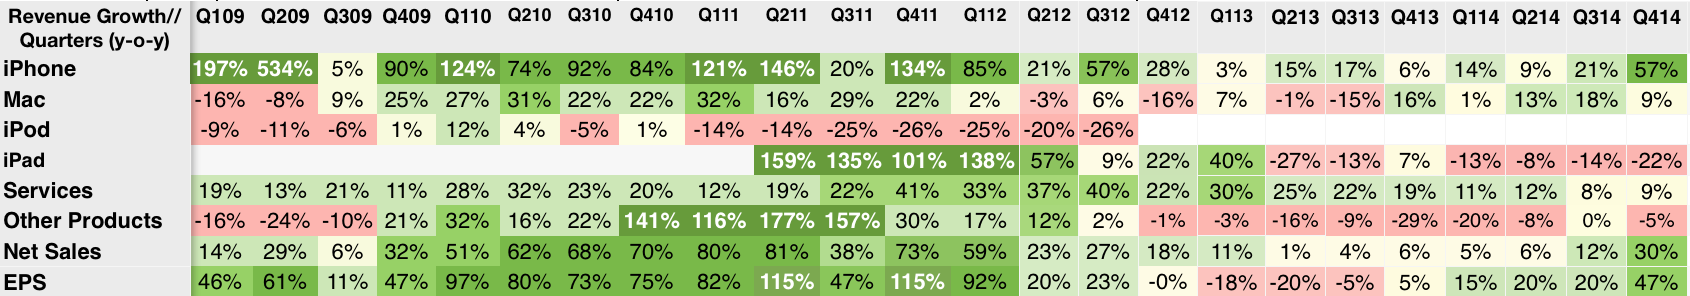
    Apple's Net Sales grew at the rate of 30% in the last quarter. Earnings per share grew at 47%. Both of these figures are the highest since 2012.

    Screen Shot 2015-02-08 at 5.27.47 PM

    It should be noted that although the rate of growth is extraordinarily high, the company never actually stopped growing in the past three years. As the table above shows, net sales has always had positive growth.

    Compared with the fourth calendar quarter of 2011, Apple's sales are 61% higher and earnings per share are 54% share. ((Some of the expansion in earnings per share is due to the willingness of shareholders to sell their shares to Apple. 10% of the shares around in 2011 have thus disappeared.))

    This degree of growth at this stage in the history of the markets it participates in is a revelation.

    Consider:

    • The PC market is more than 30 years old. In this mature market the Mac has been outgrowing the Windows platform for 34 out of the last 35 quarters.
    Screen Shot 2015-02-08 at 5.35.43 PM


    • The iPhone was announced eight years ago and it still managed to grow at the rate of 57%.
    Screen Shot 2015-02-08 at 5.47.11 PM
    • The market shares of its Mac, iPhone and iPad products are all remarkable only for their paucity.
    • The pricing of all their products is more than double the median for their categories.
    • Regardless of extreme growth, pricing power, headroom and, most importantly, customer loyalty, the company's prospects are seen as dismal in contrast to its underperforming peers. ((As measured by P/E or FCF/EV ratios vs. direct rivals, technology companies or the S&P 500.))
    • Such is the plight of the anomalous.
  11. Interview With Horace Dediu: What To Expect When Apple's Expecting

    Research · 24 comments

    My thanks to Eric Jackson for his thought-out questions on Apple. As published in Forbes, here is his Interview With Horace Dediu: What To Expect When Apples Expecting.

    A few excerpts:

    Q: Do you expect to see a sapphire cover on the new iPhone(s)? Is that material significant?

    I expect Sapphire will become a signature feature across many products. I don’t know if they will have capacity to deploy on iPhone this year but on a watch it’s essential. Here’s a clue: if the screen has any curvature, especially around edges, it needs to be sapphire as glass can’t take strain in that shape. The scope of the plant they are building with GT implies that they will have massive volume potential with at least one major iPhone model using the material. It’s a significant material because it allows design freedom in new directions, especially curved (concave) touch surfaces that retain a jewel-like feel. This has Jony Ive all over it.

    Q: Is it fair to conclude now based on the 5C and 5S that Apple will never launch a “cheap iPhone”?

    Oscar Wilde said a cynic is someone who knows the price of everything and the value of nothing. When I see the word “cheap” I never know if it refers to price or value. And even when we talk about price, an iPhone is cheaper than buying all the things it replaces so it’s always been a low end disruptor in my mind. (I saw a tweet with an image of a Radio Shack ad from the 1980s and every single item available on that page is now a part of the iPhone. It would have cost thousands to buy all those things back then–and dollars were worth a lot more.) Furthermore, I think Apple holds a black belt in pricing. They seem to define their position in the market by anchoring certain prices and “owning” them. Given all that I would say that Apple is not going to move their price points much. They will expand the portfolio and offer some iPhones at $300 but they will be older models. The average selling price (ASP) I expect to remain constant on a year-long average.

    Q: In the past, Apple critics were quick to dismiss the new iPad and 5C iPhone as failures upon their introduction.  You never judge. You just report the facts and data.  That said, is there anything about past new Apple products launches that we should look at as a predictor of how a new iWatch might be received by customers?

    When the iPad was imminent the great debate was over whether it would run iOS or OS X. Many imagined a touch-based Mac rather than the “big screen iPod touch”. It was a tough call and one which Microsoft could not and still does not make. Therefore, the interesting question for me with respect to iWatch is: What OS it will run? I will be shocked to the core if it does not run iOS. It is my opinion that making iOS work on it is the entire reason Apple is sweating this segment. They are in it because they are trying to make a platform product with a novel user experience and all the power of an ecosystem run on a wrist. It’s as big a problem as getting a phone-sized device to run a touch UI was in 2007. That is the crucial contribution that Apple is making to this next generation of computing. Now you might ask what users are asking for in this segment. The answer is nothing. Nobody is asking for this. As nobody asked for the iPhone (or the Mac or the iPad). It’s a new computer form factor and how it will be used will be determined by the apps written for it. But it will work and be magical out of the box in version 1. This is in contrast to the single purpose or accessory model of wearables we see to date.

    Q: As a student of disruption, where is Apple most vulnerable to being disrupted?

    Apple is a new market disruptor but much of what is put forward as a threat to it is low-end disruption. I think Apple knows enough about how that happens that it can manage its way around it. The strategy they employ is one of attrition. If you wait long enough a low-end threat tends to wear itself out as it starves of profit and is constantly gnawed-at by alternatives. (You see, if the disruptor cannot manage a profit then they cannot climb up the trajectory to get on top of the incumbent. Being profitable is a key requirement for successful disruption in the long term.) The attrition strategy works as long as you have the fortitude to hold out and the deep pockets to keep improving your product as alternatives flame out. It is my belief that Jobs made sure that thinking is inculcated in the company. So if not low-end is the company vulnerable to new-market disruptors? This is more subtle and the threat here is what Google/FaceBook/Amazon and the other ecosystems are all about. It’s creating new usage models and shifting where consumers place brand value. I think this is more what keeps Apple’s management awake at night. They are not standing still however. iTunes and Software and Services (now with Beats on board) is the way they are staying on top of that threat.

    Lots more here.