Asymco

Asymmetric Intelligence

Microsoft

  1. Mobile device OS upgrades: How hard can it be?

    Research · 45 comments

    Until the iPhone's arrival in 2007, upgrading the software on a mobile phone was a rare experience for users. So rare that effectively it was not done. Few people were bothered though since they did not see the product they used as a software product.

    This was even true for Windows Mobile and Symbian which were licensed platforms. Microsoft tried several times to offer upgrade paths, but more often than not the device vendors did not push out updates or the process required to perform an upgrade made it the reserve of either those who were paid to do it or those who enjoyed the challenge.

    In the era of the modern smartphone, upgrades are more common. Certainly with the iPhone the process is easy enough that opting out of an upgrade is more challenging than opting in. But it's still not as common with other platforms. Even with all the resources and experience behind them, Microsoft is still stumbling with Windows Phone upgrading.

    UPDATE 1-Microsoft explains phone software update delay | Reuters

    But is it really a matter of blundering or is there evidence of nominal partners working at cross-purposes?

    Upgrading a mobile device is technically challenging. There are many things that can go wrong. Integration helps, but it is also possible for a modular solution to be implemented. There are harder things to coordinate.

    However, things go wrong and as the linked article above shows, fingers get pointed. Device vendors who have no stake in a platform can easily interpretan upgraded OS as one fewer hardware upgrade. Platform vendor's lament that device guys want to proliferate unique versions and act with passive aggression. Device vendors see the software upgrade cycle as increased support and engineering costs with no upside. Consumers don't know whom to blame and often turn to the operators since that's who they pay every month.

    The problem of upgrade failure is a symptom of a deeper dysfunction inherent in immature modular business architectures. It's not just that the brightest at Microsoft or Nokia or Google can't make an upgrade stick. It's that the upgrade is not universally beneficial to the value chain. To remedy this, licensors have to resort to contractual obligations to ensure upgrades, but enforcement is non-trivial and can lead to aggravated relationships.

    Unless all licensees of a platform find compelling value in shouldering the burden of upgrades, they will continue to be really hard. This leads to increasing fragmentation and a corrosion of platform value for licensed platforms vis-à-vis their integrated alternatives.

  2. HTC and self-determination

    Research · 74 comments

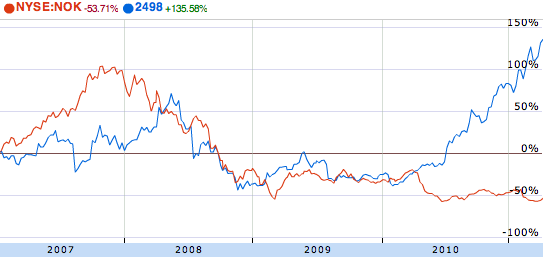
    HTC's market cap has just overtaken Nokia's. While market capitalization is a fickle thing, shifting with sentiment, this is still a remarkable feat. Nokia's market capitalization has almost halved in the space of a year while HTC has more than tripled from $10 billion to over $33 billion.

    If you roll back to 2007 and the start of the modern era of smartphones, you can see how the two companies stocks traded places:

    (source: Google finance)

    The recession was hard on everybody but HTC soared during 2010 while Nokia never recovered. Markets reward unforeseen growth and typically that means above-market growth.

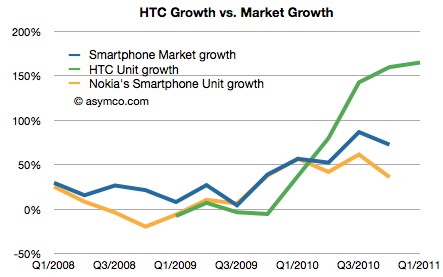
    That's reflected in the following chart (admittedly units and not profits, but pricing and margins for both have remained relatively steady.)

    As Nokia's growth lagged the market the stock was punished. As HTC's growth exceeded the market's growth, the stock was rewarded.

    But there are a few more observations to make:

    • HTC's smartphone business was under-performing the market for most of 2009. In fact, it was even in negative growth for three quarters.
    • The surge in growth coincided with HTC adding Android to its portfolio and given no other changes, seems to be causal.
    • Although not within the time range of the charts above, HTC had another period of rapid growth in the mid 2000s.

    A year ago HTC was making excuses and apologizing. Today they are more valuable than the largest phone vendors. All thanks to Android.

    But why no thanks to Microsoft?

    HTC was the primary Windows Mobile vendor a few years ago. They claimed at one point to have shipped over 80% of all Windows Mobile devices. They were also the leader in the Pocket PC franchise as they were the ODM behind the iPaq brand from HP/Compaq. HTC would not exist today were it not for Microsoft.

    The relationship is such that HTC is paying Microsoft for protection from (potential) Android IP infringements. HTC has also licensed Windows Phone though the relationship between Nokia and Microsoft must give them pause.

    But that's the whole problem. Those who live by the sword shall die by it. HTC was a Microsoft dependent and now they're a Google dependent. As the basis of innovation shifted, HTC was agile enough to make the transition. Perhaps they can execute a portfolio switch yet again as their upstream suppliers change whims or business models.

    But then again, as we saw with Windows Phone, perhaps not.

    If HTC wants to control its destiny it needs to control its suppliers. Now that its power and brand have grown, it needs software because in their market software is self-determination.

  3. Who's knifing what?

    Research · 147 comments

    Microsoft just declared the Zune end of life. This makes it a good time to look back to some notable episodes in the evolution of digital media distribution. First, an episode from 1997:

    During two days on the stand, Tevanian accused Microsoft of seeking to divide the multimedia market and then "sabotaging" QuickTime's ability to work with Windows computers when Apple declined to go along with Microsoft's plan. Justice also is accusing Microsoft of attempting to illegally allocate the Internet browser market.

    In particularly colorful testimony on Nov. 5, Tevanian described an April, 1997, meeting between two Apple and two Microsoft officials. Tevanian, who was not at the meeting, said Microsoft officials suggested that Apple abandon its business of providing "playback" software that enables users to view multimedia content on the computers. Instead, they offered Apple the much smaller portion of the market for the tools that developers use to create the content. In Apple's mind, though, the playback software was its baby.

    According to Tevanian, Apple executive Peter Hoddie asked Microsoft officials, "'Are you asking us to kill playback? Are you asking us to knife the baby?'" He said Microsoft official Christopher Phillips responded, "'Yes, we want you to knife the baby.' It was very clear."

    Business Week Online/Microsoft Watch on the cross-examination of Apple's Senior Vice-President Avadis "Avie" Tevanian Jr. during the Microsoft antitrust trial.

    Ten years later:

    “We came into the [media player] market, a market in which they are very strong, and we took, I don’t know, but I think most estimates would say we took about 20-25% of the high end of the market,” “We weren’t down at some of the lower price points, but for devices $249 and over we took, you know, let’s say about 20% of the market. So, I feel like we’re in the game, we’re driving our innovation hard and, uh, okay, we’re not the incumbent, he’s the incumbent in this game, but at the end of the day, he’s going to have to keep up an agenda that we’re gonna drive as well.”

    Steve Ballmer on Zune, iPhone (CNBC interview) .

    Four years later the Zune is no more. Besides being interesting anecdotes, what patterns emerge from these episodes?

    The evolution of the bases of competition for media distribution between 1997, 2007 and 2011 is striking.

    • In 1997 the struggle was between specific modules (formats, players and technical standards.)
    • In 2007 the basis of competition was devices integrated with music services (which encompassed formats, standards and players).
    • By 2011 the competitive standard that the iOS ecosystem is putting forward is at an even higher level of integration. Not only are the sub-modules integrated into a whole, but now apps bespoke to a platform are attracting a virtuous cycle of third party innovation.

    Now consider how the two protagonists evolved (or didn't) during this 14 year saga.

    Apple has maintained its attention steadfastly on products while Microsoft has maintained unwavering focus on the distribution and control over value chains. During the 1990s one strategy worked and the other didn't. During the following decade they changed places. The locus of the two strategies did not change. What seems to have changed is what the market values.

    So we have to ask: Is the end of the Zune a matter of poor execution or is the cause for failure something more profound? Is Microsoft's real problem that they have prioritized that which is no longer valued?

  4. Star-crossed partners

    Research · 36 comments

    Until very recently, we believed our competitive position in smartphones could be improved with Symbian, as well as MeeGo, and our strategy based on those platforms. We are now of the view, however, that for the longer term our Symbian platform is not sufficiently competitive in leading markets.

    Nokia's SEC Form 20F.

    The company's fiscal year, which ended in June, was one of the worst to date for the mobile space. Although in development since 2008, the Kin was pulled after just over six weeks of sales and amounted to a $240 million write-off before including the $500 million to buy Danger. Windows Mobile's ramp down is partly intentional as Microsoft is rebooting the platform with Windows Phone 7 and is investing $500 million in marketing to spark new interest.

    Microsoft CEO bonus cut for Kin flop, lack of iPad rival | Electronista One irony is inescapable: the world's largest device company can't build commercially successful software and the world's largest software company can't built commercially successful devices.

    Another irony is that the competitive threats that both companies face came from challengers that were not perceived as such a few years ago.

    Google was not a platform vendor three years ago and Apple was not a phone vendor four years ago.

    The largest incumbents in separate industries sought salvation in each other after the market they strove to build went to unforeseen challengers. All in a span of three years.

    I cannot think of a more succinct testament to the process of disruption.

    One can only speculate about the probability of success of this pairing, however, I struggle to find a historic precedent where this type of relationship succeeded.

  5. The Allegory of Treo

    Research · 35 comments

    The following is a work of fiction.

    The combination seemed unthinkable just a few years ago. Nokia envisioned itself as a substantial rival to Redmond, threatening to head off its computing dominance as the power of desktop computing shifted to pocket-size devices. But a series of miscues substantially weakened the company, leaving it little choice but to team up with the world's largest software maker.

    Although Nokia has pledged to continue using the Symbian OS in both handhelds and phones, the company has now significantly tied its fortunes to the rival it once denounced.

    In doing so, Nokia is making a tough bet. The company is gambling that Microsoft's operating system has advanced far enough to power a decent cell phone, while still having enough rough edges that Nokia can carve out a niche by going beyond the standard Windows Phone software. In doing so, Nokia hopes it can avoid the fate of being just another clone cranking out hardware on Microsoft's behalf.

    Microsoft, meanwhile, has scored a significant win in its decade-long quest to crack the mobile market. In wooing Nokia, Microsoft has brought a one-time rival into its fold and ideally gained a new creative force as it tries to move its PC empire into the burgeoning market for cell phones.

    "Nokia always did great work, and so we lusted after some of those things that they do well," Ballmer told reporters at Monday's launch.

    The partnership is not totally out of the blue, of course. The two companies offered a glimpse at the detente last year, announcing a pact that allowed Symbian OS-based smartphones to connect directly with Microsoft's Exchange servers for corporate e-mail and calendar information.

    In its secret meetings, Nokia execs managed to convince their Microsoft counterparts to build several software hooks they needed into the latest version of Windows Phone. The changes allowed Nokia to add some handy features into the Windows version of the N series phones. One new trick allows Nokia owners to ignore an incoming cell call, instead sending a brief text message to the caller. A second feature allows Nokia owners to navigate multiple voice-mail accounts using VCR-like buttons, rather than having to know that "5" is the key for fast forward or remember that "7" saves voice mail at work, but deletes it at home.

    A key question, though, is whether Microsoft will give Nokia enough room to innovate in the future, now that it has successfully wooed the device maker. By going with Microsoft, Nokia is letting go of one of the key differentiators between its products and those from better-known competitors.

    Elop said he understands the risk and only undertook it with assurances that Nokia would be able to build enough software on top of the OS to make his products stand out.

    "It was the only way we felt it could work for us," he said at the Monday press conference.

    Executives from both companies suggest that the Nokia-Microsoft relationship, forged at those meetings in Cannes and New Orleans, will continue to be close. But it remains to be seen whether Nokia will retain its individuality now that it has the Microsoft imprimatur.

    Wirt acknowledges that there are no formal procedures in place that ensure that Nokia will get the things it asks for the next time, or the time after that. "It's functioned more as a relationship-type thing."

    Elop said Nokia could try to patent particularly strong advances, but in general he said the company believes the best way to stay ahead is to keep cranking out new products.

    "We have ideas about many things that we didn't get to do in this version," he assured reporters.

    But for all its ideas, Nokia is still a relatively small company. And given that it has pledged continued support for the Symbian OS, it must now divide its limited engineering resources between two incompatible efforts.

    Elop acknowledged that the challenges of developing for two entirely different operating systems are enough to keep his firm hopping. He emphatically shook his head back and forth when asked if Android and MeeGo-based Nokia phones might be next.

    "We don't need another operating system," he said, adding later, "It's too much effort."

    This fictional article was created by taking an actual article from 2005 about Palm and Microsoft (Palm's tale of Treo intrigue - CNET News) and changing the words "Palm" for" Nokia", and "Colligan" for "Elop", "Ballmer" for "Gates", "Treo" for N series (or Nokia) and "Symbian" for "PalmOS". A few paragraphs about the mechanics of the deal process were deleted.

    Credit: This tweet from Charles Arthur.

  6. The skill of strategy analysis: Uncovering company priorities

    Research · 86 comments

    John Siracusa dusted off an interesting quote from a former Microsoft employee.

    Spolsky: But synergy…there are also negative synergies. In the case of Microsoft they call it "strategy tax." Where, like, the Internet Explorer team is not allowed to fix the DHTML editor because it might compete with Word. So they’re forced to make that continue to be bad.

    Via: The Apple strategy tax

    The notion is an interesting one and is a reframing of the metaphorical expression that those who live by the sword die by the sword: Building a business a certain way will, in the end cause it to perish by that way.

    In the case of Microsoft, the focus on their platform lock-in strategy binds them into avoiding compelling opportunities and, even more tellingly, keeps them from improving existing products.

    It's tempting to suggest that this "strategy tax" also applies to a company like Apple when it seems to act irrationally or sub-optimally to some arbitrary definition of optimality.

    However, what if Apple's motives are not "strategic"? What if Apple actually does act in a way to optimize what they perceive to be important: the end user experience or as I like to call it "the product".

    What if "the product" is dogma and nothing is allowed to compromise it?

    This question is not designed to glorify or defend any one approach, but rather to ask what is to be compromised. In Microsoft's case dogmatic "strategy" means the installed base and channel cannot be compromised. In Apple's dogmatic product approach, is the relationship with partners subject to compromise? Is the platform itself compromised?

    I would argue that yes, the product-focused company has to "pay a tax" for its product priority. It uses an approach with a huge built-in opportunity cost. But I would also argue that every company has some tax to pay for its priorities.

    Ultimately, every company needs to decide what is important and to pay the tax for not doing what is unimportant. Business management, like engineering, is about compromise and the choice of trade-offs. Outside observers, unaware of what the company's priorities really are, will always find it puzzling why companies do what they do. But to insiders, the puzzle is why anybody would do anything else.

    The most important skill for an analyst, and that which separates her from the casual observer, is to determine what the company's priorities really are. Interestingly, many companies don't clearly state their priorities and may not even be aware themselves of what they implicitly are.

    I believe that there are deterministic ways of uncovering priorities and categorizing companies according to them. I believe that knowledge of priorities leads to a more precise understanding of strategy and competition. I hope that within this forum, I can share and provoke debate over these methods so that these skills can become more commonplace.

  7. Flummoxed, again

    Research · 184 comments

    The last time I took a snapshot of the iPad death watch it was March 9th, 2010. Almost a year ago. The now-classic quotes are reproduced here.  Last May I wrote:

    Apple keeps a tight lid on new products so that competitors don’t get a head-start on copying, but in the case of the iPad, advance knowledge would not have had any impact. Competitors look at the iPad and see nothing.  They’ll only react once the market explodes and they start to feel belated pain.

    I thought that would be that. As the success of the product would become self-evident, predictions of imminent demise would trail off. The pain of share loss would prompt a wave of challenger copycats. Imitation would be the the best form of flattery.

    But no.

    Critics were not silenced. One year, 15 million units, and $9.2 billion later I went back to the source of the quotes and found the following (published quotes dated after March 9th 2010). (Cited from aaplinvestors.net with some editing for brevity and relevance):

    “Problematically, the Android competition is just as expensive as the iPad lineup, so Apple obviously feels free to continue gouging consumers on iPad pricing.” Paul Thurrott, Windows IT Pro, 3 March 2011

    “Apple’s iPad 2 might be ‘magical’ but it still should’ve been better ... It needs more G’s. It’s still just a toy” Zach Epstein, Boy Genius 2 March 2011

    “11 reasons NOT to buy an iPad 2 ... Reason 5: Competition David Gewirtz, ZDNet, 23 February 2011

    “Given what I’ve seen of Honeycomb and Motorola’s excellent tablet, Cupertino will have some serious catching up to do with their iPad 2.” J.P. Mangalindan, Fortune, 4 February 2011

    “We very carefully chose our tablet processor, the Nvidia Tegra 2, and to really compete it will take [Apple] some time. You know, [Nvidia] is well known for graphics.” Jonney Shih, Asustek Computer, 3 February 2011

    “If you were to ask me in two years time, will Apple have less than 50 percent of the global tablet market, I think that’s a certainty. Neil Mawston, Strategy Analytics, 31 January 2011

    “We have an extreme focus on the innovation of LePad and LePhone because these products will dominate the future market. Though Apple is winning a significant share in the Chinese market, it has not gained a clearly leading position yet. Our advantage is we know this market better.” Liu Chuanzhi, Lenovo, 27 January 2011

    “The iPad may still be the lone leader, but with 100+ competitors on the way, it won’t likely keep its majority market share unless the pending next generation iPad really addresses all the complaints about the current version, like a missing camera and a lack of a USB port, and the company has to add those features without a major price increase - a tall order, to be sure.” James Brumley, Investopedia, 13 January 2011

    “Hands-on PlayBook demonstrations at CES showed its differentiation in multitasking and performance, which may be difficult for Apple/Android to rival.” Mike Abramsky, Royal Bank of Canada Analyst, 11 January 2011

    “Apple Inc.’s popular iPad is getting its strongest competition thus far as consumer-electronics manufacturers unveil tablet computers with bigger screens, front-facing cameras for video chatting and more.” Rachel Metz, AP Technology Writer, 3 January 2011

    Apple may be simply trying to get in ahead of Research in Motion’s aggressively priced PlayBook or combat the early success of Samsung’s Galaxy Tab.” Rick Aristotle Munarriz, The Street, 29 December 2010

    4. Competitors are coming. Brett Arends, Wall Street Journal, 22 December 2010

    Reason 6: WiFi is still unreliable David Gewirtz, ZDNet, 16 December 2010

    “I can’t imagine anyone under the age of 30 wanting an iPad. A PS3, Wii, GameBoy, or even a useful laptop maybe, but an iPad? Furthermore, I do not recall ever seeing anyone under 30 actually using an iPad.” John C. Dvorak, PC Mag, 13 December 2010

    “We hope our tablet PCs can reach a global market share of 10-20% initially, and become the market leader in two to three years.” Gianfranco Lanci, CEO and President, Acer, 26 November 2010

    “It’s a nice-to-have product, for those of us who don’t have a budget, but is it a must-have product? I don’t think so.” Ashok Kumar, Analyst, Rodman & Renshaw LLC, 12 November 2010

    “Steve Jobs never says anything without thinking through it carefully. But I think in this case he may be a little afraid of this category. And he’s finding whatever he can to attack because he sees [seven-inch tablets] as a challenge to the dominance of the iPad.” Adam Hanin, VP Marketing, Viewsonic, 1 November 2010

    “There could literally be millions of first-generation iPads gathering dust in people’s home offices already. This product is the tech industry’s biggest MacGuffin yet.” Paul Thurrott, Windows IT Pro, 23 October 2010

    “I cannot see a need for the thing.”John Dvorak, MarketWatch, 22 October 2010

    ”For those of us who live outside of Apple’s distortion field, we know that 7″ tablets will actually be a big portion of the market and we know that Adobe Flash support actually matters to customers who want a real web experience.” Jim Balsillie, Research In Motion, 20 October 2010

    “iPhone and iPad have been amazing products that have opened new markets. But I do not think they will own either market in a few years. Android will.” Fred Wilson, AVC.com, 18 October 2010

    “The constant search for an ‘iPad killer’ and the sheer multitude of tablet computers launching in the next 18 months should make Apple aware that its competition is fierce and will only become tougher.” Barbara E. Hernandez, PCWorld, 5 October 2010

    “HP’s New Tablet Could Be an iPad Spoiler HP’s decision to bundle a tablet computer with its new $399 printer could make trouble for competitors.” Cliff Edwards and Aaron Ricadela, Bloomberg Businessweek, 23 September 2010

    “Our tablet will be better than the iPad.” Chang Ma, VP Marketing, LG, 20 August 2010

    “Not only is Apple typically lost in the enterprise, but it focuses very little of its time there. And with a new, potentially more compelling tablet coming — the Cisco Cius — the iPad’s success in the corporate world could be short-lived. Here’s why:... 10 The power of Windows” Don Reisinger, Channel Insider, 5 August 2010

    “I don’t think there is one size that fits all…I’ve been to too many meetings with journalists who spent the first 10 minutes of the meeting setting up iPad to look like a laptop.” Steve Ballmer, Microsoft, 29 July 2010

    “ [...] It still isn’t the device that I’d take to a meeting because it has no input.” Bill Gates, Microsoft, 2 June 2010

    “Which means I end up on the iPad — and tablets more generally — where I started. Tablets will not create a new category, but will supplant (or merge with) one or more of the current substitutes: smartphones or netbooks.Here I am less optimistic about the iPhone and webOS than I am about Android. ” Joel West, professor of Innovation & Entrepreneurship, College of Business at San José State University, 30 May 2010

    “The iPad is useless. Beautiful, but useless. The iPad is too heavy. It’s awkward to hold and view in public. It’s fragile. It requires expensive accessories to protect it and extract more functionality. ”Josh Belzman, MSNBC.com, 20 May 2010

    “Mum, the iPad is not ‘amazing.’ It’s just marketed very well, both by Apple and its culpable partners in mainstream media. ” Paul Thurrott (in response to comment by Mum), Paul Thurrott’s Super Site for Windows, 26 April 2010

    “In short, I don’t get the ‘magical and revolutionary’ vibe that Apple chief executive Steve Jobs touted at the iPad’s January unveiling.” Rob Pegoraro, Washington Post, 9 April 2010

    “The first troubling sign is the fact that you can still get an iPad today. They didn’t sell out. The pure slate form factor has failed all these years because, other than for vertical applications, people want and/or need a keyboard for regular use. The fact of the matter is that a touch screen or bluetooth keyboard just doesn’t compensate.” Jonathan Yarmis, Ovum, part of Datamonitor Group, 6 April 2010

    “I don’t get it. It costs $500 for the basic model, when you could get a laptop with a lot more functionality for about the same price. The iPad hype machine has been in full effect this week, and I still think it’s just that—hype. ” Alex Cook, Frontier Outlook, 3 April 2010

    “As far as what this means to Apple, one thing to keep in mind: Even if the iPad sells more than the iPhone did in its first year, it’s still only around 5% of the company’s revenue. So it’s a very small slice. From there, it probably doesn’t grow as large as the smartphone market. So, if you’re buying under rumors, keep perspective in mind. The iPad’s a great product, but it’s probably not a game-changer.” Eric Bleeker, Analyst, Fool.com, 31 March 2010

    “The iPad will remain an expensive, niche device compared to all-purpose netbooks.I think that one of the iPad’s most important uses will be for reading ebooks and publications. Even so, though, when it comes to the marketplace, netbooks will sales still far outstrip those of the iPad.” Preston Gralla, PC World, 30 March 2010

    “Don’t Believe the iPad Hype. Apple has sold out pre-orders of the forthcoming device, but it could all be a marketing tactic. By not manufacturing enough iPads for the initial launch date, is this a case of Apple shooting itself in the foot?” Mike Schuster, Minyanville.com, 29 March 2010

    “‘iPad Killer’ May be Palm’s Last Hope”Tom Bradley, PC World, 20 March 2010

    “Even if your company has relented and now supports the iPhone, as growing numbers of businesses do (70% of the Fortune 100 are at least testing it, says Apple) you’ll want to say “No” to the iPad and other tablets. Here’s why: 8. Speaking of money, there is no money in the company budget to pay for iPads. 9. Not supporting iPad will be the enterprise norm. Robert McGarvey, CIO Update, 16 March 2010

    “This morning, the fool’s parade gets started. Apple is taking online “pre-orders” for its iPad tablet, which is supposed to begin shipping on April 3. Buying a new kind of product sight unseen is foolish. Especially given how mysterious Apple has been on what the iPad can do and what restrictions on capabilities and media access it will place on users and content providers.” Galen Gruman, InfoWorld, 12 March 2010

    “The recent launch of Apple, the iPad tablet, has won the award for the second edition of Fiasco Awards delivered this Thursday in Barcelona. From the more than 7,000 people who voted via the website www.fiascoawards.com, 4,325 have considered it the fiasco of the year. Fiasco Awards, 2010, 11 March 2010

    “I think I’ve mentioned this once or twice before, but it bears repeating until it sinks in: the Apple iPad is not unique, nor necessarily the best of breed in the media tablet sector it is spearheading. And it ain’t gonna help Apple shareholders any.’” Anders Bylund (TMF Zahrim), 11 March 2010

    From this critical review, it looks like 2011 will indeed be the year of the iPad 2.

  8. Android vs. Windows Phone: Which vendors benefit?

    Research · 32 comments

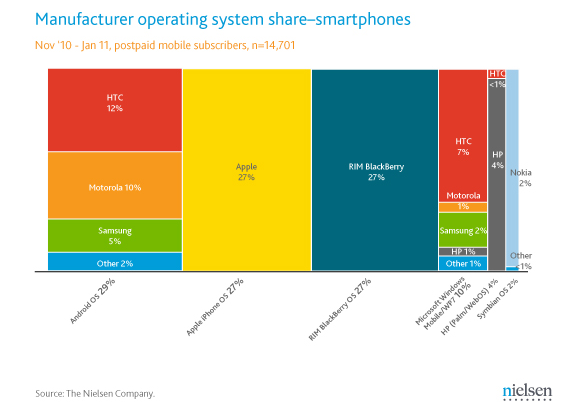
    Who is Winning the U.S. Smartphone Battle? | Nielsen Wire.

    This is a great chart from Nielsen showing the split in manufacturer share by OS in US installed base. What I consider significant is how the modular software platforms Windows Mobile and Android worked out for the licensees.

    Whereas in the case of Windows Mobile HTC took a significant, nearly dominant share, the Android ecosystem was more balanced between HTC and Motorola. However, HP and Motorola left the Microsoft camps, Motorola going exclusively for Android and HP buying Palm. That leaves Microsoft with HTC, Samsung and Other (mainly LG I presume).

    The question of how Windows Phone will shape up vs. Windows Mobile and Android remains. Motorola has signaled they are not interested in WP7 for the time being and so it's likely that they will stick with Android. Samsung is always hedging its bets so it will probably balance its portfolio. One could conceive of Nokia stepping into the US with significant WP volumes, but there are many hurdles on the way.

    One can see the challenge individual modular vendors have to edge the overall volumes of the integrated vendors. As Nielsen points out:

    But an analysis by manufacturer shows RIM and Apple to be the winners compared to other device makers since they are the only ones creating and selling smartphones with their respective operating systems

    Not only are the volumes higher, but so are the margins and hence profit share.

  9. Nokia's Burning Ships strategy

    Research · 84 comments

    In the recent series of exposés on Nokia's new strategy I sought to paint a background for what caused such a dramatic decision:

    This gives a backdrop to the decision, but it does not explain the most crucial part of the decision: why did Stephen Elop decide to maintain an exclusive platform for Nokia rather than a multi-platform approach as chosen by successful competitors such as HTC, Samsung and Sony Ericsson.

    Going from backing one "burning" platform exclusively to backing another "ice cold" alternative without bothering with a hedging alternative is very risky. This may be the biggest puzzle and mystery for outside observers.

    Here I put forward a few reasons why exclusivity attracted Nokia:

    1. The lessons of product focus (see why focusing on a few products is hard).
    2. The costs associated with Symbian and Meego were unreasonably high. (see Nokia employs as many people to develop its smartphone software as Apple does to develop all its products).
    3. The psychology of change management.

    This last one may be the most crucial of all.

    What has to be appreciated is how bloated Nokia has become. It has 140 thousand employees. It's been organized and re-organized countless times and is completely intractable even to insiders. Cutting headcount can only accomplish so much. It deals with costs, but not with motivation. What management needs to do is also incentivize the survivors.

    This is where exclusivity comes in as a motivational tool.

    To explain we need to dip into a new metaphor. Conquistador Hernan Cortés landed in Mexico with the intention to conquer it. Legend has it that as soon as he landed, he burned his ships to prevent his men from retreating and motivating them that conquest their only option.[1]

    Leaders motivating their followers by removing the means to surrender or retreat is not uncommon. It's harsh and brutal. It's not a natural thing do do: destroying perfectly useful options is value destructive and generates outrage, even mutiny.

    In Nokia's case, institutional inertia with a vestigial Symbian effort would compel the organization to maintain the current platform while treating the new alternative as a pathogen.

    Counter-distruption theory states that the response to a disruption requires a focused approach through an autonomous challenger protected from corporate antibodies by the CEO herself. In this case, the autonomous organization is outside the company (Microsoft). Protecting the new effort was not possible with a Chinese wall. The only alternative was to simply get rid of the old and start with a clean slate.

    While there are times it makes sense to burn ships to eliminate any ideas of retreat, there are other times when doing so is reckless. You can do the calculation on the basis of cost of being wrong and levels of uncertainty [2], but even when armed with all the data linked above, this decision can hardly become something that can be quantified.

    It's a gut-level decision.

    I would say that Nokia's new CEO did not just jump off a "burning platform" but that once he jumped he made sure it kept burning so that nobody thought of going back on board.

    ---

    Notes:

    1. There is a Microsoft precedent to this story. See Amazon.com: Burning the Ships: Transforming Your Company's Culture Through Intellectual Property Strategy (9780470432150): Marshall Phelps, David Kline: Books Burning the Ships recounts the decision that forced Microsoft to face its own 'succeed or die' moment. It's a lesson in strategy and survival that speaks about the courage required to embrace radical business transformation.
    2. See also: Burning Ships
  10. Where is the Windows Phone Tablet?

    Research · 78 comments

    The Windows Phone platform currently has hardware specifications that imply a cellular phone device. What is interesting in light of the new WebOS TouchPad, the newly announced Android tablets, the RIM Playbook and the iPad is that this supposed "third horse" of Windows Phone has no hint of present or future presence in the tablet form factor.

    That might have something to do with the plans to move Windows to the tablet form factor. Perhaps Microsoft thinks that pocket size devices deserve a separate operating system, platform and ecosystem than portable mobile computers. Perhaps Microsoft plans to have two separate interfaces for these tablets (slates vs. tablets?) Then again, Ballmer held up a Windows Phone and said "This is Windows too."

    It gets confusing.

    The bottom line is that without a tablet implementation, Windows Phone developers and content providers will find that the WP ecosystem will have a limited addressable market and will not be suitable for all forms of media or apps. Tablets are currently expected to grow even more rapidly than smartphones did and so there will be significant numerical advantages to those platforms that support multiple screen sizes and form factors.

    Now that Nokia has anointed the Windows Phone platform as its exclusive conveyance to the device market, the question in the headline becomes: Where is the Nokia tablet?

  11. The price of Windows Phone: Nokia's evaporating smartphone share

    Research · 61 comments

    In the last quarter Nokia sold 28.3 million Symbian phones. The average selling price was €156 or approximately $210. That price was down 17% year-on-year.

    According to the company,

    The 17% year-on-year decline in our converged mobile devices ASPs was mainly driven by general price erosion and an increase in the proportion of lower-priced converged mobile devices sales.

    ASP erosion has been a fact of life across all of Nokia's products for quite some time, checked only by the increasing mix of smartphones. However the smartphones it sells have been consistently positioned for lower price points. This is consistent with Nokia's long-term goal of serving "billions" of users.

    The trouble with the new strategy is that the Windows Phone product lines currently in the market are not likely to be priced in the $200 range. The reason is that the minimum specifications for Windows Phone 7 are:

    • Capacitive, 4-point multi-touch screen with WVGA (480x800) resolution
    • 1 GHz ARM v7 "Cortex/Scorpion" or better processor
    • DirectX9 rendering-capable GPU
    • 256 MB of RAM with at least 8 GB of Flash memory
    • Accelerometer with compass, ambient light sensor, proximity sensor and Assisted GPS
    • 5-megapixel camera with an LED flash

    These don't add up to a product that can be sold profitably at $200. The bill of materials is likely to be in that range (and one has to add $15 for Microsoft).

    So there are two possible implications for Nokia's new smartphone strategy.

    1. Windows Phone will be ported to lower spec/cost hardware to allow the traditional Nokian market growth model to continue and perhaps combat Android proliferation
    2. Nokia's smartphone portfolio will consist of high-priced products, and exclude mid-to-low price products.

    Option 1 is difficult to imagine. The user experience that Microsoft is putting forward as its differentiation depends on significant hardware which is unlikely to become very cheap very soon. It is an interesting exercise to think through however. What would we have to believe for this option to become real?

    Option 2 is more likely as Nokia conforms to this a new definition of smartphone as "high-end" only. This seems to be the default option given what is visible to observers today.

    If Option 2 is in fact the outcome of the new strategy, then it leaves Nokia very vulnerable to a low-end disruption (after it's succumbed to a new market disruption.) The $50 smartphone will be reality this year.

    Option 2 also most certainly guarantees that Nokia's current market share of 30% in smartphones is likely to be lost and never regained.

    Some might argue that's no great loss. After all, Apple does very well with low share and high prices. However, Nokia is almost religious about market share. The reason being that scale offers significant purchasing power and logistical leverage. It sustains a cost structure, distribution network and a business model that is central to the company's core competency. It's also presumably the reason Microsoft partnered with Nokia in the first place: volumes and wide distribution.

    So we're back to the old question: how does the new deal lead to a thriving ecosystem? Does it depend on vendors other than Nokia? If so how does Nokia benefit from the sale of Samsung phones?