Asymco

Asymmetric Intelligence

platform

  1. An interview with Chris Brennan for MacUser magazine UK

    Research · 30 comments

    Chris Brennan asked a few important questions regarding potential saturation of the iPhone market.

    Is the iPhone anywhere near saturation? Can Apple continue to shift iPhones in ever increasing numbers or is a sales plateau realistically on the horizon?

    The market for mobile phones is approximately 5.5 billion connections, perhaps 5 billion users. The iPhone has approximately 300 million installed base. I consider a base of 1 billion users to be a minimum for continuing participation in this market long term. Licensed platforms will reach this in no more than two years. I don't know what Apple's ambitions are but if they don't triple their base I don't see a strong future for the company in mobile phones. In order to triple the base the company will need to sell substantially more than an additional 700 million iPhones. The retirement rate can be as high as 50% of installed base. Apple will need to sell at least 1 billion iPhones in the next few years. Seen another way, Apple has a market share of about 9% on a quarterly basis. This needs a lot of improvement. Chinese vendors are not standing still.

    Can the Mac also continue to outperform the rest of the PC market for long?

    The PC market is in decline. It will continue to decline as its disruption continues. The PC market will still exist 10 years from now but, similar to the mainframe market, it will be hard to notice. Apple is doing a fine job carving out a large portion of that market for itself but overall it's an increasing portion of a decreasing pie. It would be better to track the share of profits captured or even share of value rather than units. The reason units were important 20 years ago was because platform dynamics determined whether a marginal platform could survive. Would a 5% share be enough to attract developers? That is no longer an interesting discussion. Applications for PCs are not an area of investment for any significant pool of capital. Development has moved almost entirely into mobile or web. Therefore, as the PC is now a commodity product, the best performers are those who can capture a larger margin. Those margins should be subsequently be invested in new platforms. PC vendors who neither capture margin, nor invest in new platforms are strategically insolvent.

    Finally, this exponential growth of Apple products has to end some time soon doesn't it? How many high-income buyers for expensive products can there be left for Apple to target?

    Trying to calculate the limits to growth is futile. There are limits but they are not calculable and inaccurate estimates don't offer any useful information.

    In 1939 a total of 921 military aircraft were built in the United States. Five years later, in 1944, annual production was 96,318. A question could have been asked by an aviation analyst in 1939 about whether the American aircraft industry could grow. Aircraft, especially multi-engined ones used by the military were _extremely_ expensive. The reason an industry grew exponentially making extraordinarily expensive products was not because of organic demand but because the primary buyers engaged in a cataclysmic global war. In other words, there was a will to buy and hence there came a way to build. Therefore the answer to the question of sustainable growth comes not from an analysis of demand but from an analysis of the consequences of not growing. Not growing would have meant the end of many nation states.

    Your question was framed by an implied market categorization: that buyers are either high-income or, presumably, low-income. This is a false dichotomy. Buyers are either needful of a job to be done or not. If the job is important enough, money will be found to hire a product. Sellers of products will also find ways to meet the demand through lower prices and increased capacity. Every product Apple makes used to be out of the reach of all consumers. Whether computers (portable or not), music players and professional grade software, voice recognizing personal assistant cellular phones and tablets are all luxuries or necessities is only a question of timing.

  2. An interview with Kenney Ho of The Chosun Daily of Korea

    Research · 21 comments

    Kenney Ho, a staff reporter from Korean newspaper The Chosunilbo (The Chosun Daily) sent me a set of delightful questions.

    According to Kenney, The Chosunilbo "has a history of 90 years, has been the most dominant, and influential paper of all time in Korea. It is the No.1 newspaper company in Korea with more than 1.8 million circulation, firmly holding the largest market possession. The paper is recognized Asianwide, where there are many readers in Japan and China."

    -You said "All mobile device vendors experiencing losses are not likely to really recover". Even though, it wouldn't mean that the employees, executives of Nokia has completely nothing in hands for recovery. If you are the CEO of Nokia right now, What are your steps to make Nokia recover its deficits?

    My statement was based on the historic data which shows that 14 phone vendors have either exited the business or lost their independence during the last decade. No vendor that has reached a period of prolonged loss making has recovered. These are just observations and it's possible that Nokia may be the first to recover. However, going by the patterns of the past, it would be very unlikely. When I thought about the reasons why companies have not been able to recover I came to the second observation about the way phones are sold. Once a brand reaches a point where it's considered "risky" for distributors and operators to range they tend to defer purchases which leads to a spiral of continuing losses and more damage to the brand. The market amplifies "distress" and recovery becomes impossible.

    If I were the CEO of Nokia I would set course for turning the company into a new business. I would approach the market asymmetrically and not try to compete directly with the other vendors. I would look toward services, platforms and software solutions and de-emphasize hardware.

    -Many experts say that because Nokia dominated phone making industry in the 2000s, they maintained a corporate culture of complacency, which led them to decline. Do you agree with this? If you agree, Can you point out the examples of Nokia's complacency?

    Complacency would mean that Nokia would not invest or try new things. This is not quite right. The company invested in software, services and platforms. It tried many new things and had a large R&D budget. It was the leader in mobile software for many years. There was, however, a culture of arrogance about their position. This meant that they did not think the basis of competition would change. They thought they were too big to fail. They did not challenge the core business model of hardware-first and try to find an internal disruptive business.

    -Experts note that Nokia should have reacted directly to Apple's iPhone appearance at 2007. What should have Nokia have done at that time?

    The iPhone showed that software and experiences matter more than operator relationships. Nokia did a lot of research on user experiences and software but when the decision came to implement the ideas, the constraints of hardware and logistics and operator preferences took precedence and the software was compromised. What Nokia needed to do is build product around software not software around the hardware and the market.

    -Since Apple's iPhone appeared in 2007, Samsung took a Fast-follower tactics which made them successful, which Nokia could not. Do you think Fast-follower have advantage over first-mover?

    I don't consider first-mover or fast-follower to be accurate descriptions of strategy. Success follows from innovation and only from innovation. There are various forms of innovation: there is new market creation, new business models, low cost or distribution innovation. Nokia tended to create low cost innovations which opened new, low-end markets. Apple created a new market for browser-based devices and for app-based experiences. These were enabled by an ecosystem that benefited from integration.

    Samsung implemented a portfolio strategy with a large number of devices and price points which allowed them to find market niches that could be exploited. This was a distribution innovation. Each strategy has advantages and disadvantages and each strategy is usually linked to company core priorities and processes. There are times during a technology cycle when one strategy is better and another is worse. This is why companies find themselves successful and then fail. Their processes don't match the technology adoption cycle.

    For example, in the PC market there is little potential for new experiences tied to an integrated device (except for tablets) and hence there is little growth opportunity for an Apple-like approach. The innovation that matters in the PC market is mostly cost reduction. Nokia was doing cost reduction at a time when voice products were commoditizing. Cost reduction does not work when the basis of competition is new experiences and new business models. As smartphone hardware commoditizes, it's unlikely that Samsung will have an advantage unless is goes to a low-cost approach and enters into direct competition with low-end devices.

    -Can you predict the 'Big 5' in handset industry 10years from now? Many people think the list will include Apple, Samsung. Who else might be on the lists?

    There is no guarantee that Apple or Samsung will be the top vendors 10 years from now. I expect Chinese brands to become dominant in market volumes. I expect online service companies like Amazon, Baidu, Facebook to create new platforms which and have their own devices, perhaps in large volumes. I expect new input methods (like voice) to create new opportunities and perhaps new platforms and ecosystems. I expect Google may make a lot of money. One thing is for sure, being a hardware-oriented company without software and services and platforms and ecosystems is a sure path to becoming disrupted.

    -Nokia was the leading company in Finland. What are the reactions of Finland towards Nokia's downfall?

    People tend to blame each other for failures and this is the main discussion topic in Finland: who's to blame. The failure of a company is rooted in complex decision processes which usually take years to run their course. It's quite futile to lay blame on persons, especially since the same persons were celebrated for their wisdom at another point of time. At the same time as Nokia is failing however, another Finnish startup is celebrated world-wide and about to go public: Rovio, the maker of Angry Birds. It will be bigger than Nokia. Finland should make sure there are more Rovios to come.

  3. Android economics: An introduction

    Research · 53 comments

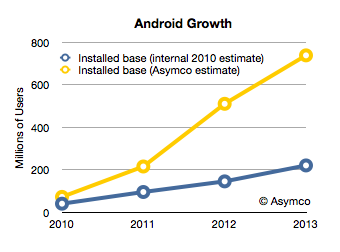
    Android has had unprecedented growth. Based on activation announcements, it's possible to estimate that thus far, about 370 million Android devices have been activated. The total number of devices in use is a lower figure which depends on replacement rate and retirement rate. This total number of devices in use at year end is estimated in the following chart.

    I added the blue line which represents what Google had as an internal estimate in mid-2010.[1] The difference between the two lines shows that Android's growth is far higher than what the company expected.  If the company itself did not expect this growth, it's unlikely anybody else did either.

    Unexpected, exponential user growth is usually accompanied by a dramatic positive improvement in the finances of a company and a higher return to shareholders. The curious aspect of Android's success is that it has not had an impact on either. The market has not "discounted" the half-billion anticipated Android users into a price for Google shares that reflects this growth. It can only imply that those users are not very valuable.

    But why would there be such a disconnect between the number of users and their value?

    In order to answer this question we have to come to grips with what I call "Android economics". We need to understand how Google uses Android to make money and whether it is succeeding and if it's not, why not.

    In many ways, the Android business model is straight forward. It's an extension of the existing Google business model: Revenue is obtained from Search, AdSense and the applications that enable these two.  In the case of Android there is also revenue from app sales (Google Play a.k.a. Android Market) and from AdMob. Of course, all these revenue sources (except for Play) are sold through other mobile channels that include alternative, competing platforms. They are present on iOS, Symbian, BlackBerry and even embedded OS phones ranged directly by carriers. For each of these alternatives, Google pays for placement of their search as the default search in the browser.

    To Google, total search revenue from iOS is far higher than it is from Android. That's because iOS users engage more with their devices and there are not yet a large multiple of installed Android users vs. iOS users.

    But it would make sense that having your own platform would be more economical because there would be none of these placement fees. In this sense Android is another "channel" for distribution of Search and AdSense. But one which may be a lot cheaper.

    However, it turns out that it does not work that way. Android has other costs.

    In fact, Android's distribution costs might be higher than other channels. What we have to understand is that all of Google's channel revenues have a "cost". The revenue from a particular distributor of search results that Google generates is offset by the cost to acquire the terms. You can think of it as Google paying for the queries through a revenue sharing agreement. Google does not get search terms directly and depends on distribution. Overall, it pays about 50% of revenues back to distributors. In the case of its own web sites the rate might be lower, perhaps 40%.

    Google even has a term for it: Traffic Acquisition Costs or TAC.

    This revenue sharing in exchange for search terms extends to Android. Google pays about 40% TAC to Android distributors of those searches. But since Android is owned by Google, who does Google need to pay for traffic? Who is an Android distributor? Who gets the revenue share?

    Google does not make a secret of it: network carriers and device vendors (OEMs) receive revenue share. From the latest earnings conference call:

    Yes. I mean, again, I'm not going to talk about specific of the TAC on mobile. But as you know, we get people using our devices both organically as well as through our distribution partnerships with carriers and OEMs. And typically, the OEMs and carriers participate in some of the economics that are on the Android marketplace or Google Play and some of them participate in the economics around Google Search just the way we would do syndication on the Web platform, which you do with many partners around the world. We have similar deals on the mobile front.

    - Nikesh Arora, senior vice president and chief business officer at Google Google Management Discusses Q1 2012 Results - Earnings Call Transcript - Seeking Alpha

    Arora made another point in the quote above. Not only is there revenue sharing with carriers and OEMs for Search and AdSearch but also for Google Play (app and content sales.)

    Device vendors and carriers get a cut. Google's model has always been one of giving a cut of revenue to their upstream distribution. It just might be surprising to hear that device vendors like Samsung and carriers get a piece of Search and apps.

    This basic observation leads to a series of questions:

    • How much is paid out and to whom?
    • Is that revenue sharing sustaining the ecosystem? Do vendors create Android devices and do carriers push Android to consumers because they get this revenue share or is the amount insignificant vs. device margin? What about tablets? Why haven't Android tablets they taken off as Android phones have? Are the economics to blame?
    • Is this a competitive advantage vs. other platforms? Does Windows Phone compete with revenue share for Bing? Is Microsoft offering a bigger carrot (as well as a stick?)
    • How does this economic picture show up in Google's financial and stock price performance? Or, more precisely, why doesn't it?
    • And, finally, what conditions create a virtuous cycle of growth and what conditions could turn it into a vicious cycle of decline? Is there a lurking factor which would cause Google to benefit greatly from this user base or is there an inherent point of failure in the model?

    I'll be answering these questions in a series of posts this week.

    --

    Notes:

    1. Google's internal documents were leaked as part of the Oracle trial (Exhibit 1061). They can be found by using Google search with the following search term: "OC quarterly review".
  4. Jim Zellmer interviews me about my life

    Research · 45 comments

    This is a transcript of a voice interview conducted April 19th 2012.

    The interview is available as an audio file here.

    --

    Jim Zellmer: I thought we'd start by describing your education from the beginning, Horace.

    Horace Dediu: OK, that's good, yeah. I like to say I'm the product of the public school systems. I went to public schools in three different countries, and probably maybe a dozen different schools altogether because we moved a lot, moved over 30 times.

    My family emigrated, and we were what you might call political refugees for a while. We were stateless. We didn't have passports. We were officially not citizens of any country. So, for a period of about four or five years, that was the case. I started having regular schooling in Romania, and then moved to Italy and was enrolled in a school, actually, in the city of Verona, which is where "Romeo and Juliet" was originally set.

    I was saying...my background. I spent a year in school in Italy, and I went to school in the north of Italy, in Torino. The thing was that I didn't know Italian, so I actually had to learn. But that's a lot easier for children. I was about nine, I think. And so, I learned Italian, was able to have a good school year. But then we moved.

    In the summer, we moved again, and we emigrated to the United States. It took about a year to get the paperwork for that--because that was our ultimate goal was to be in the US. I was enrolled in the public schools. First, in Cleveland, where we found someone to help us. I actually went to, I guess, elementary school in the city of Cleveland, where we lived.

    And then, later on, for middle school... What happened in Cleveland around that time was that busing started, desegregation. It would have meant, for me, more than one-hour journey across the whole city, from the west end to the east end of Cleveland, and my parents would have none of that. So, we moved to a suburb, immediately adjacent, which is called Lakewood. I went to middle school and high school in Lakewood, Ohio, for three years in high school.

    And then, we actually moved yet again, to Boston. My father got a job in the booming tech sector at the time, which was in the early '80s. I ended up in a suburb of Boston called Medford. We didn't know much. Again, we were flying pretty blind here. We weren't familiar with neighborhoods or what were good schools or anything like that--"good schools." Mostly it was a question of, "Can we find affordable housing?"

    Medford turned out to be a pretty lucky choice. In one hand, at the time, it was a blue-collar town. It was one of the near suburbs. So the closer to the city, it tends to be the older the immigrant generations are. It was settled mostly by Italian Americans. And so, a lot of the children I met in school were of some ethnic background.

    Again, in the Midwest, that was a bit more rare. So East Coast, for me, was a little bit more vibrant in the sense that there were more interesting ethnic backgrounds and people from different histories and so on.

    I enjoyed it, but I only had one year at Medford High School. It was actually more enjoyable, that year, I would say, than my years in Ohio. I have friends that I retained from that one year, and I don't have friends I stay in touch with from Ohio.

    But it has changed. The city since has become much more, I would say, a lot of those families moved yet again, probably to a further suburb, and has changed character. I think it's more Hispanic now, the city overall. Nothing wrong with that, it just probably would feel different to anyone there now.

    I was, again, in Medford. My choice, my next question, was where to go to college. I had been doing OK in school. And that was an interesting puzzle to solve as a kid, because you don't quite know how to fit in, the usual problems. Fortunately, having moved around so much, I had a pretty thick skin, and having had an accent or a strange background just made you a little bit tougher. And so, I was pretty immune to some of the high-school politics.

    I focused on studies, and my parents are both educators. My father has a PhD in mathematics, and my mother had a Master's in mathematics and she taught. Actually, her job was as a teacher. They both got certified as teachers in the United States. My father had taught, also, university in Romania, but he ended up teaching high school and other two-year colleges in the US. It's very hard to go into academia from another country.

    In any case, the fact that I had such devoted, academically inclined parents helped in focusing me on academics. That also, I think, was my nature. As far as college, my concern, we always had financial concerns, right?

    Jim Zellmer: Right.

    Horace: So, for me, I wasn't interested in the social aspect of college. For us, really, the decision was, "Can we keep expenses down?" I was accepted at Tufts University and also at Brandeis, which were local. That was important to me, that it would be near to my home and I could actually commute to these places.

    Tufts was slightly better. It was a little bit closer. It was actually in Medford. So, I almost went to the college that was nearest to me. It had a very good program, also, in both engineering and computer science.

    The odd thing is now, in college for me, was that - it's almost accidental - but, they had an option for you to take two degrees. The dual degree program was meant for people to study liberal arts and engineering. The idea would be you'd be a well-rounded individual.

    The weird thing is that when I went there, which is 1985 to 1989, the School of Liberal Arts included the mathematics department and included the computer science department, which is a spinoff of the math department. So, computer science was a Liberal Arts degree; whereas, engineering was like electrical, mechanical, and so on, the traditional subjects.

    I enrolled in the dual degree program with the intention of obtaining a computer science degree from the Liberal Arts School and a computer engineering degree from the School of Engineering. That meant that I would essentially take about 30 percent more courses. I think it was 50 credits versus the standard 30, or so. So, I was going for incrementally more material, but I would end up with two bachelor's degrees.

    That's what I did. I actually also did it in an accelerated fashion. I ended up doing that in three and a half years, rather than what they expected it to take, five years.

    Jim Zellmer: Wow.

    Horace: That involved a lot of summer school. I was actually going through taking some of the requirement courses in the summer. So, I was basically a student 365 days a year and I managed to get the two degrees.

    In the third year, there was one of these internship opportunities for research in a lab, GTE Laboratories.

    Jim Zellmer: I'm sure.

    Horace: GTE Labs was, again, local, which was important to me. They actually put us up in the dorms. So, the only time I spent living in a dorm was during the summer of my internship because it was paid for by the employer.

    That was a great time. I loved it. I absolutely adored it. Those years right at... In my third year, which actually was my, I guess, my second year as I was a junior a bit early, I was going through this internship and I was studying, I was going working in the research lab. Then I ended up doing my senior year, my last year, I kept going back there. Somehow they kept me around as a part time employee because the project I had been on turned out to be useful.

    It was in the library. I was actually working on indexing, which turned into search, which turned into Google later on, but we didn't know what it was then. We called it information retrieval. The algorithms, so we now do search intuitively when it actually became a commercial product, but it was something we did as research back then.

    It was great because I was getting the experience I wanted desperately, loved it, and then I was still in school and I managed to get my degree. I was even earning money while I was doing this. It worked out very well, but it was a very tough period.

    I graduated with not the highest scores, but I think I was magna cum laude, or something like that, which is not summa cum laude, but it's pretty good. It's like 3.8 GPA, or something like that. That's it. I don't know if that's what you wanted to hear. Then, of course, I did grad school.

    Two years, while I was still employed. I took a full time job at the labs, then essentially I did two years. In '92, I got my Master's in computer engineering. Then I spent about a year or two figuring out what to do next. I went to New York to have a bit of experience. Oh yeah, I remember. I applied to Harvard because I wanted to go to business school. The reason I wanted to go to business school was I didn't understand business.

    Jim Zellmer: [laughs] How did that play out? MBA's are often criticized.

    Horace: Yeah, I'll tell you how it played out. Well, first thing is this. I'm sitting with my friends. We're all engineers, hackers, if you will. We're like, "We don't understand. We don't understand how we get funded."

    Here we are sitting in these nice offices, but how does this company, who's basically a boring utility, how are they going to fund us to do cool stuff? We just compared notes and nobody knew. I realized none of us knew how business worked.

    I said, "Well, I better learn about this." To me, I had been so focused in engineering that all this business stuff, the only thing I knew was because I would read the "Wall Street Journal." I didn't have either friends, acquaintances, families. All my friends were nerds. All my family were educators. I knew nobody, literally not one person, who could tell me how the stock market worked.

    I would pick up the Wall Street Journal, read it cover to cover, and I wouldn't understand what the heck they were talking about. It sounded very abstract to me. It sounded like I need to learn something that there was something missing in my education.

    I felt that the only way to get that training was to go to business school. And so, I applied. I was rejected, and the assumption was, in my mind, that I was too technical, too focused in a very, very narrow niche. Back then, there were headhunters that were trying to headhunt people. So, one headhunter got a hold of me and they said they had an opportunity in New York. I said, "Oh, New York. I know they do business in New York. So I better learn more from going to New York."

    And so, I took a job with Chase Manhattan, at the time. It's called something else now, but it was Chase Manhattan. The job was also in IT, but at least it was IT, more pragmatic--corporate technology they call it. But I was there trying to understand more about business. I would still read the "Wall Street Journal" every day, still wouldn't understand it.

    I reapplied to business school. I told them what I did. I said, "Look, I took this job because I wanted to learn business." I think I somehow convinced them the second time because I was so mad to do these things.

    Jim Zellmer: Persistent.

    Horace: Persistent. Somehow, I got accepted. I'll never know how they made that mistake.

    Jim Zellmer: [laughs] Yes, of course.

    Horace: But, anyway, once I went there, I was like, "OK, teach me." Now, the problem was that you start to learn with the case method, and you realize pretty quickly that there is no real curriculum. This is actually a lot of examples you're being given. It's not even empirical. It's like, "Let's throw a lot of examples and see if something makes sense in a pattern somewhere."

    Jim Zellmer: This was Harvard?

    Horace: Yeah. So, Harvard Business School. It was the only school I applied to, because I felt I didn't know how to qualify quality in terms of business. It was just a brand name. If you know nothing about phones, you just buy the iPhone because you know it's the best, right? So that was me, very naive. And throughout the school, it wasn't as rigorous.

    In many ways, it was easy, because in engineering, engineering is very hard. You have to take test and you have to get answers right. And then in business school, it seemed like you just had to talk and you had to be articulate and you had to somehow be sufficiently smart-sounding to succeed.

    Jim Zellmer: The theater, aesthetics.

    Horace: Yeah. They drilled that into you. They said, "This is what we're teaching you is how to basically be a leader," and that leadership meant being proactive, not being passive. It meant getting in, if you will, on the discussion. I got that. I got it. It made sense to me because, yeah, in the meeting, if you sit there and say nothing, probably no one pays attention to you. You won't go anywhere in life.

    So that was one of lessons. The other ones were about vocabulary. What we're not learning here, however, is that there's axioms. There's no specific rules of business. In fact, if you were to put rules down, there'd be many which would contradict each other. One of the classics is that money now is better than money later. But you need spend money now in order to have money later.

    Jim Zellmer: [laughs]

    Horace: So these two things are contradictory. There were no rules in business that made any sense as if you were proving a theorem or something like that. I decided all right, let's just go with the flow. I met nice people. I learned more from a lot of people.

    The best thing that happened to me is that I had Clay Christensen as a professor. He was the nicest guy. The way he taught, it just resonated with me. He hadn't yet published "The Innovator's Dilemma." He was only teaching us operations, which is a first year course.

    It's the only technical course in the sense that you do some process diagrams and you do some analysis. Finance is another analytical course, but the math is pretty straightforward. It's not very conceptual, in a way. Accounting is not either. It's interpretation.

    But the professor, Christensen, he had a way of speaking to me that made sense as an engineer. It wasn't just me, there were a lot of people in the class who just felt that this guy was getting to the heart of a lot of the questions that we had. I took him as much as I could. I also had the option to take him in the second year. But, unfortunately, there was change in the dean and I think he had to change courses that he was teaching in the second year.

    In any case, we had a good two years there. My question was, what do I do after I graduate? This was 1996. The Internet, at the time, was just emerging. Netscape existed as of 1994 or 1995. There were no Internet business models per se. Certainly, there was a technology industry. But it was pretty much boring and either IBM or commodity PCs and you had a bunch of software companies like Microsoft and Adobe.

    It was already getting a little bit tired as an industry. As an MBA, it wasn't really that exciting. Everybody was doing either consulting or investment banking. Those were the typical ways of getting out of school. I had, of course, done something different. I did a startup. And nobody...

    In fact when I told people I wanted to do a startup everybody said "You came to the wrong school. No one goes to Harvard to learn how to do a startup. There are specific schools that  train you for entrepreneurship." Like for example, Simmons or something. I forgot the names now. Maybe that's a women's college. I don't remember the names.

    But the point is guys were saying "No, when you come out of here, you are either going to become a CEO of a Fortune 500 company or you're going to be a consultant for life or you're going to be in finance, managing other people's money or in private equity." I was like "Oh man. All right, well, whatever."

    Jim Zellmer: [laughs]

    Horace: I went and did this startup. I did a startup with no VC money. It was done with a partner in California who had raised money from the government using SBIR grants.

    We're talking the Department of Defense, and we were doing algorithms research. I went back to my university and recruited an engineer who I worked with in a basement office right off of Massachusetts Avenue. That was in '96. We built a system. We ended up licensing it to Adobe. It was a plugin to Acrobat. We didn't benefit much from it financially. Other people made a lot of money but not us.

    But we did learn a lot. So I'm thinking: In business school, I didn't really learn how business works, but I have this degree which gives me credibility. Now, I'm going to do my own business...

    Jim Zellmer: It's a ticket horse, yes.

    Horace: Yeah, but I did my own business. I threw away the ticket.  It didn't help me at all. What I was realizing, for example ... I didn't know how to do sales. I thought when you're doing your own business, you actually need to know how to do sales, and they don't teach you that at business school. I actually went and took a sales course, like they do in a daylong seminar.

    I'm saying there are so many pieces that are missing. I didn't know how VCs, how to handle VCs and how to do pitches and do all these things. And none of that was taught, so I thought, OK, what I'm going to do? I'm going to do on-the-job training. I'm going to figure this out. And [learn from] networking with people in technology.

    Eventually, I decided from the learning we had in the first startup to do another one, to do e-books! That was 1999. I'm trying to do an e-book startup in 1999. [So] I get on a standards body. I'm doing something with folks and I'm actually in a standards group that includes people from Microsoft, from Adobe, from a bunch of other startups, and from Nokia.

    Actually that's where I met someone from Nokia, who...

    At the time--it was 1999--I realized at that moment, with or without Nokia, I said, all computers are going to be handheld devices. This is so obvious. I can't express how obvious it is. I was interested, because Nokia had pretty much at the time the best mobile devices.

    Jim Zellmer: Yeah, they were the player, no doubt.

    Horace: I was asking myself, look, everybody in the U.S. doesn't get mobile. It's obvious that either it's Japan or Europe. And so, the question in my mind was, do I stay with the technology industry and try to figure out how this mobile computing will play out, or do I go to somebody who really knows mobile and expect that they will actually figure out how to become a computing company?

    I chose the latter, partly because they also offered me a job and the dot-com bubble burst, and I wasn't ever going to get funding for my e-book business, which was called Handheld Media by the way. It was a great idea, great business idea, that we would actually help publishers convert books. Because at the time, the publishing workflow didn't include exporting tools. You either went to print or PDF, and we had this tool that would reformat a PDF book into a publishable format, like what e-pub is now.

    Jim Zellmer: E-pub, right.

    Horace: At the time, it was called OEBF, Open E-Book Format. It was using HTML, a variant. I actually had a workflow I could execute on my own and I could basically produce e-books. I did a couple of dozen, mostly as trials. I remember them even now, actually going through and manually extracting hundreds of pages, fairly quickly though.

    But, anyway, that all came crashing down because although e-books were still interesting, there was no more funding in the docket. I had the opportunity to work with Nokia because they were actually very interested in launching something, not necessarily in e-books, but in media distribution. They wanted to sell music. They wanted to sell video. They wanted all those things in 2000. I came to them. Now, I'm playing my ticket, my bus ticket.

    [The job] was something about how to do business strategy. They hired me. I had this technical background as well. One year I spent based in Boston. But then I was fairly quickly moved to Finland because that's really where you need to be to have any career opportunities. I was young. I was not married. Finland has its charms.

    [I met] another American ex-pat who had moved there before I did and he extolled its virtues. I was pretty sold on that. Even though you pay more taxes, you get less wages, everything I did was economically the wrong thing to do.

    Jim Zellmer: [laughs] That's a learning, though, too. You've learned a lot. Looking back on all that, Horace, what might have been better or more effective? When you think about your kids today...?

    Horace: I don't know. I'm probably having too long of a chat on this, I mean fooling around this. But yeah, I'm very conscious of education, as I said. I realized pretty much after a year after leaving ... When I started Asymco, it's very weird. Again, you never know when you start down a journey where you're going to end up.

    It was purely going to be app development because apps were just starting out. Apps were really almost invisible or there was no development going on in Europe. So my idea was why don't I bring iPhone apps into the land of Nokia, because here it's a green field site.

    Jim Zellmer: Yes.

    Horace: But it was a tough sell. I got one customer, but it was very, very tough. I wanted to bring apps to small and medium companies. I was going to essentially do apps as marketing material, like apps that are essentially a branding thing.

    I was naïve also about the Finnish business culture because I think Finnish businesses are extremely conservative and that wasn't playing out. But the fortunate thing was that I began to blog because I had blogged while I was inside Nokia. I told that story about how I started doing it because I realized I wanted a bigger audience.

    Then when I left, people kept saying "Why don't you do that while you're on the outside, just for fun?" I took that year to figure things out. I  went back to writing my blog. Then, literally, everything was happening in 20 minutes. It was like a fire hose. I had to learn everything. I kept asking: OK, how do I do this?

    So, I am learning every single thing, because I had done it inside Nokia where it was movable type. It was a completely different system. I didn't have to set up anything. It was very simple. It was done for me.

    But on the outside, I am having to do it all myself. I started using actually iWeb, which at that time had a blogging tool. So, I opened an account on MobileMe. I was just putting everything through the desktop tools. They were right under my nose. Then I realized the limitations of that, and I moved to the next thing. I was like, "Oh! Seems like WordPress is something people use. Let's go to that." So, I went to WordPress.

    Then I realized, "Oh! Hang on! If they are hosting me, they are going to put ads in my stuff, and I don't know what they put there. So, I better host myself...how do you do that? " I need to find a hosting provider. How do you do that?"

    So, every technology, every bit of knowledge I had to have, I obtained strictly on my own. I say that every single character written in Asymco and every single mouse click that made it possible was performed by me.

    I had no technical support at all. It helps maybe to have a computer science background, but years had passed. So, I was able to... Here the key to the whole thing is that, every step, I am learning, and it keeps me motivated. I am like, "Oh! I understand how this works."

    I had some friends, who were more technical, and I would ask them, and they would say, "Oh! You are wasting your time. You can't get any traffic. This won't work." I would ask: "Tell me about Twitter", and they would say, "Oh! You're better off on Facebook." I was like, "Oh! Man!" Every single thing that I was given as advice turned out to be...

    Jim Zellmer: Wrong?

    Horace: Yes, doing the opposite would actually be the right thing. And so, I started learn about stats, the numbers game of blogging. So, how does that work? What does it mean to have good traffic?

    I didn't expect to get advertising revenue, but I was thinking: what does it mean to be successful? So, I would go to John Gruber's site. John puts up his own rates, and I am like, "Oh wow! Look at the numbers." He actually tells you how much he charges per week, and then he says he is fully booked. So, you know what his income is. And so, from that, I was like wow! That's my goal I said to myself.

    If I can get the traffic that Gruber gets, then I can charge these rates. I was trying to figure out how much traffic he was getting. He was getting like four million page views a month. I said, "I don't know if that's a lot or not." It certainly is a lot to get money, but you know, how do I get from zero to four million? So, what happened is that also when I was starting out, I reached out to John by email, directly by email.

    Some time before I mailed him and said, "I used to work at Nokia and there's a couple of things you're writing about that I wanted to amplify or I wanted to give you some background." He has great stuff, and he actually used my material in one or two blog posts. I wasn't blogging at that moment.

    But once I started blogging I mentioned to him, I said "Remember me? I sent you that info, and now I have my own blog." He didn't say anything. But then I wrote, I think the first piece that I wrote that was provocative. It was why someone at Microsoft had been fired or something like that. He linked to me. Then I saw. Then my eyes were open, because then my traffic... from zero to 12,000 a day.

    Jim Zellmer: Yeah.

    Horace: 12,000 views, for me, was like infinity. My server crashed and all that. I went back [to him] and I said "Thanks for the traffic. Now what do I do because I need money to be able to get this traffic managed." He said "No, you don't need money." You need to turn on caching." I was like "Oh."

    Jim Zellmer: [laughs]

    Horace: That solved the problem. But then I was asking him "So where do I go from here? Should I think about putting ads on my site? Is that the right thing," because I was so naïve. And he said "No, no, no."

    He gave me one piece of advice. This is the only piece of advice I ever got from and from anybody that was useful. He said "Don't put ads. Just do what you do. Your value is in the future. Just keep doing what you're doing." That's all he said, one line.

    I said "OK. If he says that, I believe it. That makes sense. Let's do it." I kept getting better at what I was doing, basically writing as well as I could, getting the feedback from comments and learning every step of the way.

    This is still going on. One year on, I learned what Twitter really meant. I didn't know Twitter. The first thing I learned at Asymconf was what a hash tag is good for. [I mean] I knew what they were. But I did not use them. I never used a hash tag before Asymconf because I don't use Twitter that way. I don't use it to look up stuff. I mostly use it as a way to get my word out and get feedback, just like a mini micro blog.

    But then I didn't understand the potential of a hash tag. It dawned on me when people were writing about Asymco and using a hash tag and if I searched on that I could find out everything that everybody said about it, a great idea.

    But that I learned again just a few days ago. So many things I learned, thousands and thousands of details. So many things that the tables are now turned. Now people expect me to teach them about blogging.

    Jim Zellmer: Yeah. [laughs]

    Horace: For example, how to get traffic. A lot of people are sending me emails with paragraphs and paragraphs of effusive, "Oh you are so great. Thank you so much. Can you help me with this?" I'm like "Well, you don't need to say any of those thank you things, just tell me what you need."

    A 15 year old sent me a request for an online interview. He made it easy. Five questions. So sure, I'll answer five questions. I treat everybody equally. Whether it's the Wall Street Journal or a 15 year old. I give them equal attention. I learn as much from both. The kids will teach you more, actually.

    Jim Zellmer: Given all of that, if you were entering college today, what would you study?

    Horace: I would still study engineering, absolutely. I am at heart an engineer. My son, I hope he does the same things I do. When I was a kid  I loved building things.

    I loved building Lego, although I didn't have money for a lot of them. I loved building model kits, the little plastic model kits, planes, and so on. That's not fashionable anymore, and mostly, it's old men who do it nowadays.

    Jim Zellmer: [laughs]

    Horace: [But] I'm trying to teach my kid. I actually bought a whole bunch of kits and began to model again so he could see me do it so he would get a passion for it.

    I think building things with your hands, learning how things work, being passionate about numbers and about technology and things that are tangible is the only way to really create if your mind works that way. I'm not saying it's for everyone. To me, that's the heart and soul of progress.

    By the way, I didn't mention this, but my parents also infused in me a love for the arts, and not "modern music". Being Romanians and of a certain age, they weren't ever part of the Rock and Roll, if you will, generation, although they knew of the Beatles.

    So, they listened to classical music. Throughout my life I was exposed. I was taken to the theatre, opera, ballet. I used to sit in these performances since I was five years old. I maybe didn't get it. I wasn't talented. I tried to play the violin. I wasn't good at it, but I understood, after repetition, I understood the value of that.

    When I went to that liberal arts college and got my degree, even though it was in computer science, I had a lot of requirements. I had to take English poetry. I had to take Japanese art. I had to take a lot of courses that were basic requirements. At the time, they were a burden, but in retrospect, they actually taught me a great deal. I'm very proud of having that background.

    I'm not saying to not have an arts education, but absolutely, if you have the skills and can execute or can perform as an engineering student, do that and do the other things. Do the other things which develop the other half of your brain.

    Jim Zellmer: Where did you learn to write, Horace? You write very well. Especially given that English is not your first language, you're able to be succinct and you have a wide ranging command of the language. So, where did you learn that?

    Horace: Reading, partly. OK, so I have to give a lot of credit, and I did once on Twitter, give a credit to my English high school teacher. I said if you like the writing I have on Asymco, you should thank her.

    Actually I wrote to her. She had seen my work in "The Boston Globe." It had been syndicated from that or something.

    Jim Zellmer: [laughs] Wow.

    Horace: She wrote me an email saying me an email saying, "I'm so proud to see your work and I sent it to your calculus teacher, as well."

    They were both retired. The calculus teacher had seen my work in the financial section, actually. He sent her a note saying, "Check out the. . ." They read the paper. These are from that generation, right?

    Jim Zellmer: Yes.

    Horace: I've never seen my work in print. I've seen it online, but there it was. I thanked her. What I said is this: What she taught me was to write plainly and write clearly. This was Medford High School, a working class neighborhood, nothing special about it.

    The teachers I had in English in Ohio didn't instill in me the same passion. The same books were read. Right? The same classics.

    Jim Zellmer: Classics, yeah.

    Horace: Twain and Conrad and all those classics, but the teacher in Medford, when I would write an essay, and also, I think, there was positive feedback because I was perhaps a little bit better than average in her class. Better than I was in Ohio. There I was about average, maybe.

    I had good grades, but I didn't feel like I was great at it. I was nervous because a lot of the tests were vocabulary, or a lot of the tests were not essays.

    This teacher instilled in me the passion for writing good essays. She kept telling me how great my essays were.  I was writing somehow, and I loved reading the books. That's the other thing, the other kids would cheat. They would read the Cliff Notes.

    Jim Zellmer: Yes.

    Horace: They would copy from each other or do all these things. I was like, "No, no. I want to go home and I really want to read this book. These are really nice books." So, a lot of reading, a lot of passion for reading and I think practicing with essays. Practicing, also, in the writing of work online.

    Now, again, when I look back at my early stuff, I cringe. It took me a while to find my voice. I didn't know what a voice was. I figured that out quickly. Then I had this challenge of working in the rigor of data. I realized the way to make my stuff stand out is to avoid opinion, to avoid hyperbole, to avoid all these things which bloggers seem to do.

    So, anyway, it took some time. I think there's both a lot of ability, like, Einstein said, "It's 20 percent ability, 80 percent perseverance or perspiration." It's just practice. The other thing is it's like an athlete, right? An athlete gets good because they practice every day.

    When I set out I said, "This is so much fun. I want to keep to it. I want to write a story every day. I want to write a blog post every day. I pretty much stuck to that. I was even writing on weekends, but I stopped because time, family. But, I write every day. I think of it as mental athleticism. You've got to go running every day if you want to be an athlete. You've got to write every day if you want to be a writer.

    I heard, later on, that Jerry Seinfeld said he wrote every day. That was his key to success. He always tried to write jokes every day. That, to me, is what I learned. You bite your tongue sometimes, you learn how to deal with comments. Through comments, you see exactly how people make mistakes. They make mistakes by getting ahead of their thoughts, or they are too impulsive.

    You get this great sense of what makes it good and I thought myself being able to write things. I write email in a good way, crisp in the email. You get a sense for it. For example, if somebody sends me ad copy, like a sponsor, and they send me a copy, I sometimes cringe when I look at it.

    Jim Zellmer: I noticed that!

    Horace: I can't help myself, I edit their copy, and even though they probably don't want me to, there is no time to go back and do feedback. But it's something you learn as a skill.

    Some other people have asked me, "How can I teach my son to write well?" To me, it's not about being able to do more, it's actually being able to cut stuff out, and just go straight to thought. Maybe it takes practice.

    Jim Zellmer: Now that you are a parent in Finland, your children are in Finland, so what choices do you have for your kids'?

    Horace: We are very conscious of that. So, I like [Finland]. Well, I came for one reason, because, it was a wonderful place to play. But I stayed because it's a wonderful place for families.

    What Finland's known for, among other things, is that it has the best scoring students on tests ...So, their educational system is considered absolutely in the top, literally top of the world.

    There's a lot of mystery about why that is, and you can't really put your finger on it. A lot of educators from Finland have been on world tours trying to explain what they do, and everybody comes away scratching their heads.

    I think this actually goes back to Christiansen theory, because when you study it people want to see a formula or an algorithm, but in fact, what is happening is, is something about whether the system is integrated or modular.

    Whether the system is centralized or decentralized. So, it's not a question of process. It's like when he approaches health care, he comes  at it from these two different angles. He says, "It's not about being public or private. It's being modular or integrated."

    The assumption in other countries is always that everything is modular, and it cannot be anything else. So, in a sense, you need to question down at the deeper roots of causality.

    So, my son, just to give you some perspective. He is now in pre-school.

    He is six now or he is in grade zero, as they call it here, and he is going to a French school, meaning that they speak French in class.

    Jim Zellmer: An immersion school. Yes.

    Horace: There are several language schools like this. We're going to the French one partly because his mother went to a French school, his uncle went to a French school and they have loyalty to it, but also because I'd personally like for him to learn a romance language because I knew one. I still know Romanian. I had learned Italian, and I took French in school myself.

    The thing is that it doesn't cost any more to go to that school than any other school. All education is free. Not everybody can get into any school, but it isn't about money. The other thing is that it's a small nation.

    There's only about five million people, so all the decision-making can be centralized. There is no local school boards. There's no organization down to the smaller units that you might imagine. It's very simple and it's top down.

    If you were to try to do a top down approach for a country as big as the United States it wouldn't work. You can't really transplant this system. People are very wary of centralization and control and the decision-making at the top that is incompetent. I completely understand that.

    However, this being a small nation, it works and it's central. There's a question of optimum size. I mean, in some sense five million might be the right, maybe 8, even 10 million maybe works. I don't know  beyond that.

    There's also the question of how different the people are in terms of homogeneity. Although Finns are fairly homogeneous, there are minority groups as well and there's been plenty of immigrants. I'm not an expert on any of this, but I'm just pointing out some minor details.

    I really like the school system. We actually had a parent teacher meeting this morning. They're very relaxed. Children seem to be much more relaxed. This is one thing that came across from the educators meeting and discussing around the world.

    There's no pressure. Even though they're performing exceptionally well, there doesn't seem to be that pressure on testing, on measurement, on all these things that supposedly correlate with performance. In many ways, it's asymmetric, or doesn't make sense to people who are steeped in education theory.

    I don't know if that's advisable, though. The problem, again, is that it may only work in this context. It may only work in the Nordic country, but we're very happy with the way it works. It's the same thing, by the way, with healthcare. Healthcare here is also centralized. It is a public resource.

    Jim Zellmer: Yeah. What's your sense of the teachers you've encountered? One of the things "The Economist" reported a couple years ago was that Finland requires master's degrees from teachers. Contrasting that with what you experienced in America and Verona and Romania, do you have a sense of differences in the teacher capabilities, or no?

    Horace: Because here mostly all degrees are considered Master's, it's essentially, I think, five years of school, of education. There's so many differences I can't even begin.

    My wife, for example, she has a master's degree. A bachelor's degree would be more equivalent to like a two year college in perception.

    Jim Zellmer: OK.

    Horace: So, if you have a technical degree...a lot of people drop out. They get out because it is somewhat  long and tedious and it is also not conducted in the American's style of valuing... It's so hard to explain. I actually would like him to go to university in the U.S., but I'd like him to go to every other school in Europe, or in Finland, more specifically.

    I think the U.S. higher education system is better. It's better because it actually doesn't teach you according to a cookbook. It's actually much more open. In a way, that's the opposite in the lower grades.

    Jim Zellmer: Yes.

    Horace: The lower grades are open and the students are given a lot more freedom, and the teachers are given a lot more freedom. So, it's the opposite.

    You'll see this, also, in Japan. Japan's educational system is a bit of a joke because they drill so hard in order to get good scores and get into a good university, but once they get into the university, they do nothing.

    The entry is your ticket. After that there's hardly any effort. I've heard from others that the way university programs here are, many students will stay in for 6, even 10 years. It takes a long time because they'll drop in and out. They'll take a couple of courses. They'll do something else.

    It isn't rigorous in the sense of, "Hey, the clock is running. This burns a lot of money. You've got to get a job to pay off loans." Because you've got that pressure on you in American universities, I think people actually are faster. It's more efficient. It tends to also draw more talent into it. The professors are more ambitious.

    So, there's something I like about the U.S. higher education system, although if you listen to Clay, he'll say that it's also being disrupted, and he's probably right, especially the bigger names are going to be pressured from online education.

    Jim Zellmer: Given your steep experience in technology and engineering, what is the role or is there a role for technology in education? Certainly in America and other countries we have all these people who say "Gee, our kids don't have iPads, they're just falling behind," among other things. So what is your perspective on that, Horace?

    Horace: Well, technology is useless without the software. Hardware is useless without software. Computers are useless without a job to be done.

    Jim Zellmer: Yes.

    Horace:  I believe technology will help, but we have to make sure that we solve the job problem with technology, rather than saying that technology itself is this answer. I think the iPad has potential because it enables the content to come through again. What you might learn by using it is focused on the content itself.

    In other words, a computer was always hard to use. Most of the time you spent using it was actually learning how to use it. So you have to fight through it to get to the actual content and material was supposed to teach you something. Even the way that it used to be, that there was a computer room or a computer lab and you would go and sit in front of these computers and there were all these things considered.

    In other words, it got in the way. I think that what the content needs to do is be more pervasive. You need to give the platform to someone who can build something on top of it, someone who can actually create new content, new material, new ways of teaching.

    The real innovations that I've seen have been the Khan Academy or even Ted Talks or something along the lines of video content that is packaged in small pieces that people can take and learn at the rate that they're comfortable with. That makes a lot of sense to me. I don't know how that can be worked to the K-12 system because that is so regimented. But I think kids having iPads seems to be potentially a breakthrough opportunity there for how to really teach.

    It's all going to come down to the materials. Is this a platform that teachers can build stuff on? The only thing I have to criticize the system for is that it's still not possible for laymen to create material for it. We need more and better tools that sit on top of the tools we have. So abstract from the hardware so you can create great e-books, you can create... experiments and so on.

    Jim Zellmer: Right. Well, that's great. I appreciate your time today, Horace. Perhaps we can continue this again one day on education, which certainly continues to change. Again, good luck with the French school, with your son.

  5. Google and Microsoft speak volumes with silence

    Research · 23 comments

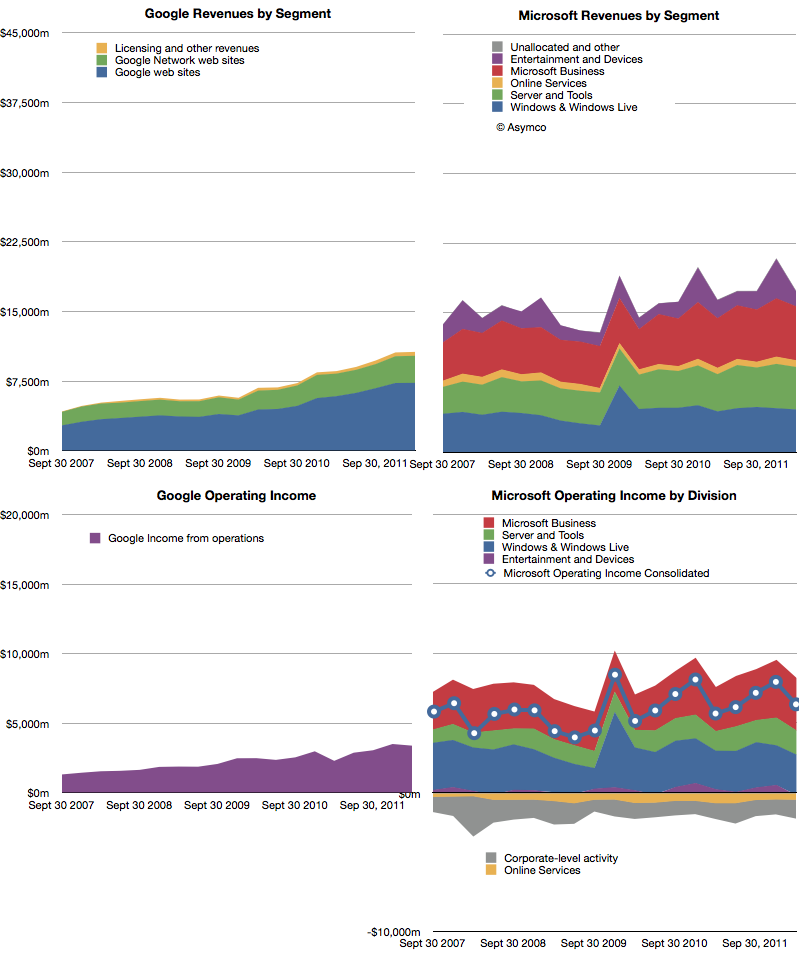
    The following charts show Google and Microsoft revenues and operating income:

    Both companies showed healthy growth. Revenues: Microsoft 6%, Google 24%. Operating Income: Microsoft 12%, Google 48%. Google had a particularly weak margin Q1 2011 so its income growth appears very strong.

    The surprise in Microsoft's performance was the 4.8% increase in Windows revenue at a time when PC sales were expected to be declining or flat. Final PC numbers are not yet out so we'll have to check back on this figure to see whether Microsoft has been able to get higher pricing for Windows or whether the market did expand. (Average revenues per PC sold have been quite steady for years). Overall, Microsoft's business shows consistency. Of course, that should not be cause for comfort. Nokia had remarkable consistency until it jumped from a burning platform and RIM grew more rapidly until its platform imploded.

    As Google still obtains 96% of its income from advertising, it's quite remarkable that it is now at 61% of Microsoft's revenues. Google is also growing more rapidly than Microsoft so the possibility exists that the top ad service will overtake the top software company in revenue, establishing a new benchmark for how software can be monetized.

    The curious thing about both of these companies' financial performance is that mobility does not appear to have had any impact on either top or bottom lines[1].  There is no business division or income statement line that can be attached to mobile revenues. Microsoft placed Windows Phone under Entertainment and Devices but that division is dominated by Xbox and accessories. Google bundles everything under Advertising and has never broken out mobile, much less Android-derived income.

    The surge in valuation for mobile-focused startups seems to leave investors in both these companies unaffected. The damnation for both companies lies in mobility being non-core businesses whose strategies center on reaction and defense.

    ---

    Notes:

    1. Google does not answer specific questions about the impact of mobile on their business but they do acknowledge that there are traffic acquisition costs (TAC) associated with OEMs and Carriers who deploy Android. This means that there are costs of mobile sales (i.e. Search) but not to any measure of specific value.
  6. Forecasting Nokia's Windows Phone sales and Microsoft's mobile customer acquisition cost

    Research · 56 comments

    Our agreement with Microsoft includes platform support payments from Microsoft to us as well as software royalty payments from us to Microsoft. In the first quarter 2012, we received a quarterly platform support payment of USD 250 million (approximately EUR 189 million). We have a competitive software royalty structure, which includes minimum software royalty commitments. Over the life of the agreement, both the platform support payments and the minimum software royalty commitments are expected to measure in the billions of US Dollars. The total amount of the platform support payments is expected to slightly exceed the total amount of the minimum software royalty commitments.

    From Nokia's Q1 2012 financial interim report

    The figure of $250 million for Q1 is the same as the amount Nokia received for "platform support" in Q4 2011. This means Microsoft has paid $500 million over two quarters. During the same time frame Nokia shipped approximately three million Windows Phone devices. The average cost to Microsoft to acquire a Nokia Windows Phone user is therefore $167 per user. This is down from $250/user in the last quarter.[1]

    If the royalty is equivalent to a license fee then the more interesting question is how and when will the royalty payments nearly match the platform support payments as expected. This might give us an estimate of what both parties are expecting from the relationship.

    If the payment schedule of $250 million per quarter is maintained through 2014, Microsoft will have paid $3.25 billion to Nokia. This is well within the "billions of US dollars" range that is cited above. (The minimum would be $2 billion which would mean payments through the end of 2013).

    We also need to estimate the royalty payment structure. One figure that has been circulating for a long time is that Microsoft prices Windows Phone (and its antecedent Windows Mobile) at $15/unit. It's an aggressive price point for a mobile software license and should be subject to volume discounts but let's assume it's correct. If it is correct then the only remaining question is how quickly will Windows Phone units grow at Nokia?

    One way to begin is to calibrate WP growth to iPhone growth. For the first two quarters iPhone and Lumia have sold at rough parity.[2] iPhone sold 1.4 million in its first quarter (including opening weekend sales of 270k in previous quarter) while Nokia sold "approximately" one million Lumias in its first quarter[3]. In the second quarter Nokia cited 2 million Lumia units and Apple had 2.3 million iPhone sold in Q4 07. So far Lumia is slightly under the iPhone ramp, but let's give it the benefit of doubt.

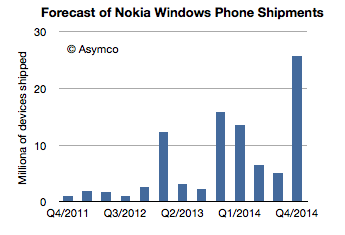
    If we  apply iPhone growth rates to Lumia then we have the following sales forecast for Nokia's Windows Phones:

    This looks like healthy growth, as was the iPhone's. However, this "iPhone growth" pattern only results in about $1.4 billion in payments in exchange for $3.25 billion from Microsoft, leaving a deficit of $1.9 billion in the "platform support" balance.

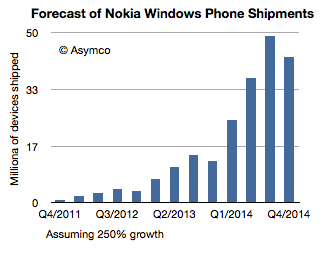
    To erase the deficit, I tried an approach where I assigned 3 million and 4 million for Q2 and Q3 shipments respectively then applied a constant (y/y) growth rate thereafter. Solving for a figure of growth which results rough parity with platform support payments gives us about 250% growth. The resulting sales profile looks like this:

    This ramp would result in 210 million Windows Phones shipped over about three years. It would also generate nearly $3.2 billion in "royalties" for Microsoft offsetting $3.25 billion in "platform support" payments by Microsoft to Nokia.

    There are many assumptions in this, royalty rate and length of contract chief among them, but the key question should be a sanity check: is this a feasible product ramp. It's certainly far faster growth than Apple has been able to achieve. On average Apple obtained about 160% quarterly y/y growth. It also exceeds the growth rate that Samsung has been able to achieve (165 to 170 million smartphones shipped from a standing start three years ago). It implies 150 million units shipping in the third year of sales and nearly 50 million in a peak quarter. It assumes perhaps as much as 20% market share in smartphones in 2014. It's certainly ambitious.

    But even if it's achieved, it's only a break-even point for Microsoft's relationship with Nokia. It would imply that payments to and payments from Nokia would be in balance. The road to (dare one say it?) profitability for Microsoft in mobile would just begin to be visible at that point.

    ---

    Notes:

    1. What the quote above also reveals is that Nokia is also expecting to pay back some of these "support payments" in the form of "royalty payments" for the software. That's an interesting word choice as usually an OEM would pay a license rather than a royalty for software. I'm not sure if this implies anything but it may.
    2. See also Charles Arthur's analysis of comparable growth ramps for mobile phone platforms here.
    3. This figure was cited "to date" in a March statement so actual calendar Q1 may have been less, perhaps 650k.


  7. Take the money and run

    Research · 26 comments

    In August 2007, during the HD format wars between HD-DVD and Blu-ray format, Toshiba offered Paramount and Dreamworks $150 million to produce HD versions of their movies exclusively as HD-DVD.[1]

    This type of deal is equivalent to an "advance" offered to a book author. The DVD manufacturer pays studios up-front cash for the right to make its DVDs. From an accounting point of view this is treated as an advance that the manufacturer recovers by selling the DVDs back to the studio's video division in the same way a publisher earns back the advance it gives an author.

    In this case, the payment was so large and the sales of HD-DVDs so small that Toshiba was unlikely to earn back the entire advance. The way the deal made any sense for Toshiba was that it was exclusive: the studios could not continue to release their movies in Blu-ray. The deal was done explicitly to hobble a competitor and create "critical mass" of content for its own format.

    But then in March 2008, Toshiba threw in the towel and abandoned the HD-DVD format. The way the deal worked, the studios got to keep almost all of the $150 million. They then re-released all their movies in the Blu-ray format. The only "cost" to the $150 million windfall was that there was a nine month delay in the eventual release to Blu-ray--a small price to pay for an emergent format without a large install base.[2]

    Platform owners go to great lengths to ensure "content" for their platform. They will, essentially, finance an ecosystem when there are barriers to entry or when competing ecosystems are far more lucrative.

    This scenario for movies is being played again with Netflix, Hulu and other distributors who need to fill their pipelines. Netflix's content acquisition costs are exploding and putting the whole company's future in doubt.

    But this scenario is also being played out with app developers. Most recently, news broke that developers are receiving payments from Microsoft for Windows Phone ports of popular apps. In mobile platforms, apps are the new content and developers are the new studios.  It's also a practice that is not without precedent[3].

    This is as it should be. The value of the platform lies mainly in what is built on top of it just like a foundation is not much use without a house on it. However, the practice of "priming the pump" with cash payments for porting is not ideal. Like spiffs, those who receive payments may become used to it and withhold development if there is no payment. Also, those who did not get payment offers may feel shunned and retaliate in kind. Those who receive payment may become cynical about it and may not put in the extra effort (or, more probably, outsource) to make the work spectacular.

    Or, like Paramount, they may just take the money and run if/when the platform fails.

    ---

    Notes:

    1. Source: The Hollywood Economist 2.0: The Hidden Financial Reality Behind the Movies by Edward Jay Epstein.
    2. Paramount made $250 million more from three "replication output" deals: $50 million from Toshiba for agreeing to release Titanic on DVD in time for Christmas sales, $150 million from Panasonic for agreeing to allow them to take over video replication from Thompson, and $50 million from the law firm Ziffrin, Brittenham and Circuit City stores for agreeing to support the DIVX format. Paramount got to keep the money even though DIVX never launched.
    3. Although it's never been reported that Apple pays developers for building iOS apps, some developers do benefit from promotional placement and visibility during launch events and from early access to devices or SDKs under development.
  8. Half of US iPhones are repeat purchases

    Research · 46 comments

    Canaccord Genuity analyst Mike Walkley writes in a note to clients today. “In fact, we believe iPhones are outselling all other smartphones combined at Sprint and AT&T and selling at roughly equal volume to all Android smartphones at Verizon.”

    via iPhone Tops Sales Charts at Each of Its U.S. Carriers - John Paczkowski - Mobile - AllThingsD.

    That's useful data. Mainly because we can use it in combination with comScore data that tracks a different market measure. comScore's MobiLens service tracks US mobile installed base. By measuring the difference between their stats one month to the next, one can measure the gain in a particular platform.

    Comparing that gain with the sell-through rate in the same period can yield a figure for the number of units sold as upgrades vs. those sold to new users.

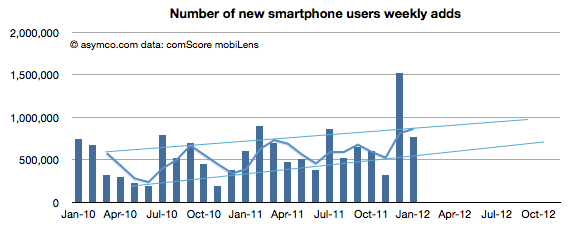
    The latest comScore data (period ending February) shows that Android added 2.87 million users to its base while iPhone added 1.52 million. If we assume that Android sold a minimal number of replacements (due to the limited time in use of bulk of units) and round up to 3 million for February, and if we assume that Apple sells as many iPhones as Android (which is what Walkley suggests) then we can conclude that in the US roughly half the iPhones are bought as replacements for existing iPhones.

    Extrapolating this to global markets may be risky but already we can begin to form a picture of how the iPhone franchise is becoming an annuity-based business.

    Apple likes to point out that "half of Mac buyers are first time buyers." In the case of the iPhone perhaps they could also say "half of iPhone buyers are repeat customers." At this stage in the platform, that's a powerful statement. If the repeat customer rate is high then it suggests strong loyalty but it also may suggest poor competitive position vs. non-consumption or alternate platforms. If the repeat customer rate is very low it may suggest competition vs. non-consumption but it may also suggest low loyalty. It all depends on the overall growth in the market and size of installed base.

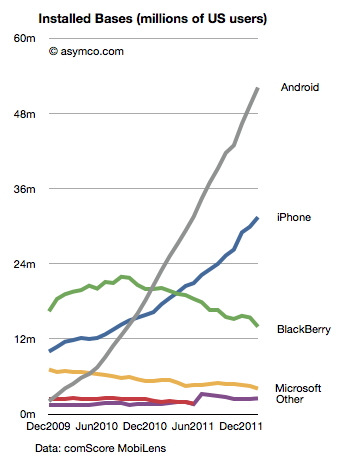
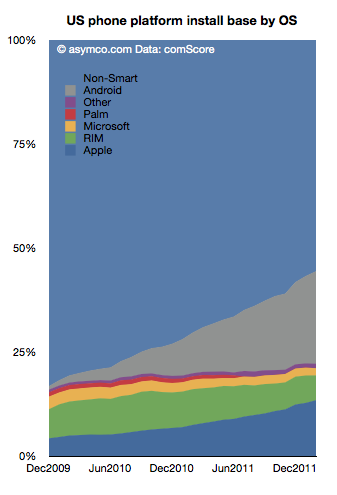
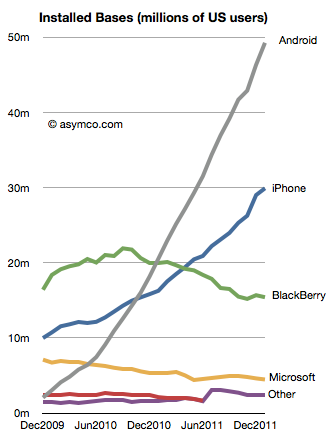
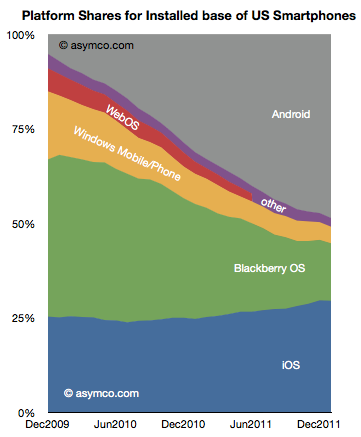
    The following chart shows the overall market growth and the position of the various platforms within that growth.

    Note the time scale is slightly more than two years. This suggests that the vast bulk of Android units in use (grey area) consists of first use units. New purchases are going to first time buyers. In contrast, the shrinking RIM total implies extremely low sales as the age of the base is far older than the time scale. iPhone base is both growing and being upgraded.

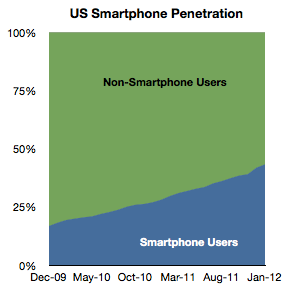
    As we reach 50% penetration of smartphones, platform churn will become a significant component of market performance. The loyalty and "stickiness" of Android will begin to be tested. Current surveys show reasonably good satisfaction ratings for Android phones (around 60%) while iPhone's are even higher. But let's keep in mind that RIM's satisfaction and the loyalty of their customers was exceptionally high a few years ago. The rate of evaporation of goodwill toward the brand is breathtaking.

    The longer term test of mobile platform performance will be in the recurring purchase rates. Loyalty must be earned and preserved. I.e. "You come for the product, you stay for the ecosystem."

    So far, the iPhone seems to be getting a passing grade while Android has yet to face the test.

  9. Android Economics

    Research · 88 comments

    Charles Arthur, writing for The Guardian, has noted that court filings seem to be revealing Google's Android revenues. If this is the case, we have a significant breakthrough in understanding the economics of Android and the overall mobile platform strategy of Google.

    The new data is a reference to a settlement offer Google made to Oracle of $2.8 million and 0.515% of Android revenues on an ongoing basis. The key assumption to make this data useful is that the $2.8 million offer represents 0.515% of revenues to date.

    In other words, that revenues from 2008 to end of 2011 multiplied by 0.00515 results in $2.8 million. That implies that revenues from 2008 to 2011 were $544 million.

    I think that's a fair assumption. I don't see why Google would offer a higher or lower royalty rate for years 2008 through 2011 than for years after 2011. The offer would seem to be 0.0515% in the future as well as retroactively in the past.

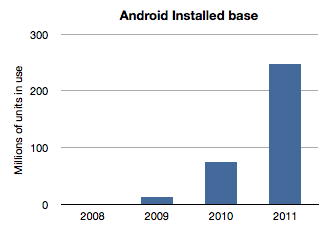
    If we work with this assumption then the next question is how to distribute this $544 million over the four years 2008 through 2011? The installed base of Android has grown exponentially and it would seem logical to assume that revenues have followed in a similar pattern. Here is a chart of installed base given activation data supplied by Google.

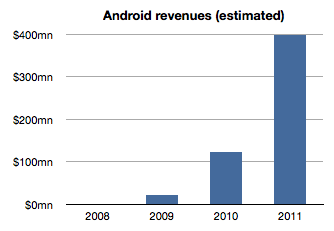
    If we assume revenues were distributed the same way we would get something like this:

    The sum of the bars in this chart equals $544 million and the ramp is approximately the same as the installed base. The relationship between the first graph and the second is a multiple equivalent to the revenue per device.

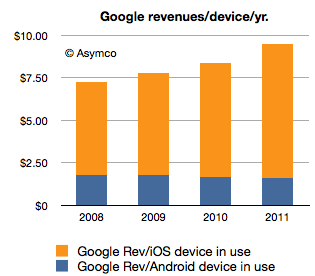
    Therefore a second assumption is that revenue per device remained fairly constant. In this model the revenue comes out to be about $1.70 per device per year. It's possible that rev/dev/yr. is increasing as Google services are discovered by users. It's also possible that the rev/dev/yr. is decreasing as later adopters are less likely to engage as early users. I just don't know how to adjust this value so by leaving it at the average, I can avoid introducing more assumptions.

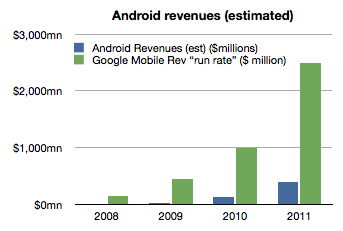
    Now we can stop and look at this figure and do a test. Does $1.70 make sense as a device revenue for Android? Google had spoken about targeting $10/device/yr. but we have no indication that they are nearly at that level. If they did achieve that level, with an installed base of 300 million, Google could be collecting $3 billion a year in Android income. Are they getting it?

    As of October, Google mentioned that it had a $2.5 billion "mobile run rate". But we know that this figure is not only from Android. Mobile includes all mobile devices and services including those running inside iOS, Symbian, BlackBerry, Windows Phone, etc.  They could be counting ads on all mobile browsers as well as ads running inside all apps on all platforms. Furthermore, Google also testified that iOS accounts for two thirds of their mobile search revenues[1].

    Adding run rate to the Android revenue chart results in the following:

    So the step is to take the "run rate" figure of $2.5 billion and assume, as Charles Arthur did, that iOS income is what is left after taking out the Android part[2]. I also noted that Google previously mentioned a run rate of $1 billion and I will assign that run rate to 2010 and $2.5b to all of 2011. Since we know the number of iOS devices in use for years 2010 and 2011 we can calculate Google's revenues per iOS device in use.

    If we thus combine all the data we know (revenues derived from settlement offer, units in use, run rate and iOS installed base) we get the following revenue profile:

    This shows a positive trend for Google: revenues per smartphone per year is increasing. However, the growth is coming from non-Android devices which means mostly iOS. Revenues per device for Android is probably declining.

    The story for iOS revenues however is not all rosy for Google. Google has to pay for that revenue. The mechanism is a payment that Google makes to Apple for the prominent and default placement of Google search on Safari.

    We don't know the terms of the arrangement but if we assume $2/device Google needs to shave $2 from the top of the chart above with that money going to Apple (attached as iPhone/iPad service revenues.)[3]

    That still leaves a healthy $8.33 in 2011 as operating income from mobile with $1.70 or so coming from Android.

    However, to make this operating income into bottom line profit, we have to extract the R&D and SG&A associated with mobile at Google. This would be, therefore, Andy Rubin's yearly budget.

    Andy Rubin has stated in the past that Android is profitable. That is certainly believable. The budget would have to be about $400 million/year in 2011.

    Charles Arthur concluded that Google obtains four times more revenue from iOS than from Android. My estimates indicate that in 2011 the revenue ratio was closer to 5 but if we subtract the cost of those sales in the form of payments to Apple then the ratio could well be four to one.

    Many of these figures begin to "hang together" as we balance assumptions about costs, revenues and statements made in public. There is a consistency within a comfortable margin of error. If that is the case, then the economics of Android begins to take shape.

    My take is that it's not a bad business. But it's also not a great one. As long as there is exponential growth in units, Android will improve its position inside Google relative to iOS. But from Google's perspective, iOS is today a bigger business. And iOS is not standing still. It's growing not only in terms of units but in revenue per unit.

    Strategically, and historically Android was never one thing. P&L considerations were not the only (or even at all) factors in investment for Google. Having a hedge against hegemony of potential rivals, having a means to learn and develop new business and having a role in defining the post-PC computing paradigm are all probably bigger considerations than profitability.

    So in terms of returns, Android is sustainable. However, in relative terms the value created leaves much to be desired. Whereas Android generates $1.70/device/year and thus an Android device with a two year life generates about $3.5 to Google over its life, Apple obtained $576.3 for each iOS device it sold in 2011[4]. The economics of Android are nothing like the economics of iOS.

    ---

    Notes:

    1. This figure is also not conclusive as search is not the only form of revenue on a mobile device but it does imply that Android is not the majority of Google's mobile revenues.
    2. Clearly this is overstating iOS as the non-Android income is broken up between several platforms. We can only say that iOS is the vast majority of non-Android income.
    3. Assuming a $2/device payment model means Google paid $312 million to Apple in 2011 and $171 million in 2010. This would go toward boosting Apple's revenue per iOS device. Naturally, if this distribution cost is higher or would be subject to re-negotiation then it could vary widely.
    4. The iOS figure includes accessories and licensing of trademarks but excludes income from App Store, iTunes music, movies, TV shows, iBooks, greeting cards or textbooks.
  10. Top-down vs. bottom-up: Which market analysis method is appropriate when disruption is knocking

    Research · 29 comments

    In terms of platforms, IDC expects a relatively dramatic shift between 2011 and 2016, with the once-dominant Windows on x86 platform, consisting of PCs running the Windows operating system on any x86-compatible CPU, slipping from a leading 35.9% share in 2011 down to 25.1% in 2016. The number of Android-based devices running on ARM CPUs, on the other hand, will grow modestly from 29.4% share in 2011 to a market-leading 31.1% share in 2016. Meanwhile, iOS-based devices will grow from 14.6% share in 2011 to 17.3% in 2016.

    Via: IDC - Press Release - prUS23398412

    The company provides a stacked bar chart (follow link above) to illustrate their view of the market. I took the data they included and measured the implied growth rates for the product categories:

    IDC is implying that in four years the tablet market will be growing at 10%, the Smartphone market will grow at 11% and the PC category will grow at 11%. In other words, five years from now the PC market is expected to grow faster than the tablet market and just as fast as the smartphone market!

    What's more remarkable is that this situation is not going to happen in four years. The slowdown in growth is actually expected much sooner. The growth rates two years from now are expected to be: Tablets 17%, Smartphones 15% and PC 10%. IDC is unequivocal: by 2014 the good times will come to an end to the post-PC challengers. These growth rates would be catastrophic for share prices and the value propositions of the new platforms to developers, partners and consumers.

    What's more, these growth rates are striking not only because they predict a collapse in the value of most market challengers but that they also predict a strongly resilient PC market. How can we test this forecast?

    I tried to reconcile this doomsday scenario with what is known about the components making up the data. I.e. what "bottom-up" data is IDC using? In the quote above, IDC offers some insight into this market participant data. Based on the category and share data they published it's possible to infer the following:

    Bearing in mind that neither iOS nor Android existed five years ago, we can observe they are bigger together than the PC market. And yet, IDC predicts a compounded average yearly growth rate of 16.7% in Android, 19.4% in iOS and 7.5% in Windows between today and 2016.

    In aggregate, IDC forecasts that in the next five years Android will not manage to double and that iOS will only increase by a factor of 2.4. Is this believable?

    I try to stay away from long term forecasts, but I do maintain a short term forecast based on recent growth data. My forecasts for this year and next year are shown below.

    I super-imposed my short-term forecast (outline bars) on IDC's long term forecast (solid bars) and a several differences become apparent.

    First, my 2013 forecast is nearly the same as IDC's 2016 forecast. To see why we need to look at each platform separately.

    Perhaps we might (with difficulty) agree on Microsoft's potential. I believe Windows 8 will have a catalyzing effect and that Microsoft will begin to see its platform grow again. However, my expectations are modest. To increase Windows sales rate by 100 million units/yr between 2013 and 2016 is possible but ambitious.

    The real problem is that our Android and iOS forecasts are outside any zone of possible agreement. Maybe there is a difference in what we measure. For a hint, we seem to disagree on the number of Android devices shipped in 2011. I used Google's own reports of activations to work out the yearly shipment estimates. Perhaps IDC is including versions of Android that are not Google sanctioned.

    We also disagree on the 2011 iOS figures. I obtained 156 from Apple's own reports. Again, perhaps the difference is the inclusion of the iPod in my case.

    Nevertheless, the difference in the long term cannot be accounted for only through these categorization differences. I would put the cause of the difference down to the methods used in forecasting. As can be seen from the first chart above, IDC's growth rate reductions are extraordinarily steep. Perhaps the approach used by IDC was to forecast the overall market growth and then assignment of shares to participants. This can be called the "top-down" approach. In contrast, my approach is to forecast growth rates based on recent growth rates and moderating these rates gradually. This can be called the "bottom-up" approach.

    My experience and all the data I've ever collected about historic disruptions tell me that the entrants tend to win these types of paradigm shifts. They win through a vast expansion of consumption and the recruitment of non-consumers. Markets tend to experience vast shifts in composition. If we believe this to be true then the bottom-up approach focused on entrants is likely to be more effective vis-a-vis the top-down approach of projecting steady state markets and the implicit assumption of incumbent share preservation.

  11. The unrelenting trends in the US smartphone market

    Research · 27 comments

    The latest comScore US mobile subscriber monthly data is in: comScore Reports January 2012 U.S. Mobile Subscriber Market Share - comScore, Inc.

    January saw a return to trend line growth in US smartphone add rates. The 767k/week rate is within the band after November's below- and December's above-the-line outliers. The weekly add rates are shown (with projection of trend) below:

    The pattern shows a likely 1 million new smartphone users per week being added consistently by the fourth quarter of this year.

    Overall, penetration of the sampled population (above age of 13, primary phone and excluding business purchases in the US) reached 43.3% in January. The increase was 1.45 points from December.

    A significant 35 million US users  switched to smartphones in the last 12 months, equivalent to 15% of the user population. My current forecast is that 50% of the user base would be smartphone users by June 28th.

    The platform data shows a continuing pattern. In terms of absolute users Android has reached nearly 50 million users, iPhone 30 million, BlackBerry 15 million and Microsoft (Windows Phone and Windows Mobile combined) 4.5 million.

    In terms of market share of the smartphone population, the various platforms stack up as follows:

    The net gains for each platform by month are shown in the following diagram:

    RIM and Microsoft have continued to lose users while Google and Apple have continued to gain.

    The two trends that continue are that overall penetration is nearing saturation and that two platforms seem to be increasing their share of that base. The "comeback story" for any of the hopefuls will depend either on switching users away from their current platforms of trying to engage with late adopters. The first option is daunting due to latent network effects related to platforms and the second sounds to be symmetric to existing incumbent strategies.

    Without an asymmetric approach, the challengers are unlikely to succeed.