Asymco

Asymmetric Intelligence

revenue

  1. When Watch surpassed iPod

    Research · 18 comments

    The last time Apple reported iPod unit and revenues was for the third quarter of 2014. Thereafter the product segment called “Other Products” was used to include what was formerly the iPod segment and the “Accessories” segment. Exactly two quarters later Apple began to sell the Apple Watch. Apple Watch was not broken out as a separate product segment and remained a part of Other Products along with iPod touch, Beats, Apple TV, and Apple-branded and third-party accessories. Soon the HomePod will also join the Other products.

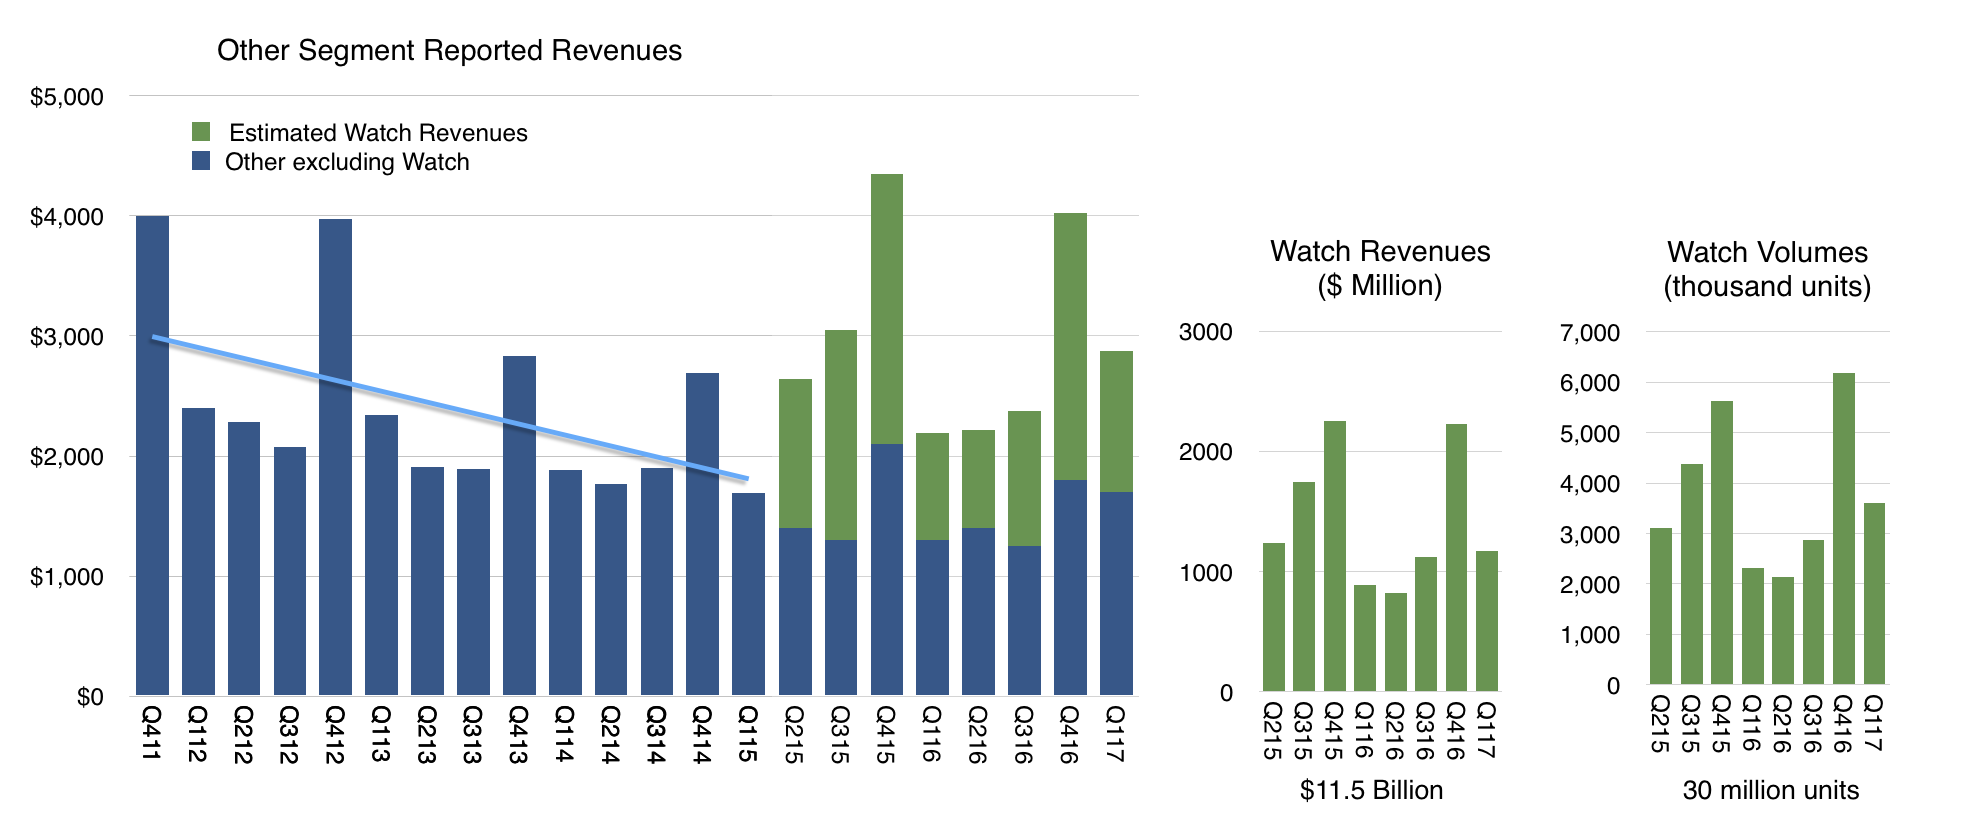
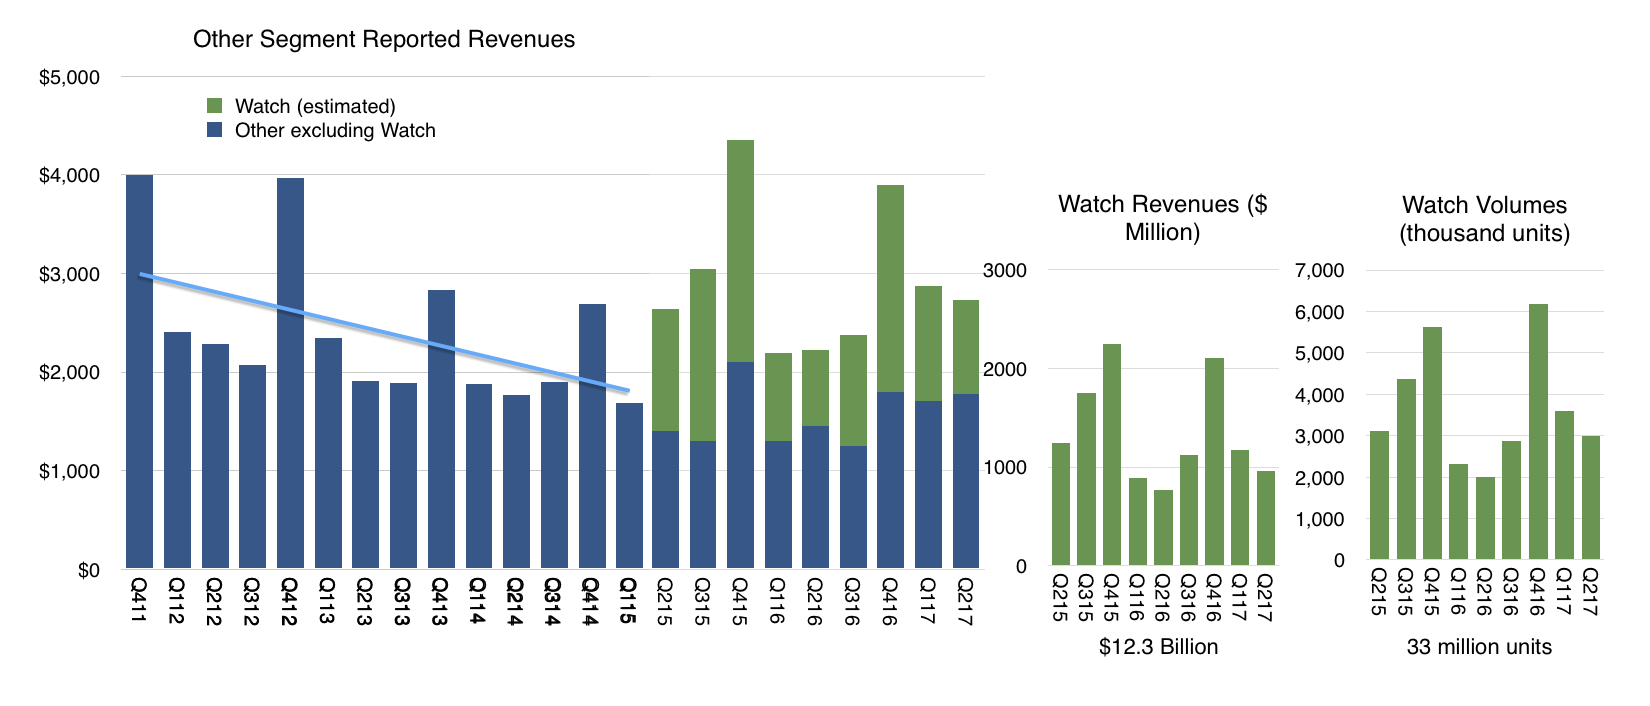
    The combined iPod, Accessories and “Other” product sales are shown in the following graph. ((Two quarters include estimated iPod revenues: Q4 ’14 and Q1 ’15. The iPod contribution is estimated with a simple extrapolation using the previous four quarters’ average rate of decline))
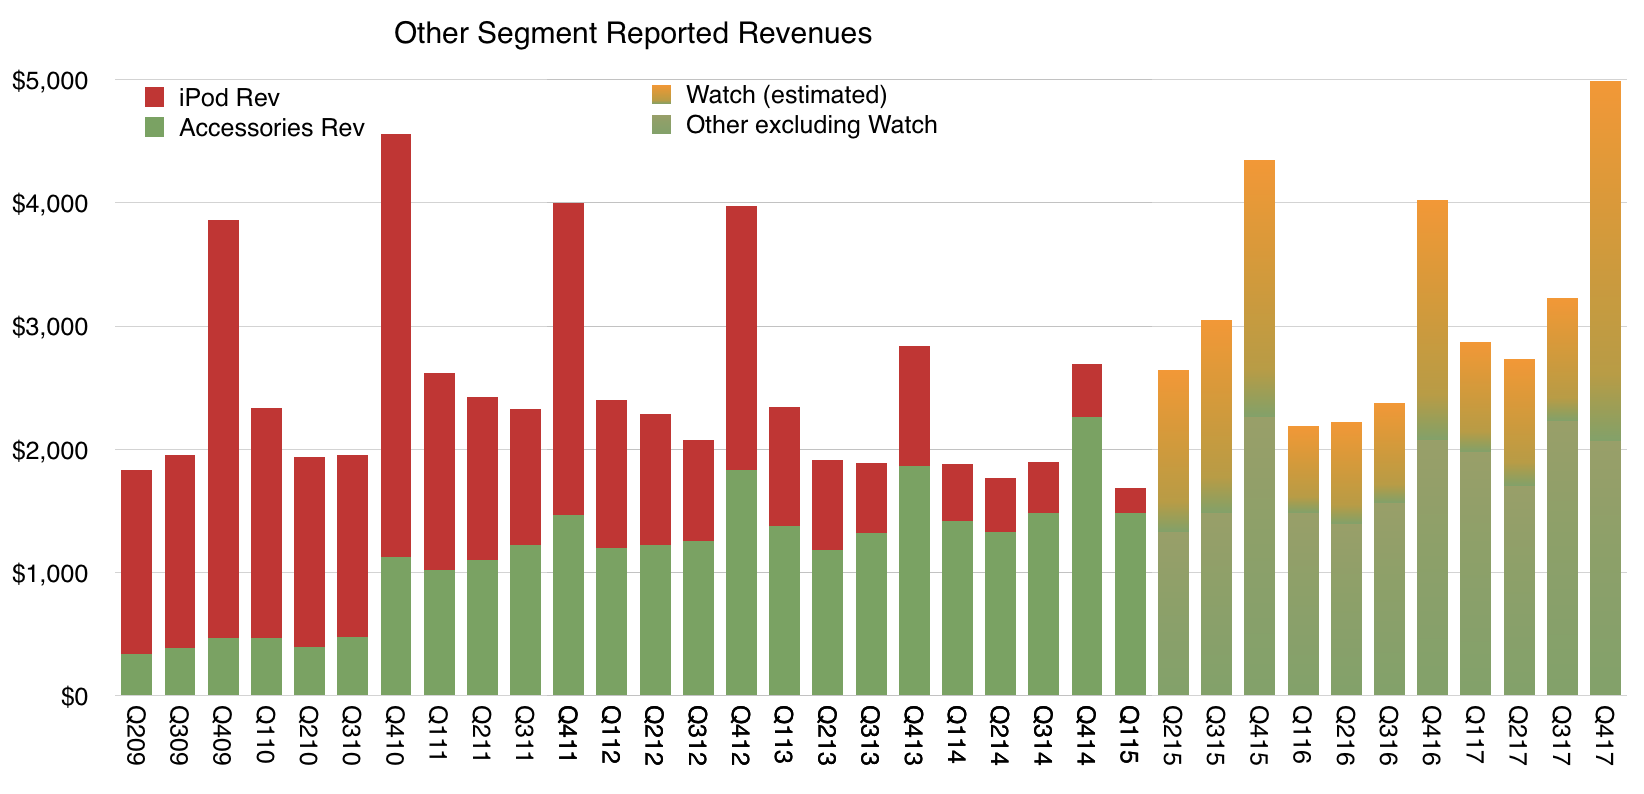
    Note that an attempt is made to estimate the contribution of Apple Watch to the mix. The method is simple: if you can estimate the non-Watch sales trajectory then the Watch is the difference between Other total and this trajectory.

    If we discount the iPod, the non-Watch revenues come down to Apple TV and Beats, mainly.  Note that the data shows the contribution of Beats (Q4 2010) but it’s hard to parse specifically the growth of Beats. Since the Watch launched we also saw the introduction of AirPods and new Apple TVs, both of which probably contributed to some growth to “Other excluding Watch.”

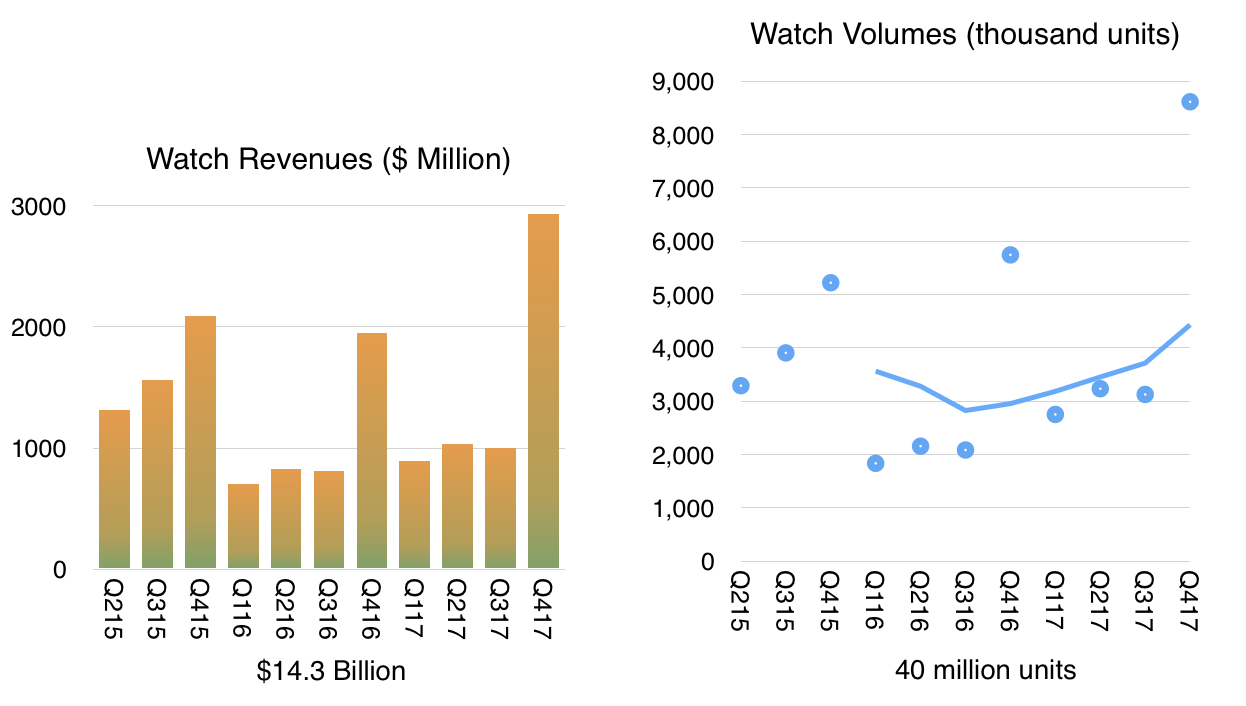
    We can take a stab at the first 6 quarters of Watch by projecting Other with some nominal growth. Thereafter Watch can be modeled using growth assumptions. Apple stated that growth was above 50% during the past three quarters. There are a few quarters where we must make guesses but overall the picture that emerges, shown below, is fairly robust. Note that I’ve included estimates for the fourth quarter of 2017 assuming continuing 50% growth. This is driven primarily by the launch of the LTE-enabled Series 3.

    The result is a cumulative sales value of $14.3 billion and a volume of 40 million units (based on average pricing assumptions).
     

    But what most catches the eye is the transition from iPod to Watch. Watch entered nearly at the same time as iPod bowed out. Its contribution to sales seems to mirror the iPod as well. The interesting question then becomes if the Watch will eventually match and indeed exceed the revenues from iPod.

    I’d say the better question is _when_ Watch will overtake iPod. From a revenue point of view, I believe next year’s fourth quarter will see the Watch generating higher revenues than the highest quarter for the iPod. ((That was in Q4 2007 when iPod managed $4 billion.))

    In terms of yearly unit sales it may take longer. The biggest year for iPod units was 2008 when about 55 million iPods shipped. Watch is now running at about 16million. If it could sustain 30% growth then it would take until 2022. 40% growth would mean 2021 and 50% 2020.

    It’s not easy to predict growth but my bet remains that Watch will get there eventually becoming the third most popular Apple product. Perhaps even second.

    Overtaking the iPod is quite an achievement considering that the iPod was once synonymous with Apple itself. Although Watch may overcome iPod, Apple may never be known as the Watch company. That’s perhaps for the best. I’ve noted before that Apple was once seen as the Apple II company, became the Mac company then the iPod company. Now of course it is thought of as the iPhone company though it’s no more that than it ever was any of the other things.


  2. Does the iPhone 8 have what it takes to be a success?

    Research · 96 comments

    Source: ¿El iPhone 8 tiene lo que se necesita para ser un éxito?

    The above interview was conducted October 17 with Carlos Morales
    Editor en Jefe, Forbes Digital (Mexico).

    The source questions and my answers in English are below:

    How can we read the fact that the new iPhone lineup raised so little noise? There was no massive lines outside the Apple Stores and people demonstrated almost zero interest in the new models compared with the hype motivated by the iPhone 7.

    I don’t know about you but I don’t like waiting in lines. I don’t think Apple considers waiting in lines to be a good user experience for its customers. Over the years Apple has been able to improve availability and online orders so that lines can be eliminated. I suggest a better way to gauge interest in new models and that would be to look at sales. Sales seem to be going up even as lines have been going down.

    The iPhone 8. What do you think of the fact that the iPhone 7 is outselling the iPhone 8?

    Is it a fact? I think this notion is coming from a survey of operator stores in the US over a short time period. The mix of phones has never been known and is a matter of speculation. The only data we do have is the average selling price derived by dividing the revenues by the number of units sold (and ignoring deferrals). This price set a new record during the last 12 months. Expectations are that it will increase to another record again next year. I might add that this has never been observed in the phone business as far as I know. The opposite has been the trend.

    Whats the outlook for the the iPhone 8 vs the iPhone 7 and the iPhone X?

    The iPhone 8 is likely to be the best selling model over the next 12 months. The iPhone X will be the best seller in the first quarter but I expect it will come second during the following quarters. The iPhone 7 will end up 3rd.

    What do you think about the smartphone prices, aren't they too high? How far can they be stretched ?

    Smartphone prices are very low. World-wide, average smartphones sell for less than $300. You can see a break-down by region here.

    iPhone prices are, on average, more than double the average of all smartphones. Note that apple’s latest line-up also includes the cheapest iPhone ever with the SE now starting at $350.

    I don’t think the average selling price will increase in 2018 globally. It will probably decrease as it has for a long time. Average iPhone prices will increase but probably only by $10 or so.

    The iPhone price tiers are well understood. I published an analysis here:

    More important however is that the iPhone remains priced at about $1/day, no matter the model, and as such the value users perceive is very high. The most expensive iPhone costs about 8 cents per hour of use, 1.4 cents each time you unlock it and 1 cent for ever 25 interactions you have with it (touches or taps). On a per use basis the iPhone is extraordinarily cheap. I know of no consumer product that is cheaper. This is determined partly by the intensity of use and by the high resale value (I assume 30% residual value after 2 years).

    Do we really need a borderless OLED display in a smartphone? What about the face recognition technology?

    Having no borders means you can get a screen that is bigger than the iPhone Plus in a phone the size of an iPhone. I think users will value getting more screen in a smaller phone. I certainly would. Having OLED means it can be curved a bit and also have nicer, truer black.

    Face recognition saves time and is more secure. I don’t know another way of making the experience better for something that you do 30,000 times a year.

    What do you think about the Apple Watch, which seems to be—finally—on the right track?

    The Apple Watch has been on the same track for 2.5 years. I don’t see any change in that trajectory.


  3. A small-screen iPod, an Internet Communicator and a Phone

    Research · 111 comments

    Apple is now the biggest watchmaker in the world, overtaking Rolex during the last quarter. This achievement happened less than two and a half years after Apple entered the watch market. Rolex, on the other hand, was founded in 1905, 112 years ago at a time when watches were the avant-garde of technology. Given this revelation of sales, we can test the estimates I put forward on the Apple Watch sales, shown below:

    We know that Rolex produces about 1 million watches a year and we also know that Rolex had sales of $4.7 billion in 2016. The average revenue per watch ((Includes services such as repairs)) was therefore about $4,700.

    My estimate has been that Apple sold about 15 million Watches in the last 12 months at an average price of about $330. This puts the Apple Watch revenue run rate at $4.9 billion, indeed above Rolex.

    They may be slightly high but the news makes me feel quite comfortable in my methodology. Note also that within the last quarter Apple said sales for the Watch increased by 50%. This is also reflected in my estimate of 3 million in Q2 vs. ~2 million for 2016 Q2.

    Overall, about 33 million Apple Watch units have been sold since launch and they generated about $12 billion in sales. Coupled with a 95% customer satisfaction score, altogether, this has been a great success story. But only 2.5 years in, it's still act one.

    To understand the long term trajectory, it's important to qualify this product as part of another, larger story. The Watch, even with LTE, is an accessory to the iPhone. It still cannot be activated without it. Even the coverage plan is an extension to an iPhone plan. The company is careful to address it as a companion product.

    But how long will that last?

    It used to be necessary to first attach an iPhone to a computer to activate it. That used to be cited as a reason for the iPhone not being a "proper computer", diverting attention from what it would inevitably become. Those who clung to that thin wire as a reason not to face the future were deceived. The iPhone and the iPad now stand alone of any PC or Mac. Will the Watch cut these familial links and stand alone some day?

    I think this too is inevitable. The technology trajectories are easy enough to plot. Apple has invested enormously in the silicon that goes inside the Watch and has taken it to new levels of connectivity with LTE, 85% faster WiFi, and a 70% faster processor; all with 50% better power efficiency.

    These enable independent voice entry, Siri everywhere, Find My Friends, Maps, music streaming. These breakthroughs are only possible with a new W2 processor which is more powerful than the first iPhone processors.

    This comparison is apt: the Watch is effectively stealing usage from the iPhone. At first it took alerts, timekeeping, and basic messaging away. Now it's taking basic phone calls and music and maybe maps.

    It's fitting therefore to remember how the iPhone was launched; as a tentpole troika: A wide-screen iPod, an Internet Communicator and a Phone. Today the new Watch is a small-screen iPod, an Internet Communicator and a Phone.

    So not only is the Series 3 Watch more powerful than the original iPhone but it is also poetically capable of the same tentpole jobs. But it's not just a miniature iPhone. It has a new, completely orthogonal attack on non-consumption and market creation: fitness and health. This is a key point. The iPhone was born a phone but grew up to be something completely unprecedented, unforeseen by its creators and, frankly, undescribable in the language of 2007.

    The Watch was born a timepiece but it is traversing through the early iPhone and pulling in a new direction all of its own. The fact that we are talking about "Resting Rate", "Arrhythmia" and "Atrial fibrillation" at a timekeeping launch event indicates that new behaviors will follow and so will the language we'll use to describe this child-like product once it grows up.

  4. How much will the new iPhone cost?

    Research · 83 comments

    The answer, regardless of when you ask, is: The same as the current iPhone.

    Of course, this is the answer to the question of what will the average new iPhone cost. The average selling price (which combines the revenues and the volumes of all units sold and is reported every quarter) has not varied very much since early 2008. To the degree that there is variance (between $600 and $700) it is due mostly to seasonality and reflects a mix of more expensive units during the launch quarters and a cheaper units during later periods when the product is older and due for an update.

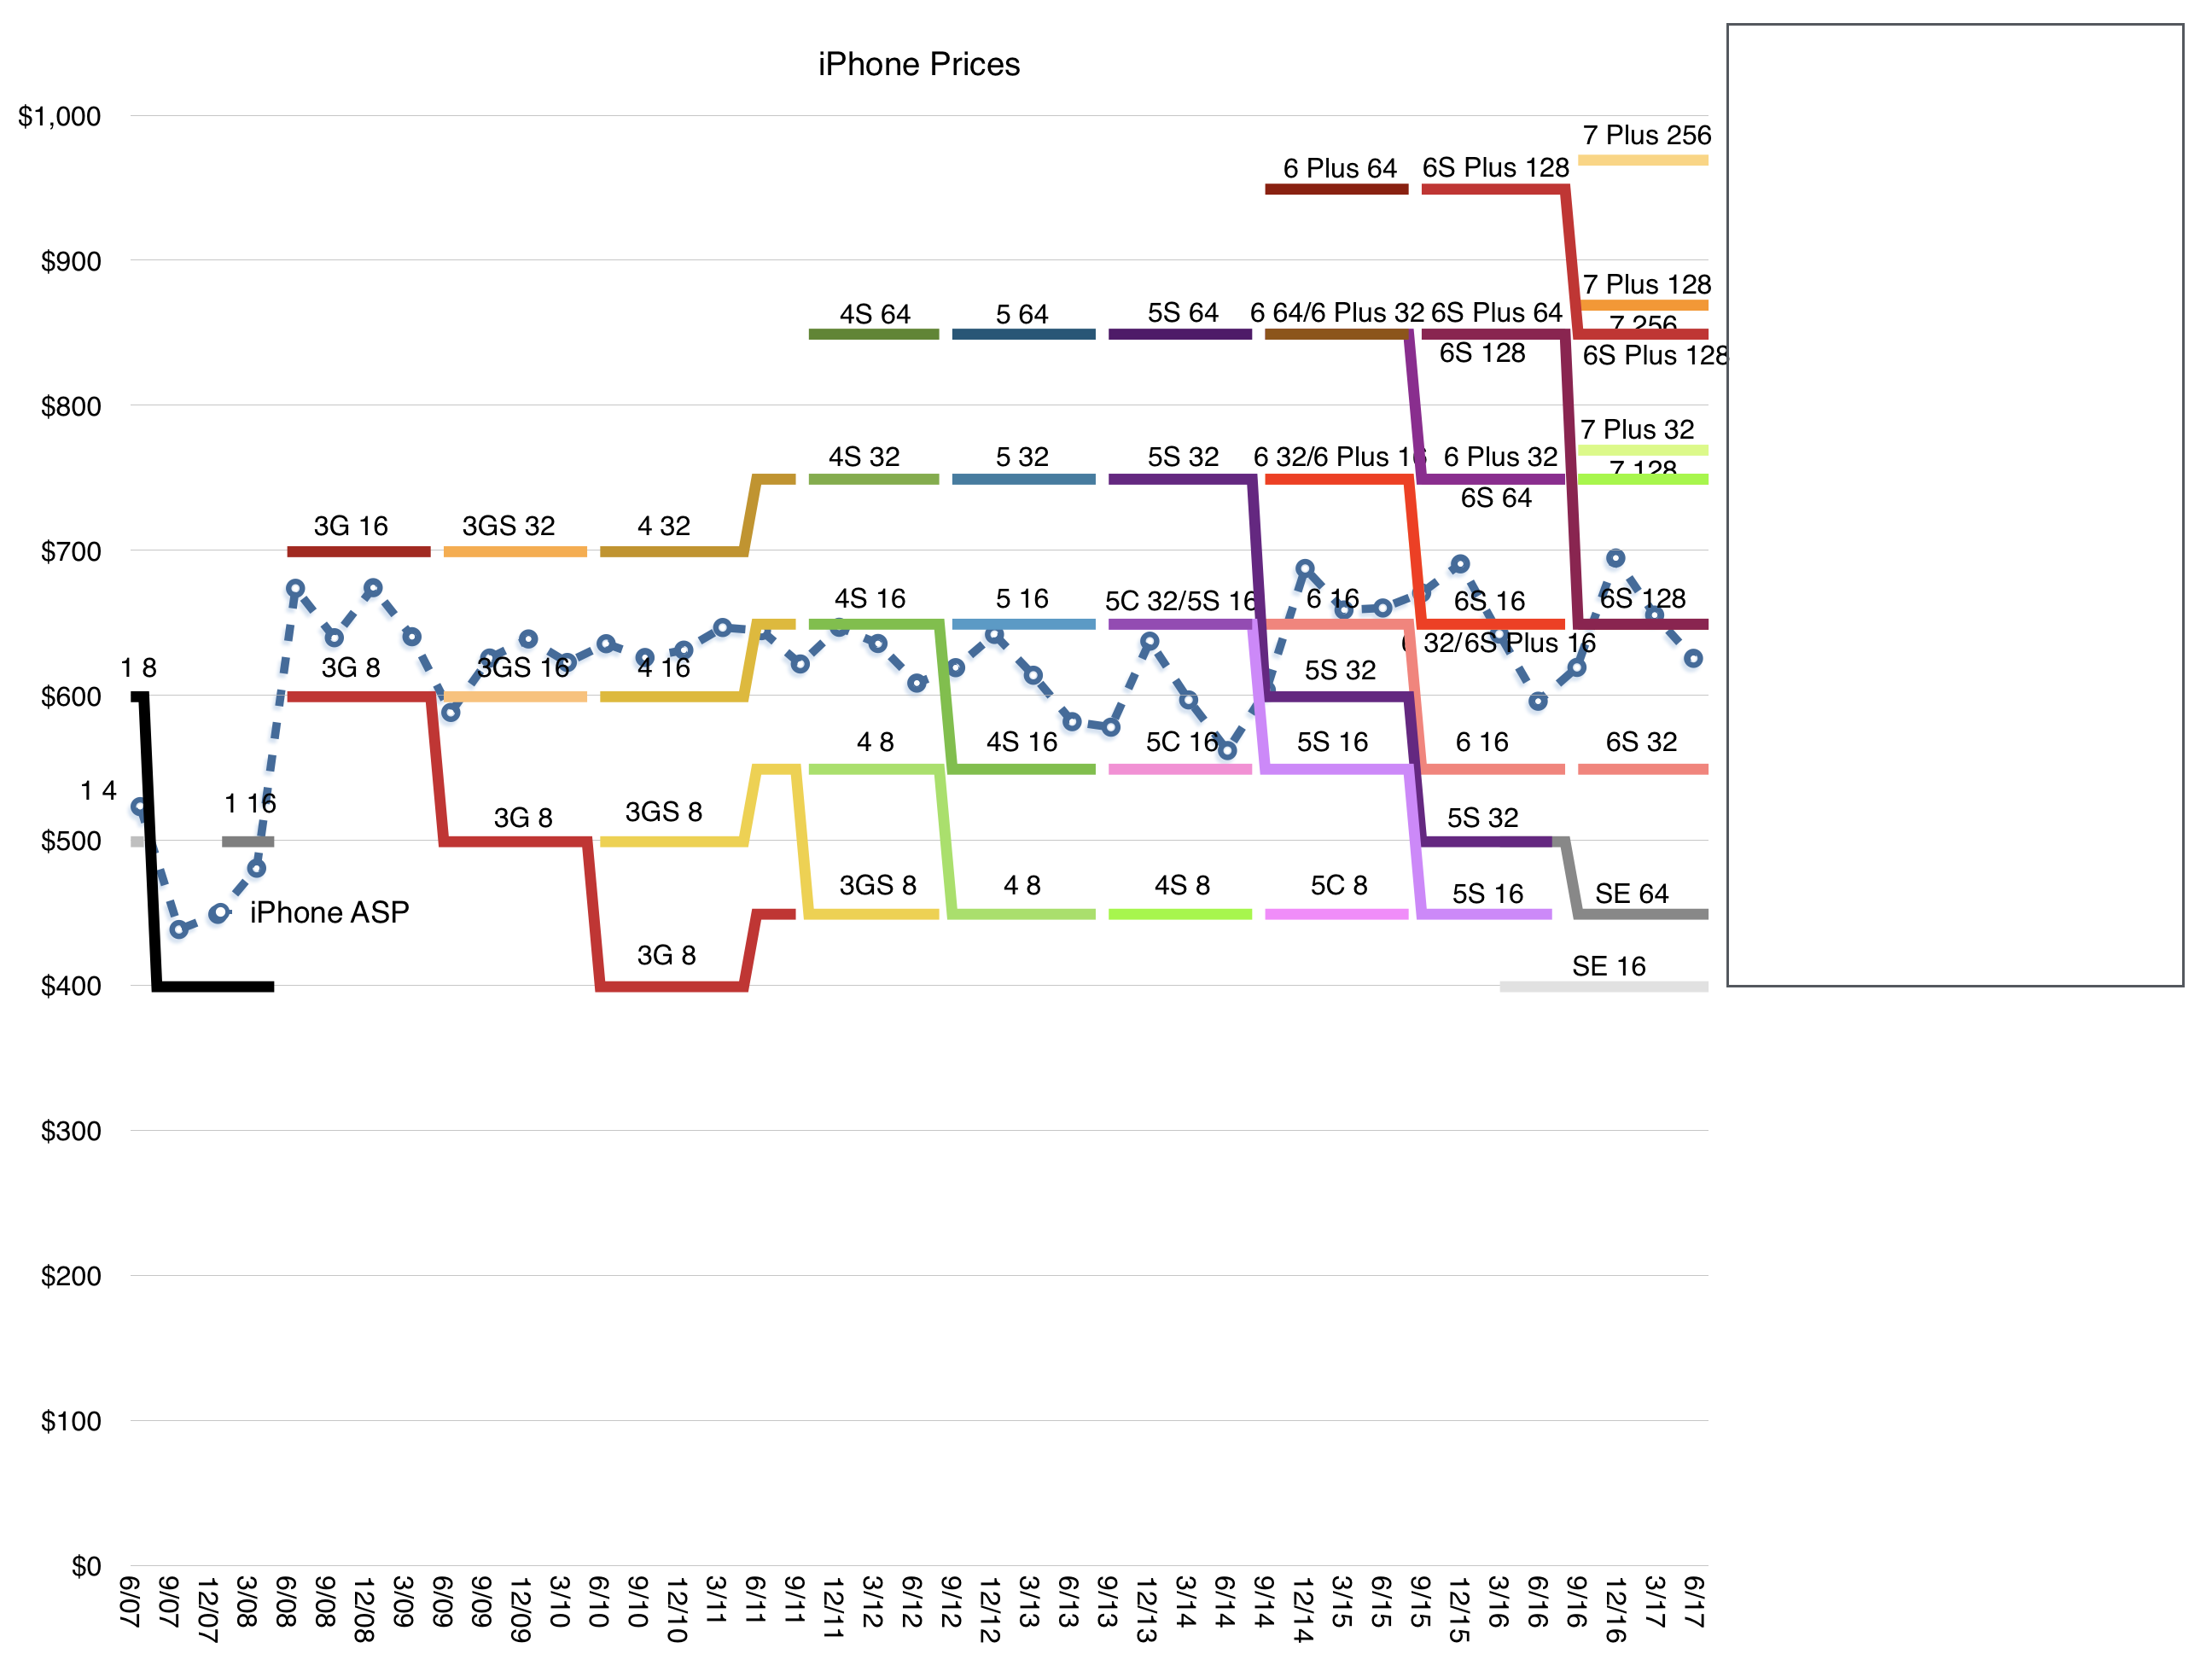
    The graph below shows the average selling price as a dashed line and the corresponding prices of individual product variants available for sale in the US during the same time frame. ((Prices outside the US vary depending on duties, taxes and currency hedging but generally are based on the US price))

    The graph shows a high degree of consistency of pattern: Every year a new iPhone is launched which replaces the one launched the year before. The older product is still offered at a reduced price. Price brackets are very firm and set at fixed intervals about $100 apart.

    A few minor changes in pattern over the years can be observed:

    • The original iPhone price changed due to a shift in subsidy model shortly after launch.
    • An increase of $50 mid-2011 when the iPhone became available unlocked.
    • Every three years a new, higher, price bracket is introduced, with a  doubling of maximum memory capacity.
    • The iPhone SE was introduced at a slightly lower price.
    • The last year saw a slight increase in the highest price.

    The overall pattern looks like a staircase with a widening price range where the lowest price remains constant and the upper price rises every three years by $100.

    The "floor" of the range is a consistent $400 while the "ceiling" has expanded from $700 to about $950.

    This year's ceiling is due for the fourth leg up and if the pattern persists, we should expect it to reach $1100.

    This iPhone staircase has been built over 10 years and I don't see it changing over the next three. I therefore drew the blank box over what I thought would be the price range from now until late 2020.

    This is what I call the staircase model of Apple pricing. The staircase model must be understood in combination with the flat iPhone average price as the product matures.

    As the product matures the user base grows (to nearly 1 billion today). Later buyers will opt for the lower price points, but the availability of higher, more aspirational models (sustained by the brand) means that a minority will gravitate upward, mainly because they can. This ensures that although the median and mode of the price trend downward, the average price stays the same.

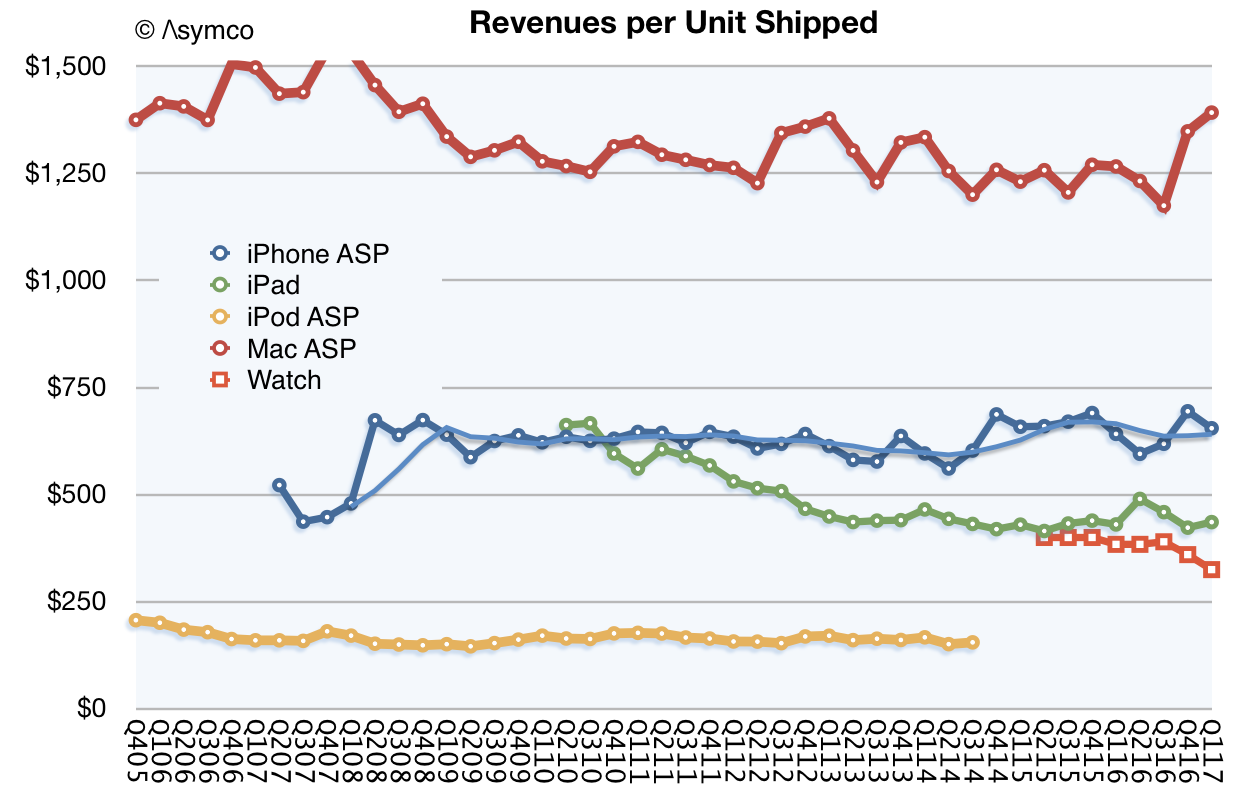
    The flatness of iPhone pricing is also to be understood in combination with the flatness of Mac, iPod and iPad average pricing (shown below)

    The technique of preservation of average price seems to be in effect across Apple. In other words, the evidence suggests that Apple prefers to keep average pricing for all products constant. Individual variants are priced so that, as the category matures, the changing mix leads to consistency in price ownership.

    Thus the iPhone can be seen as controlling the $650 point, the Mac $1200, the iPod $200 and the iPad $450. This pricing signals the product's value and the value of the brand.

    The signaling is not just to buyers but also to competitors. Ownership of price forces competitors to occupy adjacent brackets. This process begins at launch: the new Apple product is introduced in what is perceived as a premium stratum ((See for example the pricing of the new HomePod)) thus the reaction from competitors is to "undercut" it. But, as Apple climbs the price staircase, preserving the floor, it keeps competitors bunched up at the bottom. Competing in the same brackets with Apple is futile as other brands can't sustain the perceived premium position.

    The result is a remarkable consistency of average pricing which, coupled with a remarkable consistency of competitive positioning, coupled with a remarkable consistency of customer satisfaction and loyalty, leads to a remarkable predictability of cash flows and ability to invest in new product creation..

    Apple is thus quite easily understood as a remarkably consistent consumer products business. The only surprise that remains is how long it takes for that understanding to propagate.


  5. Estimating Apple's Second Calendar Quarter

    Research · 8 comments

    Apple reports second calendar quarter results in about a week. I propose the following estimates:

    Fiscal Q3 2017:
    Rev ($B) 45.321
    EPS ($) 1.62
    iPhone (units) 41 million
    iPad (units) 9.8 million
    Mac (units) 4.35 million
    Watch (units) 2.5 million
    Services ($) 7.2 billion
    Other products ($) 2.6 billion
    Gross margin (%) 38.4

    The revenue estimate is visualized in relation to guidance (revenue between $43.5 billion and $45.5 billion) and shown in the context of previous actual revenues below:p

    The estimates are also consistent with additional guidance provided:

    • Gross margin between 37.5% and 38.5%
    • Operating expenses between $6.6 billion and $6.7 billion
    • Other income/(expense) of $450 million
    • Tax rate of 25.5%

    The estimates (and guidance) suggest modest growth of 7% in revenues and 13.7% EPS. The predictability of the quarter suggests that attention will mostly be focused on guidance for the next quarter.

    Expectations can vary quite a bit because of the effects of a new launch. The product mix, pricing and timing are all unknown at this time.

    What is known however is that the customer base for Apple is increasing and loyalty is higher than ever. What I sense, coming from very few data points, is that there are more iPhones in use than ever before. A few years ago when the market was less saturated it was easy to assume that commodity Android phones and tablets would surge and swamp iPhone/iOS usage.

    This has not happened, indeed the data suggests that iOS usage is stronger than ever and that there are many more "switchers" moving from Android to iOS than vice-versa.

    This may surprise some but if we look at the PC market, a similar phenomenon has been taking place for years. Mac usage grows and Macs are more visible and valuable than PCs.

    It's important to note that in the latter, post saturation stages, the markets for both phones and computers are increasingly driven by brand value. This resistance to commoditization is due to buyers' perceptions of quality moving beyond utility and of the prioritization by buyers of new measures of performance. These new measures defy measurement.

    Much of what is therefore required of market analysts is intuition.

  6. Other Products

    Research · 6 comments

    From the way Apple reports its revenues you might think that the company has several operating segments. There are the iPhone, the Mac, the iPad for which units and revenues are reported. Then there are Services and Other Products for which we have revenues only.

    Services is a collection of all non-hardware revenues and is (finally) being recognized as a non-trivial business. With reported revenues of $26.6 billion in the last twelve months, it's big enough to be a Fortune 100 company and set to double in four years. ((Although a non-zero business, the valuation of Services continues to confound observers who cannot separate it from the hardware businesses it attaches to--which themselves are considered near commodity value--thus paradoxically valuing the overlying asset of Services near or precisely at zero. Incidentally, Facebook is Fortune 98 at $27.3 billion and it is also one of the top 5 largest business by market capitalization.))

    That leaves "Other Products" which now becomes the revenue segment that is  "most likely to be ignored." This segment had revenues of only about $11.5 billion in the last 12 months which would place it at only a Fortune 245 ranking, equivalent to a Toys "R" Us or Biogen. How should we value Other Products?

    Other includes many hardware products including iPod, Apple TV, Beats, Apple Watch, AirPods and, soon, HomePod. Each is a significant product, with Watch probably the largest single contributor. But since we don't have specific unit numbers, we are left guessing at the contribution of each.

    The Watch itself has been a point of scrutiny as it could be initially teased out of the mix through an observation of the before-and-after launch vs. trend-line as shown below:

    This separation of Watch became harder to discern after the launch of AirPods. Though they are still very hard to obtain, they might be "moving the needle" by now with a contribution that would muddy the Other category further. Same with updated Beats headphones.

    This separation will be harder still with the launch of HomePod later this year. This product is priced at a point similar to the Watch and the quantities sold will be very hard to estimate without Apple's revealing of actuals.

    Fundamentally however, all the "Other products" will have a common relationship to the iOS and MacOS hardware: attachment to and integration with a "parent" platform. Apple TV might be stand-alone but I strongly doubt there are many sold into offices or households which don't have iOS usage.

    This means that "Other Products" are very similar to "Services" in that there is a dependency on a primary platform and, as it has been argued, they are therefore fragile. If the core platform declines then the Services and Other Products decline as well.

    Given this dependency it makes little sense to carve these categories out as separate businesses. They cannot stand alone. They are very much the "children" of the parent platforms.

    This is why it's assumed that Services, (a Fortune 100 company) and Other Products (a Fortune 250 company) can be discounted to zero. By focusing attention on the iPhone one can capture all the essential value of Apple. This is in contrast to the "sum-of-parts" valuation that could be applied to a set of independent business units in other companies.

    And yet I started this discussion with the point that you might be tempted to look at Apple on the basis of these reported revenue segments. The choice of what Apple reports is arbitrary. It could report no segment revenues at all and publish just one revenue number. This is roughly what Google Amazon and Facebook do. Or it could report segments in some other way. For instance, app store revenues and AirPods could be reported as part of "The iPhone Division". Or maybe it could bundle all iOS devices and services and accessories into another segment called "The iOS Group". Or it could create a "Devices group" and a "Personal Computing" group. Microsoft famously shuffles its revenues into creative segments based on various organizational structures or choice of what it wants to project as its focus.

    There is no limit to the ways Apple could slice revenues into segments. The reason Apple does it the way they do is mostly due to historical reasons. The company used to report the iPod separately as a segment but it no longer does. It also used to report Software separately, because, presumably,  it charged for it but now it no longer does. It also separated laptops or portables from desktops.

    The current reporting system is tempting us to draw certain "business unit" conclusions. These boundaries are illusions because Apple does not have business units. It has only one Profit and Loss statement (P/L) and is organized functionally. There is no "head of iPhone" or "head of Mac" responsible for each siloed revenue and cost structure. Instead, the entire business should be seen as a whole because it is managed as a whole.

    This is easily evident in how the products are designed and marketed and how they are engineered. The iPhone may spawn AirPods and AirPods may have no value outside the iPhone but the iPhone is valuable precisely because it has AirPods and Apps and Music and iCloud. And Apple TV, and HomePod and whatever comes next. The reason the iPhone can be sold at three times the price of competitor products is because of the Services and Other Products and iPad and Mac symbiosis. This integration drives the satisfaction, loyalty, price and brand value. There there are the Apple Stores and the launch events and the countless details that make up the ownership experience.

    The fact is that you can't slice and dice Apple.

    There is one Apple and it must be analyzed as a unitary entity. That analysis is therefore difficult. It is easy to pick up the numbers given and study them in isolation. The iPhone, the iPad, the Mac. We all do that.. However we miss a great deal in doing that.

    The lesson is that data we obtain leads us to see something but it also blinds us by taking attention away from what we cannot see. All data lies by omission. That which is left unmeasured may be where all the truth lies.

  7. App Story

    Research · 21 comments

    The App Store is almost 9 years old. In that time it has generated about $100 billion in revenues, of which about $70 billion has been passed on to developers and $30 billion was kept by Apple. It's very likely that running the App Store for 9 years did not cost $30 billion so, if it were an independent "business unit" it would probably have been and still be quite profitable.

    But Apple does not run "business units" with separate Profit and Loss statements. The App Store is a part of Services which is an amalgamation of non-hardware sources of revenues but that does not mean it's a business. The purpose of Services isn't to turn a profit or define its value through some metric of financial performance.

    The purpose of Services is to make the experience for the Apple user better. The combination of good experiences allows Apple to be perceived as a valuable brand and that allows it to obtain consistently above-average profitability through pricing power. I like to emphasize that the iPhone at over $600 in average price is more than twice the average price of all the other smartphones and captures over 90% of all available profits.

    This is something that remains after a decade and indeed the price is rising in the face of overall price erosion, all without a decrease in volumes. The sustainability of this exceptionalism is due to no one single thing. It's due to the persistence across all the things Apple does: product, stores, software and services and many other details too numerous to count.

    The result is a large and expanding base of satisfied customers and a large and expanding base of partners both in hardware and software and services. The WWDC event this year showed how the ecosystem of Apple is booming with over 3 million new developers and Keynote screenfuls of partnerships. All this makes for a complex picture but it's a real picture.

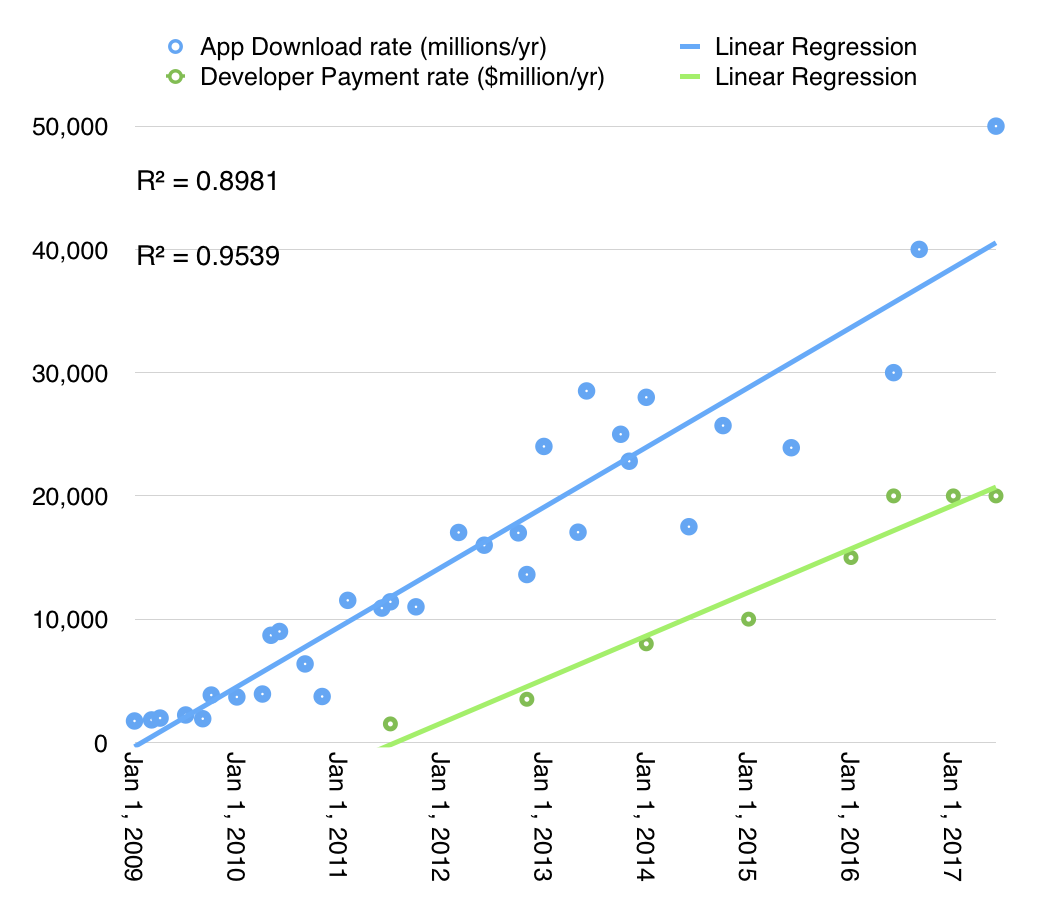
    The latest numbers on Services try to tell this story: 180 billion App downloads from 500 million App store weekly visitors. The download rate is accelerating as shown in the following graph:

    The revenue or payment rates can also be shown as accelerating though at a different rate. In both cases, the story of apps is not yet over, regardless of commentary to the contrary. Much of this growth comes from new markets like China and as India joins the iOS world, there is yet more opportunity emerging.

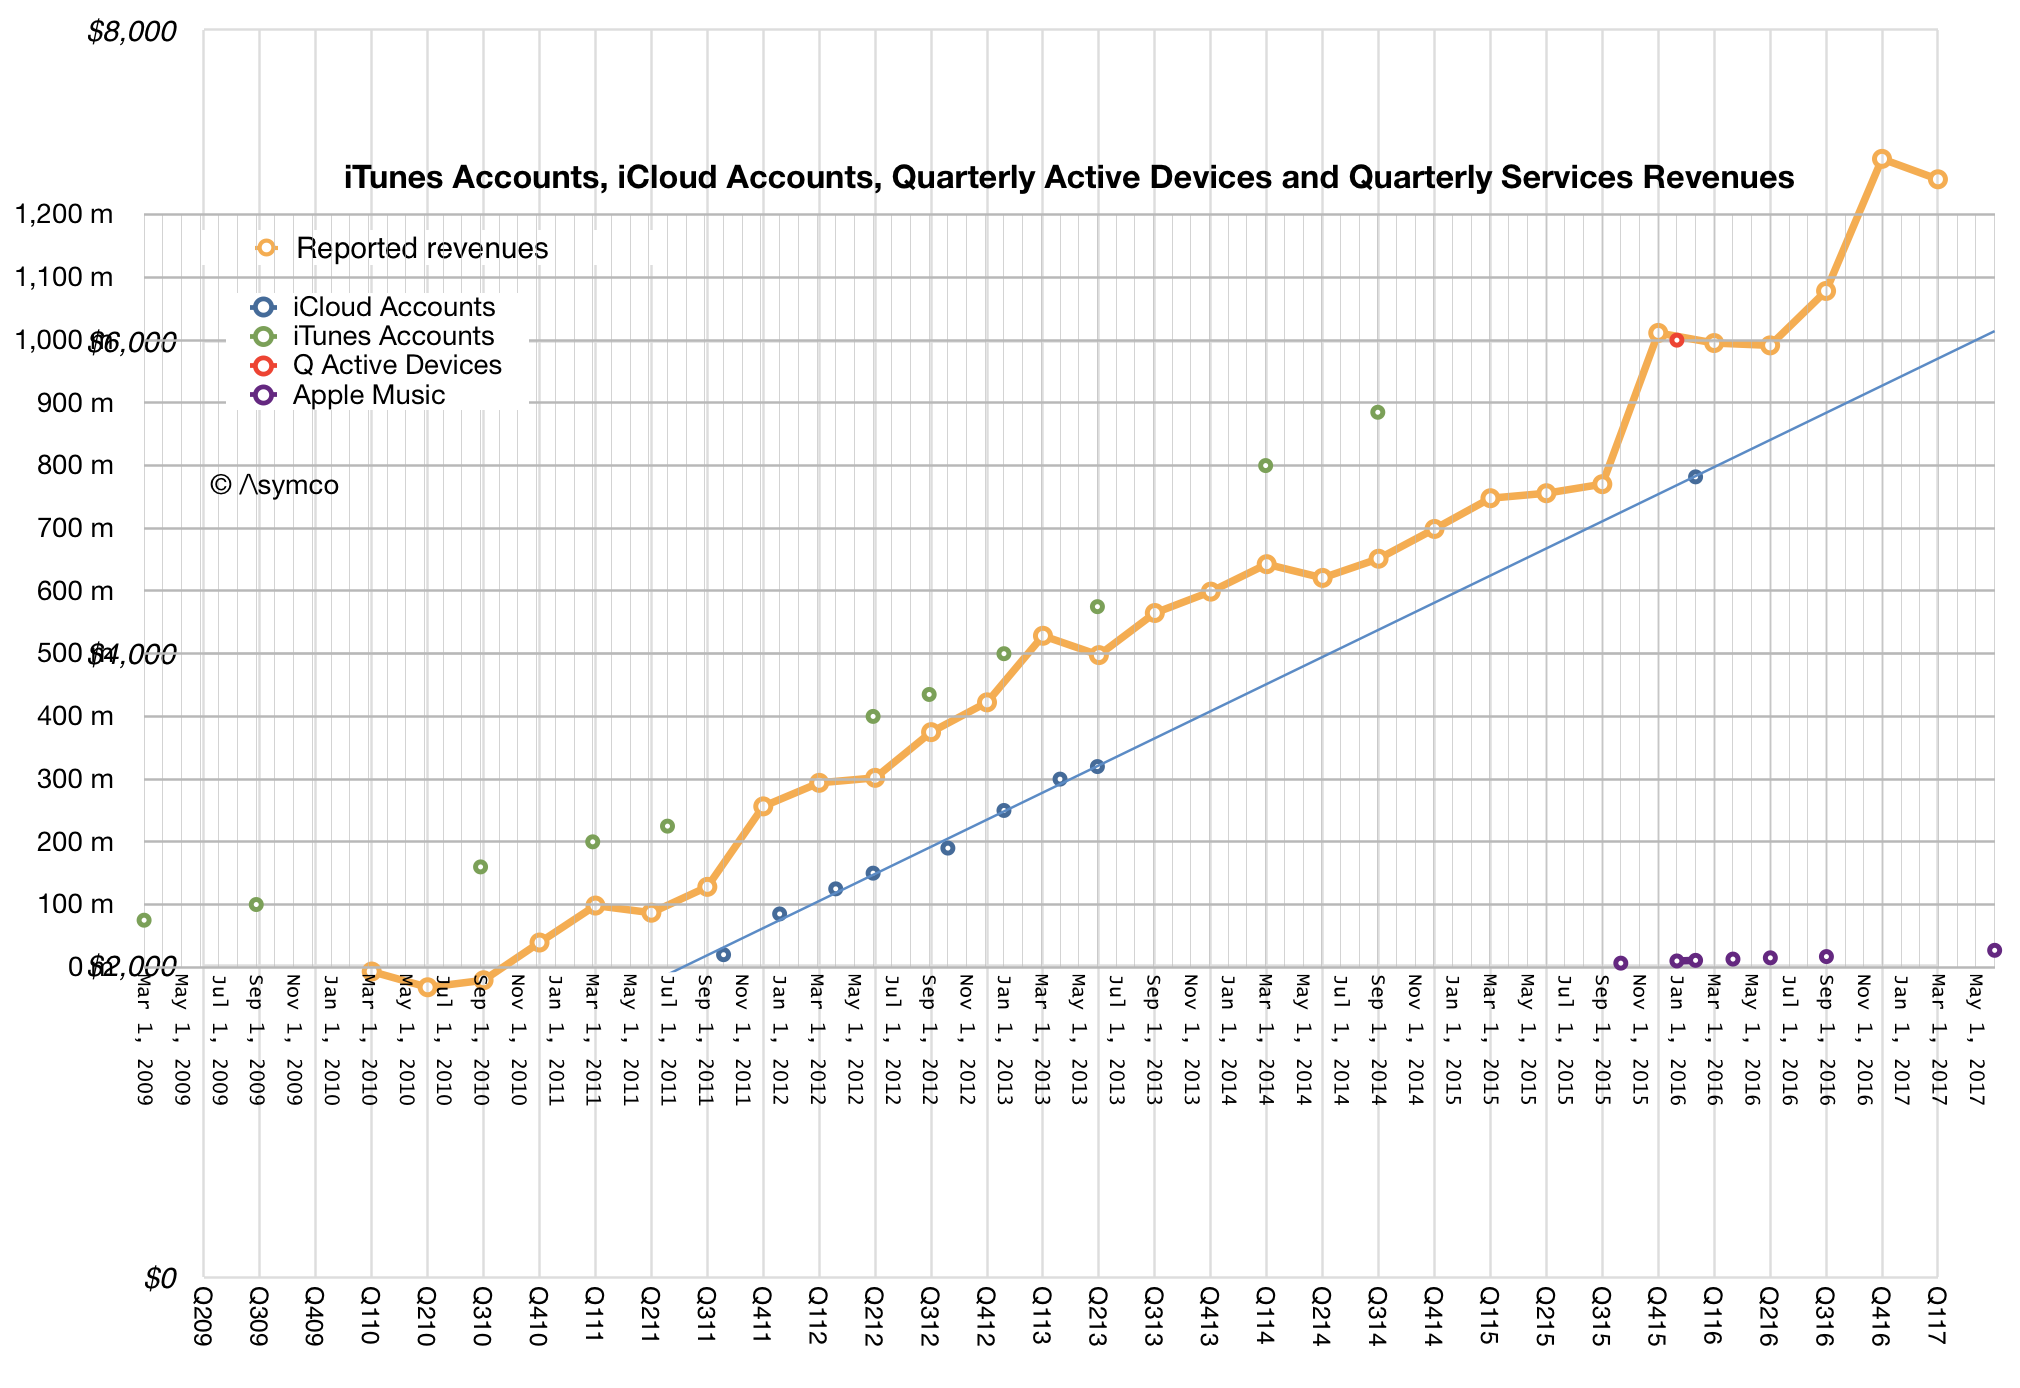
    This enables part of the story of Services which can be tracked with several other metrics: reported revenues, iCloud accounts, active devices, and iTunes accounts are highly correlated.

    The patterns after a decade are remarkably consistent. One would have thought that with mobile saturation in advanced markets, the content story would be told through horizontal lines. What we still see is the same slopes we've seen since the earliest days.

    But the biggest story at WWDC was the re-design of the App Store as a curated content market. The changes are profound: discovery, curation and the surfacing of content have been revamped. It's hard to predict the implications of this but one of the indications of direction was the separation of "Games" from "Apps". This is a jarring idea since if all Apps are content, what makes Games different from other Apps? Is this a genre elevated to a new medium?

    I can't yet get a sense of where this is heading, if anywhere, but the remarkable story of Apps is that it's still an ongoing story. We may be on chapter 2 and we can't predict how many chapters remain.

    Keep an eye on Apps and Services and developers. They are not lagging indicators of success for Apple. They are very much leading.

  8. Predictably Profitable, Unpredictably Valuable

    Research · 11 comments

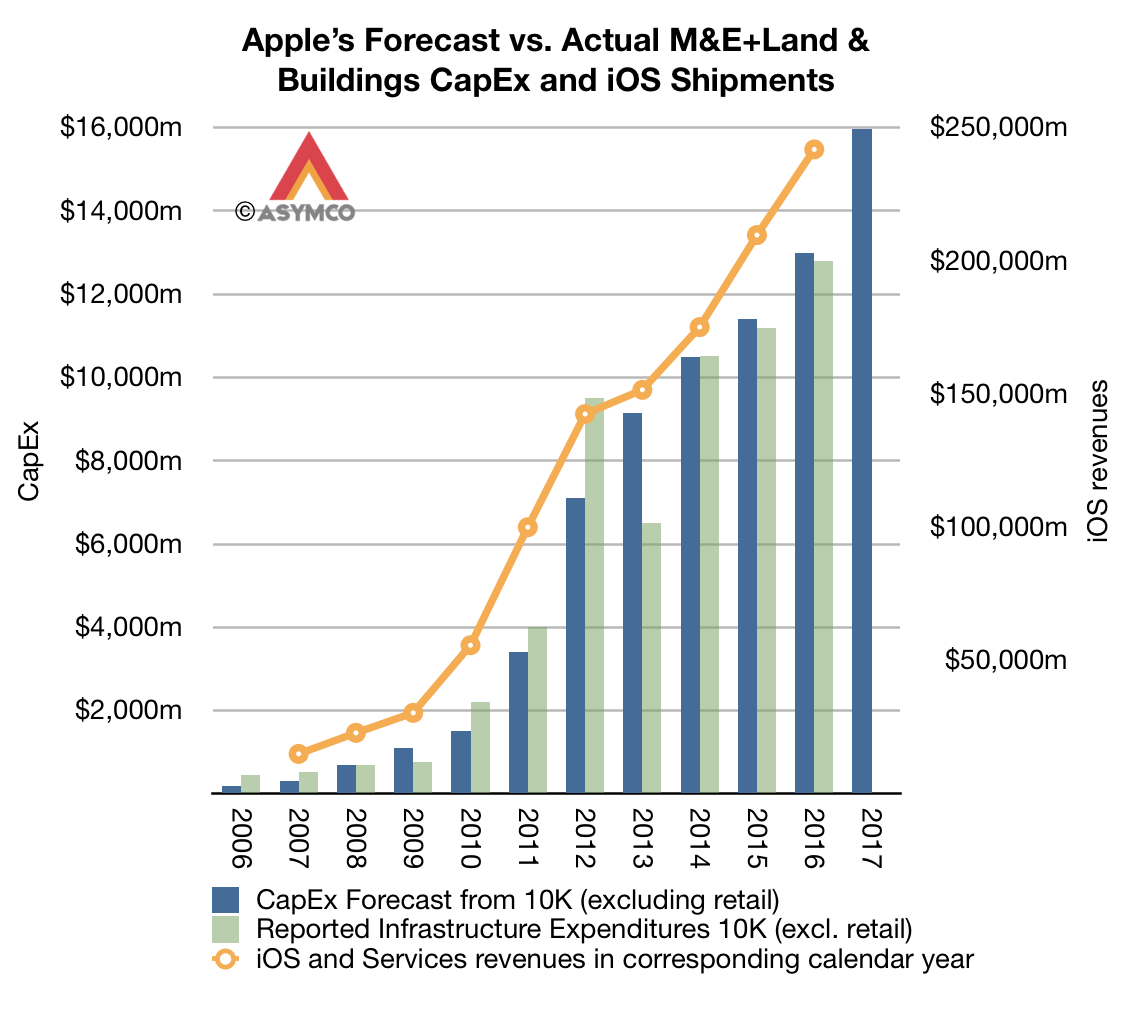
    Predicting Apple's yearly revenues has been fairly easy. The following graph shows the relationship between budgeted spending on Machinery, Equipment, Internal-use software, Land & Buildings and the shipment of iOS device revenues.

    The company conveniently publishes a full-year forecast of these expenditures every fiscal year so by October we know roughly how sales will be during the following year. This pattern has held for 10 years so there is little uncertainty about the 11th year of iOS devices.

    Although the two are not very tightly coupled, there is a causal link between them: spending on machinery and equipment for production leads to more production which leads to more sales (assuming prices are stable--which they are).

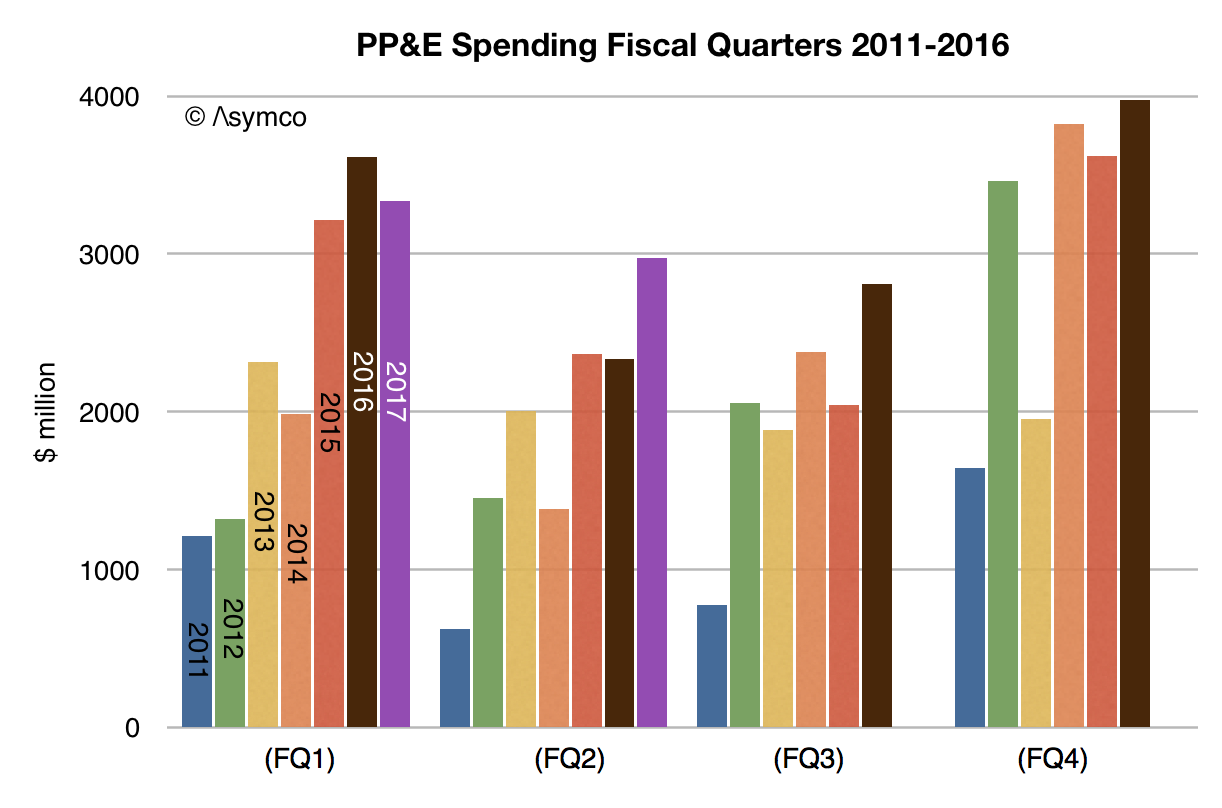
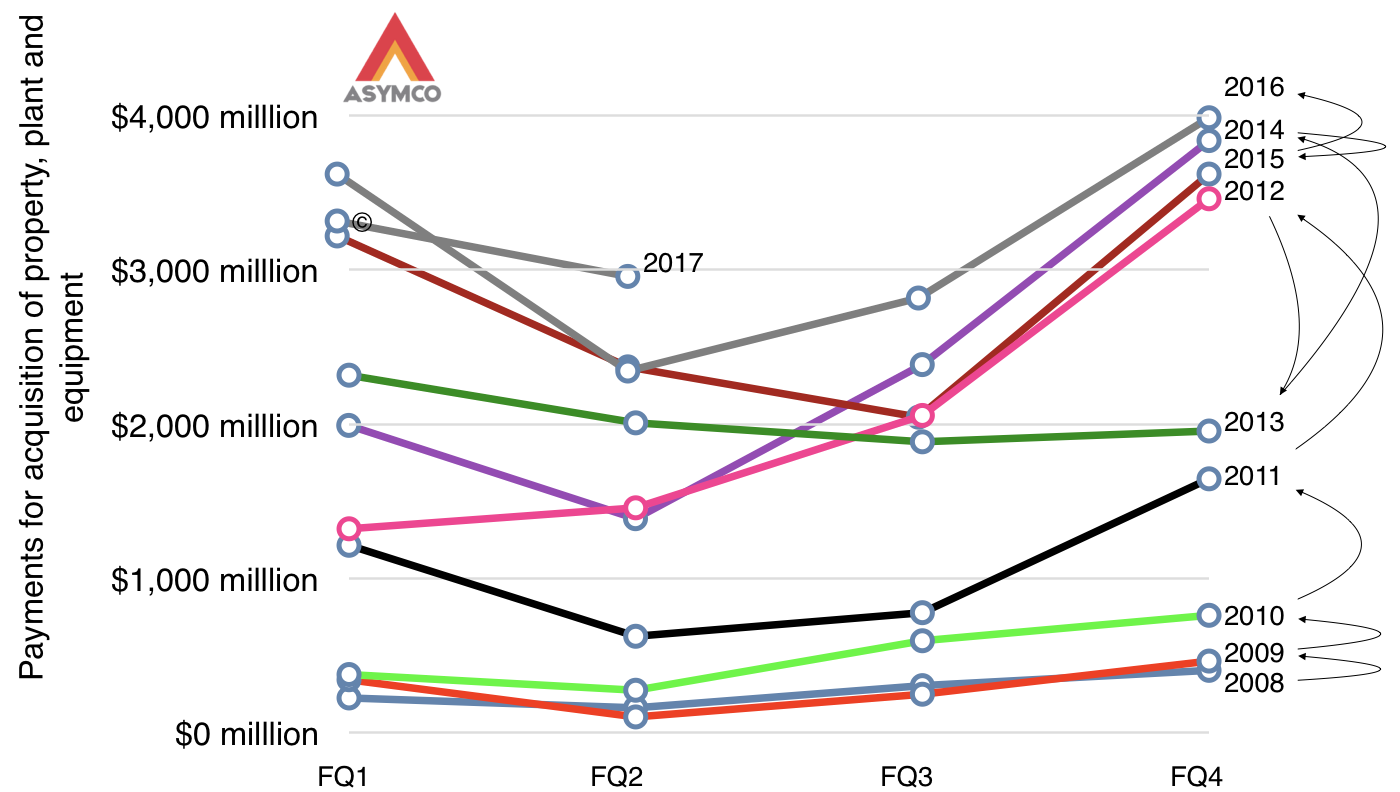
    We are, as of the time of writing, half-way through a fiscal year and the quarterly spending can be inspected for any surprises. None are evident as the second fiscal year (first calendar quarter of 2017) shows a new high in capital spending at nearly $3 billion, placing us on track for the surge into the production of the new iPhone (and iPads.)

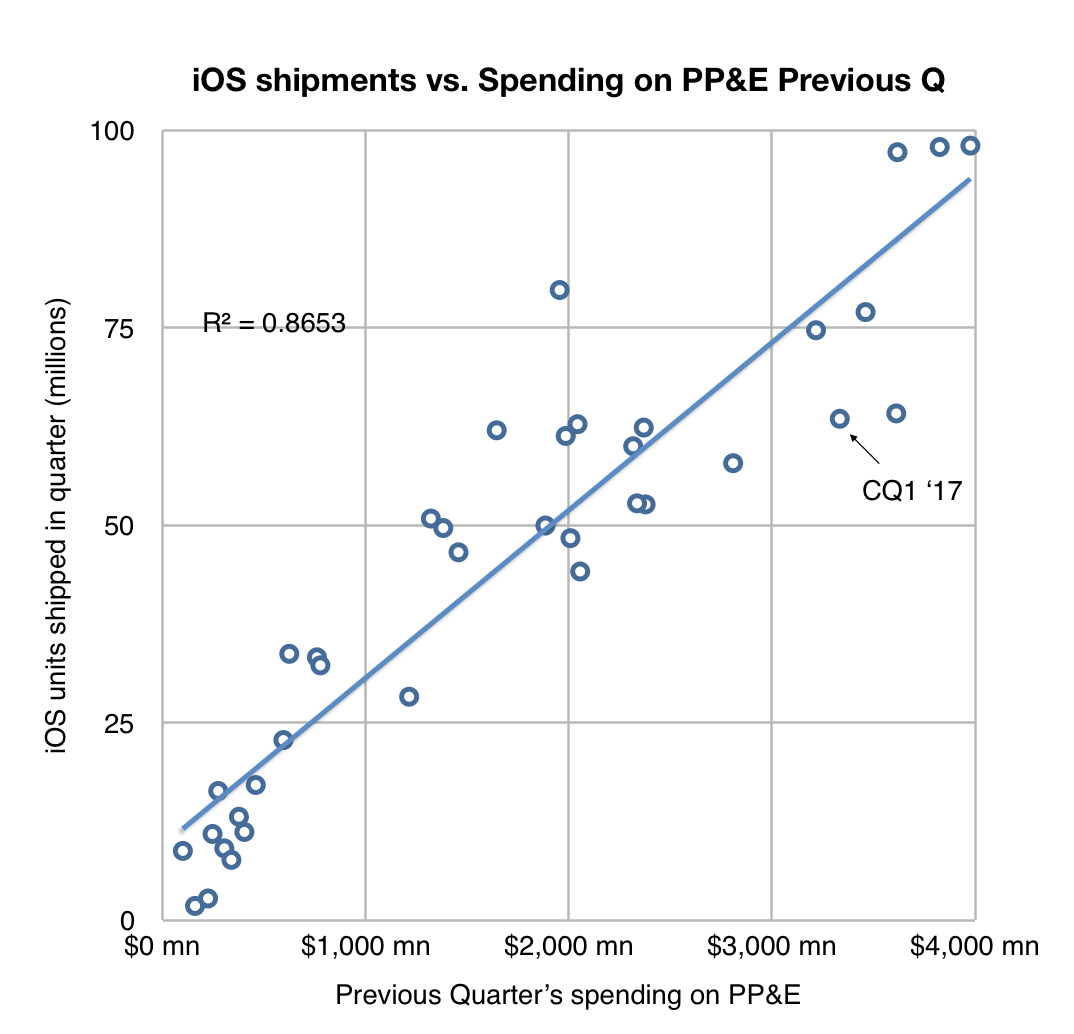
    The quarterly relationship between sales and spending is less precise as equipment buying is "front-loaded" into a production cycle but there is a strong correlation nonetheless.

    When looking through the data, quarter after quarter, year after year, there is a consistency and reliability to the spending/revenue relationship which implies, to me at least, a high degree of certainty.

    This predictability, however, has not detracted from the volatility in Apple's share price--an instrument designed to embody precisely this prediction.

    Apple's share price continues to see swings of more than 70% in any given 52 week period. In the latest 52 week period the shares traded between $89.47 and $154.88, a 73% swing.100% is not unheard of. Incidentally, S&P 500 volatility ranges around 45%. Apple is by far the largest company in the world and fairly old by large company standards. It should attract a certain premium of stability.

    And yet it doesn't. Skepticism around the company is continuously evident. It's in the headlines written every day which concoct convoluted reasons to doubt future performance. It's in the conversations I have with investors who question the tiniest of details in the design of a product (like headphone jack or home butto) in order to gauge their impact on the survival of the firm. It's in the continuous parade of "disruptive entrants" or "established giants" ready to knock the company off its perch by virtue of simply existing.

    Perhaps the panic it induces in investors with its reliable profits is Apple's most predictable attribute.

  9. Predicting The Second Quarter

    Research · 51 comments

    The last quarter of 2016 was Apple's biggest ever. $78.4 billion in revenues. 78.3 million iPhones. Both records. Earnings of $3.36 ((On shares priced at the time around $105 or 3.2% yield quarterly earnings)) and cash reached new highs. The growth was modest but Services is now not just the second largest revenue but also the fastest growing, on track to doubling in four years.

    The reason for this is the vastness of Apple's user base coupled with the loyalty the brand engenders. The company reached one billion active devices more than a year ago and is quite likely to have nearly a billion users. Not just any billion either--the best billion most probably.

    The realization that Apple benefits from extreme quantity and quality of customers has led some observers to defer the imminence of Apple's demise. Share prices have risen lately to new highs and the ratios between these prices and earnings have started to come closer to the average of other large companies.

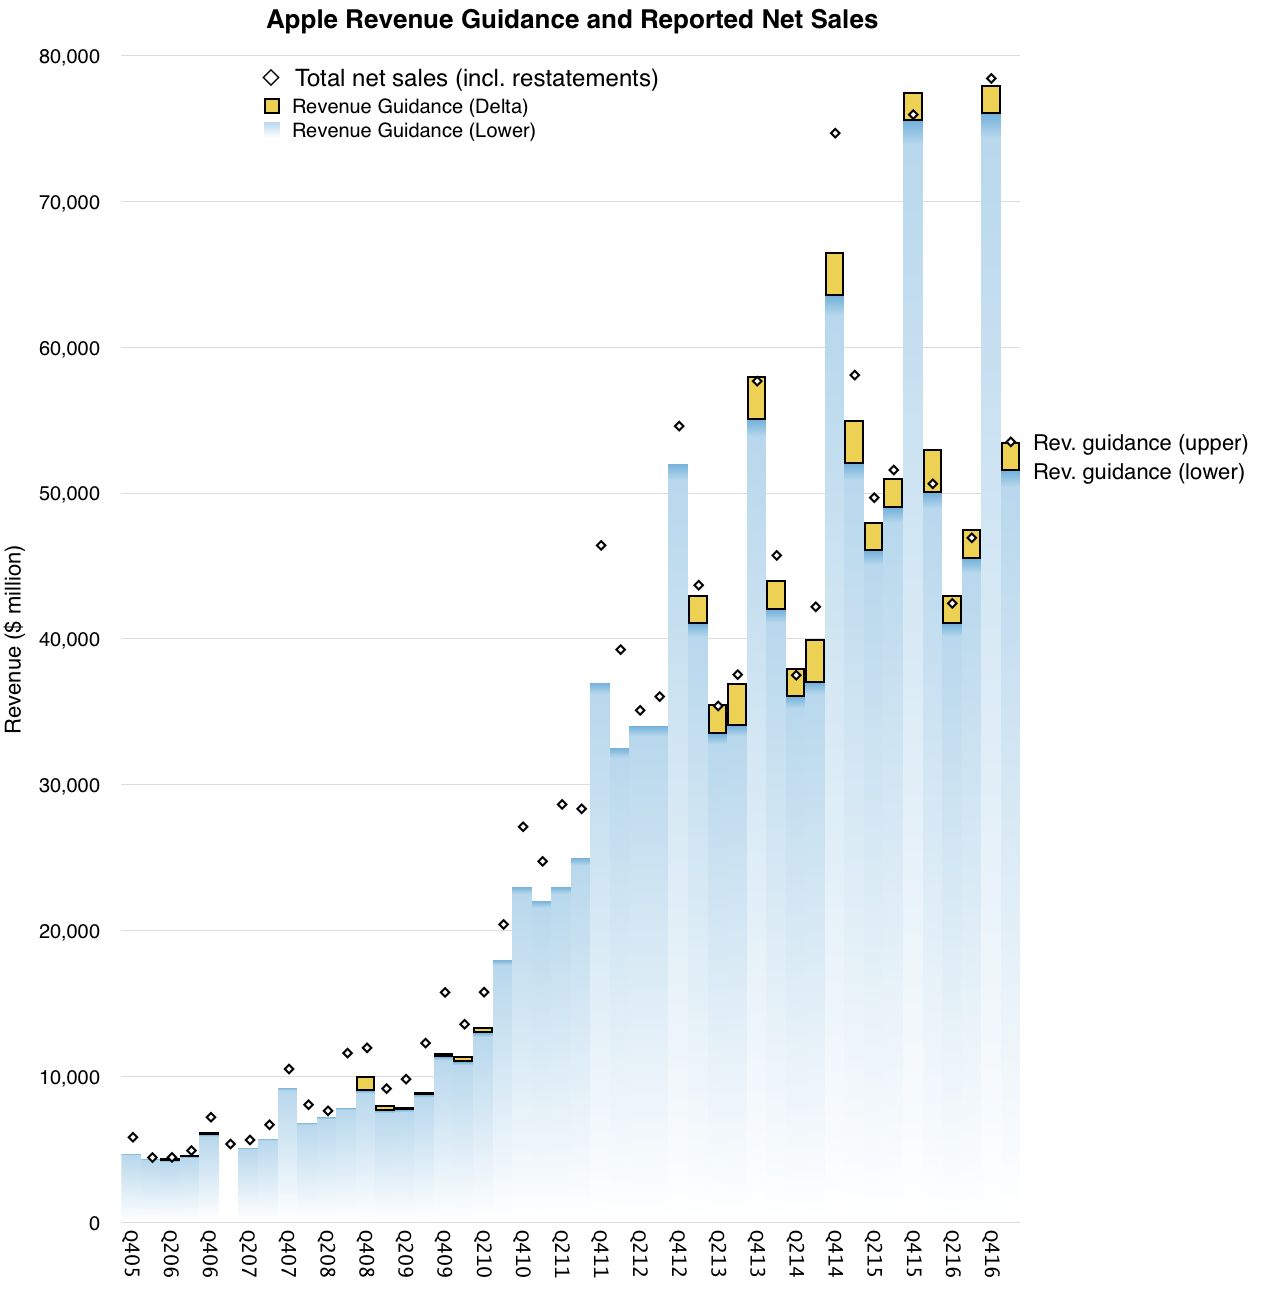
    But enough with the reductio ad absurdum. Let's look at the next quarter. The company has been very precise with its own offered predictions (guidance) so it's a simple task to make an accurate forecast. The history of guidance vs. outcomes for revenues is shown below:

    Placing the pipper on the upper edge of the guidance range was a safe targeting method for 11 of the last 17 quarters. We have never seen a drop below the bottom of the range but had a few overshoots, some huge. Doing this for the latest quarter and working backwards to the individual product contributions to revenue and using historical margin and cost patterns we can get the following core financial performance metrics:

    Fiscal Q2 2017:
    Rev ($B) 53.4
    EPS ($/share) 1.96
    iPhone (thousand units) 53100
    iPad (thousand units) 9900
    Mac (thousand units) 4100
    Watch (thousand units) 2300
    Services ($ million) 7129
    Other products ($ million) 2300
    Gross margin (%) 37.8

    I sent these estimates to Philip-Elmer DeWitt and I recommend looking at his survey of the other analyst estimates on his excellent Apple 3.0 blog.

    Overall, the quarter is shaping up to offer slight growth y/y and indicating a plateau formed after the surge from the iPhone 6 surge in '15. All eyes are on the "super cycle" for the next iPhone.

    The reason it's "super" is that the iPhone has a 2+ year cadence for form factor changes and the user base updates on a similar cycle. The demand is vast due to the user base and accumulated age of devices in use. Expectations are that supply will be offered to meet this demand.

    If history is a guide then the next iPhone will be the best iPhone ever.


  10. Contact Less

    Research · 21 comments

    In September 2016 Apple Pay came to support the world's largest public transit system. It happened through the integration with Japan's FeliCa and gave Apple Pay access to 160 million daily transactions.

    This, along with many other milestones don't get a lot of attention. Apple Pay is in what could be considered an attritional competition with non-consumption. There are no decisive battles won or lost, only the relentless pressure to make progress against a reluctance to change.

    Before I go on, I should make the attrition/decisive type of conflict clear. The terms come from military science. A war of attrition is one where two sides essentially grind against each other and the winner is the one which lasts longest. A decisive battle is one where a conflict is won through a single, acute encounter where, due to either demoralizing or circumstance reasons, one side gives up. It's the knock-out punch vs. the fight to exhaustion.

    When applying this dichotomy to competition, we need to be careful about who we define as competitors. Note that I said that Apple Pay is in a fight with non-consumption. It's tempting to say Apple Pay competes with some other payment system like Samsung Pay or Google Pay. But none of these alternatives are as powerful as the existing mix of contact payment systems: cash, credit card magnetic swiping and some other hybrid of codes and user experiences (especially online.)

    When seen this way the challenger must compete through persistence. It's impossible for Apple Pay to decisively defeat non-consumption in one battle. It takes literally millions of decisions for adoption: each consumer, each merchant, each bank, each point of sale. It's a relentless grind of pitching, selling, demonstrating and shaming into action.

    It's been three years of this type of competition and progress may seem hard to spot. That is because we don't see the big wins. We can only see small wins. The win in Japan, as significant as it might be (160 million daily transactions added to the addressable market) is still small compared to all transactions world-wide.

    Merchants tell Apple that 90% of contactless transactions in the US were Apple Pay. Apple sees continuous growth and cited 500% grown y/y in payments last quarter. The total amounts to hundreds of millions of transactions worth billions of dollars.

    Anecdotally, the points-of-sale supporting the system are growing. 76% of the top US merchants have agreed to deploy by end of this year. ((Note that that does not mean 76% of all points of sale will have it but rather the commitment at the top is there.))

    But the total market is probably measured in billions of transactions and trillions of dollars. There is a lot to go.

    On the bank side, the US wins came quickly and thoroughly. 3500 US banks support Apple Pay through their issued credit cards. Globally the figures are unstated with some countries absent completely and others engaging quickly. Australia lags while the UK is mostly on-board.

    The point of sale terminals are also largely not an obstacle with the current generations almost all being able to process contactless transactions. The amazing thing about this business is just how many sides there are to this market: merchants, users, Apple, banks, POS terminals, credit card companies, online payment systems, etc.

    To see progress at all is surprising. Changing payment systems is extremely complicated due to the breadth and depth of infrastructure. There are already 5 million contactless acceptors in the US. But there are many more points of sale ((How many exactly is actually hard to determine.)) There is a long tail distribution for these systems so saturation will take a very long time.

    Apple Pay is however only the first battle. Beside credit cards and cash, inside your wallet are more items that need to move into your devices: access cards, passports, driver's licenses, IDs.

    One unsung hero has been the device-based boarding pass. Security and gate agents don't touch your phone so when you are invited to place the phone on the scanner at security or boarding, there is a sense of tangible and visible progress.  It was a rare sight a few years ago but I see it more and more each day I fly. The paper-less boarding pass has crossed the chasm into mainstream. Cash, plastic cards and IDs will also be deprecated. All it takes is persistence and time.

    We all crave decisive battles and can't stay tuned for the attritional outcomes. Nonetheless that is how most conflicts end up. This is the sort of conflict where a superpower wins and an asymmetric challenger falters. It's resources and processes rather than enthusiasm that matter most.


  11. iPad Optics

    Research · 33 comments

    The iPad has an installed base of over 300 million. This is a far larger audience than that of the Mac (which has somewhere between 100 million and 150 million). And whereas the iPad acquired this audience in about 7 years, the Mac took 33 years.

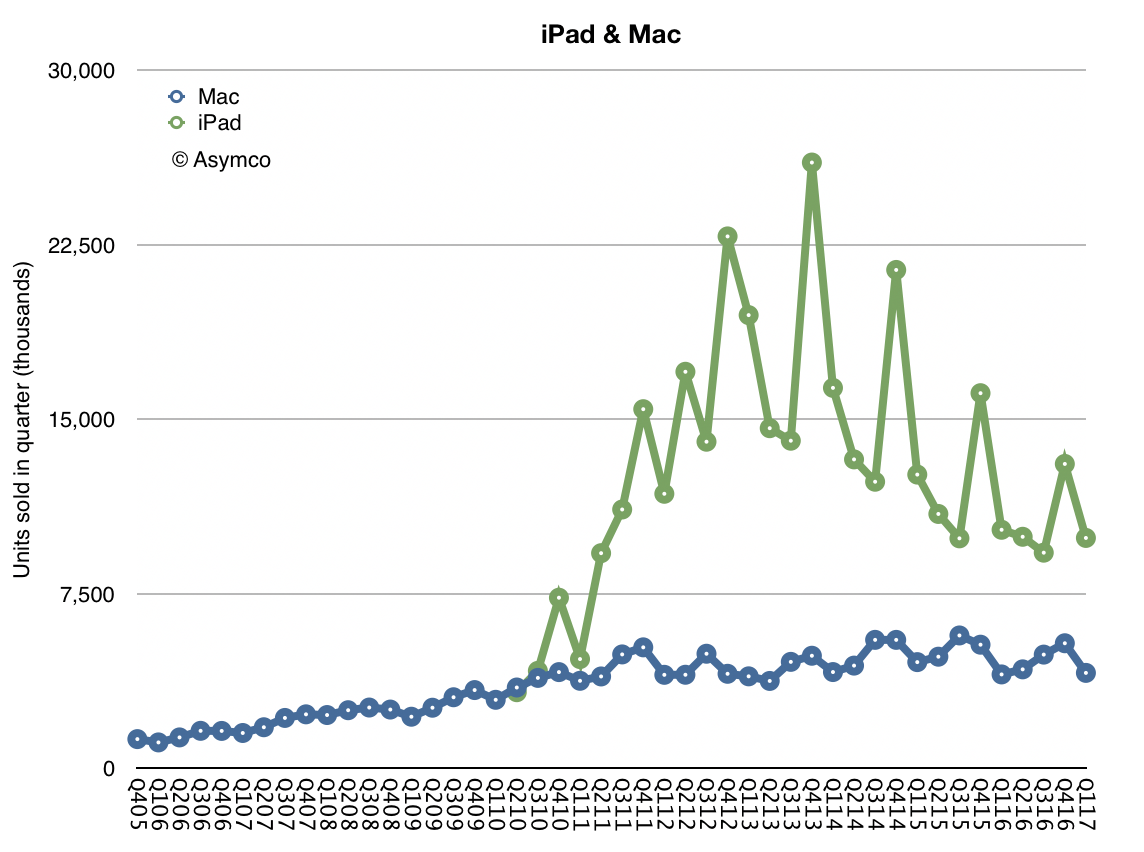
    Curiously however, it is the iPad that is seen as the more fragile product. The iPad is considered to be failing, with a presumption of an end of life in the near future. The evidence of this failure the year-on-year decline in units sold. This is illustrated by the following graph. 

    Screen Shot 2017-03-23 at 10.05.21 PM

    Note that the iPad decline is paired with a steady increase in the Mac. The iPad exhibits a four year decrease in overall volumes. This has, as they say, bad optics.

    But what is seen isn't all that might be,

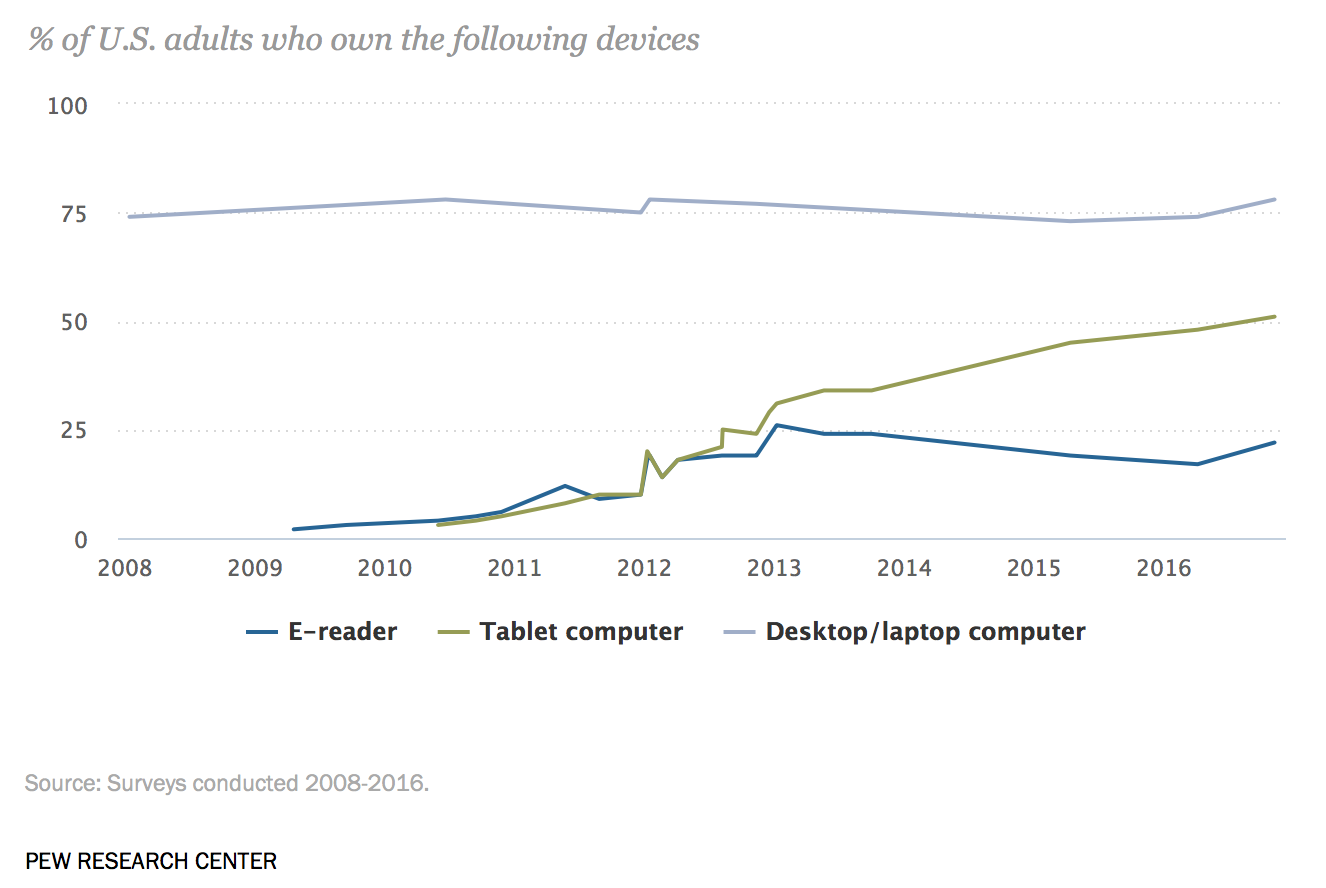
    If we look further we see that the iPad is still a much loved and much used product. Data from the Pew Internet Survey shows that tablet ownership among US adults increased from 45% in April 2015 to 48% in April 2016 and 51% in November 2016. The rise has been steady. Although this counts tablets, the iPad had 85% share of the U.S. market for tablets priced above $200 so it's a fair assumption that the iPad audience is growing. Similar data exists for the UK.

    Screen Shot 2017-03-23 at 10.11.50 PM

    In addition, user satisfaction with the product continues to be very high. Apple cited that in November, 451 Research measured a 94% consumer satisfaction rate for iPad Mini, a 97% rate for iPad Air, and 96% for iPad Pro. Finally, browsing, shopping and app usage data also show continuing high utilization for iPads.

    Furthermore, iPads are still growing in "non-consuming" markets. iPad posted double-digit growth in both Mainland China and India, it continues to attract a very high percentage of first-time tablet buyers.

    Finally, within corporate buyers there is a 96% satisfaction rate with 66% purchase intent. Apps and solutions are continually being developed for the platform.

    Taking into account that the iPad has a large, stable, engaged and loyal user base that continues to expand and find new uses the optically bad sales data needs an explanation. The simplest explanation is probably the best: iPads remain in use far longer than phones, and perhaps even longer than some computers.

    Anecdotally we can see evidence for this. Few iPads are replaced every two years the way phones are. They are not tied to service contracts or subsidized. They are also less likely to be damaged during usage as phones are dropped and banged-up. iPads are more stationary or carried in protected containers. Phones are in pockets, iPads are in bags.

    So iPads are longer-lived products and it's perfectly reasonable that people who have them keep using them and more people are joining them but slowly. Note also that the decline in sales seems to be flattening out and perhaps might show stabilization.

    Further countering of the iPad in decline idea is the continual improvement in the product. The latest is a refresh of the iPad with more battery life, a better screen and support for Pencil.

    Perhaps the iPad will not return to rapid growth, or perhaps it will. But the more likely possibility is that the iPad will level out maintaining steady levels and, perhaps, grow slightly. This flat rather than up/down trajectory is unusual in devices but it isn't when you look at the Mac. And isn't the goal of the iPad to become a computer?  If so then perhaps Mission Accomplished.