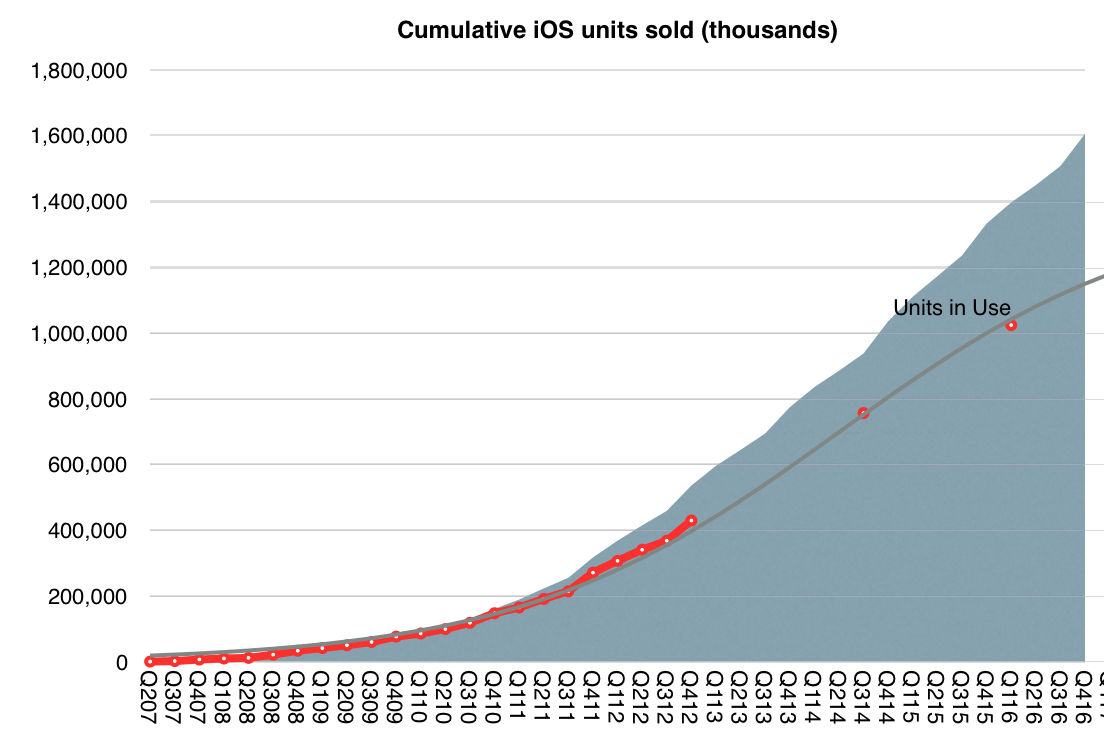
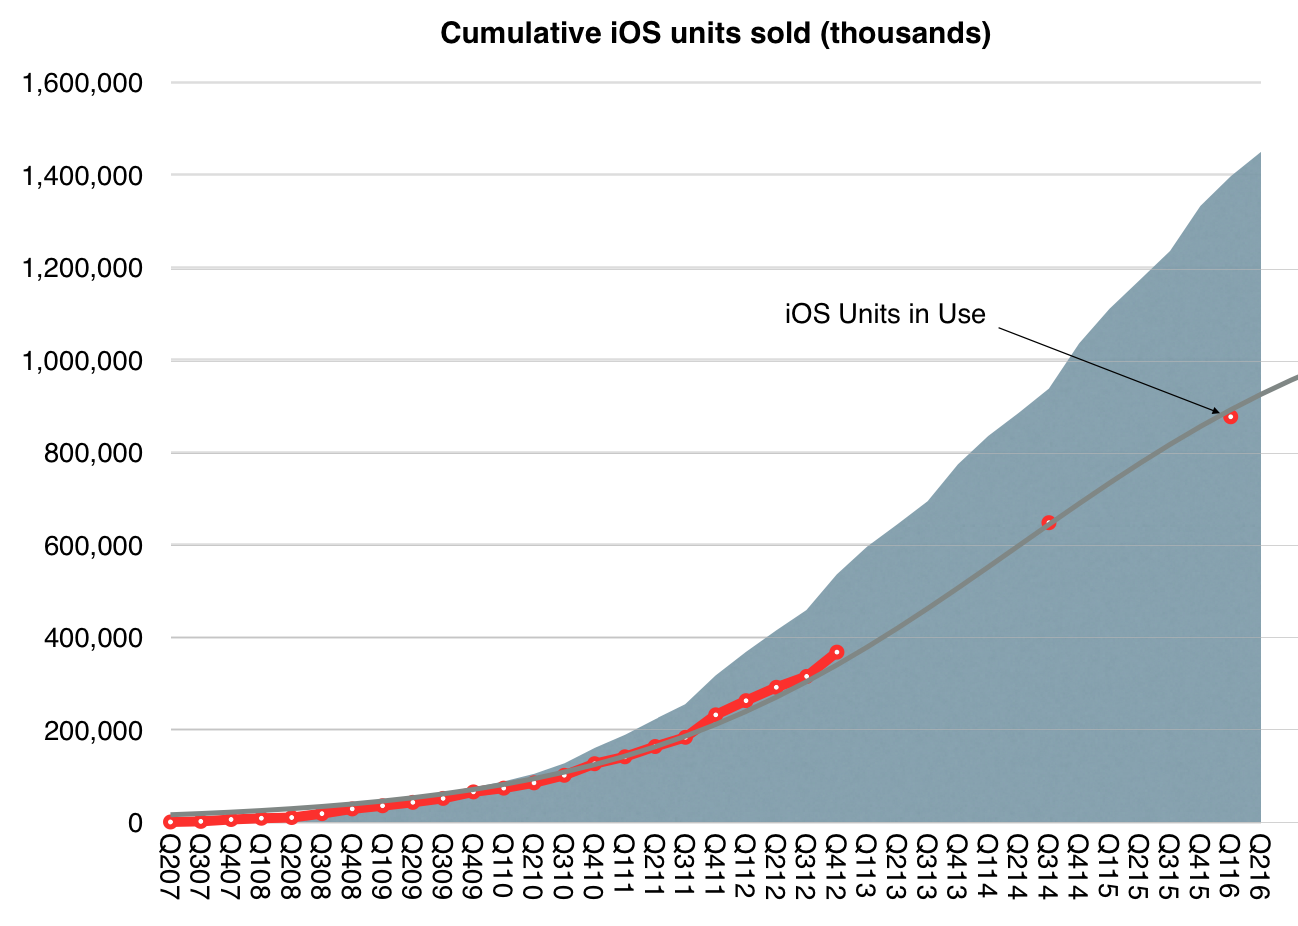
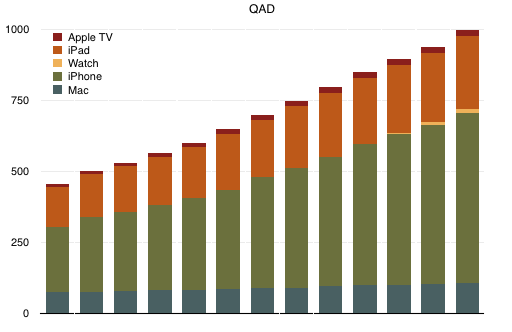
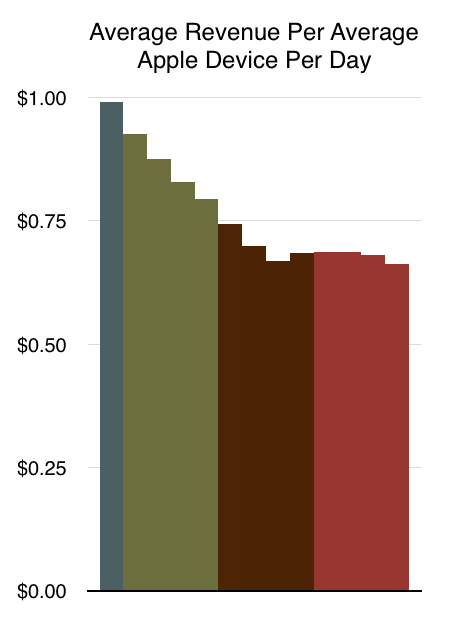In its first 10 years, the iPhone will have sold at least 1.2 billion units, ((Includes forecast for first six months of 2017)) making it the most successful product of all time. The iPhone also enabled the iOS empire which includes the iPod touch, the iPad, the Apple Watch and Apple TV whose combined total unit sales will reach 1.75 billion units over 10 years. This total is likely to top 2 billion units by the end of 2018.
The revenues from iOS product sales will reach $980 billion by middle of this year. In addition to hardware Apple also books iOS services revenues (including content) which have totaled more than $100 billion to date.
This means that iOS will have generated over $1 trillion in revenues for Apple sometime this year.
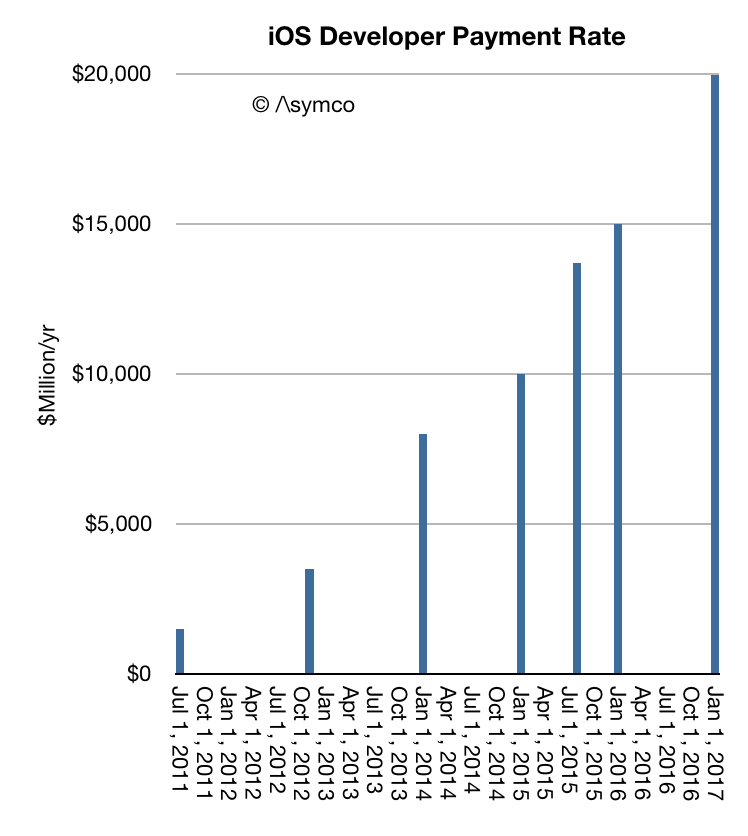
In addition, developers building apps for iOS have been paid $60 billion. The rate of payments has now reached $20 billion/yr.
Not included in this payment total are "mobile-first" or "mobile mainly" businesses such as FaceBook, Twitter, Linkedin, Tencent, YouTube, Yahoo, NetEase, Pandora Radio, Google Search, Baidu, Google Maps, Gmail, Instagram, Amazon, eBay, JD.com, Alibaba, Priceline, Expedia, Salesforce and Other Enterprise Software, Ride Sharing Apps, AirBnB and many other services which monetize independently of the App Store.
I estimate that the cumulative revenues enabled by iOS across these businesses have exceeded $500 billion, with a rate of revenue soon to reach $300 billion/yr.
The revenue numbers can only hint at the change in behavior among users. An iPhone is unlocked 80 times a day. Assuming 600 million devices in use there are 48 billion sessions on iPhones every day. 17.5 trillion sessions every year. It is these instances of interaction and engagement which are desired by all businesses built on top of the ecosystem.
These instances of engagement must be multiplied by the quality of the customers which Apple captures. iOS users spend more and are more loyal than those on alternative platform thus qualifying the platform as "premium" and thus adding to its value in the eyes of developers, content producers and service providers.
As the install base of iOS increases and as users hire the devices to do more and spend more time with them the virtuous cycle of value creation will continue and accelerate.
There is a temptation to think that such a business is fragile and will be disrupted. Challengers appear daily and the number of iPhone "killers" is not measurable. One can cite the billion users of Nokia phones which defected. One can cite the loyalty of BlackBerry users that evaporated. One can even cite the juggernaut of Windows and how it became impotent. One can cite the vast number of Android devices offered at low prices.
But there are reasons to believe that the iOS empire is far stronger and resilient.
Unlike Nokia's phones, Apple's product is an ecosystem with network effects and dependencies on software and services. It's also a monolithic product with a singular interface and form factor.
Unlike BlackBerry, the iPhone does many jobs--too many to count. Indeed the iPhone evolves and changes its core value over time.
Although different in many ways from Windows there are strong similarities in terms of loyalty and persistence of users. iOS even developed a dominant position in enterprises. Microsoft's attempt to become a hardware company is a testament to the confluence of the two business models.
And whereas Android was originally seen as the "good enough" iPhone, potentially disrupting it, it turns out to be the ersatz iPhone. Chances are higher that users will switch from Android to iPhone and not the other way. Again, the reasons have more to do with the ecosystem and quality of users (which are hard to measure) than with the hardware (which is easy to measure.)
As we look toward the second decade of the iPhone, the expectation isn't one of another "big bang" but a process of continuous improvement. The market is nearing saturation so the goals must be to capture more switchers from Android. Apple has achieved this with the Mac: survival, persistence and eventual redemption.
More exciting is the apparent expansion of a network of ancillary "smart" accessories. The Apple Watch, the AirPods, Pencil and possible new wearables point toward a future where the iPhone is a hub to a mesh of personal devices. The seamless integration of such devices is what has always set Apple apart.
Managing the Mac product line must be one of the most challenging problems at Apple. That may not be obvious given the product's success. Consider what it has achieved:
The product is in its 32nd year of market presence. A longevity that in unmatched by any other PC maker.
Apple reached a top five position in the ranking of PC vendors. This was achieved for the first time only this year, far along in the evolution of the market.
With about $23 billion in revenues per year, Apple places among the top four PC vendors in terms of revenue.
With an estimated $5.5 billion in operating margin Apple is the most profitable PC vendor, capturing over 60% of the available PC hardware profits.
The product has retained an average selling price of over $1200 for at least a decade. At the same time the average pricing of Personal Computers has more than halved.
Although volumes have fallen for three quarters, the product grew volumes and sales for 22 out of 29 quarters. As a result, volumes almost doubled in eight years. ((The unit volumes in third quarter 2008 were 2.6 million. Eight years later they are 4.9 million and could easily be over 5 million in the holiday quarter.))
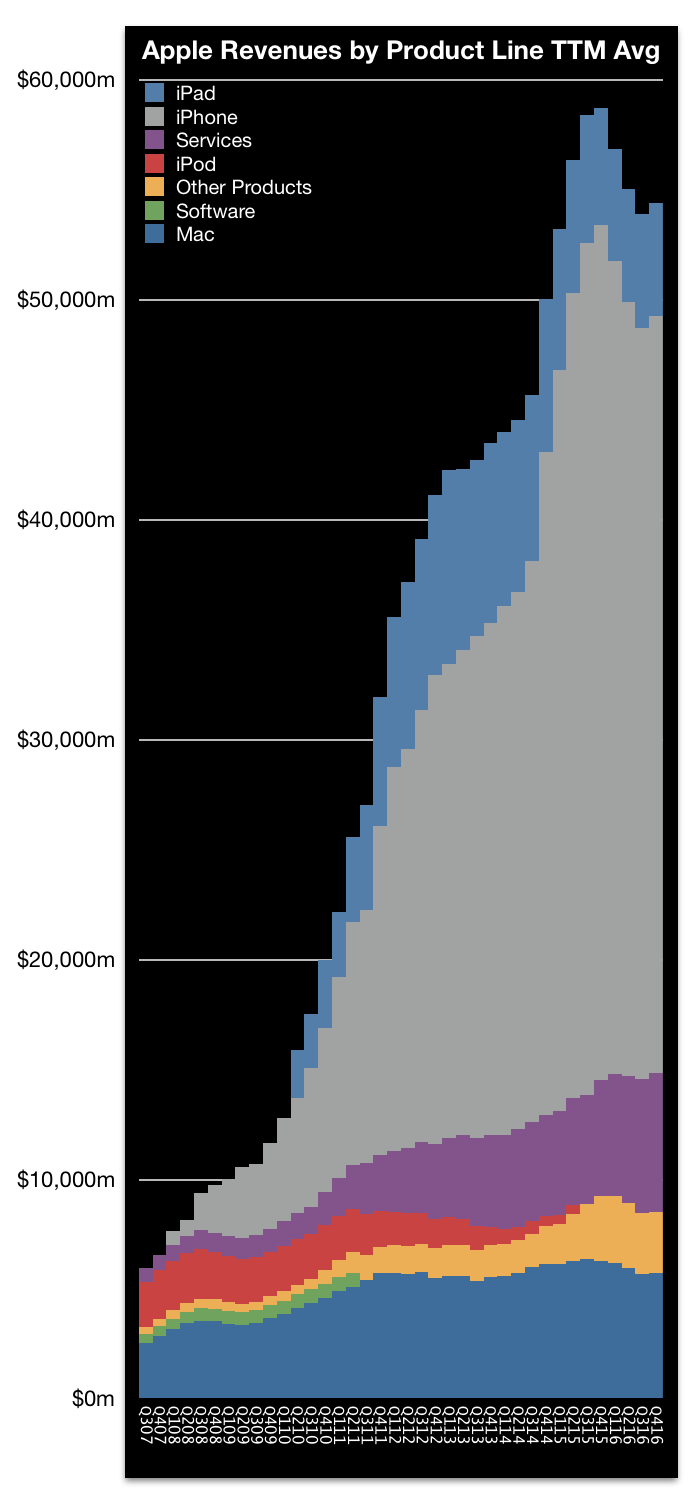
The contribution of the Mac to Apple's revenues is shown in the following graph.
It's attractive and convenient to contrast the Mac with the rest of the PC industry. A David vs. Goliath tale of redemption. The classic comeback story. But the split between the two old rivals (Windows/MacOS) focuses the mind into a limited view of the computing market. The big change in computing has not been a growing Mac vs. declining PC. It has been a huge surge in mobile device use vs. a decline in PC use overall.
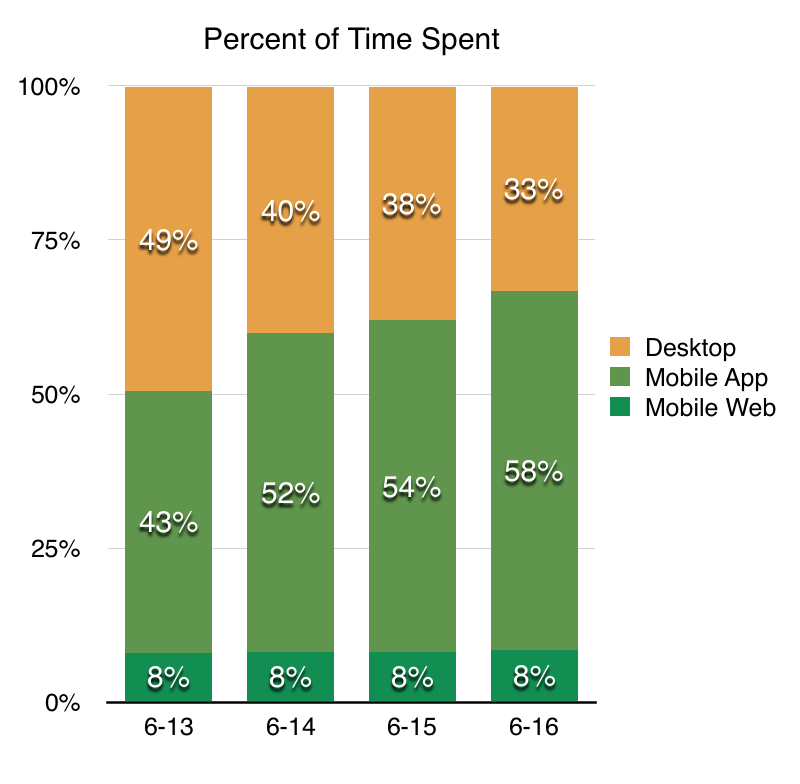
This data is visible in many ways. Browsing data shows mobile overtook PC use this year. Shopping data around Black Friday points in the same direction. Data on user interaction captured by comScore is shown below ((Although US only, the global picture is likely to be even more skewed toward mobile as PC didn't saturated global markets before the smartphone swept to power.))
PC use went from half to a third of time while mobile went the other way: from a third to half of time within only four years. All the data is consistent: mobile use has swept PC use aside.
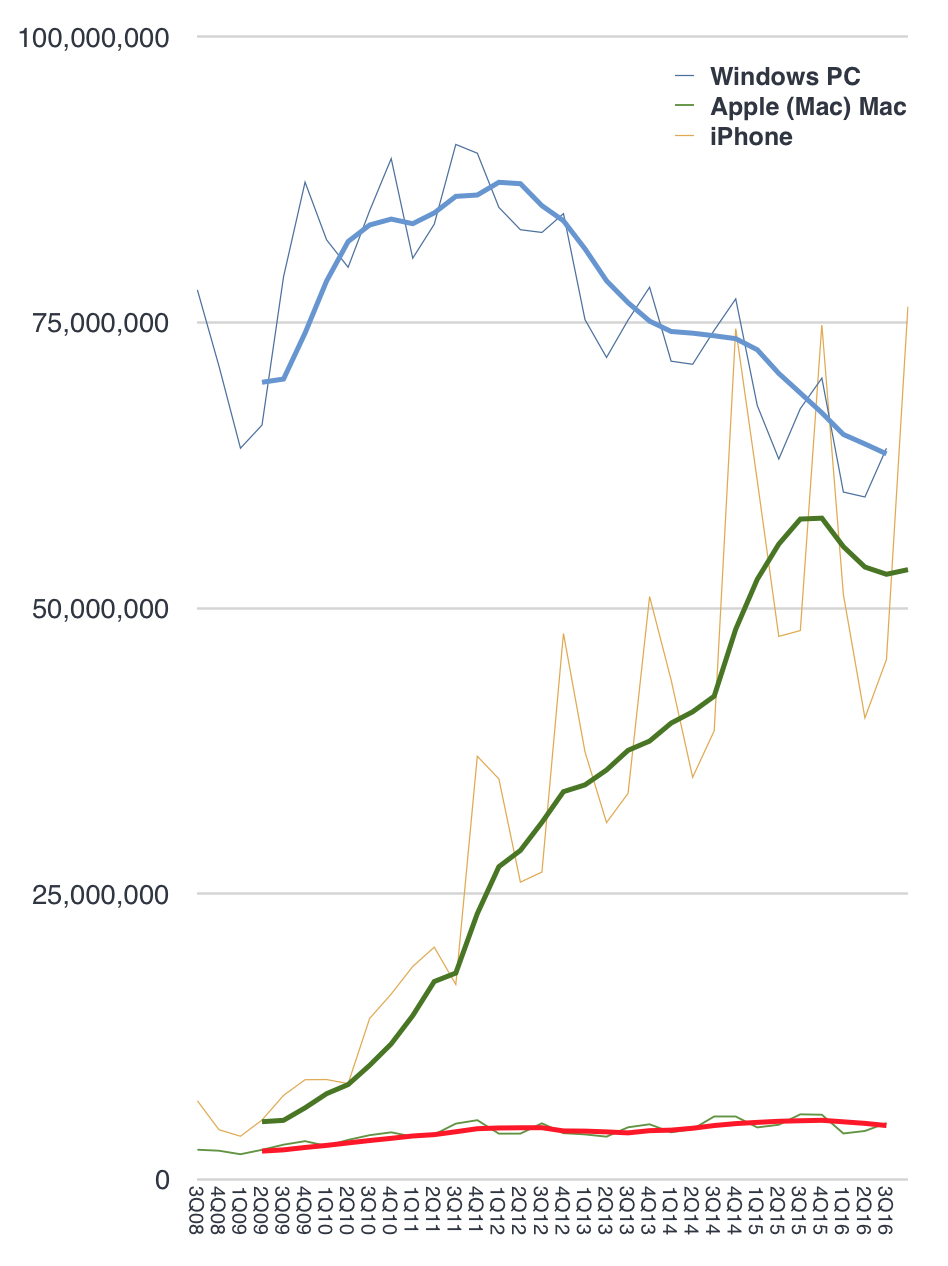
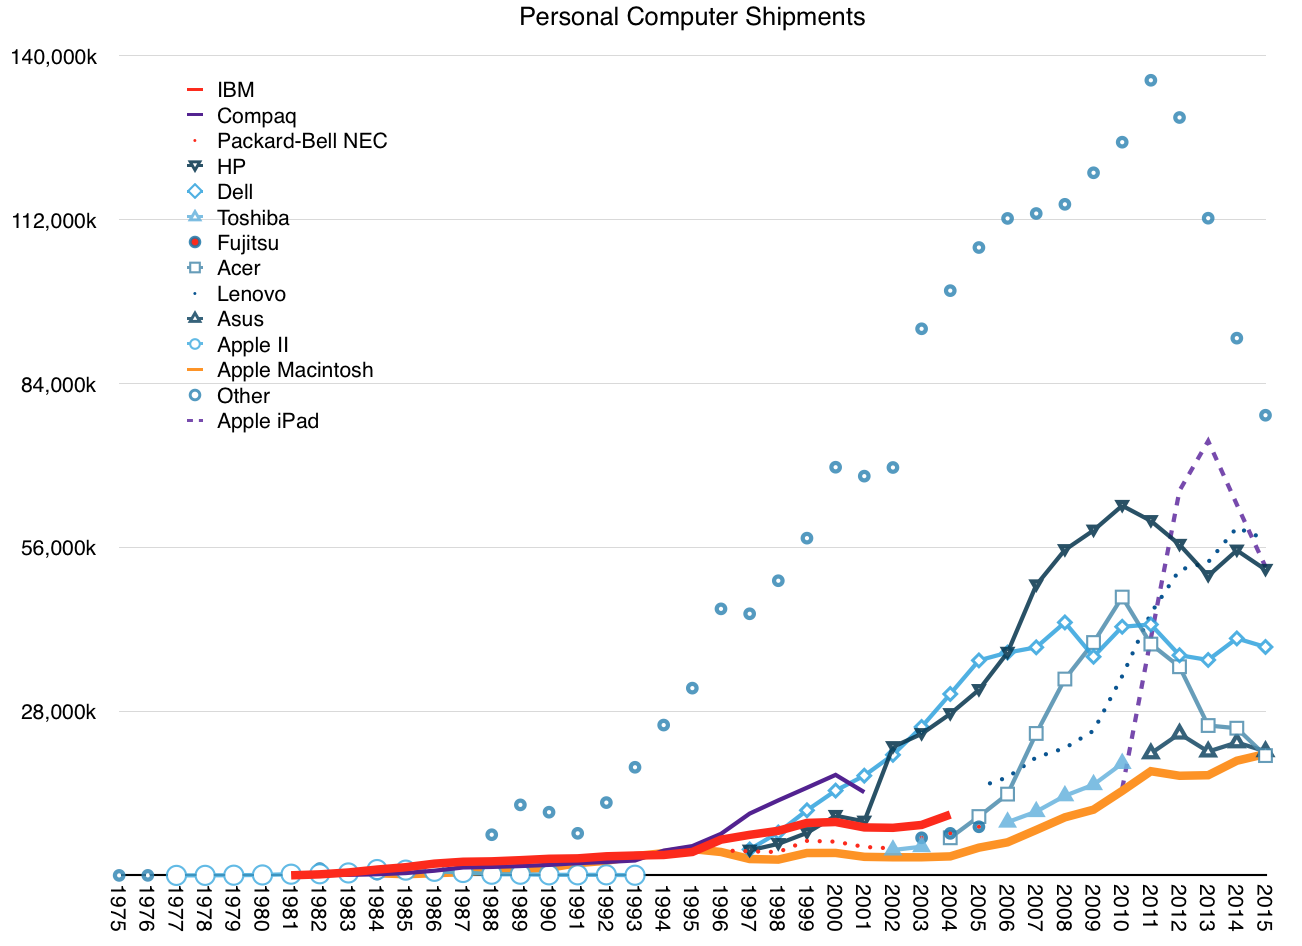
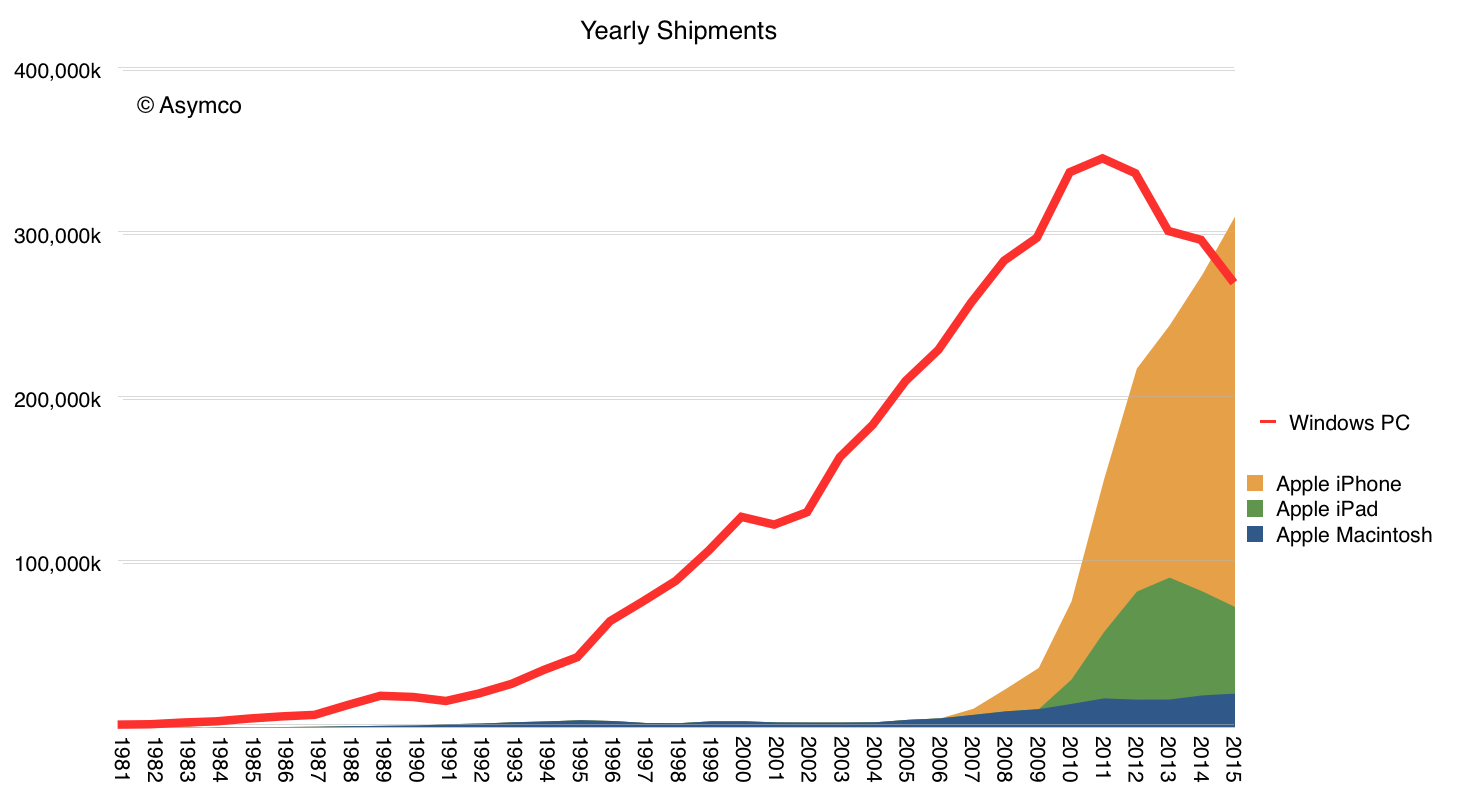
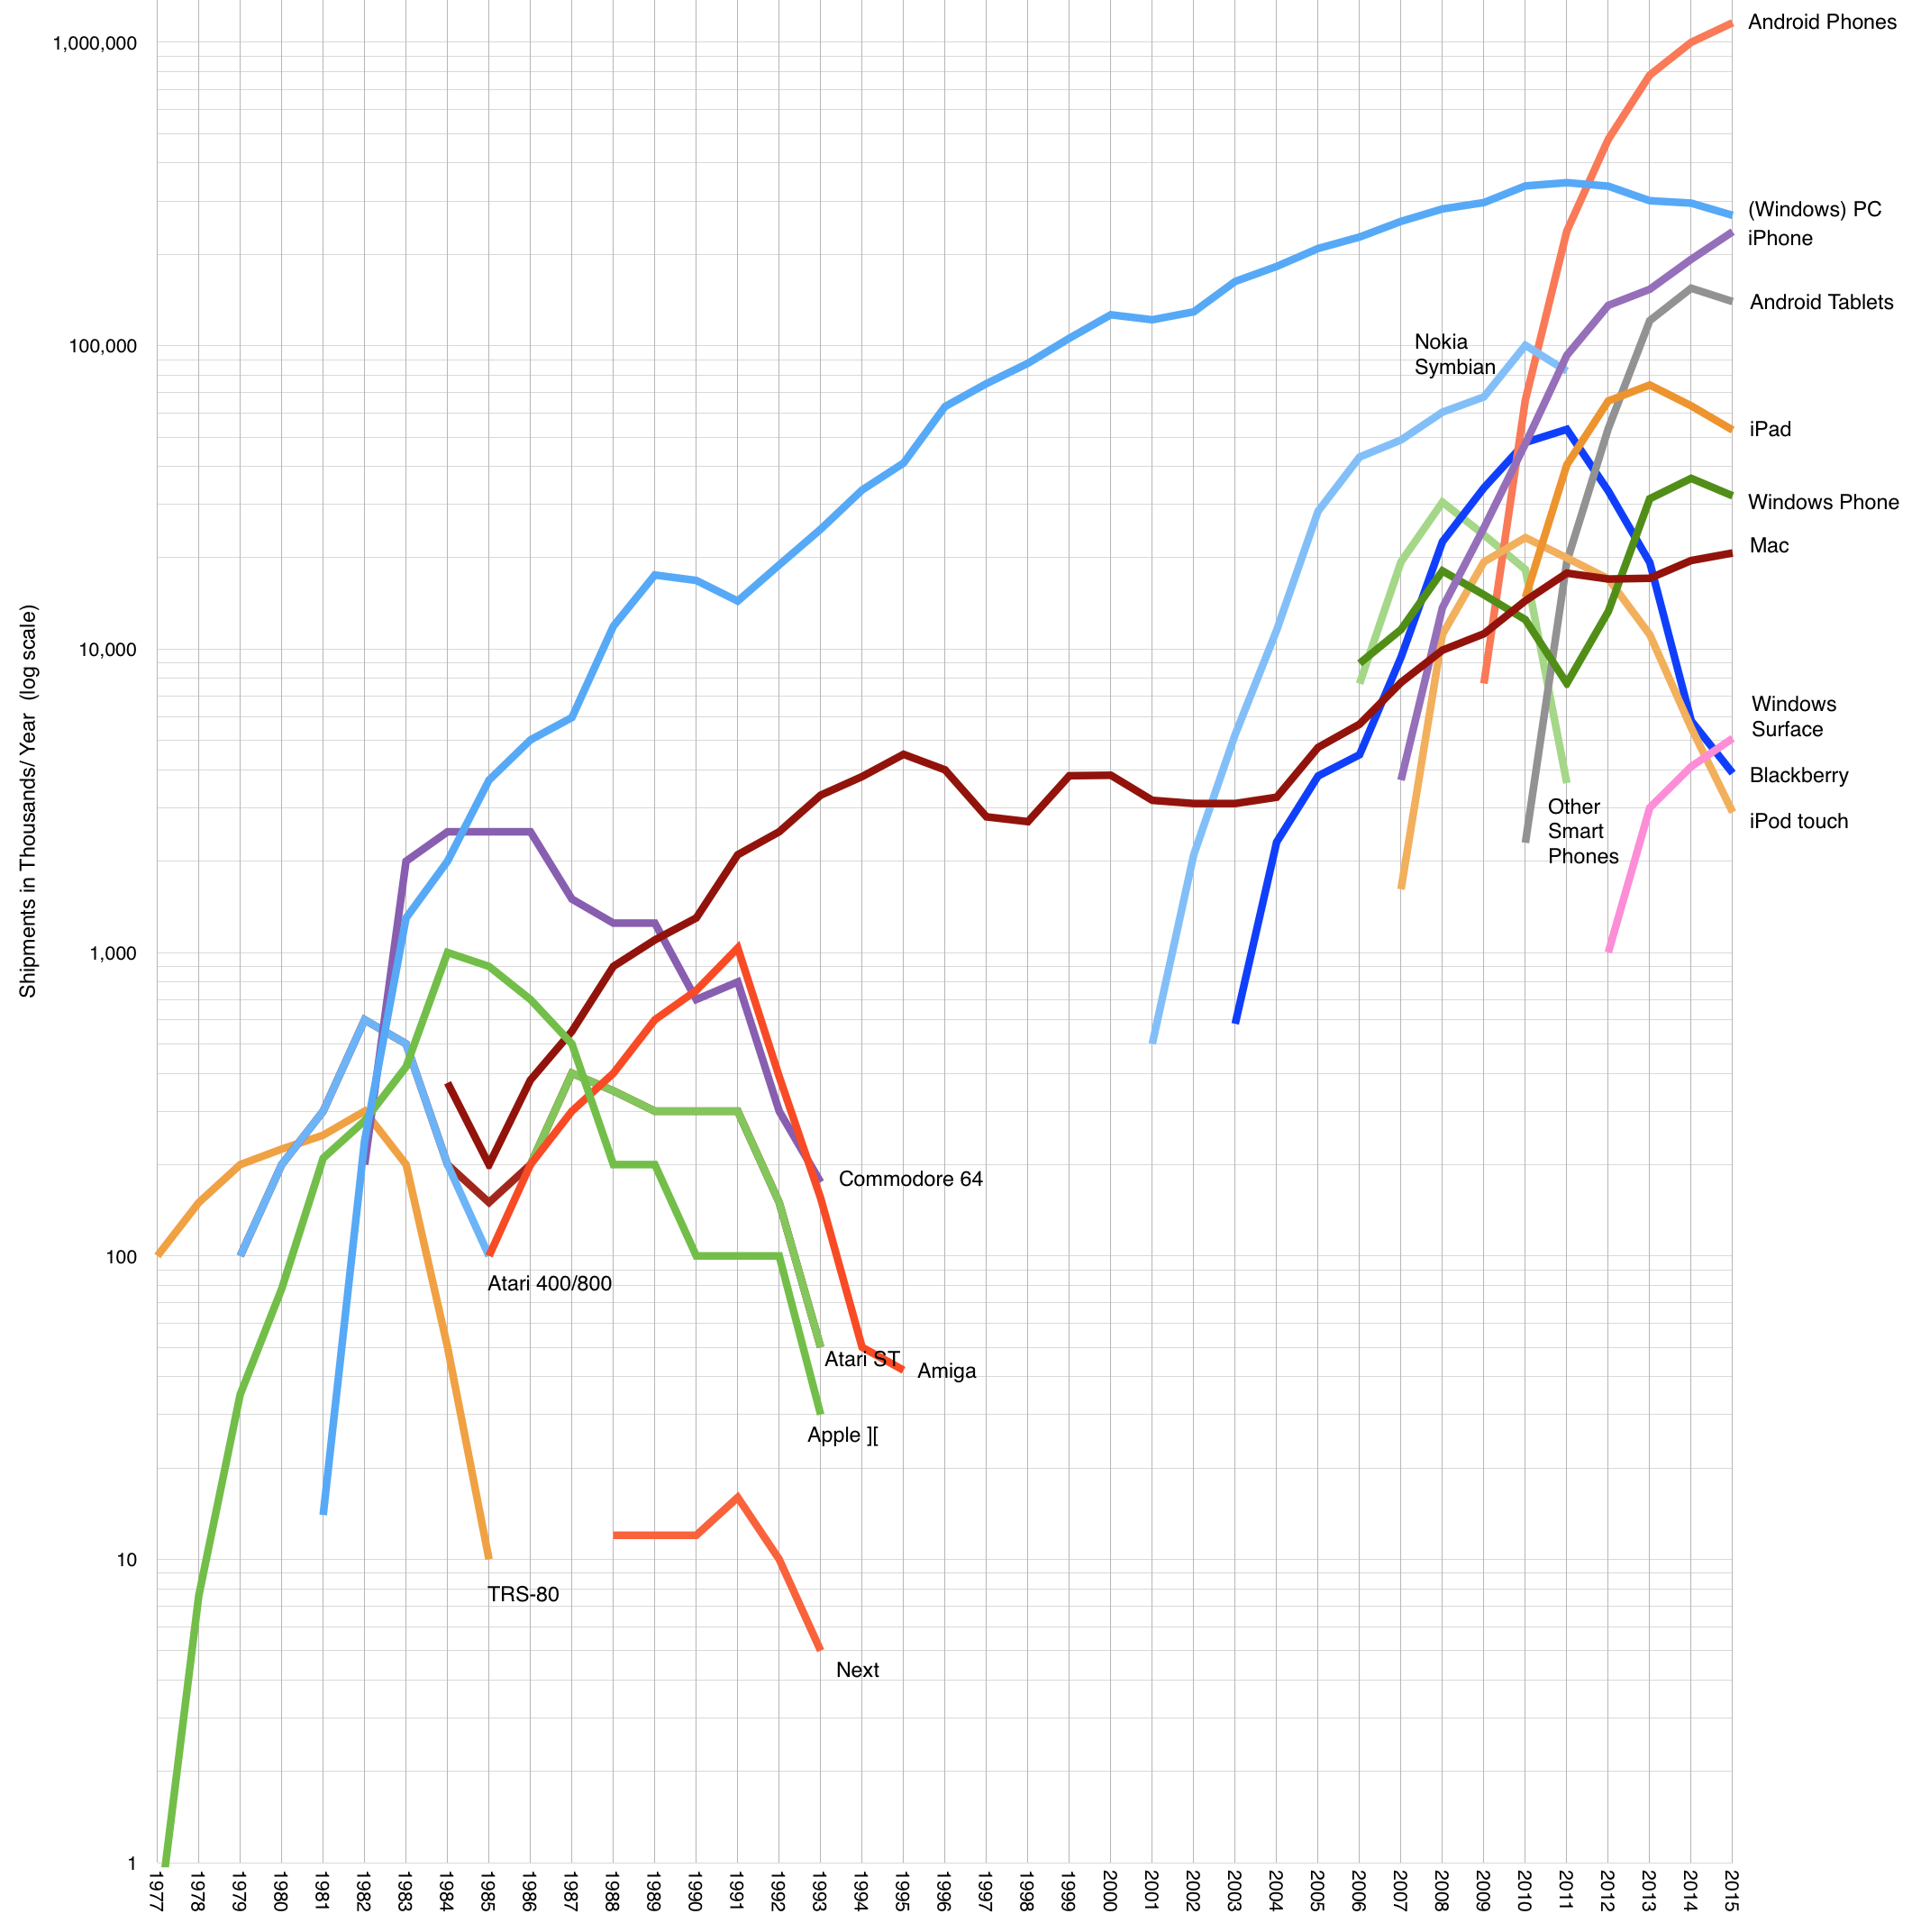
We can see the contrast simply by placing iPhone, Mac and all Windows PC on the same shipment graph.
This contrast is spectacular.
I bring this contrast up because I believe it is what focuses the minds at Apple. For them it's pretty clear where the puck is going. And not just now. Mobile has been foreseeable as a disruption to computing a decade ago–at least to some of us.
And so what do you with the Mac?
To answer this we have to ask what exactly is the purpose of the Mac in the age of the Mobile device?
Note that this is not the same as asking what is the PC in this world. The PC is not having to share a resource pool with an iPad/iPhone. It does not have to answer for its existence to a phone. PC makers and Microsoft are not fighting with an usurper in their midst. They may see the outsider challenger but it's not an inside challenger. This makes all the difference.
Indeed, because no usurper was allowed to emerge, PC/Windows never moved to a mobile evolution of computing. Microsoft's platform future was lost because the antibodies which eat disruptions were left unchecked.
But Apple's immune system was suppressed. It allowed a disruptor to emerge from within. Apple gave birth to its future by suppressing the reaction to that new seemingly parasitic organism. It took an immense willpower to allow this to happen.
But it takes us back to the question of what to do with the incumbent, the donor of DNA and resources. The parent that sacrificed for the child.
The Mac is thus not treated disparagingly. It deserves and gets respect. It is preserved but with limited responsibilities.
Which brings me to the question of what it is allowed to be and hence what it is. It cannot take on the role of being the future. That belongs to the touch screen devices. It will not morph into a touch device any more than a teen's parent will become cool by putting on skinny jeans. What it will do is become better at what it is hired to do.
The key to the Mac therefore becomes that which the iPad/iPhone isn't: an indirect input device. The keyboard and mouse/trackpad are what define the Mac. The operating system, the apps, the UX, are all oriented around the indirect input method. The iPhone's capacitive touch brought about the direct input method, a third pivot in input methods (first was mouse, second trackpad/scroll wheel). Each pivot launched a new set of platforms and the Mac is the legacy of the second.
It's not obsolete but it is a decreasing share of engagement. Alternate ways of doing the jobs it does well with direct input are emerging on the third pivot but they are not yet good enough. The children are still adolescent and making lots of stupid mistakes. There's still life in the parents.
The management thus has to focus on how to make the keyboard/trackpad interface better while still saying and believing that the future is touch.
In this context the newest MacBooks Pro are a logical extension of the second wave of computing while avoiding cramming them into the third wave. They are defined by their constraints. Seen thusly, the move from keyboard/trackpad to keyboard/touchbar/trackpad is pure genius.
The touchbar coupled to the other two inputs is a totally new way to interact with computing products. It's not an "easy" interface as it's not direct manipulation. It remains indirect, a defining characteristic of the second wave. Indirect inputs are powerful and lend themselves to muscle memory with practice. This is the way professional users become productive. The same way keyboard shortcuts are hard to learn but pay off with productivity, touchbar interactions are fiddly but will pay off with a two-handed interaction model. They are not something you "get" right away. They require practice and persistence for a delayed payoff. But, again, that effort is what professionals are accustomed to investing.
This is a leap forward and a big deal. For 32 years the UX model of the Mac has been two-handed typing with one handed gesturing. Now we have the option of two-handed indirect manipulation: one hand on the touchbar and one hand on the touchpad ((the iPad pro already encourages two handed direct manipulation)). Imagine you've been playing guitar with one hand for years and then someone lets you use your left hand. Holy cow.
Even so, it may seem that Apple is pulling punches. The product could have evolved into the full-touch, dual screens, pen input, hybrid model of Windows. But that only makes sense if you don't have a mobile product that is promising the same and tearing up the world at the same time.
You've unleashed a disruptive force and now you're supposed to retrofit the incumbent with the tools to compete. Why not just let the disruptor grow up unhindered.
The Mac is what it is because it's not alone. It's part of a family. It is a parent. It strives to be better but will not take the future from its child.
Berkshire Hathaway, led by Warren Buffett, now owns about $1.4 billion of Apple. Occasionally we hear about various "celebrity investors" taking positions in the company or exiting those positions. The last one I remember was Carl Icahn. He seems to have exited Apple before Berkshire entered. There are some who will act because of these decisions. You should not be one of them.
Nor should the management of the firm act in response to investor decisions or concerns. Management is specifically distinct from ownership in the corporate construct precisely in order to bring professionalism to the role. The manager must set priorities as they see fit, irrespective of what the transient owner might prioritize. The separation of ownership and management is one of the greatest innovations in commerce.
There are many opinions on what priorities should be. Delivering a specific financial ratio, achieving a certain market position, changing the world for the better. These have all been cited as top priorities. I happen to believe that what matters most is the creation and preservation of customers. That is because I see customer creation as causal to the other desirable outcomes and it is therefore the more important priority.
And this is why, whenever possible, I try to deduce how well a company is performing on this metric. The greatest companies (by market capitalization) today are certainly examples of achievement in customer creation. Facebook, Microsoft and Google are members of the "billion user club" or companies that crossed a billion active users.
But do they really have a billion customers? Microsoft has over 1.2 billion users but many (most?) of those users are using computers that their employers provide on which Microsoft software was installed. They may not have made the choice to purchase the tools they are using. Microsoft certainly has millions of customers in the form of "accounts" purchasing its products and services, but It's not likely that there are a billion people who have directly chosen to buy a Microsoft product.
Facebook has over a billion daily users. Facebook users are certainly using the service of their own accord but they are not paying for the service. Quite the contrary, the actual customers of Facebook are companies buying an advertising service offered in the form of exposure to those billion users. The Facebook users are the product being sold, not the buyers. Thus Facebook's total number of paying customers is probably only in the tens or hundreds of thousands. ((Orr Sella @orrsella pointed out that Facebook has stated that they have 3 million businesses actively advertising on their networks.))
Same with Google. We don't know how many accounts Google send invoices to but the number is very likely not even in the 100 million range. Its billions of users are beneficiaries of services but they are not paying Google/Alphabet.
Amazon has many millions of customers, if not billions. Prime membership is above 50 million but not above 100 million. Amazon may some day have a billion customers but there are limits to how quickly that can happen. The growth potential is governed by logistics and that's as much an issue with atoms as it is with electrons.
Which brings us to Apple. Apple does not offer a figure on its specific user count, but we have some viable proxies:
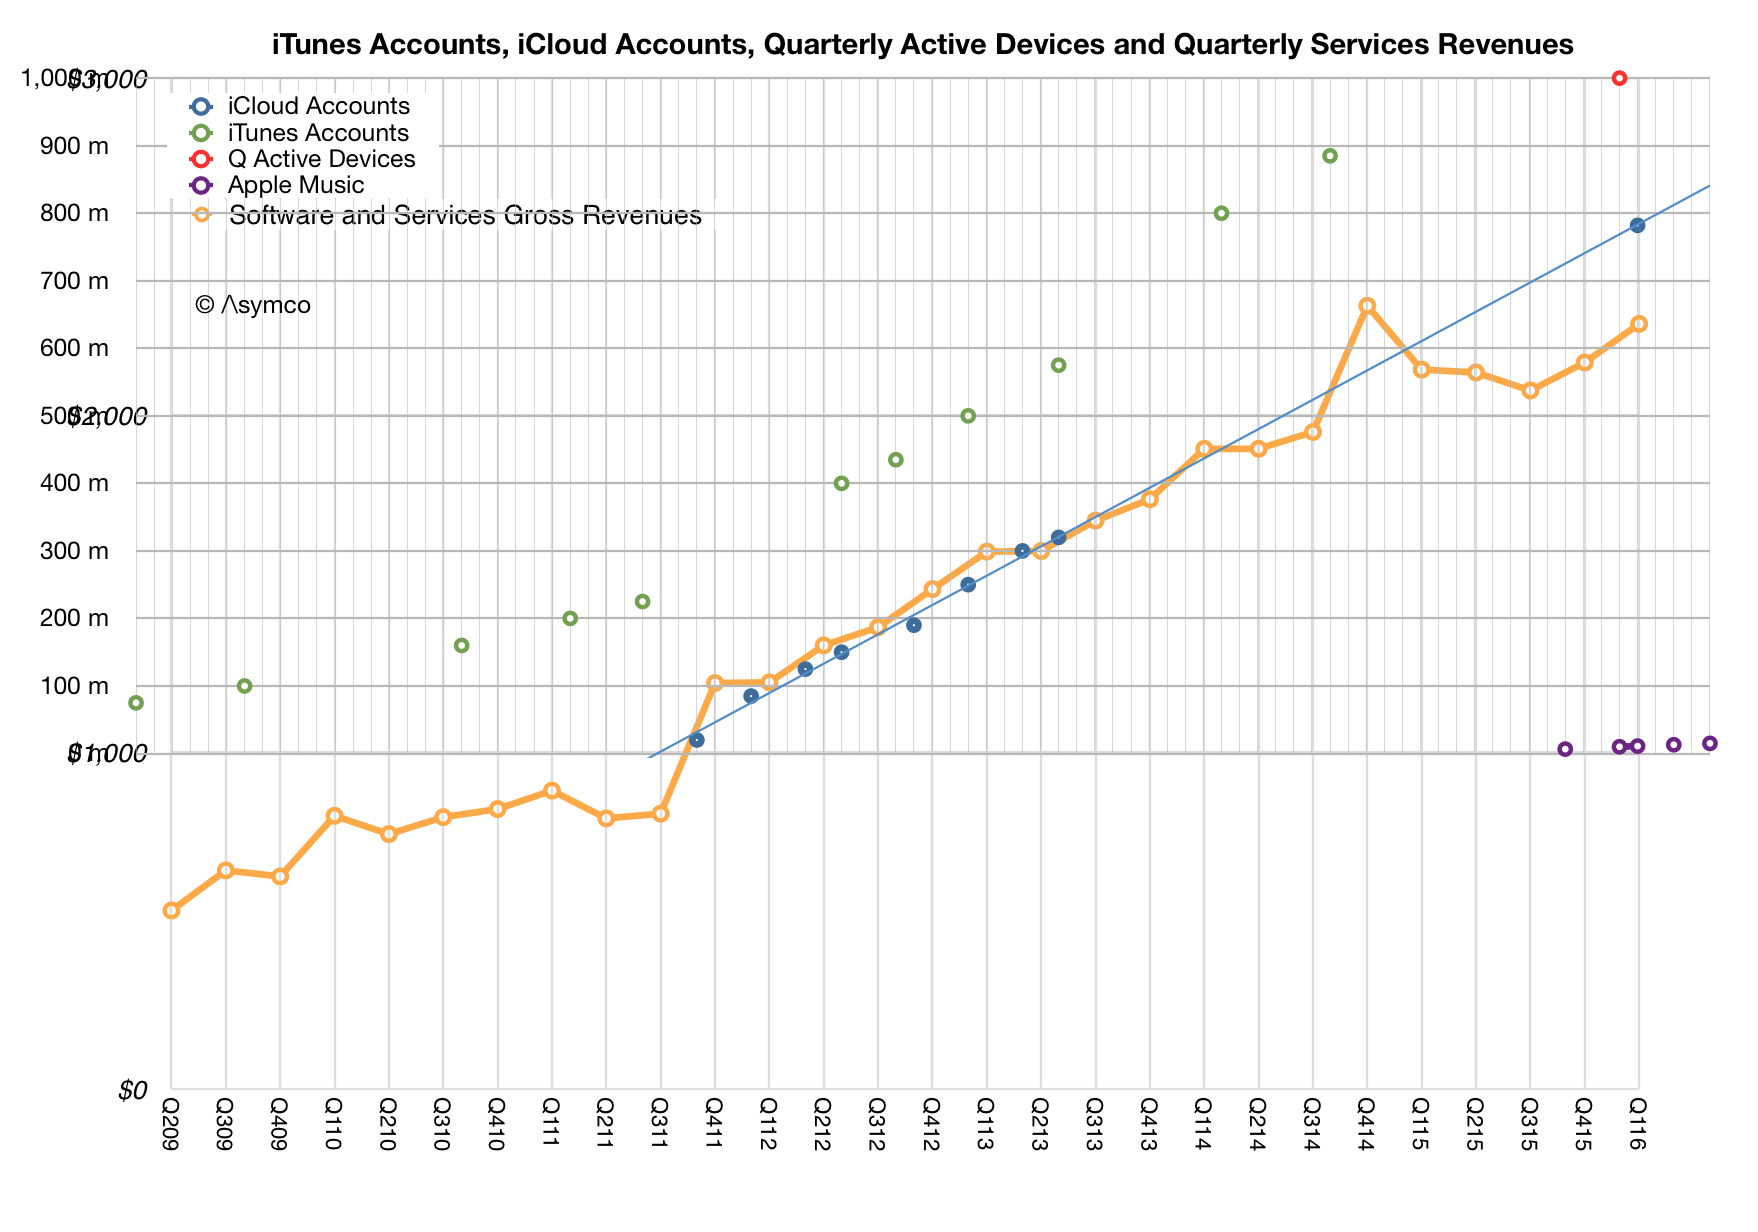
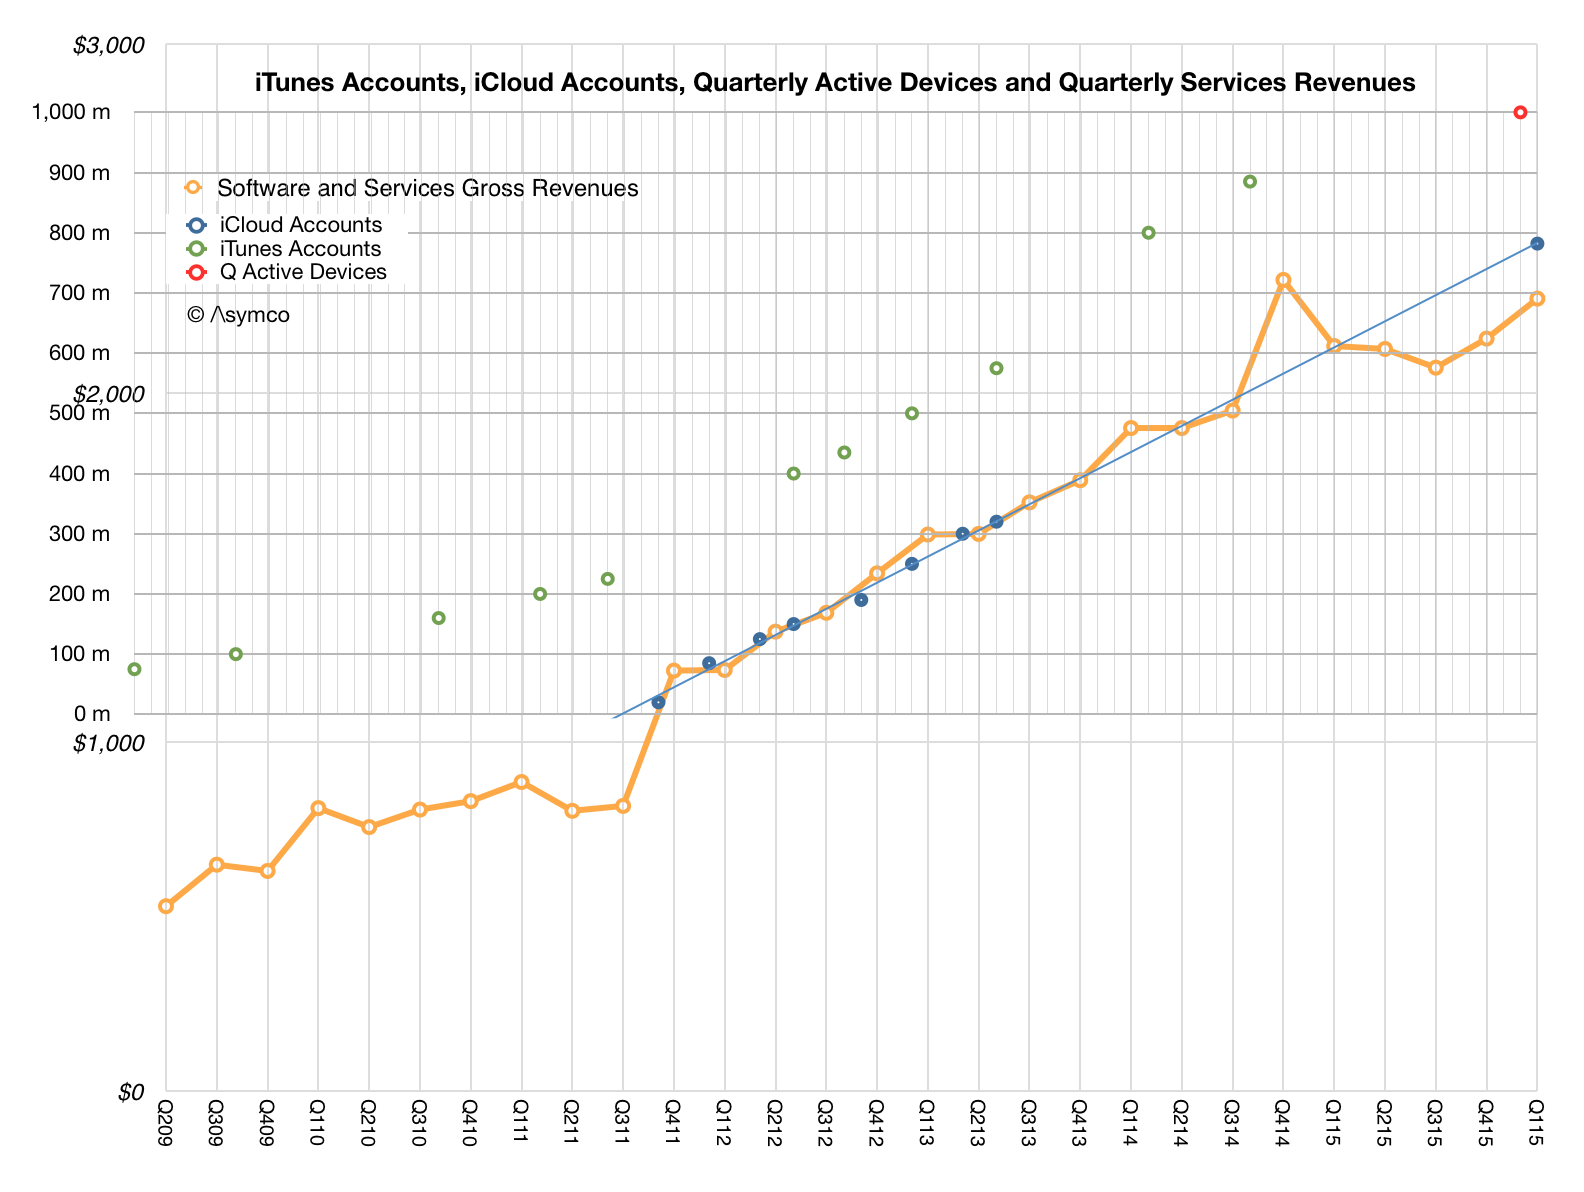
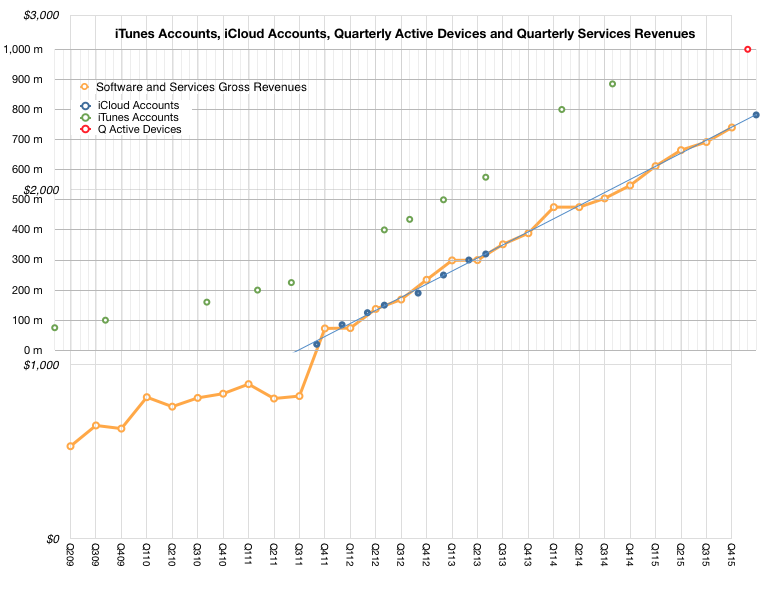
iCloud accounts reached 782 million in February 2016.
iTunes accounts reached 885 million in September 2014
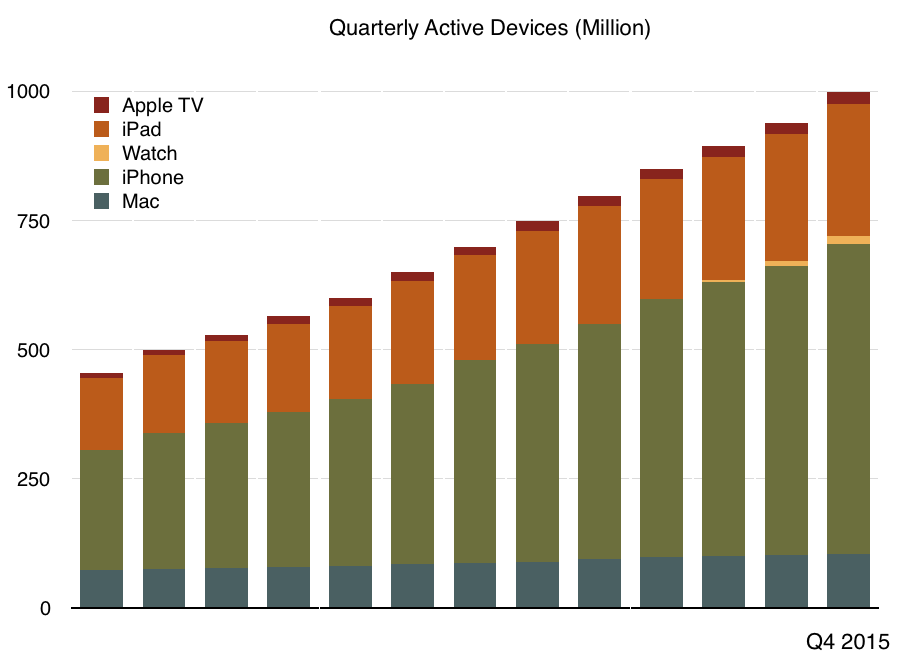
Active devices reached one billion in January 2016. That number is likely above 1.1 billion now. (Includes all devices, hence Macs and Apple TVs).
These figures are also parts of patterns (shown below) which offer an indication of predictable growth.
In addition to the absolute figures and their growth there is also the question of loyalty (frequently cited by the company), switching from other platforms (also frequently cited) and revenues. The company publishes specific figures on service revenues for consumer attached devices showing a run rate of $41 billion/yr in services for their device base.
In combination, a picture emerges which shows that Apple has nearly a billion customers. I can't say how many with any precision but it's certainly above 500 million (on the basis of iCloud and iTunes accounts). It's below one billion because some users have more than one device.
Even though it has not happened yet, the trend is pretty clear. Apple will at some point in time have a billion paying customers.
What is more significant than the specific count is that these customers mostly chose to be customers individually. Some may have been given the products as gifts, but the vast majority bought the items for themselves. Apple benefitted from hundreds of million of individual purchase decisions.
Furthermore, having made the decision to purchase, chances are that they will do so again. Apple customers are a recurring revenue stream. In fact, it's fairly easy to calculate that being an Apple customer is equivalent to spending about $1/day on its products and services, indefinitely.
Apple is not there yet, but a billion dollars a day from a billion customers is not inconceivable. That would be quite an achievement.
At WWDC 2016 Apple offered a set of new data points to illustrate its ecosystem's robustness.
First, the number of registered developers increased by 2 million in the last year to a total of 13 million. That is a growth rate of 18%. To compare this total consider that Oracle claimed in 2014 9 million Java developers and IDC claimed in 2014 there were 18.5 million software developers in the world, of which 11 million were professional software developers and 7.5 million were hobbyist developers. It's therefore possible that Apple's "market share" among developers is close to 70%.
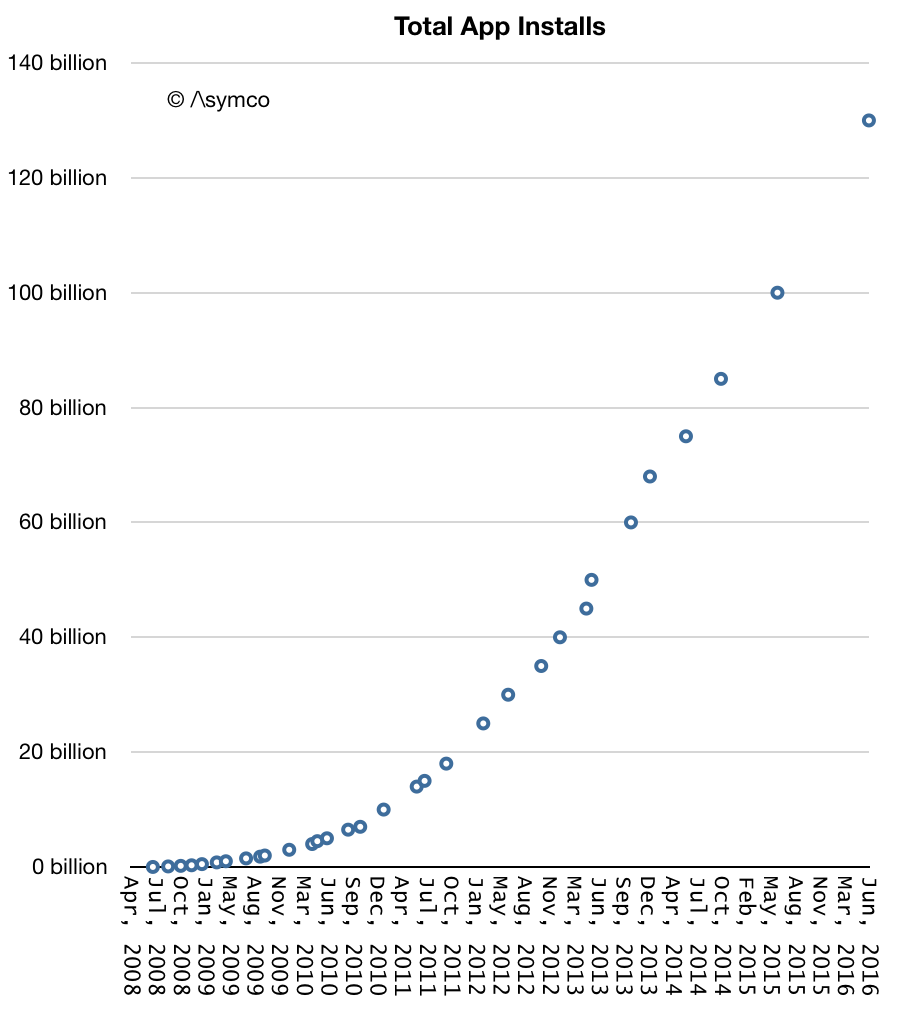
Second, App installs have now reached 130 billion. The cumulative growth is shown in the graph below:
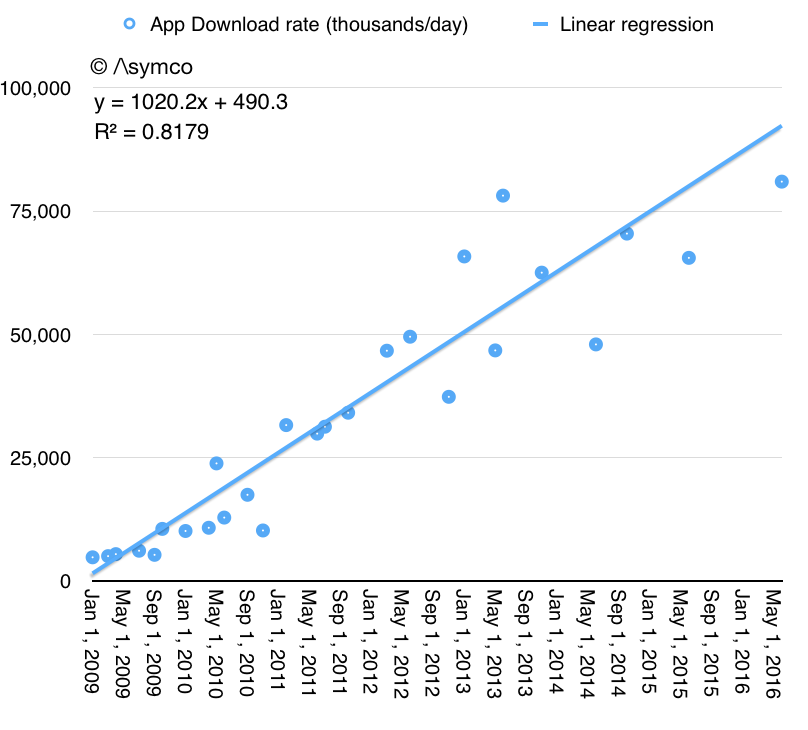
The rate of growth is also shown in the following graph:
Note that the rate of growth continues to increase and is now above 30 billion/yr. It turns out that apps continue to be a popular download item. The size of the audience continues to grow (see graph below) and it's therefore understandable that activity in the store continues to grow.
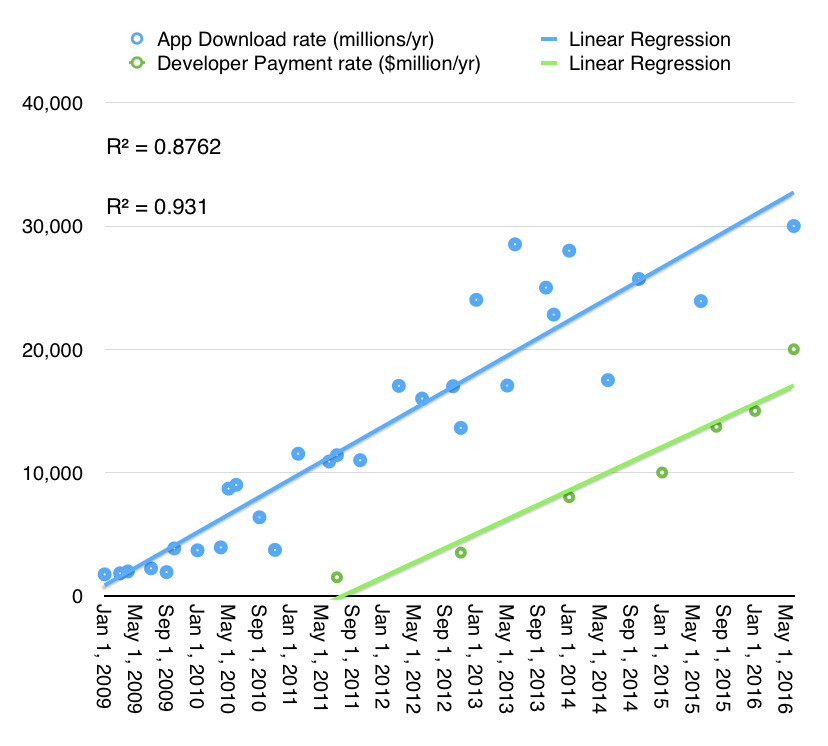
Third, the rate of payment to developers has also increased to over $20 billion/yr., with the total payments having reached $50 billion.
The graph above shows the derived payment rate (in green) relative to the download rate (blue). Although not completely parallel, the overall correlation is plain to see.
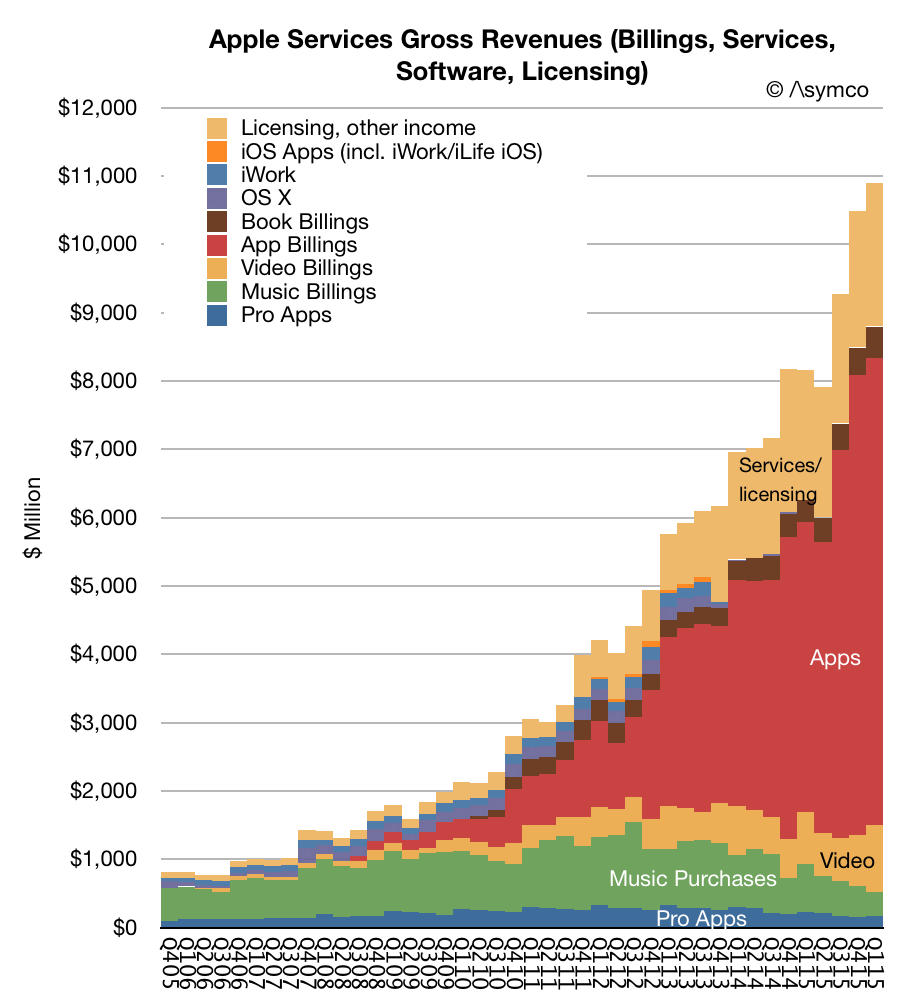
Fourth, there are more platforms than ever (four device and three services). As a result, Apps and services continue to outgrow traditional content revenues. Gross revenues for iTunes/Apps/Software/Services/Licensing is shown below:
Overall, economic activity transacted directly through Apple's platforms is approaching the run rate of $40 billion/yr. It continues to grow at about 20%, so it's foreseeable that it will reach at least $50 billion/yr.
It's hard to compare to other ecosystems as metrics vary but this rate alone places Services as one of the larges businesses in the world (service or otherwise).
There are other ecosystems "on top" of iOS which transact outside the Apple systems (and hence are not reported in the total above). These include Facebook, Google, Uber, Amazon and other economies which use iOS devices to enable engagement. These add up to hundreds of billions of dollars in transactional value. My estimate is that all mobile services are at least $250 billion/yr today and will reach $800 billion/yr in 2020. Apple is and will continue to be the home or enabler to the majority of this revenue.
But the more profound point to be made is that this ecosystem relies mainly on direct payments by the beneficiaries of the service or content. Apple contents itself with the $35 billion it can transact through its own storefronts because it feels that the business models are compatible with its brand.
When it comes to all the ways of "monetizing" platforms, this may be a very conservative strategy but it's one that also avoids the potential pitfalls of social scandal.
In Apple's first 40 years it shipped 1,591,092,250 computers ((including Apple II, Mac, iPhone, iPad and iPod touch; excluding Apple Watch, Apple TV and other iPods. Includes Q1 shipments estimated at 63,597,000 Macs, iPhones and iPads)).
This shipment total is higher than any other computer company in its first 40 years. Actually there are no other PC makers that are 40 years old. One computer maker (IBM) is older but they only sold PCs for 24 years and what they still sell they don't sell in high numbers.
That does not make it the top seller in a given year. Looking at only the Mac, Apple's traditional form factor personal computer, Apple has only returned to the top 5 last year. Only if including the iPad it was the top computer vendor in 2011 and including iPhone, it was first in 2009.
After having a 40 year run and after selling more computers than all American and Japanese computer companies put together, how should we think about the next 40 years?
First, clearly Apple shifted from being a "computer company". It has already changed its name to exclude the word "Computer" but that has been interpreted as saying that it sells devices (which happen to also be computers.) The word "computer" is already archaic. We stopped using computers to compute in the 40s. We used them to make decisions, keep track of things, speed things up and then to communicate and then to entertain.
Devices, it seems, are what customers mainly use to do, well, everything. Computing has grown to encompass most activities we engage in. So is Apple then a device maker?
More broadly, irrespective of the name, is Apple at 40 still defined as a hardware company? Certainly Wall Street ((i.e. average people)) still think so. The conversations one hears clearly consider Apple's future to be tied to the sales volume of specific products. At one time it may have been the Mac, another, the iPod and now the iPhone. This thinking is again a legacy of where the company was but mainly it's a reflection of how revenues are reported.
We see a line item in the income statement that says "iPhone" and it has a big number next to it so we, of course, fixate on that big shiny number. But if we were to unpack that number and see why it's so big we would discover that buyers are buying something other than what financial statements report.
Buyers are buying experiences, I hear you say. Yes, but more than that. Much more. They are buying safety, comfort, convenience, simplicity, productivity. They are buying modules to combine with other modules that help to do something. Something better. They are buying hope, satisfaction, escape or vanity. In other words they don't know what they want but know when they have it. They trust products unseen which have a reputation of delivering that which they think they might like, without knowing what that is. By employing the product, and a whole lot more—effort, time, mental energy and repetitive actions—they learn to exploit a product to achieve satisfaction.
Products are enablers, as are experiences and software and ecosystems and services. They are modules used in a melee of activity to make the user feel they are making progress. And if that module is better than no module then it will command a price and if it's better than another module or modules then it will command a premium. And if most people agree then it will be popular with many. And only if all these are true will it create a big number on a report.
And so we must search for other names to call a company that delivers an enabler that may lead to progress. Crude categorization like the reporting of finances leads to self-deception and a loss of opportunity to understand. Firms are often victims of this self-deception because they start believing that customers buy the things they sell. They start to believe that what is on their financial reports is a reflection of the value they create. It's a simple mistake to make, but a mistake which leads to catastrophe. If its data is mis-categorized, by chasing numbers the company runs away from opportunity, leaving it to competitors otherwise unencumbered with knowledge of numbers.
Assuming Apple avoids mis-categorizing what it does, will it be a "solutions" or "services" or "brand" company? Is it, as I used to say, a "blockbuster manufacturing line"?
Yes, and still that's not all it could be. Nor is it enough to understand what will come.
My simple proposal is to think of Apple (and actually any company) as a customer creator. It creates and maintains customers. The more it creates, the more it prospers. The more customers it preserves the more it's likely to persevere. This measure of performance for a company is not easy to obtain. It's not a line item in any financial report.
The closest figure we have is that today Apple has one billion active devices in use. We're not told of the total users or total customers because Apple cannot count people or wallets as accurately as it can count active devices. But as imperfect as it is, this number gives us a way to get close to counting customers.
So we know that at least Apple has created a large number of customers. Knowing total devices sold and number in use means that we can be sure that 63% of all the computers Apple sold are still in use. This means that most customers are recent customers. That is not necessarily good news. New customers are not well understood. We don't know how these new customers might behave in the future.
Will they come back for more of whatever Apple makes? If we look at the history of competitors or technology products in general, chances are they won't. The industries Apple has been a part of are filled with one hit wonders. Companies which had parabolic trajectories and built no loyalties. Statistically speaking, success in Apple's markets is always followed by failure.
But what if we did not seek correlation but looked for causation? What if we ignore statistics about companies other than Apple and focus on statistics about Apple's actual customers? Rather than assume all companies are the same, what if we assume that some can be exceptional? What if we we look for the anomalies, not the clusters?
We might want to ask about the causes of success or failure for a single company. We might want to sample its specific customers. We might want to observe how Apple's own customers behaved in the past. We might want to use theories of brand value or theories of network effects or theories of software ecosystems.
These measures, rather than those of "comparable companies" might lead to different conclusions: That customers are loyal, that they will value the brand and that they are invested in a network. In other words, that they will buy from Apple again.
If we then factor in the size and persistence of Apple's audience (customer base) we might conclude that there are factors which will allow it to grow rather than shrink. My analysis based on public data shows that the customer base has been increasing steadily.
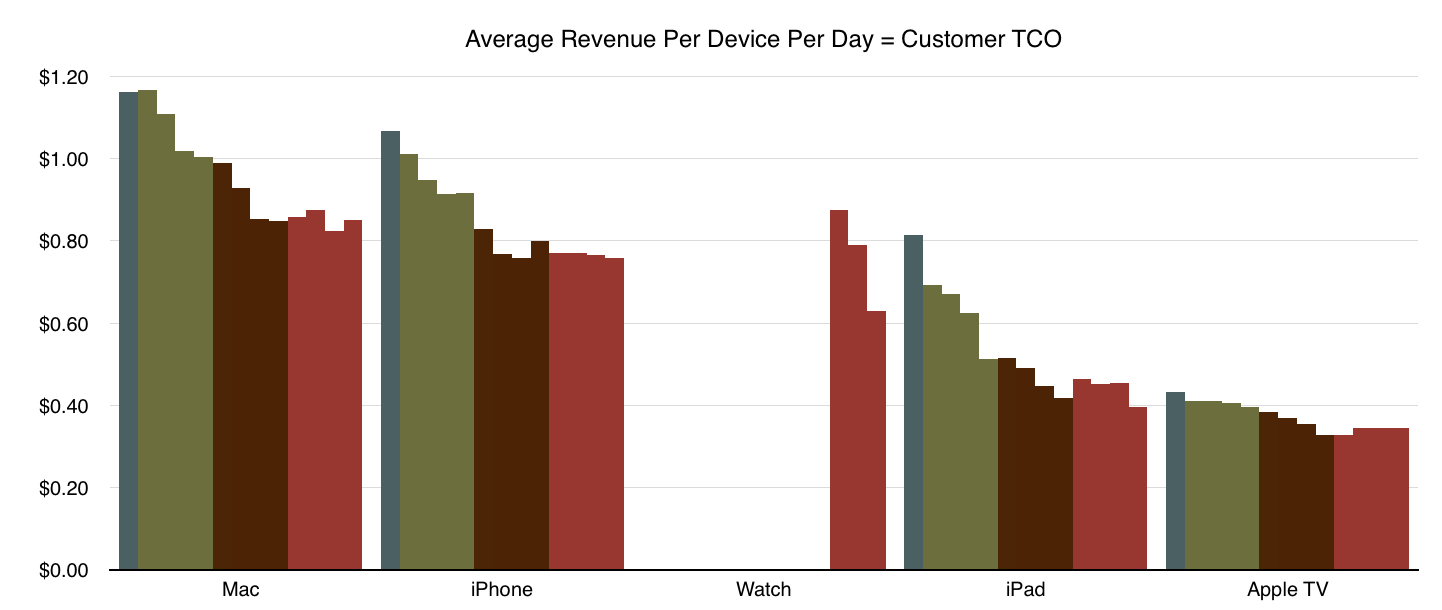
Considering this audience and the revenues generated, we can categorize the revenue by active device as follows.
Each bar represents that product's revenue per day in a given quarter (from Q4 2012 to Q4 2015). Each year is therefore represented by a different color. Dark green for 2012, light green for 2013, burgundy red for 2014 and dark red for 2015. For example, each iPhone in use was generating exactly $1/day in revenues (including services and accessories) during the first quarter 2013.
This allocates all of Apple's revenues to these products and by proxy to customers.
In summary, the "average revenue per Apple device per day" is currently $0.68. If we assume one unique user per device then Apple collects 68 cents from each customer each day. ((In reality the figure may be closer to $1, as there are likely to be more 1.2 to 1.5 devices per person.))
Combining the history of customer creation and customer preservation with the value obtained from each customer implies that the next 40 years will be about creating another large tranche of customers whose willingness to spend on whatever Apple creates will be relatively unchanged.
We don't know the limit. One billion was hard to imagine even one year ago. We might see two billion devices in short order. Perhaps not. Perhaps as we have a multitude of devices about us all day the number will become less meaningful. But if the number of middle class customers grows and as Apple keeps its products within their reach, there is no reason to think that there will be a reversal of the last 40 years in terms of customer acquisition.
This analysis contradicts the current perception of the company as reflected by its stock price. That price assumes the audience will wither ((With a P/E ratio of 11, without a change in revenue per user, the only justification would be the audience shrinking by more than 90% over the next 20 years.)) That is not insanity. It is what we could expect if Apple were unexceptional.
We could surrender to correlation and ignore causation but statistics show that such an approach rarely works.
-------
Incidentally, this and a lot more will be discussed at the next Subscribe conference.
How Apple is managed is one of its enduring mysteries. The idea that a company with $235 billion in sales is managed with a single P/L ((Profit and Loss statement is an income statement usually applied for a subset of a larger company which allows subdivisions to be managed individually.)) is fascinating in many ways. Not least of which is how it allocates resources. The fundamental question of which great idea gets to be funded and which great idea gets to be ignored is the core of every manager's dilemma. The Apple problem is at scale when each decision's consequences are so momentous. In the case of Apple there are so few projects that reach the market and their impact is so great that one wonders how they can be sure they are doing the right thing.
Conventionally, product development is filtered through a sieve of metrics, market sizing and impact on top/bottom income lines. These "financial" measures of success are considered prudent and optimized for return on equity (also known as the maximization of shareholder returns).
But this can be a toxic formula. The financial optimization algorithm always prioritizes the known over the unknown since the known can be measured and is assigned a quantum of value while the unknown is "discounted" with a steep hurdle rate, and assigned a near zero net present value. Thus the financial algorithm leads to promoting efficiency at the expense of creation. Efficiency may be the right priority when times are difficult and resources are scarce but creativity is the right priority in a time of plenty. And abundance is what being big is all about.
To allow for some creation large firms create divisions. Some divisions are tasked with "core products" which are measured by a set of firm metrics and some are tasked with "emerging products" which are given a set of loose metrics. This leads to obvious resentment and war between divisions when resources need allocating.
Ominously, the core divisions tend to always win. At the root of divisional power struggles are measurements--the roots of financial metrics. Managers fight with data. "You can't manage what you can't measure" they're taught. But if you have something that can be easily measured and something that is difficult to measure, won't the easily-measured be managed and the hard-to-measure be ignored?
There is a general principle at work here: Managing by measurement is fraught with the pitfall of measuring the wrong thing. Making sure that you're measuring the right thing becomes the value-adding role of the manager. A role that is increasingly being neglected.
The mass phenomenon of measuring the wrong thing because it's the easiest to measure is called "financialization". Financialization is the process by which finance and finances (rather than creation) determine company, individual and society's priorities. It comes about from an abundance of data that leads to fixation on what is observable to the detriment of awareness of hazards or obstacles or alternatives. This phenomenon is more likely when the speed of change increases and decision cycles shorten.
Financialization is creeping into all aspects of society and the extent to which it infects companies is the extent to which they suffer from early mortality.
So is Apple avoiding financialization? How can anyone avoid the tyranny of mis-optimization?
The unified P/L might be a clue. It obviates the need for divisional rivalry and power-based or financial politics. Without divisional P/L, management can be organized functionally with the obvious benefit of de-politicization. The singular P/L does create another problem however: the absence of an alternative resource allocation algorithm centralizes the decision. By centralizing decisions at the highest level, few decisions can be taken and that means each decision has to be right more often. We swap a distributed but financialized process for a central but capricious one.
So how is the central decision process made fair? What guides the allocation process?
I believe that Apple does not avoid quantified decision making. I believe the logic of their decisions is based on a nuanced quantification of the company's customer base. Opting to think about how many customers they have rather than how many things they can sell could offer the Apple manager a better decision tool, avoiding financialization and mis-optimization.
The guiding principle is putting the customer rather than the firm at the center of the decision process. The idea of this change of orientation extends to a re-definition of the purpose of the firm. Apple calls it its "North Star" and it places "making the best product" at that location.
The challenge is how to measure "goodness" of product. It's easy to overshoot "best" and become too good. What regulates greatness is another measurement: absorption of what you create. The true orientation (which Apple won't confess to) is absorbable greatness.
Absorbable greatness is measured through other proxies: customer creation, customer satisfaction, and customer retention. By adding and preserving great customers you can be sure that what you create is indeed the "best". Setting the goal, and indeed the purpose of the firm, as the creation and preservation of customers seems to be the unwritten constitution of Apple.
The idea that the purpose of the firm is to create and maintain customers is not new ((Customer creation is in contrast to the notion that the purpose of the firm is to maximize shareholder returns. The notion of customer creation as primary purpose was popularized by Peter Drucker. The notion of optimization through shareholder value creation was popularized by Jack Welch.)) but it is relatively rarely practiced. The reason is that the data is harder to obtain. The data that comes from sales is crisp and concrete. The data about customers is muddy and soft. In a world where spreadsheets are used as weapons, the crisper the data, the better the ammunition.
Clarity wins arguments but it may not be where salvation or truth can be found. Good judgement in a cloudy reality is a better compass than a clear road map to a fantasy world.
Optimizing around customer acquisition rather than equity returns leads to a new set of metrics. What would these metrics look like for Apple?
The company publicly offers three separate sets of quantity of customers and quality of customers.
In terms of quantity we have:
Number of iTunes accounts
Number of iCloud accounts
Number of active devices
In terms of quality of customers we have:
Average selling prices for devices (as a proxy for willingness to pay)
Customer satisfaction (as a proxy for loyalty )
Services and accessory revenues (post-sales and recurring value)
The following graph shows the historic data for service accounts and corresponding services revenues.
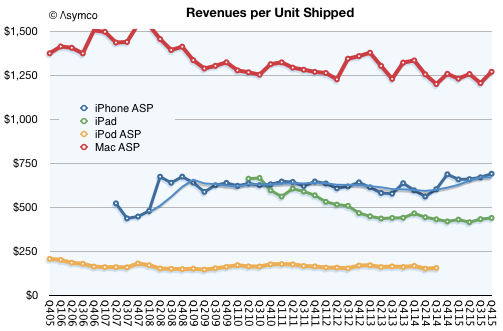
The following graph shows the average price per hardware product indicative of loyalty through stability in the face of growing competition.
The following graph shows an estimate of growth in active devices as a proxy of customer base.
Unlike product shipments and revenue data which follow rises and falls in individual products due to the cyclicality of technology and adoption, these graphs show a smoothness and predictability of customer base behavior.
Looking at Apple this way gives the impression that the company has a large number (nearly a billion) of repeat (subscribed to service) customers. These customers can be seen to spend a predictable recurring amount (average selling price) on Apple's brand. The repetition of these metrics in public commentary suggests that customer acquisition and retention are among Apple's goals.
The key question is whether this is Apple's primary goal.
Seen this way each centralized resource allocation question can be assumed to be prefaced with "In order to create/preserve customers should we...?"
This leads to answers quite different from questions that start with "In order to sell/profit more should we...?"
For instance, offering education products, retail store experiences, healthcare products, green energy initiatives, accessories, content and services make sense even if they may have poor financial "returns". These initiatives score highly on customer retention and satisfaction. They may lead to engagement and repeat sales. Managers working on these initiatives would gain the respect of their peers, leading to more esteem and higher quality output. Finally, and most importantly, these efforts would be preserved regardless of cyclical downturns.
The assessment of analysts should therefore be couched in similar terms: "What is the impact of a new initiative in customer creation and preservation?" rather than "What is the impact of a new initiative in driving revenues and profitability".
We can see immediately why the second question is popular while the first isn't: it's easier to assess an answer to the second because we have the data that allows for its calculation.
This is why asking the wrong questions is popular.
In my quoting of the "Cook Doctrine" I cited the primary criteria for Apple to enter a new market:
We believe that we need to own and control the primary technologies behind the products we make, and participate only in markets where we can make a significant contribution.
These criteria, often repeated, were certainly in force when Apple chose to enter the watch market. Apple has sought and achieved a significant market share and did so while owning and controlling the primary technologies behind the product.
I now turn to the significant contribution criterion to study the possibility of Apple's entry into the car industry. ((Control of the primary technologies behind the product is a topic for another post.))
The significance test shifts the speculation from whether Apple would build a car, to how many cars is could build. Making a few cars is easy (see first commandment of The Entrant's Guide to the Automotive Industry). Making lots of cars is hard and hence significance in the automotive market (as in watches and phones) means achieving some degree of adoption, a higher degree of usage and a very high degree of profitability.
So what does being significant in the car business mean? Does it mean becoming the next Tesla? The next BYD or the next VW? How quickly?
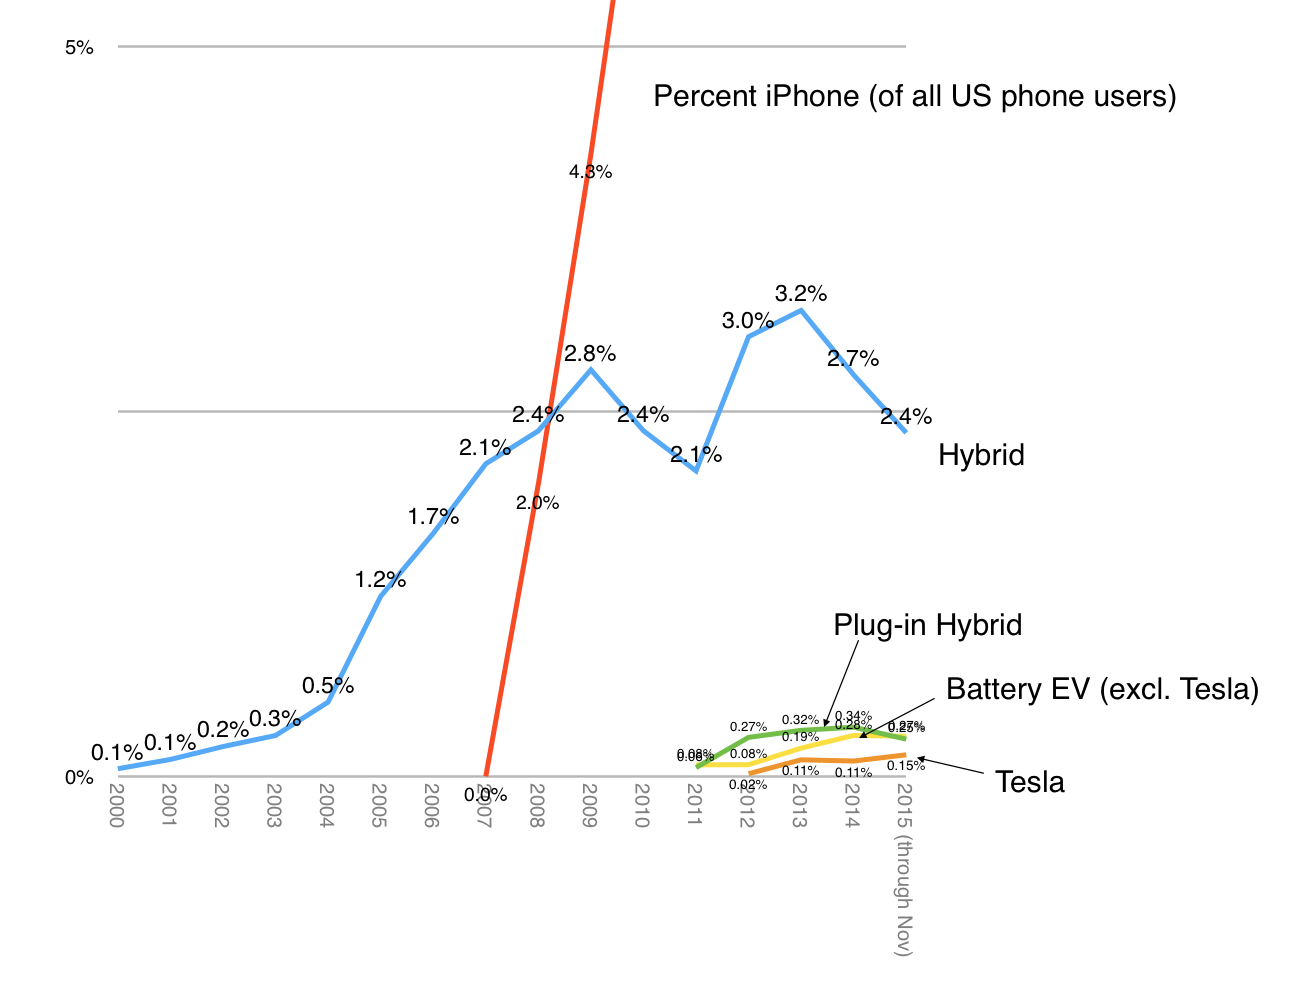
Fortunately, we have something to compare an Apple entry to. Apple has made a "significant" market entry in phones and others have made entries in cars. If we contrast the rate of growth of Tesla, EVs, and Hybrids ((Of which Toyota has 70% to 80% share)) to the rate of growth of iPhones in their respective US markets, we obtain a test of significance:
The graph shows the percent of sales for the alternative car technologies (and Tesla) vs. the percent of US phone users using iPhones (comScore). Here are the conclusions:
Hybrid cars were introduced in 2000 in the US. They managed to gain 2.5% within 8 years but have not increased to a consistently higher level since.
Electric vehicle sales re-sarted in earnest in 2008 and have gained 0.4% share in eight years. They are still growing, partly helped by significant federal and state subsidies.
Between sales start in 2008 and 2015 Tesla achieved 0.15% share.
The iPhone ushered in a new paradigm within the phone market ((Incidentally the number of phones in use and cars in use in the US is comparable.)) in mid 2007. In the time since, Apple achieved the equivalent of about 35% share of unit sales. ((Significantly more in terms of sales value and over 90% of profitability.))
Between 2002 and 2015 the share of smartphones as a percent of all phones reached over 80%.
To summarize, the range for entrant technology share capture spans between 0.4% (EVs between 2008 and 2015), 2.4% (Hybrids between 2000 and 2015) and 80% (Smartphones between 2002 and 2015).
Within a similar time frame, the range for entrant company share capture spanned between 0.15% (Tesla as percent of US car market) and 35% (Apple iPhone percent of US phone market). ((Toyota's capture of 2% of the market with hybrids may or may not be considered entrant--I chose to consider Toyota an incumbent which took share from others with the Prius))
The differences thus span two orders of magnitude (>100x). Put another way, if Tesla's car entry was equivalent to Apple's iPhone entry they would have delivered about 5.5 million cars rather than the 50.5k they delivered in 2015.
This wide gap in the impact of entry in the two markets has much to do with how modular are the systems being engaged by the entrants. An electric automotive system requires new infrastructure, new user behavior, and, in the case of Tesla, new distribution network and new post-sales support network. Offsetting this partially is a government subsidy.
In contrast, the smartphone communications and computing system leveraged existing infrastructure ((And vice-versa)), consistent behavior, at least initially, and the same distribution and support network. In addition, smartphones benefited from significant hardware and software and services ecosystems which encouraged third parties to add value to the system.
The difference in collaborative development and conforming user experiences (i.e. modularity) between the two innovations allowed the speed of change to be two orders of magnitude faster. The result is what I would consider significance for the iPhone vs. insignificance for electric vehicles to date.
Which leads us back to the question of why Apple would enter this market. If the absence of modularity prevents rapid change, that implies Apple cannot achieve any significant impact from entry.
We could ask the question differently: If they do enter, they could achieve significance only if they change the degree of modularity in the system. Think of it as allowing infrastructure leverage, consistent user behavior, wide distribution, wide support network, ecosystems, and component architecture; allowing rapid scale production and lower costs, etc.
Therefore the only way that Apple could justify entry would be if they "rationalized" the system into a sufficiently modular alternative. Only if we assume that change is possible could we then target share above the 0.1% insignificant change that has been demonstrated. They might even perhaps aim at 1% impact within a few years of entry. 1% was the iPhone target within the first full year of sales.
If system-wide change could be brought about and made uniquely (through some form of sustainable asymmetry) then the foreseeable share possibility quickly reaches the 10% range.
The last time that happened was when Toyota changed the way cars are designed and built. ((VW before Toyota and GM before VW. Incidentally Toyota, GM and VW are now nearly tied as the top three automakers globally.))
What if Apple did make a car? How significant could their products be? What would it take to influence the industry's architecture?
The global market is forecast to reach 88.6 million vehicles in 2015 and there are many ways to segment it. One could look at geography or at product configurations or the emergence of new powertrain technologies.
One could also look at the participants.
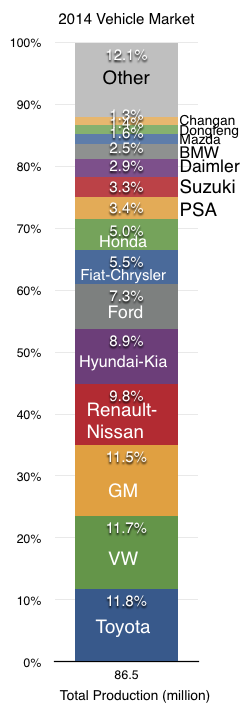
In 2014 Toyota was the top selling automaker with a total sales volume of 10.23 million vehicles. The following graph shows the leading 15 producers and the percent of total production.
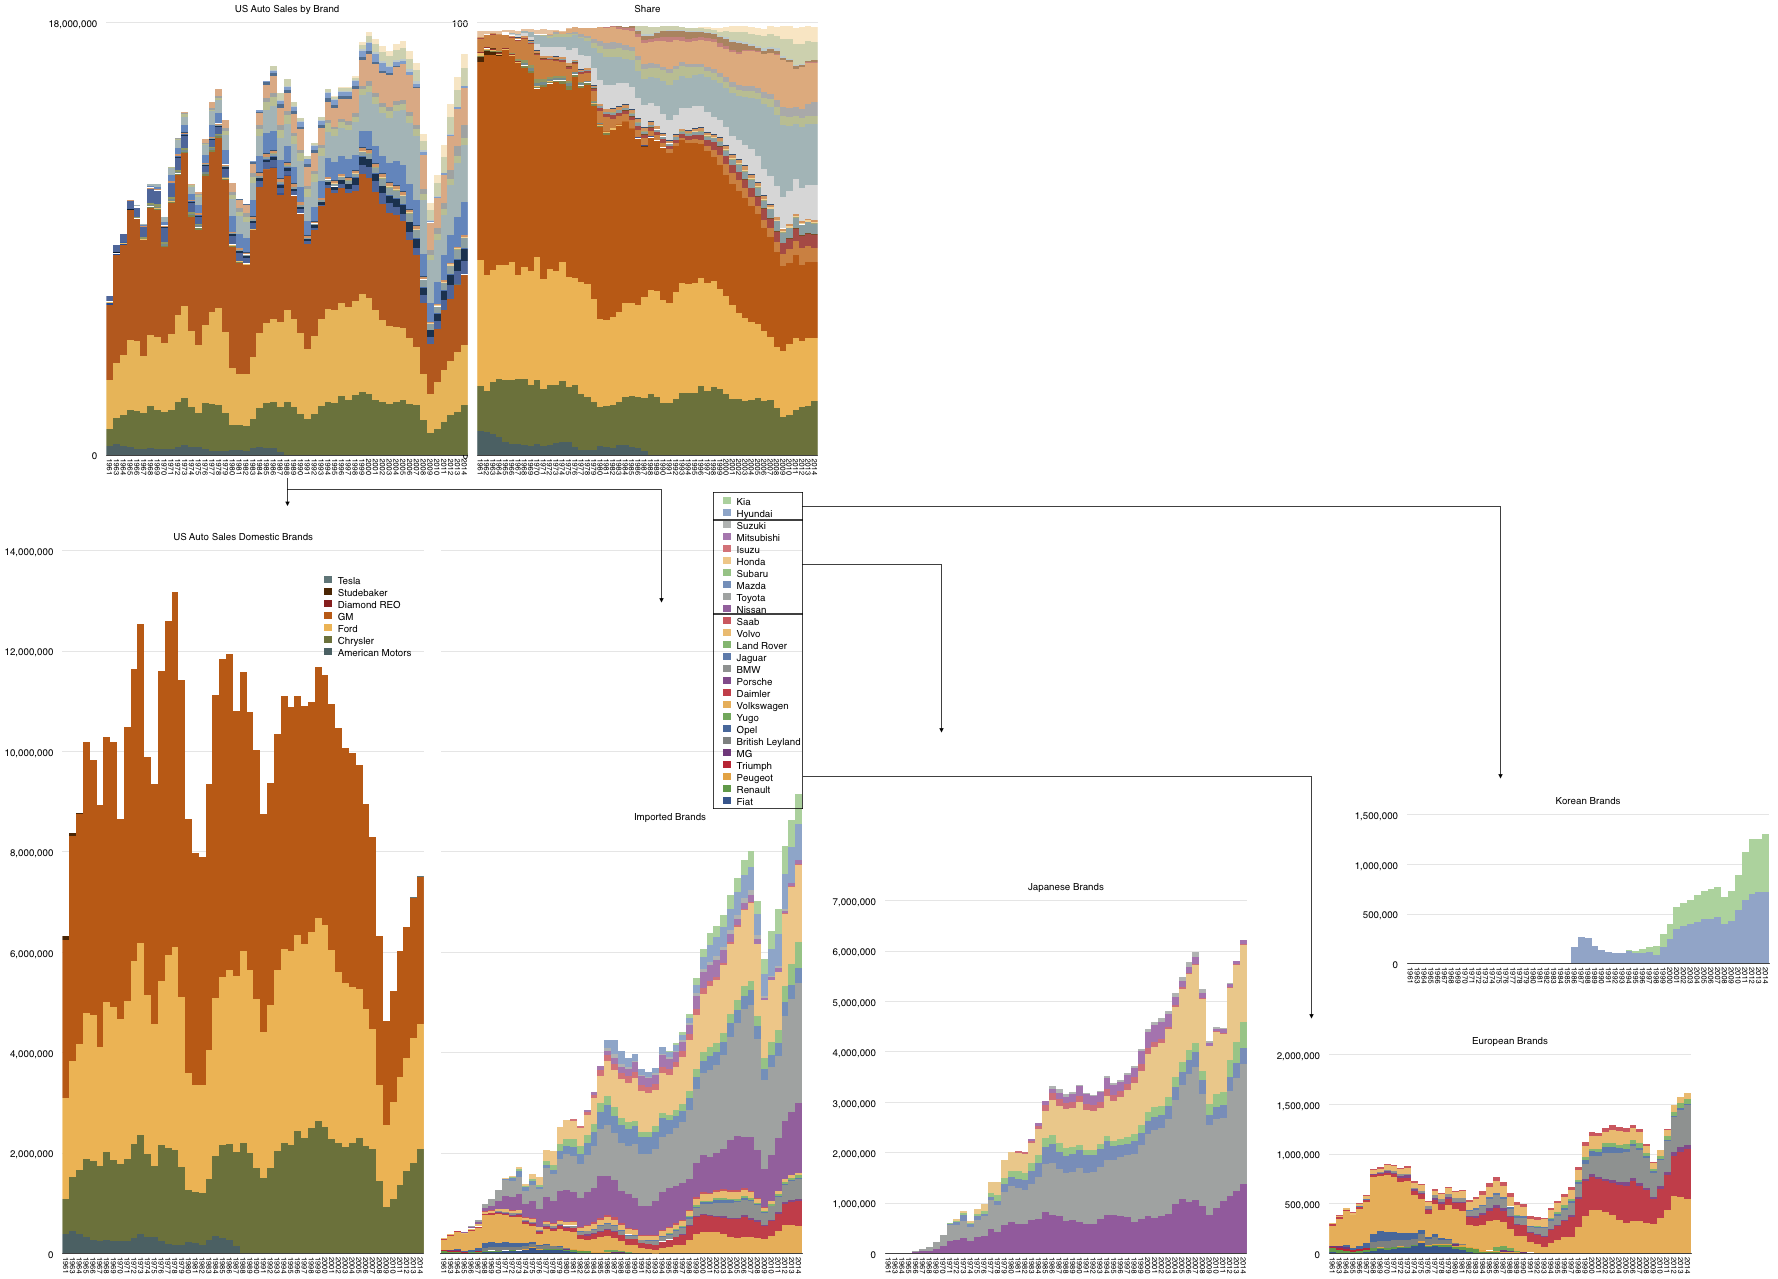
One thing to note is the relative balance in market share. The top five vendors have volumes in a very similar range (9 to 12 million). Two vendors are at around 5%. Three are at 3%. To preserve this equilibrium the industry undergoes periodic merging and consolidation. Over the last half-century, there has been room for new entrants. Japanese brands entered between the 1960s and 1970s. Korean entries occurred in the 1990s and Chinese in the 2000s.
Regardless of the entries, the industry has a high degree of centralization. Ownership is often more narrowly controlled through cross-ownership and licensing. French/Japanese, US/Italian/German, Indian/German/UK cross-over ownerships indicate a globalization of financing. Indeed, only a dozen countries account for over 80% of the production (less than 10% of nations produce significant numbers of vehicles).
This structure is driven by the cost structure of volume production. The production system dictates financing and location and time constraints which underpin all deals. None of the entries (Japan, Korea, China) did much to redefine the core industry architecture (resources, processes or priorities).
So how could Apple think different?
First, the model of production could be substituted with a modular approach. This would separate the engine/body/paint/assembly plant into a deeper supplier network where components would be sourced and tooling dependence would be reduced.This speeds up ramps, reduces capital expenditure, increases flexibility, and accelerates the cadence of product evolution. Essentially, the focus would shift away from manufacturing toward design, iteration, customization and experience engineering.
Second, Apple could change the distribution model. Controlling the relationship with the end user could allow a conversation which will reveal new jobs to be done.
Third, Apple could affect the vehicle's lifespan and hence the financing/resale and inherent brand promise of car ownership.
These are fairly obvious business innovations and they are easily foreseen.But are they enough? Would they even "move the needle"?
To break into the top 10 brands would imply a production volume of at least 2.5 million units (about the same as Daimler ships today.) At 2.65 million and a price of $55k/vehicle Apple's revenues from cars would total about $145 billion. This is roughly the sales value of the iPhone business today. Not bad. Maybe that would satisfy a financial analyst. ((Yeah, right.))
Even so, would a top 10 rank in shipments change the industry's structure?
When I first saw the iPhone I knew that nothing would be the same after it and that Apple was poised to dominate the phone business. For the Apple car to do a similar trick in transportation the product itself has to change the perception of what a car is. Today a phone is barely something one speaks into.
Approaching the operations side of the business with a clean sheet of paper allows a fresh and rational attack on the problem. But to really make a dent in the universe Apple also needs to change the product in ways that re-define what it's good for. And this is supposedly why Apple gets into markets. To make a meaningful contribution.
Apple is categorized as a vendor of consumer electronics. More specifically, a member of the "Electronic Equipment" industry in the "Consumer Goods" sector. If indeed this is what it's thought to be selling, there is a problem because it isn't what its customers are buying.
Apple's customers buy a mix of hardware, software and services under a brand that assures a certain quality of experience. This bundling and integration of otherwise disparate things is why the brand is such a success.
This anomaly between what Apple is thought to sell and what buyers actually buy can leave the casual observer confused. As a result the company's categorization as vendor of hardware deeply discounts its shares. It is, in other words a less valuable business. This is because a seller of consumer electronics does not benefit from "system valuation" since there is minimal loyalty to the product after the sale.
The consumer electronics vendor has no network to leverage, no ecosystem adding value after the sale, no platform and works through multiple levels of distribution to reach the customer. In contrast, a system vendor can expect benefits from network effects, ecosystems, and a coveted relationship with the end user.
The result is that the valuation of a consumer electronics vendor is based on the momentum of individual products. Apple has always been valued this way. Each hit product is considered to be a stroke of luck/genius and the chances of recurring are discounted to about zero. Regardless of the fact that it has a track record of "home runs", Apple's hit rate is not considered sustainable. ((The P/E ratio is the primary indicator in this analysis)). Certainly Apple is not valued as being able to generate reliably recurring revenues.
But what if we were to value Apple on the basis of what people are buying rather than what it's thought to be selling?
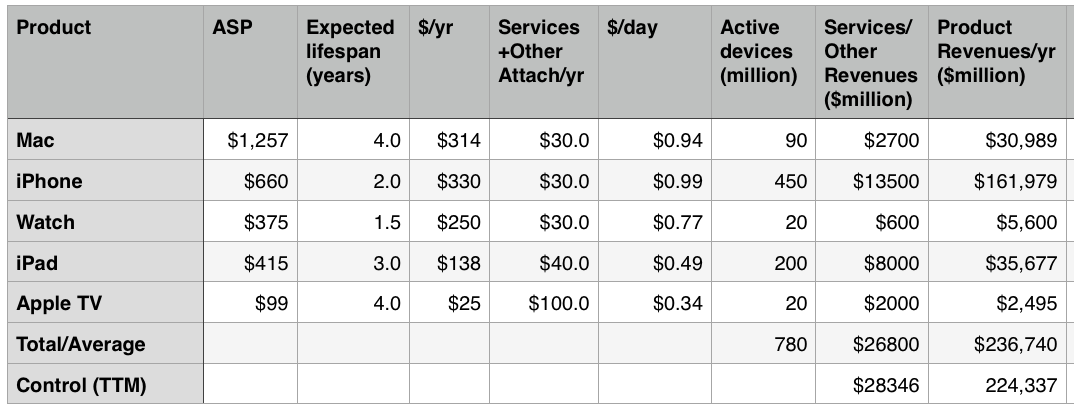
The model is simple enough: determine the number of users, estimate the lifespan of the products, and figure out the services attached to the products; then, given the price, obtain a price per product per day. You then can get a recurring revenue figure.
I did just that and the results are in the following table:
The first column is the product, the second is the Average Selling Price (ASP), the third is the expected lifespan of the product, and the fourth column is a calculation of the end user’s “spending per year” on the product.
The fifth column is an estimate of the revenues from Apple's Services and "Other" groups from post-sale revenues attached to the product. This Services revenue includes AppleCare, iCloud, Music, App Store, other stores, Beats, accessories, iAd, and Made for i (MFI) licensing. It also includes Google traffic acquisition revenues and other licensing.
The sixth column is an estimate of the consumer "spend per day" on Apple's product lines taking into consideration Services.
The seventh column is an estimate of the number of active devices in the hands of users. Note that these are expected to change over time.
The eighth column is a calculation of Services/Other income on a per-product allocation. This is a test of the Services+Other estimate and is meant to sum to nearly what Apple currently reports as Services+Other revenues.
The ninth column is a test of overall revenues on a per-product allocation. This should add up to total revenues (estimated for next year.) ((Naturally, the active devices estimate is the most sensitive but it should be tweaked to create a reasonable forecast for next year.))
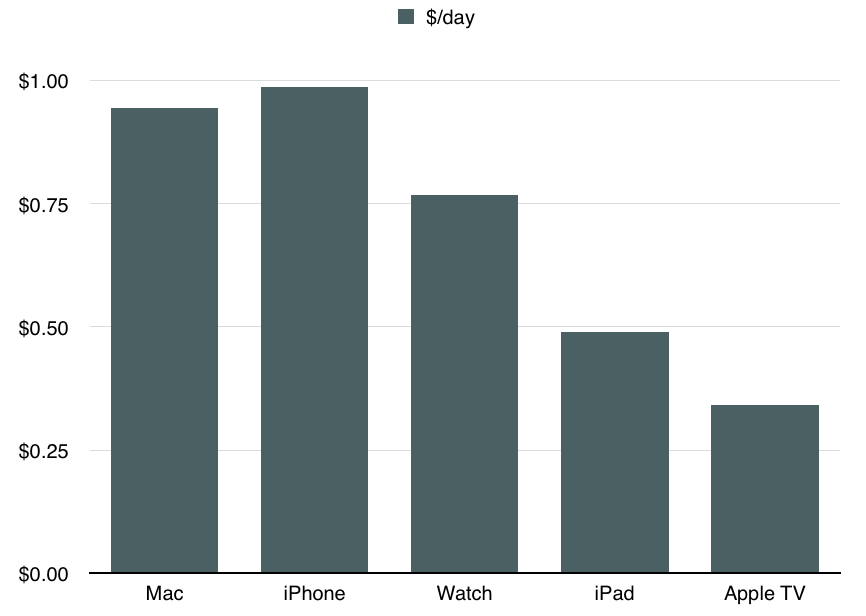
The bottom line is the following graph which shows the revenue per device per day inclusive of Services and Other income (The sixth column).
This is, in my opinion, a reasonable way to approach valuation of Apple as a business. It's also a way to inspect its strategy.
As a valuation we can easily obtain the net present value. The model gives us sales and by estimating a net margin (which is remarkably steady around 22%) we can get the free cash flow.Iterate into perpetuity with a discount rate, and you can get the net present value of the company. With a modest growth rate leading to a billion active devices in use and a normalized revenue per device of $0.92 you can easily see cash flows equivalent to $1 trillion in present value.
But much more interesting than this value is the notion that Apple is in business to deliver a product/service mix to loyal customers and to preserve their loyalty through constant improvement and innovation. You can see strategic intent in increasing the attach rate of services per device. You can see a strategic intent in building loyalty and the right customer base which is likely to be loyal. You can see strategic intent in the iteration of the product in a way that extends loyalty and expands the solid base but also increases the $/day rate. This analysis correctly informs almost all decisions the company makes.
What we just saw in the launch of a new Apple TV and a new iPad is consistent with this strategy. Apple TV will have a higher service attach rate with apps while keeping pricing well below consoles thus expanding the user base. The iPad is increasing in price and getting more accessories. The developers are encouraged to build richer and more valuable apps that are uniquely enabled by the new device.
The fact that Apple has just launched a subscription service for the iPhone makes what was clearly their strategy all along plain to see however it has been a strategy in effect for decades.
It isn't a difficult idea to embrace. It always surprises me that it's not more commonly held. The reason may be that Apple is mis-categorized.
Or perhaps the entire categorization of industries and sectors is obsolete in what is a new post-industrial age. Some have figured this out already. Others will take longer.
When exactly did enterprises become late adopters of technology? We know that they were some of the first buyers of computers. IBM sold tabulating and later computing machines to businesses starting in the 1910s. During the 1980s it was businesses which bought PCs in significant numbers to augment, and later replace, their centralized computing resources. Networking was in use in government and in business long before consumers saw any value in it.
In my talks I often point out that if you wanted to create a near-monopoly in computing in the 1990s all you needed was to convince 500 people to adopt your technology: the IT managers of the Fortune 500. If the largest companies used your product then they would impose the standard on all their suppliers and distributors and pretty soon there would be no alternatives.
So what happened during the last decade or so?
Today IT departments are known as the Information Denial department. I recall that when the DVD first became an option on desktop or laptop computers, IT departments were first to decline the option (presumably because it would be used for entertainment rather than work.) When instant messaging first became available, it was IT departments who blocked the ports. When mobile devices with cameras became available signs went up that no cameras would be allowed on company premises. When USB sticks became available, USB ports started getting glued shut. When iOS became available, no devices running it were allowed on the network. Then came Facebook, Instagram and dozens of social media.
This pattern of not only a refusal to adopt but an outright ban on new technologies by enterprises made them fall off the radar of technology developers. Quite simply everyone outside the supply chain into enterprises stopped developing new markets around them. From venture funds to developers, enterprises fell out of the business plans.
The enterprise stood as a place of "legacy" and "security" which prevented mobile or other forms of computing. Paradoxes emerged wherein an administrative assistant had more computing power in his pocket than the CEO had in her data center; where the same assistant would know what was happening faster than any of the bosses. Homes had better connectivity than offices and productivity at small firms increased faster than at big firms. Incidentally, even the slowest enterprises were faster then the government. The bigger the firm, the slower and stupider it seemed. Were large firms employing dumb managers or did being a manager in a large firm make you dumb?
One resolution to this paradox might be that mobility and the movement of processing onto consumer devices increased the cadence of product development to such a degree that the purchase cycle and dollar amounts involved ran out of the range which companies could absorb.
A simple way to explain it is this: A company takes longer to decide to purchase a device than the device's shelf life. In other words, by the time all the salespeople and committees and standards setting and golf playing and dining and site visits would be completed, the object whose purchase was being discussed would be discontinued.
A more onerous issue is that companies have procedures for accepting technologies (capital expenditures) which require high degrees of interaction and decision making. In order to step though these procedures, the vendors need to have sales people who need to invest lots of their time and therefore need to be compensated with large commissions. If those commissions are a percent of sale then the total sales price needs to be large enough "to make it worth while to all parties". As a result, paradoxically, an enterprise technology must be sufficiently slow and expensive to be adopted.
Mobility was disruptive to enterprise because the new computing paradigm was both too fast and too cheap to be implementable.
This implies that the problem with enterprises is not the stupidity of its buyers. They are no less smart than the average person--in fact, they are as smart with their personal choices for computing as anybody. The problem is that enterprises have a capital use and allocation model which is obsolete. This capital decision process assumes that capital goods are expensive, needing depreciation, and therefore should be regulated, governed and carefully chosen. The processes built for capital goods are extended to ephemera like devices, software and networking.
It does not help that these new capital goods are used to manage what became the most important asset of the company: information. We thus have a perfect storm of increasingly inappropriate allocation of resources to resolving firms' increasingly important processes. The result is loss of productivity, increasingly bizarre regulation and prohibition of the most desirable tools.
Which brings us to the latest announcement of collaboration between the new disruptor of computing Apple and the vendors supplying Enterprises like IBM and Cisco.
Apple was the loser in the standardization of computing during the 1990s but is the winner in the mobilization of computing during the 2010s. The company positioned itself in both cases on consumer computing but it never gave up on enterprises.
The approach of Apple seems to be to enable the larger suppliers of technology to enterprises to bundle iOS as part of the acceptable set of services and products. In essence, Apple is complying with the requirement to be slow and expensive in order to be adopted. It can maintain the cadence of product development while attaching itself to the purchase cycle of the enterprise.
In a way it's like an automatic transmission in a car. Operating through gears, the engine can rev at a different rate than the wheels turn. Occasionally, shifting happens but the fluid coupling keeps both the engine and the wheels from absorbing any damaging shocks.
Eddy Cue seems like a nice guy. I can't say that for sure as I've never met him, but he seems to be amiable enough. Maybe it's because he has a seat on Ferrari's board of directors. Maybe it's because he enjoys dancing.
Or maybe it's because he's in charge of the only real "division" at Apple. All the other senior managers have functional roles. Eddy has a bona-fide business unit called Services.
Services is Apple's division of many things. It has the iTunes stores (Music, Video, Apps and iBooks). It has Software with consumer bundles like iWork and iLife and Pro tools like Aperture, Final Cut Pro and Logic Pro. It still has OS X as a product, though revenues are pretty low as updates are now free. It also includes Services with iCloud, Apple Music and Applecare.
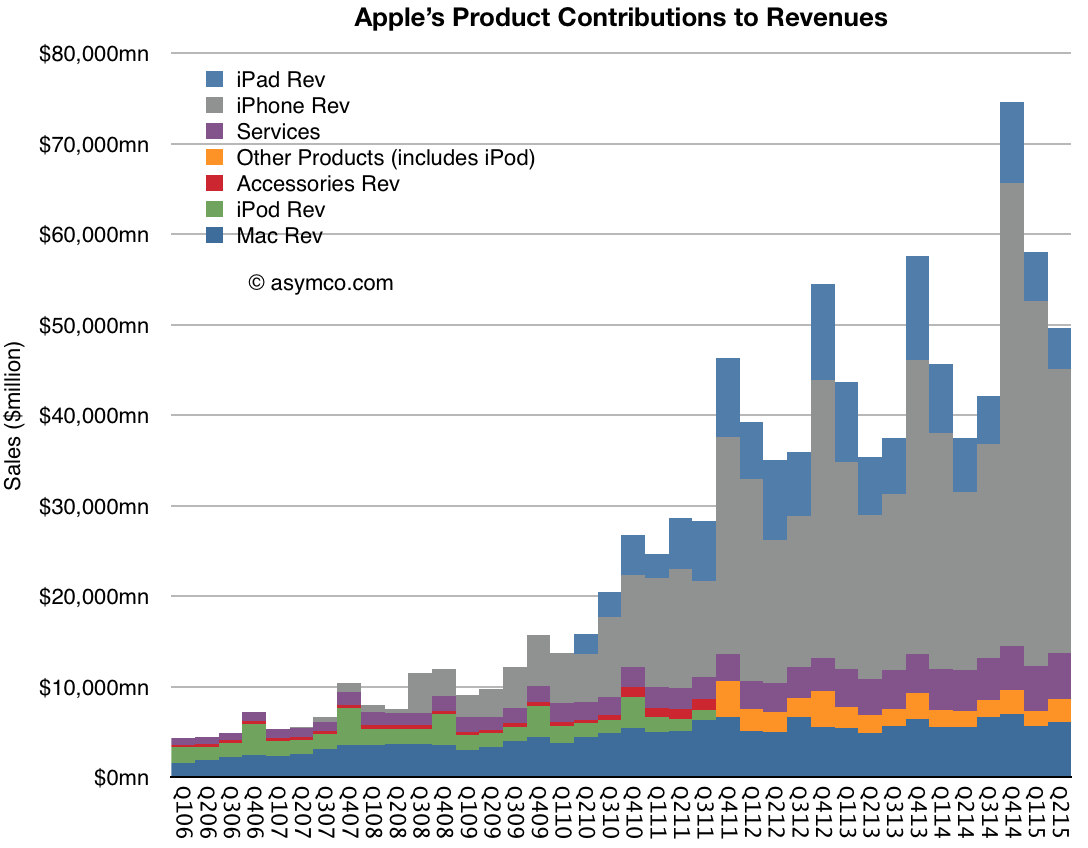
These things are not iPhones or iPads but they are many and all together they form a modest little unit. I say modest because not much is said about it. When seen in contrast to the other Apple product lines, it's hard to be impressed. In the graph below it's the purple area.
Apple does not help much. Occasionally Apple offers updates on iTunes/Services using various (rarely the same) metrics. For example, in early August, Eddy Cue offered an update during an interview with USA Today on Apple Music relating how many users there were one month after the service started (11 million). It was worth a few headlines.
However he also noted in passing that the App store did $1.7 billion in transactions during July. If you convert that to a yearly run-rate it comes out to about $20 billion/yr. Digging through previous announcements, the equivalent figure for 2014 was about $13.7 billion. Nice growth.
But is $20 billion of "transactions" of any significance? It's not even a figure that Apple reports as revenue. For apps, Apple reports only the 30% fee as revenues so 70% of that transaction value passes through to developers and is therefore not part of its statement of accounts. ((From SEC filings: For third-party applications sold through the App Store and Mac App Store and certain digital content sold through the iTunes Store, the Company does not determine the selling price of the products and is not the primary obligor to the customer. Therefore, the Company accounts for such sales on a net basis by recognizing in net sales only the commission it retains from each sale. The portion of the gross amount billed to customers that is remitted by the Company to third-party app developers and certain digital content owners is not reflected in the Company’s Consolidated Statements of Operations.))
However perhaps we should consider the figure in some way. It represents transactions in an economic sense--the amount people spend on apps. It's therefore comparable with what people spend on other forms of entertainment. Movies for example.
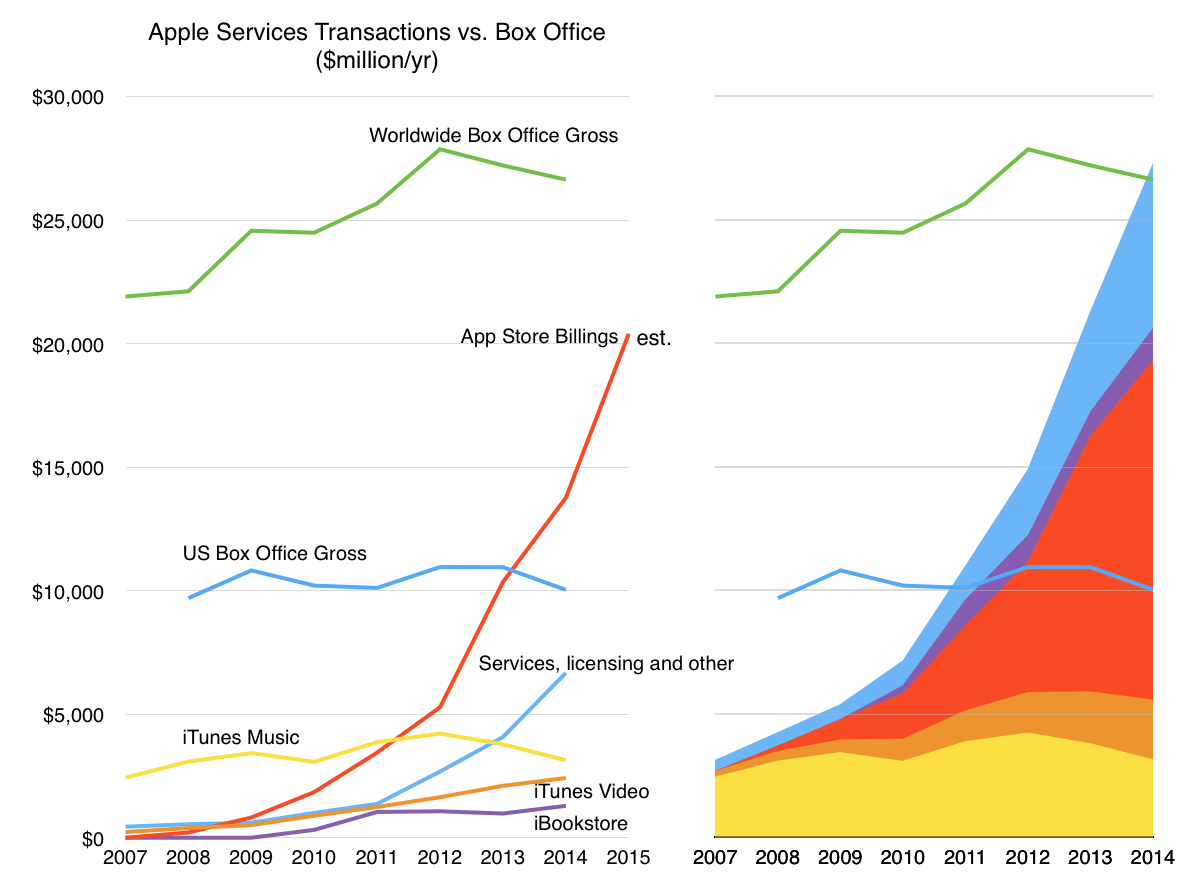
The following graph shows the spending on apps within the iTunes App Store ((note that this does not include Google's Play Store whose transaction values are not public and is therefore not a gauge of all apps.)) as well as spending on other forms of iTunes stores as well as Services. It also shows how all the services compare with box office revenues from movies. Both the US and World-wide. And how these figures changed over the few years that the App Store has been in existence. The individual service line items are shown in the graph on the left and the stacked totals are on the right.
Note that already last year App Store Billings overtook US Box Office gross revenues and that Services a whole overtook Global Box Office gross revenues. It's not likely to happen this year but next year Apple's Apps will almost certainly overtake global Box Office in revenues.
This contrast with movies gives some perspective on the creation of a new market. Apps did not exist as a medium in 2007. But, together with Android apps, apps are likely to have already overtaken revenues from an industry that is a century old. And not just any industry. Hollywood represents more than an economic power, it has a cultural power affecting perceptions and political opinion. And although universally envied, it has not been successfully replicated.
So having created this market and becoming bigger than Hollywood, and grossing more than what 90 countries produce, Apple's Services not something that is interesting to many who think about technology or even to many who think about Apple.
Which is why I think Eddy's such a nice guy. No matter how little attention is paid to his economic empire, he always seems to be in a good mood. Maybe he knows something we don't.