Asymco

Asymmetric Intelligence

share

  1. Measuring Mobile Platform Churn in the US Market

    Research · 48 comments

    The following chart shows the net gains in users for the major mobile platforms in the US. The data is derived from comScore's MobiLens report.
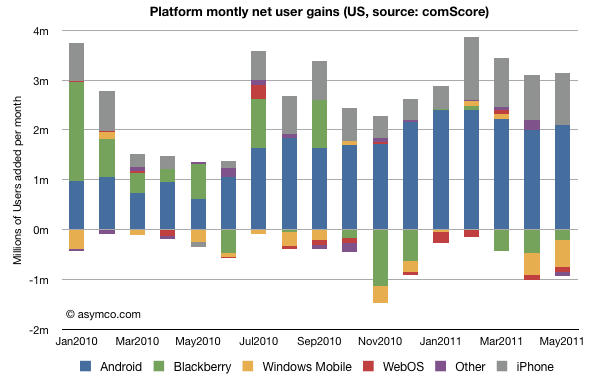
    The raw numbers for the last period (ending May) are:

    1. Android gained 2.1 million users
    2. iPhone gained 1.0 million users
    3. WebOS/PalmOS lost 96k users
    4. Blackberry lost 202k users
    5. "Other" lost about 95k users

    The "churn" or percent of smartphone users who switched platforms is 1.22%/month  of the overall users (assuming users to left one platform moved to another rather than to non-smart devices.)

    The share of the platforms and the overall composition of users is shown in the following two charts:
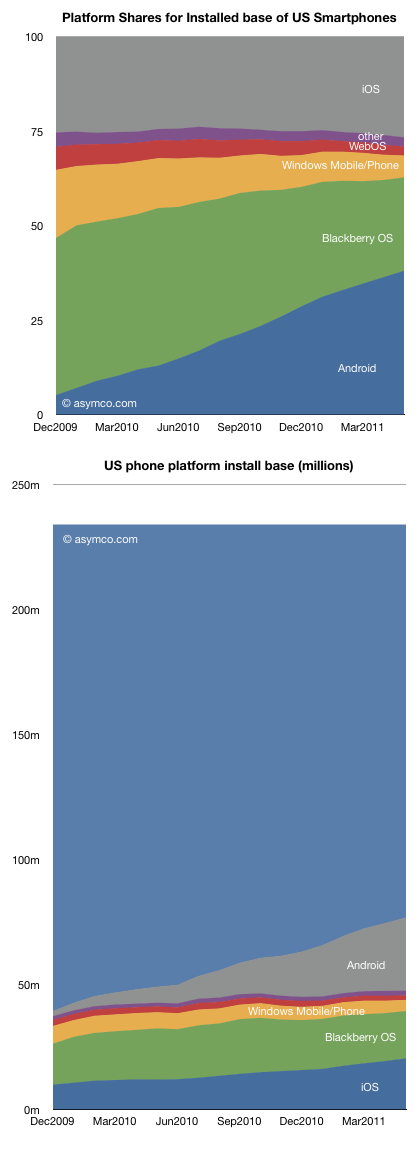
    As usual, caution should be exercised when looking at share (top chart) outside the context of overall growth. The second chart may be more illustrative of what is happening. The light blue area on top is the smartphone non-consuming population.

    Android has been a tremendous accelerant of smartphone adoption while iOS has grown as well but share has not grown significantly. iPhone growth has kept up with market growth. This cannot be said for the other platforms which have been "squeezed" between these two entrants.

    So although the main competition is with non-consuming users and smartphones are winning in general, the loss of users by some of the incumbents is unsettling.

    Microsoft lost just over 2 million users in the US last year while RIM lost a net of 1.5 million. Palm lost about half a million. Contrast this with 8.5 million iPhone additions and 23 million new Android users.

    In particular, Windows Mobile/Phone is down to 5.8 million users (down from 18m in December 2009). With a loss of half a million per month, and share down to 4.5%, a lot is riding on the new platform.

    I've argued that the post-PC era will be a multi-platform era. Although it may seem that the situation in the US is rapidly moving toward a duopoly, it may not end up that way. Note how much non-consumption still exists.

    Note the time frame of the charts is only 18 months. The rapidity with which platforms gain ground could allow for continuing platform churn.
  2. The iPhone at four; growing up or just growing?

    Research · 74 comments

    Ever since the iPhone launched four years ago (to the day), the question on everyone's mind has been: When will Apple expand the portfolio to reach into all market segments? I remember thinking in 2007 whether it would be in six months or a year that they would create a "mini", "nano" and "classic" line-up which served them so well with the iPod.

    Apple however took a different approach. To their credit, they focused on the platform and built a consistent experience around a fixed screen size to nurture an ecosystem. They also improved the power of the device so that experience would improve to be better and more robust. In other words, they treated every iPhone as not being good enough, needful of every megahertz of power, every pixel of screen and every minute of battery life. They polished the OS constantly and added APIs by the thousands.

    In other words, they acted like a computer software company, not like a "device vendor" or like a handset manufacturer which was everyone's (including mine) frame of reference.

    Having expanded from iPhone to iOS and built the platform into non-cellular centric computers like iPad and iPod touch, they clearly showed a nonchalance about the operator channel and the amplification power it offers (an amplification which comes with a hefty price of dependency and strategic illusion.)

    But the mind always wonders back to the question of portfolio. Now that the product is maturing, the hardware is getting nearly "good enough". Perhaps even Apple might now consider letting go of the "frontier" of what's technologically possible and consider expanding its reach to the broader audiences it has willfully kept out of reach.

    And broad they are.

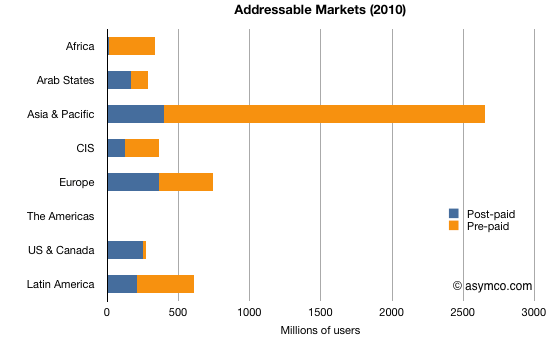
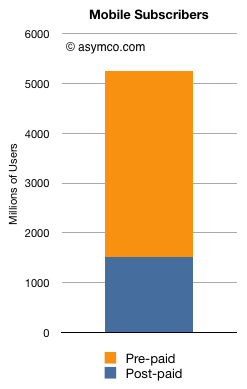
    Based on data published by Deutsche Bank and the ITU, we can calculate roughly how many customers Apple's current iPhone positioning has left unserved. I chose to use pre-paid/post-paid split as a proxy for unaddressed/addressed. This is an imperfect proxy but a pretty good one as most pre-paid subs see a full price for the iPhone (retail around $700 to $1000) vs. post-paid customers seeing a price of $200 or below. The $200 happens to be an important psychological price inflection point where volumes increase dramatically.

    The first chart shows the global split between pre-/post-paid subscribers as of 2010. Roughly 1.5 billion are post-paid and 3.7 billion are pre-paid. That means that nearly 70% of the world is not being addressed by the iPhone as it currently stands. Put another way, a shift in positioning might result in a 250% increase in addressable market.

    Tim Cook alluded to this in the last conference call when he said pre-paid markets, especially in China, are huge with share figures "starting with a nine". He also said separately that they would not be ceding any market--a hint if there ever was one, given the broadening of Android into previously feature-phone price bands.[1]

    We can even see the situation more clearly on a regional scale. The following chart shows the same pre-/post-paid split by region.

    You can visualize the iPhone having spent the last four years penetrating into the blue areas of the chart through the expansion of carrier agreements. With half the US & Canada area being finally filled in this year, most of the blue is now more-or-less within reach.

    Given the constraints on production, and given the improvements in the product and the improvements in the hardware (learning curves and price points) it may mean that Apple could finally be turning its attention to those orange areas.

    The time may be soon at hand that maturity coupled with limits of organic growth are leading the four-year-old iPhone to finally be re-defined as more than a post-paid skimming entrant. It may be time for the iPhone to more than just grow. It may be time for it to grow up and take on the whole market. Five billion people are waiting.

    ---

    Notes:

    1. Contrary to a commonly held belief, Apple does not shy away from market share. In the case of the iPod and even the original Apple 2, the company sought and obtained the top share ranking. In fact, the decision to pursue share vs profit is "context sensitive". Steve Jobs, at least, thinks so.
  3. Thinking over Apple's value

    Research · 71 comments

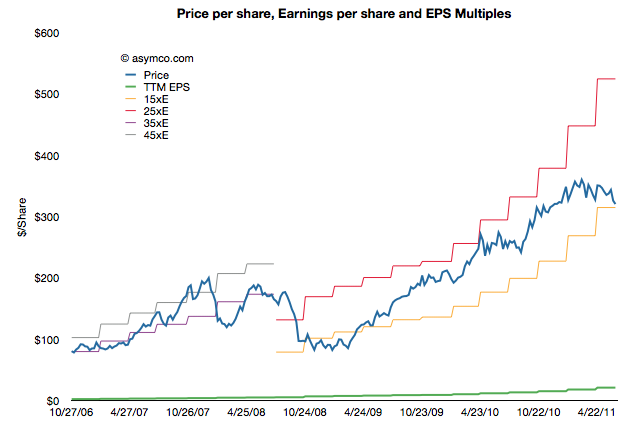
    In intra-day trading Apple's stock price traded at a P/E ratio below 15. That threshold is now at a price of about $315/share. Excluding cash the P/E is under 12. On a forward basis, there is widespread agreement that Apple has the reward (yield) profile of a bond without the risk of inflation.

    The history of the P/E ratio and the share price is shown in the following chart:

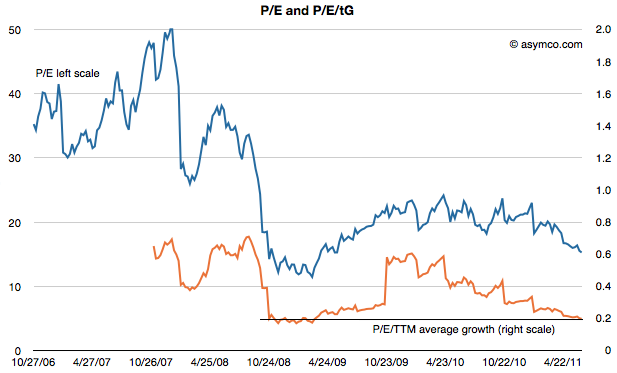
    As the chart shows, Apple traded in a range of P/E between 35 and 45 until late 2008 and has been trading between a range of 15 and 25 since about spring 2009. It might seem that the price is rewarding growth, but it's not.

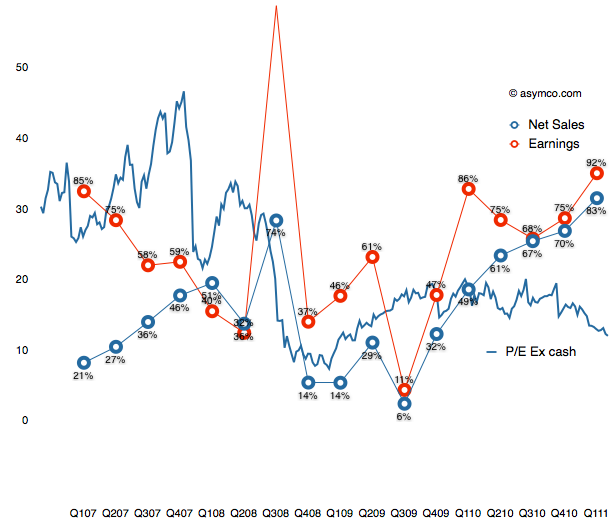
    When adjusting for the growth the company has maintained, the company is at a similar P/E/tG (Price/Earnings/trailing Growth) to the depths of the recession.

    At the trough shown above, the company was growing earnings at high 30% rates and sales in the teens. Today the company is growing earnings at 92% and sales at 83%. the following chart shows P/E ratio vs. growth.

    From a historic perspective, Apple is as cheap as it was at the bottom of the recession. At the time there were many reasons given for why the company would suffer 'headwinds'. Most commonly cited was that the company was a maker of "luxury" products and luxury does not sell in a recession.

    Today reasons being given for why the company will not prosper are far more nuanced. I won't re-iterate them but they deal with competition, platform issues, production issues, sympathy with companies that are failing, and saturation of markets.

    The trouble is that these arguments are easier to refute than the luxury vs. economy argument.  Exactly because the arguments are more precise, there is data that can be used to counter pessimism.

    And yet, with or without data, markets sometimes decide that profits are not reliable indicators of value created or potential for value creation.

  4. Peak RIM

    Research · 37 comments

    In their monthly survey update on US phone usage, comScore reported that by the end of April 74.6 million people in the U.S. owned smartphones. In the same period a year ago only 48.1 million did. The percent of smartphone users out of total phone users has reached 32%.

    The following data points can also be deduced:

    • 2.1 million or 474k people/week became smartphone users during April.
    • 62% of smartphones in use in the US are either Android or iOS. The sum a year ago was 37%.
    • There are about 20 million iPhone users and 27 million Android users in the US today. A year ago there were 12 and 6 million respectively.
    • RIM's US user base peaked at 22 million in Sept 2010. It is now 19 million and dropping.
    • Usage of Microsoft mobile operating systems in the US is in steady decline dropping from 7 to 5 million users in one year.
    • During April 475,000 people abandoned their Blackberries.
    • Android and iOS gained 3 million users in April. One million switched from other smartphones and 2 million switched from non-smartphones.

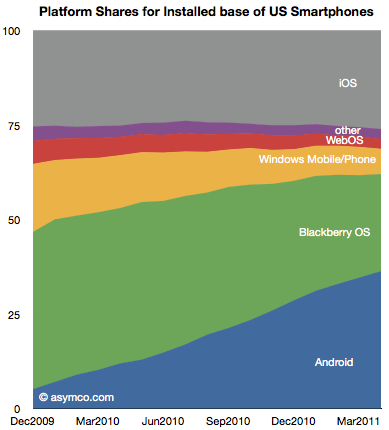
    The following chart shows the evolution of installed base share of platforms among users of smartphones in the US.

    The impressive share gains for Android are apparently at the expense of RIM and Microsoft. Over the period shown, Android gained 25 million users while RIM gained only about 2.8 million.

    Although perhaps comforting to see some growth overall, the situation for RIM is more grim than that. During the first half of the period (December 2009 to August 2010) RIM had gained 4.6 million users. During the second half (Sept 2010 to April 2011) RIM lost 1.8 million users.

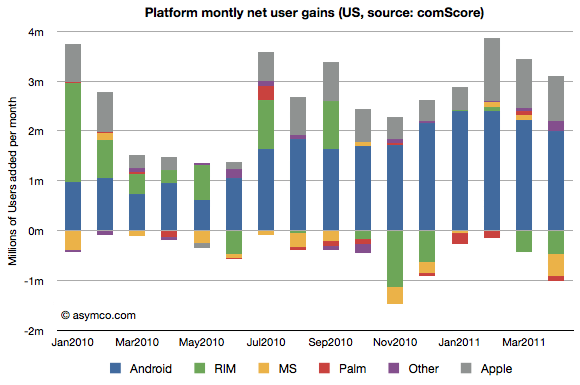
    The net user gains and losses for the various platforms is shown in the following chart:

    Note how RIM (green bars) went from being a consistent net usage gainer to a consistent net usage loser during this 16 month period. In addition, note how Microsoft's platforms (yellow bars) have had a very poor showing with very small gains during four months and moderate losses during the others. The losses in usage even increased after the release of Windows Phone late last year suggesting no traction whatsoever for Windows Phone.

    The other point to be made is that if we assume smartphone users remain smartphone users, then those platform losses are gains by other platforms. In other words, the areas less than zero in the chart above represent smartphone "churn" or switching between platforms (As a percent of all smartphone users that number represents 1.35%.) That number is far lower than the total smartphone gains, so it's safe to say that most of the iOS and Android gains were at the expense of feature phones rather than other smartphones. And since iOS share is consistent (and supplies are constrained), few if any Android gains are at the expense of iOS.

    There are many interesting patterns to observe in the data, but I think the most evocative is the erosion of Blackberry usage. If the Blackberry peaked, and a follower platform not yet in sight, the question is how long will RIM survive?

  5. Does the phone market forgive failure?

    Research · 59 comments

    One of the details of Nokia's warning which did not get a lot of attention was the mention that profitability for the current quarter could not be guaranteed. That is to say that Nokia may make a loss, perhaps for the first time in more than a decade.

    This may not be that newsworthy except for the strange fact that as far as I've been able to observe, any company in the mobile phone market that ended up losing money has never recovered its standing in terms of share or profit (i.e. AMP index value has never recovered).

    Here is a list companies that have "hit the rocks" in terms of mobile phone profitability and their fates (in no particular order).

    1. Alcatel of France. Sold its brand and operations to TCL Communications of China in 2004.
    2. Siemens of Germany. Exited in 2005 through acquisition by BenQ of Taiwan.
    3. BenQ of Taiwan. Mobile devices division declared bankruptcy in 2006.
    4. Ericsson of Sweden. Exited by merging with Sony in 2001 even though third in volume share the prior year.
    5. Sony of Japan.  Joined with Ericsson to form Sony Ericsson in 2001. Held less than 1% share prior to merger.
    6. Motorola of the United States. Even though once the largest vendors, after a period of severe distress, Motorola spun off Motorola Mobility. Market value shows long-term viability still a concern.
    7. Casio of Japan. Merged with NEC and Hitachi in 2010.
    8. NEC of Japan. Merged phone units with Casio and Hitachi in 2010.
    9. Hitachi of Japan. Merged phone units with NEC and Casio in 2010.
    10. Fujitsu of Japan. Merged with Toshiba in 2010. Held 15 percent of Japanese market prior to merger.
    11. Toshiba of Japan. Merged with Fujitsu in 2010. Held 4% share in Japan.
    12. Palm of the United States. Sold to HP in 2010.
    13. Handspring of the United States. Sold to Palm in 2003.

    That makes 13 large phone brands that, in less than a decade, have either exited or lost independence after suffering crises of profitability.

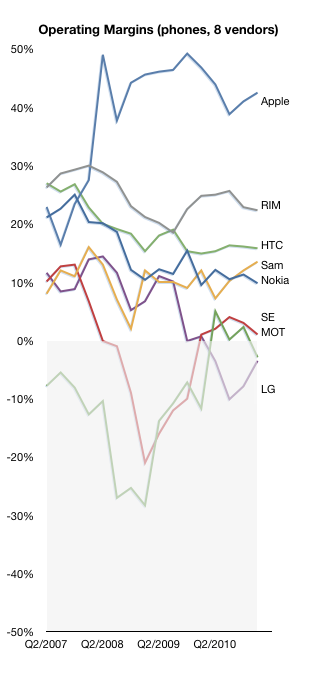
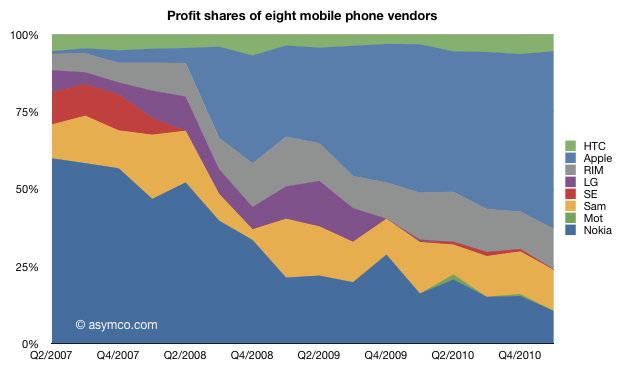
    As the following chart shows, at this time Motorola, Sony Ericsson and LG are still operating but have been dipping into the red.

    The three suffered severe volume contractions in feature phones and have no differentiation in software or platform products which makes their position precarious.

    This cursory survey shows that it's difficult to be optimistic once a company reaches a point of crisis. It's a curious outcome given that the market is so vast and growth is so robust.

    But the fact is that because of the technology cycle time, rapid business model evolution and fairly low barriers to entry, there is great rivalry between competitors. Profitability is the canary in the coal mine. It causes a brand to be tarnished in the eyes of distributors who, because of sales cycle times, are extremely sensitive to obsolete inventory. A loss maker is seen as a maker of damaged goods.

    It then turns off the tap of incentives, promotions and hence visibility in the eyes of consumers. It's a vicious cycle from which few (if any) can recover. Past greatness offers no succor.

    And so, with Nokia about to join the list of loss-makers it's only natural to question its fate as an independent company.

  6. A new mobile phone market index

    Research · 90 comments

    Measurements of "share" are abundant. There is journalistic value in summarizing performance in a single figure of "share" but it usually is a very limiting view. For example in the global mobile phone market there are at least the following measurements available:

    1. Share of all handset units sold
    2. Share of installed based of handsets (penetration)
    3. Share of smartphones
    4. Share of mobile computers
    5. Share of value (revenues) captured
    6. Share of profits
    7. Share of platforms
    8. Share within a given platform
    9. Share by regions/countries/geographies/demographics

    One could go on. So performance in a market can only be measured if you know to what end is that measure applied. Are you trying to determine current performance or are you assuming that the future will be different and trying to figure out what that future will look like?

    There is no good answer. It depends. But at least we can combine more than one share value into a summary. Mark Hernandez suggested that I put forward a "composite index" to measure vendor performance. I am willing to give it a try. The first iteration can be an unweighted average of four "shares":

    1. Share of all handset units sold (global)
    2. Share of smartphones
    3. Share of value (revenues)
    4. Share of profits

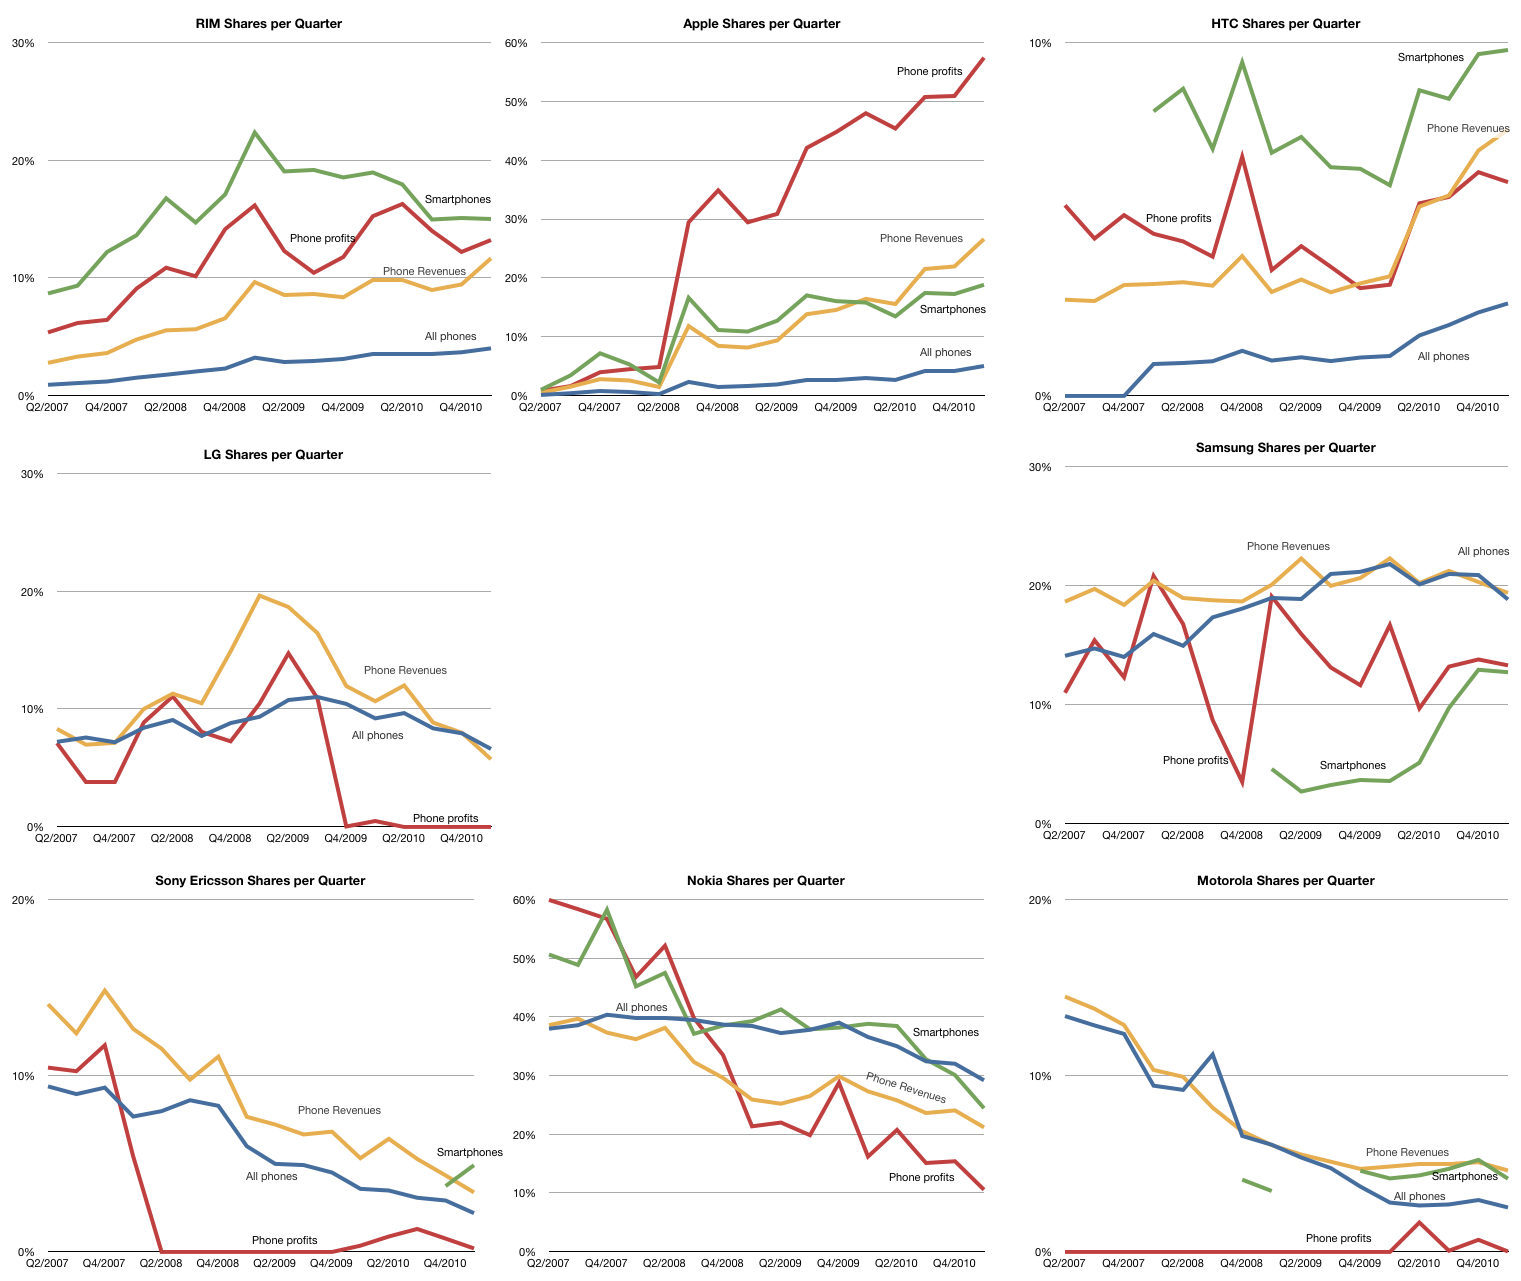
    The raw data for each share is shown in the following charts (note change of vertical scale: each gridline represents 10%).

    Note that the vendors are arranged in a particular way: top row are entrants, bottom row are incumbents with late incumbents from Korea arranged in the middle.

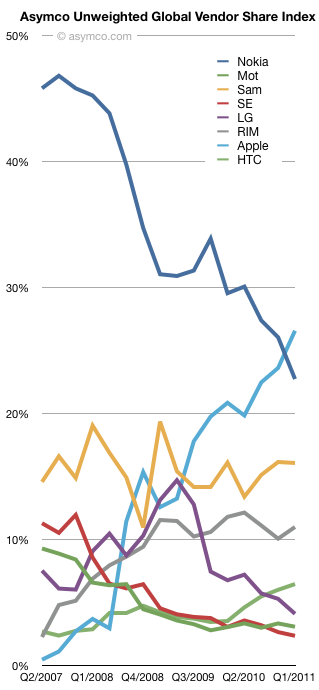
    Taking the average of each of the lines above, the unweighted share index (Units, Smartphones, Value and Profit) is shown below:

    Over the time period since Apple's entry in the market, the index shows interesting patterns:

    • Apple and Nokia trading places
    • Relative stability for Samsung
    • A leveling off for RIM
    • The Peaking for LG
    • Very tightly coupled declines for Motorola and Sony Ericsson
    • Gradual improvement in HTC

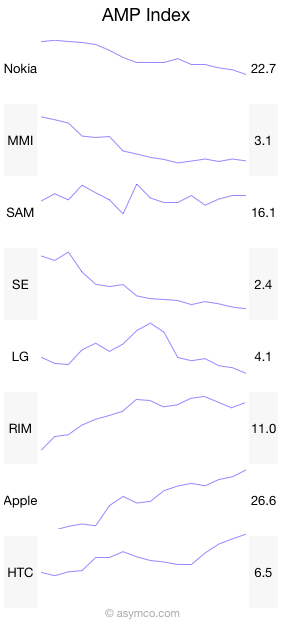
    And here it is in sparklines:

    Like many indices, this is a generalization that measures a section of reality. The value is in its use as a benchmark. If nothing else, it has journalistic value. I'm open to suggestions on how to improve it. Perhaps some form of weighting would be useful. Also, if anyone can suggest good name for it, it might be easier to communicate.

  7. A disruption is not sufficiently described by the success of some. Others must fail.

    Research · 46 comments

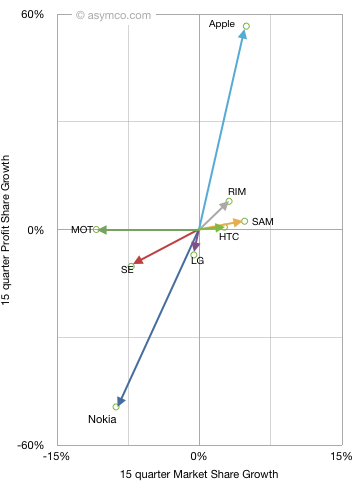
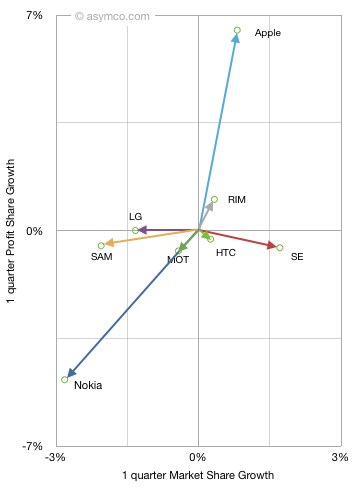
    Last fall I introduced the "vector space" model of visualizing vendor performance. It shows performance along two dimensions: market share growth vs. profit share growth for a set of competitors.

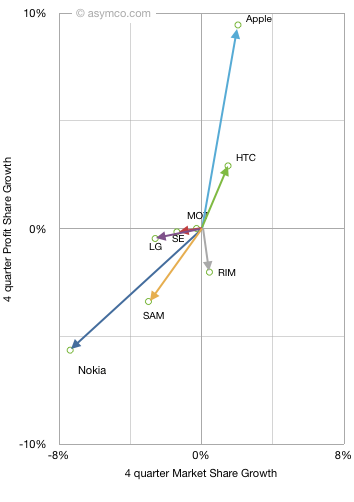
    When introduced, I chose a long time frame (15 quarters) to see the long-term pattern. This quarter I add two more time frames: year-on-year and sequential. This allows a view of how market change is itself changing. The three diagrams are shown below (note difference in scales)

    One way to interpret this is movement toward the upper right is positive while movement down or to the left is negative. A deeper meaning can be obtained from noting that the vector sum or "net" of vertical and horizontal data points should be zero (i.e. the gains in share should be at the expense of losses in share). In terms of phone market share the "net" is not zero as "others" are excluded, but the difference is visually not perceivable.

    Since we're dealing with share, one way to interpret the data is that "improvement" in one's position is offset by the "decline" in another's. We cannot ascribe the benefit of a vendor directly to the loss of another but overall net gainers are offset by net losers.

    By tracking this position change over time we can see if there is a set of consistent winners and a set of consistent losers. The pattern does show that:

    • Smartphone vendors grow consistently
    • Apple in particular has consistent growth with profit growth faster than share growth
    • Nokia in particular has consistent decline with profit decline faster than share decline
    • RIM shows profitability concern in the near term. In particular vs. HTC
    • Samsung shows some near term share loss, probably due to unbranded vendors
    • It's very rare to have a company lose market share while gaining profit share or to gain market share and lose profit share. This implies that in this market one does not trade off volume for profit.

    The correlation between profit and volume growth is very telling. As is the consistent clustering of winners and losers. This analysis demonstrates the shift in the industry is not a short term phenomenon but a disruptive changing of the guard. If history is any guide, this change is not going to be undone.


  8. Why the phone market is resilient to low-end disruption

    Research · 10 comments

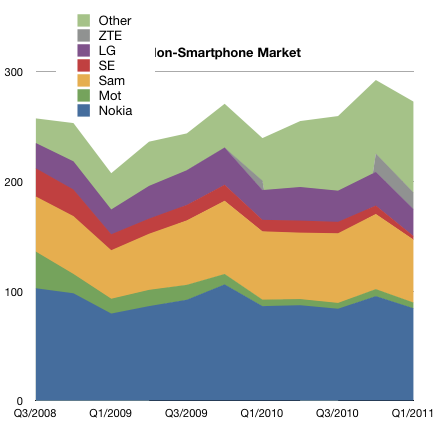
    The phone market excluding smartphones is not growing. Over a three year period it grew at 2% compounded.

    The following chart show the make-up of the market by vendor.

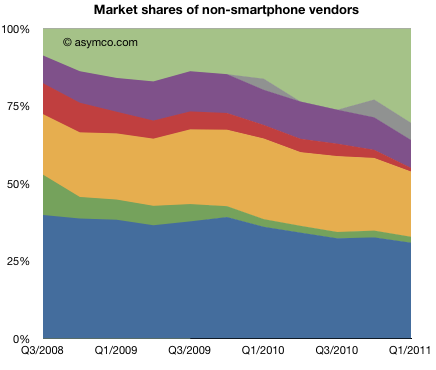
    Since it is not expanding rapidly, share over time has a lot more meaning.

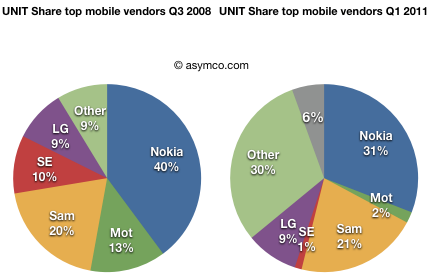
    The change in share over the last few years (since Q3 2008) is shown in the following two pie charts:

    Although many will argue that the non-smart market is one of great opportunity, the historic data shows that the market is not vibrant:

    • It's growing slowly if at all
    • Prices are falling as buyers find nothing of value in new products
    • There are fewer branded competitors (from 5 to 3)
    • There is increasing "white label" or unbranded volume growth (from less than 10% to over 30% share in three years)

    Although low end entries (in this case the unbranded new vendors) can signal disruptive potential, that potential is unlikely to manifest itself in voice-oriented products. Low-end disruptions take hold when markets are overshooting the expectations of the majority of buyers and incumbents are motivated to exit.

    However, if we consider all phones as a single market, then there is vast under-performance in the high end--something another set of entrants have taken advantage of and something neither the incumbents nor the low-end entrants are motivated or capable of pursuing.

    The phone market is not being disrupted because of the low end entrants. Nokia and Samsung are motivated to compete for those customers. It's being disrupted because the new market of mobile computing is completely asymmetric.

  9. "Other" vendors sell 10% of Smartphones but 30% of voice-oriented phones

    Research · 12 comments

    In the last post, I highlighted the difference between smartphones and non-smart device sales last quarter. The trajectory of share growth for smart devices would appear to have accelerated due to Android.

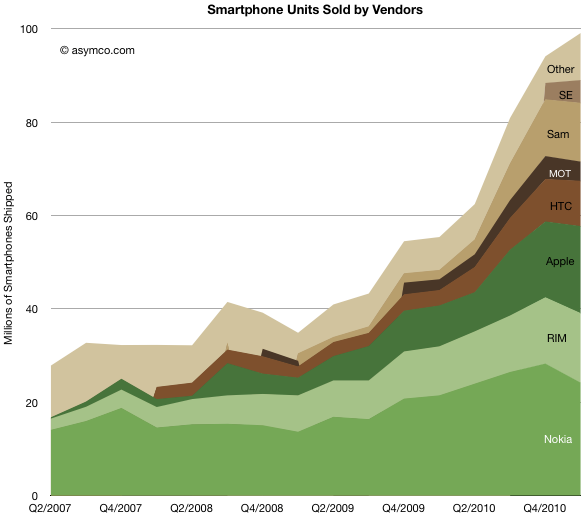
    The following charts show the evolution of smartphone vendors and platforms over the last few years.

    Like in the past, I used color clustering to show the separation between "integrated" (in green) and "modular" (in brown) platforms and their users.

    Unlike the non-smart market where "other" make up 30% of the market, smartphones are still a big brand business. "Other" make up only 11% of units. and that number has been trending down. It would seem that the age of unbranded Android phones is still not upon us.

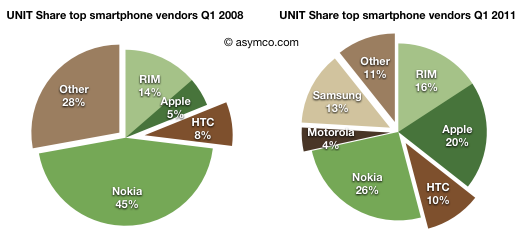
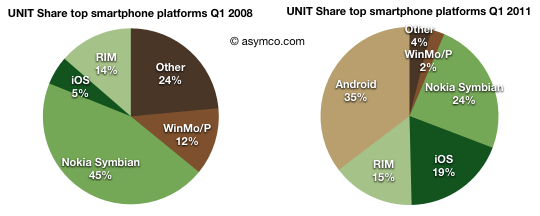
    Comparing three years "before and after" here is Q1 2008 vs. Q1 2011 by vendors share:


    Apple added 15% of share, Samsung 13%, Motorola 4%, RIM and HTC 2%. Nokia lost nearly 20% of share.

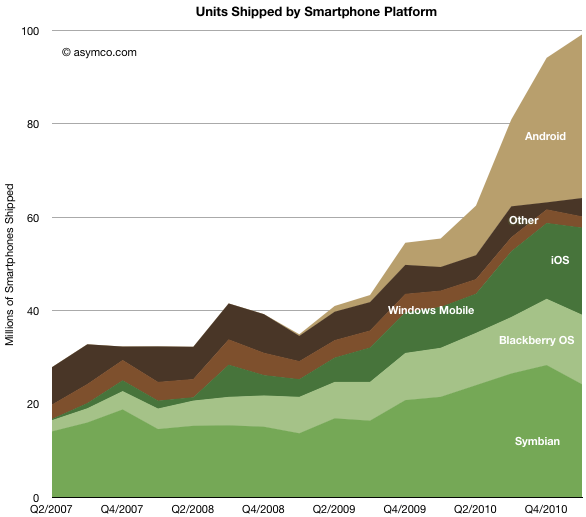
    From a platform point of view, the unit chart looks like this:

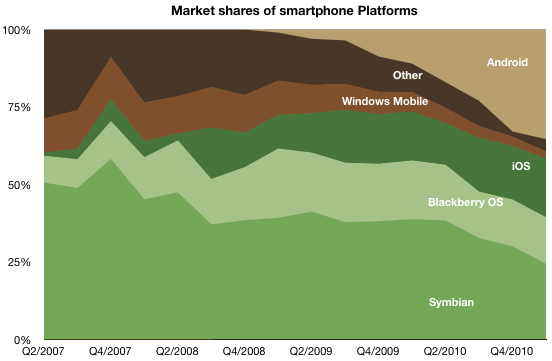
    Note that Android's growth came at a time when Symbian had a terrible quarter. The evidence is visible in the share chart:

    Android's gain seems to be at the expense of Other, Windows Mobile and Symbian. In the pie chart snapshot over a three year period the transfer seems clear.

    Android took 35% of share, iOS 14% and RIM 1%. Windows Mobile/Phone has collapsed to 2%.

    But again I would caution about drawing "sustainability" conclusions from looking at this market with a share perspective. As it's growing at a huge rate (73% year/year) it's bound to be become so large that single digit share numbers still amount to vast ecosystems while huge shares of fragmented products don't amount to much of value. To emphasize the point, I would remind that in 2008 Symbian was not just Nokia but a lot of "Other" was made up of Symbian in Japan. The combined fragmented footprint of Symbian was well over 60% of the market. It did not do much good for the platform.

  10. Smartphones: the end of the beginning or the beginning of the end?

    Research · 43 comments

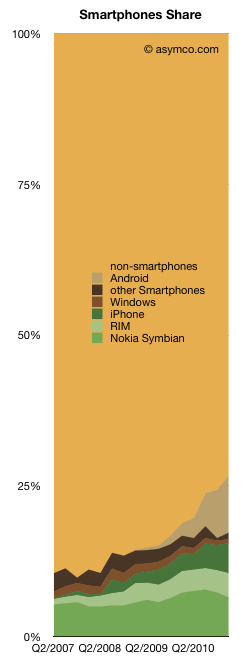
    The smartphone market grew to about 100 million phones last quarter. The volumes grew sequentially and as a result reached a new record share of 27% of total phones shipped. The chart on the left shows how this market evolved over the last few years.

    I've added each platform's contribution.

    While much of the focus will be on who had what share, the better question might be who has the better chance to beat smartphone non-consumption? Non-smart devices are still the dominant competitors. Though it's getting easier to win against them, they still have some compelling competitive advantages.

    What the chart shows is that Android (and phone versions of iOS) have taken share from direct competitors but have taken more from non-consumption. Rather than focusing on rivalry between platforms, minds should be focused on the shape of the smartphone adoption curve.

    The market is largely un-penetrated and yet some argue that "it's too late" to enter or that "the game is over" and winners have already been decided. This is an argument that we are at the beginning of the end. Once the market is predictable it's discountable. Once it's discountable it becomes economically uninteresting.

    I've argued that this is far from certain. In a short span of a few years, a decades old business has been re-defined. But that was just the device side of a larger business. Smartphones have been, so far, sustaining to the telcos who capture the vast majority of revenues and are thus the true incumbents.

    If and how they will be affected by further evolution of smart devices and new business models around them remains to be determined.

  11. iPhone share of phone market in Q1: 5% volumes, 20% revenues, 55% profit

    Research · 40 comments

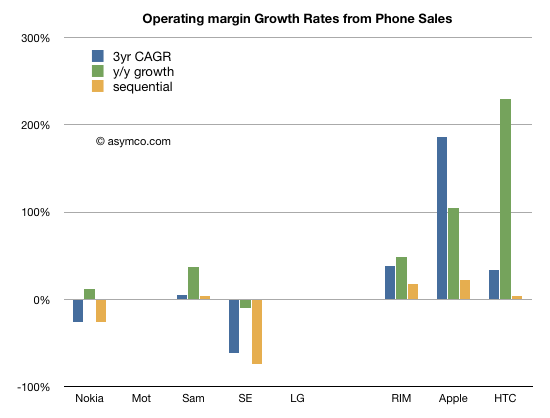
    Operating profits for the eight vendors I track increased at a compounded 25% over three years. As with revenues, the growth is concentrated. The following chart shows operating profit growth across three time frames: three year compounded, year/year and sequential. Loss-making vendors are excluded from this chart.

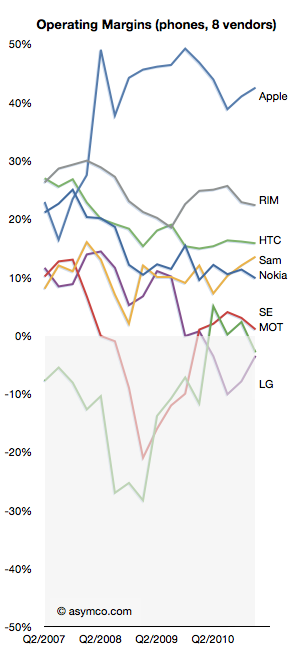
    Looking at individual performance, the following chart shows how each vendor performed over time:

    The mobile industry has historically been unforgiving. Companies that fall into unprofitability tend to stay there or exit/merge. This has claimed many: Ericsson, Siemens, Alcatel, BenQ, Palm, Sony, Toshiba, Handspring, NEC, Hitachi, Casio.

    LG, MMI and Sony Ericsson are all in the same precarious situation. We'll have to watch carefully whether a recovery is possible for any of them and whether Nokia will reach the same rocky position.

    Looking at operating profit shares, the picture is plain to see. While RIM, Samsung and HTC have maintained profit share, between 2007 and now, profit share has mostly shifted from Nokia to Apple.

    But this does not tell the whole story. Here are the absolute amounts of operating profit from mobile phones. Exactly three years ago Nokia was earning 47% profit share or $2.35 billion. This past quarter Apple's 57% was equivalent to $5.23 billion, more than twice as much.

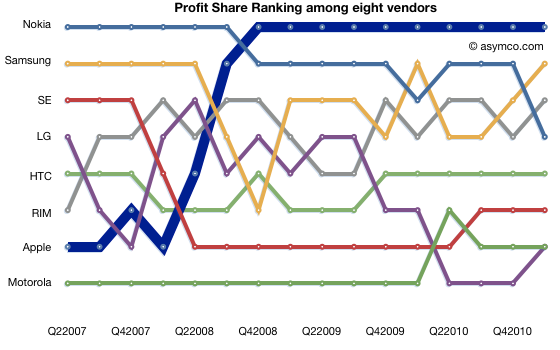
    Finally, the league table shows how Nokia has now dropped from second to fourth in the last quarter. Not only Samsung, but RIM has overtaken Nokia as well.

    It's become routine to see Apple at the top of the list of profit earners from mobile phones.