Asymco

Asymmetric Intelligence

Horace Dediu

  1. Predicting iPhone sales for dummies

    Research · 36 comments

    Apple's second fiscal quarter has just ended. Time for analysts to put forward their predictions for the quarter's report (due in about 3 weeks.) If history is a guide, the estimates will range quite widely and accuracy will be determined mostly by the ability of an analyst to predict iOS device sales (and iPhone most of all).

    How hard can it be?

    It depends on what you choose to prioritize as the proxy for sales. In competitive markets there is usually a constraint on demand and rivalry among suppliers. If that's your assumption you might want to use samples from the sales channel as a proxy. That means sampling distribution channels and sales through to end users at retail. You might even watch competitors and index them to each other using historic market shares.

    In markets where demand outstrips supply, the best method would be to determine the constraints to production and measure those.

    In Apple's case we know from company statements that Apple faces more demand than it can supply. That makes things easier for the amateur because she can just figure out production. In other words, the logical way to forecast Apple's iPhone sales is to guess how many they can make.

    That is not trivial since production data is not public. However, we have historic sales data. We also can make assumptions about how much inventory is carried (some data is actually available here as well.)

    Combining these public data sets we can build up a model of production ramps and look for patterns of growth.

    So here are the patterns of sales for the four versions of iPhone sold to date with some production ramps overlaid. The monthly sales are approximations based on actual quarterly sales divided over the months according to the number of days available.
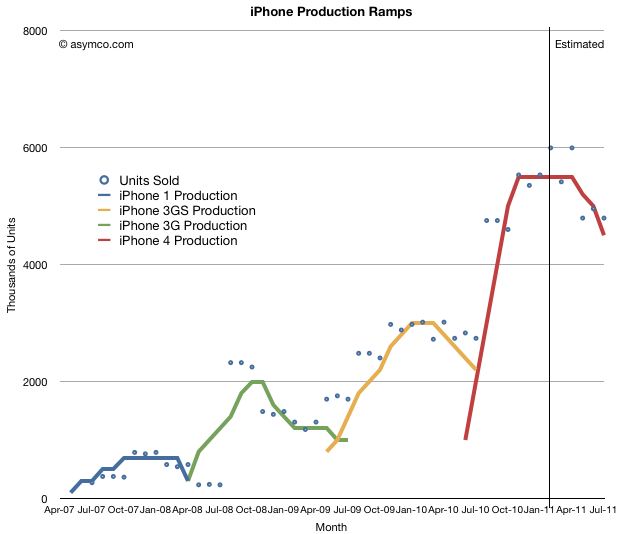
    The assumptions are:

    1. Inventory during any one month has to be greater than zero.
    2. Inventory must be minimized. Ideally it should not exceed 2 million units and preferably should be around 1 million units at any given time.
    3. There is a limited amount of overlap between production of various generations. I.e. once a new version is launched, the older product should end production. Continuing sales of older model should be made available from inventory.

    The following chart shows the ramps for the various versions of iPhone that satisfy these assumptions and are shown relative to the same time frame (each line shows the number of units produced per month for each generation of iPhone):
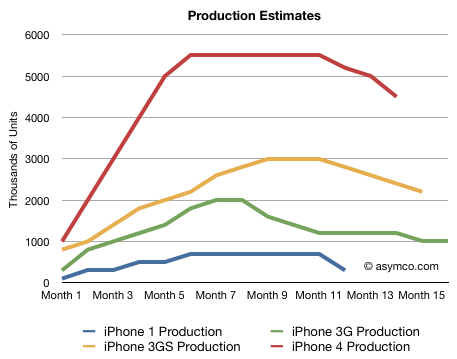
    I need to stress that this is just my estimate. It's an approximation and not reality. What it does is give reasonably accurate predictions for units sold.

    What I've always assumed is that each new version of the iPhone sells twice as many units as the last. This is roughly translated into: each ramp is roughly double the previous ramp (at least on average). The data bears this out. Apple has been very considerate in keeping products on similar cycle times so that we can see this pattern emerge.

    Once you build these models, forecasts are not that hard to make:

    • The current generation will probably sell around 60 to 65 million units.
    • The product will still sell for at least one more quarter (CQ2, FQ3)
    • We know how many have been sold so far, so we can be pretty sure what will happen in the quarter just ended and the one just starting.
    • Looking at the pattern between generations, we can guess what the iPhone 5 curve will look like and build up the units forecast by month and quarter.

    You can sanity-check the forecast by looking at overall market shares for Apple and overall market growth. If share moves too far up or down it might makes sense to revisit the data.
  2. Understanding RIM's tablet platform app strategy

    Research · 135 comments

    Yesterday RIM reported their quarterly earnings. The results were mixed to slightly negative and the shares were down 10% in after-hours trading.

    I'll work through the smartphone market data at a later time but for now what I want to focus on is RIM's strategy which really means understanding RIM's intentions or their approach to the market. For that we have to go straight to the source: what management actually says. Trouble is, management often speaks in a jargon that is unfamiliar to people (sometimes unfamiliar to anyone outside the company).

    Strategy analysis involves translation. So here follows the interpretation of Jim Balsillie's remarks during the conference call (transcript sourced from Businessinsider.com).

    What Balsillie SaidMy interpretation
    First of all, what we announced is Gingerbread. This is not Honeycomb. I don't know what the number of Honeycomb apps is, but it's not very many. Whereas Gingerbread they've got lots of them.RIM will support Android apps in the PlayBook tablet. As there is not one Android, I need to clarify that RIM will not support Android tablet (Honeycomb) apps but Android phone (Gingerbread) apps. So RIM's tablet will support Android phone apps even though our tablet does not actually have a phone in it, but requires tethering to a BlackBerry for cellular data.
    You've got the volume of the handset apps, so if you're looking for the tonnage of apps, or some kind of long tail stuff, you've got it.This support means there will be many apps including apps that are not very popular. We don't like supporting unpopular apps. We like a few good quality apps but this approach allows us to offer all kinds of apps.
    At the end of the day, people are going to want performance.However, many apps will not run smoothly.
    You're just not going to get things like gaming and multimedia, you're not going to get the speed going through a VM interface. If you want content, or Flash type stuff, or you're looking at AIR-type, evolving web-type assets, that's what you're going to do.Games and graphics will not run well through emulation. For processor intensive experiences we will have native execution options or browser apps.
    There's no compromise here. You've got the tonnage of apps. And you've got the performance. Do I think the tonnage is overplayed? Yes.By supporting emulation of Android apps we can offer a large catalog of so-so apps while having a small portfolio of high quality native apps.
    But if you think it's about having a couple hundred thousand apps, there you goFor people who value large selections, they can go to one store.
    Do we believe it's about super high performance? YesBut for those people who value quality, they can come to our store.
    I'll just offer that observation that today broadly in the world without any specific comment on us or our competitors, there are multiple ecosystem patterns that need to be consideredBeside emulation and native we also think there are many other ways to deliver applications.
    Do we believe it's about full web fidelity? Yes.For example, Flash.
    These are concepts that were really relegated as not technically possible, which we're doing here. This is a no compromise environment.Because of Moore's law, Flash is becoming viable on a mobile device.
    If you want to work on Android, great. Do we think people will want to migrate web assets? YesThen there are browser apps.
    Do we think they're going to want super high performance native assets with the SDK? AbsolutelyWe will have our own native SDK.
    You think they're going to want to use their Flash based stuff for an offline Flash/AIR type environment? YesAnd support Flash.
    I'm just not interested in these sort of religious application tonnage issues.  I really think we put that issue to bed.We have a new platform but catalog sizes can no longer be used against us.
    And if you think the whole world's going to want to develop for Gingerbread, fine. Do I think that's going to happen? Then why is there a different environment for a tablet? And you know about the performance issues and you know about the app volume issues, cause it's tough. And that's why QNX mattersGoogle's ecosystem is fragmented, Android apps are not able to rely on competitive hardware and there is too much competition. That's why developers should target QNX (which is unfragmented, built on fast hardware and there are few apps on it).
    Is this stuff going to go more in the browser and HTML 5 and more native? These are going to be strong trends. But if you want these app players for different VMs -- and don't forget we have 25,000 BlackBerry 6 appsBrowser apps will increase in value and we also have legacy BlackBerry apps.
    So, at the end of the day, we believe this is going to be about performance. It's going to be about enterprise greatness.But we believe in a future with native applications running on QNX.
    Things like multi-threaded capability, symmetric multiprocessing. We believe it's about an uncompromised web. We believe it's about enterprise security. True multitasking, not with suspension -- and that matters because you're going to want to run these things in the background.Because QNX is a robust operating system with PC-like performance. It also supports a good browser.
    But I'm out of the religious war on tonnage, which I'm delighted.However, before QNX takes off, we will provide access to catalogs of apps which are built for other platforms.
  3. Analysts: Apple's growth next year to drop to half of what it could obtain during the recession

    Research · 72 comments

    Apple is having difficulty meeting demand for the iPhone and the iPad. It is growing both businesses at more than 100% and they make up about 65% of revenues, and 71% of profits. The Mac business is also growing at 2x to 3x the PC industry.

    Being supply constrained makes it therefore a great challenge to forecast future growth for the company. Supply issues and ramp rates are needful of an operational expertise few possess outside of the industry. But many take up this challenge, myself included. We put up our numbers every quarter and get scrutinized and challenged for our failures.

    So it's always exciting to see how others are looking at the big picture. Sadly, with the growth data being what it is, there seems to be a great deal of pessimism around the company's prospects. The P/E ratio has remained at despondent levels for over two years, barely tracking with the P/E of the S&P 500 and not reflecting the company's historic or current growth.

    The logical explanation is that pricing reflects a consensus that growth will fall off a cliff. Indeed this can be confirmed. Bloomberg surveyed analysts and they say:

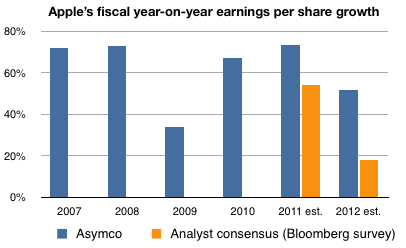
    Apple’s sales may climb 54 percent to $100.3 billion this fiscal year, which ends in September, the average prediction of analysts surveyed by Bloomberg. Growth may slow to 18 percent the following year.

    Fifty percent growth this year and 18 percent next year is indeed catastrophic. Consider the company's recent history as shown in the following chart:

    The company has been growing earnings around 70% a year since 2007 at least. The exception being 2009 when in the middle of the worst recession for a century the growth dropped to 34%.

    I took the liberty of adding the estimates cited above to the chart (in orange) while putting forward my estimates for the same time frame.

    I am, I believe, conservative in my estimates (for example, my estimates do not take into account any new product categories Apple may launch). But the prospect of 18% growth for the fiscal year beginning this October is quite hard to justify knowing what I know about the markets Apple competes in. As I've amply described in this blog, the mobile computing (aka post-PC) shift is underway and Apple is leading the charge. The prospect of billions of unserved customers beckons and Apple is crushed with demand.

    But let's not quibble about billions of desperately underserved consumers. The thing that sticks out from the chart is that analysts are forecasting growth about half of what Apple was able to achieve in 2009--a time when consumer spending practically stopped world-wide and there was talk of another depression.

    Either they're in agreement that we're in for something resembling a global plague starting in six months or they believe Apple is singularly positioned to drop the ball.

    I would love to hear some these scenarios defended because I see no evidence for either.

  4. The American Wireless Galapagos Syndrome: How the industry set itself up for a rout

    Research · 193 comments

    AT&T's intent to acquire T-Mobile USA is subject to regulatory approval. Will regulators look at the deal through the lenses of sustaining the traditional industry's profit allocation or through the lenses of device-led disruption?

    In theory, regulators are to make a determination on whether the deal will reduce customer choice. But the question is really choice of what? The focus is presumably on the choice of service plans. That's understandable, however coupled to that choice is the choice of devices and even more importantly, the choice of platforms.

    The trouble is that US consumers have never had much choice and the US wireless marketplace has been a minefield of incompatibilities and obstacles to market forces.

    To begin with, US carriers maintain multiple incompatible network standards. Phones which work on one network do not work on any other. A Sprint phone won't work on AT&T or on Verizon. In fact, some Sprint phones won't work on all of Sprint's network as it still uses the iDen standard legacy from the Nextel acquisition. Even the iPhone which is designed for the AT&T network does not handle T-Mobile's version of 3G. So a consumer cannot make a decision on devices independent of a decision on carrier. This is a phenomenon unique to the US[1].

    Secondly, in the US carriers charge for incoming minutes and have shunned pre-paid customers. There was a time when SMS messages were not compatible between networks, which led to the emergence of RIM as the only wireless messaging solution available, though initially not to the average teenager.

    Thirdly, because of the multiple incompatible standards, network coverage in the US is still abysmal. Each carrier has had to build out parallel (incompatible) networks at great expense using non-standard equipment over a vast landmass. The result is not only a very expensive network whose capex demands high service fees, but a very poor quality network which is always both spotty and capacity constrained. Operators are therefore keen to lock customers in to post-paid plans to ensure cash flows that drive capital allocations. This is essentially an upmarket flight which does not encourage low end innovation.

    These idiosyncrasies are rooted in historical regulatory rulings that led operators to create a uniquely American wireless market. The key regulation was that the US shall have no single wireless standard. In the spirit of laissez-faire this may make sense. But the result has been failure of the common good. This is sharply contrasted with other developed countries which (with notable exceptions) deliver superior service with high efficiency.

    The US is so unique that it developed its own "Galapagos syndrome". Few global brands can be bothered to invest in it. Vodafone tried to play in the US with Verizon, but its minority position offered no leverage because Verizon spent the better part of a decade avoiding global networking standards. Now T-Mobile is desperate for an exit after trying to leverage the foothold it paid dearly for and failing to offer devices that capture users' imaginations (because they were railroaded into another incompatibility with 3G). Conversely, no US brands have been able to expand internationally. US operators are non-entities abroad, even in what would be natural expansion territories like Latin America or the Caribbean.  Those markets belong to European investors today.

    Given this background, it's very likely that regulators will look at the deal in terms of balancing what is essentially a deeply flawed, cobbled together industry.  Companies can argue that they are rationalizing through consolidation but regulators can argue that "choice" is decreasing. These arguments are mostly moot. The problem is that the US wireless market is balkanized and byzantine.

    It's therefore perhaps stunning that the platforms that are currently winning in mobile computing are American: iOS and Android[2]. Note further that none of these winners came from the world of wireless or telecom. These new points of profit condensation in the industry entered from a different industry: computing. But are they now pursuing telecom-compliant strategies? Arguably no. I choose to call them mobile computing and not phone platforms specifically because they will tolerate the cellular regimes as long as they need to, and no longer. Once they will reach the perch of power, the industry will conform to them, not vice versa.

    ---

    Notes:

    1. Japan has a similar problem but less pronounced.
    2. Microsoft is still in the running as is Palm, both American.
  5. Which mobile users will platforms harvest first?

    Research · 23 comments

    When tallying up the race to a billion users, I noted that both iOS and Android seem to have the potential to reach that size of user base. However, that raises the question of where those users will come from. We have to note the fact that there aren't a billion users to be captured today.

    If not today, then how soon, and where are they?

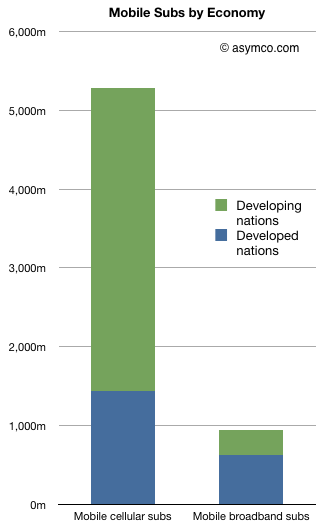
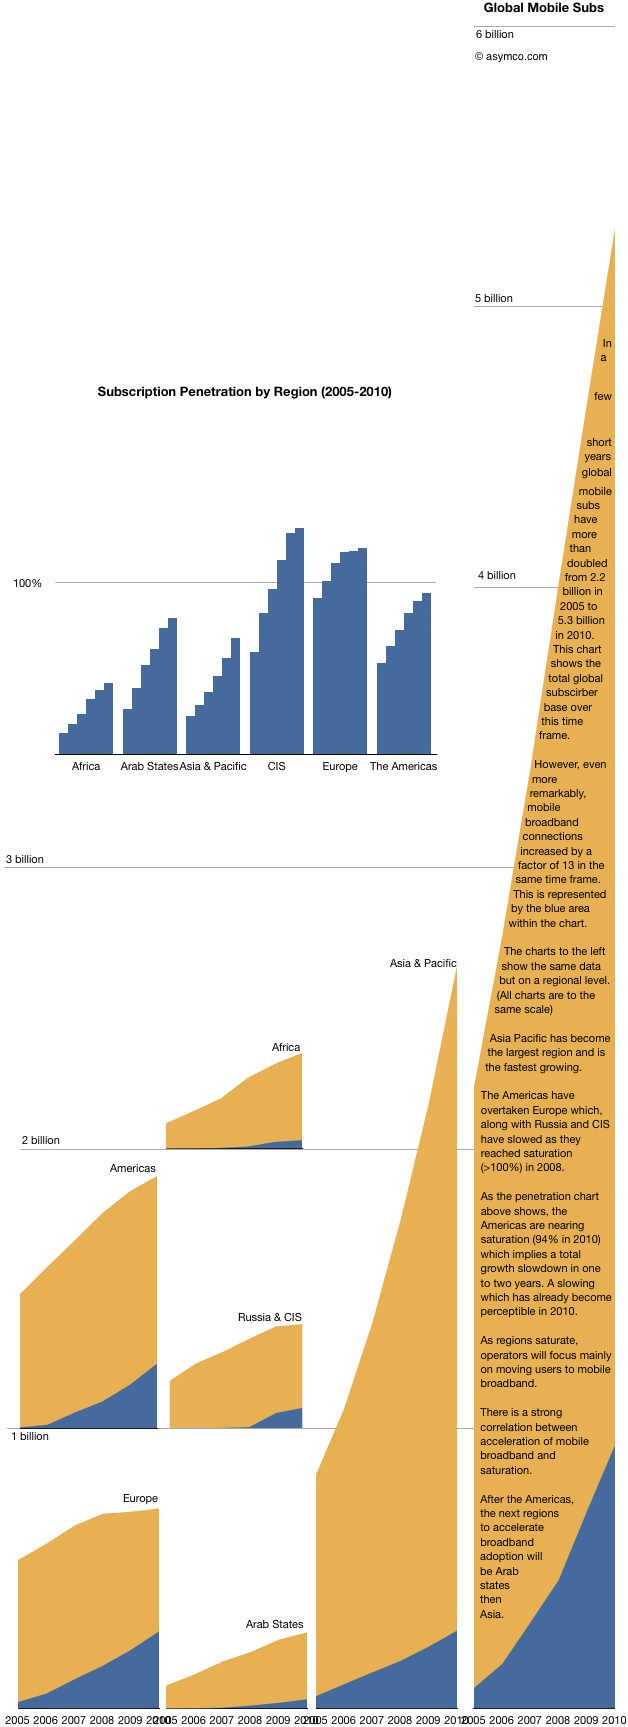
    The first question is who is addressable. If we stick with mobile cellular subscribers, there seem to be plenty of users (at least 5.3 billion as of October 2010 according to the ITU). However, the number of "mobile broadband" (i.e. 3+G network subs) is about 940 million. The chart to the left shows the difference and adds the subdivision between developed and developing economies.

    Over half (51.1%) of developed nations' populations have signed up for mobile broadband while only 5.4% of developing country populations are on 3G. And whereas developing countries have added 2.6 billion mobile subs in 5 years, they added only 293 million mobile broadband (MB) subs. Developed nations added 574 million MBs in the same time frame.

    As a result, two thirds of mobile broadband subscribers reside in developed nations as of 2010. This number will decrease rapidly as MB penetration reaches saturation in developed countries, however the race to a billion is being run in these markets first.

    Which leads back to the question of platform potential. Platforms that target developing nations have the challenge of low broadband availability in the near term in addition to the challenge of device pricing. There are still 800 million developed country subscribers who have yet to upgrade to mobile broadband.

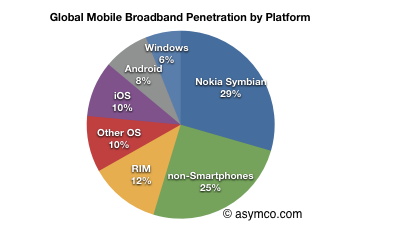
    At the time these statistics and knowing the platform sales histories, my estimate is that only 18% of mobile broadband subscribers were using either iOS or Android. 25% were not even using a smartphone and 29% were using Symbian. (See pie chart).

    But existing smartphone users are not the most attractive market to target with a new platform device.

    A new smartphone user could come from the following groups of users:

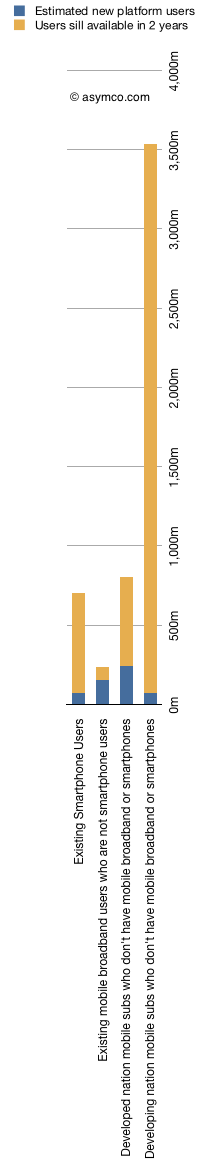
    1. Existing smartphone users:  700 million. This is tough head-to-head competition for every new user.
    2. Existing mobile broadband users who are not smartphone users: 240 million. The easiest group to switch to using smartphones.
    3. Developed nation mobile subs who don't have mobile broadband or smartphones: 800 million. This seems very attractive since they can be mostly upgraded using subsidized phones into an available 3G network.
    4. Developing nation mobile subs who don't have mobile broadband or smartphones: 3.5 billion. This is a very tough market because the availability of 3G will take time and until it appears, the buyers are unlikely to adopt devices that are useful only though a 3G data plan. They are also a difficult market to target with high ARPU phones/plans.

    To assess the timing, one could assign some probability weights to these categories to create various scenarios for adoption. My own guess is that the next 500 million smartphone users are easily within reach in the next two years without a significant amount of inter-platform rivalry (See stacked bar chart to the left).

    Only after two years will existing smartphone users become attractive for poaching and even that assumes that developing nation networks will still be largely unaddressable.

  6. Ads for ads: The ad-supported app bubble

    Research · 25 comments

    By one estimate (Gartner), about 81% of apps downloaded today are free. The way free apps are able to generate revenue is through advertising. 16 percent of application store markets' $5.2 billion revenue was generated from advertising.

    But advertising what?

    It seems that most of the ad dollars spent on in-app ads are spent by developers to promote other apps. I'd like to get hard data to prove this, but assuming it's true, we have to ask if the apps being promoted through ads in apps are free apps seeking more revenue from ads...from other apps.

    To put it bluntly, the $816 million that "comes from advertising" is not coming from consumers but churning around the ecosystem like a hot potato. This figure is said to triple this year.

    It's arguable that this is only logical. App users are pre-qualified as app downloaders so it makes sense to target them through apps for more apps. But where does value actually flow into the ecosystem from consumers? This problem of commerce through apps being nothing but virtual app goods implies that there is a bubble forming. This is more likely to be a problem for Android as the ratio of advertising to purchase of Android apps is higher than on iOS, but it's a problem for all app advertising.

    It's even more ironic that the developer looking to create revenues through their app is promoting competing apps seeking the same user.

    I don't see how this can end well.

    The only way ads really work is for users to transfer cash for underlying value. Aside from paid apps which have entertainment or functional value, how much spending from traditional ad buyers (brands) is targeting apps? Perhaps transitioning ad buyers is what Apple had in mind a year ago with iAd. Signs so far are not encouraging that their approach is working. That may be bad news for Apple, but it's worse news for AdMob.

  7. Talent follows where business models lead: The Media Business Disruptions

    Research · 46 comments

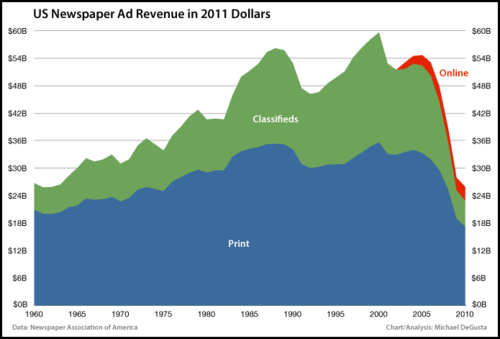
    Michael DeGusta created beautiful and informative charts on how The Newspaper Business Implodes.

    With charts, he also told the story of how the recorded music industry followed a similar path:

    Image (media.tumblr.com)

    He writes:

    As in the music business, digital revenue is failing to make up for the loss of traditional revenue. Ominously, online revenue is largely flat, basically unchanged from 5 years ago and still below its 2007 peak.

    What I find fascinating is how both industries reacted to the crisis of old media. They embraced the new "digital" distribution model, earnestly tried to transplant their business models and found no succor.

    Many observers may say that both print and music businesses were "foolish" and that they ignored the new medium of web. That somehow management dithered and missed the new wave blaming failure on incompetence. Putting aside the fact that all industry participants seem to have conspired to be foolish at the same time, this is not supported by the data. As the charts show, both industries built digital businesses. Newspapers have some of the most desirable web properties and digital music is a growing business with clever new distribution deals. They became quite smart in their respective adaptations of web distribution.

    They may have started slowly but there are many cases where incumbents reacted slowly to technological change, and won.

    But it's not working.

    The reason is that what we have here is a disruption. Unlike a sustaining technological shift, the new medium of the web did not permit the same business models to continue. Money was being made, just not in the same way and thus could not support the cost structures of the incumbents. Consumption of news and music is increasing but the way that it is valued is changing.

    Furthermore, it's become modularized. All the objects contained in a newspaper could, with the web, be offered independently of one-another (opinion, news, classifieds, lifestyle can each be built by specialists.)

    This is because the technology of the printing press benefits the integration of content while the technology of the web benefits the disintegration of content (similar phenomenon to the music industry's bundling into albums, vs. unbundling of digital downloads.)

    Now I'm going to take a leap and suggest that a re-birth of the container of the newspaper in the tablet medium will require a re-integration once again. As I've pointed out before in The integrated iPad news daily: Read all about it! the answer is not in integration or disintegration per se. It's in approaching the question of value chain evolution with an eye toward what is good enough and what isn't. Integrate when the product is emerging and unsatisfying, modularize when the product is mature and over-serving.

    We're observing the same phenomenon with television. Netflix, a distributor, is vertically integrating by entering production with an exclusive top talent series.

    Developers are not the only innovators that see disruption happening. Just like in "The Daily", in music and television, talent follows where business models lead.

  8. Who's knifing what?

    Research · 147 comments

    Microsoft just declared the Zune end of life. This makes it a good time to look back to some notable episodes in the evolution of digital media distribution. First, an episode from 1997:

    During two days on the stand, Tevanian accused Microsoft of seeking to divide the multimedia market and then "sabotaging" QuickTime's ability to work with Windows computers when Apple declined to go along with Microsoft's plan. Justice also is accusing Microsoft of attempting to illegally allocate the Internet browser market.

    In particularly colorful testimony on Nov. 5, Tevanian described an April, 1997, meeting between two Apple and two Microsoft officials. Tevanian, who was not at the meeting, said Microsoft officials suggested that Apple abandon its business of providing "playback" software that enables users to view multimedia content on the computers. Instead, they offered Apple the much smaller portion of the market for the tools that developers use to create the content. In Apple's mind, though, the playback software was its baby.

    According to Tevanian, Apple executive Peter Hoddie asked Microsoft officials, "'Are you asking us to kill playback? Are you asking us to knife the baby?'" He said Microsoft official Christopher Phillips responded, "'Yes, we want you to knife the baby.' It was very clear."

    Business Week Online/Microsoft Watch on the cross-examination of Apple's Senior Vice-President Avadis "Avie" Tevanian Jr. during the Microsoft antitrust trial.

    Ten years later:

    “We came into the [media player] market, a market in which they are very strong, and we took, I don’t know, but I think most estimates would say we took about 20-25% of the high end of the market,” “We weren’t down at some of the lower price points, but for devices $249 and over we took, you know, let’s say about 20% of the market. So, I feel like we’re in the game, we’re driving our innovation hard and, uh, okay, we’re not the incumbent, he’s the incumbent in this game, but at the end of the day, he’s going to have to keep up an agenda that we’re gonna drive as well.”

    Steve Ballmer on Zune, iPhone (CNBC interview) .

    Four years later the Zune is no more. Besides being interesting anecdotes, what patterns emerge from these episodes?

    The evolution of the bases of competition for media distribution between 1997, 2007 and 2011 is striking.

    • In 1997 the struggle was between specific modules (formats, players and technical standards.)
    • In 2007 the basis of competition was devices integrated with music services (which encompassed formats, standards and players).
    • By 2011 the competitive standard that the iOS ecosystem is putting forward is at an even higher level of integration. Not only are the sub-modules integrated into a whole, but now apps bespoke to a platform are attracting a virtuous cycle of third party innovation.

    Now consider how the two protagonists evolved (or didn't) during this 14 year saga.

    Apple has maintained its attention steadfastly on products while Microsoft has maintained unwavering focus on the distribution and control over value chains. During the 1990s one strategy worked and the other didn't. During the following decade they changed places. The locus of the two strategies did not change. What seems to have changed is what the market values.

    So we have to ask: Is the end of the Zune a matter of poor execution or is the cause for failure something more profound? Is Microsoft's real problem that they have prioritized that which is no longer valued?

  9. On Feeds and Speeds

    Research · 54 comments

    And a lot of folks in this tablet market are rushing in and they're looking at this as the next PC. The hardware and the software are done by different companies. And they're talking about speeds and feeds just like they did with PCs

    Steve Jobs, iPad 2 launch event March 2011.

    I'm not above doing a feeds and speeds comparison.

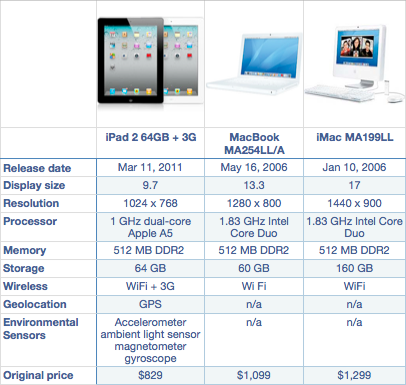
    All the products above have dual core processors, 512 MB of memory. The iPad processor is a bit slower. The iPad also has a slightly smaller resolution screen than a MacBook from mid 2006. However, unlike the others, the iPad has cellular broadband connectivity, loads more sensors, and a battery that will last at least 5 times longer.

    It's also a lot cheaper and a lot smaller.

    Although five years old, nobody would question that the MacBook or iMacs shown above are still computers. They still run the latest versions of OS X and are probably still in widespread use.

    The new iPad is still not considered a computer by the majority of market analysts. One wonders how long this will go on. The specs of the iPad are just going to keep getting better...

  10. Star-crossed partners

    Research · 36 comments

    Until very recently, we believed our competitive position in smartphones could be improved with Symbian, as well as MeeGo, and our strategy based on those platforms. We are now of the view, however, that for the longer term our Symbian platform is not sufficiently competitive in leading markets.

    Nokia's SEC Form 20F.

    The company's fiscal year, which ended in June, was one of the worst to date for the mobile space. Although in development since 2008, the Kin was pulled after just over six weeks of sales and amounted to a $240 million write-off before including the $500 million to buy Danger. Windows Mobile's ramp down is partly intentional as Microsoft is rebooting the platform with Windows Phone 7 and is investing $500 million in marketing to spark new interest.

    Microsoft CEO bonus cut for Kin flop, lack of iPad rival | Electronista One irony is inescapable: the world's largest device company can't build commercially successful software and the world's largest software company can't built commercially successful devices.

    Another irony is that the competitive threats that both companies face came from challengers that were not perceived as such a few years ago.

    Google was not a platform vendor three years ago and Apple was not a phone vendor four years ago.

    The largest incumbents in separate industries sought salvation in each other after the market they strove to build went to unforeseen challengers. All in a span of three years.

    I cannot think of a more succinct testament to the process of disruption.

    One can only speculate about the probability of success of this pairing, however, I struggle to find a historic precedent where this type of relationship succeeded.