Asymco

Asymmetric Intelligence

Horace Dediu

  1. Apps are 15 times more popular than ebooks

    Research · 71 comments

    “It doesn’t matter how good or bad the product is, the fact is that people don’t read anymore,” he said. “Forty percent of the people in the U.S. read one book or less last year. The whole conception is flawed at the top because people don’t read anymore.”

    The Passion of Steve Jobs - NYTimes.com

    It was almost exactly three years ago that Steve Jobs dismissed the Kindle reader as a futile attempt to change user behavior.

    Yesterday, Steve Jobs announced that the iBooks store served 100 million ebooks in its first 11 months of operations.

    So do we have another example of Steve's classic misdirection where he dismisses a category only to enter and dominate it at some later time?

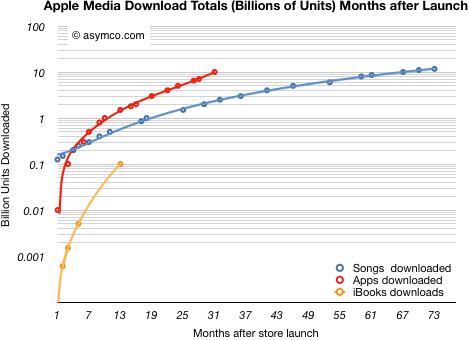
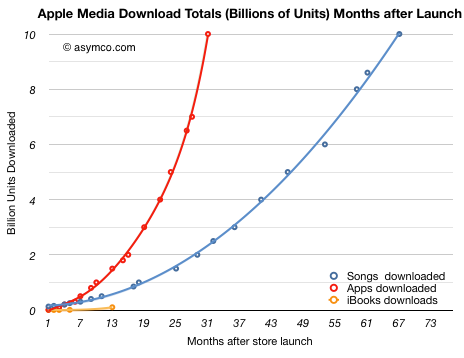
    Let's look at the data. The chart below shows the sales ramp of three media types served by Apple: songs, apps and books.

    At the same point in time (11 months post-launch) there were five times as many songs downloaded and 15 times as many apps downloaded as ebooks. You can see the relationship between different media consumption more clearly on a log chart:

    The conclusion that can be drawn so far is that apps/songs show an order of magnitude more popularity than ebooks. Perhaps Kindle ebooks outsell Amazon music downloads, but we don't have comparable data from Amazon and it would be a challenge to compare the two Amazon media as they are packaged and dlievered in different ways (Amazon's digital music is not an integrated offering while their ebooks are.)

    Books are a 400 year old medium. Songs only 100 years old and apps a mere 10. For three centuries, the book medium had a monopoly on solitary entertainment. The download data shows how quickly new media displace the old. Therefore, in this context, it's perhaps fair to say that Steve was right three years ago when he said "People don't read anymore."

    Today he could add that people use apps instead. Many of the apps available are hired to do the same job for users: solitary, immersive entertainment.

  2. Lookout ZTE and Huawei: Here come NEC, Sharp and Kyocera

    Research · 29 comments

    Sony Ericsson, NEC and Kyocera are among the other Japanese handset makers also betting on Android as their path to international sales.

    via Japanese Phone Makers Look to Ride Android’s Surge - NYTimes.com.

    The Japanese positioning is based on the notion that current Android phones are not good enough and that they can bring "great hardware, great R&D and great engineers" to solve the existing problems with Android portfolio phones.

    That's an interesting observation by Google's own director of Android Global Partnerships. The idea that the market can still reward hardware innovation would also imply that Apple could benefit from that demand.

    So is the message that there is still room for device innovation?

    Perhaps not. Perhaps Android's pursuit of Japanese vendors (and vice-versa) is just evidence of the rush into smartphones by those possessing excess hardware R&D and manufacturing capacity and a deficit of software assets.

    It's still striking that there are hundreds of hardware vendors and supposedly "only two" platforms.

  3. Nokia: We depend on uninformed customers, deception preserves brand value and uncompetitive software will keep us competitive

    Research · 99 comments

    In a previous post I asked whether Nokia's strategy is dependent on a "built-in assumption that end users are inherently stupid."

    Nokia confirmed that this is indeed the case.

    “Millions of consumers are oblivious to the announcements that we have made,” she said. Those consumers value Nokia’s brand, she said, and will continue to buy devices provided the company keeps making competitive products.

    via Nokia's Jo Harlow on the Move To Windows Phone, the Future of Symbian and More | Ina Fried | Mobilized | AllThingsD

    There are three statements being made:

    1. Nokia is counting on uninformed customers, not just end users but the shops and operators which will keep stocking the end-of-life product lines. There needs to be a conspiracy of stupidity for this plan to work.
    2. Nokia's brand will survive even after customers are deceived into buying lame duck products. The idea that buyers value a brand that is offering products that the company does not believe have a future is cynical.
    3. The absurd implication that Nokia's products will be "competitive" even though management asserted clearly and emphatically that the software they run--the very basis of competition for any smartphone--isn't. If a smartphone is expected to be competitive even though its software isn't then it's not competing on the basis of software. If it isn't then how smart is this smartphone?

    One gets the sense that Nokia is undergoing significant ethical decay.

    [UPDATE]

    To paraphrase the ethical dilemma:

    "We want a three horse race. We're not there yet. In the meantime we have a sturdy donkey that can still walk. We expect 150 million people to bet on it."

    [UPDATE 2]

    I take issue with the ethics of jumping off a burning platform while selling tickets to tourists to come visit.

  4. Asymco Interactive

    Research · 5 comments

    Ever since I started publishing this blog there have been requests for access to the underlying data sets. That's not an easy thing to do. Spreadsheets are not "productized". It's very hard to explain how to use one and even harder for charts. Having been an user of commercial spreadsheet models, I know that it's a massive undertaking to produce and support them. Many large companies can afford this but few individuals would be willing to pay $15,000 for an analyst's data.

    In many cases even at large companies professional information services staff are employed to master the data sets and answer questions for the general user. The complexity and cost of comprehensive market research is a huge burden for innovation in analysis.

    As an independent analyst, I've struggled with the question of how to provide this access to a large audience on any device.

    Fortunately, modern browsers have the capability to allow interaction with rich charts. Inspired companies are taking advantage of this and implementing data viewers which extend the way users can visualize complex data. Timetric is one such company.

    Over the past few months we've worked together to find a way to deliver Asymco charts and data as an interactive and downloadable product.

    Our first result is this report: Mobile Phone Market Overview: Q4 2010

    The video below highlights the main features of the Asymco Interactive report:

    httpv://www.youtube.com/watch?v=maNxiXmKVTA

  5. Why operators will find it hard to sell tablets

    Research · 107 comments

    On the eve of iPad 2.0, it's time to think again about this curious new computer. My intuition tells me that this product category will behave very differently from the iPhone and will not be subject to the same sales ramp.

    The iPad has been on the market for less than a year but it's still a puzzle for many. It's a product that's often seen as an iPhone product line extension. From a hardware point of view, it certainly seems to be. It has an almost identical internal architecture and uses almost the same software. An engineer would look at it and reasonably say it's the same thing.

    However, from the way it's used and the way it's sold, it has very little in common with its smaller cousin. There are plenty of experts who can detail how the products are used differently, but I would highlight the portability of the iPhone makes it suitable for a completely different set of tasks than the less portable but more immersive iPad.

    But what I want to dwell on here is how differently the products are sold.

    I'll build the case from evidence that Apple provides. The most important observation is that the iPad is an unlocked product. Although you can hire an operator to provide you with data services for it, the product is designed not to rely on that. As a result the product is effectively "divorced" from the operator channel. This means it does not typically benefit (or suffer) from subsidy.

    This may seem an interesting side-note to the iPad story, but I think this is a central pillar of the market strategy. The iPhone was designed around a high-ARPU data plan. I've even suggested that the iPhone is nothing more than a data plan wrapped in glass and polished metal. Because it was designed to enable migration of cellular voice users to data plans, it's priced to skim profits from the migration. At some future point in time when a skimming strategy is no longer optimal, the iPhone might be re-positioned for penetration, but that time is not now.

    As part of a skimming strategy, the iPhone has a limited distribution channel. It's only sold through special agreement with selected operators. Again, timing is crucial. That channel is expanding, but for nearly four years the product has not been positioned for sale through any channel other than Apple retail and Operator retail.

    On the other hand, the iPad is marketed for penetration. It had a low price and an unlimited distribution strategy. It could be sold through any consumer electronics product point of sale. And then some. It could conceivably be sold through as many if not more points of sale as the iPod (i.e. tens of thousands.)

    It can be sold in any country, can be distributed through middlemen and can be priced arbitrarily [1]. It can be bought in bulk by companies or schools or hospitals. It can be re-sold in a secondary market. It is essentially a perfectly liquid commodity.

    Now we can step back and ask why and what are the implications for competitors.

    The reason the iPad was positioned asymmetrically to the iPhone is, I believe, because it could be. I believe that the iPhone is sold the way it is (through operators) because that's the only way it could be sold effectively. Cellular products have always come with lots of fine print, footnotes and asterisks rooted in the regulatory environment that underlies the industry.

    The iPad is a product built and sold along the lines of the Mac and the iPod--unrestricted by orifices and aligned with the unregulated environment that computers have always enjoyed. Essentially, for the iPhone, Apple chose to go along with the telecom industry's rules but as soon as it had a product that did not need to comply to those rules, it ran back to its comfort zone: control.

    If we take this to be the cause, the implications for competitors become clearer. Apple is more in its element selling the iPad than it is in selling the iPhone. Other tablet contenders however are in an opposite strategic stance. Almost all the credible tablet alternatives rely on the telecom channel for distribution. The rush to build iPad alternatives is as predictable as the derision that was poured on the product when it was launched.

    But the alternative products are positioned in different ways. They are positioned as big phones.

    Which brings me to my final point: selling big phones is hard.

    These products are not compliant with what users expect from an operator: a service plan. As a result they are also not competitively priced with the iPad. Apple engineered a price for the iPad that makes comparisons extremely favorable. Buyers know the thing they are buying is not a phone so they look at the price carefully.

    But the most crucial weakness of alternative vendors is the fact that operators don't know how to sell tablets. Tablets are small computers. They are bought in the same way that buyers buy laptops: in-store testing. Notice that except for the iPhone operators only provide phone mockups in their stores. This is because they want buyers to discuss their purchase with a sales rep. This is not the way laptop hunters shop. Another tell-tale sign of a disconnect between operators and tablets is that operator shops are physically tiny. PCs (and tablets) need large tables for users to look, touch, heft and fondle. Just on square feet alone, operators and tablets are not a good match.

    If you need any more evidence, consider the plight of operator-subsidized netbooks.


    ---

    Notes:

    1. I realize that this is not currently true and the distribution is limited but that's only a matter of supply constraints. There is no theoretical positioning limitation.

     

  6. The platform as a promise

    Research · 39 comments

    In a recent answer on quora, I wrote that I did not believe developers are tempted primarily by economic incentives when choosing which platforms to work on. I suggested that they hire platforms because of their star-making potential and that star-making value is not a something that money can buy. Using Hollywood as an example I suggested that subsidies decrease the perceived value of a talent-oriented platform.

    The notion that a platform signals meaning to developers led me to think about how mobile platforms signal meaning to consumers. I have a hypothesis that platforms can and should be treated as brands. This point of view allows platform orchestrators to develop a comprehensive market-driven strategy for platforms that transcends technical debate.

    First a word about what a brand is.

    Brands are vaguely defined. They are identities, names, symbols or attitudes or all of the above. Marketers struggle to define brand value because they are trying to encapsulate what they sell into a single symbolism. The problem is that there are vast varieties of things being sold. Every product or service has different meaning to buyers and it cannot be captured the same way. Because I cannot rely on a single definition I have to create a specific definition of brand to the context of mobile platforms.

    I choose to define brand in this context of platforms as the "promise of the platform". A platform is a promise that the products will function in ways beyond what's "written on the box"; that the product is extensible and has value provided by an ecosystem bigger than the original vendor.

    For example, although the iPhone is based on iOS platform, iOS is not the brand. "iPhone" encompasses the platform brand and it's a promise to users that they can expect apps and content and an extended flow of innovation to continue well beyond the initial purchase of the device. This brand value is attached to iPod touch and iPad even though it's not communicated as a unified platform. In other words, consumers don't look for "iOS inside" but the implicit value of "there's an app for that" covers all the products.

    When looking at platforms as promises or brands, we can observe how some are more powerful than others.

    Symbian or Series 60 was never marketed as a brand and Nokia users are generally unaware of what OS or platform their phone runs. Does Symbian make a promise of an "extended flow of innovation to the device" after the time of purchase? It's hard to make that promise when you can't communicate clearly anything but device specs.[1]

    Conversely, Android has become a strong brand. The Android label (and mascot) is frequently used by device vendors to signal platform brand value.

    How did Google achieve in a year this value with Android while Nokia continued to squander any brand goodwill around Symbian for a decade? The answer lies in marketing decisions. Nokia wanted to focus on the hardware as value (and the Nokia brand as the way that value is encapsulated). Google and Android OEMs wanted to lift their own device brands into becoming smartphone brands and attached the value of Android branding to them.

    Which brings me to the question of how to design platforms as powerful brands. Creating awareness of extensible value is the way to signal to developers and all members of an ecosystem that a platform is valuable. Apple did this very well with their iPhone ads which focused on the app value of the product. They showed the product in use and did not rely on metaphors. Developers saw other specific apps being advertised by Apple and it engendered huge star value in the platform. Every developer wanted a shot at being featured in an iPhone ad. The iPhone could and did make stars.

    But you can't make the great promise of the platform without the ensuring consistency, reliability and longevity. Fragmentation, malware, copyright infringement and arbitrary termination amount to the confiscation of platform value by the orchestrator. Poor custodianship results in the destruction of both ecosystem and end user value.

    --

    Notes:

    1. The lack of platform promise for Symbian may also explain why Nokia believes they can sell 150 million Symbian devices which have a deprecated platform. Those devices could be sold as feature phones, not platform products. The challenge for them will be to get a smartphone price for a feature phone product.
  7. Google and Apple as mobile co-belligerents

    Research · 94 comments

    The relationship between Google and Apple is an interesting one. It's enticing to declare them "at war" with one another, but that type of relationship does not account for the collaboration and partnerships they enjoy. To wit:

    • Google pays Apple for default Search placement on Safari. This means that Google treats Apple as a distributor.
    • We can presume that there is a deal between the two over Gmail and Maps on the iPhone as well.
    • AdMob is available on iOS without hindrance.

    The business relationships between the two companies are self-evident. However, I would suggest that there are more important strategic reasons why Google and Apple are in fact implicitly collaborating against a common goal.

    The concept of "co-belligerence" may describe the relationship: The state of fighting against a common adversary without a formal alliance and without a guarantee of non-agression against each other.

    The common adversary is the telecom industry. It's an industry being undermined by the technological change of mobile computing and its profits are up for grabs. Apple and Google have different approaches in implementing this change but in the end they dismantle and absorb profits from the same target.

    They are also benefiting each other. Apple benefits Google by creating user experience innovations which Google can rapidly copy. Google benefits Apple by increasing smartphone consumption--educating markets to the value of mobile computing and crippling the profitability (and thus the ability to innovate) of Apple's direct competitors.

    If I may belabor the point, it's like the concept of fast food. One company invents the fast food franchise process, another popularizes it and creates demand. Finally, the innovator comes in with a premium brand to split the market.

    Apple innovates in product innovation with Google as a fast follower. Google then innovates on distribution and penetration enabling Apple to follow with a skimming strategy.

    The end result is a more rapid and thorough profit evaporation from incumbents with corresponding condensation around the entrants.

    To visualize it further, consider what the market would look like if one or the other of the co-belligerents was not participating. Could Google have developed their software without the iPhone as a reference design? At the same time, as Android eliminates the opportunity for alternative software investments by competitors[1] could Apple have remained the only integrated vendor with a uniquely high profit margin?

    Of course, this is not a guarantee of success. New platforms may still take root and integration by HP may actually pan out. But the point I'm trying to make is that, for the time being, Google and Apple are not so much adversaries as comfortably busy winning against a rather weak common target.

    ---

    Notes:

    1. Consider how hard it is for OEMs to justify investing in their own OS post-Android. Consider the desperate status of Nokia who abandoned a broad ecosystem and the paucity of alternatives.
  8. Nokia's Burning Ships strategy

    Research · 84 comments

    In the recent series of exposés on Nokia's new strategy I sought to paint a background for what caused such a dramatic decision:

    This gives a backdrop to the decision, but it does not explain the most crucial part of the decision: why did Stephen Elop decide to maintain an exclusive platform for Nokia rather than a multi-platform approach as chosen by successful competitors such as HTC, Samsung and Sony Ericsson.

    Going from backing one "burning" platform exclusively to backing another "ice cold" alternative without bothering with a hedging alternative is very risky. This may be the biggest puzzle and mystery for outside observers.

    Here I put forward a few reasons why exclusivity attracted Nokia:

    1. The lessons of product focus (see why focusing on a few products is hard).
    2. The costs associated with Symbian and Meego were unreasonably high. (see Nokia employs as many people to develop its smartphone software as Apple does to develop all its products).
    3. The psychology of change management.

    This last one may be the most crucial of all.

    What has to be appreciated is how bloated Nokia has become. It has 140 thousand employees. It's been organized and re-organized countless times and is completely intractable even to insiders. Cutting headcount can only accomplish so much. It deals with costs, but not with motivation. What management needs to do is also incentivize the survivors.

    This is where exclusivity comes in as a motivational tool.

    To explain we need to dip into a new metaphor. Conquistador Hernan Cortés landed in Mexico with the intention to conquer it. Legend has it that as soon as he landed, he burned his ships to prevent his men from retreating and motivating them that conquest their only option.[1]

    Leaders motivating their followers by removing the means to surrender or retreat is not uncommon. It's harsh and brutal. It's not a natural thing do do: destroying perfectly useful options is value destructive and generates outrage, even mutiny.

    In Nokia's case, institutional inertia with a vestigial Symbian effort would compel the organization to maintain the current platform while treating the new alternative as a pathogen.

    Counter-distruption theory states that the response to a disruption requires a focused approach through an autonomous challenger protected from corporate antibodies by the CEO herself. In this case, the autonomous organization is outside the company (Microsoft). Protecting the new effort was not possible with a Chinese wall. The only alternative was to simply get rid of the old and start with a clean slate.

    While there are times it makes sense to burn ships to eliminate any ideas of retreat, there are other times when doing so is reckless. You can do the calculation on the basis of cost of being wrong and levels of uncertainty [2], but even when armed with all the data linked above, this decision can hardly become something that can be quantified.

    It's a gut-level decision.

    I would say that Nokia's new CEO did not just jump off a "burning platform" but that once he jumped he made sure it kept burning so that nobody thought of going back on board.

    ---

    Notes:

    1. There is a Microsoft precedent to this story. See Amazon.com: Burning the Ships: Transforming Your Company's Culture Through Intellectual Property Strategy (9780470432150): Marshall Phelps, David Kline: Books Burning the Ships recounts the decision that forced Microsoft to face its own 'succeed or die' moment. It's a lesson in strategy and survival that speaks about the courage required to embrace radical business transformation.
    2. See also: Burning Ships
  9. Platform sunk (cost): What is the value of a quarter billion Symbian users?

    Research · 38 comments

    In the quarterly smartphone summary published here, I noted the significant acceleration of Android sales at the expense of "other" and Windows Mobile/Phone. Some share was also lost to Symbian. This might be seen as justification for the "platform jump" that Nokia undertook.

    In a second discussion, I published the history and life cycles of the smartphone platforms, identifying 10 platforms (out of 16) still in the market. This challenged the view that it was a two horse race today and that it will become no more than a three horse race in the future.

    Questions came up about the "quality" of these platforms. Clearly some are barely viable while some are thriving. To explain the value of a platform, one metric we can use is the cumulative sales which allows us to derive the installed base.

    The following charts do just that.

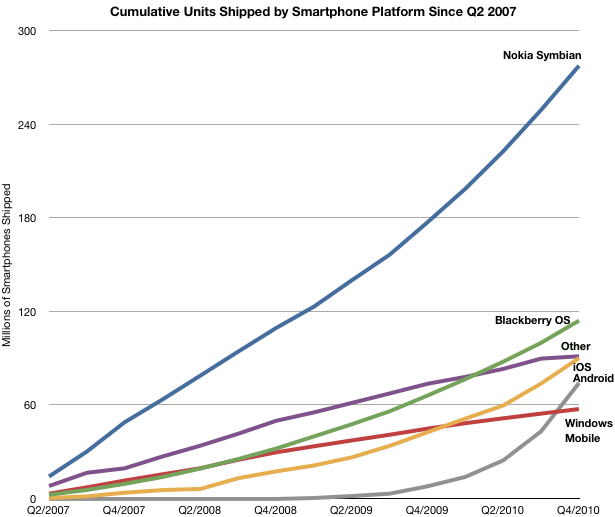
    This first chart shows the cumulative total of units sold since Q2 2007. This is the sum of all smartphones sold in the last 3.5 years. There are some interesting patterns here, but right now we want to focus on the installed base.

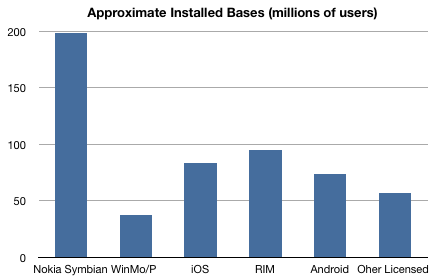
    3.5 years of cumulative sales is an upper bound on the installed base. We can get a better estimate the phones in use by subtracting from the base phones older than 2.5 years. This is shown in the second chart below:

    As of the last quarter, Nokia's Symbian is likely to have 200 million in use. Apple may have about 85 million iPhones in use (this excludes iPod touch and iPads) and Android about 75 million. RIM is around 95 million and Windows Mobile less than 40 million.

    What's interesting is that of these installed bases, the largest is the one that's just been abandoned, and the smallest was chosen as its replacement. Even that's not quite fair since Windows Mobile is not a valid replacement. It's Windows Phone that was chosen and that probably has an installed base of about 1 million [Unlike the measurement of units shipped, Microsoft reported two million licenses were sold to OEMs who had to build those into phones which would be shipped to carriers and distributors. One million may be a generous estimate.]

    The bottom line is that there are about 5 Windows Phone users for every 1000 Symbian users. In other words, Nokia jumped from the "burning" 200 million user Symbian platform to the "ice cold" 1 million user Windows Phone platform.

    The disposal of such a large installed base must count among the largest divestitures in technology history and, when coupled with the adoption of the least-tested alternative as a replacement, elevates platform risk-taking to a new level. It may seem bold, but there is a fine line between courage and recklessness.

    I'll do my own "dive" into the possible justification for this in a future posting.

  10. The lives and deaths of mobile platforms

    Research · 68 comments

    When Stephen Elop said that Nokia and Microsoft sought to create a "three horse race" he implied that there were only two viable mobile ecosystems today. With that statement he sought to deprecate or declare "end of life" two platforms: Symbian and MeeGo, implying that Nokia's efforts at being the third way failed.

    However, he also implicitly declared irrelevant a larger set of market participants. In fact, the market is awash with platforms. Far more than the three or five that Stephen considered.

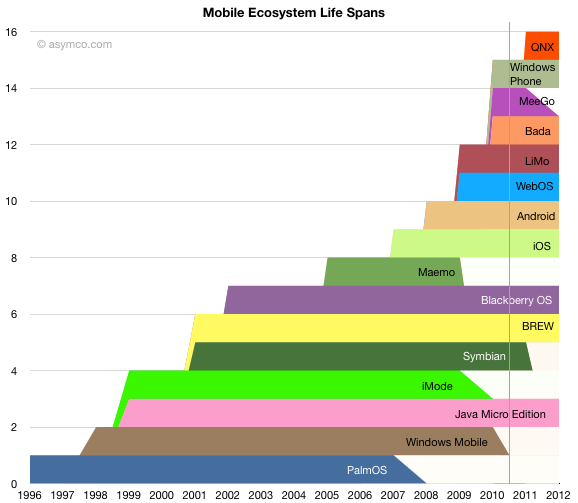
    To illustrate I built the following chart showing the history of all major mobile platforms. The are ranked by launch date (earliest at the bottom). A vertical line marks the present. End dates are approximate and based on declarations of end of life rather than end of usage.

    There have been 16 total mobile platforms[1], 10 of which are still (or soon will be) on the market. Of the six that were terminated, three had replacements built by the same orchestrating company (Windows Mobile begat Windows Phone; Maemo begat MeeGo, and PalmOS eventually led to WebOS.) Only three reached end of life with no known descendant (iMode, MeeGo[2] and Symbian).

    Operating systems that were launched in the 1990s or early 2000s have mostly been withdrawn/replaced with the exception of Java and BREW.  "Modern" operating systems all emerged after 2007 (following iOS). A total of eight such new OSs were introduced in four years[3].

    What I find noteworthy is that there is an implied peculiar fatalism about the market when only two platforms are considered viable, neither of which are more than 3 years old. While visiting the Mobile World Congress, I sensed this jumping to conclusions about platforms was eerily similar to that of a few years ago when new entrants like Apple and Google were declared dead on arrival.

    I can only conclude that there is a great deal of groupthink going on in the industry. A perfect setting for a disruptive entrant to change everything, all over again.

    ---

    Notes:

    1. I excluded some platforms like Motorola's Linux, SavaJe and perhaps some others (Openmoko, Qtopia) which did not gain significant traction. I also excluded any embedded OSs which did not have native APIs.
    2. The end of MeeGo is speculative. Intel is still defending it and may continue developing it.
    3. Android variants like Tapas could be considered new platforms, but I maintain them as part of one OS for the time being.
  11. Where is the Windows Phone Tablet?

    Research · 78 comments

    The Windows Phone platform currently has hardware specifications that imply a cellular phone device. What is interesting in light of the new WebOS TouchPad, the newly announced Android tablets, the RIM Playbook and the iPad is that this supposed "third horse" of Windows Phone has no hint of present or future presence in the tablet form factor.

    That might have something to do with the plans to move Windows to the tablet form factor. Perhaps Microsoft thinks that pocket size devices deserve a separate operating system, platform and ecosystem than portable mobile computers. Perhaps Microsoft plans to have two separate interfaces for these tablets (slates vs. tablets?) Then again, Ballmer held up a Windows Phone and said "This is Windows too."

    It gets confusing.

    The bottom line is that without a tablet implementation, Windows Phone developers and content providers will find that the WP ecosystem will have a limited addressable market and will not be suitable for all forms of media or apps. Tablets are currently expected to grow even more rapidly than smartphones did and so there will be significant numerical advantages to those platforms that support multiple screen sizes and form factors.

    Now that Nokia has anointed the Windows Phone platform as its exclusive conveyance to the device market, the question in the headline becomes: Where is the Nokia tablet?