The iPad and iPhone came, saw and conquered new markets. But since the products launched the question on every analyst's mind has been on how much have these products "cannibalized" their brethren the iPod and the Mac.
This notion of "cannibalization" applies when a product is designed to compete and "eat" the share of another product in a company's portfolio. It has some negative connotations since it implies loss but many times the thinking is that it's better to cannibalize oneself rather than have it done by a competitor.
But have iPhone and iPad taken share from their competitors?
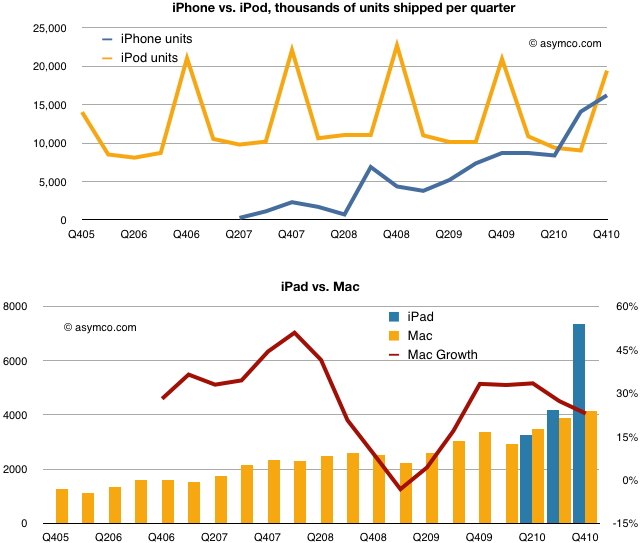
The following charts compare the total units of iPhones vs. iPods and iPads and iPads vs. Macs.
The evidence does not show cannibalization.
Although both iPhone and iPad have crossed over and are selling more units than their internal competitors, the old guard has not faded away.
Indeed, the Mac shows resilience and the iPod, although not growing in units has maintained sales value. What we don't see is a clear gain for the entrants at the expense of the incumbents.
We can't be sure how long this happy co-habitation will last, but for now the new products are fine and young but not cannibals.
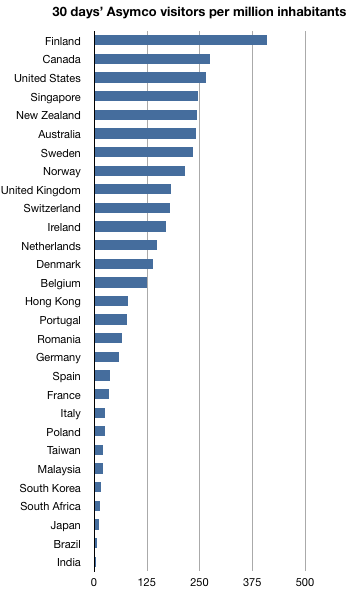
When looking at unique visitors as a proportion of population, this site is more popular in Finland and Canada than in the United States.
Very impressed with Singapore and New Zealand who punch above their weight. UK is second in overall volume. Honorable mention to Australia, Sweden, Norway and Switzerland.
It's interesting to compare this list with Newsweek's ranking of the world's best countries.
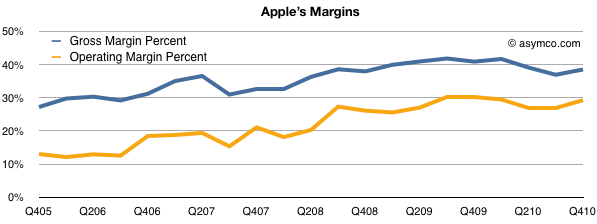
As the highly profitable iPhone makes up an increasingly larger proportion of Apple's sales, the overall gross margin would be expected to grow.
Sure enough that's what's been happening.
The gross margin percent, which measures the direct or variable costs of production vs. price, shows a healthy rise in the last five years from slightly below 30% to around 40%. The Operating Margin, which also includes the overhead or fixed costs like R&D and SG&A, shows a similar rise, reaching about 30%.
Margin expansion while sales quadruple is a good indicator that a company is producing real value not just trading sales volume for profit.
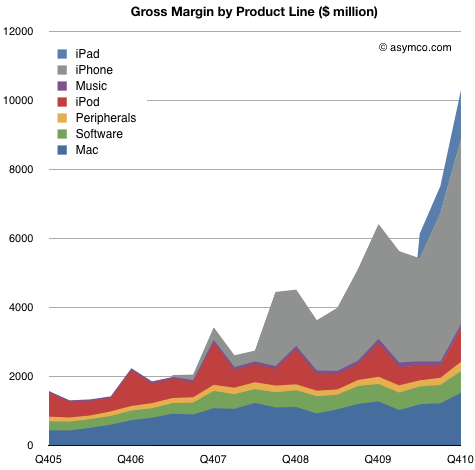
Focusing attention on individual product lines, it's clear that the iPhone is the largest component of sales and of profits. We don't have specific product line-item gross margins from management, but we can estimate a figure for the iPhone by several means.
First, we can work out roughly what every other product line's margin is due to their longer histories. (Mac and iPod have reliable profitability estimates). What's left can be deduced to make up the iPhone's margin.
Alternatively, we can get estimates of the bill of materials and add in some of the other direct expenses like manufacturing, warranties, shipping and incidentals to get an estimate of the cost of production.
These methods allow me to guess at a margin for the iPhone of about 50% for the last quarter. Based on these inputs we can plot the gross margins for the entire company's product lines:
Overall, gross margins have reached over $10.3 billion in the quarter, increasing 543% from five years ago and 61% from a year ago.
That's great, but by knowing product line profitability we can get a better feel how the company changed strategically.
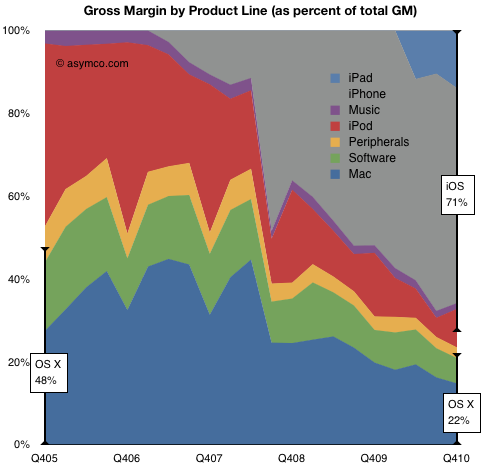
In the following chart I show the percent of gross profit captured by each product line.
What we can observe is that at the end of 2005, OS X based products made up nearly half the profits. The rest was mostly the iPod, which was not a software platform product.
A short five years later, OS X products which, although having grown in volume, made up only 22% of total margin. The rest was mostly iPhone but with significant contributions from iPad and iPod. What's most important to note is that the non-OS X profits are almost all powered by iOS.
iOS powers about 70% of Apple's current gross profits. Combined with OS X, 93% of profits are from platform products.
So again the question about Apple being a software, hardware or media company comes back. Perhaps, those categories are not relevant. Perhaps Apple is a platform company.
As shown in the Apple growth scorecard, the company's earnings growth is continuing at 75% with the top line increasing at the annual rate of 70%.
The $59 billion of cash on the balance sheet has reached the equivalent of $64 per share yielding an enterprise value of $263 per share based on closing price of January 21st.
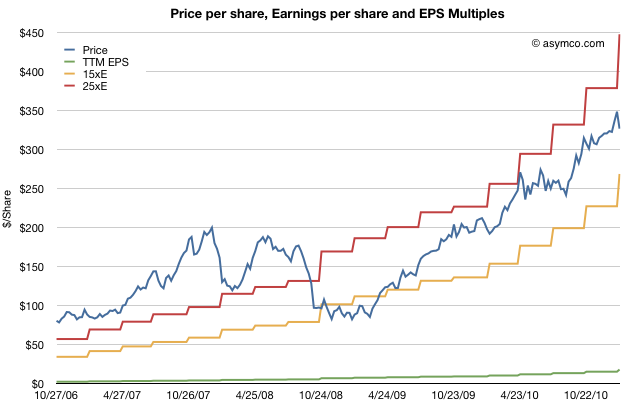
The stock price has been rising but not outside a narrow P/E band. The following chart shows the stock price and the 15 P/E and 25 P/E bands that have bounded it for nearly three years.
As previously observed, this overall share appreciation is not accounting for the growth in earnings.
The trailing twelve months' earnings were $17.91 per share. Therefore the P/E ratio is now 18.2. Excluding cash, the P/E is at 14.7. However, that's based on 2010 levels of earnings. Those earnings are increasing very quickly.
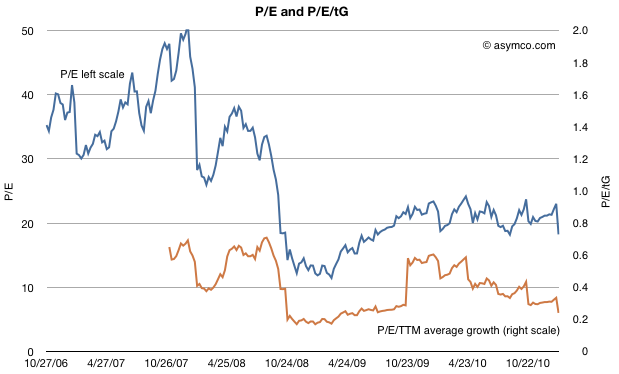
To account for earnings and their growth, I developed the following chart which shows the P/E and P/E/trailing-Growth for the stock.
The P/E is fluctuating on either side of 20 but when considering trailing growth, comparable companies, the macroeconomic conditions and guidance the value of the company is reaching new lows.
P/E/tG nearing recession lows
Earnings were 75% higher in 2010 than the year before. So based on the growth, the rule-of-thumb ratio P/E/trailing Growth (P/E/tG) is 0.24. This ratio (where 1.0 is seen as "fair value") is the lowest since July 2009, during the first months of recession recovery. The trend for this ratio is down (see the burnt orange line in the chart above). It's not far from hitting the lowest point during the recession at 0.17.
Now I'd like to reminisce a bit about that point in time. The stock had bottomed at $78/share[1]. It was trading at barely 3x cash and a P/E of 11 but growing 3x that level (32% in the slowest recession quarter but averaging much higher).
So today we are at a similar point in valuation. The cash is at $64/share, shares are priced 5x that amount and the growth is 4x P/E[2]. Although analyst targets are less comical, there is still the sense of extreme despondency when looking at the valuation ratios.
Guidance, Comparables and Macroeconomics
Unlike two years ago there aren't the same dark clouds on the macro horizon. The company is also not as cautious on its guidance (guiding 63% EPS growth must be a new record for a post-holiday quarter) and there is talk of bubble in valuation for comparable companies. Netflix, Amazon, and ARM have eye-watering valuations relative to growth.
A discount to the S&P 500
And to round out the tragic tale, Apple's P/E is, once again, at a discount to the S&P 500 P/E (14.7 vs. 16.57 respectively).
Given the new low in valuation contrasted with optimism on behalf of many (including management), on some forums there is discussion about Apple becoming the target for a take-over.
There is some perverse merit to this logic. With $64 in cash, $25/yr in earnings and 75% growth it's so cheap that if credit were available, it would make a tempting candidate. Private equity could take it private and use the gigantic cash flow to pay off debt (in about four years). In bygone days, this would have been an easy pitch.
Alas, the capital markets may not have liquidity for the size of the market cap Apple holds and I don't see any competitors able to get the leverage for an acquisition either. Or can they?
---
Notes:
In early summer 2009 some analysts put 12 month targets for the stock at $70, so their predictions were within $6/share to today's book value.
A buyer of shares two years ago would only have to wait two years to have 80% of their investment sitting in retained earnings. An investor who read the data from Apple and knew that the iPhone existed could not fail but be amazed.
Apple set a new record for Mac sales in the fourth quarter. This was not a surprise. The growth was perhaps a bit lower than some expected (including me) but it was still a healthy 23% and 8x the PC growth rate. The Mac has outgrown the PC (and hence has gained share) for 19 quarters straight, nearly five years.
What's more interesting is where the growth came from. Every region outgrew the market. Asia-Pacific led with a 67% year-over-year increase, almost 10x the market. Japan grew at 56%, which is about 6x the market, and Europe and the United States both grew in double-digits despite both markets contracting overall.
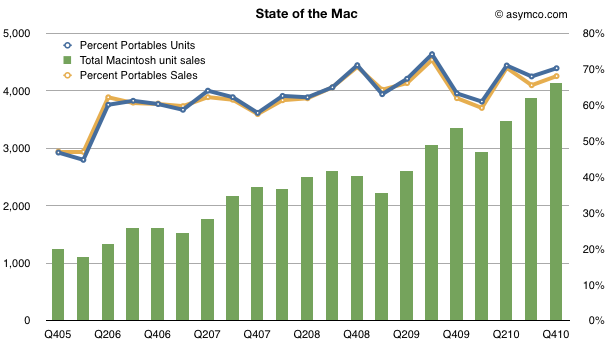
Looking over a longer time frame, the Mac has nearly quadrupled in volume in five years. In the last quarter of 2005, Apple sold 1.2 million units. In the latest quarter it sold 4.1 million. So the performance has been relatively good.
One significant reason for the growth has been the shift from desktop to portables. The lines show how the percent of portables went from about 50% to 70% of units and sales in four years.
[hang1column]
[/hang1column]
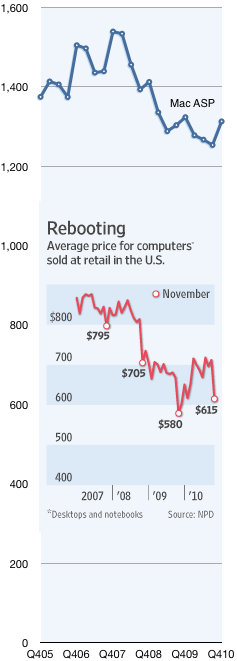
But what was surprising was that the average selling price increased to $1,313, up from $1,253 and nearly even with last year's $1,324.
Prices in the PC industry tend to fall. Actually, to be more precise, they tend to collapse. Compare the Mac's price trend with the rest of the industry as seen in the chart to the left[1]. It shows the Mac Average Selling Price which is what Apple books from selling into the channel vs. the retail price of PCs in the US.
The chart tells a partial story. The PC figures are retail while the Mac figures are wholesale. Furthermore, the PC figures include Mac, so stripping out the Mac would show the PC prices to be even lower. Lastly the Mac figures are global whereas the PC figures are US only.
But what I want to focus on is not the absolute difference, rather the relative value difference, which is diverging: The average PC went from $795 retail at the end of 2007 to $615 in November 2010. That's a drop of 22%. In the same time frame the Mac went from $1,539 to $1,313 wholesale, a drop of 15%.
In other words, the Mac price premium at the end of 2007 was at least 93% and it now is at least 114%.
So here's the real surprise: How does the Mac gain share while increasing its price premium over the PC?
The only answer I can offer is what I already wrote on the Mac in November:
...something changed with PCs when the laptop became “good enough”. With portable computing, the job the PC was hired to do evolved. It was more important that the product be well designed (for aesthetic value, usability and reliability) than just fast and spacious. The microprocessors were plenty fast but what mattered more was low power consumption, a low profile and tighter integration with software.
In other words, computers became re-integrated. You only need to touch the MacBook Air to understand why.
----
Notes:
The inset chart comes from The Wall Street Journal using data from NPD. The Mac data comes from Apple financial reports.
When I wrote suggesting that the "best use of cash" was not acquisition but integration of manufacturing under the Apple control umbrella, the rumor that set off that discussion was that Apple was financing new facilities for its suppliers.
Those rumors were quashed, but we now know there is something to them.
During the September and December quarters, we executed long-term supply agreements with three vendors through which we expect to spend a total of approximately $3.9 billion in inventory component prepayments and capital expenditures over a two-year period. We made approximately $650 million in payments under these agreements in the December quarter, and anticipate making $1.05 billion in payments in the March quarter.
So Peter Oppenheimer confirmed that Apple is using its cash as a loan facility for its manufacturing partners. It's not for the first time either. Apple used the same leverage to ensure the supply of flash memory for the iPod line in 2005.
Philip Elmer-DeWitt reminds us Tim Cook confirmed:
The deal, he said, is similar to the one Apple cut five years ago:
"As you probably remember," he began, "we signed a deal with several flash [memory chip] suppliers back at the end of 2005 that totaled over $1 billion because we anticipated that flash would become increasingly important across our entire product line and increasingly important to the industry. And so we wanted to secure supply for the company.
Partly as a result was a dominant position in the music player market that is still paying off today.
The use of capital to pre-pay for production is not therefore new. What we saw last quarter however is that it's using capital to ensure there is additional capacity.
In other words, Apple Inc. pre-buys additional capacity by using Bank of Apple capital as a loan facility to bring more capacity online. How to judge this use of capital depends on your perspective:
From a fiscal perspective, Apple is acting like a trade lender (with moderate to low returns on capital.)
From the operational perspective Apple is acting as a limited manufacturing partner, just short of an equity holder.
From a strategic perspective, the Bank of Apple lends only to suppliers that commit to producing for Apple Inc. Thus locking out competitors.
This strategy is not without risk. Those loans are forward contracts on production. The risk is that production is unneeded and hence the loans won't be "paid back". But Apple knows demand and supply in this market better than anyone else, so it has an unfair advantage over the market. So the rewards are probably out of proportion to the risk.
By buying an option on production, not production itself Apple has a clever way to "own factories" without actually owning them: gain control over marginal increase in production without the impact from CapEX or depreciation.
The return on that option will never be seen on the OI&E line in the income statement and the cash once recycled back into the balance sheet will seem to be sitting unrewarded. But the return on that capital will show up in the bottom line by way of margin and top line expansion for years to come.
The committed capital is still tiny, but a proper analysis of Apple's cash management would be to look at the return on cash as more than the return on treasury bills.
We expect revenue to be about $22 billion, compared to $13.5 billion in the March quarter last year. We expect gross margins to be about 38.5%, reflecting approximately $50 million related to stock-based compensation expense. We expect OpEx to be about $2.35 billion, including about $250 million related to stock-based compensation. We expect OI&E to be about $50 million, and we expect the tax rate to be about 25.5%. We are targeting EPS of about $4.90.
This is a particularly aggressive revenue growth forecast of 63% (note again that Apple's P/E has dropped to 18 and 14 ex cash and 10 on a forward basis) . Since Apple always guides very conservatively, the likely figures for the top and bottom lines are likely to be higher.
How much higher? Here are my estimates (growth in parentheses is year over year).
iPhone units: 18.4 million (110%)
Macs: 3.62 million (23%)
iPads: 6 million
iPods: 10.1 million (-7%)
Music (incl. app) rev. growth: 25%
Peripherals rev. growth: 23%
Software rev. growth: 23%
Total sales: $24.5 billion (82%)
GM: 38.8%
EPS: $5.89 (77%)
Looking a bit further ahead, earnings suggest the company is now trading at a forward P/E of about 9.5.
At the risk of repetition, there are three instances in conference calls that Apple management has stated that the iPhone has a fixed price for all operators and resellers.
The first was in October 20, 2009:
“So when you go from exclusive to multiple, you don’t change the charge to the carrier?”
Cook answered: “Correct.”
The second was a year later, October 18, 2010:
Chris Whitmore – Deutsche Bank: And what is your experience then when you’ve gone non-exclusive from a subsidy and margin standpoint on the phone, have you had to give anything up in the past?
Tim Cook: We don’t give specific information out on the margins. But I think you can look at our ASPs and see that they’ve generally stayed above $600, and that’s despite opening up several markets from an exclusive market to a non-exclusive market.
And the third was a few days ago on January 8, 2011:
Toni Sacconaghi - Bernstein Research: You've said on previous earnings calls that the move to iPhone non-exclusivity in regions of the world has had no impact on your ASPs. Can you comment on whether that is it still the case today and whether we should expect any impact in the migration away from U.S. exclusivity?
Timothy Cook: I don't envision the overall iPhone ASP decreasing from the December quarter that we just completed to the March quarter that we're currently in.
But, as always, we can confirm and validate using the data on pricing we have available.
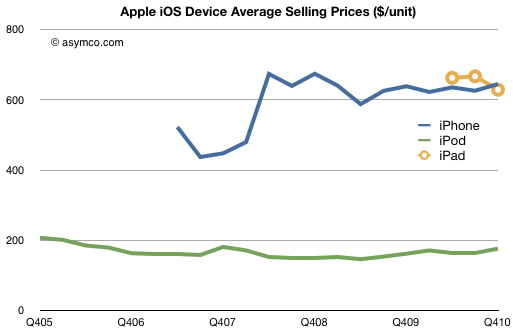
In this case in the financial reports (take iPhone revenue and divide by units sold):
You can see that after the first iPhone "2G" which had a peculiar pricing that included revenue sharing with the operator and which showed up differently in the accounting, the iPhone has had a steady price slightly above $600 for over two years[1].
This is despite having more than 60% sales outside the US and being non-exclusive multi-operator in many countries. Despite being available locked, unlocked and everything in-between.
We can even confirm what one particular operator paid exactly. In October 2008 AT&T reported that they had paid $900 million for 2.4 million iPhones. That's $375 per phone. Assuming a mix of $199 and $299 3G phones that gives something around $600--below the global ASP for that quarter of about $676. Here exclusivity would imply a discount to average price! The reason for the discount is most likely volume as AT&T was by far the largest buyer of iPhones globally.
Still unconvinced? Try shopping for an unlocked iPhone at any of various retail locations where it's available unlocked. Accounting for VAT or other taxation, the price is always the same and is a slight mark-up to the operator ASP due to retail margins.
Judging from comments on this site, the myth that loss of exclusivity in the US will change profit margins for Apple still persists no matter how many times I repeat this story.
-----
Notes:
The steadiness of the price should give another huge clue as to the effect of competition on the product.
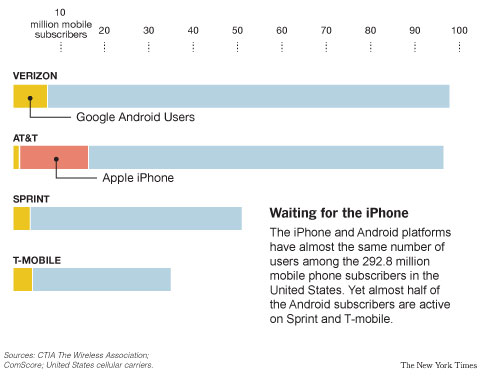
Although the population of Android users is near in size to the population of iPhone users, the concentration in one carrier shows how distribution agreements hamstring platform choice.
The chart also shows how the iPhone had a huge effect on smartphone adoption at AT&T and how it sucked the oxygen out of the segment for competitors.
It is possible that we'll see more Android at AT&T and a lot more iPhone everywhere else, but on balance, the chart shows how exclusivity distorted the market.
It sounded like Tim Cook was really relieved to announce in the earnings conference call that:
We are not under a contractual exclusivity now in any country in the world. The last one was the United States. We have moved away from those.
...
What I've said before and we have seen this in every case, literally, that we've done, is where we've moved from an exclusive carrier arrangement to a dual- or multi-carrier arrangement, our growth has changed significantly and our market share has increased.
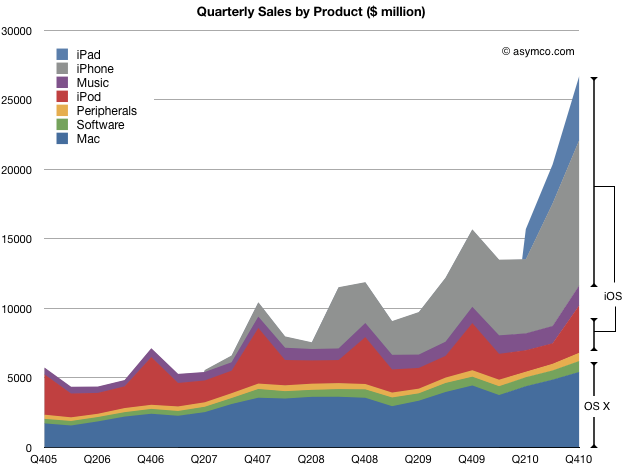
The iPhone and iPad generated $15 billion of revenue last quarter. In addition, iPod touch generated about $2.3 billion, implying that iOS based devices were responsible for sales of $17.3 billion.
To put that in perspective I drew this chart which shows not only the sales by products but a rough representation of share of the two OS variants Apple uses to power its products.
iOS powered products (which did not exist three and a half years ago) generated 65% of all sales in the last quarter. OS X powered products generated 20% of sales. That's a noteworthy combined total of 85%.
But software is even more important for Apple.
The sale of OSX software (both the operating system and applications for it) accounted for another $786 million or 3% of total. In addition, I've put forward some evidence to suggest that the proportion of sales due to Apps in the Music store is nearly half, or another $600 million (a bit more than 2%).
Therefore only 10% of Apple's sales were for products not directly powered by its vengeful operating system. That speaks volumes not only for the importance of software to Apple but for the cohesion of an extensible, flexible architecture that allows it to inhabit a portfolio spanning from a music player and an enterprise server.
I recently answered a question on Quora on whether Apple is a Software, Hardware or Media company by saying it's all three.
With 90% of sales dependent on a unique, proprietary operating system[1], perhaps the answer should have been different.
---
I know that OS X has a large amount of open source. Proprietary, like Open is a partial definition.
But in this forum I've been critical of their strategy. Though I'll be the first to admit that such criticism is not founded on data but on intuition, strategy is always made in a vacuum of data. It is just an unfortunate fact of life that we don't have data about the future.
But what data we do have is about the past and it shows the contrast between Apple and Google.
As a sample, let's look at the performance in the last quarter:
[nohang]
Growth
Google
Apple
Revenue
26%
70%
Earnings
29%
75%
P/E
24.13
18.57
[/nohang] Apple grew about 2.5x faster. The companies are in very different businesses, but the money they make is the same color. The investors have been paying attention:
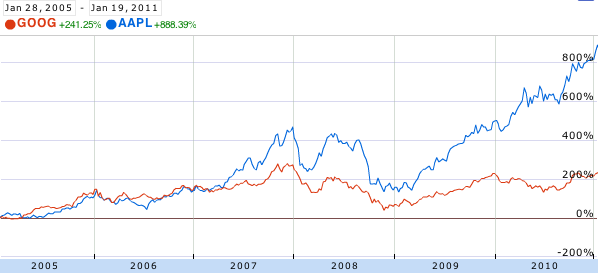
In 2005 and 2006, Apple and Google were neck-and-neck in terms of returns to shareholders. However, with the iPhone's arrival in 2007 the stocks diverged. Google gained 38% since January 2007 while Apple gained 300%.
However, going forward, the market is kinder to Google than to Apple, punishing Apple's 75% growth with a P/E of 18 (ex-cash 15) and rewarding Google's 29% growth with a P/E of 24 (22.5 ex-cash) . Although Google's P/E is proportionate relative to its growth, Apple's P/E implies deep pessimism.
But does Google's performance suggest management failure? Certainly not. It's been a great performance. Google is arguably at the top of its game. Market share of search has never been better.
Cracks in strategy are hard to spot. One hint is that most of Google's R&D efforts are defensive. Building browsers and mobile operating systems are methods to ensure they have distribution of search to as many screens as possible. These are expensive means to ensure channels are available for distribution. Expensive not only in terms of engineering costs but also in terms of relationships and opportunity costs.
But even a defensive posture is not sufficient for management change. What I think is the most serious failure is that for the past five years Google has not addressed the possibility of search itself becoming commoditized. Social media and app economies are asymmetric to search. They make money in different ways and appear to be less efficient or effective means to reach users, but they are growing. Facebook has overtaken Google in terms of page views and apps are a new interaction model for cloud-based content that does away with the indexing model Google champions.
The real condemnation of the leadership at Google is that there has been a failure to create entirely new disruptions. As the stock chart above confirms, Android and Chrome are, if successful, sustaining technologies for Google. That's not going to be enough.