In Barcelona attending Mobile World Congress
I'm registered as a member of the Press and will be attending the MWC 2011 in Barcelona February 14 through 15th. Please email me if you would like to schedule a meeting.

I'm registered as a member of the Press and will be attending the MWC 2011 in Barcelona February 14 through 15th. Please email me if you would like to schedule a meeting.
Research #Industry · 58 comments
The following chart shows the units, sales and profit shares for the top eight phone vendors.
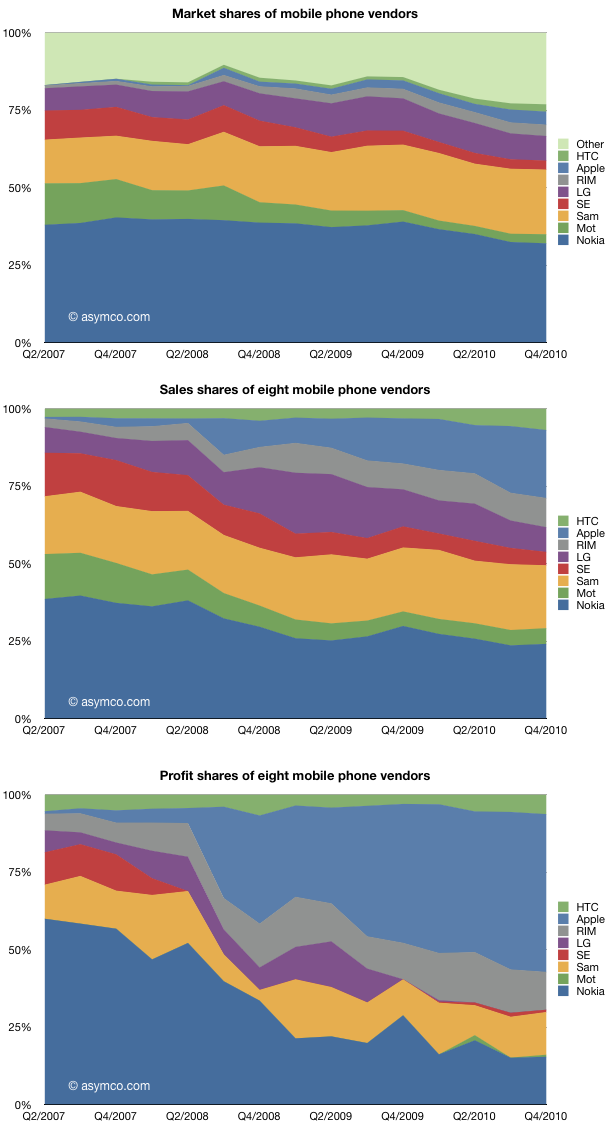
The fourth quarter did not see change in the ranking of the top eight vendors except for Sony Ericsson dropping in sales rank (to eighth). Samsung beat RIM to third spot in profit ranking, a position it held for most of 2009.
Research #Theory · 21 comments
In the earnings Q&A Stephen Elop used the word 'Platform' once, 'Operating System' three times and 'Ecosystem' 15 times.
Though they seem interchangeable, the three phrases have significant differences in meaning. Briefly put, a Platform is a business model concept, an OS is a technology concept and an Ecosystem is a marketing concept.
A platform, as the New York Times recently pointed out, can take many forms. The Barbie doll is a platform as is the US Interstate Highway system. These are products or infrastructure that allow other products to be 'built on top' and can thus charge rents from them. When building platforms, a company needs to think of how to make their work foundational so it can support other structures. Other examples of platforms are browsers, the Apple 30 pin dock connector, Game Consoles and Facebook.
In terms of innovation theory, a platform is a signal to industry that the company is willing to allow its innovations to be extended and thus share in the creativity of adopters. There is however a down side: platform adopters may also create so much value that users will shift loyalties to the layers above the platform thus restricting the freedom of the platform owner to modify or modernize the underlying platform.
This loss of control over the roadmap often forces platform owners to institute draconian limits to the extensibility of the platform (e.g. the iPhone developer restrictions.) In other cases, platform owners have acquired and integrated various core apps or services so that the platform and core apps can be upgraded in sync. This was the impetus to the development of Microsoft Office. Office was motivated by a need to prevent Lotus from slowing the upgrade path for Windows not, as it's assumed, to create a new revenue source. However, again, the effect is the destruction of the ability to innovate on that particular area (no new Word Processor or Spreadsheet programs for 20 years).
It takes a great deal of work to platformize a product. I would guess 10x more than a similar product which does not allow collaborative innovation. Platforms are difficult to build, require delicate balancing acts to maintain but can be enormously valuable due to network effects.
In contrast an Operating System has a very clear technical definition. It has been extended to include many applications and services, but it's basically the control system of a computer. An OS may or may not be a platform. For example embedded operating systems typically do not have APIs to support applications. Some basic mobile operating systems support applications through a sandbox like JaveME (in this case the platform is Java) and are therefore also not platforms.
A company licensing an OS may not accept the platform with the license or may not consider it valuable. It's even possible to license an OS and consider the platform value to be a liability to your own strategy (arguably HP fits in this scenario as regards to Windows. HP had its own operating systems and tried to build alternative platforms in spite of Windows).
An example of an OS with minimal platform value may be WebOS which has a very limited API for native applications.
The word ecosystem as it applies to technology was coined by Palm to describe the app vendors that built apps and the accessories for its Palm Pilot. This is not a common word as it's largely equivalent to Platform. The subtle difference is that it's used in a marketing context to signal platform value. Having a large ecosystem implies the acceptance of a platform by a large base of developers.
For example a platform may not have a viable ecosystem if there are few developers and/or little economic value 'on top' of the platform. Symbian is often cited as being a decent OS, but a poor platform with a mediocre ecosystem.
So these three phrases are overlapping but have a different tone. Although perhaps unintentional, Elop's emphasis on Ecosystem vs. Platform or OS, might signal that what's missing from Nokia's strategy is the motivation or encouragement of developers to participate. My prediction of WP7 licensing may not fit well with this deficiency but perhaps Microsoft's ecosystem building potential is still greater than Nokia's.
I should also point out that Nokia's platform strategy has also included an intermediate layer called Qt that enables cross-platform ecosystems, thus making the OS irrelevant. Technically this may have merit, but it's a long haul to getting an ecosystem for it.
Research #Nostalgia · 30 comments
To me, Apple exists in the spirit of the people that work there, and the sort of philosophies and purpose by which they go about their business. So if Apple just becomes a place where computers are a commodity item and where the romance is gone, and where people forget that computers are the most incredible invention that man has ever invented, then I'll feel I have lost Apple. But if I'm a million miles away and all those people still feel those things and they're still working to make the next great personal computer, then I will feel that my genes are still in there.
Jobs Talks About His Rise and Fall - Print - Newsweek
In the language of innovation theory that Clayton Christensen created, companies are characterized by three attributes
Resources come and go, typically arriving every morning and leaving every evening.
Processes take a lot of hard work to change but they can be changed.
Values and priorities are almost immutable. They are what Jobs refers to as the "genes".
The fact that Steve Jobs said these words about Apple in 1985 after his first departure gives one hope that in 2011 (after his return and departure and return and departure again) the genes are still in there.
Research #Elop #Market #Nokia · 66 comments
Yesterday I made my predictions on Nokia's new platform strategy. They should be treated as pure guesswork, but they are informed guesses. I based them on public information.
That information comes in the form of statements from Nokia's CEO at the earnings call. I made a table of all the statements that dealt with platform decisions and my interpretations of those statements.
You may do your own interpretation, but to me there is significant evidence here to support my predictions.
| What Elop Said | My interpretation |
| In certain markets where there’s a greater preponderance of competing platform devices, we have some competitiveness problems | We have problems in the US |
| Broadly the conversation about operating system and positioning of relative operating systems in different places is something that we'll reserve for the February 11th meeting, | Different markets require different operating systems |
| The general comment I’d like to make though is that in today’s world it is the case that given the different price performance characteristics of different chipsets, we get into situations, where the best experiences are not necessarily delivered by systems that are capable of delivering the highest end experiences. We have to be very mindful at what level of the price curve we deliver what type of device with what operating system. | Different price points require different operating systems |
| When I think about geographies, the area, I've mentioned this indirectly during my comments, but I'll be more precise in answering your question and that is clearly, there is a pattern of disappointments in the United States. A pattern there where efforts have been made, competitiveness, challenges exist and we very much need to address those | We have problems in the US. We're going to address these. |
| That's why I characterize very clearly in the framework for the decision making ahead, that whatever the strategy is that we outline on February 11th, we very clearly will be ensuring that it gives us the opportunity to reopen doors in markets such as the US and some others where we have not recently been present | We are going to enter the US with this platform |
| With respect to the question of ecosystems and so forth, it's important to note, in my opening comments, I referenced the fact that there are today different ecosystems and different patterns at play | Different OS for different markets |
| If you like the high-end ecosystems where there is particular rate of momentum and share gain taking place. At the same time, the dynamics at the very low end of market which itself is an ecosystem of sorts, is very different with very different demands and expectations | High end and low end require different OS |
| I'll just offer that observation that today broadly in the world without any specific comment on us or our competitors, there are multiple ecosystem patterns that need to be considered | More on the need for multiple OS |
| I'd also point out that very critical in whatever combination of ecosystem or ecosystems or whatever our strategy outlines, the need to maintain sustainable differentiation between ecosystems and within the ecosystem relative to our competitors in that ecosystem is a top priority. In everything we consider, that’s something that will be very much on our mind. | What we chose gives us some degree of differentiation--It's possible concessions were negotiated |
| With respect to comparisons to other ecosystem shifts and things like that, the real thing that one must focus on is the quality of products in the market, the momentum that one already has | Symbian is not going to disappear |
| As we’ve described the Symbian momentum that we have today; a consideration of shift of ecosystem, certainly you have to consider that potential of market share changes | Symbian will lose share |
| With respect to the ecosystem comment, without getting into specifics of different options and things like that in detail, what I will say is that the word catalyze is to imply that there is a wide variety of participants in our world, and that includes competitors, it includes operators, other technology firms and so forth who in many respects have a common interest relative to the potential strength of other ecosystems and how they may develop over time | Partner is a tech firm that has common interest -- i.e. market entry |
| The catalyst of an ecosystem could be considered as making sure the right conditions are formed in the right companies, work in such a way that alternatives emerge in a marketplace that may not exist today | Looking at growing the market for the partner-- Microsoft |
| We made a decision to not proceed as people have thought we would proceed | This is not going to be business as usual |
| You'll see that pattern of decision making from us in terms of being very crisp about what constitutes great experiences and ensuring that that is what we are delivering to our customers. | This is a marketing-led effort. We're going to stay on message and not waffle on about technology |
Since reporting on the 18th, I've mostly finished going over the the fourth quarter Apple data. Here is a quick summary of the articles that covered the financial and product performance:
| Subject | Article |
| Cash | Having added $20 billion last year, Apple’s cash growth suggests total could top $100 billion next year |
| Growth | Apple’s Growth Scorecard: 63% average earnings growth over 16 quarters |
| iPhone pricing | The end of exclusivity doesn’t change the price operators pay for the iPhone |
| Sales by product | 65% of Apple’s sales came from iOS powered devices |
| Next quarter’s estimates | Estimates for Apple’s second quarter earnings (ending March) |
| Share price/valuation | Is Apple a candidate for acquisition? |
| Margins and platform mix of profit | iOS enables 71% of Apple’s profits. Platform products power 93% of gross margin |
| Cannibalization | iPhone and iPad: Fine Young Cannibals? |
| Operational Expenses | $76 billion a year from a tableful of products |
That leaves one more: Summary view of cash flows.
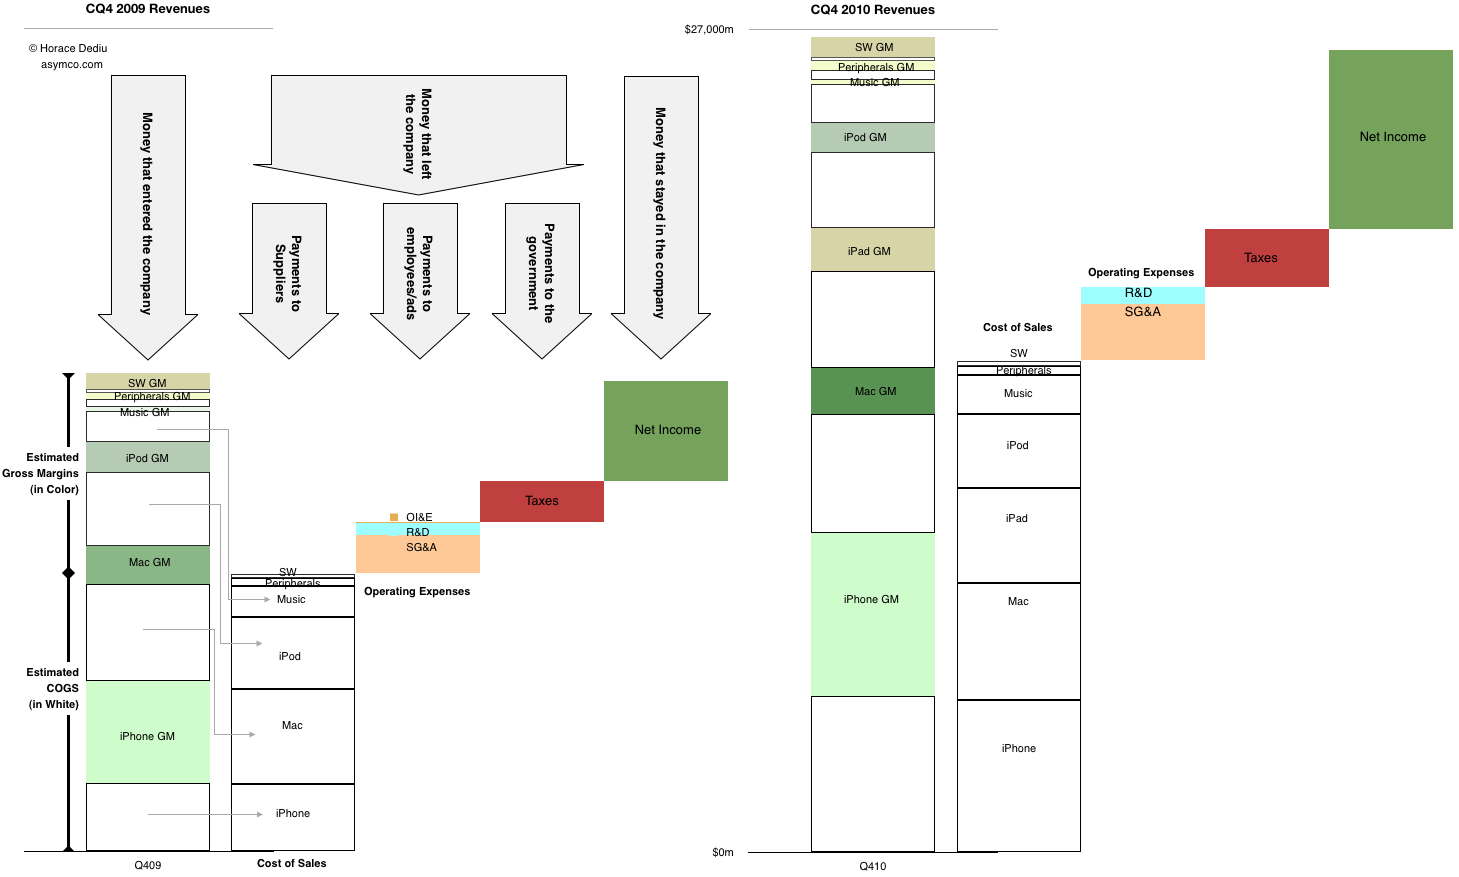
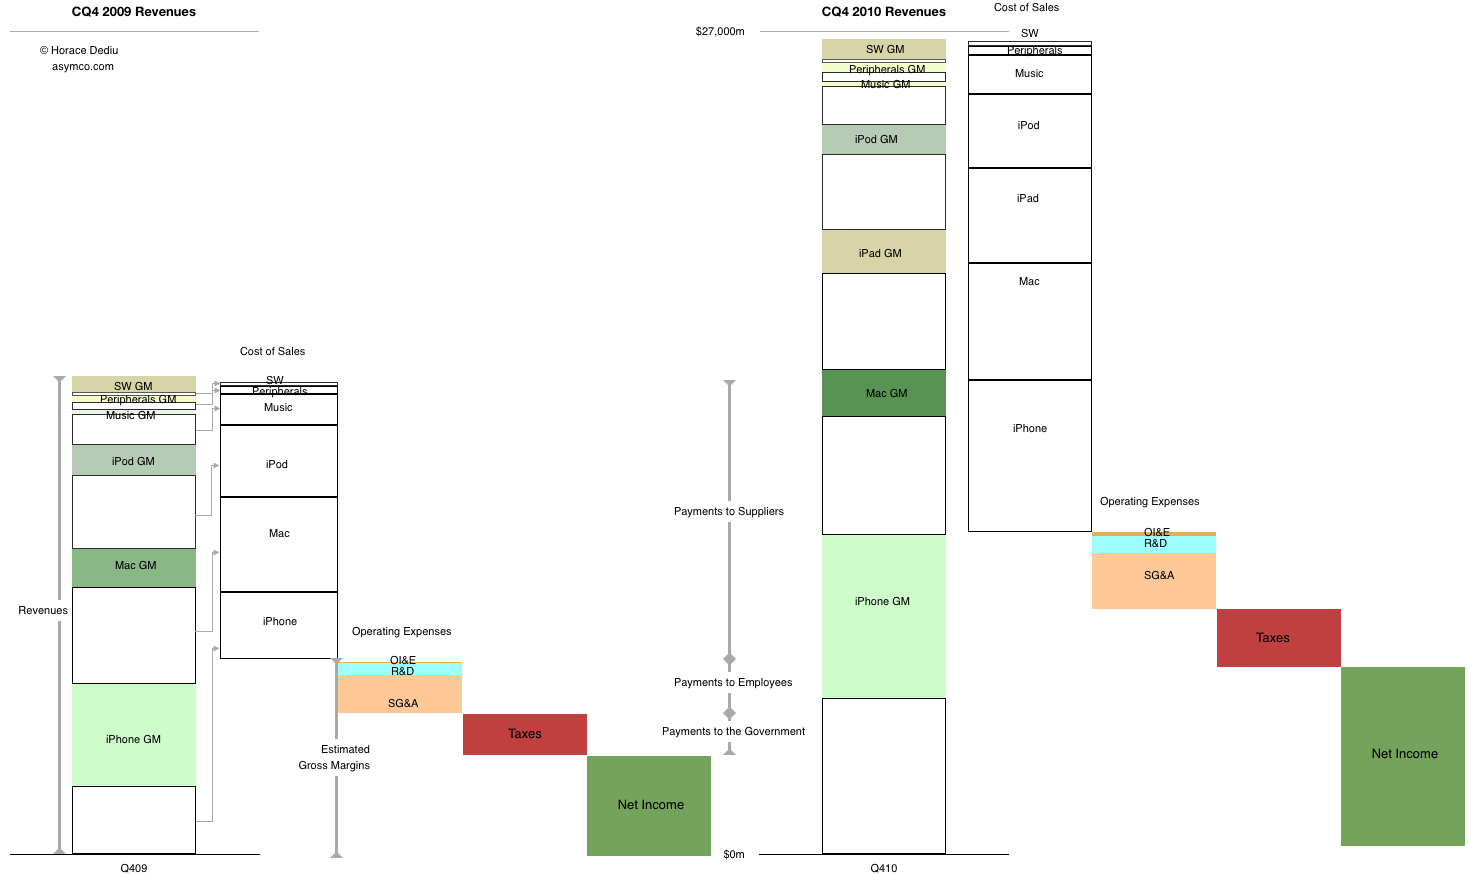
After introducing it last quarter, this is a chart that I'm trying to improve and use as a single snapshot of growth, product mix, profitability, cost structure and overall sales. The purist in me likes to see the chart clean but it can be a puzzle to some. So for the sake of explanation, this time I've added some annotations to the year-ago quarter.
The left half shows flows in the same quarter a year ago and the right side shows the flows in the fourth quarter just ended December 2010. You can see where sales came from, how much of each product's sales went to suppliers and how much was available to pay employees (and who got what). You can also see how much was paid in taxes and what was retained.
Please click on the figure (requires no scrolling when viewed on screens wider than 1464 pixels).
[Update] Alternate view using "waterfall".
Research #Industry #Samsung · 22 comments
The smartphone market grew 73% in Q4. Here are the growth rates for vendors which regularly report smartphone sales:
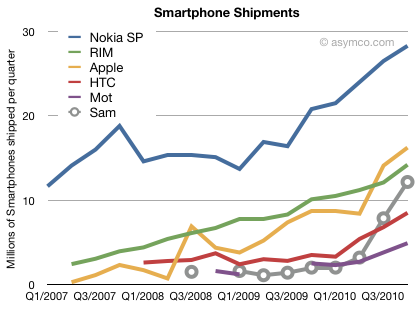
Samsung is not consistent in reporting smartphones and we don't have year-ago data but the following chart can be used to get a hint.
Samsung had a very good year with 25.2 million smartphones sold. This is compared to 2009 when they probably sold less than 5 million. Their growth has meant they overtook both Motorola and HTC and are likely to overtake RIM this year.
Samsung owes its success mainly to adopting Android. As can be seen in the next chart, Samsung moved rapidly to shift its portfolio from non-smart to smart. This is quite a feat considering the starting point well below that of Nokia.
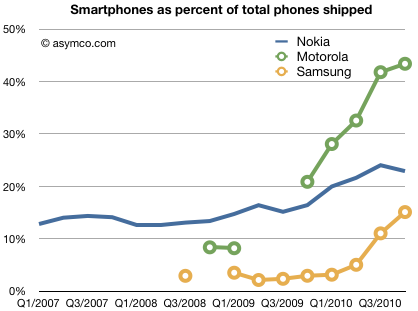
From 2% of total phones to 15% smartphone volumes in 18 months is astonishing.
Extrapolating for the missing data leads to an estimate of smartphone growth for Samsung of over 500%.
Research #Industry · 13 comments
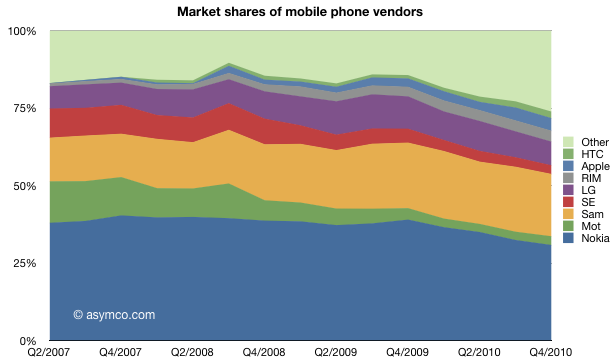
Biggest share winner: Other.
The trend toward ZTE, Huawei and others taking volume share from the traditional incumbents continues. Smartphones continue to capture value share. Dedicated smartphone vendors HTC, RIM and Apple would make up the third biggest single vendor, starting from a very small base.
Looking over this three and a half year period, the change in the market is quite dramatic.
Research #Industry #Nokia · 60 comments
Nokia must compete on an ecosystem to ecosystem basis.
In addition to great device experiences we must build, capitalize and/or join a competitive ecosystem. The ecosystem approach we select must be comprehensive and cover a wide range of utilities and services that customers expect today and anticipate in the future.
Nokia CEO Discusses Q4 2010 Results - Earnings Call Transcript - Seeking Alpha
These kind of statements are signaling that there will be fundamental changes announced.
Here are my guesses for the February 11 announcement:
This may seem like a radical departure, but in many ways it's not. Nokia has nothing to lose in the US as its platforms have zero traction. By maintaining Symbian for low end devices, they can still aim for differentiation where Nokia feels it still has distribution and cost leverage. This strategy will also allow speed in time to market.
During the calendar year 2010 Apple spent nearly $2 billion in R&D. That is a significant increase from $714 million in 2006. However, as a percent of sales, R&D spending has decreased. Sales have grown more rapidly than resources hired to develop the products (or to sell them).
In Q4 2005 Operational Expenses (costs which are not tied directly to units of production--sometimes called fixed costs) were 14.2% of sales. In the last quarter of 2010, the ratio was 9.2%. Sales and administrative expenses (which include advertising, promotion and overhead) were 7.1% and R&D (which includes all engineering, testing) were 2.2%. As percent of sales both reached new lows.
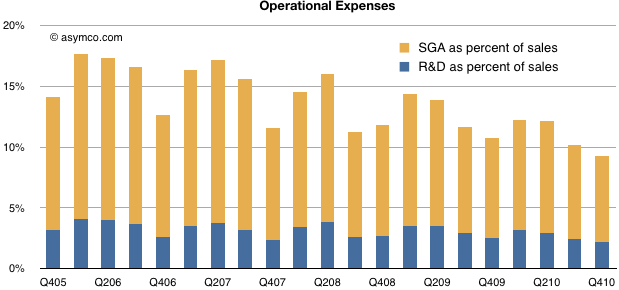
The efficiency with which Apple creates sales is legendary. There can be many explanations for this but the most telling evidence of causality I can find is the small number of products in the portfolio. Tim Cook stated that given the sales value, there is more concentration of product at Apple than at any other company except perhaps an oil company. All the products Apple sells can fit on one average sized kitchen table and they generated $76 billion in sales last year.
How is this possible? First, a few words about the often misunderstood process of product development.
Most observers of technology are not aware of the pace of its development. It's natural to assume that most R&D costs are in the product creation, or early phases of development. Coming up with something new must be hard. But that's not actually true. Most R&D work is routine polishing of products and coordination late in the development cycle. "Productization" is far more resource intensive than "concepting".
It stands to reason that making go/no-go decisions early in the pipeline is a lot less expensive than making stop-ship decisions prior to launch.
I have no specific evidence that this is the case, but I guess Apple conceives of plenty of concepts, but chooses to move forward to develop and market very few. Most companies don't have the ability to decide early which products to launch and instead proceed with costly R&D and marketing in order to find out whether products will "work" in the marketplace. The proliferation of flawed products is a big cause of the inefficiency of product development.
But launching flawed products is also detrimental to brand value, something which rarely hits the books and is thus invisible to operational managers.
This uncanny ability to pick winners early in a long gestation period is my guess for why Apple is so efficient with OpEx. The question of how to develop this ability is left for another day.
Research #Industry · 47 comments
‘Any argument that a pad is not a PC is simply out of sync,’ said Chiam. ‘With screen sizes of seven inches or above, ample processing power, and a growing number of applications, pads offer a computing experience comparable to netbooks. They compete for the same customers and will happily coexist. As with smart phones, some users will require a physical keyboard, while others will do without.’
‘Each new product category typically causes a significant shift in market shares,’ said Chiam. ‘Apple is benefiting from pads, just as Acer, Samsung and Asus previously did with netbooks. The PC industry has always evolved this way, starting when Toshiba and Compaq rode high on the original notebook wave.’
via Canalys reports global PC market growth of 19% in Q4 2010 (Canalys research release: r2011012).
Five years ago, back when Gartner and IDC were confused about what a smartphone was Canalys was on top of the market and was the first to correctly describe the smartphone.
Kudos for being first again to recognize a re-defined market.