Asymco

Asymmetric Intelligence

Horace Dediu

  1. Half of US population to use smartphones by end of 2011

    Research · 35 comments

    60.7 million people in the U.S. owned smartphones during the three months ending in October, up 14 percent from the preceding three month period, representing 1 out of every 4 mobile subscribers.[...] Despite losing share to Android, most smartphone platforms continue to gain subscribers as the smartphone market overall continues to grow.

    via comScore Reports October 2010 U.S. Mobile Subscriber Market Share - comScore, Inc.

    Separately, Nielsen reports on the same market:

    29.7 percent of U.S. mobile subscribers now own smartphones that run full operating systems.

    The most popular smartphones are the Apple iPhone and RIM Blackberry, which are caught in a statistical dead heat with 27 percent of smartphone market share in the U.S. Twenty-two percent of smartphone owners have devices with the Android operating system.

    via U.S. Smartphone Battle Heats Up: Which is the “Most Desired” Operating System? | Nielsen Wire.

    I've been tracking the Nielsen data and using it as a basis for forecasting the penetration of smartphones. While most coverage of this data focuses on splits between current OS platforms, I will look at competition with non-consumption and the impact on operator services.

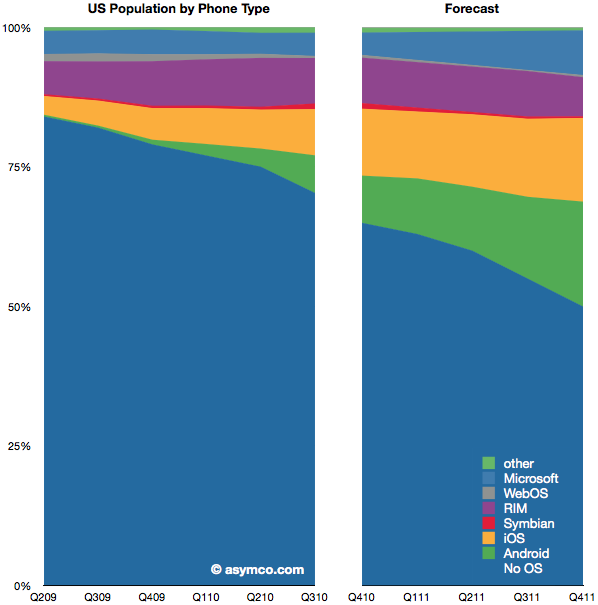
    The chart on the left shows the historic penetration of smartphones since mid-2009 based on Nielsen's reports. The chart on the right is my forecast. This is an update from the last quarter's chart here. My forecast was fairly accurate with respect to platform shares in the last quarter so I've had to make only small adjustments and extended the forecast one quarter further out. [1]

    If my forecast is correct, smartphones will make up 50% of all phones in use by the end of 2011. That's up from nearly 30% today and 18% a year ago.

    One in three of all phones in use will be either iOS or Android. That adds up to about 80 million users; up from 35 million today. Overall, 120 million Americans will be using smartphones.

    Now consider the consequences for how services are delivered by operators. The most popular product operators will be selling will be unlimited data plans. One year hence, by 2012, unlimited data plans may become the largest service revenue generator for mobile operators in the US. Pricing and competition will inevitably be in a state of extreme flux. I leave the consequences to the imagination of the reader.

    ---

    [1] Note that the charts show share of phones in use, not phones sold in a particular point in time. In other words, this is measuring platform consumption, not units sold.

  2. I see no major acquisitions in Apple's future

    Research · 34 comments

    Yesterday I attended the first meeting of the Forum for Growth and Innovation. It's an initiative where practitioners of Clayton's Christensen's theory of innovation can review new academic research before it's published.

    The Forum has another goal: to disseminate and propagate key learnings and ideas. As a keen student of the theory and a blogger, I am eager to provide a gateway for you, my audience, to this management theory.

    My modus operandi has been to discuss an industry or a set of competitors in great detail while occasionally stepping back and suggesting a cause for the patterns of behavior we are witnessing. More often than not, the causes are described very well by the theories in Christensen's writings.

    There are cases where the theory does not seem to match. That's actually the most exciting part of this process. Exception (or anomaly) handling is what allows the theory to evolve and improve.

    Yesterday's event focused on M&A. It's a cliché to say that M&A is a recipe for failure but there are recipes to follow that minimize the chance of failure. The forum debated these recipes and we were treated to the wisdom from those who learned the hard way what works and what doesn't. (For example, the ex-CEOs of Best Buy, Arrow Electronics and a senior executive who worked under Jack Welch at GE.)

    What I came away with was a new respect for the counter-intuitive and contradictory nature of acquisition integration. What often makes sense on paper like synergies or new growth can quickly turn to a loss of the core business. Recipes for deciding what to integrate and what to keep autonomous are an active area of research.

    For this and many other reasons, it's easy to understand why Apple is reluctant to make large acquisitions. The market discounts Apple's cash because it is expected to evaporate in a mis-guided acquisition (since that's what management has shown a propensity to do in most other large US companies.)

    I've written about why I think Apple's cash is worth more than other companies' cash (e.g. Microsoft.) Apple's reluctance to make large acquisitions and no record of such should provide some hope.

    However, I don't think that reluctance is simply a coincidence or a lack of suitable candidates for acquisition. I think it's more a result of the company's processes and priorities. As long as the team in charge is focused on the details of execution and integration, and as long as acquisitions are complex and fraught with unknowable risk and lack of control, I see no acquisition in Apple's future.

  3. Android is accelerating smartphone adoption

    Research · 16 comments

    According to Morgan Keegan analyst Tavis McCourt Chinese consumers purchased 8 to 10 million smartphones last quarter--implying 400% growth from the 2 to 3 million last year.

    How quickly things change. According to McCourt, Android now represents nearly 50 percent of smartphone volume in the country, up from zero last year. And Apple’s iOS, while a niche player with less than 500,000 iPhones sold last quarter, is ramping up quickly, thanks to the successful launch of the iPhone 4 in the country last month.

    via 50 Percent of Smartphones Sold in China Last Quarter Run Android | John Paczkowski | Digital Daily | AllThingsD.

    The growth of Android is far beyond what a single company can engineer. It represents the effect of uncoordinated and uncontrolled distribution. Google does not have to market, license or write contracts for Android. It also does not necessarily benefit from this work. It enables excess device manufacturing and distribution capacity to embrace browser-enabled devices.

    Android is clearly accelerating smartphone adoption and is competing very effectively with non-consumption. Without Android I doubt many of the Chinese manufacturers who are building more smartphones today would be doing it.

    One question that remains with is whether Google will do anything to police the platform or leave it to run and splinter.

    Another question is what will current Android users aspire to purchase for their next phone.

  4. The companion screen: will TV learn to be social?

    Research · 7 comments

    I've been traveling the past few days and did not have access to substantial enough bandwidth to make meaningful contributions to the blog.

    However, I will be online for the next few days and will catch up.

    One observation I had while visiting App World is how apps are affecting the future of television. The notion of single screen viewing is rapidly receding. In the UK among certain demographics, half of the viewers watch TV while interacting with a "companion" screen. This figure is significant in other markets as well.

    The consequences of this dual-screen experience could be profound. More profound than what PVR technology enabled. What I would like to think about is whether the dual-screen experience enables new jobs-to-be-done for TV (e.g. "social" TV) vs. what PVR did which was make TV watching "better".

    The key question is whether solitary TV viewing is a different job from accompanied viewing.

    If viewing while in the company of others is a distinctly different job from solitary viewing then a dual-screen approach will allow interaction with a companion even if they are not in the same room. This implies that the more natural interaction for TV viewers is not with the programming but with other viewers.

    On the other hand, solitary viewing may be hired for a very different job. Not all programming is suitable for a social experience. Producers need to carefully categorize their production according to what jobs it's getting hired for.

    An even deeper strategic question is whether programs themselves should be designed with social interaction in mind, and if so, is TV production something that should be built in an inter-dependent way with the devices and the second screen in mind? Does there need to be a "studio system" for TV where production, talent and distribution are under one over-arching controller?

    This discussion parallels that around the re-integration of the value chains where Apple participates. Perhaps the challenge for the re-invention of TV is really to what extent can any one participant in the value network orchestrate an integrated approach.

    More on this topic to follow.

  5. The iPhone is not superfluous, not easily copied, not revolutionary and not a premium product

    Research · 61 comments

    The release of the iPhone is rightly acclaimed as a watershed event in the history of telecom. It was a sensation. But it was also a product that was widely underestimated and dismissed. Even today expert opinion is divided. The critics of the product transitioned directly from labeling it a superfluous bauble to an obvious and copyable sustaining innovation. Advocates of the product describe it as revolutionary and dazzling with the potential for capturing significant profit share due to premium pricing and positioning.

    So which is it?

    I'll argue that it's none of the above. The iPhone is not superfluous, not easily copied, not revolutionary and not a premium product. What it is is disruptive.

    First, we have to quickly define disruptive potential.

    A product is disruptive if it competes with an existing, incumbent set of products on a new basis. It competes along a new measure of performance. That means it's either "low end" and hence cheaper, simpler, more modular and conformable, or it creates a "new market" where completely new measures of performance or quality are relevant.

    In both "low end" and "new market" disruptions the product is usually wrapped in a business model that insulates it from incumbent response due to inherent asymmetries. Incumbents will find the economics of the entrant product unattractive and will be motivated to ignore it or actively avoid copying it.

    The consequences of disruptive product entires are often catastrophic for the incumbents because, over time, the disruptor product vacuums up all the profits in the industry, robbing the incumbents of the fuel to respond by the time they become motivated to do so. In essence, the transfer of value to the new basis of competition happens so slowly that the threat is imperceptible until it's too late.

    If we look at this definition, it's startling that the iPhone does not seem to fit.

    As a phone, it's not cheaper, nor modular and hence not "low end". It did not create a new market.  As a phone, although it did recruit more regular phone users into becoming smartphone users, it was not the first or last phone to do so. Its phone business model was not a radical departure. It was not ignored by the mobile phone incumbents who reacted with various degrees of urgency and vigor. It was actively copied in every way from the UI to the ecosystem to the pricing model and distribution.

    The only thing that seems to have happened according to the disruptive formula was the transfer of profits from incumbents to Apple, at least temporarily.

    So the iPhone seems to be correctly classified as a sustaining innovation. Something that moves the phone market forward and which, except for a temporary misallocation of profits, will entrench the incumbents after they manage to copy it effectively.

    However, here is where we have to dig a little deeper.

    Market analysis easily becomes myopic when looking only at a market defined by a product. I've argued in the past that strategic insight comes from looking at products that cross over their market boundaries. Especially products that are hired to do different jobs than the same products in their categories. The iPod may seem like an MP3 player but it caused catastrophic profit collapse in multiple industries. It knocked out the CD business, it crippled the component audio system "Hi-Fi" industry, it razed the music retail business and affected the entire music value chain. It's still pounding at the gates of video and TV production. And, almost as a side-show, it crushed the Walkman.

    Even though it was a music player, the MP3 device market was the smallest target for the iPod. It turned out to be far more dangerous to ancillary industries. The reason is subtle: it competed as an integrated ecosystem. You hired the iPod to serve you music everywhere, not just in your living room. And it did the job in an integrated way from source to earbuds taking what was a hodgepodge of modular components built around analog music and smoothly integrated them to deliver music in new, non-consuming contexts.

    The lesson is therefore that when looking at the iPhone one has to look at ancillary industries not just at phones.

    Phones have always been a component in a wider inter-related telecom value network. Even today they are often called "terminals" in the industry meaning that they are the end points of a network. Similar to the PC, the iPhone enables a migration of intelligence away from the center toward the edge of the network resulting in a de-valuation of the network itself.

    I argue that the real disruption of mobile computing (i.e. iPhone) is made possible not by the smartphone technologies but by mobile broadband. Once broadband became mobile with 3G the smartphone could shift its focus (jobs it's hired to do) from voice to data. That shift is disruptive to incumbents because they built their businesses around operator distribution and operator service economics. With apps, mobile computing brings with it services which allow all communications to be independent of operators. Selling ringtones, maps, email and video-on-demand are all dead business plans today. But operators clung on to these hopes for many years and forced vendors to comply to this strategy.

    The incumbents relied so much on the telecom value chain, where the value flows from the monthly service charge, that they would not deploy technologies or business models that were asymmetric to operator business models. This is the root cause for Nokia and Samsung and Motorola and LG "missing the boat" on smartphones. All the vendors had the pieces of technology on their shelves. But when they took these technologies to their customers, the customers rejected the package.

    This is why entrants like RIM and Apple could easily gain a foothold and grow. They had modest volumes, sold new concepts like business email and new UIs with iconic designs, but did not go after the core business model. This is similar to how iPod/iTunes got a toehold with the record labels. By the time the disruption took hold, operators were addicted to the new high-ARPU being generated even though they were all pure bitpipe plans. A bird in the hand is worth two in the bush, so the new device brands stuck.

    Do the incumbents still have time to respond effectively? It's less and less likely. They cannot build the new computing ecosystem without the distribution power of operators. Note that iPhone 'clones' in Android are still sold via operators and that nobody is interested in making either iPod touch clones or iPad clones sold independent of the operator channel/subsidy model. This is not because of technical or economic reasons but because of a lack of distribution (and lack of integrated content).

    When you step back and look at the phone in the context of the network business model as well as the shifts in consumer jobs to be done you realize the potential is far greater than taking share from incumbents. The iPhone is not divided into a portfolio of different phones, but it's a part of a portfolio of new mobile computing products. It just happens to be the only one which still depends on the cellular operator distribution network.

    Seen as part of a new mobile computing paradigm and following the trajectory of the mainframe, mini-computer, PC and laptop, the iPhone is an essential, non-superfluous device for a vast population of new users.

    Seen as an integrated app ecosystem with strong network effects, it's not easily copied. Responses that only account for it as a glass and metal object of desire will fall way short of being competitive. As the hardware was always available to competitors, it's not a revolution in hardware or even in user experience.

    Most importantly, seen as a computing alternative merged with a communication appliance, it and its siblings are not premium products. The pricing and service structure around it make it seem a low cost alternative for solving the jobs it's hired to do.

    In other words, it is as disruptive as it gets.

  6. I'll let you in on a secret: insider info is bogus

    Research · 11 comments

    So the SEC is investigating analysts who peddle "channel checks" for violation of securities laws. Former SEC chairman Paul Atkins summarizes the law as follows:

    "Insider trading basically comes down to where you know or ought to know that the person from whom you're getting this information has a duty to someone else to keep it confidential. If you go in and pay the mail clerk to give you special information, that's not proper."

    This is perhaps newsworthy. But the real news is that information that comes from sources that cannot be verified should not be trusted and certainly not valued.

    Here's why: if someone holds information that is non-public they automatically treat it as more valuable. It's more valuable because it's not something everyone has. It's not valuable because it's accurate. By definition, that accuracy cannot be proven so the assumption of its value is based entirely on exclusivity. So valuable perhaps that you can even sell it, and surely many do.

    However, simply not being public makes is no more likely to be accurate. You have a situation where people ascribe more value to something that is equally (and sometimes even more) inaccurate as background noise.

    Beware of anyone offering non-public information to a larger audience. The data and the person's ethics are both suspect.

    The proof comes every quarter: those who rely on inside info are no better and often worse in predicting fundamental performance.

  7. Measuring iPad enterprise use

    Research · 25 comments

    I've noticed that there is a lot of speculation on the prospects for iPad use "in the enterprise". Business users could sure benefit from the device and anecdotal evidence does point to many cases of use in business.

    But anecdotes are not conclusive evidence. How can one make a better guess? Based on reader input, I thought I'd test this hypothesis directly on my own stats.

    As pointed out a recent posting on my stats, the iPad has been a popular device in accessing this site. 102k out of 1.06m views came from iPad users. A statistically interesting number.

    One way to check enterprise use is to measure the ratio of use of the product during weekends vs. use during weekdays. The logic being that weekend use is almost strictly consumer use and weekday use is mixed. Any normalized significant difference between the two measures should indicate a bias toward consumer use or vice versa.

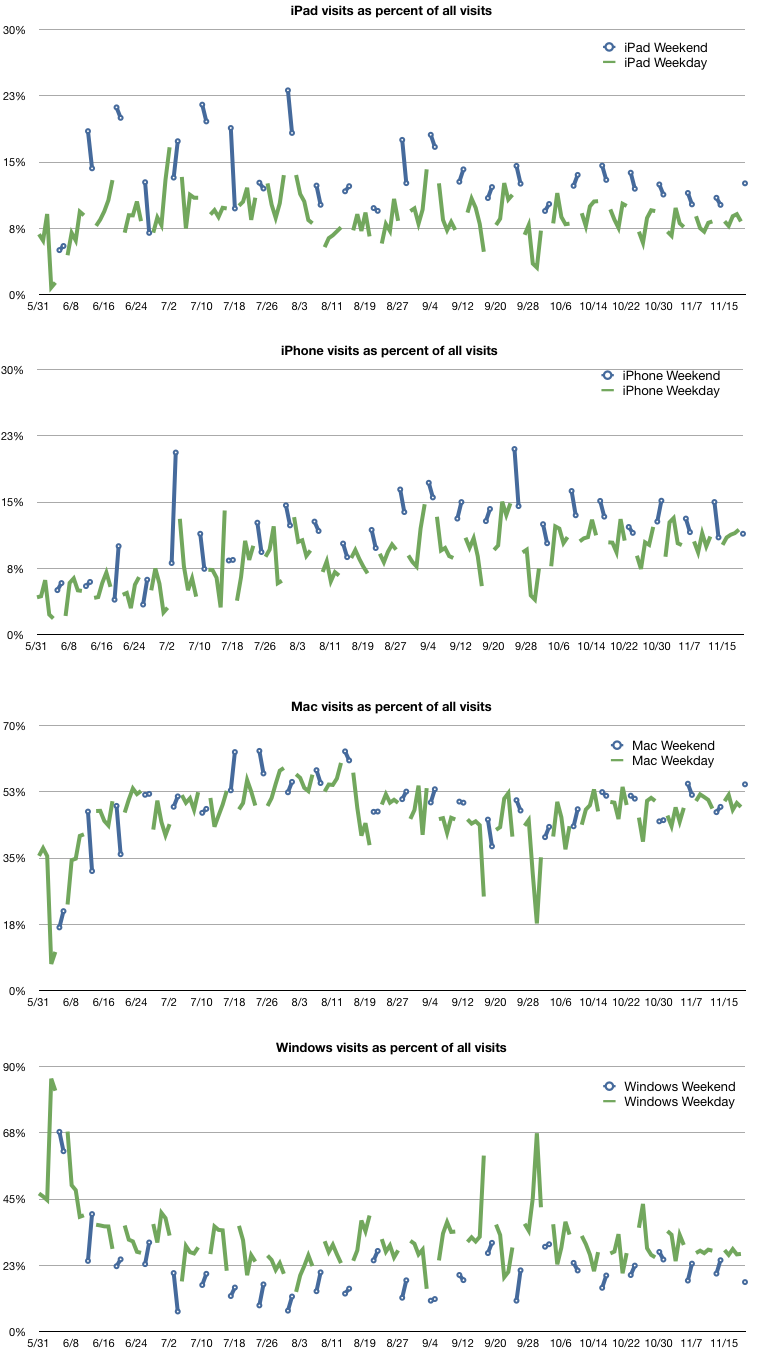
    The following charts show the percent of each platform's use with weekends separated from weekdays.

    The larger the delta the more likely the more the bias one way or the other. To that end I measured the average percent of visits from iPad (as a total of all visits) for weekends and weekdays and measured the delta between the two. On the weekend the iPad was accounting for 13.3% of visits. On weekdays it was 8.8%. A difference of about 4.5% in favor of weekend use.

    To calibrate that figure I did the same for iPhone, Mac and Windows use.

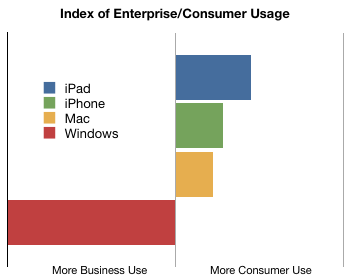
    The following chart shows this ad-hoc index of "enterprise use".

    Essentially the data is inline with assumptions. The iPad is the most likely to be hired by consumers. The iPhone is more than the Mac and they're all far more likely to be consumerized than Windows.

    The average consumption of Asymco.com through Windows was 32% of during weekdays but only 22% during weekends.

    In order to make this measure more meaningful, the evolution over time of these figures should be tracked. If the Blue bar above moves more toward the center then the chances are that iPad will be more adapted by business users, or at least more in use at work.

    Does this seem like a valid method for measuring relative enterprise use?

  8. The integrated iPad news daily: Read all about it!

    Research · 28 comments

    When I wrote my opinion on the future of publishing (Citizen Publisher), I focused my lens on books and magazines. Published works that have relatively low time-sensitivity and hence relatively long shelf life are quite different from newspapers which package material with very brief temporal relevance.

    The print-based news industry has suffered much more than print-based books and magazines. The primary cause is that "print" plays a far larger role in newsprint-based newspapers than in books.

    To give you an idea of how important the printing plant is, consider that a huge proportion of a newspaper's assets are tied up in its printing plant. That plant is so large and so demanding that it ends up causing the whole business to revolve around it: Print runs are done at night to make sure the product is delivered in the morning. That puts a hard deadline on the writers to submit stories before the product is "frozen" into a final edition. Writers and editors and advertisers need to march in lock-step to the cycle time of a big manufacturing operation.

    There are 19 presses and 17 printing plants that print the two million copies of the U.S. edition of The Wall Street Journal. To make changes to the plant require large amounts of capital investment and that capital's depreciation is an integral part of the financial balance of the company. So much so that one wit remarked that a newspaper is nothing more than an instrument that permits the depreciation of a printing plant.

    Costs of manufacturing have been slightly offset by better technology and distributed printing but newsprint itself has soared in price so the dependence on physical product has made the economics worse over time.

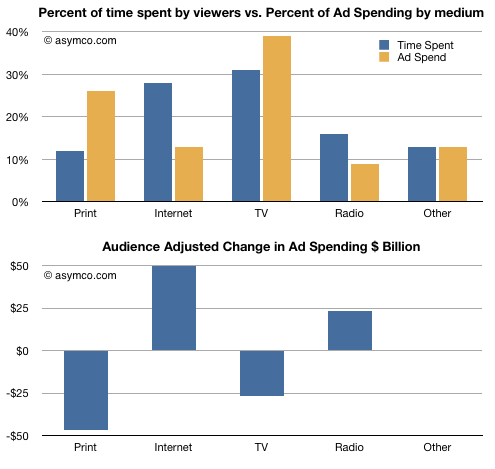
    That's the cost side. But if you keep following the money from the revenue side, you realize that the situation is critical. In the US, a large part of the local paper's revenue base was wiped out by Craig's list. Classifieds are a fading memory. With respect to regular ads, the story is almost as bad. 26% of ad spend in 2009 was allocated to print, while only 12% of time spent consuming media was spent on it. In contrast, Internet use is at 28% of time where only 13% of ad dollars are allocated.

    Source: Morgan Stanley Internet Trends Presentation.pdf

    It's inevitable that advertisers will shift their budgets to follow where the attention is going. Potentially that's a $50 billion shift into Internet advertising. The number nearly matches the $47 billion loss from print.

    This future is not far off. In fact, it's already happening. in recent years the number of newspapers slated for closure, bankruptcy or severe cutbacks has risen—especially in the United States, where the industry has shed a fifth of its journalists since 2001.

    Once the printing plant is taken out of the equation, the raison d'être of the package itself ends. For this reason, the newspaper product cannot survive on-line. Reading news is still very popular, but newspapers aren't.

    So will the iPad save this medium?

    As in Citizen Publisher, I argue that for that to happen, the medium needs its Orson Welles. Furthermore, to have him emerge, the business must be architected as an integrated approach to solve a new job to be done.

    The latest story from The Guardian suggests that Rupert Murdoch is working on just such an approach. In another interview Murdoch explained the project in more detail:

    What is the biggest thing on your mind now?

    ...There are so many disruptive technologies coming all the time! [This in almost a whoop of excitement.] Pretty. Damn. Interesting! Just trying to stay ahead of the technology. I'm starting a paper in six weeks. A brand new paper. It will be a bit like the New York Post . But it will be national. Have that sort of humour and attitude like the Post . It will only be seen on tablets. It will only employ journalists - and maybe eight to 10 technicians.

    What sort of circulation will you need?

    At the price we are talking about, that's $1 a week - not a day, a week - we need 800,000. By the end of next year there will be 30 to 40 million iPads. I believe every single person will eventually have one, even children.

    Via: afr.com

    What's more, it's suggested that an unreformed disruptor is mysteriously involved.  One can only speculate, but the hints of autonomy, dedicated (and incentivized) creative professionals involved in a new (not re-purposed) publication with a low-cost structure bodes well.

    The medium may get its Orson Welles after all.

  9. Stats update: Asymco reaches one million pageviews

    Research · 16 comments

    I began writing in February of 2010 but I moved to my own domain in June. More than 95% of my traffic came after June 1st (during which time 284 articles were written.)

    Since then 270,036 visitors came to visit 592,351 times and saw 1,063,355 pages. 65,331  stopped by more than once. 337,270 of the visits came because someone told them about Asymco. 27,113 visits came because a search engine sent them. 1,548 of those who came had something to say and they said 5,273 things. Over 2,500 asked to keep in touch.

    Here is the less lyrical breakdown of that traffic as reported by Google Analytics:

    1,063,355 Pageviews

    270,036 Unique Visitors

    • 269,167 New Visitors
    • 65,331 Returning Visitor

    592,351 visits

    • 337,270 from referring Sites (56.94%)
    • 227,277 direct traffic (38.37%)
    • 27,113 from search Engines (4.58%)

    Views by operating system (top ten of 25):

    1. Macintosh 433,624
    2. Windows 271,938
    3. iPhone 201,940
    4. iPad 102,870
    5. Linux 19,898
    6. iPod 14,033
    7. Android 12,191
    8. (not set) 3,954
    9. SymbianOS 1,399
    10. BlackBerry 1,196

    5,273 comments from 1,548 readers

    1042 Twitter followers

    248 Facebook "Like"

    Approximately 1000 active RSS feeds

  10. Did Google Arm Its Own Enemies With Android?

    Research · 42 comments

    James Allworth, a Fellow at the Forum for Growth and Innovation at Harvard Business School writes:

    Baidu,... has taken an even bolder approach. It's reportedly in negotiations with a number of smartphone manufacturers to remove all references to Google, and replace them with Baidu.

    ... Microsoft recently negotiated with Verizon that some of the Android phones that ship to Verizon customers will have Microsoft's Bing, not Google, as the default search engine. And the manufacturers are getting in on the act too: Motorola recently released a new phone, the Citrus, based on Android, but shipping with Bing.

    Yes, it's Google's operating system. In both these instances, it counts as a "win" in the handset volume war against Apple, Microsoft, Nokia and RIM. But Google will not make a cent on this handset, despite having enabled its creation with Android. All the search revenue will flow to Microsoft.

    via Did Google Arm Its Own Enemies With Android? - James Allworth - The Conversation - Harvard Business Review.

    Readers of this blog might find these arguments familiar.

    Since February this year, I wrote four articles under the headline "Google vs. Android" documenting these contradictions in Google's strategy. There have been numerous other opinion pieces that described how Google's approach was not consistent with an innovation-based disruption.

    I've also argued that there is strategic incoherence in building systems software and hardware while selling web services.

    Android is powerful, but as Google is finding out, power can be very dangerous without control.

  11. Why the Mac keeps growing

    Research · 63 comments

    When the iPhone vs. Android rhetorical war heats up, both sides bring up the history of Macs vs. Windows PCs. The commonly held thesis is that Windows triumphed as the PC was commoditized (and modularized). This triumph was at the expense of the over-serving and over-priced Mac.

    This is a largely accurate view of what happened during the 90s. But the problem with this thesis is that (1) the PC's job has been slowly changing in the last decade (2) the Mac keeps growing faster than the PC and (3) Apple keeps capturing a vast portion of the profits in the PC industry.

    These anomalies or contradictions to the thesis imply that something changed. What changed and can these changes turn the tables on the market and create an opportunity for a new computing disruption?

    The PC of the 90s was hired first by companies as a productivity boosting tool and second by consumers as a way to duplicate their work productivity and communications in their personal lives.

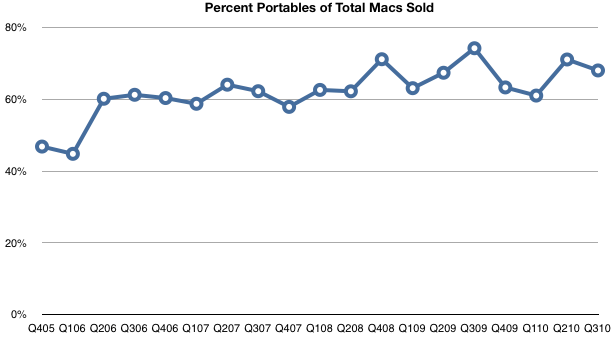
    However something changed with PCs when the laptop became "good enough". With portable computing, the job the PC was hired to do evolved. It was more important that the product be well designed (for aesthetic value, usability and reliability) than just fast and spacious. The microprocessors were plenty fast but what mattered more was low power consumption, a low profile and tighter integration with software.

    The product was also purchased in a different way. A desktop could be purchased on specs alone, sight unseen, from a catalog. But a laptop had to be touched, hefted and the screen had to be observed and the whole design contemplated before a purchase decision was made. The product had an integrated keyboard, display, touchpad and storage. It was not easily serviced by end users. It was, in a word, re-integrated.

    You can see how portability changed the job and therefore everything else as well. Consumer tastes became important, retail distribution became necessary and R&D resources had to be applied to solve what was no longer good enough: the whole package.

    Vendors which did not prioritize design, retail and R&D were left flat-footed.

    At the same time, systems software became more commoditized and productivity software became portable. The old measures of performance were being over-shot while the new measures of performance were under-served.

    While this shift was underway on the hardware side, Microsoft continued to improve their product to serve more demanding business productivity jobs. Their software was not getting optimized for this new portable consumer job. They left the new market open to disruption.

    In stepped the MacBook with good enough (and improving) office productivity. With excellent appeal along the dimensions of performance consumers demand most of all. It was priced higher than other laptops but the price points were affordable and, inflation-adjusted, lower than they'd ever been. It should not be a surprise that Apple was one of the first vendors to see its portables line become bigger than its desktop lines. The market evolved to the point where what Apple had was what the buyers needed.

    The shift to portability is a compelling story for Apple as disruptor in the PC market. It may not result in a complete reversal of the PC hegemony but it allows Apple to grow a product line at triple the growth rate of the market. A market that was considered completely dominated by entrenched incumbents with an unbreakable profit formula.

    But with the iPad Apple is clearly also aiming at disrupting the Mac (and, transitively, the PC as a whole.) The iPad can be seen as an evolution toward seamless portability; the mobile computing paradigm shift.