The US is not the market where penetration is highest. However, it is the largest market where we have reliable penetration data (from at least two sources) and the one where penetration is near the top of the range.
The graph showing the US ranked against others as of a year ago is here. The US was cited at 56.4% at the time. I keep track of comScore's data and it showed 58.2% at the end of March and 55.3% at the end of January, making the figure very believable.
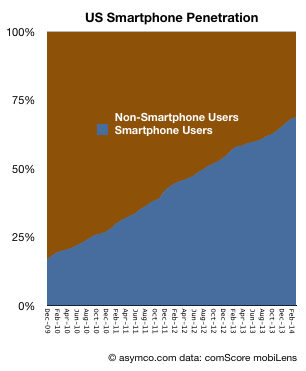
The most recent data from comScore shows penetration at 68.8%. In order to understand what the limits of that growth could be it's important to see the longer-term pattern. It would show whether there is a clear point of inflection and thus a predictable "saturation" around an asymptotic value.
The following graph shows the percentage of smartphone users/non-users since late 2009.
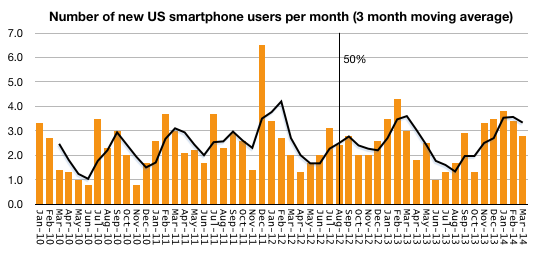
The following graph shows the rate at which users are being added to the smartphone ranks (measured as new users per month.)
To summarize, the conversion of users from non-smart to smartphone usage is fairly constant. The March '14 period saw 2.8 million new-to-smartphone users. the March '13 period saw 3.0 million, the March '12 period saw 2.0 million and March '11 saw 3.0 million. There is no discernible slowing of adoption.
Note that I added a trailing three period average in new users which fluctuates somewhat predictably due to seasonality. Finally, note that the figure of 50% penetration was reached almost two years ago and no noticeable change of adoption has happened since. Cellular phone ownership in the US is still rising (though very slowly) and it now about 90%.
The only conclusion is that even at the current 68.8% penetration, we are not anywhere near "saturation" of smartphone users in the US, and the US is a leader among "developed markets" so there is little to suggest that saturation has happened anywhere with significant populations.
In the postmodern computing world that we live in, the measure of success isn't revenue or profit or units sold but the number of users that an ecosystem can attract. Therefore the monthly active user (MAU) unit of performance seems to be in vogue right now. E.g.:
Facebook claims Messenger has more than 200 million MAUs
WhatsApp has 500 million MAUs, 48 million of whom are in India
Line last month announced that it had 400 million users (active or not)
WeChat claimed 355 million MAUs
Viber claims 105 million MAUs
Startups are aggregating these millions of MAUs in order to obtain valuations for raising capital ((It's been said that it's difficult to get funded with only 10 million MAUs)) and the faster the growth in MAUs the more "successful" the company is considered.
When companies are acquired it's common to take the transaction value and divide it by MAUs to get an idea of "what an user is worth". This is because there are no revenues to measure and MAUs are taken as a proxy. However, the process by which a MAU becomes a dollar of profit is, to put it kindly, circuitous.
For most (all?) it's not yet clear how it happens especially since not all MAUs are created equal and MAU loyalties can change rapidly and if we added all the projected revenues each MAU will contribute to each app on her device we might reach some absurdity. In actuality, today, for the companies listed above, there are no revenues at all directly from their services.
In violation of this convention, there are some companies which manage to obtain revenues from their users. Two such are Apple and Amazon. In the last quarter Apple reported having 800 million iTunes accounts. ((adding, for some unknown reason, that most of them have credit cards.)) These aren't MAUs since the activity level is not noted, but we do know how much is spent on iTunes and services. In addition, Amazon cites 244 million active customer accounts representing accounts which generated purchases within the last 12 months.
This allows us to compare Apple and Amazon in terms of accounts, revenue per account, and, via some analysis, even profitability per account.
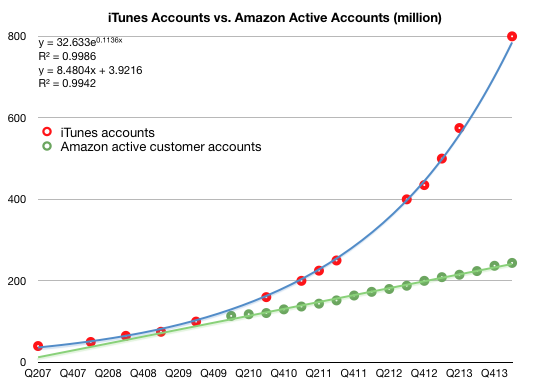
The following graphs tell this story. First, the total number of accounts:
Note that I added trend lines to both graphs and their formulas.
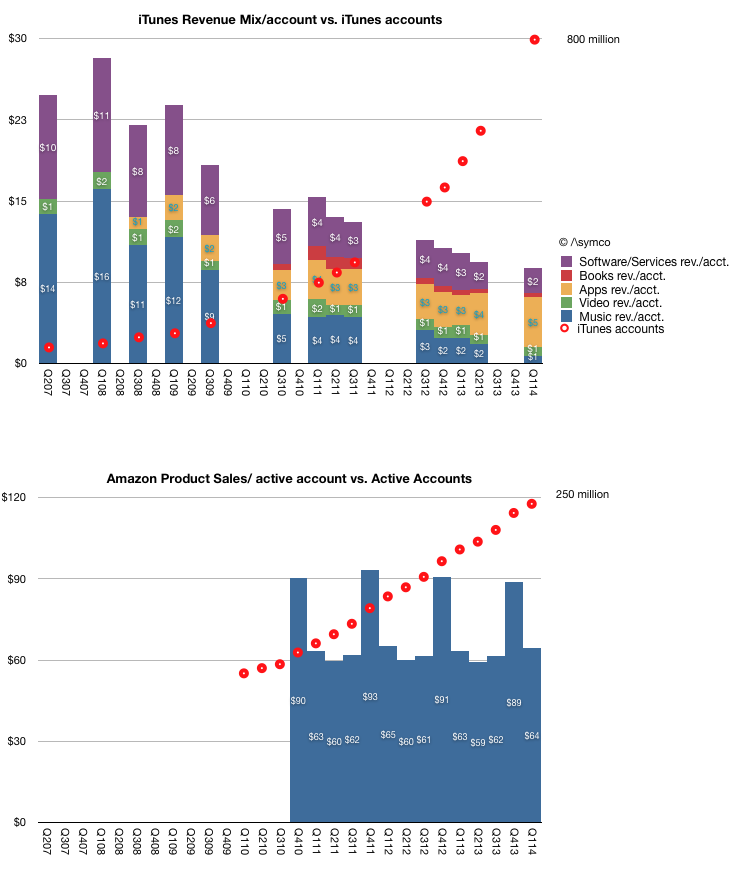
The following are the revenue per account for iTunes (further broken into estimated iTunes segment revenues per account.) and for Amazon. Note that the vertical scales are different.
This view shows just how different the economic value of users can be. In the case of Apple, it's growing its user base at (literally) exponential rates. The revenues per user does, understandably, decline. This is because new/later users don't spend as much as early users. There might be some stability toward the later stages of adoption in revenue per user. The other point about iTunes data is how the mix of revenues has shifted from music to Apps and Services pointing out how users can be migrated across revenue sources over time.
In the case of Amazon it's growing its user base at a linear rate (note equation). The revenue per account remains very steady however.
Broadly speaking, it would seem logical that the speed of user growth has an effect on the quality of those users. This relationship should guide further thinking about the quality of hundreds of millions of users acquired within a few months.
Apple's user growth is a function of expanding its device portfolio and distribution. Apple has shown that there are limits this type of growth. Achieving 830 million or so iOS device sales within 7 years is an amazing feat and one can forgive not having achieved billions more since they managed to obtain significant hardware and service/content revenues from most of them and that those who reached higher figures more quickly didn't manage the same revenue per user.
Amazon's user growth is a function of expanding its logistics and merchandise mix. This is also not easy to do globally. Arguably, Amazon cannot scale in the exponential rates seen by Apple or the other MAU aggregators because it has to depend on trucks and roads and regulators to complete most of its sales.
I suppose, in conclusion, that there is no "right" or "wrong" business model for a user base. Both Apple and Amazon are doing well in building their customer bases and creating loyalties which will serve them well in the future. However whereas there is no right or wrong revenue structure per user, it seems to me that there ought to be some such structure. In most cases this remains a matter of faith rather than reason.
“Innovation” is one of those words that, through casual overuse, has come to signify a wide array of distinct concepts – in some sense, the word is literally losing definition, like an out-of-focus photograph that manages to become blurrier every time you look at it.
These days, anytime anyone does something vaguely new, or a new feature gets added to some gadget or other, the innovation word gets flung about. Indeed, the word is used with the same reckless abandon as those other favourites of jargon-loving MBA types, “solutions” and “disruption”, rendering it increasingly meaningless.
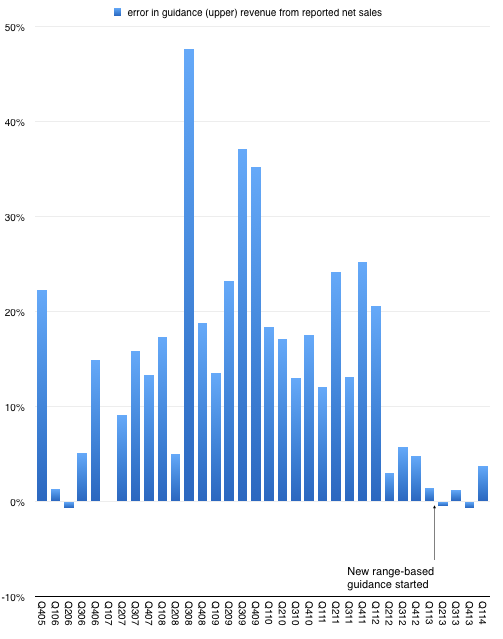
After n quarters of predictability, Apple surprised with sales performance that was 3.74% above the top of their guidance. This may not seem significant but since instituting a new range-bound guidance method in Q1 of last year the company reported revenue within about 1% of the top of the range.
This is in stark contrast to the wide variance in prior years. The following graph shows the "error" in guidance as the percent difference between reported sales and guidance ((Upper end of range in quarters where a range was given.)).
So prior to last quarter we were lulled into thinking that guidance was very nearly perfectly predicting the company. As I tweeted, it took the "sport" out of trying to do any forecasting. All an analyst had to do is tweak the main product growth figures to hit the sales target and then subtract the (generously provided) operating expenses and (also provided) tax rate to get the earnings. Only unknown to getting to an estimate of EPS was how many shares would still be outstanding. ((The company itself would not know shares outstanding as their buying was opportunistic during the quarter.))
Knowing Apple also means that average selling prices are also very rigidly set in stone so the degrees of freedom in analysis were becoming highly constrained.
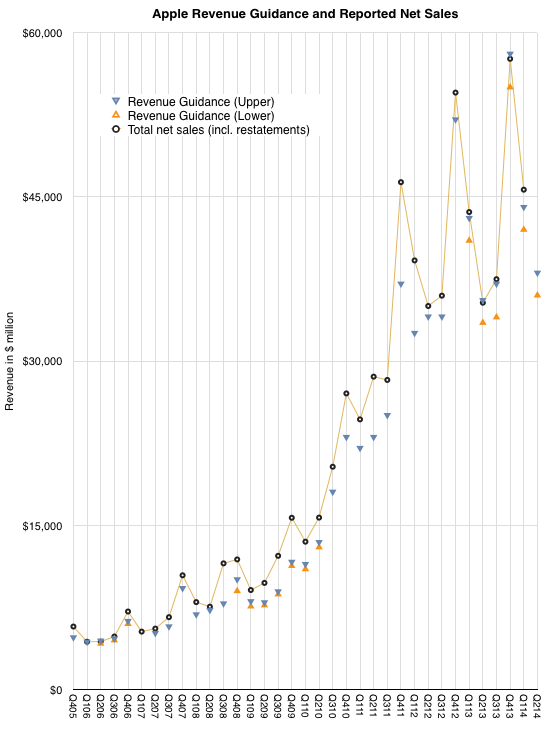
But just when you think you spotted a pattern, it changes. The company surprised with performance outside the band. The following graph shows the estimate ranges it has given and the actual revenues delivered. ((Next quarter is also pencilled in.))
So what happened?
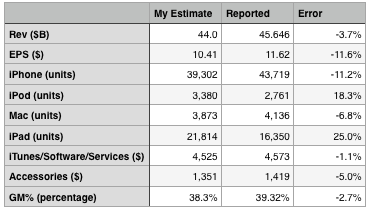
The answer seems to be better iPhone performance. The following table shows my expectations, which were tuned to return revenues exactly at the top of the guidance range.
On product shipments/sales I underestimated the iPhone and Mac and overestimated the iPad and iPod. I estimated iTunes accurately and underestimated accessories by 5%. I also generally got the blend of margins fairly close, being 1 point too low on gross margin.
The bottom line was that the Revenue and Earnings surprise could be accounted for through a significant outperformance on iPhone which offset a less significant underperformance on the iPad.
The iPhone grew sales by 14% which more than offset a drop of 13% in iPad sales and was enough to allow net sales to grow by 5%. Since the company guided nearly flat growth, that 5% was a big surprise.
Now one could ask whether 14% growth in the iPhone revenues is a meaningful change in the long-term evolution of the category. This is a difficult question. The way the iPhone is positioned makes it a great success in the premium segment of the market but it does not place it in competition with the perhaps 80% of the market which seems to be defined by a lower price point.
However let's not forget that pricing is correlative to the market but it may not be causal. Purchase decisions are complex and price is one aspect of that decision. But there are many others. Availability, channels, service, brand all play parts. The error of many analysts is to conclude that price and price alone is causal to behavior. That may be so with commodities, but let us not forget that these products and their uses are newly created and how value is perceived has been changing rapidly. Buyers follow a learning curve in terms of discovering the uses and value of products. These learning curves can be modeled and usually show several years (sometimes decades) for most populations between early and late adoption.
We don't know where the iPhone is on the learning curve for any particular region and that means we can still be surprised by how it grows.
Illiteracy is the inability to read and write. Though the percent of sufferers has halved in the last 35 years, currently 15% of the world has this affliction. Innumeracy is the inability to apply simple numerical concepts. The rate of innumeracy is unknown but chances are that it affects over 50% of us. This tragedy impedes our ability to have a discourse on matters related to quantitative judgement while policy decisions increasingly depend on this judgement.
But there is another form of ignorance which seems to be universal: the inability to understand the concept and role of innovation. The way this is exhibited is in the misuse of the term and the inability to discern the difference between novelty, creation, invention and innovation. The result is a failure to understand the causes of success and failure in business and hence the conditions that lead to economic growth.
My contribution to solving this problem is to coin a word: I define innoveracy as the inability to understand creativity and the role it plays in society. Hopefully identifying individual innoveracy will draw attention to the problem enough to help solve it.
"Lastly, nationally circulating tabloid Ilta-Sanomat gets a look at Nokia’s fabled tablet computer that was developed nine years before the iPad hit the market. According to the paper, Nokia had its own innovative tablet device ready in 2001, but unfortunately it never made it to the shops. A former Nokia expert Esko Yliruusi says that the project was suspended a heartbeat before the tablet hit the market because it was thought that there was insufficient demand for such a device." ((A video showing the device is here, in Finnish.))
To explain what's wrong with this usage we need some definitions.
The definition of innovation is easy to find but it's one thing to read the definition and another to understand its meaning. Rather than defining it again, I propose using a simple taxonomy of related activities that put it in context.
Novelty: Something new
Creation: Something new and valuable
Invention: Something new, having potential value through utility
Innovation: Something new and uniquely useful
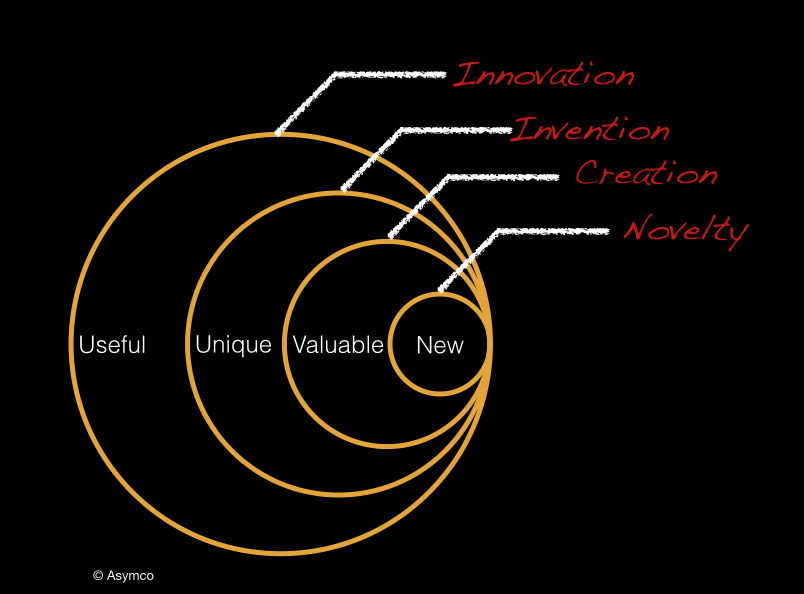
The taxonomy is illustrated with the following diagram. The position of the circles shows the embedding of meaning ((The size of the circles also suggests degree of effort required and potential reward. Note that this is not a Venn diagram.))
To illustrate further, here are some examples of the concepts.
Novelties: The choice of Gold as a color for the iPhone; the naming of a version of Android as "Kit Kat"; coining a new word.
Creations: The fall collection of a fashion designer; a new movie; a blog post.
Inventions: Anything described by a patent; The secret formula for Coca Cola.
Innovations: The iPhone pricing model; Google's revenue model; The Ford production system; Wal-Mart's store design; Amazon's logistics.
The differences are also evident in the mechanisms that exist to protect the works:
Novelties are usually not protectable but since their value is very limited the copying is not seen to cause harm.
Creations are protected by copyright or trademark but are not patentable since they lack utility.
Inventions can be protected for a limited time through patents but can also be protected indefinitely by being kept secret. Their uniqueness may also be the means by which they can be kept a secret.
Innovations can be protected through market competition but are not defensible through legal means.
Note that the taxonomy has a hierarchy. Creations are novel, inventions are creations and innovations are usually based on some invention. However inventions are not innovations and neither are creations or novelties. Innovations are therefore the most demanding works because they require all the conditions in the hierarchy. Innovations implicitly require defensibility through a unique "operating model". Put another way, they remain unique because few others can copy them.
To be innovative is very difficult, but because of the difficulty, being innovative is usually well rewarded. Indeed, it might be easier to identify innovations simply by their rewards. It's almost a certainty that any great business is predicated on an innovation and that the lack of a reward in business means that some aspect of the conditions of innovation were not met.
The causal, if-and-only-if connection with reward is what should be the innovation litmus test. If something fails to change the world (and hence is unrewarded) you can be pretty sure it was not innovative enough.
Which brings us to the quote above. The fact that the Nokia tablet of 2001 not only did not succeed in the market but was not even released implies that it could not have been innovative. The product was only at the stage of perhaps being an invention (if it can be shown to be unique) or merely a creation (if it isn't.) Furthermore, if the product is so poorly designed that it is literally unusable then it is just a novelty. A design, sketch or verbal description might be novel but it does not qualify as an innovation or an invention or even a creation. How far the depiction went toward making a dent in the universe defines its innovativeness.
Why does this matter?
Understanding that innovation requires passing a market test and that passing that test is immensely rewarding both for the creator and for society at large means that we can focus on how to make it happen. Obsessing over the mere novelties or inventions means we allocate resources which markets won't reward. Misusing the term and confusing it with activities that don't create value takes our eye off the causes and moves us away from finding ways of repeatably succeeding.
Recognizing that innoveracy is a problem allows us to address it. Addressing it would mean we could speak a language of value creation that everyone understands.
In this inaugural episode we open with the biggest question facing the biggest technological innovation of our time: the limit to growth of the Internet. The Internet is the backbone of our post-industrial society as much as the railroad was the backbone of the industrial revolution. Even more so, the diffusion of internet consumption is the fundamental engine of growth at a time when industrial economies are all mired in syndromes of underinvestment and misallocation of resources.
And so it matters greatly if and when the Internet will "inflect" in growth, going from acceleration to deceleration. Mobile computing sustained this acceleration, bringing computing and connectivity to the billions for whom the PC would always be beyond reach. But even with the expansion of device-based usage limits are in sight.
The implications could be profound. Frothy valuations and optimism could evaporate. Venture Capital could find few exits and the "second Internet Bubble" could burst. On the other hand, maybe the data shows that opportunity is largely unmet. Quantity of users is but one proxy. How can growth and business model innovation continue?
Horace and Moisés talk about Amazons acquisition of ComiXology, digging into the very "local" nature of book publishing in general and the extreme regional differences in content popularity and delivery.
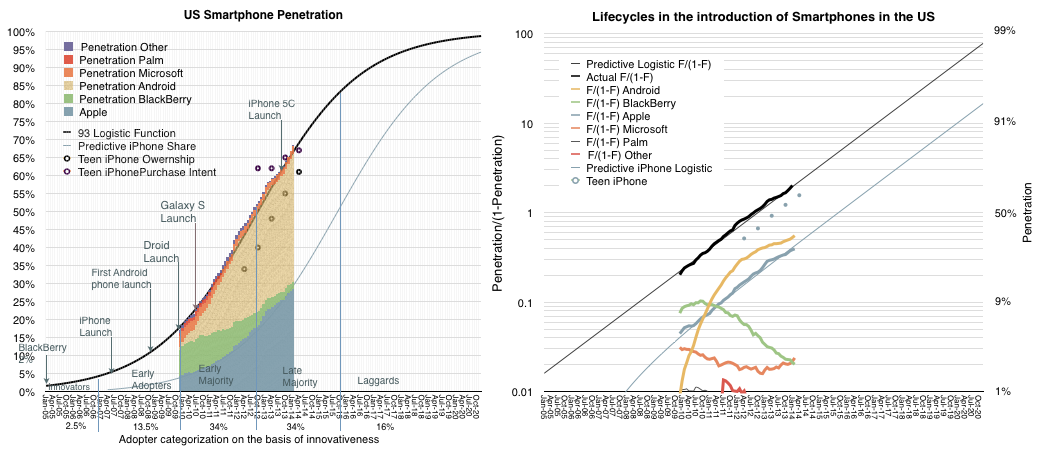
Philip Elmer-DeWitt cited Piper Jaffray's latest Teen Survey on Device Ownership where ~7,500 teens in the US are asked about their device ownership. This type of data is similar to the method comScore uses to measure penetration smartphones in the US making the two data sets comparable.
The combined data is shown the following graphs.
One graph is the penetration data and the other is the ratio of penetration to unpenetrated on a log scale. The PJC Teen Survey data is shown as dots on both graphs. In the spring of 2012 the difference between teen iPhone ownership and overall population iPhone ownership was 20 percentage points. In the fall 2012 it was 22 points. In spring 2013 it was 25 points. The spread increased to 30 points in the fall of 2013.
This implies that the latest sample (April 2014) should have at least a 31 point lead on what comScore will report in another two months. ((comScore reports data during the first week of a month for a period ending one month earlier. So the April release covers a sampling period ending February)) In other words current iPhone penetration in the US is probably 30%. This assumes of course that the relationship between teens and overall population has not changed. But there is consistency in the pattern of iPhone growth for over 50 months.
In addition, the purchase intent data is showing that there is growing interest and that interest reflects demand which has been largely met by a purchase decision.
Teens are leading adoption in this particular sector because the device is very well suited to the jobs that they need to do, mainly social interaction. It's no coincidence that the audiences for the fastest-rising services (SnapChat, WhatsApp, Vine, YouTube, Instagram) consist mainly of teens. They also lead adoption in FaceBook, iTunes, MySpace, etc. In that regard teens are an early indicator of mainstream behavior.
Teens taught the world new habits throughout the 20th century ((An entertaining review of the contribution (and invention) of teenagers in the 20th century can be enjoyed in James May's 20th Century Episode 5)) and they certainly seem to be teaching us in the present.
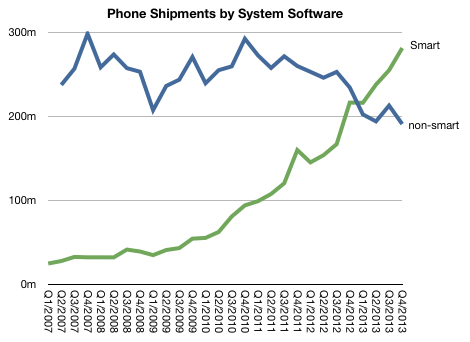
The smartphone market continues to grow. 2013 saw total shipment of around one billion units (up from 683 million in 2012). In contrast, non-smartphone shipments continue to decline, with shipments around 800 million (down from 987 million in 2012).
This pattern is shown below:
Note that prior to 2012 the non-smart market seemed to be holding steady in spite of the growth in smartphones. The notion that smartphones would become universal was widely dismissed. I certainly heard many objections to my 2010 hypothesis that not only would smartphones become ubiquitous but that it would become increasingly difficult to find anything else to buy. (This in spite of the clearly evident demand for "low-end" non-smart devices.) ((The analogy I used was that of the black-and-white TV market as color TV became increasingly popular. There probably was a market for monochrome screens for a long time after they were discontinued but that is beside the point: the old technology becomes increasingly scarce because of economies of scale))
I also suggested that the notion of distinguishing phones with the"smart" tag would become irrelevant and that we would just call these devices "phones". That is coming to pass, at least among the conversations I'm privy to.
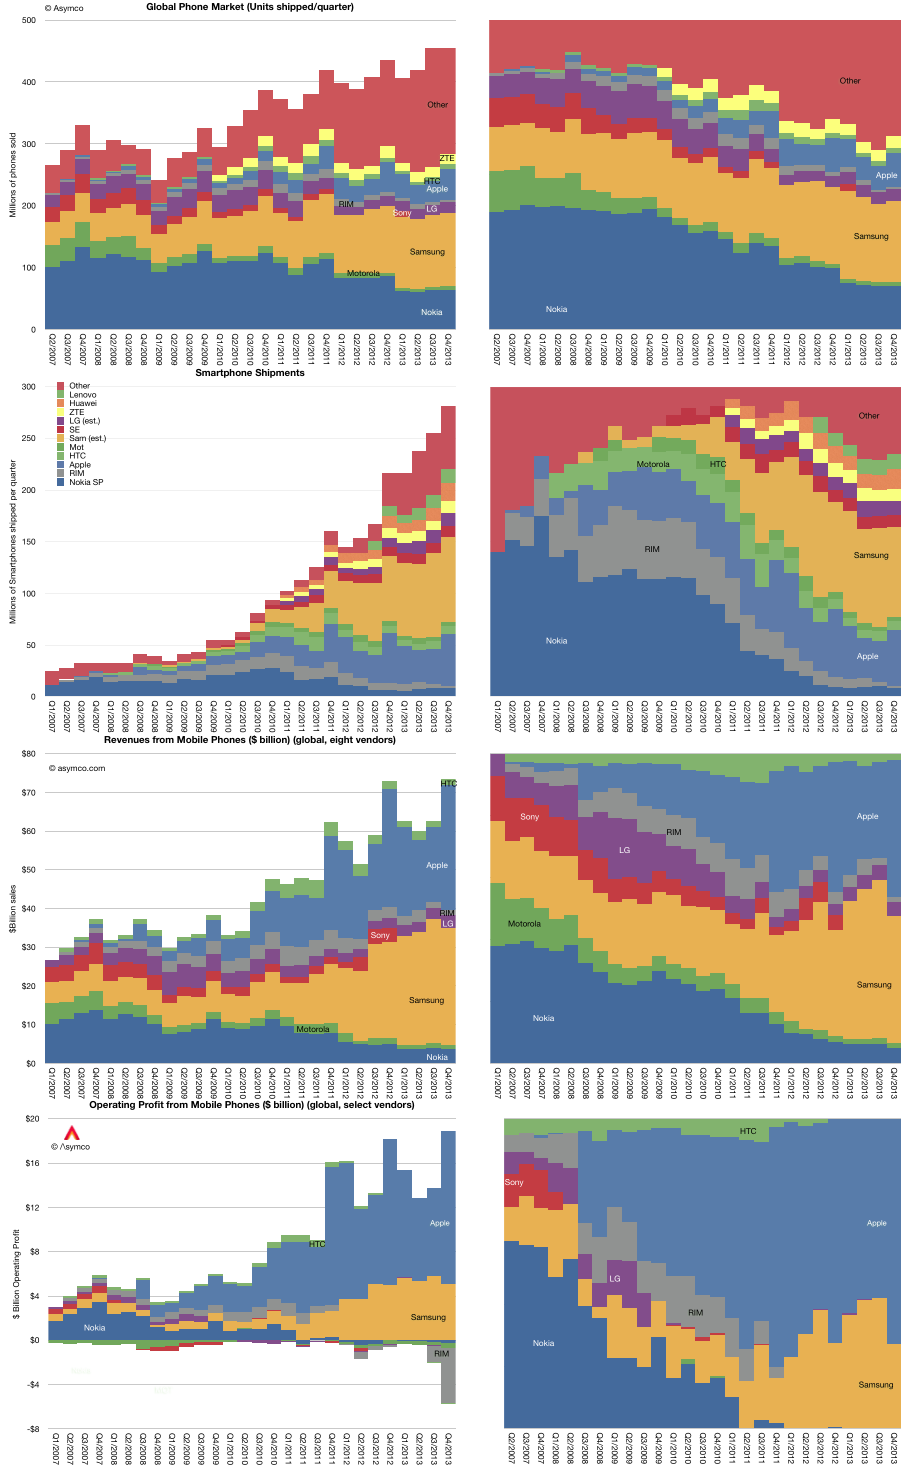
So if the conversation is about "phones" and the expectation that all phones will be smart, what can we observe about the market? The following graphs provide the picture of shipments, revenues and operating margin in absolute and relative measure for the most significant brands.
This arrangement shows the disruptive effect of adding "smart" to phones. In only a few short years ((Six shown but the effect was pronounced already in four)) profits have dramatically shifted in the industry.
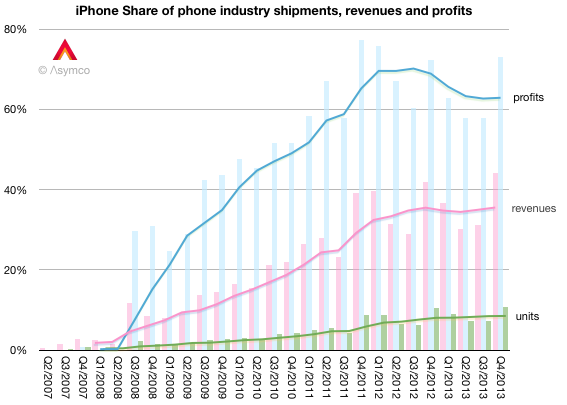
Indeed, since the launch of the iPhone ((Which I consider to be the start of the current epoch of the industry)) the net profits earned by the collection of protagonists shown was $215 billion (($234 billion of positive operating earnings, offset by $19 billion of operating losses)). 60% has been earned by Apple, a newcomer to the market. That figure is also consistent on an ongoing basis, having reached 60% as early as 2011 and remained in a band around that figure since.
The fact that this happened without corresponding dominance in units shipped shows evidence of something startling: Consistent value creation.
To earn profit is hard, to do so in an outsized way is very hard and to do so with consistency shows a defensibility of market access that is rarest of all. The only cases where this typical is in a monopoly or protected market situation (aka cronyism.) Apple's lack of market monopoly coupled with a (near-) monopoly in profits can only be explained by disproportionate value creation.
The mystery then is how is it possible to build a monopoly in value creation.
We explore the strategic and tactical considerations behind BMW’s i sub-brand. Why did BMW attach a new BMW sub-brand to a new powertrain rather than using another brand, like Mini? The answer helps explain how innovations and brands inter-relate and how incumbents can attempt to absorb what is potentially non-sustaining.
We consider the pros and cons of innovation within an operating business – “intrepreneurship” – compared with creating an autonomous enterprise for the “new new thing”. I contrast BMW i with General Motors’ failed Saturn experiment.
We consider the burden that regulation, girth, cycle times, legacy practices, financialization and strategy taxes place on incumbents.
Finally, we look at what it takes to cross over the line which separates the device-based nice-to-have infotainment options from the must-have driver and ownership assistants that will inevitably find home in these devices.