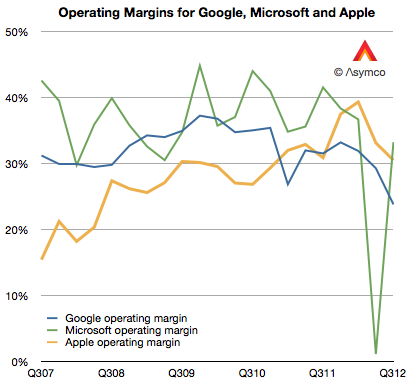
Google's operating margins fell to 23.7% last quarter. This level is the lowest I'm aware of. From 2007 to late 2009 margin went from about 31% to about 37%. Then from early 2010 until present they fell. The history is shown the the following graph.
[I included Microsoft and Apple operating margins for comparison.]
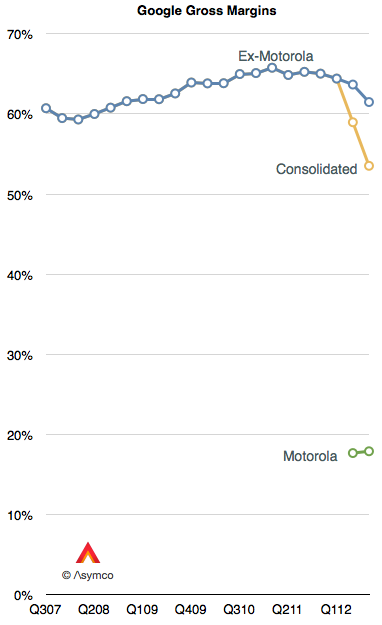
Some of the recent decline is due to the inclusion of Motorola into consolidated earnings. Motorola gross margins were therefore 18%. Excluding Motorola, Google gross margins (Revenues-Cost of Revenues) were 61.5% of revenues. However, even excluding Motorola, Google's core margins dropped.
One reason for the decline in core margins is the reduction in cost per click (-16% for search and -18% for network sites.) This is what Google pays to partners for access to traffic. The trend is not new. It was first discussed in January.
The bottom line is that an individual click is not as valuable as it used to be. Would a larger volume of mobile usage be a reason? Google won't say.
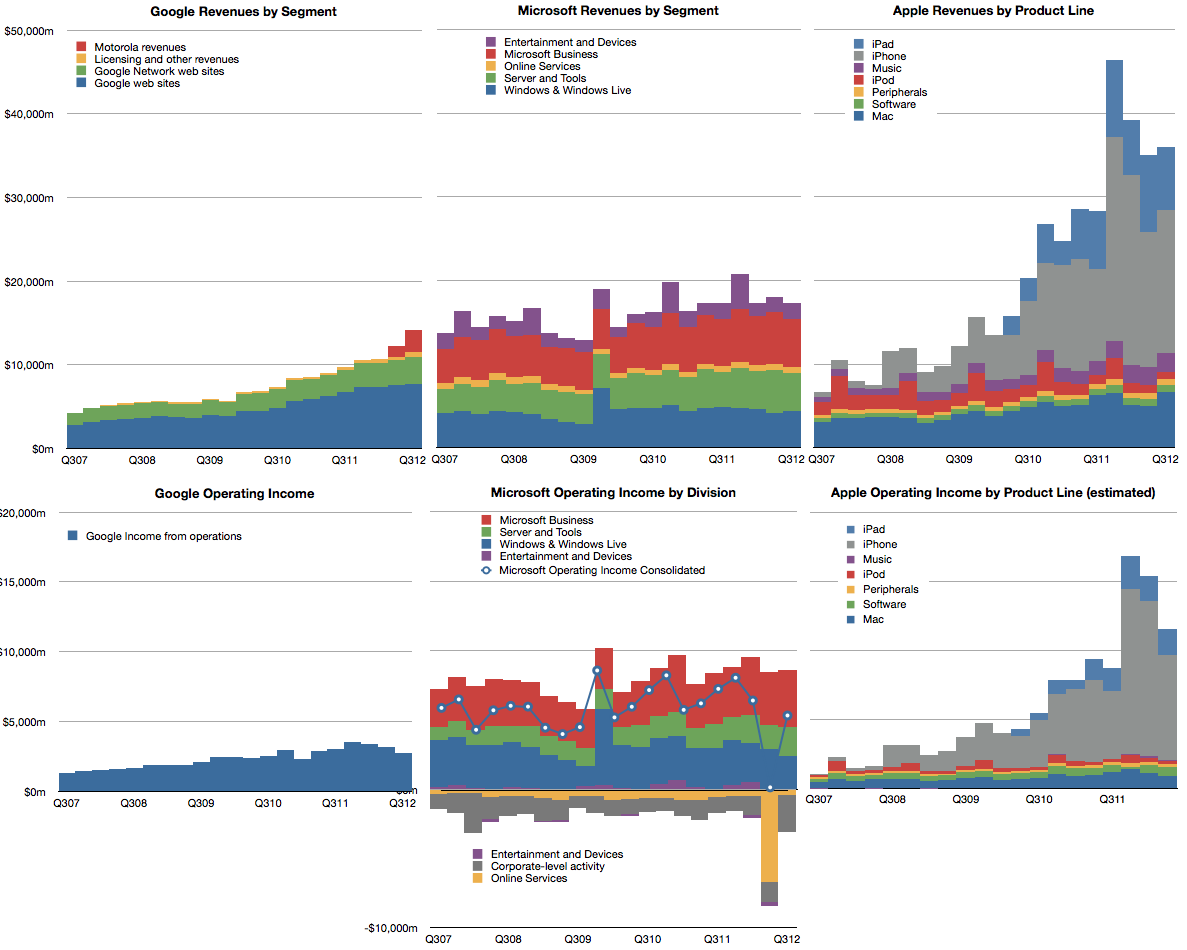
The overall result in the bottom line is shown below. Microsoft and Apple are again put forward for comparison.
Horace and Moisés talk about the consequences of Samsung's absorption of all Android profits, the limits of iPhone's addressable market, Apple bear markets and, like an object in orbit, how Apple seems to always be falling but never hits Earth. Finally, Horace introduces Asymconf California.
Asymconf California is the second[1] in the series and will expand in scope and intensity relative to the first event in Amsterdam. Attendees will be treated to an engaging, participatory experience. Using the case method to teach (and learn), we will look at the state, history and future of innovation as seen from a Californian perspective.
There will be four themes:
Being Back. How California came to disrupt and be disrupted.
It's always sunny. Californians invented the concept of lifestyle. Did they also invent the concept of business style?
Going West. The role of frontiers (geographic, conceptual and societal) in the creation of wealth. Escaping the zero-sum trap.
North vs. South (California.) A modern civil war.
Distinguished guests will be invited to act as presenters and panel members.
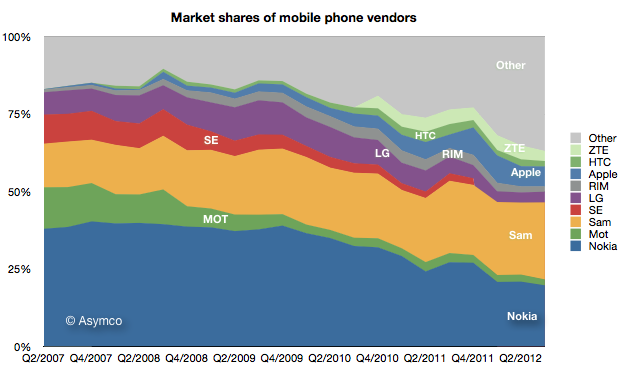
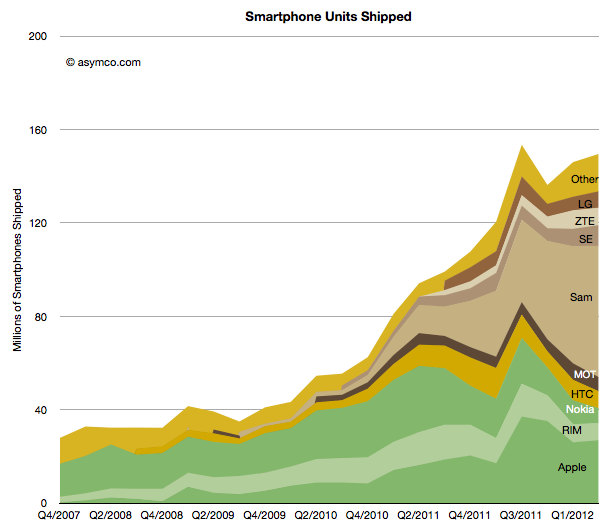
Samsung's recent success in mobile phones has been spectacular. It overtook Nokia for the top spot in overall unit sales.
It went from having almost no smartphone sales to selling over 50 million units per quarter in a matter of two years.
It now accounts for nearly 40% of all industry profits.
A key decision which made this success possible was to shift its portfolio to smartphones and to offer a large variety of such phones.
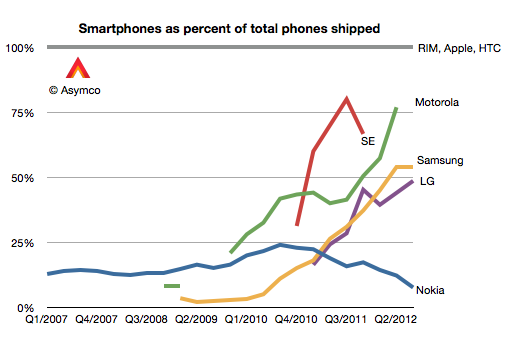
In Q1 2010 only 3% of the phones Samsung sold were smartphones. In the latest quarter the ratio was 54%.
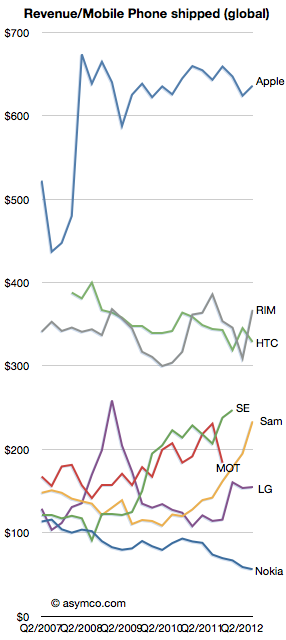
As a result the average selling price more than doubled, from $115 to $234.
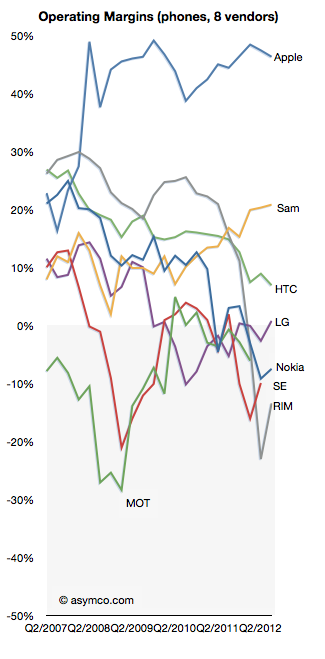
Profit margins also soared in proportion: from 12% to 21%.
All this plus an overall growth in volumes from 64 million to over 100 million per quarter has meant that the company is raking in enormous profits. Not only did it overtake Nokia, the market share leader for 14 years, but is making more profits than Nokia ever did.
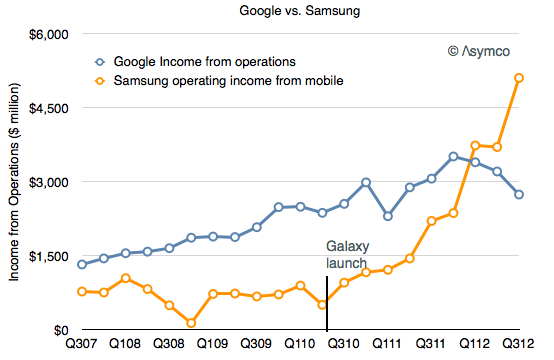
So much profit in fact that it has overtaken Google's decisively.
The reason I point this out is that Samsung's success is dependent on having ridden on the back of Android. Samsung's ascent can be precisely timed to their adoption of Android. The groundbreaking Samsung Galaxy launch was the Galaxy S which shipped in June 2010.
Meanwhile, indications are that "mobile" is causing a contraction in Google's margins.
If nothing else, Android has created a very interesting industry. There are many questions of course: Is Samsung's trajectory sustainable? Why aren't there other vendors successful with Android? Why isn't Google successful with Android? Why isn't Google's Motorola successful with Android? What would happen if Samsung soaks up so much profit from mobile that it's in a position to acquire Google and control the trajectory of their enabling platform?
Apple's renaissance began with the iPod. This was not evident right away however. The product was unveiled on October 23, 2001 at a time when Apple's share price had just fallen 70% from year-earlier levels. It was perhaps a good point from which one could expect a recovery to begin.
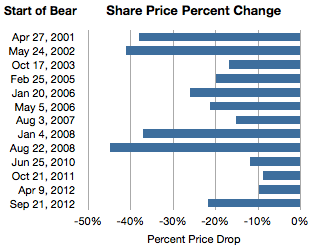
It was not to be. One year after the iPod's launch the stock price had fallen another 20%. Indeed during 2001 the company was in the throes of a "bear market" in its shares. If we measure a time of persistent share price reduction as a bear market, then the one in 2001 was significant. For 154 days, between April 27 and September 28, 2001 the shares fell 38%. This represents the first bar in the following graph showing all the Apple bear markets since then.
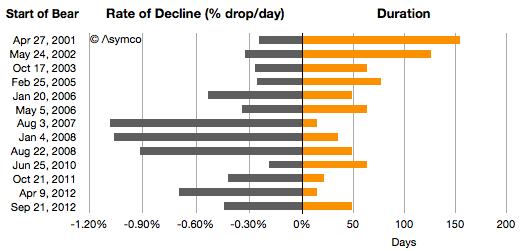
I also illustrated these bear markets in terms of their duration and the average %drop/day.
Chronicling these periods:
From May 24th 2002 and September 27th, 2002 the stock fell 41%.
2003 was less harsh but on the second anniversary of the iPod, for two months between October 17th 2003 and December 19, 2003 the stock fell another 17%.
By 2004 the iPod looked like a hit. The stock rose consistently during the year. Then, in early in 2005, from February 25th to May 13, the stock fell 20%.
In early 2006, January 20th to March 10th, the stock dropped 26%. The iPod was reaching incredible levels of popularity and the Mac was looking to be returning to prominence with the switch to Intel.
2007 was the year the iPhone launched. Right after the launch for two weeks between August 3rd and August 17th, the stock fell 15%. That's the equivalent of 1% per day for two weeks.
As the iPhone was shown to be a hit (and before the credit crunch), for four weeks during January 2008 the stock fell 37%. Again, equivalent to 1% a day for 35 days.
Then after the iPhone 3G was launched and growth reached triple digits, Apple's shares fell for 50 days. From August 22 to October 10th they fell a total of 45%. Again, the equivalent rate was 1% every day for a month and a half.
In 2009 the stock recovered steadily but in 2010, again around iPhone launch season the stock fell 12% over a two month period.
Then in 2011 October, 9% was wiped out.
Then for two weeks in April 2012 10% disappeared.
Which brings us to September 21 to November 9th, 2012. This latest "bear market" has run up a loss of 21.7%, running for 49 days.
Sounds dramatic. The even more dramatic twist is that in this same time frame the share price increased by 576 points or the equivalent of 6,294%. Nevertheless, there were 13 episodes when the shares dropped violently and sometimes persistently for long periods.
Why does this happen?
It's important to recall that at no point during Apple's ascent was there "consensus" that Apple was being successful and certainly not sustainably so. Analysts gave it at best a growth prospect of 20%, and the risks were always obvious and prominent. The company was always on the edge and everybody from the layperson to the experts could see that everything was wrong with Apple. Apple went from being irrelevant to being too big without passing through being boring.
So there is a simple explanation for occasional panic: Apple is not predictable.
But it also seems too consistent. Is the pattern of share price collapse actually rooted in some fundamentals, transient or otherwise? There is a clear failure in understanding the long term but were these downdrafts justified as the market "foresaw" or "discounted" the near future? Were these more than just crises of confidence? Was there wisdom in the drops because they were followed by earnings drops or slowing growth? In other words, if there was smoke, was there fire? Was the market being efficient?
No.
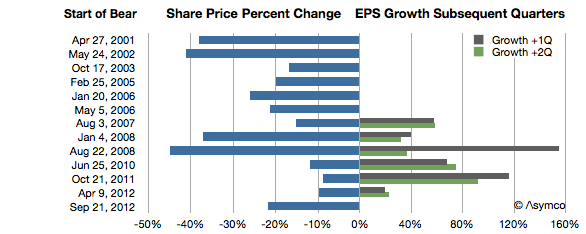
The graph below shows the share price change in the more recent episodes above and the earnings growth during the current and following quarters.
At least since the iPhone launched, every dramatic drop in share price was followed by a surge in earnings growth. One could even say the worse the bear, the better the growth.
Sounds completely counter-intuitive, but there is some perverse logic in this as well. The market reflects crises (as well as over-abundance) of confidence. Unforeseen growth is what creates wealth and the crisis in confidence is a reflection of the improbability of continuing out-performance. When Apple's performance is foreseeable the stock moves slowly upward. When its performance is unforeseeable the stock moves dramatically downward.
A pithy way of putting it is: No news is good news. Good news is bad news.
When a product is understood the stock is mildly desirable. When a new product appears the future is hazy and the stock is undesirable. But that haziness hides potential but up and down. New products is what innovators produce. Bizarre new products is what disruptors produce.
In other words, the paradoxical observation in the chart above of "the more drama in the market, the more success in the marketplace" makes sense when inverted.
For disruptive companies, it should be "the more success in the marketplace, the more drama in the market."
In that sense the current downdraft may be quite auspicious. --- Notes:
Another set of similar observations were made by Eric Jackson in early October in Forbes.
Apple's Retail head was recently replaced. The hire seems to have been a mistake dealt with quite swiftly. It is tempting to think that the firing of a manager is due to a failure in their performance, measurable in quarterly reported metrics. But this is not often the case. It may be true of sales or some operations, but most strategic management decisions take months to make and years to implement before you can have the luxury of measured results. And even then the dependencies of performance are many and outside the control of specific managers.
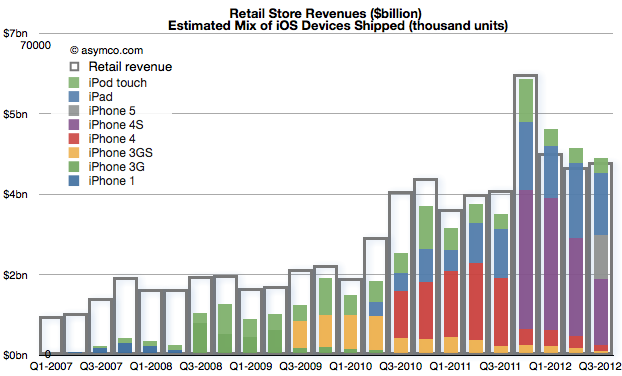
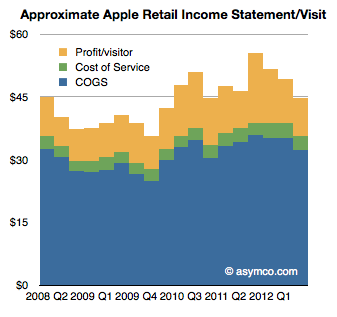
John Browett joined Apple in April and left in October. A mere six months. How did Apple retail perform in those two quarters? Very well actually. Which is to say, as well as it has previously given the overall performance of the company. The correlation can be shown between store revenues and iOS device shipments:
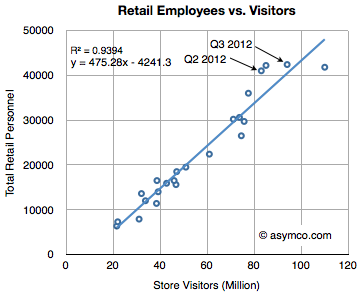
Store visits increased to 94 million in Q3, second only to fourth quarter of 2011. The growth was 21%. Year-on-year growth in revenues was about 17% for both quarters, in-line with company growth. Profits grew 5% in Q2 and 25% in Q3.
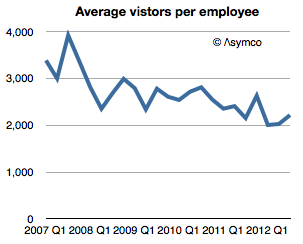
Average visitors per employee picked up slightly but remained largely unchanged since 2008.
Employment increased in proportion to visitors, consistent with previous quarters.
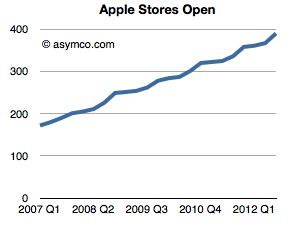
Store openings were 9 and 18, above the recent past but consistent with historic trend.
[It should be noted here that the lead time for a store's opening is longer than the development time of an iPhone so whatever was opened was probably planned in 2010 or so.]
Based on employment time and cost, the "performance" of the stores were not divergent from the overall historic trend (and product launch cycles of the company.)
If stores did not show any effect of poor management, then why was Browett fired? I suspect it had mostly to do with a mis-match of understanding of the job the stores are hired to do by consumers and by Apple itself. The company treats the stores as a sales channel but also as a communications channel with its customers. Recall when Steve Jobs was asked why they stopped attending MacWorld (and any other trade show) he answered that they had the dialog they needed with customers through their stores making.
That dialog is engaged between 100 million visitors and 42,000 employees every three months. The average time spent with each visitor is 13 minutes. Each visitor also leaves about $45 behind. As I put it earlier, the stores are the face of the brand.
Whoever is in charge must understand this special relationship. The surprise for me is not that Browett was fired, but that if he did not understand this relationship, how was he ever hired?
In this episode Horace and Moisés discuss the iPad mini launch weekend (vis-a-vis older iPads and Windows 8), the curious case of choosy late adopters of smartphones in the US and the mystery of Apple's capex late in the year. Horace spins a yarn about how Apple is playing chess with Sharp and Foxconn (and others) vs. Samsung.
The latest yearly report from Apple includes, as it has in the past, the forecast of Capital Expenditures. I've been tracking this data as an indicator of both strategic intent and potential forecasting tool for iOS device production.
Before exploring Apple's own forecast, we should look at how they met expectations for fiscal 2012.
In October 2011 the company forecast was as follows:
The Company anticipates utilizing approximately $8.0 billion for capital expenditures during 2012, including approximately $900 million for retail store facilities and approximately $7.1 billion for product tooling and manufacturing process equipment
The Company’s capital expenditures were $10.3 billion during 2012, consisting of $865 million for retail store facilities and $9.5 billion for other capital expenditures, including product tooling and manufacturing process equipment, and other corporate facilities and infrastructure. The Company’s actual cash payments for capital expenditures during 2012 were $8.3 billion.
There are two points that need to be highlighted:
Expenditures overall were $2.3 billion higher than forecast. Nearly all of the over-spending was for "product tooling, manufacturing process equipment and infrastructure". Retail was planned at $900 million and actual was $865 (an under-spend of $35 million). As no major real estate assets were acquired (change in those assets was $380 million, less than 2011 or 2010) the "deficit" in budgeted expenditures can be attributed entirely to product tooling and manufacturing process equipment.[1] The $2.3 billion spending over expectations amounts to 34% of forecast.
The cash payments for capex were $2 billion lower than expenditures. This is a curious situation which was not highlighted in previous 10 K reports. What this implies is that much of the "over-spend" was not paid for though cash and since no new debt was booked it's likely to have been paid for through some form of vendor financing. I'll explore some explanations below.
So it's important to note that the company spent a great deal more (one third more) than expected and paid for some of the acquisitions through uncharacteristic or unorthodox means.
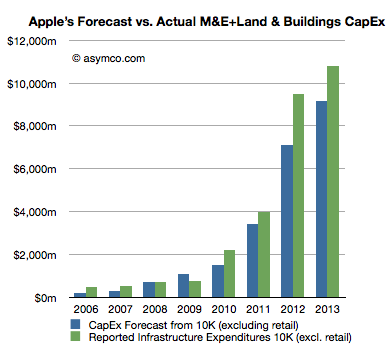
The historic budgeting for Machinery & Equipment (+Land & Buildings) is shown in the following graph:
I included the forecast for 2013 ($9.15 billion) and added 18% to estimate 2013 actual spend.
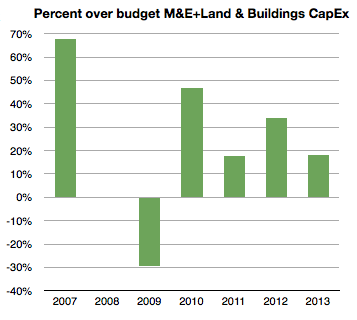
The percent over/under budget (percent difference between green and blue bars above) is shown below:
[Again, note that I took the liberty of forecasting 2013 over-spending at 18% or $10.8 billion.]
Note that 2008 and 2009 were either on target or below target. The recession of 2008/2009 might have had something to do with that. The under-spending situation of 2009 was made up for during 2010 with over 45% extra spending. 2011 came in at 18% over and 2012, as already noted, was 34% over budget. I then suggest that 2013 will be at 18%, same as in 2011.
When seen in this historic context, the increase of 2012 is even more dramatic. Apple overspent in 2012 more than it spent overall two years earlier. 2012 spending on M&E (and Land) was up 138% sequentially and nearly seven times the level of three years ago.
With this splurge in mind it's necessary to think about that second noteworthy point above. There is evidence that at least some of the $2.3 billion over-budget was unanticipated and came late in the year. We saw the surge in spending in FQ4 from the gross asset value change data. The question is what was it spent on and why did it not go through the cash flow statement?
Circumstantial[2] evidence points to the asset being production equipment (or even a whole plant) previously owned by Sharp. Sharp is a key supplier of screens to Apple but is also in financial distress. Sharp has also been the object of an intended investment by Foxconn [Hon Hai]. That deal fell through as Sharp's finances deteriorated. My guess is that these attempts to shore up Sharp are directed by Apple to ensure both continuity of supply and a balanced supplier base (offsetting Samsung, another supplier.) If Sharp were to enter into some form of bankruptcy, the key plant(s) used in producing screens for Apple might be "up for grabs" by creditors and they might be taken off-line, jeopardizing Apple's production capacity, irrespective of contractual obligations. I believe that Apple's late and unprecedented expenditure was to secure this asset. I further believe that the financing for this deal was done through a swap of "pre-orders". Stepping even further into the hypothesis, I believe Apple arranged to move a Sharp screen production line onto its books and "paid" for it through a pre-payment of components. This being a pre-payment it would be in the form of an "off balance sheet" commitment. Apple reported that "As of September 29, 2012, the Company had outstanding off-balance sheet third-party manufacturing commitments and component purchase commitments of $21.1 billion" [my emphasis]. This is a significant increase from earlier years and allows for a huge "slush fund" to cover asset swaps.
If we take the timing of this expenditure into consideration, I consider it reasonable to assume that 2013 spending is lower by this amount. In other words, I think that about $2 billion, including the Sharp plant, may have been "brought forward" by a few months from 2013. If the company had spent more on schedule and on budget (i.e. with an over-spend of 15% rather than 34%) it would have spent about $8.2 billion. Therefore, as next year's forecast is for $9.15 billion and as I would also expect an over-spend of 18% or $10.8 billion total, adding the brought-forward $2 billion would imply sequential growth from $8.2 to $12.8 or 56%.
This is in contrast to the indicated change of $9.5 billion (actual) to $9.15 billion (forecast), or decrease of 4%.
So, recapping the CapEx story, the company over-spent far more in 2012 than anticipated. It did so late in the year. It did it while a supplier was in distress and another's supplier's efforts in rescue failed. Furthermore, it indicated a modest and thus uncharacteristic increase in the next year's CapEx budget. My take is that the trajectory of investment is not being altered dramatically but it's had an adjustment in timing, a kink in the line. The overall story remains that Apple is still injecting vast and growing amounts of capital into production and placing those assets on its own balance sheet.
---
Notes:
I track this spending through asset value changes in the balance sheet. That change in value excludes depreciation which turned to to be substantial in 2012: $2.44 billion.
What follows is strictly hypothetical and based only on pieces of evidence that have become public hinting at an explanation but there is no proof.
A video of Horace Dediu's presentation at IBM's Electronics Global Leadership Forum in Taipei on 23 October 2012. Horace discusses how Apple's enormous capital spending is reshaping the global supply chain for the industry.
Here is an exchange with Robert van Apeldoorn, Journalist with Trends Tendances Magazine in Belgium. (www.trends.be/fr). The exchange took place in early September via e-mail.
Robert: -Information and Communications Technology (ICT) is considered in Europe as a way to push growth, and is a target of national and EU policies (digital growth,etc), but the result seems to be a failure: the European computer industry (hardware) is almost dead (ICL, Siemens computers bought by Fujitsu, Olivetti almost out of computer business, Nixdorf dead) since the 90’, and the telco industry seems to be in crisis. All European companies are out of the handset business (big and fading exception is Nokia, but with American software), and Alcatel is suffering with telco equipement manufacturing. It seems that at best, Europe can be a good niche player, with companies like ARM (chips). Technology seems to be reduced to localized services (computer services), some software businesses. What do you thing about that point of view? Is it correct or exaggerated ? What will remain to the European companies ?
The main problem is perphaps the creation of European platform/ecosystems. Almost all are American today: Apple IOS-iTunes, Android, Amazon,…
Why Symbian didn’t succeed as a competitive platform ?
Is it possible to create European platforms? After all, IOS succeed after a short period of time.
What are the European tech companies that could play an important role in the near future ?
My answer: You are correct in this observation. Europe has failed to generate growth on the basis of ICT. The reasons are that the rate of change in ICT is rapid and getting more so. If European businesses require intervention, support or other forms of assistance in terms of policy, the time for that coordination to take effect is longer than the cycle time of disruption.
Almost all growth has come from companies that entered the space. Google, Amazon, Apple and Facebook and even Microsoft came into positions of power from outside the industries they entered. Policy tends to offer means of sustaining incumbents or finding "logical" or defensible entrants. I should mention that the problem of industrial policy failing is not unique to Europe. Japan and to a lesser degree Korea are also facing crises of innovation due to policies designed to sustain rather than disrupt.
It's understandable given the need to justify spending other people's money. No policy maker wants to spend it recklessly. However, the process of unforeseen growth is, well, unforeseeable. It cannot be predicted and it's very likely to come from somewhere other than where you expect it.
This quickly becomes a lengthy discussion, but fundamentally the innovation process is chaotic. It's very similar to the process of artistic creation. The crisis in innovation comes from not having sufficient chaos. If Europe wants to preserve, sustain, nurture, and maintain it will do so at the expense of creative destruction. Nobody likes chaos but everybody wants innovation. Unfortunately they are concurrent things.
thank you very much for these interesting answer. Usually the answer is the lack of venture capital or the compartimented market.
So Nokia was an exception ?
If a lack of venture capital is the problem then what is the cause of a lack of venture capital? There is plenty of capital on the continent. Why should it not be allocated to ventures? Capital markets in Europe are quite free and liquid and capital will find the best opportunities. The problem is that there are few fundable opportunities.
I think Nokia was not an exception in the sense that it was not a "managed" success. The company (and Finland) emerged from a crisis in the early 90s. The crisis forced a re-evaluation of priorities and the success of Nokia could be attributed to a lack of emphasis in what was considered sustaining at the time (consumer electronics, TVs, natural resources, etc.) Entry into mobile phones was not what policy would have suggested was the biggest opportunity at the time. The market for mobile phones was projected to be insignificant in comparison to what was seen as success of the time (Sony, et. al.)
[Addendum: What are policy makers suggesting as the key investment themes? Which projects get funding today and which don't?]