Asymco

Asymmetric Intelligence

Research

  1. The diffusion of iPhones as a learning process

    Research · 50 comments

    All theoretical and empirical diffusion studies agree that an innovation diffuses along a S-shaped trajectory. Indeed, the S-shaped pattern of diffusion appears to be a basic anthropologic phenomenon.

    This observation dates as far back as 1895 when the French sociologist Gabriel Tarde first described the process of social change by an imitative "group-think" mechanism and a S-shaped pattern. ((Tarde was probably influenced by mathematician Pierre François Verhulst who first published the logistic function in 1845)) In 1983 Everett Rogers, developed a more complete four stage model of the innovation decision process consisting of: (1) knowledge, (2) persuasion, (3) decision and implementation, and (4) confirmation.

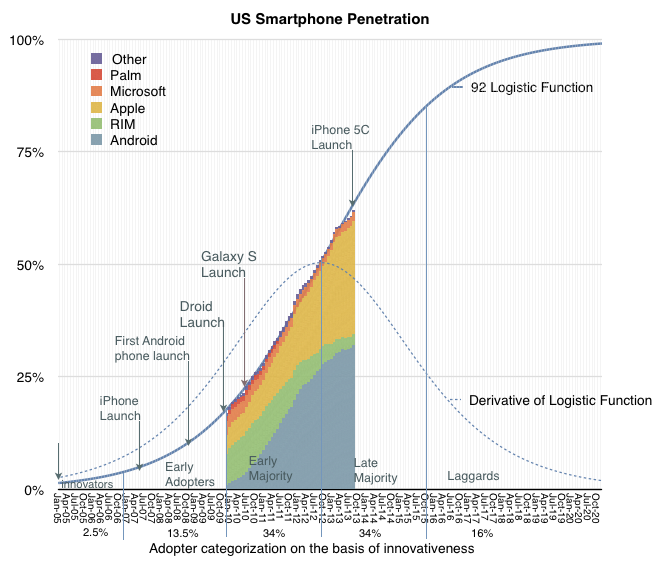
    Consequently, Rogers divided the population of potential adopters according to their adoption date and categorized them in terms of their standard deviation from the mean adoption date. He presented extensive empirical evidence to suggest a symmetric bell shaped curve for the distribution of adopters over time. This curve matches in shape the first derivative of the logistic growth and substitution curve as shown below. 
    Screen Shot 2013-11-06 at 11-6-1.51.57 PM

    In the graph above I applied the Rogers adopter characterization to the data we have on the adoption of smartphones in the US. The latest data covering September is included.

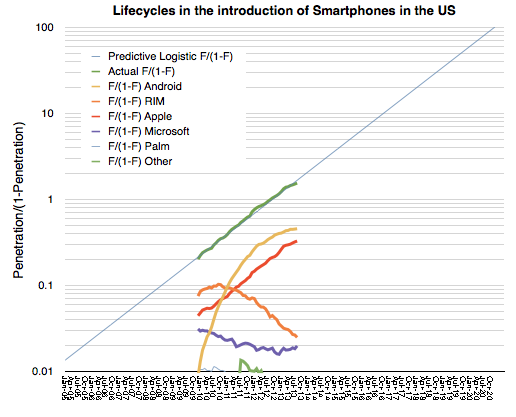
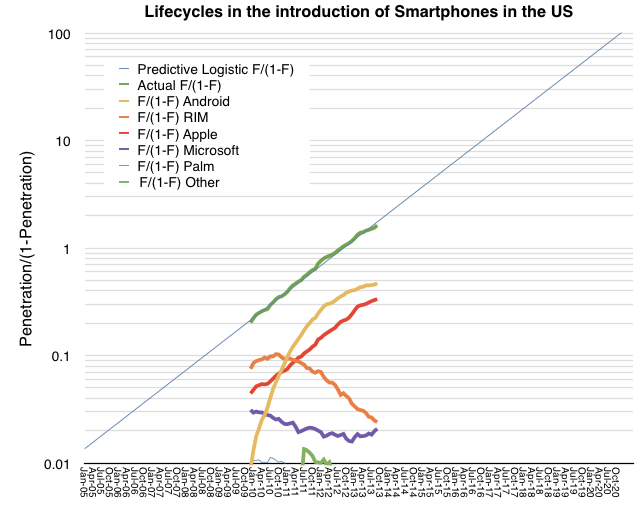
    The fact that smartphones in the US follow the theory is exciting, but what can we conclude about the adoption of specific platforms? There has been quite a bit of turnover in the leadership of the market in the first half of the time frame given. You can see this more clearly in the following fractional market share transformation.
    Screen Shot 2013-11-06 at 11-6-2.16.03 PM

    Note that, with the exception of the iPhone, if each platform is studied individually, it would not follow a logistic (i.e. linear) pattern even though, as a whole, the technology does.

    This then is the big puzzle: while we might be able to predict how smartphones will diffuse into society, we can't seem to predict how any single firm will fare. This means that an investor cannot make a credible "bet" on the technology ((Indeed investors often get burned when new technologies emerge. While the technology booms, individual firms supplying it often fail. See the history of transportation, communication, computing and energy.)). If they choose a single company as proxy, chances are they will lose. If they bet on a basket of companies then, again, chances are they will lose. There is usually one unforeseeably clear winner.

    Before we get further into the question of picking winners or predicting the future division of share among rivals, we should understand the underlying causes for this pattern of adoption.

    Rogers concluded that the learning behavior of individuals is the underlying cause of the symmetry of the diffusion process.

    At the beginning, when an individual is confronted with a new (learning) situation they make many mistakes. These mistakes are gradually reduced (by learning) over time because more and more information is received and acts as a stimulus. The gain in learning per trial is proportional to the product of the amount already learned and the amount remaining to be learned before the limit of learning is reached.

    Arnulf Grübler ((The Rise and Fall of Infrastructures, Physica-Verlag 1990)) explains:

    This is exactly equivalent to the F(1-F) transformation of the logistic curve. It should be emphasized that these properties of the learning process were found in real learning situations and are confirmed by a large number of laboratory and field experiments. Thus each adoption of an innovation in a social system is equivalent to a learning trial by an individual. Thus, the symmetric diffusion pattern results from the way messages about an innovation are emitted and processed by social learning.

    So these observers of the process assign learning behavior as the cause for adoption of a technology. Can the learning behavior be applied to individual platforms? It's tempting.

    The hypothesis would go as follows: adopters are not only processing messages about the new technology but they are also trying different platforms as they enter and as they upgrade their phones. If we see platform choice as a learning process then if one platform has a natural advantage, it settles into a dominant position as users "learn" of its advantage. Conversely, if no platform has an advantage then platform "churn" repeats as rivals gain/lose positions of leverage in the market.

    The pattern shown so far seems to point to Apple's iPhone having a logistic pattern indicating that it might be benefiting from a learning pattern. The alternative platforms may simply be jockeying for temporary advantage.

    It's an interesting hypothesis. To be developed further we need to answer what any learnable advantage might be. I suspect it has to do with the ability to solve unmet and unarticulated needs. In other words, that the winning product solves a set of "jobs to be done" which are difficult to pin down and are perceived rather than defined.
  2. Do ads work? The ad budgets of various companies

    Research · 59 comments

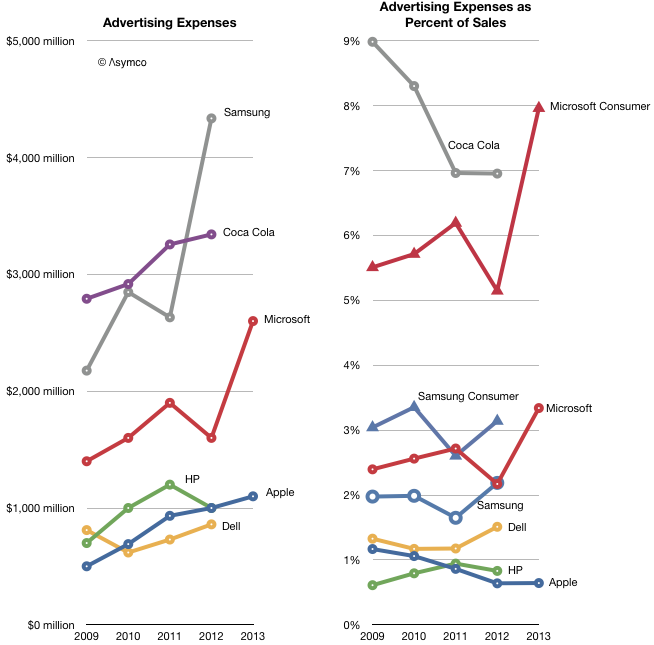
    Microsoft spent $2.6 billion for Advertising in the fiscal year ended June. Apple spent $1.1 billion in its fiscal year ended October.

    Other companies will report their full year ad spending later but their previous years' spending is shown below.

    Screen Shot 2013-11-04 at 11-4-4.55.03 PM

    I added a second graph showing the percent of sales that each ad budget represents. Note that Coca Cola retains the crown as the most prolific advertiser when it comes to budgeting. ((Think of it as 7 percent of every Coke purchase going to pay for the ad that presumably got you to buy it.))

    However, Microsoft is climbing into a region of 3 to 5% of sales. What's even more striking is that we can isolate the revenues which are actually being targeted by the ads: consumers. Microsoft's Business and Server and Tools divisions may have some ad budget but it's likely to be much smaller than the Windows, Entertainment and Online divisions.

    When the ad budget is measured as a percent of consumer sales, Microsoft suddenly looks like the biggest spender overtaking even Coca-Cola. ((Note that Samsung can also be similarly split into consumer vs. total.)) I don't know what to make of this. It seems extraordinary that Microsoft needs the same level of effort to sell software (and some hardware) as Coca Cola does to sell soft drinks. Coca Cola spends heavily to preserve brand value for what is essentially a commodity product. Is this the way to read Microsoft's marketing?

    It's also interesting that Apple spends the least (nearly) in absolute terms and fractionally less (one twelfth) in relative terms. This is in contrast to the alternatives above. The stronger, more differentiated the product, the less it needs to be propped up by the ad.


  3. Owing how much to how few?

    Research · 7 comments

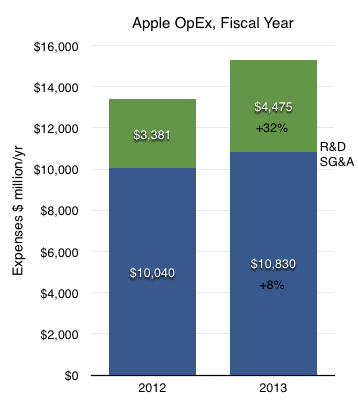
    For the year ending October Apple's R&D costs were $4.475 billion. These costs have been rising. Though, as the company explains, not faster than net sales:

    The growth in R&D expense was driven by an increase in headcount and related expenses to support expanded R&D activities. Although total R&D expense increased 32% and 39% in 2013 and 2012, respectively, it remained fairly consistent as a percentage of net sales.

    [My emphasis]

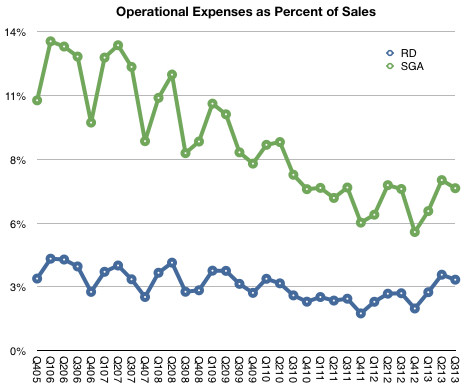
    We can see this in the following graph:

    Screen Shot 2013-11-01 at 11-1-4.37.48 PM

    R&D has remained very nearly 3% of sales since at least 2005.


    SG&A Expenses barely grew however:

    The growth in SG&A during 2013 was primarily due to the Company’s continued expansion of its Retail segment and increased headcount and related expenses, partially offset by decreased spending on professional services.

    The change in R&D and SG&A on a full-year basis is shown below.

    Screen Shot 2013-11-01 at 11-1-4.42.06 PM

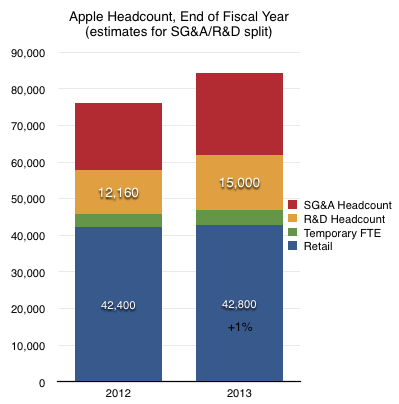
    I emphasized the mention of increases in headcount. We cannot know with any precision what portion of last year's $15 billion in operating expenses went toward wage expenses since there are other costs such as advertising ((Apple's advertising expenditures for fiscal 2013 were $1.1 billion or 10% of SG&A or 0.64% of sales.)) commissions and public relations in the case of SG&A and outside services, equipment leases, in the case of R&D. However, it's more likely that wage expenses are a far larger proportion of total R&D than they are of SG&A.

    My estimate, based on wage rates, is that there are approximately 15,000 R&D staff at Apple.

    Screen Shot 2013-11-01 at 11-1-4.42.49 PM

    If we divide sales by this number we get $11.4 million in sales per engineer.

  4. The Quantum Leap in Retail

    Research · 46 comments

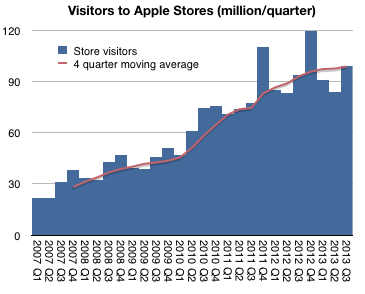
    In fiscal 2013 there were 395 million visits to Apple retail stores. In 2012 there were 372 million.

    Screen Shot 2013-10-31 at 10-31-2.15.13 PM

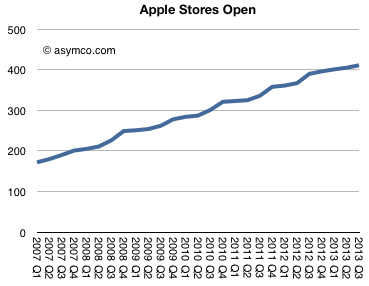
    The difference is approximately the population of Australia. This was in addition to the population of the US and Canada already passing through. Although this is a fun way to think about total traffic, it does not reflect performance of the stores themselves since new stores are always being opened. 21 new stores in 2013, to be precise.

    Screen Shot 2013-10-31 at 10-31-2.15.21 PM

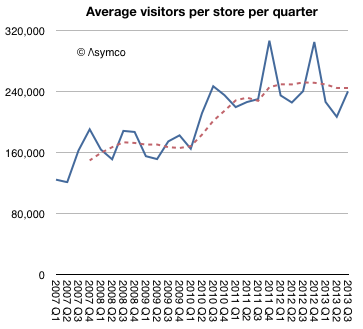
    The better benchmark should be the number of visitors per store.

    Screen Shot 2013-10-31 at 10-31-2.17.15 PM

    This shows that, except for seasonal peaks, the visitors per store per quarter has been a fairly steady 240k since mid-2010. What's more, this rate was also remarkably steady at around 160k/store/quarter from 2007 to 2010.

    So what caused this quantum jump (("Quantum leap" is often used to mean "giant leap" but in the original usage it meant a specific, discrete jump)) in traffic? Was it due to a re-design of the stores? Was it a change in product mix? Or was it due to a change in staffing rules?

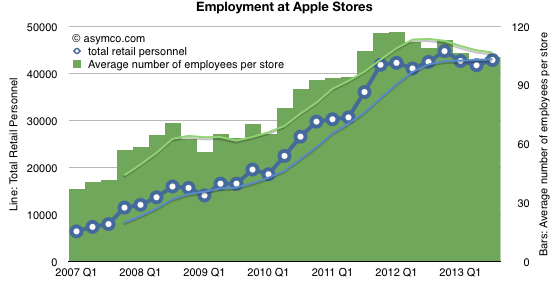
    I think we can rule out staffing changes. The data shows that staffing ramps with visitors and there was no specific "quantum" increase in employment (on a per-store basis or otherwise).

    Screen Shot 2013-10-31 at 10-31-2.18.56 PM

    Re-design as a cause has some more merit. On one hand, we have seen bigger stores opening and many more flagship stores. We have also seen specific renovations of existing stores. We have also seen re-designs where the layout was changed to allow for more traffic. The only problem with this as a cause for the quantum leap is that these changes are constantly under-way and have been for some time. It's hard to point to a specific "big bang" redesign across the board in early 2010 as possibly a cause.

    That leaves product. Here we have a clear suspect. The iPad launched exactly at the point in time when the visitor count leaped. In my opinion this is the best explanation.

    Let's remember also the comment from Ron Johnson at the time of the iPad launch. He said that it was as if the stores were designed for a product like the iPad. In other words, the iPad is something that needs to be discovered with a retail experience. You can sense this when you visit the stores and the placement of the iPads within.

    It all points to a something more profound: that the stores are brand ambassadors. Apple products create a purchase decision by speaking directly to  the users. For the type of product Apple makes, that conversation can only happen face-to-face. The place where this meeting happens is the store.

  5. How many iOS devices will be produced in the next 12 months?

    Research · 56 comments

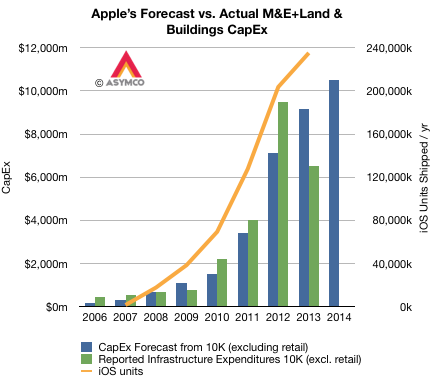
    Apple's capital expenditures for product tooling, manufacturing process equipment, corporate facilities and infrastructure has followed very closely their production of iOS devices. The pattern is shown in the graph below.

    Screen Shot 2013-10-30 at 10-30-2.12.28 PM

    Note that although reported expenditures did not match forecasts for 2012 and 2013, the differences nearly cancel each other. ((I suspect that the difference might be caused by a payment being brought forward in 2012.)) The company's forecast for fiscal 2014 is shown as well.

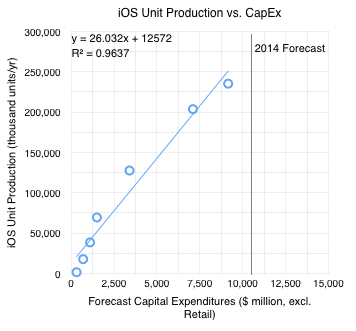
    The orange line shows iOS unit production ((Technically, shipments)) with the scale on the right-side axis. Note the correlation with forecasts on CapEx. The relationship can be seen more clearly in the following scatter plot.

    Screen Shot 2013-10-30 at 10-30-2.33.26 PM

    I added the 2014 Forecast ($10.5 billion from the latest 10-K filing). If the relationship holds into next year then the iOS unit shipments should be between 250 million and 285 million. ((The equation for the trend line shown suggests 285,908,000 units)).

  6. The newly integrated company

    Research · 25 comments

    During the first quarter of fiscal year 2014, we changed our organizational structure as part of our transformation to a devices and services company. As a result of these changes, information that our chief operating decision maker regularly reviews for purposes of allocating resources and assessing performance changed. Therefore, beginning in fiscal year 2014, we are reporting our financial performance based on our new segments; Devices and Consumer (“D&C”) Licensing, D&C Hardware, D&C Other, Commercial Licensing, and Commercial Other.

    The previous reporting segments were:

    • Windows & Windows Live
    • Server and Tools
    • Online Services
    • Microsoft Business
    • Entertainment and Devices
    • Unallocated and other

    The new are:

    • D&C Licensing: Windows OEM licensing, Consumer Windows, Consumer Office, Windows Phone (including related patent licensing)
    • D&C Hardware:  Xbox 360, second-party and third-party video games, and Xbox LIVE subscriptions; Surface; PC accessories
    • D&C Other: Resale, including Windows Store, Xbox LIVE transactions, Windows Phone Marketplace; search advertising; display advertising; Subscriptions including Office 365 Home Premium; Studios including first-party video games; retail stores.
    • Commercial Licensing: Windows Server, Microsoft SQL Server, Visual Studio, System Center; Windows Embedded; volume licensing of Windows; Microsoft Office for business (Office, Exchange, SharePoint, and Lync); Client Access Licenses;  Dynamics, Skype.
    • Commercial Other: Enterprise Services, including Premier product support services and Microsoft Consulting Services; Cloud Services, comprising O365, other Microsoft Office online offerings, Dynamics CRM Online, and Windows Azure.

    From Microsoft's FY14 Q1 10Q via Microsoft Investor Relations - Press Releases

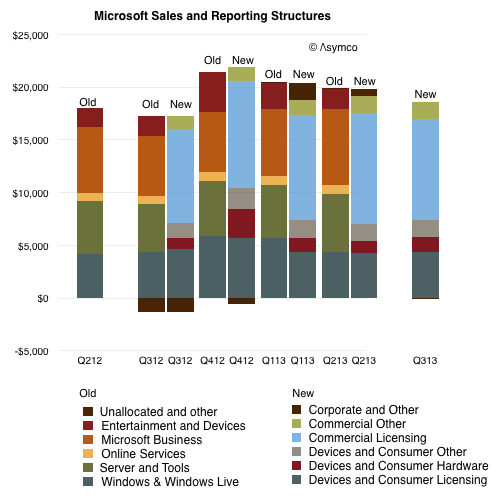
    The mapping between the old and new is not straight forward. There is overlap between D&C Licensing and the old Windows and perhaps between Entertainment and Devices and D&C Hardware but there are many gaps. There is also some overlap between the old "Business"/"Server" segments and the new "Commercial" but, again, they cannot be matched.

    I show the difference between the two structures in the way revenues are allocated below, using color to try to show similarities.

    Screen Shot 2013-10-25 at 10-25-11.25.07 AM

    Given the re-stated quarters it's possible to compare one year's historic performance at a segment level. For example, the company states that "Devices and Consumer revenue grew 4% to $7.46 billion" while "Commercial revenue grew 10% to $11.20 billion".

    Since we don't have data older than one year, our ability to assess the company over longer time periods will be drastically reduced and a new picture will take a long time to emerge.

    There is however one aspect of the new structure that needs to be appreciated right away: the allocation of costs has changed fundamentally. The company explains:

    Cost of revenue is directly charged to the D&C Hardware segment. For the remaining segments, cost of revenue is directly charged in most cases and allocated in certain cases, generally using a relative revenue methodology.

    We do not allocate operating expenses to our segments. Rather, we allocate them to our two segment groups, Devices and Consumer and Commercial. Due to the integrated structure of our business, allocations of expenses are made in certain cases to incent[sic] cross-collaboration among our segment groups so that a segment group is not solely burdened by the cost of a mutually beneficial activity as we seek to deliver seamless experiences across devices, whether on premise or in the cloud.

    [my emphasis]

    In that brief paragraph Microsoft has formally and in a financially binding way declared itself to being a functional organization. ((Welcome to the club.))

    The mechanism seems banal: operating costs are no longer assigned to product divisions but to two large buckets. In practice this means that profitability (P/L) cannot be assessed or assigned to individual managers. The lack of P/L responsibility means that incentives from top to bottom have to be re-engineered. If this goes wrong, the Assets ((read: people)) of the company could evaporate.

    If the assets go, then processes and priorities are for naught.

    In other words, what the company is undertaking is a priority shift (to a  functional structure to create integrated experiences) which requires a process change (whereby employees work according to new incentives) while preserving the fragile assets the company depends on (a motivated and skilled base of employees.)

    This makeover is as ambitious as a re-org gets and the context, scope and target are as difficult as they can be. This is, after all, the largest software company operating the the most dynamic industry whose multi-sided markets are notoriously volatile due to disruptive forces.

    The challenge also suggests why Ballmer left and who should replace him. A priority transplant operation requires a different set of skills than those held by the manager who created the processes for the previous set of priorities. That's the manager's dilemma: even if you foresee the changes needed and push for them to be enacted, your reward might be to be replaced by someone who can make the changes happen.

    Those who envision and persuade for change are rarely allowed to enact it.

  7. The value of zero-priced software

    Research · 128 comments

    Apple's latest product launch (new OSX, iPads, Macs and iWork/iLife) came with a change in pricing for software. OS X and iWork and iLife and updates are now made available free on new Macs and, in the case of the suites, on iOS devices as well.

    Recall also that iOS updates are now free as well and that OS X had been reduced in price from about $129 to $29 with Snow Leopard in August 2009 and to $19 with Mountain Lion in July 2012. The iSuites have also dropped in price over time so the pattern of evaporating software prices is long-running.

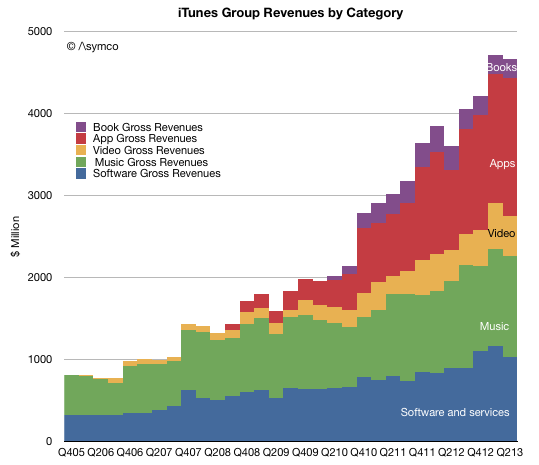
    But how fast and what is the impact? The historic performance Apple's Software business is not easily determined since it was always blended with additional businesses. Until September of last year, Software was reported as part of "Software and Services" and since then as part of "iTunes, Software and Services." Some assumptions allow the following picture to be drawn:

    Screen Shot 2013-10-24 at 10-24-5.07.03 PM

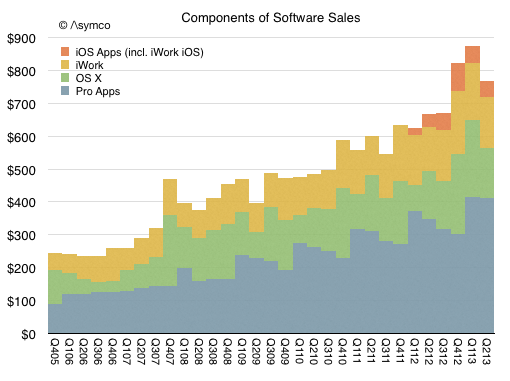
    One additional wrinkle to the Apple software story is that OS X and iWork/iLife are not all the software titles available. Apple's software includes Pro apps as well as the non-free OS X server. The non-free software US prices are:

    • Aperture: $79.99
    • Final Cut Pro: $299.99
    • Motion: $49.99
    • Compressor: $49.99
    • Logic Pro X: $199.99
    • MainStage 3: $29.99
    • OS X Server: $19.99
    • Apple Remote Desktop: $79.99

    Given that and additional assumptions can lead to the following picture of the components of Apple's Software sales (in $ million/quarter).

    Screen Shot 2013-10-24 at 10-24-5.08.54 PM

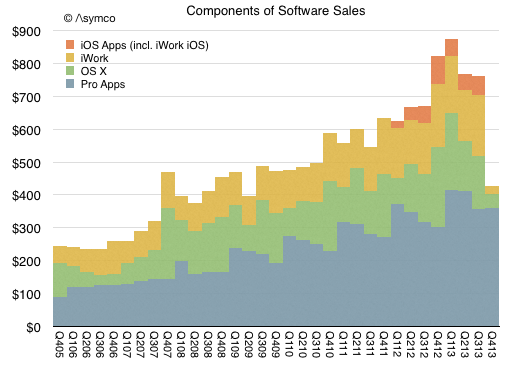
    Given this picture of the software business and the change in pricing, here is my forecast for the third and fourth quarters (in $ million/quarter):

    Screen Shot 2013-10-24 at 10-24-5.21.30 PM

    The foregone revenues could be as much as $450 million from what would have been received with existing pricing model.

    So the question that naturally arises is whether this is "worth it". Whether by offering free software hardware or service revenues rise.

    Perhaps. Certainly service revenue in the form of iCloud might rise with more usage of iWork and iLife. But I don't think that this is the calculus underlying the decision. Remember that Apple does not have a Profit/Loss accountability. It's not necessary (and perhaps not even preferred) that a division balances costs and revenues. ((The graphs in this post (and the preceding 1900 on this blog) were created using Numbers.))

    Fundamentally Apple remains a systems company where software is a key element in its definition of value. That is not changing. What is changing instead is the bundling of application software with the systems software and the system itself. The presence of iWork and hassle-free updating of that suite (and the same for the OS) means that utilization rates will increase.

    I believe the logic for Apple is that usage of the products determines their value and therefore placing powerful software in the hands of more users means they will value the entire system more. This leads to the notion of greater "stickiness" or "lock-in" but also to higher satisfaction and loyalty, rate of upgrades and even more third party purchases and yet more usage.

    This is the virtuous cycle platform custodians seek to engender. This is what Apple is trying to build and the transition of apps into the system bundle is part of this re-enforcement.

    One wonders how long before Apple's approach becomes the norm for other platforms.

  8. How many mobile platforms can a market sustain?

    Research · 83 comments

    Using logistic curves to measure diffusion of innovations is a powerful method of analysis. However there are limits to what can be learned. The methodology helps in understanding how quickly a pervasive technology is adopted. It assumes that the technology "fills all available space" within a market. It therefore also assumes that whatever problems the technology solves are universal problems.

    Put another way, if a technology is not universally useful, it tends to peak before a market saturates. This "universality" condition is in evidence when observing that pervasive technologies are adopted not only by all members of one national market but also all nations and through all means of government and regulation. In other words that the jobs that the technologies are hired to do are so important that they bulldoze any and all obstacles placed in the path of adoption.

    The only difference is one of timing. Some regions are quicker than others. Institutionalized obstacles essentially defer rather than deter adoption. They impede rather than block.

    And I am pretty sure that smartphones solve universal needs and their adoption will be nearly 100%. They also have fairly low impedance given the speed of adoption (50% penetration in most large markets seems to come in less than 5 years.)

    That's the story for the technology, but how value is captured is another story.

    Who captures and how it's captured are questions of commerce not economics. They are informed by competitive advantage and business models. The puzzle seems to be that individual companies don't capture value in the patterns of Logistic curves. Or at least I don't think they do.

    Consider the graph below.

    Screen Shot 2013-10-22 at 10-22-1.25.54 PM

    It shows the transformation of a logistic curve into a linear representation. It's a log-scale graph of fractional shares of smartphones in general (Blue/green Lines) and individual platforms in the US.

    The individual platforms are shown as (Platform x share of all phones/share of all others). This is a "logistic substitution trajectory". ((Fisher and Pry, 1971, proposed a similar model to study the replacement of old by new technologies. The basic assumptions of the Fisher-Pry model are: (1) The substitution process is competitive. (2) Once substitution by the new technology has progressed as far as a few percent (i.e., "lock-in"), it will proceed until a complete takeover occurs. (3) the rate of fractional substitution F1 is proportional to the remaining substitution 1- F1 possible. Source: Grübler, The Rise and Fall of Infrastructures Physica-Verlag 1990.))

    The problem is that whereas the overall category (smartphones) reaches saturation, it's not at all clear that any individual platform does. At least from the data we have so far, there is far too much volatility in platforms to see a clear pattern of monopoly emerging.

    I'm not sure if this is "proof" enough to convince anyone that this market supports any number of platforms, but it certainly disproves that there will be only one. ((The odd pattern here seems to be Apple's consistent (i.e. parallel) adoption. One hypothesis could be that Apple is different in solving the prevailing job to be done while rivals jockey for positional advantage.)) We're too far along for churn to convert existing users before saturation sets in.

  9. Cinematic

    Research · 12 comments

    Screen Shot 2013-10-18 at 8.04.50 AM

    Cinematic is to film as Literary is to prose. It's not a measure of quality or of beauty. It's mainly the application of technique to impart an additional layer of meaning to the writing, performance and direction of the medium. Cinematic technique lifts the viewer to another, more profound point beyond the literal.

    Whether it's film, literature, verse, stagecraft or other visual arts, techniques vary but they have the same purpose. They make the audience feel more than what is said.

    The quality of a good work of art is that it tells a truth without saying it.

    And this, I believe, is what the analyst should also strive for. It is at least what I try to do and, having practiced for a while, I think I can convey some of the techniques I learned.

    We don't have a better word for describing these techniques than "cinematic". They allow the presenter of complex and rich data to convey meaning with an economy of rhetoric. They draw the audience into completing the picture thus making it their own. They persuade without pleading. They teach without lecturing. They create, in a way, a poetic language for data that combines techniques from several arts, especially cinema.

    The means for teaching this is a workshop called Airshow.

    Together with IBM, we are proud to bring Airshow to Boston, New York and Helsinki this year.

    Register here.

  10. The iPhone company

    Research · 33 comments

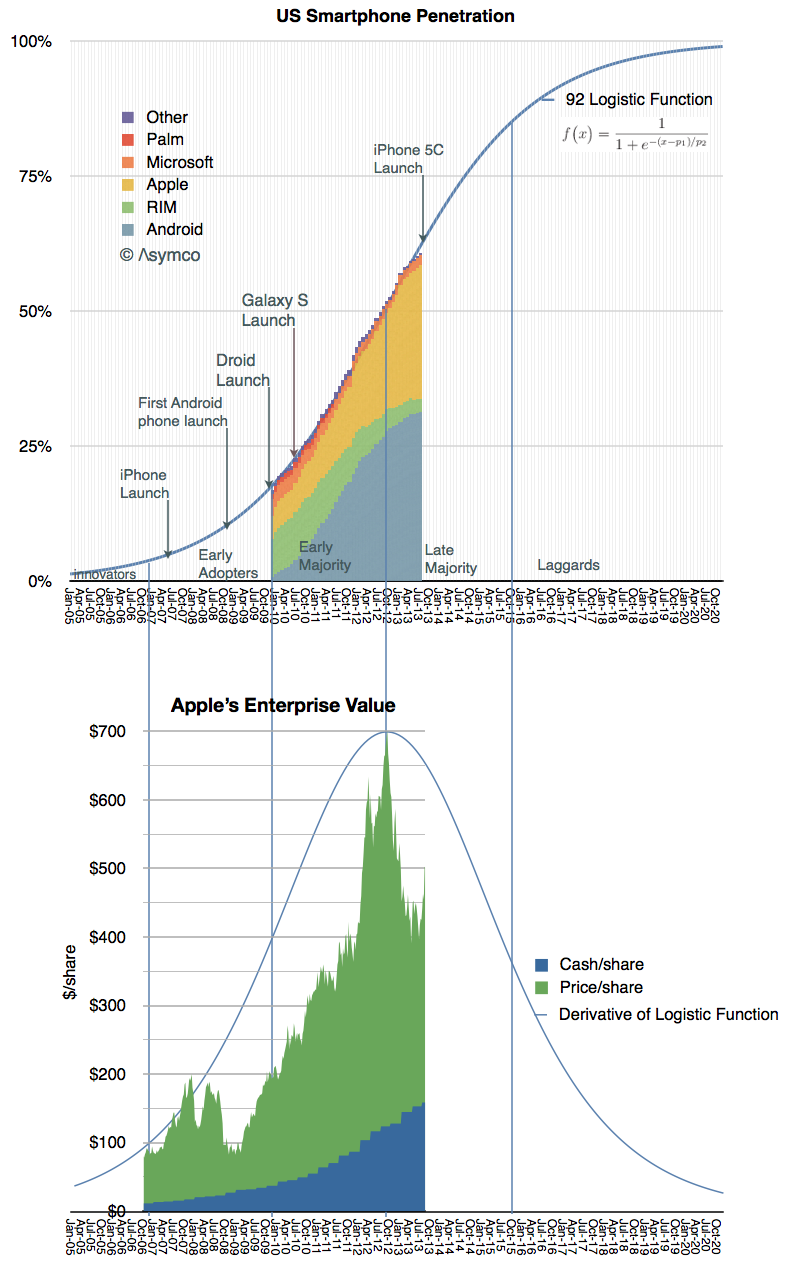
    The analyses of adoption of smartphones in the US and EU5 are remarkably consistent with each other. They also turn out to be consistent with the valuation of Apple.

    Screen Shot 2013-10-17 at 10-17-4.01.35 PM

    I show the stages of adoption overlaid with the derivative of the Logistic Function and Apple's enterprise value. The derivative of the Logistic Function shows the speed of adoption, peaking at the inflection point when adoption ceases to accelerate and begins to decelerate.

    The peak in Apple's enterprise value happens to fall at the exact point of inflection in the adoption curve and hence maximum growth.

    It could suggest that the market perceives the value of Apple to be entirely reflective of the US market.

    But I can't imagine anyone would be so foolish as to believe it.

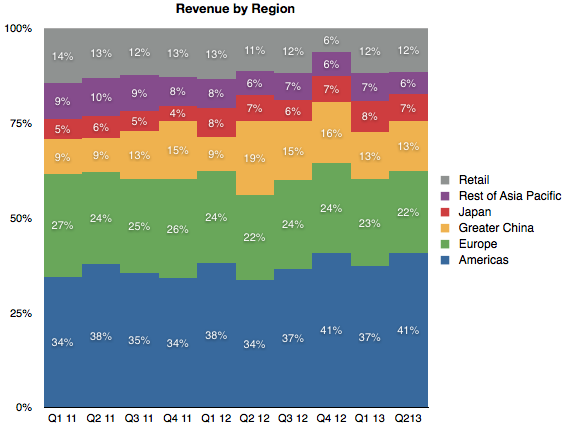
    One can only conclude that it must be just a coincidence. (( Apple's revenues by region:

    Screen Shot 2013-10-17 at 10-17-7.18.56 PM

    ))

  11. When will the European Union Five reach smartphone saturation?

    Research · 46 comments

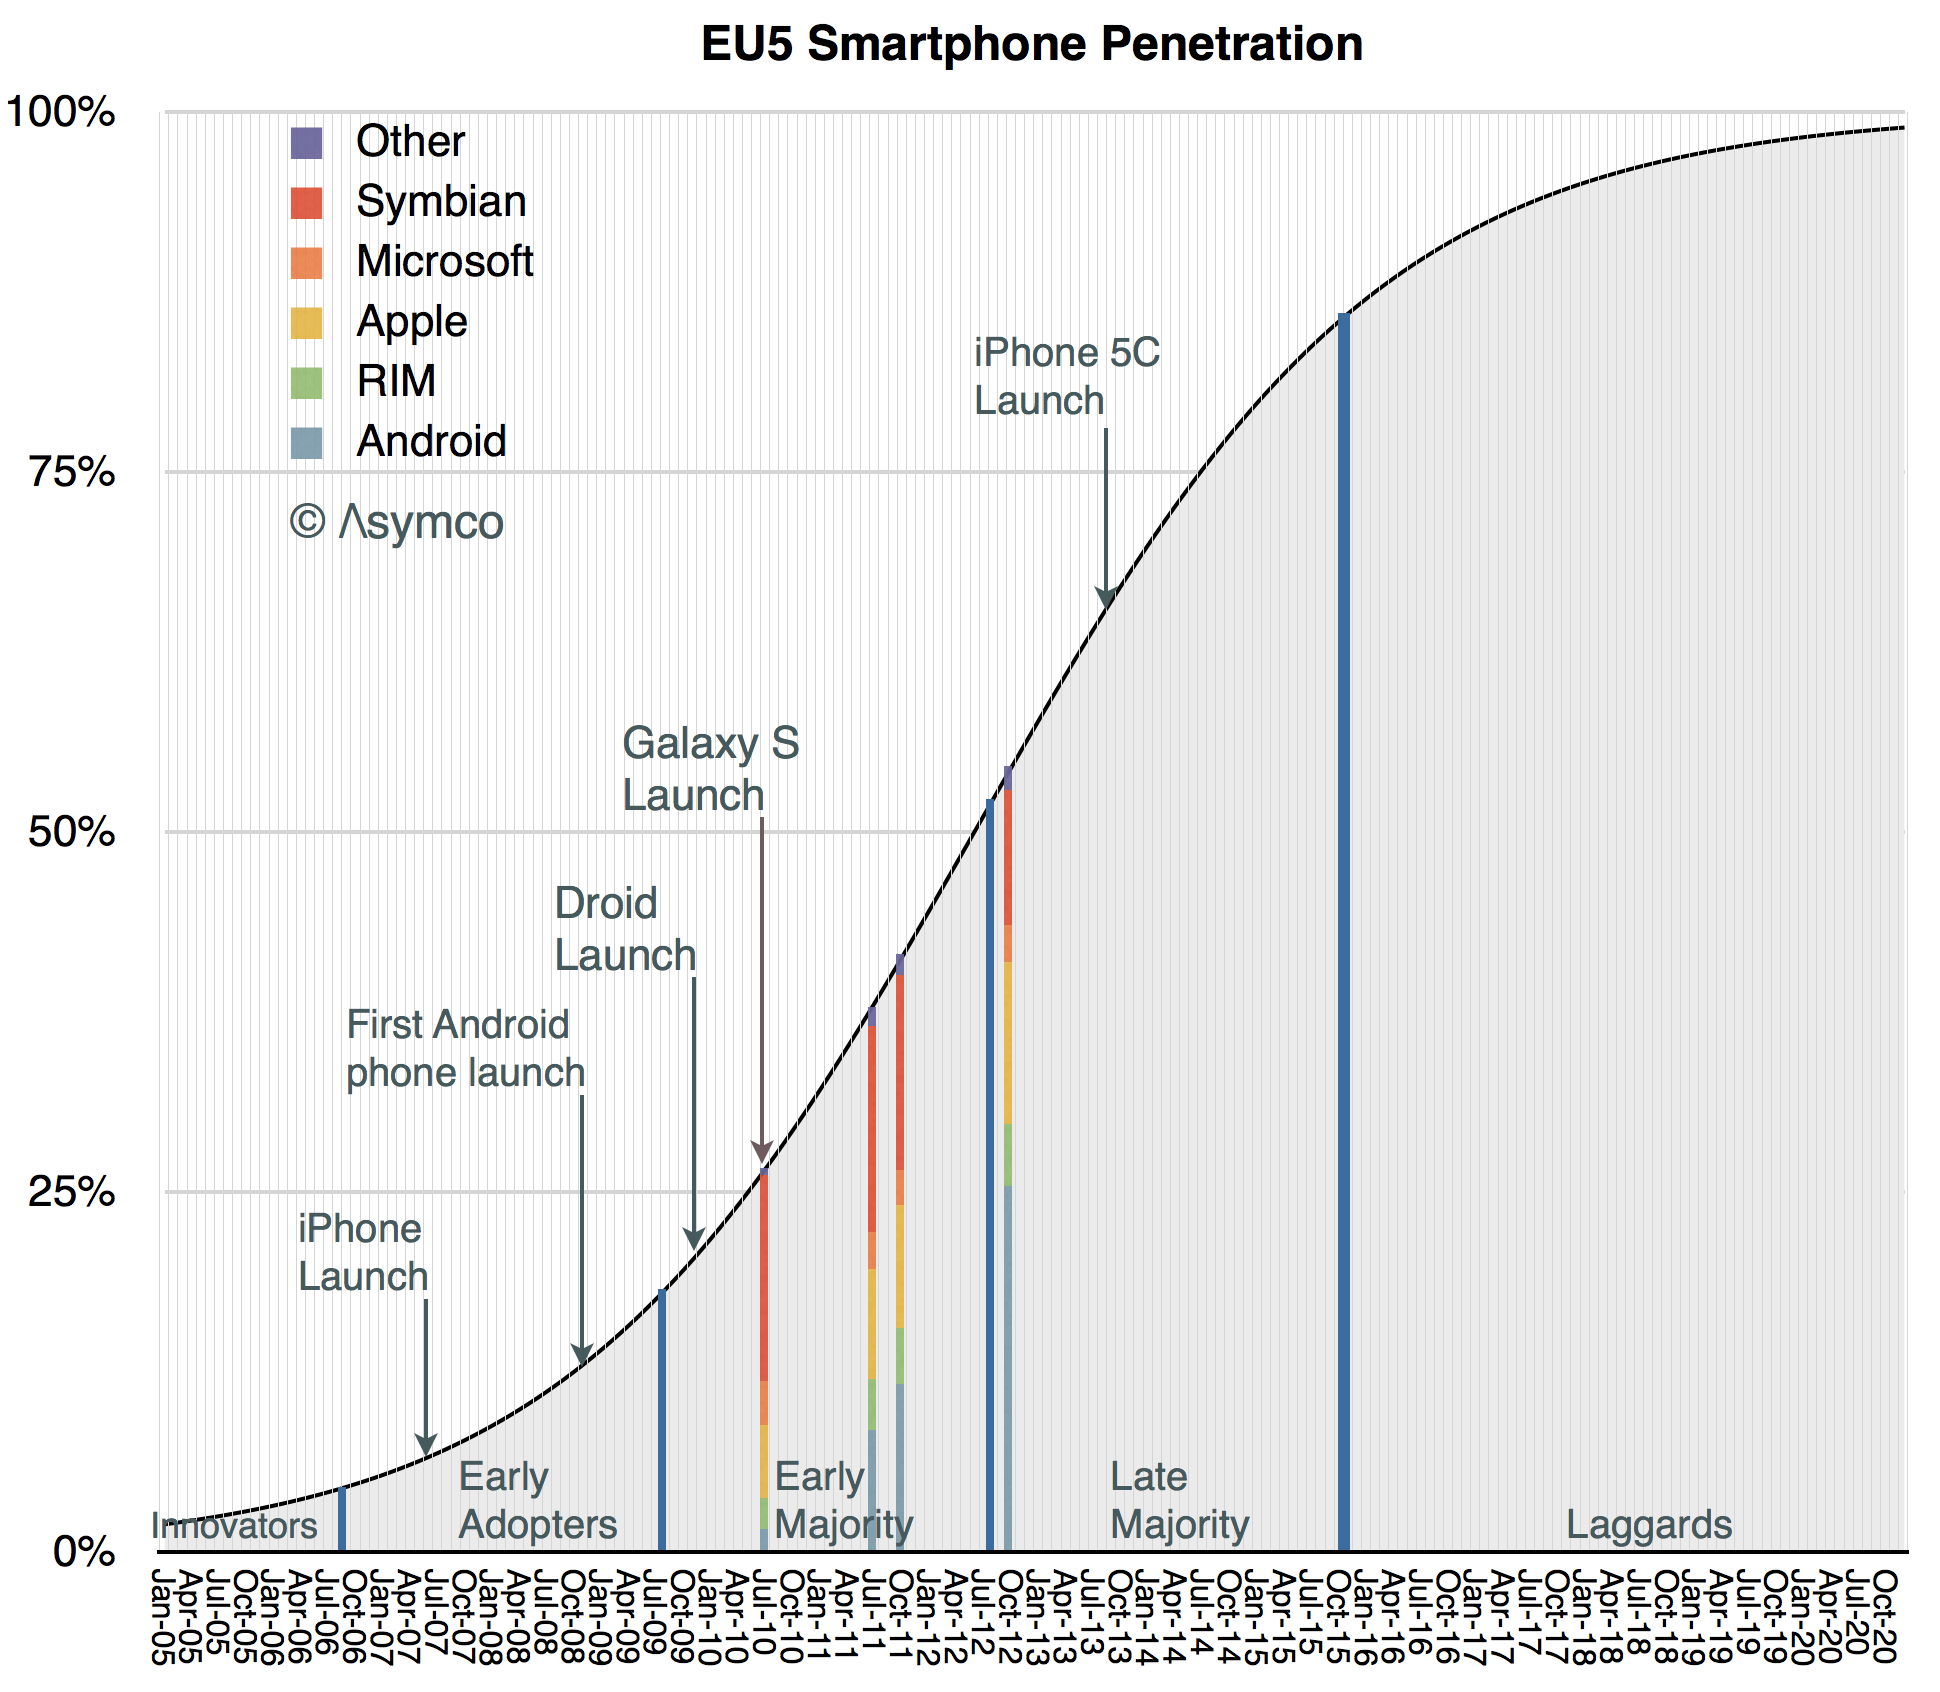
    Thanks to Symbian, the EU5 countries (France, Germany, Italy, Spain and the UK) had an earlier start in the conversion of phone usage from non-smart to smart devices. According to published comScore data, in July 2010 the EU5 were at 26.6% penetration of smartphones and the US was at 22.8% ((The population is defined as adults using phones for themselves. Meaning it excludes children and phones purchased by companies.)).

    However, with the aid of mobile operator subsidies, by the beginning of this year, the US caught up. According to comScore EU5 reached 57% penetration in March 2013 while the equivalent figure for the US was 58%.

    Using the logistic curve model introduced last week, it's possible to get an approximate categorization of the adopters of the technology:

    Screen Shot 2013-10-16 at 10-16-2.02.44 PM

    As with the previous analysis, the graph identifies the following dates:

    • The Innovators' period ended in the EU5 approximately in September 2006. (The equivalent period ended in the US in February 2007.)
    • The Early Adoption period ended in the EU5 in August 2009. (US: December 2009).
    • The Early Majority period ended in the EU5 in August 2012. (US: September 2012)
    • Late Majority will end in the EU5 in November 2015 (US: November 2015)

    Therefore if we want to suggest that saturation happens near 100% then the answer to the question in the headline is "the end of 2020." If we want to suggest that saturation is the end of the Late Majority then the answer is "two years from now."

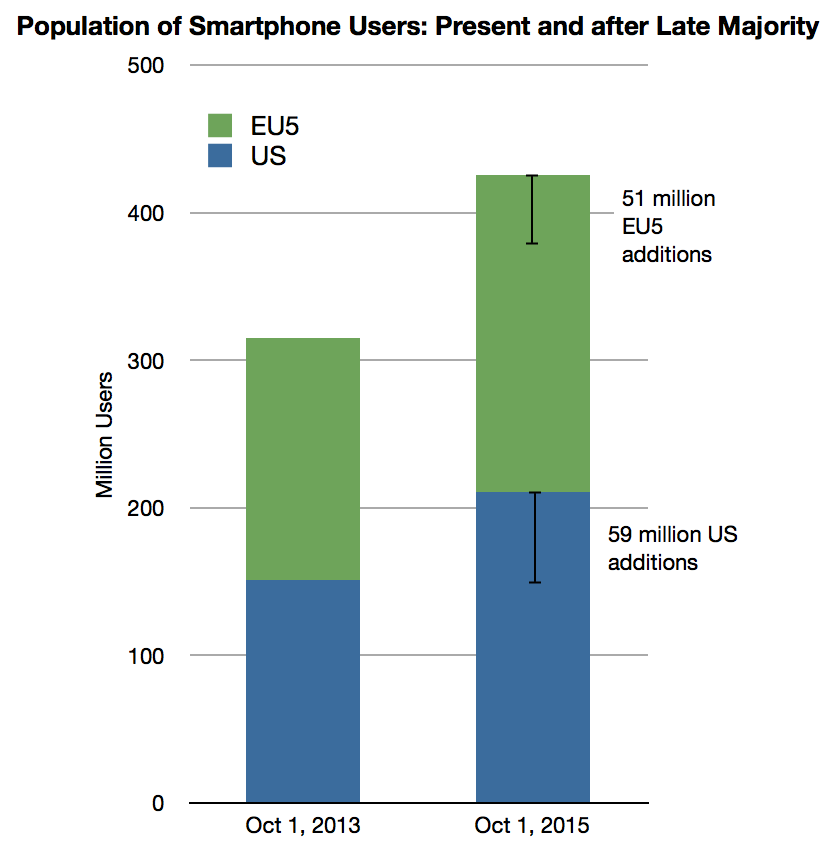
    One final observation: the two markets appear to be converging thus placing the analyst in the comfortable position of forecasting the adoption of smartphones for a total population of 425 million people ((see previous note)).

    Screen Shot 2013-10-16 at 10-16-2.01.07 PM

    If we define saturation as the end of the "Late Majority" period then the number of new-to-smartphone users remaining for the combined EU5 + USA markets is 110 million of which 59 million will adopt in the US and 51 million in Europe. They will all join ecosystems in the next two years.

    Plan accordingly.